Key Statistics
Key Takeaways
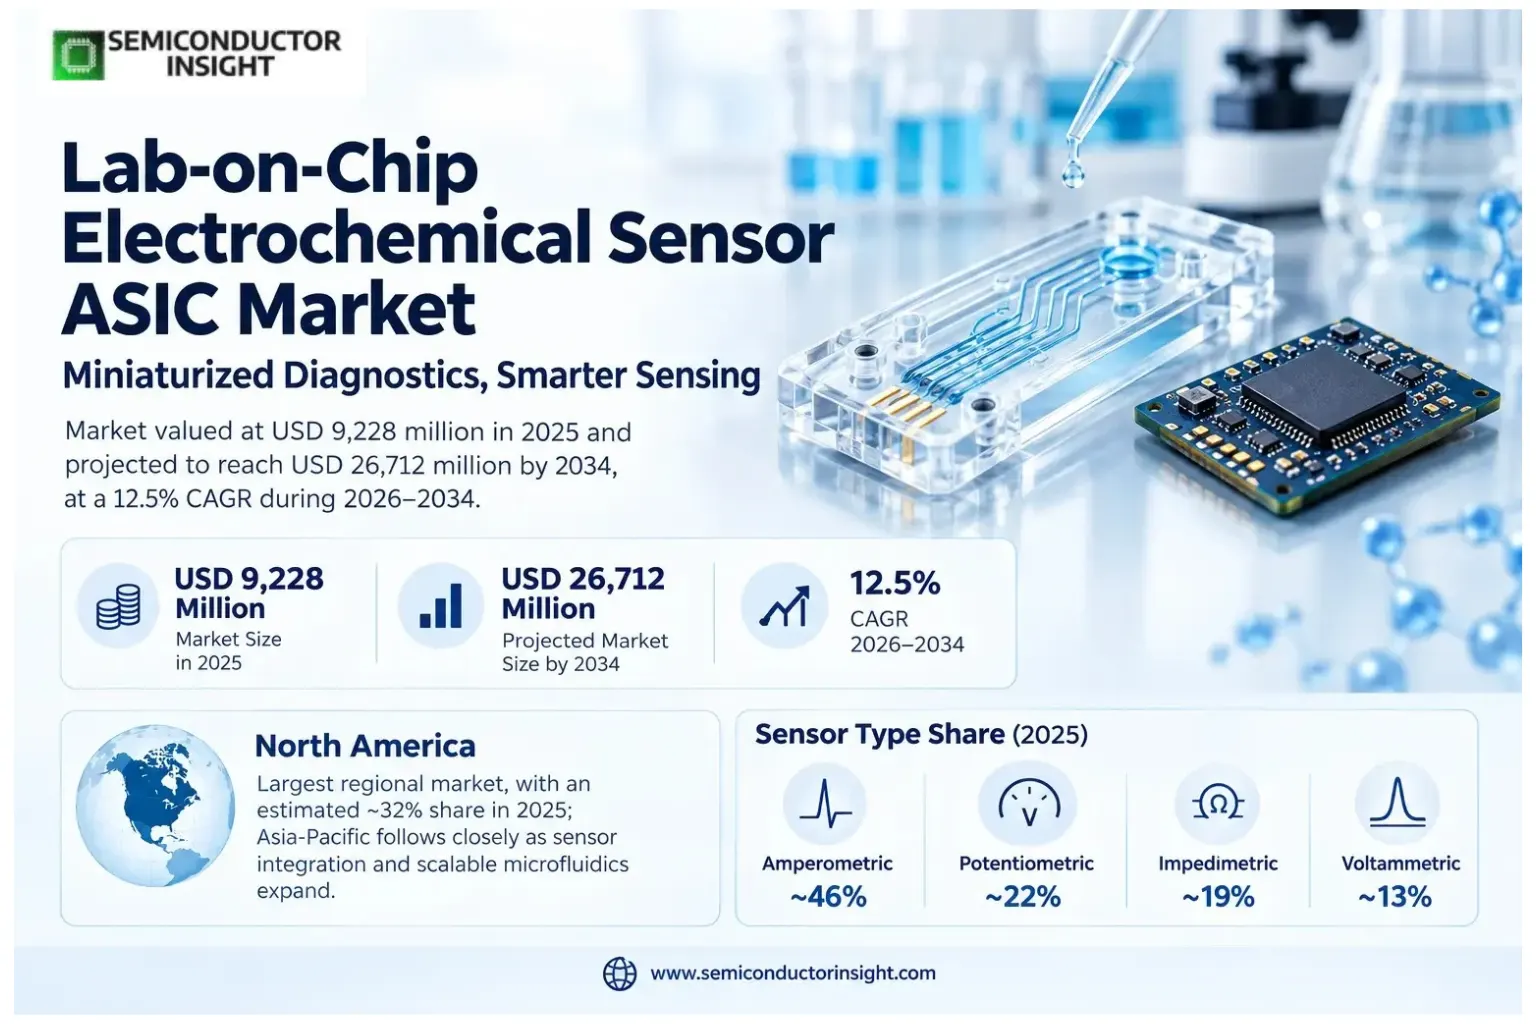
- Value progression: Electrochemical lab-on-chip technology demand stood at USD 9,228 million in 2025 and is forecast at USD 26,712 million in 2034, representing 12.5% CAGR over the forecast interval. This series includes the integrated sensor electronics and associated microfluidic platform value rather than standalone merchant ASIC invoices.
- Detection electronics: Amperometric Sensor ASICs account for an estimated ~46% of 2025 value, followed by potentiometric ~22%, impedimetric ~19% and voltammetric ~13%; differential pulse and impedance methods create room for multi-analyte assays and richer signal interpretation.
- Use cases: Point-of-Care Diagnostics leads with an estimated ~49% of 2025 value, compared with Environmental Monitoring at ~19%, Pharmaceutical Research at ~15%, Food Safety Testing at ~12% and other settings at ~5%; sample preparation and cartridge usability strongly affect purchasing.
- Regional pattern: North America is the largest regional market at an estimated ~32% share, followed by Asia-Pacific at ~30% and Europe at ~24%. Asia-Pacific is modeled to expand fastest at ~13.9% CAGR, supported by miniaturized electronics production and decentralized testing needs.
- Commercial gate: Reliability depends on electrode drift, fluidic sealing, calibration stability, clinical or industrial validation, and reproducible cartridge manufacture. Supplier selection therefore rewards a qualified measurement workflow rather than a highly sensitive laboratory electrode in isolation.
Lab-on-Chip (LoC) Electrochemical Sensor ASIC Market Overview
Lab-on-chip electrochemical sensor ASIC market was valued at USD 9,228 million in 2025 and is projected to reach USD 26,712 million by 2034, reflecting 12.5% CAGR through 2026–2034. North America accounted for an estimated ~32% of the 2025 market, while Asia-Pacific follows closely because sensor integration and scalable microfluidic manufacturing increasingly intersect.
An electrochemical lab-on-chip instrument combines a miniaturized sample pathway with working, reference and counter electrodes, analog conditioning and an electronic readout. Amperometric techniques translate oxidation or reduction current into analyte information; potentiometric systems measure electrode potential; impedimetric methods interrogate interfacial electrical properties; and voltammetry sweeps potential to separate response peaks. The ASIC may integrate a potentiostat, programmable gain, excitation generation, analog-to-digital conversion and digital control. Disposable fluidic cartridges and reusable readers distribute these functions differently, so platform design determines the practical addressable electronics content.
The monetary boundary covers the publisher-defined value of electrochemical lab-on-chip sensing technologies, including associated microfluidic platform components and integrated sensing electronics where these are supplied as part of the described technology. It is not a merchant semiconductor ASIC-only revenue series. Optical-only central laboratory analyzers, unrelated processors, generic microcontrollers without a lab-on-chip electrochemical role, and large centralized instruments outside the defined workflow are excluded. This boundary matters because a diagnostic cartridge may contain electrodes and fluidics while a companion reader houses the silicon that controls and interprets measurements.
Analog Devices offers the AD5940 and AD5941 electrochemical analog front ends, as well as the ADuCM355 mixed-signal controller for electrochemical measurements. Texas Instruments provides the LMP91000 configurable potentiostat front end, and PalmSens supplies OEM electrochemical measurement modules used in instrument integration. These are examples of measurement building blocks rather than proof that every product is a custom merchant ASIC or that an entire diagnostic platform is attributable to silicon. Design wins depend on electrode chemistry, calibration algorithms, input leakage, reference stability, noise floor and system power consumption.
Recent peer-reviewed work shows why device-level innovation is moving toward the fluidics-electronics interface. A 2025 study demonstrated an automated three-dimensional printed microfluidic oxygen-sensing platform; another reported on-chip extraction and electrochemical detection of enrofloxacin in milk. A separate publication described a portable multiplexed potentiostat for on-site biomarker measurement. These results demonstrate feasible architectures and application demand, but experimental detection limits and prototype costs are not equivalent to mass-production yields, regulatory clearance or recurring sales. Transfer from laboratory prototypes to repeatable manufactured cartridges remains a major commercialization challenge.
The strongest demand is associated with diagnostic workflows that reduce sample handling, turnaround time and dependence on a centralized laboratory. Environmental testing agencies and food processors also value portable electrochemical analysis where shipping samples introduces delay or degradation. Pharmaceutical researchers use microfluidic monitoring to observe biochemical changes in controlled experiments. For each buyer group, an acceptable total test cost combines reader amortization, disposable materials, assay reagents, labor and quality control; electronics performance is necessary but insufficient without reproducible sampling and reliable interpretation.
Segment Analysis: By Type
The functional segmentation spans amperometric, potentiometric, impedimetric and voltammetric sensor ASICs. Amperometric devices represent an estimated ~46% of 2025 value, followed by potentiometric at ~22%, impedimetric at ~19% and voltammetric at ~13%. Voltammetric architectures show modeled growth of ~14.1% CAGR, while high-volume amperometric channels retain the largest initial revenue pool because simple current readouts suit many enzymatic assays.
| Type | Function | Market position |
|---|---|---|
| Amperometric Sensor ASICs | Amperometric Sensor ASICs (~46% share; ~11.9% CAGR). For amperometric sensor asics, these devices measure current generated by analyte-linked redox reactions at a controlled electrode potential, making enzyme-coupled metabolites and chemical contamination natural targets. When evaluating amperometric sensor asics, the AD5940 potentiostat signal chain demonstrates how current ranges, low-noise amplification and programmable excitation are coordinated in a compact reader. The commercial consequence for amperometric sensor asics is a balance between assay reproducibility and the resources required to integrate the sensing electronics with a small fluidic sample volume. Qualification of amperometric sensor asics must account for the following exposure: electrode fouling and interference from matrix constituents require calibration protocols and disposable-surface quality controls. For end customers choosing amperometric sensor asics, clinical assay developers seek repeatability across multiple cartridge lots and temperature ranges. The estimated ~46% starting position for amperometric sensor asics reflects its operating role rather than an independently audited transaction ledger for every reader and cartridge. | Commercial position of Amperometric Sensor ASICs (~46% share; ~11.9% CAGR). For commercial position of amperometric sensor asics, the AD5940 potentiostat signal chain demonstrates how current ranges, low-noise amplification and programmable excitation are coordinated in a compact reader. When evaluating commercial position of amperometric sensor asics, clinical assay developers seek repeatability across multiple cartridge lots and temperature ranges. The commercial consequence for commercial position of amperometric sensor asics is a balance between assay reproducibility and the resources required to integrate the sensing electronics with a small fluidic sample volume. Qualification of commercial position of amperometric sensor asics must account for the following exposure: electrode fouling and interference from matrix constituents require calibration protocols and disposable-surface quality controls. For end customers choosing commercial position of amperometric sensor asics, these devices measure current generated by analyte-linked redox reactions at a controlled electrode potential, making enzyme-coupled metabolites and chemical contamination natural targets. The estimated ~46% starting position for commercial position of amperometric sensor asics reflects its operating role rather than an independently audited transaction ledger for every reader and cartridge. |
| Potentiometric Sensor ASICs | Potentiometric Sensor ASICs (~22% share; ~11.7% CAGR). For potentiometric sensor asics, this class monitors potential differences between sensing and reference electrodes and is especially relevant to ion-selective and pH-oriented microfluidic assays. When evaluating potentiometric sensor asics, a stable reference system and low input bias are as important as converter resolution when a sensor must operate with tiny volumes. The commercial consequence for potentiometric sensor asics is a balance between assay reproducibility and the resources required to integrate the sensing electronics with a small fluidic sample volume. Qualification of potentiometric sensor asics must account for the following exposure: drift in reference chemistry or contamination from storage materials can dominate apparent electronics accuracy. For end customers choosing potentiometric sensor asics, water quality operators prefer devices that can be recalibrated without specialist instrumentation. The estimated ~22% starting position for potentiometric sensor asics reflects its operating role rather than an independently audited transaction ledger for every reader and cartridge. | Commercial position of Potentiometric Sensor ASICs (~22% share; ~11.7% CAGR). For commercial position of potentiometric sensor asics, a stable reference system and low input bias are as important as converter resolution when a sensor must operate with tiny volumes. When evaluating commercial position of potentiometric sensor asics, water quality operators prefer devices that can be recalibrated without specialist instrumentation. The commercial consequence for commercial position of potentiometric sensor asics is a balance between assay reproducibility and the resources required to integrate the sensing electronics with a small fluidic sample volume. Qualification of commercial position of potentiometric sensor asics must account for the following exposure: drift in reference chemistry or contamination from storage materials can dominate apparent electronics accuracy. For end customers choosing commercial position of potentiometric sensor asics, this class monitors potential differences between sensing and reference electrodes and is especially relevant to ion-selective and pH-oriented microfluidic assays. The estimated ~22% starting position for commercial position of potentiometric sensor asics reflects its operating role rather than an independently audited transaction ledger for every reader and cartridge. |
| Impedimetric Sensor ASICs | Impedimetric Sensor ASICs (~19% share; ~13.6% CAGR). For impedimetric sensor asics, alternating-current excitation and phase-sensitive measurement probe electrode interfaces, affinity binding and changes in sample conductivity without requiring a conventional endpoint current signal. When evaluating impedimetric sensor asics, frequency sweep design, electrode geometry and parasitic capacitance determine whether a portable reader can separate analyte response from cartridge effects. The commercial consequence for impedimetric sensor asics is a balance between assay reproducibility and the resources required to integrate the sensing electronics with a small fluidic sample volume. Qualification of impedimetric sensor asics must account for the following exposure: complex fitting and temperature dependence complicate the translation of research signatures into field-ready thresholds. For end customers choosing impedimetric sensor asics, pharmaceutical assay teams value repeated observations where destructive sample handling would distort kinetics. The estimated ~19% starting position for impedimetric sensor asics reflects its operating role rather than an independently audited transaction ledger for every reader and cartridge. | Commercial position of Impedimetric Sensor ASICs (~19% share; ~13.6% CAGR). For commercial position of impedimetric sensor asics, frequency sweep design, electrode geometry and parasitic capacitance determine whether a portable reader can separate analyte response from cartridge effects. When evaluating commercial position of impedimetric sensor asics, pharmaceutical assay teams value repeated observations where destructive sample handling would distort kinetics. The commercial consequence for commercial position of impedimetric sensor asics is a balance between assay reproducibility and the resources required to integrate the sensing electronics with a small fluidic sample volume. Qualification of commercial position of impedimetric sensor asics must account for the following exposure: complex fitting and temperature dependence complicate the translation of research signatures into field-ready thresholds. For end customers choosing commercial position of impedimetric sensor asics, alternating-current excitation and phase-sensitive measurement probe electrode interfaces, affinity binding and changes in sample conductivity without requiring a conventional endpoint current signal. The estimated ~19% starting position for commercial position of impedimetric sensor asics reflects its operating role rather than an independently audited transaction ledger for every reader and cartridge. |
| Voltammetric Sensor ASICs | Voltammetric Sensor ASICs (~13% share; ~14.1% CAGR). For voltammetric sensor asics, potential scanning and pulse sequences provide peak positions and magnitudes that help distinguish compounds in electroactive mixtures. When evaluating voltammetric sensor asics, the portable multiplexed electrochemical platform described in 2025 used several voltammetric techniques to evaluate biochemical analytes. The commercial consequence for voltammetric sensor asics is a balance between assay reproducibility and the resources required to integrate the sensing electronics with a small fluidic sample volume. Qualification of voltammetric sensor asics must account for the following exposure: acquisition time, waveform precision and electrode conditioning can constrain throughput in multi-channel systems. For end customers choosing voltammetric sensor asics, food safety laboratories use selective electrochemical responses to screen residues before confirmatory testing. The estimated ~13% starting position for voltammetric sensor asics reflects its operating role rather than an independently audited transaction ledger for every reader and cartridge. | Commercial position of Voltammetric Sensor ASICs (~13% share; ~14.1% CAGR). For commercial position of voltammetric sensor asics, the portable multiplexed electrochemical platform described in 2025 used several voltammetric techniques to evaluate biochemical analytes. When evaluating commercial position of voltammetric sensor asics, food safety laboratories use selective electrochemical responses to screen residues before confirmatory testing. The commercial consequence for commercial position of voltammetric sensor asics is a balance between assay reproducibility and the resources required to integrate the sensing electronics with a small fluidic sample volume. Qualification of commercial position of voltammetric sensor asics must account for the following exposure: acquisition time, waveform precision and electrode conditioning can constrain throughput in multi-channel systems. For end customers choosing commercial position of voltammetric sensor asics, potential scanning and pulse sequences provide peak positions and magnitudes that help distinguish compounds in electroactive mixtures. The estimated ~13% starting position for commercial position of voltammetric sensor asics reflects its operating role rather than an independently audited transaction ledger for every reader and cartridge. |
Amperometric Sensor ASICs
Architecture for Amperometric Sensor ASICs (~46% share; ~11.9% CAGR). For architecture for amperometric sensor asics, these devices measure current generated by analyte-linked redox reactions at a controlled electrode potential, making enzyme-coupled metabolites and chemical contamination natural targets. When evaluating architecture for amperometric sensor asics, the AD5940 potentiostat signal chain demonstrates how current ranges, low-noise amplification and programmable excitation are coordinated in a compact reader. The commercial consequence for architecture for amperometric sensor asics is a balance between assay reproducibility and the resources required to integrate the sensing electronics with a small fluidic sample volume. Qualification of architecture for amperometric sensor asics must account for the following exposure: electrode fouling and interference from matrix constituents require calibration protocols and disposable-surface quality controls. For end customers choosing architecture for amperometric sensor asics, clinical assay developers seek repeatability across multiple cartridge lots and temperature ranges. The estimated ~46% starting position for architecture for amperometric sensor asics reflects its operating role rather than an independently audited transaction ledger for every reader and cartridge.
Potentiometric Sensor ASICs
Architecture for Potentiometric Sensor ASICs (~22% share; ~11.7% CAGR). For architecture for potentiometric sensor asics, this class monitors potential differences between sensing and reference electrodes and is especially relevant to ion-selective and pH-oriented microfluidic assays. When evaluating architecture for potentiometric sensor asics, a stable reference system and low input bias are as important as converter resolution when a sensor must operate with tiny volumes. The commercial consequence for architecture for potentiometric sensor asics is a balance between assay reproducibility and the resources required to integrate the sensing electronics with a small fluidic sample volume. Qualification of architecture for potentiometric sensor asics must account for the following exposure: drift in reference chemistry or contamination from storage materials can dominate apparent electronics accuracy. For end customers choosing architecture for potentiometric sensor asics, water quality operators prefer devices that can be recalibrated without specialist instrumentation. The estimated ~22% starting position for architecture for potentiometric sensor asics reflects its operating role rather than an independently audited transaction ledger for every reader and cartridge.
Impedimetric Sensor ASICs
Architecture for Impedimetric Sensor ASICs (~19% share; ~13.6% CAGR). For architecture for impedimetric sensor asics, alternating-current excitation and phase-sensitive measurement probe electrode interfaces, affinity binding and changes in sample conductivity without requiring a conventional endpoint current signal. When evaluating architecture for impedimetric sensor asics, frequency sweep design, electrode geometry and parasitic capacitance determine whether a portable reader can separate analyte response from cartridge effects. The commercial consequence for architecture for impedimetric sensor asics is a balance between assay reproducibility and the resources required to integrate the sensing electronics with a small fluidic sample volume. Qualification of architecture for impedimetric sensor asics must account for the following exposure: complex fitting and temperature dependence complicate the translation of research signatures into field-ready thresholds. For end customers choosing architecture for impedimetric sensor asics, pharmaceutical assay teams value repeated observations where destructive sample handling would distort kinetics. The estimated ~19% starting position for architecture for impedimetric sensor asics reflects its operating role rather than an independently audited transaction ledger for every reader and cartridge.
Voltammetric Sensor ASICs
Architecture for Voltammetric Sensor ASICs (~13% share; ~14.1% CAGR). For architecture for voltammetric sensor asics, potential scanning and pulse sequences provide peak positions and magnitudes that help distinguish compounds in electroactive mixtures. When evaluating architecture for voltammetric sensor asics, the portable multiplexed electrochemical platform described in 2025 used several voltammetric techniques to evaluate biochemical analytes. The commercial consequence for architecture for voltammetric sensor asics is a balance between assay reproducibility and the resources required to integrate the sensing electronics with a small fluidic sample volume. Qualification of architecture for voltammetric sensor asics must account for the following exposure: acquisition time, waveform precision and electrode conditioning can constrain throughput in multi-channel systems. For end customers choosing architecture for voltammetric sensor asics, food safety laboratories use selective electrochemical responses to screen residues before confirmatory testing. The estimated ~13% starting position for architecture for voltammetric sensor asics reflects its operating role rather than an independently audited transaction ledger for every reader and cartridge.
Segment Analysis: By Application
Point-of-Care Diagnostics accounts for an estimated ~49% of 2025 demand, compared with Environmental Monitoring at ~19%, Pharmaceutical Research at ~15%, Food Safety Testing at ~12% and other uses at ~5%. The fastest modeled application is Food Safety Testing at ~13.1% CAGR as portable residue screening and faster process decisions encourage cartridge-based electrochemical measurements.
| Application | Demand characteristics |
|---|---|
| Point-of-Care Diagnostics | Point-of-Care Diagnostics (~49% share; ~12.9% CAGR). For point-of-care diagnostics, near-patient infectious disease and metabolic testing require compact sample preparation, reproducible electrochemical readout and a clear result interface. When evaluating point-of-care diagnostics, hospitals assess test sensitivity and specificity alongside time to answer, operator steps and cartridge storage life. The commercial consequence for point-of-care diagnostics is a balance between assay reproducibility and the resources required to integrate the sensing electronics with a small fluidic sample volume. Qualification of point-of-care diagnostics must account for the following exposure: clinical validation, patient safety and instrument service contracts determine whether a prototype becomes a routine test. For end customers choosing point-of-care diagnostics, assay operators therefore weigh the cost per validated result against deployment speed and reader maintenance. The estimated ~49% starting position for point-of-care diagnostics reflects its operating role rather than an independently audited transaction ledger for every reader and cartridge. |
| Environmental Monitoring | Environmental Monitoring (~19% share; ~11.8% CAGR). For environmental monitoring, field detection of dissolved oxygen, ionic contamination and selected pollutants benefits from small instruments that work close to sampling locations. When evaluating environmental monitoring, water utilities and inspection teams need durable electrodes, traceable calibration and straightforward decontamination between sites. The commercial consequence for environmental monitoring is a balance between assay reproducibility and the resources required to integrate the sensing electronics with a small fluidic sample volume. Qualification of environmental monitoring must account for the following exposure: variable salinity, temperature and fouling demand correction strategies beyond the initial semiconductor noise specification. For end customers choosing environmental monitoring, assay operators therefore weigh the cost per validated result against deployment speed and reader maintenance. The estimated ~19% starting position for environmental monitoring reflects its operating role rather than an independently audited transaction ledger for every reader and cartridge. |
| Pharmaceutical Research | Pharmaceutical Research (~15% share; ~12.2% CAGR). For pharmaceutical research, microphysiological experiments use electrochemical oxygen and metabolite measurements to observe cellular response under controlled perfusion. When evaluating pharmaceutical research, drug developers value time-series measurements that preserve the microenvironment while limiting sensor footprint. The commercial consequence for pharmaceutical research is a balance between assay reproducibility and the resources required to integrate the sensing electronics with a small fluidic sample volume. Qualification of pharmaceutical research must account for the following exposure: sterilization compatibility and biofouling are recurring integration risks in multi-day culture studies. For end customers choosing pharmaceutical research, assay operators therefore weigh the cost per validated result against deployment speed and reader maintenance. The estimated ~15% starting position for pharmaceutical research reflects its operating role rather than an independently audited transaction ledger for every reader and cartridge. |
| Food Safety Testing | Food Safety Testing (~12% share; ~13.1% CAGR). For food safety testing, portable electrochemical assays can screen antibiotic residues or process contaminants before centralized laboratory confirmation. When evaluating food safety testing, processors favor workflows that produce interpretable results with limited sample preparation and a low consumable cost. The commercial consequence for food safety testing is a balance between assay reproducibility and the resources required to integrate the sensing electronics with a small fluidic sample volume. Qualification of food safety testing must account for the following exposure: matrix effects in milk and processed food require validation against reference methods before broad deployment. For end customers choosing food safety testing, assay operators therefore weigh the cost per validated result against deployment speed and reader maintenance. The estimated ~12% starting position for food safety testing reflects its operating role rather than an independently audited transaction ledger for every reader and cartridge. |
| Others | Others (~5% share; ~10.9% CAGR). For others, education, specialty industrial quality assurance and emerging wearables form a heterogeneous residual application category. When evaluating others, university and pilot buyers may favor configurable potentiostat modules over highly integrated single-purpose chips. The commercial consequence for others is a balance between assay reproducibility and the resources required to integrate the sensing electronics with a small fluidic sample volume. Qualification of others must account for the following exposure: small batches and diverse assay chemistries constrain scale economics despite useful technical demonstrations. For end customers choosing others, assay operators therefore weigh the cost per validated result against deployment speed and reader maintenance. The estimated ~5% starting position for others reflects its operating role rather than an independently audited transaction ledger for every reader and cartridge. |
Clinical buyers do not purchase electrode sensitivity as a standalone outcome. They require defined specimen types, controls for interfering substances, documented clinical performance and clear interpretation under routine conditions. The 2025 global bacterial diagnostic landscape published by the World Health Organization identifies continuing gaps in rapid pathogen identification and resistance testing; this supports the need for improved diagnostic approaches without implying that every recommended test uses electrochemical ASICs. Integration suppliers must translate a promising electrical measurement into a regulated, reproducible clinical workflow.
Environmental and food applications differ because many purchasing decisions emphasize ruggedness, sample preparation time and regulatory screening thresholds rather than patient outcomes. An electrochemical device may work well with a reference buffer but require extensive correction when exposed to turbid water, milk or industrial process fluid. Developers can win contracts by offering stable disposable electrodes, configurable readout and data traceability. Growth in these settings is tied to the number of field measurements displaced from central laboratories, not simply the number of published sensor papers.
The secondary lenses of End User, Integration Level and Detection Technique capture procurement authority, electronic packaging and assay chemistry. Hospitals and Clinical Laboratories lead end users at ~44%; Fully Integrated LoC ASICs lead integration at ~47%; and Biosensor-Based Detection leads methods at ~43%. Those dimensions are complementary, not additive: a hospital could purchase a fully integrated biosensor cartridge, while an academic laboratory may assemble modular potentiostat electronics with an experimental nucleic-acid microfluidic assay.
Regional Analysis
North America held the largest estimated share at ~32% in 2025, followed by Asia-Pacific at ~30% and Europe at ~24%; Middle East & Africa represented ~8% and South America ~6%. Asia-Pacific has the fastest modeled expansion at ~13.9% CAGR, compared with ~11.5% for North America and ~11.8% for Europe. These shares represent the broad publisher-defined electrochemical lab-on-chip technology market rather than semiconductor die sales alone.
Where is electrochemical lab-on-chip technology being adopted most rapidly?
Regional demand reflects the intersection of laboratory decentralization, assay validation and accessible electronics supply. North American hospital systems have resources to validate diagnostic workflows, but regulatory and procurement requirements can extend commercialization timelines. Asia-Pacific manufacturing networks support cost-efficient electronics and disposable cartridge production, while European research organizations contribute microfluidic assay development. The regions therefore differ in what constitutes an attractive commercial product: some emphasize clinical reliability, others affordability and scalable manufacturing, and others specialized analytical performance.
Estimated regional growth rates are not direct measurements of installed electrochemical chips. They describe expected evolution of the wider technology category, including the fluidic and integration value embedded in systems. Asia-Pacific expansion benefits from manufacturing proximity and a large potential user base, whereas Middle East & Africa may grow from a smaller baseline through targeted access programmes. Every region faces the same physical challenges of electrode stability, assay specificity and sample preparation, but the relative weight of certification, distribution and maintenance changes substantially.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| North America | ~32% estimated share | ~11.5% CAGR | Clinical procurement and instrument regulatory pathways | For suppliers targeting North America, Analog Devices electrochemical readout components are widely accessible to North American engineering teams, while hospital procurement places weight on clinical evidence and maintenance coverage. The estimated ~32% position and ~11.5% annual growth reflect demand for practical electrochemical lab-on-chip workflows rather than only reader-chip sales. For selection committees in North America, fDA regulatory pathways and institutional validation budgets are the primary gates for near-patient testing, not the presence of a single sensor chip. A successful commercial entry in North America also requires validated sample matrices, traceable calibration, stable cartridge manufacturing and service coverage suited to local procurement conditions. |
| Asia-Pacific | ~30% estimated share | ~13.9% CAGR | Electronics manufacturing and decentralized access | For suppliers targeting Asia-Pacific, Large electronics supply chains in East Asia support electrode printing, packaging and compact reader assembly, while India and Southeast Asia have substantial decentralized testing requirements. The estimated ~30% position and ~13.9% annual growth reflect demand for practical electrochemical lab-on-chip workflows rather than only reader-chip sales. For selection committees in Asia-Pacific, cost per disposable test, channel distribution and heat-tolerant storage are decisive in many procurement settings. A successful commercial entry in Asia-Pacific also requires validated sample matrices, traceable calibration, stable cartridge manufacturing and service coverage suited to local procurement conditions. |
| Europe | ~24% estimated share | ~11.8% CAGR | Research hospitals and analytical instrumentation | For suppliers targeting Europe, European microfluidics and biomedical engineering groups contribute research on oxygen sensing and cell-culture monitoring, with suppliers serving both clinical and industrial laboratories. The estimated ~24% position and ~11.8% annual growth reflect demand for practical electrochemical lab-on-chip workflows rather than only reader-chip sales. For selection committees in Europe, cE conformity, laboratory accreditation and assay documentation influence commercialization across national health systems. A successful commercial entry in Europe also requires validated sample matrices, traceable calibration, stable cartridge manufacturing and service coverage suited to local procurement conditions. |
| Middle East & Africa | ~8% estimated share | ~13.2% CAGR | Diagnostic access and imported instrument service | For suppliers targeting Middle East & Africa, Public health laboratories and hospital networks seek practical decentralized tests where specialist laboratory access can be uneven across geographies. The estimated ~8% position and ~13.2% annual growth reflect demand for practical electrochemical lab-on-chip workflows rather than only reader-chip sales. For selection committees in Middle East & Africa, reliable reagent logistics, technical training and affordable cartridge replacement govern the adoption of electrochemical platforms. A successful commercial entry in Middle East & Africa also requires validated sample matrices, traceable calibration, stable cartridge manufacturing and service coverage suited to local procurement conditions. |
| South America | ~6% estimated share | ~12.8% CAGR | Food-export compliance and regional diagnostics | For suppliers targeting South America, Agricultural testing and healthcare providers can benefit from portable electrochemical instruments when central laboratory turnaround limits decisions. The estimated ~6% position and ~12.8% annual growth reflect demand for practical electrochemical lab-on-chip workflows rather than only reader-chip sales. For selection committees in South America, currency exposure, import approvals and the availability of trained maintenance partners affect supplier competitiveness. A successful commercial entry in South America also requires validated sample matrices, traceable calibration, stable cartridge manufacturing and service coverage suited to local procurement conditions. |
Competitive Landscape: Electrochemical Sensor Electronics and Lab-on-Chip Platforms
Competition spans precision analog semiconductor suppliers, electrochemical instrumentation integrators, disposable microfluidic developers and diagnostic platform vendors. The largest commercial distinction is between a component enabling electrode readout and a complete regulated assay product. A chip vendor may supply the measurement interface while a separate company controls electrode chemistry, disposable fluidics, assay software and clinical validation, so supplier rankings cannot be inferred from device catalog breadth alone.
Analog Devices has a focused portfolio for electrochemical readout through AD5940, AD5941 and ADuCM355. These components enable excitation, low-current measurement and mixed-signal processing for portable devices, but the end application still requires a calibrated electrode and sample interface. Texas Instruments supplies the LMP91000 potentiostat analog front end, giving equipment designers another configurable route. Their competitive strengths arise from documentation, analog performance, supply continuity and the engineering resources available to customers designing validated measurement workflows.
PalmSens serves OEM electrochemical measurement developers through modular potentiostat platforms. Such modules can accelerate prototyping and lower firmware integration work, especially for researchers transitioning from benchtop electrochemistry to compact instruments. They should not be classified automatically as merchant electrochemical ASIC sales because their delivered value can include measurement electronics, firmware and module assembly. Buyers compare these solutions with discrete analog-front-end designs according to volume, power budget, firmware flexibility and the cost of in-house validation.
Diagnostic and analytical instrument businesses participate at a different level of the value chain. Abbott, Roche, Siemens Healthineers and Agilent operate in relevant clinical or analytical ecosystems, but a broad diagnostic product catalog does not establish direct manufacture of electrochemical lab-on-chip ASICs. Their market relevance is primarily through assay workflow requirements, channel access and potential integration demand. A technically superior sensor architecture may fail commercially if it cannot meet the workflow, quality and supply constraints imposed by downstream instrument providers.
The principal competitive moat is accumulated assay validation rather than patent ownership alone. Developers need stable electrode surface chemistry, controlled fluidic tolerances, robust analog calibration and traceable software outputs across different users and sample matrices. University prototypes demonstrate feasibility, while repeatable commercial production requires qualification of substrate suppliers, surface coatings, assembly processes and cartridge packaging. Partnership models can therefore outperform vertically isolated chip designs when they shorten the path from experimental electrochemistry to an approved field-use device.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Precision electronics | Analog Devices; Texas Instruments; Microchip Technology | Electrochemical analog front ends and embedded control architectures compete on input noise, current range, integration support and documented device longevity. These suppliers enable a reader architecture but do not necessarily capture the full disposable-cartridge value. The central buying decision is whether the selected chip can maintain accuracy after sensor aging, matrix variation and temperature excursions. |
| OEM electrochemistry | PalmSens; specialist potentiostat integrators | Configurable potentiostat modules and application firmware support fast prototyping of amperometric and voltammetric workflows. Customers accept a higher module bill of materials when reduced development effort or calibration support offsets the cost. These firms compete at instrument subsystem level, so their module receipts cannot be equated directly with semiconductor die revenue. |
| Diagnostic and assay platforms | Abbott; Roche; Siemens Healthineers; Agilent Technologies | Downstream testing platforms and analytical laboratories establish usability, service, validation and reagent requirements that influence component selection. Participation in diagnostics does not by itself verify proprietary electrochemical ASIC shipments. Competitive advantage comes from delivering a repeatable result in the intended care or laboratory environment rather than maximizing a single electrode sensitivity figure. |
Key companies profiled
- Analog Devices
- Texas Instruments
- PalmSens
- Microchip Technology
- STMicroelectronics
- Abbott
- Agilent Technologies
- Roche
- Siemens Healthineers
Electrochemical Lab-on-Chip Production and Qualification Analysis
Manufacturing capacity for electrochemical lab-on-chip products depends on more than standard CMOS wafer starts. Electrode deposition, microfluidic channel fabrication, surface functionalization, adhesive compatibility and reader assembly can each become the throughput bottleneck. Product value may include a reusable electronic reader and a high-volume disposable cartridge, which creates different quality-control and margin profiles across the same assay platform.
A programmable analog front end can be fabricated using established semiconductor processes, but the signal it receives is controlled by electrodes exposed to biological or environmental fluids. Gold, carbon and printed electrode surfaces can require different conditioning, coatings and packaging. Fluidic bonding must prevent leaks while preserving analyte transport and avoiding contamination from adhesives. Yield therefore emerges from a multi-step assembly chain rather than only die test, and a low-cost chip cannot compensate for high cartridge rejection rates.
Production scaling requires standard reference solutions, calibration procedures and sampling plans that detect drift before product shipment. Clinical platforms may need lot-level traceability and stability studies covering storage, transport and repeated user handling. Environmental equipment requires rugged connectors, enclosure protection and straightforward field calibration. These requirements shape supplier choice because a manufacturer with reliable analog electronics but inconsistent electrode chemistry may still face high returns and service expense.
The balance between disposable and reusable components determines revenue recurrence. A single reader can support hundreds or thousands of cartridges, while a research system may use interchangeable electrodes with limited commercial repetition. Investors and suppliers should therefore distinguish reader installations, cartridge volumes and measured assay throughput. Academic demonstrations provide valuable architecture evidence but do not reveal manufacturing utilization, sustained production yields or regulated demand at scale.
Market Dynamics: Drivers, Restraints and Commercial Opportunities
Electrochemical lab-on-chip adoption is propelled by decentralized diagnostics, lower-power analog integration and portable environmental testing. These drivers are moderated by sensor drift, assay validation expense and fluidic manufacturing complexity. The contribution model expresses their relative influence on the forecast growth path while recognizing that a laboratory detection breakthrough does not automatically produce a qualified device or an affordable recurring test.
MARKET DRIVERS
Drivers Impact Analysis*
| Market Drivers | Impact Rank | CAGR Contribution (%) | 2026–2028 | 2029–2031 | 2032–2034 |
|---|---|---|---|---|---|
| Decentralized diagnostic workflows | High | +6.00% | High | High | High |
| Compact potentiostat and mixed-signal integration | High | +4.00% | High | High | Medium |
| Food and environmental screening expansion | Medium-High | +3.20% | Medium | High | High |
| Microfluidic assay multiplexing | Medium | +2.20% | Medium | High | High |
| Pharmaceutical microphysiological testing | Low-Medium | +1.50% | Low | Medium | High |
| Others (academic translation, digital reporting and low-volume field testing) | Low | +1.10% | Low | Medium | Medium |
Decentralized diagnostics
Hospitals and public health systems value rapid answers near the patient when specimen transport delays clinical decisions. Electrochemical lab-on-chip devices can combine sample preparation, electrode-based detection and digital interpretation in a small footprint. However, clinical acceptance requires sensitivity and specificity established for the actual intended population, not only a response curve in buffer. Developers that design cartridge handling and quality controls alongside the analog electronics are better positioned to convert diagnostic need into recurring orders.
Mixed-signal electronics integration
Electrochemical front ends can consolidate programmable excitation, current sensing, analog-to-digital conversion and digital control in compact low-power readers. Products such as ADuCM355 and LMP91000 illustrate component architectures available to designers. Integration reduces board area and may improve repeatability, but performance still depends on the electrode interface, reference chemistry and firmware calibration. The most valuable engineering gains arise when electrical noise, battery life and sample handling are optimized together.
Portable contaminant monitoring
Food producers and water utilities often need screening information before a sample can reach a specialized analytical laboratory. Microfluidic electrochemical assays can provide localized measurements for selected contaminants, oxygen or ionic conditions. The 2025 enrofloxacin research example demonstrated on-chip extraction and detection in milk, showing how chemistry and fluidics can address matrix effects. Commercial demand nevertheless depends on validated thresholds, rugged sampling procedures and a clear escalation path to confirmatory analysis.
Multiplexed sensing
Several electrode channels or programmed voltammetric modes can extract multiple biochemical signals from a compact device. A 2025 portable potentiostat study reported multiplexed detection capabilities and wireless connectivity, offering evidence of the architectural direction. In a production instrument, channel-to-channel interference, cross-contamination and calibration complexity must be managed before multiplexing reduces total test cost. Suppliers that offer consistent electrode fabrication and software interpretation can create differentiated assay platforms.
Microphysiological research
Drug discovery teams use organ-on-chip and perfused cell models to observe oxygen availability, metabolic changes and stress responses without repeatedly removing samples. Integrated electrochemical sensors can capture temporal variation that a single endpoint assay would miss. The commercial opportunity is specialized and technically demanding because biocompatibility, sterilization and multi-day drift affect measurement credibility. Successful systems must support research reproducibility and data export rather than simply miniaturize a conventional bench instrument.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Market Restraints | Impact Rank | CAGR Contribution (%) | 2026–2028 | 2029–2031 | 2032–2034 |
|---|---|---|---|---|---|
| Electrode drift and sample matrix interference | High | -2.30% | High | High | Medium |
| Clinical and industrial validation expense | Medium-High | -1.40% | High | Medium | Medium |
| Fluidic packaging and cartridge yield | Medium | -1.20% | Medium | High | High |
| Others (reader servicing, reimbursement uncertainty and competing assays) | Low | -0.60% | Medium | Medium | Low |
Electrode and reference stability
Biological proteins, changing ionic strength and electrode-surface contamination can alter an electrochemical signal even when the semiconductor electronics remain stable. Reference electrodes may drift during storage or repeated use, making calibration frequency a key cost determinant. These effects can produce false variation between cartridge lots and undermine customer confidence. Manufacturers must demonstrate performance with real sample matrices, controlled shelf-life testing and appropriate compensation algorithms before a promising sensor architecture becomes a routine field product.
Validation and regulatory burden
Clinical assays require documented performance in intended users and sample types, and environmental tests must satisfy relevant analytical standards. A paper demonstrating an attractive limit of detection is a starting point, not evidence of regulatory approval or reimbursement. Validation programmes require specimen access, reproducible manufacturing, trained operators and quality-system documentation. This slows commercialization and raises financing requirements, particularly for small firms attempting to integrate custom electronics with novel electrode chemistry.
Disposable cartridge manufacturing
Electrode printing, microfluidic bonding and reagent deposition introduce variability that does not appear in wafer-level electrical tests. Minute differences in channel geometry or adhesive leaching can change analyte transport and apparent concentration. A product must also withstand packaging, distribution and storage conditions before reaching the user. Consequently, the economics of cartridge yield and shelf life can dominate the total cost of a diagnostic test even when silicon integration is efficient.
MARKET OPPORTUNITIES
Integrated multi-analyte readers
Developers can build configurable platforms that support amperometry, impedance and pulse voltammetry without requiring a new reader for every assay. Shared hardware could lower deployment friction if the electrode cartridges remain assay-specific and quality controlled. This approach offers a route to repeat consumable revenue while retaining software upgrade flexibility. The commercial risk is that overly general designs become difficult to validate for each clinical or environmental use case.
Industrial process monitoring
Small electrochemical modules can be placed closer to process lines for water quality, dissolved oxygen or contamination screening. Continuous or frequent measurement can reduce the delay between sampling and corrective action, provided sensor surfaces can be maintained or replaced economically. Integrators may combine existing precision analog components with custom fluidics instead of designing a dedicated chip at low volume. Success depends on rugged packaging and clear service intervals.
Regional manufacturing partnerships
A supplier of analog readout silicon can partner with an electrode printer, a microfluidic fabricator and a local diagnostic distributor to reduce development bottlenecks. Such partnerships can localize cartridge production and improve responsiveness to market-specific testing requirements. They also create a more complex quality system, because performance depends on multiple manufacturing steps and transport conditions. A documented division of calibration, assembly and validation responsibilities is essential for durable commercial scale.
Value Chain: Electrode Materials, ASICs, Microfluidics and Testing
The lab-on-chip electrochemical value chain begins with electrodes and analog measurement components, moves through fluidic integration and reagent preparation, and ends with assay validation and user support. A failure at any stage can degrade the measured signal or the clinical interpretation. Semiconductor content is a necessary contributor to many reader designs, but it represents only one part of the technology value included in the defined market.
Electrode input. Conductive materials and surface coatings define the chemical selectivity that electronics must read. Gold, carbon and functionalized polymer interfaces differ in fouling behavior, operating potential and fabrication cost. Suppliers need consistent surface area and reference chemistry so that a calibration established during design remains useful after scale-up. Variability at this first stage can propagate through the entire measurement chain even when the analog converter is accurately specified.
Semiconductor conversion. Precision analog front ends translate small electrode currents or potentials into digitized data. Designers select programmable gain, waveform generation and power modes according to the analyte, electrode geometry and battery budget. The silicon may be located in a reusable reader rather than the disposable cartridge. This placement changes the economics of recurring demand and makes it important to separate platform shipments from semiconductor component content.
Fluidic assembly. Miniaturized channels, valves, reservoirs and reagent interfaces determine whether the correct amount of sample reaches the electrode under controlled conditions. Poor bonding or inconsistent channel dimensions can undermine assay reproducibility. Manufacturers must balance low-cost polymers with chemical compatibility and stable surface treatment. Assembly yield and shelf life therefore have a direct effect on unit economics and customer willingness to deploy the platform outside a specialist laboratory.
Field qualification. Final acceptance depends on documented test performance, user training, software reporting and local support. Clinical customers may require regulatory evidence and integration with laboratory information systems, while environmental agencies prioritize rugged operation and traceable calibration. The manufacturer must control consumable lots and provide a response when a measurement fails quality checks. A qualified service model is an economic asset that cannot be inferred from semiconductor datasheet specifications alone.
Recent Developments in Electrochemical Lab-on-Chip Sensing
- 4 November 2025 Published
A peer-reviewed Lab on a Chip paper presented a compact multiplexed portable potentiostat with wireless connectivity and several voltammetric modes, demonstrating a possible architecture for on-site biomarker measurement. The researchers reported performance comparisons with a conventional workstation and demonstrated cholesterol and triglyceride measurements. This is direct technical evidence for portable electrochemical integration, but it is a research prototype rather than a verified commercial ASIC product launch or a measure of shipment revenue. Source - 2 October 2025 Published
The World Health Organization released a landscape assessment of in-vitro diagnostics for bacterial priority pathogens, mapping gaps in identification and antimicrobial susceptibility testing. The publication provides adjacent evidence of demand for faster, accessible diagnostic workflows. It does not claim that the identified diagnostic products use electrochemical ASICs. For lab-on-chip developers, its significance is the need to design usable sample-to-answer systems that address real testing constraints rather than optimizing an isolated electrode signal. Source - 5 August 2025 Published
A peer-reviewed study described an integrated microfluidic electrochemiluminescence platform for diabetes-related biomarker detection. The research illustrates how sample handling, excitation and measurement architecture can be combined in compact analytical systems. Electrochemiluminescence includes a light-emission readout, so it should be interpreted as adjacent microfluidic integration evidence rather than a pure amperometric ASIC launch. The commercial implication is the continued convergence of assay chemistry and chip-scale fluidics, with validation still required for production deployment. Source - 27 June 2025 Published
Researchers reported a three-dimensional printed on-chip platform using selective extraction and electrochemical detection of enrofloxacin, including experiments in milk. The work highlights how sample matrix preparation can be integrated with the measurement stage for food-safety applications. It supports technical feasibility for portable residue screening, not a claim of commercial distribution or regulatory certification. The broader market significance is the potential to reduce laboratory turnaround when manufacturers can reproduce electrode chemistry and sample preparation reliably. Source - 9 May 2025 Announced
The World Health Organization and Medicines Patent Pool announced a sublicensing agreement for rapid diagnostic test technology in Nigeria. This is adjacent access and technology-transfer evidence, not a direct electrochemical chip order or launch. Its relevance lies in the emphasis on affordable local testing and manufacturing capability, which may influence future instrument and cartridge design requirements. Suppliers still need to establish that any electrochemical platform meets the intended assay performance and service constraints. Source - 11 March 2025 Published
A Lab on a Chip paper detailed automated electrochemical oxygen sensing within a three-dimensional printed microfluidic system. The device combined a micromixer, bubble trap and electrodes to monitor oxygen conditions relevant to biological models. This provides direct research evidence for coupling electrochemical electronics with controlled fluid handling, particularly in microphysiological experiments. It does not establish a mass-produced diagnostic cartridge or a proprietary merchant ASIC shipment, and additional validation would be needed for routine pharmaceutical use. Source - 9 January 2025 Published
Researchers released a paper-interfaced printed electrochemical device for uric-acid detection in sweat, examining electrode surface modification and small-volume sample handling. The study illustrates the design trade-off between disposable sensor materials and measurement accuracy in a portable setting. It is relevant to non-invasive biosensor development, but the reported laboratory performance does not demonstrate a regulated consumer product or a new electrochemical ASIC sale. Manufacturing stability and user-specific matrix variation remain commercialization gates. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2020–2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| Historical Period | 2020–2024 |
| Market Size 2025 | USD 9,228 million |
| Market Size 2026 | USD 10,385 million |
| Market Size 2034 | USD 26,712 million |
| Growth Rate | CAGR of 12.5% during 2026–2034 |
| Unit | USD million; publisher-defined electrochemical LoC technologies including associated microfluidic platforms |
| Segmentation | Type, Application, End User, Integration Level, Detection Technique and Region |
| By Type | Amperometric Sensor ASICs · Potentiometric Sensor ASICs · Impedimetric Sensor ASICs · Voltammetric Sensor ASICs |
| By Application | Point-of-Care Diagnostics · Environmental Monitoring · Pharmaceutical Research · Food Safety Testing · Others |
| By End User | Hospitals and Clinical Laboratories · Pharmaceutical and Biotechnology Companies · Academic and Research Institutions · Environmental Testing Agencies |
| By Integration Level | Fully Integrated LoC ASICs · Hybrid Integrated ASICs · Modular ASIC Platforms |
| By Detection Technique | Biosensor-Based Detection · Immunosensor-Based Detection · DNA/Nucleic Acid Electrochemical Detection · Ion-Selective Electrode Detection |
| By Region | Five regions are analyzed using estimated 2025 shares and differentiated forecast growth rates; estimates cover electrochemical LoC technology value. North AmericaUnited States; Canada; and other national markets with relevant diagnostic and analytical demand Asia-PacificChina; India; and other national markets with relevant diagnostic and analytical demand EuropeGermany; United Kingdom; and other national markets with relevant diagnostic and analytical demand Middle East & AfricaUnited Arab Emirates; South Africa; and other national markets with relevant diagnostic and analytical demand South AmericaBrazil; Chile; and other national markets with relevant diagnostic and analytical demand |
| Key Companies Profiled | Analog Devices, Texas Instruments, PalmSens, Microchip Technology, STMicroelectronics, Abbott, Agilent Technologies, Roche, Siemens Healthineers |
| Customization Scope | Country-level demand splits, assay-technology analysis, disposable-cartridge and reader value-chain mapping, manufacturer profiles, clinical versus industrial workflows, and application-specific qualification priorities. |
Frequently Asked Questions
What is the size and forecast for the lab-on-chip electrochemical sensor ASIC market?
The publisher-defined electrochemical lab-on-chip technology market was USD 9,228 million in 2025 and is projected at USD 26,712 million in 2034, representing 12.5% CAGR across the forecast period. These figures include associated microfluidic sensing platform value where described by the market definition, rather than only merchant analog-front-end or custom ASIC invoices. Reader and cartridge economics therefore influence the monetary total.
Which electrochemical sensing type has the largest share?
Amperometric Sensor ASICs lead the type mix with an estimated ~46% share in 2025, followed by Potentiometric Sensor ASICs at ~22%, Impedimetric Sensor ASICs at ~19% and Voltammetric Sensor ASICs at ~13%. Amperometry suits current-based redox and enzyme assays, while impedance and voltammetry support more complex detection signatures. The fastest modeled type growth is voltammetric at ~14.1% CAGR, reflecting expanded portable multi-analyte applications.
Which application generates the most demand?
Point-of-Care Diagnostics is the largest application with an estimated ~49% of 2025 value. Environmental Monitoring represents ~19%, Pharmaceutical Research ~15%, Food Safety Testing ~12% and other applications ~5%. Hospitals require validated near-patient workflows, while field and food users emphasize sample handling, calibration and ruggedness. The largest addressable revenue opportunity depends on reproducible results and affordable consumables, not just electrode sensitivity.
Which region leads the market?
North America leads with an estimated ~32% of 2025 revenue, followed by Asia-Pacific at ~30%, Europe at ~24%, Middle East & Africa at ~8% and South America at ~6%. Asia-Pacific has the strongest modeled growth at ~13.9% CAGR as local manufacturing and decentralized testing expand. The regional differences reflect instrument qualification, assay adoption and microfluidic manufacturing capability rather than only semiconductor fabrication capacity.
What are the main integration architectures?
Fully Integrated LoC ASICs account for an estimated ~47% of 2025 value, Hybrid Integrated ASICs for ~33% and Modular ASIC Platforms for ~20%. Fully integrated designs can reduce reader size and simplify power management, while modular approaches remain useful for research and low-volume applications that need flexibility. The correct architecture depends on assay maturity, sensor-electrode requirements, production scale and the cost of validating each hardware revision.
How do electrochemical detection methods differ?
Biosensor-Based Detection represents an estimated ~43% share, Immunosensor-Based Detection ~24%, DNA/Nucleic Acid Electrochemical Detection ~20% and Ion-Selective Electrode Detection ~13%. These techniques vary in recognition chemistry, signal conditioning and the degree of sample preparation required. A nucleic-acid assay may need upstream amplification or extraction, whereas an ion-selective electrode can be more directly linked to potential measurement and calibration.
Who supplies relevant electrochemical electronics?
Analog Devices supplies AD5940, AD5941 and ADuCM355 electrochemical measurement components, while Texas Instruments offers the LMP91000 programmable analog front end. PalmSens provides OEM potentiostat modules for instrument developers. Diagnostic and analytical platform companies can influence adoption through workflow specifications, but participation in diagnostics does not prove direct manufacture of merchant electrochemical ASICs. Supplier assessment should distinguish chip, module, cartridge and complete assay system revenue.
What constrains commercialization of lab-on-chip electrochemical assays?
Electrode drift, sample matrix interference, reference stability, fluidic leakage and cartridge manufacturing variation are central technical constraints. Clinical applications additionally require validation in intended users and relevant regulatory pathways, while industrial buyers demand calibration traceability and robust field operation. A strong academic demonstration can fail to translate into sales if manufacturing yield, reagent shelf life or support economics remain unresolved. Qualification must cover the entire measurement chain.
What is the role of microfluidics in the revenue boundary?
Microfluidic channels and sample-handling structures control analyte transport, mixing and contact with the electrodes. They are included when supplied within the publisher-defined electrochemical lab-on-chip technology platform. This is broader than a standalone semiconductor chip market, so the monetary series should not be treated as direct merchant ASIC sales. A reusable reader and disposable fluidic cartridge may generate very different revenue patterns and manufacturing cost structures.
What developments could shape the market through 2034?
Portable multiplexed potentiostats, integrated oxygen sensing in microphysiological models, and on-chip extraction for food contamination screening illustrate potential technical directions. The 2025 research literature shows practical combinations of electrode chemistry, signal processing and fluidic integration. Commercial expansion will depend on moving these architectures through reproducible production, appropriate validation and affordable service channels. Growth is likely to be uneven across clinical, environmental and pharmaceutical customers.
Research Sources & Evidence Base

Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF