Building Energy Efficient LED Market Insights
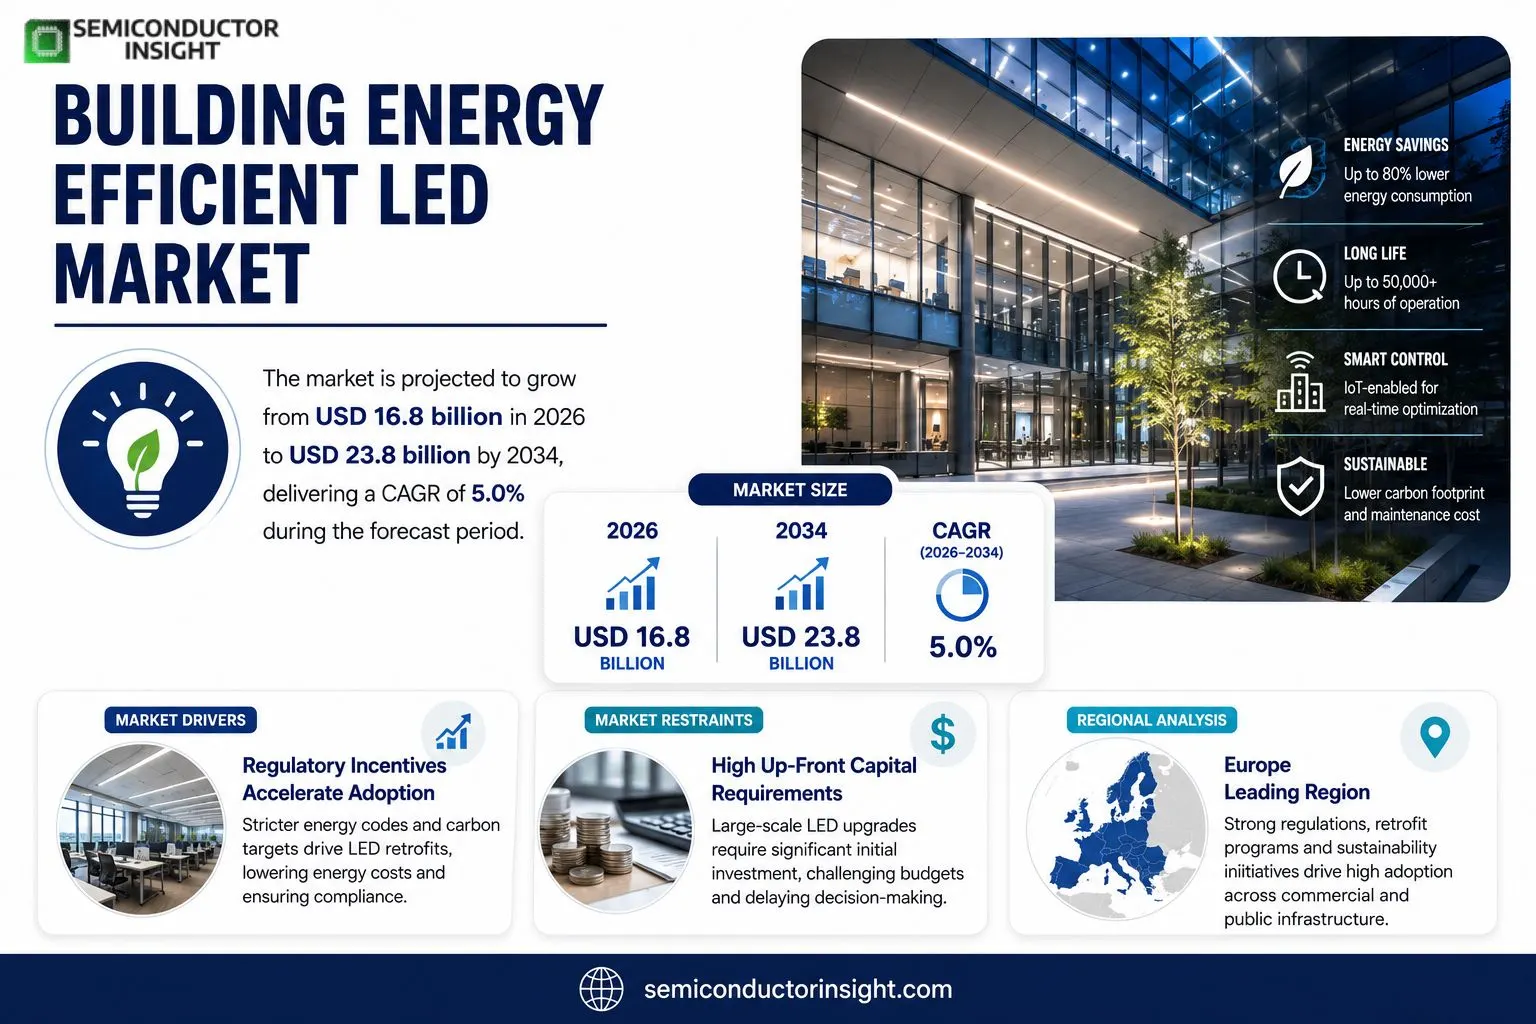
Building Energy Efficient LED market size was valued at USD 15.3 billion in 2024. Forecasts indicate the market will rise from USD 16.8 billion in 2026 to USD 23.8 billion by 2034, delivering a compound annual growth rate of 5.0%.
Building Energy Efficient LEDs are solid‑state lighting devices engineered for higher luminous efficacy, extended service life, and reduced power consumption relative‑to conventional lamps. Their adoption across residential, commercial and industrial premises supports lower energy demand while preserving illumination quality.
MARKET DRIVERS
Regulatory Incentives Accelerate Adoption
Across major economies, building codes have been tightened to meet carbon‑neutral targets. Building Energy Efficient LED Market benefits because property owners must replace legacy lighting to avoid penalties. This regulatory pressure translates into a steady pipeline of retrofit projects, especially in commercial office towers where energy bills represent a sizable cost component.
Cost Competitiveness of LED Technology
LED luminaires now command price points comparable to traditional fixtures, while delivering up to 80% lower operating expenses. The payback period for a typical mid‑size building has shrunk to under three years, prompting finance teams to prioritize LED upgrades in capital‑expenditure plans. This shift in investment logic fuels demand for high‑efficiency solutions.
➤ “When the total cost of ownership aligns with short‑term ROI expectations, decision‑makers move quickly.”
The convergence of stricter energy standards and declining component costs creates a virtuous cycle: higher market penetration drives volume discounts, which in turn further depresses prices. Companies that position themselves as turnkey providers can capture a larger share of these emerging retrofit contracts.
MARKET CHALLENGES
Integration Complexity in Legacy Buildings
Older structures often feature proprietary wiring schematics and confined ceiling spaces, making LED retrofits labor‑intensive. Installation crews must navigate code‑compliant upgrades while preserving aesthetic integrity, a combination that inflates project timelines and erodes anticipated savings.
Other Challenges
Skill Shortage in Advanced Lighting Controls
The market increasingly demands smart dimming, occupancy sensing, and daylight harvesting. Yet the pool of technicians trained to program and maintain these systems remains limited, slowing rollout speed and raising service costs.
MARKET RESTRAINTS
High Up‑Front Capital Requirements for Large‑Scale Projects
While operating savings are attractive, the initial outlay for a district‑wide LED overhaul can exceed several million dollars. Organizations with constrained balance sheets may defer upgrades, opting instead for incremental replacements that dilute the overall impact on energy consumption.Financing mechanisms such as energy‑service agreements are still nascent in many regions, limiting the ability of smaller developers to access capital without taking on debt. Consequently, the pace of market expansion may be uneven, concentrated in jurisdictions with mature funding ecosystems.Furthermore, uncertainty around future policy revisions creates a risk‑averse environment; firms hesitate to commit large budgets when potential retroactive compliance changes could render current installations suboptimal.
MARKET OPPORTUNITIES
Smart Building Platforms Enable New Revenue Streams
The rise of integrated building management systems offers a channel for LED manufacturers to bundle hardware with analytics services. By providing real‑time energy dashboards, vendors can transition from pure product sales to subscription‑based models, increasing recurring revenue and deepening client relationships.Urban redevelopment initiatives in rapidly growing megacities present a fertile ground for large‑scale LED deployments. These projects often include sustainability clauses, allowing early‑stage suppliers to lock in long‑term contracts and shape the design standards for emerging districts.Finally, the expanding focus on indo or health and wellbeing creates demand for LEDs that support circadian rhythms. Products delivering tunable white light can command premium pricing, opening a niche segment that aligns with the broader objectives of Building Energy Efficient LED Market.
Building Energy Efficient LED Market Trends
Shift to Integrated Smart Controls in Commercial Buildings
The commercial sector is increasingly wiring LED luminaires into building‑automation ecosystems. The convergence of occupancy sensors, daylight harvesting modules, and cloud‑based management platforms lets facility managers fine‑tune illumination levels in real time, cutting energy waste while preserving occupant comfort. This technical convergence is not a fleeting fad; it reflects stricter energy‑performance codes and the growing financial incentive of utility rebate schemes. As a result, contractors are bundling LED fixtures with IoT gateways, which reshapes procurement cycles and creates a new revenue stream for manufacturers that can supply both hardware and software services. The trend forces traditional lighting firms to develop or acquire digital expertise, otherwise they risk losing market share to tech‑savvy entrants.
Other Trends
Demand Surge in Residential Retrofit Projects
Homeowners are replacing legacy incandescent and fluorescent sources with high‑efficiency LEDs at an accelerating pace. Tax credits for energy‑saving upgrades, combined with growing consumer awareness of electricity costs, are turning retrofit decisions into a mainstream budgeting item. Because retrofits often involve multiple product categoriesbulbs, panel lights, and light stripssuppliers that offer a diversified portfolio enjoy cross‑selling opportunities. Moreover, the renovation boom in suburban markets fuels a steady flow of orders, encouraging manufacturers to prioritize low‑cost, high‑lumen designs that meet the aesthetic expectations of modern interiors while delivering measurable savings.
Regional Divergence: Asia‑Pacific Outpaces North America
While North America sees moderate adoption driven by mature code environments, the Asia‑Pacific region exhibits a markedly higher pace of new‑construction projects that embed energy‑efficient LEDs as the default lighting solution. Rapid urbanization in China and India, together with aggressive national energy‑efficiency mandates, creates a pipeline of large‑scale developments that prioritize LED integration from the design stage. This geographic shift prompts OEMs to allocate more production capacity to Asian factories, reducing lead times for regional distributors. Companies that can navigate local regulatory nuances and forge partnerships with regional developers will capture a disproportionate share of Building Energy Efficient LED Market growth in the next decade.
COMPETITIVE LANDSCAPE
Key Industry Players
Building Energy Efficient LED Market – Competitive Overview
Signify commands the upper tier of the LED arena, leveraging a portfolio that blends smart‑connected fixtures with high‑efficiency lumen output. Its breadth across residential, commercial and industrial segments grants it leverage in procurement negotiations and accelerates adoption of integrated lighting‑control ecosystems. The firm’s strategic acquisitions in the past five years have widened its geographic footprint, especially in emerging Asian markets, allowing it to capture a disproportionate share of volume growth despite intense price pressure. This concentration around a few megatrendsenergy‑cost reduction and digitalizationmeans that Signify’s product roadmap heavily influences market pricing, channel dynamics, and the speed at which newer form factors such as OLED‑based panels achieve scale.Beyond the market leader, a cadre of midsize innovators sustains competitive pressure. Osram and GE Lighting exploit legacy OEM relationships to introduce upgraded driver technologies that improve thermal management, while Cree differentiates through GaN‑on‑Silicon chips that push efficacy margins. Regional specialists such as Eaton Cooper (North America) and Lighting Science (Europe) focus on niche applications like high‑bay and horticultural lighting, carving out profitable pockets insulated from commoditization. Meanwhile, Acuity Brands, Hubbell, Feit Electric and Soraa maintain strong distributor networks that keep shelf‑space availability high, even as they vie for margin improvement through modular design and localized manufacturing. The resulting competitive mosaic blends scale‑driven pricing with differentiated product attributes, compelling all participants to balance cost efficiency against the need for rapid innovation.
List of Key Building Energy Efficient LED Companies Profiled
- Signify
- Osram
- GE Lighting
- Eaton Cooper
- Cree
- Lighting Science
- Acuity Brands
- Hubbell
- Feit Electric
- Soraa
- Philips Lighting
- Panasonic Lighting
Segment Analysis:
| Segment Category | Sub-Segments | Key Insights |
| By Type |
|
LED Bulb Light
|
| By Application |
|
Commercial Building
|
| By End User |
|
Facility Managers
|
| By Fixture Form Factor |
|
Integrated Fixtures
|
| By Smart Integration |
|
IoT Connected
|
Regional Analysis: Building Energy Efficient LED Market
Europe
The EU’s Energy Efficiency Directive mandates periodic performance inspections, compelling building owners to adopt LED solutions that meet verifiable efficiency thresholds. This regulatory cadence generates a predictable pipeline of retrofit projects, especially in the office and retail sectors where energy savings directly affect operating margins.
Deployments increasingly pair LEDs with IoT‑enabled controls, enabling occupancy‑based dimming and daylight harvesting. The convergence of lighting and data analytics opens ancillary revenue streams for service providers, while offering occupants more responsive environments.
To meet demand spikes and reduce carbon exposure, several European manufacturers are scaling domestic assembly lines. This shift shortens delivery cycles, improves compliance oversight, and aligns with broader reshoring trends within the lighting sector.
Heritage projects demand LEDs that respect architectural aesthetics while delivering efficiency. Companies that can blend low‑profile optics with high CRI values are securing contracts that would otherwise remain with specialty lighting firms.
North America
In the United States and Canada, corporate sustainability pledges and state‑level energy codes drive Building Energy Efficient LED Market forward. Large‑scale campus retrofits are common, with facilities managers prioritising solutions that deliver measurable cost avoidance. The market also sees a rise in private‑equity backed lighting as a service platforms, which bundle hardware, installation and ongoing performance monitoring into a single contract, reducing capital barriers for adopters. Consumer awareness around “green building” certifications such as LEED further nudges developers toward LED specifications that enhance indoor environmental quality while supporting marketable sustainability narratives.
Asia‑Pacific
Rapid urbanisation across China, India, and Southeast Asia fuels demand for energy‑saving lighting in new constructions. Governments are embedding LED mandates within building codes, yet the region grapples with fragmented standards, creating opportunities for firms that can navigate local compliance landscapes. Meanwhile, the proliferation of smart city initiatives introduces networked LED installations that interface with traffic management and public safety systems, expanding the functional scope of lighting beyond illumination alone.
South America
Economic recovery efforts in Brazil, Argentina and Chile increasingly view energy‑efficient LEDs as a lever for fiscal stability. Public‑sector budgeting cycles allocate funds for municipal street‑light upgrades, while private developers adopt LEDs to differentiate projects in competitive real‑estate markets. Supply constraints persist, prompting import reliance, but emerging regional manufacturers are leveraging lower labor costs to establish footholds, particularly in modular LED panels designed for high‑rise residential blocks.
Middle East & Africa
Building Energy Efficient LED Market in this diverse territory is shaped by two contrasting forces: ambitious sustainability roadmaps in Gulf Cooperation Council states and constrained fiscal environments elsewhere. In the Gulf, flagship developments incorporate sophisticated lighting controls linked to renewable energy sources, showcasing the region’s capacity for high‑tech implementations. Conversely, Sub‑Saharan nations prioritize basic efficiency upgrades, often supported by international development programs that subsidise LED distribution in schools and health clinics, laying a foundation for broader market expansion.
Report Scope
This market research report provides a comprehensive analysis of the Building Energy Efficient LED Market , covering the forecast period 2026–2034. It offers detailed insights into market dynamics, technological advancements, competitive landscape, and key trends shaping the industry.
Key focus areas of the report include:
- Market Overview: The report begins with an overview outlining its current market scenario, key growth indicators, and industry transformation drivers. It discusses macroeconomic factors, demand–supply balance, regulatory landscape, and the strategic role of semiconductors in powering advancements across industries such as automotive, telecommunications, consumer electronics, and industrial automation.
- Market Size & Forecast: Historical data and future projections for revenue, unit shipments, and market value across major regions and segments.
- Segmentation Analysis: Detailed breakdown by product type, technology, application, and end-user industry to identify high-growth segments and investment opportunities.
- Regional Insights: Insights into market performance across North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa, including country-level analysis where relevant.
- Competitive Landscape: Profiles of leading market participants, including their product offerings, R&D focus, manufacturing capacity, pricing strategies, and recent developments such as mergers, acquisitions, and partnerships.
- Technology Trends & Innovation: Assessment of emerging technologies, integration of AI/IoT, semiconductor design trends, fabrication techniques, and evolving industry standards.
- Market Drivers & Restraints: Evaluation of factors driving market growth along with challenges, supply chain constraints, regulatory issues, and market-entry barriers.
- Stakeholder Insights: Insights for component suppliers, OEMs, system integrators, investors, and policymakers regarding the evolving ecosystem and strategic opportunities.
Primary and secondary research methods are employed, including interviews with industry experts, data from verified sources, and real-time market intelligence to ensure the accuracy and reliability of the insights presented.
FREQUENTLY ASKED QUESTIONS:
What is the current market size of Building Energy Efficient LED Market?
-> Building Energy Efficient LED Market was valued at USD million in 2024 and is expected to reach USD million by 2031, growing at a CAGR of % during the forecast period.
Which key companies operate in Building Energy Efficient LED Market?
-> Key players include Signify, Osram, GE Lighting, Eaton Cooper, Cree, Lighting Science, Acuity Brands, Hubbell, Feit Electric, Soraa.
What are the key growth drivers?
-> Key growth drivers include energy‑efficiency regulations, rising construction activity, decreasing LED component costs, and increasing sustainability commitments by governments and corporations.
Which region dominates the market?
-> North America leads the market, driven primarily by the United States, while Asia, especially China, exhibits rapid growth potential.
What are the emerging trends?
-> Emerging trends include smart and connected lighting, integration of AI/IoT for adaptive lighting control, and advanced phosphor technologies improving luminous efficacy.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF