Key Statistics
Key Takeaways
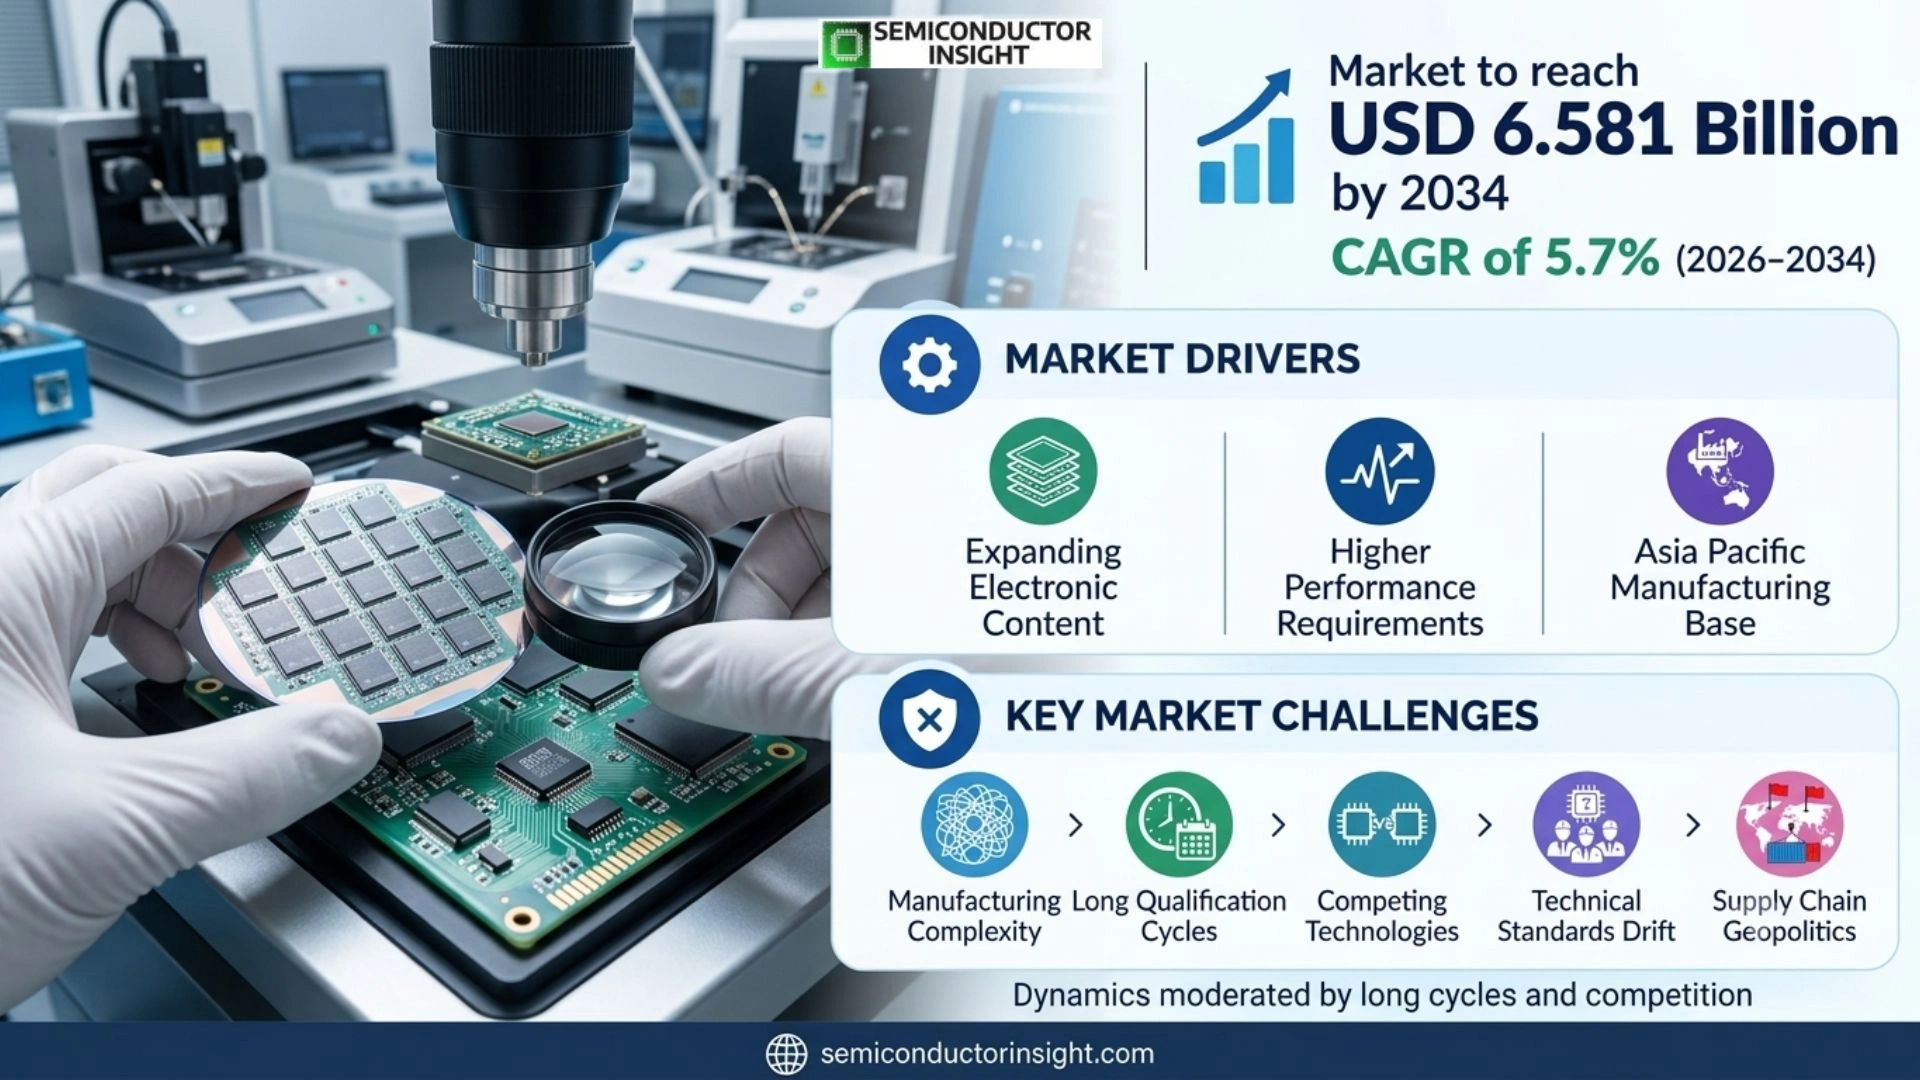
- The TV Tuner IC Market was valued at USD 3.995 billion in the 2025 base year and is projected to reach USD 6.581 billion by 2034, expanding at a 5.7% CAGR during 2026–2034.
- 5th Generation Silicon Tuner ICs is a leading product grouping because customers value qualified performance, integration readiness, and lifecycle support.
- Smart TVs and Set-top Boxes is a major demand centre, while adjacent uses broaden the addressable opportunity.
- Asia Pacific leads the regional market through concentrated manufacturing, customers, and technology investment.
- Reliability, qualification, software or service, and total ownership economics shape competition.
TV Tuner IC Market Overview
TV Tuner IC Market was valued at USD 3.995 billion in 2025 and is projected to reach USD 6.581 billion by 2034, growing at a CAGR of 5.7% during 2026–2034. Asia Pacific held the largest regional position in 2025, supported by concentrated manufacturing, downstream electronics production and established component supply networks.
TV tuner ICs convert terrestrial, cable, satellite, or hybrid broadcast signals into the digital data used by televisions, set-top boxes, automotive receivers, and other display systems. Modern devices integrate RF tuning, filtering, signal conversion, demodulation support, low-noise amplification, and software-configurable standards in compact semiconductor packages. Product value depends on sensitivity, selectivity, power consumption, multi-standard support, integration, and long-term availability.
The 2026 estimated year begins with demand from smart TVs, digital-terrestrial transitions, set-top-box replacement, automotive entertainment, hospitality displays, and broadcast infrastructure. Customers increasingly require tuners that support high-definition signals, difficult multipath environments, low standby power, and regional standards without adding board space. Streaming changes the usage mix but also creates demand for hybrid broadcast-broadband architectures.
Competition is shaped by standards coverage, RF performance, software configurability, package integration, cost, qualification, and supply continuity. OEMs evaluate the tuner together with demodulators, codecs, system-on-chip devices, antennas, power management, and firmware. Suppliers that combine strong reception with simple reference designs and global regulatory support can win design slots across several device generations.
Segment Analysis: By Type
By type, the TV Tuner IC market is segmented into 5th Generation Silicon Tuner ICs · 6th Generation Silicon Tuner ICs · Hybrid and Other Advanced Tuner ICs. Each category represents a different degree of integration, qualification burden and value capture, so suppliers compete through a combination of material performance, design support, manufacturing consistency, package architecture and application-specific testing rather than through unit price alone. Procurement also reflects lifecycle support, interoperability, compliance evidence, warranty exposure, and the cost of unsuccessful qualification.
| Type | Market relevance |
|---|---|
| 5th Generation Silicon Tuner ICs | Distinct performance, condition, integration, and qualification requirements shape demand and supplier positioning. |
| 6th Generation Silicon Tuner ICs | Distinct performance, condition, integration, and qualification requirements shape demand and supplier positioning. |
| Hybrid and Other Advanced Tuner ICs | Distinct performance, condition, integration, and qualification requirements shape demand and supplier positioning. |
Segment Analysis: By Application
By application, the market covers Smart TVs and Set-top Boxes · Digital Broadcasting Equipment · Automotive Infotainment · Other Consumer Electronics. Demand varies by production volume and qualification intensity: consumer programmes reward scale and miniaturisation, while automotive, industrial, aerospace, medical or security designs place greater weight on reliability evidence, long product availability and system-level performance under demanding operating conditions. Channel design, documentation, service coverage, and total ownership economics further determine which application converts technical interest into repeat purchasing.
| Application | Market relevance |
|---|---|
| Smart TVs and Set-top Boxes | Purchasing criteria reflect use-case economics, technical requirements, warranty expectations, and channel support. |
| Digital Broadcasting Equipment | Purchasing criteria reflect use-case economics, technical requirements, warranty expectations, and channel support. |
| Automotive Infotainment | Purchasing criteria reflect use-case economics, technical requirements, warranty expectations, and channel support. |
| Other Consumer Electronics | Purchasing criteria reflect use-case economics, technical requirements, warranty expectations, and channel support. |
Regional Analysis
Asia Pacific is the largest regional market for TV Tuner IC products, combining an established component-production ecosystem with major downstream customers. North America and Europe are strategically important for premium, automotive, aerospace, industrial and specialised applications, while South America and Middle East & Africa are primarily import- and project-led markets where distributor reach, local support and supply continuity shape vendor selection.
How does regional demand differ across this market?
For TV Tuner IC, Asia Pacific holds the largest position, supported by an established customer base, supplier presence, and mature purchasing channels. Europe contributes regulation, industrial demand, and technical expertise, while Asia Pacific combines electronics manufacturing, large device populations, and expanding engineering capability. South America and the Middle East and Africa develop through targeted infrastructure, enterprise, research, consumer, or public-sector programs rather than uniform adoption.
| Region | Position |
|---|---|
| North America | Developing demand shaped by local applications, channels, and qualification conditions |
| Europe | Developing demand shaped by local applications, channels, and qualification conditions |
| Asia Pacific | Largest and most established demand base |
| South America | Developing demand shaped by local applications, channels, and qualification conditions |
| Middle East & Africa | Developing demand shaped by local applications, channels, and qualification conditions |
Key TV Tuner IC Manufacturers and Competitive Landscape
The TV Tuner IC competitive landscape includes global technology leaders, diversified semiconductor or component groups, RF and imaging specialists, and regional manufacturers. The report profiles every named company across product positioning, manufacturing footprint, application exposure, recent development activity and strategic strengths; the complete coverage list is reproduced below so the intended company universe is explicit.
The competitive landscape covers Skyworks Solutions, STMicroelectronics, MaxLinear, NXP Semiconductors, Infineon Technologies, Silicon Laboratories, Analog Devices, and AltoBeam. The report profiles their tuner architectures, standards support, product generations, application exposure, customer focus, regional reach, and recent development activity. The analysis also considers qualification requirements, supplier capability, regional purchasing conditions, technology substitution, operating economics, implementation risk, customer procurement cycles, lifecycle support, regulatory context, and evidence required for sustained commercial adoption through the forecast period.
Suppliers compete on sensitivity, selectivity, noise figure, interference rejection, power, package size, multi-standard support, software configuration, automotive qualification, price, and lifecycle support. Digital and hybrid tuners can command value when they reduce board complexity or improve reception in dense RF environments, while cost-sensitive products compete through integration and high-volume manufacturing.
Key companies profiled
- Skyworks Solutions
- STMicroelectronics
- MaxLinear
- NXP Semiconductors
- Infineon Technologies
- Silicon Laboratories
- Analog Devices
- AltoBeam
TV Tuner IC Production Capacity Analysis
Production capacity is a material competitive factor in the TV Tuner IC market because electrical performance depends on specialised processes, qualified materials, repeatable yields and application-specific test capability. Capacity cannot be assessed only by nominal factory floor area: effective supply is the output that passes dimensional, electrical, reliability and customer qualification requirements at the required product mix.
Production capacity depends on RF CMOS wafers, precision passive components, package substrates, test equipment, reference designs, firmware validation, and semiconductor assembly. Effective capacity is qualified IC output that meets sensitivity, linearity, phase-noise, power, electromagnetic compatibility, and regional-standard requirements. The analysis also considers qualification requirements, supplier capability, regional purchasing conditions, technology substitution, operating economics, implementation risk, customer procurement cycles, lifecycle support, regulatory context, and evidence required for sustained commercial adoption through the forecast period.
Multi-standard devices require extensive RF and software testing across frequencies, modulation schemes, interference conditions, and regional broadcast rules. Suppliers improve throughput through reusable silicon platforms, automated calibration, common firmware, and external assembly partnerships, although customer-specific variants can lengthen validation. The analysis also considers qualification requirements, supplier capability, regional purchasing conditions, technology substitution, operating economics, implementation risk, customer procurement cycles, lifecycle support, regulatory context, and evidence required for sustained commercial adoption through the forecast period.
Support capacity includes reference boards, antenna matching, driver software, certification assistance, failure analysis, and long-term product availability. OEMs value rapid application engineering because a tuner issue can delay a complete television or vehicle program. The analysis also considers qualification requirements, supplier capability, regional purchasing conditions, technology substitution, operating economics, implementation risk, customer procurement cycles, lifecycle support, regulatory context, and evidence required for sustained commercial adoption through the forecast period.
TV Tuner IC Market Dynamics: Drivers, Restraints and Opportunities
TV Tuner IC market growth reflects expanding electronic content and higher performance requirements, moderated by manufacturing complexity, long qualification cycles and competing technologies. The impact ranges below are directional analytical estimates rather than additive forecasts; they show the relative pressure each factor can place on the baseline CAGR when other assumptions remain broadly stable.
TV tuner IC demand reflects digital broadcasting, smart-TV penetration, set-top-box renewal, automotive displays, and hybrid broadcast-broadband products. Streaming reduces reliance on traditional linear reception in some households, but terrestrial and satellite reception remains important for live events, public alerts, local channels, and markets where broadband access is uneven. The analysis also considers qualification requirements, supplier capability, regional purchasing conditions, technology substitution, operating economics, implementation risk, customer procurement cycles, lifecycle support, regulatory context, and evidence required for sustained commercial adoption through the forecast period.
Architectural tradeoffs include discrete tuners versus integrated receiver SoCs, single-standard versus multi-standard products, and high performance versus low cost. AI-assisted interference mitigation, software-configurable standards, low-power standby, and compact RF integration create product differentiation. The analysis also considers qualification requirements, supplier capability, regional purchasing conditions, technology substitution, operating economics, implementation risk, customer procurement cycles, lifecycle support, regulatory context, and evidence required for sustained commercial adoption through the forecast period.
MARKET DRIVERS
Drivers Impact Analysis*
| Driver | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Digital broadcast transition | +1.7% | Asia Pacific, Latin America, Middle East & Africa | Medium term (2–4 years) |
| Smart TV and set-top-box replacement | +1.3% | Global consumer markets | Short term (≤2 years) |
| Automotive infotainment and rear-seat displays | +0.9% | Europe, China, Japan, North America | Long term (≥4 years) |
| 4K/8K and high-dynamic-range reception | +0.7% | North America, Europe, Asia Pacific | Medium term (2–4 years) |
| Hybrid broadcast-broadband architectures | +0.6% | Global connected-TV markets | Medium term (2–4 years) |
| Low-power multi-standard integration | +0.4% | Global OEM programs | Short term (≤2 years) |
Digital broadcast transition is influencing demand, investment and adoption across the Asia Pacific, Latin America, Middle East & Africa region over the medium term (2–4 years). The analysis also considers qualification requirements, supplier capability, regional purchasing conditions, technology substitution, operating economics, implementation risk, customer procurement cycles, lifecycle support, regulatory context, and evidence required for sustained commercial adoption through the forecast period.
Smart TV and set-top-box replacement is influencing demand, investment and adoption across the Global consumer markets region over the short term (≤2 years). The analysis also considers qualification requirements, supplier capability, regional purchasing conditions, technology substitution, operating economics, implementation risk, customer procurement cycles, lifecycle support, regulatory context, and evidence required for sustained commercial adoption through the forecast period.
Automotive infotainment and rear-seat displays is influencing demand, investment and adoption across the Europe, China, Japan, North America region over the long term (≥4 years). The analysis also considers qualification requirements, supplier capability, regional purchasing conditions, technology substitution, operating economics, implementation risk, customer procurement cycles, lifecycle support, regulatory context, and evidence required for sustained commercial adoption through the forecast period.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Restraint | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| OTT streaming substitution | −1.5% | North America, Europe, developed Asia | Persistent |
| Fragmented regional broadcast standards | −1.0% | Global tuner suppliers | Persistent |
| Low margins in mature consumer devices | −0.8% | Price-sensitive markets | Medium term (2–4 years) |
| Long OEM qualification cycles | −0.6% | Automotive and television programs | Medium term (2–4 years) |
| RF component and semiconductor supply risk | −0.5% | Cross-border supply chains | Short term (≤2 years) |
OTT streaming substitution can delay purchasing, reduce utilisation, or increase qualification and lifecycle cost for north america, europe, developed asia customers over the persistent. The analysis also considers qualification requirements, supplier capability, regional purchasing conditions, technology substitution, operating economics, implementation risk, customer procurement cycles, lifecycle support, regulatory context, and evidence required for sustained commercial adoption through the forecast period.
Fragmented regional broadcast standards can delay purchasing, reduce utilisation, or increase qualification and lifecycle cost for global tuner suppliers customers over the persistent. The analysis also considers qualification requirements, supplier capability, regional purchasing conditions, technology substitution, operating economics, implementation risk, customer procurement cycles, lifecycle support, regulatory context, and evidence required for sustained commercial adoption through the forecast period.
Low margins in mature consumer devices can delay purchasing, reduce utilisation, or increase qualification and lifecycle cost for price-sensitive markets customers over the medium term (2–4 years). The analysis also considers qualification requirements, supplier capability, regional purchasing conditions, technology substitution, operating economics, implementation risk, customer procurement cycles, lifecycle support, regulatory context, and evidence required for sustained commercial adoption through the forecast period.
MARKET OPPORTUNITIES
Hybrid broadcast-broadband receivers, ATSC 3.0, DVB-T2, ISDB, automotive entertainment, public-alert reception, hospitality televisions, and digital-transition programs create opportunities. The analysis also considers qualification requirements, supplier capability, regional purchasing conditions, technology substitution, operating economics, implementation risk, customer procurement cycles, lifecycle support, regulatory context, and evidence required for sustained commercial adoption through the forecast period.
Software-configurable tuners can reduce SKU fragmentation and support regional standards from a common silicon platform. Reference designs, low-power modes, integrated demodulation, and interference mitigation can raise value per device. The analysis also considers qualification requirements, supplier capability, regional purchasing conditions, technology substitution, operating economics, implementation risk, customer procurement cycles, lifecycle support, regulatory context, and evidence required for sustained commercial adoption through the forecast period.
Emerging markets with expanding digital terrestrial coverage need low-cost, reliable tuners and local technical support. Suppliers that coordinate with broadcasters, OEMs, antenna companies, and system-chip vendors can accelerate design adoption. The analysis also considers qualification requirements, supplier capability, regional purchasing conditions, technology substitution, operating economics, implementation risk, customer procurement cycles, lifecycle support, regulatory context, and evidence required for sustained commercial adoption through the forecast period.
TV Tuner IC Supply Chain Analysis
The TV Tuner IC supply chain links specialty materials and wafer or ceramic processing equipment to high-precision manufacturing, packaging, distribution and downstream system integration. Commercial resilience depends on qualified alternate materials, realistic yield assumptions, geographic redundancy and traceable process controls because a nominal second source is not interchangeable until the customer has validated electrical behaviour, reliability and package compatibility.
The supply chain includes RF CMOS wafers, filters, oscillators, package substrates, leadframes, test equipment, firmware, reference boards, antennas, demodulators, codecs, and system-on-chip devices. IC suppliers design and qualify the tuner before integration by television, set-top-box, automotive, and broadcast-equipment manufacturers. The analysis also considers qualification requirements, supplier capability, regional purchasing conditions, technology substitution, operating economics, implementation risk, customer procurement cycles, lifecycle support, regulatory context, and evidence required for sustained commercial adoption through the forecast period.
Resilience requires multiple assembly and test sources, long-lived process nodes, software maintenance, regional inventory, and careful change control. A change in RF process, package, firmware, or calibration can alter reception performance and trigger customer requalification. The analysis also considers qualification requirements, supplier capability, regional purchasing conditions, technology substitution, operating economics, implementation risk, customer procurement cycles, lifecycle support, regulatory context, and evidence required for sustained commercial adoption through the forecast period.
Recent Developments in the TV Tuner IC Market
Developments tracked to September 2026 and linked to official company or industry sources.
- July 2026 Published
MaxLinear’s current portfolio continues to target broadband and connectivity applications where highly integrated mixed-signal devices support compact consumer and infrastructure designs. Source - January 2025 Published
Skyworks continued to present RF and connectivity technologies for consumer and communications applications, relevant to tuner integration and front-end performance. Source - January 2025 Published
NXP’s silicon tuner documentation supports terrestrial and cable digital-TV reception in compact receiver designs. Source - July 2013 Published
MaxLinear introduced a software-programmable hybrid television tuner designed for low power and global broadcast support. Source - June 2012 Published
Silicon Labs announced low-power digital set-top-box tuner ICs integrating global standards and consuming less than 500 mW, illustrating the continuing value of compact silicon tuning. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2021–2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Year | 2034 |
| Historical Period | 2021–2025 |
| Market Size 2025 | USD 3.995 billion |
| Market Size 2034 | USD 6.581 billion |
| Growth Rate | CAGR of 5.7% from 2026–2034 |
| Unit | Value in USD billion and shipment or production volume where disclosed |
| Segmentation | By Type, By Application, additional technology axis and By Region |
| By Type | 5th Generation Silicon Tuner ICs · 6th Generation Silicon Tuner ICs · Hybrid and Other Advanced Tuner ICs |
| By Application | Smart TVs and Set-top Boxes · Digital Broadcasting Equipment · Automotive Infotainment · Other Consumer Electronics |
| By End-user and Integration Level | Consumer Electronics · Automotive · Broadcasting Equipment · Discrete Tuner ICs · Integrated Receiver SoCs |
| By Region | Each region analysed by type, application and countryNorth AmericaU.S., Canada, MexicoEuropeGermany, France, U.K., Italy, Nordic Countries, BeneluxAsia PacificChina, Japan, South Korea, India, Southeast AsiaSouth AmericaBrazil, Argentina, Rest of South AmericaMiddle East & AfricaTurkey, Israel, Saudi Arabia, UAE, Rest of MEA |
| Key Companies Profiled | Skyworks Solutions; STMicroelectronics; MaxLinear; NXP Semiconductors; Infineon Technologies; Silicon Laboratories; Analog Devices; AltoBeam |
| Customization Scope | Free report customization equivalent to up to four analyst working days with purchase, including additions or alterations to country, regional and segment coverage. |
Frequently Asked Questions
What is a TV tuner IC?
The TV Tuner IC Market is valued at USD 3.995 billion in the 2025 base year and is projected to reach USD 6.581 billion by 2034, expanding at a CAGR of 5.7% during 2026–2034. The outlook covers fifth- and sixth-generation silicon tuners, hybrid receivers, digital broadcasting equipment, smart televisions, set-top boxes, automotive infotainment, and other consumer electronics, with Asia Pacific holding the leading regional position.
What is the market outlook through 2034?
Demand should expand through 2034 as digital broadcasting transitions continue, smart-TV and set-top-box platforms are refreshed, automotive entertainment systems add reception capability, and hybrid broadcast-broadband architectures develop. Standard fragmentation, streaming substitution, low consumer-electronics margins, and long OEM qualification cycles will keep design wins dependent on low power, multi-standard support, RF performance, and stable supply.
Which product type leads?
5th-generation silicon tuner ICs lead broad volume because they balance performance, integration, and cost. 6th-generation devices gain share where 4K/8K, difficult RF conditions, software configuration, or automotive qualification justify higher performance. Hybrid products serve markets with mixed standards or broadcast and broadband delivery. The analysis also considers qualification requirements, supplier capability, regional purchasing conditions, technology substitution, operating economics, implementation risk, customer procurement cycles, lifecycle support, regulatory context, and evidence required for sustained commercial adoption through the forecast period.
Which applications create demand?
Smart TVs, set-top boxes, digital-broadcast equipment, automotive entertainment, hospitality displays, and other consumer electronics create demand. Automotive and broadcast programs have longer qualification cycles, while consumer devices prioritize low cost, compact packages, low standby power, and rapid standards support. The analysis also considers qualification requirements, supplier capability, regional purchasing conditions, technology substitution, operating economics, implementation risk, customer procurement cycles, lifecycle support, regulatory context, and evidence required for sustained commercial adoption through the forecast period.
Why does Asia Pacific lead?
Asia Pacific combines television and set-top-box manufacturing, semiconductor assembly, broadcast infrastructure, device brands, and digital-transition programs. North America and Europe contribute premium televisions, automotive electronics, and advanced broadcast standards, while emerging markets create demand as terrestrial coverage expands. The analysis also considers qualification requirements, supplier capability, regional purchasing conditions, technology substitution, operating economics, implementation risk, customer procurement cycles, lifecycle support, regulatory context, and evidence required for sustained commercial adoption through the forecast period.
What drives growth?
Digital broadcast migration, smart-TV replacement, high-definition reception, automotive displays, hybrid receivers, low-power design, and multi-standard silicon drive growth. Public-alert systems and live local content preserve demand for broadcast reception even as streaming changes daily viewing habits. The analysis also considers qualification requirements, supplier capability, regional purchasing conditions, technology substitution, operating economics, implementation risk, customer procurement cycles, lifecycle support, regulatory context, and evidence required for sustained commercial adoption through the forecast period.
What limits adoption?
Streaming substitution, fragmented standards, mature-device pricing, long OEM qualifications, and RF supply risks limit adoption. Suppliers must support several regional standards while maintaining sensitivity, interference rejection, low power, and reliable firmware without materially increasing bill-of-materials cost. The analysis also considers qualification requirements, supplier capability, regional purchasing conditions, technology substitution, operating economics, implementation risk, customer procurement cycles, lifecycle support, regulatory context, and evidence required for sustained commercial adoption through the forecast period.
How do suppliers compete?
Suppliers compete on sensitivity, selectivity, noise, power, package size, standards coverage, software, automotive qualification, reference designs, price, and lifecycle support. Integrated tuners that simplify board design and reduce calibration work can win against lower-priced discrete alternatives. The analysis also considers qualification requirements, supplier capability, regional purchasing conditions, technology substitution, operating economics, implementation risk, customer procurement cycles, lifecycle support, regulatory context, and evidence required for sustained commercial adoption through the forecast period.
Where are the best opportunities?
Hybrid broadcast-broadband receivers, ATSC 3.0, DVB-T2, ISDB, automotive entertainment, hospitality, public-alert reception, and emerging digital-transition markets offer opportunities. Software-configurable platforms and low-cost reference designs can expand adoption across regional OEMs. The analysis also considers qualification requirements, supplier capability, regional purchasing conditions, technology substitution, operating economics, implementation risk, customer procurement cycles, lifecycle support, regulatory context, and evidence required for sustained commercial adoption through the forecast period.
Which companies are covered?
The report covers Skyworks Solutions, STMicroelectronics, MaxLinear, NXP Semiconductors, Infineon Technologies, Silicon Laboratories, Analog Devices, and AltoBeam. Profiles assess product generations, standards, RF performance, applications, supply, partnerships, and strategic positioning. The analysis also considers qualification requirements, supplier capability, regional purchasing conditions, technology substitution, operating economics, implementation risk, customer procurement cycles, lifecycle support, regulatory context, and evidence required for sustained commercial adoption through the forecast period.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF