SEMICONDUCTOR INSIGHT
MARKET RESEARCH REPORT

HMI Chip Market

2026 to 2034
MARKET INTELLIGENCE
ACROSS KEY REGIONS
2026 EDITION
CHIP Semiconductor Market Research

HMI Chip Market

Size, Share & Industry Analysis, By Type (Industrial Grade, Consumer Grade), By Application (Consumer Electronics, Industrial Control, Automotive, Medical Devices), By Function (Graphics/Display Processing, Touch Processing, Multimedia, Connectivity & Control), By Interface (MIPI/LVDS, RGB/LCD, CAN/Ethernet, I2C/SPI), and Regional Forecast, 2026-2034

◷
UPDATED 08 October 2026
▤
REPORT LENGTH Detailed Report
▣
REPORT CODE 39e935e6bebc
▯
FORMATS PDF

HMI chip market was valued at USD 2.12 billion in 2025 and is projected to reach USD 4.67 billion by 2034, growing at a CAGR of 8.2% over the 2026–2034 forecast period. Asia Pacific held the largest regional position in 2025, while Asia Pacific has the strongest growth profile.

Get the sample PDF with study scope, segmentation and methodology details.

Key Statistics

2025 Market Size
USD 2.12 billion
2034 Projected Market Size
USD 4.67 billion
CAGR (2026–2034)
8.2%
Largest Market in 2025
Asia Pacific

Key Takeaways

  • Industrial Grade is a leading product category because it addresses the largest current application base.
  • Consumer Electronics is a major application, with demand shaped by performance, reliability and system integration.
  • Asia Pacific leads current market value, while Asia Pacific provides the strongest growth profile.
  • Higher-resolution displays, smarter touch processing and greater graphics/control integration is the main technology direction influencing new design wins.
  • Market size and growth: USD 2.12 billion in 2025 is projected to reach USD 4.67 billion by 2034 at a 8.2% CAGR during 2026–2034.

HMI Chip Market Overview

HMI chip market was valued at USD 2.12 billion in 2025 and is projected to reach USD 4.67 billion by 2034, growing at a CAGR of 8.2% over the 2026–2034 forecast period. Asia Pacific held the largest regional position in 2025, while Asia Pacific has the strongest growth profile.

Base year: 2025 · Estimated year: 2026 · Forecast period: 2026–2034 · Historical data: 2021–2025 · Values in USD

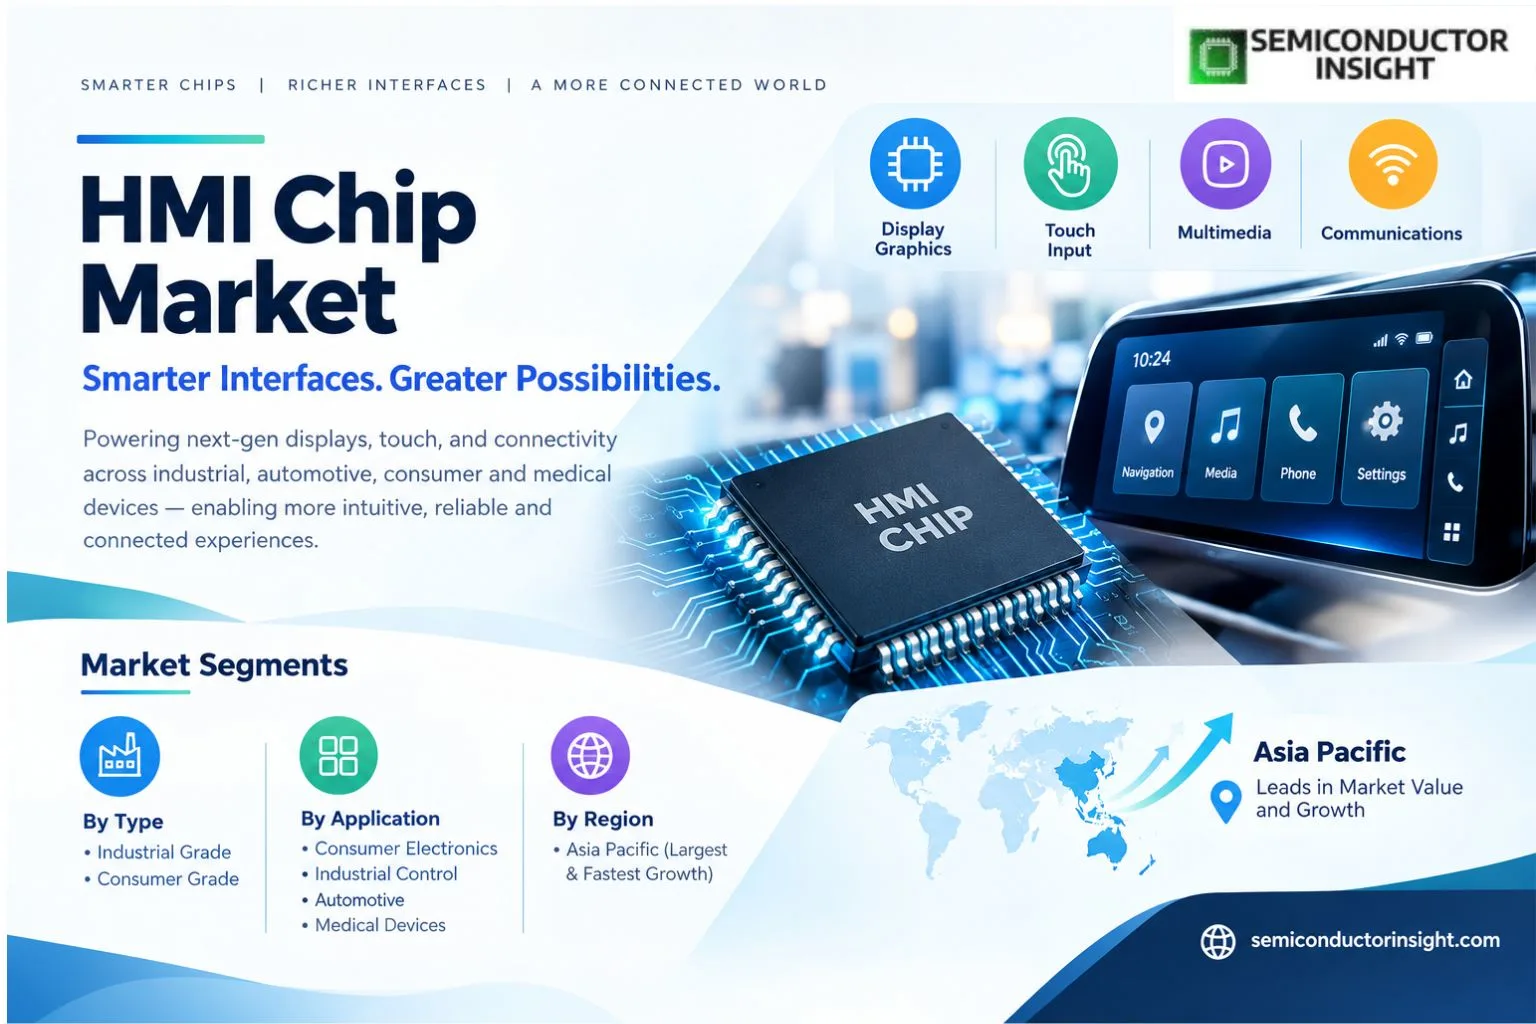
 HMI chips process display graphics, touch input, multimedia and communications for human-machine interfaces used in industrial controls, vehicles, consumer electronics and medical devices. Commercial decisions in the HMI Chip market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.

The client evidence values the market at USD 2.12 billion in 2025, USD 2.31 billion in 2026 and USD 4.67 billion by 2034 at an 8.2% CAGR. Asia Pacific has the strongest growth profile because of electronics manufacturing, vehicle production and industrial automation. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.

NXP’s current HMI portfolio spans embedded processors, LCD drivers and automotive touch controllers. Its S32T family supports next-generation cockpit displays and smart surfaces with up to 20 simultaneous touch points, display support up to 20 inches and automotive qualification. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.

Segment Analysis: By Type

By type, the HMI chip market is segmented into Industrial Grade, Consumer Grade. Each category has a distinct functional role and commercial position, so the analysis emphasizes use case, integration and competitive relevance rather than repeating a single market statistic across every row. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.

Type Function Market position
Industrial Grade Industrial Grade addresses a distinct architecture or performance requirement within the HMI Chip market. Commercial demand depends on application fit, qualification, cost and lifecycle requirements rather than a single headline statistic.
Consumer Grade Consumer Grade addresses a distinct architecture or performance requirement within the HMI Chip market. Commercial demand depends on application fit, qualification, cost and lifecycle requirements rather than a single headline statistic.

Pricing by type

Industrial-grade HMI chips command premiums through extended temperature, lifecycle support and qualification, while consumer-grade devices compete more heavily on graphics performance and cost. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment. Commercial decisions in the HMI Chip market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.

Segment Analysis: By Application

By application, the market is segmented into Consumer Electronics, Industrial Control, Automotive, Medical Devices. Application economics differ by qualification, lifecycle, reliability and system-level value, so each row below uses context specific to that application rather than mechanically repeating headline evidence. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.

Application Demand characteristics
Consumer Electronics Consumer Electronics creates demand where HMI chip improves integration, performance, reliability or system economics.
Industrial Control Industrial Control creates demand where HMI chip improves integration, performance, reliability or system economics.
Automotive Automotive creates demand where HMI chip improves integration, performance, reliability or system economics.
Medical Devices Medical Devices creates demand where HMI chip improves integration, performance, reliability or system economics.

HMI CHIP GROWTH AND OUTLOOK

Regional Analysis

Asia Pacific leads current market value, while Asia Pacific has the strongest growth profile. Regional demand is shaped by manufacturing concentration, technology adoption, customer investment cycles and local supplier ecosystems. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.

How does regional demand differ across the HMI chip market?

Asia Pacific provides the deepest manufacturing scale, North America contributes high-value technology and enterprise demand, and Europe remains important in industrial, automotive and regulated applications. South America and the Middle East & Africa are smaller but developing markets. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.

Region Position Growth outlook Demand profile What decides supplier selection
Asia Pacific Largest Highest consumer electronics, automotive displays and industrial automation Supply scale and qualification
North America High Moderate-high software-defined vehicles, industrial controls and premium HMIs Technology capability and service
Europe Moderate-high Moderate automotive cockpits, machinery and regulated industrial interfaces Compliance and lifecycle
South America Smaller Moderate Import/industrial led Cost and distribution
Middle East & Africa Smallest base Emerging Infrastructure led Project support

Asia Pacific LARGEST & FASTEST-GROWING

What shapes demand in Asia Pacific?

Asia Pacific demand is led by China, Japan, South Korea, Taiwan and India, with consumer electronics, automotive displays and industrial automation shaping the regional opportunity. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment. Commercial decisions in the HMI Chip market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.

Market positionLargest
Growth outlookHighest
Demand profileconsumer electronics, automotive displays and industrial automation
Market access gateSupply scale and qualification
Country Position in region What drives demand
China Largest scale Manufacturing and end-market demand.
Japan High-spec Technology and industrial applications.
South Korea Advanced electronics High-value manufacturing and digital infrastructure.
India High growth Infrastructure and enterprise adoption.

Market instances

  • Manufacturing scale supports fast commercialization. Local supply chains reduce lead times and qualification friction.
  • China and India expand the addressable base. Demand grows through infrastructure, industrialization and digital adoption.
In the full report: country-level market size, segment revenue, supplier analysis and forecast detail across 2021–2034.

North America HIGH-VALUE REGION

What shapes demand in North America?

North America is a high-value market where software-defined vehicles, industrial controls and premium hmis supports premium demand and early technology adoption. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.

Market positionHigh
Growth outlookModerate-high
Demand profilesoftware-defined vehicles, industrial controls and premium HMIs
Market access gateTechnology capability and service
Country Position in region What drives demand
United States Dominant Technology, enterprise and industrial demand.
Canada Established Industrial and communications applications.
Mexico Manufacturing support Electronics and automotive assembly.

Market instances

  • The United States anchors regional value. Large OEM, cloud and enterprise ecosystems support advanced deployments.
  • Supplier support matters. Customers value long lifecycle, integration and application engineering.
In the full report: country-level market size, segment revenue, supplier analysis and forecast detail across 2021–2034.

Europe HIGH-VALUE REGION

What shapes demand in Europe?

Europe is a technically demanding market where automotive cockpits, machinery and regulated industrial interfaces supports qualified, long-lifecycle products. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.

Market positionModerate-high
Growth outlookModerate
Demand profileautomotive cockpits, machinery and regulated industrial interfaces
Market access gateCompliance and lifecycle
Country Position in region What drives demand
Germany Largest Automotive and industrial applications.
France High-value Industrial, aerospace and digital systems.
United Kingdom Technology led Enterprise, telecom and research demand.
Italy Industrial Machinery and electronics applications.

Market instances

  • Qualification and compliance influence supplier selection. Customers emphasize reliability and support.
  • Industrial and automotive demand supports durable revenue. Long product cycles create sticky design wins.
In the full report: country-level market size, segment revenue, supplier analysis and forecast detail across 2021–2034.

South America

What shapes demand in South America?

South America is a smaller market led by Brazil, with demand concentrated in industrial modernization, telecom and imported systems. Commercial decisions in the HMI Chip market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.

Market positionSmaller
Growth outlookModerate
Demand profileImport/industrial led
Market access gateCost and distribution
Country Position in region What drives demand
Brazil Largest Industrial and electronics demand.
Argentina Niche Enterprise and industrial applications.
Rest of region Import led Demand follows infrastructure investment.

Market instances

  • Brazil anchors the regional opportunity. Local industry creates the largest addressable base.
  • Distribution and landed cost matter. Most advanced products rely on imported supply.
In the full report: country-level market size, segment revenue, supplier analysis and forecast detail across 2021–2034.

Middle East & Africa EMERGING

What shapes demand in Middle East & Africa?

Middle East & Africa is an emerging market where digital infrastructure, energy and industrial projects create selective demand. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.

Market positionSmallest base
Growth outlookEmerging
Demand profileInfrastructure led
Market access gateProject support
Country Position in region What drives demand
UAE Technology led Digital infrastructure and enterprise systems.
Saudi Arabia Growth market Infrastructure and industrial investment.
South Africa Industrial niche Automation and enterprise demand.

Market instances

  • Gulf projects support premium deployments. New infrastructure can adopt advanced architectures from the outset.
  • Regional demand is project-based. Supplier service and local integration remain important.
In the full report: country-level market size, segment revenue, supplier analysis and forecast detail across 2021–2034.

Key HMI Chip Manufacturers and Competitive Landscape

The competitive landscape includes Infineon Technologies, NXP Semiconductors, Texas Instruments, STMicroelectronics, Renesas Electronics, Microchip Technology, Anyka Microelectronics, Plinxinchi Technology, Ligong Technology, Yingshang Microelectronics. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment. Commercial decisions in the HMI Chip market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.

Competition centers on higher-resolution displays, smarter touch processing and greater graphics/control integration, customer qualification, manufacturing consistency and application support. Once a product is designed into a long-lifecycle system, switching costs can protect incumbent positions but also raise the importance of roadmap continuity. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.

Tier structure

Tier Companies Basis of competition
Tier 1 Infineon Technologies, NXP Semiconductors, Texas Instruments, STMicroelectronics Global scale, broad customer qualification and advanced technology portfolios.
Tier 2 Renesas Electronics, Microchip Technology, Anyka Microelectronics, Plinxinchi Technology Strong specialist capability, regional design wins and application-focused portfolios.
Tier 3 Regional and niche suppliers Cost competition, customization and specialized customer support.

Key companies profiled

  • Infineon Technologies
  • NXP Semiconductors
  • Texas Instruments
  • STMicroelectronics
  • Renesas Electronics
  • Microchip Technology
  • Anyka Microelectronics
  • Plinxinchi Technology
  • Ligong Technology
  • Yingshang Microelectronics

HMI Chip Production Capacity Analysis

Production capacity in the HMI Chip market is shaped by the underlying manufacturing process, qualification burden and customer-specific configuration. Suppliers must balance equipment utilization with quality control because high-volume output only creates value when yield, reliability and traceability remain stable. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.

Capacity additions tend to follow customer program ramps rather than headline market growth alone. Regional supply resilience is becoming more important, particularly where customers require second-source planning, long product lifecycles or shorter engineering-response times. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.

The practical bottleneck is often qualified output rather than nominal installed capacity. Manufacturing, assembly, test and application support must scale together to avoid creating capacity that cannot be used in production programs. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.

HMI Chip Market Dynamics: Drivers, Restraints and Opportunities

The HMI Chip market is shaped by growth is driven by software-defined vehicles, industrial digitalization, richer consumer interfaces and medical equipment requiring responsive graphics and touch. At the same time, growth is constrained by thermal limits, software complexity, long industrial qualification, display-interface fragmentation and price pressure in consumer applications. The strongest commercial opportunities are concentrated in automotive cockpit controllers, smart surfaces, edge-ai hmis and integrated graphics/touch processors create the strongest opportunities.

MARKET DRIVERS

Drivers Impact Analysis*

Driver (~) % impact on CAGR forecast Geographic relevance Impact timeline
Technology upgrade cycle +1.6% Global; strongest in leading adopter markets Near to medium term
End-market expansion +1.2% Application-specific Near term
Higher value per system +0.8% Premium and advanced systems Medium term

Technology adoption expands addressable demand

Technology upgrade cycle+1.6%Global; strongest in leading adopter marketsNear to medium termEnd-market expansion+1.2%Application-specificNear termHigher value per system+0.8%Premium and advanced systemsMedium term

Technology adoption expands addressable demand

Growth is driven by non-invasive health monitoring, AR/vision-assistance research and continuing advances in ultra-low-power ASIC design and flexible electronics. This demand is strongest where customers can measure a clear improvement in system performance, footprint, energy efficiency, reliability or operating cost. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.

End-market modernization increases content per system

The technology upgrade cycle supports replacement and redesign activity as OEMs move to higher-performance architectures. New designs typically create the best opportunity because suppliers can influence specifications before qualification is locked. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.

Higher-value architectures support premium mix

Expanding end markets also increase content per system, creating value growth even when unit shipments grow more slowly. Suppliers that combine engineering support with reliable supply are better positioned to capture those design transitions. Commercial decisions in the Semiconductor for Smart Contact Lenses market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.

MARKET RESTRAINTS

Restraints Impact Analysis*

Restraint (~) % impact on CAGR forecast Geographic relevance Impact timeline
Qualification and integration burden -0.7% Global Ongoing
Price and substitution pressure -0.5% Cost-sensitive applications Ongoing
Supply-chain or process complexity -0.4% Global Medium term

Qualification burden slows supplier switching

Growth is constrained by ocular safety, heat, power delivery, regulatory validation, data accuracy and the difficulty of packaging semiconductors inside soft, transparent lens materials. These constraints are most significant where customers have qualified alternatives or where the technology must prove a clear system-level advantage over lower-cost incumbent solutions. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.

Price competition limits margin expansion

Qualification and integration can extend sales cycles because customers must validate performance, reliability and compatibility in their own system environment. That makes early engineering engagement important for new suppliers. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.

Alternative technologies constrain selected use cases

Supply-chain complexity can also limit growth when specialized materials, tooling, test or regional support are required. Customers increasingly evaluate resilience alongside price when choosing long-lifecycle suppliers. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.

MARKET OPPORTUNITIES

Advanced integration creates premium opportunities

Glucose monitoring, intraocular-pressure sensing, AR display integration and multimodal ocular biosensing create the strongest opportunities. The most attractive opportunities are where customers are redesigning systems rather than simply replacing like-for-like components. Commercial decisions in the Semiconductor for Smart Contact Lenses market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.

Regional capacity and supply resilience

Ultra-low-power mixed-signal integration, wireless power and flexible biocompatible packaging can create premium value when it lowers system complexity, improves performance or supports a new product architecture that is difficult to achieve with incumbent approaches. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.

Application engineering deepens customer value

Regional engineering support and application-specific customization provide another route to growth because customers increasingly expect suppliers to support qualification, transition planning and lifecycle management. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.

Semiconductor for Smart Contact Lenses Supply Chain Analysis

Upstream. Ultra-low-power CMOS, flexible interconnects, biosensors, antennas, encapsulation, wireless power circuits and biocompatibility validation form the supply chain. Supply quality at this stage directly affects downstream yield, reliability and cost. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.

UpstreamElectromechanical relays, microcontrollers, passive components, moulded housings, DIN clips, terminal blocks
ManufacturingPCB assembly, housing moulding, calibration and functional test, approval marking
ChannelElectrical wholesalers, industrial distributors, catalogue houses, direct OEM supply
DownstreamPanel builders, machine OEMs, electrical contractors, facility maintenance, utilities

Manufacturing. Core production combines process control, assembly, inspection and test, with product-specific qualification used to verify performance before customer shipment. Commercial decisions in the Semiconductor for Smart Contact Lenses market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.

Distribution. High-value programs are typically won through direct OEM, Tier-1 or design-house engagement, while distributors serve prototypes, regional customers and lower-volume applications. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.

Downstream. End users integrate the product into systems where switching costs rise after qualification, making lifecycle support and supply continuity commercially important. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.

Downstream. Panel builders and machine OEMs are the primary specifying customers, followed by electrical contractors working on building services and by facility maintenance teams handling replacement. The specification decision is usually made once, at panel design, and then repeats for the life of the design — which makes design-in position considerably more valuable than any individual transaction.

Recent Developments in the Semiconductor for Smart Contact Lenses Market

Developments tracked through September 2026. Items are selected for direct relevance to product technology, deployment or standards. Commercial decisions in the Semiconductor for Smart Contact Lenses market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.

  • 2026 Current
    Smart-contact-lens ASIC development continues The adjacent glucose-sensor ASIC market remains focused on ultra-low-power sensing, wireless power and flexible integration for non-invasive monitoring. Source
  • 2026 Current
    Flexible medical electronics expand Semiconductor miniaturization and flexible substrate integration continue improving the feasibility of electronics embedded in ocular wearables. Source
  • 2026 Current
    Low-power sensor integration remains critical Smart-lens designs increasingly combine sensor readout, wireless communication and power management within tiny thermal budgets. Source

REPORT SCOPE & SEGMENTATION

Attribute Details
Study Period 2021–2034
Base Year 2025
Estimated Year 2026
Forecast Period 2026–2034
Historical Period 2021–2025
Market Size 2025 USD 210.00 million
Market Size 2034 USD 651.23 million
Growth Rate CAGR of 13.4% from 2026–2034
Unit Value (USD Million)
Segmentation By Type, By Application, By Power Architecture, By End User, and By Region
By Type Sensor ASIC · Wireless / Power Management IC · Display / Driver IC · Mixed-Signal Processor
By Application Glucose Monitoring · Vision Enhancement · AR Display · Ocular Monitoring · Other Medical Sensing
By End User Medical Device Developers · Consumer Electronics Companies · Research Institutions
By Power Architecture Wireless Power / NFC · Microbattery · Energy Harvesting
By Region Each region analysed by Type, Application and Country
North AmericaU.S., Canada, Mexico
EuropeGermany, France, U.K., Italy, Russia, Nordic Countries, Benelux
AsiaChina, Japan, South Korea, India, Southeast Asia
South AmericaBrazil, Argentina, Rest of South America
Middle East & AfricaTurkey, Israel, Saudi Arabia, UAE, Rest of MEA
Key Companies Profiled Sony Semiconductor Solutions, STMicroelectronics, Texas Instruments, NXP Semiconductors, Samsung Electronics, imec, Mojo Vision, Verily, Infineon Technologies, Sensirion
Customization Scope Free report customization (equivalent to up to 4 analyst working days) with purchase. Addition or alteration to country, regional and segment scope.

Frequently Asked Questions

What is the current size of the Semiconductor for Smart Contact Lenses market?

The market is valued at USD 210.00 million in 2025 and is projected to reach USD 651.23 million by 2034, expanding at a 13.4% CAGR during 2026–2034.

Which companies lead the Semiconductor for Smart Contact Lenses market?

Key participants include Sony Semiconductor Solutions, STMicroelectronics, Texas Instruments, NXP Semiconductors, Samsung Electronics, imec, Mojo Vision, Verily.

What is Semiconductor for Smart Contact Lenses?

Semiconductors for smart contact lenses include ultra-low-power sensor ASICs, power-management circuits, wireless interfaces and display or driver ICs designed to operate inside an extremely constrained ocular form factor.

What are the main product types?

Growth is driven by software-defined vehicles, industrial digitalization, richer consumer interfaces and medical equipment requiring responsive graphics and touch.

What are the main challenges?

Growth is constrained by thermal limits, software complexity, long industrial qualification, display-interface fragmentation and price pressure in consumer applications.

Research Sources & Evidence Base
View research sources used for this overview
  1. NXP Semiconductors. S32T Touch Controller, current automotive touch-controller architecture and HMI use cases.
  2. NXP Semiconductors. Human Machine Interface Solutions, current HMI processor, MCU and interface context.
HMI Chip Market Size, Share & Industry Analysis, By Type (Industrial Grade, Consumer Grade), By Application (Consumer Electronics, Industrial Control, Automotive, Medical Devices), By Function (Graphics/Display Processing, Touch Processing, Multimedia, Connectivity & Control), By Interface (MIPI/LVDS, RGB/LCD, CAN/Ethernet, I2C/SPI), and Regional Forecast, 2026-2034

Get Sample Report PDF for Exclusive Insights

Report Sample Includes

  • Table of Contents
  • List of Tables & Figures
  • Charts, Research Methodology, and more...

PDF Icon Download Sample Report PDF
SKU: 39e935e6bebc
Category:
License Type

Corporate License, Excel License, PDF and Excel Databook License

Download Sample Report

Table of Content

1 Introduction to Research & Analysis Reports
1.1 HMI Chip Market Definition
1.2 Market Segments
1.2.1 Segment by Type
1.2.2 Segment by Application
1.3 Global HMI Chip Market Overview
1.4 Features & Benefits of This Report
1.5 Methodology & Sources of Information
1.5.1 Research Methodology
1.5.2 Research Process
1.5.3 Base Year
1.5.4 Report Assumptions & Caveats
2 Global HMI Chip Overall Market Size
2.1 Global HMI Chip Market Size: 2025 VS 2034
2.2 Global HMI Chip Market Size, Prospects & Forecasts: 2026-2034
2.3 Global HMI Chip Sales: 2026-2034
3 Company Landscape
3.1 Top HMI Chip Players in Global Market
3.2 Top Global HMI Chip Companies Ranked by Revenue
3.3 Global HMI Chip Revenue by Companies
3.4 Global HMI Chip Sales by Companies
3.5 Global HMI Chip Price by Manufacturer (2021-2026)
3.6 Top 3 and Top 5 HMI Chip Companies in Global Market, by Revenue in 2025
3.7 Global Manufacturers HMI Chip Product Type
3.8 Tier 1, Tier 2, and Tier 3 HMI Chip Players in Global Market
3.8.1 List of Global Tier 1 HMI Chip Companies
3.8.2 List of Global Tier 2 and Tier 3 HMI Chip Companies
4 Sights by Type
4.1 Overview
4.1.1 Segment by Type – Global HMI Chip Market Size Markets, 2025 & 2034
4.1.2 Industrial Grade
4.1.3 Consumer Grade
4.2 Segment by Type – Global HMI Chip Revenue & Forecasts
4.2.1 Segment by Type – Global HMI Chip Revenue, 2021-2026
4.2.2 Segment by Type – Global HMI Chip Revenue, 2027-2034
4.2.3 Segment by Type – Global HMI Chip Revenue Market Share, 2026-2034
4.3 Segment by Type – Global HMI Chip Sales & Forecasts
4.3.1 Segment by Type – Global HMI Chip Sales, 2021-2026
4.3.2 Segment by Type – Global HMI Chip Sales, 2027-2034
4.3.3 Segment by Type – Global HMI Chip Sales Market Share, 2026-2034
4.4 Segment by Type – Global HMI Chip Price (Manufacturers Selling Prices), 2026-2034
5 Sights by Application
5.1 Overview
5.1.1 Segment by Application – Global HMI Chip Market Size, 2025 & 2034
5.1.2 Consumer Electronics
5.1.3 Industrial Control
5.1.4 Automotive
5.1.5 Medical Devices
5.1.6 Others
5.2 Segment by Application – Global HMI Chip Revenue & Forecasts
5.2.1 Segment by Application – Global HMI Chip Revenue, 2021-2026
5.2.2 Segment by Application – Global HMI Chip Revenue, 2027-2034
5.2.3 Segment by Application – Global HMI Chip Revenue Market Share, 2026-2034
5.3 Segment by Application – Global HMI Chip Sales & Forecasts
5.3.1 Segment by Application – Global HMI Chip Sales, 2021-2026
5.3.2 Segment by Application – Global HMI Chip Sales, 2027-2034
5.3.3 Segment by Application – Global HMI Chip Sales Market Share, 2026-2034
5.4 Segment by Application – Global HMI Chip Price (Manufacturers Selling Prices), 2026-2034
6 Sights Region
6.1 By Region – Global HMI Chip Market Size, 2025 & 2034
6.2 By Region – Global HMI Chip Revenue & Forecasts
6.2.1 By Region – Global HMI Chip Revenue, 2021-2026
6.2.2 By Region – Global HMI Chip Revenue, 2027-2034
6.2.3 By Region – Global HMI Chip Revenue Market Share, 2026-2034
6.3 By Region – Global HMI Chip Sales & Forecasts
6.3.1 By Region – Global HMI Chip Sales, 2021-2026
6.3.2 By Region – Global HMI Chip Sales, 2027-2034
6.3.3 By Region – Global HMI Chip Sales Market Share, 2026-2034
6.4 North America
6.4.1 By Country – North America HMI Chip Revenue, 2026-2034
6.4.2 By Country – North America HMI Chip Sales, 2026-2034
6.4.3 United States HMI Chip Market Size, 2026-2034
6.4.4 Canada HMI Chip Market Size, 2026-2034
6.4.5 Mexico HMI Chip Market Size, 2026-2034
6.5 Europe
6.5.1 By Country – Europe HMI Chip Revenue, 2026-2034
6.5.2 By Country – Europe HMI Chip Sales, 2026-2034
6.5.3 Germany HMI Chip Market Size, 2026-2034
6.5.4 France HMI Chip Market Size, 2026-2034
6.5.5 U.K. HMI Chip Market Size, 2026-2034
6.5.6 Italy HMI Chip Market Size, 2026-2034
6.5.7 Russia HMI Chip Market Size, 2026-2034
6.5.8 Nordic Countries HMI Chip Market Size, 2026-2034
6.5.9 Benelux HMI Chip Market Size, 2026-2034
6.6 Asia
6.6.1 By Region – Asia HMI Chip Revenue, 2026-2034
6.6.2 By Region – Asia HMI Chip Sales, 2026-2034
6.6.3 China HMI Chip Market Size, 2026-2034
6.6.4 Japan HMI Chip Market Size, 2026-2034
6.6.5 South Korea HMI Chip Market Size, 2026-2034
6.6.6 Southeast Asia HMI Chip Market Size, 2026-2034
6.6.7 India HMI Chip Market Size, 2026-2034
6.7 South America
6.7.1 By Country – South America HMI Chip Revenue, 2026-2034
6.7.2 By Country – South America HMI Chip Sales, 2026-2034
6.7.3 Brazil HMI Chip Market Size, 2026-2034
6.7.4 Argentina HMI Chip Market Size, 2026-2034
6.8 Middle East & Africa
6.8.1 By Country – Middle East & Africa HMI Chip Revenue, 2026-2034
6.8.2 By Country – Middle East & Africa HMI Chip Sales, 2026-2034
6.8.3 Turkey HMI Chip Market Size, 2026-2034
6.8.4 Israel HMI Chip Market Size, 2026-2034
6.8.5 Saudi Arabia HMI Chip Market Size, 2026-2034
6.8.6 UAE HMI Chip Market Size, 2026-2034
7 Manufacturers & Brands Profiles
7.1 Infineon
7.1.1 Infineon Company Summary
7.1.2 Infineon Business Overview
7.1.3 Infineon HMI Chip Major Product Offerings
7.1.4 Infineon HMI Chip Sales and Revenue in Global (2021-2026)
7.1.5 Infineon Key News & Latest Developments
7.2 NXP Semiconductors
7.2.1 NXP Semiconductors Company Summary
7.2.2 NXP Semiconductors Business Overview
7.2.3 NXP Semiconductors HMI Chip Major Product Offerings
7.2.4 NXP Semiconductors HMI Chip Sales and Revenue in Global (2021-2026)
7.2.5 NXP Semiconductors Key News & Latest Developments
7.3 Texas Instruments
7.3.1 Texas Instruments Company Summary
7.3.2 Texas Instruments Business Overview
7.3.3 Texas Instruments HMI Chip Major Product Offerings
7.3.4 Texas Instruments HMI Chip Sales and Revenue in Global (2021-2026)
7.3.5 Texas Instruments Key News & Latest Developments
7.4 STMicroelectronics
7.4.1 STMicroelectronics Company Summary
7.4.2 STMicroelectronics Business Overview
7.4.3 STMicroelectronics HMI Chip Major Product Offerings
7.4.4 STMicroelectronics HMI Chip Sales and Revenue in Global (2021-2026)
7.4.5 STMicroelectronics Key News & Latest Developments
7.5 Renesas Electronics
7.5.1 Renesas Electronics Company Summary
7.5.2 Renesas Electronics Business Overview
7.5.3 Renesas Electronics HMI Chip Major Product Offerings
7.5.4 Renesas Electronics HMI Chip Sales and Revenue in Global (2021-2026)
7.5.5 Renesas Electronics Key News & Latest Developments
7.6 Microchip Technology
7.6.1 Microchip Technology Company Summary
7.6.2 Microchip Technology Business Overview
7.6.3 Microchip Technology HMI Chip Major Product Offerings
7.6.4 Microchip Technology HMI Chip Sales and Revenue in Global (2021-2026)
7.6.5 Microchip Technology Key News & Latest Developments
7.7 Anyka Microelectronics
7.7.1 Anyka Microelectronics Company Summary
7.7.2 Anyka Microelectronics Business Overview
7.7.3 Anyka Microelectronics HMI Chip Major Product Offerings
7.7.4 Anyka Microelectronics HMI Chip Sales and Revenue in Global (2021-2026)
7.7.5 Anyka Microelectronics Key News & Latest Developments
7.8 Plinxinchi Technology
7.8.1 Plinxinchi Technology Company Summary
7.8.2 Plinxinchi Technology Business Overview
7.8.3 Plinxinchi Technology HMI Chip Major Product Offerings
7.8.4 Plinxinchi Technology HMI Chip Sales and Revenue in Global (2021-2026)
7.8.5 Plinxinchi Technology Key News & Latest Developments
7.9 Ligong Technology
7.9.1 Ligong Technology Company Summary
7.9.2 Ligong Technology Business Overview
7.9.3 Ligong Technology HMI Chip Major Product Offerings
7.9.4 Ligong Technology HMI Chip Sales and Revenue in Global (2021-2026)
7.9.5 Ligong Technology Key News & Latest Developments
7.10 Yingshang Microelectronics
7.10.1 Yingshang Microelectronics Company Summary
7.10.2 Yingshang Microelectronics Business Overview
7.10.3 Yingshang Microelectronics HMI Chip Major Product Offerings
7.10.4 Yingshang Microelectronics HMI Chip Sales and Revenue in Global (2021-2026)
7.10.5 Yingshang Microelectronics Key News & Latest Developments
7.11 Allwinner Technology
7.11.1 Allwinner Technology Company Summary
7.11.2 Allwinner Technology Business Overview
7.11.3 Allwinner Technology HMI Chip Major Product Offerings
7.11.4 Allwinner Technology HMI Chip Sales and Revenue in Global (2021-2026)
7.11.5 Allwinner Technology Key News & Latest Developments
7.12 Kaibeite Technology
7.12.1 Kaibeite Technology Company Summary
7.12.2 Kaibeite Technology Business Overview
7.12.3 Kaibeite Technology HMI Chip Major Product Offerings
7.12.4 Kaibeite Technology HMI Chip Sales and Revenue in Global (2021-2026)
7.12.5 Kaibeite Technology Key News & Latest Developments
7.13 Jiangxinchuang Technology
7.13.1 Jiangxinchuang Technology Company Summary
7.13.2 Jiangxinchuang Technology Business Overview
7.13.3 Jiangxinchuang Technology HMI Chip Major Product Offerings
7.13.4 Jiangxinchuang Technology HMI Chip Sales and Revenue in Global (2021-2026)
7.13.5 Jiangxinchuang Technology Key News & Latest Developments
8 Global HMI Chip Production Capacity, Analysis
8.1 Global HMI Chip Production Capacity, 2026-2034
8.2 HMI Chip Production Capacity of Key Manufacturers in Global Market
8.3 Global HMI Chip Production by Region
9 Key Market Trends, Opportunity, Drivers and Restraints
9.1 Market Opportunities & Trends
9.2 Market Drivers
9.3 Market Restraints
10 HMI Chip Supply Chain Analysis
10.1 HMI Chip Industry Value Chain
10.2 HMI Chip Upstream Market
10.3 HMI Chip Downstream and Clients
10.4 Marketing Channels Analysis
10.4.1 Marketing Channels
10.4.2 HMI Chip Distributors and Sales Agents in Global
11 Conclusion
12 Appendix
12.1 Note
12.2 Examples of Clients
12.3 DisclaimerList of Tables
Table 1. Key Players of HMI Chip in Global Market
Table 2. Top HMI Chip Players in Global Market, Ranking by Revenue (2025)
Table 3. Global HMI Chip Revenue by Companies, (US$, Mn), 2021-2026
Table 4. Global HMI Chip Revenue Share by Companies, 2021-2026
Table 5. Global HMI Chip Sales by Companies, (K Units), 2021-2026
Table 6. Global HMI Chip Sales Share by Companies, 2021-2026
Table 7. Key Manufacturers HMI Chip Price (2021-2026) & (US$/Unit)
Table 8. Global Manufacturers HMI Chip Product Type
Table 9. List of Global Tier 1 HMI Chip Companies, Revenue (US$, Mn) in 2025 and Market Share
Table 10. List of Global Tier 2 and Tier 3 HMI Chip Companies, Revenue (US$, Mn) in 2025 and Market Share
Table 11. Segment by Type – Global HMI Chip Revenue, (US$, Mn), 2025 & 2034
Table 12. Segment by Type – Global HMI Chip Revenue (US$, Mn), 2021-2026
Table 13. Segment by Type – Global HMI Chip Revenue (US$, Mn), 2027-2034
Table 14. Segment by Type – Global HMI Chip Sales (K Units), 2021-2026
Table 15. Segment by Type – Global HMI Chip Sales (K Units), 2027-2034
Table 16. Segment by Application – Global HMI Chip Revenue, (US$, Mn), 2025 & 2034
Table 17. Segment by Application – Global HMI Chip Revenue, (US$, Mn), 2021-2026
Table 18. Segment by Application – Global HMI Chip Revenue, (US$, Mn), 2027-2034
Table 19. Segment by Application – Global HMI Chip Sales, (K Units), 2021-2026
Table 20. Segment by Application – Global HMI Chip Sales, (K Units), 2027-2034
Table 21. By Region – Global HMI Chip Revenue, (US$, Mn), 2025 & 2034
Table 22. By Region – Global HMI Chip Revenue, (US$, Mn), 2021-2026
Table 23. By Region – Global HMI Chip Revenue, (US$, Mn), 2027-2034
Table 24. By Region – Global HMI Chip Sales, (K Units), 2021-2026
Table 25. By Region – Global HMI Chip Sales, (K Units), 2027-2034
Table 26. By Country – North America HMI Chip Revenue, (US$, Mn), 2021-2026
Table 27. By Country – North America HMI Chip Revenue, (US$, Mn), 2027-2034
Table 28. By Country – North America HMI Chip Sales, (K Units), 2021-2026
Table 29. By Country – North America HMI Chip Sales, (K Units), 2027-2034
Table 30. By Country – Europe HMI Chip Revenue, (US$, Mn), 2021-2026
Table 31. By Country – Europe HMI Chip Revenue, (US$, Mn), 2027-2034
Table 32. By Country – Europe HMI Chip Sales, (K Units), 2021-2026
Table 33. By Country – Europe HMI Chip Sales, (K Units), 2027-2034
Table 34. By Region – Asia HMI Chip Revenue, (US$, Mn), 2021-2026
Table 35. By Region – Asia HMI Chip Revenue, (US$, Mn), 2027-2034
Table 36. By Region – Asia HMI Chip Sales, (K Units), 2021-2026
Table 37. By Region – Asia HMI Chip Sales, (K Units), 2027-2034
Table 38. By Country – South America HMI Chip Revenue, (US$, Mn), 2021-2026
Table 39. By Country – South America HMI Chip Revenue, (US$, Mn), 2027-2034
Table 40. By Country – South America HMI Chip Sales, (K Units), 2021-2026
Table 41. By Country – South America HMI Chip Sales, (K Units), 2027-2034
Table 42. By Country – Middle East & Africa HMI Chip Revenue, (US$, Mn), 2021-2026
Table 43. By Country – Middle East & Africa HMI Chip Revenue, (US$, Mn), 2027-2034
Table 44. By Country – Middle East & Africa HMI Chip Sales, (K Units), 2021-2026
Table 45. By Country – Middle East & Africa HMI Chip Sales, (K Units), 2027-2034
Table 46. Infineon Company Summary
Table 47. Infineon HMI Chip Product Offerings
Table 48. Infineon HMI Chip Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2021-2026)
Table 49. Infineon Key News & Latest Developments
Table 50. NXP Semiconductors Company Summary
Table 51. NXP Semiconductors HMI Chip Product Offerings
Table 52. NXP Semiconductors HMI Chip Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2021-2026)
Table 53. NXP Semiconductors Key News & Latest Developments
Table 54. Texas Instruments Company Summary
Table 55. Texas Instruments HMI Chip Product Offerings
Table 56. Texas Instruments HMI Chip Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2021-2026)
Table 57. Texas Instruments Key News & Latest Developments
Table 58. STMicroelectronics Company Summary
Table 59. STMicroelectronics HMI Chip Product Offerings
Table 60. STMicroelectronics HMI Chip Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2021-2026)
Table 61. STMicroelectronics Key News & Latest Developments
Table 62. Renesas Electronics Company Summary
Table 63. Renesas Electronics HMI Chip Product Offerings
Table 64. Renesas Electronics HMI Chip Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2021-2026)
Table 65. Renesas Electronics Key News & Latest Developments
Table 66. Microchip Technology Company Summary
Table 67. Microchip Technology HMI Chip Product Offerings
Table 68. Microchip Technology HMI Chip Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2021-2026)
Table 69. Microchip Technology Key News & Latest Developments
Table 70. Anyka Microelectronics Company Summary
Table 71. Anyka Microelectronics HMI Chip Product Offerings
Table 72. Anyka Microelectronics HMI Chip Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2021-2026)
Table 73. Anyka Microelectronics Key News & Latest Developments
Table 74. Plinxinchi Technology Company Summary
Table 75. Plinxinchi Technology HMI Chip Product Offerings
Table 76. Plinxinchi Technology HMI Chip Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2021-2026)
Table 77. Plinxinchi Technology Key News & Latest Developments
Table 78. Ligong Technology Company Summary
Table 79. Ligong Technology HMI Chip Product Offerings
Table 80. Ligong Technology HMI Chip Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2021-2026)
Table 81. Ligong Technology Key News & Latest Developments
Table 82. Yingshang Microelectronics Company Summary
Table 83. Yingshang Microelectronics HMI Chip Product Offerings
Table 84. Yingshang Microelectronics HMI Chip Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2021-2026)
Table 85. Yingshang Microelectronics Key News & Latest Developments
Table 86. Allwinner Technology Company Summary
Table 87. Allwinner Technology HMI Chip Product Offerings
Table 88. Allwinner Technology HMI Chip Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2021-2026)
Table 89. Allwinner Technology Key News & Latest Developments
Table 90. Kaibeite Technology Company Summary
Table 91. Kaibeite Technology HMI Chip Product Offerings
Table 92. Kaibeite Technology HMI Chip Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2021-2026)
Table 93. Kaibeite Technology Key News & Latest Developments
Table 94. Jiangxinchuang Technology Company Summary
Table 95. Jiangxinchuang Technology HMI Chip Product Offerings
Table 96. Jiangxinchuang Technology HMI Chip Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2021-2026)
Table 97. Jiangxinchuang Technology Key News & Latest Developments
Table 98. HMI Chip Capacity of Key Manufacturers in Global Market, 2024-2026 (K Units)
Table 99. Global HMI Chip Capacity Market Share of Key Manufacturers, 2024-2026
Table 100. Global HMI Chip Production by Region, 2021-2026 (K Units)
Table 101. Global HMI Chip Production by Region, 2027-2034 (K Units)
Table 102. HMI Chip Market Opportunities & Trends in Global Market
Table 103. HMI Chip Market Drivers in Global Market
Table 104. HMI Chip Market Restraints in Global Market
Table 105. HMI Chip Raw Materials
Table 106. HMI Chip Raw Materials Suppliers in Global Market
Table 107. Typical HMI Chip Downstream
Table 108. HMI Chip Downstream Clients in Global Market
Table 109. HMI Chip Distributors and Sales Agents in Global Market

List of Figures
Figure 1. HMI Chip Product Picture
Figure 2. HMI Chip Segment by Type in 2025
Figure 3. HMI Chip Segment by Application in 2025
Figure 4. Global HMI Chip Market Overview: 2025
Figure 5. Key Caveats
Figure 6. Global HMI Chip Market Size: 2025 VS 2034 (US$, Mn)
Figure 7. Global HMI Chip Revenue: 2026-2034 (US$, Mn)
Figure 8. HMI Chip Sales in Global Market: 2026-2034 (K Units)
Figure 9. The Top 3 and 5 Players Market Share by HMI Chip Revenue in 2025
Figure 10. Segment by Type – Global HMI Chip Revenue, (US$, Mn), 2025 & 2034
Figure 11. Segment by Type – Global HMI Chip Revenue Market Share, 2026-2034
Figure 12. Segment by Type – Global HMI Chip Sales Market Share, 2026-2034
Figure 13. Segment by Type – Global HMI Chip Price (US$/Unit), 2026-2034
Figure 14. Segment by Application – Global HMI Chip Revenue, (US$, Mn), 2025 & 2034
Figure 15. Segment by Application – Global HMI Chip Revenue Market Share, 2026-2034
Figure 16. Segment by Application – Global HMI Chip Sales Market Share, 2026-2034
Figure 17. Segment by Application -Global HMI Chip Price (US$/Unit), 2026-2034
Figure 18. By Region – Global HMI Chip Revenue, (US$, Mn), 2025 & 2034
Figure 19. By Region – Global HMI Chip Revenue Market Share, 2021 VS 2025 VS 2034
Figure 20. By Region – Global HMI Chip Revenue Market Share, 2026-2034
Figure 21. By Region – Global HMI Chip Sales Market Share, 2026-2034
Figure 22. By Country – North America HMI Chip Revenue Market Share, 2026-2034
Figure 23. By Country – North America HMI Chip Sales Market Share, 2026-2034
Figure 24. United States HMI Chip Revenue, (US$, Mn), 2026-2034
Figure 25. Canada HMI Chip Revenue, (US$, Mn), 2026-2034
Figure 26. Mexico HMI Chip Revenue, (US$, Mn), 2026-2034
Figure 27. By Country – Europe HMI Chip Revenue Market Share, 2026-2034
Figure 28. By Country – Europe HMI Chip Sales Market Share, 2026-2034
Figure 29. Germany HMI Chip Revenue, (US$, Mn), 2026-2034
Figure 30. France HMI Chip Revenue, (US$, Mn), 2026-2034
Figure 31. U.K. HMI Chip Revenue, (US$, Mn), 2026-2034
Figure 32. Italy HMI Chip Revenue, (US$, Mn), 2026-2034
Figure 33. Russia HMI Chip Revenue, (US$, Mn), 2026-2034
Figure 34. Nordic Countries HMI Chip Revenue, (US$, Mn), 2026-2034
Figure 35. Benelux HMI Chip Revenue, (US$, Mn), 2026-2034
Figure 36. By Region – Asia HMI Chip Revenue Market Share, 2026-2034
Figure 37. By Region – Asia HMI Chip Sales Market Share, 2026-2034
Figure 38. China HMI Chip Revenue, (US$, Mn), 2026-2034
Figure 39. Japan HMI Chip Revenue, (US$, Mn), 2026-2034
Figure 40. South Korea HMI Chip Revenue, (US$, Mn), 2026-2034
Figure 41. Southeast Asia HMI Chip Revenue, (US$, Mn), 2026-2034
Figure 42. India HMI Chip Revenue, (US$, Mn), 2026-2034
Figure 43. By Country – South America HMI Chip Revenue Market Share, 2026-2034
Figure 44. By Country – South America HMI Chip Sales, Market Share, 2026-2034
Figure 45. Brazil HMI Chip Revenue, (US$, Mn), 2026-2034
Figure 46. Argentina HMI Chip Revenue, (US$, Mn), 2026-2034
Figure 47. By Country – Middle East & Africa HMI Chip Revenue, Market Share, 2026-2034
Figure 48. By Country – Middle East & Africa HMI Chip Sales, Market Share, 2026-2034
Figure 49. Turkey HMI Chip Revenue, (US$, Mn), 2026-2034
Figure 50. Israel HMI Chip Revenue, (US$, Mn), 2026-2034
Figure 51. Saudi Arabia HMI Chip Revenue, (US$, Mn), 2026-2034
Figure 52. UAE HMI Chip Revenue, (US$, Mn), 2026-2034
Figure 53. Global HMI Chip Production Capacity (K Units), 2026-2034
Figure 54. The Percentage of Production HMI Chip by Region, 2025 VS 2034
Figure 55. HMI Chip Industry Value Chain
Figure 56. Marketing Channels