Key Statistics
Key Takeaways
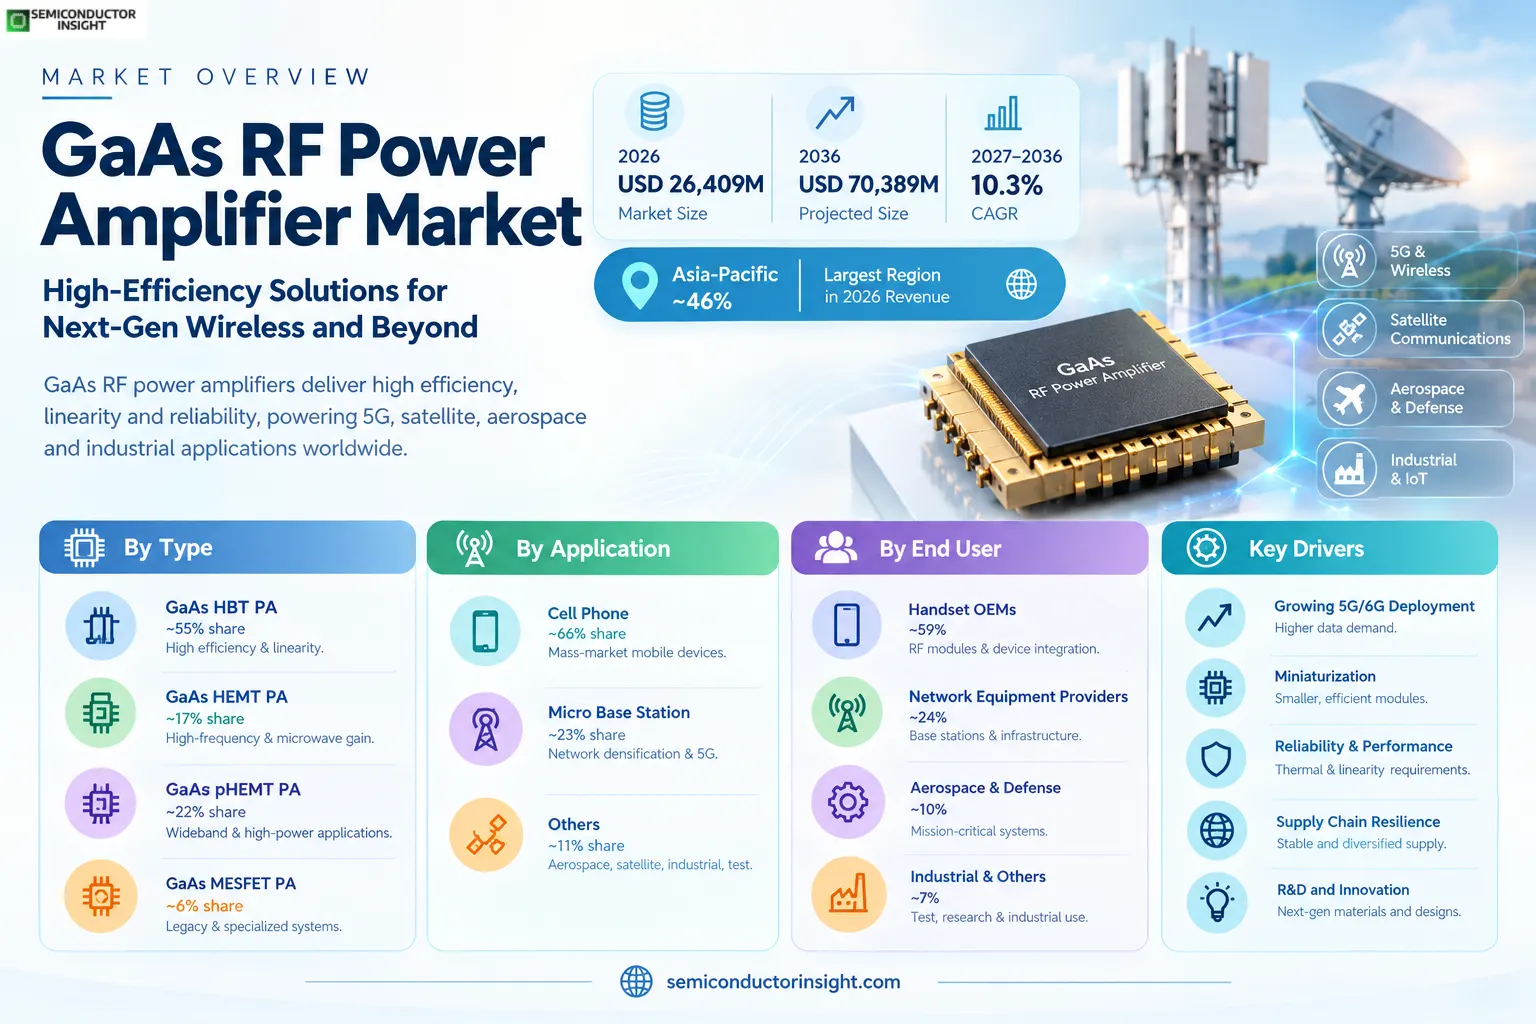
- revenue: the GaAs RF power amplifier industry represents USD 26,409 million in 2026, with a forecast of USD 70,389 million in 2036 at 10.3% CAGR. The commercial boundary is GaAs transmit power-amplifier semiconductor revenue, not every RF chip or finished radio.
- GaAs HBT PA: Heterojunction bipolar transistor amplifiers hold the largest modeled 2026 type share at ~55%, reflecting high-volume handset front ends; the HEMT and pHEMT classes are differentiated by frequency, gain, linearity and use in specialized microwave systems.
- Cell phones: Handset transmitter chains account for an estimated ~66% of 2026 application revenue, compared with ~23% for micro base stations and ~11% for other uses; multiband and carrier-aggregation requirements raise the number of qualified RF paths per device.
- Regional leadership: Asia-Pacific represents an estimated ~46% of 2026 sales because mobile-device assembly, RF front-end supply chains and telecom deployment cluster around China, Taiwan, South Korea, Japan and India; North America remains a major design and defense market.
- Technology substitution: GaN power amplifiers challenge GaAs in high-output infrastructure and satellite roles, while silicon RF-SOI and CMOS alternatives create pressure in integration-sensitive designs; GaAs maintains value in compact linear mobile transmitters and specialized microwave amplifiers.
GaAs RF Power Amplifier Market Overview
The GaAs RF power amplifier market generated USD 26,409 million in 2026 and is projected to reach USD 70,389 million by 2036, expanding at a 10.3% CAGR during 2027–2036. Asia-Pacific leads 2026 revenue with an estimated ~46% share, followed by North America at ~25%; these percentages are market estimates informed by supply-chain and deployment indicators.
Gallium arsenide radio-frequency power amplifiers convert relatively low-power modulated transmit signals into output levels suitable for antennas and subsequent radio stages. They are built with heterojunction bipolar transistors, high-electron-mobility transistors, pseudomorphic HEMTs or legacy MESFET architectures. A power amplifier differs from a low-noise receiver amplifier because its central design constraints include output compression, adjacent-channel leakage, efficiency, thermal dissipation and spectral linearity. Qorvo documents an InGaP/GaAs HBT driver operating from 2.3 to 5.0 GHz, while Analog Devices offers GaAs pHEMT MMIC amplifiers extending into the 18–44 GHz and 20–44 GHz ranges.
The revenue boundary comprises GaAs-based transmitter power-amplifier dies, packaged RF amplifier chips and the attributable GaAs amplifier content in modules supplied for mobile handsets, micro base stations and other transmitting equipment. It excludes complete phones, radio access network systems, antennas, passive filters, pure GaN power amplifiers, standalone receiver low-noise amplifiers and semiconductor wafer sales not yet embodied in a finished amplifier. This distinction matters because a large modem-RF supplier may report substantial connectivity revenue that includes processors, transceivers, switches and filters, none of which should be counted wholesale as GaAs PA sales.
In handset platforms, GaAs HBT stages provide power and linearity across multiple cellular bands; system designers increasingly balance amplifier efficiency against carrier aggregation, envelope tracking, thermal limits and antenna placement. The 2026 application allocation assigns ~66% to Cell Phone, ~23% to Micro Base Station and ~11% to Others. These shares are modeled revenue allocations rather than audited manufacturer disclosures. GSMA recorded more than 2 billion global 5G connections at the end of 2024, while its 2026 India briefing reported around 450 million 5G connections, illustrating the installed wireless base that drives continued front-end replacement and qualification.
For infrastructure and aerospace, the product mix is less uniform. Qorvo lists a 0.5 W GaAs HBT driver with 28 dB gain at 2.6 GHz, and MACOM lists a GaAs MMIC two-stage amplifier fabricated with a 0.5-micron gate process for transmitter and radar applications. Analog Devices specifies a 32 dBm GaAs pHEMT amplifier operating between 18 and 44 GHz with a temperature-compensated detector. These product specifications describe distinct amplifier classes; they do not imply that all cellular base stations use GaAs in their final high-power stage, where GaN increasingly competes.
Commercial performance depends on wafer yield, qualified foundry capacity, substrate and epitaxy availability, package thermal resistance, and the ability to sustain linear output under changing modulation bandwidths. The modeled 2026 type mix is ~55% HBT, ~17% HEMT, ~22% pHEMT and ~6% MESFET. GaAs competes against silicon RF-SOI and CMOS at the integration end of the spectrum and against GaN at high-output power. Suppliers therefore win sockets through measured efficiency, lifetime reliability and RF-system compatibility rather than through raw device gain alone.
Segment Analysis: By Type
Four transistor technology classes define the published product segmentation: GaAs HBT PA, GaAs HEMT PA, GaAs pHEMT PA and GaAs MESFET PA. HBT holds an estimated ~55% of 2026 revenue, pHEMT ~22%, HEMT ~17% and MESFET ~6%; pHEMT demand is supported by higher-frequency instrumentation, microwave links and aerospace products, while HBT remains more closely aligned with high-volume mobile transmit paths.
| Type | Technical function | 2026 competitive position |
|---|---|---|
| GaAs HBT PA | GaAs heterojunction bipolar amplifiers supply controlled gain and linearity in mobile RF transmitter chains and selected infrastructure drivers. Qorvo describes InGaP/GaAs HBT products spanning 850–960 MHz and 2.3–5.0 GHz; those operating ranges demonstrate how the process family covers low-band and mid-band radio applications without assuming one transistor geometry serves every output-power requirement. | Estimated ~55% 2026 revenue share. High-volume handset qualification, mature process control and multiband module integration are the commercial strengths. The modeled HBT revenue growth rate is ~10.1% annually, with pressure from lower handset unit pricing and competition among RF front-end module suppliers offset by more bands and advanced transmit functions. |
| GaAs HEMT PA | High-electron-mobility GaAs amplifier designs serve microwave gain blocks and specialist transmitter functions where carrier transport and frequency response are important. Device performance depends on channel design, gate length, thermal interfaces and impedance matching, rather than a single universal frequency threshold. Specialized suppliers qualify these components through compression and intermodulation measurements across actual mission bandwidths. | Estimated ~17% 2026 share. HEMT products serve differentiated RF designs with modeled growth near ~11.6% annually, supported by higher-frequency communications and aerospace demand. The technology competes with pHEMT, GaN and silicon-germanium choices, so suppliers must demonstrate the cost and reliability advantages of the exact device architecture. |
| GaAs pHEMT PA | Pseudomorphic HEMT amplifiers support broad microwave and millimeter-wave transmit applications. MACOM documents a GaAs pHEMT distributed amplifier from DC to 40 GHz; Analog Devices lists 18–44 GHz and 20–44 GHz MMIC power amplifiers, with integrated matching or detectors depending on the device. These catalogued products illustrate a differentiated power and bandwidth ladder. | Estimated ~22% 2026 share. A modeled ~11.2% growth rate reflects satellite terminals, defense electronics, instrumentation and high-frequency radios, where qualification periods are longer but unit values can be higher. Some mixed GaAs/GaN product listings should not be treated as proof that the entire module revenue belongs to GaAs. |
| GaAs MESFET PA | Metal-semiconductor field-effect transistor designs represent a mature GaAs amplifier architecture still relevant to certain legacy and specialized RF applications. Their device behavior, biasing and manufacturability differ from modern pHEMT processes. Maintenance of qualified legacy radio platforms can sustain orders even when new high-frequency designs migrate to more recent transistor technologies. | Estimated ~6% 2026 share. Modeled growth near ~6.7% trails the broader market because new design wins concentrate in HBT and HEMT families. The segment retains a maintenance and replacement role, but process discontinuation and second-source availability are material procurement risks for customers with long equipment service lives. |
Secondary segmentation: transistor process and module integration
Transistor process selection is not identical to package or system integration. A GaAs HBT die may be sold as a discrete amplifier or combined with filters, switches and control circuits in a handset front-end module; only the attributable GaAs PA content belongs within the defined revenue boundary. A pHEMT amplifier may be supplied as a bare die, a surface-mount MMIC or a hermetic microwave assembly. Analog Devices documents both chip and packaged versions of its ADPA7005 family, showing why channel mix affects average selling price and qualification.
Segment Analysis: By Application
The application split follows the publisher categories Micro Base Station, Cell Phone and Others. Cell Phone contributes an estimated ~66% of 2026 revenue, Micro Base Station ~23% and Others ~11%. These proportions reflect the difference between handset production volumes and the higher individual device values of infrastructure and specialized microwave amplifiers.
| Application | Demand characteristics |
|---|---|
| Micro Base Station | Micro base stations use RF transmitter chains to maintain signal quality and power across small-cell coverage, enterprise radio and network densification deployments. Qorvo specifies the QPA9121 as a 2.3–5.0 GHz driver for massive-MIMO transmit paths; the infrastructure socket is sensitive to digital predistortion compatibility, linearity and radio thermal limits. Estimated 2026 share is ~23%, with modeled growth near ~11.9% as radio capacity requirements evolve. |
| Cell Phone | Handsets combine several band-specific amplifier paths and switches in compact front-end modules. GaAs HBT stages remain relevant where efficiency and linear output are essential under wideband 5G modulation; the system bill of materials also includes components that are excluded from this GaAs-only market. Estimated 2026 application share is ~66%, with modeled annual growth near ~9.7% because device replacement cycles and price pressure offset richer radio capability. |
| Others | The remaining category includes point-to-point microwave radios, aerospace communications, satellite terminals, electronic warfare, industrial transmitters and test equipment. Analog Devices lists 8–14 GHz, 18–44 GHz and DC–22 GHz GaAs pHEMT devices serving several of these functions. Estimated 2026 revenue share is ~11%, with modeled growth near ~10.5%; specifications and mission qualification matter more than handset-scale unit economics. |
Application revenue should not be confused with the number of active 5G connections or total mobile-industry spending. GSMA estimates more than 2 billion 5G connections at the end of 2024 and forecasts materially different adoption trajectories across developed and emerging regions, but an active connection is not a purchased power amplifier. Demand reaches semiconductor suppliers only when device makers order RF front-end content or network vendors procure transmit hardware. In 2026, cell-phone revenue leads despite high-power microwave parts carrying higher prices per device.
For a micro base station, a GaAs driver can be paired with a GaN final stage, making semiconductor-material attribution important. Qorvo has introduced a 5G pre-driver and BAW filter portfolio for massive-MIMO radios, but the launch description does not establish that the whole radio or every new amplifier is GaAs. In the Others segment, the choice between a 5 V GaAs pHEMT MMIC and a higher-voltage GaN device depends on output power, frequency, package thermal impedance and availability of a qualified second source.
Regional Analysis
Regional revenue is concentrated where handset RF manufacturing and semiconductor design ecosystems meet telecommunications demand. Asia-Pacific leads the modeled 2026 allocation at ~46%, followed by North America ~25%, Europe ~19%, South America ~5% and Middle East & Africa ~5%. The percentages are analyst allocations grounded in the publisher North America 2023 anchor and inspected supplier and GSMA evidence; they are not independently audited market shares.
Where are GaAs RF power amplifier design, production and demand concentrated?
Asia-Pacific benefits from the combination of smartphone assembly, RF front-end supplier ecosystems and large mobile networks, while North America is particularly important for RF design, aerospace electronics and high-value microwave amplifiers. Europe contributes industrial and defense demand, with South America and Middle East & Africa more dependent on imported radio and handset equipment. The model allocates ~46%, ~25%, ~19%, ~5% and ~5% of 2026 revenue respectively, while maintaining distinct growth assumptions for each region.
The publisher places North America at USD 5,128.05 million in 2023, or 26.06% of the global USD 19,680 million total. The estimated North American share declines slightly to ~25% by 2026 as Asia-Pacific expands more rapidly. This calibration does not require the North American 2023 market to equal U.S. production or any specific supplier’s corporate sales. GSMA connectivity figures, semiconductor technical catalogues and regional equipment activity are used as directional indicators rather than direct GaAs revenue observations.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia-Pacific | Estimated ~46% of 2026 revenue; largest market position | Modeled ~11.0% CAGR to 2036, driven by local device and radio equipment mix | Handset manufacturing, RF foundry services, 5G network equipment and high-volume module integration are the principal regional demand channels. | Price, wafer yield, multiband validation and domestic component sourcing. |
| North America | Estimated ~25% of 2026 revenue; regional market position | Modeled ~8.9% CAGR to 2036, driven by local device and radio equipment mix | RF chip design, aerospace and defense, microwave instrumentation and cellular infrastructure development form the regional mix. | Qualification, government programme requirements and second-source availability. |
| Europe | Estimated ~19% of 2026 revenue; regional market position | Modeled ~9.6% CAGR to 2036, driven by local device and radio equipment mix | Telecom upgrades, aerospace, industrial test and specialist microwave radio demand underpin the modeled regional opportunity. | Product qualification, compliance, technical documentation and procurement continuity. |
| South America | Estimated ~5% of 2026 revenue; regional market position | Modeled ~11.4% CAGR to 2036, driven by local device and radio equipment mix | Imported handset RF content, telecom modernization and selective industrial radio demand are the main channels. | Foreign-exchange conditions, distributor inventory and network investment timing. |
| Middle East & Africa | Estimated ~5% of 2026 revenue; regional market position | Modeled ~11.5% CAGR to 2036, driven by local device and radio equipment mix | Cellular networks, satellite terminals and industrial communications create uneven but identifiable demand. | Imported equipment channels, operating conditions and service-support economics. |
Competitive Landscape: GaAs RF Amplifier Suppliers and Adjacent Participants
Competition spans integrated RF-front-end suppliers, microwave MMIC manufacturers, GaAs foundries and design-platform businesses. Qorvo, Skyworks, MACOM and Analog Devices have documented GaAs amplifier or associated RF product capabilities, while several names in the published company universe operate primarily in broader modem, RF integration or component distribution markets. A company being profiled does not establish an independently measured share of GaAs-only amplifier revenue.
Qorvo supplies InGaP/GaAs HBT infrastructure drivers and GaAs pHEMT microwave amplifiers. Its QPA9121 operates at 2.3–5.0 GHz, while the QPA9908 is specified for 850–960 MHz with 4 W output capability. The QPA9119 broadens the HBT driver portfolio from 400 to 4,200 MHz. Product breadth supports multiple radio design opportunities, but the vendor’s total reported revenue includes other RF technologies and power products, so it cannot be used directly as GaAs amplifier market revenue.
MACOM competes in specialist microwave and defense transmit applications. Its MAAM26100 is a two-stage GaAs MMIC made with a 0.5-micron gate process, and the MAAP-011325 is a distributed GaAs pHEMT amplifier spanning DC–40 GHz. Analog Devices also offers GaAs pHEMT amplifiers from DC–22 GHz and 18–44 GHz. These portfolios demonstrate substantial differentiation by output power, frequency, gain and package. Customers compare device-specific qualification evidence rather than relying on the company’s general position in semiconductor sales.
Handset-facing suppliers such as Skyworks, Broadcom, Maxscend, Vanchip and other regional RF designers compete through multiband module integration and relationships with mobile OEMs. Some may provide GaAs PA die, integrated front-end modules, adjacent switches or other RF components. Qualcomm Technologies is prominent in modem-to-antenna systems, but its X85 and X105 platform announcements are not proof that every associated chip is GaAs. Supplier roles therefore require technology-level screening before assigning revenue or manufacturing status.
For aerospace and defense, lifecycle and traceability can outweigh the lowest unit price. Analog Devices identifies space and military uses for several screened GaAs pHEMT products, and MACOM describes radar, electronic warfare and instrumentation applications. The same customer may specify GaN for a high-power output stage and GaAs for a driver, meaning material substitution and complementary use occur within one transmitter. Suppliers that document junction-temperature behavior, lot traceability and long-term availability are better positioned in these specialized sockets.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Tier 1 — broad direct portfolios | Qorvo; Skyworks Solutions; MACOM; Analog Devices | Verified GaAs transmitter-amplifier products or established GaAs RF-front-end capabilities; tier denotes breadth of documented relevant offerings, not audited market-share rank. |
| Tier 2 — regional and specialist | Maxscend Technologies; Vanchip; Lansus Technologies; Zhejiang Chengchang; GaXtrem | Published company universe includes specialist and regional RF participants; their direct GaAs amplifier portfolios and current commercial scale differ by product line and require customer-specific qualification. |
| Profiled / adjacent | Broadcom; Qualcomm Technologies; CML Microcircuits; Mini-Circuits; Microchip | Broad RF, modem, distribution or specialist product roles can overlap the supply chain; no company is counted as a direct GaAs PA manufacturer solely because it appears in the profile list. |
Key companies profiled
- Skyworks
- Broadcom
- Qorvo
- Macom
- CML Microcircuits
- Mini-Circuits
- Qualcomm Technologies
- Analog Devices
- Maxscend Technologies
- Lansus Technologies
- Vanchip
- Zhejiang Chengchang
- Microchip
- GaXtrem
Product Technology, RF Design and Market Positioning
GaAs amplifier selection is driven by frequency, output compression, adjacent-channel linearity, power-added efficiency, thermal management and the degree of RF integration. Device-level specifications differ sharply: the Qorvo QPA9121 is a 2.3–5.0 GHz HBT driver, MACOM documents a DC–40 GHz pHEMT distributed amplifier, and Analog Devices offers a 32 dBm GaAs MMIC operating at 18–44 GHz. These examples describe distinct products, not a uniform GaAs performance promise.
High-volume cellular HBT designs emphasize power efficiency under complex modulation, module size, and stable operation across multiple band combinations. For infrastructure, digital predistortion support matters because radio vendors need a linear transmit chain at practical operating power. Qorvo specifies its QPA9121 with 27 dBm P3dB and 28 dB gain at 2.6 GHz, and its QPA9908 with 36% power-added efficiency at a specified average output condition. Those data points illustrate performance metrics that buyers can test against their own system requirements.
At microwave frequencies, pHEMT amplifiers often trade maximum output power against gain flatness and bandwidth. Analog Devices lists the ADPA7005 with up to 32 dBm saturated output power, 15.5 dB gain and an 18–44 GHz operating band; the ADPA7002 operates from 20–44 GHz. MACOM documents a GaAs pHEMT design from DC–40 GHz. In each case, the measured performance depends on bias, package, frequency and load, so a specification for one device cannot be generalized to all GaAs PA architectures.
Product positioning also reflects lifecycle risk. Qorvo labels its TGA2514N-FL GaAs pHEMT amplifier as not recommended for new designs and suggests an alternative, while Analog Devices distinguishes recommended products from parts no longer intended for new designs. Engineers in 2026 must consider whether a selected amplifier can be procured for the entire equipment life, particularly in satellite, military and industrial systems. Replacement choices can force board redesign even when the nominal RF frequency range appears similar.
Market Dynamics: Drivers, Restraints and Opportunities
The 2026–2036 demand trajectory reflects a mixture of handset RF complexity, selective network densification and specialist microwave electronics. These drivers are balanced by GaN substitution in high-power stages, silicon integration in lower-cost radio functions, gallium supply-chain exposure and demanding thermal qualifications. Impact percentages in the tables are directional modeled contributions to the industry-wide headline growth rate, not measured independent causal effects.
MARKET DRIVERS
Drivers Impact Analysis*
| Driver | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| 5G handset RF path complexity | +~2.4% | Asia-Pacific; North America; Europe | 2026–2036 |
| Network densification and mid-band radios | +~1.6% | Asia-Pacific; North America; Middle East | 2027–2034 |
| Microwave and aerospace communications | +~1.1% | North America; Europe; selected Asia-Pacific | 2026–2036 |
More qualified RF transmit paths per connected device
The evolution from legacy single-band transmitters to carrier-aggregated 4G and 5G devices increases the number of RF operating states that manufacturers must support. GaAs HBT stages remain useful where linearity, output power and battery efficiency are jointly constrained. GSMA counted more than 2 billion 5G connections at the end of 2024, while its 2026 India report identified around 450 million 5G connections. These figures indicate scale and transition, but the actual GaAs amplifier order is created only when a phone maker procures qualified RF front-end content.
Mid-band infrastructure and specialized transmitter demand
Wireless infrastructure upgrades support demand for efficient pre-driver and medium-power amplifiers, especially when radio designers need predictable gain and digital predistortion behavior. Qorvo lists a 2.3–5.0 GHz GaAs HBT driver and separately introduced a 3.3–4.2 GHz pre-driver for 5G massive-MIMO equipment in June 2025. These product announcements demonstrate the continued importance of RF chain design, although the technology of a particular announced pre-driver should not be assumed to be GaAs without a corresponding product specification.
High-frequency communications and electronic warfare
Specialist applications create demand for pHEMT amplifiers with broad microwave coverage and reliable screening. Analog Devices documents GaAs pHEMT power amplifiers at 18–44 GHz and 20–44 GHz, while MACOM supplies a DC–40 GHz distributed amplifier intended for electronic warfare, radar and test applications. Qualification cycles can be longer than those for handset parts, but engineering requirements create differentiated opportunities. The modeled pHEMT share of ~22% reflects this specialized value rather than the total defense or satellite systems budget.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Restraint | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| GaN substitution in high-output stages | −~1.3% | Global microwave and infrastructure designs | 2026–2036 |
| RF component price compression | −~0.9% | Handset and high-volume modules | 2027–2036 |
| Yield, gallium and thermal qualification risk | −~0.6% | Foundry and high-reliability supply chains | 2026–2032 |
Competing compound semiconductors reduce some GaAs sockets
Gallium nitride can provide advantages in high-power and high-frequency output stages, particularly when the thermal and voltage requirements justify the technology. Qorvo’s June 2025 K-band satellite amplifier release explicitly describes a GaN-on-SiC product, not a GaAs one. That distinction is material: growing satellite connectivity does not automatically translate into equal GaAs revenue growth. RF designers may pair a GaAs driver with a GaN final amplifier, or replace a GaAs stage entirely when performance and cost favor an alternative process.
Manufacturing cost and qualification constrain adoption
GaAs devices require specialized epitaxy, wafer processing and packaging controls, and power-amplifier efficiency depends on operating conditions rather than a single catalogue number. Buyers must qualify linearity, adjacent-channel leakage, temperature stability and reliability across real transmit waveforms. Long-lived industrial and aerospace equipment also requires continuity of supply. These constraints can extend design-in cycles and reduce the addressable market for suppliers unable to offer documented process control or suitable second-source options.
MARKET OPPORTUNITIES
Broadband microwave modules for aerospace and satellite terminals
GaAs pHEMT devices remain relevant to point-to-point radio, satellite ground terminals and aerospace communication equipment where moderate output power, frequency coverage and linearity can outweigh mass-market pricing. Analog Devices specifies an 8–14 GHz screened amplifier with 34.5 dBm saturated output and a separate 18–44 GHz MMIC with integrated detection. The opportunity is selective and specification-driven: suppliers can win qualified sockets by meeting the exact power, gain and lifecycle requirement rather than claiming the entire satellite equipment budget.
Lower-power infrastructure drivers and dense radio architectures
Network vendors continue to reduce radio size while improving efficiency and bandwidth. In June 2025, Qorvo introduced components for 32T and 64T massive-MIMO architectures, including a pre-driver amplifier with 38 dB gain and 400–600 MHz instantaneous bandwidth. Although the release does not establish GaAs content for every product, it demonstrates demand for compact RF stages. GaAs vendors able to meet those operating conditions with reliable linearity and competitive total system cost may expand their share of suitable transmitter designs.
Supply Chain and Commercialization
The GaAs power-amplifier value chain connects gallium and arsenic materials, compound-semiconductor epitaxy, wafer fabrication, device packaging and RF-system integration. Revenue in this market is recorded at the amplifier semiconductor or attributable module-content level, not at every upstream material or downstream handset transaction. The largest 2026 modeled end-user channel is handset OEM RF modules at ~59%, followed by network radio suppliers at ~24%.
Upstream materials. The quality and availability of GaAs substrates and epitaxial structures influence defect rates and repeatability. GaAs is a compound semiconductor rather than a silicon CMOS process substitute, and foundry qualification is specific to the transistor architecture. In a high-volume HBT programme, small yield changes can materially affect amplifier economics; in a microwave pHEMT programme, wafer uniformity and gain distribution can drive screening cost. The market does not count raw substrate revenue separately because that value is embodied in the final amplifier component.
Fabrication and device test. Manufacturing requires control of transistor geometry, passivation, metallization and RF wafer probing. MACOM’s MAAM26100 specification identifies a mature 0.5-micron GaAs gate process, while Analog Devices lists pHEMT amplifiers with different output-power and frequency specifications. These examples show why a generic GaAs wafer capacity figure cannot be converted directly into RF amplifier revenue. Manufacturers must test gain, compression, harmonics and stability under bias conditions relevant to the customer’s radio architecture.
Packaging and thermal reliability. A packaged amplifier must dissipate heat while maintaining predictable RF impedance and reliability. Analog Devices offers the ADPA7005 in both packaged and die configurations, while Qorvo specifies surface-mount HBT driver products for infrastructure. System designers choose among surface-mount, bare-die and high-reliability packages based on operating temperature, repair strategy and production scale. Thermal performance can dominate long-term output-power capability even when nominal data-sheet gain and frequency coverage appear attractive.
Sales channels and product lifecycle. High-volume mobile RF amplifiers typically enter products through long OEM qualification programmes, whereas aerospace and test customers may procure screened MMICs in smaller lots. Component distributors can broaden reach but do not establish manufacturing ownership. Device status matters: a product marked not recommended for new designs may still be serviceable in an installed platform but unsuitable for a new ten-year equipment programme. The commercial model therefore separates active direct suppliers, historical product lines and adjacent RF ecosystem participants.
Recent Developments in GaAs Amplifiers and Adjacent RF Demand
- 7 October 2026 Network adoption
GSMA reported that India had around 450 million 5G connections within a base of roughly 1.2 billion active mobile connections. The announcement underscores a growing installed market for multiband handsets and related RF transmitters, but does not disclose GaAs amplifier unit sales. For semiconductor suppliers, the actionable implication is the need for affordable, qualified RF front ends capable of supporting India’s cellular band combinations and power-efficiency requirements. Source - 15 September 2026 Device affordability
GSMA’s 2026 connectivity findings highlighted the continuing mobile internet usage gap and rising pressure on entry-level smartphone affordability. These conditions matter to GaAs HBT suppliers because RF front-end content must compete for a limited bill-of-materials budget even as devices add bands and features. The report does not provide a direct GaAs revenue statistic; its significance lies in the price and procurement pressure facing handset amplifier manufacturers. Source - 2 March 2026 Modem-RF platform
Qualcomm introduced the X105 5G Modem-RF system, describing Release 19 readiness, an integrated 6 nm RF transceiver and enhanced uplink capabilities. This is a platform-level development rather than a disclosure of GaAs power-amplifier die content. It illustrates the continued increase in RF-system complexity that suppliers must support through qualified gain, efficiency and linearity across transmit paths, while the exact semiconductor-material share remains a separate procurement question. Source - 6 February 2026 Semiconductor demand
The Semiconductor Industry Association reported that worldwide semiconductor sales reached USD 791.7 billion in 2025, up 25.6% from 2024. Logic and memory were major growth drivers, so the figure must not be interpreted as GaAs amplifier revenue. The development provides a broad capacity and supply-chain context for RF chip producers, while GaAs-specific sales depend on handset, infrastructure and specialist transmitter design wins rather than aggregate semiconductor growth. Source - 18 September 2025 GaAs HBT documentation
Qorvo updated the QPA9121 product data sheet for its 2.3–5.0 GHz GaAs HBT driver amplifier. The published specification lists 27 dBm P3dB and 28 dB gain at 2.6 GHz, with suitability for digital-predistortion transmit paths. This is a dated technical-document revision rather than evidence of a new product launch; it confirms a commercially documented GaAs infrastructure driver option relevant to mid-band radio designs. Source - 23 July 2025 Regional 5G demand
GSMA released its Mobile Economy Asia Pacific 2025 findings, reporting that 5G represented 18% of the region’s mobile connections in 2024 and could reach 50% by 2030. The figures describe network adoption, not component shipments. They support the direction of regional RF front-end demand while leaving actual GaAs amplifier content dependent on phone production, base-station architecture, technology substitution and component pricing. Source - 16 June 2025 Infrastructure RF components
Qorvo introduced a compact pre-driver amplifier and a BAW filter for 5G massive-MIMO and fixed wireless equipment. Its announcement cited a 3.3–4.2 GHz operating range, 38 dB gain and 400–600 MHz instantaneous bandwidth for the pre-driver. The release does not identify the semiconductor material of every announced device, so it is used as evidence of radio-stage requirements rather than proof of a new GaAs-only amplifier shipment. Source - 3 March 2025 Handset radio systems
Qualcomm announced its X85 modem-to-antenna platform for advanced 5G smartphones, PCs and fixed wireless access. The release emphasized improved connectivity and energy efficiency and identified planned customer sampling and commercial devices later in 2025. It does not quantify GaAs amplifier content. For GaAs suppliers, the development demonstrates the RF integration and qualification pressures associated with more capable mobile platforms, including multiband transmission and battery constraints. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Report title | Global GaAs RF Power Amplifier Market, Trends and Business Strategies 2026–2036 |
| Revenue boundary | GaAs transmitter PA dies, packaged amplifier chips and attributable GaAs PA content in RF modules; excludes GaN-only PAs, pure LNAs, complete radios, smartphones and raw wafer revenue. |
| Base year | 2026 — USD 26,409 million; revenue expressed in USD million. |
| Estimated year | 2027 — USD 29,129 million; constant anchor-derived growth assumption. |
| Forecast year | 2036 — USD 70,389 million; ten-year base-to-forecast compounding interval. |
| Growth rate | 10.3% CAGR over the 2027–2036 forecast period. |
| Historical window | 2021–2025; published monetary anchor years are 2023 and 2030. |
| Largest market | Asia-Pacific with an estimated ~46% 2026 revenue share; North America ~25%, Europe ~19%, South America ~5%, Middle East & Africa ~5%. |
| Product architecture | GaAs HBT, HEMT, pHEMT and MESFET amplifiers for radio-frequency transmitter chains; technology attribution is evaluated at the PA semiconductor content level. |
| By Type | GaAs HBT PA (~55%) · GaAs HEMT PA (~17%) · GaAs pHEMT PA (~22%) · GaAs MESFET PA (~6%) |
| By Application | Micro Base Station (~23%) · Cell Phone (~66%) · Others (~11%) |
| By End-user Channel | Handset OEM RF modules (~59%) · Network radio suppliers (~24%) · Aerospace and defense systems (~10%) · Industrial and test instrumentation (~7%) |
| By Region | Estimated 2026 regional allocations and country coverage; shares sum to 100% and do not represent audited company sales. Asia-PacificChina · India · Taiwan · Japan · South Korea · Southeast Asia North AmericaUnited States · Canada · Mexico EuropeGermany · France · United Kingdom · Italy · Nordic countries South AmericaBrazil · Argentina · Chile · Colombia Middle East & AfricaSaudi Arabia · UAE · South Africa · Israel · wider GCC |
| Key Companies Profiled | Skyworks · Broadcom · Qorvo · Macom · CML Microcircuits · Mini-Circuits · Qualcomm Technologies · Analog Devices · Maxscend Technologies · Lansus Technologies · Vanchip · Zhejiang Chengchang · Microchip · GaXtrem |
| Customization Scope | Country-specific GaAs PA semiconductor revenues, RF technology splits, handset versus infrastructure exposure, supplier status and technical qualification requirements can be analyzed separately. These custom views preserve the GaAs amplifier revenue boundary and do not merge GaN-only amplifier or complete device revenues. |
Frequently Asked Questions
What is the size and growth outlook of the global GaAs RF power amplifier market?
The market is valued at USD 26,409 million in 2026 and is projected to reach USD 70,389 million in 2036, with a 10.3% CAGR for 2027–2036. The totals follow the published 2023 and 2030 monetary anchors, rebased consistently to the tracker years. The definition covers GaAs transmitter power-amplifier semiconductor content, not complete phones or all RF front-end electronics. Regional and product allocations are modeled estimates rather than independent company-revenue measurements.
Which GaAs transistor technology has the largest share?
GaAs HBT PA is the largest modeled type at ~55% of 2026 revenue, ahead of pHEMT at ~22%, HEMT at ~17% and MESFET at ~6%. The estimate reflects high-volume cellular handset front-end applications and documented InGaP/GaAs HBT products from Qorvo. pHEMT and HEMT technologies have differentiated roles in microwave links, instrumentation and aerospace systems, where frequency, linearity and screening requirements often carry greater weight than handset production volumes.
Why does Asia-Pacific lead this market?
Asia-Pacific holds an estimated ~46% of 2026 revenue because mobile-device assembly, RF module procurement, semiconductor foundries and large wireless networks are concentrated across China, Taiwan, South Korea, Japan and India. GSMA reported that 5G accounted for 18% of regional mobile connections in 2024 and forecast 50% by 2030. Those figures support the direction of technology adoption but are not a direct measurement of GaAs PA shipments or market share.
How much demand comes from cell phones versus base stations?
Cell Phone accounts for an estimated ~66% of 2026 application revenue, Micro Base Station ~23% and Others ~11%. Handsets dominate because of their unit scale and multiband transmit requirements, whereas radio infrastructure uses fewer but often higher-value qualified amplifiers. A base station may pair a GaAs driver with a GaN final output stage, so counting the entire radio as GaAs revenue would overstate the product market.
How do GaAs HBT and pHEMT power amplifiers differ?
GaAs HBT amplifiers are prominent in compact mobile and selected infrastructure transmit paths, where efficiency, linearity and integration matter. GaAs pHEMT devices are frequently selected for broader microwave frequency coverage, as shown by MACOM’s DC–40 GHz amplifier and Analog Devices’ 18–44 GHz products. The categories are defined by transistor structure, not a fixed universal frequency boundary; real performance depends on bias, packaging, gain compression and customer system requirements.
Is gallium nitride replacing gallium arsenide in RF power amplifiers?
GaN is competing strongly in higher-output radio and satellite amplifier stages because its material properties can support demanding power density and voltage requirements. Qorvo’s 2025 K-band satellite PA announcement explicitly describes GaN-on-SiC technology, which is excluded from this GaAs-only revenue boundary. GaAs remains useful in HBT handset amplifiers, microwave drivers and certain pHEMT products. Mixed-technology transmitter chains can use both materials without making their revenue interchangeable.
Which companies are important in GaAs RF power amplifiers?
The profiled company universe includes Skyworks, Broadcom, Qorvo, MACOM, CML Microcircuits, Mini-Circuits, Qualcomm Technologies, Analog Devices, Maxscend, Lansus, Vanchip, Zhejiang Chengchang, Microchip and GaXtrem. Their roles are not identical: some supply documented GaAs amplifier products, while others provide RF integration, modem platforms or adjacent components. No precise vendor market-share ranking is asserted without GaAs-only revenue disclosures and consistent product boundaries.
What technical specifications should a buyer compare?
Key parameters include operating band, gain, P1dB or P3dB compression, saturated output power, third-order intercept, power-added efficiency, supply current, package thermal resistance and digital-predistortion compatibility. For example, Qorvo lists a 2.3–5.0 GHz GaAs HBT driver with 27 dBm P3dB, while Analog Devices documents an 18–44 GHz GaAs pHEMT MMIC. The best choice depends on the transmitter architecture rather than on maximum gain alone.
What are the principal supply-chain risks?
GaAs amplifier production depends on compound-semiconductor substrate and epitaxy quality, specialized wafer processing, reliable packaging and customer qualification. Risks include wafer yield variation, gallium sourcing exposure, device obsolescence and lack of a second qualified supplier. Aerospace and industrial buyers can face longer replacement cycles than handset OEMs. A product marked not recommended for new designs should not automatically be chosen for a fresh long-life programme, even if the legacy part remains orderable.
How should regional and segment share estimates be interpreted?
The reported ~46% Asia-Pacific allocation, ~55% HBT type share and ~66% cell-phone application share are modeled 2026 revenue estimates built from the published market anchors, manufacturer product evidence and wireless deployment indicators. They are not direct audited sales splits. Each segmentation axis totals 100% independently and describes the same global market from a different perspective; adding regional, product and application percentages together would double-count the underlying revenue.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF