
Key Statistics
Key Takeaways
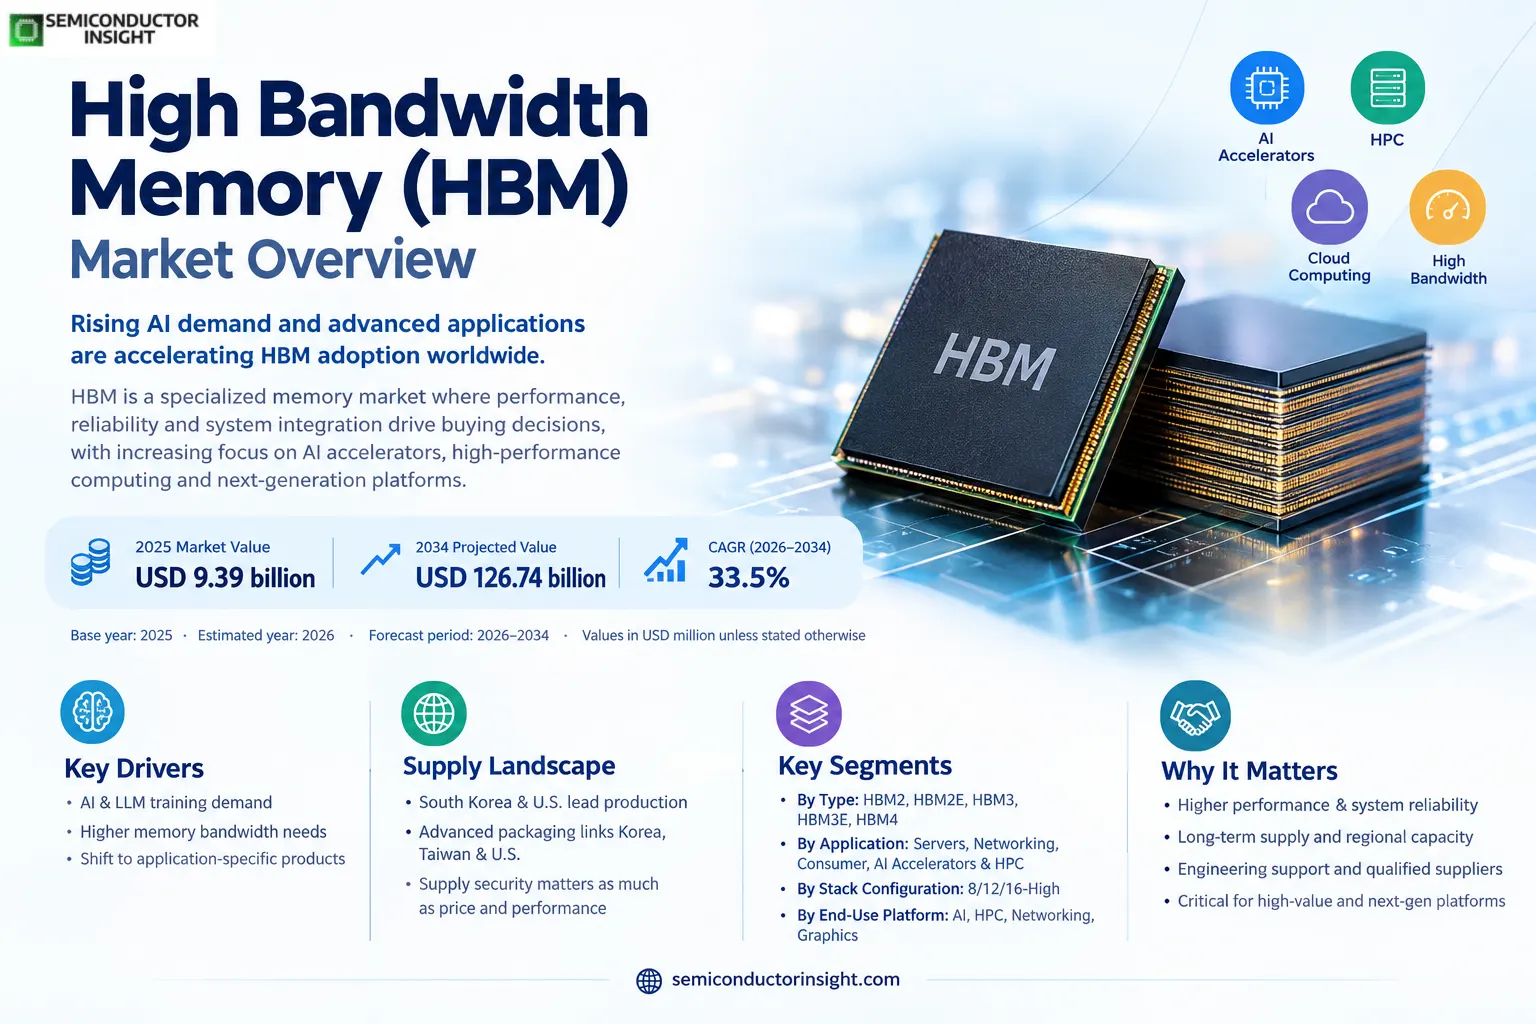
- Market size and growth: USD 9.39 billion in 2025, rising to USD 126.74 billion by 2034 at a 33.5% CAGR over 2026–2034.
- Asia Pacific is the largest market in 2025 because the region combines major end-use demand with a dense electronics and semiconductor supply base.
- HBM2 is a core product category, while technology migration is increasing the value of higher-performance and application-specific variants.
- Primary demand driver: AI accelerators and large language model training are increasing memory-bandwidth requirements faster than conventional DRAM architectures can accommodate.
- Structural restraint: HBM supply is constrained by advanced DRAM yields, through-silicon-via processing, thermal control, packaging capacity and tight qualification cycles with accelerator vendors.
- Growth opportunity: HBM4 and HBM4E create a new value pool around wider interfaces, custom base dies, higher stack counts and system-level power efficiency.
High Bandwidth Memory (HBM) Market Overview
HBM market was valued at USD 9.39 billion in 2025 and is projected to reach USD 126.74 billion by 2034, expanding at a CAGR of 33.5% during 2026–2034. Asia Pacific is the largest regional market in 2025.
High Bandwidth Memory (HBM) is a specialized electronics market in which performance, reliability and system integration determine purchasing decisions. Buyers typically qualify products against electrical, thermal, mechanical and lifecycle requirements before a supplier can enter a production program. This creates meaningful switching costs once a design is approved, while also raising the technical threshold for new suppliers seeking high-volume business.
AI accelerators and large language model training are increasing memory-bandwidth requirements faster than conventional DRAM architectures can accommodate. The commercial effect is a shift from commodity selection toward application-specific products that deliver measurable system benefits. Suppliers that can document reliability, maintain stable lead times and support customer engineering teams are positioned to capture a larger share of recurring design-win revenue.
Production is concentrated in South Korea and the United States-led memory ecosystem, while advanced packaging and base-die foundry capacity increasingly links Korea, Taiwan and the United States. This geographic concentration matters because supply security now influences sourcing alongside price and performance. OEMs increasingly seek dual sourcing, regional inventory and long-term capacity visibility, especially for components used in high-value systems where a shortage can delay an entire platform launch.
Segment Analysis: By Type
By type, the market includes HBM2, HBM2E, HBM3, HBM3E, HBM4. Product selection depends on the balance between performance, integration complexity, thermal behavior, qualification requirements and cost. The largest revenue pool is concentrated in established architectures, while newer variants generally grow faster when they solve a clear system bottleneck.
| Type | Commercial role | Market position |
|---|---|---|
| HBM2 | Defines the main product architecture and purchasing specification. | Leading / core segment. Demand depends on performance, qualification, supply continuity and total system economics rather than a single component specification. |
| HBM2E | Defines the main product architecture and purchasing specification. | High-growth segment. Demand depends on performance, qualification, supply continuity and total system economics rather than a single component specification. |
| HBM3 | Defines the main product architecture and purchasing specification. | Established segment. Demand depends on performance, qualification, supply continuity and total system economics rather than a single component specification. |
| HBM3E | Defines the main product architecture and purchasing specification. | Established segment. Demand depends on performance, qualification, supply continuity and total system economics rather than a single component specification. |
| HBM4 | Defines the main product architecture and purchasing specification. | Established segment. Demand depends on performance, qualification, supply continuity and total system economics rather than a single component specification. |
Segment Analysis: By Application
By application, demand spans Servers, Networking, Consumer, AI Accelerators & HPC. Purchasing behavior differs materially across these applications because system reliability, operating environment, qualification duration and replacement cost vary. High-value applications favor suppliers with deeper engineering support, while consumer and high-volume applications place greater weight on unit economics and manufacturing scale.
| Application | Purchasing trigger | Demand characteristics |
|---|---|---|
| Servers | Links demand to system-level performance and qualification requirements. | Leading / core segment. Demand depends on performance, qualification, supply continuity and total system economics rather than a single component specification. |
| Networking | Links demand to system-level performance and qualification requirements. | High-growth segment. Demand depends on performance, qualification, supply continuity and total system economics rather than a single component specification. |
| Consumer | Links demand to system-level performance and qualification requirements. | Established segment. Demand depends on performance, qualification, supply continuity and total system economics rather than a single component specification. |
| AI Accelerators & HPC | Links demand to system-level performance and qualification requirements. | Established segment. Demand depends on performance, qualification, supply continuity and total system economics rather than a single component specification. |
By Stack Configuration
| Stack Configuration | Market relevance |
|---|---|
| 8-High | Relevant to product selection, qualification and supplier differentiation. |
| 12-High | Relevant to product selection, qualification and supplier differentiation. |
| 16-High | Relevant to product selection, qualification and supplier differentiation. |
By End-Use Platform
| End-Use Platform | Market relevance |
|---|---|
| AI Accelerators | Creates a distinct design, performance or procurement requirement within the market. |
| High-Performance Computing | Creates a distinct design, performance or procurement requirement within the market. |
| Networking | Creates a distinct design, performance or procurement requirement within the market. |
| Graphics | Creates a distinct design, performance or procurement requirement within the market. |
Regional Analysis
Asia Pacific leads the HBM market in 2025. Regional demand differs by manufacturing concentration, end-use investment, qualification requirements and access to local supply chains. The strongest opportunities are therefore not identical across regions, even where the same product family is used.
How does regional demand differ across the market?
Regional competition is shaped by where products are designed, where they are manufactured and where the final systems are deployed. Asia Pacific benefits from electronics and semiconductor manufacturing density, North America concentrates advanced system design and cloud or defense demand, while Europe remains important in automotive, industrial and regulation-led applications. South America and the Middle East & Africa are smaller but can generate attractive project-led demand.
| Region | Position | Growth outlook | Demand profile |
|---|---|---|---|
| Asia Pacific | Largest | High | Largest manufacturing base and principal production center, led by South Korea and Taiwan. |
| North America | Established | High | Large demand center for AI accelerators, cloud infrastructure and HPC systems. |
| Europe | Established | Moderate | Selective demand from HPC, automotive compute and sovereign AI initiatives. |
| South America | Established | Moderate | Small installed base, with demand concentrated in hyperscale and research infrastructure imports. |
| Middle East & Africa | Established | Moderate | Emerging demand tied to sovereign AI, cloud data centers and high-performance computing projects. |
Competitive Landscape
Competition is driven by technical qualification, customer access, manufacturing consistency and the ability to support product transitions. Market leaders generally combine proprietary process knowledge with broad application engineering, while specialist suppliers compete through narrower performance advantages, customization or regional service.
The competitive structure rewards suppliers that can convert R&D into qualified production rather than simply demonstrating laboratory performance. Long customer qualification cycles protect incumbents once designed in, but they also create opportunities during architecture changes when OEMs reconsider vendors, package formats and performance targets.
Supply reliability has become a central differentiator. Customers increasingly evaluate capacity commitments, geographic resilience, quality systems and lifecycle support in parallel with electrical specifications. This favors companies able to coordinate manufacturing, test, logistics and engineering support across multiple regions.
| Company | Position | Competitive focus |
|---|---|---|
| SK hynix | Established participant | Competes through technology, qualification, portfolio breadth and customer relationships. |
| Samsung Electronics | Established participant | Competes through technology, qualification, portfolio breadth and customer relationships. |
| Micron Technology | Established participant | Competes through technology, qualification, portfolio breadth and customer relationships. |
| AMD | Established participant | Competes through technology, qualification, portfolio breadth and customer relationships. |
| NVIDIA | Established participant | Competes through technology, qualification, portfolio breadth and customer relationships. |
| Intel | Established participant | Competes through technology, qualification, portfolio breadth and customer relationships. |
Production Capacity Analysis
Production is concentrated in South Korea and the United States-led memory ecosystem, while advanced packaging and base-die foundry capacity increasingly links Korea, Taiwan and the United States.
Capacity expansion is not determined by floor space alone. Yield learning, specialty equipment, trained personnel, material quality and customer qualification can all delay effective output after new equipment is installed. For this reason, announced capacity and immediately usable market supply can diverge, especially in advanced products with tight process windows.
Market Dynamics
The market is shaped by a combination of end-system performance requirements, technology migration, supply-chain resilience and cost pressure. Growth is strongest where the component removes a system bottleneck or enables a new architecture, while adoption slows when qualification complexity or alternative technologies reduce the economic advantage.
AI accelerators and large language model training are increasing memory-bandwidth requirements faster than conventional DRAM architectures can accommodate. At the same time, hbm supply is constrained by advanced dram yields, through-silicon-via processing, thermal control, packaging capacity and tight qualification cycles with accelerator vendors. Suppliers therefore need to balance innovation with manufacturability, reliability and commercial discipline.
Market Drivers
Drivers Impact Analysis
| Driver | Impact | Commercial implication |
|---|---|---|
| System performance | High | Directly increases component content or value per system. |
| Technology migration | High | Creates replacement and redesign opportunities. |
| Supply resilience | Medium | Favors qualified vendors with stable capacity. |
System-level performance requirements
AI accelerators and large language model training are increasing memory-bandwidth requirements faster than conventional DRAM architectures can accommodate. This directly affects vendor selection because component-level specifications increasingly translate into measurable platform performance, energy efficiency, thermal headroom or reliability. Products that create a clear system benefit can sustain better pricing and deeper customer engagement.
Design complexity and integration
As electronic systems become more integrated, component suppliers are expected to provide reference designs, simulation support, qualification data and predictable lifecycle management. This broadens competition beyond unit price and favors vendors that can reduce engineering time for OEMs while maintaining stable production quality.
Electrification and digitalization
The continued shift toward connected, electrified and software-defined systems increases the number and value of electronics used in vehicles, industrial equipment, data centers and consumer devices. This expands the addressable opportunity for suppliers whose products improve power efficiency, signal integrity, memory bandwidth, durability or user experience.
Regional supply-chain investment
Governments and manufacturers are investing in more resilient electronics and semiconductor supply chains. Even where these programs do not directly subsidize the market, they influence localization, inventory strategy and supplier qualification, creating opportunities for vendors with manufacturing or engineering support close to major customers.
Market Restraints
Restraints Impact Analysis
| Restraint | Impact | Commercial implication |
|---|---|---|
| Qualification burden | High | Lengthens time to revenue and raises engineering cost. |
| Input cost volatility | Medium | Compresses margins when contracts limit price changes. |
| Alternative technologies | Medium | Can reduce content per system in selected applications. |
Qualification and integration cost
HBM supply is constrained by advanced DRAM yields, through-silicon-via processing, thermal control, packaging capacity and tight qualification cycles with accelerator vendors. These barriers slow supplier switching and can delay commercialization, particularly when products enter safety-critical, high-reliability or high-volume platforms. Smaller suppliers may have strong technology but still face long sales cycles before meaningful production revenue begins.
Cost pressure and substitution
OEMs continue to reduce bill-of-material cost and consolidate functions into more integrated devices. Suppliers must therefore show that the component provides a measurable system advantage. Where that advantage is weak, buyers may substitute lower-cost alternatives or redesign the function into another subsystem.
Market Opportunities
Next-generation architectures
HBM4 and HBM4E create a new value pool around wider interfaces, custom base dies, higher stack counts and system-level power efficiency. Vendors that engage early with platform designers can shape specifications, improve design-win probability and secure longer revenue lifecycles once the architecture moves into production.
Application-specific products
Specialized products for automotive, industrial, AI, medical or aerospace systems can command stronger margins because qualification requirements are tighter and failure costs are higher. The commercial opportunity is strongest where suppliers combine product performance with documentation, traceability and long-term availability.
Regional localization
Customers are diversifying sourcing and building more regional resilience into electronics supply chains. Local technical support, shorter logistics routes and qualified second-source options can therefore become competitive advantages even when manufacturing economics still favor a concentrated global production base.
Lifecycle services
Engineering support, failure analysis, reliability data and product-change management create service-based differentiation around the physical component. These capabilities strengthen customer retention and can reduce the risk of substitution when a market moves through technology transitions or periods of constrained supply.
Supply Chain Analysis
| Stage | Value creation and bottlenecks |
|---|---|
| Raw materials / upstream | Purity, consistency, specialty materials and process inputs determine yield and performance. |
| Component manufacturing | Value is created through process control, device architecture, testing and product-specific qualification. |
| Packaging / integration | System integration determines thermal performance, reliability, footprint and manufacturability. |
| OEM / end user | Design wins, lifecycle support and supply assurance determine recurring revenue and replacement demand. |
The upstream stage determines material consistency and the starting cost structure. Manufacturing then converts process control into yield and product performance, while packaging or integration determines whether the component can meet system-level thermal, mechanical and electrical requirements. The OEM stage captures value through design ownership, platform integration and end-market access. Bottlenecks at any stage can affect the whole chain because qualification limits rapid supplier substitution.
Recent Developments
Report Scope & Segmentation
| Attribute | Coverage |
|---|---|
| Market definition | High Bandwidth Memory (HBM) products and systems covered by the stated segmentation. |
| Base year | 2025 |
| Estimated year | 2026 |
| Forecast period | 2026–2034 |
| By Type | HBM2, HBM2E, HBM3, HBM3E, HBM4 |
| By Application | Servers, Networking, Consumer, AI Accelerators & HPC |
| By Stack Configuration | 8-High, 12-High, 16-High |
| By End-Use Platform | AI Accelerators, High-Performance Computing, Networking, Graphics |
| Regions | North America, Europe, Asia Pacific, South America, Middle East & Africa |
| Companies | SK hynix, Samsung Electronics, Micron Technology, AMD, NVIDIA, Intel |
Frequently Asked Questions
What is the High Bandwidth Memory (HBM) market size in 2025?
What is the projected High Bandwidth Memory (HBM) market size by 2034?
What is the CAGR of the High Bandwidth Memory (HBM) market from 2026 to 2034?
Which region leads the High Bandwidth Memory (HBM) market?
What are the main product types?
What are the key applications?
What is the main growth driver?
What is the main restraint?
Where are the strongest opportunities?
Which companies are active in the market?
Research Sources & Evidence Base
View primary and official sources used in this overview
- SK hynix: HBM4 development and mass-production readiness.
- SK hynix: Q2 2026 business results and HBM4 shipments.
- Micron: HBM3E product and performance information.
- Samsung Electronics: 36 GB HBM3E 12H development.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF




Be the first to review “High Bandwidth Memory (HBM) Market Size, Share & Industry Analysis, By Type (HBM2, HBM2E, HBM3, HBM3E, HBM4), By Application (Servers, Networking, Consumer, AI Accelerators & HPC), By Stack Configuration (8-High, 12-High, 16-High), By End-Use Platform (AI Accelerators, High-Performance Computing, Networking, Graphics), and Regional Forecast, 2026-2034”