Key Statistics
Key Takeaways
- Smart Watches are a central device category because NFC-equipped watches combine payment credentials with a wearable form factor and can support card-token or wallet-based Tap & Pay.
- Grocery Stores are a leading everyday-use application because frequent low-value purchases benefit directly from quick contactless checkout at NFC-enabled PoS terminals.
- India is the full market scope; demand is concentrated around large urban payment ecosystems, metro/transit networks, premium smartphone users and modern retail rather than a single published subregional revenue leader.
- UPI Tap & Pay is broadening NFC beyond card wallets. NPCI’s 2026 guidelines explicitly support Scan or Tap to Pay through NFC-enabled UPI interactions.
- Wearables are moving beyond watches. RuPay On-The-Go, Indus PayWear and bank-issued wristbands, rings, clasps and stickers demonstrate a wider hardware ecosystem for contactless payment.
- NCMC links payments with mobility. Contactless chips can support metro, bus, toll, parking and retail transactions, making transit one of India’s clearest physical use cases for NFC payment devices.
India NFC Payment Devices Market Overview
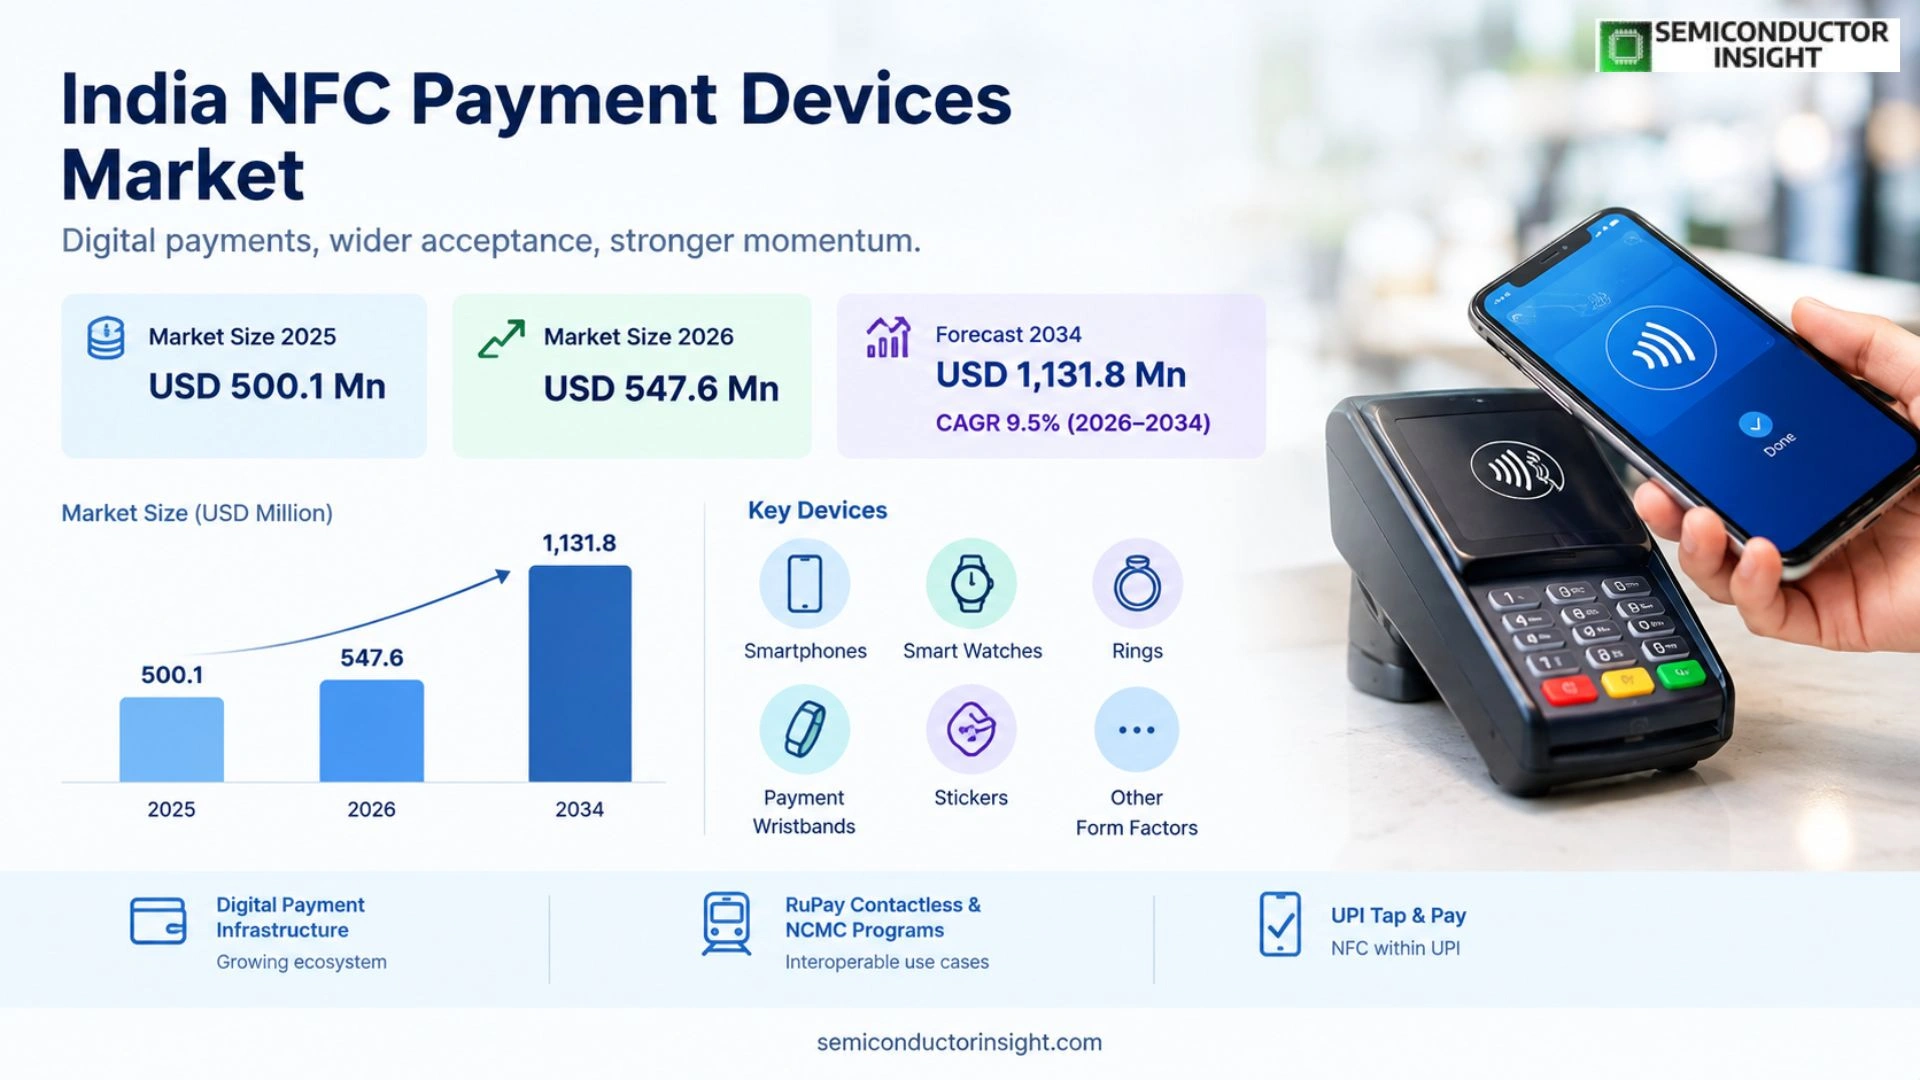
India NFC Payment Devices market is valued at USD 500.1 million in 2025, is estimated at USD 547.6 million in 2026, and is projected to reach USD 1,131.8 million by 2034, representing a CAGR of 9.5% during 2026–2034. India (national market) is the 2025 market-position reference used in this overview.
Base year: 2025 · Estimated year: 2026 · Forecast period: 2026–2034 · Values in USD million unless otherwise stated
NFC payment devices use near-field communication to exchange payment credentials with a compatible terminal over a very short distance. In India, the device ecosystem includes smartphones, smart watches, fitness-oriented wearables, payment wristbands, rings, stickers and other form factors that can present tokenized card or wallet credentials at contactless points of sale.
The market is expanding alongside India’s broader digital-payment infrastructure. RuPay Contactless and National Common Mobility Card programs have created interoperable use cases across retail and transit, while UPI Tap & Pay adds an NFC interaction path within the UPI ecosystem. This gives merchants and device makers multiple payment rails that can use the same contactless hardware layer.
Security architecture is a major product differentiator. Device-based payments can use tokenization, secure hardware, biometric authentication and issuer controls so the merchant receives a token rather than the underlying card number. Banks and wallet platforms also provide device lock, transaction monitoring and card-management tools that increase consumer confidence in wearable payments.
Segment Analysis: By Type
By type, the market is segmented into Smart Watches, Fitness Trackers, Payment Wristbands, Smart Rings, and Others. Smart watches are the most visible multifunction category, while dedicated rings and wristbands are gaining relevance through no-charge and always-wearable contactless designs.
| Segment Category | Sub-Segments | Key Insights |
|---|---|---|
| By Type | Smart Watches | Combine digital-wallet functionality, display, authentication and NFC payment capability. They suit consumers already using connected wearables for health, notifications and mobility. |
| By Type | Fitness Trackers | Compact activity bands can integrate NFC or payment credentials without requiring a full smartwatch experience, supporting low-power everyday wear. |
| By Type | Payment Wristbands | Dedicated contactless bands can work without a phone during payment and are well suited to transit, events, campuses and controlled-access environments. |
| By Type | Smart Rings | Passive or low-power rings provide tap-and-pay functionality in a small waterproof form factor and can be tokenized to a bank card. |
| By Type | Others | Includes stickers, keychains, watch clasps and other NFC accessories that extend contactless payment to existing objects or devices. |
Why are payment wearables gaining relevance beyond smartphones?
A wearable can be faster to present at a terminal, easier to use during transit or exercise and, in passive form factors, may not need charging. India already has commercial examples of payment rings, watch clasps, wristbands and stickers. The strongest products combine a secure token, simple provisioning and the ability to work at standard contactless terminals without requiring a specialized merchant device.
Segment Analysis: By Application
By application, the market covers Grocery Stores, Bars & Restaurants, Drug Stores, Entertainment Centers, and Others?. Grocery and food-service transactions are attractive because contactless payment shortens checkout time and supports frequent low-value purchases.
| Application | Demand characteristics | Key Insights |
|---|---|---|
| Grocery Stores | Frequent everyday purchases benefit from quick tap interactions and wide deployment of card-acceptance terminals. | A strong recurring-use environment where faster checkout can make contactless behavior habitual. |
| Bars & Restaurants | Contactless payments simplify counter service, quick-service restaurants and table-side terminal payments. | A high-frequency urban use case supported by modern PoS deployment and wallet adoption. |
| Drug Stores | Pharmacy and healthcare retail use standard contactless acceptance infrastructure for consumer purchases. | Steady demand with a strong need for secure, simple payment experiences. |
| Entertainment Centers | Cinemas, stadiums, events and leisure venues can combine access control with cashless purchases. | An attractive wearable-payment use case because the same device can support entry and in-venue transactions. |
| Others? | Includes transit, parking, campuses, toll-related services and other NFC-enabled payment environments. | A broad opportunity driven by NCMC, RuPay On-The-Go and UPI Tap & Pay expansion. |
Why is transit strategically important to India’s NFC device market?
Transit creates repeated physical tap behavior and requires fast local processing at gates. NCMC is designed for interoperable use across metros, buses and other mobility services and can also support retail or parking. This gives contactless cards and wearables a clear daily utility that is difficult to replicate with slower payment interactions during peak commuting periods.
Regional Analysis
India is the complete geographic scope of this market. Within the country, NFC-device demand is strongest in urban clusters with dense contactless PoS acceptance, metro or NCMC infrastructure, premium device adoption and large modern-retail footprints.
How do India’s main demand clusters differ?
West and South India combine large technology, financial-services and urban-transit ecosystems. North India has major NCR retail and mobility demand. East India is led by Kolkata and growing modern retail, while Central & Northeast India offer a smaller but expanding base through banking digitization, urban transit and smartphone adoption.
| India zone | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| West India | Large urban payment cluster | Strong | Mumbai, Pune, Ahmedabad and retail/transit use | Issuer support, PoS acceptance and device availability |
| South India | Technology & transit cluster | Strong | Bengaluru, Hyderabad, Chennai and high smartphone use | Wallet support, transit integration and premium device base |
| North India | NCR-led demand cluster | Strong | Delhi NCR, banking, retail and metro mobility | Acceptance infrastructure and issuer partnerships |
| East India | Emerging urban cluster | Moderate | Kolkata, retail and public transport | Affordability, bank support and merchant acceptance |
| Central & Northeast India | Developing market | Selective | Urban digitization and mobility expansion | Distribution, affordability and interoperable payments |
Competitive Landscape
Companies covered include Samsung India, Apple India, OnePlus India, Google India, Xiaomi India, Sony India, Huawei India, Motorola India, Nokia India and LG Electronics India. The broader device-payment ecosystem also includes banks, card networks, NPCI, tokenization providers and wearable manufacturers.
Samsung has the clearest active device-wallet position in India through Samsung Wallet, Samsung Pay and supported Galaxy Watch Tap & Pay. Its advantage combines NFC hardware, secure token storage, biometrics and issuer partnerships.
Apple, Google and Android handset brands influence the addressable device base through NFC hardware and secure-element capabilities, although payment-service availability varies by ecosystem and issuer support. The report company list therefore spans both active payment platforms and device manufacturers that determine NFC capability.
Dedicated wearable providers compete through rings, wristbands, watch clasps and stickers that can work without opening a phone. Banks and NPCI programs are important commercialization partners because the underlying credential, token and transaction rules determine whether the hardware can be used at ordinary contactless terminals.
| Competitive tier | Representative companies | Commercial basis |
|---|---|---|
| Device-wallet ecosystem | Samsung India; Google India; Apple India | NFC smartphones, secure wallets, tokenization support and user authentication. |
| Smartphone & wearable hardware brands | OnePlus India; Xiaomi India; Motorola India; Nokia India; Sony India; LG Electronics India | NFC-capable device installed base, wearable hardware and consumer distribution. |
| Payment & provisioning ecosystem | NPCI; banks; card networks; wearable issuers | Credential issuance, tokenization, NCMC, merchant acceptance and interoperability. |
Key Participants
Samsung India, Apple India, OnePlus India, Google India, Xiaomi India, Sony India, Huawei India, Motorola India, Nokia India, LG Electronics India.
Production Capacity Analysis
Production capacity in this market is a combination of consumer-device manufacturing, NFC chip and secure-element integration, payment-token provisioning, card/wearable personalization and certification against payment-network and issuer requirements.
Smartphones and smart watches are manufactured through large electronics supply chains, with NFC controllers, secure elements or embedded secure environments integrated during device design.
Dedicated wearables use small NFC antennas and secure payment chips packaged into rings, wristbands, clasps, stickers and other objects. Personalization associates the hardware with a tokenized payment credential rather than exposing the physical card number.
Commercial scaling also requires software and issuer infrastructure. Wallet certification, token lifecycle management, card controls, NFC terminal compatibility and fraud monitoring are part of the effective production stack even though they are not physical device assembly.
| Capacity layer | Where it concentrates | Commercial constraint |
|---|---|---|
| Device manufacturing | India and Asian electronics manufacturing hubs | NFC hardware integration, secure-element availability and device compatibility. |
| Wearable / card personalization | Mumbai, Navi Mumbai and other certified bureaus | Secure token provisioning, personalization and payment-network certification. |
| Wallet & token services | Banks, NPCI and device-platform providers | Issuer support, token lifecycle, authentication and security. |
| Merchant / transit acceptance | Retail and mobility operators across India | NFC PoS availability, NCMC compatibility and user experience. |
Market Dynamics
Growth is driven by India’s digital-payment scale, expanding contactless acceptance and device innovation. Competition from QR-based UPI remains strong, so NFC products need to deliver clear speed, convenience, transit or wearable advantages.
Market Drivers
| Factor | Directional impact | Why it matters |
|---|---|---|
| UPI Tap & Pay | High | NFC becomes an interaction method inside India’s largest digital-payment ecosystem. |
| NCMC mobility | High | Transit and retail interoperability creates frequent daily tap use. |
| Premium smartphone & watch adoption | Medium-High | More consumers own NFC-capable devices with secure wallets. |
| Payment wearables | Medium-High | Rings, wristbands and stickers create phone-free payment use cases. |
UPI makes NFC more locally relevant
NFC no longer has to depend only on global card-wallet models. UPI Tap & Pay can use NFC to identify a payee and keep the familiar UPI authentication flow.
Transit creates habitual tap behavior
Metro and mobility gates reward speed and low-friction interaction. NCMC turns contactless hardware into a daily-use product rather than an occasional retail novelty.
Wallet partnerships increase usable device coverage
Every additional issuer and card network supported by a wallet increases the number of consumers who can activate Tap & Pay on existing hardware.
Wearables solve contexts where phones are inconvenient
Fitness, commuting, events and quick-service purchases can favor a ring, watch or wristband that is already accessible on the body.
Market Restraints
| Factor | Directional impact | Why it matters |
|---|---|---|
| QR-based UPI substitution | High | Scan-and-pay already has huge acceptance and consumer familiarity. |
| Fragmented wallet / issuer support | High | A device may have NFC but still lack supported card provisioning. |
| Premium hardware cost | Medium-High | Smart watches and rings can be expensive relative to QR payments using an existing phone. |
| Security & lost-device concerns | Medium | Consumers need confidence in tokenization, blocking and authentication. |
QR acceptance is already ubiquitous
Merchants can accept UPI with a printed QR at very low cost, reducing the urgency to buy or upgrade NFC terminals in every location.
Payment capability depends on ecosystem support
NFC hardware alone does not guarantee Tap & Pay. Banks, networks, wallet providers and device security must all be compatible.
Dedicated wearables need a clear value proposition
A payment ring or band competes with cards and phones that users already own. Convenience, transit integration or lifestyle design must justify the extra device.
Trust is essential for wearable payments
Consumers need simple ways to lock lost devices, view transactions and understand tokenization. Poor controls can slow adoption even when technology works reliably.
Market Opportunities
UPI NFC smart tags
Merchant Tap & Pay can extend UPI into contactless interactions without abandoning the domestic payment rail.
NCMC wearables
Rings, watches and wristbands can combine transit, parking and retail payments.
Bank-tokenized rings & clasps
No-charge or passive form factors can address consumers who want phone-free payments.
Event & campus payments
One device can combine access control and spending in stadiums, colleges or corporate campuses.
Supply Chain Analysis
NFC Hardware. Device makers determine antenna performance, secure hardware and form factor. Passive wearables can operate without batteries, while smart watches add richer user interaction.
Credential Provisioning. Tokenization replaces the actual card number with a device-specific credential, reducing the impact of stolen payment data.
Merchant / Transit Acceptance. The contactless symbol, PoS firmware and transit certification determine where a device can be used. Interoperability is especially important for NCMC.
Settlement & Control. Banks and payment platforms manage authorization, PIN or biometric rules, device blocking and consumer dispute processes.
Recent Developments in the India NFC Payment Devices Market
Developments tracked to September 2026. Entries use official publication dates where available.
-
10 September 2026UPI Tap & PayIndia expanded NFC-based Tap & Pay within UPI, enabling compatible smartphones to initiate contactless transactions at supported merchant terminals. The move strengthens NFC as a domestic payment interaction rather than only a card-wallet feature.
-
June 2026Merchant guidelinesNPCI’s updated BHIM-UPI guidelines specify Scan or Tap to Pay merchant presentation with an NFC contactless symbol. The guidance formalizes NFC interaction within UPI merchant hardware and QR layouts.
-
9 March 2026MobilityPhonePe launched a RuPay On-The-Go NCMC card for offline tap-and-pay transit across NCMC-enabled services. The product supports metro, bus, train, toll and parking use.
-
30 October 2025WalletSamsung India expanded Samsung Wallet with new Tap & Pay partnerships, FOREX-card support and simpler UPI onboarding. The changes broaden the payment utility of NFC-capable Galaxy devices.
-
8 October 2025IoT paymentsNPCI extended UPI Circle to IoT devices and software profiles including smart watches, smart glasses and connected devices. This broadens the competitive landscape for device-based payments beyond traditional card-token NFC.
Report Scope & Segmentation
| Attribute | Coverage |
|---|---|
| Report title | India NFC Payment Devices Market Emerging Trends, Technological Advancements, and Business Strategies 2026-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| By Type | Smart Watches; Fitness Trackers; Payment Wristbands; Smart Rings; Others |
| By Application | Grocery Stores; Bars & Restaurants; Drug Stores; Entertainment Centers; Others? |
| Regions | West India; South India; North India; East India; Central & Northeast India |
| Companies | Samsung India; Apple India; OnePlus India; Google India; Xiaomi India; Sony India; Huawei India; Motorola India; Nokia India; LG Electronics India |
| Customization scope | Country, segment, company, application, technology, production and competitive-detail customization available within the study scope. |
Frequently Asked Questions
What is the size of the India NFC Payment Devices market?
The India NFC Payment Devices market is valued at USD 500.1 million in 2025, is estimated at USD 547.6 million in 2026, and is projected to reach USD 1,131.8 million by 2034, representing a 9.5% CAGR during 2026–2034. This remains commercially relevant because technical qualification, security or reliability, lifecycle support and supply continuity can materially affect buyer selection across the 2026–2034 forecast period. This remains commercially relevant because technical qualification, security or reliability, lifecycle support and supply continuity can materially affect buyer selection across the 2026–2034 forecast period.
What geography does the report cover?
The report covers India. Within the country, demand is strongest in large urban retail, transit and technology clusters with dense contactless acceptance and high NFC-device ownership. This remains commercially relevant because technical qualification, security or reliability, lifecycle support and supply continuity can materially affect buyer selection across the 2026–2034 forecast period. This remains commercially relevant because technical qualification, security or reliability, lifecycle support and supply continuity can materially affect buyer selection across the 2026–2034 forecast period.
Which device types are covered?
The report covers Smart Watches, Fitness Trackers, Payment Wristbands, Smart Rings and Others, including other NFC accessories such as stickers or clasps. This remains commercially relevant because technical qualification, security or reliability, lifecycle support and supply continuity can materially affect buyer selection across the 2026–2034 forecast period. This remains commercially relevant because technical qualification, security or reliability, lifecycle support and supply continuity can materially affect buyer selection across the 2026–2034 forecast period.
Which applications are covered?
Applications include Grocery Stores, Bars & Restaurants, Drug Stores, Entertainment Centers and Others?, with mobility and transit forming an important adjacent contactless use case. This remains commercially relevant because technical qualification, security or reliability, lifecycle support and supply continuity can materially affect buyer selection across the 2026–2034 forecast period. This remains commercially relevant because technical qualification, security or reliability, lifecycle support and supply continuity can materially affect buyer selection across the 2026–2034 forecast period.
What is UPI Tap & Pay?
UPI Tap & Pay uses NFC to capture the merchant or payee identity through a compatible NFC tag or smart QR, allowing the user to complete a UPI transaction without relying only on camera-based QR scanning. This remains commercially relevant because technical qualification, security or reliability, lifecycle support and supply continuity can materially affect buyer selection across the 2026–2034 forecast period. This remains commercially relevant because technical qualification, security or reliability, lifecycle support and supply continuity can materially affect buyer selection across the 2026–2034 forecast period.
Why is NCMC important?
National Common Mobility Card provides an interoperable contactless framework for transit and can also support retail, parking and other service-area functions, creating frequent real-world use for NFC devices. This remains commercially relevant because technical qualification, security or reliability, lifecycle support and supply continuity can materially affect buyer selection across the 2026–2034 forecast period. This remains commercially relevant because technical qualification, security or reliability, lifecycle support and supply continuity can materially affect buyer selection across the 2026–2034 forecast period.
What are the main restraints?
QR-based UPI substitution, fragmented wallet and issuer support, premium wearable cost and consumer security concerns are the main restraints. This remains commercially relevant because technical qualification, security or reliability, lifecycle support and supply continuity can materially affect buyer selection across the 2026–2034 forecast period. This remains commercially relevant because technical qualification, security or reliability, lifecycle support and supply continuity can materially affect buyer selection across the 2026–2034 forecast period.
Which companies are covered?
Companies covered include Samsung India, Apple India, OnePlus India, Google India, Xiaomi India, Sony India, Huawei India, Motorola India, Nokia India and LG Electronics India. This remains commercially relevant because technical qualification, security or reliability, lifecycle support and supply continuity can materially affect buyer selection across the 2026–2034 forecast period. This remains commercially relevant because technical qualification, security or reliability, lifecycle support and supply continuity can materially affect buyer selection across the 2026–2034 forecast period.
How are payment wearables secured?
Commercial payment wearables typically use tokenization so the real card number is not transmitted at the merchant. Banks can also provide blocking, transaction monitoring and issuer controls. This remains commercially relevant because technical qualification, security or reliability, lifecycle support and supply continuity can materially affect buyer selection across the 2026–2034 forecast period. This remains commercially relevant because technical qualification, security or reliability, lifecycle support and supply continuity can materially affect buyer selection across the 2026–2034 forecast period.
Where are the strongest opportunities?
The strongest opportunities are in UPI NFC smart tags, NCMC wearables, bank-tokenized rings and clasps, and event or campus payment devices. This remains commercially relevant because technical qualification, security or reliability, lifecycle support and supply continuity can materially affect buyer selection across the 2026–2034 forecast period. This remains commercially relevant because technical qualification, security or reliability, lifecycle support and supply continuity can materially affect buyer selection across the 2026–2034 forecast period.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF