Key Statistics
Key Takeaways
- Single-Mode is a leading product category because it addresses the largest current application base.
- Consumer Electronics is a major application, with demand shaped by performance, reliability and system integration.
- Asia Pacific leads current market value, while Asia Pacific provides the strongest growth profile.
- Higher-speed datacom vcsels, 940 nm sensing arrays and automotive-qualified illumination is the main technology direction influencing new design wins.
- Market size and growth: USD 1.64 billion in 2025 is projected to reach USD 4.41 billion by 2034 at a 11.6% CAGR during 2026–2034.
Gallium Arsenide (GaAs) VCSEL Market Overview
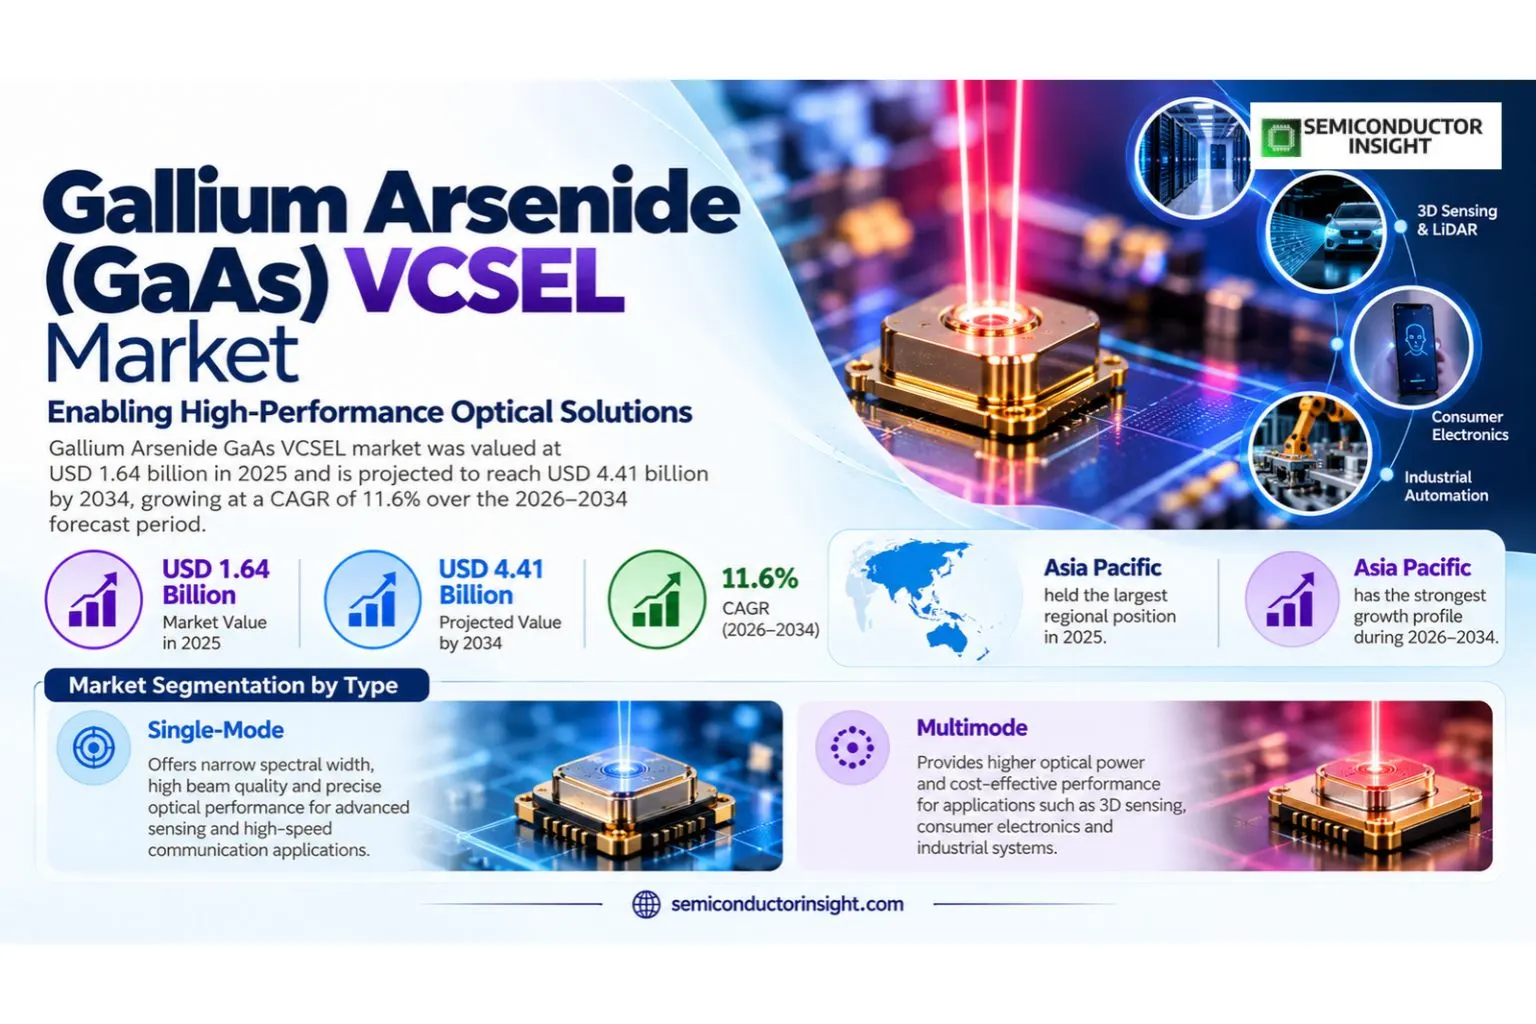
Gallium Arsenide GaAs VCSEL market was valued at USD 1.64 billion in 2025 and is projected to reach USD 4.41 billion by 2034, growing at a CAGR of 11.6% over the 2026–2034 forecast period. Asia Pacific held the largest regional position in 2025, while Asia Pacific has the strongest growth profile.
The Gallium Arsenide GaAs VCSEL market gallium arsenide VCSELs are semiconductor lasers that emit perpendicular to the wafer surface, enabling circular beams, compact arrays and high-speed modulation for sensing and short-reach optical communication. Commercial decisions in the Gallium Arsenide (GaAs) VCSEL market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
The client evidence gives a 2024 market value of USD 1.47 billion and an 11.6% growth rate through the forecast period. Application demand spans 3D sensing, data-center optical links, automotive LiDAR and in-cabin monitoring, industrial sensing and healthcare. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
Lumentum positions VCSELs across smartphones, wearables, LiDAR and in-cabin monitoring, while Coherent offers 850 nm datacom arrays and 940 nm sensing arrays. Broadcom’s OFC 2026 portfolio also highlights 200G/lane VCSEL technology for AI infrastructure. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
Segment Analysis: By Type
By type, the Gallium Arsenide GaAs VCSEL market is segmented into Single-Mode, Multimode. Each category has a distinct functional role and commercial position, so the analysis emphasizes use case, integration and competitive relevance rather than repeating a single market statistic across every row. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
| Type | Function | Market position |
|---|---|---|
| Single-Mode | Single-Mode addresses a distinct architecture or performance requirement within the Gallium Arsenide (GaAs) VCSEL market. | Commercial demand depends on application fit, qualification, cost and lifecycle requirements rather than a single headline statistic. |
| Multimode | Multimode addresses a distinct architecture or performance requirement within the Gallium Arsenide (GaAs) VCSEL market. | Commercial demand depends on application fit, qualification, cost and lifecycle requirements rather than a single headline statistic. |
Pricing by type
Multimode devices are the volume workhorse in short-reach optical links and high-power sensing arrays, while single-mode products command premiums where beam quality, spectral control or precision sensing are critical. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
Segment Analysis: By Application
By application, the market is segmented into Consumer Electronics, Data Center, Commercial & Industrial, Automotive, Healthcare. Application economics differ by qualification, lifecycle, reliability and system-level value, so each row below uses context specific to that application rather than mechanically repeating headline evidence. Commercial decisions in the Gallium Arsenide (GaAs) VCSEL market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
| Application | Demand characteristics |
|---|---|
| Consumer Electronics | Consumer Electronics creates demand where Gallium Arsenide GaAs VCSEL improves integration, performance, reliability or system economics. |
| Data Center | Data Center creates demand where Gallium Arsenide GaAs VCSEL improves integration, performance, reliability or system economics. |
| Commercial & Industrial | Commercial & Industrial creates demand where Gallium Arsenide GaAs VCSEL improves integration, performance, reliability or system economics. |
| Automotive | Automotive creates demand where Gallium Arsenide GaAs VCSEL improves integration, performance, reliability or system economics. |
| Healthcare | Healthcare creates demand where Gallium Arsenide GaAs VCSEL improves integration, performance, reliability or system economics. |
Regional Analysis
Asia Pacific is used as the largest current GaAs VCSEL region because the structured regional evidence on the client page assigns the region 48% share, while North America remains a major innovation center and Asia Pacific also has the strongest growth profile. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
How does regional demand differ across the Gallium Arsenide GaAs VCSEL market?
Regional roles differ clearly: Asia Pacific combines smartphone, module and semiconductor manufacturing; North America leads in photonics R&D, hyperscale data-center demand and advanced sensing; Europe is strongest in automotive, industrial and healthcare photonics. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia Pacific | Largest | Highest | Electronics manufacturing led | Yield, cost and supply scale |
| North America | Second | High | R&D/data-center led | Performance and vertical integration |
| Europe | Third | Moderate-high | Automotive/industrial led | Qualification and efficiency |
| South America | Smaller | Moderate | Import led | Cost and supplier access |
| Middle East & Africa | Smallest base | Emerging | Smart-city/telecom led | Import dependence |
Key Gallium Arsenide (GaAs) VCSEL Manufacturers and Competitive Landscape
The competitive landscape includes Lumentum, Coherent, ams OSRAM, TRUMPF Photonic Components, Broadcom, MKS Instruments, Santec, Vertilite, WIN Semiconductors, Leonardo Electronics. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
Competition centers on higher-speed datacom VCSELs, 940 nm sensing arrays and automotive-qualified illumination, customer qualification, manufacturing consistency and application support. Once a product is designed into a long-lifecycle system, switching costs can protect incumbent positions but also raise the importance of roadmap continuity. Commercial decisions in the Gallium Arsenide (GaAs) VCSEL market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Tier 1 | Lumentum, Coherent, ams OSRAM, TRUMPF Photonic Components | Global scale, broad customer qualification and advanced technology portfolios. |
| Tier 2 | Broadcom, MKS Instruments, Santec, Vertilite | Strong specialist capability, regional design wins and application-focused portfolios. |
| Tier 3 | Regional and niche suppliers | Cost competition, customization and specialized customer support. |
Key companies profiled
- Lumentum
- Coherent
- ams OSRAM
- TRUMPF Photonic Components
- Broadcom
- MKS Instruments
- Santec
- Vertilite
- WIN Semiconductors
- Leonardo Electronics
Gallium Arsenide (GaAs) VCSEL Production Capacity Analysis
Production capacity in the Gallium Arsenide (GaAs) VCSEL market is shaped by the underlying manufacturing process, qualification burden and customer-specific configuration. Suppliers must balance equipment utilization with quality control because high-volume output only creates value when yield, reliability and traceability remain stable. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
Capacity additions tend to follow customer program ramps rather than headline market growth alone. Regional supply resilience is becoming more important, particularly where customers require second-source planning, long product lifecycles or shorter engineering-response times. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
The practical bottleneck is often qualified output rather than nominal installed capacity. Manufacturing, assembly, test and application support must scale together to avoid creating capacity that cannot be used in production programs. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
Gallium Arsenide (GaAs) VCSEL Market Dynamics: Drivers, Restraints and Opportunities
The Gallium Arsenide (GaAs) VCSEL market is shaped by growth is driven by 3d sensing, facial recognition, ai data-center interconnects, automotive lidar and in-cabin monitoring, all of which benefit from compact arrays and fast optical modulation. At the same time, growth is constrained by gaas epitaxy cost, yield sensitivity, thermal management, price erosion and competition from edge-emitting lasers and silicon-photonics alternatives in selected applications. The strongest commercial opportunities are concentrated in 200g/lane optical links, automotive-qualified 940 nm arrays, depth-sensing modules and higher-power multi-junction vcsels create the strongest value-growth opportunities.
MARKET DRIVERS
Drivers Impact Analysis*
| Driver | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Technology upgrade cycle | +1.6% | Global; strongest in leading adopter markets | Near to medium term |
| End-market expansion | +1.2% | Application-specific | Near term |
| Higher value per system | +0.8% | Premium and advanced systems | Medium term |
Technology adoption expands addressable demand
Growth is driven by 3D sensing, facial recognition, AI data-center interconnects, automotive LiDAR and in-cabin monitoring, all of which benefit from compact arrays and fast optical modulation. This demand is strongest where customers can measure a clear improvement in system performance, footprint, energy efficiency, reliability or operating cost. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
End-market modernization increases content per system
The technology upgrade cycle supports replacement and redesign activity as OEMs move to higher-performance architectures. New designs typically create the best opportunity because suppliers can influence specifications before qualification is locked. Commercial decisions in the Gallium Arsenide (GaAs) VCSEL market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
Higher-value architectures support premium mix
Expanding end markets also increase content per system, creating value growth even when unit shipments grow more slowly. Suppliers that combine engineering support with reliable supply are better positioned to capture those design transitions. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Restraint | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Qualification and integration burden | -0.7% | Global | Ongoing |
| Price and substitution pressure | -0.5% | Cost-sensitive applications | Ongoing |
| Supply-chain or process complexity | -0.4% | Global | Medium term |
Qualification burden slows supplier switching
Growth is constrained by GaAs epitaxy cost, yield sensitivity, thermal management, price erosion and competition from edge-emitting lasers and silicon-photonics alternatives in selected applications. These constraints are most significant where customers have qualified alternatives or where the technology must prove a clear system-level advantage over lower-cost incumbent solutions. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
Price competition limits margin expansion
Qualification and integration can extend sales cycles because customers must validate performance, reliability and compatibility in their own system environment. That makes early engineering engagement important for new suppliers. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
Alternative technologies constrain selected use cases
Supply-chain complexity can also limit growth when specialized materials, tooling, test or regional support are required. Customers increasingly evaluate resilience alongside price when choosing long-lifecycle suppliers. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment. Commercial decisions in the Gallium Arsenide (GaAs) VCSEL market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
MARKET OPPORTUNITIES
Advanced integration creates premium opportunities
200G/lane optical links, automotive-qualified 940 nm arrays, depth-sensing modules and higher-power multi-junction VCSELs create the strongest value-growth opportunities. The most attractive opportunities are where customers are redesigning systems rather than simply replacing like-for-like components. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
Regional capacity and supply resilience
Higher-speed datacom vcsels, 940 nm sensing arrays and automotive-qualified illumination can create premium value when it lowers system complexity, improves performance or supports a new product architecture that is difficult to achieve with incumbent approaches. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
Application engineering deepens customer value
Regional engineering support and application-specific customization provide another route to growth because customers increasingly expect suppliers to support qualification, transition planning and lifecycle management. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
Gallium Arsenide (GaAs) VCSEL Supply Chain Analysis
Upstream. GaAs substrates, epitaxial wafers, distributed Bragg reflector stacks, lithography, wafer probing, optical packaging and beam-shaping optics form the upstream technology base. Supply quality at this stage directly affects downstream yield, reliability and cost. Commercial decisions in the Gallium Arsenide (GaAs) VCSEL market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
Manufacturing. Core production combines process control, assembly, inspection and test, with product-specific qualification used to verify performance before customer shipment. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
Distribution. High-value programs are typically won through direct OEM, Tier-1 or design-house engagement, while distributors serve prototypes, regional customers and lower-volume applications. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
Downstream. End users integrate the product into systems where switching costs rise after qualification, making lifecycle support and supply continuity commercially important. Commercial decisions in the Gallium Arsenide (GaAs) VCSEL market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
Downstream. Panel builders and machine OEMs are the primary specifying customers, followed by electrical contractors working on building services and by facility maintenance teams handling replacement. The specification decision is usually made once, at panel design, and then repeats for the life of the design — which makes design-in position considerably more valuable than any individual transaction.
Recent Developments in the Gallium Arsenide (GaAs) VCSEL Market
Developments tracked through September 2026. Items are selected for direct relevance to product technology, deployment or standards. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
- 2026 Current
Broadcom 200G/lane VCSEL for AI infrastructure Broadcom showcased 200G/lane VCSEL technology and a 3.2T VCSEL-based near-packaged optics solution for large-scale AI clusters at OFC 2026. Source - 2026 Current
Lumentum high-volume sensing VCSEL portfolio Lumentum continues positioning VCSEL arrays for smartphones, wearables, LiDAR and in-cabin monitoring. Source - 2026 Current
Coherent 940 nm VCSEL arrays Coherent offers AEC-Q102-qualified 940 nm VCSEL arrays for short-range LiDAR, 3D cameras and in-cabin automotive sensing. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2021–2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| Historical Period | 2021–2025 |
| Market Size 2025 | USD 1.64 billion |
| Market Size 2034 | USD 4.41 billion |
| Growth Rate | CAGR of 11.6% from 2026–2034 |
| Unit | Value (USD Million) |
| Segmentation | By Type, By Application, By Wavelength, By Power Output, and By Region |
| By Type | Single-Mode · Multimode |
| By Application | Consumer Electronics · Data Center · Commercial & Industrial · Automotive · Healthcare |
| By Power Output | Below 5mW · 5-10mW · Above 10mW |
| By Wavelength | 850nm · 940nm · Other Wavelengths |
| By Region | Each region analysed by Type, Application and Country North AmericaU.S., Canada, Mexico EuropeGermany, France, U.K., Italy, Russia, Nordic Countries, Benelux AsiaChina, Japan, South Korea, India, Southeast Asia South AmericaBrazil, Argentina, Rest of South America Middle East & AfricaTurkey, Israel, Saudi Arabia, UAE, Rest of MEA |
| Key Companies Profiled | Lumentum, Coherent, ams OSRAM, TRUMPF Photonic Components, Broadcom, MKS Instruments, Santec, Vertilite, WIN Semiconductors, Leonardo Electronics |
| Customization Scope | Free report customization (equivalent to up to 4 analyst working days) with purchase. Addition or alteration to country, regional and segment scope. |
Frequently Asked Questions
What is the current size of the Gallium Arsenide (GaAs) VCSEL market?
The market is valued at USD 1.64 billion in 2025 and is projected to reach USD 4.41 billion by 2034, expanding at a 11.6% CAGR during 2026–2034.
Which companies lead the Gallium Arsenide (GaAs) VCSEL market?
Key participants include Lumentum, Coherent, ams OSRAM, TRUMPF Photonic Components, Broadcom, MKS Instruments, Santec, Vertilite.
What is Gallium Arsenide (GaAs) VCSEL?
Gallium arsenide VCSELs are semiconductor lasers that emit perpendicular to the wafer surface, enabling circular beams, compact arrays and high-speed modulation for sensing and short-reach optical communication.
What are the main product types?
The market includes Single-Mode, Multimode.
What are the key applications?
The principal applications are Consumer Electronics, Data Center, Commercial & Industrial, Automotive, Healthcare.
Which region leads the market?
Asia Pacific leads current market value, while Asia Pacific has the strongest growth profile.
What drives market growth?
Growth is driven by 3D sensing, facial recognition, AI data-center interconnects, automotive LiDAR and in-cabin monitoring, all of which benefit from compact arrays and fast optical modulation.
What are the main challenges?
Growth is constrained by GaAs epitaxy cost, yield sensitivity, thermal management, price erosion and competition from edge-emitting lasers and silicon-photonics alternatives in selected applications.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...