Key Statistics
Key Takeaways
- Laser anchors the type structure defined on the source page, while demand increasingly rewards suppliers that can improve performance per watt, integration density, calibration stability, or process productivity without increasing system complexity.
- Data center & high-performance computing remains a major purchasing center because system performance directly depends on the component or equipment category; qualification cycles and lifecycle support therefore matter almost as much as headline specification.
- South India represents the leading market position in 2025, supported by the concentration of end-system production, infrastructure investment, or mission-critical procurement relevant to this category.
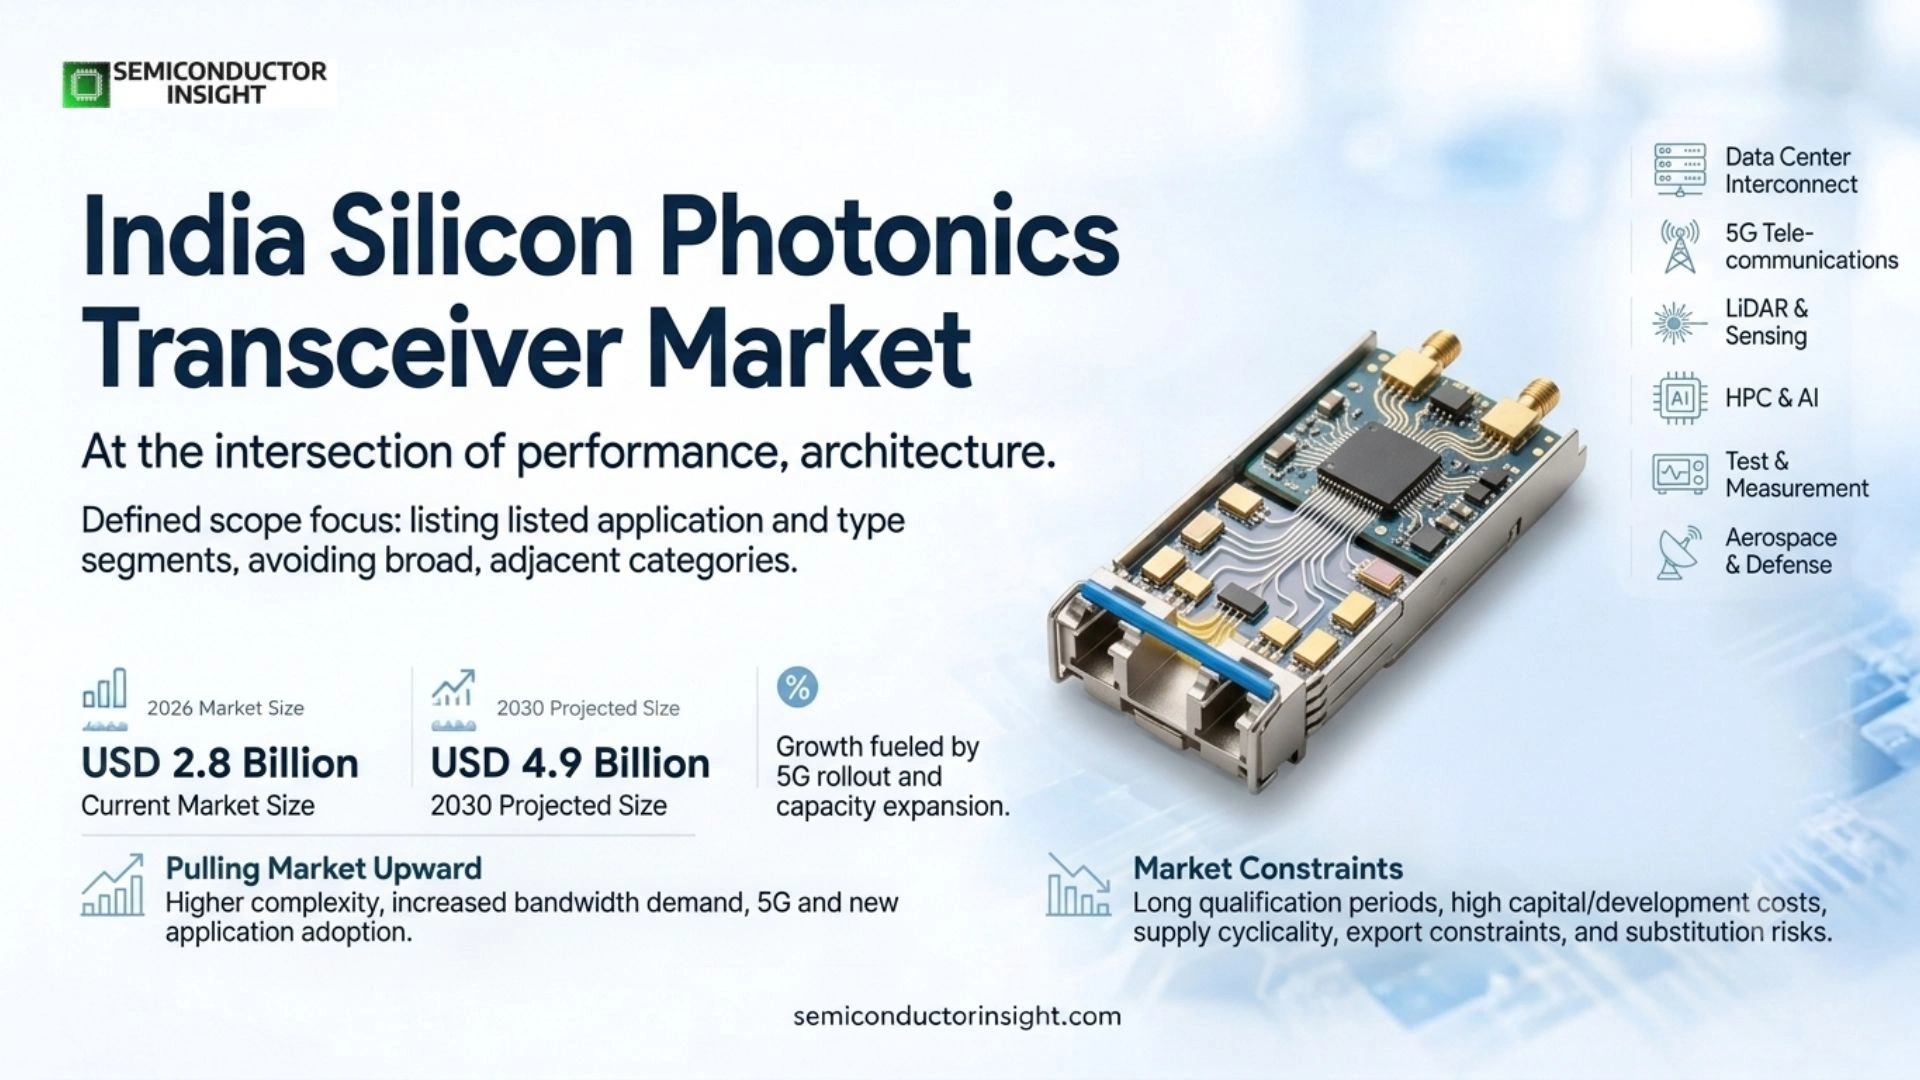
- The 2025–2034 value series rises from USD 39.6 million to USD 136.9 million, implying a 14.8% CAGR for 2026–2034 when the two published market-size anchors are treated as the controlling arithmetic basis.
- Commercial competition is increasingly ecosystem-led. Product capability remains essential, but buyers also evaluate qualification support, integration tools, service coverage, supply assurance, and roadmap continuity before changing an incumbent supplier.
India Silicon Photonics Transceiver Market Overview
India Silicon Photonics Transceiver Market is valued at USD 39.6 million in 2025, is estimated at USD 45.4 million in 2026, and is projected to reach USD 136.9 million by 2034, corresponding to a 14.8% CAGR during 2026–2034. The leading market position in 2025 is South India (leading technology and data-center cluster).
India Silicon Photonics Transceiver sits at the intersection of component performance, system architecture, and end-market investment. The commercial boundary used here follows the source page rather than a broader adjacent category: the listed type and application segments define what is included, while neighboring technologies are discussed only where they alter purchasing behavior or substitution risk. That scope discipline matters because different performance tiers can have radically different pricing, qualification, and replacement cycles.
Demand is created when customers need a measurable improvement in throughput, bandwidth, navigation confidence, yield, power efficiency, or mission reliability that cannot be achieved by software changes alone. In response, suppliers invest in device architecture, materials, packaging, calibration, process control, and integration support. The market implication is a recurring shift toward higher-value configurations whenever end systems become more complex, even if unit volumes remain cyclical.
Technology transitions are changing the competitive basis. Buyers increasingly ask how a product behaves inside a complete platform, not just whether it meets a standalone data-sheet limit. That raises the value of reference designs, process recipes, diagnostic software, field engineering, and multi-year roadmap visibility. Suppliers able to reduce integration time or qualification risk can defend pricing better than vendors competing mainly on acquisition cost.
The forecast through 2034 therefore reflects both end-demand growth and mix improvement. Capacity additions, higher system complexity, and tighter reliability requirements expand the revenue opportunity, while cyclicality, long validation periods, export restrictions, and technology substitution temper the pace. The resulting market is attractive but technically selective: growth is strongest where the category remains essential to a customer’s performance envelope.
Segment Analysis: By Type
By type, the source page segments the India Silicon Photonics Transceiver market into Laser, Photodetector, Modulator. These categories compete on different combinations of performance, integration complexity, lifecycle economics, and qualification burden, so revenue leadership does not necessarily track unit shipments.
| Type | Technical / commercial role | Market position and purchasing logic |
|---|---|---|
| Laser | Laser addresses a defined performance tier within India Silicon Photonics Transceiver. Its technical value is determined by how effectively it improves system capability, process control, signal integrity, accuracy, or manufacturing productivity relative to alternatives.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. | This segment has a leading role in the source-page structure and benefits from established qualification pathways, installed-base familiarity, and customer dependence on proven performance.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. |
| Photodetector | Photodetector addresses a defined performance tier within India Silicon Photonics Transceiver. Its technical value is determined by how effectively it improves system capability, process control, signal integrity, accuracy, or manufacturing productivity relative to alternatives.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. | This segment participates in the market where customers trade absolute performance against integration cost, power, footprint, manufacturability, or application-specific flexibility, creating room for differentiated suppliers.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. |
| Modulator | Modulator addresses a defined performance tier within India Silicon Photonics Transceiver. Its technical value is determined by how effectively it improves system capability, process control, signal integrity, accuracy, or manufacturing productivity relative to alternatives.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. | This segment participates in the market where customers trade absolute performance against integration cost, power, footprint, manufacturability, or application-specific flexibility, creating room for differentiated suppliers.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. |
Pricing and value capture by type
Pricing in India Silicon Photonics Transceiver is shaped by qualification difficulty, performance grade, yield, packaging complexity, calibration burden, service intensity, and the economic cost of system failure. Entry configurations face greater price competition, while high-performance or process-critical variants retain stronger value capture because switching suppliers can require redesign, requalification, process re-optimization, or new reliability evidence. This creates a broad price ladder rather than a single commodity benchmark.
Segment Analysis: By Application
The application structure comprises Data center & high-performance computing, Telecommunications, Military, defense, and aerospace, Medical and life sciences, Sensing. Application mix matters because purchase criteria change with reliability requirements, deployment environment, product lifecycle, acceptable downtime, and the customer’s ability to redesign around an alternative technology.
| Application | Demand characteristics |
|---|---|
| Data center & high-performance computing | Data center & high-performance computing demand is created when customers need india silicon photonics transceiver capability as part of a larger system upgrade or capacity decision. Purchasing is generally triggered by performance limits, new platform launches, capacity expansion, compliance requirements, or the need to lower operating risk. This application has the strongest structural relevance in the source-page framing and therefore serves as an important reference point for supplier positioning.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. |
| Telecommunications | Telecommunications demand is created when customers need india silicon photonics transceiver capability as part of a larger system upgrade or capacity decision. Purchasing is generally triggered by performance limits, new platform launches, capacity expansion, compliance requirements, or the need to lower operating risk.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. |
| Military, defense, and aerospace | Military, defense, and aerospace demand is created when customers need india silicon photonics transceiver capability as part of a larger system upgrade or capacity decision. Purchasing is generally triggered by performance limits, new platform launches, capacity expansion, compliance requirements, or the need to lower operating risk.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. |
| Medical and life sciences | Medical and life sciences demand is created when customers need india silicon photonics transceiver capability as part of a larger system upgrade or capacity decision. Purchasing is generally triggered by performance limits, new platform launches, capacity expansion, compliance requirements, or the need to lower operating risk.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. |
| Sensing | Sensing demand is created when customers need india silicon photonics transceiver capability as part of a larger system upgrade or capacity decision. Purchasing is generally triggered by performance limits, new platform launches, capacity expansion, compliance requirements, or the need to lower operating risk.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. |
Regional Analysis
South India (leading technology and data-center cluster) holds the leading 2025 market position. Regional demand differs according to installed manufacturing capacity, end-user concentration, government policy, technology access, local engineering depth, and the maturity of supplier service networks.
How does regional demand differ across the India Silicon Photonics Transceiver market?
The five regional groups do not buy for identical reasons. Some markets are capacity-led, others are driven by defense or public infrastructure, and still others are shaped by advanced-node transitions, local manufacturing programs, or replacement of an aging installed base. Suppliers therefore need region-specific channel, qualification, pricing, and service strategies rather than a single global commercial model.
| Region | Position | Growth outlook | Demand profile | Supplier selection |
|---|---|---|---|---|
| South India | Largest commercial cluster | High | Data centers, cloud, semiconductor design and telecom R&D in South India. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. | High-speed optical qualification and local engineering support in South India. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. |
| West India | Second tier | High | Mumbai-Pune data-center corridor, financial services and telecom in West India. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. | Carrier qualification, supply continuity and power efficiency in West India. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. |
| North India | Major demand center | High | National telecom networks, cloud regions and public digital infrastructure in North India. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. | Government procurement, interoperability and domestic value addition in North India. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. |
| East India | Emerging | Moderate | Backbone expansion, enterprise digitization and telecom upgrades in East India. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. | Price-performance and distribution reach in East India. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. |
| Central & Northeast India | Developing | Moderate | Broadband expansion, BharatNet-type connectivity and edge infrastructure in Central & Northeast India. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. | Rugged deployment, long reach and service support in Central & Northeast India. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. |
Competitive Landscape
Competition in the India Silicon Photonics Transceiver market is shaped by technical specialization, installed-base relationships, qualification history, intellectual property, process know-how, global service coverage, and the ability to support customer roadmaps over multi-year product or manufacturing cycles.
Leading suppliers protect their positions through accumulated application knowledge rather than scale alone. In India Silicon Photonics Transceiver, a customer often qualifies not just a part number but a complete performance envelope, process recipe, software interface, calibration approach, or service procedure. That creates switching friction and rewards vendors with documented field history, especially in mission-critical or high-cost production environments.
The middle of the market is more contested. Specialist suppliers can win when they offer a better balance of performance, lead time, integration support, regional responsiveness, or price than the largest incumbents. However, expanding beyond a niche requires investment in quality systems, applications engineering, channel coverage, and long-term product availability, all of which raise the fixed cost of competing globally.
Customer concentration can also shape negotiating power. Large OEMs, fabs, telecom operators, aerospace programs, or government buyers can demand custom specifications and long validation cycles, which increase development burden but create durable revenue once a supplier is designed in. The strongest competitors therefore manage portfolio breadth and customer-specific engineering without allowing customization to erode manufacturing efficiency.
The competitive shift through 2034 is toward tighter integration between hardware, software, process data, and lifecycle services. Suppliers that convert product performance into lower system-level cost, higher yield, better uptime, or reduced qualification risk are positioned to capture a larger share of value than vendors selling interchangeable hardware.
| Competitive tier | Typical position | Basis of competition |
|---|---|---|
| Global technology leaders | Large installed bases, broad portfolios and deep qualification history. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. | Technology roadmap, service coverage, IP depth and strategic customer relationships. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. |
| Specialist / focused suppliers | Narrower portfolios with strong capability in defined applications or performance tiers. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. | Agility, targeted performance, engineering support and customer-specific integration. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. |
| Regional / value competitors | Price-sensitive or locally served segments with growing technical capability. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. | Cost, lead time, localization, distributor access and improving qualification credentials. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. |
Companies profiled on the source page
Tejas Networks
HFCL Limited
C-DOT (Centre for Development of Telematics)
Tata Communications
Syska
BEL (Bharat Electronics Limited)
Prysmian Group
VVDN Technologies
Innovecture Consulting
Production Capacity Analysis
Production capacity for India Silicon Photonics Transceiver is constrained less by nominal factory floor space than by qualified process capability, specialized equipment, skilled engineering, yields, calibration or test capacity, and access to critical upstream materials or subsystems.
Where production sits reflects the technology base of the market. Capacity tends to cluster near semiconductor fabrication, precision manufacturing, aerospace electronics, photonics, advanced packaging, or specialized equipment ecosystems because suppliers need rapid access to engineering talent, component vendors, calibration facilities, and demanding customers. This clustering improves innovation speed but can increase geographic concentration risk.
Effective capacity is usually below theoretical capacity because high-performance products require lengthy setup, calibration, process stabilization, acceptance testing, and customer-specific qualification. As India Silicon Photonics Transceiver performance requirements rise, manufacturers must invest not just in more tools but in metrology, automation, software control, clean manufacturing, and reliability screening. These investments raise barriers to entry and extend the payback period for new capacity.
Supply risk is greatest when a small number of upstream technologies, process tools, materials, or precision subassemblies determine throughput. Suppliers respond through dual sourcing, longer-term agreements, internalization of critical steps, geographic diversification, and design changes that reduce dependence on constrained inputs. Customers increasingly examine these resilience measures during qualification because a technically superior product has limited value if it cannot be delivered through a full platform lifecycle.
Market Dynamics
The market is pulled upward by increasing system complexity, higher performance requirements, capacity expansion and new applications, while growth is moderated by qualification time, high capital or development cost, cyclicality, export constraints, and substitution by alternative architectures where performance is sufficient.
Market Drivers
| Driver | Directional impact* | Commercial mechanism |
|---|---|---|
| Higher performance requirements in end systems | High | As customers add AI, autonomy, high-speed connectivity, advanced manufacturing, or mission-critical functionality, system tolerances tighten. India Silicon Photonics Transceiver must deliver better accuracy, bandwidth, power efficiency, process control, yield, or reliability. This creates upgrade demand even when unit volumes grow more slowly, because higher-specification content captures more value per system.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. |
| Capacity expansion and platform refresh cycles | High | New fabs, data centers, telecom networks, aerospace platforms, industrial automation projects, or electronics programs create design-in events where India Silicon Photonics Transceiver can be specified from the start. Greenfield investment generally produces broader component and equipment demand than replacement alone, while platform refreshes create opportunities to displace incumbents before long lifecycle contracts are renewed.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. |
| Integration and miniaturization | Medium-High | Customers increasingly need more functionality in smaller footprints and at lower power or operating cost. Suppliers respond with improved materials, packaging, MEMS, photonic integration, advanced process control, software-assisted calibration, or automation. Better integration reduces the customer’s system burden and expands adoption into applications that could not previously justify size, power, or complexity.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. |
| Resilience and sovereign supply chains | Medium-High | Government incentives, export controls, and customer concern about geographic concentration are encouraging local or allied production. This does not eliminate global interdependence, but it creates parallel demand for regional capacity, second sources and localized service. Suppliers with multiple manufacturing and engineering locations can turn resilience into a commercial differentiator.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. |
Higher performance requirements in end systems
As customers add AI, autonomy, high-speed connectivity, advanced manufacturing, or mission-critical functionality, system tolerances tighten. India Silicon Photonics Transceiver must deliver better accuracy, bandwidth, power efficiency, process control, yield, or reliability. This creates upgrade demand even when unit volumes grow more slowly, because higher-specification content captures more value per system.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Capacity expansion and platform refresh cycles
New fabs, data centers, telecom networks, aerospace platforms, industrial automation projects, or electronics programs create design-in events where India Silicon Photonics Transceiver can be specified from the start. Greenfield investment generally produces broader component and equipment demand than replacement alone, while platform refreshes create opportunities to displace incumbents before long lifecycle contracts are renewed.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Integration and miniaturization
Customers increasingly need more functionality in smaller footprints and at lower power or operating cost. Suppliers respond with improved materials, packaging, MEMS, photonic integration, advanced process control, software-assisted calibration, or automation. Better integration reduces the customer’s system burden and expands adoption into applications that could not previously justify size, power, or complexity.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Resilience and sovereign supply chains
Government incentives, export controls, and customer concern about geographic concentration are encouraging local or allied production. This does not eliminate global interdependence, but it creates parallel demand for regional capacity, second sources and localized service. Suppliers with multiple manufacturing and engineering locations can turn resilience into a commercial differentiator.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Market Restraints
| Restraint | Directional impact* | Commercial mechanism |
|---|---|---|
| Long qualification and certification cycles | High | High-performance and safety-critical systems require extensive reliability evidence, process qualification, customer testing, and sometimes regulatory certification. These steps extend time to revenue and can lock customers into existing suppliers, which protects incumbents but slows adoption of technically superior new products.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. |
| High capital and development intensity | High | Advanced fabrication, precision manufacturing, specialized metrology, clean environments, calibration, software and field support require sustained investment before scale is achieved. Smaller suppliers can innovate quickly but may struggle to finance the global quality and service infrastructure needed to win large programs.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. |
| Cyclical customer investment | Medium | Semiconductor, electronics, telecom, automotive and industrial customers periodically pause capacity additions or inventory builds. The effect can be sharp because suppliers operate against long lead times. A demand correction therefore creates temporary underutilization even when the long-term technology trend remains favorable.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. |
| Technology substitution and architecture change | Medium | Software-defined functions, alternative sensing or communication technologies, system-on-chip integration, or new manufacturing flows can reduce standalone content in some applications. Suppliers need to move up the value chain and demonstrate system-level economics rather than depend on historical socket counts.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. |
Long qualification and certification cycles
High-performance and safety-critical systems require extensive reliability evidence, process qualification, customer testing, and sometimes regulatory certification. These steps extend time to revenue and can lock customers into existing suppliers, which protects incumbents but slows adoption of technically superior new products.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
High capital and development intensity
Advanced fabrication, precision manufacturing, specialized metrology, clean environments, calibration, software and field support require sustained investment before scale is achieved. Smaller suppliers can innovate quickly but may struggle to finance the global quality and service infrastructure needed to win large programs.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Cyclical customer investment
Semiconductor, electronics, telecom, automotive and industrial customers periodically pause capacity additions or inventory builds. The effect can be sharp because suppliers operate against long lead times. A demand correction therefore creates temporary underutilization even when the long-term technology trend remains favorable.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Technology substitution and architecture change
Software-defined functions, alternative sensing or communication technologies, system-on-chip integration, or new manufacturing flows can reduce standalone content in some applications. Suppliers need to move up the value chain and demonstrate system-level economics rather than depend on historical socket counts.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Market Opportunities
The strongest opportunities lie where new performance requirements create a fresh design-in event, where regional capacity is being built, or where suppliers can expand from hardware into software, service, qualification support, and lifecycle economics.
AI and high-performance computing infrastructure
AI infrastructure raises bandwidth, memory, power, manufacturing and reliability requirements across the electronics stack. Suppliers that connect their product roadmap to these system bottlenecks can capture higher-value demand rather than relying only on broad electronics growth.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Autonomy, robotics and unmanned systems
Autonomous platforms require reliable sensing, navigation, communications and control under increasingly difficult operating conditions. This expands opportunities for suppliers able to reduce size, weight, power and calibration burden while maintaining robust performance.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Regional manufacturing localization
Government programs are creating new fabs, packaging facilities, telecom networks and strategic electronics plants in markets that historically imported most high-value technology. Localization creates fresh design-in events and can open long-lived service revenue for early supplier entrants.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Service, software and lifecycle monetization
As hardware becomes more complex, customers value monitoring, calibration, process analytics, predictive maintenance, firmware, integration tools and field support. These services increase recurring revenue and can differentiate otherwise similar hardware offerings.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Supply Chain Analysis
The India Silicon Photonics Transceiver value chain moves from specialized upstream materials, devices or process technologies through component/equipment manufacturing, system integration and distribution, and finally into end-user platforms. Value capture increases where qualification, IP, process know-how or service intensity is difficult to replicate.
Upstream suppliers determine the cost and technical ceiling of the finished product through specialized materials, wafers, sensors, photonic elements, optics, precision mechanics, chemicals, electronic components, or process tools. Qualification of these inputs can be slow, so changing a supplier is rarely equivalent to purchasing a generic substitute. Long-term availability and tight incoming quality control are therefore important elements of supply resilience.
The core manufacturing stage concentrates the proprietary value in India Silicon Photonics Transceiver. Yield management, calibration, process recipes, clean manufacturing, packaging, test and software tuning convert upstream inputs into a reproducible commercial product. Improvements at this stage can reduce cost and raise performance simultaneously, which is why leaders continue to invest in automation, metrology, design-for-manufacturing and statistical process control.
Integration and distribution translate technical capability into a product a customer can actually deploy. Distributors, integrators, application engineers and field-service teams handle configuration, documentation, interoperability, spares and local support. In high-value markets, this layer can decide which qualified product wins because customers place a premium on quick fault isolation and reliable replacement supply.
End users capture the economic benefit through higher throughput, lower power, better navigation, improved yield, faster data transmission, improved reliability or reduced downtime. Their purchasing decisions feed back into supplier roadmaps, often through multi-year qualification programs. This closed loop makes the value chain relationship-based and favors vendors that understand the customer’s total system economics rather than only the unit price.
Recent Developments
Recent developments show that the market is being reshaped by technology migration, capacity investment, localization and tighter integration with end-system requirements. The entries below use official or company sources and connect each event to its commercial implication.
This supports a faster move toward high-bandwidth optical engines where silicon photonics can improve integration density and energy efficiency.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
The policy reduces the capital barrier for domestic photonic integration and creates a route toward localized assembly, testing and eventually fabrication.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
A broader semiconductor ecosystem improves access to packaging, test, engineering talent and supply-chain partners needed for silicon photonics transceiver commercialization.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2019–2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| Historical Period | 2019–2024 |
| Market Size 2025 | USD 39.6 Million |
| Market Size 2034 | USD 136.9 Million |
| Growth Rate | CAGR of 14.8% from 2026–2034 |
| Unit | Value (USD Million), Sales Volume, and Price |
| Segmentation | By Type and By Application; geographic scope is India |
| By Type | Laser · Photodetector · Modulator |
| By Application | Data center & high-performance computing · Telecommunications · Military, defense, and aerospace · Medical and life sciences · Sensing |
| Geographic Scope | India |
| Key Companies Profiled | Sterlite Technologies Limited, Tejas Networks, HFCL Limited, C-DOT (Centre for Development of Telematics), Tata Communications, Syska, BEL (Bharat Electronics Limited), Prysmian Group, VVDN Technologies, Innovecture Consulting |
| Customization Scope | Customization is available on request through the sales team for scope-related requirements. |
Frequently Asked Questions
What is the India Silicon Photonics Transceiver market size in 2025?
The market is valued at USD 39.6 million in 2025. Using the growth rate implied by the source page’s published market-size anchors, the series reaches USD 45.4 million in 2026 and USD 136.9 million by 2034, corresponding to a 14.8% CAGR for the 2026–2034 period. The standardized series keeps the source scope unchanged while extending the endpoint.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
What is the forecast for the India Silicon Photonics Transceiver market through 2034?
The market is projected to reach USD 136.9 million by 2034 from USD 39.6 million in 2025. The implied compound growth rate is 14.8% for 2026–2034. Growth is supported by performance upgrades, capacity investment, integration requirements and new applications, while qualification, capital intensity and cyclical customer spending moderate the pace.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Which market is largest in 2025?
South India (leading technology and data-center cluster) holds the leading 2025 position in this overview. The leadership reflects the concentration of relevant end users, manufacturing capacity, infrastructure investment, technology ecosystems or strategic procurement. Regional strength is not uniform across applications, so suppliers still require market-specific channel, qualification and service strategies.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
How is the India Silicon Photonics Transceiver market segmented by type?
The source page segments the market into Laser, Photodetector, Modulator. These categories serve different performance and cost requirements, which means revenue share can diverge from unit volume. Higher-performance configurations generally support stronger value capture where customer switching requires redesign, process re-optimization, calibration or new qualification evidence.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Which applications are included in the market?
The application segmentation includes Data center & high-performance computing, Telecommunications, Military, defense, and aerospace, Medical and life sciences, Sensing. Demand mechanisms differ by application because customers face different reliability, latency, throughput, certification, operating-environment and lifecycle requirements. Those differences shape supplier selection, pricing, qualification time and the level of engineering support required before a product can be adopted.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
What are the main growth drivers?
Major drivers include rising system complexity, higher performance requirements, capacity and infrastructure expansion, technology miniaturization, localization of strategic manufacturing, and increasing value placed on resilience. These forces create new design-in events and encourage customers to upgrade to higher-value configurations when system economics justify improved capability or lower operating risk.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
What are the main restraints?
Key restraints include long qualification cycles, high development and manufacturing investment, customer capital-spending cyclicality, export or regulatory restrictions in some applications, and substitution risk from alternative architectures. These factors can delay adoption even when technical demand is strong, especially where incumbent suppliers already hold long-lived qualified positions.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Who are the key companies profiled?
The source page profiles Sterlite Technologies Limited, Tejas Networks, HFCL Limited, C-DOT (Centre for Development of Telematics), Tata Communications, Syska, BEL (Bharat Electronics Limited), Prysmian Group, VVDN Technologies, Innovecture Consulting. Competitive positioning depends on product depth, qualification history, manufacturing consistency, intellectual property, engineering support, service coverage and roadmap continuity rather than on scale alone.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Why is production capacity important in this market?
Usable capacity depends on more than installed factory tools. Yields, calibration, metrology, skilled engineering, clean manufacturing, qualification, upstream component availability and final test can all constrain shipment capability. As performance requirements rise, suppliers need parallel investment in process control and service infrastructure, which raises barriers to rapid entry.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
What is the strategic outlook through 2034?
The strategic outlook remains constructive because performance requirements are rising across the market’s major applications and because regionalization is creating new capacity and supply-chain investment. The strongest suppliers will be those that connect technical improvements to measurable customer economics, support qualification efficiently and maintain dependable multi-year supply and service.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF