Key Statistics
Key Takeaways
- Market size: The market is valued at USD 748.45 million in 2025 and is projected to reach USD 2.49 billion by 2034, representing a 16.4% CAGR during 2026–2034.
- Hardware-assisted verification platforms are the largest revenue category, because billion-gate SoCs and long software workloads exceed the practical limits of software simulation alone.
- North America leads current demand through advanced AI, networking, automotive and CPU/GPU design teams, while Asia Pacific is the fastest-growth region as semiconductor design activity expands.
- Cloud-hosted emulation is widening market access, allowing teams to add peak capacity without purchasing and operating dedicated systems.
- AI-era chip complexity is increasing capacity requirements, with new platforms scaling to multi-billion-gate designs and emphasizing software bring-up, power analysis and system-level validation.
Semiconductor Emulators Market Overview
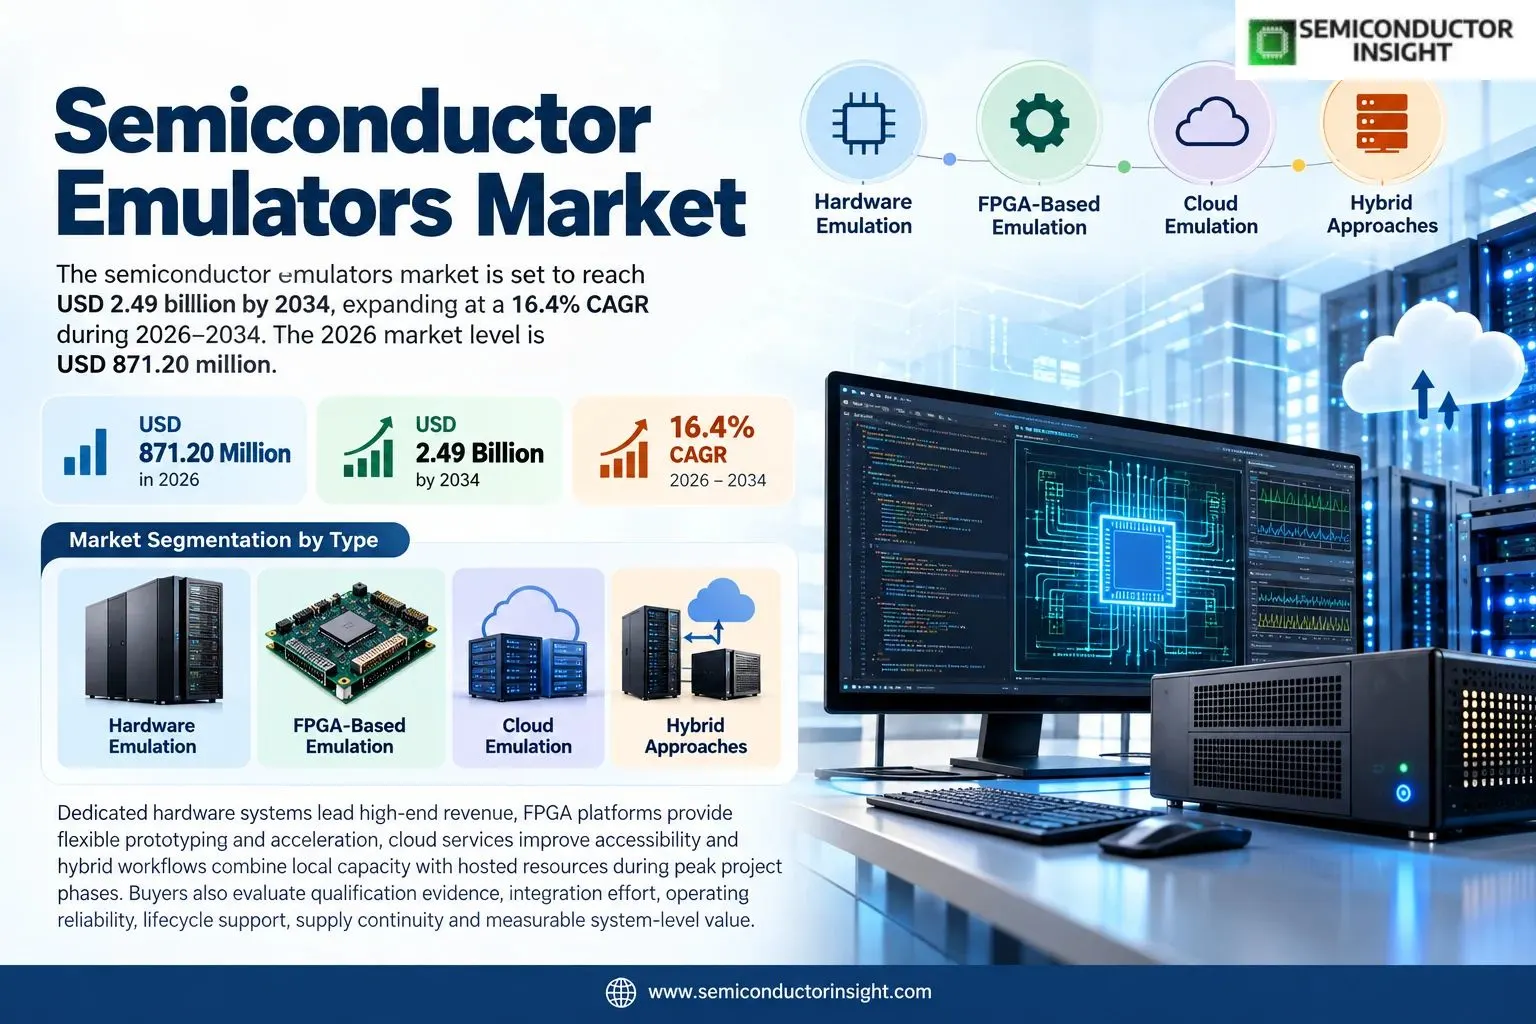
Semiconductor emulators market is valued at USD 748.45 million in 2025 and is projected to reach USD 2.49 billion by 2034, expanding at a 16.4% CAGR during 2026–2034. The 2026 market level is USD 871.20 million. North America leads current demand through advanced semiconductor design activity, while Asia Pacific is expanding rapidly across AI, automotive and consumer-chip development. Hardware-assisted verification is becoming more strategic as SoCs integrate more compute, software and chiplet complexity.
Semiconductor emulators are hardware-assisted verification platforms that execute RTL designs at speeds far above conventional software simulation. They are used to validate large SoCs before tape-out, run long regressions, bring up firmware and operating systems, analyze power and performance and reproduce system-level behavior using real interfaces. Modern emulators combine custom processors or FPGA fabrics with compilers, debug software, transactors and interface adapters.
Cadence Palladium Z3 and Synopsys ZeBu platforms illustrate the current technology frontier. Palladium Z3 increased capacity and performance over the prior generation while integrating simulation acceleration and digital-twin workflows. Synopsys ZeBu-200 scales from hundreds of millions to multi-billion gates, supports advanced debug and software-defined emulation and can be paired with hosted ZeBu Cloud capacity for secure remote access.
The purchasing decision is driven by verification throughput, compile time, capacity, debug quality, interface support and utilization across multiple teams. Systems are expensive, so large semiconductor companies operate shared emulation farms while smaller teams increasingly use cloud capacity. Vendors also compete on the breadth of protocol transactors, power-analysis tools and the ease of transitioning designs between emulation, prototyping and software-development environments.
Segment Analysis: By Type
By type, the market is segmented into hardware emulation, FPGA-based emulation, cloud emulation and hybrid approaches. Dedicated hardware systems lead high-end revenue, FPGA platforms provide flexible prototyping and acceleration, cloud services improve accessibility and hybrid workflows combine local capacity with hosted resources during peak project phases. For commercial decisions in the Semiconductor Emulators market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
| Type | Commercial role |
|---|---|
| Hardware Emulation | Purpose-built high-capacity systems for full-chip verification and software workloads. |
| FPGA-Based Emulation | Reconfigurable platforms for acceleration, validation and prototyping. |
| Cloud Emulation | Hosted secure emulation capacity used on demand. |
| Hybrid Emulation | Combined on-premise, virtual and cloud resources for flexible project scaling. |
Additional Segmentation: By Deployment
Deployment models include on-premise systems, cloud-hosted services and hybrid architectures. On-premise systems provide maximum control and high utilization for large design organizations, while cloud-hosted emulation reduces capital expenditure and provides burst capacity. Hybrid deployment is increasingly attractive because project demand is uneven and different teams need access at different phases of the design cycle.
| Deployment | Demand characteristics |
|---|---|
| On-Premise | Dedicated emulation farms operated by semiconductor companies and design centers. |
| Cloud-Hosted | Vendor-hosted secure capacity accessed remotely and provisioned by project need. |
| Hybrid | Permanent local systems supplemented with cloud capacity for peak workloads. |
Segment Analysis: By Application
By application, AI and machine learning chips are among the fastest-growing users because accelerator and GPU-class designs combine massive gate counts with complex software stacks. Networking, data-center, automotive and mobile SoCs also rely heavily on emulation to validate protocols, power behavior, boot sequences and real-world workloads before silicon is available.
| Application | Demand characteristics |
|---|---|
| AI & Machine Learning | GPU, NPU and accelerator SoCs with very large designs and complex software. |
| Networking & Data Center | Switch, NIC, CPU and infrastructure silicon requiring protocol-heavy system validation. |
| Automotive | ADAS, cockpit and domain-controller SoCs with safety and software requirements. |
| Mobile & Consumer | Application processors, connectivity and multimedia SoCs. |
| Others | Industrial, aerospace and specialized semiconductor designs. |
Additional Segmentation: By Verification Use Case
Verification use cases span early RTL validation, software bring-up, power and performance analysis and system-level validation. As designs mature, the same emulator can transition from hardware regressions to firmware and operating-system workloads, improving asset utilization. Power analysis is gaining importance because software activity increasingly determines real-world energy use in advanced chips.
| Verification Use Case | Commercial relevance |
|---|---|
| RTL Verification | Accelerated regressions and functional validation of large designs. |
| Software Bring-Up | Firmware, operating-system and driver development before silicon. |
| Power / Performance Analysis | Long workload execution for realistic power and architecture profiling. |
| System Validation | Real interfaces and end-to-end workloads used to reproduce lab-like behavior pre-silicon. |
Regional Analysis
North America leads because leading CPU, GPU, AI, networking and EDA companies are concentrated in the United States. Asia Pacific is the fastest-growth region through expanding semiconductor design centers in China, Taiwan, South Korea, Japan and India. Europe remains important in automotive, industrial and communications silicon. For commercial decisions in the Semiconductor Emulators market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Why does regional demand differ across the Semiconductor Emulators market?
Regional demand reflects the location of advanced semiconductor design rather than wafer manufacturing. North America benefits from hyperscale, AI and EDA concentration, Asia Pacific from a rapidly expanding chip-design workforce and local system companies, and Europe from automotive and industrial semiconductor development. Cloud-hosted emulation can reduce geographic barriers by letting distributed teams access shared capacity.
| Region | Position | Demand profile | Supplier-selection factor |
|---|---|---|---|
| North America | Largest | AI, CPU/GPU, networking | Advanced chip-design concentration |
| Asia Pacific | Fastest growth | Consumer, AI, automotive | Design-center expansion |
| Europe | Strategic | Automotive, industrial, telecom | Safety and system validation |
| South America | Emerging | Design services, education | Limited local advanced design |
| Middle East & Africa | Emerging | AI silicon initiatives | Greenfield design centers |
Competitive Landscape
Cadence, Synopsys and Siemens EDA form the leading hardware-assisted verification group, supported by FPGA vendors, cloud infrastructure and specialized verification companies. Competitive advantage depends on capacity, runtime performance, compile time, debug visibility, interface libraries and integration with simulation, formal verification and prototyping flows. For commercial decisions in the Semiconductor Emulators market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Cadence’s Palladium Z3 platform uses a custom emulation processor and is designed for large SoCs, software development and digital twins. Synopsys ZeBu-200 emphasizes software-defined emulation, very high design capacity and shared hardware that can transition toward prototyping. These architectures show different ways to improve utilization while serving increasingly software-heavy verification.
Cloud delivery is becoming a strategic differentiator. Synopsys ZeBu Cloud allows customers to use hosted emulation without buying hardware or to supplement on-premise capacity during specific project phases. Secure remote access can broaden the addressable market to smaller companies and globally distributed teams. For commercial decisions in the Semiconductor Emulators market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
| Competitive tier | Representative companies | Primary differentiation |
|---|---|---|
| Hardware-assisted verification leaders | Cadence, Synopsys, Siemens EDA | High-capacity emulators, software ecosystems and global support. |
| FPGA / prototyping ecosystem | AMD, Intel and platform partners | Reconfigurable hardware used in emulation and prototyping. |
| Specialist verification vendors | Aldec, Agnisys, Blue Pearl and others | Focused verification, debug and design-flow tools. |
Key companies profiled
Cadence Design Systems, Synopsys, Siemens EDA, AMD, Altair/Ansys-related verification tools, Microchip, Aldec, Agnisys, Blue Pearl Software, Temento Systems and other verification providers are included in the competitive scope. The top market tier remains concentrated because building a scalable emulator requires both advanced hardware and a large software ecosystem. For commercial decisions in the Semiconductor Emulators market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Production Capacity Analysis
Emulator capacity is measured in gates, user slots, compile throughput and available interface hardware rather than manufacturing units alone. Large systems require specialized processors or FPGAs, high-speed backplanes, memory and substantial data-center infrastructure. Vendor supply must also include transactors, speed adapters and technical support. For commercial decisions in the Semiconductor Emulators market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Utilization is a key economic metric because systems are high-value capital assets. Multi-user scheduling, virtualization and cloud access improve return on investment by keeping hardware busy across projects. Smaller system-studio products can also bring emulation to teams that do not need a full enterprise rack. For commercial decisions in the Semiconductor Emulators market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Market Dynamics
The market is driven by AI SoC complexity, software-first development, chiplets and the need to avoid costly silicon respins. Growth is restrained by high capital cost, specialist skills and compile or model-migration complexity. Cloud-hosted capacity, software-defined platforms and integrated power analysis offer the strongest opportunities. For commercial decisions in the Semiconductor Emulators market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Market Drivers
| Driver | Impact | Commercial mechanism |
|---|---|---|
| AI chip complexity | High | Very large accelerators require hardware-assisted verification. |
| Software-first development | High | Firmware and operating systems must be ready before first silicon. |
| Avoiding silicon respins | Medium-High | Late hardware bugs are extremely expensive. |
| Power and performance analysis | Medium | Real software workloads expose system behavior unavailable in short simulations. |
AI chip complexity
AI processors contain billions of gates and must run realistic software workloads. Emulation can execute far more cycles than software simulation, making it essential for deep pre-silicon validation. For commercial decisions in the Semiconductor Emulators market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Software-first development
Emulators let software teams boot operating systems, drivers and applications months before physical chips exist. Earlier software bring-up reduces product schedule risk. For commercial decisions in the Semiconductor Emulators market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Avoiding silicon respins
Advanced-node masks and development schedules make respins costly. Greater pre-silicon coverage can justify the high cost of emulation when it prevents a major design error. For commercial decisions in the Semiconductor Emulators market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Power and performance analysis
Modern platforms can run long workloads and feed power-critical windows into downstream tools. This improves architecture decisions before tape-out. For commercial decisions in the Semiconductor Emulators market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification. For commercial decisions in the Semiconductor Emulators market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Market Restraints
| Restraint | Impact | Commercial consequence |
|---|---|---|
| High capital cost | High | Enterprise emulators are expensive data-center systems. |
| Specialist skills | Medium-High | Compilation, transactors and debug require experienced teams. |
| Model migration complexity | Medium | Design environments must be adapted from simulation to emulation. |
| Data security | Medium | Cloud-hosted emulation contains highly sensitive pre-silicon IP. |
High capital cost
Only large design organizations can justify dedicated fleets at high utilization. Cloud services reduce the barrier but do not eliminate the underlying cost of capacity. For commercial decisions in the Semiconductor Emulators market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Specialist skills
Emulation flows are easier than in the past but still demand hardware-assisted verification expertise. Poor utilization or long bring-up can undermine return on investment. For commercial decisions in the Semiconductor Emulators market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Model migration complexity
Testbenches, interfaces and software workflows need compatible transactors and models. Unified vendor environments reduce the burden but switching platforms can remain difficult. For commercial decisions in the Semiconductor Emulators market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Data security
Customers require strong isolation, certified security and controlled access. Security concerns can keep the most sensitive programs on-premise despite the flexibility of cloud capacity. For commercial decisions in the Semiconductor Emulators market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Market Opportunities
Cloud emulation
Hosted capacity can attract smaller semiconductor firms and provide burst resources for large companies during peak verification phases. For commercial decisions in the Semiconductor Emulators market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification. For commercial decisions in the Semiconductor Emulators market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
AI-era multi-billion-gate systems
Larger accelerators and chiplet systems require more emulation capacity and advanced debug. For commercial decisions in the Semiconductor Emulators market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification. For commercial decisions in the Semiconductor Emulators market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Software-defined emulation/prototyping
Shared hardware that changes role through software can improve asset utilization across the development cycle. For commercial decisions in the Semiconductor Emulators market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification. For commercial decisions in the Semiconductor Emulators market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Pre-silicon power analysis
Running realistic software before tape-out creates a premium use case for emulator-based power profiling and optimization. For commercial decisions in the Semiconductor Emulators market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification. For commercial decisions in the Semiconductor Emulators market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Supply Chain Analysis
Hardware. Custom processors or large FPGA arrays, memory, high-speed interconnect and interface adapters provide the execution engine. System architecture determines capacity and predictable runtime performance. For commercial decisions in the Semiconductor Emulators market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
System integration. Vendors assemble racks or smaller studio systems with cooling, power and networking. Reliability and remote management matter because emulator farms are shared across many engineers. For commercial decisions in the Semiconductor Emulators market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Software. Compilers map RTL into the emulator, while debug tools, transactors and virtual models connect the design with software and external interfaces. Software quality is a major source of differentiation. For commercial decisions in the Semiconductor Emulators market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Deployment. Verification and software teams schedule workloads across projects. Cloud or hybrid models can add capacity for tape-out peaks and let globally distributed teams collaborate securely. For commercial decisions in the Semiconductor Emulators market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Recent Developments in the Semiconductor Emulators Market
Developments tracked through September 2026 and limited to events that materially affect technology, capacity, adoption or competition.
- 2026 Product Portfolio
Synopsys ZeBu-200 is positioned as a software-defined emulation platform with up to 2X runtime performance over the prior ZeBu EP generation and capacity scaling into multi-billion-gate designs. Source - 2026 Cloud Offering
Synopsys ZeBu Cloud provides hosted emulation capacity with secure remote access for software bring-up, power analysis and system validation, allowing customers to add capacity without operating additional hardware. Source - 17 April 2024
Cadence introduced Palladium Z3 with more than 2X capacity and 1.5X higher performance than the prior generation, targeting advanced AI, mobile, automotive and hyperscale designs. Source
Report Scope & Segmentation
| Attribute | Scope |
|---|---|
| Base year | 2025 |
| Estimated year | 2026 |
| Forecast period | 2026–2034 |
| 2025 market size | USD 748.45 million |
| 2026 estimated size | USD 871.20 million |
| 2034 projected size | USD 2.49 billion |
| CAGR (2026–2034) | 16.4% |
| Largest market in 2025 | North America |
| By Type | Hardware Emulation; FPGA-Based Emulation; Cloud Emulation; Hybrid Emulation |
| By Application | AI & Machine Learning; Networking & Data Center; Automotive; Mobile & Consumer; Others |
| By Deployment | On-Premise; Cloud-Hosted; Hybrid |
| By Verification Use Case | RTL Verification; Software Bring-Up; Power/Performance Analysis; System Validation |
| Companies profiled | Cadence; Synopsys; Siemens EDA; AMD; Microchip; Aldec; Agnisys; Blue Pearl and other verification vendors |
Frequently Asked Questions
What is the semiconductor emulators market size in 2025?
The global market is valued at USD 748.45 million in 2025 across hardware-assisted verification, FPGA and cloud-based emulation.
What is the market forecast for 2034?
The market is projected to reach USD 2.49 billion by 2034, representing a 16.4% CAGR during 2026–2034. The 2026 market level is USD 871.20 million.
Which region leads the market?
North America leads because advanced AI, CPU/GPU, networking and EDA companies are concentrated in the region.
Why are emulators needed?
They execute large RTL designs much faster than software simulation, enabling long regressions, software bring-up and system validation before silicon.
Which applications are growing fastest?
AI accelerators, networking, data-center and automotive SoCs are strong growth applications because design and software complexity is rising.
What is cloud emulation?
Cloud emulation provides hosted access to emulator capacity so teams can add resources without buying and operating all hardware themselves.
Who are the leading suppliers?
Cadence, Synopsys and Siemens EDA are the principal hardware-assisted verification platform vendors.
What are the main use cases?
RTL verification, software bring-up, power and performance analysis and system-level validation are the main use cases.
What limits adoption?
High capital cost, specialist skills, design migration effort and IP security concerns are the main restraints.
What will drive growth through 2034?
AI chip complexity, software-first development, chiplets, cloud access and the need to avoid costly silicon respins will support rapid expansion.
Research Sources & Evidence Base
View research sources used in this market overview
- Synopsys — ZeBu-200 Emulation Platform. Current performance, capacity and use-case evidence.
- Synopsys — ZeBu Cloud. Hosted emulation and security model evidence.
- Cadence — Palladium Z3. Platform capacity, performance and target application evidence.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF