Key Statistics
Key Takeaways
- Silicon Carbide (SiC) Power Modules lead the source-page type segmentation because traction inverters and other high-voltage EV functions benefit directly from SiC’s lower switching loss, higher thermal conductivity and strong operation at 750 V to 1,300 V class system voltages.
- Inverters are the critical source-page application because they convert battery DC into motor AC and therefore operate continuously at high power. Onboard chargers and DC-DC converters are also strong wide-bandgap opportunities because switching frequency can be raised to reduce passive-component size and improve conversion efficiency.
- Asia Pacific is retained as the largest region. IEA reported more than 13 million electric cars sold in China in 2025 and nearly 75% of global electric-car production located in China, creating the deepest regional base for automotive power-semiconductor design and volume manufacturing.
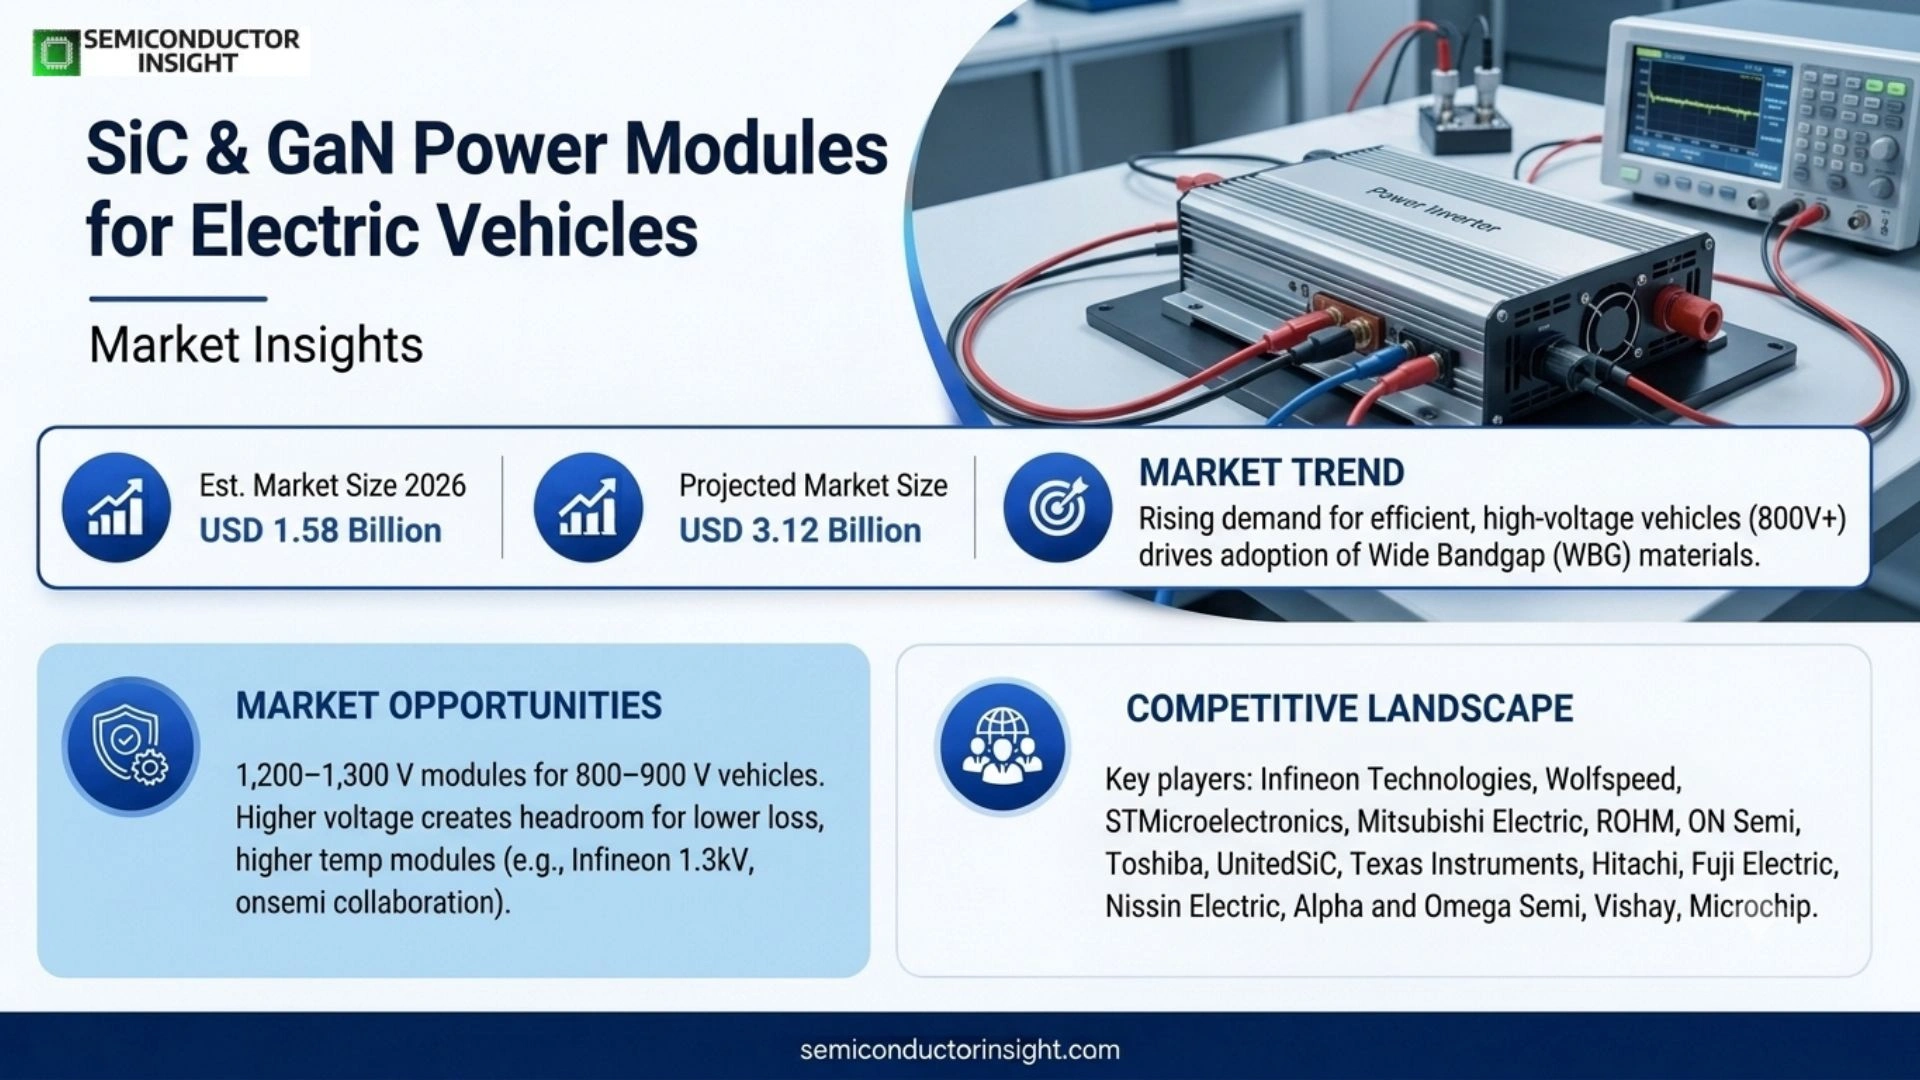
- Automotive SiC modules are moving into higher temperature and voltage classes. Infineon introduced a 1,300 V HybridPACK Drive SiC module in May 2026 capable of continuous operation up to 205°C, while onsemi expanded its Geely collaboration around next-generation 900 V EV architectures.
- The headline endpoints imply faster growth than the printed CAGR. USD 1.45 billion in 2025 and USD 3.12 billion in 2034 imply approximately 8.9% CAGR, not 8.3%, and imply a 2026 value of about USD 1.58 billion, which is close to the page’s inconsistent sentence that also labels USD 1.58 billion as a 2025 value.
Power Module (SiC & GaN) for Electric Vehicles Market Overview
Power Module (SiC & GaN) for Electric Vehicles market is valued at USD 1.45 billion in 2025, increases to an estimated USD 1.58 billion in 2026, and is projected to reach USD 3.12 billion by 2034. The selected source-page size anchors imply a 8.9% CAGR during 2026–2034. Asia Pacific is the largest market in 2025 because the source-page regional analysis explicitly describes Asia Pacific as the dominant player, supported by the world’s largest EV production and sales base, while current demand is being reshaped by 800–900 V electric-vehicle architectures, higher traction-inverter efficiency, compact onboard charging, faster DC charging, greater power density, the transition to larger SiC wafers and intensified OEM–semiconductor co-development.
SiC and GaN power modules integrate wide-bandgap power switches, substrates, interconnects and thermal structures into compact assemblies used in traction inverters, onboard chargers, DC-DC converters and auxiliary electrified systems. Their economic value comes from lowering switching and conduction losses, allowing higher switching frequency, reducing cooling demand and shrinking magnetics or passive components. For automotive customers, the module must also survive vibration, thermal cycling, humidity, high voltage and millions of operating cycles across a vehicle lifetime.
Electric-vehicle demand remains the central volume mechanism. The IEA reported that global electric-car sales exceeded 20 million in 2025, representing one in four new cars, while China sold more than 13 million and Europe reached about 4.2 million. Nearly 22 million electric cars were produced globally in 2025, with China accounting for close to three-quarters of production. This scale gives wide-bandgap suppliers a large and geographically concentrated addressable base for traction, charging and high-voltage auxiliary systems.
The technology boundary between SiC and GaN remains application dependent. SiC is currently better established in high-voltage traction inverters and high-power charging because of its voltage range, thermal performance and automotive qualification maturity. GaN is attractive where very high switching frequency can reduce magnetics and package size, particularly in onboard charging and lower-to-mid-power conversion. The source page groups both under one market, so the analysis preserves that framing while avoiding the unsupported assumption that GaN has already displaced SiC in main traction inverters.
Segment Analysis: By Type
The source page segments the market into Silicon Carbide (SiC) Power Modules and Gallium Nitride (GaN) Power Modules. SiC leads because it is already qualified across high-voltage traction and charging platforms, whereas GaN is strongest where switching frequency and compactness matter and voltage or thermal demands fit available automotive-grade device and package capability.
| Type | Technical / commercial role | Market position |
|---|---|---|
| Silicon Carbide (SiC) Power Modules | SiC modules combine MOSFETs or related SiC devices with isolated substrates, copper structures, thermal interfaces and gate connections. They are used in 400 V, 800 V and emerging 900 V-class vehicle architectures and can reduce inverter switching loss enough to improve range or permit smaller cooling systems. Packaging innovations such as silver sintering, copper clips and low-inductance layouts are becoming as important as device RDS(on). | Leading source-page segment. Infineon, onsemi, ST, ROHM, Mitsubishi Electric and Wolfspeed all have active automotive SiC module or platform activity. Commercial competition centers on reliability, current density, thermal resistance, power cycling, wafer supply and OEM qualification rather than device efficiency alone. |
| Gallium Nitride (GaN) Power Modules | GaN devices switch very quickly and can reduce magnetics and passive-component size in onboard chargers, DC-DC converters and selected auxiliary systems. Automotive use requires robust gate drive, package isolation, EMI control and qualification under wide voltage and temperature ranges. GaN’s advantage can be greatest at lower power than main traction inverters, where switching frequency directly shrinks system volume. | Smaller but strategically important source-page segment. Adoption is expected to broaden as automotive-qualified GaN platforms mature, but current high-power traction-module evidence is more limited than for SiC. Suppliers therefore compete by proving system-level efficiency, reliability and cost rather than only transistor switching speed. |
Secondary segmentation: By Technology Integration
The source page divides integration into Hybrid Power Modules, Discrete Power Modules and Monolithic Power Modules. Hybrid modules are described as increasingly preferred because they allow engineers to combine device and package advantages while controlling current, heat and switching behavior at system level. For automotive power-module suppliers, the commercial consequence is that voltage class, thermal resistance, power cycling, wafer yield and OEM qualification determine revenue quality much more directly than headline EV unit growth.
| Technology integration | Commercial implication |
|---|---|
| Hybrid Power Modules | Hybrid modules integrate multiple dies, gate connections, isolated substrates and thermal structures in one optimized package. They can mix device ratings or functions and are practical for traction and charging systems where modularity, serviceability and high-current routing matter. Automotive qualification depends on the complete assembly, not only the semiconductor die. |
| Discrete Power Modules | Discrete or semi-discrete architectures allow OEMs and Tier 1s greater flexibility in selecting individual devices and cooling structures. They can lower entry cost and simplify sourcing for lower-volume platforms but may require more PCB area and design effort than tightly integrated molded modules. |
| Monolithic Power Modules | Monolithic integration aims to reduce parasitic inductance and increase compactness by integrating more power functions in a unified structure. The approach is attractive for high-frequency GaN and some advanced SiC concepts, but thermal isolation, yield and automotive repairability can make full integration difficult at very high power. |
Secondary segmentation: By Vehicle Type
The source page identifies Passenger Vehicles, Commercial Vehicles and Two-wheelers and Others. Passenger vehicles lead because global electric-car volumes are far larger, while commercial EVs provide a strong efficiency case because high utilization and long duty cycles make small conversion losses economically meaningful. This distinction matters because traction inverters, onboard chargers and DC-DC converters operate at different power and switching conditions, so SiC and GaN cannot be treated as interchangeable across every vehicle subsystem.
| Vehicle type | Demand characteristics |
|---|---|
| Passenger Vehicles | Passenger EVs are the largest demand base and increasingly use 800 V architectures in premium and performance platforms. Wide-bandgap modules improve traction efficiency and fast-charging capability, but OEM cost targets are severe, so adoption depends on wafer and module cost declining while reliability remains automotive grade. |
| Commercial Vehicles | Electric buses, vans and trucks operate long hours and move heavier loads, which raises the value of drivetrain efficiency and thermal robustness. High-voltage SiC modules can reduce energy losses and cooling burden, improving route range and payload economics. The source page therefore identifies commercial EVs as an important growth opportunity. |
| Two-wheelers and Others | Electric scooters, motorcycles and specialty vehicles use lower absolute power and often remain highly cost sensitive. GaN or lower-rated SiC can enable compact converters and chargers, but silicon devices remain competitive in many price-sensitive designs. Growth depends on whether system savings offset the wide-bandgap device premium. |
Secondary segmentation: By End User
The source page identifies Original Equipment Manufacturers, Aftermarket Suppliers and Tier 1 Suppliers. OEMs dominate because module selection is embedded in new vehicle-platform engineering, while Tier 1 suppliers translate semiconductor capability into qualified inverters, chargers and integrated electric-drive systems. Buyers therefore evaluate system efficiency, cooling requirements, electromagnetic behavior, qualification evidence, supply assurance and lifecycle cost rather than selecting a module only from its nominal semiconductor material.
| End user | Commercial role |
|---|---|
| Original Equipment Manufacturers (OEMs) | OEMs define voltage architecture, power level, thermal system, warranty and lifetime requirements and increasingly work directly with semiconductor suppliers on module roadmaps. A successful design-in can persist across several vehicle years and derivatives, making early co-development strategically important. |
| Tier 1 Suppliers | Tier 1s integrate modules into traction inverters, chargers, e-axles and power distribution systems and must validate EMC, thermal cycling and functional safety at vehicle level. They are critical customers for standardized module families that can be reused across several OEM programs. |
| Aftermarket Suppliers | The aftermarket is smaller because high-voltage modules are usually replaced inside complete inverter or charger assemblies rather than as simple service parts. Long-term opportunity can grow as EV fleets age, but safety certification and software compatibility keep the segment more controlled than conventional mechanical aftermarket parts. |
Segment Analysis: By Application
By application, the source page lists Inverters, Onboard Chargers, DC-DC Converters and Others. Inverters are the largest strategic application because the traction stage handles the vehicle’s main propulsion power continuously, while onboard chargers and DC-DC converters benefit strongly from the high switching frequency available from SiC and GaN. Through 2034, suppliers that combine lower-cost wide-bandgap wafers with robust automotive packaging can expand beyond premium EVs into higher-volume platforms while preserving the efficiency advantage over silicon.
| Application | Demand characteristics |
|---|---|
| Inverters | Traction inverters convert battery DC into variable-frequency AC for the motor and operate across acceleration, cruising and regenerative braking. SiC can reduce switching losses, increase switching frequency and raise junction-temperature capability, allowing smaller passive and cooling systems. Infineon’s 1,300 V 205°C module and ROHM’s up-to-300 kW TRCDRIVE platform directly target this use case. |
| Onboard Chargers | OBCs convert grid AC to battery DC and are constrained by vehicle package volume and charging efficiency. ST’s ACEPACK DMT-32 and ROHM’s HSDIP20 use SiC to enable high-frequency PFC and conversion stages. GaN can also be attractive because higher switching frequency reduces magnetics, particularly in compact or bidirectional charger designs. |
| DC-DC Converters | DC-DC converters move energy between the high-voltage traction battery and 12 V, 48 V or intermediate vehicle buses. Wide-bandgap devices can reduce losses and shrink inductors and transformers, supporting higher accessory loads and zonal electrical architectures. Reliability and EMI are as important as peak efficiency because the converter operates whenever the vehicle is active. |
| Others | Other applications include electric compressors, battery disconnects, thermal management, charging stations and auxiliary drives. onsemi’s acquired SiC JFET technology is positioned for EV battery disconnect and solid-state switching, while automotive module vendors increasingly use common package families across several auxiliary functions to improve scale. |
Regional Analysis
The source-page regional analysis identifies Asia Pacific as the dominant market, with China, Japan and South Korea highlighted for manufacturing and EV adoption. Europe is described as a strong regulated market, and the FAQ separately calls Asia Pacific the fastest-growing region while Europe remains dominant; because the detailed region narrative directly labels Asia Pacific dominant, Asia Pacific is used for the 2025 leadership field and the FAQ wording conflict is logged.
How do EV volumes, semiconductor manufacturing and vehicle voltage architecture shape regional demand?
Asia Pacific has the largest EV production base and a dense power-electronics supply chain, creating both volume demand and module manufacturing scale. Europe has strong vehicle electrification and emissions regulation and is a major SiC design market. North America combines premium EV platforms with domestic SiC manufacturing. South America and MEA are earlier-stage demand regions where imported vehicles and charging infrastructure determine adoption rather than local module fabrication.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia Pacific | Largest | High | EV production and semiconductor manufacturing-led | Cost, scale, local qualification and supply security |
| Europe | Large high-value market | High | EV regulation and premium platform-led | Efficiency, reliability and automotive qualification |
| North America | Innovation and domestic SiC hub | Moderate to high | EV, pickup/SUV and local power-semiconductor-led | Performance, domestic supply and platform co-design |
| South America | Emerging | High from small base | Imported EV and fleet electrification-led | Cost, vehicle availability and service |
| Middle East & Africa | Emerging | Moderate from small base | Premium EV, fleet and charging-led | Thermal robustness, imported supply and infrastructure |
Competitive Landscape
The source page profiles fifteen companies: Infineon Technologies, Wolfspeed, STMicroelectronics, Mitsubishi Electric, ROHM Semiconductor, ON Semiconductor, Toshiba, United Silicon Carbide, Texas Instruments, Hitachi Automotive Systems, Nissin Electric, Fuji Electric, Alpha and Omega Semiconductor, Vishay Intertechnology and Microchip Technology. The FAQ is corrupted and names coatings companies, so it is ignored for company scope. Current-company context is added where ownership has changed.
Infineon, onsemi, ST, ROHM, Mitsubishi Electric and Wolfspeed are the clearest current automotive SiC competitors in the source list. Their differentiation spans die technology, module packaging, wafer scale, thermal design and direct OEM relationships. Infineon’s 205°C HybridPACK, onsemi’s Geely collaboration and ROHM’s TRCDRIVE demonstrate module-level competition rather than discrete-device competition alone.
Wolfspeed is vertically integrated from SiC materials through devices and modules and is commercially focused on scaling 200 mm while developing 300 mm technology. ST combines internal SiC device capability with ACEPACK module platforms, while Mitsubishi Electric is expanding trench SiC die and J3 automotive modules. Toshiba participates strongly in power semiconductors, though public current automotive module activity is less visible than the leading six.
The source-page company names contain historical structures. United Silicon Carbide was acquired by Qorvo in 2021, and onsemi acquired that SiC JFET business from Qorvo in January 2025. Hitachi Automotive Systems became part of Hitachi Astemo. ON Semiconductor now brands itself onsemi. These labels are preserved in the formal source roster but distinguished from current corporate structure.
| Competitive tier | Companies | Why they matter |
|---|---|---|
| Automotive SiC module leaders | Infineon Technologies; onsemi; STMicroelectronics; ROHM Semiconductor; Mitsubishi Electric; Wolfspeed | These suppliers have current automotive-grade SiC module, die or platform evidence and direct EV traction/charging positioning. Their competitive edge depends on qualified reliability, high-current packaging, wafer economics and long-term OEM supply. |
| Broader power-semiconductor participants | Toshiba; Fuji Electric; Texas Instruments; Microchip Technology; Alpha and Omega Semiconductor; Vishay Intertechnology | These companies participate in power semiconductors or automotive electronics but differ in current SiC/GaN module depth. They remain part of the source profile list and can address discrete, driver, auxiliary or specialty power functions. |
| Historical / integrated source labels | United Silicon Carbide; Hitachi Automotive Systems; Nissin Electric | United Silicon Carbide is now inside onsemi following Qorvo ownership, and Hitachi Automotive Systems is part of Hitachi Astemo. The names are retained for source fidelity rather than treated as equivalent standalone 2026 module suppliers. |
Companies profiled in the report
The source page profiles Infineon Technologies; Wolfspeed; STMicroelectronics; Mitsubishi Electric; ROHM Semiconductor; ON Semiconductor; Toshiba; United Silicon Carbide; Texas Instruments; Hitachi Automotive Systems; Nissin Electric; Fuji Electric; Alpha and Omega Semiconductor; Vishay Intertechnology; and Microchip Technology. The market implication is that announced device performance creates commercial value only when the complete module, cooling interface and manufacturing site are qualified for the target vehicle platform.
Production Capacity Analysis
Production capacity for automotive wide-bandgap modules spans substrate crystal growth, epitaxy, device fabrication, wafer thinning, die attach, isolated substrates, copper interconnect, molding or gel fill, power cycling and final automotive test. SiC cost remains sensitive to wafer yield and die area, while module capacity is constrained by packaging materials and thermal processes that cannot always be shared with conventional silicon IGBT products.
Wolfspeed’s current strategy illustrates wafer-scale economics. The company commercially launched a 200 mm SiC materials portfolio in 2025 and demonstrated a 300 mm single-crystal wafer in January 2026. Larger wafers can ultimately increase die output per wafer, but crystal defect density, epitaxy and device yield must mature before the diameter advantage translates into lower automotive module cost.
Module packaging is an independent capacity layer. ROHM uses copper clips and silver-sinter die attach in TRCDRIVE, Infineon uses advanced HybridPACK structures, and ST uses high-thermal-conductivity aluminum-nitride DBC in ACEPACK. These packaging processes determine thermal resistance and power cycling and require specialized assembly equipment, so extra SiC wafer supply does not automatically create qualified module capacity.
Automotive qualification makes saleable capacity slower to ramp than nameplate output. OEMs and Tier 1s validate junction temperature, insulation, thermal cycling, vibration and inverter-level performance over long programs. A new wafer fab or module line only becomes economically useful after the exact product and site are approved for a vehicle platform.
Market Dynamics
The market is driven by EV volume, 800–900 V architectures, higher switching frequency and pressure to improve range, but it faces substrate cost, packaging complexity, vehicle-platform qualification and competition from continuously improving silicon IGBTs. The strongest suppliers convert material and device advantages into measurable system savings rather than relying on wide-bandgap branding alone.
Market Drivers
| Driver | Directional impact* | Commercial mechanism |
|---|---|---|
| Global EV production | High | More than 20 million electric cars were sold in 2025, directly expanding the number of traction inverters, chargers and high-voltage converters. |
| 800–900 V architectures | High | Higher battery voltage reduces current and charging time but raises switching and insulation requirements, favoring SiC modules with strong voltage and thermal margins. |
| Range & efficiency pressure | High | Lower switching and conduction losses can translate into longer driving range or smaller batteries and cooling systems. |
| Fast-charging & compact OBC | Medium to High | Higher switching frequency can reduce magnetics and charger volume, creating opportunities for SiC and GaN in onboard and external charging. |
EV volume provides the base demand engine
More than 20 million electric cars were sold globally in 2025, according to the IEA, and 2026 sales are expected around 23 million. Every BEV requires a traction inverter and usually an onboard charger and DC-DC converter, creating a large and growing installed base for efficient high-voltage power semiconductors. For automotive power-module suppliers, the commercial consequence is that voltage class, thermal resistance, power cycling, wafer yield and OEM qualification determine revenue quality much more directly than headline EV unit growth.
Higher battery voltage increases SiC value
Moving from 400 V toward 800 V and 900 V architectures lowers current for a given power level but increases device voltage and insulation requirements. SiC combines high breakdown field, low switching loss and strong thermal performance, making it attractive for fast-charging and high-power vehicle platforms. This distinction matters because traction inverters, onboard chargers and DC-DC converters operate at different power and switching conditions, so SiC and GaN cannot be treated as interchangeable across every vehicle subsystem.
System-level efficiency has vehicle-level value
A lower-loss inverter can extend range from the same battery or allow an OEM to achieve target range with less battery capacity. It can also reduce cooling-system size and improve sustained power. This allows semiconductor cost to be justified by savings elsewhere in the vehicle bill of materials. Buyers therefore evaluate system efficiency, cooling requirements, electromagnetic behavior, qualification evidence, supply assurance and lifecycle cost rather than selecting a module only from its nominal semiconductor material.
Higher switching frequency shrinks magnetic components
OBC and DC-DC converters can operate at higher switching frequency with SiC or GaN, reducing transformer and inductor size. The benefit is especially valuable in vehicles because package volume and weight are constrained and thermal performance affects surrounding systems. Through 2034, suppliers that combine lower-cost wide-bandgap wafers with robust automotive packaging can expand beyond premium EVs into higher-volume platforms while preserving the efficiency advantage over silicon.
Market Restraints
| Restraint | Directional impact* | Commercial mechanism |
|---|---|---|
| SiC substrate and fab cost | High | Wide-bandgap wafers and processing remain more expensive than mature silicon, limiting adoption in price-sensitive vehicle segments. |
| Module packaging complexity | High | High power density requires low-inductance interconnects, advanced die attach and robust cooling, increasing manufacturing and qualification cost. |
| Automotive qualification | Medium to High | Vehicle programs require long validation cycles, slowing new-supplier and new-factory adoption even when electrical performance is attractive. |
| Silicon IGBT competition | Medium | Improving silicon devices remain competitive in cost-sensitive 400 V and lower-performance applications, especially when vehicle efficiency benefits are modest. |
Wide-bandgap cost remains structurally higher
SiC crystal growth and wafer preparation are slower and more defect sensitive than silicon, while GaN often uses specialized epitaxy and packaging. Cost is falling with scale and larger wafers, but price-sensitive mass-market EVs can still favor advanced silicon if system efficiency gains do not justify the premium. The market implication is that announced device performance creates commercial value only when the complete module, cooling interface and manufacturing site are qualified for the target vehicle platform.
Packaging becomes harder as power density rises
Faster switches can create higher dv/dt, EMI and local heat flux. Module designers need low stray inductance, robust gate loops, high-thermal-conductivity substrates and reliable die attach. A poor package can erase much of the semiconductor’s performance advantage or reduce lifetime under automotive thermal cycling. For automotive power-module suppliers, the commercial consequence is that voltage class, thermal resistance, power cycling, wafer yield and OEM qualification determine revenue quality much more directly than headline EV unit growth.
Qualification creates long commercial lead times
OEMs may evaluate a module for years before start of production. Any material, die or assembly-site change can trigger requalification. This creates strong incumbent advantage but means new capacity or technology cannot be monetized immediately after technical launch. This distinction matters because traction inverters, onboard chargers and DC-DC converters operate at different power and switching conditions, so SiC and GaN cannot be treated as interchangeable across every vehicle subsystem.
Silicon remains economically competitive in many platforms
Modern IGBTs continue improving and have enormous scale, mature supply chains and proven automotive reliability. For lower-voltage or cost-sensitive vehicles, silicon can deliver acceptable efficiency at lower device cost, slowing full-market conversion to SiC or GaN. Buyers therefore evaluate system efficiency, cooling requirements, electromagnetic behavior, qualification evidence, supply assurance and lifecycle cost rather than selecting a module only from its nominal semiconductor material.
Market Opportunities
1,200–1,300 V modules for 800–900 V vehicles
Infineon’s 1,300 V module and onsemi’s 900 V platform collaboration show that higher-voltage vehicles create room for modules with more voltage headroom, higher junction temperature and lower loss. Through 2034, suppliers that combine lower-cost wide-bandgap wafers with robust automotive packaging can expand beyond premium EVs into higher-volume platforms while preserving the efficiency advantage over silicon.
GaN onboard charging
GaN can raise switching frequency in OBCs and auxiliary converters and reduce magnetics. As automotive-qualified GaN packages mature, suppliers can target compact bidirectional chargers where power density is more important than main-traction current capability. The market implication is that announced device performance creates commercial value only when the complete module, cooling interface and manufacturing site are qualified for the target vehicle platform.
Commercial EV and fleet applications
Buses, trucks and delivery vehicles accumulate high annual mileage, making conversion efficiency financially valuable. High-power SiC can improve route range and thermal robustness, supporting faster payback than in low-utilization passenger cars. For automotive power-module suppliers, the commercial consequence is that voltage class, thermal resistance, power cycling, wafer yield and OEM qualification determine revenue quality much more directly than headline EV unit growth.
200 mm and future 300 mm SiC scale-up
Commercial 200 mm production and early 300 mm development create a cost-reduction path. Suppliers that improve crystal and device yield while preserving reliability can lower module ASP enough to expand into mid-market EV platforms. This distinction matters because traction inverters, onboard chargers and DC-DC converters operate at different power and switching conditions, so SiC and GaN cannot be treated as interchangeable across every vehicle subsystem.
Supply Chain Analysis
SiC substrates / GaN epitaxy
Power-device fabrication
Module packaging & thermal integration
Tier 1 / OEM inverter and charger integration
SiC substrates / GaN epitaxy
SiC starts with crystal growth, slicing, polishing and epitaxy, while GaN power devices use GaN epitaxial layers on suitable substrates. Defect density, wafer diameter and epitaxial uniformity strongly influence device yield and cost. Buyers therefore evaluate system efficiency, cooling requirements, electromagnetic behavior, qualification evidence, supply assurance and lifecycle cost rather than selecting a module only from its nominal semiconductor material.
Power-device fabrication
MOSFETs, diodes and GaN transistors are fabricated using high-voltage process flows. Trench design, gate oxide reliability, ohmic contacts and passivation determine conduction loss, switching behavior and automotive lifetime. Through 2034, suppliers that combine lower-cost wide-bandgap wafers with robust automotive packaging can expand beyond premium EVs into higher-volume platforms while preserving the efficiency advantage over silicon.
Module packaging & thermal integration
Die are attached to DBC/AMB substrates or advanced molded structures, connected by wire bonds, clips or planar interconnects, and combined with sensors and terminals. Thermal resistance, stray inductance and power cycling are major differentiators. The market implication is that announced device performance creates commercial value only when the complete module, cooling interface and manufacturing site are qualified for the target vehicle platform.
Tier 1 / OEM inverter and charger integration
Modules are paired with gate drivers, capacitors, cooling plates and control software and then qualified in traction, OBC or DC-DC systems. Vehicle platform timing and warranty requirements determine commercial ramp and long-term supplier revenue. For automotive power-module suppliers, the commercial consequence is that voltage class, thermal resistance, power cycling, wafer yield and OEM qualification determine revenue quality much more directly than headline EV unit growth.
Recent Developments
Recent primary-source developments show automotive SiC moving toward higher voltage, higher temperature and more integrated module platforms, while wafer technology and OEM collaboration continue to reduce cost and qualification risk. The source-page FAQ’s unrelated coatings-company list is not used. This distinction matters because traction inverters, onboard chargers and DC-DC converters operate at different power and switching conditions, so SiC and GaN cannot be treated as interchangeable across every vehicle subsystem.
May 29, 2026 – Infineon introduced a 1,300 V SiC HybridPACK Drive module rated for 205°C
Infineon announced a new automotive CoolSiC HybridPACK Drive module capable of continuous operation up to 205°C, compared with typical existing limits around 175°C. The higher junction-temperature capability can support more continuous inverter power or allow OEMs to reduce cooling complexity and system cost in new EV designs. Buyers therefore evaluate system efficiency, cooling requirements, electromagnetic behavior, qualification evidence, supply assurance and lifecycle cost rather than selecting a module only from its nominal semiconductor material.
April 28, 2026 – onsemi and Geely expanded collaboration around 900 V EV architectures
onsemi and Geely Auto Group expanded their strategic collaboration and said EliteSiC power technologies are integrated in Geely’s SEA-S-based Super Electric Power system. The partnership targets next-generation 900 V electric and hybrid vehicles with faster charging, longer range and higher system-level efficiency. Through 2034, suppliers that combine lower-cost wide-bandgap wafers with robust automotive packaging can expand beyond premium EVs into higher-volume platforms while preserving the efficiency advantage over silicon.
April 21, 2026 – ROHM developed fifth-generation SiC MOSFETs
ROHM announced fifth-generation EcoSiC MOSFET technology with approximately 30% lower on-resistance at high temperature and positioning for EV traction inverters, AI servers and industrial power. The generation is designed to improve efficiency and power density and supports future module-platform development. The market implication is that announced device performance creates commercial value only when the complete module, cooling interface and manufacturing site are qualified for the target vehicle platform.
March 17, 2026 – ROHM released inverter reference designs around SiC modules
ROHM released three-phase inverter reference designs using HSDIP20, DOT-247 and TRCDRIVE SiC molded modules for output power up to the 300 kW class. The designs reduce evaluation and gate-drive engineering effort and accelerate adoption in automotive and industrial power systems. For automotive power-module suppliers, the commercial consequence is that voltage class, thermal resistance, power cycling, wafer yield and OEM qualification determine revenue quality much more directly than headline EV unit growth.
January 14, 2026 – Mitsubishi Electric began sampling new trench SiC MOSFET bare dies
Mitsubishi Electric announced four new trench SiC MOSFET bare-die samples for EV traction inverters, onboard chargers and renewable-energy power systems. The move expands device options for module and system manufacturers that need lower-loss SiC in custom embedded power architectures. This distinction matters because traction inverters, onboard chargers and DC-DC converters operate at different power and switching conditions, so SiC and GaN cannot be treated as interchangeable across every vehicle subsystem.
January 13, 2026 – Wolfspeed demonstrated a 300 mm single-crystal SiC wafer
Wolfspeed announced successful production of a single-crystal 300 mm SiC wafer. The milestone is a long-term manufacturing development rather than immediate automotive module capacity, but it establishes a potential future path to more die per wafer and lower SiC cost if commercial yield can be achieved. Buyers therefore evaluate system efficiency, cooling requirements, electromagnetic behavior, qualification evidence, supply assurance and lifecycle cost rather than selecting a module only from its nominal semiconductor material.
Report Scope & Segmentation
| Attribute | Coverage |
|---|---|
| Market | Power Module (SiC & GaN) for Electric Vehicles |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| 2025 Market Size | USD 1.45 billion |
| 2034 Forecast Size | USD 3.12 billion |
| CAGR | 8.9% (2026–2034) |
| Largest Market in 2025 | Asia Pacific |
| By Type | Silicon Carbide (SiC) Power Modules; Gallium Nitride (GaN) Power Modules |
| By Application | Inverters; Onboard Chargers; DC-DC Converters; Others |
| By End User | Original Equipment Manufacturers (OEMs); Aftermarket Suppliers; Tier 1 Suppliers |
| By Technology Integration | Hybrid Power Modules; Discrete Power Modules; Monolithic Power Modules |
| By Vehicle Type | Passenger Vehicles; Commercial Vehicles; Two-wheelers and Others |
| Regions | Asia Pacific; North America; Europe; South America; Middle East & Africa |
| Companies Profiled | Infineon Technologies; Wolfspeed; STMicroelectronics; Mitsubishi Electric; ROHM Semiconductor; ON Semiconductor; Toshiba; United Silicon Carbide; Texas Instruments; Hitachi Automotive Systems; Nissin Electric; Fuji Electric; Alpha and Omega Semiconductor; Vishay Intertechnology; Microchip Technology |
Frequently Asked Questions
What is the Power Module (SiC & GaN) for Electric Vehicles market size in 2025?
The source page publishes USD 1.45 billion in 2025 and USD 3.12 billion in 2034. The 2025 value is therefore preserved exactly. The endpoints imply an estimated 2026 market size of approximately USD 1.58 billion when a mathematically consistent annual compound rate is used. Through 2034, suppliers that combine lower-cost wide-bandgap wafers with robust automotive packaging can expand beyond premium EVs into higher-volume platforms while preserving the efficiency advantage over silicon.
What is the projected market size by 2034?
The source-page 2034 endpoint is USD 3.12 billion. Because the page already provides both 2025 and 2034 size anchors, the article does not substitute an outside market estimate and instead recalculates the annual compound rate so the repeated series remains internally consistent. The market implication is that announced device performance creates commercial value only when the complete module, cooling interface and manufacturing site are qualified for the target vehicle platform.
Why is the CAGR 8.9% instead of the page’s 8.3%?
USD 1.45 billion in 2025 and USD 3.12 billion in 2034 imply approximately 8.89% compound annual growth over nine years. The source-page printed 8.3% rate therefore does not reconcile with its own endpoints. Under the batch methodology, the published size anchors control. For automotive power-module suppliers, the commercial consequence is that voltage class, thermal resistance, power cycling, wafer yield and OEM qualification determine revenue quality much more directly than headline EV unit growth.
Which type leads the market?
The source page identifies Silicon Carbide Power Modules as the leading type because SiC supports high voltage, low switching loss and strong thermal performance in EV traction and charging. GaN remains an important complementary technology for high-frequency onboard charging and compact conversion. This distinction matters because traction inverters, onboard chargers and DC-DC converters operate at different power and switching conditions, so SiC and GaN cannot be treated as interchangeable across every vehicle subsystem.
Which application is most important?
Inverters are the most critical application because they process the vehicle’s main traction power continuously. Onboard chargers and DC-DC converters are also important because higher switching frequency can shrink magnetics and improve power density, creating opportunities for both SiC and GaN. Buyers therefore evaluate system efficiency, cooling requirements, electromagnetic behavior, qualification evidence, supply assurance and lifecycle cost rather than selecting a module only from its nominal semiconductor material.
Which region dominates the market?
The detailed source-page regional analysis calls Asia Pacific the dominant market, supported by China, Japan and South Korea. The FAQ separately calls Asia Pacific fastest growing while saying Europe remains dominant. This article uses Asia Pacific for the leadership field and logs that source inconsistency. Through 2034, suppliers that combine lower-cost wide-bandgap wafers with robust automotive packaging can expand beyond premium EVs into higher-volume platforms while preserving the efficiency advantage over silicon.
How large is the EV demand base supporting the market?
IEA reported more than 20 million electric cars sold worldwide in 2025, with more than 13 million in China and around 4.2 million in Europe. Nearly 22 million electric cars were produced globally, providing a large and growing installed base for traction and charging power electronics. The market implication is that announced device performance creates commercial value only when the complete module, cooling interface and manufacturing site are qualified for the target vehicle platform.
Why are 800 V and 900 V architectures important?
Higher battery voltage reduces current for the same power and can enable faster charging and smaller conductors, but it increases device-voltage and insulation requirements. SiC modules with 1,200 V to 1,300 V ratings are well suited to these architectures because of their breakdown and thermal characteristics. For automotive power-module suppliers, the commercial consequence is that voltage class, thermal resistance, power cycling, wafer yield and OEM qualification determine revenue quality much more directly than headline EV unit growth.
Who are the companies profiled on the source page?
The source page profiles Infineon, Wolfspeed, STMicroelectronics, Mitsubishi Electric, ROHM, ON Semiconductor, Toshiba, United Silicon Carbide, Texas Instruments, Hitachi Automotive Systems, Nissin Electric, Fuji Electric, Alpha and Omega Semiconductor, Vishay and Microchip. Some names are historical corporate labels and are identified as such in the analysis. This distinction matters because traction inverters, onboard chargers and DC-DC converters operate at different power and switching conditions, so SiC and GaN cannot be treated as interchangeable across every vehicle subsystem.
What is the main strategic risk through 2034?
The main risk is that wide-bandgap cost reduction does not keep pace with silicon improvement and vehicle cost pressure. Suppliers must raise wafer and module yield, complete lengthy automotive qualifications and demonstrate system-level savings large enough to justify a higher semiconductor price. Buyers therefore evaluate system efficiency, cooling requirements, electromagnetic behavior, qualification evidence, supply assurance and lifecycle cost rather than selecting a module only from its nominal semiconductor material.

Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF