Key Statistics
Key Takeaways
- Moulded Case Circuit Breakers (MCCBs) lead the type mix because they cover a broad industrial and commercial current range, offer adjustablea protection and increasingly support electronic trip units, communications and energy monitoring.
- Manufacturing and process industries remain the largest application base, while smart/digital breakers are the fastest-growing technology segment as facilities demand remote diagnostics, predictive maintenance and tighter integration with building and plant management systems.
- Asia Pacific is the largest market and China is the central demand and manufacturing hub. Regional growth is reinforced by industrial capacity, grid investment, renewable integration and urban infrastructure expansion.
- Standards and approvals are central to market access. IEC 60947-2:2024 covers low-voltage circuit breakers up to 1,000 V AC or 1,500 V DC, making compliance, certification and application engineering part of the supplier value proposition.
- Air circuit breakers are becoming digital power-management nodes. ABB’s 2025 SACE Emax 3 launch added predictive maintenance, sensing and cybersecurity features targeted at data centers, factories and critical infrastructure.
Low-voltage Circuit Breakers Market Overview
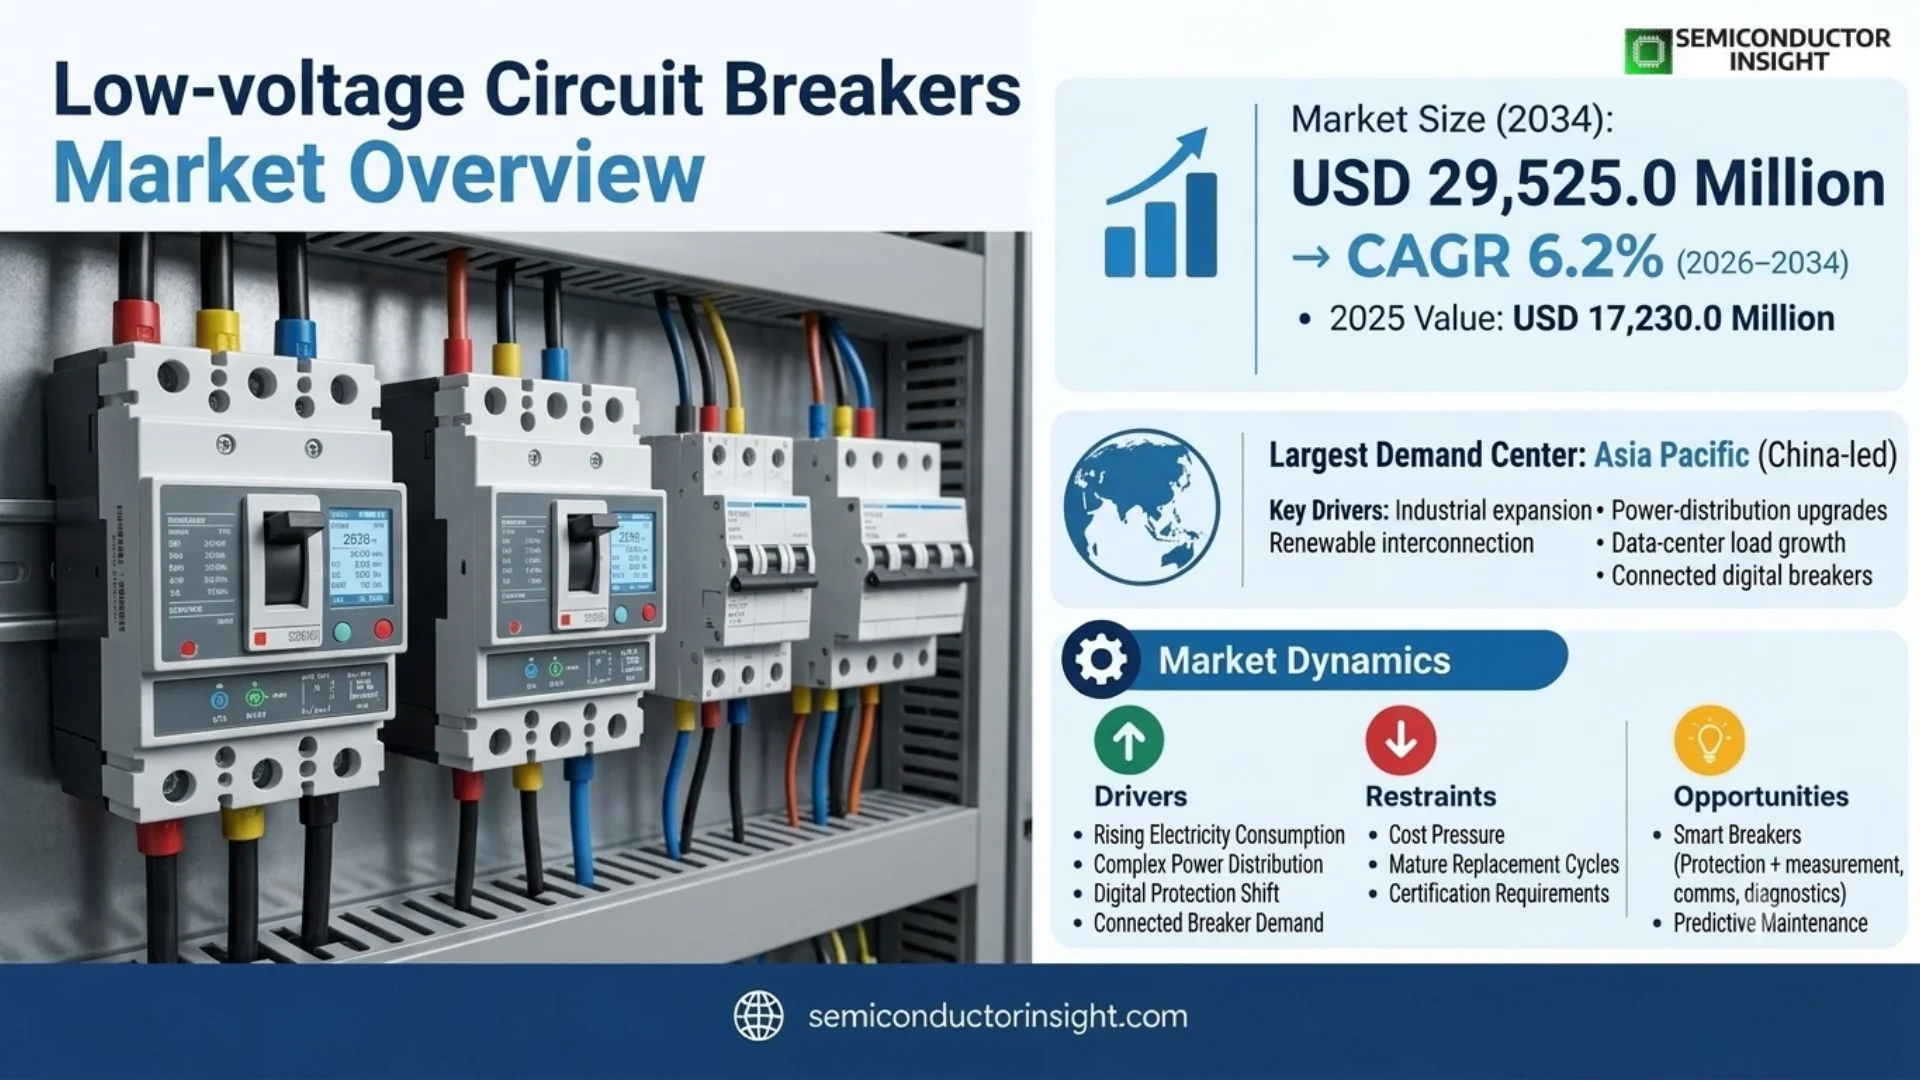
Low-voltage Circuit Breakers Market was valued at USD 17,230.0 million in 2025 and is projected to reach USD 29,525.0 million by 2034, expanding at a 6.2% CAGR during 2026–2034. Asia Pacific (China-led) is the largest demand center, supported by industrial expansion, power-distribution upgrades, renewable interconnection, data-center load growth and the shift from purely mechanical protection toward connected digital breakers.
Low-voltage circuit breakers protect electrical circuits against overload, short circuit and other fault conditions while allowing safe isolation and switching. The market spans miniature circuit breakers used in final distribution, moulded case circuit breakers used across commercial and industrial feeders, and air circuit breakers used at higher currents in main low-voltage switchboards. Although the core protective function is mature, product value is increasing through electronic trip units, communications, metering and cybersecurity.
Demand is closely linked to electricity consumption, construction, industrial capital spending and the complexity of power systems. Electrification is increasing the number of low-voltage distribution points across factories, buildings, charging infrastructure, renewable plants and data centers. At the same time, power quality and uptime expectations are rising, which encourages customers to replace basic thermal-magnetic protection with connected breakers that provide diagnostics, event logs and remote settings.
Global electricity demand rose strongly in 2024 and the IEA expects continued robust growth, with developing economies accounting for most incremental demand. This supports low-voltage switchgear investment because every additional load eventually requires distribution, isolation and protection. The market therefore benefits from both new infrastructure and the modernization of existing panels, particularly where smart breakers can reduce downtime or provide energy-management data.
Segment Analysis: By Type
By type, the market is segmented into Miniature Circuit Breakers (MCB), Moulded Case Circuit Breakers (MCCB), and Air Circuit Breakers (ACB). MCCBs hold the strongest broad-market position because their adjustable protection, current range and accessory ecosystem fit industrial and commercial distribution, while ACBs capture high-value main-switchboard applications.
| Type | Technical role | Market position |
|---|---|---|
| Miniature Circuit Breaker (MCB) | Final-circuit protection for residential, light-commercial and smaller industrial loads. | Highest unit-volume category. Competition is intense and price-sensitive, with differentiation coming from breaking capacity, compactness, approvals, accessory compatibility and brand/channel coverage. |
| Moulded Case Circuit Breaker (MCCB) | Feeder and equipment protection across industrial and commercial systems, often with adjustable or electronic trip units. | Largest value segment. MCCBs span wide current and interrupting ratings and increasingly integrate metering, communications and condition monitoring, supporting higher average selling prices. |
| Air Circuit Breaker (ACB) | Main incomer, tie and generator protection in large low-voltage switchboards and critical facilities. | Lower unit volume but high value. Data centers, hospitals, factories and large buildings increasingly specify advanced sensing, selectivity, remote diagnostics and cybersecurity. |
Technology evolution: electromechanical to smart/digital
The source report also segments the market by technology into conventional electromechanical, electronic trip unit and smart/digital products. Smart breakers are growing fastest because they convert protection equipment into a source of operating data. Remote monitoring, power metering, predictive maintenance and integration with SCADA or building-management systems can reduce outage risk and improve energy management, which shifts purchasing decisions from first cost toward lifecycle value.
Segment Analysis: By Application
By application, demand spans Manufacturing & Process Industry, Residential & Commercial, Transmission & Distribution, Power Generation, and Others. Manufacturing and process industries lead because continuous operations, motor loads and complex feeder systems require coordinated protection, while data centers and commercial buildings are increasing demand for connected breakers.
| Application | Demand characteristics |
|---|---|
| Manufacturing & Process Industry | Factories require protection for motors, drives, process equipment and distribution boards. Downtime has direct economic cost, so adjustable trip settings, selectivity, diagnostics and condition monitoring are increasingly valued. Advanced manufacturing and semiconductor facilities also need high power quality and dense distribution, supporting premium MCCB and ACB demand. |
| Residential & Commercial | Residential buildings drive high MCB unit volumes, while offices, retail, hospitals and data centers use a broader mix of MCBs, MCCBs and ACBs. Smart-building integration and energy monitoring support digital products, but procurement remains highly sensitive to local electrical codes and installer familiarity. |
| Transmission & Distribution | Low-voltage breakers sit downstream of medium-voltage substations in utility and private distribution systems. Grid modernization, distributed generation and storage increase the complexity of bidirectional power flows, creating demand for protection devices with communications and flexible settings. |
| Power Generation | Conventional, renewable and distributed generation facilities use breakers for auxiliary loads, balance-of-plant systems and low-voltage distribution. Solar and storage projects add DC and AC protection needs, while microgrids increase the value of products capable of operating across multiple power sources. |
| Others | Transport, marine, telecom, mining and public infrastructure create specialized requirements for vibration, environmental protection, remote operation or compact form factors. These niches often support higher-value configurations and application-specific certifications. |
Regional Analysis
Asia Pacific is the largest market, led by China. Industrialization, urban infrastructure, renewable deployment and local manufacturing support high unit volumes, while North America and Europe emphasize smart protection, data centers, retrofit modernization and higher-value digital functionality.
How does regional demand differ across the low-voltage circuit breakers market?
Regional purchasing reflects different combinations of construction, industrial load growth, codes and installed base. Asia Pacific is strongest in new build and manufacturing; North America has large retrofit and data-center demand; Europe emphasizes efficiency, connectivity and standards; South America is concentrated in Brazil and industrial projects; and Middle East & Africa is project-led with strong commercial-building, energy and infrastructure demand.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia Pacific | Largest | High | New build + industrial | Price, local supply, IEC/GB approvals, digital capability |
| North America | Major | Steady-high | Retrofit + data centers | UL/NEMA approvals, reliability, service, smart features |
| Europe | Major | Steady | Industrial + energy efficiency | IEC compliance, connectivity, lifecycle efficiency |
| South America | Smaller | Moderate | Industrial + commercial | Landed cost, distributor network, standards |
| Middle East & Africa | Emerging | Moderate-high | Infrastructure + data centers | Project approval, heat performance, service support |
Detailed Regional Analysis
Competitive Landscape
The market is moderately consolidated around global electrical-equipment groups with broad portfolios, supported by strong regional manufacturers. Competitive advantage depends on installed base, standards approvals, switchgear integration, channel reach, digital trip-unit capability and lifecycle service.
Schneider Electric, ABB, Eaton, Siemens and Mitsubishi Electric compete across MCB, MCCB and ACB families and benefit from deep relationships with panel builders, consultants, contractors and industrial customers. Their broad portfolios allow breakers to be sold as part of complete switchboards, power-management systems and service packages, which increases switching costs beyond the individual device.
Chinese manufacturers including CHINT, Shanghai Renmin, Liangxin and DELIXI compete strongly on price and local availability while steadily improving digital features and international market access. Their scale in the world’s largest regional market supports manufacturing efficiency and rapid product refresh cycles, increasing competitive pressure on global incumbents in standard MCB and MCCB ranges.
Digitalization is widening the competitive gap between basic protection and system-level offerings. Modern ACBs and MCCBs can include power metering, waveform data, condition monitoring, remote control and cybersecurity. These functions create recurring software and service opportunities and make the breaker part of a broader power-management architecture rather than a one-time hardware purchase.
| Competitive tier | Representative companies | Basis of competition |
|---|---|---|
| Global system leaders | Schneider Electric, ABB, Eaton, Siemens, Mitsubishi Electric | Full portfolios, switchgear integration, global approvals, digital trip units and service |
| Large regional challengers | CHINT, Fuji Electric, Hyundai, Shanghai Renmin, Liangxin, DELIXI | Cost, local manufacturing, regional channels and expanding smart features |
| Specialists / local brands | Hager, Changshu Switchgear, S. Men Rin and others | Focused channels, regional standards and selected product niches |
Companies profiled in the report
The profiled company set includes Schneider Electric, ABB, Eaton, Siemens, Mitsubishi Electric, General Electric, Hager, Fuji Electric, Hyundai, CHINT Electrics, Shanghai Renmin, Changshu Switchgear, Liangxin, DELIXI, S. Men Rin. The list is retained from the source report scope; competitive commentary differentiates suppliers by technology depth, qualification track record, regional channel access, and the application requirements they are positioned to serve rather than treating every company as interchangeable.
Production Capacity & Manufacturing Analysis
Manufacturing capacity is concentrated near major electrical-equipment and switchgear clusters in China, Europe, North America and Japan. True competitive capacity includes molded parts, contacts, trip units, arc-chute production, automated assembly, testing and certification capability.
MCBs are highly automated, high-volume products where scale and line efficiency matter. MCCBs and ACBs require more complex assembly, electronic trip units and accessory integration, so manufacturing flexibility becomes more important than simple unit throughput. Suppliers increasingly design common platforms that share frames, accessories and digital electronics across current ratings to reduce complexity and speed configuration.
Testing is a major capacity constraint because breakers must demonstrate interrupting performance, thermal behavior, endurance and coordination under defined standards. High-power short-circuit laboratories are capital intensive and cannot be replaced by ordinary production equipment. Manufacturers with internal test capability can iterate designs faster and support customer-specific certifications more efficiently than firms that depend entirely on third-party labs.
Market Dynamics
Market growth is supported by rising electricity consumption, more complex power distribution and digital protection, while cost pressure, mature replacement cycles and certification requirements temper expansion. The highest-value growth comes from breakers that combine protection with measurement, communications and predictive diagnostics.
Market Drivers
Forces expanding addressable demand
| Driver | Directional impact* | Commercial mechanism |
|---|---|---|
| Electricity demand and electrification | High | More loads and distribution points require additional protection devices. |
| Data-center and critical-power build-out | High | High uptime requirements favor premium ACB/MCCB systems with diagnostics. |
| Renewable and distributed generation | Medium-high | Bidirectional and variable power flows increase protection complexity. |
| Smart/digital breaker adoption | Medium-high | Monitoring and predictive maintenance raise product value and replacement demand. |
Rising electricity demand expands distribution infrastructure
The IEA reported a 4.3% increase in global electricity consumption in 2024 and expects robust demand growth to continue. New factories, buildings, charging systems and digital infrastructure all require low-voltage distribution and protection. This provides a direct demand mechanism for MCBs, MCCBs and ACBs even when the underlying electrical loads differ by region.
Data centers raise the value of intelligent protection
AI and cloud infrastructure use dense power distribution where a fault can interrupt high-value computing capacity. Modern ACBs combine selective protection with sensing, power-quality data and predictive maintenance, allowing operators to identify problems before an outage. This shifts purchasing toward premium products and makes digital features an important growth driver.
Renewable and storage systems add new protection requirements
Solar, wind, batteries and microgrids create more distributed and bidirectional power flows. Protection systems must accommodate changing source conditions, DC circuits and multiple operating modes. This supports demand for flexible trip units, communication capability and devices designed for renewable or direct-current applications.
Industrial modernization replaces basic thermal-magnetic products
Factories increasingly connect low-voltage equipment to SCADA, energy-management and maintenance systems. Electronic trip units and connected breakers can provide current, voltage, power and event data while supporting remote settings. The productivity and maintenance benefits create an economic reason to replace functioning but non-connected breakers during panel upgrades.
Market Restraints
Constraints on adoption and supplier economics
| Restraint | Directional impact* | Commercial mechanism |
|---|---|---|
| Price pressure in standard MCBs | Medium-high | High unit volumes attract intense regional competition and limit margin. |
| Long replacement cycles | Medium | Properly maintained breakers can remain in service for many years. |
| Certification and testing cost | Medium | Interrupting and standards tests raise development cost and time. |
| Complexity of smart products | Medium | Cybersecurity, interoperability and commissioning requirements can slow adoption. |
Standard products face intense price competition
MCBs and basic MCCBs are widely manufactured, especially in Asia, and many applications are highly price-sensitive. This limits pricing power and encourages global manufacturers to differentiate through brand, channel, approvals and accessories. Premium digital features can offset some pressure, but they are not economically justified in every residential or light-commercial circuit.
Long equipment life moderates replacement demand
Circuit breakers are safety-critical products designed for long service when properly applied and maintained. A large installed base therefore creates recurring replacement and retrofit business but not rapid annual turnover. Growth depends on new construction, capacity expansion, code-driven upgrades or digital modernization rather than frequent like-for-like replacement.
Smart functionality adds engineering and cybersecurity burden
Connected breakers require communications, firmware, system integration and cybersecurity. These features improve visibility but also increase commissioning complexity and create new lifecycle responsibilities for updates and compatibility. Customers with simple loads may continue to prefer conventional products if the operational value of connectivity does not justify additional cost.
Market Opportunities
AI-ready data centers
Data centers need high-reliability main and feeder protection with selective coordination, condition monitoring and cybersecurity. Advanced ACBs and MCCBs can capture higher value by integrating protection, metering and predictive maintenance into a single device.
Smart building retrofits
Commercial buildings increasingly seek energy data and remote management without fully replacing switchgear. Connected trip units, retrofit communication modules and digital breakers can create an upgrade market across an enormous installed base.
DC distribution and storage
Battery energy storage, EV charging and direct-current microgrids create demand for breakers designed for high-voltage DC interruption. Products certified for these applications can address a market where conventional AC protection is not sufficient.
Lifecycle services and predictive maintenance
Manufacturers can monetize installed breakers through condition assessment, retrofit kits, digital monitoring and replacement planning. This changes the business model from a one-time hardware sale toward a longer customer relationship tied to asset performance.
Supply Chain Analysis
Materials & subcomponents
Breaker manufacturing
Testing & certification
Panel / distribution channel
Upstream cost depends on copper, silver-bearing contact materials, engineered plastics, steel mechanisms and increasingly semiconductors used in electronic trip units. Commodity swings affect margins, but material substitution is constrained by safety and interruption performance. This gives scale advantages to manufacturers that can manage strategic sourcing while maintaining qualified material systems.
Manufacturing combines mechanical precision with electrical calibration. MCBs favor automated high-speed assembly, while MCCBs and ACBs require configurable trip units, accessories and communication modules. Platform design is therefore important: sharing frames and accessories across current ratings reduces inventory and supports panel builders that want consistent interfaces across an installation.
Testing and certification form a high-value barrier to entry. IEC 60947-2:2024 applies to circuit breakers up to 1,000 V AC or 1,500 V DC and defines performance requirements that must be validated through demanding tests. Suppliers also need regional approvals such as UL standards, so global expansion requires both engineering and certification investment.
Recent Developments
Report Scope & Segmentation
| Attribute | Coverage |
|---|---|
| Market | Low-voltage Circuit Breakers |
| Base year | 2025 |
| Estimated year | 2026 |
| Forecast year | 2034 |
| Forecast period | 2026–2034 |
| 2025 market size | USD 17,230.0 million |
| 2034 market size | USD 29,525.0 million |
| CAGR | 6.2% |
| By Type | Miniature Circuit Breaker (MCB), Moulded Case Circuit Breaker (MCCB), Air Circuit Breaker (ACB) |
| By Application | Manufacturing & Process Industry, Residential & Commercial, Transmission & Distribution, Power Generation, Others |
| Additional segmentation | By End User: Industrial Facilities, Commercial Buildings, Utility Providers, Residential Consumers; By Protection Type: Overload, Short Circuit, Earth Fault, Combination; By Technology: Conventional Electromechanical, Electronic Trip Unit, Smart/Digital |
| Regions | North America, Europe, Asia Pacific, South America, Middle East & Africa |
| Companies profiled | Schneider Electric, ABB, Eaton, Siemens, Mitsubishi Electric, General Electric, Hager, Fuji Electric, Hyundai, CHINT Electrics, Shanghai Renmin, Changshu Switchgear, Liangxin, DELIXI, S. Men Rin |
Frequently Asked Questions
What is the size of the Low-voltage Circuit Breakers Market?
The market is valued at USD 17,230.0 million in 2025 and is projected to reach USD 29,525.0 million by 2034. The published 2025 and 2033 size anchors imply a 6.2% CAGR for the 2026–2034 series. Growth is supported by electricity-demand expansion, industrial investment, data centers, renewable interconnection and digital breaker upgrades.
Which product type leads the market?
Moulded Case Circuit Breakers are the leading value segment because they serve a wide range of industrial and commercial feeder applications, offer adjustable protection and can integrate electronic trip units, metering and communications. Miniature Circuit Breakers lead unit volume, while Air Circuit Breakers capture high-value main-switchboard applications in larger facilities.
Which region is largest?
Asia Pacific is the largest regional market, led by China. The region combines massive electrical-equipment manufacturing with rapid industrialization, urban construction, renewable deployment and grid investment. China provides the largest single-country demand base, while India and Southeast Asia add fast-growing manufacturing and infrastructure projects.
Why are smart circuit breakers growing?
Smart breakers add sensing, event logging, communications, energy metering and predictive-maintenance functions to basic protection. These features help operators reduce downtime, identify overloads, monitor power quality and integrate electrical distribution into building or plant-management systems. The value proposition is strongest in data centers, factories, hospitals and other uptime-sensitive facilities.
What does IEC 60947-2 cover?
IEC 60947-2:2024 applies to low-voltage circuit breakers whose main contacts are connected to circuits not exceeding 1,000 V AC or 1,500 V DC, with additional provisions for certain fused and extended-voltage applications. Compliance with this and regional standards is a core market-access requirement for manufacturers and switchgear suppliers.
How do data centers affect market demand?
Data centers increase both the quantity and value of low-voltage protection because power distribution is dense and outages are costly. Main and feeder breakers need selective coordination, high interrupting capability, power monitoring and remote diagnostics. AI-driven facilities further increase load density, supporting premium ACB and MCCB demand.
What is the role of renewable energy?
Solar, wind, batteries and microgrids add new low-voltage distribution points and create more complex power flows. Breakers protect auxiliary systems, inverters, storage interfaces and facility distribution, while DC applications require specialized interruption capability. Renewable integration therefore expands both conventional and advanced protection opportunities.
What is the main market restraint?
The main commercial restraint is the combination of intense price competition in standard breakers and long replacement cycles for installed equipment. Basic MCBs are widely manufactured, which limits margins, while well-maintained breakers can remain in service for years. Suppliers therefore seek growth through new construction, digital upgrades and premium applications.
What is the 2026 estimated market size?
Using the published 2025 market size of USD 17.23 billion and 2033 forecast of USD 27.81 billion, the anchor-consistent 2026 estimate is USD 18,292.6 million. The source page also prints USD 18.45 billion for 2026, but the constant-growth series used here is derived directly from the two size anchors.
Which companies lead the competitive landscape?
The market is led by global electrical-equipment groups including Schneider Electric, ABB, Eaton, Siemens and Mitsubishi Electric, supported by strong regional manufacturers such as CHINT, Fuji Electric, Hyundai, Shanghai Renmin, Liangxin and DELIXI. Competitive strength depends on approvals, channel access, switchgear integration, digital trip units and lifecycle service.
Research Sources & Evidence Base
View research sources used for this overview.
- International Electrotechnical Commission. IEC 60947-2:2024 – Low-voltage switchgear and controlgear, Part 2: Circuit-breakers, scope and current international standard.
- International Energy Agency. Electricity 2025 – Demand, global electricity-demand growth and China contribution.
- ABB. ABB Unveils SACE Emax 3 in the US, September 2025 smart air circuit breaker launch.
- ABB. ABB Malaysia Unveils SACE Emax 3, February 2026 regional launch and market direction.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF