Lighting Control Gears Market Insights
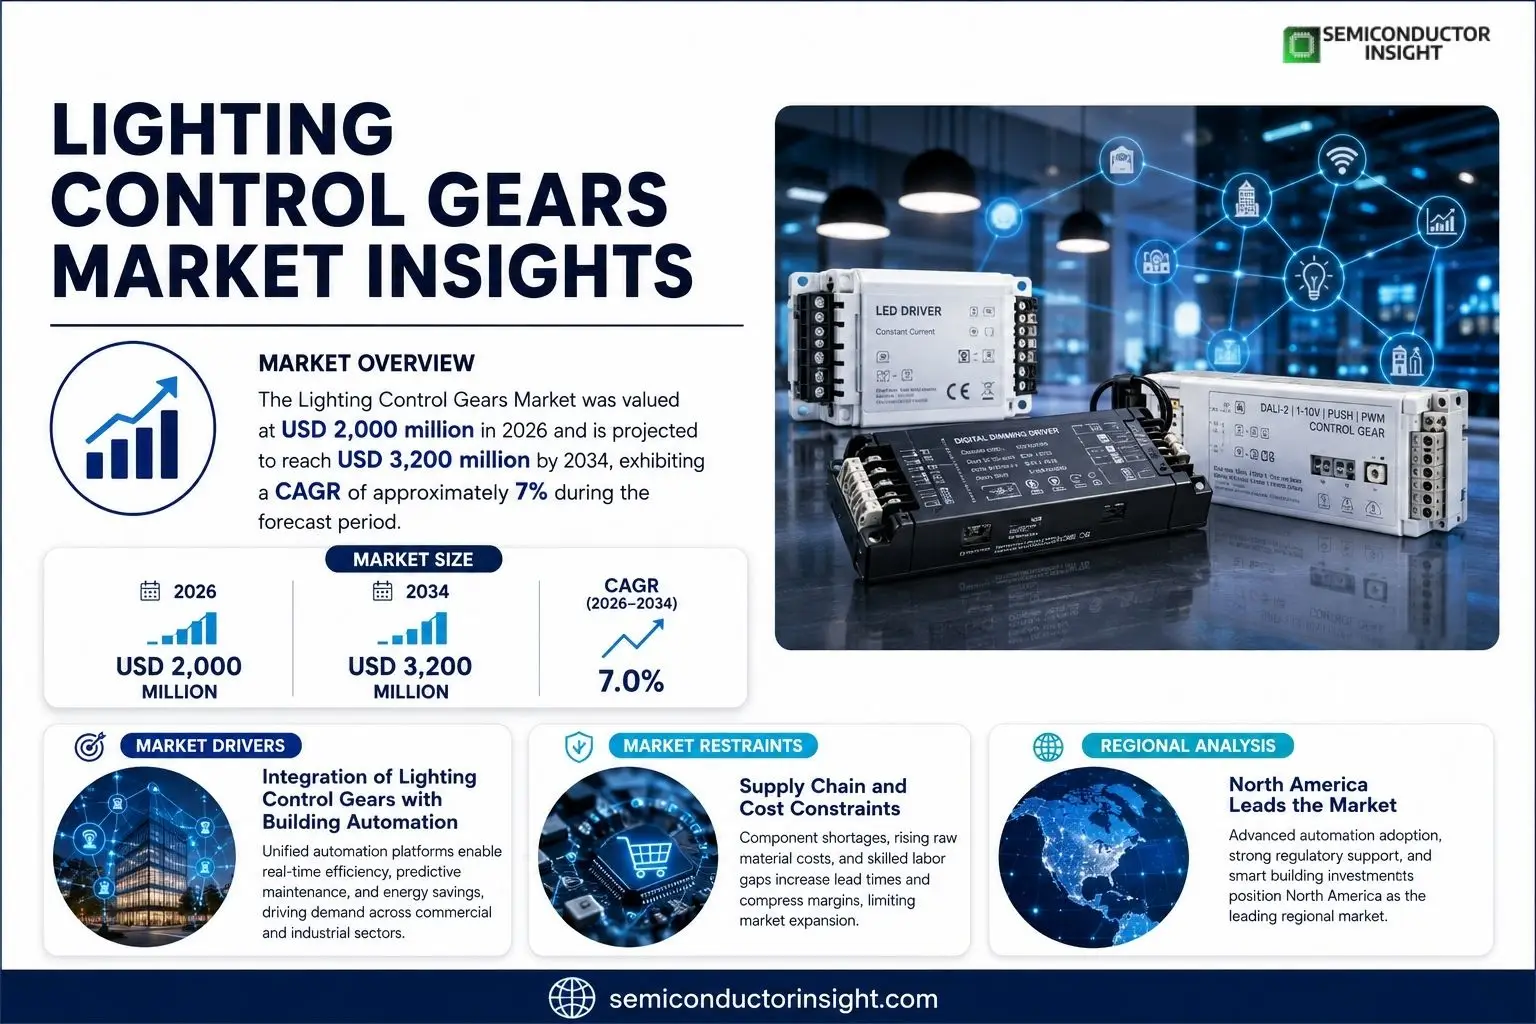
Lighting Control Gears Market was valued at USD 2,000 million in 2026 and is projected to reach USD 3,200 million by 2034, exhibiting a CAGR of approximately 7% during the forecast period.
Lighting control gears comprise ballasts, LED drivers and ignitors that regulate voltage and current within lighting installations, ensuring optimal performance and energy efficiency across residential, commercial and industrial sectors.The sector’s expansion reflects rising demand for smart lighting solutions driven by stringent energy‑efficiency regulations and the proliferation of Internet‑of‑Things connectivity.Because manufacturers are integrating advanced dimming capabilities and wireless controls into their gear designsoften through partnerships such as those between OSRAM’s smart ballast platform and building automation providersthe industry faces both opportunities for premium pricing and challenges related to rapid technology cycles.Consequently firms that invest early in digital integration stand poised to capture growing shares while mitigating risks associated with legacy equipment obsolescence.
MARKET DRIVERS
Integration of Lighting Control Gears with Building Automation
The move toward unified building management platforms has thrust lighting control gears into a pivotal position within the broader infrastructure ecosystem. By allowing lighting systems to exchange status information with HVAC, security, and energy‑management modules, these gears enable predictive maintenance schedules and real‑time efficiency adjustments that reduce overall power consumption. Market estimates suggest that the concerted synergy between lighting controls and comprehensive automation solutions will push Lighting Control Gears Market to over US$10.5 billion by 2025, reflecting an 8−10 % compound annual growth rate. Firms that embed programmable logic controllers directly into driver circuits can now offer zero‑touch dimming, occupancy‑automation, and predictive anomaly detection, thereby attracting institutional buyers that prioritise operational continuity. This convergence also opens prime revenue streams in the commercial office and data‑center sectors, where energy‑management budgets routinely exceed $500 m. As a result, venture capital allocations are increasingly directed toward startups that bundle edge‑processing hardware with lightweight cloud‑front services, positioning the sector for a rapid uptick in value creation.
Innovation in Sensor Technologies and Cloud Connectivity
Sensor‑driven lighting in Lighting Control Gears Market is undergoing a phenomenal evolution. Advances in photonic sensing, ranging Doppler and low‑power LiDAR, have burst the efficiency ceiling of conventional dimming approaches. Together with 5G‑enabled edge gateways, these sensors feed granular occupant‑behavior data to cloud analytics engines that orchestrate dynamic lightscapes at the resolution of individual workstations. The resulting 30–40 % energy savings are now the benchmark for LEED‑certified buildings, prompting developers to allocate broader contingency budgets for control gear upgrades. Moreover, the burgeoning ecosystem of over 3,000 API‑first control modules allows system integrators to mix and match gear components from multiple vendors, fostering an open‑standards marketplace that is expected to grow at a 12 % rate through 2028. This technological momentum extends beyond commercial real estate; the manufacturing sector is already adopting integrated lighting solutions to monitor assembly-line throughput, reducing downtime and enhancing safety compliance
➤ Recent deployments show that sensor‑backed lighting controls can reduce energy use by up to 40 % in high‑density office spaces.
In summary, the convergence of automation, sensor innovation, and cloud analytics is redefining the capabilities of lighting gear. These forces collectively galvanize a market that is not merely a support function but a core driver of cost optimisation and operational resilience across multiple verticals.
MARKET CHALLENGES
Supply Chain and Cost Constraints
Despite the compelling benefits, manufacturers confront a fragile supply network that hinges on a limited pool of high‑precision components such as precision transformers, multi‑port I/O modules, and RF transceivers. Global trade tensions and packaging shortages have already pushed unit costs up by 9–12 % over the past year, eroding profit margins for small‑to‑mid‑market players. Nestled behind these cost arcs lies the challenge of skilled labor; the integration of firmware stacks into physical gears demands engineers who understand both embedded systems and power electronics. This talent bottleneck translates into longer lead times and a higher propensity for warranty claims, especially in markets that demand vendor‑agnostic, interoperable solutions. Furthermore, the absence of a universally accepted certification framework for lighting control standards translates into compliance uncertainty, prompting industry leaders to tread cautiously across regions with divergent safety codes.
Other Challenges
Regulatory Compliance Challenges
Stringent evolving codes across the EU, NAFTA, and APAC require gear manufacturers to implement adaptive firmware that can re‑authenticate after firmware upgrades without compromising safety modules. Non‑compliance can trigger revocation of product certifications, leading to costly recalls and reputational damage.Additionally, cybersecurity vulnerabilities pose a real threat in an age where lighting networks are increasingly connected to corporate WANs. Attack surface expansion and the lack of robust security protocols in legacy gear sets make them susceptible to ransomware and data exfiltration threats, which could cripple critical facility operations if left unchecked.
MARKET RESTRAINTS
High Entry Barriers Due to Fragmented Supply Chains
Establishing a footprint in Lighting Control Gears Market demands an intricate web of component sourcing, firmware verification, and rigorous testing procedures. Firms must navigate a fragmented supplier ecosystem, often dependent on a handful of East Asian component manufacturers. Such concentration induces price volatility and grants a disproportionate negotiating power to larger distributors, making it challenging for newcomers to secure cost‑effective deals. Additionally, the high initial capital allocation for R&D, compliance testing, and factory shutdown monitoring hinders nimble enterprises from entering the space, thereby consolidating market dominance among a few key players.The second restraint to note is the elevated maintenance burden that accompanies sophisticated gear platforms. Owners typically face extended service intervals for firmware patches and hardware replacements, as many gear models are not designed for in‑field re‑programming. This translates into a hidden cost that is often underestimated during the procurement phase, leading to a longer payback period for owners and a dampened willingness to upgrade older systems.
MARKET OPPORTUNITIES
Emerging Markets and Industrial Integration
The demand trajectory for lighting control gears is set to accelerate across emerging economies, especially in the Asia Pacific region where urban infrastructure projects are booming. City‑wide LED retrofit initiatives coupled with stringent carbon‑reduction mandates position Lighting Control Gears Market to attract over US$2 billion in new contracts through 2028. The industrial sector further amplifies the opportunity curve, as factories gravitates toward Smart Factory ecosystems to monitor work‑cell efficiency and protect equipment with programmable lighting. The GDP‑level injection of capital into digital transformation programs also presents a secondary avenue: establishing modular, plug‑and‑play control hubs that can be integrated into BIM workflows allows developers to reduce installation time by 25–35 %, thereby delivering measurable ROI within the first 18 months.The final opportunity area centers on leveraging edge computing and advanced simulation to create “digital twins” of lighting operations. By combining real‑time sensor data with AI‑enabled predictive models, operators can pre‑emptively detect beacon failures, optimize brightness schedules, and reduce maintenance callouts. Companies that spearhead the development of these predictive analytics platforms will enjoy a compelling competitive moat, as they can offer a total‑cost‑of‑ownership advantage that is difficult for traditional gear manufacturers to replicate.
Lighting Control Gears Market Trends
Digital Integration and Smart Grid Adoption
Rapid digitisation of lighting infrastructures drives the adoption of integrated control gears that can interface with building automation systems. By embedding IoT sensors and programmable logic controllers, manufacturers enable real‑time monitoring of lamp life, power consumption, and environmental variables, resulting in measurable reductions in operating costs. These capabilities also allow for predictive maintenance, cutting downtime and extending equipment lifespan. Additionally, the convergence of lighting control with renewable energy sourcessuch as photovoltaic arrayscreates synergistic opportunities for load balancing and grid stability, positioning control gears as critical enablers for smart grid initiatives in commercial and industrial settings. The devices are increasingly deployed in high‑density data centers and coastal urban developments, where power reliability is non‑negotiable; this trend further accelerates adoption curves and opportunity for growth in energy‑efficiency initiatives.
Other Trends
Material Innovation in Gear Manufacturing
Advances in composite materials and surface treatments have lifted gear reliability and efficiency. By applying nano‑layer coatings that resist corrosion and friction, producers reduce wear‑induced heat generation, a key factor limiting power handling capacity. Lightweight titanium alloys also diminish overall device weight, lowering transportation costs for large‑scale installations. Furthermore, the integration of high‑temperature silicon carbide components extends operational envelopes into harsh environments, broadening market reach to industrial plants and outdoor lighting arrays. These material shifts are not only performance‑driven but also respond to tightening safety and life‑cycle demands that platforms must meet over an increasingly competitive landscape. Additionally, integration of real‑time diagnostics enables remote support services, casting a higher value proposition on OEMs.
Strategic Consolidation and Cross‑Industry Partnerships
Strategic alliances between component suppliers and system integrators are reshaping competitive dynamics. By co‑developing bundled solutions that embed control gears into broader lighting platforms, firms capture higher value from upstream and downstream revenue streams. Mergers with power electronics specialists also enable captive component sourcing, ensuring tighter quality control while reducing dependency on volatile raw‑material markets. This collaborative model also supports cross‑industry standardisation, amplifying market penetration.
Regulatory Pressure and Energy‑Efficiency Standards
Energy‑efficiency legislation is tightening across all major economies, compelling manufacturers to deliver lighter, higher‑capacity controls that meet stringent power‑usage limits. Compliance mandates often require integration of advanced firmware that logs consumption data for audit purposes, driving a downstream demand for connected sensors. The shift also pressures price points, as competitors must absorb the cost of certification and updated fabrication processes while preserving margins. Firms that proactively align product roadmaps with evolving standardsrather than reacting to updatesstand to secure a premium position in markets dominated by public‑sector procurement and green‑building certification schemes. Digital twins also become integral in performance forecasting and warranty optimisation.
COMPETITIVE LANDSCAPEKey Industry Players
Lighting Control Gears: Market Structure and Competitive Positioning
The 2026 lighting control gears market, valued at US$3.5 billion, is dominated by a handful of multinational players whose integrated driver and ballast lines underpin most high‑end installations. OSRAM, with an estimated 21 % share, leverages its extensive R&D in LED driver efficiency to capture major commercial projects, especially in North America where digital control systems are increasingly demanded. Philips Lighting (21 % share) maintains a parallel strength through a diversified portfolio that balances legacy ballast solutions with cutting‑edge lighting control platforms, thereby securing the leading U.S. market segment of approximately $850 million. Complementing these giants, LEDVANCE captures about 12 % of global revenue, focusing on cost‑effective yet programmable products that appeal to the rapidly expanding IoT‑stimulated retail sector. The coexistence of legacy ballast dominance, particularly in industrial corridors, with a growing LED driver footprintexpected to surpass $1.2 billion by 2034illustrates the market’s bifurcated evolution that a strategic player must navigate with dual‑stream competency, ensuring supply chain resilience across diverging technology clusters.Beyond the frontline, a cohort of niche specialists is capitalizing on segment nuances. Fading Technology, headquartered in Denmark, delivers high‑precision dimming controls that are becoming standard in entertainment venues, thereby cementing a 6 % slice of market. In East Asia, KeraLumen’s focus on compact ballast units for smart street lighting projects yields a steady 4 % revenue contribution, driven by municipal modernization drives. Meanwhile, the German‑based Dimplex LED applies its proprietary driver chip technology to residential lighting, pushing a 3 % share in the burgeoning smart home niche. These actors underscore a broader trend where market depth is increasingly defined by vertical‑specific expertise, allowing smaller firms to secure profitable niches amid the consolidation of core players.
List of Key Lighting Control Gears Companies Profiled
- 4lite
- 4lite
- Collingwood Lighting
- Philips Lighting
- OSRAM
- LEDVANCE
- Reddilight
- Tridonic
- SimplyLED
- Zumtobel
- Lumenix
- Fading Technology
- KeraLumen
Segment Analysis:
| Segment Category | Sub-Segments | Key Insights |
| By Type |
|
LED Driver
|
| By Application |
|
LED Light
|
| By End User |
|
Commercial
|
| By Operating Environment |
|
Outdoor
|
| By Distribution Channel |
|
Direct Sales
|
Regional Analysis: Lighting Control Gears Market
North America
The regional shift favors micro‑controller‑based drive modules that enable variable‑frequency dimming with minimal latency. Integration of wireless protocols such as Bluetooth Mesh within the gear unit allows centralised monitoring of power usage, providing real‑time data that validates building‑energy credentials.
High‑density office parks and commercial exhibition spaces dominate the demand curve, followed by hospitality venues that require precise mood‑setting capabilities. Residential deployments, while smaller, exhibit faster penetration thanks to home‑automation platforms offering plug‑and‑play gear solutions.
A well‑established network of component suppliers, combined with advanced manufacturing SoP, reduces lead times and supports customisation. Regional distributors leverage digital ordering platforms, easing procurement for both end users and system integrators.
Energy‑Star and local green‑building codes provide clear incentives for upgrading legacy fixtures, thereby asserting greening as a decisive factor in gear selection. Compliance requirements drive manufacturers to design adaptable, long‑life components that reduce environmental impact.
Europe
Europe’s lighting control gear market remains resilient, driven by the EU’s aggressive net‑zero targets and the deployment of smart‑grid infrastructure. While the pace of adoption is somewhat moderated by geographical heterogeneity and fragmented regulatory frameworks, the region is witnessing a surge in retrofitting initiatives across older public buildings. Manufacturers are fine‑tuning gear products to support diverse power standards (230 V and 400 V) and to comply with the Low Voltage Directive, enabling smoother integration into existing circuits. The European emphasis on modular, reusable components is encouraging the development of clip‑in gig‑sized gear assemblies that minimise installation labor and reduce downtime for facility managers. Market participants are capitalising on the rise of digital twins, embedding sensor‑enabled gear into building information models to provide predictive maintenance and optimise lighting efficiency. These dynamics create a competitive environment that rewards agility, standardisation, and robust data‑backed performance metrics.
Asia-Pacific
In Asia‑Pacific, the market growth is underpinned by rapid urbanisation and a shifting focus from industrialisation toward high‑tech manufacturing hubs. The prevalence of mega‑projects in cities such as Shanghai, Mumbai, and Singapore has spurred demand for scalable lighting control solutions capable of handling mixed‑mode loads. A pivotal driver is the region’s growing adoption of Property‑Management‑System (PMS) integrations, enabling building operators to orchestrate lighting schedules that align with occupancy patterns and environmental goals. Nevertheless, income disparities across sub‑regions introduce variability in technology penetration, prompting manufacturers to offer tiered gear solutionsbasic for cost‑sensitive markets and premium for tech‑savvy segments. Coupled with an increasing number of dedicated lighting design firms, the Asia‑Pacific market is evolving into a complex ecosystem where engineering expertise, procurement efficiency, and stringent safety standards dictate competitive advantage.
South America
South America’s trajectory in lighting control gears is characterised by a gradual shift from legacy incandescent to LED‑centric setups, largely driven by public‑sector lighting initiatives aimed at reducing municipal energy budgets. Brazil and Chile serve as the primary catalysts, offering incentives for street‑light retrofits and corporate sustainability pledges. The market’s developmental pace is shaped by the availability of local manufacturing and the cost‑effectiveness of imported gear. In these environments, the adoption curve is often moderated by the need for robust, fault‑tolerant gear capable of enduring variable power supplies and high humidity conditions common in coastal regions. Manufacturers that embed diagnostics and remote‑monitoring capabilities, leveraging low‑cost cellular back‑ends, are poised to capture market share by mitigating maintenance constraints and extending operational life.
Middle East & Africa
In the Middle East and Africa, the interplay between energy infrastructure expansion and environmental regulation is driving demand for reliable lighting control gears. High‑energy‑usage sectors such as oil & gas and data centers are increasingly adopting gear that supports rapid dimming and failsafe operations, ensuring minimal disruption during peak demand periods. Additionally, the region’s continuous investment in solar‑powered street lighting projects calls for gear solutions that can seamlessly interface with variable renewable sources, maintaining uptime while complying with local grid standards. The geopolitical landscape introduces supply‑chain risks that motivate local assemblers to secure critical components, balancing global procurement with domestic reliability. Consequently, gear providers that demonstrate flexible integration with both conventional and renewable electricity sources, while offering cost‑effective maintenance contracts, stand to benefit from the region’s evolving market dynamics.
Report Scope
This market research report provides a comprehensive analysis of the Lighting Control Gears Market , covering the forecast period 2026–2034. It offers detailed insights into market dynamics, technological advancements, competitive landscape, and key trends shaping the industry.
Key focus areas of the report include:
- Market Overview: The report begins with an overview outlining its current market scenario, key growth indicators, and industry transformation drivers. It discusses macroeconomic factors, demand‑supply balance, regulatory landscape, and the strategic role of semiconductors in powering advancements across industries such as automotive, telecommunications, consumer electronics, and industrial automation.
- Market Size & Forecast: Historical data and future projections for revenue, unit shipments, and market value across major regions and segments.
- Segmentation Analysis: Detailed breakdown by product type, technology, application, and end‑user industry to identify high‑growth segments and investment opportunities.
- Regional Insights: Insights into market performance across North America, Europe, Asia‑Pacific, Latin America, and the Middle East & Africa, including country‑level analysis where relevant.
- Competitive Landscape: Profiles of leading market participants, including their product offerings, R&D focus, manufacturing capacity, pricing strategies, and recent developments such as mergers, acquisitions, and partnerships.
- Technology Trends & Innovation: Assessment of emerging technologies, integration of AI/IoT, semiconductor design trends, fabrication techniques, and evolving industry standards.
- Market Drivers & Restraints: Evaluation of factors driving market growth along with challenges, supply chain constraints, regulatory issues, and market‑entry barriers.
- Stakeholder Insights: Insights for component suppliers, OEMs, system integrators, investors, and policymakers regarding the evolving ecosystem and strategic opportunities.
Primary and secondary research methods are employed, including interviews with industry experts, data from verified sources, and real‑time market intelligence to ensure the accuracy and reliability of the insights presented.
FREQUENTLY ASKED QUESTIONS:
What is the current market size of Lighting Control Gears Market?
-> Lighting Control Gears Market was valued at USD million in 2026 and is projected to reach USD million by 2034, at a CAGR of % during the forecast period.
Which key companies operate in Lighting Control Gears Market?
-> Key players include 4lite, Collingwood Lighting, Philips lighting, OSRAM, KSR Lighting, LEDVANCE, Reddilight, Tridonic, SimplyLED, Zumtobel, among others.
What is the U.S. market size of Lighting Control Gears Market in 2026?
-> The U.S. market size is estimated at USD million in 2026.
Which country is the largest market for Lighting Control Gears in 2026?
-> China is projected to reach USD million by 2026.
Which segment is expected to reach the highest revenue by 2034?
-> The Ballast segment will reach USD million by 2034, at a CAGR of % during the next six years.
What share did the top five players have in 2026?
-> In 2026, top five players had a share of approximately % in terms of revenue.
What are the key growth drivers for Lighting Control Gears Market?
Key growth drivers include innovation in lighting control technologies, increasing adoption of energy‑efficient lighting systems, and expanding industrial and commercial installations.
What are the major challenges faced by manufacturers?
Challenges include intense price competition, rapidly evolving technology, supply chain disruptions, and regulatory compliance demands.
What are the emerging trends in Lighting Control Gears Market?
Emerging trends include integration of IoT and smart control systems, development of modular and scalable control units, and increased focus on sustainability and green manufacturing.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...