Global SATA Solid-state Drives Market Research Report 2026-2034
Electronic Components

Global SATA Solid-state Drives Market Research Report 2026-2034

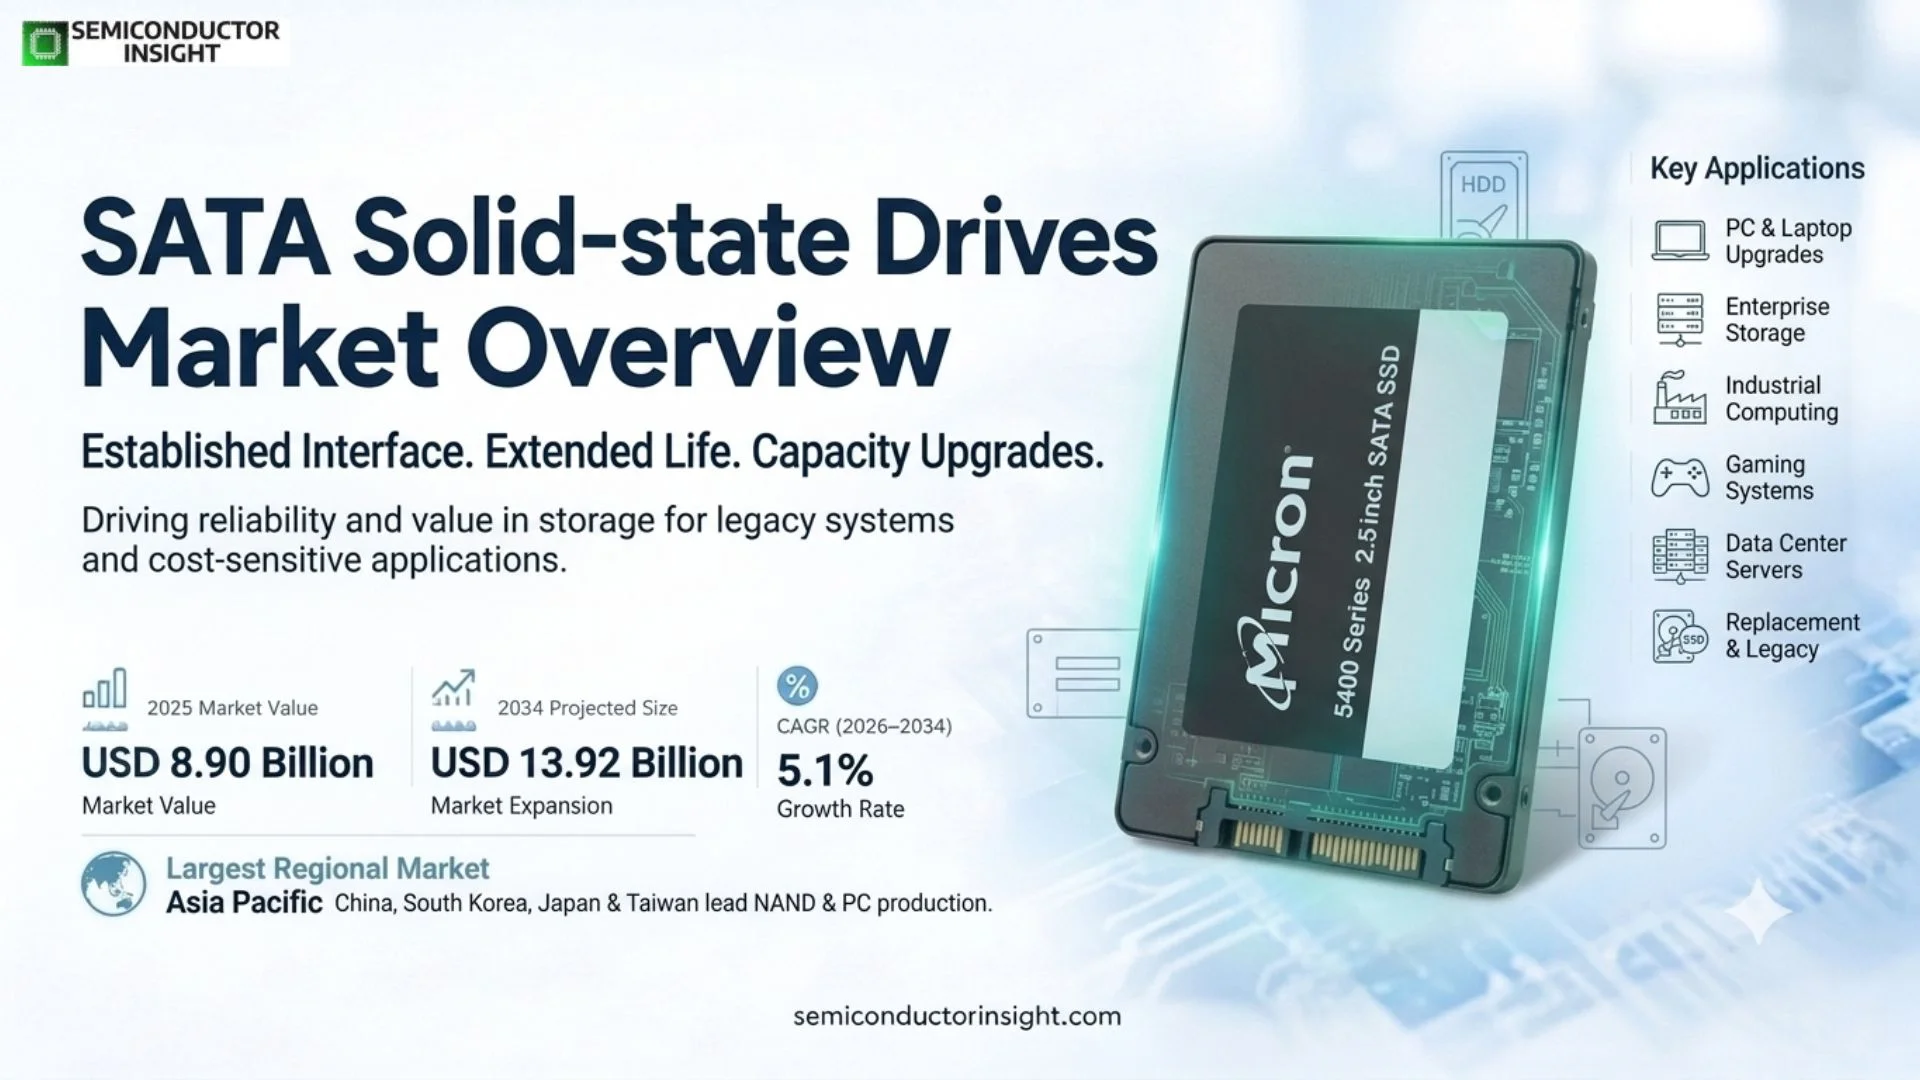
SATA Solid-state Drives Market is estimated at USD 9.35 billion in 2026. The market is projected to reach USD 13.92 billion by 2034, representing a CAGR of 5.1% during 2026–2034. Asia Pacific is the largest regional market because China, South Korea, Japan and Taiwan combine NAND manufacturing, PC production and broad consumer or enterprise storage demand.

REPORT TYPE Market Research
UPDATED September 2026
REPORT ID e7ecfc8f9108
DELIVERY Digital
Quick Delivery Digital report access
Secure Payment Protected checkout
Analyst Support Scope and research assistance

Key Statistics

2025 Market Size
USD 8.90 billion
2026 Estimated Market Size
USD 9.35 billion
2034 Projected Market Size
USD 13.92 billion
CAGR (2026–2034)
5.1%

Key Takeaways

  • Market size and growth: the market is estimated at USD 9.35 billion in 2026 and is projected to reach USD 13.92 billion by 2034, representing a 5.1% CAGR during 2026–2034.
  • Below 1TB drives retain the largest unit share in consumer upgrades and cost-sensitive PCs, while 1TB-3TB capacities capture rising value as NAND cost per bit declines.
  • Online sales are an important route to market for consumer SATA SSDs because upgrades are easy to compare and install, while enterprise products rely more heavily on OEM and channel relationships.
  • Asia Pacific leads through NAND and PC manufacturing, but North America remains a major enterprise and aftermarket market with large installed bases of SATA servers and desktop systems.
  • SATA remains relevant despite NVMe growth: Micron’s 5400 data-center SATA SSD supports capacities up to 7.68TB and targets existing SATA server sockets where compatibility, qualification and predictable latency matter more than peak interface speed.

SATA Solid-state Drives Market Overview

SATA Solid-state Drives market was valued at USD 8.90 billion in 2025 and is estimated at USD 9.35 billion in 2026. The market is projected to reach USD 13.92 billion by 2034, representing a CAGR of 5.1% during 2026–2034. Asia Pacific is the largest regional market because China, South Korea, Japan and Taiwan combine NAND manufacturing, PC production and broad consumer or enterprise storage demand.

Base year: 2025 · Estimated year: 2026 · Forecast period: 2026–2034 · Values in USD million unless otherwise stated

SATA solid-state drives use NAND flash memory behind the Serial ATA interface and provide significantly lower latency, higher shock resistance and lower power consumption than hard-disk drives. The category includes 2.5-inch, M.2 SATA and legacy mSATA products sold into consumer upgrades, PCs, industrial systems and data centers. Although NVMe has become the preferred interface for performance-sensitive new platforms, SATA remains deeply installed and economically attractive where compatibility, mature qualification and moderate bandwidth are sufficient.

The market increasingly behaves as a replacement and capacity-upgrade segment rather than a leading-edge interface category. Consumers use SATA SSDs to extend the life of desktops and notebooks, while enterprises replace aging SATA HDDs or earlier-generation SSDs without redesigning server platforms. Micron’s 5400 demonstrates the continuing enterprise use case with capacities from 240GB to 7.68TB and a design intended to saturate typical SATA server workloads while preserving compatibility with established infrastructure.

NAND cost, endurance and controller quality determine competitive positioning. As flash prices fall, buyers move toward higher capacities, but price competition remains intense because SATA performance is constrained by the interface and therefore difficult to differentiate on peak throughput. Vendors compete through reliability, warranty, firmware, power-loss protection, endurance ratings and channel reach. The strongest long-term niche is installed-base replacement where switching to NVMe would require a platform redesign.

Segment Analysis: By Type

By type, the market is segmented by capacity into below 1TB, 1TB-3TB and above 3TB. Below 1TB remains important for low-cost PC upgrades and embedded systems, while 1TB-3TB is becoming the mainstream value segment as consumers and commercial users store more local data. Above 3TB is a smaller but higher-value category concentrated in enterprise, workstation, surveillance and capacity-sensitive applications where SATA compatibility is retained.

Type Technical / commercial role Market position
Below 1TB Entry-level and mainstream consumer, embedded and legacy-system upgrades. Largest unit segment; highly price competitive.
1TB-3TB Mainstream growth capacity for PCs, workstations and commercial systems. Strong value growth as NAND cost per bit declines.
Above 3TB High-capacity enterprise, workstation and specialized storage. Smaller units but higher revenue per drive.

Segment Analysis: By Application

By application, the market is segmented into online sales and offline sales. Online channels are important for consumer and small-business upgrades because capacity, price and brand can be compared easily and installation is standardized. Offline channels remain relevant for system integrators, enterprise procurement and markets where local retail or distributor support is important. Large enterprise deployments are frequently purchased through OEM or channel agreements rather than purely transactional e-commerce.

Application Demand characteristics
Online Sales Strong consumer-upgrade channel with transparent pricing and broad SKU availability.
Offline Sales Important for OEM, enterprise, retail and distributor-led procurement where support or qualification matters.

Segment Analysis: By End User

End-user demand spans consumer PCs and laptops, enterprise data centers and industrial or embedded systems. Consumer upgrades generate large unit volumes because SATA is compatible with many existing machines. Enterprise users value qualified drives that can replace older SATA HDDs or SSDs without changing server architecture. Industrial and embedded customers often prioritize long product availability, power-fail behavior and firmware stability, creating higher-value niches despite lower unit volumes.

End User Demand logic
Consumer PCs & Laptops Largest upgrade market for extending device life and increasing local storage.
Enterprise & Data Center Replacement and moderate-performance storage in installed SATA infrastructure.
Industrial & Embedded Long-lifecycle systems requiring stable firmware, endurance and predictable availability.

Segment Analysis: By Form Factor

Form factor influences where SATA SSDs remain competitive. The 2.5-inch format dominates server, desktop and notebook upgrades because the physical and electrical ecosystem is deeply installed. M.2 SATA serves thinner systems that use the M.2 mechanical format but do not support PCIe NVMe, while mSATA and other legacy formats remain in older embedded or industrial platforms. Long-tail compatibility is therefore a central reason the market persists despite interface substitution.

Form Factor Market role
2.5-inch Largest installed base across servers, desktops, notebooks and industrial equipment.
M.2 SATA Compact client and embedded systems that use SATA signaling in the M.2 form factor.
mSATA & Others Legacy embedded and industrial platforms requiring continued replacement support.

Global SATA Solid-state Drives Market Size

Regional Analysis

Asia Pacific is the largest regional market because it contains major NAND manufacturers, PC assembly ecosystems and large consumer-electronics markets. North America is a major enterprise and aftermarket region, while Europe has substantial PC replacement and industrial demand. Emerging regions support SATA through cost-sensitive upgrades because it offers a straightforward performance improvement for systems that cannot justify complete platform replacement.

Regional demand reflects both storage manufacturing and the installed base of SATA-capable systems. South Korea, Japan and China contribute NAND, controller and drive production. North America has large data-center and commercial fleets that continue to replace older SATA devices. Europe’s industrial and enterprise systems value long qualification life, while South America and Middle East & Africa use SATA SSDs extensively in aftermarket upgrades where affordable performance and universal compatibility are more important than maximum throughput.

Region Position Growth outlook Demand profile Supplier-selection factor
Asia Pacific Largest Moderate-High NAND, PCs, consumer electronics Scale and price
North America Major Moderate Enterprise and aftermarket Reliability and compatibility
Europe Established Moderate PC replacement and industrial Lifecycle and warranty
South America Growth Moderate Consumer upgrades Affordability
Middle East & Africa Growth Moderate PC and server upgrades Price and availability
Asia PacificLARGEST

What defines demand in Asia Pacific?

Asia Pacific leads because it combines major NAND and SSD suppliers with the world’s largest PC and electronics manufacturing base. South Korea contributes Samsung, China has large consumer and aftermarket demand, and Japan remains important through storage and electronics suppliers. Regional pricing is highly competitive because manufacturers and distributors operate close to production, making SATA SSDs a popular upgrade path for mainstream PCs and commercial systems.

PositionLargest
Demand baseNAND + PCs
Commercial focusScale and price
Key hubsChina, Korea, Japan
Country / subregion Role Demand logic
China Large consumer market PC upgrades and local brands create high unit demand.
South Korea NAND supplier hub Samsung and memory manufacturing support the ecosystem.
Japan Storage / enterprise Established storage suppliers and enterprise customers sustain demand.

Regional demand is shaped by the local concentration of customers, supplier service capability and the availability of qualified technical support. Companies that can shorten lead times, maintain local application engineering and support product changes during the customer lifecycle are better positioned to convert market growth into durable share. These factors matter most in technically demanding markets where a design change can affect validation, uptime or manufacturing yield.

North AmericaMAJOR

What defines demand in North America?

North America is a major market because enterprises and consumers operate a large installed base of SATA servers, desktops and laptops. The United States also has significant data-center demand for qualified SATA SSDs where applications do not require NVMe bandwidth. Reliability, warranty and firmware support carry more weight than the lowest retail price in enterprise programs, while consumers remain highly price sensitive in aftermarket channels.

PositionMajor
Demand baseEnterprise + aftermarket
Commercial focusReliability
Primary hubUnited States
Country / subregion Role Demand logic
United States Primary market Large PC and data-center installed base supports replacement demand.
Canada Consumer / enterprise Similar upgrade dynamics at smaller scale.
Mexico PC manufacturing Assembly and consumer demand support regional distribution.

Regional demand is shaped by the local concentration of customers, supplier service capability and the availability of qualified technical support. Companies that can shorten lead times, maintain local application engineering and support product changes during the customer lifecycle are better positioned to convert market growth into durable share. These factors matter most in technically demanding markets where a design change can affect validation, uptime or manufacturing yield.

EuropeESTABLISHED

What defines demand in Europe?

Europe is an established market where SATA SSDs remain common in PC upgrades, industrial systems and enterprise infrastructure. Germany and other industrial economies value long-life products and firmware stability, while retail markets support consumer upgrades. Environmental and lifecycle considerations can also favor SSD replacement over full device replacement when older systems remain otherwise serviceable.

PositionEstablished
Demand basePC + industrial
Commercial focusLifecycle
Key hubsGermany, UK, France
Country / subregion Role Demand logic
Germany Industrial / enterprise Long-life systems support qualified SATA replacements.
United Kingdom Consumer / business Aftermarket upgrades sustain demand.
France Enterprise / consumer Mature PC base supports replacement cycles.

Regional demand is shaped by the local concentration of customers, supplier service capability and the availability of qualified technical support. Companies that can shorten lead times, maintain local application engineering and support product changes during the customer lifecycle are better positioned to convert market growth into durable share. These factors matter most in technically demanding markets where a design change can affect validation, uptime or manufacturing yield.

South AmericaGROWTH

What defines demand in South America?

South America has strong upgrade-driven demand because SATA SSDs offer a relatively low-cost way to improve older desktops and notebooks without replacing the full system. Brazil is the largest market, while other countries depend heavily on imported drives. Currency and retail pricing influence capacity selection, making sub-1TB and 1TB products especially important. Online channels are increasingly influential for brand and price comparison.

PositionGrowth market
Demand baseConsumer upgrades
Commercial focusAffordability
Primary hubBrazil
Country / subregion Role Demand logic
Brazil Primary market Large PC installed base supports aftermarket demand.
Argentina Upgrade market Price sensitivity favors lower-capacity drives.
Chile / Colombia Retail growth Online and retail channels support adoption.

Regional demand is shaped by the local concentration of customers, supplier service capability and the availability of qualified technical support. Companies that can shorten lead times, maintain local application engineering and support product changes during the customer lifecycle are better positioned to convert market growth into durable share. These factors matter most in technically demanding markets where a design change can affect validation, uptime or manufacturing yield.

Middle East & AfricaGROWTH

What defines demand in Middle East & Africa?

Middle East & Africa demand is driven by PC upgrades, small-business servers and replacement of aging hard drives. Gulf countries purchase higher-capacity products and enterprise systems, while African markets are more price sensitive. SATA’s compatibility is valuable because it allows storage upgrades without changing motherboards or server platforms, making it attractive in regions where extending hardware life is economically important.

PositionGrowth market
Demand basePC + server upgrades
Commercial focusPrice and availability
Key hubsGulf, South Africa
Country / subregion Role Demand logic
Gulf states Commercial / enterprise Higher-capacity systems support premium demand.
South Africa Regional PC market Aftermarket upgrades create steady demand.
Rest of Africa Cost-sensitive SATA provides an accessible HDD replacement path.

Regional demand is shaped by the local concentration of customers, supplier service capability and the availability of qualified technical support. Companies that can shorten lead times, maintain local application engineering and support product changes during the customer lifecycle are better positioned to convert market growth into durable share. These factors matter most in technically demanding markets where a design change can affect validation, uptime or manufacturing yield.

Competitive Landscape

Competition in the SATA Solid-state Drives market is shaped by technology performance, customer qualification, application engineering and continuity of supply. Leading companies use product breadth and global support to win large programs, while specialist suppliers can defend attractive niches through deeper technical performance in specific applications. As the market expands, customers increasingly evaluate total system value and lifecycle support rather than relying only on initial component price.

The leading suppliers compete through a combination of proprietary technology, manufacturing scale and customer relationships. In the SATA Solid-state Drives market, design wins can remain in place for several product generations because switching suppliers often requires requalification, software changes or manufacturing adjustments. This creates durable revenue positions for vendors that deliver reliable performance and responsive technical support.

Regional suppliers can still gain share where local availability, cost and fast engineering response matter. Their strongest opportunities are generally in standardized or mature applications, while the highest-performance segments remain concentrated among companies with deeper intellectual property, process control and qualification histories. This creates a market structure with both global platform leaders and specialized regional competitors.

Competitive strategy is increasingly moving toward integrated solutions. Customers prefer suppliers that can combine the core product with software, interface components, testing, support or adjacent technologies because integration reduces project risk and development time. Companies able to solve a broader customer problem therefore have more pricing power than vendors competing only on a single specification.

Competitive tier Representative companies Competitive basis
Global technology leaders Samsung Electronics, Micron Technology, Western Digital, Kioxia Scale, broad product portfolios, strong R&D and global customer support.
Established specialists Seagate, Kingston Technology, Crucial, SK hynix Application-specific engineering and strong qualification in selected segments.
Regional / emerging suppliers ADATA, Transcend, TeamGroup, Gloway, Plextor Local service, competitive pricing and focused customer relationships.

Key Participants

The profiled competitive set includes Samsung Electronics, Micron Technology, Western Digital, Kioxia, Seagate, Kingston Technology, Crucial, SK hynix, ADATA, Transcend, TeamGroup, Gloway, Plextor. Supplier position depends on engineering performance, customer qualification, manufacturing continuity and the ability to support design changes over long product cycles. Larger vendors benefit from broad portfolios and application teams, while specialists can retain strong positions in narrow, technically demanding subsegments where historical qualification and process know-how create meaningful switching costs.

Production Capacity Analysis

Production capacity for SATA Solid-state Drives is constrained by the combination of specialized equipment, qualified materials, process know-how and customer-specific validation. Nominal factory output can overstate commercial supply because a new line or material source must often demonstrate consistent performance before it can serve high-value customers. This makes qualified capacity more important than raw nameplate capacity.

Regional manufacturing and service capacity influence lead time and resilience. Customers increasingly prefer suppliers that can support major production clusters from more than one site, reducing exposure to logistics disruption and single-factory events. At the same time, duplicating specialized processes can be difficult because equipment recipes, trained engineers and quality systems must be transferred without changing product performance.

The strongest capacity investments are aligned with structural demand drivers rather than short-term cycles. Suppliers expanding around AI, advanced semiconductor manufacturing, automotive electronics or industrial automation seek to secure positions before customer volumes scale. Effective capacity therefore includes engineering resources, test capability and local technical support in addition to physical manufacturing equipment.

Capacity factor Market implication
Specialized manufacturing Determines qualified output and technical performance.
Critical materials / components Can constrain supply despite available factory floor space.
Qualification and test Controls how quickly new capacity becomes usable by customers.
Regional support Improves lead time, resilience and customer retention.

Market Dynamics

The SATA Solid-state Drives market is driven by higher system performance, automation, digitalization and expanding use in high-value applications. Growth is moderated by development cost, qualification requirements and supply-chain concentration. The strongest opportunities occur where new architectures or applications create a clear performance advantage and where suppliers can reduce integration complexity for customers.

MARKET DRIVERS

Driver Relative impact Commercial mechanism
Structural end-market growth High Expanding deployments increase unit demand and installed-base requirements.
Technology upgrade cycle High Higher performance raises value per product and accelerates replacement.
Customer integration needs Medium-High Validated solutions reduce engineering time and project risk.
Regional capacity expansion Medium New manufacturing clusters create local supplier demand.

Structural end-market expansion

Growth in the SATA Solid-state Drives market is supported by rising deployment across its principal applications. Customers are investing because the technology improves performance, efficiency, automation or product capability in ways that are difficult to replicate with older approaches. This expands both new-system demand and the installed base that later requires replacement, upgrades or related services.

Higher technical requirements increase value per system

New product generations demand tighter performance, greater integration and better reliability. These requirements can increase selling prices even when unit volumes grow more slowly, because customers are willing to pay for solutions that protect yield, uptime or user experience. Suppliers with stronger engineering capability therefore benefit disproportionately from technology transitions.

Regional investment broadens customer access

Manufacturing and infrastructure investment in North America, Europe and Asia is creating additional customer clusters outside traditional centers. Local engineering support and shorter supply chains help suppliers qualify products earlier in new projects, creating an opportunity to win design positions before production reaches full scale.

MARKET RESTRAINTS

Restraint Relative impact Commercial mechanism
Development and qualification cost High Raises barriers to entry and lengthens customer adoption.
Supply-chain concentration Medium-High Critical components or materials can limit output.
Price pressure Medium Customers seek lower total system cost as volumes increase.
Technology substitution Medium Alternative architectures can replace incumbent solutions in selected uses.

Qualification slows supplier switching

Customers in technical markets cannot change suppliers based only on purchase price. New products must demonstrate performance, reliability and compatibility in the actual application, which can require months of engineering work. This limits the pace at which new entrants gain share and can delay commercialization of technically promising products.

Specialized inputs can constrain supply

Advanced products depend on a limited number of qualified materials, components or manufacturing tools. Shortages or long lead times at one upstream stage can restrict finished-product output even when downstream assembly capacity is available. Suppliers therefore carry strategic inventory or qualify alternate sources, but those actions increase cost.

Customer cost pressure remains persistent

As a technology becomes more widely adopted, customers expect lower unit costs and may redesign systems to use standardized components. Suppliers must offset this pressure through better performance, lower manufacturing cost and additional software or service value. Vendors that cannot maintain differentiation can face margin erosion even in a growing market.

MARKET OPPORTUNITIES

Legacy-server replacement

A large installed base of SATA servers remains operational in enterprises and data centers. Replacing aging HDDs or older SSDs can improve reliability and power efficiency without changing host interfaces or software. Suppliers that maintain qualified enterprise SATA products can capture recurring refresh demand even as new high-performance servers shift toward NVMe.

Industrial long-lifecycle systems

Industrial automation, medical equipment and embedded systems can remain deployed for a decade or longer. These customers value stable firmware, controlled bill-of-material changes and long product availability more than peak throughput. SATA SSD vendors that maintain extended-lifecycle product lines can command stronger margins than highly commoditized consumer retail products.

Higher-capacity SATA upgrades

Falling NAND cost allows buyers to move toward 1TB, 2TB and higher capacities while retaining the SATA interface. This supports market value even if total units grow slowly. The opportunity is strongest among workstation, surveillance, small-business and prosumer users that need more local capacity but do not require NVMe performance.

HDD-to-SSD conversion in emerging markets

Many desktops and notebooks in emerging economies still use hard drives. SATA SSDs offer a straightforward upgrade that can materially improve boot time, application responsiveness and power consumption. Online retail and local PC service channels can expand this opportunity by offering affordable drives bundled with cloning or installation support.

Supply Chain Analysis

Stage 1
Specialized materials and components
Stage 2
Core product manufacturing
Stage 3
Qualification and system integration
Stage 4
End-user deployment, service and replacement

The upstream supply chain provides the specialized materials, semiconductor devices, mechanical components or substrates that determine baseline product performance. Qualified inputs are important because changes in composition or manufacturing source can alter reliability, electrical behavior or process compatibility. Suppliers therefore maintain close technical relationships with upstream partners and often approve alternate sources before a disruption occurs.

Manufacturing converts these inputs into finished products using process-specific equipment, inspection and test. Quality systems are central because customers expect lot-to-lot consistency and traceability, particularly in semiconductor, automotive and industrial applications. High-value suppliers differentiate through process control rather than simple assembly scale, and they invest heavily in metrology or validation to protect yield.

Downstream value is created when the product is integrated into the customer system and validated under real operating conditions. Application engineers support installation, software, calibration or process optimization, while service teams maintain the installed base. This lifecycle relationship creates recurring revenue through replacement, updates, refurbishment or expansion and makes customer support an important part of the market structure.

Recent Developments

2026 – Micron continues enterprise SATA SSD support through the 5400 family

Micron’s 5400 SATA SSD uses 176-layer NAND, supports capacities from 240GB to 7.68TB and targets established data-center SATA sockets where qualification, endurance and compatibility remain important. Source

2026 – Installed SATA infrastructure sustains replacement demand

Server and industrial customers continue qualifying SATA SSDs for legacy sockets because replacing the storage device is often less disruptive than redesigning an entire platform around PCIe NVMe. Source

2026 – NAND cost declines continue shifting demand toward higher capacities

As NAND cost per bit declines, mainstream buyers increasingly move from sub-1TB products toward 1TB and larger drives, supporting market value even as SATA faces interface substitution from NVMe. Source

REPORT SCOPE & SEGMENTATION

Base Year 2025
Estimated Year 2026
Forecast Year 2034
2025 Market Size USD 8.90 billion
2026 Market Size USD 9.35 billion
2034 Market Size USD 13.92 billion
CAGR 5.1% during 2026–2034
Largest Market / Leading Geography Asia Pacific
By Type Below 1TB; 1TB-3TB; Above 3TB
By Application Online Sales; Offline Sales
By End User Consumer PCs & Laptops; Enterprise & Data Center; Industrial & Embedded
By Form Factor 2.5-inch; M.2 SATA; mSATA & Others

Frequently Asked Questions

What is the size of the SATA Solid-state Drives market?

The market is estimated at USD 9.35 billion in 2026 and is projected to reach USD 13.92 billion by 2034, representing a 5.1% CAGR during 2026–2034.

Which capacity segment leads the market?

Below 1TB remains the largest unit segment, while 1TB-3TB is gaining value as NAND pricing makes higher capacities affordable.

Why does SATA SSD demand persist despite NVMe?

SATA remains deeply installed in PCs, servers and industrial systems. Customers can upgrade performance and reliability without redesigning the platform.

Which region leads the market?

Asia Pacific leads because it combines NAND manufacturing, PC production and large consumer-electronics markets.

Which end users provide the strongest long-term demand?

Consumer upgrades provide the largest unit base, while enterprise and industrial users provide durable demand through qualified installed infrastructure.

What are the main restraints?

NVMe substitution, interface speed limits, intense price competition and mature PC replacement cycles are the main restraints.

Research Sources & Evidence Base
View research sources used for this overview
  1. Micron Technology. 5400 SATA SSD, data-center SATA capacities, endurance and compatibility.
  2. Samsung Semiconductor. Consumer SSD Portfolio, consumer SATA and NAND storage product context.
Global SATA Solid-state Drives Market Research Report 2026-2034

Get Sample Report PDF for Exclusive Insights

Report Sample Includes

  • Table of Contents
  • List of Tables & Figures
  • Charts, Research Methodology, and more...

PDF Icon Download Sample Report PDF

Download Sample Report

Table of Content

Table of Contents
1 Research Methodology and Statistical Scope
1.1 Market Definition and Statistical Scope of SATA Solid-state Drives
1.2 Key Market Segments
1.2.1 SATA Solid-state Drives Segment by Type
1.2.2 SATA Solid-state Drives Segment by Application
1.3 Methodology & Sources of Information
1.3.1 Research Methodology
1.3.2 Research Process
1.3.3 Market Breakdown and Data Triangulation
1.3.4 Base Year
1.3.5 Report Assumptions & Caveats
2 SATA Solid-state Drives Market Overview
2.1 Global Market Overview
2.1.1 Global SATA Solid-state Drives Market Size (M USD) Estimates and Forecasts (2019-2032)
2.1.2 Global SATA Solid-state Drives Sales Estimates and Forecasts (2019-2032)
2.2 Market Segment Executive Summary
2.3 Global Market Size by Region
3 SATA Solid-state Drives Market Competitive Landscape
3.1 Global SATA Solid-state Drives Sales by Manufacturers (2019-2025)
3.2 Global SATA Solid-state Drives Revenue Market Share by Manufacturers (2019-2025)
3.3 SATA Solid-state Drives Market Share by Company Type (Tier 1, Tier 2, and Tier 3)
3.4 Global SATA Solid-state Drives Average Price by Manufacturers (2019-2025)
3.5 Manufacturers SATA Solid-state Drives Sales Sites, Area Served, Product Type
3.6 SATA Solid-state Drives Market Competitive Situation and Trends
3.6.1 SATA Solid-state Drives Market Concentration Rate
3.6.2 Global 5 and 10 Largest SATA Solid-state Drives Players Market Share by Revenue
3.6.3 Mergers & Acquisitions, Expansion
4 SATA Solid-state Drives Industry Chain Analysis
4.1 SATA Solid-state Drives Industry Chain Analysis
4.2 Market Overview of Key Raw Materials
4.3 Midstream Market Analysis
4.4 Downstream Customer Analysis
5 The Development and Dynamics of SATA Solid-state Drives Market
5.1 Key Development Trends
5.2 Driving Factors
5.3 Market Challenges
5.4 Market Restraints
5.5 Industry News
5.5.1 New Product Developments
5.5.2 Mergers & Acquisitions
5.5.3 Expansions
5.5.4 Collaboration/Supply Contracts
5.6 Industry Policies
6 SATA Solid-state Drives Market Segmentation by Type
6.1 Evaluation Matrix of Segment Market Development Potential (Type)
6.2 Global SATA Solid-state Drives Sales Market Share by Type (2019-2025)
6.3 Global SATA Solid-state Drives Market Size Market Share by Type (2019-2025)
6.4 Global SATA Solid-state Drives Price by Type (2019-2025)
7 SATA Solid-state Drives Market Segmentation by Application
7.1 Evaluation Matrix of Segment Market Development Potential (Application)
7.2 Global SATA Solid-state Drives Market Sales by Application (2019-2025)
7.3 Global SATA Solid-state Drives Market Size (M USD) by Application (2019-2025)
7.4 Global SATA Solid-state Drives Sales Growth Rate by Application (2019-2025)
8 SATA Solid-state Drives Market Segmentation by Region
8.1 Global SATA Solid-state Drives Sales by Region
8.1.1 Global SATA Solid-state Drives Sales by Region
8.1.2 Global SATA Solid-state Drives Sales Market Share by Region
8.2 North America
8.2.1 North America SATA Solid-state Drives Sales by Country
8.2.2 U.S.
8.2.3 Canada
8.2.4 Mexico
8.3 Europe
8.3.1 Europe SATA Solid-state Drives Sales by Country
8.3.2 Germany
8.3.3 France
8.3.4 U.K.
8.3.5 Italy
8.3.6 Russia
8.4 Asia Pacific
8.4.1 Asia Pacific SATA Solid-state Drives Sales by Region
8.4.2 China
8.4.3 Japan
8.4.4 South Korea
8.4.5 India
8.4.6 Southeast Asia
8.5 South America
8.5.1 South America SATA Solid-state Drives Sales by Country
8.5.2 Brazil
8.5.3 Argentina
8.5.4 Columbia
8.6 Middle East and Africa
8.6.1 Middle East and Africa SATA Solid-state Drives Sales by Region
8.6.2 Saudi Arabia
8.6.3 UAE
8.6.4 Egypt
8.6.5 Nigeria
8.6.6 South Africa
9 Key Companies Profile
9.1 Dell
9.1.1 Dell SATA Solid-state Drives Basic Information
9.1.2 Dell SATA Solid-state Drives Product Overview
9.1.3 Dell SATA Solid-state Drives Product Market Performance
9.1.4 Dell Business Overview
9.1.5 Dell SATA Solid-state Drives SWOT Analysis
9.1.6 Dell Recent Developments
9.2 HP
9.2.1 HP SATA Solid-state Drives Basic Information
9.2.2 HP SATA Solid-state Drives Product Overview
9.2.3 HP SATA Solid-state Drives Product Market Performance
9.2.4 HP Business Overview
9.2.5 HP SATA Solid-state Drives SWOT Analysis
9.2.6 HP Recent Developments
9.3 Seagate
9.3.1 Seagate SATA Solid-state Drives Basic Information
9.3.2 Seagate SATA Solid-state Drives Product Overview
9.3.3 Seagate SATA Solid-state Drives Product Market Performance
9.3.4 Seagate SATA Solid-state Drives SWOT Analysis
9.3.5 Seagate Business Overview
9.3.6 Seagate Recent Developments
9.4 Toshiba
9.4.1 Toshiba SATA Solid-state Drives Basic Information
9.4.2 Toshiba SATA Solid-state Drives Product Overview
9.4.3 Toshiba SATA Solid-state Drives Product Market Performance
9.4.4 Toshiba Business Overview
9.4.5 Toshiba Recent Developments
9.5 WD
9.5.1 WD SATA Solid-state Drives Basic Information
9.5.2 WD SATA Solid-state Drives Product Overview
9.5.3 WD SATA Solid-state Drives Product Market Performance
9.5.4 WD Business Overview
9.5.5 WD Recent Developments
9.6 Samsung
9.6.1 Samsung SATA Solid-state Drives Basic Information
9.6.2 Samsung SATA Solid-state Drives Product Overview
9.6.3 Samsung SATA Solid-state Drives Product Market Performance
9.6.4 Samsung Business Overview
9.6.5 Samsung Recent Developments
9.7 Intel
9.7.1 Intel SATA Solid-state Drives Basic Information
9.7.2 Intel SATA Solid-state Drives Product Overview
9.7.3 Intel SATA Solid-state Drives Product Market Performance
9.7.4 Intel Business Overview
9.7.5 Intel Recent Developments
9.8 Kingston
9.8.1 Kingston SATA Solid-state Drives Basic Information
9.8.2 Kingston SATA Solid-state Drives Product Overview
9.8.3 Kingston SATA Solid-state Drives Product Market Performance
9.8.4 Kingston Business Overview
9.8.5 Kingston Recent Developments
9.9 Gloway
9.9.1 Gloway SATA Solid-state Drives Basic Information
9.9.2 Gloway SATA Solid-state Drives Product Overview
9.9.3 Gloway SATA Solid-state Drives Product Market Performance
9.9.4 Gloway Business Overview
9.9.5 Gloway Recent Developments
9.10 Plextor
9.10.1 Plextor SATA Solid-state Drives Basic Information
9.10.2 Plextor SATA Solid-state Drives Product Overview
9.10.3 Plextor SATA Solid-state Drives Product Market Performance
9.10.4 Plextor Business Overview
9.10.5 Plextor Recent Developments
10 SATA Solid-state Drives Market Forecast by Region
10.1 Global SATA Solid-state Drives Market Size Forecast
10.2 Global SATA Solid-state Drives Market Forecast by Region
10.2.1 North America Market Size Forecast by Country
10.2.2 Europe SATA Solid-state Drives Market Size Forecast by Country
10.2.3 Asia Pacific SATA Solid-state Drives Market Size Forecast by Region
10.2.4 South America SATA Solid-state Drives Market Size Forecast by Country
10.2.5 Middle East and Africa Forecasted Consumption of SATA Solid-state Drives by Country
11 Forecast Market by Type and by Application (2025-2032)
11.1 Global SATA Solid-state Drives Market Forecast by Type (2025-2032)
11.1.1 Global Forecasted Sales of SATA Solid-state Drives by Type (2025-2032)
11.1.2 Global SATA Solid-state Drives Market Size Forecast by Type (2025-2032)
11.1.3 Global Forecasted Price of SATA Solid-state Drives by Type (2025-2032)
11.2 Global SATA Solid-state Drives Market Forecast by Application (2025-2032)
11.2.1 Global SATA Solid-state Drives Sales (K Units) Forecast by Application
11.2.2 Global SATA Solid-state Drives Market Size (M USD) Forecast by Application (2025-2032)
12 Conclusion and Key FindingsList of Tables
Table 1. Introduction of the Type
Table 2. Introduction of the Application
Table 3. Market Size (M USD) Segment Executive Summary
Table 4. SATA Solid-state Drives Market Size Comparison by Region (M USD)
Table 5. Global SATA Solid-state Drives Sales (K Units) by Manufacturers (2019-2025)
Table 6. Global SATA Solid-state Drives Sales Market Share by Manufacturers (2019-2025)
Table 7. Global SATA Solid-state Drives Revenue (M USD) by Manufacturers (2019-2025)
Table 8. Global SATA Solid-state Drives Revenue Share by Manufacturers (2019-2025)
Table 9. Company Type (Tier 1, Tier 2, and Tier 3) & (based on the Revenue in SATA Solid-state Drives as of 2022)
Table 10. Global Market SATA Solid-state Drives Average Price (USD/Unit) of Key Manufacturers (2019-2025)
Table 11. Manufacturers SATA Solid-state Drives Sales Sites and Area Served
Table 12. Manufacturers SATA Solid-state Drives Product Type
Table 13. Global SATA Solid-state Drives Manufacturers Market Concentration Ratio (CR5 and HHI)
Table 14. Mergers & Acquisitions, Expansion Plans
Table 15. Industry Chain Map of SATA Solid-state Drives
Table 16. Market Overview of Key Raw Materials
Table 17. Midstream Market Analysis
Table 18. Downstream Customer Analysis
Table 19. Key Development Trends
Table 20. Driving Factors
Table 21. SATA Solid-state Drives Market Challenges
Table 22. Global SATA Solid-state Drives Sales by Type (K Units)
Table 23. Global SATA Solid-state Drives Market Size by Type (M USD)
Table 24. Global SATA Solid-state Drives Sales (K Units) by Type (2019-2025)
Table 25. Global SATA Solid-state Drives Sales Market Share by Type (2019-2025)
Table 26. Global SATA Solid-state Drives Market Size (M USD) by Type (2019-2025)
Table 27. Global SATA Solid-state Drives Market Size Share by Type (2019-2025)
Table 28. Global SATA Solid-state Drives Price (USD/Unit) by Type (2019-2025)
Table 29. Global SATA Solid-state Drives Sales (K Units) by Application
Table 30. Global SATA Solid-state Drives Market Size by Application
Table 31. Global SATA Solid-state Drives Sales by Application (2019-2025) & (K Units)
Table 32. Global SATA Solid-state Drives Sales Market Share by Application (2019-2025)
Table 33. Global SATA Solid-state Drives Sales by Application (2019-2025) & (M USD)
Table 34. Global SATA Solid-state Drives Market Share by Application (2019-2025)
Table 35. Global SATA Solid-state Drives Sales Growth Rate by Application (2019-2025)
Table 36. Global SATA Solid-state Drives Sales by Region (2019-2025) & (K Units)
Table 37. Global SATA Solid-state Drives Sales Market Share by Region (2019-2025)
Table 38. North America SATA Solid-state Drives Sales by Country (2019-2025) & (K Units)
Table 39. Europe SATA Solid-state Drives Sales by Country (2019-2025) & (K Units)
Table 40. Asia Pacific SATA Solid-state Drives Sales by Region (2019-2025) & (K Units)
Table 41. South America SATA Solid-state Drives Sales by Country (2019-2025) & (K Units)
Table 42. Middle East and Africa SATA Solid-state Drives Sales by Region (2019-2025) & (K Units)
Table 43. Dell SATA Solid-state Drives Basic Information
Table 44. Dell SATA Solid-state Drives Product Overview
Table 45. Dell SATA Solid-state Drives Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 46. Dell Business Overview
Table 47. Dell SATA Solid-state Drives SWOT Analysis
Table 48. Dell Recent Developments
Table 49. HP SATA Solid-state Drives Basic Information
Table 50. HP SATA Solid-state Drives Product Overview
Table 51. HP SATA Solid-state Drives Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 52. HP Business Overview
Table 53. HP SATA Solid-state Drives SWOT Analysis
Table 54. HP Recent Developments
Table 55. Seagate SATA Solid-state Drives Basic Information
Table 56. Seagate SATA Solid-state Drives Product Overview
Table 57. Seagate SATA Solid-state Drives Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 58. Seagate SATA Solid-state Drives SWOT Analysis
Table 59. Seagate Business Overview
Table 60. Seagate Recent Developments
Table 61. Toshiba SATA Solid-state Drives Basic Information
Table 62. Toshiba SATA Solid-state Drives Product Overview
Table 63. Toshiba SATA Solid-state Drives Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 64. Toshiba Business Overview
Table 65. Toshiba Recent Developments
Table 66. WD SATA Solid-state Drives Basic Information
Table 67. WD SATA Solid-state Drives Product Overview
Table 68. WD SATA Solid-state Drives Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 69. WD Business Overview
Table 70. WD Recent Developments
Table 71. Samsung SATA Solid-state Drives Basic Information
Table 72. Samsung SATA Solid-state Drives Product Overview
Table 73. Samsung SATA Solid-state Drives Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 74. Samsung Business Overview
Table 75. Samsung Recent Developments
Table 76. Intel SATA Solid-state Drives Basic Information
Table 77. Intel SATA Solid-state Drives Product Overview
Table 78. Intel SATA Solid-state Drives Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 79. Intel Business Overview
Table 80. Intel Recent Developments
Table 81. Kingston SATA Solid-state Drives Basic Information
Table 82. Kingston SATA Solid-state Drives Product Overview
Table 83. Kingston SATA Solid-state Drives Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 84. Kingston Business Overview
Table 85. Kingston Recent Developments
Table 86. Gloway SATA Solid-state Drives Basic Information
Table 87. Gloway SATA Solid-state Drives Product Overview
Table 88. Gloway SATA Solid-state Drives Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 89. Gloway Business Overview
Table 90. Gloway Recent Developments
Table 91. Plextor SATA Solid-state Drives Basic Information
Table 92. Plextor SATA Solid-state Drives Product Overview
Table 93. Plextor SATA Solid-state Drives Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 94. Plextor Business Overview
Table 95. Plextor Recent Developments
Table 96. Global SATA Solid-state Drives Sales Forecast by Region (2025-2032) & (K Units)
Table 97. Global SATA Solid-state Drives Market Size Forecast by Region (2025-2032) & (M USD)
Table 98. North America SATA Solid-state Drives Sales Forecast by Country (2025-2032) & (K Units)
Table 99. North America SATA Solid-state Drives Market Size Forecast by Country (2025-2032) & (M USD)
Table 100. Europe SATA Solid-state Drives Sales Forecast by Country (2025-2032) & (K Units)
Table 101. Europe SATA Solid-state Drives Market Size Forecast by Country (2025-2032) & (M USD)
Table 102. Asia Pacific SATA Solid-state Drives Sales Forecast by Region (2025-2032) & (K Units)
Table 103. Asia Pacific SATA Solid-state Drives Market Size Forecast by Region (2025-2032) & (M USD)
Table 104. South America SATA Solid-state Drives Sales Forecast by Country (2025-2032) & (K Units)
Table 105. South America SATA Solid-state Drives Market Size Forecast by Country (2025-2032) & (M USD)
Table 106. Middle East and Africa SATA Solid-state Drives Consumption Forecast by Country (2025-2032) & (Units)
Table 107. Middle East and Africa SATA Solid-state Drives Market Size Forecast by Country (2025-2032) & (M USD)
Table 108. Global SATA Solid-state Drives Sales Forecast by Type (2025-2032) & (K Units)
Table 109. Global SATA Solid-state Drives Market Size Forecast by Type (2025-2032) & (M USD)
Table 110. Global SATA Solid-state Drives Price Forecast by Type (2025-2032) & (USD/Unit)
Table 111. Global SATA Solid-state Drives Sales (K Units) Forecast by Application (2025-2032)
Table 112. Global SATA Solid-state Drives Market Size Forecast by Application (2025-2032) & (M USD)
List of Figures
Figure 1. Product Picture of SATA Solid-state Drives
Figure 2. Data Triangulation
Figure 3. Key Caveats
Figure 4. Global SATA Solid-state Drives Market Size (M USD), 2019-2032
Figure 5. Global SATA Solid-state Drives Market Size (M USD) (2019-2032)
Figure 6. Global SATA Solid-state Drives Sales (K Units) & (2019-2032)
Figure 7. Evaluation Matrix of Segment Market Development Potential (Type)
Figure 8. Evaluation Matrix of Segment Market Development Potential (Application)
Figure 9. Evaluation Matrix of Regional Market Development Potential
Figure 10. SATA Solid-state Drives Market Size by Country (M USD)
Figure 11. SATA Solid-state Drives Sales Share by Manufacturers in 2023
Figure 12. Global SATA Solid-state Drives Revenue Share by Manufacturers in 2023
Figure 13. SATA Solid-state Drives Market Share by Company Type (Tier 1, Tier 2 and Tier 3): 2023
Figure 14. Global Market SATA Solid-state Drives Average Price (USD/Unit) of Key Manufacturers in 2023
Figure 15. The Global 5 and 10 Largest Players: Market Share by SATA Solid-state Drives Revenue in 2023
Figure 16. Evaluation Matrix of Segment Market Development Potential (Type)
Figure 17. Global SATA Solid-state Drives Market Share by Type
Figure 18. Sales Market Share of SATA Solid-state Drives by Type (2019-2025)
Figure 19. Sales Market Share of SATA Solid-state Drives by Type in 2023
Figure 20. Market Size Share of SATA Solid-state Drives by Type (2019-2025)
Figure 21. Market Size Market Share of SATA Solid-state Drives by Type in 2023
Figure 22. Evaluation Matrix of Segment Market Development Potential (Application)
Figure 23. Global SATA Solid-state Drives Market Share by Application
Figure 24. Global SATA Solid-state Drives Sales Market Share by Application (2019-2025)
Figure 25. Global SATA Solid-state Drives Sales Market Share by Application in 2023
Figure 26. Global SATA Solid-state Drives Market Share by Application (2019-2025)
Figure 27. Global SATA Solid-state Drives Market Share by Application in 2023
Figure 28. Global SATA Solid-state Drives Sales Growth Rate by Application (2019-2025)
Figure 29. Global SATA Solid-state Drives Sales Market Share by Region (2019-2025)
Figure 30. North America SATA Solid-state Drives Sales and Growth Rate (2019-2025) & (K Units)
Figure 31. North America SATA Solid-state Drives Sales Market Share by Country in 2023
Figure 32. U.S. SATA Solid-state Drives Sales and Growth Rate (2019-2025) & (K Units)
Figure 33. Canada SATA Solid-state Drives Sales (K Units) and Growth Rate (2019-2025)
Figure 34. Mexico SATA Solid-state Drives Sales (Units) and Growth Rate (2019-2025)
Figure 35. Europe SATA Solid-state Drives Sales and Growth Rate (2019-2025) & (K Units)
Figure 36. Europe SATA Solid-state Drives Sales Market Share by Country in 2023
Figure 37. Germany SATA Solid-state Drives Sales and Growth Rate (2019-2025) & (K Units)
Figure 38. France SATA Solid-state Drives Sales and Growth Rate (2019-2025) & (K Units)
Figure 39. U.K. SATA Solid-state Drives Sales and Growth Rate (2019-2025) & (K Units)
Figure 40. Italy SATA Solid-state Drives Sales and Growth Rate (2019-2025) & (K Units)
Figure 41. Russia SATA Solid-state Drives Sales and Growth Rate (2019-2025) & (K Units)
Figure 42. Asia Pacific SATA Solid-state Drives Sales and Growth Rate (K Units)
Figure 43. Asia Pacific SATA Solid-state Drives Sales Market Share by Region in 2023
Figure 44. China SATA Solid-state Drives Sales and Growth Rate (2019-2025) & (K Units)
Figure 45. Japan SATA Solid-state Drives Sales and Growth Rate (2019-2025) & (K Units)
Figure 46. South Korea SATA Solid-state Drives Sales and Growth Rate (2019-2025) & (K Units)
Figure 47. India SATA Solid-state Drives Sales and Growth Rate (2019-2025) & (K Units)
Figure 48. Southeast Asia SATA Solid-state Drives Sales and Growth Rate (2019-2025) & (K Units)
Figure 49. South America SATA Solid-state Drives Sales and Growth Rate (K Units)
Figure 50. South America SATA Solid-state Drives Sales Market Share by Country in 2023
Figure 51. Brazil SATA Solid-state Drives Sales and Growth Rate (2019-2025) & (K Units)
Figure 52. Argentina SATA Solid-state Drives Sales and Growth Rate (2019-2025) & (K Units)
Figure 53. Columbia SATA Solid-state Drives Sales and Growth Rate (2019-2025) & (K Units)
Figure 54. Middle East and Africa SATA Solid-state Drives Sales and Growth Rate (K Units)
Figure 55. Middle East and Africa SATA Solid-state Drives Sales Market Share by Region in 2023
Figure 56. Saudi Arabia SATA Solid-state Drives Sales and Growth Rate (2019-2025) & (K Units)
Figure 57. UAE SATA Solid-state Drives Sales and Growth Rate (2019-2025) & (K Units)
Figure 58. Egypt SATA Solid-state Drives Sales and Growth Rate (2019-2025) & (K Units)
Figure 59. Nigeria SATA Solid-state Drives Sales and Growth Rate (2019-2025) & (K Units)
Figure 60. South Africa SATA Solid-state Drives Sales and Growth Rate (2019-2025) & (K Units)
Figure 61. Global SATA Solid-state Drives Sales Forecast by Volume (2019-2032) & (K Units)
Figure 62. Global SATA Solid-state Drives Market Size Forecast by Value (2019-2032) & (M USD)
Figure 63. Global SATA Solid-state Drives Sales Market Share Forecast by Type (2025-2032)
Figure 64. Global SATA Solid-state Drives Market Share Forecast by Type (2025-2032)
Figure 65. Global SATA Solid-state Drives Sales Forecast by Application (2025-2032)
Figure 66. Global SATA Solid-state Drives Market Share Forecast by Application (2025-2032)