SEMICONDUCTOR INSIGHT
MARKET RESEARCH REPORT

Global Earphones and Headphones Market

2026 to 2034
MARKET INTELLIGENCE
ACROSS KEY REGIONS
2026 EDITION
CONSUMER ELECTRONICS Semiconductor Market Research

Global Earphones and Headphones Market

Trends, Business Strategies 2026-2034

◷
UPDATED 22 September 2026
▤
REPORT LENGTH Detailed Report
▣
REPORT CODE 7532be1b2dc6
▯
FORMATS PDF

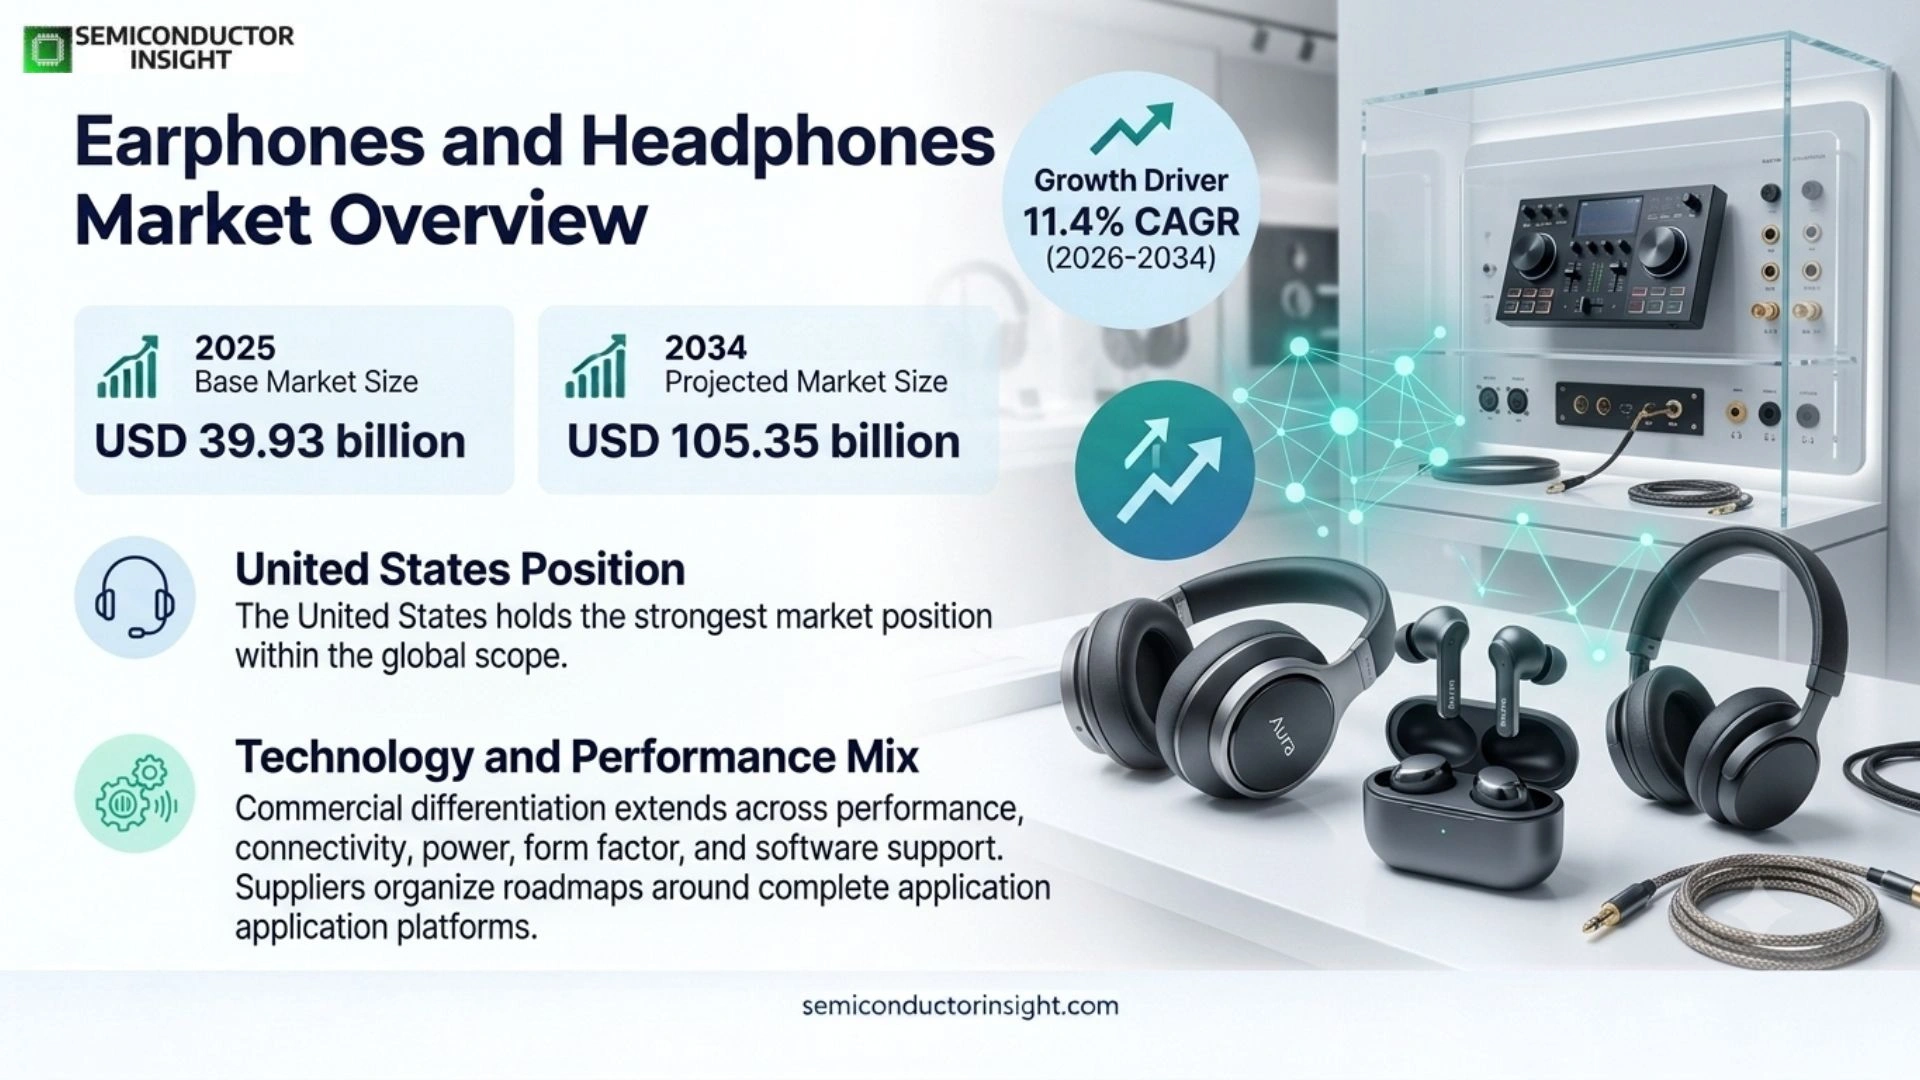
Earphones and Headphones Market is projected to reach USD 105.35 billion by 2034, representing a CAGR of 11.4% during 2026–2034. United States holds the strongest market position in the source-defined scope.

Get the sample PDF with study scope, segmentation and methodology details.

Key Statistics

2025 Market Size
USD 39.93 billion
2034 Projected Size
USD 105.35 billion
CAGR (2026–2034)
11.4%
Largest Market in 2025
United States

Key Takeaways

  • In-Ear / TWS is the largest type position in the source-defined scope, while In-Ear / TWS carries the strongest structural growth case as product architectures move toward higher integration, efficiency and performance requirements.
  • Residential is the leading application position, while Gaming & Smart Audio is the most important incremental demand engine because system complexity and electronic content are rising faster than unit volumes alone.
  • North America has the strongest market position, supported by manufacturing scale, design activity and downstream demand that create both volume purchasing and faster qualification of new product generations.
  • The 2025–2034 value path rises from USD 39.93 billion to USD 105.35 billion, with a rebased CAGR of 11.4% for 2026–2034. This series uses the two published market-size anchors as the controlling values.
  • Supplier differentiation increasingly depends on system-level performance, qualification, software or application support, and lifecycle reliability rather than on component price alone, which favors vendors able to solve integration problems for OEM customers.

Earphones and Headphones Market Overview

Earphones and Headphones Market was valued at USD 39.93 billion in 2025 and is projected to reach USD 105.35 billion by 2034, representing a CAGR of 11.4% during 2026–2034. United States holds the strongest market position in the source-defined scope.

Base year: 2025 · Estimated year: 2026 · Forecast period: 2026–2034 · Historical data: 2021–2025 · Values in USD

The earphones and headphones market covers personal audio devices worn in, on or around the ear for music, video, gaming, communications and professional monitoring. The report scope divides products into in-ear devices and headphones, with residential and commercial applications. Wireless connectivity, active noise cancellation, microphones, spatial processing and integrated sensing increasingly determine product value beyond the acoustic transducer itself.

True wireless earbuds have become the center of volume growth because they combine portability, smartphone integration and frequent replacement cycles. Bluetooth SIG’s 2024 market update forecast 448 million Bluetooth earbuds shipments for 2024 and a 59% rise to 712 million by 2028, while LE Audio and Auracast add lower-power audio, broadcast capability and new accessibility use cases. Those platform transitions create recurring upgrade demand even when basic stereo playback is already mature.

Premiumization is also changing what a headset contains. Active noise cancellation, adaptive transparency, lossless and spatial audio, AI-assisted voice pickup, health sensors and cross-device connectivity increase semiconductor and software content per unit. Apple’s 2025 AirPods Pro 3 added stronger ANC, heart-rate sensing and longer battery life, while Qualcomm’s Snapdragon Sound platform highlights lossless audio, low latency, AI and Wi-Fi-based XPAN connectivity as differentiation points for premium wireless products.

Segment Analysis: By Type

By type, the report segments the market into In-Ear, Headphone. In-Ear / TWS holds the leading position, while In-Ear / TWS offers the strongest structural growth path as buyers prioritize newer performance and integration requirements.

Type Demand characteristics Market position
In-Ear In-Ear serves a distinct portion of the earphones and headphones market. Its purchasing logic depends on the balance between performance, integration, cost, lifecycle support and downstream design requirements. The segment’s commercial position is best understood through design-win persistence: once an OEM validates a component or product architecture, qualification cost and software or mechanical integration can keep that choice in production for multiple product generations. Largest / established segment describes its current strategic role. Largest / established segment. Supplier competition centers on specifications that reduce customer design risk while preserving cost, availability and qualification continuity.
Headphone Headphone serves a distinct portion of the earphones and headphones market. Its purchasing logic depends on the balance between performance, integration, cost, lifecycle support and downstream design requirements. The segment’s commercial position is best understood through design-win persistence: once an OEM validates a component or product architecture, qualification cost and software or mechanical integration can keep that choice in production for multiple product generations. Application-dependent demand describes its current strategic role. Application-dependent demand. Supplier competition centers on specifications that reduce customer design risk while preserving cost, availability and qualification continuity.

Technology and performance mix

Although the source page uses a compact type axis, commercial differentiation extends across performance, connectivity, power, form factor and software support. These attributes determine average selling price and the persistence of design wins, so suppliers increasingly organize road maps around complete application platforms rather than isolated part numbers.

Segment Analysis: By Application

The application scope includes Residential, Commercial. Residential carries the largest current position, while Gaming & Smart Audio is the most important incremental growth channel because it combines new unit demand with rising content or feature value per system.

Application Demand characteristics
Residential
Leading application
Residential demand is created when end users need the core function of the earphones and headphones category inside a finished system. Purchasing is triggered by product refresh cycles, performance targets, compliance requirements and the economics of integrating a validated solution. OEMs tend to favor suppliers that can document reliability, maintain availability and support engineering teams through design and qualification. This makes application expertise a commercial advantage rather than a marketing label.
Commercial
Established application
Commercial demand is created when end users need the core function of the earphones and headphones category inside a finished system. Purchasing is triggered by product refresh cycles, performance targets, compliance requirements and the economics of integrating a validated solution. OEMs tend to favor suppliers that can document reliability, maintain availability and support engineering teams through design and qualification. This makes application expertise a commercial advantage rather than a marketing label.

Global Earphones and Headphones Market Prizing

Regional Analysis

North America holds the strongest regional position, while the market’s regional structure reflects different combinations of manufacturing, downstream adoption, regulation, channel depth and design activity. These differences affect not only growth rates but also which product specifications and supplier capabilities convert into revenue.

How does regional demand differ across the Earphones and Headphones market?

Region Position Commercial logic
Asia Pacific Fast-growth China is the central manufacturing base for TWS and Bluetooth audio, while large smartphone ecosystems in China, India, South Korea and Southeast Asia broaden unit demand. Regional vendors also compete aggressively in value and mid-premium tiers.
North America Largest The source page values the United States market at USD 10.25 billion in 2024, creating the strongest national revenue anchor. Premium TWS, gaming headsets, remote-work audio and high smartphone penetration support high average selling prices.
Europe Established / emerging Strong premium headphone brands, commuter use and workplace audio support demand. Safe-listening expectations and EU consumer regulation increase emphasis on volume management, durability and product transparency.
South America Established / emerging Brazil and other large urban markets drive wireless-audio adoption through smartphone replacement and streaming use. Price sensitivity increases the role of mid-range TWS and local e-commerce channels.
Middle East & Africa Established / emerging Gulf markets skew toward premium consumer electronics, while Africa is more price sensitive and mobile-first. Distribution, counterfeit control and affordable wireless models shape supplier performance.
Asia Pacific FASTEST-GROWING & MANUFACTURING HUB

What shapes Asia Pacific demand in the Earphones and Headphones market?

China is the central manufacturing base for TWS and Bluetooth audio, while large smartphone ecosystems in China, India, South Korea and Southeast Asia broaden unit demand. Regional vendors also compete aggressively in value and mid-premium tiers.

Market positionFast-growth
Demand profileFastest-Growing & Manufacturing Hub
Forecast window2026–2034
Supplier priorityQualification + channel support
Country What drives demand
China The manufacturing hub for TWS and a major domestic consumer market with rapid feature diffusion across price bands. The commercial implication is that winning suppliers need a combination of local channel coverage, qualification support and product availability matched to the application mix rather than a uniform regional sales model.
India Large smartphone installed base and online retail create fast unit growth in value and mid-tier wireless earbuds. The commercial implication is that winning suppliers need a combination of local channel coverage, qualification support and product availability matched to the application mix rather than a uniform regional sales model.
Japan Premium audio, gaming and commuter use support strong headphone and ANC demand. The commercial implication is that winning suppliers need a combination of local channel coverage, qualification support and product availability matched to the application mix rather than a uniform regional sales model.
South Korea Advanced smartphone ecosystems accelerate adoption of integrated wireless features. The commercial implication is that winning suppliers need a combination of local channel coverage, qualification support and product availability matched to the application mix rather than a uniform regional sales model.

Market instances

  • The region’s strongest demand pockets are those where downstream production, infrastructure investment or consumer adoption is expanding faster than the installed base. That creates fresh design decisions rather than replacement-only purchasing and gives suppliers an opportunity to win multi-year platform positions.
  • Channel structure matters because qualification and availability often determine supplier selection before headline price. Vendors with local technical support, stocked inventory and application-specific reference designs can convert a global portfolio into regional share more effectively than remote catalog-only competitors.
  • Product mix also differs by country. Mature markets pay for efficiency, reliability, software and advanced features, while faster-growing value markets require cost discipline and simpler integration. A supplier that uses one undifferentiated configuration across all countries risks losing both ends of the market.
In the full report: country-level market size, volume, average selling price, supplier share and CAGR across the study period, with segment cross-tabulation by the source-defined type and application axes.
North America LARGEST VALUE MARKET

What shapes North America demand in the Earphones and Headphones market?

The source page values the United States market at USD 10.25 billion in 2024, creating the strongest national revenue anchor. Premium TWS, gaming headsets, remote-work audio and high smartphone penetration support high average selling prices.

Market positionLargest
Demand profileLargest Value Market
Forecast window2026–2034
Supplier priorityQualification + channel support
Country What drives demand
United States The source page values the U.S. market at USD 10.25 billion in 2024; premium earbuds, gaming and hybrid work support high value per user. The commercial implication is that winning suppliers need a combination of local channel coverage, qualification support and product availability matched to the application mix rather than a uniform regional sales model.
Canada High smartphone and streaming use sustains premium wireless demand. The commercial implication is that winning suppliers need a combination of local channel coverage, qualification support and product availability matched to the application mix rather than a uniform regional sales model.
Mexico Mobile-first consumers and electronics retail expansion support mid-range TWS growth. The commercial implication is that winning suppliers need a combination of local channel coverage, qualification support and product availability matched to the application mix rather than a uniform regional sales model.

Market instances

  • The region’s strongest demand pockets are those where downstream production, infrastructure investment or consumer adoption is expanding faster than the installed base. That creates fresh design decisions rather than replacement-only purchasing and gives suppliers an opportunity to win multi-year platform positions.
  • Channel structure matters because qualification and availability often determine supplier selection before headline price. Vendors with local technical support, stocked inventory and application-specific reference designs can convert a global portfolio into regional share more effectively than remote catalog-only competitors.
  • Product mix also differs by country. Mature markets pay for efficiency, reliability, software and advanced features, while faster-growing value markets require cost discipline and simpler integration. A supplier that uses one undifferentiated configuration across all countries risks losing both ends of the market.
In the full report: country-level market size, volume, average selling price, supplier share and CAGR across the study period, with segment cross-tabulation by the source-defined type and application axes.
Europe PREMIUM & REGULATED

What shapes Europe demand in the Earphones and Headphones market?

Strong premium headphone brands, commuter use and workplace audio support demand. Safe-listening expectations and EU consumer regulation increase emphasis on volume management, durability and product transparency.

Market positionEstablished / emerging
Demand profilePremium & Regulated
Forecast window2026–2034
Supplier priorityQualification + channel support
Country What drives demand
Germany Premium audio, commuting and gaming sustain balanced earbud and over-ear demand. The commercial implication is that winning suppliers need a combination of local channel coverage, qualification support and product availability matched to the application mix rather than a uniform regional sales model.
United Kingdom High streaming penetration and hybrid work support premium wireless headsets. The commercial implication is that winning suppliers need a combination of local channel coverage, qualification support and product availability matched to the application mix rather than a uniform regional sales model.
France Music, commuting and premium lifestyle electronics support established brand demand. The commercial implication is that winning suppliers need a combination of local channel coverage, qualification support and product availability matched to the application mix rather than a uniform regional sales model.

Market instances

  • The region’s strongest demand pockets are those where downstream production, infrastructure investment or consumer adoption is expanding faster than the installed base. That creates fresh design decisions rather than replacement-only purchasing and gives suppliers an opportunity to win multi-year platform positions.
  • Channel structure matters because qualification and availability often determine supplier selection before headline price. Vendors with local technical support, stocked inventory and application-specific reference designs can convert a global portfolio into regional share more effectively than remote catalog-only competitors.
  • Product mix also differs by country. Mature markets pay for efficiency, reliability, software and advanced features, while faster-growing value markets require cost discipline and simpler integration. A supplier that uses one undifferentiated configuration across all countries risks losing both ends of the market.
In the full report: country-level market size, volume, average selling price, supplier share and CAGR across the study period, with segment cross-tabulation by the source-defined type and application axes.
South America SMARTPHONE-LED

What shapes South America demand in the Earphones and Headphones market?

Brazil and other large urban markets drive wireless-audio adoption through smartphone replacement and streaming use. Price sensitivity increases the role of mid-range TWS and local e-commerce channels.

Market positionEstablished / emerging
Demand profileSmartphone-Led
Forecast window2026–2034
Supplier priorityQualification + channel support
Country What drives demand
Brazil The region’s largest consumer-electronics base, with wireless earbuds increasingly replacing wired accessories. The commercial implication is that winning suppliers need a combination of local channel coverage, qualification support and product availability matched to the application mix rather than a uniform regional sales model.
Argentina Demand remains import- and currency-sensitive, favoring broad price ladders. The commercial implication is that winning suppliers need a combination of local channel coverage, qualification support and product availability matched to the application mix rather than a uniform regional sales model.

Market instances

  • The region’s strongest demand pockets are those where downstream production, infrastructure investment or consumer adoption is expanding faster than the installed base. That creates fresh design decisions rather than replacement-only purchasing and gives suppliers an opportunity to win multi-year platform positions.
  • Channel structure matters because qualification and availability often determine supplier selection before headline price. Vendors with local technical support, stocked inventory and application-specific reference designs can convert a global portfolio into regional share more effectively than remote catalog-only competitors.
  • Product mix also differs by country. Mature markets pay for efficiency, reliability, software and advanced features, while faster-growing value markets require cost discipline and simpler integration. A supplier that uses one undifferentiated configuration across all countries risks losing both ends of the market.
In the full report: country-level market size, volume, average selling price, supplier share and CAGR across the study period, with segment cross-tabulation by the source-defined type and application axes.
Middle East & Africa YOUNG CONSUMER BASE

What shapes Middle East & Africa demand in the Earphones and Headphones market?

Gulf markets skew toward premium consumer electronics, while Africa is more price sensitive and mobile-first. Distribution, counterfeit control and affordable wireless models shape supplier performance.

Market positionEstablished / emerging
Demand profileYoung Consumer Base
Forecast window2026–2034
Supplier priorityQualification + channel support
Country What drives demand
UAE Premium smartphone penetration and travel retail support higher-end earbuds and headphones. The commercial implication is that winning suppliers need a combination of local channel coverage, qualification support and product availability matched to the application mix rather than a uniform regional sales model.
Saudi Arabia Young consumers, gaming and digital entertainment support fast premium-audio adoption. The commercial implication is that winning suppliers need a combination of local channel coverage, qualification support and product availability matched to the application mix rather than a uniform regional sales model.
South Africa Retail and mobile ecosystems form the strongest sub-Saharan demand base. The commercial implication is that winning suppliers need a combination of local channel coverage, qualification support and product availability matched to the application mix rather than a uniform regional sales model.

Market instances

  • The region’s strongest demand pockets are those where downstream production, infrastructure investment or consumer adoption is expanding faster than the installed base. That creates fresh design decisions rather than replacement-only purchasing and gives suppliers an opportunity to win multi-year platform positions.
  • Channel structure matters because qualification and availability often determine supplier selection before headline price. Vendors with local technical support, stocked inventory and application-specific reference designs can convert a global portfolio into regional share more effectively than remote catalog-only competitors.
  • Product mix also differs by country. Mature markets pay for efficiency, reliability, software and advanced features, while faster-growing value markets require cost discipline and simpler integration. A supplier that uses one undifferentiated configuration across all countries risks losing both ends of the market.
In the full report: country-level market size, volume, average selling price, supplier share and CAGR across the study period, with segment cross-tabulation by the source-defined type and application axes.

Competitive Landscape

The competitive landscape includes global platform suppliers, application specialists and regional value players. Key profiled companies include Sennheiser, Sony, Shure, JVC, Skullcandy, Philips, Bose, Beats Electronics, with competition increasingly decided by design support, product breadth, qualification history, software or ecosystem compatibility and the ability to maintain supply through long customer lifecycles.

Large suppliers benefit from portfolio breadth and cross-selling because customers can qualify several adjacent functions through one vendor relationship. Specialists can still win where they provide superior performance, domain-specific engineering or faster product innovation. The result is a market in which share is often determined during the design phase and then protected by switching costs once the customer enters production.

Pricing power is strongest where a product solves a system-level constraint, such as energy efficiency, functional safety, acoustic performance, low power, security, thermal limits or time to market. Commodity positions are more exposed to price erosion and distributor substitution, while differentiated positions can preserve margin through software, reference designs, certification packages and application engineering.

Tier Companies Basis of competition
Tier 1 Sennheiser, Sony, Shure, JVC, Skullcandy Global design-in reach, broad portfolio, strong channel access and sustained R&D investment.
Tier 2 Philips, Bose, Beats Electronics, Audio-Technica, Samsung (Harman Kardon), AKG Application specialization, regional strength and targeted technology differentiation.
Tier 3 / Other profiled Logitech, Monster, Klipsch, Apple, Huawei, Xiaomi Value positioning, local distribution and focused product niches.

Key companies profiled in the report scope

  • Sennheiser
  • Sony
  • Shure
  • JVC
  • Skullcandy
  • Philips
  • Bose
  • Beats Electronics
  • Audio-Technica
  • Samsung (Harman Kardon)
  • AKG
  • Logitech
  • Monster
  • Klipsch
  • Apple
  • Huawei
  • Xiaomi

Earphones and Headphones Production Capacity Analysis

Manufacturing capacity is concentrated across East and Southeast Asia, where contract manufacturers, acoustic-component suppliers, battery vendors, semiconductor providers and plastics tooling ecosystems can support high-volume TWS and headphone production. Premium brands retain product architecture, industrial design and software control while relying on specialized manufacturing partners for assembly and test.

The principal capacity constraints are less about final assembly line count and more about component qualification, battery-cell availability, acoustic consistency, RF performance, yield on miniature assemblies and the speed at which new features can be validated. TWS products combine tiny mechanical tolerances with microphones, antennas, charging contacts, batteries and DSP-heavy electronics, so small process changes can affect both user fit and radio or acoustic performance.

Market Dynamics

Market growth is supported by technology upgrade cycles, broader downstream adoption and rising system-level performance requirements. The principal counterweights are qualification cost, price competition, integration complexity and supply-chain risk. The balance of these forces supports the rebased 11.4% CAGR for 2026–2034.

MARKET DRIVERS

Drivers Impact Analysis*

Factor Directional impact Geographic relevance Impact timeline
True wireless replacement cycle High Global with strongest relevance in North America 2026–2034
ANC, spatial and AI feature adoption High Global with strongest relevance in North America 2026–2034
LE Audio and Auracast transition Medium Global with strongest relevance in North America 2026–2034
Gaming, work and multi-device use Medium Global with strongest relevance in North America 2026–2034

True wireless replacement cycle

Bluetooth SIG forecast 448 million Bluetooth earbuds shipments in 2024 and 712 million by 2028, showing how earbuds remain the largest growth engine within wireless headsets. The commercial response is therefore visible in product road maps, qualification strategy and channel positioning, which determines whether the factor expands total addressable demand or simply redistributes share among existing suppliers.

ANC, spatial and AI feature adoption

Premium devices increasingly compete on active noise cancellation, transparency, spatial processing, voice isolation and AI-based personalization, lifting semiconductor content and average selling price. The commercial response is therefore visible in product road maps, qualification strategy and channel positioning, which determines whether the factor expands total addressable demand or simply redistributes share among existing suppliers.

LE Audio and Auracast transition

Bluetooth LE Audio improves power efficiency and introduces standardized broadcast audio. The ecosystem transition creates new device-refresh triggers across earbuds, headphones, phones, TVs and public audio venues. The commercial response is therefore visible in product road maps, qualification strategy and channel positioning, which determines whether the factor expands total addressable demand or simply redistributes share among existing suppliers.

Gaming, work and multi-device use

Low-latency gaming, video calls and laptop use broaden daily wearing time. Qualcomm’s 2025 State of Sound work found battery life, comfort and sound quality among the top purchase criteria for wireless audio used with laptops. The commercial response is therefore visible in product road maps, qualification strategy and channel positioning, which determines whether the factor expands total addressable demand or simply redistributes share among existing suppliers.

MARKET RESTRAINTS

Restraints Impact Analysis*

Factor Directional impact Geographic relevance Impact timeline
Severe price competition High Global with strongest relevance in North America 2026–2034
Battery aging and small-form-factor limits High Global with strongest relevance in North America 2026–2034
Hearing-health concerns Medium Global with strongest relevance in North America 2026–2034
Platform fragmentation Medium Global with strongest relevance in North America 2026–2034

Severe price competition

TWS manufacturing scale and low entry barriers have produced dense competition at entry and mid tiers, limiting margins for brands that cannot differentiate through software, ecosystem integration or acoustic quality. The commercial response is therefore visible in product road maps, qualification strategy and channel positioning, which determines whether the factor expands total addressable demand or simply redistributes share among existing suppliers.

Battery aging and small-form-factor limits

Tiny cells, thermal constraints and charging cycles limit product lifespan and create tension between stronger ANC, AI processing and longer runtime. The commercial response is therefore visible in product road maps, qualification strategy and channel positioning, which determines whether the factor expands total addressable demand or simply redistributes share among existing suppliers.

Hearing-health concerns

WHO states that more than one billion people aged 12–35 are at risk of hearing loss from recreational loud-sound exposure, increasing pressure for safer listening features and user controls. The commercial response is therefore visible in product road maps, qualification strategy and channel positioning, which determines whether the factor expands total addressable demand or simply redistributes share among existing suppliers.

Platform fragmentation

Codec, multipoint, operating-system and spatial-audio differences can prevent a feature from working consistently across devices, increasing software validation cost and weakening cross-platform value. The commercial response is therefore visible in product road maps, qualification strategy and channel positioning, which determines whether the factor expands total addressable demand or simply redistributes share among existing suppliers.

MARKET OPPORTUNITIES

Health-sensing earbuds

Apple added heart-rate sensing to AirPods Pro 3, demonstrating how earbuds can expand from audio accessories into wearable sensing platforms. The commercial response is therefore visible in product road maps, qualification strategy and channel positioning, which determines whether the factor expands total addressable demand or simply redistributes share among existing suppliers.

Wi-Fi extended-range audio

Qualcomm’s XPAN implementation in Xiaomi Buds 5 Pro extends earbud connectivity beyond conventional Bluetooth range through Wi-Fi, creating new premium use cases. The commercial response is therefore visible in product road maps, qualification strategy and channel positioning, which determines whether the factor expands total addressable demand or simply redistributes share among existing suppliers.

LE Audio accessibility

Auracast and the Bluetooth Hearing Access Profile create pathways for personal audio products to interact with broadcast and assistive-listening systems. The commercial response is therefore visible in product road maps, qualification strategy and channel positioning, which determines whether the factor expands total addressable demand or simply redistributes share among existing suppliers.

AI-enhanced voice and personalization

On-device AI for call cleanup, adaptive sound, hearing compensation and context-aware ANC gives semiconductor and software suppliers new differentiation layers. The commercial response is therefore visible in product road maps, qualification strategy and channel positioning, which determines whether the factor expands total addressable demand or simply redistributes share among existing suppliers.

Earphones and Headphones Supply Chain Analysis

Components

Audio SoCs, Bluetooth radios, MEMS microphones, speakers, batteries, PCBs and plastics determine core performance and cost.

Module & Assembly

TWS and headphone assembly integrates acoustic chambers, RF antennas, batteries, charging interfaces and firmware calibration.

Brand & Platform

Brands control industrial design, acoustic tuning, apps, ecosystem functions, marketing and channel strategy.

Distribution & User

E-commerce, electronics retail, telecom channels and direct stores convert feature differentiation into consumer sell-through.

Components: Audio SoCs, Bluetooth radios, MEMS microphones, speakers, batteries, PCBs and plastics determine core performance and cost. Value capture at this stage depends on the ability to solve a bottleneck that downstream customers cannot easily substitute, so qualification, yield, intellectual property, logistics and support all influence bargaining power.

Module & Assembly: TWS and headphone assembly integrates acoustic chambers, RF antennas, batteries, charging interfaces and firmware calibration. Value capture at this stage depends on the ability to solve a bottleneck that downstream customers cannot easily substitute, so qualification, yield, intellectual property, logistics and support all influence bargaining power.

Brand & Platform: Brands control industrial design, acoustic tuning, apps, ecosystem functions, marketing and channel strategy. Value capture at this stage depends on the ability to solve a bottleneck that downstream customers cannot easily substitute, so qualification, yield, intellectual property, logistics and support all influence bargaining power.

Distribution & User: E-commerce, electronics retail, telecom channels and direct stores convert feature differentiation into consumer sell-through. Value capture at this stage depends on the ability to solve a bottleneck that downstream customers cannot easily substitute, so qualification, yield, intellectual property, logistics and support all influence bargaining power.

Recent Developments in the Earphones and Headphones Market

2025-09 – Apple introduced AirPods Pro 3 with stronger active noise cancellation, improved fit, heart-rate sensing during workouts and longer battery life, showing continued premiumization of the TWS category. Source
2025-06 – Qualcomm highlighted Xiaomi Buds 5 Pro as the first earbuds using its XPAN approach to extend Snapdragon Sound connectivity over Wi-Fi, expanding the range and use cases of wireless earbuds. Source
2025-02 – Bluetooth SIG published updated guidance on LE Audio and Auracast, reflecting the transition toward lower-power audio, broadcast use cases and new interoperability profiles. Source
2025-01 – Bluetooth SIG released the second edition of its LE Audio guide with expanded material on real-world implementations, broadcast audio and gaming profiles. Source

REPORT SCOPE & SEGMENTATION

Attribute Details
Study Period 2021–2034
Base Year 2025
Estimated Year 2026
Forecast Period 2026–2034
Historical Period 2021–2025
Market Size 2025 USD 39.93 billion
Market Size 2034 USD 105.35 billion
Growth Rate CAGR of 11.4% from 2026–2034
Unit Value (USD Million/Billion) and Volume (Units/Thousand Units where applicable)
Segmentation By Type, By Application, By Region
By Type In-Ear · Headphone
By Application Residential · Commercial
By Region Each region analysed by Type, Application and Country
North AmericaUnited States, Canada, Mexico
EuropeGermany, France, U.K., Italy, Russia, Rest of Europe
Asia PacificChina, Japan, South Korea, India, Southeast Asia, Rest of Asia Pacific
South AmericaBrazil, Argentina, Colombia, Rest of South America
Middle East & AfricaSaudi Arabia, UAE, Egypt, Nigeria, South Africa, Rest of MEA
Key Companies Profiled Sennheiser · Sony · Shure · JVC · Skullcandy · Philips · Bose · Beats Electronics · Audio-Technica · Samsung (Harman Kardon) · AKG · Logitech · Monster · Klipsch · Apple · Huawei · Xiaomi
Customization Scope Free report customization equivalent to up to four analyst working days with purchase. Addition or alteration to country, regional and segment scope.

Frequently Asked Questions

What is the current size of the market?

Earphones and Headphones market is valued at USD 39.93 billion in 2025 and is projected to reach USD 105.35 billion by 2034. The rebased series implies a 11.4% CAGR during 2026–2034. The forecast is anchored to the two published market-size values on the source report page and then normalized to the requested 2025 base and 2034 endpoint.

Which product type leads the market?

In-Ear / TWS holds the leading type position in the source-defined segmentation. Its advantage reflects the balance of installed-base demand, performance requirements, design familiarity and supplier availability. In-Ear / TWS has the strongest structural growth case because newer systems place greater emphasis on integration, efficiency, advanced features or performance that expands value per unit.

Which application is most important?

Residential is the largest current application position, while Gaming & Smart Audio is the most important incremental growth channel. Application growth is not only about shipment volume: it also reflects rising content, more demanding technical specifications, stronger qualification requirements and a greater need for system-level support from component or product suppliers.

Which market or region leads in 2025?

United States holds the strongest market position in 2025 within the available source evidence, while North America has the most important regional role in the broader competitive structure. Leadership is supported by a combination of downstream demand, manufacturing capacity, design activity, channel depth and faster adoption of newer product generations.

What is the estimated market size in 2026?

The normalized 2026 estimate is USD 44.48 billion. This value sits between the 2025 base of USD 39.93 billion and the 2034 forecast of USD 105.35 billion, using the same constant annual growth factor implied by the report page’s published market-size anchors. That keeps the series internally consistent across all headline figures.

What are the main growth drivers?

The principal growth drivers are technology upgrade cycles, broader downstream adoption, rising system complexity and expanding demand in Gaming & Smart Audio. These forces increase either the number of products required, the technical value of each product, or both. Suppliers benefit most when they convert those requirements into qualified platforms that are difficult for customers to replace after design-in.

What are the main restraints?

Key restraints include qualification cost, product or software migration effort, price competition, supply-chain volatility and the engineering complexity of adopting newer architectures. These factors do not eliminate demand, but they can slow design conversion, compress margins or extend customer validation cycles. The result is a market where execution quality matters as much as end-market growth.

How is competition changing?

Competition is moving from individual product specifications toward complete application platforms. Leading suppliers increasingly combine hardware performance with reference designs, software, development tools, certification support, lifecycle management and distribution. This raises switching costs and makes early design engagement more important because a supplier that wins the architecture can retain revenue across several years of production.

What is the most important opportunity through 2034?

The strongest opportunity is the transition toward higher-value products that solve system-level constraints in Gaming & Smart Audio and other performance-sensitive applications. These products can command better pricing because they reduce engineering risk, power consumption, space, integration time or compliance burden. The opportunity therefore favors suppliers that invest in application-specific innovation rather than relying on commodity volume alone.

What period and segmentation does the report cover?

The normalized analysis uses 2025 as the base year, 2026 as the estimated year and 2034 as the forecast endpoint. The source-defined scope covers the listed type and application segments, regional markets across North America, Europe, Asia Pacific, South America, and Middle East & Africa, plus the full company list reproduced in the Report Scope & Segmentation table.

Research Sources & Evidence Base

View primary and industry evidence sources
  1. Bluetooth SIG. 2024 Bluetooth Market Update – Earbud shipment forecasts, LE Audio and Auracast adoption evidence.
  2. Bluetooth SIG. Bluetooth Market Update 2025 – Bluetooth device and technology-roadmap evidence.
  3. World Health Organization. Making Listening Safe – Hearing-health risk and safe-listening standards.
  4. World Health Organization. WHO-ITU standard for safe listening devices and systems – Recommended safe-listening device features.
  5. Apple. AirPods Pro 3 announcement – Premium TWS feature and health-sensing development.
  6. Qualcomm. Snapdragon Sound Technology Suite – Lossless, low-latency, AI and XPAN audio platform evidence.
  7. Qualcomm. State of Sound 2025 – Wireless-audio usage and consumer purchase criteria.
Global Earphones and Headphones Market, Trends, Business Strategies 2026-2034

Get Sample Report PDF for Exclusive Insights

Report Sample Includes

  • Table of Contents
  • List of Tables & Figures
  • Charts, Research Methodology, and more...

PDF Icon Download Sample Report PDF

Download Sample Report

Table of Content

Table of Contents
1 Research Methodology and Statistical Scope
1.1 Market Definition and Statistical Scope of Earphones and Headphones
1.2 Key Market Segments
1.2.1 Earphones and Headphones Segment by Type
1.2.2 Earphones and Headphones Segment by Application
1.3 Methodology & Sources of Information
1.3.1 Research Methodology
1.3.2 Research Process
1.3.3 Market Breakdown and Data Triangulation
1.3.4 Base Year
1.3.5 Report Assumptions & Caveats
2 Earphones and Headphones Market Overview
2.1 Global Market Overview
2.1.1 Global Earphones and Headphones Market Size (M USD) Estimates and Forecasts (2019-2030)
2.1.2 Global Earphones and Headphones Sales Estimates and Forecasts (2019-2030)
2.2 Market Segment Executive Summary
2.3 Global Market Size by Region
3 Earphones and Headphones Market Competitive Landscape
3.1 Global Earphones and Headphones Sales by Manufacturers (2019-2024)
3.2 Global Earphones and Headphones Revenue Market Share by Manufacturers (2019-2024)
3.3 Earphones and Headphones Market Share by Company Type (Tier 1, Tier 2, and Tier 3)
3.4 Global Earphones and Headphones Average Price by Manufacturers (2019-2024)
3.5 Manufacturers Earphones and Headphones Sales Sites, Area Served, Product Type
3.6 Earphones and Headphones Market Competitive Situation and Trends
3.6.1 Earphones and Headphones Market Concentration Rate
3.6.2 Global 5 and 10 Largest Earphones and Headphones Players Market Share by Revenue
3.6.3 Mergers & Acquisitions, Expansion
4 Earphones and Headphones Industry Chain Analysis
4.1 Earphones and Headphones Industry Chain Analysis
4.2 Market Overview of Key Raw Materials
4.3 Midstream Market Analysis
4.4 Downstream Customer Analysis
5 The Development and Dynamics of Earphones and Headphones Market
5.1 Key Development Trends
5.2 Driving Factors
5.3 Market Challenges
5.4 Market Restraints
5.5 Industry News
5.5.1 New Product Developments
5.5.2 Mergers & Acquisitions
5.5.3 Expansions
5.5.4 Collaboration/Supply Contracts
5.6 Industry Policies
6 Earphones and Headphones Market Segmentation by Type
6.1 Evaluation Matrix of Segment Market Development Potential (Type)
6.2 Global Earphones and Headphones Sales Market Share by Type (2019-2024)
6.3 Global Earphones and Headphones Market Size Market Share by Type (2019-2024)
6.4 Global Earphones and Headphones Price by Type (2019-2024)
7 Earphones and Headphones Market Segmentation by Application
7.1 Evaluation Matrix of Segment Market Development Potential (Application)
7.2 Global Earphones and Headphones Market Sales by Application (2019-2024)
7.3 Global Earphones and Headphones Market Size (M USD) by Application (2019-2024)
7.4 Global Earphones and Headphones Sales Growth Rate by Application (2019-2024)
8 Earphones and Headphones Market Segmentation by Region
8.1 Global Earphones and Headphones Sales by Region
8.1.1 Global Earphones and Headphones Sales by Region
8.1.2 Global Earphones and Headphones Sales Market Share by Region
8.2 North America
8.2.1 North America Earphones and Headphones Sales by Country
8.2.2 U.S.
8.2.3 Canada
8.2.4 Mexico
8.3 Europe
8.3.1 Europe Earphones and Headphones Sales by Country
8.3.2 Germany
8.3.3 France
8.3.4 U.K.
8.3.5 Italy
8.3.6 Russia
8.4 Asia Pacific
8.4.1 Asia Pacific Earphones and Headphones Sales by Region
8.4.2 China
8.4.3 Japan
8.4.4 South Korea
8.4.5 India
8.4.6 Southeast Asia
8.5 South America
8.5.1 South America Earphones and Headphones Sales by Country
8.5.2 Brazil
8.5.3 Argentina
8.5.4 Columbia
8.6 Middle East and Africa
8.6.1 Middle East and Africa Earphones and Headphones Sales by Region
8.6.2 Saudi Arabia
8.6.3 UAE
8.6.4 Egypt
8.6.5 Nigeria
8.6.6 South Africa
9 Key Companies Profile
9.1 Sennheiser
9.1.1 Sennheiser Earphones and Headphones Basic Information
9.1.2 Sennheiser Earphones and Headphones Product Overview
9.1.3 Sennheiser Earphones and Headphones Product Market Performance
9.1.4 Sennheiser Business Overview
9.1.5 Sennheiser Earphones and Headphones SWOT Analysis
9.1.6 Sennheiser Recent Developments
9.2 Sony
9.2.1 Sony Earphones and Headphones Basic Information
9.2.2 Sony Earphones and Headphones Product Overview
9.2.3 Sony Earphones and Headphones Product Market Performance
9.2.4 Sony Business Overview
9.2.5 Sony Earphones and Headphones SWOT Analysis
9.2.6 Sony Recent Developments
9.3 Shure
9.3.1 Shure Earphones and Headphones Basic Information
9.3.2 Shure Earphones and Headphones Product Overview
9.3.3 Shure Earphones and Headphones Product Market Performance
9.3.4 Shure Earphones and Headphones SWOT Analysis
9.3.5 Shure Business Overview
9.3.6 Shure Recent Developments
9.4 JVC
9.4.1 JVC Earphones and Headphones Basic Information
9.4.2 JVC Earphones and Headphones Product Overview
9.4.3 JVC Earphones and Headphones Product Market Performance
9.4.4 JVC Business Overview
9.4.5 JVC Recent Developments
9.5 Skullcandy
9.5.1 Skullcandy Earphones and Headphones Basic Information
9.5.2 Skullcandy Earphones and Headphones Product Overview
9.5.3 Skullcandy Earphones and Headphones Product Market Performance
9.5.4 Skullcandy Business Overview
9.5.5 Skullcandy Recent Developments
9.6 Philips
9.6.1 Philips Earphones and Headphones Basic Information
9.6.2 Philips Earphones and Headphones Product Overview
9.6.3 Philips Earphones and Headphones Product Market Performance
9.6.4 Philips Business Overview
9.6.5 Philips Recent Developments
9.7 Bose
9.7.1 Bose Earphones and Headphones Basic Information
9.7.2 Bose Earphones and Headphones Product Overview
9.7.3 Bose Earphones and Headphones Product Market Performance
9.7.4 Bose Business Overview
9.7.5 Bose Recent Developments
9.8 Beats Electronics
9.8.1 Beats Electronics Earphones and Headphones Basic Information
9.8.2 Beats Electronics Earphones and Headphones Product Overview
9.8.3 Beats Electronics Earphones and Headphones Product Market Performance
9.8.4 Beats Electronics Business Overview
9.8.5 Beats Electronics Recent Developments
9.9 Audio-Technica
9.9.1 Audio-Technica Earphones and Headphones Basic Information
9.9.2 Audio-Technica Earphones and Headphones Product Overview
9.9.3 Audio-Technica Earphones and Headphones Product Market Performance
9.9.4 Audio-Technica Business Overview
9.9.5 Audio-Technica Recent Developments
9.10 Samsung(Harman Kardon)
9.10.1 Samsung(Harman Kardon) Earphones and Headphones Basic Information
9.10.2 Samsung(Harman Kardon) Earphones and Headphones Product Overview
9.10.3 Samsung(Harman Kardon) Earphones and Headphones Product Market Performance
9.10.4 Samsung(Harman Kardon) Business Overview
9.10.5 Samsung(Harman Kardon) Recent Developments
9.11 AKG
9.11.1 AKG Earphones and Headphones Basic Information
9.11.2 AKG Earphones and Headphones Product Overview
9.11.3 AKG Earphones and Headphones Product Market Performance
9.11.4 AKG Business Overview
9.11.5 AKG Recent Developments
9.12 Logitec
9.12.1 Logitec Earphones and Headphones Basic Information
9.12.2 Logitec Earphones and Headphones Product Overview
9.12.3 Logitec Earphones and Headphones Product Market Performance
9.12.4 Logitec Business Overview
9.12.5 Logitec Recent Developments
9.13 Monster
9.13.1 Monster Earphones and Headphones Basic Information
9.13.2 Monster Earphones and Headphones Product Overview
9.13.3 Monster Earphones and Headphones Product Market Performance
9.13.4 Monster Business Overview
9.13.5 Monster Recent Developments
9.14 Klipsch
9.14.1 Klipsch Earphones and Headphones Basic Information
9.14.2 Klipsch Earphones and Headphones Product Overview
9.14.3 Klipsch Earphones and Headphones Product Market Performance
9.14.4 Klipsch Business Overview
9.14.5 Klipsch Recent Developments
9.15 Apple
9.15.1 Apple Earphones and Headphones Basic Information
9.15.2 Apple Earphones and Headphones Product Overview
9.15.3 Apple Earphones and Headphones Product Market Performance
9.15.4 Apple Business Overview
9.15.5 Apple Recent Developments
9.16 Huawei
9.16.1 Huawei Earphones and Headphones Basic Information
9.16.2 Huawei Earphones and Headphones Product Overview
9.16.3 Huawei Earphones and Headphones Product Market Performance
9.16.4 Huawei Business Overview
9.16.5 Huawei Recent Developments
9.17 Xiaomi
9.17.1 Xiaomi Earphones and Headphones Basic Information
9.17.2 Xiaomi Earphones and Headphones Product Overview
9.17.3 Xiaomi Earphones and Headphones Product Market Performance
9.17.4 Xiaomi Business Overview
9.17.5 Xiaomi Recent Developments
10 Earphones and Headphones Market Forecast by Region
10.1 Global Earphones and Headphones Market Size Forecast
10.2 Global Earphones and Headphones Market Forecast by Region
10.2.1 North America Market Size Forecast by Country
10.2.2 Europe Earphones and Headphones Market Size Forecast by Country
10.2.3 Asia Pacific Earphones and Headphones Market Size Forecast by Region
10.2.4 South America Earphones and Headphones Market Size Forecast by Country
10.2.5 Middle East and Africa Forecasted Consumption of Earphones and Headphones by Country
11 Forecast Market by Type and by Application (2025-2030)
11.1 Global Earphones and Headphones Market Forecast by Type (2025-2030)
11.1.1 Global Forecasted Sales of Earphones and Headphones by Type (2025-2030)
11.1.2 Global Earphones and Headphones Market Size Forecast by Type (2025-2030)
11.1.3 Global Forecasted Price of Earphones and Headphones by Type (2025-2030)
11.2 Global Earphones and Headphones Market Forecast by Application (2025-2030)
11.2.1 Global Earphones and Headphones Sales (K Units) Forecast by Application
11.2.2 Global Earphones and Headphones Market Size (M USD) Forecast by Application (2025-2030)
12 Conclusion and Key FindingsList of Tables
Table 1. Introduction of the Type
Table 2. Introduction of the Application
Table 3. Market Size (M USD) Segment Executive Summary
Table 4. Earphones and Headphones Market Size Comparison by Region (M USD)
Table 5. Global Earphones and Headphones Sales (K Units) by Manufacturers (2019-2024)
Table 6. Global Earphones and Headphones Sales Market Share by Manufacturers (2019-2024)
Table 7. Global Earphones and Headphones Revenue (M USD) by Manufacturers (2019-2024)
Table 8. Global Earphones and Headphones Revenue Share by Manufacturers (2019-2024)
Table 9. Company Type (Tier 1, Tier 2, and Tier 3) & (based on the Revenue in Earphones and Headphones as of 2022)
Table 10. Global Market Earphones and Headphones Average Price (USD/Unit) of Key Manufacturers (2019-2024)
Table 11. Manufacturers Earphones and Headphones Sales Sites and Area Served
Table 12. Manufacturers Earphones and Headphones Product Type
Table 13. Global Earphones and Headphones Manufacturers Market Concentration Ratio (CR5 and HHI)
Table 14. Mergers & Acquisitions, Expansion Plans
Table 15. Industry Chain Map of Earphones and Headphones
Table 16. Market Overview of Key Raw Materials
Table 17. Midstream Market Analysis
Table 18. Downstream Customer Analysis
Table 19. Key Development Trends
Table 20. Driving Factors
Table 21. Earphones and Headphones Market Challenges
Table 22. Global Earphones and Headphones Sales by Type (K Units)
Table 23. Global Earphones and Headphones Market Size by Type (M USD)
Table 24. Global Earphones and Headphones Sales (K Units) by Type (2019-2024)
Table 25. Global Earphones and Headphones Sales Market Share by Type (2019-2024)
Table 26. Global Earphones and Headphones Market Size (M USD) by Type (2019-2024)
Table 27. Global Earphones and Headphones Market Size Share by Type (2019-2024)
Table 28. Global Earphones and Headphones Price (USD/Unit) by Type (2019-2024)
Table 29. Global Earphones and Headphones Sales (K Units) by Application
Table 30. Global Earphones and Headphones Market Size by Application
Table 31. Global Earphones and Headphones Sales by Application (2019-2024) & (K Units)
Table 32. Global Earphones and Headphones Sales Market Share by Application (2019-2024)
Table 33. Global Earphones and Headphones Sales by Application (2019-2024) & (M USD)
Table 34. Global Earphones and Headphones Market Share by Application (2019-2024)
Table 35. Global Earphones and Headphones Sales Growth Rate by Application (2019-2024)
Table 36. Global Earphones and Headphones Sales by Region (2019-2024) & (K Units)
Table 37. Global Earphones and Headphones Sales Market Share by Region (2019-2024)
Table 38. North America Earphones and Headphones Sales by Country (2019-2024) & (K Units)
Table 39. Europe Earphones and Headphones Sales by Country (2019-2024) & (K Units)
Table 40. Asia Pacific Earphones and Headphones Sales by Region (2019-2024) & (K Units)
Table 41. South America Earphones and Headphones Sales by Country (2019-2024) & (K Units)
Table 42. Middle East and Africa Earphones and Headphones Sales by Region (2019-2024) & (K Units)
Table 43. Sennheiser Earphones and Headphones Basic Information
Table 44. Sennheiser Earphones and Headphones Product Overview
Table 45. Sennheiser Earphones and Headphones Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2024)
Table 46. Sennheiser Business Overview
Table 47. Sennheiser Earphones and Headphones SWOT Analysis
Table 48. Sennheiser Recent Developments
Table 49. Sony Earphones and Headphones Basic Information
Table 50. Sony Earphones and Headphones Product Overview
Table 51. Sony Earphones and Headphones Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2024)
Table 52. Sony Business Overview
Table 53. Sony Earphones and Headphones SWOT Analysis
Table 54. Sony Recent Developments
Table 55. Shure Earphones and Headphones Basic Information
Table 56. Shure Earphones and Headphones Product Overview
Table 57. Shure Earphones and Headphones Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2024)
Table 58. Shure Earphones and Headphones SWOT Analysis
Table 59. Shure Business Overview
Table 60. Shure Recent Developments
Table 61. JVC Earphones and Headphones Basic Information
Table 62. JVC Earphones and Headphones Product Overview
Table 63. JVC Earphones and Headphones Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2024)
Table 64. JVC Business Overview
Table 65. JVC Recent Developments
Table 66. Skullcandy Earphones and Headphones Basic Information
Table 67. Skullcandy Earphones and Headphones Product Overview
Table 68. Skullcandy Earphones and Headphones Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2024)
Table 69. Skullcandy Business Overview
Table 70. Skullcandy Recent Developments
Table 71. Philips Earphones and Headphones Basic Information
Table 72. Philips Earphones and Headphones Product Overview
Table 73. Philips Earphones and Headphones Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2024)
Table 74. Philips Business Overview
Table 75. Philips Recent Developments
Table 76. Bose Earphones and Headphones Basic Information
Table 77. Bose Earphones and Headphones Product Overview
Table 78. Bose Earphones and Headphones Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2024)
Table 79. Bose Business Overview
Table 80. Bose Recent Developments
Table 81. Beats Electronics Earphones and Headphones Basic Information
Table 82. Beats Electronics Earphones and Headphones Product Overview
Table 83. Beats Electronics Earphones and Headphones Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2024)
Table 84. Beats Electronics Business Overview
Table 85. Beats Electronics Recent Developments
Table 86. Audio-Technica Earphones and Headphones Basic Information
Table 87. Audio-Technica Earphones and Headphones Product Overview
Table 88. Audio-Technica Earphones and Headphones Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2024)
Table 89. Audio-Technica Business Overview
Table 90. Audio-Technica Recent Developments
Table 91. Samsung(Harman Kardon) Earphones and Headphones Basic Information
Table 92. Samsung(Harman Kardon) Earphones and Headphones Product Overview
Table 93. Samsung(Harman Kardon) Earphones and Headphones Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2024)
Table 94. Samsung(Harman Kardon) Business Overview
Table 95. Samsung(Harman Kardon) Recent Developments
Table 96. AKG Earphones and Headphones Basic Information
Table 97. AKG Earphones and Headphones Product Overview
Table 98. AKG Earphones and Headphones Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2024)
Table 99. AKG Business Overview
Table 100. AKG Recent Developments
Table 101. Logitec Earphones and Headphones Basic Information
Table 102. Logitec Earphones and Headphones Product Overview
Table 103. Logitec Earphones and Headphones Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2024)
Table 104. Logitec Business Overview
Table 105. Logitec Recent Developments
Table 106. Monster Earphones and Headphones Basic Information
Table 107. Monster Earphones and Headphones Product Overview
Table 108. Monster Earphones and Headphones Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2024)
Table 109. Monster Business Overview
Table 110. Monster Recent Developments
Table 111. Klipsch Earphones and Headphones Basic Information
Table 112. Klipsch Earphones and Headphones Product Overview
Table 113. Klipsch Earphones and Headphones Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2024)
Table 114. Klipsch Business Overview
Table 115. Klipsch Recent Developments
Table 116. Apple Earphones and Headphones Basic Information
Table 117. Apple Earphones and Headphones Product Overview
Table 118. Apple Earphones and Headphones Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2024)
Table 119. Apple Business Overview
Table 120. Apple Recent Developments
Table 121. Huawei Earphones and Headphones Basic Information
Table 122. Huawei Earphones and Headphones Product Overview
Table 123. Huawei Earphones and Headphones Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2024)
Table 124. Huawei Business Overview
Table 125. Huawei Recent Developments
Table 126. Xiaomi Earphones and Headphones Basic Information
Table 127. Xiaomi Earphones and Headphones Product Overview
Table 128. Xiaomi Earphones and Headphones Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2024)
Table 129. Xiaomi Business Overview
Table 130. Xiaomi Recent Developments
Table 131. Global Earphones and Headphones Sales Forecast by Region (2025-2030) & (K Units)
Table 132. Global Earphones and Headphones Market Size Forecast by Region (2025-2030) & (M USD)
Table 133. North America Earphones and Headphones Sales Forecast by Country (2025-2030) & (K Units)
Table 134. North America Earphones and Headphones Market Size Forecast by Country (2025-2030) & (M USD)
Table 135. Europe Earphones and Headphones Sales Forecast by Country (2025-2030) & (K Units)
Table 136. Europe Earphones and Headphones Market Size Forecast by Country (2025-2030) & (M USD)
Table 137. Asia Pacific Earphones and Headphones Sales Forecast by Region (2025-2030) & (K Units)
Table 138. Asia Pacific Earphones and Headphones Market Size Forecast by Region (2025-2030) & (M USD)
Table 139. South America Earphones and Headphones Sales Forecast by Country (2025-2030) & (K Units)
Table 140. South America Earphones and Headphones Market Size Forecast by Country (2025-2030) & (M USD)
Table 141. Middle East and Africa Earphones and Headphones Consumption Forecast by Country (2025-2030) & (Units)
Table 142. Middle East and Africa Earphones and Headphones Market Size Forecast by Country (2025-2030) & (M USD)
Table 143. Global Earphones and Headphones Sales Forecast by Type (2025-2030) & (K Units)
Table 144. Global Earphones and Headphones Market Size Forecast by Type (2025-2030) & (M USD)
Table 145. Global Earphones and Headphones Price Forecast by Type (2025-2030) & (USD/Unit)
Table 146. Global Earphones and Headphones Sales (K Units) Forecast by Application (2025-2030)
Table 147. Global Earphones and Headphones Market Size Forecast by Application (2025-2030) & (M USD)
List of Figures
Figure 1. Product Picture of Earphones and Headphones
Figure 2. Data Triangulation
Figure 3. Key Caveats
Figure 4. Global Earphones and Headphones Market Size (M USD), 2019-2030
Figure 5. Global Earphones and Headphones Market Size (M USD) (2019-2030)
Figure 6. Global Earphones and Headphones Sales (K Units) & (2019-2030)
Figure 7. Evaluation Matrix of Segment Market Development Potential (Type)
Figure 8. Evaluation Matrix of Segment Market Development Potential (Application)
Figure 9. Evaluation Matrix of Regional Market Development Potential
Figure 10. Earphones and Headphones Market Size by Country (M USD)
Figure 11. Earphones and Headphones Sales Share by Manufacturers in 2023
Figure 12. Global Earphones and Headphones Revenue Share by Manufacturers in 2023
Figure 13. Earphones and Headphones Market Share by Company Type (Tier 1, Tier 2 and Tier 3): 2023
Figure 14. Global Market Earphones and Headphones Average Price (USD/Unit) of Key Manufacturers in 2023
Figure 15. The Global 5 and 10 Largest Players: Market Share by Earphones and Headphones Revenue in 2023
Figure 16. Evaluation Matrix of Segment Market Development Potential (Type)
Figure 17. Global Earphones and Headphones Market Share by Type
Figure 18. Sales Market Share of Earphones and Headphones by Type (2019-2024)
Figure 19. Sales Market Share of Earphones and Headphones by Type in 2023
Figure 20. Market Size Share of Earphones and Headphones by Type (2019-2024)
Figure 21. Market Size Market Share of Earphones and Headphones by Type in 2023
Figure 22. Evaluation Matrix of Segment Market Development Potential (Application)
Figure 23. Global Earphones and Headphones Market Share by Application
Figure 24. Global Earphones and Headphones Sales Market Share by Application (2019-2024)
Figure 25. Global Earphones and Headphones Sales Market Share by Application in 2023
Figure 26. Global Earphones and Headphones Market Share by Application (2019-2024)
Figure 27. Global Earphones and Headphones Market Share by Application in 2023
Figure 28. Global Earphones and Headphones Sales Growth Rate by Application (2019-2024)
Figure 29. Global Earphones and Headphones Sales Market Share by Region (2019-2024)
Figure 30. North America Earphones and Headphones Sales and Growth Rate (2019-2024) & (K Units)
Figure 31. North America Earphones and Headphones Sales Market Share by Country in 2023
Figure 32. U.S. Earphones and Headphones Sales and Growth Rate (2019-2024) & (K Units)
Figure 33. Canada Earphones and Headphones Sales (K Units) and Growth Rate (2019-2024)
Figure 34. Mexico Earphones and Headphones Sales (Units) and Growth Rate (2019-2024)
Figure 35. Europe Earphones and Headphones Sales and Growth Rate (2019-2024) & (K Units)
Figure 36. Europe Earphones and Headphones Sales Market Share by Country in 2023
Figure 37. Germany Earphones and Headphones Sales and Growth Rate (2019-2024) & (K Units)
Figure 38. France Earphones and Headphones Sales and Growth Rate (2019-2024) & (K Units)
Figure 39. U.K. Earphones and Headphones Sales and Growth Rate (2019-2024) & (K Units)
Figure 40. Italy Earphones and Headphones Sales and Growth Rate (2019-2024) & (K Units)
Figure 41. Russia Earphones and Headphones Sales and Growth Rate (2019-2024) & (K Units)
Figure 42. Asia Pacific Earphones and Headphones Sales and Growth Rate (K Units)
Figure 43. Asia Pacific Earphones and Headphones Sales Market Share by Region in 2023
Figure 44. China Earphones and Headphones Sales and Growth Rate (2019-2024) & (K Units)
Figure 45. Japan Earphones and Headphones Sales and Growth Rate (2019-2024) & (K Units)
Figure 46. South Korea Earphones and Headphones Sales and Growth Rate (2019-2024) & (K Units)
Figure 47. India Earphones and Headphones Sales and Growth Rate (2019-2024) & (K Units)
Figure 48. Southeast Asia Earphones and Headphones Sales and Growth Rate (2019-2024) & (K Units)
Figure 49. South America Earphones and Headphones Sales and Growth Rate (K Units)
Figure 50. South America Earphones and Headphones Sales Market Share by Country in 2023
Figure 51. Brazil Earphones and Headphones Sales and Growth Rate (2019-2024) & (K Units)
Figure 52. Argentina Earphones and Headphones Sales and Growth Rate (2019-2024) & (K Units)
Figure 53. Columbia Earphones and Headphones Sales and Growth Rate (2019-2024) & (K Units)
Figure 54. Middle East and Africa Earphones and Headphones Sales and Growth Rate (K Units)
Figure 55. Middle East and Africa Earphones and Headphones Sales Market Share by Region in 2023
Figure 56. Saudi Arabia Earphones and Headphones Sales and Growth Rate (2019-2024) & (K Units)
Figure 57. UAE Earphones and Headphones Sales and Growth Rate (2019-2024) & (K Units)
Figure 58. Egypt Earphones and Headphones Sales and Growth Rate (2019-2024) & (K Units)
Figure 59. Nigeria Earphones and Headphones Sales and Growth Rate (2019-2024) & (K Units)
Figure 60. South Africa Earphones and Headphones Sales and Growth Rate (2019-2024) & (K Units)
Figure 61. Global Earphones and Headphones Sales Forecast by Volume (2019-2030) & (K Units)
Figure 62. Global Earphones and Headphones Market Size Forecast by Value (2019-2030) & (M USD)
Figure 63. Global Earphones and Headphones Sales Market Share Forecast by Type (2025-2030)
Figure 64. Global Earphones and Headphones Market Share Forecast by Type (2025-2030)
Figure 65. Global Earphones and Headphones Sales Forecast by Application (2025-2030)
Figure 66. Global Earphones and Headphones Market Share Forecast by Application (2025-2030)