Key Statistics
Key Takeaways
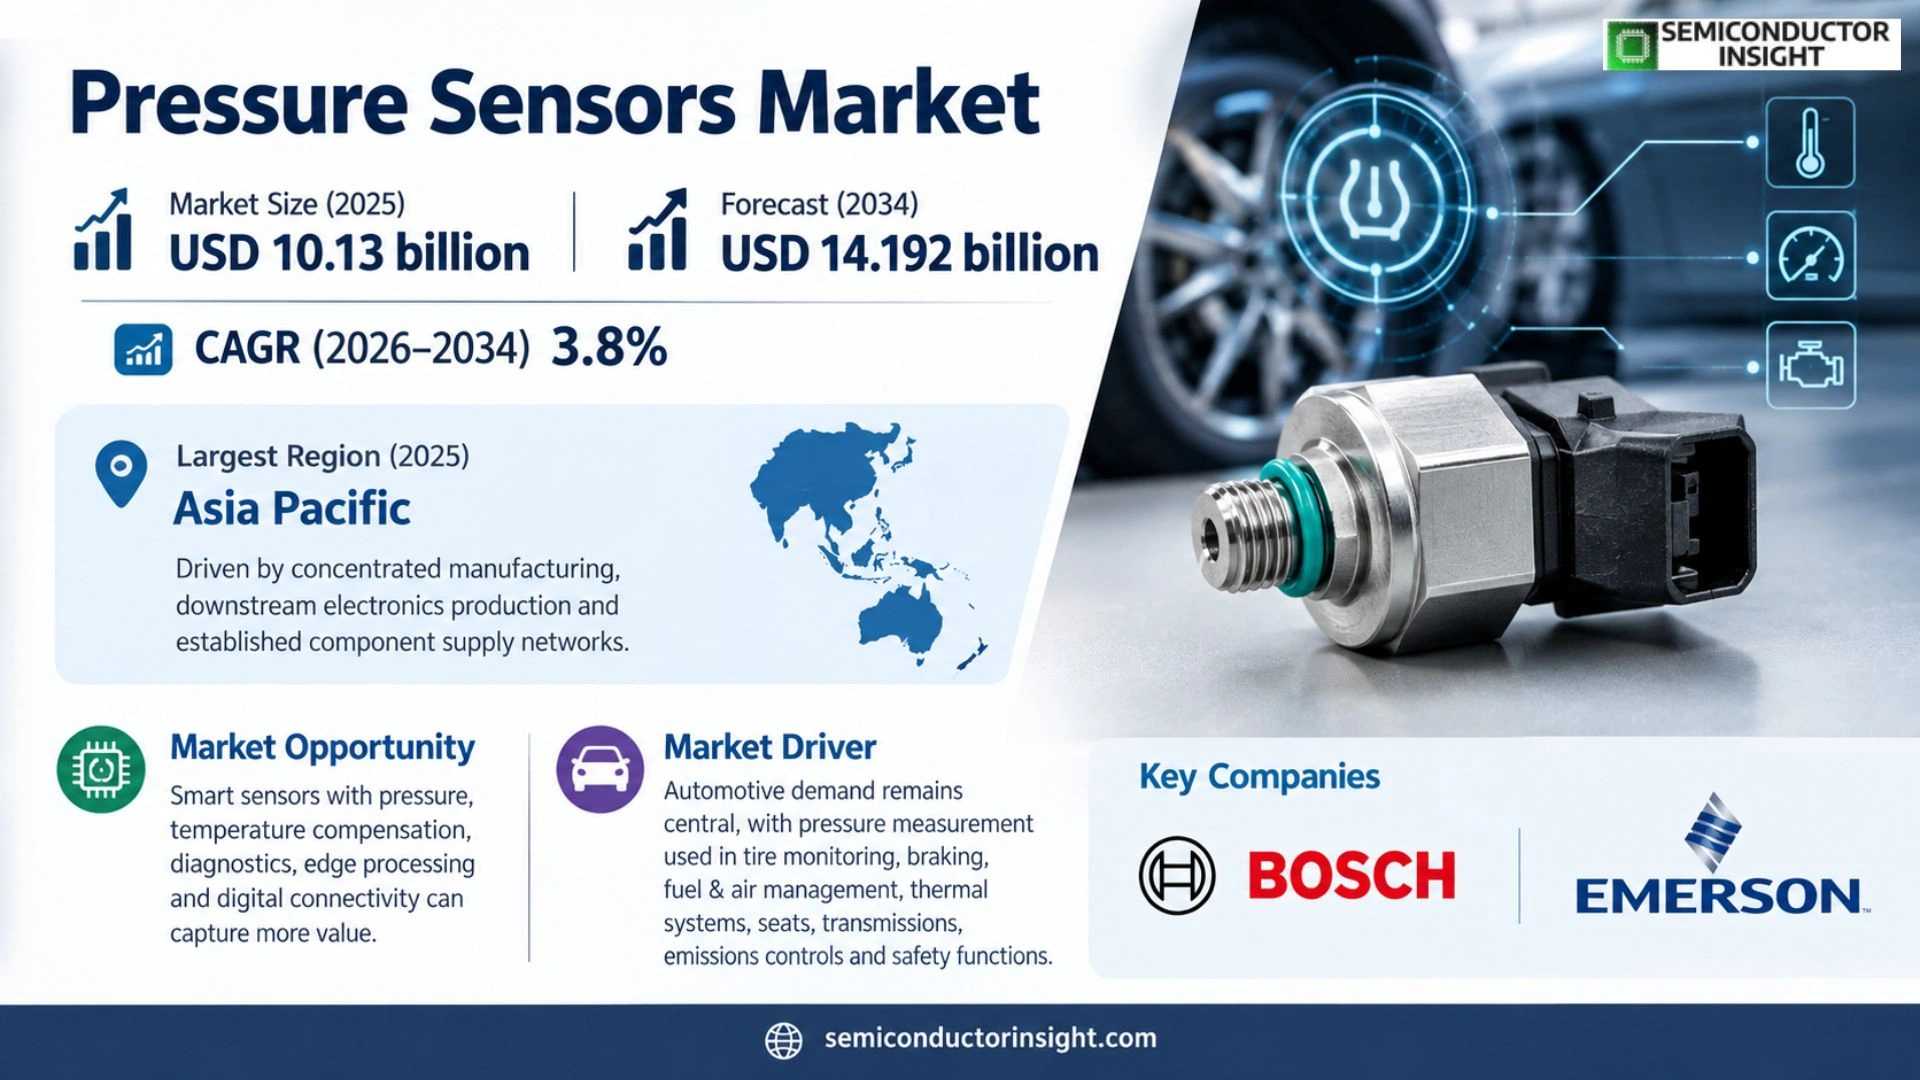
- The Pressure Sensors Market was valued at USD 10.13 billion in the 2025 base year and is projected to reach USD 14.192 billion by 2034, expanding at a 3.8% CAGR during 2026–2034.
- Ceramic pressure sensors retain a strong product position through corrosion resistance, mechanical robustness, thermal stability, and dependable operation in automotive and industrial environments.
- Automotive is the largest application, with pressure measurement used in tires, braking, engines, thermal management, emissions control, transmissions, seats, and vehicle safety systems.
- Asia Pacific leads through extensive vehicle, electronics, appliance, semiconductor, industrial-equipment, and medical-device production across major regional manufacturing economies.
- Integration and qualification shape supplier value. Digital compensation, diagnostics, connectivity, media-compatible packaging, calibration, certifications, and lifecycle support often matter more than the bare sensing element.
Pressure Sensors Market Overview
Pressure Sensors Market was valued at USD 10.13 billion in 2025 and is projected to reach USD 14.192 billion by 2034, growing at a CAGR of 3.8% during 2026–2034. Asia Pacific held the largest regional position in 2025, supported by concentrated manufacturing, downstream electronics production and established component supply networks.
Pressure sensors convert gas or liquid pressure into an electrical signal used for monitoring, control, safety, diagnostics, and automation. Commercial products range from bare MEMS dies and compensated sensor elements to packaged transducers, transmitters, and wireless instruments. Absolute, gauge, differential, and vacuum measurements serve very different operating environments, so market value depends on pressure range, accuracy, media compatibility, temperature stability, packaging, calibration, electronics, connectivity, and certification.
The market enters the 2026 estimated year with established demand from automotive control, tire-pressure monitoring, industrial automation, medical equipment, process industries, consumer electronics, aerospace, and energy infrastructure. Growth through 2034 will reflect additional sensing points per system, wider adoption of predictive maintenance, more capable MEMS integration, vehicle electrification, and demand for compact digital sensors that combine compensation, diagnostics, and communication interfaces in one qualified package.
Procurement differs sharply by application. Consumer and mobile products emphasize miniature size, low power, and price; vehicle programs require automotive qualification and long availability; industrial and oil-and-gas users prioritize rugged media isolation and calibration stability; medical devices require repeatability, biocompatible flow paths, and regulatory documentation. Suppliers therefore compete through application engineering and qualification evidence as much as through the nominal sensitivity of the sensing element.
Segment Analysis: By Type
By type, the Pressure Sensors market is segmented into MEMS Pressure Sensors · Ceramic Pressure Sensors · Other Pressure Sensors. Each category represents a different degree of integration, qualification burden and value capture, so suppliers compete through a combination of material performance, design support, manufacturing consistency, package architecture and application-specific testing rather than through unit price alone. Procurement also reflects lifecycle support, interoperability, compliance evidence, warranty exposure, and the cost of unsuccessful qualification.
| Type | Market relevance |
|---|---|
| MEMS Pressure Sensors | Distinct performance, condition, integration, and qualification requirements shape demand and supplier positioning. |
| Ceramic Pressure Sensors | Distinct performance, condition, integration, and qualification requirements shape demand and supplier positioning. |
| Other Pressure Sensors | Distinct performance, condition, integration, and qualification requirements shape demand and supplier positioning. |
Segment Analysis: By Application
By application, the market covers Automotive · Medical · Industrial · Consumer Electronics · Oil and Gas · Aerospace & Defense · Other Applications. Demand varies by production volume and qualification intensity: consumer programmes reward scale and miniaturisation, while automotive, industrial, aerospace, medical or security designs place greater weight on reliability evidence, long product availability and system-level performance under demanding operating conditions. Channel design, documentation, service coverage, and total ownership economics further determine which application converts technical interest into repeat purchasing.
| Application | Market relevance |
|---|---|
| Automotive | Purchasing criteria reflect use-case economics, technical requirements, warranty expectations, and channel support. |
| Medical | Purchasing criteria reflect use-case economics, technical requirements, warranty expectations, and channel support. |
| Industrial | Purchasing criteria reflect use-case economics, technical requirements, warranty expectations, and channel support. |
| Consumer Electronics | Purchasing criteria reflect use-case economics, technical requirements, warranty expectations, and channel support. |
| Oil and Gas | Purchasing criteria reflect use-case economics, technical requirements, warranty expectations, and channel support. |
| Aerospace & Defense | Purchasing criteria reflect use-case economics, technical requirements, warranty expectations, and channel support. |
| Other Applications | Purchasing criteria reflect use-case economics, technical requirements, warranty expectations, and channel support. |
Regional Analysis
Asia Pacific is the largest regional market for Pressure Sensors products, combining an established component-production ecosystem with major downstream customers. North America and Europe are strategically important for premium, automotive, aerospace, industrial and specialised applications, while South America and Middle East & Africa are primarily import- and project-led markets where distributor reach, local support and supply continuity shape vendor selection.
How does regional demand differ across this market?
For Pressure Sensors, Asia Pacific holds the largest position, supported by an established customer base, supplier presence, and mature purchasing channels. Europe contributes regulation, industrial demand, and technical expertise, while Asia Pacific combines electronics manufacturing, large device populations, and expanding engineering capability. South America and the Middle East and Africa develop through targeted infrastructure, enterprise, research, consumer, or public-sector programs rather than uniform adoption.
| Region | Position |
|---|---|
| Asia Pacific | Largest and most established demand base |
| North America | Developing demand shaped by local applications, channels, and qualification conditions |
| Europe | Developing demand shaped by local applications, channels, and qualification conditions |
| South America | Developing demand shaped by local applications, channels, and qualification conditions |
| Middle East & Africa | Developing demand shaped by local applications, channels, and qualification conditions |
Key Pressure Sensors Manufacturers and Competitive Landscape
The Pressure Sensors competitive landscape includes global technology leaders, diversified semiconductor or component groups, RF and imaging specialists, and regional manufacturers. The report profiles every named company across product positioning, manufacturing footprint, application exposure, recent development activity and strategic strengths; the complete coverage list is reproduced below so the intended company universe is explicit.
The competitive landscape includes Bosch, Emerson, TE Connectivity, Yokogawa Electric, Sensata Technologies, Honeywell, Infineon Technologies, Amphenol, Continental, Denso, NXP Semiconductors, Huba Control, Panasonic, Baker Hughes through Druck, and STMicroelectronics. These companies span automotive MEMS, industrial transmitters, harsh-environment transducers, process instrumentation, medical sensing, consumer barometers, and integrated semiconductor solutions, creating distinct competitive groups rather than one uniform product market.
Vendors differentiate through measurement accuracy, drift, media compatibility, operating temperature, pressure range, response time, overpressure tolerance, package size, power consumption, digital interfaces, diagnostics, cybersecurity, calibration services, and application certifications. Automotive incumbency and long OEM relationships are important for high-volume platforms, while industrial suppliers compete through installed instrumentation bases, field service, hazardous-area approvals, and integration with control systems. Semiconductor vendors add value through smaller packages and embedded compensation.
Key companies profiled
- Bosch
- Emerson
- TE Connectivity
- Yokogawa Electric
- Sensata Technologies
- Honeywell
- Infineon Technologies
- Amphenol
- Continental
- Denso
- NXP Semiconductors
- Huba Control
- Panasonic
- Baker Hughes (Druck)
- STMicroelectronics
Pressure Sensors Production Capacity Analysis
Production capacity is a material competitive factor in the Pressure Sensors market because electrical performance depends on specialised processes, qualified materials, repeatable yields and application-specific test capability. Capacity cannot be assessed only by nominal factory floor area: effective supply is the output that passes dimensional, electrical, reliability and customer qualification requirements at the required product mix.
Effective capacity combines MEMS wafer fabrication, ceramic or metal sensing structures, application-specific signal-conditioning silicon, wafer test, package assembly, media-isolation structures, calibration, compensation, and final verification. A high nominal die output does not guarantee finished-sensor availability because pressure ports, gels, diaphragms, oil fills, wire bonds, housings, connectors, and calibration equipment can constrain throughput. Product mix also matters because automotive, medical, and industrial devices require different test conditions and traceability.
MEMS pressure-sensor manufacturing requires stable diaphragm dimensions, controlled cavities, wafer bonding, hermetic sealing, contamination prevention, and accurate trimming. Ceramic and industrial transducers add metallization, thick-film processing, mechanical assembly, welding, media isolation, and pressure cycling. Calibration may be performed across several pressure and temperature points, making test time a significant capacity driver. Automation, parallel test, statistical process control, and reusable package platforms improve output without weakening accuracy or reliability.
Qualification capacity is especially important in regulated and safety-critical programs. Automotive devices require production-part approval, change control, and long reliability testing; medical components need documented materials and process consistency; aerospace and energy applications may require extended environmental validation. Suppliers with accredited laboratories, traceable reference standards, regional calibration services, and rapid failure analysis can convert manufacturing output into approved customer supply more effectively than firms relying only on low-cost sensor fabrication.
Pressure Sensors Market Dynamics: Drivers, Restraints and Opportunities
Pressure Sensors market growth reflects expanding electronic content and higher performance requirements, moderated by manufacturing complexity, long qualification cycles and competing technologies. The impact ranges below are directional analytical estimates rather than additive forecasts; they show the relative pressure each factor can place on the baseline CAGR when other assumptions remain broadly stable.
Market growth is supported by increasing automation, electronic control, emissions management, electrified powertrains, connected medical devices, smart buildings, and industrial condition monitoring. Pressure information often enables closed-loop control or a safety function, making the sensor a small but essential part of the system bill of materials. Revenue growth is moderated by price erosion in mature high-volume applications and by customer expectations for greater integration without a proportional increase in component cost.
Technical requirements continue to diverge. Miniature consumer barometers need very low power and small packages, while process transmitters must withstand corrosive media, vibration, hazardous locations, and years of field operation. Vehicle systems require functional diagnostics and automotive-grade quality, and medical flows demand low pressure ranges and repeatable performance. This diversity favors suppliers with reusable sensing platforms and application-specific packaging, but it also increases development, inventory, and qualification complexity.
MARKET DRIVERS
Drivers Impact Analysis*
| Driver | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| More pressure-sensing points in vehicles | +0.9% | Asia Pacific, Europe, North America | Medium term (2–4 years) |
| Industrial automation and predictive maintenance | +0.8% | China, Germany, United States, Japan | Medium term (2–4 years) |
| Connected and portable medical equipment | +0.6% | North America, Europe, developed Asia | Long term (≥4 years) |
| Miniature waterproof MEMS devices | +0.5% | Global wearables and IoT markets | Short term (≤2 years) |
| Energy and infrastructure monitoring | +0.4% | Middle East, North America, Europe, Asia | Long term (≥4 years) |
| Smart diagnostics and digital connectivity | +0.3% | Global industrial and OEM markets | Medium term (2–4 years) |
Automotive demand remains central because modern vehicles use pressure measurement in tire monitoring, braking, fuel and air management, thermal systems, seats, transmissions, emissions controls, and safety functions. Electrification changes rather than eliminates this requirement: battery cooling, heat pumps, refrigerant circuits, pneumatic comfort systems, and brake controls create new measurement points. Vehicle platforms reward suppliers that combine low power, diagnostics, wireless capability, automotive qualification, and dependable supply across long production lives.
Industrial automation and predictive maintenance expand demand for pressure transmitters and compact digital sensors. Pneumatic equipment, hydraulic systems, pumps, compressors, process lines, water networks, and HVAC installations use pressure data to regulate operation and identify leakage, blockage, wear, or abnormal loading. Connected instruments can provide remote diagnostics and condition information, but adoption depends on secure interfaces, calibration stability, retrofit practicality, and analytics that translate measurements into actionable maintenance decisions.
Healthcare applications create attractive growth across ventilators, respiratory equipment, infusion pumps, blood-pressure devices, dialysis, anesthesia, sleep therapy, surgical tools, and portable diagnostics. These systems require sensitivity at low pressure, repeatability, compact packaging, and careful control of contamination and drift. Demand strengthens as care moves toward portable and home settings, although suppliers must support medical-device documentation, consistent materials, lifecycle control, and validated integration with fluid paths and electronics.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Restraint | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Price erosion in high-volume applications | −0.9% | Automotive and consumer electronics | Persistent |
| Harsh-media packaging and reliability burden | −0.7% | Industrial, energy and automotive uses | Persistent |
| Calibration, drift and field-service costs | −0.5% | Medical and process instrumentation | Long term (≥4 years) |
| Application-specific qualification and change control | −0.4% | Automotive, medical and aerospace | Medium term (2–4 years) |
| Component and material supply disruptions | −0.3% | Global manufacturing networks | Short term (≤2 years) |
Price pressure is persistent in automotive and consumer programs because OEMs purchase high volumes and regularly seek cost reductions. Sensor suppliers must add diagnostics, compensation, smaller packages, or connectivity while maintaining quality and absorbing semiconductor and material volatility. Product proliferation can dilute scale when customers request unique ranges, ports, connectors, calibrations, or firmware. Platform reuse and standardized interfaces help, but qualification requirements often limit rapid substitution once a design enters production.
Harsh media and environmental conditions constrain performance. Corrosive fluids, condensation, dust, shock, vibration, electromagnetic interference, temperature cycling, and mechanical mounting stress can shift readings or damage exposed diaphragms. Protective gels, ceramic cells, stainless isolation, oil filling, and remote seals improve robustness but increase size, cost, and response complexity. Users must match construction to the medium because a sensor rated for clean dry air may fail in wet, chemically aggressive, or high-temperature service.
Calibration and drift create lifecycle costs. High-accuracy industrial and medical systems may need periodic verification, reference equipment, trained technicians, and controlled procedures. Field access can be difficult, and an inaccurate reading may affect safety, product quality, energy use, or regulatory compliance. Self-diagnostics and digital compensation reduce some burden, but users still require traceable performance and clear uncertainty. These needs can slow adoption in low-value applications where manual indicators remain economically adequate.
MARKET OPPORTUNITIES
Smart sensors that combine pressure, temperature compensation, diagnostics, edge processing, and digital connectivity can capture more value than uncompensated elements. Embedded intelligence can detect blocked ports, drift, leakage, abnormal cycles, or installation errors and transmit usable status information to controllers. Suppliers can differentiate through low-power operation, secure firmware, standardized industrial protocols, and configuration tools that make advanced functions accessible without creating a difficult integration burden for equipment manufacturers.
Miniature waterproof and contamination-resistant MEMS devices open opportunities in wearables, drones, appliances, logistics trackers, sports electronics, and outdoor equipment. Barometric information supports altitude, floor detection, weather context, navigation, and activity recognition. Commercial success requires stable accuracy after soldering and enclosure assembly, protection against liquids and dust, low current, and effective software filtering. Reference designs that address venting and mechanical placement can reduce common integration errors and accelerate adoption.
Energy transition and infrastructure modernization create new demand in hydrogen systems, heat pumps, refrigerant management, battery thermal control, water distribution, renewable assets, and emissions monitoring. These applications may expose sensors to unfamiliar media or pressure cycles, creating openings for specialized materials, isolation structures, and certified transmitters. Suppliers that collaborate early with equipment OEMs can define measurement ranges, diagnostics, and service requirements before architectures become fixed and highly price competitive.
Pressure Sensors Supply Chain Analysis
The Pressure Sensors supply chain links specialty materials and wafer or ceramic processing equipment to high-precision manufacturing, packaging, distribution and downstream system integration. Commercial resilience depends on qualified alternate materials, realistic yield assumptions, geographic redundancy and traceable process controls because a nominal second source is not interchangeable until the customer has validated electrical behaviour, reliability and package compatibility.
The supply chain begins with silicon wafers, ceramics, metals, glass, piezoresistive and capacitive structures, ASICs, substrates, bonding materials, protective gels, diaphragms, housings, pressure ports, cables, connectors, and calibration references. Sensor manufacturers integrate these inputs through wafer processing, packaging, compensation, calibration, and test. Distributors, instrumentation suppliers, system integrators, OEMs, calibration laboratories, and maintenance organizations then deliver and support sensors across vehicle, industrial, medical, consumer, and infrastructure applications.
Resilience depends on qualified alternates and configuration control. Changing a MEMS die, ASIC, gel, ceramic material, diaphragm, connector, or calibration algorithm can alter accuracy, drift, media compatibility, or reliability and may require customer requalification. Strong suppliers maintain traceable lots, controlled firmware, approved material lists, lifetime planning, regional inventory, and calibration capability. Dual sourcing is most effective when both sources reproduce the mechanical interface and validated measurement behavior, not merely a similar electrical output.
Recent Developments in the Pressure Sensors Market
Developments tracked to September 2026 and linked to official company or industry sources.
- February 2026 Published
STMicroelectronics completed its acquisition of NXP’s MEMS sensor business, expanding its position in automotive safety, tire-pressure monitoring, engine-management, industrial pressure sensing, and related sensor applications. Source - July 2025 Published
STMicroelectronics agreed to acquire NXP’s MEMS sensor business for up to USD 950 million, including automotive monitoring products such as tire-pressure and engine-management sensors plus industrial pressure sensors. Source - May 2025 Published
Infineon highlighted the XENSIV DPS368 miniature digital pressure sensor with IPx8 water resistance, a 2.0 by 2.5 by 1.1 millimeter package, and suitability for wearables and harsh IoT environments. Source - May 2025 Published
STMicroelectronics detailed how MEMS pressure and other sensors enable real-time process monitoring, predictive maintenance, resource efficiency, and human-machine collaboration in smart factories. Source - April 2025 Published
STMicroelectronics issued a revised LPS22DF datasheet documenting a compact digital barometer with 260–1260 hPa range, low-power operation, 24-bit output, embedded compensation, and multiple digital interfaces. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2021–2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Year | 2034 |
| Historical Period | 2021–2025 |
| Market Size 2025 | USD 10.13 billion |
| Market Size 2034 | USD 14.192 billion |
| Growth Rate | CAGR of 3.8% from 2026–2034 |
| Unit | Value in USD billion and shipment or production volume where disclosed |
| Segmentation | By Type, By Application, additional technology axis and By Region |
| By Type | MEMS Pressure Sensors · Ceramic Pressure Sensors · Other Pressure Sensors |
| By Application | Automotive · Medical · Industrial · Consumer Electronics · Oil and Gas · Aerospace & Defense · Other Applications |
| By Technology and Measurement Mode | Piezoresistive · Capacitive · Resonant · Optical · Absolute Pressure · Gauge Pressure · Differential Pressure · Vacuum Pressure |
| By Region | Each region analysed by type, application and countryNorth AmericaU.S., Canada, MexicoEuropeGermany, France, U.K., Italy, Nordic Countries, BeneluxAsia PacificChina, Japan, South Korea, India, Southeast AsiaSouth AmericaBrazil, Argentina, Rest of South AmericaMiddle East & AfricaTurkey, Israel, Saudi Arabia, UAE, Rest of MEA |
| Key Companies Profiled | Bosch; Emerson; TE Connectivity; Yokogawa Electric; Sensata Technologies; Honeywell; Infineon Technologies; Amphenol; Continental; Denso; NXP Semiconductors; Huba Control; Panasonic; Baker Hughes (Druck); STMicroelectronics |
| Customization Scope | Free report customization equivalent to up to four analyst working days with purchase, including additions or alterations to country, regional and segment coverage. |
Frequently Asked Questions
What is a pressure sensor?
The Pressure Sensors Market is valued at USD 10.13 billion in the 2025 base year and is projected to reach USD 14.192 billion by 2034, expanding at a CAGR of 3.8% during 2026–2034. The outlook covers MEMS, ceramic, and other pressure-sensing products used in automotive, medical, industrial, consumer, energy, aerospace, and infrastructure applications, with Asia Pacific holding the leading regional position.
What is the market outlook through 2034?
Demand is expected to increase steadily through 2034 as vehicles, machines, medical devices, consumer products, buildings, and infrastructure incorporate more electronic monitoring and control. Automotive electrification, predictive maintenance, portable healthcare, miniature waterproof MEMS devices, and energy-system modernization will broaden applications. Suppliers offering accurate sensing, durable packaging, digital compensation, diagnostics, connectivity, calibration, and long-term qualification support are positioned to capture the strongest opportunities.
Which product type leads the market?
Ceramic pressure sensors hold a strong position because ceramic sensing cells offer corrosion resistance, mechanical robustness, thermal stability, and dependable performance in automotive and industrial environments. MEMS pressure sensors are central to high-volume compact applications such as vehicles, phones, wearables, medical devices, and IoT nodes. Product leadership varies by whether market value includes semiconductor dies, packaged transducers, or complete calibrated industrial transmitters.
Which application creates the largest demand?
Automotive applications create the largest demand through tire-pressure monitoring, braking, engine and air management, fuel systems, transmissions, emissions control, thermal management, seats, and safety functions. Electrified vehicles add pressure requirements in heat pumps, refrigerant circuits, battery cooling, and brake systems. Industrial and medical markets are also important because they purchase more specialized devices with rigorous accuracy, packaging, calibration, and certification requirements.
Why does Asia Pacific lead?
Asia Pacific combines large automotive and electronics production, semiconductor and MEMS manufacturing, industrial automation, appliance output, infrastructure investment, and expanding medical-device supply chains across China, Japan, South Korea, India, Taiwan, and Southeast Asia. North America and Europe remain major markets for automotive, aerospace, medical, process, and industrial instrumentation, while regional demand patterns depend on local manufacturing, energy activity, safety regulation, and service capability.
What drives market growth?
Growth is driven by more sensing points per vehicle and machine, mandatory and voluntary safety monitoring, connected medical devices, predictive maintenance, smart factories, energy efficiency, and compact consumer electronics. MEMS manufacturing lowers size and power consumption, while digital interfaces, compensation, diagnostics, and wireless connectivity increase value. New demand is also emerging from hydrogen equipment, heat pumps, battery thermal systems, drones, wearables, and intelligent water networks.
What limits adoption?
Price erosion, demanding qualification, harsh-media exposure, drift, calibration cost, fragmented mechanical interfaces, and component shortages limit adoption. A low-cost sensing die may require protective packaging, compensation, connectors, software, and validation before it works reliably in the final system. Automotive and medical customers also require strict change control and long availability, making alternate sourcing slower than substituting an ordinary electronic component with similar headline specifications.
How do suppliers compete?
Suppliers compete through accuracy, repeatability, drift, pressure range, media compatibility, response time, overpressure tolerance, temperature performance, package size, power, digital interfaces, diagnostics, cybersecurity, and certification. Automotive vendors benefit from OEM relationships and proven quality, while industrial suppliers rely on calibration, hazardous-area approvals, field service, and installed control-system channels. Application engineering and lifecycle support frequently determine the final design choice.
Where are the best opportunities?
Opportunities include smart industrial transmitters, wireless monitoring, predictive maintenance, miniature waterproof MEMS barometers, connected healthcare, vehicle electrification, hydrogen systems, heat pumps, refrigerant management, battery cooling, drones, sports wearables, and smart water infrastructure. Suppliers can capture additional value through embedded diagnostics, secure firmware, reference designs, calibration services, application-specific packaging, and software that converts raw pressure readings into maintenance, safety, or control decisions.
Which companies are covered?
The report covers Bosch, Emerson, TE Connectivity, Yokogawa Electric, Sensata Technologies, Honeywell, Infineon Technologies, Amphenol, Continental, Denso, NXP Semiconductors, Huba Control, Panasonic, Baker Hughes through Druck, and STMicroelectronics. Profiles examine sensing technology, product range, application focus, manufacturing and calibration capability, geographic reach, customer channels, strategic positioning, partnerships, and recent developments for every company included in the report.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF