Key Statistics
Key Takeaways
- Battery functional devices are the largest product category, supported by battery insulation, thermal interface, bonding, protective circuits and mechanical components used across smartphones, tablets, laptops and wearables.
- Communication applications lead demand because smartphones and networked devices combine battery, thermal, EMI, structural and optical functions in very limited internal volume.
- The United States accounted for 28% of global revenue in 2024, while China is one of the fastest-growing major markets and Asia remains the largest manufacturing base for 3C electronics.
- Miniaturization raises the value of functional materials. EMI shielding, graphite heat spreaders, optically clear adhesives, protective films, acoustic meshes and precision die-cut components are increasingly designed as integrated stacks rather than simple commodity parts.
- Manufacturing capacity is becoming more geographically diversified. Jabil opened a new Pune facility in June 2026, while Foxconn continues to expand smart-consumer-electronics and component manufacturing across India, Vietnam, Mexico, Europe and other regions.
3C Electronic Functional Devices Market Overview
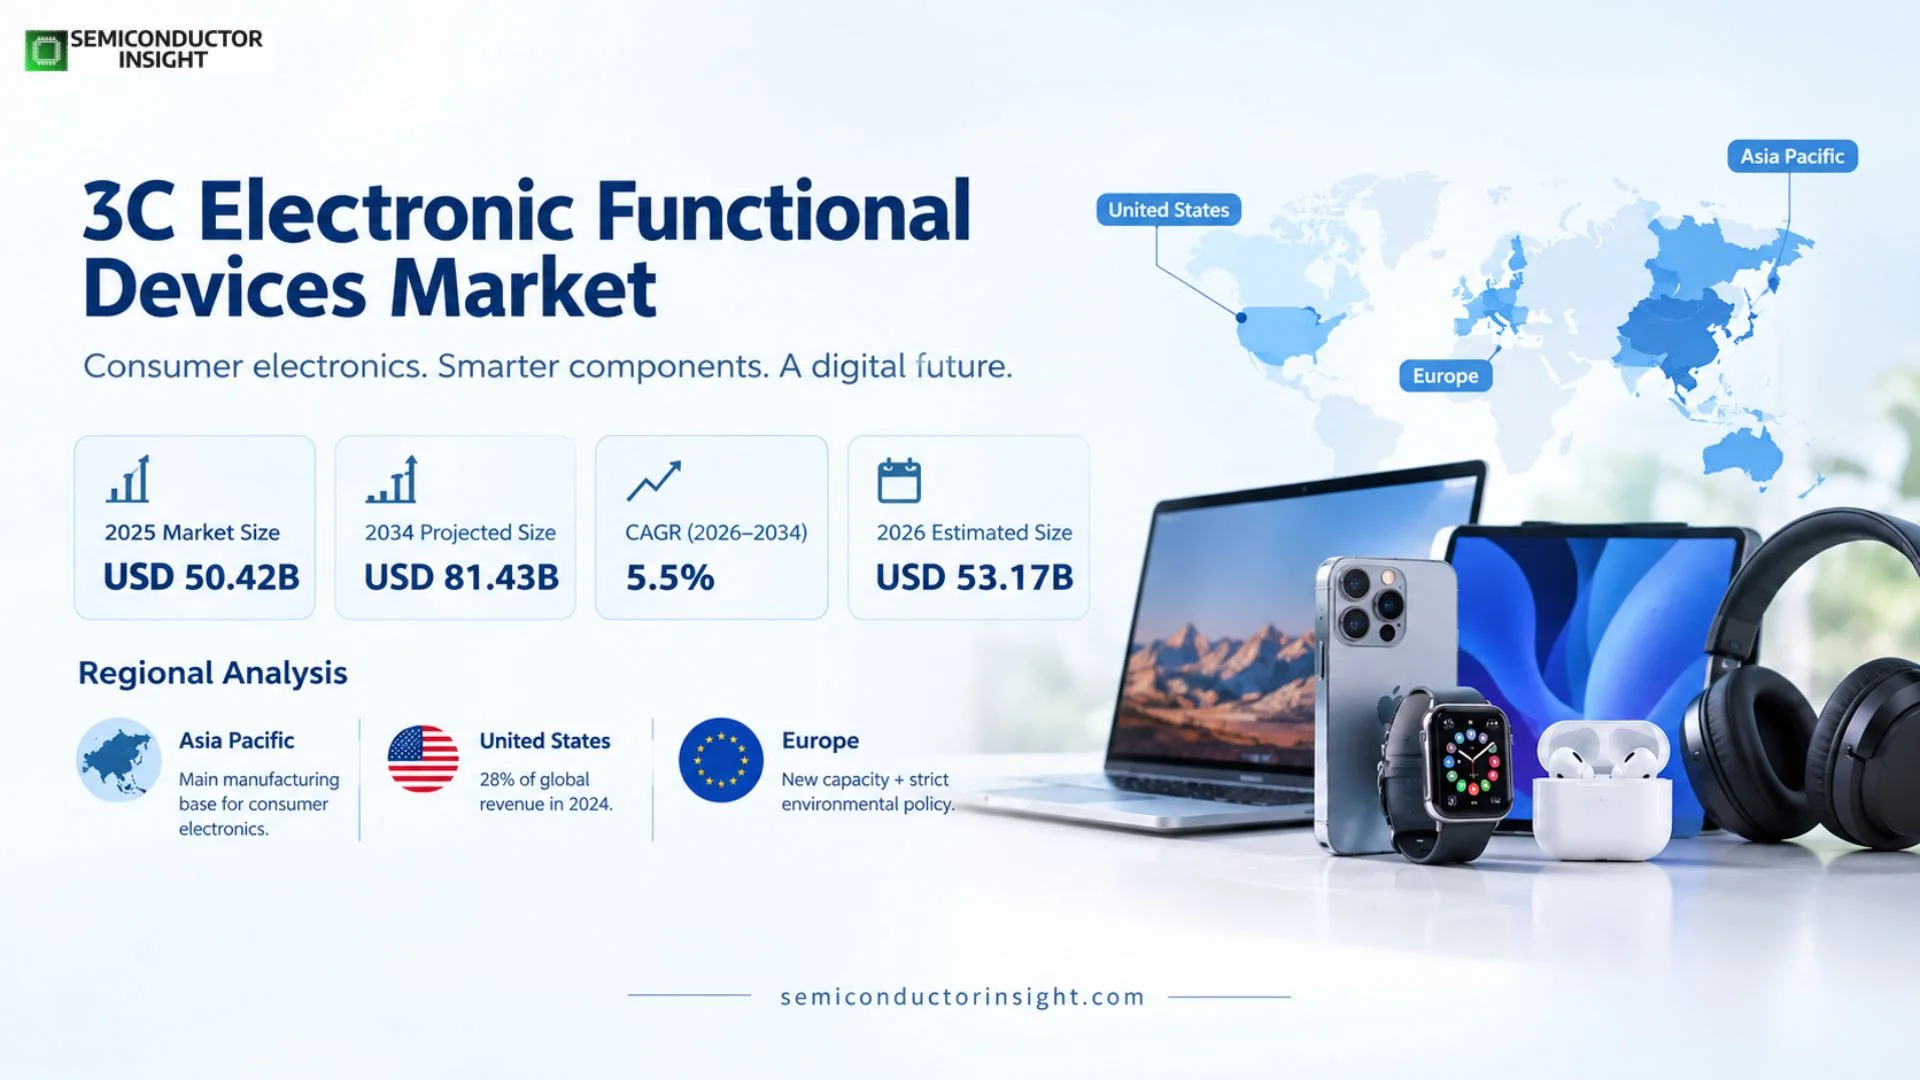
3C Electronic Functional Devices market is valued at USD 50.42 billion in 2025 and is projected to reach USD 81.43 billion by 2034, representing a 5.5% CAGR during 2026–2034. The 2026 estimated market size is USD 53.17 billion. The United States represented 28% of global revenue in 2024, while Asia Pacific remains the principal manufacturing base for consumer electronics and functional-component production.
3C electronic functional devices are enabling components used across computers, communications equipment and consumer electronics. The category includes battery-related functional parts, structural and protective components, and optical/display-related devices or materials. Examples include thermal interfaces, EMI shielding, battery adhesives, insulators, gaskets, display films, camera gaskets, optically clear adhesives and precision mechanical structures.
These components rarely determine the headline compute specification of a smartphone, laptop or wearable, but they strongly influence thickness, thermal performance, signal integrity, durability, sealing, optical efficiency and battery safety. As devices become thinner and more powerful, mechanical and materials engineering has to solve more functions within less internal space.
Manufacturing is highly integrated with OEM assembly. Many functional devices are custom die-cut, laminated, stamped, molded or bonded to suit a specific product geometry. Qualification therefore includes not only material properties but also roll-to-roll converting, automated placement, cleanliness, tolerance control and compatibility with the customer’s assembly line.
Segment Analysis: By Type
By type, the market is segmented into Battery Functional Devices, Structural Functional Devices, Optical Functional Devices and Others. Battery functional devices are the largest segment because portable 3C products require increasingly sophisticated power-management, insulation, thermal and safety components.
| Type | Typical components | Market position |
|---|---|---|
| Battery Functional Devices | Battery adhesives, insulators, compression materials, thermal interface components, protective circuits, vents and safety barriers used around cells, packs and charging systems. | Largest segment. Higher energy density, fast charging and thinner devices increase thermal, mechanical and dielectric requirements around portable batteries. |
| Structural Functional Devices | Housings, brackets, gaskets, seals, EMI shields, foam pads, protective films, acoustic meshes and bonding components that support, protect or isolate device assemblies. | Large high-volume category driven by device miniaturization, drop resistance, water ingress protection and automated assembly. |
| Optical Functional Devices | Camera gaskets, display films, optically clear adhesives, light-control films, reflectors, diffusers and optical protection layers. | High-value segment tied to display quality, camera performance, brightness, touch integration and optical efficiency. |
| Others | Thermal spreaders, specialty membranes, grounding components, labels, sensors and application-specific integrated material stacks. | Fragmented innovation segment that grows as OEMs combine several functions into one converted or molded component. |
Technology and end-user segmentation
Advanced materials are gaining share because higher device density increases thermal, EMI and optical requirements. Conventional foams, films and adhesives remain important, but graphite, conductive foils, advanced optical films, nanomaterials and hybrid structures deliver more function per unit thickness. OEMs are the largest end-user group because most components are designed directly into the product assembly.
| Axis | Segments | Commercial implication |
|---|---|---|
| By Technology | Conventional Materials · Advanced Materials · Hybrid Solutions | Advanced materials improve thermal conductivity, shielding, optical efficiency or strength; hybrid stacks combine adhesive, foam, foil and film functions to reduce assembly steps. |
| By End User | OEMs · Aftermarket · R&D Institutions | OEMs dominate because functional components are custom-qualified for device platforms; aftermarket demand is concentrated in repair and replacement; R&D supports next-generation materials and prototypes. |
Segment Analysis: By Application
By application, the market is segmented into Computer, Communication and Consumer Electronics. Communication is the leading application because smartphones, wearables and networking devices combine high component density with demanding battery, RF, display and structural requirements.
| Application | Key market insight |
|---|---|
| Communication | Smartphones, routers and connected devices require EMI shielding, thermal spreaders, battery adhesives, camera gaskets, acoustic meshes and display films. 5G raises RF density and heat generation, increasing the value of functional materials. |
| Computer | Laptops, tablets, desktops and peripherals use thermal interfaces, display bonding, shielding, structural foams, fan seals and battery components. Thin notebooks require particularly tight thermal and mechanical integration. |
| Consumer Electronics | Wearables, game consoles, smart-home products, audio devices and entertainment systems use compact functional components for sealing, bonding, optical performance and thermal control. |
| Smart Displays / HMI | Optically clear adhesives, brightness-enhancement films, diffuser films, camera gaskets and display seals improve optical performance and durability in touchscreens and digital displays. |
| Adjacent Automotive Electronics | ADAS displays, sensors and infotainment increasingly use materials originally developed for 3C devices, creating cross-market opportunities in thermal, optical and EMI components. |
Regional Analysis
The United States accounted for 28% of global 3C functional-device revenue in 2024, while Asia Pacific is the core manufacturing region. China, Taiwan, India, Vietnam and Southeast Asia host large electronics-assembly and component ecosystems, and China is expected to grow faster than the global market.
How do demand and production geography differ in 3C functional devices?
North America has strong high-value OEM and technology demand, while Asia Pacific handles most high-volume device and component manufacturing. Europe focuses on premium consumer, industrial and sustainability-oriented electronics. India and Southeast Asia are gaining manufacturing share as OEMs diversify supply chains.
| Region | Market position | Growth outlook | Core demand | Commercial priority |
|---|---|---|---|---|
| North America | U.S.: 28% global revenue in 2024 | Moderate to high | Premium consumer & computing | Innovation, material performance and qualification |
| Asia Pacific | Manufacturing center | High | Smartphones, laptops & wearables | Scale, cost and supply-chain proximity |
| Europe | Premium / sustainability market | Moderate | Consumer, industrial & display | Compliance, recyclability and quality |
| South America | Emerging | Moderate | Consumer electronics | Affordability and local assembly |
| Middle East & Africa | Emerging | Moderate | Smart devices & telecom | Distribution and product affordability |
Competitive Landscape
Key participants include Marian, Boyd Corporation, Brady Corporation, Kersentech, Suzhou Anjie Electronics, Suzhou Hengmingda Electronic Technology, Shenzhen FRD, SZCDL, Foxconn, Jabil, BYD Electronics and Tongda Group. The market is fragmented because different suppliers specialize in battery, structural, optical, EMI, thermal or integrated manufacturing functions.
Marian and Boyd represent the engineered-materials side of the market. Marian converts thermal interface materials, foams, adhesives, OCA, films, vents and EMI components into precision die-cut parts for automated assembly. Boyd provides display, shielding, bonding, protection and optical-material integration across mobile electronics and other markets.
Foxconn, Jabil and BYD Electronics compete from the EMS and vertical-integration side. Their scale allows functional components to be designed around complete product assembly, sourcing and automation. Foxconn’s current product portfolio explicitly includes smart consumer electronics, computing products and components such as connectors and optical components.
Chinese suppliers including Anjie, Hengmingda and FRD compete strongly in precision die-cutting, structural parts, thermal materials and EMI management. Proximity to smartphone and computer assembly supports rapid prototype-to-volume transitions and aggressive cost control.
Competitive tier structure
| Competitive tier | Representative companies | Competitive strengths |
|---|---|---|
| Engineered-materials leaders | Marian; Boyd; Brady | Thermal, EMI, optical, adhesive, sealing and converted functional components |
| EMS / vertically integrated leaders | Foxconn; Jabil; BYD Electronics | Product design support, high-volume electronics manufacturing and supply-chain integration |
| China / Asia specialists | Anjie; Hengmingda; FRD; Kersentech; SZCDL; Tongda | Precision structural parts, die-cut materials, thermal and EMI components close to device assembly |
Key companies profiled
3C Functional-Device Manufacturing & Conversion Capacity Analysis
Capacity depends on roll-to-roll converting, precision die cutting, stamping, molding, lamination, cleanroom optical bonding, CNC/laser processing, inspection and automated packaging for placement. A supplier may process billions of small components per year, but effective capacity is constrained by tooling, material qualification and the exact format required by the customer’s assembly line.
Miniaturization increases tolerance requirements. Camera gaskets, mesh vents, shielding foils and optical adhesive frames can be only a few millimeters wide and may need multilayer lamination with tight registration. High-speed automated placement also requires controlled liner, pitch and roll orientation.
Global capacity is increasingly duplicated across regions. OEMs want the same qualified component produced in China, India, Vietnam, Mexico or Eastern Europe so final assembly can move without a complete materials requalification. This favors suppliers with common quality systems and transferable tooling.
Market Dynamics
Growth is driven by smart-device shipments, 5G, miniaturization, higher battery energy density, premium displays and localized electronics manufacturing. Restraints include intense price competition, short product cycles, raw-material volatility and qualification complexity. Opportunities center on integrated material stacks, thermal management, EMI shielding, optical films and regionalized production.
MARKET DRIVERS
More functions are packed into thinner devices
Higher compute, cameras, antennas and batteries increase heat and EMI inside less volume, supporting more engineered functional materials.
Battery safety requirements are rising
Fast charging and higher energy density increase the need for insulation, thermal spreading, protection and secure bonding.
Displays are becoming more sophisticated
OLED, high refresh and edge-to-edge designs require better OCA, films, gaskets and heat spreading.
Manufacturing localization creates new supplier footprints
OEMs are adding India, Vietnam, Mexico and European capacity, requiring functional-component suppliers to follow.
Drivers Impact Analysis
| Driver | Impact | Primary markets | Time horizon |
|---|---|---|---|
| Smart-device replacement | High | Global | Persistent |
| 5G / higher RF density | High | Smartphones & telecom | Medium term |
| Miniaturization | High | All premium devices | Persistent |
| Supply-chain localization | Medium to high | India, Southeast Asia, Mexico | Medium to long term |
MARKET RESTRAINTS
OEMs demand continuous cost reduction
High-volume functional components can have low unit value, so yield, automation and material utilization are critical.
Designs change rapidly
A part may be customized to one smartphone generation and become obsolete within two or three years.
Advanced materials can be supply constrained
Specialty graphite, optical film, conductive foam and high-performance adhesive availability can affect production.
Qualification extends beyond the material itself
The converted part, liner, cleanliness, dimensional tolerance and automated-placement behavior all require approval.
Restraints Impact Analysis
| Restraint | Impact | Exposure | Time horizon |
|---|---|---|---|
| Price competition | High | High-volume consumer electronics | Persistent |
| Short product cycles | High | Smartphones / wearables | Persistent |
| Material-price volatility | Medium | Films, foils & adhesives | Recurring |
| Qualification complexity | Medium to high | Optical / safety-critical parts | Persistent |
MARKET OPPORTUNITIES
Integrate several functions into one converted component
Laminating shielding, insulation, adhesive and cushioning can reduce OEM assembly steps and part count.
Expand high-performance thermal materials
AI-enabled PCs, gaming and premium smartphones create stronger hot spots and higher surface-temperature constraints.
Grow optical-film and OCA solutions
Thinner OLED and touch displays create opportunities in low-bubble bonding, anti-glare, brightness enhancement and protection.
Build regional duplicate capacity
Suppliers that reproduce qualified processes in India, Vietnam, Mexico and Eastern Europe can follow OEM manufacturing shifts.
3C Electronic Functional Devices Value Chain Analysis
Functional materials
Converting / component manufacturing
EMS / OEM integration
Retail / installed device base
Material selection determines the performance envelope
Thermal conductivity, dielectric strength, optical clarity and shielding effectiveness are established before converting.
Precision converting determines manufacturability
Tolerances, liner design and roll format affect whether the part can be placed at high speed.
OEM qualification creates stickiness
Once a component is designed into a device and assembly process, switching suppliers requires dimensional and reliability validation.
Device cycles determine capacity timing
Suppliers must ramp before major product launches and then manage rapid volume decline after the platform matures.
Recent Developments in the 3C Electronic Functional Devices Market
Foxconn reports record second-quarter results and smart-consumer-electronics growth
Foxconn reported record Q2 revenue and maintained a strong 2026 outlook, with smart consumer electronics expected to grow through the traditional second-half peak season.
Jabil opens new electronics-manufacturing facility in Pune
Jabil expanded its India manufacturing capacity with a new Pune factory, strengthening regional electronics and supply-chain capability.
Boyd completes sale of thermal business to Eaton
Boyd’s Engineered Materials business continues independently with a focus on sealing, shielding, insulation and protection technologies across high-growth electronics markets.
Foxconn launches 2026–2030 sustainability roadmap
The electronics manufacturer set new clean-energy, supply-chain and manufacturing sustainability goals that will influence material and supplier requirements across global electronics production.
Marian expands precision functional-component solutions for electronics
The company’s current electronics portfolio includes thermal management, OCA, EMI shielding, insulation, filters, meshes and vents designed for automated consumer-electronics assembly.
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2020–2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| Historical Period | 2020–2025 |
| Market Size 2025 | USD 50.42 billion |
| Market Size 2034 | USD 81.43 billion |
| Growth Rate | 5.5% during 2026–2034 |
| Unit | Value (USD Million/Billion) and functional-component shipments |
| By Type | Battery Functional Devices · Structural Functional Devices · Optical Functional Devices · Others |
| By Application | Computer · Communication · Consumer Electronic |
| By End User | OEMs · Aftermarket · Research & Development Institutions |
| By Technology | Conventional Materials · Advanced Materials · Hybrid Solutions |
| By Region | Each region analysed by device type, application, end user, material technology and country electronics-manufacturing ecosystem North AmericaUnited States, Canada, Mexico EuropeGermany, United Kingdom, France, Nordics and other European markets Asia PacificChina, Taiwan, India, Vietnam, Southeast Asia, Japan and other Asian markets South AmericaBrazil, Argentina and other South American markets Middle East & AfricaUAE, Saudi Arabia, South Africa and other MEA markets |
| Key Companies Profiled | Marian, Inc. · Boyd Corporation · Brady Corporation · Kersentech · Suzhou Anjie Electronics · Suzhou Hengmingda Electronic Technology · Shenzhen FRD · SZCDL · Foxconn · Jabil · BYD Electronics · Tongda Group |
| Customization Scope | Free report customization equivalent to up to four analyst working days with purchase. Addition or alteration to country, regional and segment scope. |
Frequently Asked Questions
What is the 2025 size of the 3C Electronic Functional Devices market?
The market is valued at USD 50.42 billion in 2025 and is projected to reach USD 81.43 billion by 2034. The 2026 estimate is USD 53.17 billion and the 2026–2034 CAGR is 5.5%.
Which product type leads the market?
Battery functional devices are the largest category because smartphones, tablets, laptops and wearables require thermal, insulation, bonding, safety and power-management components around the battery system.
Which application is the largest?
Communication is the leading application because smartphones and networked devices combine high RF density, batteries, displays, cameras and compact structures that require many functional components.
Which market is the largest?
The United States accounted for 28% of global revenue in 2024, making it the largest country share explicitly identified in the market data. Asia Pacific remains the main manufacturing region.
What is the estimated market size in 2026?
The 2026 estimated market size is USD 53.17 billion within the consistent long-term forecast series.
Why is miniaturization important?
Thinner devices leave less room for heat spreading, EMI control, sealing and mechanical tolerance, increasing the value of precise multifunctional films, foams, foils and adhesives.
What are the main market restraints?
Price pressure, short product cycles, specialty-material volatility and demanding OEM qualification are the main restraints.
How are advanced materials changing the market?
Graphite, conductive foils, advanced optical films, high-performance adhesives and hybrid laminates allow more thermal, optical and EMI functionality in less space.
Which companies are active in the market?
Key participants include Marian, Boyd, Brady, Anjie Electronics, Hengmingda, Shenzhen FRD, Foxconn, Jabil, BYD Electronics and Tongda Group.
What does the report cover?
The report covers battery, structural and optical functional devices; computer, communication and consumer applications; end users, material technologies, five global regions, manufacturing, competition, dynamics, recent developments and value chain.
Research Sources & Evidence Base
View primary and authoritative evidence used in this overview
- Marian. Electronics Die-Cut Components – Official evidence on thermal, EMI, optical adhesive, vent and protective functional components for consumer electronics.
- Boyd. Consumer Electronics – Official evidence on sealing, insulation, display, camera, battery and EMI technologies in mobile electronics.
- Boyd. Display and HMI Solutions – Official evidence on optical films, OCA, gaskets, graphite heat spreaders and display functional materials.
- Foxconn. Products and Services – Official evidence on smart consumer electronics, computing, connectors, optical components and vertical manufacturing integration.
- Jabil. Electronics Capabilities – Official evidence on electronics manufacturing, miniaturization, flexible electronics and system integration.
- Jabil. Pune Manufacturing Expansion – June 2026 evidence on expansion of electronics-manufacturing capacity in India.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF