SEMICONDUCTOR INSIGHT
MARKET RESEARCH REPORT

Wafer Level Glass Technology Market

2026 to 2034
MARKET INTELLIGENCE
ACROSS KEY REGIONS
2026 EDITION
SEMICONDUCTOR MATERIALS Semiconductor Market Research

Wafer Level Glass Technology Market

Size, Share & Industry Analysis, By Type (Micro-Lens Array, Shack-Hartmann Lens Array, Uniform Compound Eye Lens, Laser Collimator, Others), By Application (Consumer Electronics, Vehicle Electronics, Smart Grid, Industrial Automation, Others), By Wafer Size (150 mm, 200 mm, 300 mm, 450 mm), By Technology (Through Glass Via (TGV), Temporary Bonding, Glass Reflow, Direct Bonding), and Regional Forecast, 2026-2034

◷
UPDATED 15 October 2026
▤
REPORT LENGTH Detailed Report
▣
REPORT CODE d4ac9c67d8b6
▯
FORMATS PDF

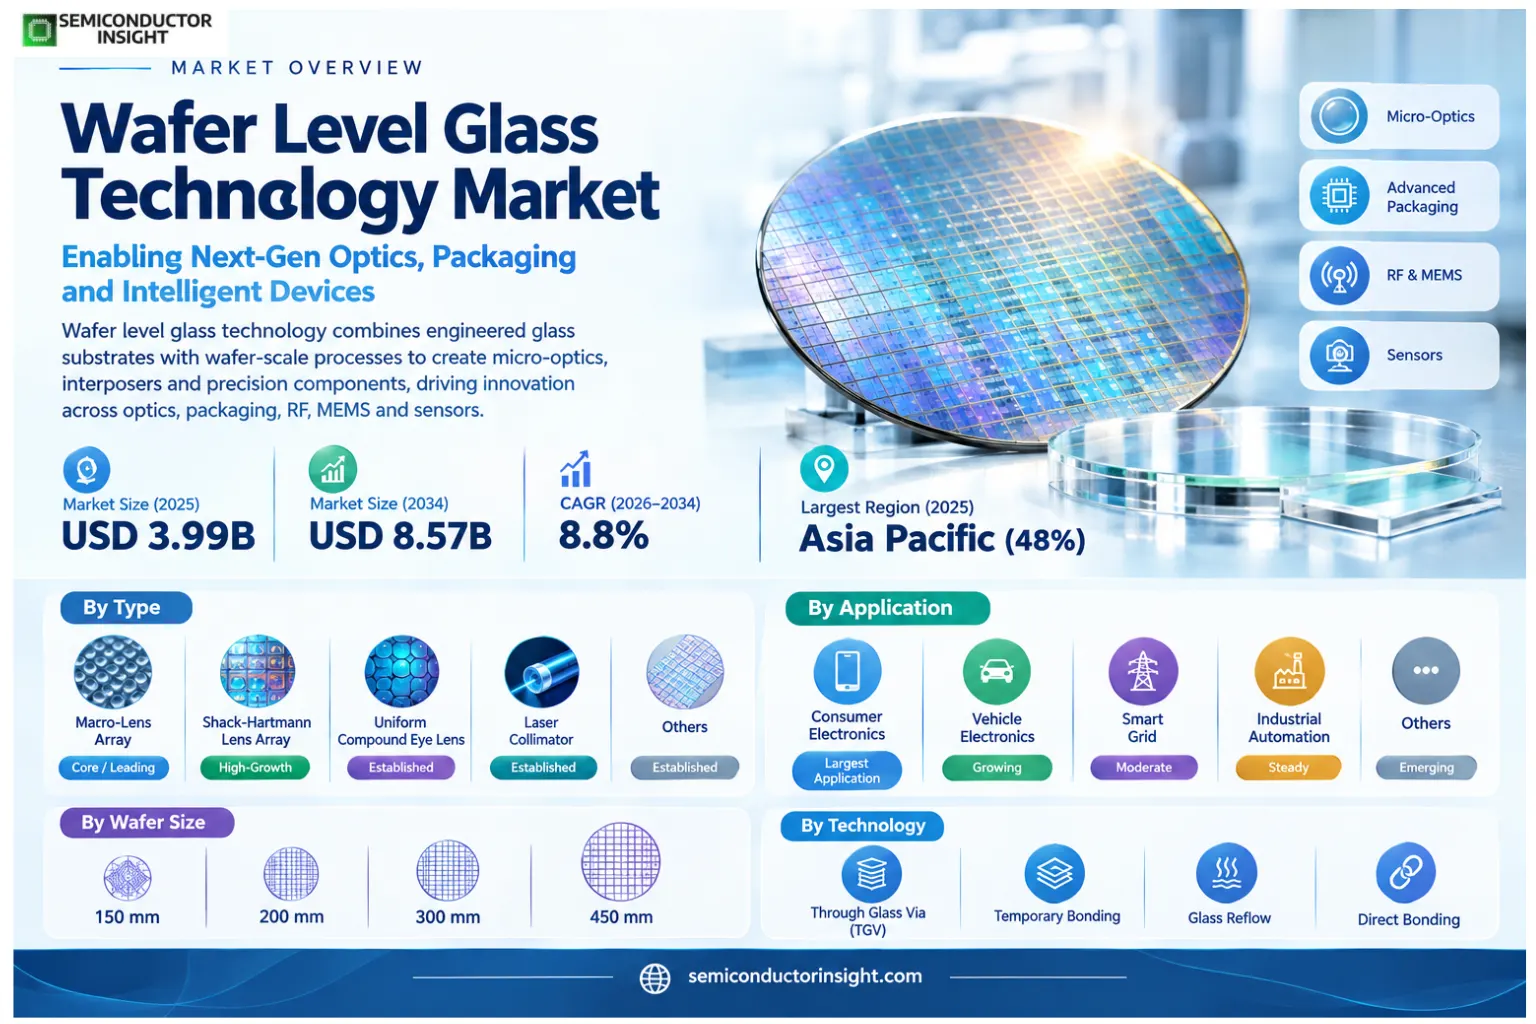
wafer level glass technology market was valued at USD 3.99 billion in 2025 and is projected to reach USD 8.57 billion by 2034, expanding at a CAGR of 8.8% during 2026–2034. Asia Pacific is the largest regional market in 2025 (48%).

Get the sample PDF with study scope, segmentation and methodology details.

Key Statistics

2025 Market Size
USD 3.99 billion
2034 Projected Market Size
USD 8.57 billion
CAGR (2026–2034)
8.8%
Largest Market in 2025
Asia Pacific (48%)

Key Takeaways

  • Market size and growth: USD 3.99 billion in 2025, rising to USD 8.57 billion by 2034 at a 8.8% CAGR over 2026–2034.
  • Asia Pacific is the largest regional market in 2025 (48%), supported by the location of relevant manufacturing, customers and supply chains.
  • Micro-Lens Array is a core product segment, while newer or more integrated variants create higher-value growth opportunities.
  • Consumer Electronics represents an important application cluster because purchasing is directly linked to system performance and qualification requirements.
  • Primary driver: Wafer-level replication allows many micro-optical structures to be formed and aligned in parallel, supporting compact cameras, sensing modules and AR/VR optics.
  • Structural restraint: Particle defects, alignment error, thickness variation or bonding defects can affect many devices on one wafer, making process control essential.

Wafer Level Glass Technology Market Overview

wafer level glass technology market was valued at USD 3.99 billion in 2025 and is projected to reach USD 8.57 billion by 2034, expanding at a CAGR of 8.8% during 2026–2034. Asia Pacific is the largest regional market in 2025 (48%).

Base year: 2025 · Estimated year: 2026 · Forecast period: 2026–2034 · Values in USD million unless stated otherwise

Wafer level glass technology combines engineered glass substrates with wafer-scale optical or packaging processes to create micro-optical structures, carriers, interposers and precision components. Glass offers controllable thermal expansion, low total-thickness variation, electrical insulation and optical transparency, which makes it useful in wafer-level optics, advanced packaging, RF structures, MEMS and sensor integration.

The market is being pulled by two distinct technology paths. Wafer-level optics uses molding, nanoimprint lithography, alignment and stacking to fabricate micro-lenses and optical structures at wafer scale. Advanced packaging uses glass as a carrier or functional substrate, including through-glass-via approaches where electrical routing, panel scaling and warpage control are important. Suppliers therefore compete on material properties, process compatibility and yield rather than on glass composition alone.

Asia Pacific held the largest share in the source scope, reflecting concentrated semiconductor packaging, smartphone, imaging-sensor and electronics manufacturing. Corning’s packaging-carrier portfolio highlights glass’s low warp and CTE control, while EV Group’s wafer-level optics platform shows how lens molding, nanoimprint and aligned stacking can be scaled to high-volume production.

Segment Analysis: By Type

By type, the market is segmented into Micro-Lens Array, Shack-Hartmann Lens Array, Uniform Compound Eye Lens, Laser Collimator, Others. Product selection reflects performance, integration requirements, qualification burden and total lifecycle economics. The leading categories benefit from established installed bases, while newer technologies gain share when they solve a measurable system constraint or reduce ownership cost.

Type Commercial role Market position
Micro-Lens Array The leading type because micro-lens arrays are widely used in imaging, sensing, illumination and compact optical modules. Wafer-scale replication lowers cost per optical element once volume is established. Core / leading segment
Shack-Hartmann Lens Array Used in wavefront sensing and precision optical measurement. Demand is smaller but technically demanding because pitch, surface quality and lens uniformity are critical. High-growth segment
Uniform Compound Eye Lens Supports wide-field and compact imaging architectures where multiple micro-optical channels are integrated on one substrate. Established / specialized segment
Laser Collimator Used to shape and align optical beams in compact sensing and projection systems, including selected industrial, automotive and consumer modules. Established / specialized segment
Others Includes specialty diffractive and micro-optical structures that do not fit the core lens-array categories. Established / specialized segment

Segment Analysis: By Application

By application, demand spans Consumer Electronics, Vehicle Electronics, Smart Grid, Industrial Automation, Others. Purchasing behavior varies because operating conditions, product life, reliability thresholds and unit volumes differ by application. High-value applications emphasize qualification and engineering support, while high-volume uses add stronger cost and supply-continuity pressure.

Application Demand characteristics
Consumer Electronics The largest application in the source scope, supported by smartphone imaging, 3D sensing, biometric functions and compact optical modules that benefit from wafer-scale processing.
Vehicle Electronics Growing with in-cabin sensing, lighting, projection, HUD and optical sensor content. Automotive qualification raises the value of thermal stability and long-term reliability.
Smart Grid Uses glass-enabled sensing and optical modules in monitoring and communications equipment, though volumes are lower than consumer electronics.
Industrial Automation Machine vision, metrology and sensor systems use precision optics where wafer-level replication can lower cost at scale.
Others Includes medical imaging, AR/VR, photonics and specialty sensing.

By Wafer Size

Wafer Size Market relevance
150 mm Creates a distinct design, manufacturing or procurement requirement within the market.
200 mm Creates a distinct design, manufacturing or procurement requirement within the market.
300 mm Creates a distinct design, manufacturing or procurement requirement within the market.
450 mm Creates a distinct design, manufacturing or procurement requirement within the market.

By Technology

Technology Market relevance
Through Glass Via (TGV) Creates a distinct design, manufacturing or procurement requirement within the market.
Temporary Bonding Creates a distinct design, manufacturing or procurement requirement within the market.
Glass Reflow Creates a distinct design, manufacturing or procurement requirement within the market.
Direct Bonding Creates a distinct design, manufacturing or procurement requirement within the market.

Wafer Level Glass Technology Market Size & Growth

Regional Analysis

Asia Pacific leads the Wafer Level Glass Technology market in 2025. Regional demand differs according to manufacturing concentration, end-use investment, qualification practices and local supplier support. The largest region combines the strongest near-term demand base with established customers and supply-chain infrastructure, while other regions create opportunities around localization, research, specialty manufacturing or fast-growing end uses.

How does regional demand differ across the market?

Regional market structure is not simply a difference in size. Asia Pacific typically benefits from manufacturing density and electronics supply chains, North America from system design and advanced technology investment, Europe from specialized industrial and automotive applications, and emerging regions from selective infrastructure and localization projects. Supplier strategy therefore needs to account for qualification, service coverage, logistics and customer concentration in each geography.

Region Position Growth outlook Demand profile What decides supplier selection
Asia Pacific Largest / major High Manufacturing-led Local qualification and scale
North America Major High-value Design and investment-led Engineering support and supply security
Europe Established Moderate Specialty industrial-led Quality, compliance and lifecycle support
South America Emerging Selective Import-led Landed cost and channel access
Middle East & Africa Emerging Selective Project-led Project timing and local support
Asia Pacific

What defines demand in Asia Pacific?

Asia Pacific is the largest regional market, with the source scope indicating a 48% share. China, Japan, South Korea and Taiwan combine large electronics production with packaging, imaging-sensor and optical-component supply chains. The region benefits from high-volume manufacturing, local tooling ecosystems and close proximity between glass processing, semiconductor packaging and consumer-device assembly.

Market positionLargest
Growth outlookHigh
Demand profileManufacturing and end-use
Supplier focusQualification, service and supply continuity
Country / subregion Commercial relevance
China Large electronics and manufacturing base; demand depends on the specific market’s local production, system assembly and supplier ecosystem.
Japan Strong materials, component and precision-manufacturing base with demanding quality requirements and long supplier relationships.
South Korea Important semiconductor, display and electronics production center with concentrated high-volume customers.
Taiwan Foundry, packaging and electronics manufacturing create dense demand for qualified component and materials suppliers.
North America

What defines demand in North America?

North America is anchored by specialty glass technology, semiconductor design and advanced packaging development in the United States. Corning’s glass carrier portfolio and U.S. R&D infrastructure support adoption in packaging, photonics and precision optics. Demand is less volume-driven than Asia but strong in higher-value development programs where material properties and process integration are prioritized.

Market positionMajor
Growth outlookModerate / selective
Demand profileDesign and end-use
Supplier focusQualification, service and supply continuity
Country / subregion Commercial relevance
United States Largest regional technology and end-use market, with strong semiconductor, cloud, automotive, industrial and healthcare design activity depending on the market.
Canada Smaller market focused on research, industrial technology and selected electronics manufacturing, usually served through North American supply chains.
Mexico Electronics and automotive assembly supports component demand where production is linked to U.S. OEM and Tier-1 programs.
Europe

What defines demand in Europe?

Europe’s role is defined by process equipment, optics and automotive electronics. Austria-based EV Group supplies wafer-level optics, bonding and nanoimprint platforms, while Germany and other European markets contribute automotive, industrial and photonics demand. The region is important for manufacturing-process innovation even when volume production is ultimately located in Asia.

Market positionEstablished
Growth outlookModerate / selective
Demand profileSpecialty / project demand
Supplier focusQualification, service and supply continuity
Country / subregion Commercial relevance
Germany Europe’s largest industrial and automotive manufacturing hub, with strong engineering, specialty semiconductor and automation demand.
France Important semiconductor, aerospace and industrial technology base with research and advanced-manufacturing activity.
United Kingdom Demand is weighted toward design, research, photonics, healthcare and specialty electronics rather than large-scale wafer fabrication.
Italy Industrial electronics and automotive supply chains support specialized component and materials demand.
South America

What defines demand in South America?

South America has limited wafer-level glass manufacturing capacity and is mainly an end-market and research opportunity. Brazil is the principal electronics market, with adoption tied to imported imaging modules, industrial systems and automotive electronics. Local demand is served largely through global component and equipment supply chains.

Market positionEmerging
Growth outlookModerate / selective
Demand profileSpecialty / project demand
Supplier focusQualification, service and supply continuity
Country / subregion Commercial relevance
Brazil The region’s largest electronics and industrial economy; demand is mainly supplied through global OEMs, distributors and imported components.
Argentina Smaller demand base concentrated in industrial, research and imported electronics applications.
Middle East & Africa

What defines demand in Middle East & Africa?

The region remains small but has selective opportunities in photonics research, sensing, defense electronics and emerging semiconductor initiatives. Israel has the strongest established technology base, while Gulf investments may support future packaging and advanced-manufacturing projects. High-value applications can justify imported precision glass even at limited volumes.

Market positionEmerging
Growth outlookModerate / selective
Demand profileSpecialty / project demand
Supplier focusQualification, service and supply continuity
Country / subregion Commercial relevance
Israel The region’s strongest established semiconductor and advanced-electronics ecosystem, with design, fab and research activity.
United Arab Emirates Smart infrastructure and advanced-technology investment create selective opportunities in imported high-value electronics.
Saudi Arabia Industrial diversification and digital infrastructure programs create emerging demand, though local semiconductor manufacturing remains limited.
South Africa Industrial, mining, automotive and research applications support a modest imported-component market.

Competitive Landscape

The Wafer Level Glass Technology market is shaped by qualification depth, process know-how and customer support rather than by price alone. Leading suppliers use installed-base relationships, intellectual property, manufacturing quality and field engineering to protect design wins. Competition is strongest when customers can qualify multiple technically comparable suppliers, while highly specialized applications remain concentrated among vendors with proven reliability records.

Large suppliers typically compete across several adjacent product families, allowing them to bundle technical support and simplify customer sourcing. Specialized companies compete by focusing on a narrower technology, material set or performance envelope. In both cases, the ability to maintain consistent quality during volume production is essential because a component or material change can require renewed process qualification.

Regional presence is also strategic. Customers increasingly value local application engineering, shorter repair or replenishment cycles and geographically diversified production. This favors suppliers that can combine global process standards with local service infrastructure close to major manufacturing clusters.

Company Competitive position Primary basis of competition
Corning Incorporated Tier 1 / established Competes through qualified products, technical support and customer integration.
EV Group Tier 1 / established Competes through qualified products, technical support and customer integration.
Himax Technologies Tier 1 / established Competes through qualified products, technical support and customer integration.
ams OSRAM Tier 1 / established Competes through qualified products, technical support and customer integration.
Tianshui Huatian Technology Established / specialized Competes through qualified products, technical support and customer integration.
China Wafer Level CSP Established / specialized Competes through qualified products, technical support and customer integration.
Largan Precision Established / specialized Competes through qualified products, technical support and customer integration.
Zhuhai Multiscale Optoelectronics Technology Established / specialized Competes through qualified products, technical support and customer integration.

Companies Profiled

Corning Incorporated; EV Group; Himax Technologies; ams OSRAM; Tianshui Huatian Technology; China Wafer Level CSP; Largan Precision; Zhuhai Multiscale Optoelectronics Technology.

Production Capacity Analysis

Production capacity is constrained less by nominal factory floor space than by precision process capability, clean manufacturing, calibrated equipment and qualified upstream materials. Expanding output therefore requires more than adding assembly stations: suppliers must preserve contamination control, statistical process capability and traceability as volume increases. Capacity decisions are also influenced by the need to remain close to key customers and reduce logistics risk.

The strongest capacity additions are likely to follow major customer clusters. This favors Asia Pacific for high-volume electronics and semiconductor production, while the United States and Europe attract selective localization in strategic technologies. Suppliers that can duplicate qualified processes across regions gain resilience, but transferring a tightly controlled process between sites can itself require customer revalidation.

Market Dynamics

The market grows as device makers seek smaller optical modules, lower packaging warpage and scalable wafer-level processing. Demand is strongest where glass delivers a measurable advantage in flatness, thermal expansion matching, transparency or electrical insulation.

Market Drivers

Drivers Impact Analysis

Driver Impact Why it matters
Miniaturized optical modules High Wafer-level replication allows many micro-optical structures to be formed and aligned in parallel, supporting compact cameras, sensing modules and AR/VR optics.
Advanced packaging adoption High Glass carriers and TGV substrates address warpage, transparency and dimensional stability requirements in fan-out and heterogeneous integration.
Automotive sensing content Medium-High More cameras, optical sensors, HUDs and in-cabin monitoring systems increase the number of precision optical components per vehicle.
Scaling to larger substrates Medium-High Migration toward 300 mm wafers and panel formats can lower cost per device when process uniformity and yield are maintained.

Miniaturized optical modules

Wafer-level replication allows many micro-optical structures to be formed and aligned in parallel, supporting compact cameras, sensing modules and AR/VR optics. The commercial implication is stronger design-in activity for suppliers that can translate the technical requirement into reliable volume production and responsive customer support.

Advanced packaging adoption

Glass carriers and TGV substrates address warpage, transparency and dimensional stability requirements in fan-out and heterogeneous integration. The commercial implication is stronger design-in activity for suppliers that can translate the technical requirement into reliable volume production and responsive customer support.

Automotive sensing content

More cameras, optical sensors, HUDs and in-cabin monitoring systems increase the number of precision optical components per vehicle. The commercial implication is stronger design-in activity for suppliers that can translate the technical requirement into reliable volume production and responsive customer support.

Scaling to larger substrates

Migration toward 300 mm wafers and panel formats can lower cost per device when process uniformity and yield are maintained. The commercial implication is stronger design-in activity for suppliers that can translate the technical requirement into reliable volume production and responsive customer support.

Market Restraints

Restraints Impact Analysis

Restraint Impact Commercial effect
Yield sensitivity High Particle defects, alignment error, thickness variation or bonding defects can affect many devices on one wafer, making process control essential.
High tooling and qualification cost Medium Nanoimprint, bonding and wafer-level optical lines require specialized capital equipment and long customer qualification cycles.
Competing substrate technologies Medium Silicon, organic laminates and conventional discrete optics remain attractive in applications where glass does not provide a clear system-level benefit.

Yield sensitivity

Particle defects, alignment error, thickness variation or bonding defects can affect many devices on one wafer, making process control essential. This restraint does not eliminate demand, but it changes the pace of adoption and favors suppliers with stronger balance sheets, technical data and established qualification histories.

High tooling and qualification cost

Nanoimprint, bonding and wafer-level optical lines require specialized capital equipment and long customer qualification cycles. This restraint does not eliminate demand, but it changes the pace of adoption and favors suppliers with stronger balance sheets, technical data and established qualification histories.

Competing substrate technologies

Silicon, organic laminates and conventional discrete optics remain attractive in applications where glass does not provide a clear system-level benefit. This restraint does not eliminate demand, but it changes the pace of adoption and favors suppliers with stronger balance sheets, technical data and established qualification histories.

Market Opportunities

Co-packaged optics and photonics

Glass-compatible optical structures and precision alignment create opportunities as optical I/O moves closer to compute packages. The opportunity is strongest where the supplier can document a system-level benefit and support the customer through integration, qualification and scale-up.

Panel-level packaging

Large glass formats can improve area utilization for larger interposers and heterogeneous packages. The opportunity is strongest where the supplier can document a system-level benefit and support the customer through integration, qualification and scale-up.

AR/VR micro-optics

Diffractive and refractive microstructures manufactured at wafer scale can support lighter optical engines and higher production throughput. The opportunity is strongest where the supplier can document a system-level benefit and support the customer through integration, qualification and scale-up.

Automotive optical integration

Lighting, sensing and projection modules create long-life applications where glass stability supports premium pricing. The opportunity is strongest where the supplier can document a system-level benefit and support the customer through integration, qualification and scale-up.

Supply Chain Analysis

Stage 1
Specialty glass composition and wafer forming
Stage 2
Grinding, polishing, TGV formation and surface preparation
Stage 3
Nanoimprint, bonding, lens molding and wafer-level integration
Stage 4
Module assembly, packaging, optical alignment and end-system qualification

Stage 1 — Specialty glass composition and wafer forming: Value capture depends on process control, yield and the ability to meet downstream qualification requirements. Bottlenecks at this stage can propagate quickly because customers often depend on validated materials, calibrated components or approved production routes rather than interchangeable spot-market supply.

Stage 2 — Grinding, polishing, TGV formation and surface preparation: Value capture depends on process control, yield and the ability to meet downstream qualification requirements. Bottlenecks at this stage can propagate quickly because customers often depend on validated materials, calibrated components or approved production routes rather than interchangeable spot-market supply.

Stage 3 — Nanoimprint, bonding, lens molding and wafer-level integration: Value capture depends on process control, yield and the ability to meet downstream qualification requirements. Bottlenecks at this stage can propagate quickly because customers often depend on validated materials, calibrated components or approved production routes rather than interchangeable spot-market supply.

Stage 4 — Module assembly, packaging, optical alignment and end-system qualification: Value capture depends on process control, yield and the ability to meet downstream qualification requirements. Bottlenecks at this stage can propagate quickly because customers often depend on validated materials, calibrated components or approved production routes rather than interchangeable spot-market supply.

Recent Developments

September 1, 2026 — EV Group announced expanded support for co-packaged optics using wafer bonding, nanoimprint lithography and thin-wafer processing, linking wafer-level optical manufacturing to AI and high-performance computing infrastructure. Source
May 26, 2025 — EV Group introduced the LITHOSCALE XT maskless exposure system for high-volume heterogeneous integration, including fan-out, advanced imaging sensor and automotive applications. Source
Current — Corning’s advanced packaging glass carriers are designed for wafer thinning, fan-out and 2.5D/3D packaging, with portfolio options targeted at lower warpage and controlled CTE. Source

Report Scope & Segmentation

Attribute Coverage
Market Wafer Level Glass Technology
Base Year 2025
Estimated Year 2026
Forecast Period 2026–2034
2025 Market Size USD 3.99 billion
2034 Projected Market Size USD 8.57 billion
CAGR (2026–2034) 8.8%
Largest Market in 2025 Asia Pacific (48%)
By Type Micro-Lens Array, Shack-Hartmann Lens Array, Uniform Compound Eye Lens, Laser Collimator, Others
By Application Consumer Electronics, Vehicle Electronics, Smart Grid, Industrial Automation, Others
By Wafer Size 150 mm, 200 mm, 300 mm, 450 mm
By Technology Through Glass Via (TGV), Temporary Bonding, Glass Reflow, Direct Bonding
Companies Profiled Corning Incorporated, EV Group, Himax Technologies, ams OSRAM, Tianshui Huatian Technology, China Wafer Level CSP, Largan Precision, Zhuhai Multiscale Optoelectronics Technology
Regions North America; Europe; Asia Pacific; South America; Middle East & Africa

Frequently Asked Questions

What is the Wafer Level Glass Technology market size in 2025?

The global Wafer Level Glass Technology market is valued at USD 3.99 billion in 2025.

What is the projected Wafer Level Glass Technology market size by 2034?

The market is projected to reach USD 8.57 billion by 2034.

What is the CAGR of the Wafer Level Glass Technology market from 2026 to 2034?

The market is projected to expand at a 8.8% CAGR during 2026–2034.

Which region leads the Wafer Level Glass Technology market?

Asia Pacific is the largest market in 2025 (48%).

What are the main product types?

Micro-Lens Array, Shack-Hartmann Lens Array, Uniform Compound Eye Lens, Laser Collimator, Others.

What are the key applications?

Consumer Electronics, Vehicle Electronics, Smart Grid, Industrial Automation, Others.

What is the main growth driver?

Wafer-level replication allows many micro-optical structures to be formed and aligned in parallel, supporting compact cameras, sensing modules and AR/VR optics.

What is the main restraint?

Particle defects, alignment error, thickness variation or bonding defects can affect many devices on one wafer, making process control essential.

Where are the strongest opportunities?

Glass-compatible optical structures and precision alignment create opportunities as optical I/O moves closer to compute packages. Large glass formats can improve area utilization for larger interposers and heterogeneous packages.

Which companies are active in the market?

Corning Incorporated, EV Group, Himax Technologies, ams OSRAM, Tianshui Huatian Technology, China Wafer Level CSP, Largan Precision, Zhuhai Multiscale Optoelectronics Technology are among the companies active in the market.

Research Sources & Evidence Base

View primary and official sources used in this overview
  1. Corning — Advanced Packaging Glass Carriers. Glass carrier properties and packaging use cases.
  2. Corning — Semiconductor Glass Wafers. Carrier glass, TGV and wafer properties.
  3. EV Group — Wafer-Level Optics. Lens molding, nanoimprint and stacking process architecture.
  4. EV Group — Co-Packaged Optics Manufacturing Challenges. Recent photonics and packaging process development.
Wafer Level Glass Technology Market Size, Share & Industry Analysis, By Type (Micro-Lens Array, Shack-Hartmann Lens Array, Uniform Compound Eye Lens, Laser Collimator, Others), By Application (Consumer Electronics, Vehicle Electronics, Smart Grid, Industrial Automation, Others), By Wafer Size (150 mm, 200 mm, 300 mm, 450 mm), By Technology (Through Glass Via (TGV), Temporary Bonding, Glass Reflow, Direct Bonding), and Regional Forecast, 2026-2034

Get Sample Report PDF for Exclusive Insights

Report Sample Includes

  • Table of Contents
  • List of Tables & Figures
  • Charts, Research Methodology, and more...

PDF Icon Download Sample Report PDF

Download Sample Report

Table of Content

1 Introduction to Research & Analysis Reports
1.1 Wafer Level Glass Technology Market Definition
1.2 Market Segments
1.2.1 Segment by Type
1.2.2 Segment by Application
1.3 Global Wafer Level Glass Technology Market Overview
1.4 Features & Benefits of This Report
1.5 Methodology & Sources of Information
1.5.1 Research Methodology
1.5.2 Research Process
1.5.3 Base Year
1.5.4 Report Assumptions & Caveats
2 Global Wafer Level Glass Technology Overall Market Size
2.1 Global Wafer Level Glass Technology Market Size: 2024 VS 2032
2.2 Global Wafer Level Glass Technology Market Size, Prospects & Forecasts: 2026-2034
2.3 Key Market Trends, Opportunity, Drivers and Restraints
2.3.1 Market Opportunities & Trends
2.3.2 Market Drivers
2.3.3 Market Restraints
3 Company Landscape
3.1 Top Wafer Level Glass Technology Players in Global Market
3.2 Top Global Wafer Level Glass Technology Companies Ranked by Revenue
3.3 Global Wafer Level Glass Technology Revenue by Companies
3.4 Top 3 and Top 5 Wafer Level Glass Technology Companies in Global Market, by Revenue in 2024
3.5 Global Companies Wafer Level Glass Technology Product Type
3.6 Tier 1, Tier 2, and Tier 3 Wafer Level Glass Technology Players in Global Market
3.6.1 List of Global Tier 1 Wafer Level Glass Technology Companies
3.6.2 List of Global Tier 2 and Tier 3 Wafer Level Glass Technology Companies
4 Sights by Product
4.1 Overview
4.1.1 Segmentation by Type – Global Wafer Level Glass Technology Market Size Markets, 2024 & 2032
4.1.2 Micro-Lens Array
4.1.3 Shack-Hartmann Lens Arry
4.1.4 Uniform Compound Eye Lens
4.1.5 Laser Collimator
4.1.6 Others
4.2 Segmentation by Type – Global Wafer Level Glass Technology Revenue & Forecasts
4.2.1 Segmentation by Type – Global Wafer Level Glass Technology Revenue, 2020-2025
4.2.2 Segmentation by Type – Global Wafer Level Glass Technology Revenue, 2026-2032
4.2.3 Segmentation by Type – Global Wafer Level Glass Technology Revenue Market Share, 2026-2034
5 Sights by Application
5.1 Overview
5.1.1 Segmentation by Application – Global Wafer Level Glass Technology Market Size, 2024 & 2032
5.1.2 Consumer Electronics
5.1.3 Vehicle Electronics
5.1.4 Smart Grid
5.1.5 Others
5.2 Segmentation by Application – Global Wafer Level Glass Technology Revenue & Forecasts
5.2.1 Segmentation by Application – Global Wafer Level Glass Technology Revenue, 2020-2025
5.2.2 Segmentation by Application – Global Wafer Level Glass Technology Revenue, 2026-2032
5.2.3 Segmentation by Application – Global Wafer Level Glass Technology Revenue Market Share, 2026-2034
6 Sights by Region
6.1 By Region – Global Wafer Level Glass Technology Market Size, 2024 & 2032
6.2 By Region – Global Wafer Level Glass Technology Revenue & Forecasts
6.2.1 By Region – Global Wafer Level Glass Technology Revenue, 2020-2025
6.2.2 By Region – Global Wafer Level Glass Technology Revenue, 2026-2032
6.2.3 By Region – Global Wafer Level Glass Technology Revenue Market Share, 2026-2034
6.3 North America
6.3.1 By Country – North America Wafer Level Glass Technology Revenue, 2026-2034
6.3.2 United States Wafer Level Glass Technology Market Size, 2026-2034
6.3.3 Canada Wafer Level Glass Technology Market Size, 2026-2034
6.3.4 Mexico Wafer Level Glass Technology Market Size, 2026-2034
6.4 Europe
6.4.1 By Country – Europe Wafer Level Glass Technology Revenue, 2026-2034
6.4.2 Germany Wafer Level Glass Technology Market Size, 2026-2034
6.4.3 France Wafer Level Glass Technology Market Size, 2026-2034
6.4.4 U.K. Wafer Level Glass Technology Market Size, 2026-2034
6.4.5 Italy Wafer Level Glass Technology Market Size, 2026-2034
6.4.6 Russia Wafer Level Glass Technology Market Size, 2026-2034
6.4.7 Nordic Countries Wafer Level Glass Technology Market Size, 2026-2034
6.4.8 Benelux Wafer Level Glass Technology Market Size, 2026-2034
6.5 Asia
6.5.1 By Region – Asia Wafer Level Glass Technology Revenue, 2026-2034
6.5.2 China Wafer Level Glass Technology Market Size, 2026-2034
6.5.3 Japan Wafer Level Glass Technology Market Size, 2026-2034
6.5.4 South Korea Wafer Level Glass Technology Market Size, 2026-2034
6.5.5 Southeast Asia Wafer Level Glass Technology Market Size, 2026-2034
6.5.6 India Wafer Level Glass Technology Market Size, 2026-2034
6.6 South America
6.6.1 By Country – South America Wafer Level Glass Technology Revenue, 2026-2034
6.6.2 Brazil Wafer Level Glass Technology Market Size, 2026-2034
6.6.3 Argentina Wafer Level Glass Technology Market Size, 2026-2034
6.7 Middle East & Africa
6.7.1 By Country – Middle East & Africa Wafer Level Glass Technology Revenue, 2026-2034
6.7.2 Turkey Wafer Level Glass Technology Market Size, 2026-2034
6.7.3 Israel Wafer Level Glass Technology Market Size, 2026-2034
6.7.4 Saudi Arabia Wafer Level Glass Technology Market Size, 2026-2034
6.7.5 UAE Wafer Level Glass Technology Market Size, 2026-2034
7 Companies Profiles
7.1 Himax Technologies, Inc.
7.1.1 Himax Technologies, Inc. Corporate Summary
7.1.2 Himax Technologies, Inc. Business Overview
7.1.3 Himax Technologies, Inc. Wafer Level Glass Technology Major Product Offerings
7.1.4 Himax Technologies, Inc. Wafer Level Glass Technology Revenue in Global Market (2020-2025)
7.1.5 Himax Technologies, Inc. Key News & Latest Developments
7.2 EV Group
7.2.1 EV Group Corporate Summary
7.2.2 EV Group Business Overview
7.2.3 EV Group Wafer Level Glass Technology Major Product Offerings
7.2.4 EV Group Wafer Level Glass Technology Revenue in Global Market (2020-2025)
7.2.5 EV Group Key News & Latest Developments
7.3 Corning
7.3.1 Corning Corporate Summary
7.3.2 Corning Business Overview
7.3.3 Corning Wafer Level Glass Technology Major Product Offerings
7.3.4 Corning Wafer Level Glass Technology Revenue in Global Market (2020-2025)
7.3.5 Corning Key News & Latest Developments
7.4 Tianshui Huatian Technology Co.,Ltd
7.4.1 Tianshui Huatian Technology Co.,Ltd Corporate Summary
7.4.2 Tianshui Huatian Technology Co.,Ltd Business Overview
7.4.3 Tianshui Huatian Technology Co.,Ltd Wafer Level Glass Technology Major Product Offerings
7.4.4 Tianshui Huatian Technology Co.,Ltd Wafer Level Glass Technology Revenue in Global Market (2020-2025)
7.4.5 Tianshui Huatian Technology Co.,Ltd Key News & Latest Developments
7.5 China Wafer Level CSP Co., Ltd.
7.5.1 China Wafer Level CSP Co., Ltd. Corporate Summary
7.5.2 China Wafer Level CSP Co., Ltd. Business Overview
7.5.3 China Wafer Level CSP Co., Ltd. Wafer Level Glass Technology Major Product Offerings
7.5.4 China Wafer Level CSP Co., Ltd. Wafer Level Glass Technology Revenue in Global Market (2020-2025)
7.5.5 China Wafer Level CSP Co., Ltd. Key News & Latest Developments
7.6 AMS AG.
7.6.1 AMS AG. Corporate Summary
7.6.2 AMS AG. Business Overview
7.6.3 AMS AG. Wafer Level Glass Technology Major Product Offerings
7.6.4 AMS AG. Wafer Level Glass Technology Revenue in Global Market (2020-2025)
7.6.5 AMS AG. Key News & Latest Developments
7.7 Largan Precision Co.,Ltd.
7.7.1 Largan Precision Co.,Ltd. Corporate Summary
7.7.2 Largan Precision Co.,Ltd. Business Overview
7.7.3 Largan Precision Co.,Ltd. Wafer Level Glass Technology Major Product Offerings
7.7.4 Largan Precision Co.,Ltd. Wafer Level Glass Technology Revenue in Global Market (2020-2025)
7.7.5 Largan Precision Co.,Ltd. Key News & Latest Developments
7.8 Zhuhai Multiscale Optoelectronics Technology Co.,Ltd
7.8.1 Zhuhai Multiscale Optoelectronics Technology Co.,Ltd Corporate Summary
7.8.2 Zhuhai Multiscale Optoelectronics Technology Co.,Ltd Business Overview
7.8.3 Zhuhai Multiscale Optoelectronics Technology Co.,Ltd Wafer Level Glass Technology Major Product Offerings
7.8.4 Zhuhai Multiscale Optoelectronics Technology Co.,Ltd Wafer Level Glass Technology Revenue in Global Market (2020-2025)
7.8.5 Zhuhai Multiscale Optoelectronics Technology Co.,Ltd Key News & Latest Developments
8 Conclusion
9 Appendix
9.1 Note
9.2 Examples of Clients
9.3 DisclaimerList of Tables
Table 1. Wafer Level Glass Technology Market Opportunities & Trends in Global Market
Table 2. Wafer Level Glass Technology Market Drivers in Global Market
Table 3. Wafer Level Glass Technology Market Restraints in Global Market
Table 4. Key Players of Wafer Level Glass Technology in Global Market
Table 5. Top Wafer Level Glass Technology Players in Global Market, Ranking by Revenue (2024)
Table 6. Global Wafer Level Glass Technology Revenue by Companies, (US$, Mn), 2020-2025
Table 7. Global Wafer Level Glass Technology Revenue Share by Companies, 2020-2025
Table 8. Global Companies Wafer Level Glass Technology Product Type
Table 9. List of Global Tier 1 Wafer Level Glass Technology Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 10. List of Global Tier 2 and Tier 3 Wafer Level Glass Technology Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 11. Segmentation by Type – Global Wafer Level Glass Technology Revenue, (US$, Mn), 2024 & 2032
Table 12. Segmentation by Type – Global Wafer Level Glass Technology Revenue (US$, Mn), 2020-2025
Table 13. Segmentation by Type – Global Wafer Level Glass Technology Revenue (US$, Mn), 2026-2032
Table 14. Segmentation by Application– Global Wafer Level Glass Technology Revenue, (US$, Mn), 2024 & 2032
Table 15. Segmentation by Application – Global Wafer Level Glass Technology Revenue, (US$, Mn), 2020-2025
Table 16. Segmentation by Application – Global Wafer Level Glass Technology Revenue, (US$, Mn), 2026-2032
Table 17. By Region– Global Wafer Level Glass Technology Revenue, (US$, Mn), 2024 & 2032
Table 18. By Region – Global Wafer Level Glass Technology Revenue, (US$, Mn), 2020-2025
Table 19. By Region – Global Wafer Level Glass Technology Revenue, (US$, Mn), 2026-2032
Table 20. By Country – North America Wafer Level Glass Technology Revenue, (US$, Mn), 2020-2025
Table 21. By Country – North America Wafer Level Glass Technology Revenue, (US$, Mn), 2026-2032
Table 22. By Country – Europe Wafer Level Glass Technology Revenue, (US$, Mn), 2020-2025
Table 23. By Country – Europe Wafer Level Glass Technology Revenue, (US$, Mn), 2026-2032
Table 24. By Region – Asia Wafer Level Glass Technology Revenue, (US$, Mn), 2020-2025
Table 25. By Region – Asia Wafer Level Glass Technology Revenue, (US$, Mn), 2026-2032
Table 26. By Country – South America Wafer Level Glass Technology Revenue, (US$, Mn), 2020-2025
Table 27. By Country – South America Wafer Level Glass Technology Revenue, (US$, Mn), 2026-2032
Table 28. By Country – Middle East & Africa Wafer Level Glass Technology Revenue, (US$, Mn), 2020-2025
Table 29. By Country – Middle East & Africa Wafer Level Glass Technology Revenue, (US$, Mn), 2026-2032
Table 30. Himax Technologies, Inc. Corporate Summary
Table 31. Himax Technologies, Inc. Wafer Level Glass Technology Product Offerings
Table 32. Himax Technologies, Inc. Wafer Level Glass Technology Revenue (US$, Mn) & (2020-2025)
Table 33. Himax Technologies, Inc. Key News & Latest Developments
Table 34. EV Group Corporate Summary
Table 35. EV Group Wafer Level Glass Technology Product Offerings
Table 36. EV Group Wafer Level Glass Technology Revenue (US$, Mn) & (2020-2025)
Table 37. EV Group Key News & Latest Developments
Table 38. Corning Corporate Summary
Table 39. Corning Wafer Level Glass Technology Product Offerings
Table 40. Corning Wafer Level Glass Technology Revenue (US$, Mn) & (2020-2025)
Table 41. Corning Key News & Latest Developments
Table 42. Tianshui Huatian Technology Co.,Ltd Corporate Summary
Table 43. Tianshui Huatian Technology Co.,Ltd Wafer Level Glass Technology Product Offerings
Table 44. Tianshui Huatian Technology Co.,Ltd Wafer Level Glass Technology Revenue (US$, Mn) & (2020-2025)
Table 45. Tianshui Huatian Technology Co.,Ltd Key News & Latest Developments
Table 46. China Wafer Level CSP Co., Ltd. Corporate Summary
Table 47. China Wafer Level CSP Co., Ltd. Wafer Level Glass Technology Product Offerings
Table 48. China Wafer Level CSP Co., Ltd. Wafer Level Glass Technology Revenue (US$, Mn) & (2020-2025)
Table 49. China Wafer Level CSP Co., Ltd. Key News & Latest Developments
Table 50. AMS AG. Corporate Summary
Table 51. AMS AG. Wafer Level Glass Technology Product Offerings
Table 52. AMS AG. Wafer Level Glass Technology Revenue (US$, Mn) & (2020-2025)
Table 53. AMS AG. Key News & Latest Developments
Table 54. Largan Precision Co.,Ltd. Corporate Summary
Table 55. Largan Precision Co.,Ltd. Wafer Level Glass Technology Product Offerings
Table 56. Largan Precision Co.,Ltd. Wafer Level Glass Technology Revenue (US$, Mn) & (2020-2025)
Table 57. Largan Precision Co.,Ltd. Key News & Latest Developments
Table 58. Zhuhai Multiscale Optoelectronics Technology Co.,Ltd Corporate Summary
Table 59. Zhuhai Multiscale Optoelectronics Technology Co.,Ltd Wafer Level Glass Technology Product Offerings
Table 60. Zhuhai Multiscale Optoelectronics Technology Co.,Ltd Wafer Level Glass Technology Revenue (US$, Mn) & (2020-2025)
Table 61. Zhuhai Multiscale Optoelectronics Technology Co.,Ltd Key News & Latest Developments

List of Figures
Figure 1. Wafer Level Glass Technology Product Picture
Figure 2. Wafer Level Glass Technology Segment by Type in 2024
Figure 3. Wafer Level Glass Technology Segment by Application in 2024
Figure 4. Global Wafer Level Glass Technology Market Overview: 2024
Figure 5. Key Caveats
Figure 6. Global Wafer Level Glass Technology Market Size: 2024 VS 2032 (US$, Mn)
Figure 7. Global Wafer Level Glass Technology Revenue: 2026-2034 (US$, Mn)
Figure 8. The Top 3 and 5 Players Market Share by Wafer Level Glass Technology Revenue in 2024
Figure 9. Segmentation by Type – Global Wafer Level Glass Technology Revenue, (US$, Mn), 2024 & 2032
Figure 10. Segmentation by Type – Global Wafer Level Glass Technology Revenue Market Share, 2026-2034
Figure 11. Segmentation by Application – Global Wafer Level Glass Technology Revenue, (US$, Mn), 2024 & 2032
Figure 12. Segmentation by Application – Global Wafer Level Glass Technology Revenue Market Share, 2026-2034
Figure 13. By Region – Global Wafer Level Glass Technology Revenue Market Share, 2026-2034
Figure 14. By Country – North America Wafer Level Glass Technology Revenue Market Share, 2026-2034
Figure 15. United States Wafer Level Glass Technology Revenue, (US$, Mn), 2026-2034
Figure 16. Canada Wafer Level Glass Technology Revenue, (US$, Mn), 2026-2034
Figure 17. Mexico Wafer Level Glass Technology Revenue, (US$, Mn), 2026-2034
Figure 18. By Country – Europe Wafer Level Glass Technology Revenue Market Share, 2026-2034
Figure 19. Germany Wafer Level Glass Technology Revenue, (US$, Mn), 2026-2034
Figure 20. France Wafer Level Glass Technology Revenue, (US$, Mn), 2026-2034
Figure 21. U.K. Wafer Level Glass Technology Revenue, (US$, Mn), 2026-2034
Figure 22. Italy Wafer Level Glass Technology Revenue, (US$, Mn), 2026-2034
Figure 23. Russia Wafer Level Glass Technology Revenue, (US$, Mn), 2026-2034
Figure 24. Nordic Countries Wafer Level Glass Technology Revenue, (US$, Mn), 2026-2034
Figure 25. Benelux Wafer Level Glass Technology Revenue, (US$, Mn), 2026-2034
Figure 26. By Region – Asia Wafer Level Glass Technology Revenue Market Share, 2026-2034
Figure 27. China Wafer Level Glass Technology Revenue, (US$, Mn), 2026-2034
Figure 28. Japan Wafer Level Glass Technology Revenue, (US$, Mn), 2026-2034
Figure 29. South Korea Wafer Level Glass Technology Revenue, (US$, Mn), 2026-2034
Figure 30. Southeast Asia Wafer Level Glass Technology Revenue, (US$, Mn), 2026-2034
Figure 31. India Wafer Level Glass Technology Revenue, (US$, Mn), 2026-2034
Figure 32. By Country – South America Wafer Level Glass Technology Revenue Market Share, 2026-2034
Figure 33. Brazil Wafer Level Glass Technology Revenue, (US$, Mn), 2026-2034
Figure 34. Argentina Wafer Level Glass Technology Revenue, (US$, Mn), 2026-2034
Figure 35. By Country – Middle East & Africa Wafer Level Glass Technology Revenue Market Share, 2026-2034
Figure 36. Turkey Wafer Level Glass Technology Revenue, (US$, Mn), 2026-2034
Figure 37. Israel Wafer Level Glass Technology Revenue, (US$, Mn), 2026-2034
Figure 38. Saudi Arabia Wafer Level Glass Technology Revenue, (US$, Mn), 2026-2034
Figure 39. UAE Wafer Level Glass Technology Revenue, (US$, Mn), 2026-2034
Figure 40. Himax Technologies, Inc. Wafer Level Glass Technology Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 41. EV Group Wafer Level Glass Technology Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 42. Corning Wafer Level Glass Technology Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 43. Tianshui Huatian Technology Co.,Ltd Wafer Level Glass Technology Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 44. China Wafer Level CSP Co., Ltd. Wafer Level Glass Technology Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 45. AMS AG. Wafer Level Glass Technology Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 46. Largan Precision Co.,Ltd. Wafer Level Glass Technology Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 47. Zhuhai Multiscale Optoelectronics Technology Co.,Ltd Wafer Level Glass Technology Revenue Year Over Year Growth (US$, Mn) & (2020-2025)