Key Statistics
Key Takeaways
- Market size and growth: USD 307.8 million in 2025, rising to USD 542.1 million by 2034 at a 6.5% CAGR over 2026–2034.
- Asia Pacific is the largest market in 2025 because the region combines major end-use demand with a dense electronics and semiconductor supply base.
- Amplifier is a core product category, while technology migration is increasing the value of higher-performance and application-specific variants.
- Primary demand driver: Demand for precise, click-free and digitally programmable audio gain control is expanding across professional audio, smart speakers, automotive infotainment and premium consumer devices.
- Structural restraint: Designers must manage noise, distortion, channel tracking, power consumption and control-interface integration while competing against highly integrated audio codecs and DSPs.
- Growth opportunity: Spatial audio, multi-zone automotive systems and AI-assisted adaptive audio create opportunities for higher-channel-count and digitally networked gain-control devices.
Volume Control ICs Market Overview
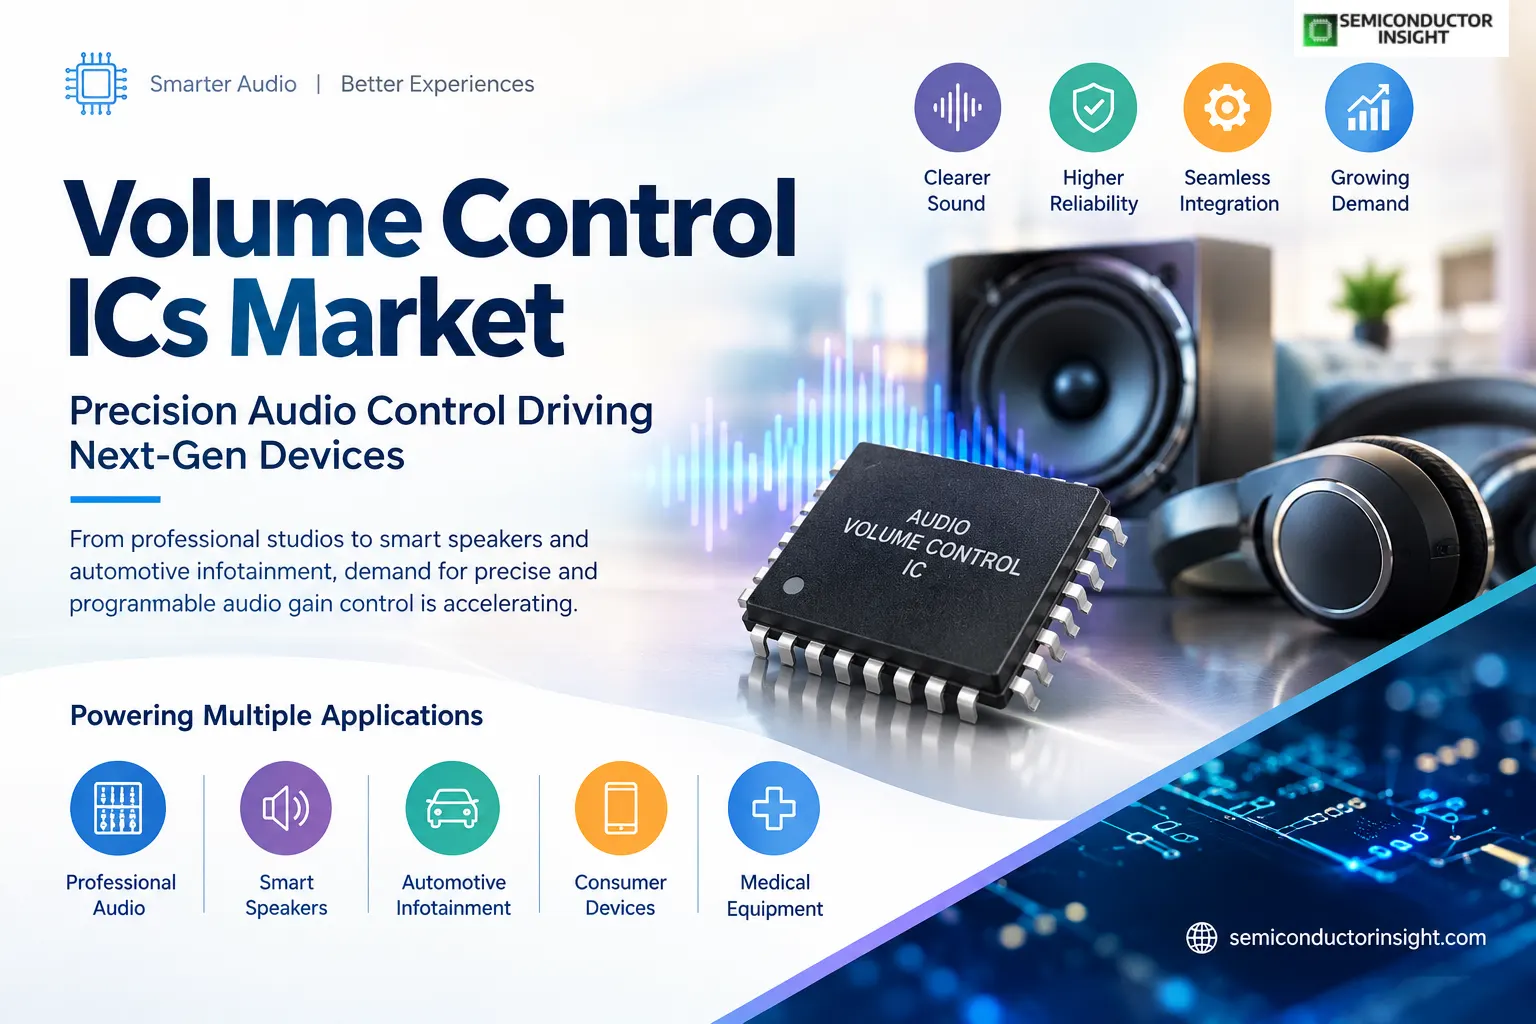
volume control ICs market was valued at USD 307.8 million in 2025 and is projected to reach USD 542.1 million by 2034, expanding at a CAGR of 6.5% during 2026–2034. Asia Pacific is the largest regional market in 2025.
Volume Control ICs is a specialized electronics market in which performance, reliability and system integration determine purchasing decisions. Buyers typically qualify products against electrical, thermal, mechanical and lifecycle requirements before a supplier can enter a production program. This creates meaningful switching costs once a design is approved, while also raising the technical threshold for new suppliers seeking high-volume business.
Demand for precise, click-free and digitally programmable audio gain control is expanding across professional audio, smart speakers, automotive infotainment and premium consumer devices. The commercial effect is a shift from commodity selection toward application-specific products that deliver measurable system benefits. Suppliers that can document reliability, maintain stable lead times and support customer engineering teams are positioned to capture a larger share of recurring design-win revenue.
Production uses mature mixed-signal and analog semiconductor processes, so capacity is geographically diversified but still exposed to foundry allocation and specialty analog-node availability. This geographic concentration matters because supply security now influences sourcing alongside price and performance. OEMs increasingly seek dual sourcing, regional inventory and long-term capacity visibility, especially for components used in high-value systems where a shortage can delay an entire platform launch.
Segment Analysis: By Type
By type, the market includes Amplifier, Attenuator, Digital Signal Processor, Hybrid IC, Others. Product selection depends on the balance between performance, integration complexity, thermal behavior, qualification requirements and cost. The largest revenue pool is concentrated in established architectures, while newer variants generally grow faster when they solve a clear system bottleneck.
| Type | Commercial role | Market position |
|---|---|---|
| Amplifier | Defines the main product architecture and purchasing specification. | Leading / core segment. Demand depends on performance, qualification, supply continuity and total system economics rather than a single component specification. |
| Attenuator | Defines the main product architecture and purchasing specification. | High-growth segment. Demand depends on performance, qualification, supply continuity and total system economics rather than a single component specification. |
| Digital Signal Processor | Defines the main product architecture and purchasing specification. | Established segment. Demand depends on performance, qualification, supply continuity and total system economics rather than a single component specification. |
| Hybrid IC | Defines the main product architecture and purchasing specification. | Established segment. Demand depends on performance, qualification, supply continuity and total system economics rather than a single component specification. |
| Others | Defines the main product architecture and purchasing specification. | Established segment. Demand depends on performance, qualification, supply continuity and total system economics rather than a single component specification. |
Segment Analysis: By Application
By application, demand spans Professional Studio, High-End Studio, Consumer Electronics, Automotive Audio Systems, Others. Purchasing behavior differs materially across these applications because system reliability, operating environment, qualification duration and replacement cost vary. High-value applications favor suppliers with deeper engineering support, while consumer and high-volume applications place greater weight on unit economics and manufacturing scale.
| Application | Purchasing trigger | Demand characteristics |
|---|---|---|
| Professional Studio | Links demand to system-level performance and qualification requirements. | Leading / core segment. Demand depends on performance, qualification, supply continuity and total system economics rather than a single component specification. |
| High-End Studio | Links demand to system-level performance and qualification requirements. | High-growth segment. Demand depends on performance, qualification, supply continuity and total system economics rather than a single component specification. |
| Consumer Electronics | Links demand to system-level performance and qualification requirements. | Established segment. Demand depends on performance, qualification, supply continuity and total system economics rather than a single component specification. |
| Automotive Audio Systems | Links demand to system-level performance and qualification requirements. | Established segment. Demand depends on performance, qualification, supply continuity and total system economics rather than a single component specification. |
| Others | Links demand to system-level performance and qualification requirements. | Established segment. Demand depends on performance, qualification, supply continuity and total system economics rather than a single component specification. |
By Control Interface
| Control Interface | Market relevance |
|---|---|
| SPI | Relevant to product selection, qualification and supplier differentiation. |
| I2C | Relevant to product selection, qualification and supplier differentiation. |
| Pushbutton | Relevant to product selection, qualification and supplier differentiation. |
| Serial | Relevant to product selection, qualification and supplier differentiation. |
By End Use
| End Use | Market relevance |
|---|---|
| Professional Audio | Creates a distinct design, performance or procurement requirement within the market. |
| Consumer Electronics | Creates a distinct design, performance or procurement requirement within the market. |
| Automotive | Creates a distinct design, performance or procurement requirement within the market. |
| Medical | Creates a distinct design, performance or procurement requirement within the market. |
Regional Analysis
Asia Pacific leads the volume control ICs market in 2025. Regional demand differs by manufacturing concentration, end-use investment, qualification requirements and access to local supply chains. The strongest opportunities are therefore not identical across regions, even where the same product family is used.
How does regional demand differ across the market?
Regional competition is shaped by where products are designed, where they are manufactured and where the final systems are deployed. Asia Pacific benefits from electronics and semiconductor manufacturing density, North America concentrates advanced system design and cloud or defense demand, while Europe remains important in automotive, industrial and regulation-led applications. South America and the Middle East & Africa are smaller but can generate attractive project-led demand.
| Region | Position | Growth outlook | Demand profile |
|---|---|---|---|
| Asia Pacific | Largest | High | Largest market because audio electronics manufacturing, smartphones, smart speakers and automotive electronics are concentrated in China, Japan, South Korea and Southeast Asia. |
| North America | Established | High | High-value demand comes from professional audio, semiconductor design and automotive infotainment platforms. |
| Europe | Established | Moderate | Automotive and premium audio applications support demand for low-noise and highly reliable devices. |
| South America | Established | Moderate | Import-led consumer and automotive electronics account for most demand. |
| Middle East & Africa | Established | Moderate | Premium hospitality, entertainment and consumer electronics drive a smaller but expanding market. |
Competitive Landscape
Competition is driven by technical qualification, customer access, manufacturing consistency and the ability to support product transitions. Market leaders generally combine proprietary process knowledge with broad application engineering, while specialist suppliers compete through narrower performance advantages, customization or regional service.
The competitive structure rewards suppliers that can convert R&D into qualified production rather than simply demonstrating laboratory performance. Long customer qualification cycles protect incumbents once designed in, but they also create opportunities during architecture changes when OEMs reconsider vendors, package formats and performance targets.
Supply reliability has become a central differentiator. Customers increasingly evaluate capacity commitments, geographic resilience, quality systems and lifecycle support in parallel with electrical specifications. This favors companies able to coordinate manufacturing, test, logistics and engineering support across multiple regions.
| Company | Position | Competitive focus |
|---|---|---|
| Texas Instruments | Established participant | Competes through technology, qualification, portfolio breadth and customer relationships. |
| STMicroelectronics | Established participant | Competes through technology, qualification, portfolio breadth and customer relationships. |
| Analog Devices | Established participant | Competes through technology, qualification, portfolio breadth and customer relationships. |
| Renesas Electronics | Established participant | Competes through technology, qualification, portfolio breadth and customer relationships. |
| onsemi | Established participant | Competes through technology, qualification, portfolio breadth and customer relationships. |
| Diodes Incorporated | Established participant | Competes through technology, qualification, portfolio breadth and customer relationships. |
| Toshiba | Established participant | Competes through technology, qualification, portfolio breadth and customer relationships. |
Production Capacity Analysis
Production uses mature mixed-signal and analog semiconductor processes, so capacity is geographically diversified but still exposed to foundry allocation and specialty analog-node availability.
Capacity expansion is not determined by floor space alone. Yield learning, specialty equipment, trained personnel, material quality and customer qualification can all delay effective output after new equipment is installed. For this reason, announced capacity and immediately usable market supply can diverge, especially in advanced products with tight process windows.
Market Dynamics
The market is shaped by a combination of end-system performance requirements, technology migration, supply-chain resilience and cost pressure. Growth is strongest where the component removes a system bottleneck or enables a new architecture, while adoption slows when qualification complexity or alternative technologies reduce the economic advantage.
Demand for precise, click-free and digitally programmable audio gain control is expanding across professional audio, smart speakers, automotive infotainment and premium consumer devices. At the same time, designers must manage noise, distortion, channel tracking, power consumption and control-interface integration while competing against highly integrated audio codecs and dsps. Suppliers therefore need to balance innovation with manufacturability, reliability and commercial discipline.
Market Drivers
Drivers Impact Analysis
| Driver | Impact | Commercial implication |
|---|---|---|
| System performance | High | Directly increases component content or value per system. |
| Technology migration | High | Creates replacement and redesign opportunities. |
| Supply resilience | Medium | Favors qualified vendors with stable capacity. |
System-level performance requirements
Demand for precise, click-free and digitally programmable audio gain control is expanding across professional audio, smart speakers, automotive infotainment and premium consumer devices. This directly affects vendor selection because component-level specifications increasingly translate into measurable platform performance, energy efficiency, thermal headroom or reliability. Products that create a clear system benefit can sustain better pricing and deeper customer engagement.
Design complexity and integration
As electronic systems become more integrated, component suppliers are expected to provide reference designs, simulation support, qualification data and predictable lifecycle management. This broadens competition beyond unit price and favors vendors that can reduce engineering time for OEMs while maintaining stable production quality.
Electrification and digitalization
The continued shift toward connected, electrified and software-defined systems increases the number and value of electronics used in vehicles, industrial equipment, data centers and consumer devices. This expands the addressable opportunity for suppliers whose products improve power efficiency, signal integrity, memory bandwidth, durability or user experience.
Regional supply-chain investment
Governments and manufacturers are investing in more resilient electronics and semiconductor supply chains. Even where these programs do not directly subsidize the market, they influence localization, inventory strategy and supplier qualification, creating opportunities for vendors with manufacturing or engineering support close to major customers.
Market Restraints
Restraints Impact Analysis
| Restraint | Impact | Commercial implication |
|---|---|---|
| Qualification burden | High | Lengthens time to revenue and raises engineering cost. |
| Input cost volatility | Medium | Compresses margins when contracts limit price changes. |
| Alternative technologies | Medium | Can reduce content per system in selected applications. |
Qualification and integration cost
Designers must manage noise, distortion, channel tracking, power consumption and control-interface integration while competing against highly integrated audio codecs and DSPs. These barriers slow supplier switching and can delay commercialization, particularly when products enter safety-critical, high-reliability or high-volume platforms. Smaller suppliers may have strong technology but still face long sales cycles before meaningful production revenue begins.
Cost pressure and substitution
OEMs continue to reduce bill-of-material cost and consolidate functions into more integrated devices. Suppliers must therefore show that the component provides a measurable system advantage. Where that advantage is weak, buyers may substitute lower-cost alternatives or redesign the function into another subsystem.
Market Opportunities
Next-generation architectures
Spatial audio, multi-zone automotive systems and AI-assisted adaptive audio create opportunities for higher-channel-count and digitally networked gain-control devices. Vendors that engage early with platform designers can shape specifications, improve design-win probability and secure longer revenue lifecycles once the architecture moves into production.
Application-specific products
Specialized products for automotive, industrial, AI, medical or aerospace systems can command stronger margins because qualification requirements are tighter and failure costs are higher. The commercial opportunity is strongest where suppliers combine product performance with documentation, traceability and long-term availability.
Regional localization
Customers are diversifying sourcing and building more regional resilience into electronics supply chains. Local technical support, shorter logistics routes and qualified second-source options can therefore become competitive advantages even when manufacturing economics still favor a concentrated global production base.
Lifecycle services
Engineering support, failure analysis, reliability data and product-change management create service-based differentiation around the physical component. These capabilities strengthen customer retention and can reduce the risk of substitution when a market moves through technology transitions or periods of constrained supply.
Supply Chain Analysis
| Stage | Value creation and bottlenecks |
|---|---|
| Raw materials / upstream | Purity, consistency, specialty materials and process inputs determine yield and performance. |
| Component manufacturing | Value is created through process control, device architecture, testing and product-specific qualification. |
| Packaging / integration | System integration determines thermal performance, reliability, footprint and manufacturability. |
| OEM / end user | Design wins, lifecycle support and supply assurance determine recurring revenue and replacement demand. |
The upstream stage determines material consistency and the starting cost structure. Manufacturing then converts process control into yield and product performance, while packaging or integration determines whether the component can meet system-level thermal, mechanical and electrical requirements. The OEM stage captures value through design ownership, platform integration and end-market access. Bottlenecks at any stage can affect the whole chain because qualification limits rapid supplier substitution.
Recent Developments
Report Scope & Segmentation
| Attribute | Coverage |
|---|---|
| Market definition | Volume Control ICs products and systems covered by the stated segmentation. |
| Base year | 2025 |
| Estimated year | 2026 |
| Forecast period | 2026–2034 |
| By Type | Amplifier, Attenuator, Digital Signal Processor, Hybrid IC, Others |
| By Application | Professional Studio, High-End Studio, Consumer Electronics, Automotive Audio Systems, Others |
| By Control Interface | SPI, I2C, Pushbutton, Serial |
| By End Use | Professional Audio, Consumer Electronics, Automotive, Medical |
| Regions | North America, Europe, Asia Pacific, South America, Middle East & Africa |
| Companies | Texas Instruments, STMicroelectronics, Analog Devices, Renesas Electronics, onsemi, Diodes Incorporated, Toshiba |
Frequently Asked Questions
What is the Volume Control ICs market size in 2025?
What is the projected Volume Control ICs market size by 2034?
What is the CAGR of the Volume Control ICs market from 2026 to 2034?
Which region leads the Volume Control ICs market?
What are the main product types?
What are the key applications?
What is the main growth driver?
What is the main restraint?
Where are the strongest opportunities?
Which companies are active in the market?
Research Sources & Evidence Base
View primary and official sources used in this overview
- Texas Instruments: PGA2311 stereo audio volume control.
- Analog Devices: Digital potentiometers for audio and control applications.
- Analog Devices: DS1882 dual log audio digital potentiometer.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF