SEMICONDUCTOR INSIGHT
MARKET RESEARCH REPORT

Two Dimensional Optical Position Sensor Market

2026 to 2034
MARKET INTELLIGENCE
ACROSS KEY REGIONS
2026 EDITION
SENSORS Semiconductor Market Research

Two Dimensional Optical Position Sensor Market

◷
UPDATED 28 October 2026
▤
REPORT LENGTH Detailed Report
▣
REPORT CODE 0d42aa92c9d4
▯
FORMATS PDF

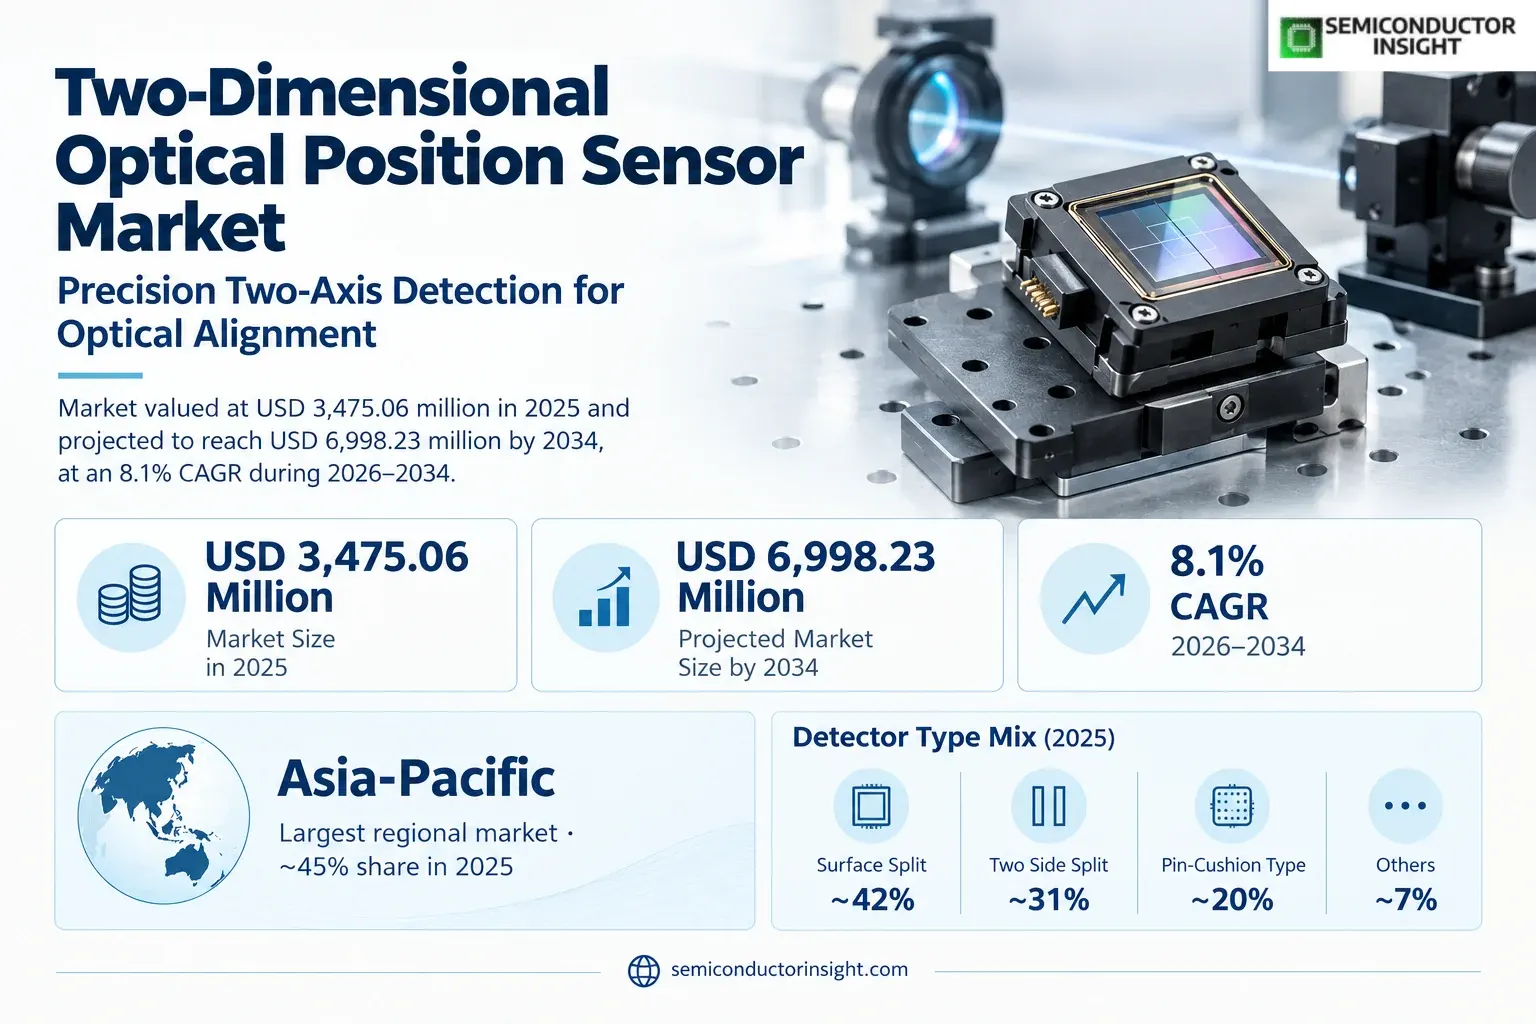
Two dimensional optical position sensor market was valued at USD 3,475.06 million in 2025 and is projected to reach USD 6,998.23 million by 2034, representing a CAGR of 8.1% during 2026–2034. Asia-Pacific is the largest region, accounting for an estimated ~45% of 2025 revenue as electronic assembly, optical alignment and industrial measurement require two-axis feedback.

Get the sample PDF with study scope, segmentation and methodology details.

Key Statistics

2025 Market Size
USD 3,475.06 million
2034 Projected Size
USD 6,998.23 million
CAGR (2026–2034)
8.1%
Largest Market in 2025
Asia-Pacific (~45%)

Key Takeaways

  • Market trajectory: The market was valued at USD 3,475.06 million in 2025 and is forecast to reach USD 6,998.23 million by 2034, with a 8.1% CAGR for 2026–2034. The projection covers qualifying two-axis optical position-sensing components, rather than the entire revenue of manufacturers that also sell cameras and laser displacement equipment.
  • Surface-split detectors: This category held an estimated ~42% of 2025 type revenue, with two-side-split products at ~31% and pin-cushion geometries at ~20%. The respective 2034 modeled values of USD 2,694.3 million, USD 2,239.4 million and USD 1,609.6 million reflect different response, packaging and linearity requirements.
  • Consumer electronics and automation: Consumer electronics accounted for an estimated ~35% of application revenue, followed by industrial automation at ~26% and automotive at ~20%. Laser-based sensing represented ~46% of technology revenue, whereas infrared and LED-based implementations addressed illumination and power requirements that differ by equipment design.
  • Regional leadership: Asia-Pacific represented an estimated ~45% of the 2025 market and is modeled to grow at ~8.9% CAGR, supported by precision assembly and optical component manufacturing. North America followed at ~27%, with Europe at ~21%; these are analytical allocations rather than measured sales disclosures from suppliers.
  • Competitive and technical considerations: Hamamatsu Photonics and SiTek offer direct two-dimensional position-sensitive detectors; LASER COMPONENTS distributes SiTek products and associated electronics. Micro-Epsilon and Renishaw demonstrate adjacent industrial positioning demand, but their complete displacement sensors and optical encoders are not treated as identical component products.

Two Dimensional Optical Position Sensor Market Overview

Two dimensional optical position sensor market was valued at USD 3,475.06 million in 2025 and is projected to reach USD 6,998.23 million by 2034, representing a CAGR of 8.1% during 2026–2034. Asia-Pacific is the largest region, accounting for an estimated ~45% of 2025 revenue as electronic assembly, optical alignment and industrial measurement require two-axis feedback.

Base year: 2025 · Estimated year: 2026 · Forecast period: 2026–2034 · Historical context: 2021–2024 · Values in USD million

A two-dimensional position-sensitive detector converts the location of an incident light spot into two continuous electrical coordinates. Unlike a camera, a lateral-effect photodiode does not require a pixel-by-pixel image readout to locate a beam centroid; the ratio of currents collected at opposing contacts provides the horizontal and vertical signal. This architecture is useful in alignment, vibration monitoring, beam stabilization and optical feedback where response time and repeatability can be more important than image detail. The product boundary includes qualifying detector components and directly integrated sensing electronics, not the value of complete machines into which they are installed.

The product mix spans surface-split, two-side-split and pin-cushion arrangements. Detector geometry affects active-area size, spot-position linearity, stray-light sensitivity and the circuitry needed to convert photocurrent into stable coordinates. Hamamatsu lists a 9 × 9 mm active area and a 2 microsecond typical rise time for its S15535 surface-mount device; the compact package supports placement onto populated electronic assemblies. By comparison, SiTek products distributed by LASER COMPONENTS extend from 2 × 2 mm to 45 × 45 mm active areas, demonstrating that optical aperture is not a single standard size across applications.

The revenue object follows the position-sensing component rather than every product described by the broad phrase optical sensor. A finished laser triangulation instrument contains emitters, optics, calibration hardware and signal processing, while an optical encoder reads a patterned scale or disk and uses a different measurement architecture. Both can compete for positioning budgets without belonging in the same detector shipment count. The distinction also prevents supplier-wide revenue from being mistaken for sales of two-axis photodiodes, particularly when the supplier operates across industrial metrology, imaging, machine vision and semiconductor inspection.

Demand is influenced by how equipment makers distribute measurement intelligence. An analog PSD may feed an external transimpedance amplifier and controller, while a module can combine the sensing element and conditioned output in one purchased assembly. SiTek SPC-PSD offerings provide four transimpedance stages and coordinate-related signals, allowing buyers to reduce analog design effort. Integration can increase the component selling price but also creates competition from custom boards built by equipment manufacturers. Purchasers therefore evaluate detector linearity, optical power range, noise, temperature drift, mounting tolerance and the engineering time required to qualify the full signal chain.

The market outlook is shaped by precision electronics assembly, laser-based measurement, automated material handling and specialized medical instrumentation. Faster motion-control systems require feedback with predictable latency, but adoption is not automatic: a camera, encoder or time-of-flight sensor can be more suitable when a customer needs scene recognition, absolute travel or depth rather than the centroid of a light spot. The forecast accordingly combines replacement demand from established industrial installations with new design wins in compact electronics and laboratory equipment, while recognizing component-level price competition and long qualification cycles.

Segment Analysis: By Type

By type, the market is divided into Surface Split, Two Side Split, Pin-Cushion Type and Others. Surface Split is the largest 2025 category at an estimated ~42% share and a modeled ~7.0% CAGR. Two Side Split contributes ~31% and is projected to grow ~8.5%, while Pin-Cushion Type, at ~20%, has a modeled ~9.8% CAGR because some precision systems require geometry-specific response characteristics. These labels describe the publisher segmentation, not an industry-wide standards classification.

Type Detector role and technical selection Market position and modeled value
Surface Split Continuous two-axis position sensing using surface electrode layouts; chosen for compact beam tracking, alignment fixtures and embedded optical feedback. Packaging can favor surface-mount production and automated board assembly when the optical spot geometry is controlled. Estimated ~42% of 2025 revenue; USD 1,459.5 million base value, USD 2,694.3 million by 2034 and ~7.0% CAGR. The larger installed application base supports steady orders even when premium geometries grow faster.
Two Side Split Alternative contact arrangement serving two-coordinate detection with design-specific linearity and biasing requirements. Selection depends on active area, sensitivity, illumination profile and compatibility with an equipment maker’s analog front end. Estimated ~31% share, USD 1,077.3 million in 2025 and USD 2,239.4 million in 2034. The modeled ~8.5% CAGR reflects continuing use in alignment equipment and optical monitoring subsystems.
Pin-Cushion Type Tetra-lateral configurations associated with distinct spatial-response trade-offs; Hamamatsu S5991-01 and S5990-01 illustrate commercial pin-cushion PSD products. Integrators consider correction, calibration and optical spot movement across the active surface. Estimated ~20% of revenue, equivalent to USD 695.0 million in 2025. A modeled ~9.8% CAGR gives a USD 1,609.6 million 2034 segment forecast, although product qualification can slow adoption.
Others Custom and specialized geometries not captured by the principal categories, including configurations optimized for a particular aperture, coating, wavelength response or packaging constraint. These tend to be project-specific purchases. Estimated ~7% share, USD 243.3 million in the base year and USD 454.9 million by 2034, with a modeled ~7.2% CAGR. Limited scale can support higher unit prices but restrict volume.

Technology and end-use segmentation

Technology is classified by the illumination approach surrounding the sensing component: Laser-Based, Infrared, LED-Based and Others. Laser-Based designs account for an estimated ~46% of 2025 revenue, with an implied USD 1,598.5 million component opportunity, while Infrared contributes ~25% and LED-Based ~20%. The light source is not necessarily part of the PSD itself; these categories indicate the measurement configuration in which a qualifying two-dimensional position sensor operates. For this reason, technology shares should not be read as revenue for lasers or LED emitters.

Axis and member 2025 share 2025 value, USD m 2034 value, USD m Modeled CAGR
Technology: Laser-Based ~46% 1,598.5 3,499.1 ~9.1%
Technology: Infrared ~25% 868.8 1,679.6 ~7.6%
Technology: LED-Based ~20% 695.0 1,329.7 ~7.5%
Technology: Others ~9% 312.8 489.9 ~5.1%
End use: Electronics Manufacturing ~34% 1,181.5 2,239.4 ~7.4%
End use: Automotive ~23% 799.3 1,749.6 ~9.1%
End use: Healthcare ~14% 486.5 1,014.7 ~8.5%
End use: Industrial ~18% 625.5 1,329.7 ~8.7%
End use: Aerospace and Defense ~7% 243.3 454.9 ~7.2%
End use: Others ~4% 139.0 209.9 ~4.7%

Electronics Manufacturing represents an estimated ~34% of end-use revenue, compared with ~23% for Automotive and ~18% for Industrial buyers. These end-user allocations differ from application categories because a detector used in an automotive production line may be purchased by an industrial-equipment builder but ultimately serve vehicle manufacturing. Healthcare contributes ~14% of modeled end-use revenue through specialized optical instruments. The forecast places Aerospace and Defense at ~7% and residual end users at ~4%, with all six categories summing to 100% for the base year.

Segment Analysis: By Application

Applications are segmented into Consumer Electronics, Automotive, Industrial Automation, Medical Devices, Aerospace and Defense, and Others. Consumer Electronics held an estimated ~35% share in 2025, while Industrial Automation accounted for ~26% and Automotive for ~20%. The modeled growth rates differ: automotive applications advance at ~10.3% CAGR, industrial automation at ~8.5%, and consumer electronics at ~6.6%, reflecting varying rates of sensor integration and equipment replacement.

Application Demand characteristics
Consumer Electronics Estimated ~35% share; USD 1,216.3 million in 2025 and USD 2,169.5 million in 2034. Optical alignment, compact position feedback and calibration systems support the broadest unit demand, while consumer product cost targets limit detector pricing. Modeled growth is ~6.6% CAGR.
Automotive Estimated ~20% share, with USD 695.0 million in 2025 and USD 1,679.6 million in 2034. Optical test fixtures, vehicle-component alignment and specialized measurement modules create demand; an estimated ~10.3% CAGR reflects increasing precision requirements, not a claim that every vehicle uses a standalone PSD.
Industrial Automation Estimated ~26% share and USD 903.5 million base-year revenue. Robotic tooling, machine calibration and laser alignment support a modeled USD 1,889.5 million 2034 value and ~8.5% CAGR. Alternatives include encoder feedback and finished triangulation instruments, so component selection depends on measurement geometry.
Medical Devices Estimated ~9% share, USD 312.8 million in 2025 and USD 664.8 million by 2034. Optical instruments and alignment modules can use fast spot-centroid feedback, although medical qualification and system validation slow redesigns. The segment is modeled at ~8.7% CAGR.
Aerospace and Defense Estimated ~6% of application revenue, corresponding to USD 208.5 million in 2025 and USD 384.9 million in 2034. Ruggedized beam-position monitoring and precision optical subsystems are specialized opportunities with a modeled ~7.0% CAGR, but qualification volumes are smaller.
Others Estimated ~4% share and USD 139.0 million in 2025. Laboratory experiments, educational systems and specialized optical feedback create diverse small orders. The modeled USD 209.9 million forecast and ~4.7% CAGR reflect a fragmented application base with limited repeat production.

The difference between application and end-user classifications matters when sizing revenue. A detector shipped into an industrial robot used for electronics assembly is classified by its immediate measurement task in one view and by the customer industry in another. These are separate, non-additive slices of the same market, not incremental revenue pools. Equipment makers frequently buy a detector, amplifier and calibration service as a package, and the hardware boundary must isolate the qualifying sensor value from software licenses, robotics equipment and manufacturing services.

Optical beam position is a specialized measurement rather than a universal substitute for machine vision. A camera can identify several objects in one frame, whereas a two-axis PSD follows the centroid of an illuminated spot with analog continuity. That distinction favors fast stabilization loops, compact laser alignment and controlled target geometry, while visual inspection and object classification generally remain camera tasks. Procurement teams compare the total cost of optics, calibration and electronics, not just the detector purchase price, before selecting a sensing architecture.
Regional Analysis

Asia-Pacific leads the market with an estimated ~45% of 2025 revenue and a modeled ~8.9% CAGR, reflecting electronics manufacturing concentration and precision optical component demand. North America accounts for ~27% and Europe for ~21%, while South America contributes ~4% and the Middle East and Africa ~3%. The five regional allocations total 100%; their modeled growth paths reproduce the global 2034 forecast without relying on conflicting regional percentages from broad industry commentary.

How do electronics manufacturing, metrology capabilities and local integration affect regional demand?

The region where a detector is designed can differ from the region where it is assembled, integrated into equipment or finally used. Hamamatsu supplies Japanese-designed optoelectronic components to customers worldwide, and SiTek products reach buyers through international photonics distribution. Regional market allocation therefore follows estimated equipment demand rather than the nationality of the detector supplier. This distinction is particularly important for electronics manufacturing, where a component may pass through several cross-border transactions before it becomes part of a calibrated optical positioning system.

The five regional models imply 2025 values of USD 1,563.8 million in Asia-Pacific, USD 938.3 million in North America, USD 729.8 million in Europe, USD 139.0 million in South America and USD 104.3 million in the Middle East and Africa. Their corresponding 2034 projections are USD 3,359.2 million, USD 1,819.5 million, USD 1,399.6 million, USD 244.9 million and USD 175.0 million. These figures are modeled allocations of the global headline, not independent national sales surveys, and their precision should not be mistaken for audited regional invoices.

Region Position Growth outlook Demand profile What decides supplier selection
Asia-Pacific Largest (~45% in 2025) ~8.9% CAGR Electronics assembly, photonics production, factory automation Detector linearity, assembly yield and integration with high-volume equipment
North America Second (~27% in 2025) ~7.6% CAGR Research instrumentation, aerospace optics and precision industrial systems Traceable calibration, engineering support and long-term component availability
Europe Third (~21% in 2025) ~7.5% CAGR Industrial metrology, automotive equipment and specialized photonics Documentation, distributor support and mechanical compatibility
South America Emerging (~4% in 2025) ~6.5% CAGR Imported automation systems and industrial inspection Total landed cost, local maintenance and replacement lead times
Middle East and Africa Developing (~3% in 2025) ~5.9% CAGR Research facilities and imported precision manufacturing equipment Integrator expertise, service access and reliability in local environments

Asia-Pacific LARGEST · ~45% SHARE

Why is Asia-Pacific the leading two-axis optical sensor market?

Asia-Pacific represents an estimated ~45% of 2025 revenue and is modeled at ~8.9% CAGR through 2034. Its estimated base value of USD 1,563.8 million grows to USD 3,359.2 million as electronic assembly, optical inspection and precision motion equipment expand. Japan anchors important detector design and supply capabilities, while China and other manufacturing economies generate integration demand. The share describes where qualifying sensors are used rather than the consolidated revenue of Japanese and Chinese equipment companies.

Market positionLargest (~45%)
Growth outlookAbove-average (~8.9% CAGR)
Demand profileElectronics and optics manufacturing
Market access gateComponent qualification and yield
Country Position in region What drives demand
China Largest equipment market China combines electronics assembly, production-line automation and optical test-equipment procurement, making it the largest demand contributor within the region in the modeled allocation. A two-axis PSD may be incorporated into an imported inspection machine or into locally built alignment equipment; both uses generate component demand without implying that the entire machine sale is detector revenue. Supplier selection often balances optical response, repeatability and high-volume manufacturing cost.
Japan Major component supplier Japan has an established photonics component ecosystem, illustrated by Hamamatsu Photonics product lines that include compact surface-mount detectors and tetra-lateral geometries. Domestic demand also arises from semiconductor equipment, robotics and laboratory instruments requiring optical position feedback. Japanese suppliers can compete internationally on datasheet detail, application engineering and stability, while the sensor market remains smaller than the broad revenues of optical and imaging equipment makers.
South Korea and Taiwan Advanced electronics hubs South Korea and Taiwan support precision sensing through semiconductor production, electronics assembly and automated test operations. Equipment builders can use continuous two-axis detector feedback for beam alignment and machine calibration, especially where a controlled spot is more efficient than full-frame image processing. Purchasing decisions emphasize reproducibility over many production cycles, integration with existing controllers and the ability to qualify equivalent parts before a manufacturing line changes its sensor design.
Market instances

  • Hamamatsu introduced compact reflow-compatible two-dimensional PSD packaging in 2026. The S15534 and S15535 product family demonstrates how the detector format is being adapted for automated circuit-board production rather than only laboratory fixtures. The S15535 offers a 9 × 9 mm photosensitive area in a glass-epoxy package and supports lead-free solder reflow. For Asian equipment makers, compact mounting reduces mechanical assembly steps while leaving optical alignment, analog noise and calibration as critical design tasks.
  • SiTek detector apertures span compact and large optical spots. The distributor portfolio includes two-axis silicon PSDs from 2 × 2 mm to 45 × 45 mm, illustrating why a single package does not address all machine layouts. Larger apertures help track beam displacement over longer travel, whereas small sensors suit tight assemblies and low optical power budgets. The commercial consequence is a mix of standard parts and engineering-intensive custom selections rather than one universal high-volume component.
In the full report: Country-specific demand, product geometry and equipment integration across China, Japan, South Korea, Taiwan, India and Southeast Asia, with separate estimates for manufacturing and laboratory applications.

North America SECOND · ~27% SHARE

What determines North American optical position sensor purchasing?

North America accounts for an estimated ~27% of 2025 market revenue, equivalent to USD 938.3 million, and is modeled to reach USD 1,819.5 million in 2034 at ~7.6% CAGR. Precision instrumentation, aerospace optics and industrial automation support specialized purchases, but the installed base also creates replacement demand. Customers may source detector chips from international manufacturers and integrate them locally into calibrated assemblies, so component origin and final application geography are not interchangeable.

Market positionSecond (~27%)
Growth outlookSteady (~7.6% CAGR)
Demand profileInstrumentation and advanced manufacturing
Market access gateDocumentation and supply continuity
Country Position in region What drives demand
United States Largest regional buyer The United States supports detector demand through precision machine builders, optical laboratories, aerospace contractors and medical instrument designers. Two-axis PSDs are useful where a laser spot must be tracked with low latency and a compact analog signal path, but the same projects may consider cameras or encoders. Procurement is influenced by calibration traceability, engineering access, long-term component availability and the costs of redesigning an established instrument around another sensor geometry.
Canada Research and industrial niche Canada has specialized photonics, scientific instrumentation and automated inspection activity that creates a smaller but technically demanding customer base. A two-dimensional optical position sensor may be purchased as a discrete detector or as part of an electronics module assembled by a local integrator. Buyers typically need dependable documentation and stable performance under laboratory or industrial conditions; local demand is not equivalent to the revenues of all Canadian machine-vision or automation companies.
Mexico Assembly-oriented demand Mexico participates through automotive and electronics manufacturing, where imported test equipment and locally configured production fixtures can require optical alignment components. Detector purchasing is often indirect, embedded in machines acquired from global equipment suppliers rather than ordered as a standalone catalog item. Demand growth therefore follows factory investment and maintenance cycles, while local service access and spare-part availability can matter more than a marginal improvement in laboratory-level resolution.
Market instances

  • A compact detector can replace a camera in controlled beam-tracking loops. Where the target is a single illuminated spot, continuous current-ratio measurement can avoid a frame-processing pipeline and provide predictable response for active alignment. The trade-off is limited scene information: a PSD does not classify multiple objects or supply a full image. North American instrument developers therefore select this architecture for defined optical tasks rather than treating it as a general-purpose replacement for machine-vision sensors.
  • Industrial alternatives place a ceiling on direct detector adoption. Renishaw offers optical encoder systems for motion feedback, while Micro-Epsilon sells complete laser displacement instruments for production measurement. These offerings confirm the breadth of positioning demand but operate at different hardware boundaries from bare two-axis photodiodes. Their presence encourages PSD suppliers to demonstrate a clear advantage in spot tracking, electrical response or integration cost before a buyer replaces an established encoder or triangulation architecture.
In the full report: Detailed United States, Canada and Mexico estimates by detector geometry, industrial sector and optical source configuration, with engineering qualification and supply-chain mapping.

Europe THIRD · ~21% SHARE

How does European metrology influence two-dimensional detector selection?

Europe represents an estimated ~21% of the market in 2025, with a modeled value of USD 729.8 million and ~7.5% CAGR to 2034. The forecast reaches USD 1,399.6 million as industrial measurement, automotive equipment and photonics research sustain purchases. European customers frequently buy through specialist distributors that provide datasheets and signal-conditioning support. Supplier qualification emphasizes repeatability, documented linearity and compatibility with existing machine control, rather than the detector price alone.

Market positionThird (~21%)
Growth outlookModerate (~7.5% CAGR)
Demand profileMetrology and automotive equipment
Market access gateApplication engineering and compliance
Country Position in region What drives demand
Germany Industrial measurement hub Germany is a central European market for precision manufacturing, industrial optics and machine-building applications. Micro-Epsilon product lines illustrate the demand for laser-based displacement and triangulation measurements, although finished instruments are not equivalent to standalone position-sensitive photodiodes. German buyers of qualifying detectors focus on electrical noise, calibration intervals, mounting stability and support for repeatable production, with component selection frequently embedded in a larger equipment certification process.
United Kingdom Photonics distribution center The United Kingdom has research instrumentation and specialized optical engineering demand supported by distributors such as LASER COMPONENTS. SiTek two-axis detectors are available in several active-area formats, with signal-processing electronics offered for integrators who prefer a more complete sensing assembly. This distribution structure matters to small equipment manufacturers that need samples, documentation and application assistance before committing to a production bill of materials.
France and Italy Precision systems users France and Italy contribute through industrial inspection, optical laboratories, automotive machinery and other precision systems. Their demand is more project-driven than high-volume consumer assembly, so engineers often prioritize stable specifications and predictable lifecycle support. Optical PSDs compete with cameras and laser displacement devices depending on whether the task requires centroid feedback, surface profile or object recognition, making application fit more important than a generic regional growth narrative.
Market instances

  • European distributors bridge detector fabrication and instrument design. SiTek designs the underlying silicon detector portfolio, while LASER COMPONENTS offers product selection and related signal-conditioning equipment to regional customers. This arrangement can reduce the time needed to identify an appropriate active area, sensitivity and mounting scheme. It also means a distributor listing is evidence of product availability rather than proof of the distributor manufacturing the photodiode or owning its global sales revenue.
  • Calibration requirements create a differentiated value proposition. Position-sensing systems often need correction for illumination geometry, optical spot distribution and analog offset before their coordinates are usable in a precision machine. A supplier that documents linearity and supports compatible amplifier boards can shorten commissioning time even if the discrete detector carries a higher unit price. The benefit is strongest in research and low-volume machinery, where engineering hours outweigh the savings from a cheaper unqualified component.
In the full report: Country-level demand and component integration across Germany, the United Kingdom, France, Italy, Spain and the Nordic region, with detector specifications and distributor routes.

South America EMERGING · ~4% SHARE

Where does South American two-axis optical sensing demand originate?

South America accounts for an estimated ~4% of global 2025 revenue, or USD 139.0 million, and is modeled at ~6.5% CAGR through 2034. The implied forecast is USD 244.9 million. Most demand is associated with imported manufacturing equipment, laboratory instruments and industrial automation rather than a large domestic detector fabrication base. Availability of replacement components, currency exposure and integrator competence influence the choice between a discrete PSD and a fully assembled measurement instrument.

Market positionEmerging (~4%)
Growth outlookMeasured (~6.5% CAGR)
Demand profileImported automation equipment
Market access gateService and landed-cost economics
Country Position in region What drives demand
Brazil Largest regional application base Brazil provides the largest regional opportunity through industrial equipment, automotive production and research laboratories that use optical measurement. Qualifying two-axis detectors can appear in alignment fixtures or in imported precision instruments maintained by local integrators. Purchasers may accept a higher sensor price when it avoids a prolonged machine outage, while customs procedures, replacement lead times and technical support can restrict adoption of unfamiliar components.
Argentina Specialized instrumentation Argentina has a smaller market shaped by scientific equipment, industrial inspection and selective manufacturing projects. Detector orders are often low-volume and specification-led, making access to technical documentation and calibration advice important. A two-axis PSD can be suitable for laser spot tracking, but complete optical measurement systems may be easier to maintain when local engineering resources are limited; the choice depends on lifetime cost rather than a simple sensor price comparison.
Chile and Colombia Developing industrial users Chile and Colombia create selective demand through mining equipment, laboratory research and automation projects that require reliable optical feedback. Their equipment purchases commonly involve overseas manufacturers, so the detector can be embedded in a machine supplied through a local service partner. Import logistics and spare-parts stocking affect replacement decisions, while the relatively small project pipeline makes the region sensitive to the timing of individual capital investments.
Market instances

  • Replacement cycles are more visible than local semiconductor fabrication. An imported machine can generate follow-on demand for optical alignment components after installation, even when the host country has no substantial PSD wafer fabrication. This produces a market shaped by maintenance stock, distributor availability and engineer familiarity with the installed device. The resulting demand is narrower than total spending on automation, which includes motors, cameras, software and mechanical systems that fall outside the component revenue boundary.
  • A low-cost sensor may be expensive to integrate. If an equipment owner replaces a qualified photodiode with a different geometry, the project may require new amplifier settings, recalibration and optical alignment. In smaller markets, that engineering effort can exceed the nominal component price difference, particularly when the original machine supplier provides limited documentation. A reliable supply of established parts therefore competes effectively with newer designs offering improved laboratory specifications but uncertain field interchangeability.
In the full report: Brazil, Argentina, Chile, Colombia and the remaining South American countries, with imported-equipment exposure, detector replacement and optical integration opportunities.

Middle East & Africa DEVELOPING · ~3% SHARE

Which applications support two-dimensional optical sensing in the Middle East and Africa?

The Middle East and Africa hold an estimated ~3% of 2025 revenue, or USD 104.3 million, and are modeled to expand at ~5.9% CAGR to USD 175.0 million in 2034. Scientific laboratories, aerospace-related optical projects and imported industrial inspection equipment create specialized demand. Buyers generally depend on international suppliers and integrators, making delivery reliability, technical service and operating-environment tolerance central purchasing considerations. The region remains a small part of global component revenue despite visible investment in advanced equipment.

Market positionDeveloping (~3%)
Growth outlookSelective (~5.9% CAGR)
Demand profileResearch and imported systems
Market access gateLocal technical support access
Country Position in region What drives demand
United Arab Emirates Research and technology adopter The United Arab Emirates supports demand through research laboratories, advanced manufacturing pilots and imported precision instruments. Two-dimensional PSDs can be incorporated into optical alignment setups where continuous spot tracking is useful, but broader spending on automation or imaging does not directly indicate detector sales. Equipment integrators often determine component selection, and customers value documentation, replacement supply and compatibility with the control electronics already installed.
Saudi Arabia Industrial project market Saudi Arabia presents project-based opportunities in industrial automation, laboratory systems and specialized optical measurement. Component demand tends to be bundled into imported instruments or integrated by contractors, rather than purchased in large quantities by domestic detector manufacturers. Qualification depends on reliability and maintenance access, particularly where optical equipment operates under challenging thermal or dust conditions; those system requirements should not be confused with verified PSD market volumes.
South Africa Established industrial niches South Africa has industrial measurement, scientific research and maintenance activity that can use position-sensitive optical devices. Demand is concentrated in specialized machinery and instrument repair rather than consumer-scale detector integration. A buyer selecting a discrete PSD must consider the availability of analog processing electronics and calibration skills; an alternative complete laser sensor may reduce integration risk but moves expenditure into a different hardware category.
Market instances

  • Equipment integration determines the geographic point of sale. A detector manufactured in Japan or Europe may enter a laboratory in the Gulf through an imported instrument, and the component can be replaced later by a local service company. This creates several commercial transactions around one sensor without multiplying the sensor market itself. Regional allocations therefore reflect estimated component demand within equipment and spares rather than the total import value of optical or industrial machinery.
  • Harsh environments increase the value of protected assemblies. Dust, vibration and elevated ambient temperature can complicate optical alignment even when the silicon detector operates within its electrical specification. Integrators may add protective windows, mechanical isolation and periodic calibration, raising the complete system price without increasing the underlying photodiode value by the same amount. The practical opportunity is to supply stable, documented detector assemblies that simplify maintenance in specialized installations.
In the full report: Country and application estimates for the United Arab Emirates, Saudi Arabia, Israel, South Africa and other regional markets, with attention to imported instrumentation and maintenance channels.

Two Dimensional Optical Position Sensor Manufacturers and Competitive Landscape

The competitive landscape is shaped by a relatively small group of direct position-sensitive detector suppliers and a much larger ecosystem of optical measurement equipment companies. Hamamatsu Photonics sells two-dimensional silicon PSDs in multiple geometries, while SiTek devices are available internationally through LASER COMPONENTS. Buyers differentiate direct detectors on active area, linearity, speed and package suitability. Complete laser displacement systems and optical encoders address overlapping measurement budgets but should not be assigned the same component-level revenue.

Hamamatsu provides a clear example of product-level differentiation within one supplier. Its S2044 family supports compact continuous position sensing, the S15535 uses a surface-mount glass-epoxy package, and the S5990-01 and S5991-01 illustrate tetra-lateral pin-cushion designs. These devices do not have interchangeable optical and electrical properties, so procurement teams qualify a particular active area, biasing circuit and mechanical arrangement. The company’s broad optoelectronics business does not disclose a standalone worldwide revenue figure for this narrow detector segment in the cited technical pages.

SiTek emphasizes high-linearity position-sensitive detectors in a wide aperture range. LASER COMPONENTS distributes devices whose side lengths extend from 2 mm to 45 mm, with wavelength-optimized and coated versions available for specialized optical arrangements. The distributor also lists SPC-PSD electronics that condition multiple photocurrents into coordinate-related outputs, making the offer attractive to customers without a dedicated analog design team. Supplier and distributor roles must remain distinct: the availability of a product in a distributor catalogue is not evidence that the distributor fabricates the semiconductor die.

A second competitive layer comprises companies whose products solve related but different positioning problems. Micro-Epsilon supplies finished laser triangulation instruments, while Renishaw supplies optical encoder systems for motion feedback. Their equipment can compete against a PSD-based design at the system-selection stage, especially where the user needs absolute displacement, scale reading or a turnkey industrial interface. However, revenue from complete instruments, encoders and controller software cannot be counted as sales of standalone two-dimensional optical position-sensitive components without a defensible product-level allocation.

Supplier concentration is reinforced by the difficulty of replacing a detector after design qualification. Optical geometry, analog current conversion, temperature drift and calibration algorithms are jointly optimized around a selected part, so changing vendors can trigger additional engineering and field validation. This favors companies that provide stable datasheets, evaluation circuits and long product lifecycles. Smaller entrants can still compete through custom packaging or wavelength response, but a nominally cheaper device may lose the tender when the customer includes redesign and reliability costs.

Tier structure

Tier Companies Basis of competition
Direct detector suppliers Hamamatsu Photonics; SiTek Commercial two-dimensional silicon PSD families with published active-area and response specifications. Product differentiation centers on geometry, packaging, sensitivity, optical coating and support for signal conditioning rather than a single standardized performance class.
Distribution and integration LASER COMPONENTS; specialist photonics integrators Product access, application engineering, sampling, calibration and compatible electronics help equipment makers adopt PSD components. A distributor can support regional sales without being the original semiconductor manufacturer, and bundled electronics should be distinguished from bare detector revenue.
Adjacent positioning competitors Micro-Epsilon; Renishaw; industrial machine-vision vendors Complete laser displacement instruments and optical encoders serve alternative measurement tasks. Their competitive relevance lies in architecture choice at the equipment level, while their consolidated revenues are not a proxy for two-axis PSD component sales.

Key companies profiled

  • Hamamatsu Photonics (Japan) — direct two-dimensional PSD supplier
  • SiTek Electro Optics (Sweden) — direct PSD product line
  • LASER COMPONENTS (Germany/United Kingdom) — distributor and signal-processing solutions
  • Micro-Epsilon (Germany) — adjacent laser displacement instrumentation
  • Renishaw (United Kingdom) — adjacent optical encoders and motion feedback
  • Panasonic — broader optical sensing ecosystem, direct two-axis PSD participation not established in cited sources
  • OMRON — industrial sensing ecosystem, not counted as a verified merchant PSD maker
  • First Sensor AG — historical sensor company name; product-level two-axis PSD participation not verified

Two Dimensional Optical Position Sensor Manufacturing and Integration Analysis

Manufacturing involves silicon photodiode processing, electrode formation, passivation, packaging, optical characterization and final electrical testing. The detector can then be sold as a discrete component or combined with amplifier and calibration electronics. Japan and parts of Europe host established product-development capabilities, while Asia-Pacific electronics manufacturing drives large integration volumes. Unlike a finished displacement instrument, the position-sensitive element alone does not include the laser source, target optics or the complete machine controller.

The fabrication challenge is not merely producing a light-sensitive junction. A two-axis PSD must distribute photocurrent predictably as the illuminated spot moves across the active surface, and non-linearity or stray light can create errors in the derived coordinates. Hamamatsu offers multiple geometries, while SiTek specifies high-linearity silicon devices in different aperture sizes. Packaging decisions affect the usable optical field, mechanical alignment and thermal behavior, so process control and calibration are essential to reproducible sensor performance across manufacturing lots.

Electronics integration determines whether a buyer purchases a bare PSD or a conditioned module. SiTek SPC-PSD products incorporate transimpedance and summing circuitry that translate four detector currents into outputs representing position and optical intensity. A complete assembly saves engineering effort but adds analog components, connectors and calibration cost. High-volume original-equipment manufacturers may instead build custom boards to reduce unit cost, whereas research users often favor ready-to-operate modules because the instrument development schedule matters more than a small difference in component pricing.

Supply resilience depends on component availability and the time required to approve alternatives. A replacement detector with a different active area, electrode configuration or response curve may require changes to optical geometry and software calibration even when it fits the same board footprint. Distributors help manage smaller orders and provide technical guidance, but customers still need to evaluate lifecycle commitments and process variation. The result is a manufacturing market in which qualification, documentation and continuity can protect margins despite competitive pressure on standard silicon devices.

Two Dimensional Optical Position Sensor Market Dynamics: Drivers, Restraints and Opportunities

The modeled growth path reflects expanding optical alignment in electronics assembly, precision automation and specialized instruments, partly offset by competing measurement architectures and the cost of calibrating analog position signals. Demand is strongest where a single light spot must be tracked continuously on two axes with low latency. The impact tables allocate percentage-point contributions to the headline growth rate; these are analytical estimates of relative market forces rather than independently observed causal coefficients.

MARKET DRIVERS

Drivers Impact Analysis*

Market Drivers Impact Rank CAGR Contribution (%) 2026–2028 2029–2031 2032–2034
Precision electronics assembly and alignment High +3.10% High High Medium
Industrial automation and motion feedback High +2.50% High High High
Compact optical packaging and integration Medium-High +2.10% Medium High High
Automotive test and calibration equipment Medium +1.60% Medium High High
Laboratory and medical optical instrumentation Low-Medium +1.30% Medium Medium Medium
Others (specialized beam stabilization and research systems) Low +1.00% Low Medium Medium

Precision assembly increases demand for two-coordinate feedback

Automated electronics manufacturing requires repeatable alignment of optics, circuit assemblies and moving fixtures. A continuous two-axis PSD can locate a controlled laser spot without the image-processing load of a camera, which makes it useful for compact feedback loops. The demand mechanism is specific: more stations using optical alignment create additional detector sockets, while upgrades to existing stations can raise the value of sensing modules with improved packaging and electrical stability. The modeled driver contributes +3.10 percentage points to forecast growth.

Factory automation expands specialized measurement tasks

Robotic tooling and production machines use several position-feedback methods, including encoders, triangulation instruments and optical spot detectors. A PSD gains design wins where the task is tracking beam displacement or aligning a target rather than recognizing an image. Industrial automation is modeled at ~26% of application revenue and ~8.5% CAGR, reflecting equipment investment and replacement. The estimated +2.50-point driver captures growth in qualifying components without treating total robotics or machine-vision expenditure as detector sales.

Surface-mount packaging lowers integration friction

Compact packages can make a PSD easier to incorporate into a printed circuit board, particularly when the assembly process already uses automated placement and lead-free solder reflow. Hamamatsu’s S15535 provides a concrete example of this direction, with a 12.8 × 11.6 × 1.5 mm package and a 9 × 9 mm active area. These dimensions matter because reduced mechanical assembly can improve repeatability, although optical aperture and analog calibration remain necessary. The modeled contribution from packaging and integration is +2.10 points.

Vehicle-related optical testing supports faster applications

Automotive manufacturing uses precision inspection and alignment fixtures, while specialized vehicle electronics can require optical position monitoring. The automotive application segment is modeled at ~20% of base-year revenue and ~10.3% CAGR, faster than consumer electronics. This does not mean a discrete PSD is installed in every vehicle; much of the opportunity is inside production equipment and test systems. The estimated +1.60-point driver represents incremental demand from these defined optical measurement tasks and their ongoing qualification requirements.

Scientific and medical instruments require controlled optical signals

Laboratory instruments can benefit from a PSD when they measure laser-beam drift, mechanical vibration or the position of an illuminated target. Medical equipment developers face stricter validation and may prefer established sensing designs with traceable performance rather than frequently changing components. The modeled Medical Devices application share is ~9%, with ~8.7% CAGR, and specialized research uses contribute additional demand outside mass production. This driver is assigned +1.30 percentage points, reflecting modest volume but relatively demanding specifications.

MARKET RESTRAINTS

Restraints Impact Analysis*

Market Restraints Impact Rank CAGR Contribution (%) 2026–2028 2029–2031 2032–2034
Competition from cameras, encoders and laser displacement systems High -1.40% High High High
Calibration, noise and integration engineering cost Medium-High -1.00% High Medium Medium
Long qualification cycles and supplier substitution risk Medium -0.70% Medium Medium High
Others (price pressure and niche-volume variability) Low -0.40% Medium Low Low
*CAGR contribution shows the percentage points each factor adds to or removes from the forecast CAGR for 2026–2034; driver contributions less restraint contributions equal the market CAGR. Period columns rate the strength of each factor in that window.

Alternative architectures can better match the measurement problem

A PSD is not an all-purpose position sensor. Cameras can inspect several features and identify objects, encoders measure motion relative to scales, and laser triangulation instruments supply calibrated distance outputs. These architectures can win projects that require information beyond the centroid of a light spot, limiting addressable PSD demand. The modeled restraint is −1.40 percentage points, representing lost design opportunities rather than a decline in overall demand for industrial optical measurement.

Analog signal conditioning adds engineering and calibration costs

The detector generates photocurrents that must be amplified, normalized and corrected for optical and electrical effects before the coordinate output is dependable. Low illumination, stray light, offset drift and package misalignment can compromise results. Suppliers offer processing circuits and integrated modules to reduce the burden, but those solutions raise the assembly price. The modeled −1.00-point restraint captures projects that choose a more integrated alternative because the engineering cost of a discrete PSD exceeds its unit-price advantage.

Qualified detector designs are difficult to change quickly

Optical instruments are often designed around a particular active area, response curve and mounting arrangement, making second-source qualification expensive. If a component is discontinued or delivery becomes uncertain, an equipment maker may need new calibration data, circuit modifications and field testing. Such work delays new installations and can divert budgets to alternative sensing architectures. This factor subtracts an estimated −0.70 percentage points from growth, with the greatest impact in long-life industrial and medical systems.

MARKET OPPORTUNITIES

Integrated sensing electronics can expand the addressable customer base

A supplier offering a detector with compatible amplification and position-output electronics can serve buyers that lack specialist analog engineering. SiTek’s SPC-PSD architecture illustrates the value of reducing the steps between optical illumination and usable coordinate signals. The opportunity is strongest among laboratories, small machine builders and custom instrument developers, which often buy a complete functional block to shorten development time. Differentiation depends on low noise, accessible calibration and clear interface documentation rather than a larger photodiode alone.

Wavelength-optimized detectors address specialized optical designs

The silicon PSD portfolio includes devices optimized for different illumination conditions and aperture requirements, including UV- and YAG-oriented versions distributed by LASER COMPONENTS. Equipment designers can choose a sensing surface tailored to the source rather than accepting a general-purpose response curve. This can create higher-value orders in beam stabilization, research and optical manufacturing, although qualification volumes are typically smaller than mainstream electronics assembly. The opportunity lies in verified application fit and engineering support.

Equipment redesign creates openings for compact two-axis feedback

When a manufacturer redesigns a machine for lower size, weight or power consumption, it may reconsider a camera-based or mechanically complex measurement subsystem. A compact PSD can be attractive if the system only needs a spot centroid and the illumination geometry is controlled. The commercial opening is not universal substitution: suppliers must demonstrate enough speed, linearity and reliability to justify integration work. Early design engagement can secure long production lifecycles once the new sensing architecture is qualified.

Two Dimensional Optical Position Sensor Value Chain and Purchasing Analysis

The value chain begins with silicon photodiode fabrication and specialized electrode geometries, proceeds through packaging and characterization, and ends with electronics integration into equipment. Direct component suppliers control the detector design and manufacturing process; distributors and module specialists connect those parts to equipment builders. End users purchase the resulting industrial, scientific or medical instrument. Revenue attribution must stop at the qualifying position-sensing component or directly integrated detector assembly rather than absorbing every downstream machine transaction.

UpstreamSilicon wafers, photodiode structures, electrodes, optical coatings and package materials
Component productionTwo-axis detector fabrication, electrical test, optical characterization and packaging
Integration channelSpecialist distributors, amplifier-board suppliers and original-equipment design teams
DownstreamElectronics manufacturing, industrial automation, laboratories and medical instruments

Upstream. Silicon detector fabrication must control dark current, photosensitivity, resistance and electrode uniformity so that position signals remain stable over the active area. Optical coatings and package windows can be selected for the illumination wavelength, while die and substrate geometry affect the available travel of a light spot. Input cost is only part of the economics: process consistency and the ability to characterize each device are essential because a small electrical deviation can create a measurable position error.

Component production. The manufacturing stage converts photodiode wafers into tested two-dimensional devices and packages them for the required optical aperture. Surface-mount products favor automated board assembly, while ceramic and larger-area designs can support research or specialized industrial instruments. Hamamatsu’s catalogue illustrates both compact and tetra-lateral configurations. Producers compete on linearity, rise time, documentation and stable product supply, with engineering support often determining whether a device is qualified for repeat orders.

Distribution and integration. LASER COMPONENTS provides access to SiTek detector variants and compatible electronics, helping buyers compare aperture, wavelength response and calibration needs. A distributor can reduce sampling friction, but it does not replace the instrument designer’s responsibility to validate the optical path and analog circuitry. Original-equipment manufacturers may purchase a bare photodiode for a custom board or a more complete sensing module when development resources are constrained. These channels create different price points around the same underlying measurement function.

Downstream. The final sensor becomes part of a factory fixture, research instrument or precision control subsystem. Users evaluate uptime and measurement reliability at the system level, so a component failure can cause costs far greater than its purchase price. That makes documented lifecycle support and qualified replacement stock valuable. However, the complete equipment sale includes optics, mechanical stages, controllers and software; those downstream values should not be added to the market for qualifying two-dimensional optical position-sensing components.

Recent Product and Technology Developments in Two Dimensional Optical Position Sensing

  • 30 June 2026 Featured product
    Hamamatsu Photonics featured the S15534 and S15535 two-dimensional position-sensitive detector family, emphasizing compact glass-epoxy packaging and suitability for automated circuit-board assembly. The S15535 combines a 9 × 9 mm photosensitive area with a surface-mount form factor and lead-free reflow compatibility. This product direction addresses integration cost and mechanical repeatability rather than changing the fundamental current-ratio method used to locate an illuminated spot. Source
  • 2026 product portfolio Specification
    Hamamatsu lists the S5991-01 as a tetra-lateral pin-cushion position-sensitive detector with a 9 × 9 mm active area. The device illustrates the continued commercial availability of geometry-specific silicon PSDs alongside newer surface-mount designs. Instrument builders selecting this configuration must consider its optical footprint, current-output arrangement and calibration needs; the listing is evidence of a product specification, not a dated announcement of new sales volume. Source
  • 2026 product portfolio Specification
    LASER COMPONENTS describes SiTek two-dimensional silicon PSDs with active-area dimensions extending from 2 × 2 mm to 45 × 45 mm, including wavelength-optimized and coated variants. The breadth of this range supports both compact beam alignment and larger-spot tracking applications. The distributor documentation establishes technical availability and configuration choices, but it does not disclose global unit shipments or an independently measured share of detector revenue. Source
  • 2026 product portfolio Specification
    SiTek SPC-PSD modules distributed by LASER COMPONENTS combine a position-sensitive element with signal-conditioning electronics. Four transimpedance channels and summing circuitry convert electrode currents into coordinate-related outputs, reducing the analog design work required by an instrument maker. Such integration is relevant to small production runs and research equipment where engineering hours dominate the cost of a discrete semiconductor device. The catalogue entry is not presented as a new product launch. Source
  • 11 March 2013 Supplier history
    LASER COMPONENTS described two-dimensional SiTek detectors with typical non-linearity around ±0.3% and active areas up to 45 × 45 mm in a supplier announcement. The historical product communication establishes that high-linearity analog position sensing predates the current forecast period and remains a mature technical capability. Growth in the forecast therefore depends on new equipment sockets and packaging improvements rather than the first commercialization of the underlying detector concept. Source

REPORT SCOPE & SEGMENTATION

Attribute Details
Study Period 2021–2034
Base Year 2025
Estimated Year 2026
Forecast Period 2026–2034
Historical Context 2021–2024
Market Size 2025 USD 3,475.06 million
Market Size 2026 USD 3,756.15 million
Market Size 2034 USD 6,998.23 million
Growth Rate CAGR of 8.1% during 2026–2034
Unit Revenue in USD million; estimated segment shares and growth rates
Segmentation By Type, By Application, By Technology, By End Use Industry and By Region
By Type Surface Split · Two Side Split · Pin-Cushion Type · Others
By Application Consumer Electronics · Automotive · Industrial Automation · Medical Devices · Aerospace and Defense · Others
By Technology Laser-Based · Infrared · LED-Based · Others
By End Use Industry Electronics Manufacturing · Automotive · Healthcare · Industrial · Aerospace and Defense · Others
By Region Each region assessed by type, application, technology and end-use industry
North AmericaUnited States, Canada, Mexico
EuropeGermany, United Kingdom, France, Italy, Spain, Nordic countries, Rest of Europe
Asia-PacificChina, Japan, South Korea, Taiwan, India, Southeast Asia, Rest of Asia-Pacific
South AmericaBrazil, Argentina, Chile, Colombia, Rest of South America
Middle East & AfricaUnited Arab Emirates, Saudi Arabia, Israel, South Africa, Rest of Middle East and Africa
Key Companies Profiled Hamamatsu Photonics; SiTek Electro Optics; LASER COMPONENTS (distribution); Micro-Epsilon (adjacent complete laser sensors); Renishaw (adjacent optical encoders); Panasonic, OMRON and First Sensor AG (broader or historical sensing ecosystem, direct participation not established by cited product evidence)
Customization Scope Optional country-level and product-geometry detail, calibration requirements, supplier comparison and component-versus-system boundary review, subject to the buyer’s stated application requirements.

Frequently Asked Questions

What is the global two dimensional optical position sensor market size?

The global market was valued at USD 3,475.06 million in 2025 and is projected to reach USD 6,998.23 million by 2034, growing at a CAGR of 8.1% during 2026–2034. The revenue boundary concerns qualifying two-axis optical position-sensing components and directly integrated detector assemblies. It does not count the complete price of industrial laser instruments, machine-vision cameras, robots or optical encoders whose measurement architectures differ from the position-sensitive photodiode.

What is a two-dimensional position-sensitive optical detector?

It is a photodiode-based device that determines where an illuminated spot falls along two coordinates by comparing currents collected at several electrodes. A continuous sensing surface permits position feedback without reconstructing an image from a pixel array. This is valuable in beam stabilization, alignment and vibration measurement, but the detector generally requires suitable illumination and analog processing. Its output is a spot position, not a full picture or an automatic identification of objects.

Which product types account for the largest revenue shares?

Surface Split is the largest modeled type at ~42% of 2025 revenue, followed by Two Side Split at ~31% and Pin-Cushion Type at ~20%; the residual group accounts for ~7%. The segmentation distinguishes electrode and geometry arrangements rather than different industries. Buyers choose a configuration after comparing active-area dimensions, linearity, speed, package form and compatibility with the optical spot and current-conversion circuitry in their instrument.

Which applications are most important for two-axis optical sensing?

Consumer Electronics leads the application mix with an estimated ~35% share, followed by Industrial Automation at ~26% and Automotive at ~20%. Medical Devices, Aerospace and Defense, and smaller specialist applications make up the balance. These categories are non-additive views of where the detector is used; the revenue associated with a factory robot or a vehicle test machine is not included in full merely because that equipment contains one position-sensitive component.

Which region leads the two-dimensional optical position sensor market?

Asia-Pacific is the largest region at an estimated ~45% of 2025 revenue, supported by electronics production and photonics component supply. North America follows at ~27% and Europe at ~21%, while South America and the Middle East and Africa contribute smaller shares. Regional percentages are modeled allocations of qualifying component demand and should not be confused with independently disclosed supplier sales by country or the headquarters locations of multinational optical equipment manufacturers.

How do laser-based, infrared and LED-based configurations differ?

The technology categories describe the optical illumination and measurement context around a two-axis detector. Laser-Based systems account for an estimated ~46% of the base-year market because coherent spots are useful for alignment; Infrared contributes ~25%, and LED-Based configurations ~20%. A silicon PSD can work with different light sources within its spectral response, so these categories should not be interpreted as separate kinds of semiconductor material or as direct revenue for the light emitters.

Who are the leading companies in this market?

Hamamatsu Photonics and SiTek have directly documented two-dimensional position-sensitive detector products, while LASER COMPONENTS distributes SiTek devices and signal-processing solutions. Micro-Epsilon and Renishaw are relevant competitors at the broader measurement-system level because their laser instruments and encoders can serve some of the same positioning tasks. A company name in the industrial sensing ecosystem does not by itself establish merchant sales of two-axis PSD components, and supplier roles need to be distinguished.

What drives demand for continuous two-coordinate optical feedback?

The principal demand drivers are precision electronics assembly, factory automation, compact detector packaging, automotive test equipment and specialized scientific instrumentation. A continuous photodiode signal can be attractive where a single beam spot must be tracked rapidly and predictably. Growth is constrained when the task requires image recognition, absolute encoder feedback or a complete calibrated distance instrument, because those needs favor other sensing architectures despite the usefulness of analog spot tracking.

What technical challenges affect supplier selection?

Customers must account for non-linearity across the active surface, optical spot size, dark current, amplifier noise, temperature drift and mechanical alignment. Replacing one qualified PSD with another can require recalibration even when both produce nominal X and Y outputs. Integrated amplifier modules reduce development work but increase component cost. The winning choice depends on lifetime instrument performance and the expense of maintaining a reliable measurement chain, not solely on detector sensitivity or catalog price.

What is included in the 2025–2034 study scope?

The study covers a 2025 base year, a 2026 estimate and a forecast through 2034, with segmentation by Type, Application, Technology, End Use Industry and five world regions. Revenue includes qualifying continuous two-axis optical position sensors and directly associated detector assemblies. Complete cameras, robotics platforms, industrial laser displacement instruments and unrelated encoders are excluded. Country and segment allocations are analytical estimates designed to reconcile with the overall market trajectory rather than independently audited shipment statistics.

Research Sources & Evidence Base
View research sources used for this overview
  1. Hamamatsu Photonics. S2044 two-dimensional position-sensitive detector, Product specification for continuous two-axis optical spot sensing and package performance.
  2. Hamamatsu Photonics. S15535 surface-mount two-dimensional PSD, Device data for 9 × 9 mm active area, response, reflow-compatible packaging and spectral range.
  3. Hamamatsu Photonics. S15534 and S15535 featured detector products, 30 June 2026 feature on compact glass-epoxy two-axis PSD packaging.
  4. Hamamatsu Photonics. S5991-01 tetra-lateral detector, Product-level evidence of pin-cushion geometry and optical aperture.
  5. Hamamatsu Photonics. S5990-01 two-dimensional PSD, Smaller active-area pin-cushion configuration and circuit compatibility.
  6. Hamamatsu Photonics. C4674-01 signal processing circuit, Current conversion and adjustable electronic sensitivity for PSD integration.
  7. LASER COMPONENTS / SiTek. Two-dimensional silicon PSD portfolio, Detector dimensions, continuous spot tracking and wavelength-specific variants.
  8. LASER COMPONENTS / SiTek. SPC-PSD integrated electronics, Amplifier and coordinate-signal integration for two-axis detectors.
  9. LASER COMPONENTS. Two-dimensional position sensing detectors, Supplier communication dated 11 March 2013 covering linearity and large-area designs.
  10. LASER COMPONENTS / SiTek. Position-sensitive phototransistors, Higher-responsivity alternative and documented 2L10ES specifications.
  11. Micro-Epsilon. optoNCDT 2300 laser displacement sensor, Adjacent complete laser measurement equipment and high-speed industrial positioning.
  12. Micro-Epsilon. optoNCDT 1900 laser displacement sensor, Alternative integrated triangulation instrument for industrial applications.
  13. Renishaw. Multi-degree-of-freedom optical encoders, Adjacent position-feedback technology in precision machinery.
  14. Renishaw. RESOLUTE absolute optical encoder series, Different motion-feedback architecture for equipment designers.
  15. Micro-Epsilon. Industrial laser sensor portfolio, Manufacturing applications and complete measurement-system alternatives.
  16. Renishaw. Open optical encoder range, Industrial position measurement alternatives and integration context.
Two Dimensional Optical Position Sensor Market

Get Sample Report PDF for Exclusive Insights

Report Sample Includes

  • Table of Contents
  • List of Tables & Figures
  • Charts, Research Methodology, and more...

PDF Icon Download Sample Report PDF
SKU: 0d42aa92c9d4
Category:

Download Sample Report

Table of Content

1 Introduction to Research & Analysis Reports
1.1 Two Dimensional Optical Position Sensor Market Definition
1.2 Market Segments
1.2.1 Segment by Type
1.2.2 Segment by Application
1.3 Global Two Dimensional Optical Position Sensor Market Overview
1.4 Features & Benefits of This Report
1.5 Methodology & Sources of Information
1.5.1 Research Methodology
1.5.2 Research Process
1.5.3 Base Year
1.5.4 Report Assumptions & Caveats
2 Global Two Dimensional Optical Position Sensor Overall Market Size
2.1 Global Two Dimensional Optical Position Sensor Market Size: 2024 VS 2032
2.2 Global Two Dimensional Optical Position Sensor Market Size, Prospects & Forecasts: 2026-2034
2.3 Global Two Dimensional Optical Position Sensor Sales: 2026-2034
3 Company Landscape
3.1 Top Two Dimensional Optical Position Sensor Players in Global Market
3.2 Top Global Two Dimensional Optical Position Sensor Companies Ranked by Revenue
3.3 Global Two Dimensional Optical Position Sensor Revenue by Companies
3.4 Global Two Dimensional Optical Position Sensor Sales by Companies
3.5 Global Two Dimensional Optical Position Sensor Price by Manufacturer (2020-2025)
3.6 Top 3 and Top 5 Two Dimensional Optical Position Sensor Companies in Global Market, by Revenue in 2024
3.7 Global Manufacturers Two Dimensional Optical Position Sensor Product Type
3.8 Tier 1, Tier 2, and Tier 3 Two Dimensional Optical Position Sensor Players in Global Market
3.8.1 List of Global Tier 1 Two Dimensional Optical Position Sensor Companies
3.8.2 List of Global Tier 2 and Tier 3 Two Dimensional Optical Position Sensor Companies
4 Sights by Product
4.1 Overview
4.1.1 Segment by Type – Global Two Dimensional Optical Position Sensor Market Size Markets, 2024 & 2032
4.1.2 Surface Split
4.1.3 Two Side Split
4.2 Segment by Type – Global Two Dimensional Optical Position Sensor Revenue & Forecasts
4.2.1 Segment by Type – Global Two Dimensional Optical Position Sensor Revenue, 2020-2025
4.2.2 Segment by Type – Global Two Dimensional Optical Position Sensor Revenue, 2026-2032
4.2.3 Segment by Type – Global Two Dimensional Optical Position Sensor Revenue Market Share, 2026-2034
4.3 Segment by Type – Global Two Dimensional Optical Position Sensor Sales & Forecasts
4.3.1 Segment by Type – Global Two Dimensional Optical Position Sensor Sales, 2020-2025
4.3.2 Segment by Type – Global Two Dimensional Optical Position Sensor Sales, 2026-2032
4.3.3 Segment by Type – Global Two Dimensional Optical Position Sensor Sales Market Share, 2026-2034
4.4 Segment by Type – Global Two Dimensional Optical Position Sensor Price (Manufacturers Selling Prices), 2026-2034
5 Sights by Application
5.1 Overview
5.1.1 Segment by Application – Global Two Dimensional Optical Position Sensor Market Size, 2024 & 2032
5.1.2 Aerospace
5.1.3 Electronic Product
5.1.4 Car
5.1.5 Other
5.2 Segment by Application – Global Two Dimensional Optical Position Sensor Revenue & Forecasts
5.2.1 Segment by Application – Global Two Dimensional Optical Position Sensor Revenue, 2020-2025
5.2.2 Segment by Application – Global Two Dimensional Optical Position Sensor Revenue, 2026-2032
5.2.3 Segment by Application – Global Two Dimensional Optical Position Sensor Revenue Market Share, 2026-2034
5.3 Segment by Application – Global Two Dimensional Optical Position Sensor Sales & Forecasts
5.3.1 Segment by Application – Global Two Dimensional Optical Position Sensor Sales, 2020-2025
5.3.2 Segment by Application – Global Two Dimensional Optical Position Sensor Sales, 2026-2032
5.3.3 Segment by Application – Global Two Dimensional Optical Position Sensor Sales Market Share, 2026-2034
5.4 Segment by Application – Global Two Dimensional Optical Position Sensor Price (Manufacturers Selling Prices), 2026-2034
6 Sights by Region
6.1 By Region – Global Two Dimensional Optical Position Sensor Market Size, 2024 & 2032
6.2 By Region – Global Two Dimensional Optical Position Sensor Revenue & Forecasts
6.2.1 By Region – Global Two Dimensional Optical Position Sensor Revenue, 2020-2025
6.2.2 By Region – Global Two Dimensional Optical Position Sensor Revenue, 2026-2032
6.2.3 By Region – Global Two Dimensional Optical Position Sensor Revenue Market Share, 2026-2034
6.3 By Region – Global Two Dimensional Optical Position Sensor Sales & Forecasts
6.3.1 By Region – Global Two Dimensional Optical Position Sensor Sales, 2020-2025
6.3.2 By Region – Global Two Dimensional Optical Position Sensor Sales, 2026-2032
6.3.3 By Region – Global Two Dimensional Optical Position Sensor Sales Market Share, 2026-2034
6.4 North America
6.4.1 By Country – North America Two Dimensional Optical Position Sensor Revenue, 2026-2034
6.4.2 By Country – North America Two Dimensional Optical Position Sensor Sales, 2026-2034
6.4.3 United States Two Dimensional Optical Position Sensor Market Size, 2026-2034
6.4.4 Canada Two Dimensional Optical Position Sensor Market Size, 2026-2034
6.4.5 Mexico Two Dimensional Optical Position Sensor Market Size, 2026-2034
6.5 Europe
6.5.1 By Country – Europe Two Dimensional Optical Position Sensor Revenue, 2026-2034
6.5.2 By Country – Europe Two Dimensional Optical Position Sensor Sales, 2026-2034
6.5.3 Germany Two Dimensional Optical Position Sensor Market Size, 2026-2034
6.5.4 France Two Dimensional Optical Position Sensor Market Size, 2026-2034
6.5.5 U.K. Two Dimensional Optical Position Sensor Market Size, 2026-2034
6.5.6 Italy Two Dimensional Optical Position Sensor Market Size, 2026-2034
6.5.7 Russia Two Dimensional Optical Position Sensor Market Size, 2026-2034
6.5.8 Nordic Countries Two Dimensional Optical Position Sensor Market Size, 2026-2034
6.5.9 Benelux Two Dimensional Optical Position Sensor Market Size, 2026-2034
6.6 Asia
6.6.1 By Region – Asia Two Dimensional Optical Position Sensor Revenue, 2026-2034
6.6.2 By Region – Asia Two Dimensional Optical Position Sensor Sales, 2026-2034
6.6.3 China Two Dimensional Optical Position Sensor Market Size, 2026-2034
6.6.4 Japan Two Dimensional Optical Position Sensor Market Size, 2026-2034
6.6.5 South Korea Two Dimensional Optical Position Sensor Market Size, 2026-2034
6.6.6 Southeast Asia Two Dimensional Optical Position Sensor Market Size, 2026-2034
6.6.7 India Two Dimensional Optical Position Sensor Market Size, 2026-2034
6.7 South America
6.7.1 By Country – South America Two Dimensional Optical Position Sensor Revenue, 2026-2034
6.7.2 By Country – South America Two Dimensional Optical Position Sensor Sales, 2026-2034
6.7.3 Brazil Two Dimensional Optical Position Sensor Market Size, 2026-2034
6.7.4 Argentina Two Dimensional Optical Position Sensor Market Size, 2026-2034
6.8 Middle East & Africa
6.8.1 By Country – Middle East & Africa Two Dimensional Optical Position Sensor Revenue, 2026-2034
6.8.2 By Country – Middle East & Africa Two Dimensional Optical Position Sensor Sales, 2026-2034
6.8.3 Turkey Two Dimensional Optical Position Sensor Market Size, 2026-2034
6.8.4 Israel Two Dimensional Optical Position Sensor Market Size, 2026-2034
6.8.5 Saudi Arabia Two Dimensional Optical Position Sensor Market Size, 2026-2034
6.8.6 UAE Two Dimensional Optical Position Sensor Market Size, 2026-2034
7 Manufacturers & Brands Profiles
7.1 First Sensor AG
7.1.1 First Sensor AG Company Summary
7.1.2 First Sensor AG Business Overview
7.1.3 First Sensor AG Two Dimensional Optical Position Sensor Major Product Offerings
7.1.4 First Sensor AG Two Dimensional Optical Position Sensor Sales and Revenue in Global (2020-2025)
7.1.5 First Sensor AG Key News & Latest Developments
7.2 Siemens
7.2.1 Siemens Company Summary
7.2.2 Siemens Business Overview
7.2.3 Siemens Two Dimensional Optical Position Sensor Major Product Offerings
7.2.4 Siemens Two Dimensional Optical Position Sensor Sales and Revenue in Global (2020-2025)
7.2.5 Siemens Key News & Latest Developments
7.3 Panasonic Corporation
7.3.1 Panasonic Corporation Company Summary
7.3.2 Panasonic Corporation Business Overview
7.3.3 Panasonic Corporation Two Dimensional Optical Position Sensor Major Product Offerings
7.3.4 Panasonic Corporation Two Dimensional Optical Position Sensor Sales and Revenue in Global (2020-2025)
7.3.5 Panasonic Corporation Key News & Latest Developments
7.4 Illinois Tool Works Inc
7.4.1 Illinois Tool Works Inc Company Summary
7.4.2 Illinois Tool Works Inc Business Overview
7.4.3 Illinois Tool Works Inc Two Dimensional Optical Position Sensor Major Product Offerings
7.4.4 Illinois Tool Works Inc Two Dimensional Optical Position Sensor Sales and Revenue in Global (2020-2025)
7.4.5 Illinois Tool Works Inc Key News & Latest Developments
7.5 SHARP CORPORATION
7.5.1 SHARP CORPORATION Company Summary
7.5.2 SHARP CORPORATION Business Overview
7.5.3 SHARP CORPORATION Two Dimensional Optical Position Sensor Major Product Offerings
7.5.4 SHARP CORPORATION Two Dimensional Optical Position Sensor Sales and Revenue in Global (2020-2025)
7.5.5 SHARP CORPORATION Key News & Latest Developments
7.6 Renishaw plc
7.6.1 Renishaw plc Company Summary
7.6.2 Renishaw plc Business Overview
7.6.3 Renishaw plc Two Dimensional Optical Position Sensor Major Product Offerings
7.6.4 Renishaw plc Two Dimensional Optical Position Sensor Sales and Revenue in Global (2020-2025)
7.6.5 Renishaw plc Key News & Latest Developments
7.7 Bourns, Inc
7.7.1 Bourns, Inc Company Summary
7.7.2 Bourns, Inc Business Overview
7.7.3 Bourns, Inc Two Dimensional Optical Position Sensor Major Product Offerings
7.7.4 Bourns, Inc Two Dimensional Optical Position Sensor Sales and Revenue in Global (2020-2025)
7.7.5 Bourns, Inc Key News & Latest Developments
7.8 Honeywell International
7.8.1 Honeywell International Company Summary
7.8.2 Honeywell International Business Overview
7.8.3 Honeywell International Two Dimensional Optical Position Sensor Major Product Offerings
7.8.4 Honeywell International Two Dimensional Optical Position Sensor Sales and Revenue in Global (2020-2025)
7.8.5 Honeywell International Key News & Latest Developments
7.9 Micro-Epsilon
7.9.1 Micro-Epsilon Company Summary
7.9.2 Micro-Epsilon Business Overview
7.9.3 Micro-Epsilon Two Dimensional Optical Position Sensor Major Product Offerings
7.9.4 Micro-Epsilon Two Dimensional Optical Position Sensor Sales and Revenue in Global (2020-2025)
7.9.5 Micro-Epsilon Key News & Latest Developments
7.10 Balluff Automation India Pvt. Ltd
7.10.1 Balluff Automation India Pvt. Ltd Company Summary
7.10.2 Balluff Automation India Pvt. Ltd Business Overview
7.10.3 Balluff Automation India Pvt. Ltd Two Dimensional Optical Position Sensor Major Product Offerings
7.10.4 Balluff Automation India Pvt. Ltd Two Dimensional Optical Position Sensor Sales and Revenue in Global (2020-2025)
7.10.5 Balluff Automation India Pvt. Ltd Key News & Latest Developments
7.11 Celera Motion
7.11.1 Celera Motion Company Summary
7.11.2 Celera Motion Business Overview
7.11.3 Celera Motion Two Dimensional Optical Position Sensor Major Product Offerings
7.11.4 Celera Motion Two Dimensional Optical Position Sensor Sales and Revenue in Global (2020-2025)
7.11.5 Celera Motion Key News & Latest Developments
7.12 Pilz GmbH & Co. KG
7.12.1 Pilz GmbH & Co. KG Company Summary
7.12.2 Pilz GmbH & Co. KG Business Overview
7.12.3 Pilz GmbH & Co. KG Two Dimensional Optical Position Sensor Major Product Offerings
7.12.4 Pilz GmbH & Co. KG Two Dimensional Optical Position Sensor Sales and Revenue in Global (2020-2025)
7.12.5 Pilz GmbH & Co. KG Key News & Latest Developments
7.13 Ifm Electronic Gmbh
7.13.1 Ifm Electronic Gmbh Company Summary
7.13.2 Ifm Electronic Gmbh Business Overview
7.13.3 Ifm Electronic Gmbh Two Dimensional Optical Position Sensor Major Product Offerings
7.13.4 Ifm Electronic Gmbh Two Dimensional Optical Position Sensor Sales and Revenue in Global (2020-2025)
7.13.5 Ifm Electronic Gmbh Key News & Latest Developments
7.14 EFI Automotive
7.14.1 EFI Automotive Company Summary
7.14.2 EFI Automotive Business Overview
7.14.3 EFI Automotive Two Dimensional Optical Position Sensor Major Product Offerings
7.14.4 EFI Automotive Two Dimensional Optical Position Sensor Sales and Revenue in Global (2020-2025)
7.14.5 EFI Automotive Key News & Latest Developments
7.15 OMRON Corporation
7.15.1 OMRON Corporation Company Summary
7.15.2 OMRON Corporation Business Overview
7.15.3 OMRON Corporation Two Dimensional Optical Position Sensor Major Product Offerings
7.15.4 OMRON Corporation Two Dimensional Optical Position Sensor Sales and Revenue in Global (2020-2025)
7.15.5 OMRON Corporation Key News & Latest Developments
7.16 Hamamatsu Photonics K.K
7.16.1 Hamamatsu Photonics K.K Company Summary
7.16.2 Hamamatsu Photonics K.K Business Overview
7.16.3 Hamamatsu Photonics K.K Two Dimensional Optical Position Sensor Major Product Offerings
7.16.4 Hamamatsu Photonics K.K Two Dimensional Optical Position Sensor Sales and Revenue in Global (2020-2025)
7.16.5 Hamamatsu Photonics K.K Key News & Latest Developments
7.17 Melexis
7.17.1 Melexis Company Summary
7.17.2 Melexis Business Overview
7.17.3 Melexis Two Dimensional Optical Position Sensor Major Product Offerings
7.17.4 Melexis Two Dimensional Optical Position Sensor Sales and Revenue in Global (2020-2025)
7.17.5 Melexis Key News & Latest Developments
8 Global Two Dimensional Optical Position Sensor Production Capacity, Analysis
8.1 Global Two Dimensional Optical Position Sensor Production Capacity, 2026-2034
8.2 Two Dimensional Optical Position Sensor Production Capacity of Key Manufacturers in Global Market
8.3 Global Two Dimensional Optical Position Sensor Production by Region
9 Key Market Trends, Opportunity, Drivers and Restraints
9.1 Market Opportunities & Trends
9.2 Market Drivers
9.3 Market Restraints
10 Two Dimensional Optical Position Sensor Supply Chain Analysis
10.1 Two Dimensional Optical Position Sensor Industry Value Chain
10.2 Two Dimensional Optical Position Sensor Upstream Market
10.3 Two Dimensional Optical Position Sensor Downstream and Clients
10.4 Marketing Channels Analysis
10.4.1 Marketing Channels
10.4.2 Two Dimensional Optical Position Sensor Distributors and Sales Agents in Global
11 Conclusion
12 Appendix
12.1 Note
12.2 Examples of Clients
12.3 DisclaimerList of Tables
Table 1. Key Players of Two Dimensional Optical Position Sensor in Global Market
Table 2. Top Two Dimensional Optical Position Sensor Players in Global Market, Ranking by Revenue (2024)
Table 3. Global Two Dimensional Optical Position Sensor Revenue by Companies, (US$, Mn), 2020-2025
Table 4. Global Two Dimensional Optical Position Sensor Revenue Share by Companies, 2020-2025
Table 5. Global Two Dimensional Optical Position Sensor Sales by Companies, (K Units), 2020-2025
Table 6. Global Two Dimensional Optical Position Sensor Sales Share by Companies, 2020-2025
Table 7. Key Manufacturers Two Dimensional Optical Position Sensor Price (2020-2025) & (US$/Unit)
Table 8. Global Manufacturers Two Dimensional Optical Position Sensor Product Type
Table 9. List of Global Tier 1 Two Dimensional Optical Position Sensor Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 10. List of Global Tier 2 and Tier 3 Two Dimensional Optical Position Sensor Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 11. Segment by Type – Global Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2024 & 2032
Table 12. Segment by Type – Global Two Dimensional Optical Position Sensor Revenue (US$, Mn), 2020-2025
Table 13. Segment by Type – Global Two Dimensional Optical Position Sensor Revenue (US$, Mn), 2026-2032
Table 14. Segment by Type – Global Two Dimensional Optical Position Sensor Sales (K Units), 2020-2025
Table 15. Segment by Type – Global Two Dimensional Optical Position Sensor Sales (K Units), 2026-2032
Table 16. Segment by Application – Global Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2024 & 2032
Table 17. Segment by Application – Global Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2020-2025
Table 18. Segment by Application – Global Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2026-2032
Table 19. Segment by Application – Global Two Dimensional Optical Position Sensor Sales, (K Units), 2020-2025
Table 20. Segment by Application – Global Two Dimensional Optical Position Sensor Sales, (K Units), 2026-2032
Table 21. By Region – Global Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2025-2032
Table 22. By Region – Global Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2020-2025
Table 23. By Region – Global Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2026-2032
Table 24. By Region – Global Two Dimensional Optical Position Sensor Sales, (K Units), 2020-2025
Table 25. By Region – Global Two Dimensional Optical Position Sensor Sales, (K Units), 2026-2032
Table 26. By Country – North America Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2020-2025
Table 27. By Country – North America Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2026-2032
Table 28. By Country – North America Two Dimensional Optical Position Sensor Sales, (K Units), 2020-2025
Table 29. By Country – North America Two Dimensional Optical Position Sensor Sales, (K Units), 2026-2032
Table 30. By Country – Europe Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2020-2025
Table 31. By Country – Europe Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2026-2032
Table 32. By Country – Europe Two Dimensional Optical Position Sensor Sales, (K Units), 2020-2025
Table 33. By Country – Europe Two Dimensional Optical Position Sensor Sales, (K Units), 2026-2032
Table 34. By Region – Asia Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2020-2025
Table 35. By Region – Asia Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2026-2032
Table 36. By Region – Asia Two Dimensional Optical Position Sensor Sales, (K Units), 2020-2025
Table 37. By Region – Asia Two Dimensional Optical Position Sensor Sales, (K Units), 2026-2032
Table 38. By Country – South America Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2020-2025
Table 39. By Country – South America Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2026-2032
Table 40. By Country – South America Two Dimensional Optical Position Sensor Sales, (K Units), 2020-2025
Table 41. By Country – South America Two Dimensional Optical Position Sensor Sales, (K Units), 2026-2032
Table 42. By Country – Middle East & Africa Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2020-2025
Table 43. By Country – Middle East & Africa Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2026-2032
Table 44. By Country – Middle East & Africa Two Dimensional Optical Position Sensor Sales, (K Units), 2020-2025
Table 45. By Country – Middle East & Africa Two Dimensional Optical Position Sensor Sales, (K Units), 2026-2032
Table 46. First Sensor AG Company Summary
Table 47. First Sensor AG Two Dimensional Optical Position Sensor Product Offerings
Table 48. First Sensor AG Two Dimensional Optical Position Sensor Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 49. First Sensor AG Key News & Latest Developments
Table 50. Siemens Company Summary
Table 51. Siemens Two Dimensional Optical Position Sensor Product Offerings
Table 52. Siemens Two Dimensional Optical Position Sensor Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 53. Siemens Key News & Latest Developments
Table 54. Panasonic Corporation Company Summary
Table 55. Panasonic Corporation Two Dimensional Optical Position Sensor Product Offerings
Table 56. Panasonic Corporation Two Dimensional Optical Position Sensor Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 57. Panasonic Corporation Key News & Latest Developments
Table 58. Illinois Tool Works Inc Company Summary
Table 59. Illinois Tool Works Inc Two Dimensional Optical Position Sensor Product Offerings
Table 60. Illinois Tool Works Inc Two Dimensional Optical Position Sensor Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 61. Illinois Tool Works Inc Key News & Latest Developments
Table 62. SHARP CORPORATION Company Summary
Table 63. SHARP CORPORATION Two Dimensional Optical Position Sensor Product Offerings
Table 64. SHARP CORPORATION Two Dimensional Optical Position Sensor Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 65. SHARP CORPORATION Key News & Latest Developments
Table 66. Renishaw plc Company Summary
Table 67. Renishaw plc Two Dimensional Optical Position Sensor Product Offerings
Table 68. Renishaw plc Two Dimensional Optical Position Sensor Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 69. Renishaw plc Key News & Latest Developments
Table 70. Bourns, Inc Company Summary
Table 71. Bourns, Inc Two Dimensional Optical Position Sensor Product Offerings
Table 72. Bourns, Inc Two Dimensional Optical Position Sensor Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 73. Bourns, Inc Key News & Latest Developments
Table 74. Honeywell International Company Summary
Table 75. Honeywell International Two Dimensional Optical Position Sensor Product Offerings
Table 76. Honeywell International Two Dimensional Optical Position Sensor Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 77. Honeywell International Key News & Latest Developments
Table 78. Micro-Epsilon Company Summary
Table 79. Micro-Epsilon Two Dimensional Optical Position Sensor Product Offerings
Table 80. Micro-Epsilon Two Dimensional Optical Position Sensor Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 81. Micro-Epsilon Key News & Latest Developments
Table 82. Balluff Automation India Pvt. Ltd Company Summary
Table 83. Balluff Automation India Pvt. Ltd Two Dimensional Optical Position Sensor Product Offerings
Table 84. Balluff Automation India Pvt. Ltd Two Dimensional Optical Position Sensor Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 85. Balluff Automation India Pvt. Ltd Key News & Latest Developments
Table 86. Celera Motion Company Summary
Table 87. Celera Motion Two Dimensional Optical Position Sensor Product Offerings
Table 88. Celera Motion Two Dimensional Optical Position Sensor Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 89. Celera Motion Key News & Latest Developments
Table 90. Pilz GmbH & Co. KG Company Summary
Table 91. Pilz GmbH & Co. KG Two Dimensional Optical Position Sensor Product Offerings
Table 92. Pilz GmbH & Co. KG Two Dimensional Optical Position Sensor Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 93. Pilz GmbH & Co. KG Key News & Latest Developments
Table 94. Ifm Electronic Gmbh Company Summary
Table 95. Ifm Electronic Gmbh Two Dimensional Optical Position Sensor Product Offerings
Table 96. Ifm Electronic Gmbh Two Dimensional Optical Position Sensor Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 97. Ifm Electronic Gmbh Key News & Latest Developments
Table 98. EFI Automotive Company Summary
Table 99. EFI Automotive Two Dimensional Optical Position Sensor Product Offerings
Table 100. EFI Automotive Two Dimensional Optical Position Sensor Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 101. EFI Automotive Key News & Latest Developments
Table 102. OMRON Corporation Company Summary
Table 103. OMRON Corporation Two Dimensional Optical Position Sensor Product Offerings
Table 104. OMRON Corporation Two Dimensional Optical Position Sensor Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 105. OMRON Corporation Key News & Latest Developments
Table 106. Hamamatsu Photonics K.K Company Summary
Table 107. Hamamatsu Photonics K.K Two Dimensional Optical Position Sensor Product Offerings
Table 108. Hamamatsu Photonics K.K Two Dimensional Optical Position Sensor Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 109. Hamamatsu Photonics K.K Key News & Latest Developments
Table 110. Melexis Company Summary
Table 111. Melexis Two Dimensional Optical Position Sensor Product Offerings
Table 112. Melexis Two Dimensional Optical Position Sensor Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 113. Melexis Key News & Latest Developments
Table 114. Two Dimensional Optical Position Sensor Capacity of Key Manufacturers in Global Market, 2023-2025 (K Units)
Table 115. Global Two Dimensional Optical Position Sensor Capacity Market Share of Key Manufacturers, 2023-2025
Table 116. Global Two Dimensional Optical Position Sensor Production by Region, 2020-2025 (K Units)
Table 117. Global Two Dimensional Optical Position Sensor Production by Region, 2026-2032 (K Units)
Table 118. Two Dimensional Optical Position Sensor Market Opportunities & Trends in Global Market
Table 119. Two Dimensional Optical Position Sensor Market Drivers in Global Market
Table 120. Two Dimensional Optical Position Sensor Market Restraints in Global Market
Table 121. Two Dimensional Optical Position Sensor Raw Materials
Table 122. Two Dimensional Optical Position Sensor Raw Materials Suppliers in Global Market
Table 123. Typical Two Dimensional Optical Position Sensor Downstream
Table 124. Two Dimensional Optical Position Sensor Downstream Clients in Global Market
Table 125. Two Dimensional Optical Position Sensor Distributors and Sales Agents in Global Market

List of Figures
Figure 1. Two Dimensional Optical Position Sensor Product Picture
Figure 2. Two Dimensional Optical Position Sensor Segment by Type in 2024
Figure 3. Two Dimensional Optical Position Sensor Segment by Application in 2024
Figure 4. Global Two Dimensional Optical Position Sensor Market Overview: 2024
Figure 5. Key Caveats
Figure 6. Global Two Dimensional Optical Position Sensor Market Size: 2024 VS 2032 (US$, Mn)
Figure 7. Global Two Dimensional Optical Position Sensor Revenue: 2026-2034 (US$, Mn)
Figure 8. Two Dimensional Optical Position Sensor Sales in Global Market: 2026-2034 (K Units)
Figure 9. The Top 3 and 5 Players Market Share by Two Dimensional Optical Position Sensor Revenue in 2024
Figure 10. Segment by Type – Global Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2024 & 2032
Figure 11. Segment by Type – Global Two Dimensional Optical Position Sensor Revenue Market Share, 2026-2034
Figure 12. Segment by Type – Global Two Dimensional Optical Position Sensor Sales Market Share, 2026-2034
Figure 13. Segment by Type – Global Two Dimensional Optical Position Sensor Price (US$/Unit), 2026-2034
Figure 14. Segment by Application – Global Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2024 & 2032
Figure 15. Segment by Application – Global Two Dimensional Optical Position Sensor Revenue Market Share, 2026-2034
Figure 16. Segment by Application – Global Two Dimensional Optical Position Sensor Sales Market Share, 2026-2034
Figure 17. Segment by Application -Global Two Dimensional Optical Position Sensor Price (US$/Unit), 2026-2034
Figure 18. By Region – Global Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2025 & 2032
Figure 19. By Region – Global Two Dimensional Optical Position Sensor Revenue Market Share, 2020 VS 2024 VS 2032
Figure 20. By Region – Global Two Dimensional Optical Position Sensor Revenue Market Share, 2026-2034
Figure 21. By Region – Global Two Dimensional Optical Position Sensor Sales Market Share, 2026-2034
Figure 22. By Country – North America Two Dimensional Optical Position Sensor Revenue Market Share, 2026-2034
Figure 23. By Country – North America Two Dimensional Optical Position Sensor Sales Market Share, 2026-2034
Figure 24. United States Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2026-2034
Figure 25. Canada Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2026-2034
Figure 26. Mexico Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2026-2034
Figure 27. By Country – Europe Two Dimensional Optical Position Sensor Revenue Market Share, 2026-2034
Figure 28. By Country – Europe Two Dimensional Optical Position Sensor Sales Market Share, 2026-2034
Figure 29. Germany Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2026-2034
Figure 30. France Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2026-2034
Figure 31. U.K. Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2026-2034
Figure 32. Italy Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2026-2034
Figure 33. Russia Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2026-2034
Figure 34. Nordic Countries Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2026-2034
Figure 35. Benelux Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2026-2034
Figure 36. By Region – Asia Two Dimensional Optical Position Sensor Revenue Market Share, 2026-2034
Figure 37. By Region – Asia Two Dimensional Optical Position Sensor Sales Market Share, 2026-2034
Figure 38. China Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2026-2034
Figure 39. Japan Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2026-2034
Figure 40. South Korea Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2026-2034
Figure 41. Southeast Asia Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2026-2034
Figure 42. India Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2026-2034
Figure 43. By Country – South America Two Dimensional Optical Position Sensor Revenue Market Share, 2026-2034
Figure 44. By Country – South America Two Dimensional Optical Position Sensor Sales, Market Share, 2026-2034
Figure 45. Brazil Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2026-2034
Figure 46. Argentina Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2026-2034
Figure 47. By Country – Middle East & Africa Two Dimensional Optical Position Sensor Revenue, Market Share, 2026-2034
Figure 48. By Country – Middle East & Africa Two Dimensional Optical Position Sensor Sales, Market Share, 2026-2034
Figure 49. Turkey Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2026-2034
Figure 50. Israel Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2026-2034
Figure 51. Saudi Arabia Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2026-2034
Figure 52. UAE Two Dimensional Optical Position Sensor Revenue, (US$, Mn), 2026-2034
Figure 53. Global Two Dimensional Optical Position Sensor Production Capacity (K Units), 2026-2034
Figure 54. The Percentage of Production Two Dimensional Optical Position Sensor by Region, 2024 VS 2032
Figure 55. Two Dimensional Optical Position Sensor Industry Value Chain
Figure 56. Marketing Channels