SEMICONDUCTOR INSIGHT
MARKET RESEARCH REPORT

SJ MOSFETs Market

2026 to 2034
MARKET INTELLIGENCE
ACROSS KEY REGIONS
2026 EDITION
POWER ELECTRONICS Semiconductor Market Research

SJ MOSFETs Market

◷
UPDATED 26 October 2026
▤
REPORT LENGTH Detailed Report
▣
REPORT CODE 9ce291f078b4
▯
FORMATS PDF

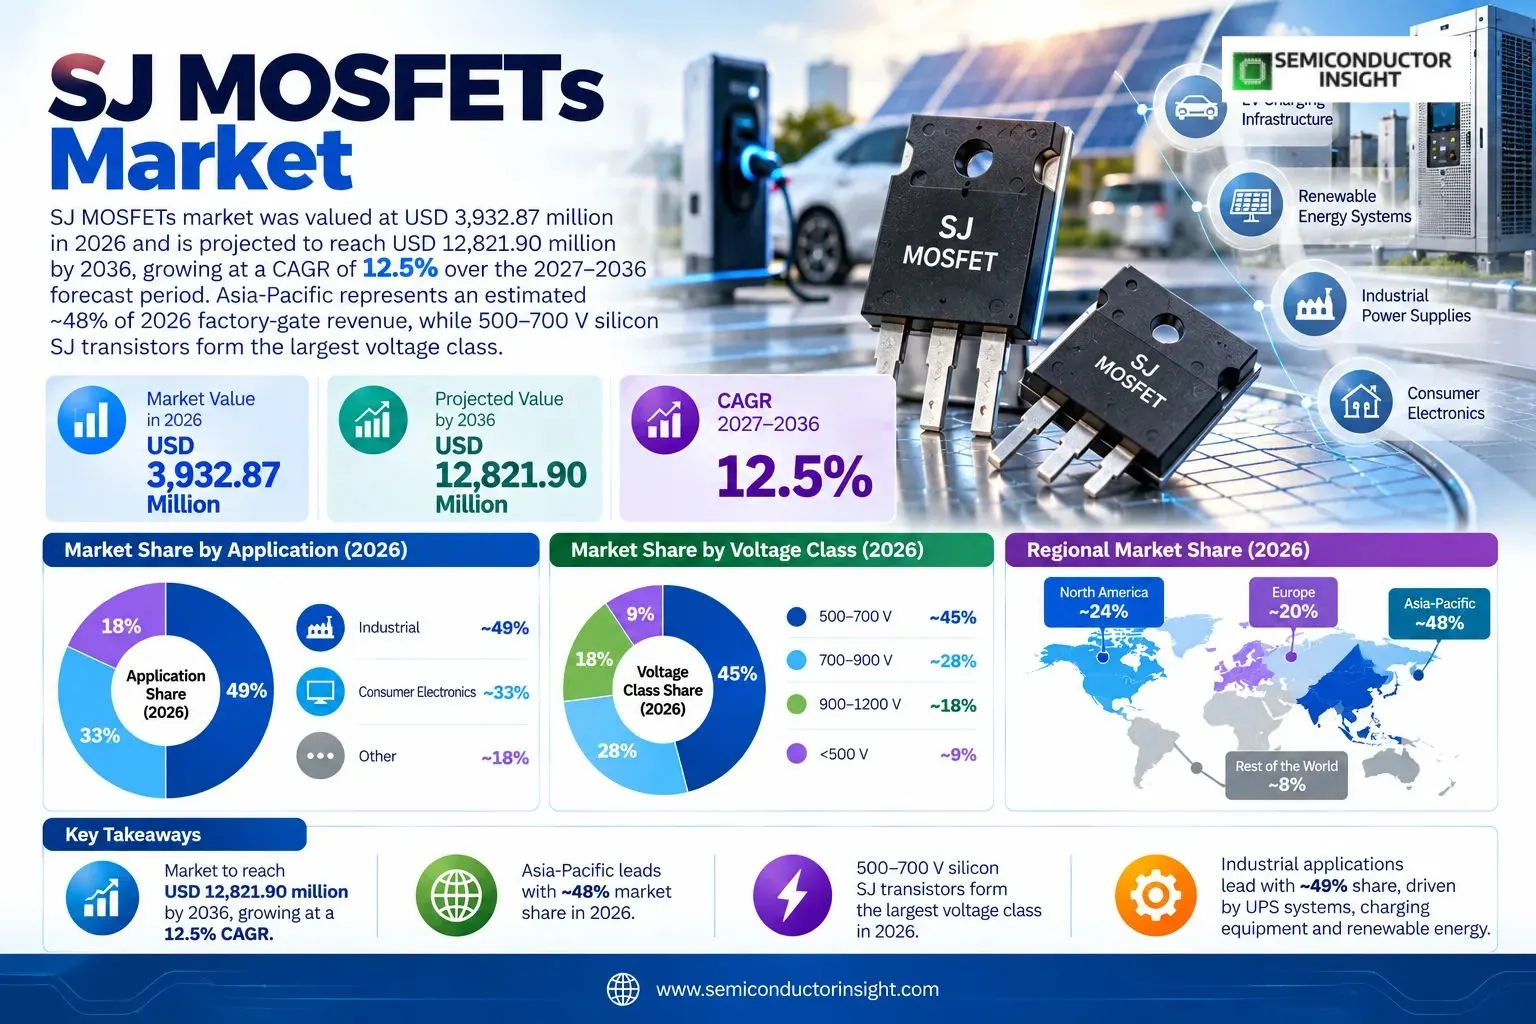
SJ MOSFETs market was valued at USD 3,932.87 million in 2026 and is projected to reach USD 12,821.90 million by 2036, growing at a CAGR of 12.5% over the 2027–2036 forecast period. Asia-Pacific represents an estimated ~48% of 2026 factory-gate revenue, while 500–700 V silicon SJ transistors form the largest voltage class.

Get the sample PDF with study scope, segmentation and methodology details.

Key Statistics

2026 Market Size
USD 3,932.87 million
2036 Projected Size
USD 12,821.90 million
CAGR (2027–2036)
12.5%
Largest Market in 2026
Asia-Pacific (~48%)

Key Takeaways

  • Market trajectory: factory-gate silicon superjunction transistor revenue is modeled at USD 3,932.87 million in 2026, increasing to USD 12,821.90 million in 2036 at a reconciled 12.5% CAGR; demand is tied to efficient high-voltage AC/DC conversion rather than complete power-system value.
  • 500–700 V: this core voltage class is estimated at ~70% of 2026 revenue; 600 V and 650 V parts dominate server supplies, adapters, power-factor correction and industrial conversion, with 700–900 V options used when voltage margin and ruggedness are priorities.
  • Industrial demand: industrial applications hold an estimated ~49% share, supported by charging equipment, UPS, factory supplies and solar power electronics; the consumer-electronics application is modeled at ~33% because adapters and household appliances continue to need cost-effective silicon devices.
  • Asia-Pacific: the largest regional demand and manufacturing cluster holds an estimated ~48% of 2026 sales; China, Japan, South Korea and Taiwan combine consumer-electronics assembly, industrial conversion demand and SJ product engineering.
  • Technology boundary: silicon SJ devices compete with silicon carbide and gallium nitride in some converter positions but their revenues cannot be aggregated with wide-bandgap MOSFET and HEMT categories; wafer revenue and finished converters are excluded.

SJ MOSFETs Market Overview

SJ MOSFETs market was valued at USD 3,932.87 million in 2026 and is projected to reach USD 12,821.90 million by 2036, growing at a CAGR of 12.5% over the 2027–2036 forecast period. Asia-Pacific represents an estimated ~48% of 2026 factory-gate revenue, while 500–700 V silicon SJ transistors form the largest voltage class.

Base year: 2026 · Estimated year: 2027 · Forecast: 2027–2036 · Historic reference: 2024 · Unit: USD million · Finished silicon SJ MOSFET devices only

Superjunction MOSFETs use charge-balanced vertical silicon structures to reduce the resistance penalty normally associated with high blocking voltage. In a 600 V converter, this topology can lower conduction losses without the material and manufacturing cost profile of silicon carbide. The addressable product is the finished transistor shipped to an equipment maker or distributor, not the circuit board, driver IC, complete inverter, upstream wafer or energy delivered by the equipment.

The 2026 market model reconciles two historical monetary endpoints using an eight-year compounding interval. A 2024 value of USD 3.105 billion and a 2032 value of USD 7.992 billion produce an implied annual increase of ~12.54%, materially below a separate stated 16.5% growth figure. The published 2036 extension therefore follows the endpoint-consistent trajectory; it remains a scenario beyond the final monetary endpoint rather than a manufacturer-certified shipment projection.

Electrical selection is a trade-off between drain-source on-resistance, gate charge, output capacitance, body-diode recovery and thermal path. Infineon markets 600 V CoolMOS 8 with an integrated fast body diode, while ST introduced a 600 V deep-trench STMESH device fabricated on 12-inch wafers. Vishay, Toshiba and AOS likewise describe new 600–650 V families aimed at efficiency improvements in servers, power supplies and industrial equipment.

Competition is not confined to one region or process generation. Magnachip expanded its sixth-generation catalog in 2025 and 2026, including consumer-adapter and AI-server devices; ROHM offers high-speed 600 V superjunction products, and Fuji Electric continues to describe its Super J MOS line. China-based Wayon and Oriental Semiconductor add manufacturing and catalog breadth, although the evidence establishes product availability rather than an audited revenue share for any company.

The primary commercial tension is between silicon cost and the high-frequency capability of wide-bandgap alternatives. Silicon SJ remains attractive where mature package supply, robust body diodes and predictable qualification outweigh the last increment of switching speed. GaN can displace silicon in very compact chargers, while SiC can win higher-voltage, high-temperature sockets; neither technology is counted as SJ silicon revenue in this study.

Segment Analysis: By Type

The voltage-class view groups finished silicon SJ MOSFETs by rated drain-source breakdown voltage rather than by wafer diameter or package. The 500–700 V class represents an estimated ~70% of 2026 factory-gate revenue, as 600 V and 650 V parts fit mainstream AC/DC and PFC designs. Higher ratings trade switching efficiency and cost against margin in demanding industrial applications.

Voltage class Engineering role and buying decision 2026 revenue position
500–700 V This class contains the 500 V, 600 V and 650 V silicon SJ transistors used in the largest number of offline converter topologies. The buyer chooses a resistance and gate-charge combination that balances load efficiency, heat removal and switching frequency, with different body-diode options for PFC and resonant stages. Largest estimated ~70% share in 2026. Infineon CoolMOS 8, ST STMESH, Vishay E Series, Toshiba DTMOSVI, ROHM R60 and AOS alphaMOS products provide direct examples. The market is competitive on package yield and qualified supply, so a technology generation does not automatically translate into higher unit revenue.
700–900 V Higher breakdown ratings address industrial inputs, power-factor-correction margin and line-transient conditions that can make a 600 V device unsuitable. These parts may sacrifice some conduction or switching efficiency for electrical headroom, and qualification includes avalanche energy, surge robustness and recovery behavior under realistic operating conditions. Estimated ~19% of 2026 revenue. Supplier portfolios offer selective higher-voltage SJ options, but design-in frequency is lower than for the 600–650 V mainstream. Product mix is driven by end-equipment standards and circuit topology, not by a claim that every high-voltage MOSFET uses a superjunction architecture.
Others The residual voltage grouping captures SJ products outside the two main rating intervals, including specialized voltage options where the topology can meet unusual equipment specifications. A MOSFET rated below 500 V must be demonstrably a silicon superjunction device to qualify; ordinary low-voltage trench products and non-SJ planar devices are not included merely because their vendors also sell SJ families. Estimated ~11% of 2026 revenue. The category is deliberately limited to verified SJ architectures, not an all-purpose residual for power transistors. Some suppliers use charge-balanced concepts at lower voltages, but the addressable value is narrower than the broad low-voltage MOSFET industry and cannot be combined with it.

Secondary segmentation: end user and technology

End-user segmentation separates Automotive, Telecommunications, Energy & Power and Others; the latter includes consumer appliances and general computing supplies rather than an additional industry counted twice. Technology segmentation distinguishes conduction-loss-optimized devices, fast-switching designs and specialized other SJ variants. Each axis is a complete alternative view of the same market, so their percentages are not additive across axes. The estimated ~31% Energy & Power share is a demand scenario, not a manufacturer-disclosed revenue figure.

Axis Segment Modeled share Modeled growth
End User Automotive ~18% of 2026 revenue ~13.9% CAGR
End User Telecommunications ~20% of 2026 revenue ~11.5% CAGR
End User Energy & Power ~31% of 2026 revenue ~13.4% CAGR
End User Others ~31% of 2026 revenue ~11.4% CAGR
Technology Conduction Loss Optimized ~53% of 2026 revenue ~12.3% CAGR
Technology Fast-Switching ~37% of 2026 revenue ~13.6% CAGR
Technology Others ~10% of 2026 revenue ~9.4% CAGR

The secondary model reconciles category growth to the same 2036 market total. A fast-switching device may be sold into a telecom rectifier, so technology and end-user shares describe different attributes of one transistor transaction. Product sheets substantiate the existence of low gate-charge, fast-diode and low-resistance choices; they do not disclose shipment splits. For that reason all individual growth rates and segment percentages are presented as modeled rather than audited results.

Segment Analysis: By Application

Application demand is segmented into Consumer Electronics, Industrial and Other. Industrial conversion is the largest estimated application at ~49% of 2026 revenue, reflecting UPS systems, charging equipment, solar power electronics and factory power supplies. Consumer Electronics follows at ~33% through TVs, notebook adapters, household appliance controls and desktop power supplies; Other captures applications outside these groups without counting finished systems.

Application Demand characteristics
Consumer Electronics Estimated ~33% of 2026 revenue. Magnachip introduced 15 sixth-generation E6 superjunction parts for TVs, notebook adapters and PC supplies in October 2026, while Infineon lists adapters and residential appliance PFC among silicon SJ applications. Buyers emphasize compact thermal design, stable electromagnetic interference and cost in products manufactured at large scale, with many designs using 500–650 V switching devices.
Industrial Largest estimated ~49% of 2026 revenue. Industrial AC/DC supplies, EV charging equipment, UPS, telecom infrastructure and solar conversion stages use 600–900 V SJ switches where body-diode behavior and reliable operation matter. AOS, Vishay, Toshiba and ST document silicon SJ families aimed at these power stages. The value counted is the transistor purchased by an equipment manufacturer, not the charging station or inverter selling price.
Other Estimated ~18% of 2026 revenue. This residual includes specialized infrastructure, energy-management and equipment sockets that cannot be classified cleanly as consumer or general industrial conversion. Each eligible sale must still be a finished silicon superjunction MOSFET. A generic transistor listing or downstream service contract is insufficient to count as SJ market revenue, and end-use labels do not replace device-level evidence.

Across application categories, qualification cycles determine revenue timing. A new SJ generation can deliver lower conduction loss or smaller package area, yet the equipment maker must still validate switching stress, temperature rise, EMI and long-term supply. The 2026 industrial share of ~49% therefore should not be interpreted as the same percentage of global industrial equipment production. It is an allocation of silicon SJ transistor purchases only.

Consumer demand is more sensitive to product refreshes and component prices, whereas industrial buyers often pay for long-lived packages and application engineering. The ~33% consumer allocation includes adapter and appliance applications with repetitive high-volume sockets, but does not imply that every TV or computer uses a superjunction device. GaN adapters, integrated flyback solutions and conventional MOSFETs compete for parts of the same end-equipment demand.
Regional Analysis

The global demand model allocates 2026 silicon SJ MOSFET revenue across five non-overlapping regions. Asia-Pacific is the largest at an estimated ~48%, followed by Europe at ~22%, North America at ~20%, South America at ~5%, and Middle East & Africa at ~5%. Each share refers to finished silicon SJ transistor value, not the location of wafer fabrication, a manufacturer headquarters or the value of complete power equipment.

How do regional manufacturing ecosystems influence superjunction MOSFET demand?

Regional demand depends on the geographic location of the finished-device customer, while technology leadership can originate elsewhere. Infineon and ST engineer European silicon SJ processes; AOS and Vishay market U.S.-linked products; Toshiba, ROHM, Magnachip and Chinese manufacturers maintain Asian portfolios. This distinction is essential because a transistor can be designed in one country, fabricated in another, assembled in a third and sold through an international distributor.

Growth differs by the pace of power-supply redesign, efficiency requirements and OEM qualification. The model assigns Asia-Pacific a ~13.1% CAGR, Europe ~11.3%, North America ~12.2%, South America ~13.6% and Middle East & Africa ~14.4%. These values reconcile with the total forecast through share-weighted compounding; they are analytical allocations, not figures separately published by national statistical offices.

Region Position Growth outlook Demand profile What decides supplier selection
Asia-Pacific ~48% of 2026 revenue ~12.9% CAGR Supply and design hub Device qualification, thermal limits and channel access
Europe ~22% of 2026 revenue ~11.3% CAGR Design leadership Device qualification, thermal limits and channel access
North America ~20% of 2026 revenue ~12.2% CAGR Cloud and power equipment Device qualification, thermal limits and channel access
South America ~5% of 2026 revenue ~13.6% CAGR Industrial and appliance base Device qualification, thermal limits and channel access
Middle East & Africa ~5% of 2026 revenue ~14.4% CAGR Energy and digital facilities Device qualification, thermal limits and channel access

Asia-Pacific ~48% SHARE · ~12.9% CAGR

What is driving silicon SJ MOSFET demand in Asia-Pacific?

Asia-Pacific accounts for an estimated ~48% of global 2026 silicon superjunction MOSFET revenue, with a modeled ~12.9% CAGR through 2036. Regional purchasing characteristics differ: China emphasizes supply and design hub, while Japan contributes high-voltage engineering and South Korea and Taiwan adds power supply ecosystems. For Asia-Pacific, those purchasing channels require qualified voltage classes, thermal designs and component supply strategies that reflect the regional equipment mix; the scenario excludes the value of complete power systems.

Market position~48% (2026)
Growth outlook~12.9% CAGR
Demand profile600–650 V conversion
Market access gateQualified supplier channels
Country Position in region What drives demand
China Supply and design hub Chinese firms such as Wayon and Oriental Semiconductor explicitly identify superjunction MOSFET portfolios for industrial and consumer power conversion. Regional revenue is driven by finished-device demand and not by counting semiconductor wafer production a second time. Manufacturing scale may influence prices, but it does not establish an audited national market share; the ~48% regional allocation remains a modeled scenario.
Japan High-voltage engineering Toshiba introduced a 600 V DTMOSVI device in a compact DFN8x8 package in November 2025, and ROHM lists 600 V high-speed superjunction products. Fuji Electric also maintains a Super J MOS catalog. Japanese demand favors thermal stability and power-supply reliability, particularly in industrial automation and household appliances, rather than an assumption that every locally designed converter uses silicon SJ.
South Korea and Taiwan Power supply ecosystems Magnachip expanded its Gen6 SJ product portfolio with server, EV charging and consumer-adapter variants during 2025 and 2026. Korean design engineering supports higher switching performance and smaller dies; Taiwan contributes power-supply OEM and ODM activity. The market impact is a broad qualification pipeline, although company launch counts are not directly convertible into national revenue.

Market instances

  • Magnachip expanded Gen6 devices for server power. The company announced 25 sixth-generation SJ MOSFETs in March 2025 and added two 600 V devices in June 2026. These products address efficiency and switching in servers and charging equipment. The development supports an active Asia-Pacific supply base and technology migration, but the announcements do not report global unit shipments or prove the modeled ~48% regional share.
  • Oriental Semiconductor markets GreenMOS technology. The Chinese manufacturer describes its GreenMOS family as a high-voltage superjunction portfolio serving power supplies, charging and industrial systems. The presence of a dedicated SJ product line supports local design and manufacturing capability. It should not be treated as a published country revenue series or as evidence that all MOSFETs sold by the company qualify for this market.
  • ROHM lists 600 V high-speed SJ options. ROHM identifies R6030KNZ4 as a 600 V, 30 A high-speed switching superjunction device and links the family to PFC and LLC stages. This gives buyers a specific Japanese device family for comparison with imported alternatives. It supports a technically diversified supplier field without independently measuring the number of Japanese or regional purchases.
In the full report: Country-specific silicon SJ transistor revenue, qualified manufacturer sales and end-user applications across Asia-Pacific, with separate treatment of 500–700 V, 700–900 V and other silicon SJ voltage classes. It examines China in detail alongside Japan and South Korea and Taiwan, excluding upstream wafers and finished converter systems.

Europe ~22% SHARE · ~11.3% CAGR

What is driving silicon SJ MOSFET demand in Europe?

Europe accounts for an estimated ~22% of global 2026 silicon superjunction MOSFET revenue, with a modeled ~11.3% CAGR through 2036. Regional purchasing characteristics differ: Germany emphasizes design leadership, while France and Italy contributes industrial power systems and United Kingdom and Nordic countries adds specialized power conversion. For Europe, those purchasing channels require qualified voltage classes, thermal designs and component supply strategies that reflect the regional equipment mix; the scenario excludes the value of complete power systems.

Market position~22% (2026)
Growth outlook~11.3% CAGR
Demand profile600–650 V conversion
Market access gateQualified supplier channels
Country Position in region What drives demand
Germany Design leadership Infineon developed CoolMOS 8 for server, telecom and energy-conversion applications and disclosed a LITEON design-in for 600 V parts in April 2025. Germany is important for product engineering and qualification even when semiconductor diffusion, assembly and end-system manufacturing occur in different countries. The ~22% regional revenue share is modeled demand rather than a calculation from Infineon consolidated sales.
France and Italy Industrial power systems STMicroelectronics documents 600 V STMESH deep-trench technology and a 12-inch wafer process, with applications in UPS, charging, renewable energy and telecom. European customers often evaluate power density and production consistency alongside switching losses. These technical factors support silicon SJ sockets, but the existence of European engineering sites does not prove the origin of every device shipment.
United Kingdom and Nordic countries Specialized power conversion Industrial power-supply integrators, renewable-power electronics firms and equipment designers create smaller but specification-sensitive demand. Buyers value lifecycle support, thermal data and repeatable device characteristics under varied operating conditions. Revenue is assigned to finished SJ device purchases in these countries, not to the capital value of wind farms, battery projects or entire industrial control systems.

Market instances

  • Infineon confirmed a 600 V CoolMOS 8 server design-in. On 30 April 2025 Infineon described a CoolMOS 8 supply relationship with LITEON for server power supplies, including claimed improvements in gate charge and thermal performance. This is concrete product-application evidence for Europe-origin technology. The commercial effect is qualification in high-efficiency systems, not a disclosed regional MOSFET revenue number.
  • ST documented its 12-inch superjunction process. ST introduced a deep-trench 600 V STMESH device and described the manufacturing simplification enabled by a 12-inch wafer platform in February 2025. The engineering relevance is a possible cost and capacity advantage for mature silicon high-voltage switches. That wafer diameter is a fabrication characteristic, not a separate category of finished SJ market sales.
  • IceMOS describes a deep-trench SJ architecture. IceMOS presents a high-voltage superjunction transistor concept alongside MEMS and substrate engineering activities. Its documentation indicates technical participation in the ecosystem, although merchant shipment scale and current finished-device availability require individual qualification. This distinction prevents research, process IP and substrate activity from being counted automatically as finished silicon MOSFET revenue.
In the full report: Country-specific silicon SJ transistor revenue, qualified manufacturer sales and end-user applications across Europe, with separate treatment of 500–700 V, 700–900 V and other silicon SJ voltage classes. It examines Germany in detail alongside France and Italy and United Kingdom and Nordic countries, excluding upstream wafers and finished converter systems.

North America ~20% SHARE · ~12.2% CAGR

What is driving silicon SJ MOSFET demand in North America?

North America accounts for an estimated ~20% of global 2026 silicon superjunction MOSFET revenue, with a modeled ~12.2% CAGR through 2036. Regional purchasing characteristics differ: United States emphasizes cloud and power equipment, while Canada contributes industrial and infrastructure and Mexico adds electronics assembly. For North America, those purchasing channels require qualified voltage classes, thermal designs and component supply strategies that reflect the regional equipment mix; the scenario excludes the value of complete power systems.

Market position~20% (2026)
Growth outlook~12.2% CAGR
Demand profile600–650 V conversion
Market access gateQualified supplier channels
Country Position in region What drives demand
United States Cloud and power equipment AOS announced a 600 V alphaMOS E2 platform in January 2026 and top-side cooled variants in September, targeting servers, solar conversion and industrial supplies. Vishay introduced a 650 V Gen 4.5 E Series product in March 2025. These launches support a robust U.S.-linked product ecosystem, but manufacturer headquarters do not define the geography of final transistor consumption.
Canada Industrial and infrastructure Canadian demand comes from data-center electrical infrastructure, industrial automation and power electronics for energy projects. Buyers must evaluate surge ratings, conduction losses and package reliability under demanding duty cycles. The market boundary covers silicon SJ devices imported or locally purchased for such equipment, rather than the entire cost of energy projects, battery storage installations or utility construction.
Mexico Electronics assembly Power-supply manufacturing and appliance assembly create demand for qualified high-voltage MOSFETs in Mexico. Purchasing may be controlled by international OEMs and executed through regional distributors, complicating attribution by country. A finished SJ transistor should be counted once at factory-gate value even if it crosses several borders before being installed in a finished appliance or server.

Market instances

  • AOS launched 600 V alphaMOS E2 in January 2026. AOS described the AOTL037V60DE2 600 V SJ MOSFET for servers, telecom rectifiers, solar inverters and industrial power systems, including availability in production quantities. This establishes a merchant product offering and links technical requirements to power-density demand. It does not disclose the North American share of global device revenue.
  • Vishay introduced a 650 V E Series MOSFET. Vishay announced the SiHK050N65E in March 2025, citing low on-resistance and figures of merit for telecom, computing and industrial power conversion. The product supports a clear North American design-and-sales role in high-voltage silicon switching. Its published electrical specifications should not be transformed into an unverified company revenue share.
  • AOS expanded top-side cooling options in September 2026. AOS released 600 V top-side cooled SJ variants for power systems, solar inverters and server applications. The package innovation can reduce thermal bottlenecks and support denser assemblies, which is relevant to North American computing infrastructure. The announcement is evidence of product development, not a quantified regional shipment forecast.
In the full report: Country-specific silicon SJ transistor revenue, qualified manufacturer sales and end-user applications across North America, with separate treatment of 500–700 V, 700–900 V and other silicon SJ voltage classes. It examines United States in detail alongside Canada and Mexico, excluding upstream wafers and finished converter systems.

South America ~5% SHARE · ~13.6% CAGR

What is driving silicon SJ MOSFET demand in South America?

South America accounts for an estimated ~5% of global 2026 silicon superjunction MOSFET revenue, with a modeled ~13.6% CAGR through 2036. Regional purchasing characteristics differ: Brazil emphasizes industrial and appliance base, while Argentina contributes selective replacement and Chile and Colombia adds energy electronics. For South America, those purchasing channels require qualified voltage classes, thermal designs and component supply strategies that reflect the regional equipment mix; the scenario excludes the value of complete power systems.

Market position~5% (2026)
Growth outlook~13.6% CAGR
Demand profile600–650 V conversion
Market access gateQualified supplier channels
Country Position in region What drives demand
Brazil Industrial and appliance base Brazilian industrial drives, commercial power supplies and appliance assembly create applications for imported 600–650 V superjunction MOSFETs. Procurement commonly relies on global distributors and OEM-qualified power platforms, making local manufacturer revenue attribution difficult. The estimated ~5% share is a model of finished transistor demand, not a statement about the share of global electrical generation or semiconductor fabrication.
Argentina Selective replacement Replacement power supplies, industrial maintenance and specialized conversion equipment create more episodic SJ demand. Price and import availability can determine whether a designer uses a newer low-resistance device or continues with a qualified older package. The region is not assumed to have large local silicon SJ fabrication merely because equipment incorporating these devices is assembled or serviced there.
Chile and Colombia Energy electronics Solar inverters, UPS and telecom power equipment provide potential SJ sockets, especially where buyers prefer mature 600 V silicon platforms. The finished transistor represents only a small component of the equipment value, so project investment is not used as a direct revenue proxy. The regional growth estimate is a modeled demand trajectory rather than a measured semiconductor shipment series.

Market instances

  • Industrial power conversion uses mature SJ architectures. Manufacturers including AOS and ROHM document 600 V superjunction products for solar and industrial supplies, which can be sourced into South American equipment through international channels. The evidence establishes technical suitability but not a country-level installation count. Consequently the modeled ~5% regional allocation is deliberately separated from unsupported claims of domestic SJ wafer production.
  • Package selection affects import economics. Vishay and Toshiba offer different high-voltage SJ packages with thermal and switching trade-offs. For import-dependent markets, an established footprint can reduce redesign costs and supply disruptions, while compact SMD options support denser boards. The commercial implication is vendor qualification and stock availability, not a measurable market-share change from a single product announcement.
  • Renewable conversion is a component-level opportunity. Solar power electronics and storage systems use multiple switching technologies, and the same system may contain silicon SJ, SiC or GaN devices. Only the finished SJ silicon transistor portion belongs in this market. This prevents the value of an entire inverter or battery installation from inflating the regional revenue estimate.
In the full report: Country-specific silicon SJ transistor revenue, qualified manufacturer sales and end-user applications across South America, with separate treatment of 500–700 V, 700–900 V and other silicon SJ voltage classes. It examines Brazil in detail alongside Argentina and Chile and Colombia, excluding upstream wafers and finished converter systems.

Middle East & Africa ~5% SHARE · ~14.4% CAGR

What is driving silicon SJ MOSFET demand in Middle East & Africa?

Middle East & Africa accounts for an estimated ~5% of global 2026 silicon superjunction MOSFET revenue, with a modeled ~14.4% CAGR through 2036. Regional purchasing characteristics differ: Gulf Cooperation Council emphasizes energy and digital facilities, while South Africa contributes industrial electrical systems and Türkiye and North Africa adds manufacturing and assembly. For Middle East & Africa, those purchasing channels require qualified voltage classes, thermal designs and component supply strategies that reflect the regional equipment mix; the scenario excludes the value of complete power systems.

Market position~5% (2026)
Growth outlook~14.4% CAGR
Demand profile600–650 V conversion
Market access gateQualified supplier channels
Country Position in region What drives demand
Gulf Cooperation Council Energy and digital facilities Data-center power supplies, UPS systems and renewable-energy conversion create high-voltage switching opportunities. Buyers prioritize thermal headroom and reliable operation at elevated ambient temperatures. Device sourcing typically involves international OEMs and component distributors, so the estimated ~5% regional share is a demand model rather than evidence of local superjunction fabrication or independently measured shipment totals.
South Africa Industrial electrical systems Industrial maintenance, telecommunications power systems and commercial energy conversion support selective use of mature silicon SJ transistors. Voltage margins and replacement compatibility matter because installed equipment may operate for many years. The finished semiconductor transaction is distinct from power-system engineering contracts, and no local revenue figure is inferred from the value of infrastructure investment.
Türkiye and North Africa Manufacturing and assembly Electronics assembly and industrial power-supply manufacturing can draw on global 600 V superjunction catalogs. Availability, certification and cost are important in supplier selection, particularly where procurement involves multiple currencies and long lead times. The regional model does not assume that imported converter assemblies are produced entirely from SJ transistors or that all power MOSFETs use this architecture.

Market instances

  • High-temperature operation raises qualification requirements. Infineon and Toshiba publish thermal and package information for high-voltage SJ products, giving equipment designers a basis for checking junction temperature under hot ambient conditions. In Gulf installations, such qualification can matter more than nominal room-temperature resistance. The source evidence concerns component capabilities and does not provide a country-level merchant sales series.
  • Server and telecom supplies use silicon SJ switches. AOS and Vishay identify server and telecom power applications for 600–650 V superjunction MOSFETs. These product families can serve regional data-center and communications equipment procured from international OEMs. The presence of those applications supports demand potential without proving the volume of semiconductor purchases in Middle Eastern or African markets.
  • Solar equipment is not itself semiconductor revenue. ROHM, Magnachip and Infineon document high-voltage silicon switches used in power conversion, including renewable-energy applications. The model attributes only eligible transistor sales to the region, excluding complete solar inverters, cables, control software and construction. This accounting boundary keeps regional allocations consistent with the factory-gate product definition.
In the full report: Country-specific silicon SJ transistor revenue, qualified manufacturer sales and end-user applications across Middle East & Africa, with separate treatment of 500–700 V, 700–900 V and other silicon SJ voltage classes. It examines Gulf Cooperation Council in detail alongside South Africa and Türkiye and North Africa, excluding upstream wafers and finished converter systems.

Key SJ MOSFET Manufacturers and Competitive Landscape

Competition in silicon superjunction MOSFETs is shaped by device resistance, switching charge, diode recovery, manufacturing yield and package availability. Infineon, ST, Vishay, Toshiba, AOS, Magnachip and ROHM publish directly relevant high-voltage SJ portfolios, while Fuji Electric, Wayon, IceMOS and Oriental Semiconductor provide additional evidence of supplier participation. A manufacturer listing alone is not a measured market-share ranking.

Infineon offers CoolMOS 8 at 600 V and 650 V with integrated fast body diodes and a range of surface-mount packages. ST differentiates through deep-trench STMESH processing and 12-inch fabrication. Vishay emphasizes figures of merit for computing and telecom supplies, while Toshiba focuses on compact DTMOSVI packages and switching-loss reduction. These examples illustrate different engineering strategies rather than a uniform performance hierarchy across all converter topologies.

AOS introduced alphaMOS E2 in January 2026 and top-side cooled options in September, targeting high-density power conversion. Magnachip expanded its Gen6 lineup for server, charging and consumer applications, including 15 E6 products for adapters and TVs. ROHM publishes high-speed R60 series products, and Fuji Electric identifies a Super J MOS line. Actual vendor revenue shares cannot be inferred from announcement counts or catalog sizes.

China-based Wayon and Oriental Semiconductor broaden the supply field, and IceMOS describes deep-trench SJ capability. Their presence may strengthen regional sourcing options, but current merchant shipments and comparable device-level revenue are not fully disclosed in the inspected sources. Company-level power-semiconductor sales may include conventional MOSFETs, SiC, GaN, IGBTs and integrated power products, so such totals cannot be substituted for silicon SJ MOSFET revenue.

Tier structure

Tier Companies Basis of competition
Large diversified suppliers Infineon; STMicroelectronics; Vishay; Toshiba; onsemi Broad power semiconductor portfolios and qualification infrastructure, with multiple silicon and non-silicon device technologies.
Focused high-voltage participants AOS; Magnachip; ROHM; Fuji Electric Published 600–650 V superjunction product families and targeted application engineering for power supplies.
Specialized and regional suppliers Wayon; Oriental Semiconductor; IceMOS Specific SJ device or process portfolios, with varied levels of public shipment and commercial revenue disclosure.

Key companies profiled

  • Infineon Technologies
  • STMicroelectronics
  • Vishay Intertechnology
  • Toshiba Electronic Devices & Storage
  • Alpha and Omega Semiconductor
  • Magnachip Semiconductor
  • ROHM Semiconductor
  • Fuji Electric
  • Wayon Electronics
  • Oriental Semiconductor
  • IceMOS Technology
  • onsemi

Manufacturing, Packaging and Product Development

Silicon superjunction MOSFET economics combine charge-balanced cell structures with mature high-voltage processing, package thermal design and repeated qualification. Process refinements target resistance per die area, output charge, diode recovery and reliability rather than a single benchmark. The 2026–2036 market model values completed transistors at the factory gate and therefore does not add upstream wafer shipments or the sales of downstream converters.

ST reports a deep-trench STMESH architecture fabricated on 12-inch wafers, while AOS has discussed 300 mm production for earlier alphaMOS generations. These wafer dimensions indicate manufacturing technology, not market segmentation by end-device size. The finished transistor can be packaged in TO-247, TO-220, TOLL, DFN or top-side cooled formats, and the value of a device sold once should not be counted again when integrated into a power module or appliance.

Electrical figures of merit vary with circuit operation. Vishay reports a 650 V E Series part aimed at lower on-resistance and gate charge, Toshiba describes DTMOSVI switching and thermal improvements, and Infineon emphasizes the integrated fast diode in CoolMOS 8. These specifications require interpretation within hard-switching PFC, LLC resonant or other converter conditions; comparing resistance alone can conceal reverse-recovery, gate-drive and thermal losses.

Magnachip launched 25 Gen6 devices in March 2025 and later added 600 V server and charger parts in June 2026, followed by 500–600 V E6 products in October. AOS introduced a 600 V platform and later top-side cooled devices in the same year. The cadence supports active innovation in mature silicon, but catalog launches cannot independently verify annual market revenue, manufacturer market share or the 2036 scenario endpoint.

Market Dynamics: Drivers, Restraints and Opportunities

Demand for silicon SJ MOSFETs is driven by the need to improve high-voltage converter efficiency while preserving a mature silicon cost structure. Server power supplies, industrial electrification, renewable conversion and adapter redesigns create qualified sockets. Competition from GaN and SiC, ongoing price reductions and long equipment-qualification cycles constrain growth, particularly where a new architecture requires different gate driving or protection.

MARKET DRIVERS

Drivers Impact Analysis

Market Drivers Impact Rank CAGR Contribution (%) 2026–2029 2030–2033 2034–2036
Server and AI power supply efficiency High +6.10% High High Medium
Industrial electrification and charging High +4.30% High High High
Solar and energy storage conversion Medium-High +3.50% Medium High High
Consumer power adapter redesigns Medium +2.80% High Medium Low
Others (packaging and qualified replacement) Low-Medium +2.10% Medium Medium Medium

Server and AI power supply efficiency

Server and telecom power supplies must deliver high efficiency at rising power density while maintaining acceptable heat and reliability. Infineon reported a 600 V CoolMOS 8 design-in with LITEON in April 2025, and AOS introduced 600 V alphaMOS E2 for server and industrial conversion in January 2026. The modeled ~6.1 percentage-point growth contribution represents the relative importance of qualified server sockets, not a measured causal coefficient.

Industrial electrification and charging

Industrial UPS, charging equipment and automation power stages use high-voltage silicon switches where low conduction loss, robust body-diode recovery and predictable qualification can outweigh the higher-frequency benefits of wide-bandgap devices. Toshiba and Vishay product releases document continued development in this area. The modeled ~4.3 percentage-point contribution is a scenario allocation across the 2026–2036 horizon rather than a direct calculation from national electrification investment.

Solar and storage power electronics

Power-factor correction and DC/DC stages in renewable-energy systems create a recurring need for qualified 600–900 V devices. AOS describes alphaMOS E2 applications in solar inverters, while ROHM and Infineon list high-voltage SJ devices for efficient power conversion. The modeled ~3.5 percentage-point contribution reflects potential transistor content in eligible converter stages, excluding the value of complete solar installations and battery systems.

Consumer adapter and appliance redesigns

Notebook adapters, televisions and household appliance power supplies remain important high-volume markets for silicon switching. Magnachip introduced 15 sixth-generation E6 devices for consumer and computing power in October 2026, citing balanced thermal and switching performance. The modeled ~2.8 percentage-point contribution assumes continuing device refreshes, although GaN integration and falling component prices can limit the revenue gained from higher unit volumes.

Other packaging and qualified replacement

Compact TOLL, DFN and top-side cooled packages can extend the life of silicon SJ designs by reducing board area and thermal resistance without requiring an entirely different semiconductor material. Toshiba and AOS announcements provide examples. The modeled ~2.1 percentage-point contribution covers replacement cycles and specialized applications, but does not imply that all package innovations lead to incremental end-equipment production.

MARKET RESTRAINTS

Restraints Impact Analysis

Market Restraints Impact Rank CAGR Contribution (%) 2026–2029 2030–2033 2034–2036
SiC and GaN substitution in premium sockets High -2.70% Medium High High
Price erosion and product commoditization Medium-High -1.90% High High Medium
Others (qualification and supply disruption) Medium -1.70% Medium Medium Medium

Wide-bandgap competition

Gallium nitride can provide higher switching frequency in compact power supplies, while silicon carbide can offer high-voltage and high-temperature performance in demanding industrial systems. Silicon SJ remains competitive on price and established qualification, but substitution can remove high-value sockets from its addressable market. The modeled ~2.7 percentage-point restraint describes relative competitive pressure, not an audited loss of silicon SJ revenue to any named competitor.

Price erosion and commoditization

Multiple suppliers offer 600 V and 650 V silicon superjunction transistors with overlapping application targets, creating pricing pressure in adapters, consumer electronics and standardized industrial supplies. Improvements in wafer yield and die area can lower manufacturing cost while also compressing average selling prices. The modeled ~1.9 percentage-point restraint reflects that revenue growth may trail transistor unit growth even when efficiency requirements strengthen.

Other qualification and supply risks

Power designers must validate switching transients, avalanche behavior, EMI, thermal cycling and package lifetime before approving a replacement device. These processes delay conversion of new product launches into commercial sales. The modeled ~1.7 percentage-point restraint includes supply concentration and redesign costs, while distinguishing device-level reliability issues from broader shortages in complete power-system equipment.

MARKET OPPORTUNITIES

Thermal-aware packaging

Top-side cooling and compact surface-mount packaging offer a path to retain silicon SJ devices in higher-density server and industrial supplies. AOS introduced top-side cooled 600 V products in September 2026, and Toshiba markets compact DFN DTMOSVI variants. Equipment designers can reduce heat-spreader constraints while preserving familiar gate-drive behavior, creating an opportunity for package differentiation even when die-level switching performance changes only incrementally.

Flexible voltage portfolios

A broad range of 500–900 V SJ ratings helps suppliers serve regional input standards and converter topologies without relying on one flagship part. Infineon, ST, ROHM and AOS publish multiple high-voltage families with different diode and switching characteristics. The opportunity is stronger qualification coverage across customers, although manufacturer catalogs should not be interpreted as independently measured segment shares or guaranteed production volumes.

Supply Chain, Distribution and Value Capture

The silicon superjunction supply chain runs from device engineering and wafer fabrication through packaging, electrical testing, distribution and equipment integration. Revenue in this market is recognized at the finished-device factory gate, even when later assembly, distribution or system integration occurs in another country. This prevents the same MOSFET from being counted as a wafer, a packaged device and part of a completed power converter.

Design and processCharge-balanced silicon cells, trench structures, voltage rating and diode behavior determine die characteristics and yield.
Wafer fabricationHigh-voltage silicon diffusion and etch processes produce qualified SJ die; 200 mm and 300 mm are manufacturing attributes.
Assembly and testingTO-247, TOLL, DFN and top-side cooled packages are screened for breakdown, resistance, switching and thermal reliability.
Channel and OEMDistributors and power-supply manufacturers qualify devices for PFC, LLC, UPS, charging and industrial systems.

Engineering and wafer economics. ST describes 12-inch fabrication for a deep-trench SJ family, while AOS has disclosed 300 mm production capability for high-voltage MOSFETs. Wafer scale can influence die cost and output but is not a separate revenue stream in the finished-device market. Manufacturing location also differs from end-customer location, so regional shares are assigned to modeled demand rather than the country of silicon processing.

Packaging and distribution. Infineon, Toshiba, Vishay and AOS publish multiple packages and application-specific switching features. OEMs often purchase through authorized distribution channels and qualify devices for several product generations, which creates stable sockets but can delay adoption of new parts. The modeled ~49% industrial application share concerns finished SJ transistors purchased for equipment, not the total sales of distributors or complete power supplies.

Recent Developments in the SJ MOSFETs Market

  • 5 October 2026 Product launch
    Magnachip announced 15 Gen6 E6 superjunction MOSFETs at 500 V and 600 V for televisions, notebook adapters and PC power supplies. The products were described as in mass production, adding qualified silicon choices for compact consumer conversion. Their commercial significance is a wider high-volume catalog rather than an independently disclosed global revenue contribution. Source
  • 8 September 2026 Product launch
    AOS released two top-side cooled 600 V alphaMOS E2 SJ MOSFETs for high-density power systems, solar conversion and servers. The devices combine silicon superjunction switching with a package designed to improve thermal paths. The event highlights how package innovation can preserve silicon competitiveness against higher-frequency alternatives without changing the finished-device market boundary. Source
  • 22 June 2026 Product launch
    Magnachip introduced two Gen6 600 V SJ MOSFETs for AI-server supplies, EV charging and industrial applications, with low resistance and fast body-diode recovery. This is direct evidence of continued silicon product investment in power-density applications. The announcement does not report audited worldwide sales or the share of a particular end-user segment. Source
  • 27 January 2026 Platform launch
    AOS unveiled the alphaMOS E2 600 V superjunction platform and its first high-voltage device for server, telecom, solar and industrial conversion. The company described production availability and a defined component price for volume orders. The development supports a merchant-device market, but a single price quotation cannot establish the global average selling price. Source
  • 27 November 2025 Product launch
    Toshiba introduced the 600 V DTMOSVI TK057V60Z in a compact DFN8x8 package with 47 milliohm typical on-resistance. The device targets servers, UPS and photovoltaic power conditioning, demonstrating continued high-voltage silicon engineering. Package and resistance improvements may affect OEM qualification but do not directly disclose country-level market revenue. Source
  • 30 April 2025 Design-in
    Infineon reported that LITEON selected 600 V CoolMOS 8 for server power supplies and described reductions in gate charge and improved thermal behavior. The announcement demonstrates a concrete OEM application of a silicon SJ transistor. Its significance is design adoption, not proof of the publisher’s separate manufacturer-share assertions. Source
  • 26 March 2025 Product launch
    Vishay introduced a 650 V Gen 4.5 E Series power MOSFET with low on-resistance and gate-charge figures of merit for computing, telecom and industrial conversion. The product broadens device selection for PFC and DC/DC stages. Published electrical specifications substantiate technical capability but cannot be converted into verified market-share percentages. Source
  • 18 February 2025 Technology release
    ST described its 600 V STWA60N028T deep-trench superjunction device fabricated on 12-inch wafers, highlighting lower process complexity and 28 milliohm resistance. The event points to manufacturing economics and die-performance differentiation in mature silicon technology. The wafer size is not a market-share measure and should not be confused with finished device dimensions. Source

REPORT SCOPE & SEGMENTATION

Attribute Details
Study Period 2024–2036
Base Year 2026
Estimated Year 2027
Forecast Period 2027–2036
Historical Reference 2024
Market Size 2026 USD 3,932.87 million
Market Size 2027 USD 4,426.23 million
Market Size 2036 USD 12,821.90 million
Growth Rate 12.5% CAGR, 2027–2036
Unit Value in USD million; finished silicon SJ MOSFET factory-gate revenue
Segmentation By Type, Application, End User, Technology and Region
By Type 500–700 V · 700–900 V · Others
By Application Consumer Electronics · Industrial · Other
By End User Automotive · Telecommunications · Energy & Power · Others
By Technology Conduction Loss Optimized · Fast-Switching · Others
By Region Five regions represent disjoint end-customer demand, not production origin; shares are modeled 2026 allocations.
North AmericaUnited States, Canada, Mexico
EuropeGermany, France, Italy, United Kingdom, Nordics, Rest of Europe
Asia-PacificChina, Japan, South Korea, Taiwan, India, Southeast Asia, Rest of Asia-Pacific
South AmericaBrazil, Argentina, Chile, Colombia, Rest of South America
Middle East & AfricaGCC, Türkiye, South Africa, North Africa, Rest of Middle East & Africa
Key Companies Profiled Infineon Technologies, STMicroelectronics, Vishay Intertechnology, Toshiba Electronic Devices & Storage, Alpha and Omega Semiconductor, Magnachip Semiconductor, ROHM Semiconductor, Fuji Electric, Wayon Electronics, Oriental Semiconductor, IceMOS Technology, onsemi
Customization Scope Country-level silicon SJ device revenue and qualified manufacturer mix, with scenario sensitivity for voltage, package and application; excludes SiC/GaN devices, wafers, drivers and finished converters.

Frequently Asked Questions

What is the size of the SJ MOSFETs market?

The global finished silicon superjunction MOSFET market is modeled at USD 3,932.87 million in 2026 and is projected to reach USD 12,821.90 million by 2036, a reconciled 12.5% CAGR over 2027–2036. The forecast is a mathematical extension of earlier monetary endpoints and includes only qualified silicon SJ devices, not conventional MOSFETs, silicon carbide, gallium nitride or finished power systems.

What does superjunction mean in a silicon MOSFET?

Superjunction describes a charge-balanced vertical silicon structure that improves the trade-off between breakdown voltage and on-resistance. It is particularly useful in 500–900 V switching devices for offline power supplies, industrial conversion and power-factor correction. The architecture is distinct from silicon carbide MOSFETs and gallium nitride HEMTs, even when all three compete in a converter design.

Which voltage class is largest?

The 500–700 V segment is estimated at ~70% of 2026 silicon SJ MOSFET revenue, reflecting the prevalence of 600 V and 650 V devices in server supplies, adapters, UPS and industrial power conversion. Supplier examples include CoolMOS 8, STMESH, DTMOSVI and alphaMOS. This percentage is a modeled allocation, not an audited shipment split reported by those manufacturers.

Which application has the greatest share?

Industrial applications are estimated at ~49% of 2026 revenue because industrial power supplies, charging equipment, UPS and renewable conversion use qualified high-voltage silicon switching. Consumer electronics contribute an estimated ~33% through adapters, TVs and appliances, while other applications form the balance. These categories represent end-use allocation of transistor revenue, not the sales value of complete equipment.

Which region leads the market?

Asia-Pacific is the largest modeled regional market at ~48% of 2026 finished silicon SJ MOSFET revenue, supported by power-electronics manufacturing and demand across China, Japan, South Korea and Taiwan. Europe and North America also have significant product-engineering and end-equipment demand. Regional percentages are scenario estimates and should not be confused with semiconductor wafer-production shares or company headquarters.

Which manufacturers supply superjunction MOSFETs?

Relevant product portfolios are published by Infineon, STMicroelectronics, Vishay, Toshiba, AOS, Magnachip, ROHM and Fuji Electric, with additional offerings or technical capabilities from Wayon, Oriental Semiconductor and IceMOS. onsemi also has a historical SuperFET family. Product documentation supports technical participation but does not independently establish each supplier’s share of global silicon SJ device revenue.

What drives growth through 2036?

High-efficiency server supplies, industrial electrification, renewable-energy conversion and compact consumer power adapters support demand for silicon superjunction MOSFETs. New product releases from Infineon, AOS, Magnachip, Vishay and Toshiba show ongoing engineering activity. Growth depends on successful OEM qualification and stable device pricing; a product announcement is not automatically equivalent to incremental market sales.

What limits market expansion?

The main constraints are competition from GaN and SiC in premium sockets, annual price erosion among overlapping 600–650 V silicon products, and lengthy electrical and thermal qualification. A device with low on-resistance can still underperform if diode recovery, switching charge or package thermal behavior is unsuitable. The model therefore separates technical opportunity from actual commercial adoption.

Why does the reconciled growth differ from some published claims?

A 2024 market anchor of USD 3.105 billion and a 2032 forecast of USD 7.992 billion imply roughly 12.54% annual compounding over eight years, rather than a separately stated 16.5%. The 2026–2036 scenario uses the endpoint-consistent rate and extends four years beyond the original forecast horizon. The extrapolation is not independently validated manufacturer guidance.

What is included in the study boundary?

The study counts finished silicon superjunction MOSFET transistors sold at the factory gate, with separately attributable SJ transistor value in eligible modules. It excludes ordinary planar or trench non-SJ devices, SiC MOSFETs, GaN HEMTs, wafers, drivers, complete converters and end equipment. It analyzes five world regions plus Type, Application, End User and Technology dimensions using modeled shares.

Research Sources & Evidence Base
View research sources used for this overview
  1. Infineon Technologies. CoolMOS 8 at LITEON, 30 April 2025; 600 V superjunction MOSFET design-in for server power, with switching and thermal claims.
  2. Infineon Technologies. 650 V CoolMOS 8 portfolio, High-voltage SJ topology, integrated fast diode and PFC/LLC power-supply applications.
  3. STMicroelectronics. STMESH trench T series, 600 V deep-trench superjunction MOSFET and manufacturing differentiation.
  4. STMicroelectronics. STWA60N028T technical introduction, 18 February 2025; 600 V, 28 milliohm device and 12-inch fabrication.
  5. Vishay Intertechnology. Gen 4.5 650 V E Series launch, 26 March 2025; 650 V superjunction MOSFET and low-resistance efficiency metrics.
  6. Toshiba Electronic Devices & Storage. DTMOSVI 600 V launch, 27 November 2025; DFN8x8 package and 47 milliohm SJ device.
  7. Magnachip Semiconductor. Gen6 25-device expansion, 12 March 2025; 25 new SJ MOSFETs, switching and die-area improvements.
  8. Magnachip Semiconductor. Gen6 600 V server and charging devices, 22 June 2026; new 600 V SJ MOSFETs for servers, chargers and industry.
  9. Magnachip Semiconductor. E6 consumer power MOSFET expansion, 5 October 2026; 15 500 V and 600 V devices, mass production for adapters and TV supplies.
  10. Alpha and Omega Semiconductor. AlphaMOS E2 platform, 27 January 2026; production 600 V SJ MOSFET for solar, server and industrial power.
  11. Alpha and Omega Semiconductor. Top-side cooled SJ devices, 8 September 2026; 600 V top-side cooled packages for power systems.
  12. Alpha and Omega Semiconductor. AlphaMOS5 FRD series, 3 January 2024; 600 V fast-recovery-diode SJ family.
  13. ROHM Semiconductor. R6030KNZ4 power MOSFET, Recommended 600 V high-speed SJ device, 30 A, 115 milliohm typical on-resistance.
  14. ROHM Semiconductor. Fourth-generation SJ product portfolio, 600 V product matrix showing on-resistance and body-diode trade-offs.
  15. Fuji Electric. Super J MOS series, Official catalog explicitly identifies 600 V superjunction power MOSFET products.
  16. Wayon Electronics. Superjunction MOSFET portfolio, Official manufacturer identifies superjunction MOSFETs among power semiconductor products.
  17. IceMOS Technology. Deep-trench superjunction capability, Official company identifies SJ MOSFETs and target power supply applications.
  18. Oriental Semiconductor. GreenMOS superjunction portfolio, Official Chinese manufacturer lists GreenMOS SJ products for power conversion.
SJ MOSFETs Market

Get Sample Report PDF for Exclusive Insights

Report Sample Includes

  • Table of Contents
  • List of Tables & Figures
  • Charts, Research Methodology, and more...

PDF Icon Download Sample Report PDF

Download Sample Report

Table of Content

1 Introduction to Research & Analysis Reports
1.1 SJ MOSFETs Market Definition
1.2 Market Segments
1.2.1 Segment by Type
1.2.2 Segment by Application
1.3 Global SJ MOSFETs Market Overview
1.4 Features & Benefits of This Report
1.5 Methodology & Sources of Information
1.5.1 Research Methodology
1.5.2 Research Process
1.5.3 Base Year
1.5.4 Report Assumptions & Caveats
2 Global SJ MOSFETs Overall Market Size
2.1 Global SJ MOSFETs Market Size: 2024 VS 2032
2.2 Global SJ MOSFETs Market Size, Prospects & Forecasts: 2026-2034
2.3 Global SJ MOSFETs Sales: 2026-2034
3 Company Landscape
3.1 Top SJ MOSFETs Players in Global Market
3.2 Top Global SJ MOSFETs Companies Ranked by Revenue
3.3 Global SJ MOSFETs Revenue by Companies
3.4 Global SJ MOSFETs Sales by Companies
3.5 Global SJ MOSFETs Price by Manufacturer (2020-2025)
3.6 Top 3 and Top 5 SJ MOSFETs Companies in Global Market, by Revenue in 2024
3.7 Global Manufacturers SJ MOSFETs Product Type
3.8 Tier 1, Tier 2, and Tier 3 SJ MOSFETs Players in Global Market
3.8.1 List of Global Tier 1 SJ MOSFETs Companies
3.8.2 List of Global Tier 2 and Tier 3 SJ MOSFETs Companies
4 Sights by Product
4.1 Overview
4.1.1 Segment by Type – Global SJ MOSFETs Market Size Markets, 2024 & 2032
4.1.2 500 – 700 V
4.1.3 700 – 900 V
4.1.4 Others
4.2 Segment by Type – Global SJ MOSFETs Revenue & Forecasts
4.2.1 Segment by Type – Global SJ MOSFETs Revenue, 2020-2025
4.2.2 Segment by Type – Global SJ MOSFETs Revenue, 2026-2032
4.2.3 Segment by Type – Global SJ MOSFETs Revenue Market Share, 2026-2034
4.3 Segment by Type – Global SJ MOSFETs Sales & Forecasts
4.3.1 Segment by Type – Global SJ MOSFETs Sales, 2020-2025
4.3.2 Segment by Type – Global SJ MOSFETs Sales, 2026-2032
4.3.3 Segment by Type – Global SJ MOSFETs Sales Market Share, 2026-2034
4.4 Segment by Type – Global SJ MOSFETs Price (Manufacturers Selling Prices), 2026-2034
5 Sights by Application
5.1 Overview
5.1.1 Segment by Application – Global SJ MOSFETs Market Size, 2024 & 2032
5.1.2 Consumer Electronics
5.1.3 Industrial
5.1.4 Other
5.2 Segment by Application – Global SJ MOSFETs Revenue & Forecasts
5.2.1 Segment by Application – Global SJ MOSFETs Revenue, 2020-2025
5.2.2 Segment by Application – Global SJ MOSFETs Revenue, 2026-2032
5.2.3 Segment by Application – Global SJ MOSFETs Revenue Market Share, 2026-2034
5.3 Segment by Application – Global SJ MOSFETs Sales & Forecasts
5.3.1 Segment by Application – Global SJ MOSFETs Sales, 2020-2025
5.3.2 Segment by Application – Global SJ MOSFETs Sales, 2026-2032
5.3.3 Segment by Application – Global SJ MOSFETs Sales Market Share, 2026-2034
5.4 Segment by Application – Global SJ MOSFETs Price (Manufacturers Selling Prices), 2026-2034
6 Sights by Region
6.1 By Region – Global SJ MOSFETs Market Size, 2024 & 2032
6.2 By Region – Global SJ MOSFETs Revenue & Forecasts
6.2.1 By Region – Global SJ MOSFETs Revenue, 2020-2025
6.2.2 By Region – Global SJ MOSFETs Revenue, 2026-2032
6.2.3 By Region – Global SJ MOSFETs Revenue Market Share, 2026-2034
6.3 By Region – Global SJ MOSFETs Sales & Forecasts
6.3.1 By Region – Global SJ MOSFETs Sales, 2020-2025
6.3.2 By Region – Global SJ MOSFETs Sales, 2026-2032
6.3.3 By Region – Global SJ MOSFETs Sales Market Share, 2026-2034
6.4 North America
6.4.1 By Country – North America SJ MOSFETs Revenue, 2026-2034
6.4.2 By Country – North America SJ MOSFETs Sales, 2026-2034
6.4.3 United States SJ MOSFETs Market Size, 2026-2034
6.4.4 Canada SJ MOSFETs Market Size, 2026-2034
6.4.5 Mexico SJ MOSFETs Market Size, 2026-2034
6.5 Europe
6.5.1 By Country – Europe SJ MOSFETs Revenue, 2026-2034
6.5.2 By Country – Europe SJ MOSFETs Sales, 2026-2034
6.5.3 Germany SJ MOSFETs Market Size, 2026-2034
6.5.4 France SJ MOSFETs Market Size, 2026-2034
6.5.5 U.K. SJ MOSFETs Market Size, 2026-2034
6.5.6 Italy SJ MOSFETs Market Size, 2026-2034
6.5.7 Russia SJ MOSFETs Market Size, 2026-2034
6.5.8 Nordic Countries SJ MOSFETs Market Size, 2026-2034
6.5.9 Benelux SJ MOSFETs Market Size, 2026-2034
6.6 Asia
6.6.1 By Region – Asia SJ MOSFETs Revenue, 2026-2034
6.6.2 By Region – Asia SJ MOSFETs Sales, 2026-2034
6.6.3 China SJ MOSFETs Market Size, 2026-2034
6.6.4 Japan SJ MOSFETs Market Size, 2026-2034
6.6.5 South Korea SJ MOSFETs Market Size, 2026-2034
6.6.6 Southeast Asia SJ MOSFETs Market Size, 2026-2034
6.6.7 India SJ MOSFETs Market Size, 2026-2034
6.7 South America
6.7.1 By Country – South America SJ MOSFETs Revenue, 2026-2034
6.7.2 By Country – South America SJ MOSFETs Sales, 2026-2034
6.7.3 Brazil SJ MOSFETs Market Size, 2026-2034
6.7.4 Argentina SJ MOSFETs Market Size, 2026-2034
6.8 Middle East & Africa
6.8.1 By Country – Middle East & Africa SJ MOSFETs Revenue, 2026-2034
6.8.2 By Country – Middle East & Africa SJ MOSFETs Sales, 2026-2034
6.8.3 Turkey SJ MOSFETs Market Size, 2026-2034
6.8.4 Israel SJ MOSFETs Market Size, 2026-2034
6.8.5 Saudi Arabia SJ MOSFETs Market Size, 2026-2034
6.8.6 UAE SJ MOSFETs Market Size, 2026-2034
7 Manufacturers & Brands Profiles
7.1 Infineon
7.1.1 Infineon Company Summary
7.1.2 Infineon Business Overview
7.1.3 Infineon SJ MOSFETs Major Product Offerings
7.1.4 Infineon SJ MOSFETs Sales and Revenue in Global (2020-2025)
7.1.5 Infineon Key News & Latest Developments
7.2 STMicroelectronics
7.2.1 STMicroelectronics Company Summary
7.2.2 STMicroelectronics Business Overview
7.2.3 STMicroelectronics SJ MOSFETs Major Product Offerings
7.2.4 STMicroelectronics SJ MOSFETs Sales and Revenue in Global (2020-2025)
7.2.5 STMicroelectronics Key News & Latest Developments
7.3 Vishay
7.3.1 Vishay Company Summary
7.3.2 Vishay Business Overview
7.3.3 Vishay SJ MOSFETs Major Product Offerings
7.3.4 Vishay SJ MOSFETs Sales and Revenue in Global (2020-2025)
7.3.5 Vishay Key News & Latest Developments
7.4 ON Semiconductor
7.4.1 ON Semiconductor Company Summary
7.4.2 ON Semiconductor Business Overview
7.4.3 ON Semiconductor SJ MOSFETs Major Product Offerings
7.4.4 ON Semiconductor SJ MOSFETs Sales and Revenue in Global (2020-2025)
7.4.5 ON Semiconductor Key News & Latest Developments
7.5 Toshiba
7.5.1 Toshiba Company Summary
7.5.2 Toshiba Business Overview
7.5.3 Toshiba SJ MOSFETs Major Product Offerings
7.5.4 Toshiba SJ MOSFETs Sales and Revenue in Global (2020-2025)
7.5.5 Toshiba Key News & Latest Developments
7.6 Alpha & Omega
7.6.1 Alpha & Omega Company Summary
7.6.2 Alpha & Omega Business Overview
7.6.3 Alpha & Omega SJ MOSFETs Major Product Offerings
7.6.4 Alpha & Omega SJ MOSFETs Sales and Revenue in Global (2020-2025)
7.6.5 Alpha & Omega Key News & Latest Developments
7.7 Fuji Electric
7.7.1 Fuji Electric Company Summary
7.7.2 Fuji Electric Business Overview
7.7.3 Fuji Electric SJ MOSFETs Major Product Offerings
7.7.4 Fuji Electric SJ MOSFETs Sales and Revenue in Global (2020-2025)
7.7.5 Fuji Electric Key News & Latest Developments
7.8 MagnaChip
7.8.1 MagnaChip Company Summary
7.8.2 MagnaChip Business Overview
7.8.3 MagnaChip SJ MOSFETs Major Product Offerings
7.8.4 MagnaChip SJ MOSFETs Sales and Revenue in Global (2020-2025)
7.8.5 MagnaChip Key News & Latest Developments
7.9 Silan
7.9.1 Silan Company Summary
7.9.2 Silan Business Overview
7.9.3 Silan SJ MOSFETs Major Product Offerings
7.9.4 Silan SJ MOSFETs Sales and Revenue in Global (2020-2025)
7.9.5 Silan Key News & Latest Developments
7.10 ROHM
7.10.1 ROHM Company Summary
7.10.2 ROHM Business Overview
7.10.3 ROHM SJ MOSFETs Major Product Offerings
7.10.4 ROHM SJ MOSFETs Sales and Revenue in Global (2020-2025)
7.10.5 ROHM Key News & Latest Developments
7.11 IceMOS Technology
7.11.1 IceMOS Technology Company Summary
7.11.2 IceMOS Technology Business Overview
7.11.3 IceMOS Technology SJ MOSFETs Major Product Offerings
7.11.4 IceMOS Technology SJ MOSFETs Sales and Revenue in Global (2020-2025)
7.11.5 IceMOS Technology Key News & Latest Developments
7.12 DACO
7.12.1 DACO Company Summary
7.12.2 DACO Business Overview
7.12.3 DACO SJ MOSFETs Major Product Offerings
7.12.4 DACO SJ MOSFETs Sales and Revenue in Global (2020-2025)
7.12.5 DACO Key News & Latest Developments
7.13 WUXI NCE POWER
7.13.1 WUXI NCE POWER Company Summary
7.13.2 WUXI NCE POWER Business Overview
7.13.3 WUXI NCE POWER SJ MOSFETs Major Product Offerings
7.13.4 WUXI NCE POWER SJ MOSFETs Sales and Revenue in Global (2020-2025)
7.13.5 WUXI NCE POWER Key News & Latest Developments
7.14 CYG Wayon
7.14.1 CYG Wayon Company Summary
7.14.2 CYG Wayon Business Overview
7.14.3 CYG Wayon SJ MOSFETs Major Product Offerings
7.14.4 CYG Wayon SJ MOSFETs Sales and Revenue in Global (2020-2025)
7.14.5 CYG Wayon Key News & Latest Developments
7.15 Semipower
7.15.1 Semipower Company Summary
7.15.2 Semipower Business Overview
7.15.3 Semipower SJ MOSFETs Major Product Offerings
7.15.4 Semipower SJ MOSFETs Sales and Revenue in Global (2020-2025)
7.15.5 Semipower Key News & Latest Developments
7.16 Shanghai Belling
7.16.1 Shanghai Belling Company Summary
7.16.2 Shanghai Belling Business Overview
7.16.3 Shanghai Belling SJ MOSFETs Major Product Offerings
7.16.4 Shanghai Belling SJ MOSFETs Sales and Revenue in Global (2020-2025)
7.16.5 Shanghai Belling Key News & Latest Developments
7.17 SALLTECH GROUP
7.17.1 SALLTECH GROUP Company Summary
7.17.2 SALLTECH GROUP Business Overview
7.17.3 SALLTECH GROUP SJ MOSFETs Major Product Offerings
7.17.4 SALLTECH GROUP SJ MOSFETs Sales and Revenue in Global (2020-2025)
7.17.5 SALLTECH GROUP Key News & Latest Developments
7.18 YSW
7.18.1 YSW Company Summary
7.18.2 YSW Business Overview
7.18.3 YSW SJ MOSFETs Major Product Offerings
7.18.4 YSW SJ MOSFETs Sales and Revenue in Global (2020-2025)
7.18.5 YSW Key News & Latest Developments
8 Global SJ MOSFETs Production Capacity, Analysis
8.1 Global SJ MOSFETs Production Capacity, 2026-2034
8.2 SJ MOSFETs Production Capacity of Key Manufacturers in Global Market
8.3 Global SJ MOSFETs Production by Region
9 Key Market Trends, Opportunity, Drivers and Restraints
9.1 Market Opportunities & Trends
9.2 Market Drivers
9.3 Market Restraints
10 SJ MOSFETs Supply Chain Analysis
10.1 SJ MOSFETs Industry Value Chain
10.2 SJ MOSFETs Upstream Market
10.3 SJ MOSFETs Downstream and Clients
10.4 Marketing Channels Analysis
10.4.1 Marketing Channels
10.4.2 SJ MOSFETs Distributors and Sales Agents in Global
11 Conclusion
12 Appendix
12.1 Note
12.2 Examples of Clients
12.3 DisclaimerList of Tables
Table 1. Key Players of SJ MOSFETs in Global Market
Table 2. Top SJ MOSFETs Players in Global Market, Ranking by Revenue (2024)
Table 3. Global SJ MOSFETs Revenue by Companies, (US$, Mn), 2020-2025
Table 4. Global SJ MOSFETs Revenue Share by Companies, 2020-2025
Table 5. Global SJ MOSFETs Sales by Companies, (Million Units), 2020-2025
Table 6. Global SJ MOSFETs Sales Share by Companies, 2020-2025
Table 7. Key Manufacturers SJ MOSFETs Price (2020-2025) & (US$/Unit)
Table 8. Global Manufacturers SJ MOSFETs Product Type
Table 9. List of Global Tier 1 SJ MOSFETs Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 10. List of Global Tier 2 and Tier 3 SJ MOSFETs Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 11. Segment by Type – Global SJ MOSFETs Revenue, (US$, Mn), 2024 & 2032
Table 12. Segment by Type – Global SJ MOSFETs Revenue (US$, Mn), 2020-2025
Table 13. Segment by Type – Global SJ MOSFETs Revenue (US$, Mn), 2026-2032
Table 14. Segment by Type – Global SJ MOSFETs Sales (Million Units), 2020-2025
Table 15. Segment by Type – Global SJ MOSFETs Sales (Million Units), 2026-2032
Table 16. Segment by Application – Global SJ MOSFETs Revenue, (US$, Mn), 2024 & 2032
Table 17. Segment by Application – Global SJ MOSFETs Revenue, (US$, Mn), 2020-2025
Table 18. Segment by Application – Global SJ MOSFETs Revenue, (US$, Mn), 2026-2032
Table 19. Segment by Application – Global SJ MOSFETs Sales, (Million Units), 2020-2025
Table 20. Segment by Application – Global SJ MOSFETs Sales, (Million Units), 2026-2032
Table 21. By Region – Global SJ MOSFETs Revenue, (US$, Mn), 2025-2032
Table 22. By Region – Global SJ MOSFETs Revenue, (US$, Mn), 2020-2025
Table 23. By Region – Global SJ MOSFETs Revenue, (US$, Mn), 2026-2032
Table 24. By Region – Global SJ MOSFETs Sales, (Million Units), 2020-2025
Table 25. By Region – Global SJ MOSFETs Sales, (Million Units), 2026-2032
Table 26. By Country – North America SJ MOSFETs Revenue, (US$, Mn), 2020-2025
Table 27. By Country – North America SJ MOSFETs Revenue, (US$, Mn), 2026-2032
Table 28. By Country – North America SJ MOSFETs Sales, (Million Units), 2020-2025
Table 29. By Country – North America SJ MOSFETs Sales, (Million Units), 2026-2032
Table 30. By Country – Europe SJ MOSFETs Revenue, (US$, Mn), 2020-2025
Table 31. By Country – Europe SJ MOSFETs Revenue, (US$, Mn), 2026-2032
Table 32. By Country – Europe SJ MOSFETs Sales, (Million Units), 2020-2025
Table 33. By Country – Europe SJ MOSFETs Sales, (Million Units), 2026-2032
Table 34. By Region – Asia SJ MOSFETs Revenue, (US$, Mn), 2020-2025
Table 35. By Region – Asia SJ MOSFETs Revenue, (US$, Mn), 2026-2032
Table 36. By Region – Asia SJ MOSFETs Sales, (Million Units), 2020-2025
Table 37. By Region – Asia SJ MOSFETs Sales, (Million Units), 2026-2032
Table 38. By Country – South America SJ MOSFETs Revenue, (US$, Mn), 2020-2025
Table 39. By Country – South America SJ MOSFETs Revenue, (US$, Mn), 2026-2032
Table 40. By Country – South America SJ MOSFETs Sales, (Million Units), 2020-2025
Table 41. By Country – South America SJ MOSFETs Sales, (Million Units), 2026-2032
Table 42. By Country – Middle East & Africa SJ MOSFETs Revenue, (US$, Mn), 2020-2025
Table 43. By Country – Middle East & Africa SJ MOSFETs Revenue, (US$, Mn), 2026-2032
Table 44. By Country – Middle East & Africa SJ MOSFETs Sales, (Million Units), 2020-2025
Table 45. By Country – Middle East & Africa SJ MOSFETs Sales, (Million Units), 2026-2032
Table 46. Infineon Company Summary
Table 47. Infineon SJ MOSFETs Product Offerings
Table 48. Infineon SJ MOSFETs Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 49. Infineon Key News & Latest Developments
Table 50. STMicroelectronics Company Summary
Table 51. STMicroelectronics SJ MOSFETs Product Offerings
Table 52. STMicroelectronics SJ MOSFETs Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 53. STMicroelectronics Key News & Latest Developments
Table 54. Vishay Company Summary
Table 55. Vishay SJ MOSFETs Product Offerings
Table 56. Vishay SJ MOSFETs Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 57. Vishay Key News & Latest Developments
Table 58. ON Semiconductor Company Summary
Table 59. ON Semiconductor SJ MOSFETs Product Offerings
Table 60. ON Semiconductor SJ MOSFETs Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 61. ON Semiconductor Key News & Latest Developments
Table 62. Toshiba Company Summary
Table 63. Toshiba SJ MOSFETs Product Offerings
Table 64. Toshiba SJ MOSFETs Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 65. Toshiba Key News & Latest Developments
Table 66. Alpha & Omega Company Summary
Table 67. Alpha & Omega SJ MOSFETs Product Offerings
Table 68. Alpha & Omega SJ MOSFETs Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 69. Alpha & Omega Key News & Latest Developments
Table 70. Fuji Electric Company Summary
Table 71. Fuji Electric SJ MOSFETs Product Offerings
Table 72. Fuji Electric SJ MOSFETs Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 73. Fuji Electric Key News & Latest Developments
Table 74. MagnaChip Company Summary
Table 75. MagnaChip SJ MOSFETs Product Offerings
Table 76. MagnaChip SJ MOSFETs Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 77. MagnaChip Key News & Latest Developments
Table 78. Silan Company Summary
Table 79. Silan SJ MOSFETs Product Offerings
Table 80. Silan SJ MOSFETs Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 81. Silan Key News & Latest Developments
Table 82. ROHM Company Summary
Table 83. ROHM SJ MOSFETs Product Offerings
Table 84. ROHM SJ MOSFETs Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 85. ROHM Key News & Latest Developments
Table 86. IceMOS Technology Company Summary
Table 87. IceMOS Technology SJ MOSFETs Product Offerings
Table 88. IceMOS Technology SJ MOSFETs Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 89. IceMOS Technology Key News & Latest Developments
Table 90. DACO Company Summary
Table 91. DACO SJ MOSFETs Product Offerings
Table 92. DACO SJ MOSFETs Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 93. DACO Key News & Latest Developments
Table 94. WUXI NCE POWER Company Summary
Table 95. WUXI NCE POWER SJ MOSFETs Product Offerings
Table 96. WUXI NCE POWER SJ MOSFETs Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 97. WUXI NCE POWER Key News & Latest Developments
Table 98. CYG Wayon Company Summary
Table 99. CYG Wayon SJ MOSFETs Product Offerings
Table 100. CYG Wayon SJ MOSFETs Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 101. CYG Wayon Key News & Latest Developments
Table 102. Semipower Company Summary
Table 103. Semipower SJ MOSFETs Product Offerings
Table 104. Semipower SJ MOSFETs Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 105. Semipower Key News & Latest Developments
Table 106. Shanghai Belling Company Summary
Table 107. Shanghai Belling SJ MOSFETs Product Offerings
Table 108. Shanghai Belling SJ MOSFETs Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 109. Shanghai Belling Key News & Latest Developments
Table 110. SALLTECH GROUP Company Summary
Table 111. SALLTECH GROUP SJ MOSFETs Product Offerings
Table 112. SALLTECH GROUP SJ MOSFETs Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 113. SALLTECH GROUP Key News & Latest Developments
Table 114. YSW Company Summary
Table 115. YSW SJ MOSFETs Product Offerings
Table 116. YSW SJ MOSFETs Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 117. YSW Key News & Latest Developments
Table 118. SJ MOSFETs Capacity of Key Manufacturers in Global Market, 2023-2025 (Million Units)
Table 119. Global SJ MOSFETs Capacity Market Share of Key Manufacturers, 2023-2025
Table 120. Global SJ MOSFETs Production by Region, 2020-2025 (Million Units)
Table 121. Global SJ MOSFETs Production by Region, 2026-2032 (Million Units)
Table 122. SJ MOSFETs Market Opportunities & Trends in Global Market
Table 123. SJ MOSFETs Market Drivers in Global Market
Table 124. SJ MOSFETs Market Restraints in Global Market
Table 125. SJ MOSFETs Raw Materials
Table 126. SJ MOSFETs Raw Materials Suppliers in Global Market
Table 127. Typical SJ MOSFETs Downstream
Table 128. SJ MOSFETs Downstream Clients in Global Market
Table 129. SJ MOSFETs Distributors and Sales Agents in Global Market

List of Figures
Figure 1. SJ MOSFETs Product Picture
Figure 2. SJ MOSFETs Segment by Type in 2024
Figure 3. SJ MOSFETs Segment by Application in 2024
Figure 4. Global SJ MOSFETs Market Overview: 2024
Figure 5. Key Caveats
Figure 6. Global SJ MOSFETs Market Size: 2024 VS 2032 (US$, Mn)
Figure 7. Global SJ MOSFETs Revenue: 2026-2034 (US$, Mn)
Figure 8. SJ MOSFETs Sales in Global Market: 2026-2034 (Million Units)
Figure 9. The Top 3 and 5 Players Market Share by SJ MOSFETs Revenue in 2024
Figure 10. Segment by Type – Global SJ MOSFETs Revenue, (US$, Mn), 2024 & 2032
Figure 11. Segment by Type – Global SJ MOSFETs Revenue Market Share, 2026-2034
Figure 12. Segment by Type – Global SJ MOSFETs Sales Market Share, 2026-2034
Figure 13. Segment by Type – Global SJ MOSFETs Price (US$/Unit), 2026-2034
Figure 14. Segment by Application – Global SJ MOSFETs Revenue, (US$, Mn), 2024 & 2032
Figure 15. Segment by Application – Global SJ MOSFETs Revenue Market Share, 2026-2034
Figure 16. Segment by Application – Global SJ MOSFETs Sales Market Share, 2026-2034
Figure 17. Segment by Application -Global SJ MOSFETs Price (US$/Unit), 2026-2034
Figure 18. By Region – Global SJ MOSFETs Revenue, (US$, Mn), 2025 & 2032
Figure 19. By Region – Global SJ MOSFETs Revenue Market Share, 2020 VS 2024 VS 2032
Figure 20. By Region – Global SJ MOSFETs Revenue Market Share, 2026-2034
Figure 21. By Region – Global SJ MOSFETs Sales Market Share, 2026-2034
Figure 22. By Country – North America SJ MOSFETs Revenue Market Share, 2026-2034
Figure 23. By Country – North America SJ MOSFETs Sales Market Share, 2026-2034
Figure 24. United States SJ MOSFETs Revenue, (US$, Mn), 2026-2034
Figure 25. Canada SJ MOSFETs Revenue, (US$, Mn), 2026-2034
Figure 26. Mexico SJ MOSFETs Revenue, (US$, Mn), 2026-2034
Figure 27. By Country – Europe SJ MOSFETs Revenue Market Share, 2026-2034
Figure 28. By Country – Europe SJ MOSFETs Sales Market Share, 2026-2034
Figure 29. Germany SJ MOSFETs Revenue, (US$, Mn), 2026-2034
Figure 30. France SJ MOSFETs Revenue, (US$, Mn), 2026-2034
Figure 31. U.K. SJ MOSFETs Revenue, (US$, Mn), 2026-2034
Figure 32. Italy SJ MOSFETs Revenue, (US$, Mn), 2026-2034
Figure 33. Russia SJ MOSFETs Revenue, (US$, Mn), 2026-2034
Figure 34. Nordic Countries SJ MOSFETs Revenue, (US$, Mn), 2026-2034
Figure 35. Benelux SJ MOSFETs Revenue, (US$, Mn), 2026-2034
Figure 36. By Region – Asia SJ MOSFETs Revenue Market Share, 2026-2034
Figure 37. By Region – Asia SJ MOSFETs Sales Market Share, 2026-2034
Figure 38. China SJ MOSFETs Revenue, (US$, Mn), 2026-2034
Figure 39. Japan SJ MOSFETs Revenue, (US$, Mn), 2026-2034
Figure 40. South Korea SJ MOSFETs Revenue, (US$, Mn), 2026-2034
Figure 41. Southeast Asia SJ MOSFETs Revenue, (US$, Mn), 2026-2034
Figure 42. India SJ MOSFETs Revenue, (US$, Mn), 2026-2034
Figure 43. By Country – South America SJ MOSFETs Revenue Market Share, 2026-2034
Figure 44. By Country – South America SJ MOSFETs Sales, Market Share, 2026-2034
Figure 45. Brazil SJ MOSFETs Revenue, (US$, Mn), 2026-2034
Figure 46. Argentina SJ MOSFETs Revenue, (US$, Mn), 2026-2034
Figure 47. By Country – Middle East & Africa SJ MOSFETs Revenue, Market Share, 2026-2034
Figure 48. By Country – Middle East & Africa SJ MOSFETs Sales, Market Share, 2026-2034
Figure 49. Turkey SJ MOSFETs Revenue, (US$, Mn), 2026-2034
Figure 50. Israel SJ MOSFETs Revenue, (US$, Mn), 2026-2034
Figure 51. Saudi Arabia SJ MOSFETs Revenue, (US$, Mn), 2026-2034
Figure 52. UAE SJ MOSFETs Revenue, (US$, Mn), 2026-2034
Figure 53. Global SJ MOSFETs Production Capacity (Million Units), 2026-2034
Figure 54. The Percentage of Production SJ MOSFETs by Region, 2024 VS 2032
Figure 55. SJ MOSFETs Industry Value Chain
Figure 56. Marketing Channels