Key Statistics
Key Takeaways
- Aluminum nitride heaters – Aluminum nitride remains the leading material platform because high thermal conductivity, electrical insulation and compatibility with embedded resistive circuits support fast response and tight wafer-temperature uniformity. The product earns its value through process yield and repeatability, so buyers evaluate thermal maps, plasma resistance and service life rather than comparing ceramic mass alone.
- Foundry demand – Foundries constitute the largest application because a shared manufacturing platform must run many customer processes while maintaining repeatable film thickness and chamber matching. Each qualified heater design becomes embedded in process recipes and maintenance plans, which raises switching costs and rewards suppliers able to reproduce material, metallization and joining performance across replacement cycles.
- Asia Pacific leadership – Asia Pacific leads both production and consumption through Japan’s advanced-ceramics base, South Korea’s specialist suppliers, and the concentration of wafer fabrication across Taiwan, Korea, Japan and China. Proximity reduces qualification travel and repair turnaround, while dense regional tool and materials ecosystems accelerate design changes for new nodes and larger process windows.
- Demand catalyst – SEMI reported worldwide semiconductor manufacturing-equipment sales of USD 135.1 billion in 2025, 15% above 2024. Ceramic heaters are a chamber subassembly rather than a complete tool, yet more deposition and etch capacity expands the installed base that requires new heaters, qualified spares, refurbishment and process-matched replacement units. For the semiconductor ceramic heater market, the commercial consequence of semi reported worldwide semiconductor manufacturing-equipment sales of usd is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work.
- Primary restraint – Long qualification cycles and high customer-concentration risk temper growth. A heater must survive thermal cycling, aggressive fluorine chemistry and plasma exposure without warpage, contamination or electrical drift; consequently, a technically capable entrant still faces extended sampling, chamber testing and process-of-record approval before it can earn production revenue. For the semiconductor ceramic heater market, the commercial consequence of long qualification cycles and high customer-concentration risk temper is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work.
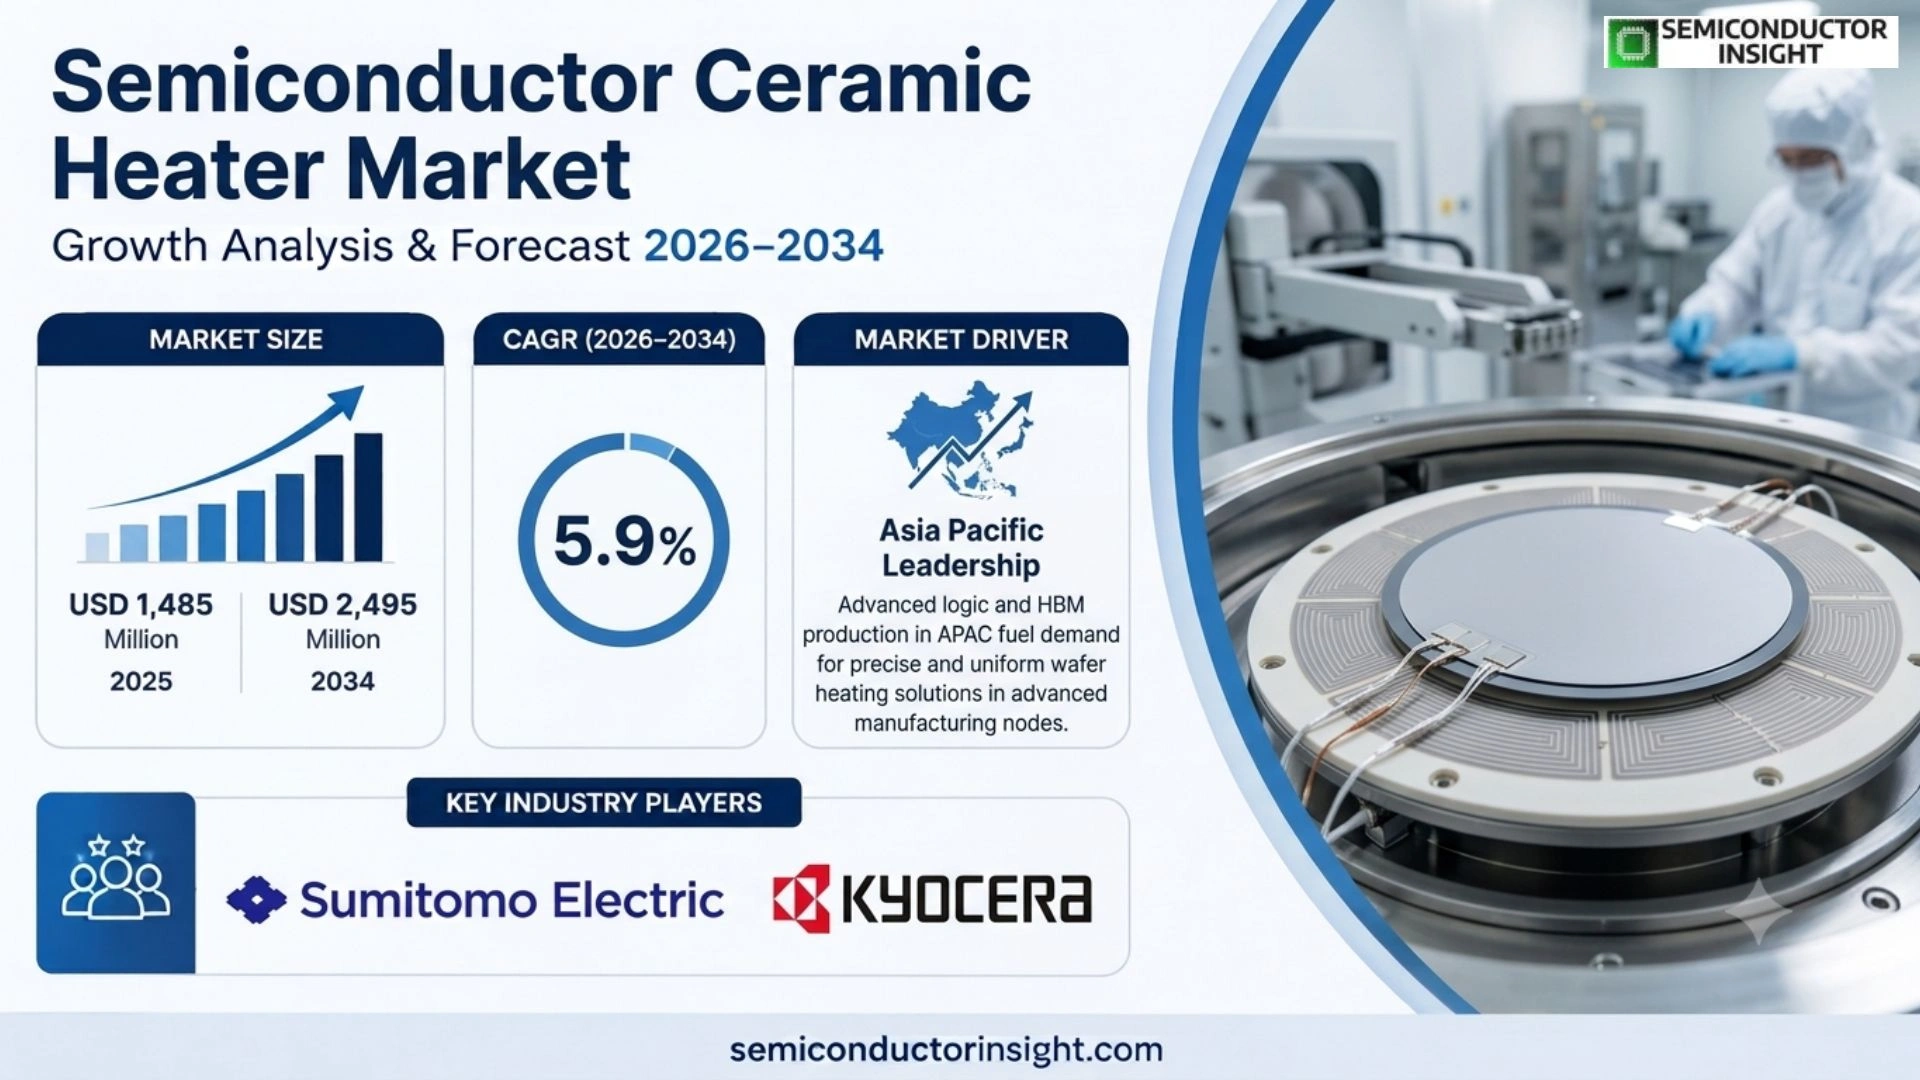
- Competitive structure – The market expands from USD 1.485 billion in 2025 to USD 2.495 billion by 2034 at a 5.9% CAGR during 2026–2034. Competition favors vertically integrated ceramic specialists that control powder formulation, forming, sintering, metallization, embedded conductors, brazing and final thermal mapping. A failure can disrupt high-value wafer output, causing equipment manufacturers and fabs to prioritize traceability and field history over low initial price.
Semiconductor Ceramic Heater Market Overview
Semiconductor Ceramic Heater Market was valued at USD 1.485 billion in 2025 and is projected to reach USD 2.495 billion by 2034, expanding at a 5.9% CAGR during 2026–2034. Asia Pacific held the largest regional position in 2025, while Asia Pacific presents the strongest expansion profile as AI-related logic, high-bandwidth memory and advanced-node investment increase the installed base of deposition and etch chambers that require uniform wafer heating.
A semiconductor ceramic heater is a wafer-support and thermal-control assembly used inside deposition, etch, cleaning and related process chambers. It typically combines a dense aluminum nitride, alumina or silicon-nitride body with embedded resistive elements, electrodes, temperature sensing, gas passages and a shaft or mounting structure. The commercial product therefore integrates ceramic science, electrical design and chamber-interface engineering.
The market scope includes heater plates, heated susceptors, electrostatic-chuck heater assemblies where heating is an integral function, replacement heater modules and associated customization or refurbishment. It excludes general industrial ceramic elements that never contact semiconductor process environments, complete wafer-fabrication tools, ordinary hot plates, and standalone chamber parts whose value is unrelated to controlled wafer temperature.
Temperature uniformity translates directly into process economics. Chemical vapor deposition and atomic-layer deposition depend on stable surface reactions across a 200 mm or 300 mm wafer, while etch and clean steps expose chamber components to chemically aggressive gases. A heater that reduces radial temperature error or particle generation can protect film uniformity, device yield and matching between chambers, justifying qualification effort and premium pricing.
The market is changing as 2 nm gate-all-around logic, high-bandwidth memory, advanced DRAM and increasingly complex 3D NAND require more exact thermal control across more process steps. SEMI’s 2025 equipment-sales data confirms a larger installed tool base, while a 36-month, EUR 1.85 million SMART EUREKA project is developing additively manufactured multi-zone ceramic heaters rated for process environments extending toward 800°C.
Segment Analysis: By Type
By material, the market is segmented into aluminum nitride, alumina, silicon nitride and other engineered ceramics. Aluminum nitride holds the largest 2025 position because it combines high thermal conductivity with electrical insulation and cleanroom-compatible processing, while advanced multi-material and additively manufactured architectures grow fastest where integrated cooling, embedded vias or non-standard zone control create measurable process gains.
| Type | Technical role | Market position |
|---|---|---|
| Aluminum Nitride (AlN) | Aluminum nitride conducts heat rapidly while electrically isolating embedded heater circuits, allowing multi-zone designs to respond quickly and distribute temperature across large wafer-support surfaces. Its processing demands controlled powder purity, sintering and metallization because oxygen content, grain structure and bonded interfaces influence thermal conductivity, dielectric strength, warpage and long-term reliability in the chamber. | Largest material segment in 2025. AlN is favored for high-value deposition and etch hardware where temperature uniformity, rapid ramping and compatibility with vacuum or plasma environments outweigh material and manufacturing cost. Suppliers compete through repeatable thermal maps, integrated electrode design and proven resistance to process gases rather than through a standardized commodity specification. |
| Alumina (Al2O3) | Alumina provides mature processing, electrical insulation, mechanical strength and a comparatively broad supplier base. It is used where operating temperature, heat flux and thermal-gradient requirements can be met without AlN-level conductivity. Design work centers on heater-trace geometry, bonding, surface finish and crack control through repeated heating and cooling cycles. For the semiconductor ceramic heater market, the commercial consequence of alumina provides mature processing, electrical insulation, mechanical strength is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. | Alumina retains a durable cost-performance position in less extreme chamber conditions and in ancillary semiconductor thermal hardware. Its commercial advantage is manufacturing maturity and familiarity, but slower lateral heat spreading can require more zones or tighter control logic. Demand therefore depends on the exact process window rather than on a universal substitution relationship with aluminum nitride. |
| Silicon Nitride (Si3N4) | Silicon nitride offers high fracture toughness, thermal-shock resistance and mechanical durability, making it relevant where rapid cycling or concentrated mechanical loading threatens brittle ceramic assemblies. Its manufacturing route and metallization compatibility differ from AlN, so suppliers must jointly engineer electrical, thermal and structural behavior instead of selecting the body material in isolation. | A smaller, application-led segment with opportunities in demanding thermal-cycling and mechanical environments. Adoption is gated by process qualification, achievable surface condition and total assembly cost. Suppliers win when silicon nitride solves a defined lifetime or shock problem that offsets redesign expense, rather than by presenting it as a general-purpose replacement for established heater platforms. |
| Advanced and Composite Ceramics | This group includes proprietary formulations, graded materials, coatings and multi-material constructions that improve plasma resistance, chemical durability, emissivity control or integration of conductive paths. Additive manufacturing can embed complex channels or zones, but each new architecture must demonstrate density, electrical isolation, dimensional control and repeatability at production scale. For the semiconductor ceramic heater market, the commercial consequence of this group includes proprietary formulations, graded materials, coatings is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. | Fastest-developing technology group. Growth comes from process steps that cannot be optimized with conventional flat, single-material designs. The segment remains qualification intensive and project specific, yet it creates attractive engineering revenue and defensible intellectual property because material formulation, geometry and process recipes are difficult to reproduce without accumulated manufacturing know-how. |
Pricing and qualification structure
Pricing is governed by diameter, material purity, number of independently controlled zones, embedded electrode complexity, integrated gas or cooling passages, shaft design, thermal-map tolerance, plasma-resistant surface treatment and qualification scope. A production-qualified 300 mm chamber assembly carries engineering and traceability value far beyond the ceramic blank, while refurbishment economics depend on whether metallization, joining or surface damage can be restored without changing validated chamber behavior.
Segment Analysis: By Application
By customer application, the market is segmented into foundries and outsourced manufacturing platforms, integrated device manufacturers, and research or pilot-line users. Foundries represent the largest demand pool because they operate large fleets across multiple customer processes, while leading-edge logic and memory programs create the fastest increase in thermal-control requirements and qualified spare intensity.
| Application | Demand characteristics |
|---|---|
| Foundries | Foundries require chamber matching across large tool fleets because the same customer process may run on several modules and sites. Heater thermal maps, particle performance and replacement consistency affect recipe transfer and wafer yield, so purchasing combines OEM-approved components, controlled refurbishment and spare strategies. Volume is high, but suppliers face demanding audit, traceability and change-notification requirements. |
| Integrated Device Manufacturers | IDMs use ceramic heaters across logic, memory, power-device, analog and specialty process lines. Demand is shaped by internal technology transitions and the age of the installed equipment base, creating a mixture of new-platform qualifications and long-tail replacement requirements. Suppliers that preserve legacy drawings while supporting new multi-zone designs can serve both stable mature-node and fast-moving advanced-node programs. |
| Equipment OEM Programs | Process-tool manufacturers integrate heaters into chamber platforms and often control the initial component qualification. They value co-development, documented configuration control and the ability to scale identical assemblies with tool shipments. Winning an OEM platform can create multi-year original-equipment and service demand, but design changes require disciplined notification because downstream fabs validate the chamber as a complete process system. |
| Research, Pilot and Specialty Lines | Universities, R&D centers, compound-semiconductor fabs and pilot lines purchase lower volumes but require unusual sizes, materials or temperature profiles. These projects are commercially important because they test architectures that may later enter production platforms. Suppliers compete through engineering access and rapid iteration, although non-recurring design effort makes pricing less comparable than in repeat replacement programs. |
Regional Analysis
Asia Pacific is the largest and fastest-growing regional market because it combines the largest concentration of wafer fabs with the principal Japanese and South Korean ceramic-heater manufacturing base. North America is an engineering and equipment-OEM center, Europe develops specialized materials and additive routes, and South America plus the Middle East and Africa remain project-led markets tied to individual semiconductor investments.
How does regional demand differ across the semiconductor ceramic heater market?
Regional economics depend on where chamber platforms are designed, where high-volume wafers are processed and where qualified ceramic manufacturing can support field failures. Asia Pacific benefits from all three functions at scale; North America has strong tool-design and leading-edge fab demand; Europe emphasizes specialty materials and localization; emerging regions require imported assemblies, local service planning and longer spare pipelines.
| Region | Position | Growth outlook | Demand profile | Market access gate |
|---|---|---|---|---|
| Asia Pacific | Largest in 2025 For the semiconductor ceramic heater market, the commercial consequence of largest in 2025 is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. | Highest For the semiconductor ceramic heater market, the commercial consequence of highest is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. | High-volume fabs and ceramic manufacturing For the semiconductor ceramic heater market, the commercial consequence of high-volume fabs and ceramic manufacturing is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. | Customer qualification, domestic technical support and export-control compliance For the semiconductor ceramic heater market, the commercial consequence of customer qualification, domestic technical support and export-control compliance is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. |
| North America | Second-largest demand center For the semiconductor ceramic heater market, the commercial consequence of second-largest demand center is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. | High For the semiconductor ceramic heater market, the commercial consequence of high is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. | Equipment OEMs, advanced logic and memory projects For the semiconductor ceramic heater market, the commercial consequence of equipment oems, advanced logic and memory projects is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. | OEM approval, traceability, cleanroom performance and rapid failure analysis For the semiconductor ceramic heater market, the commercial consequence of oem approval, traceability, cleanroom performance and rapid failure is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. |
| Europe | Specialty and localization market For the semiconductor ceramic heater market, the commercial consequence of specialty and localization market is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. | Moderate to high For the semiconductor ceramic heater market, the commercial consequence of moderate to high is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. | Power devices, R&D and advanced-material programs For the semiconductor ceramic heater market, the commercial consequence of power devices, r&d and advanced-material programs is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. | CE and customer-specific qualification, chemical compliance and local engineering For the semiconductor ceramic heater market, the commercial consequence of ce and customer-specific qualification, chemical compliance and local is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. |
| South America | Emerging For the semiconductor ceramic heater market, the commercial consequence of emerging is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. | Selective For the semiconductor ceramic heater market, the commercial consequence of selective is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. | Brazil-led specialty and packaging projects For the semiconductor ceramic heater market, the commercial consequence of brazil-led specialty and packaging projects is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. | Import lead time, spares, landed cost and local chamber-service capability For the semiconductor ceramic heater market, the commercial consequence of import lead time, spares, landed cost and local is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. |
| Middle East & Africa | Project-led from small base For the semiconductor ceramic heater market, the commercial consequence of project-led from small base is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. | High from low base For the semiconductor ceramic heater market, the commercial consequence of high from low base is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. | Sovereign semiconductor and research initiatives For the semiconductor ceramic heater market, the commercial consequence of sovereign semiconductor and research initiatives is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. | Long-term support, training, utilities compatibility and bankable delivery For the semiconductor ceramic heater market, the commercial consequence of long-term support, training, utilities compatibility and bankable delivery is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. |
Key Semiconductor Ceramic Heater Manufacturers and Competitive Landscape
The market is highly concentrated at the qualified high-performance tier because manufacturing capability alone does not create a production position. Sumitomo Electric, Kyocera, NGK, MiCo Ceramics and other specialists compete through ceramic formulation, embedded-conductor reliability, chamber integration and field history, while regional challengers target custom, refurbishment and less demanding process applications.
Competition begins with materials control. Powder purity, sintering atmosphere, grain structure and post-machining affect thermal conductivity, dielectric performance and particles; metallization and joining then determine electrical stability under cycling. A supplier that controls these steps can diagnose failures across interfaces and preserve configuration history, which is valuable to OEMs and fabs qualifying a chamber as a complete process system.
The second axis is platform access. Equipment OEMs often nominate or approve a heater during chamber development, after which fabs validate the process recipe around that configuration. Once production starts, changing a heater can require thermal remapping and wafer qualification. Incumbents therefore defend recurring original-equipment, spare and service revenue, while entrants must win on a new platform or solve an obsolescence problem.
The third axis is regional response. High-utilization fabs need rapid failure analysis and replacement, so local engineers and spare pools matter even when manufacturing remains centralized. Japanese and Korean suppliers benefit from proximity to Asian fabs; North American and European specialists can compete through OEM relationships, custom engineering, export-compliant service and localized refurbishment rather than attempting to duplicate full-scale ceramic production everywhere.
Portfolio labels require caution because not every industrial ceramic or heating company supplies production-qualified semiconductor heater assemblies. The report distinguishes core chamber-heater manufacturers from adjacent advanced-ceramics, industrial-heating and component firms. Company coverage therefore evaluates actual material, embedded-heater, chamber-interface and service capabilities instead of assuming that a broad ceramic catalog proves semiconductor qualification.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Tier 1 | Sumitomo Electric; Kyocera; NGK; MiCo Ceramics For the semiconductor ceramic heater market, the commercial consequence of sumitomo electric; kyocera; ngk; mico ceramics is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. | Vertically integrated advanced-ceramics capability, close equipment and fab relationships, proven high-volume qualification, controlled powders and sintering, and the ability to support heater designs through long replacement cycles across major Asian and global semiconductor manufacturing locations. For the semiconductor ceramic heater market, the commercial consequence of vertically integrated advanced-ceramics capability, close equipment and fab is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. |
| Tier 2 | BACH Resistor Ceramics; BOBOO Hitech; Semixicon; CoorsTek; Ferrotec; MARUWA For the semiconductor ceramic heater market, the commercial consequence of bach resistor ceramics; boboo hitech; semixicon; coorstek; ferrotec; is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. | Specialized ceramic processing, resistive-heater engineering, chamber components or regional process support. These suppliers can win custom and second-source programs when they demonstrate reproducible thermal uniformity, plasma compatibility, clean joining and field response, although platform breadth and customer qualification history vary by company. For the semiconductor ceramic heater market, the commercial consequence of specialized ceramic processing, resistive-heater engineering, chamber components or is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. |
| Tier 3 and adjacent | Durex Industries; Oasis Materials; Cactus Materials; Xiamen Innovacera; Thermcraft; NIBE Elements; Watlow; Toho Electronics For the semiconductor ceramic heater market, the commercial consequence of durex industries; oasis materials; cactus materials; xiamen innovacera; is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. | Custom and industrial thermal engineering, specialty materials, replacement components and geographically focused support. Participation ranges from direct heater assemblies to adjacent enabling technologies, so buyers must verify wafer-contact cleanliness, process-gas durability, embedded-element reliability and chamber-specific qualification rather than relying on general industrial-heater credentials. For the semiconductor ceramic heater market, the commercial consequence of custom and industrial thermal engineering, specialty materials, replacement is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. |
Key companies profiled
- Sumitomo Electric Industries, Ltd.
- Kyocera Corporation
- NGK Insulators, Ltd.
- MiCo Ceramics Ltd.
- BACH Resistor Ceramics GmbH
- BOBOO Hitech Co., Ltd.
- Semixicon LLC
- CoorsTek, Inc.
- Durex Industries
- Oasis Materials
- Cactus Materials, Inc.
- Xiamen Innovacera Advanced Materials Co., Ltd.
- Ferrotec Corporation
- MARUWA Co., Ltd.
- Thermcraft, Inc.
- NIBE Elements
- Watlow Electric Manufacturing Company
- Toho Electronics Inc.
Semiconductor Ceramic Heater Production Capacity Analysis
Production capacity is concentrated in Japan and South Korea, with additional specialist capability in Germany, the United States and China. The practical bottleneck is not furnace volume alone: high-purity feedstock, large-diameter sintering yield, embedded-circuit integrity, flatness, metallization, clean joining, thermal mapping and customer qualification jointly determine saleable capacity for 200 mm and 300 mm chamber assemblies.
A nominal ceramic furnace can produce many industrial parts, but semiconductor heaters demand tighter purity, dimensional and particle controls. Large plates can warp or crack during sintering, while embedded conductors must maintain resistance and insulation after hundreds of thermal cycles. Yield across these linked steps determines economic output, so adding furnace space without improving process control may not increase qualified capacity proportionally.
Japan’s advanced-ceramics ecosystem supports powder technology, shaping, sintering, metallization and equipment relationships, while South Korea combines domestic heater specialists with a dense memory and foundry customer base. Germany contributes resistor ceramics and additive-development capability; the United States supports equipment integration and custom thermal engineering; China is expanding domestic supply but must establish field history for critical advanced-node use.
Capacity planning follows chamber platforms rather than an undifferentiated market forecast. A new heater may require tooling, fixtures, electrical validation and customer-specific thermal maps before repeat production begins. Suppliers therefore reserve engineering and pilot capacity as carefully as serial sintering capacity. Customers mitigate risk with qualified spares, long-term agreements and sometimes second sources, although true interchangeability remains difficult.
Upstream concentration adds strategic risk. High-purity AlN powders, specialized metallization systems, joining alloys and clean machining are not universally available at consistent semiconductor grade. Export controls and customer-specific restrictions can also limit where an assembly is made or serviced. Vertical integration, dual-qualified materials and documented change control become commercial capacity because they protect continuity when one input route is disrupted.
Semiconductor Ceramic Heater Market Dynamics: Drivers, Restraints and Opportunities
Growth reflects a larger semiconductor-equipment installed base, more demanding thermal budgets at advanced nodes, and rising spare intensity in highly utilized fabs. The market is restrained by long qualification cycles, concentrated customers, brittle large-diameter manufacturing and exposure to equipment investment cycles. Opportunity centers on multi-zone control, plasma-resistant materials, refurbishment and localized support.
MARKET DRIVERS
Drivers Impact Analysis*
| Factor | Directional impact on CAGR forecast | Geographic relevance | Time horizon |
|---|---|---|---|
| Advanced-node and AI-related wafer-fab investment expands the number of deposition and etch chambers requiring new heater assemblies, while higher utilization also accelerates replacement and spare demand across production sites. For the semiconductor ceramic heater market, the commercial consequence of advanced-node and ai-related wafer-fab investment expands the number is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. | High | Asia Pacific and North America | 2026–2034 |
| Tighter within-wafer uniformity requirements increase value per qualified heater through more zones, better sensing and deeper thermal mapping rather than simply increasing shipment units. For the semiconductor ceramic heater market, the commercial consequence of tighter within-wafer uniformity requirements increase value per qualified is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. | High | Global leading-edge fabs | Immediate and ongoing |
| SEMI measured USD 135.1 billion of semiconductor-equipment sales in 2025, creating a larger installed service base for chamber components after original tool shipments enter production. For the semiconductor ceramic heater market, the commercial consequence of semi measured usd 135.1 billion of semiconductor-equipment sales is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. | Medium to high | Global | 2026–2030 |
| Localization and second-source programs encourage regional ceramic development, field service and spare stocking even where core serial manufacturing remains concentrated in Asia. For the semiconductor ceramic heater market, the commercial consequence of localization and second-source programs encourage regional ceramic development, is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. | Medium | Europe, China and North America | Medium term |
Advanced-node thermal control
Gate-all-around logic, high-bandwidth memory and complex 3D structures depend on deposition and etch steps whose results vary with wafer temperature. Customers respond by specifying more uniform multi-zone heater platforms and stricter chamber matching. Suppliers that can document thermal maps, material stability and process-gas durability capture more engineering value per system and defend recurring replacement revenue.
Equipment installed-base expansion
SEMI reported worldwide semiconductor manufacturing-equipment sales of USD 135.1 billion in 2025, up 15% from 2024. Ceramic heaters are only one chamber component, but every new deposition or etch module establishes years of spare and replacement demand. The mechanism therefore links current capital spending to a later service-market annuity for qualified suppliers.
Higher fab utilization
AI and memory demand can raise utilization on selected leading-edge tools, increasing thermal cycles and the economic cost of unexpected downtime. Fabs respond with preventive replacement, on-site spares and closer condition monitoring. Suppliers benefit when they support predictable lifetime and short turnaround, while inconsistent field performance can eliminate them from a platform regardless of nominal thermal specifications.
Localization and resilience
Governments and manufacturers want less concentrated semiconductor supply chains. Heater localization does not happen through policy alone because clean material and process qualifications remain essential, but programs such as the European CERAM-HEAT project reduce technical dependence. Commercial winners will be suppliers that convert research into repeatable large-diameter yields and win OEM or fab process approval.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Factor | Directional impact on CAGR forecast | Geographic relevance | Time horizon |
|---|---|---|---|
| Lengthy chamber and wafer qualification delays revenue and makes switching unattractive once an incumbent design is embedded in the process of record. For the semiconductor ceramic heater market, the commercial consequence of lengthy chamber and wafer qualification delays revenue and is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. | High negative | Global | Immediate |
| Large-diameter ceramic yield, warpage and embedded-element failures raise scrap cost and limit effective capacity even when furnace capacity is available. For the semiconductor ceramic heater market, the commercial consequence of large-diameter ceramic yield, warpage and embedded-element failures raise is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. | Medium negative | Manufacturing centers | Ongoing |
| Semiconductor capital-expenditure cyclicality can postpone new-platform demand while fixed ceramic and engineering costs remain in place. For the semiconductor ceramic heater market, the commercial consequence of semiconductor capital-expenditure cyclicality can postpone new-platform demand while is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. | Medium negative | Global | Short to medium term |
| Fluorine chemistry and plasma exposure shorten component life unless materials and surfaces are engineered for the exact chamber environment. For the semiconductor ceramic heater market, the commercial consequence of fluorine chemistry and plasma exposure shorten component life is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. | Medium negative | Deposition, etch and clean applications | Ongoing |
Qualification locks out technically capable entrants
A heater affects wafer temperature, film properties, particles and chamber uptime, so customers do not substitute it like a catalog resistor. OEM and fab validation may require thermal mapping, electrical testing, process wafers and extended field observation. That expense protects incumbents but slows innovation adoption, concentrates revenue and makes forecast timing dependent on individual platform approvals.
Large-format ceramic manufacturing risk
A 300 mm-class assembly must combine flatness, density, embedded conductors, gas passages and durable joining across repeated thermal cycles. Warpage, cracking, resistance drift or dielectric failure can scrap a high-value part late in production. Suppliers carry this yield risk, and buyers may face long replacement lead times when a chamber-specific design cannot be drawn from common stock.
Capital-equipment cyclicality
Ceramic-heater demand includes recurring replacement, but new-platform and first-fit volume still follows wafer-fab-equipment cycles. Memory downturns or delayed fabs can reduce tool shipments after suppliers have invested in fixtures, powders and engineering teams. Diversifying across foundry, logic, memory and specialty processes reduces exposure, though a small number of programs can still dominate annual demand.
Chemical degradation and contamination risk
Fluorine-containing process gases, plasma and rapid temperature change can degrade ceramic surfaces, metallization and joints. A failure may create particles or change temperature uniformity before it becomes electrically obvious. Customers therefore demand material traceability and conservative change control, raising lifecycle cost and restricting the use of cheaper formulations that lack long production evidence.
MARKET OPPORTUNITIES
Multi-zone heaters and integrated sensing
Advanced process windows require correction of edge losses, chamber asymmetry and changing thermal loads. More independently controlled zones and embedded sensing let equipment software compensate in real time. This expands value for suppliers that combine ceramic fabrication with electrical modeling and calibration, while creating controller, diagnostics and service opportunities around the physical heater assembly.
Additive multi-material architectures
The EUR 1.85 million, 36-month CERAM-HEAT project is developing three product families using feedstock-based 3D printing and advanced sintering. Complex channels, embedded conductive vias and integrated cooling could reduce assembly count or enable thermal patterns unavailable through conventional processing. Commercial success requires production yield and contamination evidence, not prototype geometry alone.
Refurbishment and obsolescence management
Long-lived wafer tools can outlast the original heater design or supplier support. Controlled refurbishment, reverse engineering and documented replacement allow fabs to keep mature-node chambers productive. Suppliers can build recurring service revenue with lower material consumption, but they must prove that repair does not change resistance, flatness, surface condition or validated thermal behavior.
Regional engineering and spare centers
Manufacturing will remain concentrated, yet local thermal mapping, incoming inspection, failure analysis and spare management can reduce fab downtime. A supplier can enter a region through service before duplicating full ceramic production. The model is attractive in North America, Europe and emerging Asian locations where customers want resilience but cannot justify qualifying many independent heater designs.
Semiconductor Ceramic Heater Supply Chain Analysis
The supply chain links high-purity ceramic powders and conductive materials to forming, sintering, embedded-heater fabrication, machining, joining, thermal mapping, equipment integration, fab qualification and recurring service. Value concentrates at the interfaces where material consistency becomes chamber performance, because defects discovered after joining or wafer testing carry far greater cost than raw powder or machining alone.
Materials and feedstock. For the semiconductor ceramic heater market, upstream value depends on documented composition, lot consistency and compatibility with downstream thermal or electrical processing. Within the semiconductor ceramic heater market, material substitutions can change shrinkage, coupling, insulation, corrosion or lifetime, so suppliers need controlled change notices and incoming verification. Within the semiconductor ceramic heater market, strategic sourcing therefore balances price with traceability and qualification continuity.
Ceramic and heater fabrication. For the semiconductor ceramic heater market, manufacturing value is created by yield and repeatability across multiple coupled steps. Within the semiconductor ceramic heater market, defects introduced early may appear only after poling, joining, thermal mapping or final calibration, increasing scrap. Within the semiconductor ceramic heater market, process controls, metrology and experienced engineering teams become barriers to entry because a visually acceptable component may still fail electrical or application performance.
Equipment integration and qualification. For the semiconductor ceramic heater market, integration is where component specifications are converted into a customer outcome. Within the semiconductor ceramic heater market, equipment builders combine the device with mechanics, electronics, software and safety controls, then validate it under representative loads and environments. Within the semiconductor ceramic heater market, winning this stage creates durable design-in revenue, while any uncontrolled material or process change can reopen qualification and delay a product launch.
Fab operation and lifecycle service. For the semiconductor ceramic heater market, lifecycle service protects uptime and preserves the installed base. Within the semiconductor ceramic heater market, customers need spares, failure analysis, recalibration, refurbishment or compatible replacements long after original qualification. Within the semiconductor ceramic heater market, suppliers that maintain drawings, lot history and regional support can earn recurring revenue and reduce buyer risk, whereas discontinuity may force an expensive system redesign or process revalidation.
Recent Developments in the Semiconductor Ceramic Heater Market
Official announcements and publications are dated to their original release; each entry links the event to a measurable technology, investment or market-access implication. For the semiconductor ceramic heater market, the commercial consequence of official announcements and publications are dated to their is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work.
- 7 April 2026
SEMI reported that worldwide semiconductor manufacturing-equipment sales reached USD 135.1 billion in 2025, up 15% from USD 117.1 billion in 2024. The recorded expansion matters to ceramic-heater suppliers because each installed deposition or etch chamber creates original-equipment demand followed by a multi-year requirement for qualified spares, replacement and failure-analysis support. Source - 1 April 2026
SEMI projected worldwide 300 mm fab equipment spending of USD 133 billion in 2026 and USD 151 billion in 2027, growth of 18% and 14% respectively. AI demand and regional self-sufficiency were identified as major causes, supporting multi-zone heater qualification, large-diameter ceramic capacity and regional spare strategies for advanced logic and memory chambers. Source - 16 December 2025
SEMI projected foundry and logic wafer-fab-equipment sales of USD 66.6 billion in 2025, followed by 5.5% growth in 2026 and a further 6.9% increase to USD 75.2 billion in 2027. The series links AI and advanced-node capacity directly to a larger installed base of thermal-control subassemblies that require controlled configuration and replacements. Source - 2025 project cycle
The SMART EUREKA CERAM-HEAT program disclosed a 36-month duration and EUR 1.85 million budget for three advanced ceramic-heater product families. The project combines feedstock-based additive manufacturing, advanced sintering, embedded conductive vias and integrated cooling, targeting rapid uniform heating and cooling under fluorine-containing semiconductor process environments extending toward 800°C. For the semiconductor ceramic heater market, the commercial consequence of the smart eureka ceram-heat program disclosed a 36-month is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work. Source - 2025 product evidence
Sumitomo Electric described ceramic thermal-control devices that combine high-functional materials, metallization, joining, sealing and heat-design technologies for semiconductor fabrication equipment. The manufacturer emphasizes temperature uniformity and rapid heating and cooling, supporting the market’s shift toward integrated engineering performance and showing why qualified value extends beyond the cost of the ceramic body or embedded resistor. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Category | Semiconductor Equipment > Wafer Processing Components > Ceramic Heaters and Susceptors |
| Study Period | 2021–2034 |
| Base Year | 2025 |
| Forecast Period | 2026–2034 |
| Market Size | USD 1.485 billion in 2025; USD 2.495 billion by 2034; 5.9% CAGR during 2026–2034 |
| By Type | Aluminum Nitride (AlN); Alumina (Al2O3); Silicon Nitride (Si3N4); Advanced and Composite Ceramics |
| By Application | Foundry; Integrated Device Manufacturer; Equipment OEM Program; Research, Pilot and Specialty Line |
| By End User | Semiconductor wafer fabrication; Process-equipment manufacturing; R&D and pilot production |
| Regions | North America; Europe; Asia Pacific; South America; Middle East & Africa |
| Companies | Sumitomo Electric Industries, Ltd.; Kyocera Corporation; NGK Insulators, Ltd.; MiCo Ceramics Ltd.; BACH Resistor Ceramics GmbH; BOBOO Hitech Co., Ltd.; Semixicon LLC; CoorsTek, Inc.; Durex Industries; Oasis Materials; Cactus Materials, Inc.; Xiamen Innovacera Advanced Materials Co., Ltd.; Ferrotec Corporation; MARUWA Co., Ltd.; Thermcraft, Inc.; NIBE Elements; Watlow Electric Manufacturing Company; Toho Electronics Inc. |
Frequently Asked Questions
What is the current size of the semiconductor ceramic heater market?
The global market was valued at USD 1.485 billion in 2025. This figure covers semiconductor-grade ceramic heater and heated-susceptor assemblies used in wafer-processing environments, including qualified replacement and associated engineering value. It excludes complete deposition or etch tools and general industrial ceramic heating elements that are not designed for controlled wafer temperature, cleanliness and process-gas exposure.
What will the market be worth by 2034?
The market is projected to reach USD 2.495 billion by 2034, representing a 5.9% CAGR during 2026–2034. The forecast is supported by new wafer-fab-equipment installations, recurring replacements, higher utilization and more technically valuable multi-zone assemblies. It remains sensitive to equipment cycles because platform launches and fab construction determine when first-fit heater demand enters production.
Which region leads the market?
Asia Pacific held the largest position in 2025 and is expected to grow fastest because it combines the greatest concentration of wafer manufacturing with leading Japanese and South Korean advanced-ceramic suppliers. Taiwan, Korea, Japan and China also shorten the distance between fab users, process-tool service organizations and component engineers, improving qualification and replacement response.
Which material type leads?
Aluminum nitride is the leading material segment because it provides high thermal conductivity together with electrical insulation and compatibility with embedded resistive circuits. Those properties support rapid ramping and uniform wafer temperatures. Alumina, silicon nitride and proprietary composite structures remain important where cost, thermal shock, chemical durability or specialized geometry creates a different optimization target.
Why are ceramic heaters important in semiconductor manufacturing?
The heater controls wafer temperature during deposition, etch and related chamber processes. Temperature variation changes surface reactions, film thickness and process repeatability, while particles or electrical failure can interrupt production. A qualified heater therefore protects yield and chamber matching, making material purity, thermal maps, joining quality and field reliability more important than the cost of ceramic alone.
What drives demand growth?
The principal drivers are advanced-node thermal-control requirements, expansion of the semiconductor-equipment installed base, higher tool utilization and supply-chain localization. SEMI measured USD 135.1 billion of worldwide equipment sales in 2025, up 15% from 2024. More chambers create first-fit demand immediately and a larger population of qualified replacements and spares over subsequent years.
What are the main market restraints?
Long qualification, large-diameter ceramic yield risk, capital-equipment cyclicality and degradation in fluorine or plasma environments restrain growth. A new supplier must prove thermal uniformity, cleanliness, electrical integrity and process results, not simply make a heater. Once a production chamber is qualified, buyers resist changes that could require recipe validation or introduce downtime.
Which companies are profiled in the report?
The report profiles Sumitomo Electric, Kyocera, NGK, MiCo Ceramics, BACH Resistor Ceramics, BOBOO Hitech, Semixicon, CoorsTek, Durex Industries, Oasis Materials, Cactus Materials, Xiamen Innovacera, Ferrotec, MARUWA, Thermcraft, NIBE Elements, Watlow and Toho Electronics. Coverage distinguishes core semiconductor-heater suppliers from adjacent advanced-ceramics and industrial-heating participants. For the semiconductor ceramic heater market, the commercial consequence of the report profiles sumitomo electric, kyocera, ngk, mico is that qualification evidence, integration support and lifecycle reliability influence the purchase alongside the nominal component specification. Within this semiconductor ceramic heater market context, suppliers that connect those requirements to documented process performance can protect design-in positions, while buyers reduce changeover risk and unplanned engineering work.
Where is production capacity concentrated?
Qualified capacity is concentrated in Japan and South Korea, with specialist capability in Germany, the United States and China. Effective capacity depends on powder purity, sintering yield, embedded-circuit integrity, flatness, machining, metallization, clean joining and thermal mapping. Consequently, available furnace space is not an adequate measure of output for production-qualified 200 mm and 300 mm assemblies.
What are the strongest opportunities?
The strongest opportunities are multi-zone thermal control, embedded sensing, additively manufactured multi-material designs, plasma-resistant surfaces, controlled refurbishment and local service centers. Each opportunity solves a measurable customer problem such as uniformity, lifetime, obsolescence or downtime. Suppliers still need production repeatability and chamber qualification before technical innovation converts into sustained market revenue.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF