Key Statistics
Key Takeaways
- Growth outlook: The market stands at USD 887.4 million in 2025 and reaches USD 1,378.5 million by 2034, implying a 5.0% annual increase as telecom maintenance programs adopt repeatable RF distortion testing for complex multi-band installations.
- Core instrumentation: Low frequency-band equipment covering 400 MHz to 6 GHz represents an estimated ~79% of tester demand, while millimeter-wave systems account for ~21% because higher-frequency implementation and calibration remain more specialized.
- Customer concentration: Base-station applications generate an estimated ~59% of instrument sales; telecom companies contribute roughly ~56% of the end-user classification, supported by field inspection, commissioning and investigation of interference complaints.
- Regional leadership: Asia Pacific has an estimated ~38% of revenue, reflecting wireless infrastructure activity in China, India and East Asia. North America holds ~27% through established RF measurement budgets and demanding network performance standards.
- Technical requirements: IEC 62037-1:2025 defines the two-tone measurement discipline, while instrument vendors add field portability, distance-to-PIM location and multiport testing. Buying decisions increasingly include training, calibration evidence and software lifecycle support.
PIM Tester Market Overview
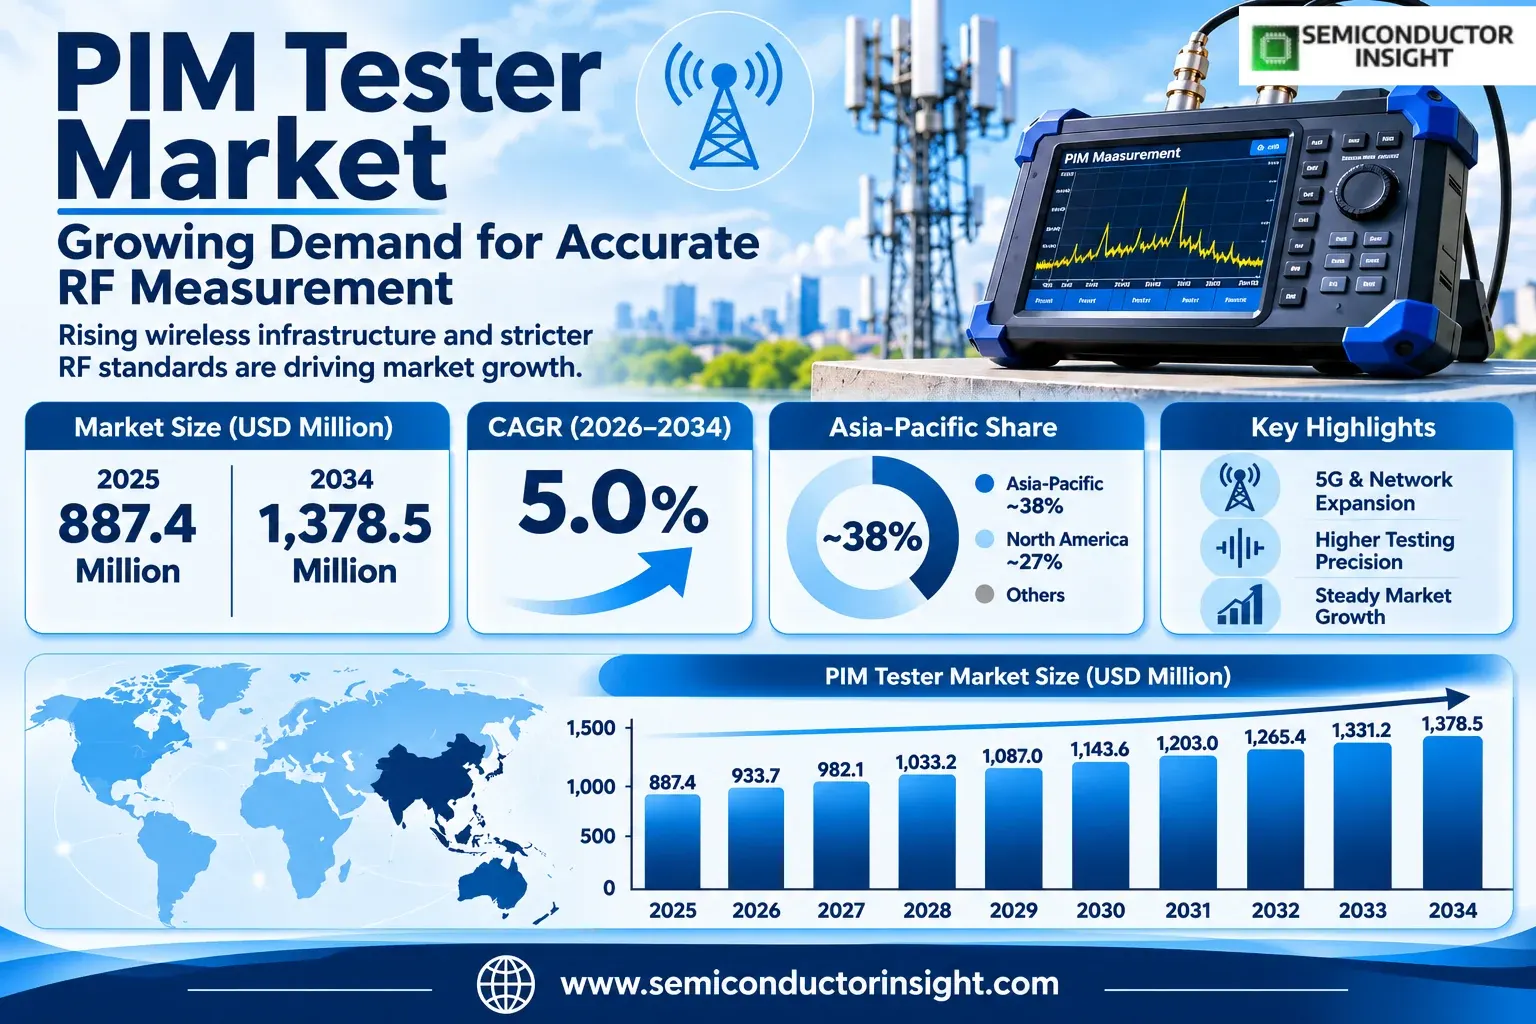
PIM tester market was valued at USD 887.4 million in 2025 and is expected to reach USD 1,378.5 million by 2034, at a CAGR of 5.0% over the forecast period. Asia Pacific leads with an estimated ~38% share, followed by North America with ~27%, as wireless infrastructure modernization and demanding passive RF component testing expand equipment requirements.
A passive intermodulation tester is a specialized RF instrument that exposes unintended mixing products created by antennas, coaxial connections, filters and other nominally passive components. Two strong transmitted signals can interact at an imperfect junction and produce an unwanted third-order response near a receiving channel. Network engineers use suitable high-power tones and a sensitive receiver to isolate the cause of the interference before correcting the physical installation or replacing the component.
The revenue boundary encompasses portable and laboratory PIM test instruments, measurement accessories and embedded test capabilities associated with the listed low-frequency and millimeter-wave bands. It includes commercial equipment purchased for cellular base stations, satellite links, vehicles, aerospace programs and RF laboratories. It does not treat complete mobile networks, satellite capacity, carrier subscriptions, antennas sold independently or unrelated general-purpose spectrum analyzers as additional PIM tester turnover.
Measurement integrity now attracts greater attention because mixed-band antennas and denser radio deployments can amplify the operational cost of a faulty connector. IEC 62037-1:2025 clarified frequency-dependent results, multiport arrangements and report completeness, giving manufacturers and purchasers a common method for describing laboratory and site measurements. A tester that performs well on a benchtop still needs stable cables, appropriate power handling and trained handling for reproducible outdoor measurements.
Dedicated equipment makers provide different routes to a diagnosis. Anritsu sells the 40-watt battery-powered PIM Master MW82119B, with optional cable and antenna analysis; Kaelus offers portable iPA and iXA families plus laboratory instruments; Rosenberger offers desk-level measurement products for precision connector work. These portfolios demonstrate that the market covers both field maintenance and manufacturing quality assurance without assuming every RF instrument company sells a dedicated PIM assemblies.
The surrounding telecommunications ecosystem is large but cannot be used directly as tester revenue. Ericsson reported more than 3.1 billion global 5G subscriptions at the end of the first quarter of 2026 and growing differentiated-connectivity offerings. That network expansion provides a reason to inspect more installation points, not a direct measure of analyzer purchases. Equipment demand depends on site spending, replacement cycles, device capability and whether work is performed by operators or contracted technicians.
Segment Analysis: By Type
Commercial analyzers separate into a conventional 400MHz–6GHz category and a higher-frequency millimeter-wave category. The low-band class holds an estimated ~79% share because most live-site maintenance covers cellular and adjacent radio bands with well-developed portable tools. Millimeter-wave equipment occupies the remaining ~21%, where tighter transmission-line tolerances, smaller connectors and demanding calibration can increase engineering expense despite more limited installed-base volume.
| Type | Function | Market position |
|---|---|---|
| Low Frequency Band (400MHz–6GHz) | Sub-6GHz analyzers perform two-tone inspection of outdoor radio installations, RF jumpers, feeder assemblies and component interfaces. Portable designs can inject substantial power, record intermodulation behavior and identify distance-related defects in the cable path. Customers value reliable field deployment, appropriate test ports and serviceable adapters as much as laboratory sensitivity. | Estimated ~79% share. Recurring maintenance work in LTE and 5G sub-6GHz networks provides the largest addressable base, with telecom technicians and installation contractors influencing purchasing specifications. |
| High Frequency Band (Millimeter Wave) | Millimeter-wave test configurations address higher bands used in advanced wireless, aerospace and high-frequency research. Cable loss, fixture repeatability and connector precision become especially consequential as wavelengths shrink. Purchasers may need laboratory arrangements or specialized extensions rather than simply selecting a conventional tower analyzer with a different screen menu. | Estimated ~21% share. Laboratory engineering and selected high-frequency deployments create disproportionate value for complex fixtures and calibration, although annual unit demand remains below established cellular maintenance applications. |
Secondary segmentation: end-user procurement
Instrument buying differs by operator, laboratory and vehicle or aerospace certification program. Telecommunication companies form the largest purchaser class, while research laboratories acquire specialized equipment for validating new connectors and antenna architectures. End-user distinctions describe who funds or operates a tester, whereas the application view explains the communications system being assessed; procurement arrangements can overlap without constituting separate revenue pools.
| Axis | Members | Commercial role |
|---|---|---|
| End User | Telecommunication Companies · Satellite Service Providers · Aerospace & Defense Organizations · Automotive Manufacturers · Research & Testing Laboratories | Estimated shares of ~56%, ~15%, ~12%, ~9% and ~8%, respectively; required power, calibration records and ownership of field-service fleets govern spending. |
Segment Analysis: By Application
Wireless communication base stations account for an estimated ~59% of use-case demand, substantially ahead of satellite communications at ~16%, aerospace at ~11%, in-vehicle communications at ~9%, and other RF development work at ~5%. Portable high-power instruments suit outdoor site certification, whereas satellite and aircraft assembly can require tightly controlled fixtures. The figures distinguish how instruments are used, not how many subscribers or vehicles an industry serves.
| Application | Demand characteristics |
|---|---|
| Wireless Communication Base Station | Cellular network installers examine antennas, duplexers, feeder cables and junctions before a new site enters service and after complaints about uplink noise. Two-tone intermodulation measurements are particularly useful when several strong radio carriers share passive hardware. Field teams place a premium on weather resistance, battery operation and a method for locating the defective junction without replacing every component. |
| Satellite Communication | Satellite service organizations qualify terrestrial RF ground equipment and interconnects where unwanted mixing could contaminate nearby receive channels. Instruments are often integrated with controlled test fixtures and calibration routines, and the frequency plan must match the actual link. Commercial opportunity follows ground infrastructure maintenance and component production, rather than the monetary value of satellite bandwidth sold. |
| In-vehicle Communication | Automotive antenna systems place cellular, navigation and other radios near metal structures, creating difficult routing and interference conditions. Manufacturers can evaluate passive nonlinearities in connectors and cable assemblies during development and supplier acceptance. Specialized frequency and power requirements keep this an engineering-intensive but smaller market than commercial cell-site testing, with repeatability important across vehicle platforms. |
| Aerospace | Aircraft and defense communications involve demanding RF integration, environmental constraints and component traceability. Testers can support inspection of antenna feeds, passive filtering and interconnects before equipment is installed into a larger assembly. Certification procedures differ by system and program, so a general-purpose cellular PIM result may require additional evidence before it is accepted in high-reliability applications. |
| Others | Universities, RF passive component manufacturers and independent certification facilities use PIM systems to investigate material interfaces and low-distortion component designs. Experimental fixtures may examine different frequencies, power levels and time behavior than a routine tower test. Revenue is more project-dependent than maintenance subscriptions and often includes service contracts or specialist calibration support alongside the primary hardware. |
A site-oriented buyer might purchase a portable tester, calibration standards and RF accessories in one order, whereas a connector manufacturer can integrate a bench system into product acceptance processes. These two channels create distinct replacement and upgrade cycles. The 5G rollout creates useful demand context, but the timing of actual instrument transactions depends on operator capital budgets, technician fleets, inspection standards and the number of contractors authorized to maintain a network.
Regional Analysis
Asia Pacific accounts for an estimated ~38% of the 2025 PIM tester business, North America ~27% and Europe ~22%. The remaining distribution is South America at ~7% and the Middle East & Africa at ~6%. These shares reflect differences in installed wireless networks, engineering service procurement and manufacturer access. Global instrument suppliers can book sales through distributors in one country while the equipment is used on a telecom site in another.
Why does wireless infrastructure activity give Asia Pacific the largest PIM test equipment position?
China, India, Japan and South Korea combine dense mobile systems with ongoing radio upgrades that require competent passive interference troubleshooting. Procurement spans large operator fleets, local integration firms and contract field-service organizations. North America attracts substantial premium test-instrument demand because mature cellular infrastructure requires continuing performance verification, while Europe supports experienced RF component designers and rigorous measurement practices. All five geographies share the same core technical challenge: keeping self-generated passive interference below accepted limits.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia Pacific | Largest (~38%) | High | Expanding multi-band mobile coverage | Field calibration and operator-approved suppliers |
| North America | Second (~27%) | High | Dense 5G sites and equipment servicing | Instrument uptime and distance-to-PIM tools |
| Europe | Established (~22%) | Moderate | RF equipment design and measured compliance | IEC testing documentation and connector quality |
| South America | Developing (~7%) | Moderate | Base-station modernization and contractor fleets | Cost of ownership and local repair capability |
| Middle East & Africa | Emerging (~6%) | Moderate | Selective 5G rollout and site maintenance | Portable power, training and distributor access |
Key PIM Tester Manufacturers and Competitive Landscape
Competition spans dedicated PIM instrument manufacturers, large electronic measurement groups and RF interconnect specialists. Anritsu and Kaelus are directly identifiable through current portable analyzer ranges, while Rosenberger supplies controlled laboratory PIM measurement products. Customers evaluate the frequency bands actually supported by a purchased configuration, the ability to locate faults and how consistently the test setup produces results after repeated deployment.
Anritsu emphasizes portable field troubleshooting. Its MW82119B family combines battery operation with high-power measurement, and certain configurations can examine cable and antenna parameters such as return loss and distance-to-fault. That integration is attractive to tower maintenance crews that cannot carry numerous heavy instruments. The product also illustrates why equipment selection depends on band options and approved accessories; a broad product-family name alone does not guarantee coverage of every site frequency.
Kaelus focuses on the passive interference problem through its iPA, iXA, bench instruments and supporting software. A September 2026 PIM Server update added support for a four-port iBA F-series configuration, demonstrating continuing attention to complex factory measurement workflows. Rosenberger participates through precision interconnect engineering and PIM desktop systems, where mechanical interfaces and setup repeatability are central to value. Customers choosing between field and bench solutions face different space and calibration needs.
Other report-listed names such as Keysight Technologies, VIAVI Solutions, EXFO, Bird Technologies and Commscope operate in adjacent RF test, antenna or communications markets. A broad RF instrument portfolio should not be interpreted as evidence of an active dedicated PIM instrument for every listed company or frequency class. Procurement specialists should request a specific current catalog number and valid calibration documentation before considering products interchangeable with a proven two-tone PIM analyzer.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Tier 1 | Anritsu · Kaelus · Rosenberger | Verified portable or laboratory PIM products, specialized RF interfaces and service relationships. |
| Tier 2 | Keysight Technologies · VIAVI Solutions · EXFO | Adjacent radio-frequency and communications test portfolios; dedicated PIM model must be confirmed. |
| Specialist and channel | AWT Global · Bird Technologies · Commscope · authorized calibration partners | Application-specific RF instrumentation, distribution and customer access where current products are verified. |
Key companies profiled
- Anritsu
- Kaelus
- Rosenberger
- Keysight Technologies (adjacent RF test portfolio)
- VIAVI Solutions (adjacent RF test portfolio)
- EXFO (adjacent radio test portfolio)
- Bird Technologies (confirm dedicated model)
- Commscope (RF infrastructure; verify test-instrument supply)
PIM Tester Production Capacity Analysis
PIM instrument manufacturing is a precision electronic measurement business, not production of telecom infrastructure itself. Manufacturing capacity consists of calibrated high-power signal paths, sensitive intermodulation receivers, low-distortion filters, display and battery integration, durable test ports and final performance verification. Production can be concentrated at specialist plants and service centers, with the ability to calibrate an instrument sometimes setting the effective customer-delivery capacity.
Core hardware includes low-distortion power amplifiers, couplers, receivers and carefully characterized passive components. Manufacturing must suppress intermodulation generated inside the analyzer so that a small device-under-test response can be detected reliably. A misassembled connector or unsuitable fixture can undermine the best receiver design. Acceptance procedures therefore exercise multiple RF powers and frequencies, inspect self-generated distortion and document uncertainty before equipment reaches a technician.
High-frequency and multiport architectures introduce additional assembly and test complexity. Compact transmission lines, specialized connectors and stable mechanical fixtures become more important as operating frequency rises. Software can configure measurement tone pairs, automate reporting and preserve traceability across field and bench workflows. The September 2026 Kaelus software release illustrates how ongoing support can extend the commercial service life of already installed physical instruments without requiring a complete hardware replacement.
The supply chain depends on specialty RF electronics, precision machining, electronics assembly and accredited calibration infrastructure. A factory may build instruments in modest batches, yet a professional service network can affect end-market confidence over several years. Sales are influenced by replacement and refurbishment of existing fleet units, not only new antenna construction. Lead times can lengthen when a specialized power component or high-stability RF connector is difficult to source.
PIM Tester Market Dynamics: Drivers, Restraints and Opportunities
Long-run growth is driven by testing intensity rather than radio subscriptions themselves. More frequency bands, closer co-location of transmitters and maintenance of complex antenna systems increase the cost of uncertain interference diagnosis. At the same time, telecom capital budgeting and the limited number of trained technicians constrain purchases. These opposing influences support moderate expansion, with specialist millimeter-wave and multiport needs increasing the value of selected instruments.
MARKET DRIVERS
Drivers Impact Analysis*
| Market Drivers | Impact Rank | CAGR Contribution (%) | 2026–2028 | 2029–2031 | 2032–2034 |
|---|---|---|---|---|---|
| 5G base-station maintenance and radio densification | High | +2.50% | High | High | High |
| Multi-band site interference troubleshooting | Medium-High | +1.80% | High | High | Medium |
| Satellite and defense RF acceptance programs | Medium | +1.20% | Medium | High | High |
| More exacting passive component validation | Low-Medium | +0.80% | Medium | Medium | High |
| Others (fleet digitization and remote diagnostics) | Low | +0.40% | Medium | Medium | High |
Growing radio networks require interference testing after installation
Ericsson identified more than 3.1 billion 5G subscriptions in the first quarter of 2026, showing the scale of contemporary cellular operation. Site operators continue adding radio layers and improving coverage, which increases the number of passive paths that can generate unwanted mixing products. A calibrated PIM tester helps determine whether a defect comes from connectors and feeder systems rather than from the radio electronics. Purchases occur only where operators fund test work or contracted engineering crews.
Shared antenna paths turn weak contacts into costly faults
Co-located transmitters can create significant intermodulation signals when an imperfect metal interface behaves nonlinearly. The resulting unwanted product may overlap a receiving channel and degrade performance without a conventional transmitter fault. Field teams equipped with distance-to-PIM features can focus repairs on a short cable section, saving technician hours. Instrument makers that simplify such troubleshooting can improve return on investment even when operators are not adding many new cell sites.
Aerospace and satellite engineering demand documented validation
Passive components in satellite ground systems, aircraft and specialized RF assemblies may operate under stringent noise requirements. Testing must reproduce relevant frequency pairs and input power, with traceable records showing the actual conditions. This creates a smaller but technically valuable destination for bench measurement systems and fixtures. The commercial link is through component qualification, project acceptance and periodic re-evaluation rather than the volume of satellites placed in orbit.
Updated standards encourage repeatable high-power measurements
IEC 62037-1:2025 drew attention to swept frequencies, multi-port setups and reporting the maximum measured intermodulation response. These refinements help laboratories compare results and specify acceptance tests with fewer ambiguities. Customers might upgrade software, fixtures or complete instruments to follow consistent procedures. No single standard revision guarantees purchases, however, because existing systems can remain useful when vendors provide appropriate updates and calibration guidance.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Market Restraints | Impact Rank | CAGR Contribution (%) | 2026–2028 | 2029–2031 | 2032–2034 |
|---|---|---|---|---|---|
| Telecom capital-budget limits | High | -0.90% | High | Medium | Medium |
| Specialist instrument prices and training requirements | Medium | -0.50% | High | Medium | Low |
| Others (maintenance fleet sharing and rentals) | Low | -0.30% | Medium | Medium | Low |
Network operators scrutinize nonessential equipment spending
Mobile infrastructure budgets compete with spectrum, energy, transport and software expenditures. If a carrier has reliable outside contractors, it may choose not to own an expensive PIM analyzer fleet. Purchases can also be postponed when a network project is delayed or when the operator prefers to rely on existing instruments. Such cycles make the tester business more uneven than network subscription growth and encourage vendors to offer flexible service arrangements.
Advanced analyzers require technical expertise and calibration
A tester can produce misleading results if the RF cables, loads, power levels or connectors in the test setup generate substantial unwanted products themselves. Operators need trained staff, safe procedures and regular performance verification. High-frequency instruments may require fragile precision parts and carefully controlled fixtures. These requirements raise the lifetime cost of ownership and can deter smaller maintenance teams from buying a dedicated unit instead of using an external laboratory.
Shared tool fleets limit purchases per serviced site
Test instruments are often moved among projects and rented by specialized contractors, so one unit can cover many cellular locations. This improves industry maintenance efficiency but weakens a direct relationship between tower count and instrument sales. Improved product reliability also extends replacement intervals. Manufacturers must therefore sell functions, accessories and service capability rather than expecting every newly deployed antenna or base station to trigger an independent equipment purchase.
MARKET OPPORTUNITIES
Multiport factory systems can increase test productivity
A bench analyzer that works with several RF ports can help antenna and connector manufacturers reduce setup changes during production qualification. The 2026 support update for Kaelus four-port iBA equipment is an example of such workflow evolution. Buyers may invest to improve repeatability and electronic recordkeeping, particularly when factory output includes complex multi-band components. Commercial growth depends on verified throughput gains, calibration stability and integration with existing product-test procedures.
Higher-frequency RF engineering expands instrument specifications
New wireless and aerospace platforms bring questions that are not always answered by a familiar sub-6GHz field tester. Specialized frequency sources, low-distortion interconnects and carefully characterized fixtures can attract value in engineering laboratories. The opportunity is strongest where a customer can define measurable interference limits and accept the cost of calibration. It is not appropriate to assume every mmWave rollout needs the same PIM test hardware as an outdoor cellular feeder system.
Software and service offerings support installed instrument fleets
As professional contractors maintain analyzers over several years, firmware, calibration, repair and measurement-report export become significant purchasing criteria. Vendors can sell extended support to customers who might otherwise replace entire units less frequently. The ability to preserve consistent test records across multiple software revisions increases confidence in long-term network contracts. Competitive advantage can therefore come from a dependable support infrastructure rather than from a single new headline specification.
PIM Tester Supply Chain Analysis
The PIM testing value chain begins with specialized microwave semiconductors, low-distortion passive parts and precision connectors, followed by instrument design, electronics production and controlled calibration. Equipment reaches telecom operators and laboratories through direct sales or qualified distributors. Technical service continues after shipment because high-power RF ports and accessories require periodic checks, making lifecycle support a practical part of instrument purchasing.
Critical microwave materials. A power amplifier and passive combining path must produce sufficiently low self-intermodulation so the instrument can identify a poor connector on the device under test. Suppliers therefore need predictable semiconductor components, high-grade cables, shielded housings and precisely manufactured RF interfaces. Design substitution is not trivial because an ostensibly equivalent part can change analyzer distortion and measurement uncertainty. This creates a qualification burden for both the manufacturer and its specialist component vendors.
Assembly and instrument verification. Manufacturers integrate generators, high-power RF paths and sensitive detectors into a stable enclosure with appropriate cooling, displays and battery management where required. End-of-line tests examine leakage, frequency calibration and repeatability across supported measurement bands. Additional fixtures may be required for multiport or millimeter-wave systems. Instruments that pass functional checks still need a documented calibration basis before being accepted into a network-contractor fleet.
Distribution and after-sales maintenance. Precision instruments often reach customers through technical distributors capable of helping select frequency bands, test leads and accessories. After purchase, damaged connectors, firmware changes and scheduled recalibration influence equipment availability. Local service provision is especially important when a customer uses a small shared fleet. A vendor offering rapid repair can generate a meaningful commercial advantage without relying on a lower initial purchase price.
Field and laboratory customers. Telecommunications contractors use portable analyzers to inspect radio installations, while laboratories employ bench systems to qualify connectors, antennas or specialized passive assemblies. Application requirements differ in power level, test frequency, evidence retention and environmental durability. The procurement decision combines instrument capabilities with employee competency and the costs of repeat site visits. Revenue arises when equipment and related support are purchased, not from the total operating income of the network.
Recent Developments in the PIM Tester Market
- 24 September 2026 Measurement software
Kaelus released PIM Server version 12.42.2, with support for four-port iBA F-series bench models and a browser-related RF-on audio indication fix. This is a traceable example of continued instrument ecosystem development rather than a new total addressable market estimate. Customers operating factory test stations should check software compatibility, instrument model and site acceptance procedure before performing a production update. Source - 14 September 2026 Field software
The Kaelus software repository listed iPA version 2.22.4 for supported iPA, iTA and iXA instruments. Maintaining test software helps contractors extend useful hardware life and reduces differences in procedures across technician crews. The dated download does not establish the number of analyzers sold during the period, but it provides evidence that field tools continue to receive product lifecycle attention. Source - 16 June 2026 Cellular infrastructure
Ericsson reported that 5G subscriptions exceeded 3.1 billion globally after 162 million additions in the first quarter of 2026. It also documented growth in standalone-network service offerings and mobile uplink demand. These changes can increase the number and complexity of radio installations that require PIM diagnosis. Subscriber counts remain an adjacent indicator of infrastructure activity, not a substitute for shipments or revenue from specialized test instruments. Source - 17 March 2026 Mobile industry
GSMA issued its Mobile Economy 2026 material describing the global communications ecosystem, network investment and the transition toward more intelligent connectivity services. Its findings support the view that long-term network performance remains a commercial priority across regions. Because the release covers mobile services and wider technology activity, the reported economic contribution is not added to instrument sales or presented as a PIM testing market measurement. Source - 26 February 2025 Technical standard
IEC published edition 3.0 of IEC 62037-1, updating the general rules for measuring passive intermodulation with two transmitting signals. It clarified frequency dependence, swept measurements, test-power constraints and reporting of maximum observed results. Equipment builders and test laboratories can use the revision when specifying new acceptance procedures. The standard does not establish a lifetime reliability guarantee or a mandatory replacement date for existing instruments. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2020–2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| Historical Period | 2020–2024 |
| Market Size 2025 | USD 887.4 million |
| Market Size 2026 | USD 931.9 million |
| Market Size 2034 | USD 1,378.5 million |
| Growth Rate | CAGR 5.0% |
| Largest Region | Asia Pacific (~38% share) |
| By Type | Low Frequency Band (400MHz–6GHz) · High Frequency Band (Millimeter Wave) |
| By Application | Wireless Communication Base Station · Satellite Communication · In-vehicle Communication · Aerospace · Others |
| By End User | Telecommunication Companies · Satellite Service Providers · Aerospace & Defense Organizations · Automotive Manufacturers · Research & Testing Laboratories |
| By Region | Five worldwide regions defined by instrument application and purchasing exposure Asia PacificChina · India · Japan North AmericaUnited States · Canada · Mexico EuropeGermany · United Kingdom · France South AmericaBrazil · Argentina · Chile Middle East & AfricaUnited Arab Emirates · Saudi Arabia · South Africa |
| Key Companies Profiled | Anritsu; Kaelus; Rosenberger; Keysight Technologies; VIAVI Solutions; EXFO; Bird Technologies; Commscope; AWT Global (company activity verified to the extent described in the competitive analysis) |
| Customization Scope | Country procurement channels, cell-site acceptance procedures, calibration strategies, satellite RF applications and high-frequency product specifications available on request. |
Frequently Asked Questions
What is the worldwide PIM tester market worth in 2025?
The global market is valued at USD 887.4 million in 2025, covering purpose-built equipment used to detect passive intermodulation in radio-frequency components and systems. It contains field, bench and specialized high-frequency analyzers serving telecommunications, satellite, aerospace and vehicle applications. The figure reflects the instrument revenue boundary and excludes the value of towers, antennas purchased as separate products and telecommunications service subscriptions.
What market value and growth rate are expected by 2034?
PIM test equipment is projected at USD 1,378.5 million in 2034, compared with USD 931.9 million in 2026, indicating a 5.0% compound annual increase during the selected horizon. These values follow the global 2024 and 2032 headline anchors and the extension required by the reporting window. Investment depends on cellular network upkeep, RF component quality checks and the costs of maintaining calibrated technical equipment.
Which geography accounts for the most analyzer spending?
Asia Pacific contributes an estimated ~38% of global PIM instrument sales in the base year, with North America around ~27% and Europe about ~22%. China and India have large network maintenance requirements, while Japan and other Asian markets support demanding RF engineering work. These shares characterize instrument purchases and servicing rather than telecommunications subscriber revenue or the number of people using mobile phones.
Why are sub-6GHz PIM instruments commercially dominant?
The low-band 400MHz–6GHz class represents an estimated ~79% of product demand because large existing mobile networks operate across radio bands addressed by portable field analyzers. These units are used to troubleshoot passive faults in antenna feeders and coaxial assemblies. Millimeter-wave measurement is valuable for some advanced systems, but calibration challenges and a smaller installed base keep it more specialist than conventional tower maintenance.
What does a passive intermodulation tester actually measure?
A PIM tester sends controlled radio-frequency tones through an antenna, cable, connector or other passive device and examines unwanted mixing products that reveal nonlinear behavior. An imperfect junction can create a signal that interferes with a receiving channel even though the transmitters themselves work properly. The instrument requires suitable power, frequency planning and a sufficiently low-distortion test setup to produce a meaningful measurement.
Who buys PIM test equipment most often?
Telecommunication companies account for an estimated ~56% of end-user revenue through their networks and outsourced service arrangements. Satellite service providers represent approximately ~15%, aerospace and defense organizations ~12%, automotive manufacturers ~9%, and testing laboratories ~8%. A large operator can buy many tools for a contractor fleet, while specialized laboratories may purchase fewer, more complex measurement configurations for particular high-frequency projects.
Which manufacturers offer identified PIM analyzer products?
Anritsu offers the MW82119B PIM Master for portable site testing, Kaelus markets iPA and iXA analyzer ranges and bench systems, and Rosenberger supplies dedicated desktop test equipment. Other communications measurement companies participate in adjacent RF instruments or infrastructure. Buyers should verify a specific available product model and supported frequencies rather than assume that every supplier of spectrum analyzers also sells a dedicated high-power passive intermodulation instrument.
How does IEC 62037 affect commercial testing programs?
IEC 62037-1:2025 establishes general conditions for two-tone passive intermodulation measurement and clarified frequency sweeps, multiport configurations, power handling and report details. Its approach helps laboratories and field teams define repeatable tests with suitable fixtures. It does not guarantee long-term product reliability. Customers still need procedures for environmental wear, technician training, calibration scheduling and the interpretation of intermittent site faults.
Why do network owners sometimes rent instruments rather than purchase them?
The utilization of an analyzer depends on how often an operator commissions sites, investigates interference or inspects components. A shared instrument fleet or a qualified external contractor may be more economical than purchasing a unit for each location. Calibration and repair costs can also be spread across customers using a rental arrangement. This behavior limits direct correspondence between the number of cell towers and annual equipment sales.
What limits the adoption of millimeter-wave PIM testing systems?
High-frequency measurements can require precision connectors, short and carefully characterized RF paths, controlled fixtures and a more complex calibration workflow. A traditional sub-6GHz tower analyzer cannot automatically cover an unrelated millimeter-wave installation. The available application base is also more specialized, spanning selected mobile architectures, advanced aerospace work and research laboratories. Expansion therefore depends on technically justified purchases rather than a blanket upgrade by every cellular maintenance contractor.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF