Key Statistics
Key Takeaways
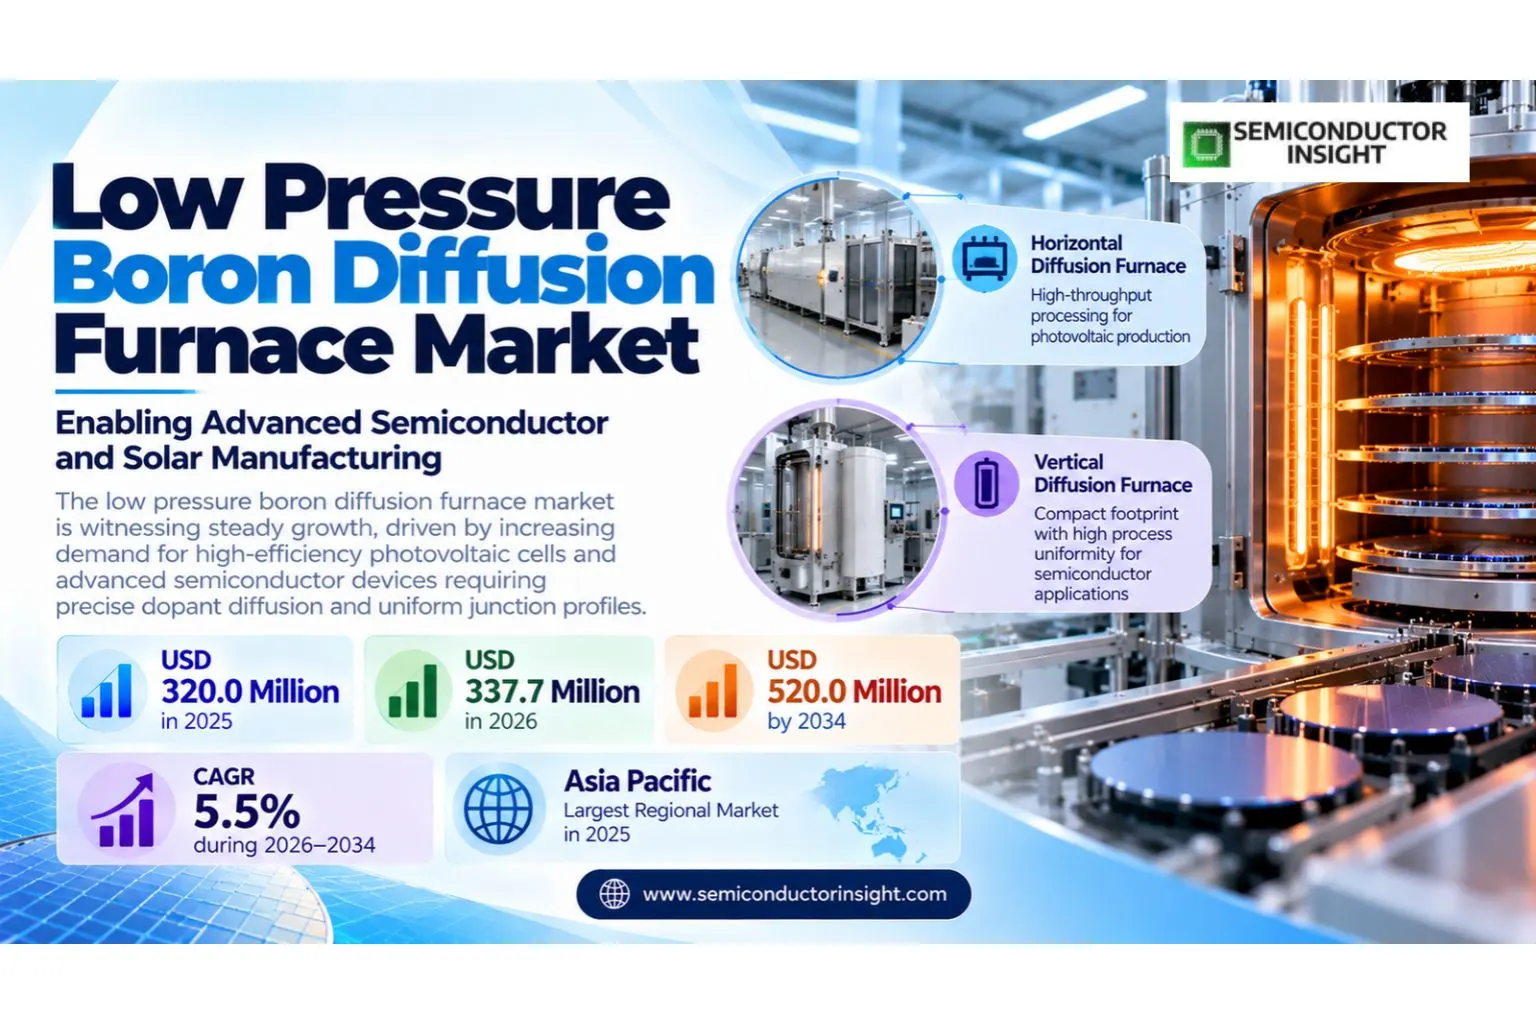
- Low pressure boron diffusion furnace market was valued at USD 320.0 million in 2025 and is projected to reach USD 520.0 million by 2034, representing a 5.5% CAGR over 2026–2034.
- Horizontal batch furnaces remain the dominant configuration in photovoltaic boron diffusion because they provide high wafer throughput and flexible BBr3-based doping across large production lots.
- Photovoltaic and power-device applications provide the strongest demand because p-type and selective boron doping are central to high-efficiency cell architectures and silicon power devices.
- Asia Pacific leads through solar-cell manufacturing in China and semiconductor or power-device capacity across China, Japan, South Korea and Taiwan.
- Process differentiation is moving toward lower pressure, tighter temperature uniformity and lower dopant cross-contamination as cell architectures and device junction requirements become more precise.
Low Pressure Boron Diffusion Furnace Market Overview
Low pressure boron diffusion furnace market was valued at USD 320.0 million in 2025, is estimated at USD 337.7 million in 2026, and is projected to reach USD 520.0 million by 2034, advancing at a 5.5% CAGR during 2026–2034. Asia Pacific represents the largest regional market in 2025, supported by the concentration of relevant manufacturing, downstream demand and supplier ecosystems.
Low-pressure boron diffusion furnaces introduce boron into silicon at elevated temperature under controlled atmosphere or reduced-pressure conditions. The process is used to form p-type doped regions in semiconductor devices and high-efficiency solar cells, commonly using boron tribromide, diborane or other boron sources.
The market is strongly influenced by photovoltaic technology shifts and specialty semiconductor production. In solar cells, boron diffusion is critical for n-type architectures that require a p+ emitter, while power devices use controlled boron profiles for junction formation. Equipment buyers therefore prioritize temperature uniformity, dopant repeatability, wafer throughput and contamination control.
The commercial structure of the low pressure boron diffusion furnace market is shaped by design qualification, production economics and the interaction between component performance and downstream system requirements. Suppliers that can combine consistent manufacturing, application engineering and supply assurance are better positioned to convert technical eligibility into repeat business. Customer decisions increasingly account for lifecycle continuity, geographic resilience and integration cost, which makes proven process control and ecosystem compatibility as important as nominal product capability.
Segment Analysis: By Type
By type, the Low Pressure Boron Diffusion Furnace market is segmented into Horizontal Diffusion Furnace, Vertical Diffusion Furnace. Horizontal furnaces dominate high-throughput photovoltaic production because multiple quartz tubes can process large batches efficiently. Vertical furnaces are attractive in semiconductor applications where footprint, automation and process uniformity justify more complex wafer handling. Purchasing decisions vary by performance requirement, qualification burden, integration complexity and lifecycle economics, so suppliers compete on application fit rather than on a single technical specification.
| Type | Role in the market | Demand characteristics |
|---|---|---|
| Horizontal Diffusion Furnace | Horizontal Diffusion Furnace addresses a distinct part of the product and process mix. Its commercial position depends on technical fit, manufacturing maturity, integration requirements and customer qualification rather than on headline specifications alone. | Demand is strongest where the segment aligns with established customer designs, predictable supply, and measurable system-level performance. Suppliers that can document repeatability, compatibility and lifecycle support are better placed to defend design wins. |
| Vertical Diffusion Furnace | Vertical Diffusion Furnace addresses a distinct part of the product and process mix. Its commercial position depends on technical fit, manufacturing maturity, integration requirements and customer qualification rather than on headline specifications alone. | Demand is strongest where the segment aligns with established customer designs, predictable supply, and measurable system-level performance. Suppliers that can document repeatability, compatibility and lifecycle support are better placed to defend design wins. |
Segment Analysis: By Wafer Size
By wafer size, the Low Pressure Boron Diffusion Furnace market is segmented into 156–182mm Solar Wafers, 200mm & Below Semiconductor Wafers, 300mm Semiconductor Wafers. Solar furnaces are optimized around current PV wafer formats, while semiconductor furnaces serve 150mm, 200mm and selected 300mm applications. Tool architecture changes materially with wafer handling and boat design. Purchasing decisions vary by performance requirement, qualification burden, integration complexity and lifecycle economics, so suppliers compete on application fit rather than on a single technical specification.
| Wafer Size | Role in the market | Demand characteristics |
|---|---|---|
| 156–182mm Solar Wafers | 156–182mm Solar Wafers represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
| 200mm & Below Semiconductor Wafers | 200mm & Below Semiconductor Wafers represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
| 300mm Semiconductor Wafers | 300mm Semiconductor Wafers represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
Segment Analysis: By Application
By application, the Low Pressure Boron Diffusion Furnace market is segmented into Semiconductor Devices, Photovoltaic Cells, Power Devices, R&D. Photovoltaic cells provide the largest volume opportunity because n-type solar architectures rely on boron-doped emitters. Semiconductor and power-device fabs create smaller but higher-specification demand where junction depth and contamination control are more stringent. Purchasing decisions vary by performance requirement, qualification burden, integration complexity and lifecycle economics, so suppliers compete on application fit rather than on a single technical specification.
| Application | Role in the market | Demand characteristics |
|---|---|---|
| Semiconductor Devices | Semiconductor Devices creates demand when the underlying system requires the market’s core function at production scale. Procurement is normally tied to platform launches, equipment upgrades, capacity expansion or replacement cycles. | Buyers evaluate reliability, qualification time, integration cost and vendor support alongside unit economics. Adoption accelerates when the solution removes a system bottleneck or supports a new performance tier without creating disproportionate redesign risk. |
| Photovoltaic Cells | Photovoltaic Cells creates demand when the underlying system requires the market’s core function at production scale. Procurement is normally tied to platform launches, equipment upgrades, capacity expansion or replacement cycles. | Buyers evaluate reliability, qualification time, integration cost and vendor support alongside unit economics. Adoption accelerates when the solution removes a system bottleneck or supports a new performance tier without creating disproportionate redesign risk. |
| Power Devices | Power Devices creates demand when the underlying system requires the market’s core function at production scale. Procurement is normally tied to platform launches, equipment upgrades, capacity expansion or replacement cycles. | Buyers evaluate reliability, qualification time, integration cost and vendor support alongside unit economics. Adoption accelerates when the solution removes a system bottleneck or supports a new performance tier without creating disproportionate redesign risk. |
| R&D | R&D creates demand when the underlying system requires the market’s core function at production scale. Procurement is normally tied to platform launches, equipment upgrades, capacity expansion or replacement cycles. | Buyers evaluate reliability, qualification time, integration cost and vendor support alongside unit economics. Adoption accelerates when the solution removes a system bottleneck or supports a new performance tier without creating disproportionate redesign risk. |
Segment Analysis: By Heating Configuration
By heating configuration, the Low Pressure Boron Diffusion Furnace market is segmented into Batch Tube, Multi-tube Production System, Compact R&D Furnace. Multi-tube batch systems maximize throughput in production, while compact R&D furnaces offer process flexibility for universities and pilot lines. Single-tube production systems can reduce cross-contamination and simplify maintenance. Purchasing decisions vary by performance requirement, qualification burden, integration complexity and lifecycle economics, so suppliers compete on application fit rather than on a single technical specification.
| Heating Configuration | Role in the market | Demand characteristics |
|---|---|---|
| Batch Tube | Batch Tube represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
| Multi-tube Production System | Multi-tube Production System represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
| Compact R&D Furnace | Compact R&D Furnace represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
Regional Analysis
Asia Pacific leads the low pressure boron diffusion furnace market in 2025, while regional growth patterns differ according to manufacturing concentration, customer investment cycles, regulation, product mix and supply-chain access. The most important regional distinction is not simply market size; it is the mechanism that converts local investment and end-market demand into qualified purchases.
How does regional demand differ across the low pressure boron diffusion furnace market?
Regional demand for low pressure boron diffusion furnace is structurally uneven because manufacturing assets, design centers, downstream customers and qualification ecosystems are not distributed evenly. Asia Pacific typically has the deepest electronics manufacturing base, North America combines technology development with capital investment, Europe emphasizes reliability and industrial requirements, and emerging regions are more dependent on imported systems. These differences influence vendor selection, inventory policy, service expectations and the pace at which new technologies are adopted.
| Region | Market position | Growth outlook | Demand profile | Supplier-selection gate |
|---|---|---|---|---|
| Asia Pacific | Largest | Strong | Solar and semiconductor manufacturing led | Throughput, uniformity and cost of ownership |
| North America | Specialty and R&D market | Moderate | Power devices, research and pilot production led | Process flexibility and service |
| Europe | Technology and specialty market | Moderate | PV equipment, power devices and R&D led | Efficiency and process control |
| South America | Emerging | Selective | Solar research and specialty processing led | Capital budget and local service |
| Middle East & Africa | Developing | Selective | Solar research and emerging semiconductor led | Technology transfer and service |
Detailed Regional Blocks
Competitive Landscape
Competition in the low pressure boron diffusion furnace market is determined by technical qualification, manufacturing consistency, customer relationships and the ability to support product lifecycles. Price matters, but it rarely overrides reliability, integration effort or switching cost once a supplier has been designed into a production platform.
The competitive field includes Centrotherm, NAURA, Han’s PV, Laplace, Songyu Technology, Ideal Deposition, alongside other specialized suppliers. Market share can shift when a vendor gains access to a new platform, expands qualified capacity or introduces a technology that materially improves system performance. Because customer validation can be lengthy, incumbent suppliers often benefit from continuity, while challengers need a clear technical or supply-chain advantage to displace an approved source.
Competitive strategy is increasingly multi-dimensional. Leading suppliers invest in process or product development, application engineering and regional support at the same time, while customers seek second-source options where technically feasible. This creates a market in which differentiation is sustained through documented performance, manufacturing yield, quality systems, responsiveness and the ability to support future roadmap transitions without forcing unnecessary redesigns.
| Company | Competitive position | Primary basis of competition |
|---|---|---|
| Centrotherm | Established global / strategic supplier | Competes through product capability, qualification, account access and supply execution. |
| NAURA | Established global / strategic supplier | Competes through product capability, qualification, account access and supply execution. |
| Han’s PV | Established global / strategic supplier | Competes through product capability, qualification, account access and supply execution. |
| Laplace | Specialist / regional competitor | Competes through product capability, qualification, account access and supply execution. |
| Songyu Technology | Specialist / regional competitor | Competes through product capability, qualification, account access and supply execution. |
| Ideal Deposition | Specialist / regional competitor | Competes through product capability, qualification, account access and supply execution. |
| Lam Research | Focused challenger / niche participant | Competes through product capability, qualification, account access and supply execution. |
| CETC | Focused challenger / niche participant | Competes through product capability, qualification, account access and supply execution. |
| ASM International | Focused challenger / niche participant | Competes through product capability, qualification, account access and supply execution. |
| SVCS | Focused challenger / niche participant | Competes through product capability, qualification, account access and supply execution. |
Production Capacity Analysis
Diffusion-furnace capacity is determined by quartz tube count, wafer boat loading, temperature uniformity, gas-delivery architecture and clean process uptime. Multi-tube horizontal systems can process very large wafer volumes, while vertical and R&D tools prioritize automation or flexibility.
China has the largest growth opportunity because of solar manufacturing scale, while Europe and Japan retain specialized equipment expertise. Qualified capacity depends on process repeatability and contamination performance rather than furnace count alone.
Capacity should therefore be evaluated on a qualified-output basis rather than as nominal installed capability. A supplier may possess equipment or production lines that appear suitable but still require customer-specific validation, process tuning, test correlation or upstream material qualification. This distinction becomes especially important during demand spikes, when headline capacity can overstate the volume that is immediately available for a particular application, technology generation or reliability class.
Market Dynamics
The low pressure boron diffusion furnace market is being shaped by rising performance requirements and technology transitions on the demand side, while qualification complexity, supply concentration and cost discipline constrain the pace of adoption. The balance of these forces favors suppliers that can solve a measurable system problem without increasing integration risk.
Demand expansion is not uniform across all product variants or customer groups. New technology creates attractive design opportunities, but buyers typically require a clear economic or performance case before changing a qualified architecture. At the same time, supply-chain localization, capacity investment and tighter quality requirements are changing procurement behavior. As a result, growth is likely to concentrate around applications where performance upgrades, manufacturing scale and lifecycle value reinforce one another.
Market Drivers
Four forces provide the strongest support for demand in the low pressure boron diffusion furnace market: performance-driven technology upgrades, expansion of relevant downstream applications, investment in manufacturing or infrastructure, and the need for more resilient supply. Their importance varies by segment, but each creates a direct reason for customers to qualify or purchase additional solutions.
| Driver | Impact | Commercial mechanism |
|---|---|---|
| N-type solar cells require boron emitters | High | High-efficiency TOPCon and related architectures increase boron diffusion demand. |
| Power devices need precise p-type junctions | High | Silicon power semiconductors use boron profiles to control breakdown and conduction behavior. |
| Batch processing lowers cost per wafer | Medium-High | Large furnace loads can spread thermal-cycle and gas costs across many wafers. |
| Lower-pressure control can improve process uniformity | Medium-High | Reduced-pressure operation can improve gas transport and help control dopant profiles across dense wafer loads. |
N-type solar cells require boron emitters
High-efficiency TOPCon and related architectures increase boron diffusion demand. The commercial effect is strongest where customers can link the technology change to higher throughput, lower power, improved reliability, reduced lifecycle cost or access to a new end-market requirement.
Power devices need precise p-type junctions
Silicon power semiconductors use boron profiles to control breakdown and conduction behavior. The commercial effect is strongest where customers can link the technology change to higher throughput, lower power, improved reliability, reduced lifecycle cost or access to a new end-market requirement.
Batch processing lowers cost per wafer
Large furnace loads can spread thermal-cycle and gas costs across many wafers. The commercial effect is strongest where customers can link the technology change to higher throughput, lower power, improved reliability, reduced lifecycle cost or access to a new end-market requirement.
Lower-pressure control can improve process uniformity
Reduced-pressure operation can improve gas transport and help control dopant profiles across dense wafer loads. The commercial effect is strongest where customers can link the technology change to higher throughput, lower power, improved reliability, reduced lifecycle cost or access to a new end-market requirement.
Market Restraints
Growth is moderated by qualification burden, cyclical purchasing, technology substitution and supply-chain risk. These restraints do not eliminate demand, but they can extend sales cycles, limit supplier switching and reduce the speed at which technically superior solutions convert into production revenue.
| Restraint | Impact | Commercial consequence |
|---|---|---|
| Boron precursors require careful safety management | High | BBr3 and diborane systems require dedicated gas or liquid delivery, scrubbing and maintenance. |
| Thermal diffusion competes with ion implantation | High | Some semiconductor junctions are formed more flexibly by implant and rapid thermal anneal. |
| Solar technology can shift rapidly | Medium | New cell architectures can change required diffusion recipes or reduce demand for a specific furnace configuration. |
| Quartzware and contamination control add maintenance cost | Medium | Deposits and dopant memory can require cleaning, tube replacement and strict process segregation. |
Boron precursors require careful safety management
BBr3 and diborane systems require dedicated gas or liquid delivery, scrubbing and maintenance. Suppliers can mitigate part of this pressure through stronger qualification support, transparent lifecycle planning, dual-source strategies and better alignment between product roadmaps and customer production schedules.
Thermal diffusion competes with ion implantation
Some semiconductor junctions are formed more flexibly by implant and rapid thermal anneal. Suppliers can mitigate part of this pressure through stronger qualification support, transparent lifecycle planning, dual-source strategies and better alignment between product roadmaps and customer production schedules.
Solar technology can shift rapidly
New cell architectures can change required diffusion recipes or reduce demand for a specific furnace configuration. Suppliers can mitigate part of this pressure through stronger qualification support, transparent lifecycle planning, dual-source strategies and better alignment between product roadmaps and customer production schedules.
Quartzware and contamination control add maintenance cost
Deposits and dopant memory can require cleaning, tube replacement and strict process segregation. Suppliers can mitigate part of this pressure through stronger qualification support, transparent lifecycle planning, dual-source strategies and better alignment between product roadmaps and customer production schedules.
Market Opportunities
The most attractive opportunities in the low pressure boron diffusion furnace market occur where a technology transition creates measurable value and where suppliers can enter before the customer architecture is locked. Early engagement, application-specific engineering and credible supply planning can convert these windows into durable design positions.
High-efficiency n-type solar expansion
Boron emitter formation remains central to many leading commercial cell architectures. The opportunity is strongest for suppliers that can demonstrate performance with production-relevant data, provide engineering support during qualification and maintain a roadmap that gives customers confidence in long-term availability.
Selective and low-pressure diffusion
Improved dopant control can support higher cell efficiency and reduced recombination. The opportunity is strongest for suppliers that can demonstrate performance with production-relevant data, provide engineering support during qualification and maintain a roadmap that gives customers confidence in long-term availability.
Power semiconductor localization
Regional investments in IGBT, diode and specialty silicon devices can create new furnace demand. The opportunity is strongest for suppliers that can demonstrate performance with production-relevant data, provide engineering support during qualification and maintain a roadmap that gives customers confidence in long-term availability.
Compact R&D platforms
Universities and pilot fabs need flexible systems supporting multiple boron sources and thermal processes. The opportunity is strongest for suppliers that can demonstrate performance with production-relevant data, provide engineering support during qualification and maintain a roadmap that gives customers confidence in long-term availability.
Supply Chain Analysis
Quartzware and heating elements
High-purity tubes, boats and resistance heaters create the thermal process environment. Value capture at this stage depends on quality consistency, technical differentiation and the difficulty of substitution. Bottlenecks can propagate downstream when qualification or material compatibility prevents customers from shifting quickly to an alternative supplier.
Boron precursor delivery
BBr3, B2H6 or solid boron sources require controlled delivery, carrier gas and safety systems. Value capture at this stage depends on quality consistency, technical differentiation and the difficulty of substitution. Bottlenecks can propagate downstream when qualification or material compatibility prevents customers from shifting quickly to an alternative supplier.
Diffusion furnace integration
Equipment vendors combine temperature control, automation, exhaust and process recipes into production systems. Value capture at this stage depends on quality consistency, technical differentiation and the difficulty of substitution. Bottlenecks can propagate downstream when qualification or material compatibility prevents customers from shifting quickly to an alternative supplier.
Solar and semiconductor processing
Customers form p-type emitters or junctions before downstream passivation, metallization or device fabrication. Value capture at this stage depends on quality consistency, technical differentiation and the difficulty of substitution. Bottlenecks can propagate downstream when qualification or material compatibility prevents customers from shifting quickly to an alternative supplier.
Recent Developments
Recent developments show how technology roadmaps, manufacturing investment and standards are changing the competitive requirements of the low pressure boron diffusion furnace market. The entries below are selected for their direct relevance to product capability, capacity, qualification or downstream adoption rather than for general corporate activity.
SVCS continues to offer horizontal batch diffusion furnaces for phosphorus and boron doping using POCl3 and BBr3, with up to five independently operated stacked quartz tubes for production and pilot use. Source
SVCS’ compact tabletop furnace supports boron doping using BBr3, B2H6 and BN sources together with annealing, oxidation and LPCVD, illustrating the flexibility required by R&D and pilot fabs. Source
Solar-cell manufacturers continue shifting toward n-type architectures, sustaining demand for controlled boron emitter formation in high-throughput batch diffusion equipment. Source
Report Scope & Segmentation
| Report attribute | Coverage |
|---|---|
| Market | Low Pressure Boron Diffusion Furnace |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| 2025 Market Size | USD 320.0 million |
| 2026 Estimated Size | USD 337.7 million |
| 2034 Forecast Size | USD 520.0 million |
| CAGR (2026–2034) | 5.5% |
| Largest Market in 2025 | Asia Pacific |
| By Type | Horizontal Diffusion Furnace, Vertical Diffusion Furnace |
| By Application | Semiconductor Devices, Photovoltaic Cells, Power Devices, R&D |
| By Wafer Size | 156–182mm Solar Wafers, 200mm & Below Semiconductor Wafers, 300mm Semiconductor Wafers |
| By Heating Configuration | Batch Tube, Multi-tube Production System, Compact R&D Furnace |
| Companies Profiled | Centrotherm, NAURA, Han’s PV, Laplace, Songyu Technology, Ideal Deposition, Lam Research, CETC, ASM International, SVCS |
Frequently Asked Questions
What was the low pressure boron diffusion furnace market size in 2025?
The global low pressure boron diffusion furnace market was valued at USD 320.0 million in 2025. The 2025 value is the base-year reference used throughout this overview and provides the starting point for comparing the 2026 estimate and the 2034 forecast.
What is the projected low pressure boron diffusion furnace market size in 2034?
The global market is projected to reach USD 520.0 million by 2034. The forecast reflects the interaction of downstream adoption, technology transitions, production investment and the qualification requirements that shape commercial conversion across the market.
What is the CAGR of the low pressure boron diffusion furnace market from 2026 to 2034?
The low pressure boron diffusion furnace market is expected to expand at a 5.5% CAGR during 2026–2034. Growth will not be uniform across every product or region because customer qualification, capital cycles, supply constraints and application-specific performance requirements differ materially.
Which region is the largest low pressure boron diffusion furnace market?
Asia Pacific is the largest regional market in 2025. Its position is supported by the concentration of relevant manufacturing, customers, technology ecosystems and downstream demand, although the precise commercial mechanism differs by country and application.
How is the low pressure boron diffusion furnace market segmented by type?
By type, the market is segmented into Horizontal Diffusion Furnace, Vertical Diffusion Furnace. These categories address different performance, cost and integration requirements, so supplier selection depends on application fit, qualification history and lifecycle economics rather than a single specification.
What are the main applications for low pressure boron diffusion furnace?
By application, the market covers Semiconductor Devices, Photovoltaic Cells, Power Devices, R&D. Demand in each application is linked to platform launches, capacity expansion, equipment replacement and the degree to which the technology improves system performance or manufacturing economics.
What are the principal growth drivers for the low pressure boron diffusion furnace market?
Key drivers include n-type solar cells require boron emitters and power devices need precise p-type junctions. These forces increase demand when customers can translate technical improvements into higher performance, lower cost, greater reliability or access to new applications.
What are the main restraints in the low pressure boron diffusion furnace market?
Important restraints include boron precursors require careful safety management and thermal diffusion competes with ion implantation. The resulting qualification burden, purchasing cyclicality and technology risk can extend sales cycles and limit rapid supplier substitution even when new solutions offer clear technical advantages.
Which companies participate in the low pressure boron diffusion furnace market?
Companies profiled in this market include Centrotherm, NAURA, Han’s PV, Laplace, Songyu Technology, Ideal Deposition, Lam Research, CETC. Competition centers on qualification, product or process performance, manufacturing consistency, customer support and the ability to maintain supply across the required product lifecycle.
What should buyers evaluate when selecting a low pressure boron diffusion furnace supplier?
Buyers should evaluate demonstrated performance, qualification history, manufacturing consistency, lifecycle support, supply resilience and integration cost. A technically strong product can still face adoption barriers if it increases redesign risk, lacks regional support or cannot meet the customer’s production and quality requirements.
Research Sources & Evidence Base
View research sources used for this overview.
- SVCS Process Innovation. Equipment for Solar Cell Production — Horizontal batch boron diffusion furnace architecture and production configuration.
- SVCS Process Innovation. Compact Tabletop Furnace — BBr3, B2H6 and BN boron doping capability for R&D and pilot processing.
- SVCS Process Innovation. Solar Cell Production Furnace Brochure — Batch diffusion process sequence, carrier gas and multi-tube production configuration.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF