SEMICONDUCTOR INSIGHT
MARKET RESEARCH REPORT

KVM over IP Market

2026 to 2034
MARKET INTELLIGENCE
ACROSS KEY REGIONS
2026 EDITION
COMMUNICATION SYSTEMS Semiconductor Market Research

KVM over IP Market

Trends, Business Strategies 2026-2034

◷
UPDATED 16 September 2026
▤
REPORT LENGTH Detailed Report
▣
REPORT CODE 5e89be4f1e32
▯
FORMATS PDF

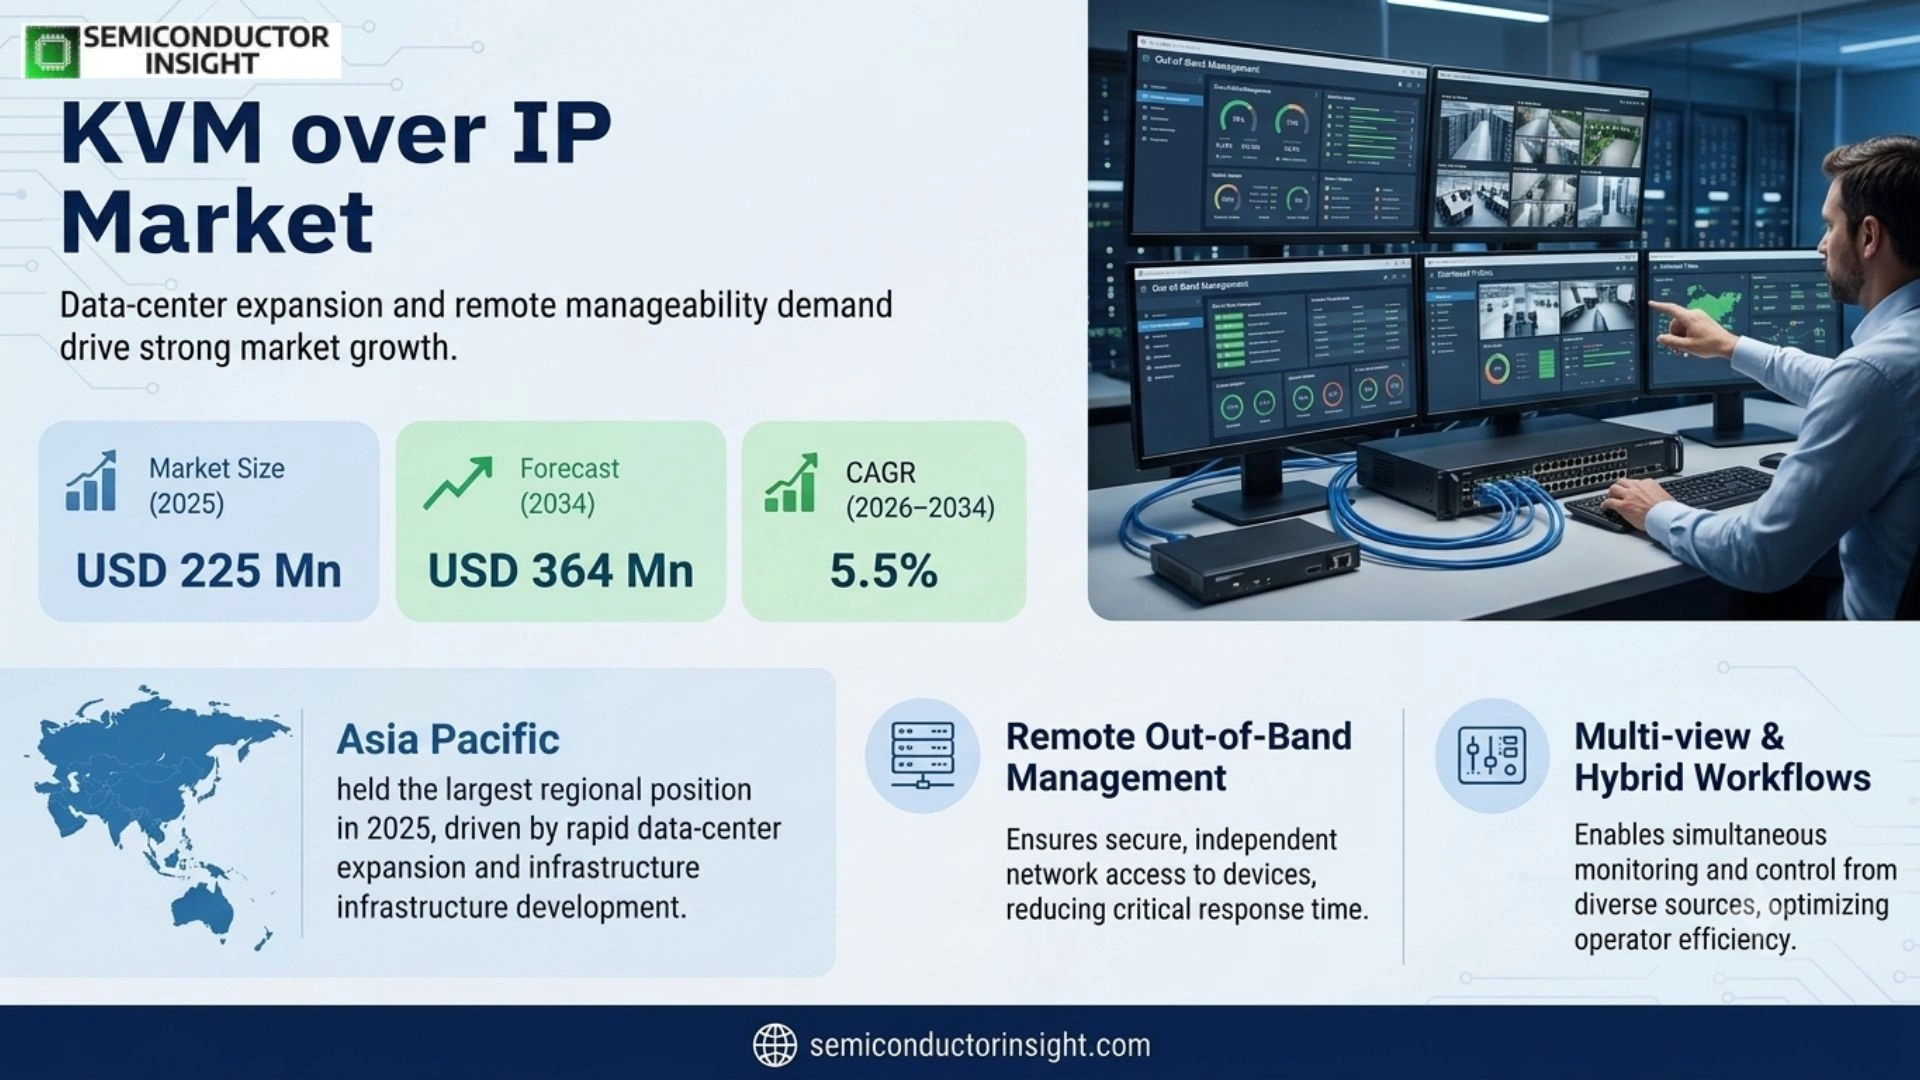
KVM over IP Market is increases to an estimated USD 237 million in 2026, and is projected to reach USD 364 million by 2034, a 5.5% CAGR during 2026–2034.

Get the sample PDF with study scope, segmentation and methodology details.

Key Statistics

2025 Market Size
USD 225 million
2034 Projected Market Size
USD 364 million
CAGR (2026–2034)
5.5%
Largest Market in 2025
Asia Pacific

Key Takeaways

  • High-End KVM over IP is the leading type on the source page, accounting for more than 45% of the market because large data centers, control rooms and regulated organizations pay for multi-user access, encryption, redundancy, high-resolution video and centralized policy management.
  • Internet-related Industry is the largest application, reflecting cloud, hosting and data-center environments where administrators need BIOS-level access even when an operating system, production network or software management layer is unavailable.
  • Asia Pacific is used as the largest region because the source page’s trend section and FAQ both identify it as the leader with more than 35% share; a contradictory North America leadership paragraph is separately flagged for human review.
  • Security is becoming a qualification gate. Current vendor roadmaps emphasize FIPS-oriented cryptography, TLS, fine-grained access, auditability and separated management networks because KVM provides privileged control below the operating-system layer.
  • Control-room convergence expands the addressable market. Multi-view receivers, virtual-machine access, SDKs and matrix-management software allow KVM systems to serve broadcast, utilities, manufacturing and command centers in addition to traditional server recovery.

KVM over IP Market Overview

KVM over IP market is rebased to USD 225 million in 2025, increases to an estimated USD 237 million in 2026, and is projected to reach USD 364 million by 2034. The source-page size anchors imply a 5.5% CAGR during 2026–2034. Asia Pacific is the largest market in 2025, while current demand is being reshaped by data-center expansion, secure out-of-band management, hybrid infrastructure, multi-view control-room workflows and the need to reduce physical intervention at distributed IT sites.

Base year: 2025 · Estimated year: 2026 · Forecast period: 2026–2034 · Values in USD million unless stated otherwise

KVM over IP systems provide remote keyboard, video and mouse control of physical computers through an IP network at a level that can remain available independently of the target operating system. This distinguishes hardware KVM from ordinary remote-desktop software: administrators can enter BIOS, recover a failed boot, mount virtual media, power-cycle attached infrastructure and troubleshoot equipment even when software services are unavailable.

Demand is linked to the growth and geographic dispersion of digital infrastructure. The International Energy Agency estimated that data centers consumed roughly 460 TWh of electricity in 2024 and expects consumption to exceed 1,000 TWh by 2030, indicating a rapidly expanding installed compute base. KVM demand does not scale one-for-one with servers, but the economic value of reducing on-site interventions rises as racks become denser and operators manage more sites.

Product architecture is moving beyond simple one-to-one remote console sessions. Current platforms combine centralized authentication, session logging, multi-user access, multi-display operation, physical and virtual resource control, API integration and bandwidth management. The purchasing decision is therefore increasingly an infrastructure-management choice involving network design, security policy, workflow software, redundancy and lifecycle support rather than a stand-alone peripheral purchase.

Segment Analysis: By Type

The source page segments the market into Low-End KVM over IP, Mid-Range KVM over IP and High-End KVM over IP. High-end products hold the strongest value position because enterprise and mission-critical customers require concurrent users, large port counts, encryption, audit trails, redundancy and high-resolution workflows that are unnecessary in small branch or laboratory deployments.

Type Technical / commercial role Market position
Low-End KVM over IP Low-end products provide basic remote console access to a small number of systems for branch offices, laboratories and small server rooms. Buyers prioritize low acquisition cost, browser accessibility, simple installation and compatibility with common server video and USB interfaces. These products face the strongest substitution from embedded server-management controllers and software remote-access tools because the core requirement is occasional recovery rather than continuous operational control. Large addressable installed base but comparatively intense price competition. Vendors defend share through reliability, installation simplicity, broad hardware compatibility and compact form factors. Growth is supported by distributed IT, but premium feature monetization is limited because small organizations may accept BMC or software tools when they provide adequate recovery access.
Mid-Range KVM over IP Mid-range systems add more ports, simultaneous users, centralized accounts, better video performance and management functions suitable for enterprise server rooms, regional data centers and telecom facilities. They support organizations that want standardized remote administration across several locations without the full matrix switching, redundant network design or formal security certifications associated with flagship platforms. Balanced growth segment. Mid-range products benefit when enterprises replace aging analog KVM or centralize support teams, but buyers remain conscious of rack-level cost. Successful products combine secure web access, practical centralized administration, firmware lifecycle support and enough concurrency to serve multiple technicians without the complexity of a mission-critical command-center architecture.
High-End KVM over IP High-end systems support large deployments, many concurrent users, 4K or multi-display operation, redundant networks or power, detailed access control, encryption, logging and integration with virtual infrastructure. They are specified in hyperscale facilities, government, broadcast, utilities, finance and command centers where remote-management downtime or weak video response can disrupt high-value operations. Leading value segment. The source page assigns more than 45% share to this type, while current ATEN and Adder developments emphasize FIPS-oriented security, 4K multi-view operation, SDKs and matrix-management software. Supplier selection is therefore based on security, resilience, workflow productivity and proven enterprise support rather than on port count alone.

Secondary segmentation: By End User

The source page also divides demand among Large Enterprises, SMBs and Government Organizations. The same remote-console technology serves all three groups, but budget, security review, staff structure and lifecycle requirements differ materially, creating distinct product and channel strategies. The commercial implication is that supplier selection depends on proven performance, lifecycle support, qualification evidence and the ability to maintain consistent service as the installed infrastructure expands over the forecast period.
End user Commercial characteristics
Large Enterprises Large enterprises operate many racks, sites and administrator teams, so centralized identity, fleet management, concurrent access, firmware policy and auditability become important. They are also more likely to integrate KVM with data-center management, incident-response or control-room software. Procurement therefore considers software usability, support coverage and lifecycle management alongside hardware specifications.
SMBs Small and medium-sized businesses use KVM over IP to avoid unnecessary travel to server rooms and to recover critical systems without keeping specialist staff on site. Port counts are lower and budgets tighter, increasing substitution from server BMCs and software tools. Compact appliances with simple browser access and low administrative overhead are the most commercially relevant.
Government Organizations Government and defense-related users place heavier emphasis on strong cryptography, access separation, audit logs, controlled firmware updates and long product lifecycles. Sales cycles are longer because cybersecurity review and procurement approval accompany technical evaluation, but successful qualification can produce durable installed-base revenue and relatively high switching costs.

Secondary segmentation: By Security Level

The page segments security into Standard Security, High Security and Military-Grade Security. These categories should be understood through actual control requirements-encryption, authentication, session logging, network separation, firmware trust and validated cryptography-rather than as generic marketing tiers. For buyers, this means the headline market trend must be translated into the exact operating environment, required measurement or access function, security conditions and support model before a purchasing decision is made.

Security level Demand profile
Standard Security General enterprise environments require encrypted sessions, user authentication and routine permissions but may not need formally validated cryptographic modules. This tier fits corporate server rooms where the KVM network is already isolated and protected. Competition is broad, so ease of deployment, compatibility and support can matter as much as the specific encryption implementation.
High Security Financial services, utilities and critical infrastructure require detailed logs, stronger authentication, role-based control and hardened firmware because a KVM channel provides privileged console access. Vendors must demonstrate secure update practices and integration with enterprise identity systems. Product qualification becomes a lifecycle security assessment rather than a one-time feature comparison.
Military-Grade Security Defense and highly sensitive government users may demand validated cryptography, strict separation, controlled configuration and procurement standards. Volumes are smaller than general enterprise, but approved platforms can remain deployed for long lifecycles. Vendor reputation, supply assurance and vulnerability response are therefore central to winning and retaining these programs.

Secondary segmentation: By Deployment

The page also lists On-premise, Cloud-based and Hybrid deployment. Hardware console access remains physically attached to target systems, but policy, identity, visibility and orchestration can be managed locally, through cloud-assisted services or through a hybrid control model. This mechanism matters commercially because the same underlying technology can produce very different revenue and margin outcomes depending on customer qualification, application criticality, regional service availability and the cost of system downtime.

Deployment Commercial characteristics
On-premise On-premise management remains common in data centers, government and regulated facilities because administrators want the privileged control plane to remain inside a private network. Buyers value redundant local appliances, independent management VLANs and integration with existing identity systems, making this approach strongest where availability and direct administrative control outweigh convenience.
Cloud-based Cloud-assisted management can centralize inventory, access policies and remote support across many smaller sites. The model is attractive for distributed enterprises, but customers scrutinize credential security, service availability and the architecture used to bridge cloud control to hardware consoles. Adoption therefore depends on vendor trust and clear separation from production networks.
Hybrid Hybrid designs preserve local console access while exposing selected monitoring, orchestration or identity functions to centralized software. This aligns with broader hybrid infrastructure because it retains an out-of-band fallback while allowing fleet-wide administration. APIs and SDKs increase the value of this approach by connecting KVM actions to established operations tools.

Segment Analysis: By Application

By application, the source page lists Internet-related Industry, Government Agencies, Telecommunications, Financial Services, Education, Manufacturing, Service Providers and Others. Internet-related infrastructure is the largest application because cloud, hosting and data-center operators run dense server fleets continuously and place direct economic value on reducing smart-hands interventions and recovery time. Over the forecast period, that combination favors vendors that connect technical performance with scalable delivery, documented quality and application engineering rather than relying mainly on price competition or isolated product specifications.

Application Demand characteristics
Internet-related Industry Cloud providers, web hosts and data centers operate dense rack environments where an inaccessible operating system can strand valuable compute capacity. KVM provides an independent console path for configuration and recovery. As data-center capacity expands globally, operators have stronger incentives to centralize remote support and reserve physical site visits for hardware replacement rather than routine troubleshooting.
Government Agencies Government systems combine distributed facilities, long equipment lifecycles and strict privileged-access controls. KVM reduces technician travel while maintaining access to physical servers on restricted networks. Buyers value encryption, session records, administrator permissions and product longevity, producing longer sales cycles but relatively sticky deployments once a platform passes security approval.
Telecommunications Telecom operators use KVM at network operations centers, switching facilities and remote infrastructure sites where a device may need recovery without dispatching field technicians. Long product lifecycles, centralized administration and network isolation matter because management traffic must remain reliable without interfering with customer service networks.
Financial Services Banks, exchanges and financial institutions prioritize availability, logging and privileged-access governance. Hardware KVM provides a fallback when software remote access is unavailable, but the channel itself is security-sensitive. Procurement therefore emphasizes encryption, auditability, low latency and integration with enterprise identity policies.
Education Universities and research institutions use remote KVM for laboratories, campus server rooms and specialized computing clusters. Centralized access supports remote experiments and after-hours maintenance, while shared infrastructure improves utilization. Budget constraints make interoperability and manageable lifecycle cost more important than the most advanced matrix features.
Manufacturing Factories and industrial control rooms use KVM to separate operators from computers located near production equipment, inside restricted zones or across noisy environments. Low-latency video, USB peripheral support, uptime and IT/OT separation can matter more than conventional server-management functions, broadening the category into operational control.
Service Providers Managed-service and colocation providers need controlled console access across many customer racks without granting unrestricted production-network access. Multi-user KVM can reduce on-site smart-hands work and document which technician accessed each system, making staff productivity and secure delegation key purchasing mechanisms.
Others Other applications include broadcast, medical imaging, transport, energy and command centers. These environments value pixel quality, multi-display operation, deterministic response and peripheral support because users interact with remote systems continuously rather than only during faults. High-performance matrix vendors can therefore capture premium revenue outside conventional IT administration.

KVM over IP Market Growth

Regional Analysis

The source page contains a material regional inconsistency: its trend section and FAQ identify Asia Pacific as the largest market with more than 35% share, while a later regional narrative states that North America dominates. The repeated quantified Asia-Pacific statement is used for the 2025 leadership card and the contradiction is retained in the reviewer note.

How do infrastructure scale, security requirements and labor economics shape regional KVM demand?

KVM adoption follows both the size of the installed compute estate and the cost of physical intervention. Asia Pacific combines rapid data-center expansion and large manufacturing/control-room estates. North America has deep hyperscale and regulated-enterprise demand. Europe emphasizes secure auditable operations, while South America and the Middle East & Africa gain from cloud, telecom and distributed infrastructure where remote site visits are costly.

Region Position Growth outlook Demand profile What decides supplier selection
Asia Pacific Largest High Data-center and manufacturing-led Price/performance, local support, multi-view capability and security
North America Mature technology market High Hyperscale, enterprise and government-led Security, APIs, redundancy and lifecycle support
Europe Mature Moderate to high Regulated enterprise and industrial-led Auditability, interoperability and data protection
South America Smaller Moderate Cloud, telecom and finance-led Affordability, remote support and channel coverage
Middle East & Africa Emerging High from small base Data-center, government and energy-led Secure remote operation, durability and local service
Asia Pacific LARGEST

Why does Asia Pacific lead KVM over IP demand?

Asia Pacific combines rapid data-center capacity growth with large manufacturing, telecom and enterprise IT estates. The source page places the region above 35% share, while Singapore’s government says the country already hosts more than 1.4 GW of data-center capacity and plans at least 300 MW of additional capacity in the near term.

Market positionLargest
Growth outlookHigh
Demand profileData-center and manufacturing-led
Market access gateLocal support, security and value
Country / subregion Position Demand mechanism
China Large infrastructure base China’s cloud, telecom and manufacturing infrastructure supports rack-management and control-room demand. Domestic vendors intensify price competition, while multinational facilities prioritize standardized security, lifecycle support and compatibility across countries. This creates parallel value and premium tiers rather than a single uniform purchasing pattern.
Singapore Regional data-center hub Singapore’s IMDA says the country has more than 1.4 GW of data-center capacity and over 70 cloud, enterprise and colocation facilities, with a roadmap targeting at least 300 MW of additional near-term capacity. Dense facilities favor centralized remote rack access and reduced technician movement.
Japan & South Korea High-reliability markets Japan and South Korea combine sophisticated electronics, telecom and data-center sectors with high expectations for reliability and lifecycle support. Suppliers compete through high-resolution video, redundant networking, localization and integration with established operations processes rather than basic remote-access functionality alone.

Market instances

  • Singapore’s Green Data Centre Roadmap targets at least 300 MW of additional capacity while the country already operates more than 1.4 GW. Each new facility increases the number of racks requiring management, and higher density raises the value of centralized out-of-band access because operators want to minimize routine physical intervention.
  • ATEN’s recent multi-view KVM receivers support multiple displays and simultaneous video sources, demonstrating how Asia-based suppliers are moving beyond basic rack recovery into mission-critical control rooms. The market implication is higher system value when a single operator workspace can consolidate many physical and virtual resources. The development matters because it changes a verifiable operating requirement or deployment condition and therefore influences supplier qualification, capacity planning, system integration or recurring maintenance demand rather than representing a generic technology trend.
  • ATEN has also emphasized modern cryptography and secure browser access in its DigiKVM platform. That direction is relevant across Asian cloud, government and infrastructure buyers because KVM provides privileged console control, making security qualification a meaningful purchasing gate rather than a secondary feature. The development matters because it changes a verifiable operating requirement or deployment condition and therefore influences supplier qualification, capacity planning, system integration or recurring maintenance demand rather than representing a generic technology trend.

Asia Pacific is not a single price-sensitive market. Singapore, Japan and South Korea reward reliability and advanced workflow features, while China combines hyperscale demand with aggressive local competition. Vendors need regional product tiers and application engineering rather than one standardized sales proposition. The result is a more selective market in which engineering credibility, dependable execution and long-term support create measurable value once a product becomes embedded in a customer’s operating or maintenance workflow.

North America SECURITY & HYPERSCALE

What drives KVM over IP adoption in North America?

North America combines the world’s deepest hyperscale cloud ecosystem with large enterprise, government, financial and colocation estates. KVM creates the most value where remote administrators need a console path that remains available during software failures and where privileged access must be logged, segmented and integrated into broader operations workflows. The commercial implication is that supplier selection depends on proven performance, lifecycle support, qualification evidence and the ability to maintain consistent service as the installed infrastructure expands over the forecast period.

Market positionMature technology market
Growth outlookHigh
Demand profileHyperscale and regulated-enterprise led
Market access gateSecurity, integration and redundancy
Country / subregion Position Demand mechanism
United States Primary regional demand U.S. hyperscalers, colocation operators and large enterprises manage geographically distributed facilities, making remote recovery economically valuable. Security teams also scrutinize privileged access, so KVM vendors must support authentication, logging, network isolation and dependable firmware lifecycle management.
Canada Cloud and regulated-enterprise demand Canada’s large geography increases the cost of dispatching technicians to remote facilities, supporting out-of-band management. Financial, telecom and public-sector users also value secure administration and regional support, giving enterprise-class vendors an advantage over low-cost appliances.
Mexico Manufacturing and cloud expansion Mexico’s manufacturing base and growing cloud infrastructure create KVM demand in plant control rooms and data centers. Multinational facilities often deploy globally standardized platforms selected through corporate cybersecurity and remote-support policies, favoring established vendors with regional channels.

Market instances

  • The International Energy Agency projects global data-center electricity demand to rise sharply through 2030, with the United States among the largest AI infrastructure markets. For KVM suppliers, expanding compute infrastructure increases the value of resilient rack management even when routine administration remains software-driven. The development matters because it changes a verifiable operating requirement or deployment condition and therefore influences supplier qualification, capacity planning, system integration or recurring maintenance demand rather than representing a generic technology trend.
  • Adder’s 2026 ARDx upgrade added multi-head connectivity, an SDK, automated discovery and frame-rate management. The commercial significance is integration: KVM can be embedded into custom operational workflows and managed over constrained networks, raising the value of software and APIs alongside hardware endpoints. The development matters because it changes a verifiable operating requirement or deployment condition and therefore influences supplier qualification, capacity planning, system integration or recurring maintenance demand rather than representing a generic technology trend.
  • Adder’s AIM 6 release strengthened visibility, configuration and access management across IP KVM matrices. These changes address the labor economics of large operations rooms, where smaller teams manage more devices. Software usability and administrator productivity therefore become competitive differentiators alongside video latency and port count. The development matters because it changes a verifiable operating requirement or deployment condition and therefore influences supplier qualification, capacity planning, system integration or recurring maintenance demand rather than representing a generic technology trend.

North American demand rewards suppliers that can integrate KVM into enterprise security and operations software. Hardware quality remains essential, but APIs, audit trails, support response and lifecycle management increasingly determine whether a platform can be standardized across many sites. For buyers, this means the headline market trend must be translated into the exact operating environment, required measurement or access function, security conditions and support model before a purchasing decision is made.

Europe REGULATED OPERATIONS

Why does Europe favor secure and auditable KVM systems?

Europe’s demand is shaped by mature enterprise IT, broadcast and industrial control-room use together with strong data-protection and infrastructure-efficiency expectations. The operating environment favors tools that centralize access, document administrator activity and support efficient remote troubleshooting without compromising privileged-network separation. This mechanism matters commercially because the same underlying technology can produce very different revenue and margin outcomes depending on customer qualification, application criticality, regional service availability and the cost of system downtime.

Market positionMature
Growth outlookModerate to high
Demand profileRegulated enterprise and industrial-led
Market access gateAuditability, standards and interoperability
Country / subregion Position Demand mechanism
Germany Industrial and data-center center Germany’s manufacturing, finance and data-center sectors create demand for rack-management and industrial KVM. Buyers emphasize availability, lifecycle support and compliance because remote-console systems can sit inside sensitive operational environments where integration with IT/OT architectures matters more than lowest hardware price.
United Kingdom Broadcast and enterprise hub The UK has strong broadcast, media and financial-services demand where high-resolution, low-latency KVM matrices support operator workflows as well as server administration. High-performance video and multi-display support are important when users interact continuously rather than only during recovery events.
France & Nordics Cloud and infrastructure market France and Nordic countries combine cloud, telecom and industrial digitalization with growing attention to data-center efficiency. KVM can reduce unnecessary physical access while procurement increasingly evaluates endpoint power, cybersecurity and compatibility with enterprise authentication and monitoring systems.

Market instances

  • The European Commission established an EU-wide data-center sustainability reporting framework in 2024, increasing operational visibility across facilities. Although the framework does not mandate KVM, the broader management culture rewards tools that centralize access, logging and troubleshooting while reducing unnecessary site visits and operational overhead. The development matters because it changes a verifiable operating requirement or deployment condition and therefore influences supplier qualification, capacity planning, system integration or recurring maintenance demand rather than representing a generic technology trend.
  • Adder’s ARDx platform was launched from the United Kingdom for secure, low-latency KVM and audio over LAN or WAN. The architecture is relevant to European broadcast and industrial users because it preserves access independently of the target operating system while supporting remote workspaces and long-distance operational workflows. The development matters because it changes a verifiable operating requirement or deployment condition and therefore influences supplier qualification, capacity planning, system integration or recurring maintenance demand rather than representing a generic technology trend.
  • Adder’s ZeroU IP KVM developments emphasize rack density, network configuration and diagnostics. This shows that mature European demand is not merely replacing analog KVM; customers are optimizing space, administration and resilience in control rooms, broadcast facilities and technical operations. The development matters because it changes a verifiable operating requirement or deployment condition and therefore influences supplier qualification, capacity planning, system integration or recurring maintenance demand rather than representing a generic technology trend.

European sales depend on trust, standards and long-term support. Vendors that document cybersecurity practices, provide strong audit functions and integrate with existing operational software are better positioned than suppliers relying on hardware specifications alone. Over the forecast period, that combination favors vendors that connect technical performance with scalable delivery, documented quality and application engineering rather than relying mainly on price competition or isolated product specifications.

South America CLOUD & TELECOM GROWTH

Where is the strongest KVM opportunity in South America?

South American demand is concentrated in Brazil and other major telecom, financial and cloud centers where distributed infrastructure makes on-site support expensive. Buyers are generally more price-sensitive than North American or Western European customers, favoring mid-range systems that provide secure browser access and centralized management without premium control-room complexity. The result is a more selective market in which engineering credibility, dependable execution and long-term support create measurable value once a product becomes embedded in a customer’s operating or maintenance workflow.

Market positionSmaller
Growth outlookModerate
Demand profileCloud, telecom and finance-led
Market access gateAffordability, channel reach and support
Country / subregion Position Demand mechanism
Brazil Largest regional opportunity Brazil’s cloud, telecom, banking and digital-service sectors create the region’s largest installed server base. Remote KVM reduces technician travel and helps centralize support. Local-language service, import cost and channel availability influence product choice alongside enterprise security requirements.
Chile Data-center and mining operations Chile combines cloud and data-center activity with geographically dispersed mining and industrial infrastructure. KVM can support remote server rooms and control environments where travel is costly, while buyers value manageable bandwidth and reliable regional distributor support.
Argentina & Rest of Region Selective enterprise demand Macroeconomic volatility can constrain capital spending, but finance, telecom and large enterprises still require remote infrastructure management. Procurement often favors proven systems with long product life and local service rather than frequent technology refreshes.

Market instances

  • Microsoft announced a multibillion-real cloud and AI infrastructure investment in Brazil in 2024. That scale of digital buildout increases the number of racks and critical systems operations teams must manage, creating an indirect but defensible demand mechanism for out-of-band recovery and centralized console access. The development matters because it changes a verifiable operating requirement or deployment condition and therefore influences supplier qualification, capacity planning, system integration or recurring maintenance demand rather than representing a generic technology trend.
  • The economic value of KVM is particularly clear in geographically distributed South American operations because a remote console can substitute for travel when a server will not boot or a management network is unavailable. Reliable mid-range systems therefore have a strong productivity-based value proposition. The development matters because it changes a verifiable operating requirement or deployment condition and therefore influences supplier qualification, capacity planning, system integration or recurring maintenance demand rather than representing a generic technology trend.
  • Banks, telecom operators and cloud facilities also face cybersecurity requirements that make consumer-grade remote desktop unsuitable for privileged infrastructure tasks. KVM vendors can differentiate through isolated management networks, encrypted browser sessions and auditable access, while local distributors reduce procurement and replacement friction. The development matters because it changes a verifiable operating requirement or deployment condition and therefore influences supplier qualification, capacity planning, system integration or recurring maintenance demand rather than representing a generic technology trend.

South America is best served through strong local channels and a value-engineered portfolio. The opportunity is not to sell the most complex KVM everywhere, but to match secure recovery and centralized management to customers whose alternative is expensive on-site intervention. The commercial implication is that supplier selection depends on proven performance, lifecycle support, qualification evidence and the ability to maintain consistent service as the installed infrastructure expands over the forecast period.

Middle East & Africa FAST INFRASTRUCTURE BUILDOUT

Why is the Middle East & Africa becoming more relevant for KVM over IP?

Gulf countries are building cloud and AI infrastructure rapidly, while energy, government and industrial sites across the wider region are geographically dispersed. KVM allows central operations teams to manage critical physical systems remotely, reducing routine travel while preserving an independent console path for recovery and maintenance. For buyers, this means the headline market trend must be translated into the exact operating environment, required measurement or access function, security conditions and support model before a purchasing decision is made.

Market positionEmerging
Growth outlookHigh from small base
Demand profileData-center, government and energy-led
Market access gateSecurity, environmental robustness and service
Country / subregion Position Demand mechanism
UAE AI and cloud hub Large cloud and AI investments increase the number of managed racks and government workloads in local facilities. Secure remote management is valuable because operators want centralized control without exposing privileged console traffic, while data sovereignty increases the importance of locally managed infrastructure.
Saudi Arabia Digital infrastructure expansion Saudi investment in cloud, data centers and smart infrastructure creates server estates across public and commercial sectors. Suppliers need local service capability and strong cybersecurity credentials to win government and critical-infrastructure projects with long procurement cycles.
South Africa & Wider Africa Distributed enterprise and telecom demand South Africa has a mature enterprise and data-center base, while other African markets rely more heavily on telecom and distributed IT. Remote console tools reduce costly travel to branch sites, but network quality, power conditions and limited specialist support make ruggedness and simple administration important.

Market instances

  • Microsoft has outlined multiyear UAE investments including substantial data-center capital expenditure through 2029. The expansion materially increases regional compute infrastructure and the number of systems requiring secure remote operations, creating demand for KVM where administrators need hardware-level access during software or network failures. The development matters because it changes a verifiable operating requirement or deployment condition and therefore influences supplier qualification, capacity planning, system integration or recurring maintenance demand rather than representing a generic technology trend.
  • Microsoft and G42 announced a major UAE data-center capacity expansion expected to begin coming online during 2026. Large clustered facilities strengthen the value of centralized out-of-band management because thousands of servers can be operated by smaller teams while physical access is reserved for hardware replacement. The development matters because it changes a verifiable operating requirement or deployment condition and therefore influences supplier qualification, capacity planning, system integration or recurring maintenance demand rather than representing a generic technology trend.
  • Outside Gulf hyperscale facilities, energy and telecom sites across Africa can be remote and difficult to staff continuously. KVM over IP can prevent technician travel for simple recovery tasks, so products that balance secure access with tolerance for variable bandwidth and field conditions have a distinct regional value proposition. The development matters because it changes a verifiable operating requirement or deployment condition and therefore influences supplier qualification, capacity planning, system integration or recurring maintenance demand rather than representing a generic technology trend.

MEA contains two different KVM markets: Gulf data centers and government facilities support premium secure platforms, while African telecom and branch environments need robust, cost-effective remote access. Vendors should separate these propositions rather than treat the region as one homogeneous emerging market. This mechanism matters commercially because the same underlying technology can produce very different revenue and margin outcomes depending on customer qualification, application criticality, regional service availability and the cost of system downtime.

Competitive Landscape

Competition is concentrated among dedicated enterprise KVM and matrix suppliers at the premium end, while lower-cost appliances and adjacent infrastructure products fragment the entry level. The source page profiles Avocent, Raritan, ATEN, WEYTEC, Belkin, Rose Electronics, Adder Technology and several broader infrastructure vendors; the tiering below separates defensible direct KVM suppliers from adjacent names retained only for report-scope consistency.

Vertiv’s Avocent, Legrand’s Raritan and ATEN compete directly for data-center rack-management deployments where buyers need many ports, multiple users, centralized management and long enterprise support. Their advantage comes from installed base, accessories, recognized product families and experience maintaining compatibility across generations of servers and management software. Over the forecast period, that combination favors vendors that connect technical performance with scalable delivery, documented quality and application engineering rather than relying mainly on price competition or isolated product specifications.

Adder, Guntermann & Drunck, WEYTEC and Rose Electronics are especially relevant in high-performance matrix and control-room applications where low latency, high-resolution video, multi-display operation and workflow software matter more than basic rack-console recovery. These specialists can defend premium pricing by improving operator productivity and allowing systems to be separated physically from user workstations.

Security is becoming a visible basis of differentiation. Buyers increasingly ask how firmware is updated, how credentials are protected, whether sessions can be logged and how management networks are isolated. The source page also names Dell, Lenovo and Schneider Electric, but these are broader infrastructure vendors rather than direct standalone KVM leaders; they are retained in scope but not over-ranked competitively.

Competitive tier Companies Why they matter
Enterprise rack-management leaders Avocent (Vertiv); Raritan (Legrand); ATEN These vendors offer dedicated KVM-over-IP hardware, centralized management, accessories and enterprise support for data-center and server-room deployments. Their advantage rests on recognized product families, long installed histories and the ability to support multi-port, multi-user environments with security controls and lifecycle service across many customer sites.
High-performance matrix specialists Adder Technology; Guntermann & Drunck; WEYTEC; Rose Electronics These companies differentiate in broadcast, command centers, industrial operations and other continuous-interaction workflows. Low latency, high-resolution video, multi-display support and matrix software matter more than basic rack access, enabling specialist suppliers to defend premium positions outside conventional server-administration procurement.
Secure / regional / channel participants Belkin; Black Box (AGC Networks); Shenzhen KinAn; Hiklife; Reton This group serves secure desktop switching, regional enterprise, channel or cost-sensitive niches. Competitive advantage may come from government-oriented security, local pricing or distributor reach. International expansion depends on meeting enterprise cybersecurity and support expectations while remaining easier or less costly to deploy than flagship matrix platforms.

Companies profiled in the report

The source page profiles Avocent (Vertiv), Raritan (Legrand), ATEN, WEYTEC, Belkin, Rose Electronics, Adder Technology, Dell Technologies, Guntermann & Drunck, Hiklife, Lenovo, Shenzhen KinAn, Black Box (AGC Networks), Schneider Electric and Reton. The full list is preserved for scope consistency even though several organizations are broader infrastructure vendors rather than directly comparable dedicated KVM suppliers.

Production Capacity Analysis

KVM over IP production is constrained less by a single semiconductor technology than by electronics assembly, secure firmware, video-processing engineering, network-interface availability, specialized connectors and final system validation. High-end products also require long lifecycle component management because enterprise customers keep KVM infrastructure deployed for years and expect replacements to remain compatible with established cabling and management software.

Manufacturing combines SoCs or FPGAs for video processing, Ethernet controllers, USB interfaces, memory, power-management devices and sometimes secure elements. A shortage in programmable logic or networking components can disrupt output even when final assembly capacity is available. Vendors with long-term component planning and redesign capability are better positioned to support enterprise deployment schedules.

Firmware and software are effectively part of production capacity because every appliance must ship with tested encryption, browser compatibility, user-management logic and update mechanisms. High-end KVM also requires interoperability testing across server graphics modes, USB peripherals, network switches and matrix software, so engineering validation can constrain ramp more than the number of assembly lines.

Regional channel stock matters because KVM is often deployed during data-center builds or urgent infrastructure refreshes. Customers may need hundreds of switches, dongles, transmitters or receivers at once. Suppliers with distributor inventory, repair capability and migration paths across North America, Europe and Asia can convert availability into a durable competitive advantage.

Market Dynamics

The market is pulled by data-center expansion, remote operations, secure out-of-band management and control-room consolidation, but growth is moderated by server BMC substitution, network dependency, cybersecurity review and premium deployment cost. The strategic question is where dedicated hardware access provides enough resilience or workflow value to justify additional infrastructure beyond software remote administration.

Market Drivers

Driver Directional impact* Commercial mechanism
Data-center expansion High More racks and geographically distributed facilities increase the cost of physical intervention. Rapid global data-center growth supports out-of-band console demand because administrators need a recovery path that remains available before an operating system or software management layer loads.
Secure remote operations High Centralized support teams and hybrid work increase remote privileged access. Hardware KVM can be isolated from production networks and preserve BIOS-level control, making it valuable for regulated environments where software remote-access tools alone are not sufficient.
Control-room consolidation Medium to High Multi-view displays, matrix software and API integration allow fewer operators to monitor more systems from one workspace. This expands KVM beyond rack troubleshooting into broadcast, utilities, transport and manufacturing operations.
Hybrid infrastructure Medium Organizations manage physical servers, appliances, edge systems and virtual resources simultaneously. KVM products that bridge hardware consoles with centralized software management remain relevant as workloads migrate toward cloud and hybrid architectures.

Data-center scale makes remote recovery more valuable

As the global compute estate expands, operators cannot economically rely on physical console access for routine recovery. KVM over IP creates a management path that remains available before the operating system loads, reducing smart-hands interventions and shortening restoration time. The value rises disproportionately in dense facilities where a technician may otherwise travel to a rack for a problem that can be solved remotely.

Privileged-access security supports premium products

Remote console access is powerful because it can bypass the operating system, which also makes the channel security-sensitive. Government, financial and infrastructure buyers therefore require strong encryption, permissions, logs and secure update practices. Compliance-oriented platforms can command higher value because they reduce the risk that remote administration becomes an uncontrolled privileged access path.

Multi-view and API integration expand use cases

Modern KVM platforms support many video sources, virtual resources and software-controlled workflows rather than one console per administrator. This creates demand in broadcast, utilities, transportation and industrial control rooms where productivity comes from consolidating operator workspaces. APIs and SDKs further allow KVM actions to be integrated into incident-management and automation tools.

Hybrid infrastructure preserves hardware-level access

Cloud adoption does not eliminate physical infrastructure. Enterprises still operate network appliances, storage, edge servers and private-cloud equipment that can become inaccessible when software management fails. Hardware KVM provides an independent fallback, while hybrid management can centralize fleets without giving up local resilience. The result is a more selective market in which engineering credibility, dependable execution and long-term support create measurable value once a product becomes embedded in a customer’s operating or maintenance workflow.

Market Restraints

Restraint Directional impact* Commercial mechanism
Server BMC substitution High Modern servers include embedded management controllers that already provide remote console and power functions. Dedicated KVM must justify itself through multi-vendor centralization, independent access, matrix workflows or stronger security rather than basic server recovery alone.
Network dependency and latency Medium IP KVM depends on network reachability and bandwidth. High-resolution multi-display workflows can be sensitive to congestion or long-distance latency, making network design part of the deployment cost.
Premium deployment cost Medium High-end matrix systems require endpoints, management appliances, switching infrastructure and support. Smaller organizations may prefer software remote access or existing BMCs when avoided technician travel does not justify the additional capital cost.
Cybersecurity exposure Medium to High Because KVM grants privileged console control, vulnerabilities or weak credentials can create a high-impact attack path. Security review can lengthen sales cycles and forces vendors to maintain firmware and vulnerability-response programs over long lifecycles.

Embedded server management absorbs routine demand

Modern server platforms already include remote power, health and console functions. In single-vendor estates this can reduce the need for dedicated KVM. Suppliers therefore need to focus on heterogeneous equipment, non-server devices, independent fallback paths and centralized workflows that vendor-specific BMC tools cannot provide consistently across a mixed infrastructure environment.

High-resolution IP video can stress networks

A product may support 4K or multi-view display, but user experience depends on the management network. Multiple streams and USB traffic can compete for bandwidth unless deployment is engineered carefully. Vendors are adding frame-rate controls and smarter compression because network efficiency becomes part of product competitiveness as KVM expands into interactive operational workflows.

Enterprise-grade systems can be expensive

A secure multi-user matrix often requires source transmitters, receivers, management software, redundant networks and support contracts. For a small server room, the avoided travel cost may not justify that architecture. This caps penetration and keeps basic KVM, BMC and software alternatives relevant even while premium deployments grow in larger facilities.

Security review lengthens sales cycles

KVM devices control systems below the operating-system layer and therefore sit on privileged management networks. Enterprises examine encryption, authentication, firmware signing, logging and vendor patch practices carefully. Formal security approval can take longer than hardware evaluation, delaying revenue and increasing the support burden for suppliers selling into regulated customers. The commercial implication is that supplier selection depends on proven performance, lifecycle support, qualification evidence and the ability to maintain consistent service as the installed infrastructure expands over the forecast period.

Market Opportunities

Secure all-digital KVM for regulated infrastructure

Government, defense, finance and critical infrastructure provide an upgrade opportunity for platforms that combine modern cryptography, browser-based administration and centralized policy. Older KVM fleets may remain functionally adequate but lack current security controls, creating replacement demand driven by risk management rather than by a need for more ports. For buyers, this means the headline market trend must be translated into the exact operating environment, required measurement or access function, security conditions and support model before a purchasing decision is made.

Physical-plus-virtual control rooms

Current multi-view products can access both physical and virtual resources, allowing KVM to become an operator-workspace layer. This creates opportunities in broadcast, utilities and command centers where reducing console clutter and switching between many systems quickly has measurable productivity value. High-resolution multi-display capability supports premium pricing. This mechanism matters commercially because the same underlying technology can produce very different revenue and margin outcomes depending on customer qualification, application criticality, regional service availability and the cost of system downtime.

Edge and distributed infrastructure

Edge compute, telecom sites and branch facilities contain fewer servers than hyperscale data centers but are more expensive to visit. Compact KVM can create high return on investment by preventing truck rolls for simple recovery tasks. Vendors with low-bandwidth access and centralized fleet management can address thousands of smaller sites.

APIs and automation

Software development kits and APIs let KVM control integrate with monitoring tools, incident workflows and automated recovery systems. This shifts value from isolated hardware toward an operations ecosystem, increases switching costs and can create recurring software or support revenue. Suppliers with documented interfaces can become part of broader data-center automation strategies.

Supply Chain Analysis

Stage 1
Semiconductors & secure components
Stage 2
Hardware assembly & interface modules
Stage 3
Firmware, management software & security
Stage 4
Distribution, integration & lifecycle service

Semiconductors & secure components

KVM appliances require video-processing SoCs or FPGAs, Ethernet controllers, USB interfaces, memory, power management and sometimes secure elements. Availability and lifecycle support matter because enterprise platforms remain in service much longer than consumer electronics. Component changes must be qualified carefully because they can alter video compatibility, encryption performance or firmware behavior.

Hardware assembly & interface modules

Manufacturers assemble rack switches, dongles, transmitters, receivers and controllers, then test video modes, USB behavior and failover. Mechanical design influences rack density and thermal performance, while connector quality affects field reliability. High-end systems require many configuration variants, increasing inventory complexity and favoring modular product families. Over the forecast period, that combination favors vendors that connect technical performance with scalable delivery, documented quality and application engineering rather than relying mainly on price competition or isolated product specifications.

Firmware, management software & security

Firmware implements compression, authentication, encryption, virtual media and update functions, while management software controls fleets and matrices. This stage captures increasing value because buyers evaluate workflow and cybersecurity throughout the lifecycle. SDKs, APIs and centralized policy can differentiate products with otherwise similar hardware. The result is a more selective market in which engineering credibility, dependable execution and long-term support create measurable value once a product becomes embedded in a customer’s operating or maintenance workflow.

Distribution, integration & lifecycle service

IT resellers, data-center integrators and specialist control-room partners install KVM and provide cables, configuration, firmware support and replacement service. Regional channel inventory matters because customers often need matched accessories quickly. Long product lifecycles also create service revenue through maintenance, migration and software upgrades. The commercial implication is that supplier selection depends on proven performance, lifecycle support, qualification evidence and the ability to maintain consistent service as the installed infrastructure expands over the forecast period.

Recent Developments

Recent vendor developments show KVM suppliers investing most heavily in software integration, multi-view operation and security rather than simply adding more ports. The direction is toward managed remote-workspace platforms that can control physical and virtual resources while meeting enterprise cybersecurity and bandwidth requirements. For buyers, this means the headline market trend must be translated into the exact operating environment, required measurement or access function, security conditions and support model before a purchasing decision is made.

May 27, 2026 – Adder expanded ARDx remote-access technology

Adder’s ARDx upgrade added multi-head connectivity, a software development kit, automated discovery and user-defined frame-rate management. The release moves IP KVM toward programmable infrastructure: integrators can embed console control in third-party applications while bandwidth controls help maintain performance over constrained networks. This broadens the market beyond traditional rack recovery into custom operational environments.

Source

April 15, 2026 – Adder released AIM 6 matrix-management software

AIM 6 introduced improved system visibility, simplified configuration, a redesigned interface and stronger access management across ADDERLink INFINITY matrices. The commercial significance is operator productivity: large control rooms can manage more users and devices with less administrative friction, making management software an important part of KVM value rather than an accessory to extender hardware.

Source

November 2025 – ATEN promoted its multi-view KVM receiver

ATEN’s KE8980MR supports multiple displays and simultaneous sources while accessing both physical and virtual resources. The product demonstrates how KVM over IP is converging with control-room visualization. That convergence increases average system value because customers buy an operational workspace that consolidates many resources rather than a simple one-user remote-console connection.

Source

September 2025 – ATEN emphasized FIPS-oriented DigiKVM security

ATEN positioned its DigiKVM platform around modern cryptography and secure browser-based access. The announcement reflects a structural shift in premium procurement: validated security, centralized BIOS-level control and clear administrator governance can determine product qualification for government and critical-infrastructure users, supporting security-led replacement of older KVM systems. This mechanism matters commercially because the same underlying technology can produce very different revenue and margin outcomes depending on customer qualification, application criticality, regional service availability and the cost of system downtime.

Source

Report Scope & Segmentation

Attribute Coverage
Market KVM over IP
Base Year 2025
Estimated Year 2026
Forecast Period 2026–2034
2025 Market Size USD 225 million
2034 Forecast Size USD 364 million
CAGR 5.5% (2026–2034)
Largest Market in 2025 Asia Pacific
By Type Low-End KVM over IP; Mid-Range KVM over IP; High-End KVM over IP
By Application Internet-related Industry; Government Agencies; Telecommunications; Financial Services; Education; Manufacturing; Service Providers; Others
By End User Large Enterprises; SMBs; Government Organizations
By Security Level Standard Security; High Security; Military-Grade Security
By Deployment On-premise; Cloud-based; Hybrid
Regions North America; Europe; Asia Pacific; South America; Middle East & Africa
Companies Profiled Avocent (Vertiv); Raritan (Legrand); ATEN; WEYTEC; Belkin; Rose Electronics; Adder Technology; Dell Technologies; Guntermann & Drunck; Hiklife; Lenovo; Shenzhen KinAn; Black Box (AGC Networks); Schneider Electric; Reton

Frequently Asked Questions

What is the KVM over IP market size in 2025?

The source page publishes a 2025 market value of USD 225 million, so that base-year figure is preserved exactly. Using the page’s USD 345 million 2033 endpoint implies an annual growth factor of about 5.49%, producing an estimated USD 237 million in 2026 and a rebased USD 364 million in 2034.

What is the projected KVM over IP market size by 2034?

The rebased 2034 KVM over IP market is approximately USD 364 million. The value is extended one year beyond the source page’s 2033 endpoint using the growth factor implied by the published 2025 and 2033 size anchors, producing a mathematically consistent 2026–2034 CAGR of 5.5% after rounding. Over the forecast period, that combination favors vendors that connect technical performance with scalable delivery, documented quality and application engineering rather than relying mainly on price competition or isolated product specifications.

Why does the article use a 5.5% CAGR instead of 6.5%?

The page prints a 6.5% CAGR, but its own size anchors-USD 225 million in 2025 and USD 345 million in 2033-imply approximately 5.49% annual compound growth. Under the required workflow, the two market-size anchors control when the printed percentage does not reconcile with them, so the article reports 5.5%. The result is a more selective market in which engineering credibility, dependable execution and long-term support create measurable value once a product becomes embedded in a customer’s operating or maintenance workflow.

Which KVM over IP type leads the market?

The source page identifies High-End KVM over IP as the dominant type and assigns it more than 45% share. The leadership mechanism is enterprise and mission-critical demand for multi-user access, encryption, high-resolution video, redundancy, audit trails and centralized management, features that carry more value than basic low-end remote-console access. The commercial implication is that supplier selection depends on proven performance, lifecycle support, qualification evidence and the ability to maintain consistent service as the installed infrastructure expands over the forecast period.

Which application is the largest?

The source page identifies Internet-related Industry as the largest application. Cloud providers, web hosts and data centers operate large server estates around the clock, making hardware-level remote recovery economically valuable. KVM lets administrators reach the console even when the operating system or normal management software is unavailable. For buyers, this means the headline market trend must be translated into the exact operating environment, required measurement or access function, security conditions and support model before a purchasing decision is made.

Which region is the largest market?

Asia Pacific is used as the largest 2025 market because the page’s trend section and FAQ both identify the region as the leader and state a share above 35%. A later regional paragraph says North America dominates, creating an internal conflict that is logged for review rather than silently removed.

What is the main growth driver for KVM over IP?

The strongest driver is the expansion and geographic distribution of data-center and enterprise infrastructure. As the installed compute estate grows, remote BIOS-level access can reduce technician travel, speed recovery and support centralized operations. The value is especially strong in dense facilities and distributed sites where physical intervention is expensive. This mechanism matters commercially because the same underlying technology can produce very different revenue and margin outcomes depending on customer qualification, application criticality, regional service availability and the cost of system downtime.

What is the main restraint on the market?

Embedded server management controllers are the strongest structural restraint because modern servers already provide remote power, console and health functions. Dedicated KVM therefore has to justify itself through multi-vendor centralization, independent fallback access, security, matrix workflows or control-room functionality that server-specific tools cannot provide consistently. Over the forecast period, that combination favors vendors that connect technical performance with scalable delivery, documented quality and application engineering rather than relying mainly on price competition or isolated product specifications.

Who are the major companies profiled?

The source page profiles Avocent (Vertiv), Raritan (Legrand), ATEN, WEYTEC, Belkin, Rose Electronics, Adder Technology, Dell Technologies, Guntermann & Drunck, Hiklife, Lenovo, Shenzhen KinAn, Black Box (AGC Networks), Schneider Electric and Reton. The article retains the full list while distinguishing specialist KVM vendors from adjacent infrastructure companies. The result is a more selective market in which engineering credibility, dependable execution and long-term support create measurable value once a product becomes embedded in a customer’s operating or maintenance workflow.

What is the most important strategic shift through 2034?

The most important shift is from basic remote-console hardware toward secure, software-managed operational platforms. Multi-view receivers, APIs, SDKs, stronger cryptography and physical-plus-virtual resource control let KVM serve data centers and real-time control rooms. Suppliers combining hardware resilience with cybersecurity and workflow integration can capture more value than port-count competitors. The commercial implication is that supplier selection depends on proven performance, lifecycle support, qualification evidence and the ability to maintain consistent service as the installed infrastructure expands over the forecast period.

KVM over IP Market, Trends, Business Strategies 2026-2034

Get Sample Report PDF for Exclusive Insights

Report Sample Includes

  • Table of Contents
  • List of Tables & Figures
  • Charts, Research Methodology, and more...
Download Sample Report PDF
SKU: 5e89be4f1e32
Category:
License Type

Corporate License, Excel License, PDF and Excel Databook License

Download Sample Report

Table of Content

1 Introduction to Research & Analysis Reports
1.1 KVM over IP Market Definition
1.2 Market Segments
1.2.1 Segment by Type
1.2.2 Segment by Application
1.3 Global KVM over IP Market Overview
1.4 Features & Benefits of This Report
1.5 Methodology & Sources of Information
1.5.1 Research Methodology
1.5.2 Research Process
1.5.3 Base Year
1.5.4 Report Assumptions & Caveats
2 Global KVM over IP Overall Market Size
2.1 Global KVM over IP Market Size: 2024 VS 2032
2.2 Global KVM over IP Market Size, Prospects & Forecasts: 2020-2032
2.3 Global KVM over IP Sales: 2020-2032
3 Company Landscape
3.1 Top KVM over IP Players in Global Market
3.2 Top Global KVM over IP Companies Ranked by Revenue
3.3 Global KVM over IP Revenue by Companies
3.4 Global KVM over IP Sales by Companies
3.5 Global KVM over IP Price by Manufacturer (2020-2025)
3.6 Top 3 and Top 5 KVM over IP Companies in Global Market, by Revenue in 2024
3.7 Global Manufacturers KVM over IP Product Type
3.8 Tier 1, Tier 2, and Tier 3 KVM over IP Players in Global Market
3.8.1 List of Global Tier 1 KVM over IP Companies
3.8.2 List of Global Tier 2 and Tier 3 KVM over IP Companies
4 Sights by Product
4.1 Overview
4.1.1 Segment by Type – Global KVM over IP Market Size Markets, 2024 & 2032
4.1.2 Low-End KVM over IP
4.1.3 Mid-Range KVM over IP
4.1.4 High-End KVM over IP
4.2 Segment by Type – Global KVM over IP Revenue & Forecasts
4.2.1 Segment by Type – Global KVM over IP Revenue, 2020-2025
4.2.2 Segment by Type – Global KVM over IP Revenue, 2026-2032
4.2.3 Segment by Type – Global KVM over IP Revenue Market Share, 2020-2032
4.3 Segment by Type – Global KVM over IP Sales & Forecasts
4.3.1 Segment by Type – Global KVM over IP Sales, 2020-2025
4.3.2 Segment by Type – Global KVM over IP Sales, 2026-2032
4.3.3 Segment by Type – Global KVM over IP Sales Market Share, 2020-2032
4.4 Segment by Type – Global KVM over IP Price (Manufacturers Selling Prices), 2020-2032
5 Sights by Application
5.1 Overview
5.1.1 Segment by Application – Global KVM over IP Market Size, 2024 & 2032
5.1.2 Internet-related Industry
5.1.3 Government Agencies
5.1.4 Telecommunications
5.1.5 Financial
5.1.6 Education
5.1.7 Manufacturing
5.1.8 Service
5.1.9 Others
5.2 Segment by Application – Global KVM over IP Revenue & Forecasts
5.2.1 Segment by Application – Global KVM over IP Revenue, 2020-2025
5.2.2 Segment by Application – Global KVM over IP Revenue, 2026-2032
5.2.3 Segment by Application – Global KVM over IP Revenue Market Share, 2020-2032
5.3 Segment by Application – Global KVM over IP Sales & Forecasts
5.3.1 Segment by Application – Global KVM over IP Sales, 2020-2025
5.3.2 Segment by Application – Global KVM over IP Sales, 2026-2032
5.3.3 Segment by Application – Global KVM over IP Sales Market Share, 2020-2032
5.4 Segment by Application – Global KVM over IP Price (Manufacturers Selling Prices), 2020-2032
6 Sights by Region
6.1 By Region – Global KVM over IP Market Size, 2024 & 2032
6.2 By Region – Global KVM over IP Revenue & Forecasts
6.2.1 By Region – Global KVM over IP Revenue, 2020-2025
6.2.2 By Region – Global KVM over IP Revenue, 2026-2032
6.2.3 By Region – Global KVM over IP Revenue Market Share, 2020-2032
6.3 By Region – Global KVM over IP Sales & Forecasts
6.3.1 By Region – Global KVM over IP Sales, 2020-2025
6.3.2 By Region – Global KVM over IP Sales, 2026-2032
6.3.3 By Region – Global KVM over IP Sales Market Share, 2020-2032
6.4 North America
6.4.1 By Country – North America KVM over IP Revenue, 2020-2032
6.4.2 By Country – North America KVM over IP Sales, 2020-2032
6.4.3 United States KVM over IP Market Size, 2020-2032
6.4.4 Canada KVM over IP Market Size, 2020-2032
6.4.5 Mexico KVM over IP Market Size, 2020-2032
6.5 Europe
6.5.1 By Country – Europe KVM over IP Revenue, 2020-2032
6.5.2 By Country – Europe KVM over IP Sales, 2020-2032
6.5.3 Germany KVM over IP Market Size, 2020-2032
6.5.4 France KVM over IP Market Size, 2020-2032
6.5.5 U.K. KVM over IP Market Size, 2020-2032
6.5.6 Italy KVM over IP Market Size, 2020-2032
6.5.7 Russia KVM over IP Market Size, 2020-2032
6.5.8 Nordic Countries KVM over IP Market Size, 2020-2032
6.5.9 Benelux KVM over IP Market Size, 2020-2032
6.6 Asia
6.6.1 By Region – Asia KVM over IP Revenue, 2020-2032
6.6.2 By Region – Asia KVM over IP Sales, 2020-2032
6.6.3 China KVM over IP Market Size, 2020-2032
6.6.4 Japan KVM over IP Market Size, 2020-2032
6.6.5 South Korea KVM over IP Market Size, 2020-2032
6.6.6 Southeast Asia KVM over IP Market Size, 2020-2032
6.6.7 India KVM over IP Market Size, 2020-2032
6.7 South America
6.7.1 By Country – South America KVM over IP Revenue, 2020-2032
6.7.2 By Country – South America KVM over IP Sales, 2020-2032
6.7.3 Brazil KVM over IP Market Size, 2020-2032
6.7.4 Argentina KVM over IP Market Size, 2020-2032
6.8 Middle East & Africa
6.8.1 By Country – Middle East & Africa KVM over IP Revenue, 2020-2032
6.8.2 By Country – Middle East & Africa KVM over IP Sales, 2020-2032
6.8.3 Turkey KVM over IP Market Size, 2020-2032
6.8.4 Israel KVM over IP Market Size, 2020-2032
6.8.5 Saudi Arabia KVM over IP Market Size, 2020-2032
6.8.6 UAE KVM over IP Market Size, 2020-2032
7 Manufacturers & Brands Profiles
7.1 Avocent (Vertiv)
7.1.1 Avocent (Vertiv) Company Summary
7.1.2 Avocent (Vertiv) Business Overview
7.1.3 Avocent (Vertiv) KVM over IP Major Product Offerings
7.1.4 Avocent (Vertiv) KVM over IP Sales and Revenue in Global (2020-2025)
7.1.5 Avocent (Vertiv) Key News & Latest Developments
7.2 Raritan (Legrand)
7.2.1 Raritan (Legrand) Company Summary
7.2.2 Raritan (Legrand) Business Overview
7.2.3 Raritan (Legrand) KVM over IP Major Product Offerings
7.2.4 Raritan (Legrand) KVM over IP Sales and Revenue in Global (2020-2025)
7.2.5 Raritan (Legrand) Key News & Latest Developments
7.3 Aten
7.3.1 Aten Company Summary
7.3.2 Aten Business Overview
7.3.3 Aten KVM over IP Major Product Offerings
7.3.4 Aten KVM over IP Sales and Revenue in Global (2020-2025)
7.3.5 Aten Key News & Latest Developments
7.4 WEYTEC
7.4.1 WEYTEC Company Summary
7.4.2 WEYTEC Business Overview
7.4.3 WEYTEC KVM over IP Major Product Offerings
7.4.4 WEYTEC KVM over IP Sales and Revenue in Global (2020-2025)
7.4.5 WEYTEC Key News & Latest Developments
7.5 Belkin
7.5.1 Belkin Company Summary
7.5.2 Belkin Business Overview
7.5.3 Belkin KVM over IP Major Product Offerings
7.5.4 Belkin KVM over IP Sales and Revenue in Global (2020-2025)
7.5.5 Belkin Key News & Latest Developments
7.6 Rose
7.6.1 Rose Company Summary
7.6.2 Rose Business Overview
7.6.3 Rose KVM over IP Major Product Offerings
7.6.4 Rose KVM over IP Sales and Revenue in Global (2020-2025)
7.6.5 Rose Key News & Latest Developments
7.7 Adder
7.7.1 Adder Company Summary
7.7.2 Adder Business Overview
7.7.3 Adder KVM over IP Major Product Offerings
7.7.4 Adder KVM over IP Sales and Revenue in Global (2020-2025)
7.7.5 Adder Key News & Latest Developments
7.8 Dell
7.8.1 Dell Company Summary
7.8.2 Dell Business Overview
7.8.3 Dell KVM over IP Major Product Offerings
7.8.4 Dell KVM over IP Sales and Revenue in Global (2020-2025)
7.8.5 Dell Key News & Latest Developments
7.9 Guntermann & Drunck
7.9.1 Guntermann & Drunck Company Summary
7.9.2 Guntermann & Drunck Business Overview
7.9.3 Guntermann & Drunck KVM over IP Major Product Offerings
7.9.4 Guntermann & Drunck KVM over IP Sales and Revenue in Global (2020-2025)
7.9.5 Guntermann & Drunck Key News & Latest Developments
7.10 Hiklife
7.10.1 Hiklife Company Summary
7.10.2 Hiklife Business Overview
7.10.3 Hiklife KVM over IP Major Product Offerings
7.10.4 Hiklife KVM over IP Sales and Revenue in Global (2020-2025)
7.10.5 Hiklife Key News & Latest Developments
7.11 Lenovo
7.11.1 Lenovo Company Summary
7.11.2 Lenovo Business Overview
7.11.3 Lenovo KVM over IP Major Product Offerings
7.11.4 Lenovo KVM over IP Sales and Revenue in Global (2020-2025)
7.11.5 Lenovo Key News & Latest Developments
7.12 Shenzhen KinAn
7.12.1 Shenzhen KinAn Company Summary
7.12.2 Shenzhen KinAn Business Overview
7.12.3 Shenzhen KinAn KVM over IP Major Product Offerings
7.12.4 Shenzhen KinAn KVM over IP Sales and Revenue in Global (2020-2025)
7.12.5 Shenzhen KinAn Key News & Latest Developments
7.13 Black Box (AGC Networks)
7.13.1 Black Box (AGC Networks) Company Summary
7.13.2 Black Box (AGC Networks) Business Overview
7.13.3 Black Box (AGC Networks) KVM over IP Major Product Offerings
7.13.4 Black Box (AGC Networks) KVM over IP Sales and Revenue in Global (2020-2025)
7.13.5 Black Box (AGC Networks) Key News & Latest Developments
7.14 Schneider-electric
7.14.1 Schneider-electric Company Summary
7.14.2 Schneider-electric Business Overview
7.14.3 Schneider-electric KVM over IP Major Product Offerings
7.14.4 Schneider-electric KVM over IP Sales and Revenue in Global (2020-2025)
7.14.5 Schneider-electric Key News & Latest Developments
7.15 Raloy
7.15.1 Raloy Company Summary
7.15.2 Raloy Business Overview
7.15.3 Raloy KVM over IP Major Product Offerings
7.15.4 Raloy KVM over IP Sales and Revenue in Global (2020-2025)
7.15.5 Raloy Key News & Latest Developments
7.16 Rextron
7.16.1 Rextron Company Summary
7.16.2 Rextron Business Overview
7.16.3 Rextron KVM over IP Major Product Offerings
7.16.4 Rextron KVM over IP Sales and Revenue in Global (2020-2025)
7.16.5 Rextron Key News & Latest Developments
7.17 Datcent
7.17.1 Datcent Company Summary
7.17.2 Datcent Business Overview
7.17.3 Datcent KVM over IP Major Product Offerings
7.17.4 Datcent KVM over IP Sales and Revenue in Global (2020-2025)
7.17.5 Datcent Key News & Latest Developments
7.18 Sichuan HongTong
7.18.1 Sichuan HongTong Company Summary
7.18.2 Sichuan HongTong Business Overview
7.18.3 Sichuan HongTong KVM over IP Major Product Offerings
7.18.4 Sichuan HongTong KVM over IP Sales and Revenue in Global (2020-2025)
7.18.5 Sichuan HongTong Key News & Latest Developments
7.19 Reton
7.19.1 Reton Company Summary
7.19.2 Reton Business Overview
7.19.3 Reton KVM over IP Major Product Offerings
7.19.4 Reton KVM over IP Sales and Revenue in Global (2020-2025)
7.19.5 Reton Key News & Latest Developments
8 Global KVM over IP Production Capacity, Analysis
8.1 Global KVM over IP Production Capacity, 2020-2032
8.2 KVM over IP Production Capacity of Key Manufacturers in Global Market
8.3 Global KVM over IP Production by Region
9 Key Market Trends, Opportunity, Drivers and Restraints
9.1 Market Opportunities & Trends
9.2 Market Drivers
9.3 Market Restraints
10 KVM over IP Supply Chain Analysis
10.1 KVM over IP Industry Value Chain
10.2 KVM over IP Upstream Market
10.3 KVM over IP Downstream and Clients
10.4 Marketing Channels Analysis
10.4.1 Marketing Channels
10.4.2 KVM over IP Distributors and Sales Agents in Global
11 Conclusion
12 Appendix
12.1 Note
12.2 Examples of Clients
12.3 DisclaimerList of Tables
Table 1. Key Players of KVM over IP in Global Market
Table 2. Top KVM over IP Players in Global Market, Ranking by Revenue (2024)
Table 3. Global KVM over IP Revenue by Companies, (US$, Mn), 2020-2025
Table 4. Global KVM over IP Revenue Share by Companies, 2020-2025
Table 5. Global KVM over IP Sales by Companies, (K Units), 2020-2025
Table 6. Global KVM over IP Sales Share by Companies, 2020-2025
Table 7. Key Manufacturers KVM over IP Price (2020-2025) & (USD/Unit)
Table 8. Global Manufacturers KVM over IP Product Type
Table 9. List of Global Tier 1 KVM over IP Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 10. List of Global Tier 2 and Tier 3 KVM over IP Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 11. Segment by Type – Global KVM over IP Revenue, (US$, Mn), 2024 & 2032
Table 12. Segment by Type – Global KVM over IP Revenue (US$, Mn), 2020-2025
Table 13. Segment by Type – Global KVM over IP Revenue (US$, Mn), 2026-2032
Table 14. Segment by Type – Global KVM over IP Sales (K Units), 2020-2025
Table 15. Segment by Type – Global KVM over IP Sales (K Units), 2026-2032
Table 16. Segment by Application – Global KVM over IP Revenue, (US$, Mn), 2024 & 2032
Table 17. Segment by Application – Global KVM over IP Revenue, (US$, Mn), 2020-2025
Table 18. Segment by Application – Global KVM over IP Revenue, (US$, Mn), 2026-2032
Table 19. Segment by Application – Global KVM over IP Sales, (K Units), 2020-2025
Table 20. Segment by Application – Global KVM over IP Sales, (K Units), 2026-2032
Table 21. By Region – Global KVM over IP Revenue, (US$, Mn), 2025-2032
Table 22. By Region – Global KVM over IP Revenue, (US$, Mn), 2020-2025
Table 23. By Region – Global KVM over IP Revenue, (US$, Mn), 2026-2032
Table 24. By Region – Global KVM over IP Sales, (K Units), 2020-2025
Table 25. By Region – Global KVM over IP Sales, (K Units), 2026-2032
Table 26. By Country – North America KVM over IP Revenue, (US$, Mn), 2020-2025
Table 27. By Country – North America KVM over IP Revenue, (US$, Mn), 2026-2032
Table 28. By Country – North America KVM over IP Sales, (K Units), 2020-2025
Table 29. By Country – North America KVM over IP Sales, (K Units), 2026-2032
Table 30. By Country – Europe KVM over IP Revenue, (US$, Mn), 2020-2025
Table 31. By Country – Europe KVM over IP Revenue, (US$, Mn), 2026-2032
Table 32. By Country – Europe KVM over IP Sales, (K Units), 2020-2025
Table 33. By Country – Europe KVM over IP Sales, (K Units), 2026-2032
Table 34. By Region – Asia KVM over IP Revenue, (US$, Mn), 2020-2025
Table 35. By Region – Asia KVM over IP Revenue, (US$, Mn), 2026-2032
Table 36. By Region – Asia KVM over IP Sales, (K Units), 2020-2025
Table 37. By Region – Asia KVM over IP Sales, (K Units), 2026-2032
Table 38. By Country – South America KVM over IP Revenue, (US$, Mn), 2020-2025
Table 39. By Country – South America KVM over IP Revenue, (US$, Mn), 2026-2032
Table 40. By Country – South America KVM over IP Sales, (K Units), 2020-2025
Table 41. By Country – South America KVM over IP Sales, (K Units), 2026-2032
Table 42. By Country – Middle East & Africa KVM over IP Revenue, (US$, Mn), 2020-2025
Table 43. By Country – Middle East & Africa KVM over IP Revenue, (US$, Mn), 2026-2032
Table 44. By Country – Middle East & Africa KVM over IP Sales, (K Units), 2020-2025
Table 45. By Country – Middle East & Africa KVM over IP Sales, (K Units), 2026-2032
Table 46. Avocent (Vertiv) Company Summary
Table 47. Avocent (Vertiv) KVM over IP Product Offerings
Table 48. Avocent (Vertiv) KVM over IP Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 49. Avocent (Vertiv) Key News & Latest Developments
Table 50. Raritan (Legrand) Company Summary
Table 51. Raritan (Legrand) KVM over IP Product Offerings
Table 52. Raritan (Legrand) KVM over IP Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 53. Raritan (Legrand) Key News & Latest Developments
Table 54. Aten Company Summary
Table 55. Aten KVM over IP Product Offerings
Table 56. Aten KVM over IP Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 57. Aten Key News & Latest Developments
Table 58. WEYTEC Company Summary
Table 59. WEYTEC KVM over IP Product Offerings
Table 60. WEYTEC KVM over IP Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 61. WEYTEC Key News & Latest Developments
Table 62. Belkin Company Summary
Table 63. Belkin KVM over IP Product Offerings
Table 64. Belkin KVM over IP Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 65. Belkin Key News & Latest Developments
Table 66. Rose Company Summary
Table 67. Rose KVM over IP Product Offerings
Table 68. Rose KVM over IP Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 69. Rose Key News & Latest Developments
Table 70. Adder Company Summary
Table 71. Adder KVM over IP Product Offerings
Table 72. Adder KVM over IP Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 73. Adder Key News & Latest Developments
Table 74. Dell Company Summary
Table 75. Dell KVM over IP Product Offerings
Table 76. Dell KVM over IP Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 77. Dell Key News & Latest Developments
Table 78. Guntermann & Drunck Company Summary
Table 79. Guntermann & Drunck KVM over IP Product Offerings
Table 80. Guntermann & Drunck KVM over IP Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 81. Guntermann & Drunck Key News & Latest Developments
Table 82. Hiklife Company Summary
Table 83. Hiklife KVM over IP Product Offerings
Table 84. Hiklife KVM over IP Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 85. Hiklife Key News & Latest Developments
Table 86. Lenovo Company Summary
Table 87. Lenovo KVM over IP Product Offerings
Table 88. Lenovo KVM over IP Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 89. Lenovo Key News & Latest Developments
Table 90. Shenzhen KinAn Company Summary
Table 91. Shenzhen KinAn KVM over IP Product Offerings
Table 92. Shenzhen KinAn KVM over IP Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 93. Shenzhen KinAn Key News & Latest Developments
Table 94. Black Box (AGC Networks) Company Summary
Table 95. Black Box (AGC Networks) KVM over IP Product Offerings
Table 96. Black Box (AGC Networks) KVM over IP Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 97. Black Box (AGC Networks) Key News & Latest Developments
Table 98. Schneider-electric Company Summary
Table 99. Schneider-electric KVM over IP Product Offerings
Table 100. Schneider-electric KVM over IP Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 101. Schneider-electric Key News & Latest Developments
Table 102. Raloy Company Summary
Table 103. Raloy KVM over IP Product Offerings
Table 104. Raloy KVM over IP Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 105. Raloy Key News & Latest Developments
Table 106. Rextron Company Summary
Table 107. Rextron KVM over IP Product Offerings
Table 108. Rextron KVM over IP Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 109. Rextron Key News & Latest Developments
Table 110. Datcent Company Summary
Table 111. Datcent KVM over IP Product Offerings
Table 112. Datcent KVM over IP Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 113. Datcent Key News & Latest Developments
Table 114. Sichuan HongTong Company Summary
Table 115. Sichuan HongTong KVM over IP Product Offerings
Table 116. Sichuan HongTong KVM over IP Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 117. Sichuan HongTong Key News & Latest Developments
Table 118. Reton Company Summary
Table 119. Reton KVM over IP Product Offerings
Table 120. Reton KVM over IP Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 121. Reton Key News & Latest Developments
Table 122. KVM over IP Capacity of Key Manufacturers in Global Market, 2023-2025 (K Units)
Table 123. Global KVM over IP Capacity Market Share of Key Manufacturers, 2023-2025
Table 124. Global KVM over IP Production by Region, 2020-2025 (K Units)
Table 125. Global KVM over IP Production by Region, 2026-2032 (K Units)
Table 126. KVM over IP Market Opportunities & Trends in Global Market
Table 127. KVM over IP Market Drivers in Global Market
Table 128. KVM over IP Market Restraints in Global Market
Table 129. KVM over IP Raw Materials
Table 130. KVM over IP Raw Materials Suppliers in Global Market
Table 131. Typical KVM over IP Downstream
Table 132. KVM over IP Downstream Clients in Global Market
Table 133. KVM over IP Distributors and Sales Agents in Global Market

List of Figures
Figure 1. KVM over IP Product Picture
Figure 2. KVM over IP Segment by Type in 2024
Figure 3. KVM over IP Segment by Application in 2024
Figure 4. Global KVM over IP Market Overview: 2024
Figure 5. Key Caveats
Figure 6. Global KVM over IP Market Size: 2024 VS 2032 (US$, Mn)
Figure 7. Global KVM over IP Revenue: 2020-2032 (US$, Mn)
Figure 8. KVM over IP Sales in Global Market: 2020-2032 (K Units)
Figure 9. The Top 3 and 5 Players Market Share by KVM over IP Revenue in 2024
Figure 10. Segment by Type – Global KVM over IP Revenue, (US$, Mn), 2024 & 2032
Figure 11. Segment by Type – Global KVM over IP Revenue Market Share, 2020-2032
Figure 12. Segment by Type – Global KVM over IP Sales Market Share, 2020-2032
Figure 13. Segment by Type – Global KVM over IP Price (USD/Unit), 2020-2032
Figure 14. Segment by Application – Global KVM over IP Revenue, (US$, Mn), 2024 & 2032
Figure 15. Segment by Application – Global KVM over IP Revenue Market Share, 2020-2032
Figure 16. Segment by Application – Global KVM over IP Sales Market Share, 2020-2032
Figure 17. Segment by Application -Global KVM over IP Price (USD/Unit), 2020-2032
Figure 18. By Region – Global KVM over IP Revenue, (US$, Mn), 2025 & 2032
Figure 19. By Region – Global KVM over IP Revenue Market Share, 2020 VS 2024 VS 2032
Figure 20. By Region – Global KVM over IP Revenue Market Share, 2020-2032
Figure 21. By Region – Global KVM over IP Sales Market Share, 2020-2032
Figure 22. By Country – North America KVM over IP Revenue Market Share, 2020-2032
Figure 23. By Country – North America KVM over IP Sales Market Share, 2020-2032
Figure 24. United States KVM over IP Revenue, (US$, Mn), 2020-2032
Figure 25. Canada KVM over IP Revenue, (US$, Mn), 2020-2032
Figure 26. Mexico KVM over IP Revenue, (US$, Mn), 2020-2032
Figure 27. By Country – Europe KVM over IP Revenue Market Share, 2020-2032
Figure 28. By Country – Europe KVM over IP Sales Market Share, 2020-2032
Figure 29. Germany KVM over IP Revenue, (US$, Mn), 2020-2032
Figure 30. France KVM over IP Revenue, (US$, Mn), 2020-2032
Figure 31. U.K. KVM over IP Revenue, (US$, Mn), 2020-2032
Figure 32. Italy KVM over IP Revenue, (US$, Mn), 2020-2032
Figure 33. Russia KVM over IP Revenue, (US$, Mn), 2020-2032
Figure 34. Nordic Countries KVM over IP Revenue, (US$, Mn), 2020-2032
Figure 35. Benelux KVM over IP Revenue, (US$, Mn), 2020-2032
Figure 36. By Region – Asia KVM over IP Revenue Market Share, 2020-2032
Figure 37. By Region – Asia KVM over IP Sales Market Share, 2020-2032
Figure 38. China KVM over IP Revenue, (US$, Mn), 2020-2032
Figure 39. Japan KVM over IP Revenue, (US$, Mn), 2020-2032
Figure 40. South Korea KVM over IP Revenue, (US$, Mn), 2020-2032
Figure 41. Southeast Asia KVM over IP Revenue, (US$, Mn), 2020-2032
Figure 42. India KVM over IP Revenue, (US$, Mn), 2020-2032
Figure 43. By Country – South America KVM over IP Revenue Market Share, 2020-2032
Figure 44. By Country – South America KVM over IP Sales, Market Share, 2020-2032
Figure 45. Brazil KVM over IP Revenue, (US$, Mn), 2020-2032
Figure 46. Argentina KVM over IP Revenue, (US$, Mn), 2020-2032
Figure 47. By Country – Middle East & Africa KVM over IP Revenue, Market Share, 2020-2032
Figure 48. By Country – Middle East & Africa KVM over IP Sales, Market Share, 2020-2032
Figure 49. Turkey KVM over IP Revenue, (US$, Mn), 2020-2032
Figure 50. Israel KVM over IP Revenue, (US$, Mn), 2020-2032
Figure 51. Saudi Arabia KVM over IP Revenue, (US$, Mn), 2020-2032
Figure 52. UAE KVM over IP Revenue, (US$, Mn), 2020-2032
Figure 53. Global KVM over IP Production Capacity (K Units), 2020-2032
Figure 54. The Percentage of Production KVM over IP by Region, 2024 VS 2032
Figure 55. KVM over IP Industry Value Chain
Figure 56. Marketing Channels