Key Statistics
Key Takeaways
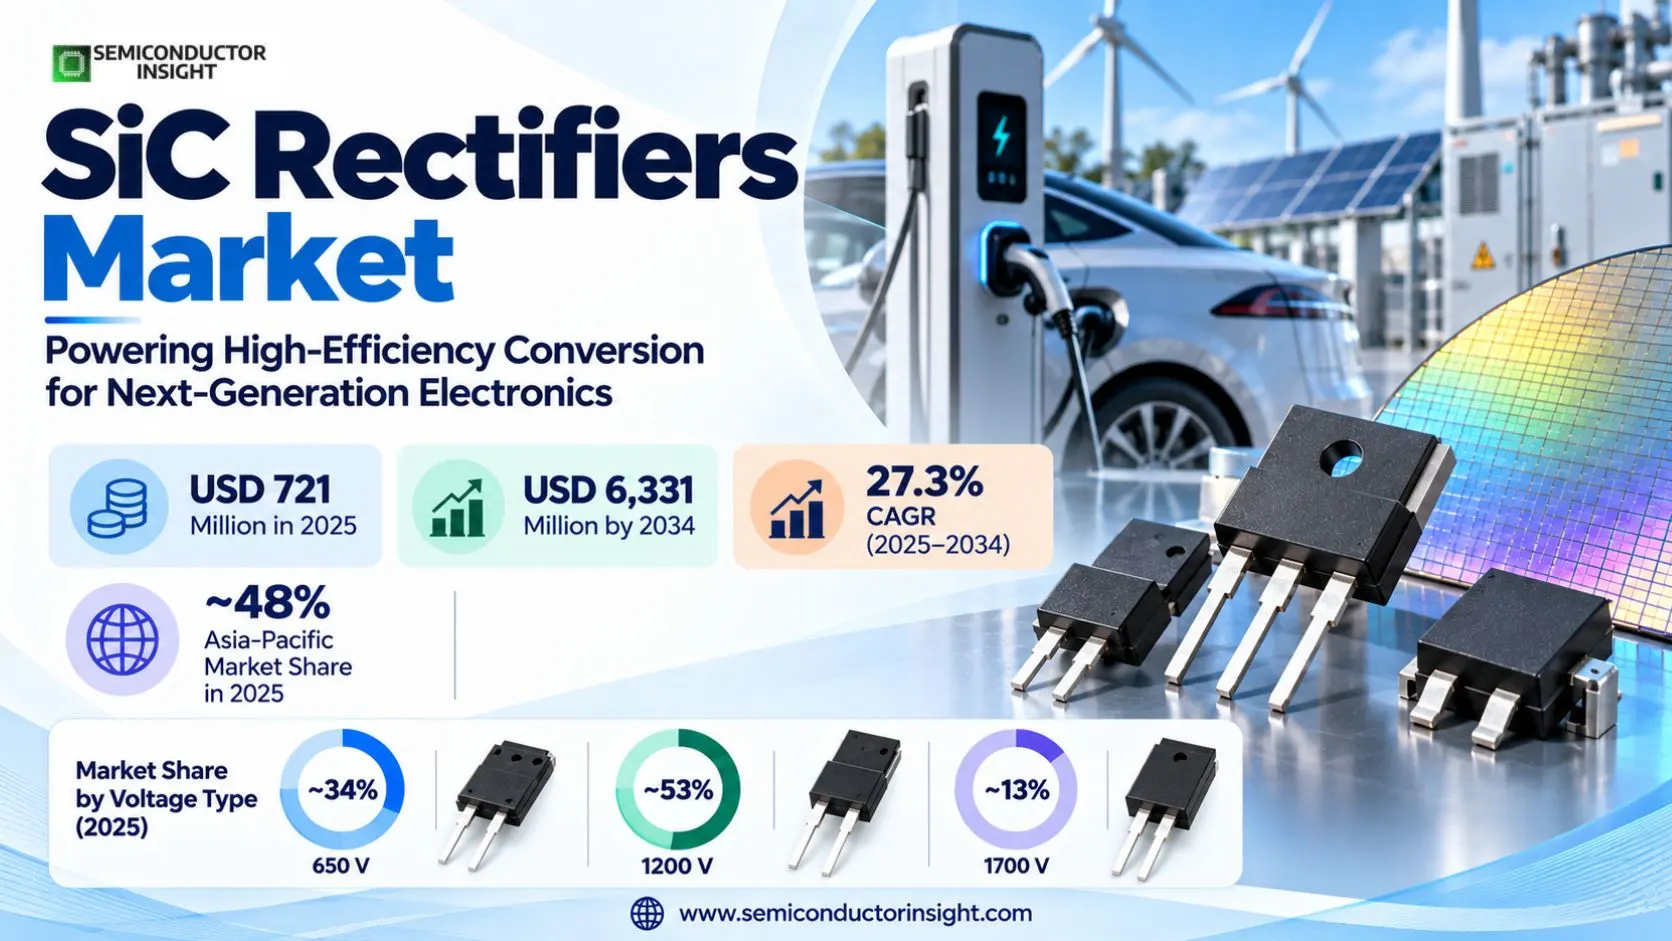
- Market outlook: The global market begins at USD 721 million in 2025 and advances toward USD 6,331 million in 2034, with 27.3% annualized growth across the nine-year 2025–2034 span. Demand combines high-frequency power-supply upgrades with electrified transport and renewable-energy conversion.
- Voltage mix: The 1200 V class represents an estimated ~53% of 2025 sales, ahead of 650 V at ~34% and 1700 V at ~13%. Voltage withstand capability, package heat flow and surge tolerance determine the bill of materials rather than a single universal rectifier specification.
- End-use mix: Automotive and EV/HEV systems account for an estimated ~28% of market value; photovoltaic, storage and wind applications contribute ~18%, while charging equipment represents ~17%. The remaining industrial, computing, rail and miscellaneous uses diversify demand across equipment cycles.
- Regional leadership: Asia-Pacific controls an estimated ~48% of 2025 demand and has the highest modeled expansion rate at ~29.1% CAGR. Its position combines China-based vehicle and converter production with Japanese and Korean device engineering and manufacturing ecosystems.
- Commercial differentiation: Suppliers compete on reverse-recovery behavior, forward voltage, thermal resistance, automotive qualification and reliable wafer sourcing. Packaged rectifier modules can command different prices from bare dies even when the underlying junction technology is related.
SiC Rectifiers Market Overview
SiC rectifiers market was valued at USD 721 million in 2025 and is projected to reach USD 6,331 million by 2034, expanding at a 27.3% CAGR across the 2025–2034 interval. Asia-Pacific was the largest regional market in the base year, accounting for an estimated ~48% of global rectifier revenue.
A silicon carbide rectifier is a diode-based semiconductor component that conducts in one direction and blocks reverse voltage inside a power-conversion circuit. Its commercial appeal is especially strong where switching frequency and efficiency requirements expose the reverse-recovery losses of conventional silicon diodes. A 650 V component may be chosen for a compact power-factor-correction stage, while 1200 V or 1700 V ratings suit higher-voltage industrial and transport equipment. These devices are specified by repetitive reverse voltage, forward current, surge capability, package and temperature envelope, not merely by the name of the semiconductor material.
The revenue boundary includes SiC rectifying diodes sold as individual packaged parts, bare die and diode-containing rectifier bridges or assemblies. It covers 650 V, 1200 V and 1700 V product classes across the stated application categories, whether customers buy a discrete rectifier for board assembly or a higher-current packaged arrangement. It excludes SiC substrate wafers sold as materials, standalone MOSFET and IGBT switching devices, finished inverters, completed chargers, and system installation services. These exclusions matter because vertically integrated semiconductor groups report much larger businesses than their diode-specific rectifier shipments.
The conversion economics reflect several interacting specifications rather than an unconditional advantage over silicon. Lower switching loss can permit higher switching frequency, smaller magnetic components and reduced cooling demand; however, forward voltage and leakage must be evaluated at the actual junction temperature. Infineon markets CoolSiC Schottky rectifiers across low- and high-voltage classes, ST supplies industrial and automotive variants, and Microchip emphasizes ruggedness and supply flexibility. Those competing engineering propositions affect design wins in a way that broad semiconductor revenue statistics cannot resolve.
Vehicle electrification is an important adoption route because onboard charging, auxiliary conversion and some traction-system supporting circuits operate under stringent heat, size and reliability constraints. High-power DC charging equipment creates additional sockets, although a charger may use several different semiconductor types and only its qualifying rectifier content belongs in this market. The International Energy Agency projected substantial global electric-car sales for 2026; that vehicle figure provides downstream context, not a measurement of SiC diode sales. Growth depends on the quantity and value of rectifiers specified per converter and on the speed of qualification cycles.
The supply landscape is broad enough to include specialist device makers, diversified semiconductor groups and suppliers of finished diode assemblies. Qualification can take longer in automotive and rail equipment than in general industrial supplies, making existing approvals valuable even when an alternative device has a better headline electrical rating. Silicon carbide wafer quality, packaging yield and high-temperature testing influence realized gross margins. The modeled market expands rapidly through 2034, but a larger installed base will also bring price pressure as 650 V and 1200 V packages become easier for procurement teams to second-source.
Segment Analysis: By Type
By type, SiC rectifiers comprise the 650 V, 1200 V and 1700 V classes. The 1200 V segment is the revenue leader at an estimated ~53% in 2025; 650 V contributes ~34% and 1700 V the remaining ~13%. Each rating serves different bus-voltage and transient-margin needs, and the mix is weighted by both shipment volumes and average device selling prices.
| Voltage class | Electrical and packaging function | Market position |
|---|---|---|
| 650 V Silicon Carbide Rectifiers | The 650 V class addresses lower-voltage DC links and high-frequency rectification in single-phase supplies, compact industrial converters and selected vehicle auxiliaries. Designers compare junction capacitance, forward drop, leakage at 175°C, package creepage and current capability, often in the 1 A to 40 A range. Automotive variants must also satisfy AEC-Q101 qualification and survive repetitive thermal cycling. A small surface-mount package can make this class economical in distributed power stages that cannot accommodate large through-hole devices. | An estimated ~34% of 2025 revenue comes from this voltage tier, with modeled growth of ~27.9% per year. High unit volumes coexist with aggressive price comparison, so suppliers defend their positions using application-specific reliability data, compact footprints and low capacitive charge. The 650 V rating is particularly relevant to server supplies and PFC circuits, where switching efficiency and assembly density influence the entire converter design. |
| 1200 V Silicon Carbide Rectifiers | A 1200 V rectifier accommodates higher-voltage industrial buses, solar conversion stages and fast-charging architectures where adequate blocking margin is essential. The category includes bare die, TO-247 or D2PAK discrete packages and bridge configurations designed for larger currents. Surge robustness and low reverse recovery are valuable where equipment must withstand line disturbances without excessive snubber losses. Suppliers therefore offer several current ratings and package formats even when the nominal voltage designation is identical. | This class leads at an estimated ~53% of base-year market value, expanding at a modeled ~26.4% CAGR. The position reflects widespread use in industrial power stages and infrastructure conversion, together with the premium available for robust packaged solutions. Semiconductor buyers compare the cost of the entire power stage rather than a diode alone, making 1200 V device selection sensitive to magnetics, cooling and long-term supply agreements. |
| 1700 V Silicon Carbide Rectifiers | The 1700 V class targets specialized high-voltage rectification where 650 V or 1200 V devices lack adequate electrical headroom. Its applications include demanding rail auxiliaries, higher-voltage industrial conversion and selected power infrastructure. Available bare-die and packaged specifications may involve current ratings around 50 A, but exact offerings depend on supplier and lifecycle status. Engineers prioritize insulation coordination, surge endurance and package thermal performance because replacement after equipment commissioning can be expensive. | The smallest voltage tier holds an estimated ~13% share in 2025 but carries the fastest modeled rate, ~29.1% CAGR, as high-voltage conversion designs widen. Commercial opportunities are narrower than for 1200 V parts and demand is often project-driven. Catalog obsolescence requires careful qualification: an older 1700 V diode listing should not be mistaken for a new production launch, and buyers frequently require an approved substitute before a long-life system is released. |
Why 1200 V is the commercial center
A 1200 V diode balances usable blocking margin with the availability of standard package families and multiple qualified vendors. This makes it attractive for converter platforms reused across charging, industrial automation and energy infrastructure. The 2025 share estimate of ~53% should be read as a revenue allocation, not a universal count of parts: larger-current 1200 V modules can generate more sales value per unit than small 650 V rectifiers. Buyers increasingly seek alternate qualified sources because the cost of revalidating a power stage can exceed a small device-price saving.
Segment Analysis: By Application
Applications are separated according to the equipment that consumes rectifier devices rather than by the entire value of that equipment. Automotive and EV/HEV systems lead at an estimated ~28% of 2025 sales; photovoltaic, storage and wind conversion account for ~18%, EV charging ~17%, industrial motor and drive ~16%, computing and UPS ~11%, rail ~6%, and miscellaneous uses ~4%.
| Application | Demand characteristics |
|---|---|
| Automotive & EV/HEV | The largest application accounts for an estimated ~28% of 2025 revenue and grows at a modeled ~28.8% CAGR. Onboard charging, DC/DC conversion and auxiliary electrification create opportunities for SiC rectifiers, but automotive qualification involves endurance, traceability and control of high-temperature electrical drift. The actual diode content per vehicle varies by architecture; an electric-car sales forecast cannot be translated directly into component revenue without a circuit-level bill of materials and realistic device pricing. |
| EV Charging | Public DC fast chargers and private high-power charging cabinets use multiple conversion stages, with rectifiers selected according to grid input, isolation topology and output power. An estimated ~17% share in 2025 and ~29.6% modeled CAGR reflect charger deployment and upgrades to higher-power configurations. Power density can favor SiC Schottky devices, but competition from synchronous rectification and alternate topologies makes device placement a design decision rather than an automatic function of charging-station count. |
| Industrial Motor/Drive | Variable-frequency drives, motor controllers and industrial AC/DC supplies use rectifier arrangements selected for reliability and lifetime cost. This application contributes an estimated ~16% of 2025 value, with modeled ~25.2% annual growth. Engineering buyers emphasize ruggedness, temperature limits and second-source qualification, while industrial purchasing cycles depend on capital spending and retrofit economics. A premium diode is easier to justify when it improves switching efficiency or allows a smaller heat sink across thousands of operating hours. |
| PV, Energy Storage, Wind Power | Renewable-energy equipment contributes an estimated ~18% of the base-year market, growing at ~25.9% annually in the modeled allocation. Photovoltaic inverters, storage converters and wind-power auxiliaries face distinct voltage and duty-cycle requirements, but all reward low-loss power conversion. The IEA-PVPS 2026 snapshot places 2025 solar additions in a very large installed-base context; module deployments and inverter replacement cycles provide demand indicators, not direct receipts for semiconductor rectifier vendors. |
| UPS, Data Center & Server | High-efficiency server power supplies and uninterruptible power systems form an estimated ~11% of 2025 rectifier revenue. Their modeled ~25.4% CAGR reflects rising conversion density and the need to control waste heat in large installations. Power-factor-correction stages are a relevant socket for low-charge diodes, while higher-power equipment may employ 1200 V devices. Designers balance conduction loss, thermal resistance, standby efficiency and manufacturing yield, making package innovation an important sales differentiator. |
| Rail Transport | Rail auxiliaries, traction support systems and infrastructure power supplies account for an estimated ~6% share, with ~26.3% modeled annual growth. Long equipment lifetimes, strict shock and thermal requirements, and prolonged approval procedures distinguish this channel from general industrial sales. A high-voltage rectifier may be specified for a platform that remains in service for decades, so continuity of supply and documented failure behavior can matter more than a marginal improvement in catalogue efficiency. |
| Others | The residual ~4% share encompasses medical imaging supplies, laboratory equipment, telecommunications power and additional specialized converters that do not fit the principal groups. Its modeled ~24.8% CAGR is lower than the market average because these niches are fragmented and qualification can be slow. Purchase orders often involve low quantities and unusual package requirements; distributors with broad inventories may be commercially important even where no single application is large enough to shape worldwide growth. |
Across applications, the revenue share of rectifiers differs from the installed value of converters because each equipment category uses a different combination of silicon, SiC and other power devices. A 650 V diode in a compact server supply is not interchangeable with a 1700 V rail part, even if both are described as silicon carbide rectifiers. Automotive and charging channels carry higher modeled growth than industrial retrofit demand, while the ~18% renewable-energy allocation reflects both new equipment and replacement requirements.
Regional Analysis
Regional demand for SiC rectifiers is shaped by the location of converter assembly, vehicle electrification, renewable-energy integration and the depth of qualified distribution networks. Asia-Pacific accounts for an estimated ~48% of 2025 value, followed by North America at ~26%, Europe at ~18%, South America at ~5% and the Middle East and Africa at ~3%. These modeled shares reflect rectifier purchases, not the regional revenue of complete EV chargers or solar installations.
Why does Asia-Pacific lead the global silicon carbide rectifier market?
China combines large-scale electric-vehicle manufacturing with solar-inverter assembly, while Japan and South Korea contribute device engineering and high-reliability industrial customers. North America has substantial design influence through automotive electronics, power supplies and semiconductor suppliers, whereas European demand is tied to automotive qualification and industrial efficiency. Smaller regions purchase many rectifiers embedded in imported power equipment, which makes local device demand less visible than equipment installations. The model assigns Asia-Pacific the largest base-year share, ~48%, and the highest growth rate, ~29.1% CAGR.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia-Pacific | Largest (~48%) | ~29.1% CAGR | EV, solar and industrial converter assembly | High-volume automotive qualification, device availability and wafer sourcing |
| North America | Second (~26%) | ~24.4% CAGR | Power supplies, charging and industrial electronics | AEC-Q101 evidence, reliability data and channel inventory |
| Europe | Third (~18%) | ~25.8% CAGR | Automotive, factory automation and energy infrastructure | Application engineering and continuity of qualified packages |
| South America | Emerging (~5%) | ~28.0% CAGR | Renewable conversion and imported charging equipment | Distribution economics, serviceability and landed cost |
| Middle East & Africa | Developing (~3%) | ~27.5% CAGR | Grid modernization, solar and infrastructure projects | Project certification, thermal endurance and spare-parts access |
Competitive Landscape of the Global SiC Rectifiers Market
Competition spans broad power-semiconductor manufacturers, specialized silicon carbide device suppliers and companies that assemble diode bridges. The market is not defined by total company revenue, because a diversified supplier may also sell MOSFETs, silicon diodes, substrates and complete modules outside the rectifier boundary. Device qualification, wafer sourcing and package breadth distinguish commercial strength more effectively than corporate scale alone.
Infineon and STMicroelectronics offer broad catalogues that support both industrial and automotive engineering teams. Their positions reflect application support, multiple voltage ratings and the ability to provide qualification records over long product lifecycles. ROHM adds bare-die options in 1200 V and 1700 V classes, which matter when customers package rectifiers inside proprietary power assemblies. These differentiated channels create competition not only on forward-voltage characteristics but also on who controls the integration step between die and finished equipment.
Vishay and Nexperia have expanded packaged rectifier choices, addressing designers who need practical footprints, surge capability and predictable thermal behavior. A 650 V surface-mount device may compete on board area and assembly cost, while a 1200 V, 20 A part can be evaluated for server infrastructure or industrial conversion. Microchip provides another channel for SiC Schottky components, with device ruggedness and manufacturing continuity part of its commercial proposition. Customers can second-source some standard ratings, but mechanical and thermal changes still require validation.
Historical supplier names require care when interpreting market participation. Microsemi is part of Microchip, GeneSiC became part of Navitas, and UnitedSiC was acquired by Qorvo; the acquired brands may still appear in legacy catalogues and purchasing records. A former supplier listing does not establish independent current sales, and an obsolete 1700 V part should not be represented as a fresh commercial launch. These distinctions help keep the competitive discussion tied to real product families rather than duplicating corporate entities.
Specialist bridge and module suppliers compete in a different part of the purchasing decision. SemiQ offers a 1200 V, 30 A Schottky bridge module that can reduce integration work for a converter manufacturer. The value of such a module includes packaging and thermal interfaces, so its average price differs from that of a bare die even when both rely on SiC rectification. Tier placement should therefore reflect active device offerings, customer qualification and supply capability, not merely the number of trademarks attached to a parent company.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Tier 1 | Infineon Technologies; STMicroelectronics; ROHM; onsemi; Wolfspeed | Large power-semiconductor portfolios, established automotive and industrial customer relationships, and experience in SiC device fabrication give these suppliers strong routes to high-volume design wins. Not every company has the same balance of discrete diodes, power modules and switching devices, so the tier denotes market reach rather than an equal share of rectifier revenue. Application engineers and qualified distribution networks are essential when customers seek long-lived 650 V and 1200 V designs. |
| Tier 2 | Vishay Intertechnology; Nexperia; Microchip Technology; Toshiba; Littelfuse; Mitsubishi Electric | These suppliers compete through specific diode architectures, packaging, surge performance and established customer channels. A 1200 V device designed for server power may not directly compete with a 1700 V specialty bare die, even though both belong to the market. Commercial differentiation includes validated temperature limits, package availability and the ability to maintain production when a customer extends a converter platform beyond its initial product cycle. |
| Tier 3 | SemiQ; Navitas Semiconductor; Qorvo; WeEn Semiconductors; PANJIT; KEC Corporation; BASiC Semiconductor | Specialists and regional suppliers can win narrower applications where rapid engineering support or a particular package is more important than global catalogue breadth. Acquired business names should be reconciled with current corporate ownership before treating them as separate competitors. In some channels the supplier provides bare die for third-party packaging; elsewhere a finished rectifier bridge is sold to an industrial equipment maker, producing materially different revenue per shipped unit. |
Key companies profiled
- Infineon Technologies
- STMicroelectronics
- ROHM
- Wolfspeed
- onsemi
- Microchip Technology
- Vishay Intertechnology
- Nexperia
- Toshiba Electronic Devices & Storage
- Littelfuse
- SemiQ
- Navitas Semiconductor
- Qorvo
- Mitsubishi Electric
- Fuji Electric
- WeEn Semiconductors
- PANJIT Group
- KEC Corporation
- BASiC Semiconductor
- Semikron Danfoss
Production Capacity, Packaging and Supply of SiC Rectifiers
Manufacturing economics depend on substrate quality, junction fabrication, wafer yield, package assembly and final electrical screening. The process chain can be divided into SiC crystal growth, substrate preparation, diode fabrication, singulation and packaging, followed by qualification. Only finished rectifying devices and qualifying bare die belong in rectifier market revenue; the upstream stages affect cost and availability without being counted again as device sales.
SiC substrates are more difficult to grow and process than conventional silicon wafers, which raises the cost of high-quality device material. A defect that reduces wafer yield can affect both 650 V and 1200 V products, while higher-voltage 1700 V devices may need additional design margin. Semiconductor suppliers mitigate these risks through improved process control, screening and longer-term wafer arrangements. When yields improve, the benefit can appear as lower cost per good die, greater package output or more flexibility to offer customers volume discounts.
Packaging creates a second source of differentiation because a rectifier is used under real current, temperature and insulation constraints. Surface-mount parts such as SlimSMA HV can reduce board height, while TO-247 and D2PAK formats address different assembly and heat-flow requirements. A 1200 V bridge may consolidate several junctions into one replaceable assembly. Packaging qualification includes thermal cycling, moisture sensitivity and creepage or clearance limits, so an apparently equivalent voltage rating does not guarantee compatibility in an existing converter design.
Capacity planning must account for demand from multiple SiC device categories sharing fabrication equipment. A wafer facility may produce diodes and MOSFETs, while an assembly site may package silicon and SiC products on related lines. This creates competition for manufacturing resources when EV, industrial and server demand accelerates at different rates. Procurement teams increasingly qualify more than one supplier for standard current and voltage classes, but that strategy remains constrained by electrical and mechanical differences that require a fresh power-stage test programme.
SiC Rectifiers Market Dynamics, Drivers, Restraints and Opportunities
Growth is driven by converter efficiency requirements, expansion of electrified transport and rising power density in industrial and digital infrastructure. The impact contributions below are a structured market-growth decomposition, expressed as percentage points of the modeled annual expansion. They are not individual company forecasts: each factor affects the volume, specification or price mix of rectifier devices, while manufacturing constraints offset a portion of the positive demand forces.
MARKET DRIVERS
Drivers Impact Analysis*
| Market Drivers | Impact Rank | CAGR Contribution (%) | 2026–2028 | 2029–2031 | 2032–2034 |
|---|---|---|---|---|---|
| EV onboard conversion and auxiliary electrification | High | +9.40% | High | High | Medium |
| High-power charging and grid-facing conversion | High | +7.10% | High | High | High |
| Renewable inverter and energy-storage upgrades | Medium-High | +6.00% | High | High | Medium |
| Data-center and UPS efficiency demand | Medium | +5.00% | Medium | High | High |
| Industrial drives and power-factor correction | Medium | +3.60% | Medium | Medium | High |
| Others (rail, specialty supplies and package innovation) | Low | +2.20% | Low | Medium | Medium |
Electrified transport expands qualified rectifier sockets
Automotive electrification increases the number of conversion stages that must meet strict power-density and reliability targets. Onboard chargers, auxiliary converters and some supporting traction circuits can specify 650 V or 1200 V SiC rectifiers to reduce switching losses. The modeled contribution of +9.40 percentage points is the largest positive driver, reflecting both device volume and richer qualification requirements. Vehicle sales remain an indirect indicator because different architectures use different rectification schemes.
Charging equipment increases high-voltage design activity
Fast-charging cabinets combine input rectification, isolation and output regulation, creating opportunities for high-efficiency diode stages where designers favor SiC. The +7.10 percentage-point contribution reflects expansion of charger installations and replacement with higher-power equipment, not the full value of charging stations. A 1200 V rectifier can be attractive when a converter requires voltage headroom and low recovery losses, although some circuits use synchronous switching devices instead.
Renewable and storage converters demand lower conversion losses
Photovoltaic inverters, battery-storage systems and wind-power auxiliaries operate over long duty cycles where a small efficiency improvement can influence lifetime economics. The modeled +6.00 percentage-point driver reflects additional conversion capacity and eventual equipment replacement. IEA-PVPS data document a large global solar installation base, but this is not equivalent to rectifier revenue. Device suppliers benefit only where converter designers actually select SiC diode stages and purchase qualifying components.
Digital infrastructure rewards compact high-frequency power stages
Server power supplies and UPS systems face increasing demands for efficiency and heat management as compute density rises. A SiC diode with low capacitive charge and negligible reverse-recovery tail can reduce switching loss in an appropriate PFC stage. The +5.00 percentage-point modeled effect includes a shift toward higher-value qualified packages as well as unit demand. Nexperia has explicitly targeted 1200 V devices at power-intensive infrastructure, supporting the relevance of this application channel.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Market Restraints | Impact Rank | CAGR Contribution (%) | 2026–2028 | 2029–2031 | 2032–2034 |
|---|---|---|---|---|---|
| High-quality SiC substrate and fabrication expense | High | -2.50% | High | Medium | Medium |
| Package and automotive qualification cost | Medium | -1.80% | High | High | Medium |
| Alternative converter topologies and silicon competition | Medium | -1.00% | Medium | Medium | High |
| Others (inventory cycles and distributor price pressure) | Low | -0.70% | Medium | Low | Low |
Substrate yield constrains price competitiveness
SiC crystal growth and device fabrication require control of material defects that can reduce the number of saleable junctions per wafer. This raises cost pressure on 650 V products competing with established silicon rectifiers and can limit attractive pricing for higher-current 1200 V packages. The modeled restraint is −2.50 percentage points, reflecting the risk that conversion benefits do not justify a price premium in every application. Process improvements can ease the constraint without eliminating the need for screening.
Qualification extends product-development lead times
A rectifier intended for automotive, rail or high-reliability industrial equipment must survive thermal, electrical and mechanical validation. Changing from one 1200 V device to another can require rechecking switching waveforms, package heat flow and surge margins, even when catalogue voltage and current match. This slows customer conversion and creates a −1.80 percentage-point modeled restraint. The same barrier can protect incumbent suppliers once their components are approved in a long-lived converter platform.
Other technologies remain viable in selected circuits
Silicon fast-recovery diodes, synchronous rectification and alternative power-stage architectures can compete with SiC Schottky devices, particularly where switching frequency is modest or component cost dominates. The −1.00 percentage-point modeled impact recognizes that not every new inverter or charger creates a silicon carbide diode socket. Designers compare total converter losses, electromagnetic behavior and package cost, so superior material properties alone cannot guarantee a commercial design win.
Channel inventory cycles can delay shipment growth
Distributors and original-equipment manufacturers may adjust component inventories when lead times normalize or end-equipment orders soften. Such corrections can temporarily depress semiconductor shipments even while the installed base of power converters expands. The residual −0.70 percentage-point restraint also reflects tender-driven price reductions in common packages. Suppliers with multiple qualified customers and stable long-term purchase commitments are better placed to absorb these short-cycle variations than niche producers serving one programme.
MARKET OPPORTUNITIES
More compact 650 V packages open dense power-supply designs
Small power supplies place a premium on board height, creepage and low capacitive charge. Vishay demonstrated a 0.95 mm-profile SlimSMA HV package with 650 V and 1200 V variants, indicating that mechanical design can create an additional route to specification. Manufacturers able to combine insulation, thermal performance and low switching loss may win sockets where a larger through-hole diode is impractical. The opportunity is strongest when an engineering team can document a system-level reduction in size or cooling burden.
High-voltage bridge assemblies broaden supplier value capture
A packaged 1200 V rectifier bridge can provide an integrator with tested thermal and electrical interfaces, reducing assembly work compared with sourcing multiple bare die. SemiQ offers a 30 A bridge example, demonstrating that this part of the market extends beyond single discrete packages. Suppliers can differentiate on integration quality and serviceability, especially in industrial conversion where replacement downtime is expensive. Revenue per bridge should not be confused with the number of individual semiconductor junctions it contains.
Advanced junction engineering may improve thermal margins
Research on SiC Schottky structures continues to target forward conduction loss and high-temperature behavior. Toshiba reported a semi-super-junction concept with lower resistance at 175°C under experimental conditions, suggesting a route to future performance gains. The commercial opportunity depends on successful manufacturing scale-up, qualification and competitive cost, not the laboratory result alone. Devices that sustain efficiency at high operating temperature could be attractive for compact chargers, industrial cabinets and renewable-energy power electronics.
Second-source engineering creates targeted sales opportunities
Many customers seek supply assurance for power components because a diode shortage can interrupt production of a much more expensive converter. Suppliers offering equivalent voltage classes, detailed switching curves and reliable packaging documentation can compete for alternate-source approvals. This creates a service-led opportunity even where overall demand is mature. The strongest candidates are those able to demonstrate electrical compatibility across the full temperature and surge envelope, rather than matching only the nominal 650 V or 1200 V rating.
Supply Chain and Value Creation in SiC Rectifiers
The SiC rectifier supply chain links crystal growers, wafer processors, diode fabrication lines, package assemblers and the engineers who design converters. Material quality determines achievable yield; device structure governs forward and reverse behavior; packaging controls heat flow and electrical isolation; and final equipment qualification converts a catalogue component into a repeatable revenue stream. Each stage affects market economics, although only qualifying diode sales belong to the stated revenue boundary.
Upstream material availability. The cost and consistency of silicon carbide substrate wafers influence rectifier economics, especially when manufacturers compete for high-quality material with MOSFET and other power-device programmes. A 1700 V diode may require different drift-region design and screening from a common 650 V part, so upstream quality is not interchangeable across every product class. Longer-term wafer sourcing can protect delivery schedules, while better crystal-growth yield can reduce cost without any change in the final device specification.
Device fabrication. Schottky and merged-PiN-Schottky junction architectures are selected to balance low reverse-recovery behavior with surge ruggedness and forward loss. Process control determines whether those benefits can be delivered consistently across wafer lots. Semiconductor suppliers may sell tested bare die to an assembler or package their own rectifiers for direct shipment, so the commercial point at which value is recognized varies. Quality screening is particularly important for parts expected to operate near the upper temperature limit of the package.
Assembly and reliability. A diode die must be connected to terminals, insulated appropriately and coupled to a thermal path that survives its duty cycle. Surface-mount packages support automated board assembly, whereas larger bridge formats can simplify high-current power-stage integration. Qualification tests may include moisture sensitivity, thermal cycling and electrical surge assessment. These processes add cost but can prevent expensive field failures, giving suppliers a way to compete beyond the forward-voltage number printed on a data sheet.
Customer design and distribution. Once a rectifier is approved in a charger, vehicle auxiliary or industrial power supply, the original-equipment manufacturer may purchase it for several years. Distributors support smaller customers with stocked 650 V and 1200 V products, while large buyers may negotiate direct agreements covering forecast volumes and replacement commitments. Design-in support matters because a change in package capacitance or thermal resistance can require circuit validation. The resulting switching costs help explain why supplier relationships persist even when prices decline.
Recent Developments in the Global SiC Rectifiers Market
- 10 July 2025 Product launch
Nexperia added two 1200 V, 20 A SiC Schottky diodes for energy-intensive server power supplies, telecommunications equipment and solar inverters. The PSC20120J uses a D2PAK surface-mount package, while the PSC20120L is supplied in a TO-247 through-hole format; both address operating temperatures up to 175°C. The commercial significance is greater package choice for high-voltage rectification rather than a new market-size estimate. Source - 9 July 2025 Product launch
Vishay introduced three Gen 3 merged-PiN-Schottky rectifiers in 650 V and 1200 V classes, with 1 A and 2 A current ratings. The SlimSMA HV format offers 3.2 mm minimum creepage distance and a low-profile package intended for dense power boards. Its significance lies in improving electrical isolation and compactness while preserving the fast-switching behavior required in modern PFC and DC/DC converter stages. Source - 9 June 2025 Technology development
Toshiba reported progress on semi-super-junction SiC Schottky barrier diodes and a separate trench-MOSFET structure. Under its research conditions, the 650 V diode concept reduced high-temperature on-resistance by about 35% at 175°C relative to a conventional SiC Schottky reference. The result illustrates an engineering direction for reducing conduction loss; commercial production and rectifier revenue should not be inferred from a technology announcement. Source - 29 January 2025 Portfolio expansion
Vishay announced 16 SiC Schottky diode products in SOT-227 packages, including dual-diode and bridge configurations for higher-current power conversion. The release widened package and current options beyond small surface-mount parts, supporting industrial engineers who prefer a packaged assembly. This development matters because integration and thermal-interface requirements influence which rectifier supplier is selected, not just the underlying 650 V or 1200 V silicon carbide junction. Source - 11 June 2024 Automotive qualification
Nexperia extended its 650 V SiC diode portfolio to automotive and additional industrial applications, offering merged-PiN-Schottky devices designed for demanding conversion conditions. Automotive qualification provides a route into equipment where traceability, temperature cycling and surge behavior must be documented before a design is released. The announcement illustrates the importance of qualification-led market access; it does not mean that all new electric vehicles contain the same diode count. Source - 9 June 2026 Adjacent device development
SemiQ described an expanded range of high-thermal-performance QSiC Dual3 modules for solid-state transformers and AC/DC converters serving AI data-center power systems. The announcement concerns a broader power-module family rather than a pure rectifier launch, so it is relevant only as context for changing converter architectures and possible integrated diode use. Its significance is the convergence of higher power density and packaging innovation across adjacent SiC device categories. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2021–2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| Historical Context | 2021–2024 |
| Market Size 2025 | USD 721 million |
| Market Size 2026 | USD 918 million |
| Market Size 2034 | USD 6,331 million |
| Growth Rate | CAGR of 27.3% for 2025–2034 |
| Unit | Value (USD million), with voltage and end-use demand classifications |
| Segmentation | By Type, By Application and By Region |
| By Type | 650V Silicon Carbide Rectifiers · 1200V Silicon Carbide Rectifiers · 1700V Silicon Carbide Rectifiers |
| By Application | Automotive & EV/HEV · EV Charging · Industrial Motor/Drive · PV, Energy Storage, Wind Power · UPS, Data Center & Server · Rail Transport · Others |
| By Region | Regional analysis of device revenue by voltage class, application and country North AmericaUnited States, Canada, Mexico EuropeGermany, France, Italy, United Kingdom, Rest of Europe Asia-PacificChina, Japan, South Korea, India, Southeast Asia, Rest of Asia-Pacific South AmericaBrazil, Argentina, Chile, Rest of South America Middle East & AfricaSaudi Arabia, United Arab Emirates, South Africa, North Africa, Rest of region |
| Key Companies Profiled | Infineon Technologies, STMicroelectronics, ROHM, Wolfspeed, onsemi, Microchip Technology, Vishay Intertechnology, Nexperia, Toshiba, Littelfuse, SemiQ, Navitas Semiconductor, Qorvo, Mitsubishi Electric, Fuji Electric, WeEn Semiconductors, PANJIT Group, KEC Corporation, BASiC Semiconductor, Semikron Danfoss |
| Customization Scope | Additional country breakdowns, diode voltage/current classes, end-use purchasing analysis and supplier product-family comparisons can be tailored to the customer’s equipment and sourcing requirements. |
Frequently Asked Questions
What is the size and growth outlook for the global SiC rectifiers market?
The market is valued at USD 721 million in 2025 and is projected to reach USD 6,331 million in 2034, with a 27.3% CAGR over the nine-year span. Growth is tied to more demanding power-conversion designs in electric vehicles, charging systems, renewable energy and industrial equipment. The monetary series measures qualifying rectifier devices, not the total value of converters or power-semiconductor businesses.
What products are included in SiC rectifier revenue?
Included products are silicon carbide rectifying diodes sold as discrete packages, bare die and diode-containing bridge or assembly formats. The voltage classes are 650 V, 1200 V and 1700 V, and purchases are attributed to the equipment application using the device. Silicon carbide substrates sold as material, standalone MOSFET switches, finished inverters and complete chargers are outside the boundary, even when the same manufacturers participate in those adjacent industries.
Which voltage class holds the largest market share?
The 1200 V category is the largest at an estimated ~53% of 2025 revenue because it serves a wide range of industrial, charging and energy-conversion equipment. The 650 V class contributes ~34%, with smaller packages prominent in high-frequency supplies, while 1700 V devices hold ~13% and address specialized high-voltage requirements. These are modeled revenue shares, so they should not be interpreted as the distribution of physical diode units.
Which applications account for the strongest rectifier demand?
Automotive and EV/HEV systems lead with an estimated ~28% of 2025 sales, followed by renewable conversion at ~18% and EV charging at ~17%. Industrial drives represent ~16%, server and UPS supplies ~11%, rail ~6%, and other uses ~4%. The relative importance of each application depends on whether a converter architecture selects SiC diodes, how many junctions it uses and the price of the qualified package.
Why is Asia-Pacific the leading region?
Asia-Pacific has an estimated ~48% of 2025 rectifier revenue and a modeled ~29.1% CAGR because vehicle, charger and inverter manufacturing is concentrated across several Asian economies. China contributes major equipment assembly demand, Japan supplies specialized power-device engineering, and South Korea and India provide additional electronics and energy applications. The share refers to regional rectifier purchases and should not be mistaken for a country’s portion of global semiconductor wafer output.
How do SiC rectifiers differ from silicon diodes?
Silicon carbide Schottky rectifiers can operate with negligible reverse-recovery charge, reducing switching losses in suitable high-frequency power stages. They also support high blocking voltages and elevated junction temperatures, but forward conduction loss, leakage, packaging and cost still require circuit-level assessment. A 650 V SiC diode is not automatically the best choice for every low-frequency supply, and a 1700 V component may be unnecessary where lower voltage ratings provide adequate design margin.
Who are the important manufacturers of SiC rectifiers?
Infineon, STMicroelectronics, ROHM, Vishay, Nexperia, Microchip, Toshiba and other semiconductor suppliers offer relevant diode or rectifier product families. SemiQ provides an example of packaged Schottky bridge capability. Some historical brand names now belong to larger groups, including Microsemi under Microchip and GeneSiC under Navitas, so commercial comparisons should distinguish current corporate ownership from older catalogue labels. Supplier selection depends on active product availability and qualified performance.
What are the main barriers to wider SiC rectifier adoption?
Substrate quality and fabrication expense can make a SiC device costlier than a silicon alternative, particularly in price-sensitive 650 V applications. Automotive and industrial qualification add time and testing costs, while synchronous rectification and alternative circuit topologies may eliminate a diode socket entirely. Customers also consider package compatibility, surge robustness and delivery reliability. These constraints explain why the modeled growth trajectory does not imply universal replacement of conventional rectifiers.
Where can advanced SiC rectifier packages create opportunities?
Compact surface-mount packages can help reduce board height and support automated assembly in high-density supplies, while 1200 V bridge arrangements simplify some high-current industrial designs. Product announcements from Vishay and Nexperia demonstrate the importance of creepage, temperature endurance and package choice alongside electrical ratings. A device maker can capture value by solving a mechanical or reliability problem that limits converter efficiency, not merely by improving a single semiconductor specification.
What geography and years does the study cover?
The base year is 2025, the estimated year is 2026 and the forecast extends to 2034, with historical context from 2021 through 2024. The geographic framework includes North America, Europe, Asia-Pacific, South America and the Middle East and Africa. Analysis covers three voltage classes and seven application groups, with regional demand evaluated separately from upstream wafer production and downstream sales of complete power-conversion equipment.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF