Key Statistics
Key Takeaways
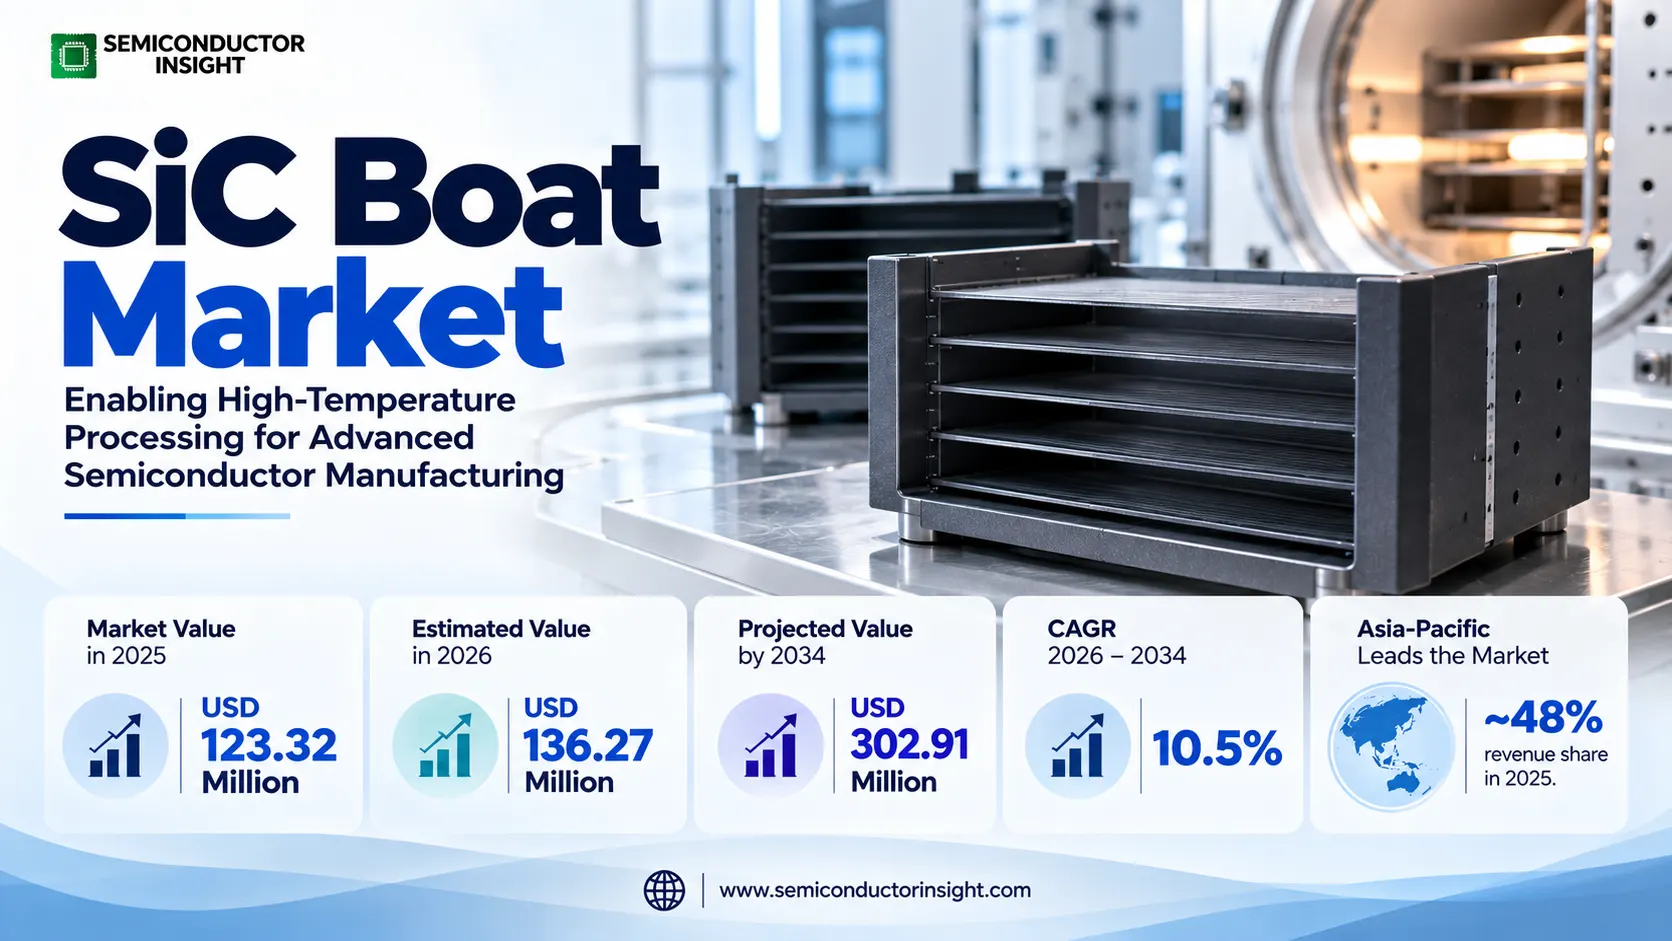
- Market scale: global sales of silicon-carbide wafer boats stood at USD 123.32 million in 2025 and are forecast to reach USD 302.91 million by 2034, representing 10.5% annual expansion in the 2026–2034 outlook as thermal processing lines demand stable, contamination-resistant wafer fixtures.
- Horizontal designs: horizontal furnace boats account for a modeled ~57% of 2025 market revenue, reflecting installed batch diffusion and oxidation tools; vertical designs hold ~43% and gain relevance where high-density wafer loading, particle control and automated handling shape new capital purchases.
- Semiconductor processing: wafer-fabrication and device-processing customers represent an estimated ~67% of demand, while LED manufacturers account for ~18% and photovoltaic producers ~15%; equipment configuration and required surface purity, rather than ceramic mass alone, determine the value of each carrier.
- Asia-Pacific leadership: the region represents an estimated ~48% of 2025 revenue, with China, Taiwan, Japan and South Korea concentrating furnace installations, specialty ceramic fabrication and qualification activity; North America follows at ~26%, with Europe at ~16%.
- Commercial constraint: buyers must reconcile ceramic durability with expensive forming, sintering, machining and CVD finishing; each carrier requires geometry-specific qualification, so suppliers compete on particle generation, dimensional stability, delivery repeatability and furnace compatibility rather than simple catalogue price.
Global SiC Boat Market Overview
SiC boat market was valued at USD 123.32 million in 2025 and is forecast to reach USD 302.91 million by 2034, a CAGR of 10.5% over 2026–2034. The 2026 estimate is USD 136.27 million. Asia-Pacific leads with an estimated ~48% share as the principal manufacturing centre for semiconductor, LED and photovoltaic thermal-processing equipment.
A silicon-carbide boat is a precision ceramic fixture that holds wafers or other substrates at controlled spacing while a furnace runs diffusion, oxidation, annealing or comparable heat treatments. The carrier must tolerate repeated heating and cooling without distorting the wafer pitch, shedding particles or reacting with process gases. Customers specify slot geometry, support points, orientation and loading equipment interfaces, making a qualified boat a process-critical consumable rather than an interchangeable piece of kiln furniture.
The revenue boundary includes finished SiC boats, related ceramic wafer carriers and variants made by sintering, reaction bonding or applying a chemical-vapour-deposited SiC surface. It captures the supplier value of machined and inspected assemblies delivered for semiconductor, LED and solar-cell process lines. It excludes the wafers themselves, bare SiC power-device substrates, complete furnaces, diffusion chemicals and downstream electronic components; these are separate purchasing categories even when sold to the same factory.
Several material routes coexist because a furnace designer may value low thermal mass, high stiffness, surface cleanliness or price differently. Dense sintered ceramics resist aggressive environments, reaction-bonded structures support complex shapes, and CVD SiC surfaces provide a controlled contact layer for contamination-sensitive recipes. CoorsTek, Ferrotec and Kyocera document semiconductor ceramic systems, while specialist manufacturers illustrate how slot count, pitch and protective coatings become commercially distinct order specifications.
A carrier is exposed to cumulative process stress rather than a single static temperature. Repeated transfers, mechanical contact at each wafer slot and changes in furnace atmosphere can alter surface roughness and particulate behaviour long before the structure fractures. Replacement demand therefore arises from preventive maintenance, new wafer formats and recipe requalification as well as from newly installed furnaces. A supplier with repeatable machining and metrology can preserve a long customer relationship despite relatively low unit shipment volume.
The strongest demand links are the number of thermal-processing chambers operating at high utilisation and the intensity of wafer-handling qualification. Semiconductor fabs typically apply the strictest contamination specifications, photovoltaic lines purchase for large batch throughput, and LED customers balance fragile substrate support with uniform heating. A shift toward larger wafers or different batch geometries can increase the engineered value per boat even where the number of installed furnaces rises only gradually.
Segment Analysis: By Type
The type classification separates horizontal and vertical wafer boats according to how wafers are arranged relative to the furnace axis. Horizontal boats hold an estimated ~57% of 2025 revenue and advance at about ~10.0% annual growth; vertical carriers account for ~43% and grow near ~11.1%. These shares reflect installed tool architectures and replacement economics rather than an asserted industry census of every furnace chamber.
| Type | Function | Market position |
|---|---|---|
| Horizontal | Horizontal SiC boats carry wafers along a longitudinal rail or slotted body into a tube furnace. The carrier geometry is designed around the tube diameter, paddle loading system and allowable wafer sag, while spacing controls gas circulation and thermal exposure. VeTek offers horizontal SiC wafer boats for furnace processing, illustrating how high-purity ceramic construction is combined with dimensional matching to existing diffusion and oxidation installations. | The largest modeled class represents ~57% of 2025 sales, reflecting replacement orders from installed horizontal batch furnaces and equipment built around familiar boat dimensions. Procurement decisions centre on mechanical fit, surface treatment, breakage history and maintenance intervals; a replacement can be more valuable when it avoids a recipe change. Mature applications limit its modeled growth to ~10.0%, below the faster conversion of vertical configurations. |
| Vertical | Vertical wafer boats stack substrates in a tall fixture for a furnace with upright loading and carefully controlled wafer pitch. Support surfaces must remain aligned through thermal cycling while allowing automated elevators or robots to engage the carrier. The design concentrates a large batch in a compact process chamber, but qualification includes handling loads, slot-to-slot variation, vibration and particle performance under the customer’s actual temperature profile. | Vertical configurations contribute a modeled ~43% share and a ~11.1% annual growth path as advanced fabs modernise batch processing and favour automated transfer. Suppliers face greater documentation and metrology demands when customer tools operate with narrow dimensional tolerances. The growth premium does not imply that vertical boats are universally superior: retrofitting a horizontal line may cost more than retaining its proven fixture architecture. |
Horizontal carrier engineering
Horizontal products require coordinated selection of rail stiffness, slot opening and wafer-contact geometry because thermal expansion occurs along a relatively long fixture. At elevated temperature the carrier must support the full wafer batch without obstructing gas movement. A ceramic that survives chemically but produces local abrasion at a slot can still fail a semiconductor acceptance test, so finish and inspection protocols often determine the final purchase decision.
Replacement economics are unusually important in horizontal installations. A factory may order a new SiC carrier to match an established tube, paddle and cassette interface, avoiding lengthy recipe changes and additional downtime. For solar-cell production, throughput and reliable batch loading matter alongside cost, whereas mature semiconductor processes may accept a higher-priced part when it reduces defect excursions across repeated furnace cycles.
Vertical carrier qualification
An upright furnace presents different structural loads, with wafer support features repeated through the height of the boat. Manufacturers control pitch uniformity, surface contamination and handling-interface tolerances so robotic loading does not introduce wafer edge damage. As a result, a new boat often enters production only after trials that compare particle results, thermal performance and slot-level defects against an incumbent fixture.
Vertical designs can benefit from higher-value upgrades in fabs that consolidate batch processes or move toward more automated material handling. However, buyers frequently qualify more than one ceramic composition before changing an installed recipe, which lengthens initial sales cycles. The resulting market opportunity rewards suppliers able to document material traceability and reproduce a proven geometry from one production lot to the next.
Annual segment revenue trajectories
The following modeled annual figures show how the three segmentation views evolve from the same global starting point. Region, type and application are alternative ways of allocating market revenue, not additive product categories, so their subtotals should be compared within each table rather than summed across the three views. Values are in USD million and rounded to one decimal; each trajectory follows the documented base-year allocation and segment-specific annual growth assumption.
Region modeled revenue (USD million)
| Year | Asia-Pacific | North America | Europe | Latin America | Middle East & Africa |
|---|---|---|---|---|---|
| 2025 | 59.2 | 32.1 | 19.7 | 7.4 | 4.9 |
| 2026 | 65.9 | 35.1 | 21.6 | 8.1 | 5.4 |
| 2027 | 73.5 | 38.5 | 23.7 | 8.8 | 6.0 |
| 2028 | 81.8 | 42.2 | 26.0 | 9.6 | 6.6 |
| 2029 | 91.2 | 46.3 | 28.6 | 10.5 | 7.2 |
| 2030 | 101.6 | 50.7 | 31.3 | 11.5 | 7.9 |
| 2031 | 113.1 | 55.6 | 34.4 | 12.5 | 8.7 |
| 2032 | 126.0 | 60.9 | 37.7 | 13.7 | 9.6 |
| 2033 | 140.4 | 66.8 | 41.4 | 15.0 | 10.5 |
| 2034 | 156.4 | 73.2 | 45.4 | 16.3 | 11.6 |
Type modeled revenue (USD million)
| Year | Horizontal | Vertical |
|---|---|---|
| 2025 | 70.3 | 53.0 |
| 2026 | 77.3 | 58.9 |
| 2027 | 85.1 | 65.5 |
| 2028 | 93.6 | 72.8 |
| 2029 | 102.9 | 80.9 |
| 2030 | 113.2 | 89.9 |
| 2031 | 124.5 | 99.9 |
| 2032 | 137.0 | 111.0 |
| 2033 | 150.7 | 123.4 |
| 2034 | 165.7 | 137.1 |
Application modeled revenue (USD million)
| Year | Semiconductor | LED | PV |
|---|---|---|---|
| 2025 | 82.6 | 22.2 | 18.5 |
| 2026 | 91.6 | 24.1 | 20.5 |
| 2027 | 101.6 | 26.2 | 22.7 |
| 2028 | 112.7 | 28.5 | 25.1 |
| 2029 | 125.0 | 31.0 | 27.8 |
| 2030 | 138.6 | 33.7 | 30.8 |
| 2031 | 153.7 | 36.6 | 34.1 |
| 2032 | 170.5 | 39.8 | 37.7 |
| 2033 | 189.0 | 43.3 | 41.7 |
| 2034 | 209.6 | 47.0 | 46.2 |
Segment Analysis: By Application
Three end-use applications are tracked: Semiconductor, LED and PV. Semiconductor manufacturing leads at an estimated ~67% of 2025 value, LED contributes ~18%, and photovoltaic thermal processing accounts for ~15%. Their demand differs in acceptable contamination, wafer throughput, temperature cycling and the commercial cost of unplanned downtime; all three require stable ceramic fixtures but do not purchase an identical specification.
| Application | Demand characteristics |
|---|---|
| Semiconductor | Semiconductor fabs use SiC wafer boats in controlled high-temperature steps where wafer-edge damage, mobile-metal contamination and particle release can undermine yield. This application holds a modeled ~67% share and grows around ~10.9% annually, supported by recurring furnace maintenance and requalification as process recipes change. Purchase orders typically reference chamber compatibility, metrology results, handling fit and evidence from prior wafer runs rather than an undifferentiated material grade. |
| LED | LED substrate processing uses thermal carriers for compound-semiconductor or related manufacturing steps in which mechanical support and surface cleanliness affect repeatability. The modeled ~18% market share reflects a smaller equipment base than silicon wafer fabrication, with annual growth near ~8.7%. Demand concentrates on durable fixtures compatible with particular batch sizes and fragile substrate formats; purchasing can be cyclical when display, lighting or specialty optoelectronics manufacturers defer equipment upgrades. |
| PV | Photovoltaic production consumes ceramic boats for diffusion and thermal treatments used in solar-cell fabrication. It represents a modeled ~15% share and a ~10.7% growth trajectory, with buyers sensitive to batch throughput, breakage and cost per processed wafer. ADCERAX documents SiC boats for photovoltaic furnaces, showing why a solar factory may select a mechanically robust carrier that can endure repetitive high-volume processing rather than pay for every feature required in leading-edge semiconductor work. |
Application mix influences average selling value more strongly than wafer counts alone. A semiconductor customer may require extended traceability, tight particle specifications and lot-level acceptance documentation, while a photovoltaic buyer places heavier emphasis on repeated high-volume cycles and replacement cost. These requirements lead manufacturers to offer different finishing and inspection packages around similar base ceramics; comparing shipments without specification detail would obscure the value distribution between the three applications.
LED and PV demand can also move independently of the semiconductor capital cycle. A solar producer may retrofit diffusion equipment for a new cell architecture while integrated-circuit fabs postpone expansion, and LED factories may change substrate size without adding a corresponding number of furnaces. Suppliers that retain flexible tooling and small-batch machining capacity can serve such shifts without depending exclusively on large new-fab construction projects.
Regional Analysis
Asia-Pacific holds the largest modeled 2025 share at ~48%, followed by North America at ~26%, Europe at ~16%, Latin America at ~6% and the Middle East and Africa at ~4%. These allocations reflect the location of wafer-furnace customers and ceramic manufacturing ecosystems, not audited national sales totals. Asia-Pacific has the highest modeled regional growth at ~11.4%, while North America advances near ~9.6%, Europe ~9.7%, Latin America ~9.2% and the Middle East and Africa ~10.0%.
How do furnace architectures and purchasing channels differ by region?
The regional market is governed by where batch furnaces are installed, who approves process consumables and whether a local specialist can machine replacement fixtures to the original geometry. Asian suppliers often serve both domestic tool makers and export customers, whereas buyers in North America and Europe may demand extensive quality records and long-term interchangeability. The same wafer boat can therefore move through different commercial channels even though its ceramic composition is unchanged.
The modeled distribution also reflects distinct end-use mixes. Asia-Pacific has substantial semiconductor, LED and photovoltaic manufacturing; North America gives greater weight to high-purity semiconductor process control; Europe combines industrial semiconductor capacity with specialty ceramic expertise. Latin American demand is concentrated in maintenance and limited advanced manufacturing, while Gulf and African orders more often depend on imported equipment, research facilities or isolated industrial projects rather than large domestic furnace fleets.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia-Pacific | ~48% modeled share | ~11.4% annual growth | Semiconductor and PV furnace density | Supplier selection depends on short qualification cycles, repeatable slot pitch and access to replacement inventory; customers also examine ceramic grade and coating traceability when introducing a new carrier into established high-temperature production. Local tool compatibility and acceptance testing determine whether a supplier wins a recurring spare-parts programme instead of a single trial order. |
| North America | ~26% modeled share | ~9.6% annual growth | High-purity process control | Fab engineers emphasise particle data, dimensional certificates and change management for replacement parts. A ceramic boat may remain on an approved-vendor list for years, making documentation and stable manufacturing routes decisive during procurement. Suppliers must also demonstrate that their packaging, cleaning process and handling instructions preserve the qualified condition of the fixture until installation. |
| Europe | ~16% modeled share | ~9.7% annual growth | Specialty semiconductor and engineered ceramics | Industrial buyers seek dependable technical support and consistent furnace-interface tolerances. Material properties, machining precision and the ability to supply small qualified lots can outweigh a lower catalogue price from an unfamiliar supplier. Replacement parts may be required for mature process tools, making drawing archives, change control and the ability to reproduce an older geometry commercially important. |
| Latin America | ~6% modeled share | ~9.2% annual growth | Imported process equipment and maintenance | Import logistics and replacement lead times dominate many purchasing decisions. Distributors able to identify the exact boat drawing and consolidate a small shipment may win orders even when regional manufacturing volumes remain comparatively limited. Technical support is valuable because a mismatched slot design can delay furnace operation, and local customers may have limited access to ceramic rework capability. |
| Middle East & Africa | ~4% modeled share | ~10.0% annual growth | Selective research and industrial applications | Demand follows specific laboratory or industrial installations rather than a broad wafer-fab cluster. Suppliers need export documentation, handling protection and technical support for users with relatively infrequent replacement requirements. Each order may require coordination with the original furnace maker, and delivery reliability can matter more than annual volume discounts when the installed equipment is highly specialised. |
Competitive Landscape of the Global SiC Boat Market
Competition is divided between established engineered-ceramics groups, semiconductor process-component specialists and smaller custom fabricators. A buyer may compare dense sintered SiC with reaction-bonded or CVD-coated constructions, then require samples for the exact furnace. The relevant commercial advantage is the ability to reproduce a qualified carrier with low particle generation, accurate slot geometry and dependable lead times; supplier revenue cannot be inferred from the breadth of an online catalogue.
Kallex offers wafer boat products and has documented vertical carrier development, positioning the company within specialised semiconductor ceramic fixtures. Ferrotec Taiwan participates through semiconductor process components and CVD-SiC technologies, while CoorsTek supplies engineered ceramics across wafer handling and thermal equipment applications. Their roles overlap but are not identical: a material-system provider can compete through purity and durability, whereas a niche boat fabricator may win on fast geometry-specific production.
Kyocera documents ceramic wafer-boat material choices and high-temperature properties, providing an established technical benchmark for customers evaluating SiC against quartz or other ceramic alternatives. A qualification decision may involve mechanical strength, thermal expansion, chemical exposure and cleaning compatibility. The supplier that best addresses a process-specific failure mechanism can earn a price premium even when the finished carrier has fewer visible features than a lower-cost rival.
Specialist producers such as 3X Ceramic Parts, FCT(Tangshan), Xi’an Zhongwei New Materials, Zhejiang Dongxin New Material and Shandong Huamei New Material appear among the profiled competitors. Their market positions should be understood through product capabilities and customer qualification rather than assumed global share rankings. In a fragmented custom-component category, capacity, material purity, machining yield and the ability to supply repeat orders matter more than headline corporate size.
VeTek, Semixlab, ADCERAX, Zirsec and other catalogued producers demonstrate how the competitive field extends beyond the eight named suppliers. A product listing may specify a 165-slot coated boat, a horizontal furnace geometry or a high-purity sintered carrier, but it does not automatically prove commercial scale or regional shipments. This distinction prevents adjacent wafer-handling and SiC-coated graphite businesses from being treated as identical to finished ceramic boat manufacturers.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Engineered ceramic platforms | CoorsTek; Kyocera; Ferrotec Taiwan Co | These companies compete through documented material properties, semiconductor process experience and broad ceramic engineering capability. Customers seeking contamination control and long production continuity may favour a supplier that can combine materials advice, finishing methods and quality records for a particular furnace family rather than provide only an off-the-shelf carrier. Repeatable acceptance inspection is especially valuable for multi-year procurement. |
| Dedicated carrier specialists | Kallex; 3X Ceramic Parts; FCT(Tangshan) | Specialists focus on wafer boat design, manufacturing and technical adaptation to process tools. A supplier can differentiate through horizontal or vertical geometries, handling-interface precision and responsiveness to engineering changes. The commercial risk is that qualification can take substantial time before the first repeat purchase, so technical service becomes a central sales capability. |
| Regional custom ceramics | Xi’an Zhongwei New Materials; Zhejiang Dongxin New Material; Shandong Huamei New Material | Regional fabricators compete on machining capability, material access, lead time and support for local equipment builders. Some customers prioritise rapid prototyping or short replacement cycles, while others demand extensive evidence of particle control. Product fit and qualification records determine which opportunities can be converted into durable supply contracts. Close coordination with the furnace design team helps avoid costly fit errors. |
Key companies profiled
- Kallex
- 3X Ceramic Parts
- CoorsTek
- Ferrotec Taiwan Co
- FCT(Tangshan)
- Xi’an Zhongwei New Materials
- Zhejiang Dongxin New Material
- Shandong Huamei New Material
SiC Boat Production Capacity and Manufacturing Economics
Manufacturing a furnace-ready SiC boat involves material preparation, forming, thermal processing, precision machining and surface finishing, followed by dimensional and cleanliness checks. The sequence varies between sintered, reaction-bonded and CVD-coated products. A manufacturer’s nominal ceramic capacity is not equivalent to saleable boat capacity because long, thin rails and closely spaced wafer slots require process-specific tooling and can be lost to distortion or machining damage.
The upstream choice of SiC powder grade and forming route determines much of the later cost structure. Reaction-bonded material can support complex shapes, while dense sintered ceramics may be preferred for other purity and corrosion requirements; an added CVD layer changes both the process steps and the finished contact surface. Material traceability matters when a wafer fab seeks to reproduce an accepted carrier after a production-lot change, because seemingly minor composition differences can affect cleaning and contamination behaviour.
Precision machining is a major conversion bottleneck. A boat may contain dozens or more than one hundred closely spaced support features, each of which must meet the wafer pitch and edge-contact requirements. The documented 165-slot VeTek configuration illustrates how a single part combines many repeated dimensions. Grinding, inspection and cleaning are therefore integral manufacturing operations, and a defect discovered after coating or final inspection can consume more value than one found during early forming.
Commercial capacity is constrained by qualification as well as factory output. A new furnace geometry can require trial lots, thermal cycling and particle measurements before a customer authorises routine deliveries. Conversely, once a design is approved, stable repeat production can generate attractive replacement business with relatively little additional product engineering. Suppliers must balance custom prototypes against recurring programmes while retaining enough material and machining flexibility to handle unexpected maintenance orders.
SiC Boat Market Dynamics, Drivers, Restraints and Opportunities
Demand for SiC wafer boats responds to the installed base and utilisation of high-temperature process furnaces, with incremental value from tighter cleanliness standards and new carrier designs. Growth is supported by semiconductor process control, photovoltaic diffusion throughput and a gradual shift to engineered high-purity surfaces. It is restrained by expensive ceramic conversion, customer qualification delays and the long life of established furnace fixtures, making replacement timing uneven across applications.
MARKET DRIVERS
Drivers Impact Analysis*
| Market Drivers | Impact Rank | CAGR Contribution (%) | 2026–2028 | 2029–2031 | 2032–2034 |
|---|---|---|---|---|---|
| Semiconductor furnace utilisation and capacity additions | High | +5.10% | High | High | Medium |
| High-purity carrier and contamination-control upgrades | High | +3.50% | Medium | High | High |
| Vertical batch furnace and automation conversion | Medium-High | +2.80% | Medium | High | High |
| PV diffusion and thermal process throughput | Medium | +2.30% | High | Medium | Medium |
| Recurring maintenance and qualified spare demand | Low-Medium | +1.70% | Medium | Medium | Medium |
| Others (LED thermal processing and laboratory pilot lines) | Low | +0.90% | Low | Medium | Medium |
Semiconductor thermal processing remains the anchor
Semiconductor processing is the largest modeled application at ~67% of 2025 sales because production lines require carriers that protect valuable wafers during repeated high-temperature steps. New tools add an initial population of boats, while operating chambers create recurring demand through maintenance and requalification. The commercial mechanism is therefore a combination of installed-furnace growth and replacement intensity, not a one-for-one relationship with the number of chips shipped.
Cleanliness requirements raise engineered value
A ceramic component can withstand furnace heat yet fail a process acceptance test if it sheds particles or introduces trace contaminants. CoorsTek and Ferrotec document SiC materials and coatings for semiconductor environments, illustrating why high-purity surfaces and controlled finishing command attention. Buyers may accept higher unit costs when a carrier reduces yield risk, especially on processes where a small defect excursion affects many wafers in a batch.
Vertical furnace adoption changes carrier specifications
The vertical type has a modeled ~43% share but a faster growth trajectory than horizontal designs because new automated batch tools demand precise upright fixtures. Changing orientation requires a different mechanical structure, handling interface and wafer support geometry, creating fresh qualification work for ceramic suppliers. This demand is strongest when a fab replaces or expands a tool platform; existing horizontal furnaces can continue purchasing their established carriers for many years.
Photovoltaic batch processing supports volume
Solar-cell manufacturing uses diffusion and annealing equipment that requires durable substrate fixtures under repetitive thermal cycles. ADCERAX lists SiC boats for photovoltaic processing, linking the material to a distinct high-throughput application. PV accounts for a modeled ~15% of 2025 value, and suppliers serving it compete heavily on replacement economics and handling durability rather than the most stringent semiconductor-grade cleanliness package.
Preventive maintenance creates a recurring order stream
Furnace boats are exposed to thermal cycling, cleaning chemicals and mechanical contact each time wafers are loaded. Operators may replace a carrier before catastrophic failure when wear or surface condition threatens process consistency. The resulting aftermarket demand can persist through periods of restrained equipment investment, but suppliers need accurate drawings and stable material recipes to reproduce a qualified part without restarting the entire process approval cycle.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Market Restraints | Impact Rank | CAGR Contribution (%) | 2026–2028 | 2029–2031 | 2032–2034 |
|---|---|---|---|---|---|
| Ceramic forming, machining and CVD finishing cost | High | -2.40% | High | High | Medium |
| Extended fab qualification and change-control cycles | Medium-High | -1.80% | High | Medium | Medium |
| Long replacement intervals for established fixtures | Medium | -1.10% | Medium | Medium | High |
| Others (freight risk, breakage and limited custom capacity) | Low | -0.50% | Medium | Low | Low |
High conversion cost limits price flexibility
A finished boat contains more value than its ceramic raw material because forming, firing, grinding, coating and inspection can each require specialised equipment. Thin support rails and closely spaced slots create scrap risk, while contamination-sensitive applications add cleaning and packaging controls. These costs restrict the ability of smaller suppliers to cut prices without weakening quality, and they can discourage buyers from upgrading a proven fixture when the existing design remains serviceable.
Qualification slows supplier substitution
A wafer fab cannot evaluate a new SiC boat solely by checking nominal dimensions. Engineers may require thermal cycling, particle measurements, chemical compatibility and multiple process runs before approving production use. This protects established suppliers but delays new entrants, particularly where an alternative ceramic grade changes the wafer-contact surface. The cost of lost process time can exceed the purchase-price saving offered by an unqualified part.
Durable carriers lengthen the replacement cycle
Silicon carbide is chosen partly because it resists high temperatures and difficult process environments, so a well-maintained boat may remain in use across many production campaigns. That durability is valuable to customers but makes recurring orders less frequent than for short-lived consumables. Sales can therefore fluctuate with maintenance shutdowns, new chamber introductions and unexpected breakage rather than rise smoothly with wafer output.
MARKET OPPORTUNITIES
Surface-engineered replacements for installed furnaces
Suppliers can target existing furnace fleets with upgraded SiC coatings or refined contact surfaces that improve contamination control while preserving the original loading geometry. This approach reduces the disruption of changing a complete tool platform and gives manufacturers a route to higher-value replacement orders. Success depends on demonstrating that the revised material behaves consistently during the customer’s actual process and cleaning sequence.
Geometry-specific service for smaller fabs
Many buyers need a replacement carrier matching a particular tube diameter, slot pitch and robotic interface rather than a high-volume standard part. Specialist ceramic firms that maintain drawing control and can machine short production runs may capture these orders even against larger competitors. The opportunity is strongest when a customer values a rapid qualified spare more than the lowest unit cost and cannot tolerate prolonged equipment downtime.
Cross-application use of manufacturing expertise
A producer experienced in semiconductor-grade SiC machining can adapt its process knowledge to LED and photovoltaic furnace fixtures, provided the different contamination and throughput requirements are respected. The applications should not be priced or qualified identically, but shared expertise in ceramic forming and precision inspection can improve capacity utilisation. This diversification may reduce exposure to any single semiconductor investment cycle.
Global SiC Boat Supply Chain Analysis
The supply chain begins with silicon-carbide powders, ceramic forming materials and coating inputs, then moves through high-temperature densification, precision machining, surface preparation and final inspection. Finished boats reach wafer fabs through direct technical sales, furnace-equipment manufacturers or maintenance channels. The commercial bottleneck is often the transfer of a proven design into repeatable production, not simply access to SiC feedstock or a catalogue of standard carrier shapes.
Materials. Feedstock composition and powder processing influence the porosity, thermal properties and achievable purity of the ceramic. A dense sintered body and a reaction-bonded structure may have different advantages in cost, machinability and chemical exposure, so suppliers select routes against the target furnace environment. Customers purchasing critical carriers may require material traceability because a change in raw-material lot or finishing chemistry can alter process contamination risk.
Manufacturing. Boat production combines complex shape control with finishing operations that can damage thin support features. Slot pitch, rail straightness and surface condition are checked after firing and machining, while coated variants add deposition and subsequent inspection. Producers with repeatable metrology and carefully controlled handling reduce the likelihood of late-stage scrap. The number of good, qualified carriers is therefore a better indicator of effective capacity than the tonnes of ceramic produced.
Distribution. Direct sales to a fab allow a supplier to coordinate drawings, process specifications and qualification trials, while tool builders and maintenance distributors can bundle a carrier with service. Import-dependent regions rely more heavily on intermediaries that identify exact part numbers and protect fragile precision features during shipment. Technical documentation travels with the component because an incorrect geometry or unapproved material can interrupt a customer’s furnace schedule.
Customer use. After delivery, the boat enters a controlled loading and cleaning routine designed around wafer contact and process atmosphere. Its service life depends on handling damage, thermal cycling, chemical exposure and the customer’s particle thresholds. A successful installation can produce repeat orders for identical spares, but process engineers may reopen qualification when changing wafer format, furnace recipe or ceramic finishing route. This makes customer retention a technical as well as commercial activity.
Recent Developments and Product Evidence in the SiC Boat Market
- 22 November 2024 Announced
Kallex publicised a vertical wafer-boat development as part of its silicon-carbide ceramic component activities. The announcement is relevant because a vertical furnace needs different wafer supports and automated handling interfaces from a horizontal tube, giving specialised manufacturers a distinct engineering opportunity. It provides evidence of product development rather than a quantified market shipment or a guarantee of adoption by any named fab. Source - October 2026 Portfolio status
Ferrotec’s accessible semiconductor-ceramics product information describes CVD silicon-carbide furnace components, including boats and holders. This documented portfolio illustrates the use of high-purity SiC surfaces in processing environments where contamination control matters. These products can serve contamination-sensitive processing environments where buyers compare ceramic material routes and qualified replacement histories, rather than assuming that all CVD-SiC parts have identical thermal or cleaning performance. Source - October 2026 Portfolio status
VeTek’s published coated wafer-boat specification identifies a configuration with 165 slots for furnace applications. The example makes the importance of slot spacing and wafer-contact consistency concrete: a large number of repeated support features must survive thermal cycling without causing mechanical damage. Such high-slot-count designs require precise dimensional control and a matching loading interface, creating a technical distinction between an approved carrier and a visually similar unqualified ceramic component. Source - October 2026 Portfolio status
Semixlab’s high-purity SiC carrier literature describes CVD-coated ceramic constructions intended for elevated-temperature semiconductor processing, including a cited configuration rated to 1600 degrees Celsius. The material and temperature specification illustrate why coating quality and structural stability are linked in buyer qualification. The specification illustrates a premium material route that may appeal to users facing high-temperature degradation, provided coating adhesion and particle behaviour are verified under their own furnace conditions. Source - October 2026 Portfolio status
Kyocera’s technical product materials identify silicon carbide as an option for ceramic wafer boats and explain relevant high-temperature material characteristics. These documents show that customers can select among ceramic material systems according to furnace atmosphere, cleanliness and dimensional needs. Buyers evaluating a ceramic replacement must consider process atmosphere and wafer-contact geometry alongside material datasheets, since a generic high-temperature rating does not establish suitability for a particular qualified recipe. Source - October 2026 Portfolio status
ADCERAX presents silicon-carbide boat products for photovoltaic diffusion and annealing, confirming an application outside integrated-circuit wafer processing. The product information supports the inclusion of PV in the demand segmentation while leaving actual customer revenue and shipment volumes unquantified. PV equipment operators evaluate carrier lifetime, batch loading reliability and replacement economics, making the documented application commercially different from the highest-purity semiconductor furnace segment. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2021–2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| Historical Context | 2021–2024 |
| Market Size 2025 | USD 123.32 million |
| Market Size 2026 | USD 136.27 million |
| Market Size 2034 | USD 302.91 million |
| Growth Rate | CAGR of 10.5% from 2026–2034 |
| Unit | Revenue (USD million); modeled shares and segment growth rates |
| Segmentation | By Type, By Application and By Region |
| By Type | Horizontal · Vertical |
| By Application | Semiconductor · LED · PV |
| By Region | Five regions assessed by Type, Application and selected countries North AmericaUnited States, Canada, Mexico EuropeGermany, France, Italy, United Kingdom, Rest of Europe Asia-PacificChina, Taiwan, Japan, South Korea, Southeast Asia, Rest of Asia-Pacific Latin AmericaBrazil, Argentina, Chile, Colombia, Rest of Latin America Middle East & AfricaIsrael, United Arab Emirates, Saudi Arabia, South Africa, Rest of Middle East & Africa |
| Key Companies Profiled | Kallex, 3X Ceramic Parts, CoorsTek, Ferrotec Taiwan Co, FCT(Tangshan), Xi’an Zhongwei New Materials, Zhejiang Dongxin New Material, Shandong Huamei New Material |
| Customization Scope | Additional furnace orientation, material-grade, country and application detail can be scoped to customer requirements, including qualified replacement cycles and high-purity coating specifications. |
Frequently Asked Questions
How large is the global SiC boat market?
The global SiC boat market measured USD 123.32 million in 2025 and is projected to reach USD 302.91 million by 2034, with a CAGR of 10.5% across 2026–2034. The estimated 2026 value is USD 136.27 million. Expansion comes from semiconductor thermal-processing capacity, recurring replacement of qualified carriers and greater use of engineered SiC surfaces in demanding furnace conditions.
What does a silicon-carbide wafer boat do?
A SiC wafer boat is a precision ceramic fixture that supports multiple wafers at controlled spacing during a high-temperature process. The part must preserve geometry while exposed to repeated heating, cooling, chemical atmospheres and automated handling. Horizontal and vertical furnace designs require different carrier architectures, and a supplier must meet the specific tool interface rather than simply offer a chemically resistant ceramic material.
Which SiC boat type accounts for the largest share?
Horizontal carriers lead the modeled 2025 type mix at ~57%, compared with ~43% for vertical boats. Their position reflects installed horizontal diffusion and oxidation furnace fleets that continue purchasing qualified replacements. Vertical designs grow somewhat faster because automated upright batch tools need dedicated fixtures, but that change is gradual and does not remove the requirement to support mature horizontal process lines.
Which application generates the most SiC boat revenue?
Semiconductor manufacturing contributes an estimated ~67% of 2025 sales because strict wafer cleanliness and process-control requirements support higher-value carrier specifications. LED processing represents ~18%, while photovoltaic diffusion and annealing contribute ~15%. The application categories are based on end use, so a boat purchased for solar-cell processing is not counted again as a semiconductor fixture merely because both use SiC.
Why is Asia-Pacific the leading regional market?
Asia-Pacific combines large wafer-fabrication clusters, solar-cell production, LED manufacturing and specialist ceramic suppliers, producing an estimated ~48% share in 2025. China, Taiwan, Japan and South Korea contain different parts of this value chain, from furnace customers to component engineering. The region’s modeled ~11.4% annual expansion is supported by installed equipment demand and higher-specification replacement parts rather than a single national sales statistic.
Which companies are active in SiC furnace boats?
Named participants include Kallex, 3X Ceramic Parts, CoorsTek, Ferrotec Taiwan Co, FCT(Tangshan), Xi’an Zhongwei New Materials, Zhejiang Dongxin New Material and Shandong Huamei New Material. Other technical-ceramic catalogues document relevant products or materials, but a catalogue listing alone cannot establish a supplier’s global revenue rank. Customers generally qualify products for individual furnaces and process conditions.
What drives the market beyond new furnace installations?
Qualified replacement demand persists because wafer carriers undergo repeated thermal cycles and mechanical handling. A factory may replace a boat when particle behaviour, slot wear or geometry threatens process stability even if its furnace remains in service. Additional value can arise from higher-purity materials, CVD surface treatments and designs adapted to automated loading, all of which require engineering and testing.
What makes SiC boat manufacturing expensive?
The conversion route may include powder processing, forming, high-temperature firing, precision grinding, coating and detailed inspection. Long support rails and numerous wafer slots create dimensional challenges, while high-purity applications add contamination-control procedures. A late-stage machining defect can scrap a nearly finished carrier, so saleable yield and qualification documentation matter more than the raw weight of silicon carbide.
How do SiC boats differ from SiC wafers?
A wafer boat is a furnace-handling fixture that carries substrates; a SiC wafer is a semiconductor material substrate that may later be processed into a device. The two products can be present in the same manufacturing ecosystem but have different buyers, unit economics and functions. This market counts the value of finished ceramic carriers and excludes separately sold semiconductor wafers, furnace systems and electronic power devices.
What geographic and segment scope is covered?
The study uses 2025 as the base year, 2026 as the estimate and 2034 as the forecast endpoint. Type categories are Horizontal and Vertical, and applications are Semiconductor, LED and PV. Regional analysis covers Asia-Pacific, North America, Europe, Latin America, and the Middle East and Africa, with country discussion focused on where thermal-processing equipment, supplier capability and replacement channels influence purchasing.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF