Key Statistics
Key Takeaways
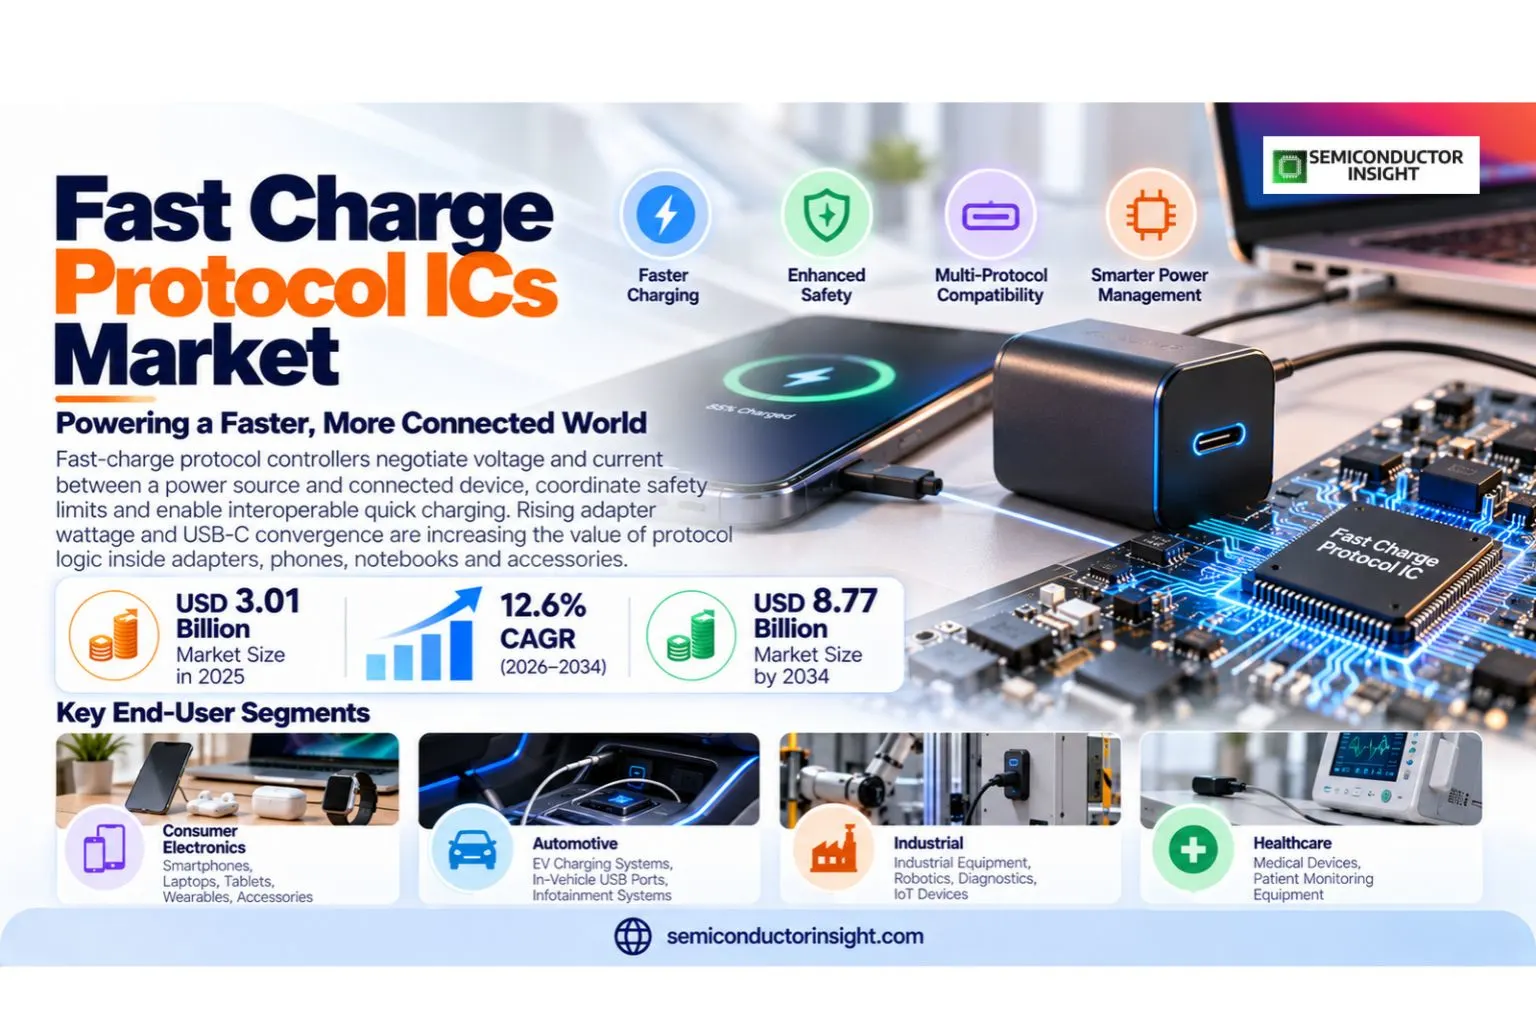
- Market size: The market is valued at USD 3.01 billion in 2025 and is projected to reach USD 8.77 billion by 2034, representing a 12.6% CAGR during 2026–2034.
- USB Power Delivery remains commercially important because of its established use in core applications.
- Asia Pacific leads current market value, while Asia Pacific offers a strong growth profile.
- Smartphones is a major demand segment, with purchasing shaped by reliability, performance and system integration.
- multi-protocol USB-C PD integration, higher charging power and GaN-optimized control is a central competitive theme through 2034.
Fast Charge Protocol ICs Market Overview
Fast charge protocol ICs market is valued at USD 3.01 billion in 2025 and is projected to reach USD 8.77 billion by 2034, expanding at a 12.6% CAGR during 2026–2034. The 2026 market level is USD 3.39 billion. Fast-charge protocol controllers negotiate voltage and current between a power source and connected device, coordinate safety limits and enable interoperable quick charging. Rising adapter wattage and USB-C convergence are increasing the value of protocol logic inside adapters, phones, notebooks and accessories.
The client evidence places the 2024 market at USD 2.67 billion and projects USD 6.89 billion by 2032. Smartphones remain the largest application, while USB Power Delivery is increasingly important because one connector and protocol can span mobile devices, PCs and many accessories. Commercial decisions in the Fast Charge Protocol ICs market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Competitive advantage depends on multi-protocol compatibility, low standby power, protection functions, firmware support and integration with power-delivery stages. GaN adapters create additional demand for controllers that can manage higher switching performance and compact thermal envelopes without compromising interoperability. Commercial decisions in the Fast Charge Protocol ICs market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Segment Analysis: By Type
By type, the market is segmented into USB Power Delivery, Qualcomm Quick Charge, MediaTek Pump Express, OPPO VOOC, Others. Each category serves a distinct performance, cost or integration requirement, so competitive positioning depends on more than shipment volume. Higher-value variants usually command premium pricing when they reduce system complexity, improve efficiency or satisfy stricter qualification requirements.
| Type | Commercial role |
|---|---|
| USB Power Delivery | Broad interoperable standard spanning phones, PCs, displays and accessories. |
| Qualcomm Quick Charge | Smartphone-centric fast-charge ecosystem used across Snapdragon-compatible systems. |
| MediaTek Pump Express | Fast-charge implementation aligned with MediaTek-powered mobile devices. |
| OPPO VOOC | High-current proprietary architecture used by selected smartphone brands. |
| Others | Proprietary and multi-protocol controllers for chargers and embedded devices. |
Additional Segmentation: By End User
End-user segmentation separates high-volume consumer demand from longer-lifecycle automotive and industrial designs. Consumer electronics prioritize compact size and protocol breadth, while automotive and healthcare buyers place more weight on protection, validation and lifecycle support. Commercial decisions in the Fast Charge Protocol ICs market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| End User | Demand characteristics |
|---|---|
| Consumer Electronics | Phones, laptops, chargers, power banks and connected devices. |
| Automotive | In-cabin USB-C charging, infotainment and accessory power. |
| Industrial | Rugged charging interfaces and portable equipment. |
| Healthcare | Portable medical electronics with controlled charging and safety needs. |
Segment Analysis: By Application
By application, demand spans Smartphones, Laptops & Tablets, Electric Vehicles, Wearables, Power Banks & Industrial Equipment. The mix changes according to performance needs, system value, reliability requirements, regulatory exposure and product lifecycle. This makes application-level analysis more useful than mechanically repeating one market statistic across every segment. Commercial decisions in the Fast Charge Protocol ICs market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Application | Demand characteristics |
|---|---|
| Smartphones | Largest unit-volume application, with fast charging a core premium and mid-range feature. |
| Laptops & Tablets | USB-C PD adoption increases protocol-controller content in adapters and devices. |
| Electric Vehicles | Selective opportunity in in-cabin and accessory charging electronics. |
| Wearables | Compact low-power systems emphasize thermal control and battery protection. |
| Power Banks & Industrial Equipment | Multi-protocol support enables one accessory to serve heterogeneous device fleets. |
Additional Segmentation: By Power Class
Power class matters because protocol negotiation, thermal design, cable requirements and power-stage architecture become more demanding as wattage rises. The market is moving upward in charging power while preserving compatibility across legacy device generations. Commercial decisions in the Fast Charge Protocol ICs market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Power Class | Commercial role |
|---|---|
| Below 45W | Wearables, compact phones and lower-power accessories. |
| 45-100W | Premium phones, tablets and many notebook PCs. |
| Above 100W | High-performance laptops, multi-port adapters and emerging high-power consumer systems. |
Regional Analysis
Asia Pacific leads because smartphone, notebook, charger and adapter manufacturing is concentrated in China, Taiwan, South Korea and Southeast Asia. North America remains a major technology hub, with the client evidence indicating a 32% revenue share in 2023. Commercial decisions in the Fast Charge Protocol ICs market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Regional demand reflects device production, replacement cycles and local OEM ecosystems. Asia Pacific combines manufacturing scale with major handset brands, North America contributes platform and semiconductor innovation, and Europe benefits from broad USB-C standardization across consumer devices. Commercial decisions in the Fast Charge Protocol ICs market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Asia Pacific
Asia Pacific demand is supported by high-volume electronics manufacturing, semiconductor fabrication, automotive production and digital-infrastructure investment. China, Japan, South Korea, Taiwan, India and Southeast Asia contribute different mixes of production, consumption and technical capability, making the region central to both scale and supply-chain development. Commercial decisions in the Fast Charge Protocol ICs market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
North America
North America remains a high-value market because of strong semiconductor design, aerospace, cloud, enterprise and advanced-manufacturing activity. The United States is the principal contributor, supported by leading technology companies, research institutions and early adoption of premium systems with demanding performance requirements. Commercial decisions in the Fast Charge Protocol ICs market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Europe
Europe combines advanced automotive, aerospace, industrial, energy and research demand. Germany, France, the United Kingdom, Italy and the Nordic markets emphasize reliability, energy efficiency, safety and regulatory compliance, supporting demand for technically differentiated products with strong lifecycle support. Commercial decisions in the Fast Charge Protocol ICs market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
South America
South America is a smaller but developing market led by Brazil and selected industrial economies. Demand is concentrated in telecom, infrastructure, industrial modernization, healthcare and consumer electronics, while import dependence makes distributor support, local certification and pricing important commercial factors. Commercial decisions in the Fast Charge Protocol ICs market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Middle East & Africa
Middle East & Africa remains an emerging market where demand is concentrated in infrastructure, telecom, aviation, defense, energy and data-center projects. Gulf countries account for much of the premium investment, while wider adoption depends on local technical capability, procurement cycles and access to qualified suppliers. Commercial decisions in the Fast Charge Protocol ICs market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Competitive Landscape
The competitive landscape includes Texas Instruments, NXP Semiconductors, Richtek, Renesas/Dialog, STMicroelectronics, Cypress/Infineon, INJOINIC, Weltrend, Zhuhai Ismartware and Silan Microelectronics. Supplier position is shaped by technical performance, qualification depth, customer relationships, manufacturing scale, software or application support and the ability to sustain product roadmaps across long customer lifecycles. Commercial decisions in the Fast Charge Protocol ICs market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
The market combines large analog and MCU suppliers with specialist protocol-IC vendors. Multi-protocol support, reference designs and close relationships with charger OEMs are decisive because customers want rapid certification and broad compatibility across branded and third-party devices. Commercial decisions in the Fast Charge Protocol ICs market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Competitive dimension | What matters |
|---|---|
| Technology | Performance, integration, roadmap credibility and IP differentiation. |
| Qualification | Customer validation, compliance and field history. |
| Supply | Capacity, lead time, quality consistency and resilience. |
| Support | Application engineering, service and lifecycle management. |
Production Capacity Analysis
Production is primarily fabless or asset-light, relying on mature-node mixed-signal foundries plus outsourced assembly and test. Capacity risk is tied to foundry allocation, package availability and the ability to qualify second sources without reworking firmware or charger designs. Commercial decisions in the Fast Charge Protocol ICs market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Because protocol ICs are relatively small silicon devices, manufacturing economics depend heavily on scale and yield. Regional design support near charger and phone manufacturing clusters can be as important as wafer capacity during rapid protocol transitions. Commercial decisions in the Fast Charge Protocol ICs market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Market Dynamics
Fast-charge demand is shaped by rising wattage, USB-C convergence and greater integration of protocol logic with power management. These shifts increase system capability but also compress standalone controller value when functions migrate into larger PMICs or charger SoCs. Commercial decisions in the Fast Charge Protocol ICs market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Protocol fragmentation remains commercially relevant despite wider USB Power Delivery adoption. Vendors must support legacy and proprietary modes, cable identification, protection and firmware updates, creating room for differentiated mixed-signal and embedded-control solutions. Commercial decisions in the Fast Charge Protocol ICs market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Market Drivers
Growth is driven by faster smartphone charging, USB-C adoption in notebooks and accessories, higher-power multi-port adapters and greater use of GaN power stages. Consumers increasingly expect shorter charging times, pushing fast-charge capability into more device tiers. Commercial decisions in the Fast Charge Protocol ICs market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Driver | Directional impact on CAGR |
|---|---|
| Technology upgrade cycle | +1.8 percentage points |
| End-market expansion | +1.3 percentage points |
| Higher content per system | +0.9 percentage points |
Market Restraints
Price pressure is intense because protocol logic is increasingly integrated into broader charger or PMIC solutions. Compatibility testing across cables, adapters and brands can lengthen development, while proprietary standards create fragmentation and duplicate engineering effort. Commercial decisions in the Fast Charge Protocol ICs market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Restraint | Directional impact on CAGR |
|---|---|
| Qualification / integration burden | -0.8 percentage points |
| Price pressure | -0.6 percentage points |
| Supply complexity | -0.5 percentage points |
Market Opportunities
The strongest opportunities are in 100W-plus USB-C, multi-port chargers, automotive cabin charging, adaptive power sharing and controllers optimized for GaN power stages. Vendors can add value with firmware, authentication, telemetry and integrated safety functions. Commercial decisions in the Fast Charge Protocol ICs market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Opportunity | Commercial significance |
|---|---|
| multi-protocol USB-C PD integration, higher charging power and GaN-optimized control | Supports premium product mix and new design wins. |
| Regional capacity | Improves lead time and supply resilience. |
| Application engineering | Deepens customer integration and raises switching costs. |
Supply Chain Analysis
The supply chain starts with mixed-signal IC design and embedded protocol firmware, moves through wafer fabrication, assembly and test, then into charger modules, adapters, smartphones and other end devices. Certification and reference-design support sit between silicon supply and volume deployment. Commercial decisions in the Fast Charge Protocol ICs market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Stage | Role |
|---|---|
| IC design & firmware | Protocol negotiation, protection, authentication and power-management logic. |
| Wafer fabrication | Mature-node mixed-signal and embedded-controller manufacturing. |
| Assembly & test | Compact QFN, WLCSP and related packages with electrical validation. |
| Charger / device integration | Reference designs, GaN stages, cables and system certification. |
Evidence density is most useful at system decision points rather than repeated in every segment row. The practical distinction is whether a protocol IC expands interoperability, increases power class, or reduces BOM and thermal burden in the charger design. Commercial decisions in the Fast Charge Protocol ICs market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Recent Developments in the Fast Charge Protocol ICs Market
Report Scope & Segmentation
This analysis covers the Fast Charge Protocol ICs market from a 2025 base year through the 2026–2034 forecast period. It evaluates demand by product type, application and two additional segmentation axes, with regional coverage spanning Asia Pacific, North America, Europe, South America, and the Middle East & Africa. Commercial decisions in the Fast Charge Protocol ICs market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Scope item | Coverage |
|---|---|
| Base year | 2025 |
| Estimated year | 2026 |
| Forecast period | 2026–2034 |
| By Type | USB Power Delivery, Qualcomm Quick Charge, MediaTek Pump Express, OPPO VOOC, Others |
| By Application | Smartphones, Laptops & Tablets, Electric Vehicles, Wearables, Power Banks & Industrial Equipment |
| By End User | Consumer Electronics, Automotive, Industrial, Healthcare |
| By Power Class | Below 45W, 45-100W, Above 100W |
| Key participants | Texas Instruments, NXP Semiconductors, Richtek, Renesas/Dialog, STMicroelectronics, Cypress/Infineon, INJOINIC, Weltrend, Zhuhai Ismartware and Silan Microelectronics |
Frequently Asked Questions
What is the Fast Charge Protocol ICs market size in 2025?
The market is valued at USD 3.01 billion in 2025.
What is the market forecast for 2034?
The market is projected to reach USD 8.77 billion by 2034, with a 12.6% CAGR during 2026–2034.
Which region leads the market?
Asia Pacific leads current market value, while Asia Pacific has a strong growth profile.
Which type is most important?
USB Power Delivery is a leading category, although mix varies by application.
Which applications matter most?
Smartphones is a major demand segment, alongside Laptops & Tablets, Electric Vehicles.
What technology trend matters most?
multi-protocol USB-C PD integration, higher charging power and GaN-optimized control is a central technology and commercialization trend.
Who are the major suppliers?
Major participants include Texas Instruments, NXP Semiconductors, Richtek, Renesas/Dialog, STMicroelectronics, Cypress/Infineon, INJOINIC, Weltrend, Zhuhai Ismartware and Silan Microelectronics.
What drives market growth?
Growth is driven by faster smartphone charging, USB-C adoption in notebooks and accessories, higher-power multi-port adapters and greater use of GaN power stages. Consumers increasingly expect shorter charging times, pus
What limits growth?
Price pressure is intense because protocol logic is increasingly integrated into broader charger or PMIC solutions. Compatibility testing across cables, adapters and brands can lengthen development, while proprietary sta
What will shape the market through 2034?
Technology roadmaps, qualification, supply continuity and multi-protocol USB-C PD integration, higher charging power and GaN-optimized control will shape competitive outcomes.
Research Sources & Evidence Base
View selected external research sources
- USB-IF — USB Charger and Power Delivery: Primary standards context for USB Power Delivery and USB-C charging. Open source
- Texas Instruments — USB Type-C & Power Delivery: Current protocol-controller and power-path product context. Open source
- NXP Semiconductors — USB Type-C & Power Delivery: Current USB-C controller and embedded-power-management context. Open source
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF