Key Statistics
Key Takeaways
- UDIMM leads the report’s type segmentation because desktops and mainstream client systems use large volumes of unbuffered memory modules, while RDIMM and newer server formats carry higher value per module.
- Computers remain the largest application in the report scope, while servers are the strongest high-value growth pool because AI and HPC platforms require more memory capacity and bandwidth per socket.
- North America is the leading current market through hyperscale data centers, enterprise IT, workstation demand and the presence of major memory-module brands and DRAM suppliers.
- Asia Pacific is the fastest-growing region and accounts for more than 40% of global consumption in the , supported by server manufacturing, electronics production and memory supply in China, Taiwan and South Korea.
- DDR5 adoption is the main technology transition, with higher bandwidth, on-module power management and dual subchannels raising both module performance and component complexity.
- Capacity is moving upward. Micron sampled 256GB DDR5 RDIMMs in 2026, while Innodisk introduced 12,800 MT/s MRDIMM for AI workloads, showing that server memory growth is increasingly tied to density and bandwidth rather than simple module counts.
Dual in-line Memory Module (DIMM) Market Overview
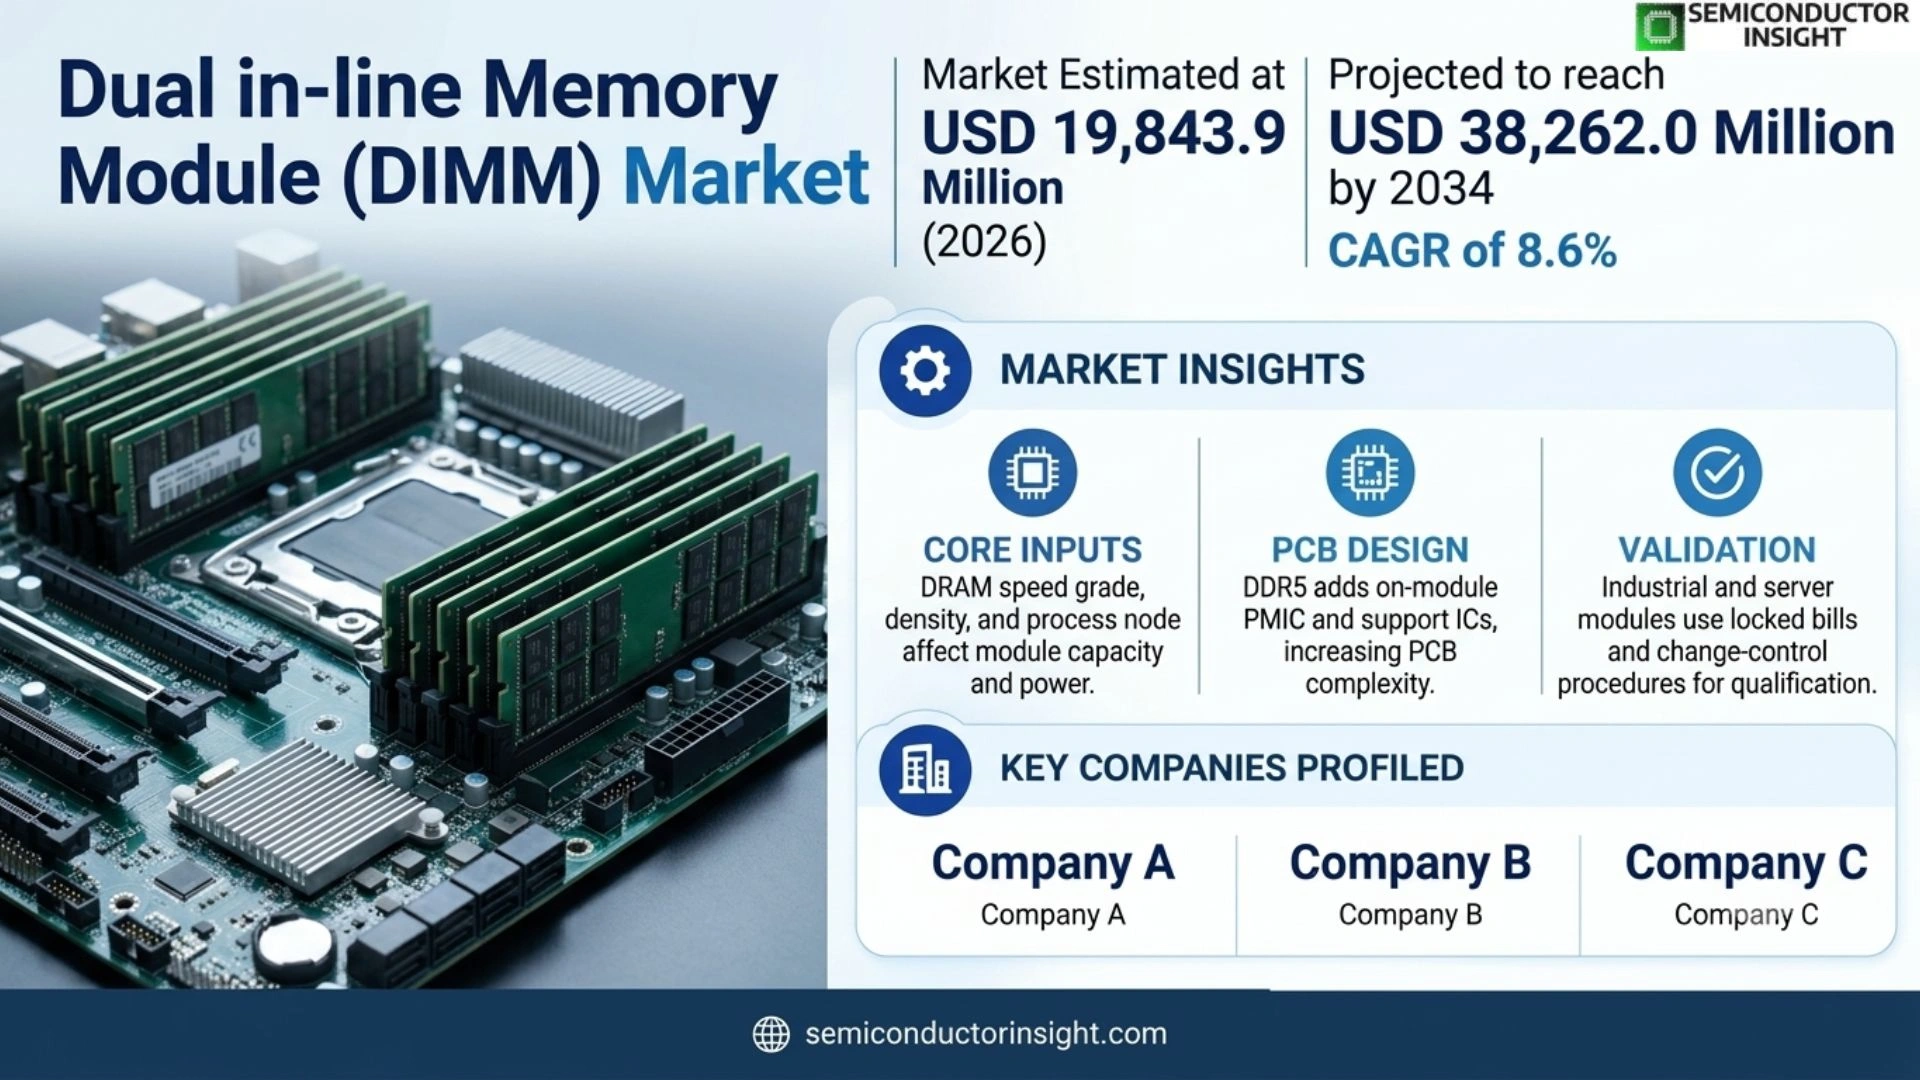
Dual in-line Memory Module Market was valued at USD 18,280.4 million in 2025, is estimated at USD 19,843.9 million in 2026, and is projected to reach USD 38,262.0 million by 2034, representing a CAGR of 8.6% during 2026–2034. North America is the largest regional market in 2025, while the commercial growth mechanism is increasingly shaped by AI and cloud servers, DDR5 platform refreshes, higher per-socket memory capacity, industrial edge computing, workstation workloads, and faster registered-memory architectures.
A dual in-line memory module is a standardized printed circuit board populated with DRAM devices and designed to plug directly into a computer or server memory channel. The market includes unbuffered DIMMs for client systems, registered and load-reduced modules for servers, specialized industrial modules and legacy fully buffered formats. DIMMs translate DRAM die technology into replaceable, platform-qualified memory products with defined electrical, mechanical and thermal characteristics.
The market is expanding because memory capacity per system is rising across data centers, workstations and AI infrastructure. Server processors expose more memory channels and customers increasingly deploy high-capacity RDIMMs to support in-memory databases, virtualization, agentic AI and CPU-intensive inference. At the same time, client platforms are moving from DDR4 toward DDR5, creating a broad replacement cycle across desktops and high-performance PCs.
Module design is becoming more complex with DDR5. Registered server DIMMs incorporate a registering clock driver, power-management IC, SPD hub and temperature sensing in addition to DRAM. Newer MRDIMM architectures add multiplexing to increase effective bandwidth. This raises validation requirements and favors module suppliers with strong DRAM sourcing, PCB design, firmware, thermal engineering and platform-qualification capabilities.
Segment Analysis: By Type
By type, the market is segmented into UDIMM, FB-DIMM, RDIMM, LR-DIMM, and Other specialized DIMM variants. UDIMM is the leading broad-volume type because desktops and client systems use unbuffered modules at scale. RDIMM and advanced registered architectures are the principal value-growth area in AI and enterprise servers.
| Type | Technical role | Market position |
|---|---|---|
| UDIMM | Unbuffered DIMMs connect DRAM devices directly to the memory controller without a register between the controller and memory devices. They are common in desktop PCs, entry workstations and other client systems. | The largest volume type in the report scope. Cost, compatibility and broad motherboard support sustain demand, while DDR5 UDIMM upgrades support new client platforms. |
| FB-DIMM | Fully Buffered DIMM uses an advanced memory buffer to serialize communications between the memory controller and module. The architecture was used in selected earlier server generations. | A legacy niche with limited new-platform relevance. Demand is concentrated in replacement and maintenance of installed systems. |
| RDIMM | Registered DIMMs buffer command and address signals through an RCD to support larger memory capacity and more modules per server channel. | A major high-value segment for data centers, AI servers and enterprise computing. Capacity and speed are rising rapidly as CPU core counts increase. |
| LR-DIMM | Load-reduced DIMMs use buffering to reduce electrical loading and support high-capacity server configurations. | A specialized server segment where maximum memory capacity and stable signal integrity justify additional module complexity. |
| Other specialized DIMM variants | Includes industrial ECC modules, overclockable workstation RDIMMs, CUDIMMs, MRDIMMs and other platform-specific memory formats. | A growing technology segment as AI and industrial systems require higher bandwidth, ruggedization, clocking or custom lifecycle support. |
Why are server DIMMs becoming more complex?
High-core-count CPUs and AI workloads need more memory capacity and bandwidth, but adding more DRAM devices creates electrical loading and power challenges. RDIMMs use registering clock drivers to improve signal integrity, while DDR5 moves power management onto the module and divides the data interface into two subchannels. MRDIMM adds multiplexing so two ranks can transfer data more effectively. These features improve bandwidth and capacity but require more ICs, tighter PCB design and greater validation.
Segment Analysis: By Application
By application, the market covers Computers, Servers, Industrial Applications, Aerospace and Defense Systems, and Manufacturing Equipment. Computers lead by broad installed volume, while servers generate the strongest value growth because high-capacity RDIMMs and MRDIMMs command materially higher content per system.
| Application | Demand characteristics | |
|---|---|---|
| Computers | Desktop PCs and workstations use UDIMM memory for gaming, content creation, engineering and general computing. DDR5 adoption is accelerating with new CPU platforms. | The largest broad application in the report scope, supported by replacement, gaming and professional workstation demand. |
| Servers | Data centers use RDIMM, LR-DIMM and emerging MRDIMM architectures to scale memory capacity and bandwidth across cloud, AI, database and virtualization workloads. | The strongest high-value growth segment. AI servers are pushing single-module capacities above 128GB and data rates well beyond earlier DDR5 generations. |
| Industrial Applications | Edge computers, automation controllers and rugged systems use long-lifecycle ECC and non-ECC DIMMs with extended-temperature and reliability options. | A resilient segment where platform longevity and controlled bills of materials create switching costs. |
| Aerospace and Defense Systems | Mission computers, simulation and secure processing platforms use qualified memory modules with reliability, traceability and long availability. | A smaller premium market where ruggedization and lifecycle support matter more than consumer pricing. |
| Manufacturing Equipment | Semiconductor tools, inspection equipment, robotics and industrial PCs use DIMMs for local compute and process-control workloads. | Steady demand linked to factory automation and the expansion of edge AI in production equipment. |
Why are AI servers driving higher DIMM revenue per system?
AI workloads increase both CPU-side memory capacity and bandwidth needs. Large servers can use many channels per socket and require hundreds of gigabytes or terabytes of DRAM. Micron’s 256GB DDR5 RDIMM is designed to increase capacity per slot while reducing operating power compared with two 128GB modules. Innodisk’s 12,800 MT/s MRDIMM illustrates a parallel shift toward higher bandwidth. These changes increase module value even when total server-unit growth is moderate.
Regional Analysis
North America is the leading current DIMM market through hyperscale data centers, enterprise infrastructure, workstations and gaming demand. Asia Pacific is the fastest-growing consumption region and the principal manufacturing base for DRAM, module assembly and server systems.
How do regional DIMM markets differ?
North America is weighted toward high-capacity enterprise and AI servers, giving RDIMM and advanced server modules a strong product mix. Asia Pacific combines the largest manufacturing ecosystem with fast server, PC and industrial demand. Europe has strong enterprise, automotive and industrial-computing requirements. South America remains price sensitive and import dependent, while Middle East and Africa growth is driven by data-center and smart-infrastructure investment.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| North America | Leading current market | Strong | Hyperscale, enterprise and workstation | Capacity, bandwidth, power and platform validation |
| Asia Pacific | Fastest-growing & manufacturing hub | Very strong | Servers, PCs, electronics and DRAM supply | Cost, supply, local manufacturing and DDR5 transition |
| Europe | Enterprise & industrial market | Moderate to strong | Data centers, industrial and automotive compute | Reliability, ECC and lifecycle support |
| South America | Developing import market | Moderate | Gaming PCs, enterprise and industrial | Price, channel availability and compatibility |
| Middle East & Africa | Emerging data-center market | Selective high growth | Cloud, smart cities and enterprise IT | Imported supply, power efficiency and service |
Competitive Landscape
The market includes Kingston Technology, Micron Technology, ADATA, Ramaxel, Transcend, Tigo, Apacer, Corsair, Team Group, Kingmax and Innodisk. Competitive differentiation spans DRAM sourcing, module PCB design, speed binning, platform validation, industrial ruggedization and channel reach.
Kingston and Micron have strong global positions through broad client and server portfolios. Micron combines DRAM manufacturing with module design, giving it direct access to leading process nodes and high-capacity 3DS packaging. Kingston differentiates through server platform validation, locked bills of materials and large distribution scale.
Taiwanese suppliers such as ADATA, Transcend, Apacer, Team Group and Innodisk compete across consumer, industrial and data-center segments. Their proximity to PC and server manufacturing enables fast product launches, while industrial vendors add extended temperature, conformal coating, controlled BOM and long-lifecycle options.
The server segment is becoming more technology intensive. Higher DDR5 speeds, 3DS, TSVs and MRDIMM require close coordination with CPU platforms and server OEMs. Suppliers with strong qualification labs and access to advanced DRAM can capture premium growth even when commodity client-module pricing is cyclical.
| Competitive tier | Representative companies | Commercial basis |
|---|---|---|
| Global module & DRAM leaders | Kingston Technology; Micron Technology | Large distribution, server validation, leading DRAM technology and high-capacity modules. |
| Taiwan module specialists | ADATA; Transcend; Apacer; Team Group; Innodisk; Kingmax | Fast product cycles, industrial memory, gaming and edge/data-center specialization. |
| China and regional OEM suppliers | Ramaxel Technology; Tigo; other module assemblers | Local server and PC relationships, competitive pricing and regional manufacturing. |
Key Market Participants
Kingston Technology, Micron Technology, ADATA Technology, Ramaxel Technology, Transcend Information, Tigo Corporation, Apacer Technology, Corsair Memory, Team Group, Kingmax Semiconductor, Innodisk.
Production Capacity Analysis
DIMM production combines DRAM sourcing, module PCB fabrication, component placement, SPD programming, thermal design and high-speed electrical testing. Server modules add RCD, PMIC, SPD hub and temperature-sensor components, while high-capacity 3DS products use stacked DRAM packages with TSVs.
DRAM devices are the main cost and performance input. Module suppliers either manufacture DRAM internally or source from major memory vendors. Speed grade, density and process node directly affect finished-module capacity and power.
The module PCB must route high-speed differential and command signals with tight impedance and length matching. DDR5 adds on-module PMIC and other support ICs, increasing PCB complexity relative to DDR4.
Final validation includes burn-in or functional tests, SPD programming and compatibility testing across server or motherboard platforms. Industrial and server products often use locked component bills and formal change-control procedures to preserve long-term qualification.
| Capacity layer | Where it concentrates | Commercial constraint |
|---|---|---|
| DRAM wafer & package supply | South Korea, United States, Taiwan and China | Node, density, speed grade, yield and long-term supply. |
| Module PCB & support ICs | Taiwan, China, South Korea and global electronics hubs | Signal integrity, RCD/PMIC availability and PCB quality. |
| Assembly & test | Taiwan, China, United States and global module plants | SPD programming, speed binning, ECC validation and thermal performance. |
| Platform qualification | Server OEMs, motherboard vendors and industrial customers worldwide | Compatibility, controlled BOM, lifecycle support and field reliability. |
Market Dynamics
DIMM demand is being driven by rising memory capacity per system and the DDR5 replacement cycle. The main risks remain DRAM price volatility, rapid platform transitions and the capital required to validate faster server-memory architectures.
Market Drivers
| Factor | Directional impact | Why it matters |
|---|---|---|
| AI and cloud servers | High | More cores and data-intensive workloads raise memory capacity and bandwidth per socket. |
| DDR5 platform refresh | High | New client and server CPUs increasingly require DDR5 memory. |
| Industrial edge AI | Medium-High | Qualified memory modules support local AI and automation platforms. |
| Higher module capacity | High | 128GB, 256GB and MRDIMM products increase revenue per slot. |
AI increases memory per server
Large models and CPU-side inference require more addressable memory and bandwidth. High-capacity RDIMMs allow data centers to increase memory per socket without expanding server count.
DDR5 creates a broad replacement cycle
Every new CPU generation that drops DDR4 support pushes PCs and servers toward DDR5 modules. This supports both unit demand and richer module content through PMIC, RCD and higher-speed PCB design.
Industrial edge systems are becoming more memory intensive
Vision, robotics and local analytics require larger DRAM capacity than traditional control applications. Industrial DDR5 modules combine higher bandwidth with ruggedization and controlled lifecycles.
Module density raises value faster than unit count
Moving from 32GB to 64GB, 128GB or 256GB materially increases module value. Data centers can also reduce DIMM count for a target capacity, improving power and airflow.
Market Restraints
| Factor | Directional impact | Why it matters |
|---|---|---|
| DRAM price cyclicality | High | Memory ASPs can change rapidly with supply-demand balance. |
| Platform compatibility | High | DIMMs must be validated against CPU and motherboard memory controllers. |
| Higher DDR5 component complexity | Medium-High | PMIC, RCD and signal-integrity requirements raise cost and failure points. |
| Technology obsolescence | Medium | New CPU generations can accelerate transitions between memory standards. |
Commodity memory cycles create revenue volatility
DRAM oversupply can lower module ASPs quickly, while shortages produce sharp increases. Module makers must manage inventory carefully to avoid holding high-cost memory through a downcycle.
Compatibility limits easy supplier switching
High-speed memory is sensitive to PCB routing, SPD settings and DRAM characteristics. Enterprise customers validate specific modules and may resist substitutions without testing.
DDR5 increases bill-of-material complexity
On-module power management and registered-clock devices improve performance but add components, validation and thermal considerations compared with earlier memory generations.
New standards can shorten product windows
Client platforms can move quickly from DDR4 to DDR5 and onward, forcing module suppliers to balance legacy inventory with investment in new designs.
Market Opportunities
256GB and higher server RDIMM
AI and memory-intensive servers need greater capacity per slot and improved power efficiency.
MRDIMM bandwidth scaling
Multiplexed registered DIMM architectures can materially increase CPU memory bandwidth without replacing the DIMM form factor.
Industrial DDR5 lifecycle products
Edge AI and factory systems need DDR5 performance plus controlled BOMs, extended temperature and long availability.
Workstation and creator memory
High-end desktops increasingly use registered or high-capacity DDR5 for engineering, simulation and AI development.
Supply Chain Analysis
DRAM Supply. Module economics begin with DRAM availability and price. Suppliers with long-term DRAM agreements or internal memory production can manage supply swings more effectively.
Module Design. High-speed DDR5 requires careful PCB routing and support IC selection. Server modules must coordinate RCD, PMIC, SPD hub and temperature sensors with the host platform.
Assembly & Test. Manufacturers perform automated placement, soldering, SPD programming and electrical test. Premium products may add burn-in, conformal coating or wider-temperature screening.
OEM Qualification. Server and industrial customers validate specific module part numbers. Locked BOMs and advance change notifications can become decisive purchasing criteria because unplanned component changes may require costly requalification.
Recent Developments in the Dual in-line Memory Module (DIMM) Market
Developments tracked to September 2026. Entries are dated to the official publication date where available.
- 30 July 2026 Product
Innodisk introduced DDR5 12,800 MT/s MRDIMM for generative AI, LLM and robotics workloads. The architecture uses multiplexed clock and data buffers to increase bandwidth versus standard RDIMM. Source - 12 May 2026 Product
Micron sampled 256GB DDR5 RDIMMs based on 1-gamma DRAM and 3DS TSV packaging. The modules support up to 9,200 MT/s and target next-generation AI and HPC servers. Source - 30 October 2025 Industrial memory
Innodisk launched DDR5-7200 RDIMM with capacities up to 64GB for advanced AI workloads. The product emphasizes industrial validation and edge/server reliability. Source - 25 February 2025 DRAM technology
Micron announced shipment of 1-gamma DRAM samples for DDR5, targeting speeds up to 9,200 MT/s and improved power efficiency. Source - 2026 Industrial transition
Apacer continues promoting DDR5 RDIMM for industrial server and embedded AI platforms with dual subchannels, PMIC, ECC and temperature sensing. Source
Report Scope & Segmentation
| Attribute | Coverage |
|---|---|
| Report title | Global Dual in-line Memory Module (DIMM) Market Research Report 2026-2034 |
| Base / estimate / forecast | 2025 base year; 2026 estimated year; 2034 forecast end year; CAGR measured for 2026–2034. |
| By Type | UDIMM; FB-DIMM; RDIMM; LR-DIMM; Other specialized DIMM variants |
| By Application | Computers (desktops & laptops); Servers; Industrial applications; Aerospace and defense systems; Manufacturing equipment |
| By Memory Technology | DDR3; DDR4; DDR5; Specialized memory variants |
| By Capacity | Below 4GB; 4GB-8GB; 8GB-16GB; Above 16GB |
| Regions | North America, Europe, Asia-Pacific, South America, and Middle East & Africa, with country-level analysis across the principal national markets. |
| Companies | Kingston Technology, Micron Technology, ADATA Technology, Ramaxel Technology, Transcend Information, Tigo Corporation, Apacer Technology, Corsair Memory, Team Group, Kingmax Semiconductor, Innodisk |
| Customization Scope | Free report customization (equivalent to up to 4 analyst working days) with purchase. Addition or alteration to country, regional and segment scope. |
Frequently Asked Questions
What is the size of the Dual in-line Memory Module market?
The global DIMM market is valued at USD 18,280.4 million in 2025, is estimated at USD 19,843.9 million in 2026, and is projected to reach USD 38,262.0 million by 2034, representing an 8.6% CAGR during 2026–2034.
Which region leads the DIMM market?
North America is the leading current market, supported by hyperscale data centers, enterprise infrastructure, gaming and major memory brands.
Which DIMM type leads?
UDIMM leads the report’s broad-volume type segmentation, while RDIMM and MRDIMM are the key high-value server growth formats.
Which application is largest?
Computers remain the largest application in the report scope, while servers generate the strongest value growth through AI and cloud demand.
What is driving DDR5 adoption?
New CPU platforms, higher bandwidth, improved power management, dual subchannels and larger memory capacity are accelerating DDR5 replacement of DDR4.
Why are RDIMMs important in servers?
Registered DIMMs buffer command and address signals so servers can support higher capacities and more modules per memory channel with stable signal integrity.
What are the main restraints?
DRAM price cyclicality, platform qualification, DDR5 component complexity and fast technology transitions are the principal restraints.
Who are the major DIMM companies?
Key companies include Kingston, Micron, ADATA, Ramaxel, Transcend, Apacer, Corsair, Team Group, Kingmax and Innodisk.
What capacity trend is most important?
Server memory is moving toward 128GB, 256GB and other high-capacity modules as AI and HPC systems increase memory per socket.
Where are the strongest opportunities?
The strongest opportunities are in high-capacity DDR5 RDIMM, MRDIMM, industrial DDR5 and workstation memory.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...