Key Statistics
Key Takeaways
- Diaphragm Pumps for Semiconductor market was valued at USD million 138.8 in 2025 and is projected to reach USD million 298.9 by 2034, representing a 8.9% CAGR over 2026–2034.
- High-purity plastic and fluoropolymer configurations are positioned for above-average growth because customer designs increasingly reward integration, performance consistency and lower system-level complexity.
- High-purity chemical delivery and advanced wet processing provides one of the clearest demand pathways as purchasing decisions move toward higher performance, tighter qualification and longer lifecycle support.
- Asia Pacific held the largest market position in 2025, supported by the concentration of relevant manufacturing, infrastructure, customers or technology investment.
- The central market constraint is not simply price; qualification, process control and switching risk can slow adoption even when a competing product offers an attractive specification.
- Competitive advantage is shifting toward suppliers that combine product performance with application engineering, dependable capacity and regional technical support.
Diaphragm Pumps for Semiconductor Market Overview
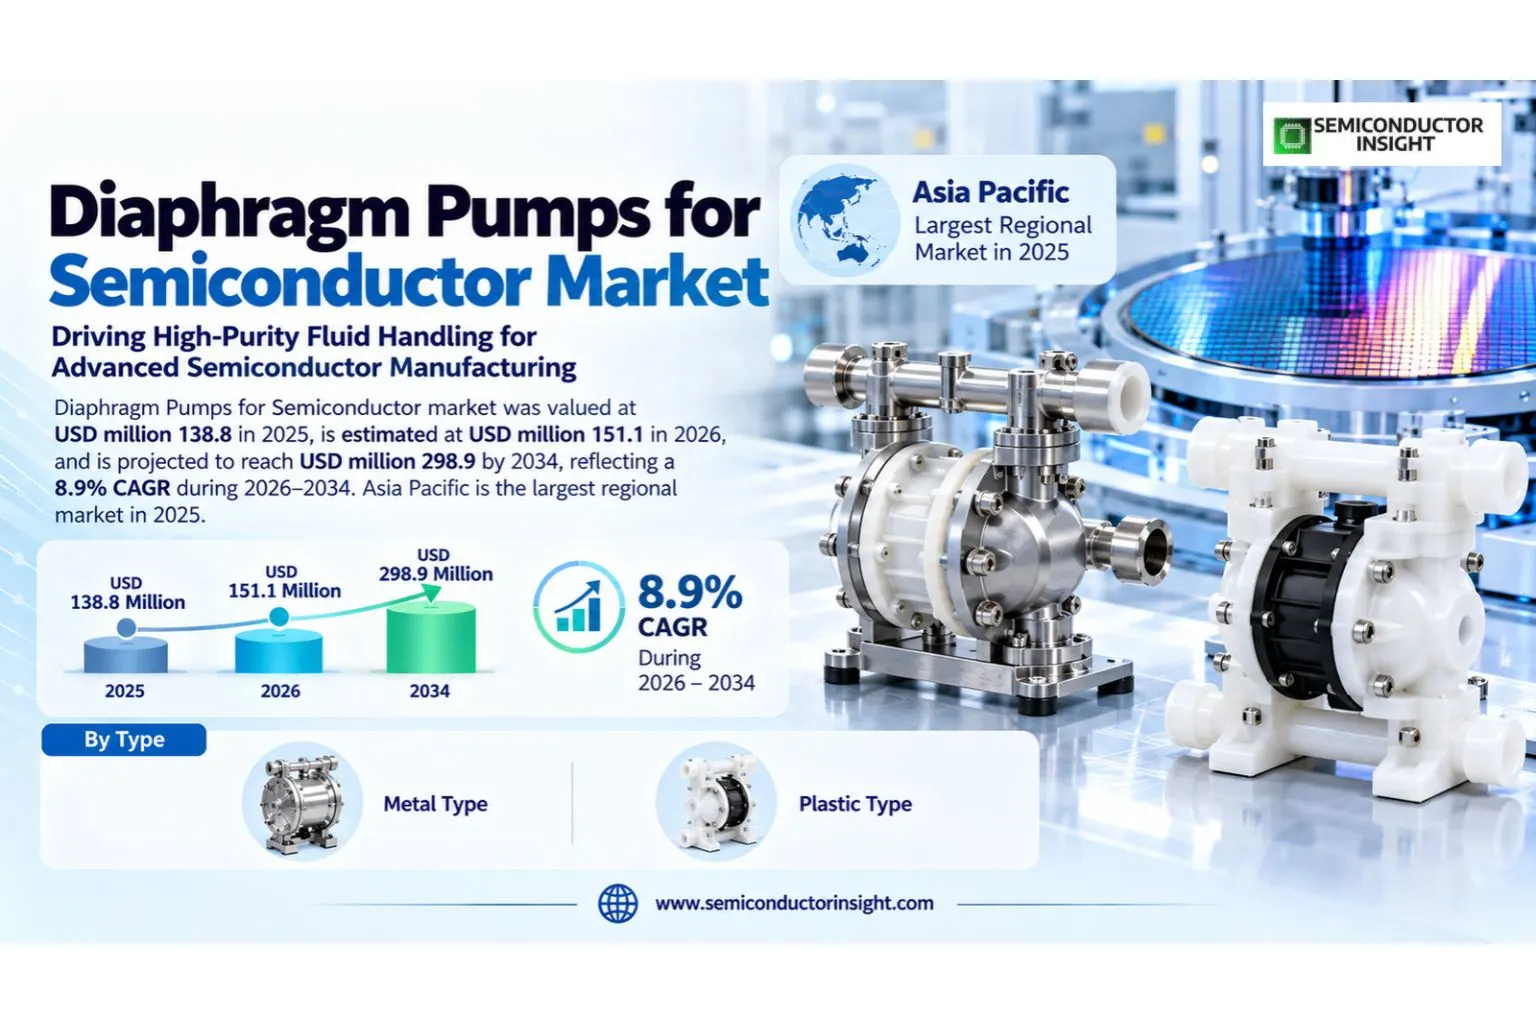
Diaphragm Pumps for Semiconductor market was valued at USD million 138.8 in 2025, is estimated at USD million 151.1 in 2026, and is projected to reach USD million 298.9 by 2034, reflecting a 8.9% CAGR during 2026–2034. Asia Pacific is the largest regional market in 2025.
Base year: 2025 · Estimated year: 2026 · Forecast period: 2026–2034 · Values in USD million unless otherwise stated
Diaphragm Pumps for Semiconductor refers to high-purity chemical-transfer and metering pumps that isolate the process fluid behind a flexible diaphragm, reducing contamination pathways while handling aggressive acids, bases, solvents and CMP slurries used in semiconductor fabrication. The commercial boundary includes products and enabling solutions sold specifically for the defined application, while excluding adjacent technologies that do not perform the same core function. This scope discipline is important because neighboring components can share end customers without being economically interchangeable.
Fab customers buy on contamination performance, chemical compatibility, pulsation behavior, uptime and serviceability. Qualification can be application-specific because a pump used for high-purity acid delivery faces different materials, particle and flow-control requirements than one handling abrasive CMP slurry.
Segment Analysis: By Type
By type, the market is segmented into Metal Type, Plastic Type. The segment mix reflects differences in architecture, cost, integration and end-use qualification. High-purity plastic and fluoropolymer configurations are positioned for stronger growth where customers value higher performance or reduced system complexity.
| Type | Market role | Commercial characteristics |
|---|---|---|
| Metal Type | Core segment | Metal Type represents a distinct purchasing and performance profile within the Diaphragm Pumps for Semiconductor market. Supplier differentiation depends on technical fit, qualification requirements, operating environment and the economics of the customer workflow rather than on a single headline specification. |
| Plastic Type | Strategic segment | Plastic Type represents a distinct purchasing and performance profile within the Diaphragm Pumps for Semiconductor market. Supplier differentiation depends on technical fit, qualification requirements, operating environment and the economics of the customer workflow rather than on a single headline specification. |
Segment Analysis: By Actuation
| Actuation | Market role | Commercial characteristics |
|---|---|---|
| Air-Operated Double-Diaphragm | Core segment | Air-Operated Double-Diaphragm represents a distinct purchasing and performance profile within the Diaphragm Pumps for Semiconductor market. Supplier differentiation depends on technical fit, qualification requirements, operating environment and the economics of the customer workflow rather than on a single headline specification. |
| Pneumatic Metering/Rolling-Diaphragm | Strategic segment | Pneumatic Metering/Rolling-Diaphragm represents a distinct purchasing and performance profile within the Diaphragm Pumps for Semiconductor market. Supplier differentiation depends on technical fit, qualification requirements, operating environment and the economics of the customer workflow rather than on a single headline specification. |
Segment Analysis: By Wetted Material
| Wetted Material | Market role | Commercial characteristics |
|---|---|---|
| PTFE/PFA | Core segment | PTFE/PFA represents a distinct purchasing and performance profile within the Diaphragm Pumps for Semiconductor market. Supplier differentiation depends on technical fit, qualification requirements, operating environment and the economics of the customer workflow rather than on a single headline specification. |
| Engineering Plastics | Strategic segment | Engineering Plastics represents a distinct purchasing and performance profile within the Diaphragm Pumps for Semiconductor market. Supplier differentiation depends on technical fit, qualification requirements, operating environment and the economics of the customer workflow rather than on a single headline specification. |
| Metal | Strategic segment | Metal represents a distinct purchasing and performance profile within the Diaphragm Pumps for Semiconductor market. Supplier differentiation depends on technical fit, qualification requirements, operating environment and the economics of the customer workflow rather than on a single headline specification. |
Segment Analysis: By Application
By application, demand spans High Purity Chemical Delivery, Cleaning Equipment, CMP Slurry Delivery, Others. High-purity chemical delivery and advanced wet processing has one of the strongest growth profiles because performance requirements and deployment intensity are increasing faster than in mature replacement-led uses.
| Application | Demand characteristics |
|---|---|
| High Purity Chemical Delivery | Purchasing in High Purity Chemical Delivery is driven by application performance, qualification, lifecycle cost and supplier support. The segment rewards vendors that can translate technical specifications into measurable system-level reliability, throughput or user value rather than competing only on component price. |
| Cleaning Equipment | Purchasing in Cleaning Equipment is driven by application performance, qualification, lifecycle cost and supplier support. The segment rewards vendors that can translate technical specifications into measurable system-level reliability, throughput or user value rather than competing only on component price. |
| CMP Slurry Delivery | Purchasing in CMP Slurry Delivery is driven by application performance, qualification, lifecycle cost and supplier support. The segment rewards vendors that can translate technical specifications into measurable system-level reliability, throughput or user value rather than competing only on component price. |
| Others | Purchasing in Others is driven by application performance, qualification, lifecycle cost and supplier support. The segment rewards vendors that can translate technical specifications into measurable system-level reliability, throughput or user value rather than competing only on component price. |
Regional Analysis
Asia Pacific leads the market in 2025. Regional demand differs by manufacturing concentration, deployment economics, regulation, infrastructure maturity and customer qualification practices, so supplier strategies must be adapted rather than copied from one geography to another.
How does regional demand differ in the Diaphragm Pumps for Semiconductor market?
Regional performance depends on where the underlying systems are manufactured, deployed and qualified. Asia Pacific benefits from the strongest concentration of the relevant demand engine, while North America and Europe typically offer deeper premium niches and structured qualification. South America and Middle East & Africa remain smaller but can provide project-driven or import-led opportunities.
| Region | Position | Growth outlook | Demand profile | Supplier selection |
|---|---|---|---|---|
| Asia Pacific | Largest | Positive | Distinct application mix | Qualification, availability and lifecycle support |
| North America | Position 2 | Positive | Distinct application mix | Qualification, availability and lifecycle support |
| Europe | Position 3 | Positive | Distinct application mix | Qualification, availability and lifecycle support |
| South America | Position 4 | Positive | Distinct application mix | Qualification, availability and lifecycle support |
| Middle East & Africa | Position 5 | Positive | Distinct application mix | Qualification, availability and lifecycle support |
Competitive Landscape
Competition in the Diaphragm Pumps for Semiconductor market is shaped by technical differentiation, qualification history, application engineering and the ability to support customers through design-in and production. Price remains important, but switching risk gives incumbents an advantage once a product is qualified.
The competitive set includes PSG (Dover), IDEX Corporation, YAMADA, Iwaki, YTS Japan, White Knight Fluid Handling alongside specialist and regional suppliers. Large diversified vendors benefit from broader customer access and manufacturing scale, while specialists compete through narrower technical depth, customization and responsiveness. The balance varies by application because qualification intensity and purchasing volumes differ materially.
Supplier share can change slowly in mature qualified applications because redesigning a component, material or software element creates engineering work beyond the purchase price. New platforms and greenfield capacity therefore create disproportionate opportunities for challengers, while aftermarket and replacement demand tends to reinforce incumbent relationships.
| Competitive group | Representative companies | Primary advantage |
|---|---|---|
| Global diversified suppliers | PSG (Dover), IDEX Corporation, YAMADA, Iwaki | Scale, broad account access, quality systems and lifecycle support |
| Specialists and focused vendors | YTS Japan, White Knight Fluid Handling, Argal Srl, Bueno Technology, Dellmeco GmbH | Application expertise, customization and faster engineering response |
| Regional and emerging suppliers | Sandpiper (Warren), Skylink, Wuhan Huaxin | Local availability, price competitiveness and proximity to customers |
Key Participants
The profiled competitive landscape includes PSG (Dover), IDEX Corporation, YAMADA, Iwaki, YTS Japan, White Knight Fluid Handling, Argal Srl, Bueno Technology, Dellmeco GmbH, Sandpiper (Warren), Skylink, Wuhan Huaxin. Competitive relevance should be read by product fit and end-market qualification, since not every supplier participates with the same breadth across all regions, specifications and customer tiers.
Production Capacity Analysis
Capacity in the Diaphragm Pumps for Semiconductor market is constrained by more than nominal factory output. The commercially useful measure is qualified capacity: production that can repeatedly meet customer specifications, quality controls and delivery requirements. Expansion therefore requires process capability, test infrastructure and trained engineering support as well as physical equipment.
Geographic concentration follows the upstream and downstream ecosystem supporting the market. Asia Pacific has a structural advantage where local suppliers can shorten qualification loops, support customer troubleshooting and synchronize capacity with nearby system manufacturers or deployment programs. North American and European suppliers often defend premium niches through IP, certification and application expertise.
The principal capacity risk is mismatch rather than absolute shortage. A supplier can have available floor space yet lack the process window, material grade, test capability or customer approval needed for a specific design. Buyers therefore increasingly examine business-continuity planning, second-source readiness and regional service capability when approving strategic suppliers.
Market Dynamics
The market is expanding because technology intensity is increasing in the systems that consume Diaphragm Pumps for Semiconductor solutions, but adoption remains gated by qualification, lifecycle economics and supply-chain execution. The strongest suppliers convert technical performance into lower integration risk and more predictable customer operations.
Market Drivers
| Driver | Impact | Commercial mechanism |
|---|---|---|
| Fab capacity expansion increases chemical-delivery points | High | Fab capacity expansion increases chemical-delivery points expands addressable demand by increasing system performance requirements, installation intensity or replacement value. The impact is strongest where customers can quantify avoided downtime, improved throughput or reduced integration complexity. |
| Advanced nodes tighten contamination-control requirements | High | Advanced nodes tighten contamination-control requirements expands addressable demand by increasing system performance requirements, installation intensity or replacement value. The impact is strongest where customers can quantify avoided downtime, improved throughput or reduced integration complexity. |
| CMP and wet cleaning create recurring pump demand | Medium | CMP and wet cleaning create recurring pump demand expands addressable demand by increasing system performance requirements, installation intensity or replacement value. The impact is strongest where customers can quantify avoided downtime, improved throughput or reduced integration complexity. |
| Automation favors stable, monitorable chemical transfer | Medium | Automation favors stable, monitorable chemical transfer expands addressable demand by increasing system performance requirements, installation intensity or replacement value. The impact is strongest where customers can quantify avoided downtime, improved throughput or reduced integration complexity. |
Fab capacity expansion increases chemical-delivery points
Fab capacity expansion increases chemical-delivery points is a meaningful driver because it changes the customer requirement rather than merely adding market awareness. Suppliers benefit when the trend creates a new technical threshold, additional unit content or a higher-value specification. Commercial conversion still depends on qualification timing and whether the customer can justify the system-level benefit against switching cost.
Advanced nodes tighten contamination-control requirements
Advanced nodes tighten contamination-control requirements is a meaningful driver because it changes the customer requirement rather than merely adding market awareness. Suppliers benefit when the trend creates a new technical threshold, additional unit content or a higher-value specification. Commercial conversion still depends on qualification timing and whether the customer can justify the system-level benefit against switching cost.
CMP and wet cleaning create recurring pump demand
CMP and wet cleaning create recurring pump demand is a meaningful driver because it changes the customer requirement rather than merely adding market awareness. Suppliers benefit when the trend creates a new technical threshold, additional unit content or a higher-value specification. Commercial conversion still depends on qualification timing and whether the customer can justify the system-level benefit against switching cost.
Automation favors stable, monitorable chemical transfer
Automation favors stable, monitorable chemical transfer is a meaningful driver because it changes the customer requirement rather than merely adding market awareness. Suppliers benefit when the trend creates a new technical threshold, additional unit content or a higher-value specification. Commercial conversion still depends on qualification timing and whether the customer can justify the system-level benefit against switching cost.
Market Restraints
| Restraint | Impact | Market effect |
|---|---|---|
| Lengthy fab qualification slows supplier switching | High | Lengthy fab qualification slows supplier switching can delay adoption, narrow the qualified supplier pool or increase total ownership cost. The effect is strongest in applications where redesign or process change creates validation risk beyond the component purchase price. |
| Diaphragm wear and pulsation require maintenance discipline | High | Diaphragm wear and pulsation require maintenance discipline can delay adoption, narrow the qualified supplier pool or increase total ownership cost. The effect is strongest in applications where redesign or process change creates validation risk beyond the component purchase price. |
| Alternative pump architectures compete in specialized process steps | Medium | Alternative pump architectures compete in specialized process steps can delay adoption, narrow the qualified supplier pool or increase total ownership cost. The effect is strongest in applications where redesign or process change creates validation risk beyond the component purchase price. |
| Material incompatibility can cause costly contamination events | Medium | Material incompatibility can cause costly contamination events can delay adoption, narrow the qualified supplier pool or increase total ownership cost. The effect is strongest in applications where redesign or process change creates validation risk beyond the component purchase price. |
Lengthy fab qualification slows supplier switching
Lengthy fab qualification slows supplier switching constrains market conversion because buyers must manage technical, operational and financial risk simultaneously. Even when the long-term technology direction is favorable, project delays, qualification burden or competing architectures can shift demand between suppliers and postpone revenue recognition. Successful vendors address the restraint through design support, reliability evidence and clearer lifecycle economics.
Diaphragm wear and pulsation require maintenance discipline
Diaphragm wear and pulsation require maintenance discipline constrains market conversion because buyers must manage technical, operational and financial risk simultaneously. Even when the long-term technology direction is favorable, project delays, qualification burden or competing architectures can shift demand between suppliers and postpone revenue recognition. Successful vendors address the restraint through design support, reliability evidence and clearer lifecycle economics.
Alternative pump architectures compete in specialized process steps
Alternative pump architectures compete in specialized process steps constrains market conversion because buyers must manage technical, operational and financial risk simultaneously. Even when the long-term technology direction is favorable, project delays, qualification burden or competing architectures can shift demand between suppliers and postpone revenue recognition. Successful vendors address the restraint through design support, reliability evidence and clearer lifecycle economics.
Material incompatibility can cause costly contamination events
Material incompatibility can cause costly contamination events constrains market conversion because buyers must manage technical, operational and financial risk simultaneously. Even when the long-term technology direction is favorable, project delays, qualification burden or competing architectures can shift demand between suppliers and postpone revenue recognition. Successful vendors address the restraint through design support, reliability evidence and clearer lifecycle economics.
Market Opportunities
Predictive maintenance using pump-cycle and pressure data
Predictive maintenance using pump-cycle and pressure data creates a focused opportunity where existing products or operating models no longer fully match customer requirements. The most attractive positioning combines a measurable technical advantage with easier qualification, reliable supply and application support. Suppliers that enter early in the design cycle can secure longer-lived revenue because redesign costs increase after customer validation.
Advanced packaging wet processes and chemical delivery
Advanced packaging wet processes and chemical delivery creates a focused opportunity where existing products or operating models no longer fully match customer requirements. The most attractive positioning combines a measurable technical advantage with easier qualification, reliable supply and application support. Suppliers that enter early in the design cycle can secure longer-lived revenue because redesign costs increase after customer validation.
Localized service hubs near Asian fab clusters
Localized service hubs near Asian fab clusters creates a focused opportunity where existing products or operating models no longer fully match customer requirements. The most attractive positioning combines a measurable technical advantage with easier qualification, reliable supply and application support. Suppliers that enter early in the design cycle can secure longer-lived revenue because redesign costs increase after customer validation.
Lower-pulsation metering for precision chemical dosing
Lower-pulsation metering for precision chemical dosing creates a focused opportunity where existing products or operating models no longer fully match customer requirements. The most attractive positioning combines a measurable technical advantage with easier qualification, reliable supply and application support. Suppliers that enter early in the design cycle can secure longer-lived revenue because redesign costs increase after customer validation.
Supply Chain Analysis
High-purity fluoropolymers, elastomers and metals
Pump machining, molding and assembly
Chemical-delivery and process-tool integration
Fab maintenance, spares and field service
High-purity fluoropolymers, elastomers and metals
High-purity fluoropolymers, elastomers and metals is a critical value-chain stage because quality, lead time and technical consistency at this point propagate into downstream performance. Value capture is highest when suppliers solve a difficult qualification or integration problem, while bottlenecks emerge when specialized materials, process know-how or test capacity cannot be substituted quickly.
Pump machining, molding and assembly
Pump machining, molding and assembly is a critical value-chain stage because quality, lead time and technical consistency at this point propagate into downstream performance. Value capture is highest when suppliers solve a difficult qualification or integration problem, while bottlenecks emerge when specialized materials, process know-how or test capacity cannot be substituted quickly.
Chemical-delivery and process-tool integration
Chemical-delivery and process-tool integration is a critical value-chain stage because quality, lead time and technical consistency at this point propagate into downstream performance. Value capture is highest when suppliers solve a difficult qualification or integration problem, while bottlenecks emerge when specialized materials, process know-how or test capacity cannot be substituted quickly.
Fab maintenance, spares and field service
Fab maintenance, spares and field service is a critical value-chain stage because quality, lead time and technical consistency at this point propagate into downstream performance. Value capture is highest when suppliers solve a difficult qualification or integration problem, while bottlenecks emerge when specialized materials, process know-how or test capacity cannot be substituted quickly.
Recent Developments
2026
SEMI reported global semiconductor equipment billings of USD 135.1 billion for 2025, up 15% year over year; China, Taiwan and Korea together represented 79% of spending. The concentration reinforces Asia Pacific as the key commercial geography for fab fluid-handling suppliers. Source
2025
High-purity pump suppliers continued to emphasize chemically resistant flow paths and contamination control for semiconductor chemical delivery, where pump material selection directly affects process cleanliness and uptime. Source
2025
Chemical-delivery architectures increasingly combine pump reliability with monitored distribution systems, creating an opportunity for suppliers that can support both component performance and application engineering. Source
Taken together, these developments show that market structure is being shaped by concrete technology, capacity, standards and regulatory changes rather than by demand growth alone. For suppliers, the practical implication is to align product roadmaps and regional support with the specific transition that is changing customer qualification or procurement behavior.
Report Scope & Segmentation
| Attribute | Coverage |
|---|---|
| Base year | 2025 |
| Estimated year | 2026 |
| Forecast period | 2026–2034 |
| 2025 market size | USD million 138.8 |
| 2026 estimated size | USD million 151.1 |
| 2034 projected size | USD million 298.9 |
| CAGR (2026–2034) | 8.9% |
| By Type | Metal Type, Plastic Type |
| By Application | High Purity Chemical Delivery, Cleaning Equipment, CMP Slurry Delivery, Others |
| By Actuation | Air-Operated Double-Diaphragm, Pneumatic Metering/Rolling-Diaphragm |
| By Wetted Material | PTFE/PFA, Engineering Plastics, Metal |
| Regions | North America, Europe, Asia Pacific, South America, Middle East & Africa |
| Companies | PSG (Dover), IDEX Corporation, YAMADA, Iwaki, YTS Japan, White Knight Fluid Handling, Argal Srl, Bueno Technology, Dellmeco GmbH, Sandpiper (Warren), Skylink, Wuhan Huaxin |
Frequently Asked Questions
What is the Diaphragm Pumps for Semiconductor market size in 2025?
The global market is valued at USD million 138.8 in 2025. The 2026 estimate is USD million 151.1, providing the starting point for the 2026–2034 forecast period.
What is the forecast market size by 2034?
The market is projected to reach USD million 298.9 by 2034, reflecting continued adoption across the applications and regions covered in this overview.
What is the expected CAGR during 2026–2034?
The market is expected to expand at a CAGR of 8.9% during 2026–2034. Growth is supported by technology upgrades, higher performance requirements and broader deployment in the strongest application segments.
Which region is the largest market?
Asia Pacific is the largest regional market in 2025. Its position reflects the concentration of relevant manufacturing, infrastructure deployment, technology investment or end-user demand supporting this market.
Which product type has the strongest growth profile?
High-purity plastic and fluoropolymer configurations have a strong growth profile because customers increasingly value performance, integration and lifecycle economics. Segment leadership can vary by application because qualification requirements and system architectures are not uniform.
Which application is expanding fastest?
High-purity chemical delivery and advanced wet processing is one of the fastest-expanding application areas, supported by rising technical requirements and a growing need for qualified suppliers that can support design-in, integration and ongoing operations.
What are the main market drivers?
The main drivers include Fab capacity expansion increases chemical-delivery points, Advanced nodes tighten contamination-control requirements, CMP and wet cleaning create recurring pump demand. Each driver affects purchasing by changing required performance, deployment intensity or the cost of system failure rather than simply increasing product awareness.
What are the main restraints?
Key restraints include Lengthy fab qualification slows supplier switching, Diaphragm wear and pulsation require maintenance discipline, Alternative pump architectures compete in specialized process steps. These factors can extend qualification cycles, raise switching costs or shift demand toward competing architectures when customers prioritize risk reduction.
Who are the key market participants?
Key profiled participants include PSG (Dover), IDEX Corporation, YAMADA, Iwaki, YTS Japan, White Knight Fluid Handling, Argal Srl, alongside additional specialist and regional suppliers. Competitive positioning depends on product fit, qualification record, supply reliability and application support.
What determines supplier selection?
Supplier selection is typically determined by technical compliance, repeatable quality, qualification history, total lifecycle cost, delivery reliability and access to regional application support. In high-consequence applications, proven field performance can outweigh a modest unit-price difference.
Research Sources & Evidence Base
View research sources used for this overview.
- SEMI. Global semiconductor equipment billings reached $135.1 billion in 2025 — Regional equipment-spending concentration and semiconductor investment context.
- White Knight Fluid Handling. Semiconductor industry solutions — High-purity fluid handling requirements for semiconductor manufacturing.
- White Knight Fluid Handling. Chemical delivery applications — Chemical delivery and semiconductor pump application context.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF