Key Statistics
Key Takeaways
- Amplifiers are the leading source-page type segment because operational, audio and RF amplifiers remain fundamental across industrial sensing, automotive systems and communication equipment. Data converters, interface ICs and power-management devices create additional high-value demand where precision, noise and efficiency become system constraints.
- Automotive is the leading application on the source page. IEA reported more than 20 million electric cars sold globally in 2025, with China above 13 million and Europe above 4 million, increasing demand for battery monitoring, power conversion, sensor interfaces and mixed-signal control.
- Asia Pacific is the largest region because the source page states the area consumes more than 50% of global analog semiconductors and its FAQ also identifies Asia Pacific as the market leader. China, Japan and South Korea combine electronics manufacturing, automotive production and industrial automation at large scale.
- Foundational analog capacity is expanding. Texas Instruments began production at its Sherman SM1 300 mm fab in December 2025, while Infineon opened a €5 billion Smart Power Fab in Dresden in July 2026 for power semiconductors and analog/mixed-signal technologies.
- The source-page CAGR is slightly inconsistent with the published size anchors. USD 82.01 billion in 2024 and USD 107.81 billion in 2032 imply approximately 3.5% annual growth, not 4.1%, so the anchor-derived series is used throughout.
General Analog Semiconductor Market Overview
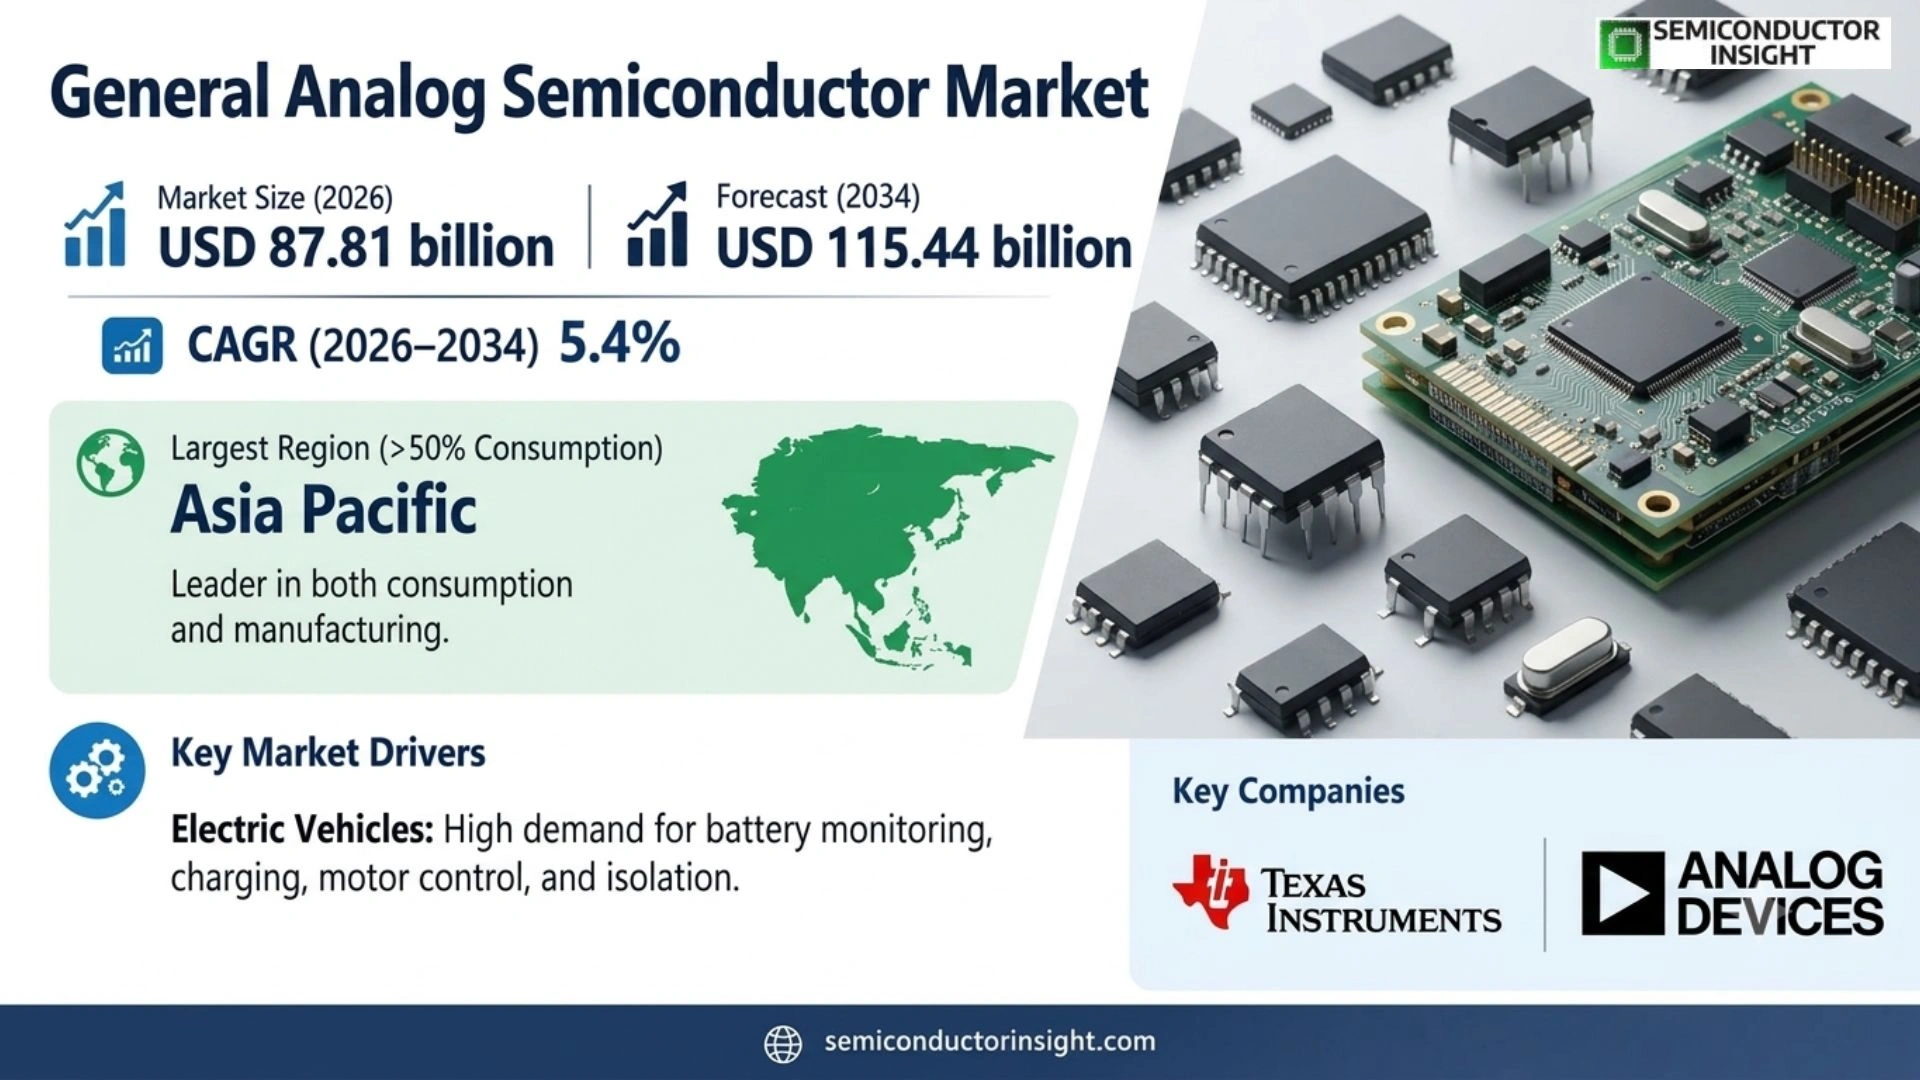
General Analog Semiconductor market is rebased to USD 84.86 billion in 2025, increases to an estimated USD 87.81 billion in 2026, and is projected to reach USD 115.44 billion by 2034. The selected source-page size anchors imply a 3.5% CAGR during 2026–2034. Asia Pacific is the largest consumption region in 2025 because the source page states that Asia Pacific accounts for more than 50% of global analog semiconductor consumption, while current demand is being reshaped by automotive electrification, industrial automation, AI data-center power delivery, precision sensing, 5G/6G connectivity and renewed 300 mm investment in mature-node analog and mixed-signal capacity.
General analog semiconductors translate, condition and manage real-world signals before or after digital processing. The category spans amplifiers, data converters, interface semiconductors and power-management ICs that regulate voltage, sense physical conditions, isolate systems and connect processors to motors, batteries, radios and sensors. Unlike advanced digital logic, many analog functions gain little from the smallest process node, so product competitiveness depends on device architecture, process specialization, packaging, precision, noise and long-term reliability.
Demand is broadening across industrial, automotive and data-center markets. Texas Instruments reported second-quarter 2026 revenue of USD 5.46 billion, up 23% year over year, with broad growth led by industrial, data center and automotive. Skyworks reported third-quarter fiscal 2026 revenue of USD 935 million and cited double-digit gains in automotive and data center within broad markets. These supplier results show that analog growth is increasingly supported by diversified infrastructure demand rather than one consumer cycle.
Production economics are also changing. TI is expanding 300 mm capacity on 45 nm to 130 nm process technologies optimized for analog and embedded products, while Infineon’s Dresden Smart Power Fab combines power devices with analog/mixed-signal technologies. Larger wafers can lower die cost for high-volume mature-node products, but analog capacity still requires dedicated process modules, high-voltage options, trimming, test and packaging that are specific to each product family.
Segment Analysis: By Type
The source page segments the market into Amplifiers, Data Converters, Interface Semiconductors, Power Management ICs and Others. Amplifiers are identified as the largest segment, while the formal Table of Contents omits Power Management ICs even though the detailed segment analysis explicitly includes them. This article preserves the broader detailed taxonomy and records the source-structure inconsistency rather than removing a major analog category.
| Type | Technical / commercial role | Market position |
|---|---|---|
| Amplifiers | Operational amplifiers, audio amplifiers and RF amplifiers condition weak or variable signals so downstream circuits can process them accurately. Industrial sensors need low offset and noise, automotive systems need wide common-mode and temperature performance, and RF chains require linearity at high frequency. The addressable market therefore spans inexpensive commodity devices through precision and high-speed specialty amplifiers. | Largest source-page segment. Volume is supported by broad electronics penetration, while revenue growth is strongest where precision, bandwidth, isolation or automotive qualification create higher ASPs and switching costs. |
| Data Converters | Analog-to-digital converters and digital-to-analog converters bridge sensors, radios and control loops with digital processors. Performance is defined by resolution, sampling rate, signal-to-noise ratio, linearity and power. Industrial instrumentation and communications can pay significant premiums for high-resolution or high-speed devices because converter performance sets system accuracy or bandwidth. | High-value growth segment. Edge intelligence, industrial condition monitoring and software-defined radio increase the number of analog channels that must be digitized, while higher sampling speed raises power and interface complexity. |
| Interface Semiconductors | Digital isolators, CAN transceivers, USB interfaces and other physical-layer devices protect, translate and transport signals between subsystems. Automotive zonal architectures, factory networks and isolated power systems require robust interfaces that tolerate voltage differences, common-mode transients and electromagnetic noise. | Durable application-driven segment. Interface ICs benefit from rising connectivity per system and long qualification cycles, especially in automotive and industrial markets where replacing a validated transceiver can require substantial engineering effort. |
| Power Management ICs | Power-management ICs regulate, convert, sequence and monitor voltage across batteries, processors, sensors and power rails. Applications range from tiny wearable regulators to multi-phase data-center controllers and high-voltage automotive power systems. Efficiency, transient response, quiescent current and integration determine system-level value. | Strategic growth category. AI servers, EVs, renewable-energy systems and battery-powered devices all increase the number and sophistication of power rails, creating strong demand for efficient analog control even when digital processor unit growth is modest. |
| Others | Other general analog devices include comparators, references, timers, sensor-conditioning ICs and application-specific mixed-signal products. These niches can be highly profitable where accuracy, safety or environment requirements are stringent and where customers maintain platforms for long periods. | Fragmented but resilient. Long product lifecycles and application-specific qualification can reduce price erosion, although addressable volumes are smaller than mainstream amplifiers or power-management devices. |
Secondary segmentation: By Technology
The source page further segments the market into Bipolar, CMOS, BiCMOS and Others, with CMOS identified as the leading technology because it combines low power, integration and cost. Bipolar devices remain important for precision and high-current behavior, while BiCMOS blends CMOS control with bipolar analog performance where system requirements justify additional process complexity.
| Technology | Commercial role |
|---|---|
| CMOS | CMOS dominates many mixed-signal and power-management functions because it supports dense digital control, low static power and scalable manufacturing. Mature 300 mm CMOS also improves cost for high-volume analog products. Designers can integrate calibration, diagnostics and communication logic around an analog core without moving to bleeding-edge nodes. |
| Bipolar | Bipolar processes provide high transconductance, predictable analog gain and strong current drive, supporting precision amplifiers, references and selected power or RF functions. The technology remains economically important where analog performance matters more than logic density. |
| BiCMOS | BiCMOS combines CMOS logic with bipolar devices, enabling high-speed interfaces, RF and precision analog functions alongside integrated control. It is more expensive than pure CMOS but can deliver system-level advantages when bandwidth, noise or output drive must be optimized together. |
| Others | Other technologies include silicon-on-insulator, BCD power processes and compound-semiconductor or specialized high-voltage variants. These platforms address application niches that cannot be served efficiently with standard CMOS, particularly power, RF and harsh-environment systems. |
Secondary segmentation: By End User
The source page identifies OEMs, Distributors, System Integrators and Others, with OEMs described as the primary purchasers. Direct OEM relationships are strategically important because analog components are selected early in system design and often remain qualified for the full lifecycle of a vehicle, industrial platform or medical instrument. For analog semiconductor suppliers, the commercial consequence is that process technology, qualification, design support and long-term manufacturing control determine revenue quality more directly than simple transistor scaling.
| End user | Commercial characteristics |
|---|---|
| OEMs | Automotive, industrial, telecom and consumer OEMs define electrical requirements and qualify analog devices against system performance. Their design wins create recurring revenue over multiple years and may include customized packaging, functional-safety documentation or supply agreements. |
| Distributors | Authorized distributors provide inventory, technical support and access to very broad analog portfolios. Distribution is especially important for industrial and medical customers that buy many low-volume part numbers and need long-tail availability rather than one large-volume direct contract. |
| System Integrators | Integrators combine sensors, processors, power electronics and communication into complete automation, energy or infrastructure systems. They value reference designs and application support because system behavior depends on interactions across many analog components. |
| Others | Other buyers include contract manufacturers, design houses and research organizations. Their purchasing influence varies by project, but they can accelerate adoption when they specify a common analog platform across several customer systems. |
Segment Analysis: By Application
By application, the source page segments demand into Automotive, IT & Telecommunications, Consumer Electronics, Healthcare Devices and Industrial Automation. Automotive is identified as the largest application, while industrial and data-center-related demand are currently especially strong in supplier results because electrification, AI power delivery and factory automation increase analog content per system.
| Application | Demand characteristics |
|---|---|
| Automotive | EV powertrains, battery management, ADAS, infotainment and zonal controllers use precision sensing, interface transceivers, regulators and power-management ICs. IEA reported more than 20 million electric cars sold globally in 2025, including more than 13 million in China and more than 4 million in Europe, expanding the addressable analog content pool. |
| IT & Telecommunications | Data centers, 5G/6G networks, switches and storage platforms need high-speed converters, clocking, isolation and sophisticated power conversion. STMicroelectronics’ 2026 collaboration with NVIDIA on 800 VDC data-center power architectures illustrates how analog and mixed-signal design is moving deeper into AI infrastructure. |
| Consumer Electronics | Smartphones, wearables, appliances and personal electronics use amplifiers, PMICs, audio, sensors and interface ICs. Unit volumes remain large, but product cycles are short and price pressure is strong, so suppliers compete through integration, low power and compact packaging. |
| Healthcare Devices | Patient monitoring, diagnostics, imaging and portable medical devices require precision analog front ends, converters and low-power management. Regulatory qualification and long product life make stable supply and noise performance more important than minimum cost alone. |
| Industrial Automation | Robots, motor drives, PLCs and predictive-maintenance systems use isolated interfaces, converters and precision signal conditioning. IFR reported 542,000 industrial robots installed in 2024, with Asia accounting for 74% of deployments, creating a broad installed base for analog control and sensing. |
Regional Analysis
The source page states that Asia Pacific accounts for more than 50% of global analog semiconductor consumption and its FAQ also identifies the region as the market leader. North America remains an innovation and design center, Europe is especially strong in automotive and industrial electronics, and emerging regions grow through vehicle electrification, telecom and factory automation.
How do analog semiconductor demand mechanisms differ across the major regions?
Analog demand follows the physical systems being electrified and automated rather than only consumer device shipments. Asia Pacific combines manufacturing volume, electric vehicles and robotics. North America drives AI data-center, industrial and product-design demand and is adding local foundational capacity. Europe couples automotive electrification with industrial control and new power/analog fabs. South America and MEA remain more import dependent but gain analog content as EV, telecom and industrial projects scale.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia Pacific | Largest – >50% source-page consumption | High | Electronics, EV and automation-led | Cost, local support, fab scale and product breadth |
| North America | Innovation and capacity hub | Moderate to high | Industrial, data center and automotive-led | Design support, supply assurance and 300 mm scale |
| Europe | Automotive/industrial specialist | Moderate to high | EV, factory automation and power electronics-led | Reliability, local manufacturing and qualification |
| South America | Emerging | Moderate | Automotive, telecom and industrial-led | Distribution, landed cost and design support |
| Middle East & Africa | Emerging | Moderate from small base | Smart-city, telecom and energy-led | Ruggedness, import availability and system integration |
Competitive Landscape
The source page profiles seven companies in its formal manufacturer section: Texas Instruments, Infineon Technologies, Skyworks Solutions, STMicroelectronics, NXP Semiconductors, Qualcomm Technologies and Mixed-Mode Technology. It also mentions onsemi and Renesas in a shorter topline list. The analysis preserves the seven fully profiled companies and excludes an unsupported source-page claim that STMicroelectronics acquired Cirrus Logic, because current primary-source verification does not support that statement.
Texas Instruments leads through an exceptionally broad catalog of amplifiers, converters, interfaces and power management and is investing heavily in 300 mm manufacturing. Its advantage is not only product breadth but cost structure and supply control: TI states it is investing in 45 nm to 130 nm nodes and aims for about 95% internal manufacturing by 2030, which can improve supply resilience for long-lifecycle analog customers.
Infineon and STMicroelectronics are especially strong in automotive, industrial and power applications. Infineon’s Smart Power Fab adds flexible 300 mm capacity, while ST is integrating analog and mixed-signal functions into AI power architectures. NXP combines analog interfaces with automotive and embedded processing, and Skyworks is expanding analog/mixed-signal exposure in data center, automotive and RF connectivity.
Qualcomm’s analog participation is more closely tied to RF front ends and mobile platforms, while Mixed-Mode Technology represents a smaller regional specialist. The broader competitive field also includes Analog Devices, onsemi and Renesas, but they are not part of the source page’s formal seven-company profile section and are therefore not added to the profiled-company list.
| Competitive tier | Companies | Why they matter |
|---|---|---|
| Global broad-line leaders | Texas Instruments; Infineon Technologies; STMicroelectronics; NXP Semiconductors | These suppliers combine broad analog portfolios with automotive, industrial and power expertise. Their competitive advantage comes from process technology, manufacturing scale, reference designs and long-term OEM qualification across many applications. |
| RF / mixed-signal specialists | Skyworks Solutions; Qualcomm Technologies | These companies compete where RF, connectivity, timing and mixed-signal performance define system value. Skyworks’ current growth in data center and automotive broad markets expands its relevance beyond traditional mobile RF. |
| Regional specialist | Mixed-Mode Technology | The company serves analog and mixed-signal applications with a smaller footprint. Regional specialists can win design slots through focused products and local support but lack the manufacturing and catalog scale of the largest global suppliers. |
Companies profiled in the report
The source-page Table of Contents profiles Texas Instruments, Infineon Technologies, Skyworks Solutions, STMicroelectronics, NXP Semiconductors, Qualcomm Technologies and Mixed-Mode Technology. The article preserves this seven-company profile list exactly as the source’s formal manufacturer section. This matters because analog devices are selected around real electrical constraints such as noise, voltage, current, isolation and temperature, so switching a qualified component can require substantial system redesign.
Production Capacity Analysis
Analog production capacity is concentrated on mature and specialty process technologies where voltage handling, noise, precision and mixed-signal integration matter more than transistor density. Capacity planning therefore centers on 200 mm and 300 mm foundational fabs, specialty process modules, backend assembly and extensive electrical test. Current investment by TI and Infineon shows that mature-node analog capacity remains strategically important through the AI and electrification cycle.
Texas Instruments says its manufacturing strategy is focused on 45 nm to 130 nm process nodes and 300 mm fabs, which lower cost per die for high-volume analog and embedded products. SM1 in Sherman began production in December 2025 and is designed to ramp with demand, while TI continues building connected fabs in Texas and Utah. This gives the company a long-duration capacity platform rather than a one-cycle expansion.
Infineon’s Dresden Smart Power Fab opened in July 2026 with a €5 billion investment and is designed for power semiconductor and analog/mixed-signal technologies. The company says capacity ramp-up can be accelerated to capture market opportunities. This flexibility is important because automotive, industrial and AI power demand do not always peak at the same time.
Backend capacity remains critical because analog devices often require package-specific thermal, isolation or sensing performance and substantial final testing. Precision converters, automotive interfaces and power ICs may need trimming, high-temperature test and reliability screening. Saleable capacity is therefore limited by the complete wafer-to-package-to-test flow rather than wafer starts alone. The purchasing decision therefore connects system performance, supply assurance, lifecycle support and application engineering rather than treating the device as a fully interchangeable commodity.
Market Dynamics
The market is driven by electrification, industrial automation, AI power delivery and connectivity, but it faces design-complexity, capacity-planning and pricing challenges. Analog products can remain qualified for many years, creating stable revenue streams, yet each new application requires engineers to balance noise, precision, efficiency and cost rather than relying on automatic digital scaling.
Market Drivers
| Driver | Directional impact* | Commercial mechanism |
|---|---|---|
| Automotive electrification | High | EVs increase battery monitoring, power-management, sensor-interface and network content per vehicle; global electric-car sales exceeded 20 million in 2025. |
| Industrial automation | High | Robots, motor drives and condition-monitoring systems require converters, isolation and precision signal conditioning; 542,000 industrial robots were installed in 2024. |
| AI data-center power | High | 800 VDC architectures, point-of-load conversion and isolation increase demand for analog control and power-management devices. |
| 5G/6G connectivity | Medium to High | RF front ends, converters, timing and interface ICs gain complexity as frequency bands and data rates increase. |
Electric vehicles multiply analog content
An EV needs battery monitoring, charging control, isolation, motor-drive sensing and vehicle-network interfaces in addition to the analog content already present in conventional vehicles. IEA’s more-than-20-million electric-car sales figure for 2025 gives a concrete scale to this content expansion, while regional growth spreads the demand across China, Europe, North America and emerging markets.
Factory automation creates recurring precision demand
Industrial systems convert temperature, pressure, vibration, current and position into digital control data. IFR’s 542,000 robot installations in 2024 represent only one part of a broader automation base that also includes drives, PLCs and condition monitoring. Analog converters and amplifiers therefore benefit from both new installations and retrofit cycles. Through 2034, suppliers that combine flexible mature-node capacity with differentiated automotive, industrial and AI power products can protect margins while serving several end-market cycles.
AI infrastructure creates a new analog growth layer
AI accelerators operate digitally, but their power distribution, timing, isolation and thermal monitoring are analog-intensive. ST’s 2026 800 VDC collaboration with NVIDIA and Skyworks’ AI data-center isolation and timing design wins show that analog suppliers can gain content as rack power rises, even though the processor itself is a leading-edge digital device.
Connectivity raises RF and interface complexity
5G, Wi-Fi 7 and early 6G systems use more frequency bands and tighter timing. Skyworks reported broad-market growth led partly by data center and connectivity and has introduced FR3 RF and timing solutions, showing how communications can increase analog value per system rather than only base-station unit counts. The market implication is that nominal wafer capacity becomes commercially valuable only when the process, package and test flow are qualified for the exact analog performance and reliability class required by customers.
Market Restraints
| Restraint | Directional impact* | Commercial mechanism |
|---|---|---|
| Analog design complexity | High | Noise, linearity, matching and stability must be optimized manually and verified across process, voltage and temperature, lengthening development cycles. |
| Capacity timing risk | Medium to High | Large 300 mm fabs take years to build; analog demand is diversified but cyclical by end market, creating utilization risk when expansions ramp. |
| Pricing pressure | Medium | Commodity amplifiers and interfaces can be multi-sourced, forcing annual cost-down unless suppliers differentiate through precision, integration or qualification. |
| Qualification burden | Medium to High | Automotive and medical products require lengthy validation and controlled changes, slowing new product adoption and raising entry barriers. |
Analog design does not scale automatically
Shrinking geometry can worsen device matching, voltage headroom and noise even as it improves digital density. Engineers must therefore redesign circuits carefully around each process. This slows development, makes experienced analog talent scarce and increases the risk that a new node fails to deliver a clear cost or performance advantage.
Capacity decisions require long lead times
TI and Infineon are investing billions in new 300 mm fabs, but demand is distributed across automotive, industrial, consumer and communications cycles. A fab that becomes available during a downturn can pressure utilization, while a delayed ramp during an upcycle can extend lead times. Flexible manufacturing and broad product portfolios are therefore strategic advantages.
Standard products face persistent price erosion
General-purpose amplifiers and interfaces can be pin compatible across several vendors. Customers can negotiate aggressively once a part becomes standardized, so suppliers must continually lower manufacturing cost or move toward precision, automotive, high-voltage and integrated products that have higher switching costs. For analog semiconductor suppliers, the commercial consequence is that process technology, qualification, design support and long-term manufacturing control determine revenue quality more directly than simple transistor scaling.
Qualification slows supplier substitution
Automotive, industrial and medical customers validate performance across temperature, lifetime and system conditions. This protects incumbent design wins but also slows adoption of new capacity or entrants. A new product can be technically superior yet generate little revenue until customer platforms complete qualification. This matters because analog devices are selected around real electrical constraints such as noise, voltage, current, isolation and temperature, so switching a qualified component can require substantial system redesign.
Market Opportunities
AI power architecture
The shift toward 800 VDC data-center distribution creates opportunities for isolation, current sensing, gate control and point-of-load regulation. Analog suppliers can capture content at multiple conversion stages and build product families around a rapidly changing infrastructure standard. The purchasing decision therefore connects system performance, supply assurance, lifecycle support and application engineering rather than treating the device as a fully interchangeable commodity.
Software-defined vehicles
Centralized compute and zonal architectures increase sensor aggregation, power domains and network interfaces. Suppliers with automotive-qualified converters, PMICs and transceivers can win long-lived platforms as vehicles become more electronically centralized. Through 2034, suppliers that combine flexible mature-node capacity with differentiated automotive, industrial and AI power products can protect margins while serving several end-market cycles.
Precision edge sensing
Industrial and medical edge devices increasingly perform local analytics but still depend on accurate physical-world data. Low-noise amplifiers and high-resolution converters can gain value as sensor quality becomes a limiting factor for machine-learning or predictive-maintenance models. The market implication is that nominal wafer capacity becomes commercially valuable only when the process, package and test flow are qualified for the exact analog performance and reliability class required by customers.
Regional manufacturing resilience
TI’s U.S. expansion and Infineon’s Dresden investment demonstrate customer willingness to value geographic supply resilience. Analog vendors with distributed fabs can use regional capacity as a commercial differentiator for automotive and industrial customers concerned about long product lifecycles. For analog semiconductor suppliers, the commercial consequence is that process technology, qualification, design support and long-term manufacturing control determine revenue quality more directly than simple transistor scaling.
Supply Chain Analysis
Silicon wafers & specialty materials
Wafer fabrication
Assembly, packaging & test
Distribution, reference design & OEM design-in
Silicon wafers & specialty materials
Analog fabs use silicon wafers, high-purity gases, metals, dielectrics and specialty process materials. High-voltage and precision devices may require unique implants, isolation structures or epitaxial layers that differ from standard digital CMOS. This matters because analog devices are selected around real electrical constraints such as noise, voltage, current, isolation and temperature, so switching a qualified component can require substantial system redesign.
Wafer fabrication
Foundries and IDMs build analog devices on mature CMOS, BCD, bipolar or BiCMOS processes. Yield, device matching and analog process characterization determine whether a technology can support precision, voltage and temperature specifications economically. The purchasing decision therefore connects system performance, supply assurance, lifecycle support and application engineering rather than treating the device as a fully interchangeable commodity.
Assembly, packaging & test
Analog products are packaged in QFN, BGA, leaded, power or isolation packages and undergo extensive electrical test. Automotive parts add AEC-Q100 qualification and long-term change control, while precision devices may require trimming and calibration. Through 2034, suppliers that combine flexible mature-node capacity with differentiated automotive, industrial and AI power products can protect margins while serving several end-market cycles.
Distribution, reference design & OEM design-in
Broad catalogs are sold through direct OEM teams and authorized distributors. Reference designs and application engineering help customers select and stabilize products, and a successful design-in can generate recurring revenue for the lifetime of a vehicle, industrial platform or medical system. The market implication is that nominal wafer capacity becomes commercially valuable only when the process, package and test flow are qualified for the exact analog performance and reliability class required by customers.
Recent Developments
Recent primary-source developments show analog semiconductor growth being supported by both manufacturing investment and new AI/automotive applications. The list excludes an unsupported acquisition claim contained on the source page and uses only current official company announcements for the developments below. For analog semiconductor suppliers, the commercial consequence is that process technology, qualification, design support and long-term manufacturing control determine revenue quality more directly than simple transistor scaling.
July 28, 2026 – Skyworks reported Q3 FY2026 results
Skyworks reported revenue of USD 935 million and said Broad Markets growth was led by automotive and data center. The company also cited AI data-center timing and 800-volt power-isolation design wins, showing that its analog and mixed-signal portfolio is moving into high-power infrastructure alongside traditional mobile RF applications. This matters because analog devices are selected around real electrical constraints such as noise, voltage, current, isolation and temperature, so switching a qualified component can require substantial system redesign.
July 22, 2026 – Texas Instruments reported broad industrial, data-center and automotive growth
TI reported second-quarter revenue of USD 5.46 billion, up 23% from the same quarter a year earlier, with broad growth led by industrial, data center and automotive. Management also highlighted the benefit of its 300 mm production strategy, connecting market recovery with lower-cost foundational semiconductor manufacturing. The purchasing decision therefore connects system performance, supply assurance, lifecycle support and application engineering rather than treating the device as a fully interchangeable commodity.
July 2, 2026 – Infineon opened the €5 billion Smart Power Fab in Dresden
Infineon opened a €5 billion 300 mm facility for power semiconductors and analog/mixed-signal technologies several months ahead of schedule. The company says the site can support AI data-center power supplies, renewable energy and software-defined vehicles and can ramp capacity faster if demand accelerates. Through 2034, suppliers that combine flexible mature-node capacity with differentiated automotive, industrial and AI power products can protect margins while serving several end-market cycles.
March 17, 2026 – ST expanded its 800 VDC AI data-center power portfolio with NVIDIA
STMicroelectronics announced 12 V and 6 V architectures that complement its 800 VDC-to-50 V conversion stage. The company emphasized its power, analog and mixed-signal technology at both chip and package level, illustrating how general analog suppliers are gaining content inside gigawatt-scale AI infrastructure. The market implication is that nominal wafer capacity becomes commercially valuable only when the process, package and test flow are qualified for the exact analog performance and reliability class required by customers.
December 17, 2025 – TI began production at its Sherman SM1 300 mm fab
Texas Instruments started production at its newest Sherman, Texas fab. TI says SM1 will ramp with customer demand and ultimately produce tens of millions of analog and embedded processing chips daily, strengthening dependable U.S. supply for automotive, industrial, medical and data-center customers. For analog semiconductor suppliers, the commercial consequence is that process technology, qualification, design support and long-term manufacturing control determine revenue quality more directly than simple transistor scaling.
Report Scope & Segmentation
| Attribute | Coverage |
|---|---|
| Market | General Analog Semiconductor |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| 2025 Market Size | USD 84.86 billion |
| 2034 Forecast Size | USD 115.44 billion |
| CAGR | 3.5% (2026–2034) |
| Largest Market in 2025 | Asia Pacific |
| By Type | Amplifiers; Data Converters; Interface Semiconductors; Power Management ICs; Others |
| By Application | Automotive; IT & Telecommunications; Consumer Electronics; Healthcare Devices; Industrial Automation |
| By Technology | Bipolar; CMOS; BiCMOS; Others |
| By End User | OEMs; Distributors; System Integrators; Others |
| Regions | North America; Europe; Asia Pacific; South America; Middle East & Africa |
| Companies Profiled | Texas Instruments; Infineon Technologies; Skyworks Solutions; STMicroelectronics; NXP Semiconductors; Qualcomm Technologies; Mixed-Mode Technology |
Frequently Asked Questions
What is the General Analog Semiconductor market size in 2025?
The source page publishes USD 82.01 billion in 2024 and USD 107.81 billion in 2032. Those anchors imply a 2025 market size of approximately USD 84.86 billion. Applying the same compound factor gives an estimated USD 87.81 billion in 2026 and approximately USD 115.44 billion in 2034. This matters because analog devices are selected around real electrical constraints such as noise, voltage, current, isolation and temperature, so switching a qualified component can require substantial system redesign.
What is the projected market size by 2034?
The rebased 2034 General Analog Semiconductor market is approximately USD 115.44 billion. This extends the source page’s 2024–2032 size anchors using the same annual compound factor and provides an internally consistent 2025 base year, 2026 estimate and 2034 endpoint. The purchasing decision therefore connects system performance, supply assurance, lifecycle support and application engineering rather than treating the device as a fully interchangeable commodity.
Why is the CAGR 3.5% instead of the page’s 4.1%?
USD 82.01 billion in 2024 and USD 107.81 billion in 2032 imply approximately 3.48% compound annual growth over eight years. Because the printed 4.1% does not reconcile with the page’s own market-size endpoints, the anchor-derived rate is used throughout this article. Through 2034, suppliers that combine flexible mature-node capacity with differentiated automotive, industrial and AI power products can protect margins while serving several end-market cycles.
Which type leads the market?
The source page identifies Amplifiers as the leading type because operational, audio and RF amplifiers are used across automotive, industrial and consumer systems. The detailed segmentation also includes Data Converters, Interface Semiconductors, Power Management ICs and Others. The market implication is that nominal wafer capacity becomes commercially valuable only when the process, package and test flow are qualified for the exact analog performance and reliability class required by customers.
Which application is the largest?
Automotive is the leading application on the source page. Electric vehicles, ADAS, infotainment and zonal architectures increase battery monitoring, power management, sensor conditioning and interface IC content per vehicle, creating a structurally strong demand pool. For analog semiconductor suppliers, the commercial consequence is that process technology, qualification, design support and long-term manufacturing control determine revenue quality more directly than simple transistor scaling.
Which region dominates the market?
Asia Pacific is the largest region because the source page states it accounts for more than 50% of global analog semiconductor consumption and its FAQ also identifies Asia Pacific as the market leader. China, Japan and South Korea provide large electronics, automotive and industrial-manufacturing bases. This matters because analog devices are selected around real electrical constraints such as noise, voltage, current, isolation and temperature, so switching a qualified component can require substantial system redesign.
How is AI affecting analog semiconductor demand?
AI increases analog demand through power conversion, isolation, current sensing, timing and thermal monitoring around accelerators and servers. STMicroelectronics and Skyworks both highlighted 800 VDC data-center power and AI infrastructure products in 2026, showing that analog content rises alongside digital compute. The purchasing decision therefore connects system performance, supply assurance, lifecycle support and application engineering rather than treating the device as a fully interchangeable commodity.
How important is 300 mm manufacturing?
TI and Infineon are expanding 300 mm foundational semiconductor capacity because larger wafers can reduce cost per die for high-volume analog and mixed-signal products. TI began production at Sherman SM1 in 2025, while Infineon opened its €5 billion Smart Power Fab in Dresden in 2026. Through 2034, suppliers that combine flexible mature-node capacity with differentiated automotive, industrial and AI power products can protect margins while serving several end-market cycles.
Who are the companies profiled in the report?
The source-page manufacturer profiles cover Texas Instruments, Infineon Technologies, Skyworks Solutions, STMicroelectronics, NXP Semiconductors, Qualcomm Technologies and Mixed-Mode Technology. Other analog suppliers may be relevant globally, but they are not added to this formal source-profile list. The market implication is that nominal wafer capacity becomes commercially valuable only when the process, package and test flow are qualified for the exact analog performance and reliability class required by customers.
What is the main strategic risk through 2034?
The main risk is mismatching long-lead manufacturing investment with changing end-market demand. Analog fabs and products serve many cycles simultaneously, so suppliers need flexible capacity, broad portfolios and strong design-in relationships to avoid underutilization while maintaining reliable long-term supply. For analog semiconductor suppliers, the commercial consequence is that process technology, qualification, design support and long-term manufacturing control determine revenue quality more directly than simple transistor scaling.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF