SEMICONDUCTOR INSIGHT
MARKET RESEARCH REPORT

Edge-Wound Inductor Market

2026 to 2034
MARKET INTELLIGENCE
ACROSS KEY REGIONS
2026 EDITION
ELECTRONIC COMPONENTS Semiconductor Market Research

Edge-Wound Inductor Market

Size, Share & Industry Analysis, By Type (Bare Copper, Surface-Mount, Press Fit, Others), By Application (Automotive, Industrial, Medical, Military Appliance, Others), By End User (Electronics Manufacturers, Automotive OEMs, Industrial Equipment Producers, Defense Contractors), By Power Class (Low-Current, Medium-Current, High-Current), and Regional Forecast, 2026-2034

◷
UPDATED 16 October 2026
▤
REPORT LENGTH Detailed Report
▣
REPORT CODE ca62f4b01935
▯
FORMATS PDF

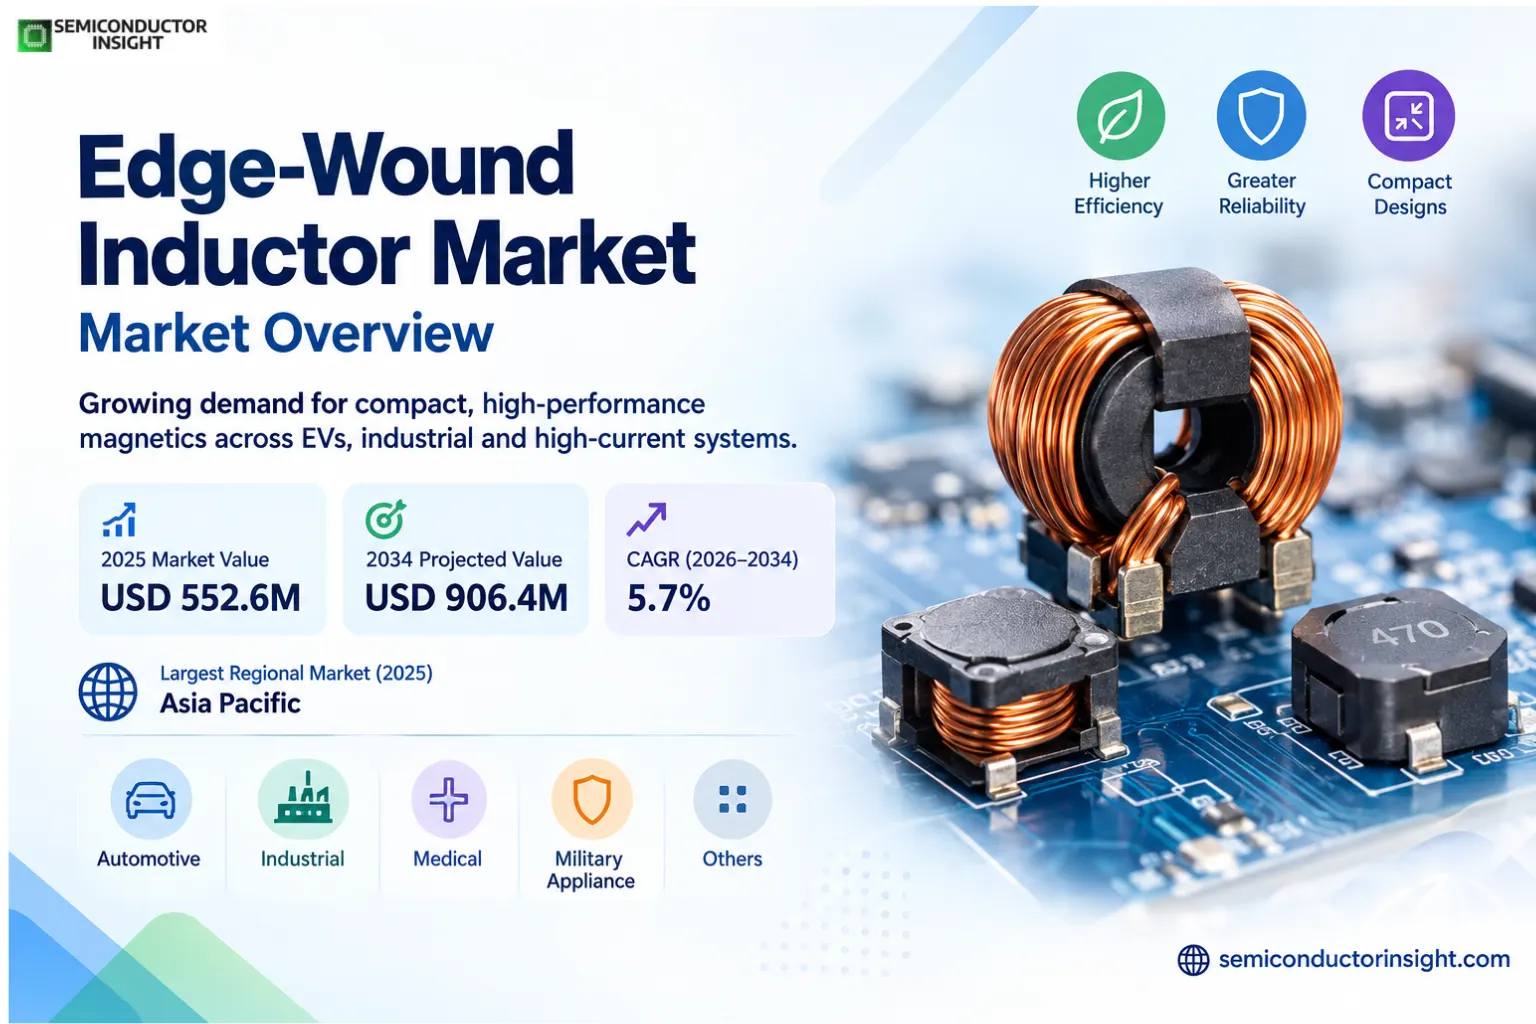
edge-wound inductor market was valued at USD 552.6 million in 2025 and is projected to reach USD 906.4 million by 2034, expanding at a CAGR of 5.7% during 2026–2034. Asia Pacific is the largest regional market in 2025.

Get the sample PDF with study scope, segmentation and methodology details.

Key Statistics

2025 Market Size
USD 552.6 million
2034 Projected Market Size
USD 906.4 million
CAGR (2026–2034)
5.7%
Largest Market in 2025
Asia Pacific

Key Takeaways

  • Market size and growth: USD 552.6 million in 2025, rising to USD 906.4 million by 2034 at a 5.7% CAGR over 2026–2034.
  • Asia Pacific is the largest market in 2025 because the region combines major end-use demand with a dense electronics and semiconductor supply base.
  • Bare Copper is a core product category, while technology migration is increasing the value of higher-performance and application-specific variants.
  • Primary demand driver: Vehicle electrification, industrial power conversion and high-current DC-DC architectures are increasing demand for compact magnetics with low DC resistance and strong thermal performance.
  • Structural restraint: Copper pricing, magnetic material availability and application-specific qualification can lengthen lead times and limit margin flexibility for specialized designs.
  • Growth opportunity: GaN and SiC power stages create opportunities for inductors engineered for higher switching frequencies, lower losses and tighter thermal envelopes.

Edge-Wound Inductor Market Overview

edge-wound inductor market was valued at USD 552.6 million in 2025 and is projected to reach USD 906.4 million by 2034, expanding at a CAGR of 5.7% during 2026–2034. Asia Pacific is the largest regional market in 2025.

Base year: 2025 · Estimated year: 2026 · Forecast period: 2026–2034 · Values in USD million unless stated otherwise

Edge-Wound Inductor is a specialized electronics market in which performance, reliability and system integration determine purchasing decisions. Buyers typically qualify products against electrical, thermal, mechanical and lifecycle requirements before a supplier can enter a production program. This creates meaningful switching costs once a design is approved, while also raising the technical threshold for new suppliers seeking high-volume business.

Vehicle electrification, industrial power conversion and high-current DC-DC architectures are increasing demand for compact magnetics with low DC resistance and strong thermal performance. The commercial effect is a shift from commodity selection toward application-specific products that deliver measurable system benefits. Suppliers that can document reliability, maintain stable lead times and support customer engineering teams are positioned to capture a larger share of recurring design-win revenue.

Manufacturing is distributed across Asia, North America and Europe, with Asia holding the deepest passive-component supply chain and the broadest high-volume electronics assembly base. This geographic concentration matters because supply security now influences sourcing alongside price and performance. OEMs increasingly seek dual sourcing, regional inventory and long-term capacity visibility, especially for components used in high-value systems where a shortage can delay an entire platform launch.

Segment Analysis: By Type

By type, the market includes Bare Copper, Surface-Mount, Press Fit, Others. Product selection depends on the balance between performance, integration complexity, thermal behavior, qualification requirements and cost. The largest revenue pool is concentrated in established architectures, while newer variants generally grow faster when they solve a clear system bottleneck.

Type Commercial role Market position
Bare Copper Defines the main product architecture and purchasing specification. Leading / core segment. Demand depends on performance, qualification, supply continuity and total system economics rather than a single component specification.
Surface-Mount Defines the main product architecture and purchasing specification. High-growth segment. Demand depends on performance, qualification, supply continuity and total system economics rather than a single component specification.
Press Fit Defines the main product architecture and purchasing specification. Established segment. Demand depends on performance, qualification, supply continuity and total system economics rather than a single component specification.
Others Defines the main product architecture and purchasing specification. Established segment. Demand depends on performance, qualification, supply continuity and total system economics rather than a single component specification.

Segment Analysis: By Application

By application, demand spans Automotive, Industrial, Medical, Military Appliance, Others. Purchasing behavior differs materially across these applications because system reliability, operating environment, qualification duration and replacement cost vary. High-value applications favor suppliers with deeper engineering support, while consumer and high-volume applications place greater weight on unit economics and manufacturing scale.

Application Purchasing trigger Demand characteristics
Automotive Links demand to system-level performance and qualification requirements. Leading / core segment. Demand depends on performance, qualification, supply continuity and total system economics rather than a single component specification.
Industrial Links demand to system-level performance and qualification requirements. High-growth segment. Demand depends on performance, qualification, supply continuity and total system economics rather than a single component specification.
Medical Links demand to system-level performance and qualification requirements. Established segment. Demand depends on performance, qualification, supply continuity and total system economics rather than a single component specification.
Military Appliance Links demand to system-level performance and qualification requirements. Established segment. Demand depends on performance, qualification, supply continuity and total system economics rather than a single component specification.
Others Links demand to system-level performance and qualification requirements. Established segment. Demand depends on performance, qualification, supply continuity and total system economics rather than a single component specification.

By End User

End User Market relevance
Electronics Manufacturers Relevant to product selection, qualification and supplier differentiation.
Automotive OEMs Relevant to product selection, qualification and supplier differentiation.
Industrial Equipment Producers Relevant to product selection, qualification and supplier differentiation.
Defense Contractors Relevant to product selection, qualification and supplier differentiation.

By Power Class

Power Class Market relevance
Low-Current Creates a distinct design, performance or procurement requirement within the market.
Medium-Current Creates a distinct design, performance or procurement requirement within the market.
High-Current Creates a distinct design, performance or procurement requirement within the market.

Edge-Wound Inductor Market Size & Share

Regional Analysis

Asia Pacific leads the edge-wound inductor market in 2025. Regional demand differs by manufacturing concentration, end-use investment, qualification requirements and access to local supply chains. The strongest opportunities are therefore not identical across regions, even where the same product family is used.

How does regional demand differ across the market?

Regional competition is shaped by where products are designed, where they are manufactured and where the final systems are deployed. Asia Pacific benefits from electronics and semiconductor manufacturing density, North America concentrates advanced system design and cloud or defense demand, while Europe remains important in automotive, industrial and regulation-led applications. South America and the Middle East & Africa are smaller but can generate attractive project-led demand.

Region Position Growth outlook Demand profile
Asia Pacific Largest High Largest production and consumption base, supported by China, Japan, South Korea and Southeast Asian electronics manufacturing.
North America Established High Demand is weighted toward automotive power electronics, defense, medical systems and industrial equipment.
Europe Established Moderate Automotive electrification and industrial drives support demand, with stringent qualification requirements.
South America Established Moderate Demand remains import-led and focused on automotive assembly and industrial power systems.
Middle East & Africa Established Moderate Project demand is concentrated in energy infrastructure, telecom equipment and industrial control.
Asia Pacific LARGEST

What defines demand in Asia Pacific?

Largest production and consumption base, supported by China, Japan, South Korea and Southeast Asian electronics manufacturing.

Market positionLargest
Demand profileApplication-led
Supplier priorityQualification & supply
Commercial gateDesign-in access
Country Demand characteristics
China China participates through a mix of local electronics demand, imported components, system integration and sector-specific investment. Supplier success depends on application qualification, access to major OEM programs and reliable regional distribution rather than headline market size alone.
Japan Japan participates through a mix of local electronics demand, imported components, system integration and sector-specific investment. Supplier success depends on application qualification, access to major OEM programs and reliable regional distribution rather than headline market size alone.
South Korea South Korea participates through a mix of local electronics demand, imported components, system integration and sector-specific investment. Supplier success depends on application qualification, access to major OEM programs and reliable regional distribution rather than headline market size alone.

The full report expands this regional view with country-level demand, supplier presence, application mix, qualification requirements and market-entry considerations. The regional opportunity is therefore assessed through actual production ecosystems and end-use programs rather than by repeating a single global statistic across countries.

North America ESTABLISHED

What defines demand in North America?

Demand is weighted toward automotive power electronics, defense, medical systems and industrial equipment.

Market positionEstablished
Demand profileApplication-led
Supplier priorityQualification & supply
Commercial gateDesign-in access
Country Demand characteristics
United States United States participates through a mix of local electronics demand, imported components, system integration and sector-specific investment. Supplier success depends on application qualification, access to major OEM programs and reliable regional distribution rather than headline market size alone.
Canada Canada participates through a mix of local electronics demand, imported components, system integration and sector-specific investment. Supplier success depends on application qualification, access to major OEM programs and reliable regional distribution rather than headline market size alone.
Mexico Mexico participates through a mix of local electronics demand, imported components, system integration and sector-specific investment. Supplier success depends on application qualification, access to major OEM programs and reliable regional distribution rather than headline market size alone.

The full report expands this regional view with country-level demand, supplier presence, application mix, qualification requirements and market-entry considerations. The regional opportunity is therefore assessed through actual production ecosystems and end-use programs rather than by repeating a single global statistic across countries.

Europe ESTABLISHED

What defines demand in Europe?

Automotive electrification and industrial drives support demand, with stringent qualification requirements.

Market positionEstablished
Demand profileApplication-led
Supplier priorityQualification & supply
Commercial gateDesign-in access
Country Demand characteristics
Germany Germany participates through a mix of local electronics demand, imported components, system integration and sector-specific investment. Supplier success depends on application qualification, access to major OEM programs and reliable regional distribution rather than headline market size alone.
United Kingdom United Kingdom participates through a mix of local electronics demand, imported components, system integration and sector-specific investment. Supplier success depends on application qualification, access to major OEM programs and reliable regional distribution rather than headline market size alone.
France France participates through a mix of local electronics demand, imported components, system integration and sector-specific investment. Supplier success depends on application qualification, access to major OEM programs and reliable regional distribution rather than headline market size alone.

The full report expands this regional view with country-level demand, supplier presence, application mix, qualification requirements and market-entry considerations. The regional opportunity is therefore assessed through actual production ecosystems and end-use programs rather than by repeating a single global statistic across countries.

South America ESTABLISHED

What defines demand in South America?

Demand remains import-led and focused on automotive assembly and industrial power systems.

Market positionEstablished
Demand profileApplication-led
Supplier priorityQualification & supply
Commercial gateDesign-in access
Country Demand characteristics
Brazil Brazil participates through a mix of local electronics demand, imported components, system integration and sector-specific investment. Supplier success depends on application qualification, access to major OEM programs and reliable regional distribution rather than headline market size alone.
Argentina Argentina participates through a mix of local electronics demand, imported components, system integration and sector-specific investment. Supplier success depends on application qualification, access to major OEM programs and reliable regional distribution rather than headline market size alone.
Chile Chile participates through a mix of local electronics demand, imported components, system integration and sector-specific investment. Supplier success depends on application qualification, access to major OEM programs and reliable regional distribution rather than headline market size alone.

The full report expands this regional view with country-level demand, supplier presence, application mix, qualification requirements and market-entry considerations. The regional opportunity is therefore assessed through actual production ecosystems and end-use programs rather than by repeating a single global statistic across countries.

Middle East & Africa ESTABLISHED

What defines demand in Middle East & Africa?

Project demand is concentrated in energy infrastructure, telecom equipment and industrial control.

Market positionEstablished
Demand profileApplication-led
Supplier priorityQualification & supply
Commercial gateDesign-in access
Country Demand characteristics
Saudi Arabia Saudi Arabia participates through a mix of local electronics demand, imported components, system integration and sector-specific investment. Supplier success depends on application qualification, access to major OEM programs and reliable regional distribution rather than headline market size alone.
United Arab Emirates United Arab Emirates participates through a mix of local electronics demand, imported components, system integration and sector-specific investment. Supplier success depends on application qualification, access to major OEM programs and reliable regional distribution rather than headline market size alone.
South Africa South Africa participates through a mix of local electronics demand, imported components, system integration and sector-specific investment. Supplier success depends on application qualification, access to major OEM programs and reliable regional distribution rather than headline market size alone.

The full report expands this regional view with country-level demand, supplier presence, application mix, qualification requirements and market-entry considerations. The regional opportunity is therefore assessed through actual production ecosystems and end-use programs rather than by repeating a single global statistic across countries.

Competitive Landscape

Competition is driven by technical qualification, customer access, manufacturing consistency and the ability to support product transitions. Market leaders generally combine proprietary process knowledge with broad application engineering, while specialist suppliers compete through narrower performance advantages, customization or regional service.

The competitive structure rewards suppliers that can convert R&D into qualified production rather than simply demonstrating laboratory performance. Long customer qualification cycles protect incumbents once designed in, but they also create opportunities during architecture changes when OEMs reconsider vendors, package formats and performance targets.

Supply reliability has become a central differentiator. Customers increasingly evaluate capacity commitments, geographic resilience, quality systems and lifecycle support in parallel with electrical specifications. This favors companies able to coordinate manufacturing, test, logistics and engineering support across multiple regions.

Company Position Competitive focus
Vishay Intertechnology Established participant Competes through technology, qualification, portfolio breadth and customer relationships.
MPS Industries Established participant Competes through technology, qualification, portfolio breadth and customer relationships.
TDK Established participant Competes through technology, qualification, portfolio breadth and customer relationships.
Murata Manufacturing Established participant Competes through technology, qualification, portfolio breadth and customer relationships.
Taiyo Yuden Established participant Competes through technology, qualification, portfolio breadth and customer relationships.
Coilcraft Established participant Competes through technology, qualification, portfolio breadth and customer relationships.
Bourns Established participant Competes through technology, qualification, portfolio breadth and customer relationships.

Production Capacity Analysis

Manufacturing is distributed across Asia, North America and Europe, with Asia holding the deepest passive-component supply chain and the broadest high-volume electronics assembly base.

Capacity expansion is not determined by floor space alone. Yield learning, specialty equipment, trained personnel, material quality and customer qualification can all delay effective output after new equipment is installed. For this reason, announced capacity and immediately usable market supply can diverge, especially in advanced products with tight process windows.

Market Dynamics

The market is shaped by a combination of end-system performance requirements, technology migration, supply-chain resilience and cost pressure. Growth is strongest where the component removes a system bottleneck or enables a new architecture, while adoption slows when qualification complexity or alternative technologies reduce the economic advantage.

Vehicle electrification, industrial power conversion and high-current DC-DC architectures are increasing demand for compact magnetics with low DC resistance and strong thermal performance. At the same time, copper pricing, magnetic material availability and application-specific qualification can lengthen lead times and limit margin flexibility for specialized designs. Suppliers therefore need to balance innovation with manufacturability, reliability and commercial discipline.

Market Drivers

Drivers Impact Analysis

Driver Impact Commercial implication
System performance High Directly increases component content or value per system.
Technology migration High Creates replacement and redesign opportunities.
Supply resilience Medium Favors qualified vendors with stable capacity.

System-level performance requirements

Vehicle electrification, industrial power conversion and high-current DC-DC architectures are increasing demand for compact magnetics with low DC resistance and strong thermal performance. This directly affects vendor selection because component-level specifications increasingly translate into measurable platform performance, energy efficiency, thermal headroom or reliability. Products that create a clear system benefit can sustain better pricing and deeper customer engagement.

Design complexity and integration

As electronic systems become more integrated, component suppliers are expected to provide reference designs, simulation support, qualification data and predictable lifecycle management. This broadens competition beyond unit price and favors vendors that can reduce engineering time for OEMs while maintaining stable production quality.

Electrification and digitalization

The continued shift toward connected, electrified and software-defined systems increases the number and value of electronics used in vehicles, industrial equipment, data centers and consumer devices. This expands the addressable opportunity for suppliers whose products improve power efficiency, signal integrity, memory bandwidth, durability or user experience.

Regional supply-chain investment

Governments and manufacturers are investing in more resilient electronics and semiconductor supply chains. Even where these programs do not directly subsidize the market, they influence localization, inventory strategy and supplier qualification, creating opportunities for vendors with manufacturing or engineering support close to major customers.

Market Restraints

Restraints Impact Analysis

Restraint Impact Commercial implication
Qualification burden High Lengthens time to revenue and raises engineering cost.
Input cost volatility Medium Compresses margins when contracts limit price changes.
Alternative technologies Medium Can reduce content per system in selected applications.

Qualification and integration cost

Copper pricing, magnetic material availability and application-specific qualification can lengthen lead times and limit margin flexibility for specialized designs. These barriers slow supplier switching and can delay commercialization, particularly when products enter safety-critical, high-reliability or high-volume platforms. Smaller suppliers may have strong technology but still face long sales cycles before meaningful production revenue begins.

Cost pressure and substitution

OEMs continue to reduce bill-of-material cost and consolidate functions into more integrated devices. Suppliers must therefore show that the component provides a measurable system advantage. Where that advantage is weak, buyers may substitute lower-cost alternatives or redesign the function into another subsystem.

Market Opportunities

Next-generation architectures

GaN and SiC power stages create opportunities for inductors engineered for higher switching frequencies, lower losses and tighter thermal envelopes. Vendors that engage early with platform designers can shape specifications, improve design-win probability and secure longer revenue lifecycles once the architecture moves into production.

Application-specific products

Specialized products for automotive, industrial, AI, medical or aerospace systems can command stronger margins because qualification requirements are tighter and failure costs are higher. The commercial opportunity is strongest where suppliers combine product performance with documentation, traceability and long-term availability.

Regional localization

Customers are diversifying sourcing and building more regional resilience into electronics supply chains. Local technical support, shorter logistics routes and qualified second-source options can therefore become competitive advantages even when manufacturing economics still favor a concentrated global production base.

Lifecycle services

Engineering support, failure analysis, reliability data and product-change management create service-based differentiation around the physical component. These capabilities strengthen customer retention and can reduce the risk of substitution when a market moves through technology transitions or periods of constrained supply.

Supply Chain Analysis

Stage Value creation and bottlenecks
Raw materials / upstream Purity, consistency, specialty materials and process inputs determine yield and performance.
Component manufacturing Value is created through process control, device architecture, testing and product-specific qualification.
Packaging / integration System integration determines thermal performance, reliability, footprint and manufacturability.
OEM / end user Design wins, lifecycle support and supply assurance determine recurring revenue and replacement demand.

The upstream stage determines material consistency and the starting cost structure. Manufacturing then converts process control into yield and product performance, while packaging or integration determines whether the component can meet system-level thermal, mechanical and electrical requirements. The OEM stage captures value through design ownership, platform integration and end-market access. Bottlenecks at any stage can affect the whole chain because qualification limits rapid supplier substitution.

Recent Developments

2025-07-01 — TDK expanded its automotive thin-film power inductor range to higher current ratings and lower DC resistance, highlighting the pressure for efficient vehicle power conversion. Source
2025-02-13 — TDK launched new wire-wound inductors for automotive power-over-coax applications with high-current capability and a -55 °C to +155 °C operating range. Source
2024-02-27 — TDK introduced a new automotive high-frequency inductor series designed for high reliability and operation up to +125 °C. Source

Report Scope & Segmentation

Attribute Coverage
Market definition Edge-Wound Inductor products and systems covered by the stated segmentation.
Base year 2025
Estimated year 2026
Forecast period 2026–2034
By Type Bare Copper, Surface-Mount, Press Fit, Others
By Application Automotive, Industrial, Medical, Military Appliance, Others
By End User Electronics Manufacturers, Automotive OEMs, Industrial Equipment Producers, Defense Contractors
By Power Class Low-Current, Medium-Current, High-Current
Regions North America, Europe, Asia Pacific, South America, Middle East & Africa
Companies Vishay Intertechnology, MPS Industries, TDK, Murata Manufacturing, Taiyo Yuden, Coilcraft, Bourns

Frequently Asked Questions

What is the Edge-Wound Inductor market size in 2025?

The market is valued at USD 552.6 million in 2025.

What is the projected Edge-Wound Inductor market size by 2034?

The market is projected to reach USD 906.4 million by 2034.

What is the CAGR of the Edge-Wound Inductor market from 2026 to 2034?

The market is expected to expand at a CAGR of 5.7% over 2026–2034.

Which region leads the Edge-Wound Inductor market?

Asia Pacific is the largest market in 2025.

What are the main product types?

The main types are Bare Copper, Surface-Mount, Press Fit, Others.

What are the key applications?

Key applications include Automotive, Industrial, Medical, Military Appliance, Others.

What is the main growth driver?

Vehicle electrification, industrial power conversion and high-current DC-DC architectures are increasing demand for compact magnetics with low DC resistance and strong thermal performance.

What is the main restraint?

Copper pricing, magnetic material availability and application-specific qualification can lengthen lead times and limit margin flexibility for specialized designs.

Where are the strongest opportunities?

GaN and SiC power stages create opportunities for inductors engineered for higher switching frequencies, lower losses and tighter thermal envelopes.

Which companies are active in the market?

Key participants include Vishay Intertechnology, MPS Industries, TDK, Murata Manufacturing, Taiyo Yuden, Coilcraft.

Research Sources & Evidence Base

View primary and official sources used in this overview
  1. TDK: Automotive thin-film power inductor expansion.
  2. TDK: Automotive wire-wound inductor launch.
  3. TDK: Automotive high-frequency inductor series.
Edge-Wound Inductor Market Size, Share & Industry Analysis, By Type (Bare Copper, Surface-Mount, Press Fit, Others), By Application (Automotive, Industrial, Medical, Military Appliance, Others), By End User (Electronics Manufacturers, Automotive OEMs, Industrial Equipment Producers, Defense Contractors), By Power Class (Low-Current, Medium-Current, High-Current), and Regional Forecast, 2026-2034

Get Sample Report PDF for Exclusive Insights

Report Sample Includes

  • Table of Contents
  • List of Tables & Figures
  • Charts, Research Methodology, and more...

PDF Icon Download Sample Report PDF

Download Sample Report

Table of Content

1 Introduction to Research & Analysis Reports
1.1 Edge-Wound Inductor Market Definition
1.2 Market Segments
1.2.1 Segment by Type
1.2.2 Segment by Application
1.3 Global Edge-Wound Inductor Market Overview
1.4 Features & Benefits of This Report
1.5 Methodology & Sources of Information
1.5.1 Research Methodology
1.5.2 Research Process
1.5.3 Base Year
1.5.4 Report Assumptions & Caveats
2 Global Edge-Wound Inductor Overall Market Size
2.1 Global Edge-Wound Inductor Market Size: 2024 VS 2032
2.2 Global Edge-Wound Inductor Market Size, Prospects & Forecasts: 2026-2034
2.3 Global Edge-Wound Inductor Sales: 2026-2034
3 Company Landscape
3.1 Top Edge-Wound Inductor Players in Global Market
3.2 Top Global Edge-Wound Inductor Companies Ranked by Revenue
3.3 Global Edge-Wound Inductor Revenue by Companies
3.4 Global Edge-Wound Inductor Sales by Companies
3.5 Global Edge-Wound Inductor Price by Manufacturer (2020-2025)
3.6 Top 3 and Top 5 Edge-Wound Inductor Companies in Global Market, by Revenue in 2024
3.7 Global Manufacturers Edge-Wound Inductor Product Type
3.8 Tier 1, Tier 2, and Tier 3 Edge-Wound Inductor Players in Global Market
3.8.1 List of Global Tier 1 Edge-Wound Inductor Companies
3.8.2 List of Global Tier 2 and Tier 3 Edge-Wound Inductor Companies
4 Sights by Product
4.1 Overview
4.1.1 Segment by Type – Global Edge-Wound Inductor Market Size Markets, 2024 & 2032
4.1.2 Bare Copper
4.1.3 Surface-mount
4.1.4 Press Fit
4.2 Segment by Type – Global Edge-Wound Inductor Revenue & Forecasts
4.2.1 Segment by Type – Global Edge-Wound Inductor Revenue, 2020-2025
4.2.2 Segment by Type – Global Edge-Wound Inductor Revenue, 2026-2032
4.2.3 Segment by Type – Global Edge-Wound Inductor Revenue Market Share, 2026-2034
4.3 Segment by Type – Global Edge-Wound Inductor Sales & Forecasts
4.3.1 Segment by Type – Global Edge-Wound Inductor Sales, 2020-2025
4.3.2 Segment by Type – Global Edge-Wound Inductor Sales, 2026-2032
4.3.3 Segment by Type – Global Edge-Wound Inductor Sales Market Share, 2026-2034
4.4 Segment by Type – Global Edge-Wound Inductor Price (Manufacturers Selling Prices), 2026-2034
5 Sights by Application
5.1 Overview
5.1.1 Segment by Application – Global Edge-Wound Inductor Market Size, 2024 & 2032
5.1.2 Automotive
5.1.3 Industrial
5.1.4 Business
5.1.5 Medical
5.1.6 Military Appliance
5.1.7 Other
5.2 Segment by Application – Global Edge-Wound Inductor Revenue & Forecasts
5.2.1 Segment by Application – Global Edge-Wound Inductor Revenue, 2020-2025
5.2.2 Segment by Application – Global Edge-Wound Inductor Revenue, 2026-2032
5.2.3 Segment by Application – Global Edge-Wound Inductor Revenue Market Share, 2026-2034
5.3 Segment by Application – Global Edge-Wound Inductor Sales & Forecasts
5.3.1 Segment by Application – Global Edge-Wound Inductor Sales, 2020-2025
5.3.2 Segment by Application – Global Edge-Wound Inductor Sales, 2026-2032
5.3.3 Segment by Application – Global Edge-Wound Inductor Sales Market Share, 2026-2034
5.4 Segment by Application – Global Edge-Wound Inductor Price (Manufacturers Selling Prices), 2026-2034
6 Sights by Region
6.1 By Region – Global Edge-Wound Inductor Market Size, 2024 & 2032
6.2 By Region – Global Edge-Wound Inductor Revenue & Forecasts
6.2.1 By Region – Global Edge-Wound Inductor Revenue, 2020-2025
6.2.2 By Region – Global Edge-Wound Inductor Revenue, 2026-2032
6.2.3 By Region – Global Edge-Wound Inductor Revenue Market Share, 2026-2034
6.3 By Region – Global Edge-Wound Inductor Sales & Forecasts
6.3.1 By Region – Global Edge-Wound Inductor Sales, 2020-2025
6.3.2 By Region – Global Edge-Wound Inductor Sales, 2026-2032
6.3.3 By Region – Global Edge-Wound Inductor Sales Market Share, 2026-2034
6.4 North America
6.4.1 By Country – North America Edge-Wound Inductor Revenue, 2026-2034
6.4.2 By Country – North America Edge-Wound Inductor Sales, 2026-2034
6.4.3 United States Edge-Wound Inductor Market Size, 2026-2034
6.4.4 Canada Edge-Wound Inductor Market Size, 2026-2034
6.4.5 Mexico Edge-Wound Inductor Market Size, 2026-2034
6.5 Europe
6.5.1 By Country – Europe Edge-Wound Inductor Revenue, 2026-2034
6.5.2 By Country – Europe Edge-Wound Inductor Sales, 2026-2034
6.5.3 Germany Edge-Wound Inductor Market Size, 2026-2034
6.5.4 France Edge-Wound Inductor Market Size, 2026-2034
6.5.5 U.K. Edge-Wound Inductor Market Size, 2026-2034
6.5.6 Italy Edge-Wound Inductor Market Size, 2026-2034
6.5.7 Russia Edge-Wound Inductor Market Size, 2026-2034
6.5.8 Nordic Countries Edge-Wound Inductor Market Size, 2026-2034
6.5.9 Benelux Edge-Wound Inductor Market Size, 2026-2034
6.6 Asia
6.6.1 By Region – Asia Edge-Wound Inductor Revenue, 2026-2034
6.6.2 By Region – Asia Edge-Wound Inductor Sales, 2026-2034
6.6.3 China Edge-Wound Inductor Market Size, 2026-2034
6.6.4 Japan Edge-Wound Inductor Market Size, 2026-2034
6.6.5 South Korea Edge-Wound Inductor Market Size, 2026-2034
6.6.6 Southeast Asia Edge-Wound Inductor Market Size, 2026-2034
6.6.7 India Edge-Wound Inductor Market Size, 2026-2034
6.7 South America
6.7.1 By Country – South America Edge-Wound Inductor Revenue, 2026-2034
6.7.2 By Country – South America Edge-Wound Inductor Sales, 2026-2034
6.7.3 Brazil Edge-Wound Inductor Market Size, 2026-2034
6.7.4 Argentina Edge-Wound Inductor Market Size, 2026-2034
6.8 Middle East & Africa
6.8.1 By Country – Middle East & Africa Edge-Wound Inductor Revenue, 2026-2034
6.8.2 By Country – Middle East & Africa Edge-Wound Inductor Sales, 2026-2034
6.8.3 Turkey Edge-Wound Inductor Market Size, 2026-2034
6.8.4 Israel Edge-Wound Inductor Market Size, 2026-2034
6.8.5 Saudi Arabia Edge-Wound Inductor Market Size, 2026-2034
6.8.6 UAE Edge-Wound Inductor Market Size, 2026-2034
7 Manufacturers & Brands Profiles
7.1 Vishay Intertechnology
7.1.1 Vishay Intertechnology Company Summary
7.1.2 Vishay Intertechnology Business Overview
7.1.3 Vishay Intertechnology Edge-Wound Inductor Major Product Offerings
7.1.4 Vishay Intertechnology Edge-Wound Inductor Sales and Revenue in Global (2020-2025)
7.1.5 Vishay Intertechnology Key News & Latest Developments
7.2 MPS Industries, Inc
7.2.1 MPS Industries, Inc Company Summary
7.2.2 MPS Industries, Inc Business Overview
7.2.3 MPS Industries, Inc Edge-Wound Inductor Major Product Offerings
7.2.4 MPS Industries, Inc Edge-Wound Inductor Sales and Revenue in Global (2020-2025)
7.2.5 MPS Industries, Inc Key News & Latest Developments
7.3 EF Johnson Technologies, Inc
7.3.1 EF Johnson Technologies, Inc Company Summary
7.3.2 EF Johnson Technologies, Inc Business Overview
7.3.3 EF Johnson Technologies, Inc Edge-Wound Inductor Major Product Offerings
7.3.4 EF Johnson Technologies, Inc Edge-Wound Inductor Sales and Revenue in Global (2020-2025)
7.3.5 EF Johnson Technologies, Inc Key News & Latest Developments
8 Global Edge-Wound Inductor Production Capacity, Analysis
8.1 Global Edge-Wound Inductor Production Capacity, 2026-2034
8.2 Edge-Wound Inductor Production Capacity of Key Manufacturers in Global Market
8.3 Global Edge-Wound Inductor Production by Region
9 Key Market Trends, Opportunity, Drivers and Restraints
9.1 Market Opportunities & Trends
9.2 Market Drivers
9.3 Market Restraints
10 Edge-Wound Inductor Supply Chain Analysis
10.1 Edge-Wound Inductor Industry Value Chain
10.2 Edge-Wound Inductor Upstream Market
10.3 Edge-Wound Inductor Downstream and Clients
10.4 Marketing Channels Analysis
10.4.1 Marketing Channels
10.4.2 Edge-Wound Inductor Distributors and Sales Agents in Global
11 Conclusion
12 Appendix
12.1 Note
12.2 Examples of Clients
12.3 DisclaimerList of Tables
Table 1. Key Players of Edge-Wound Inductor in Global Market
Table 2. Top Edge-Wound Inductor Players in Global Market, Ranking by Revenue (2024)
Table 3. Global Edge-Wound Inductor Revenue by Companies, (US$, Mn), 2020-2025
Table 4. Global Edge-Wound Inductor Revenue Share by Companies, 2020-2025
Table 5. Global Edge-Wound Inductor Sales by Companies, (K Units), 2020-2025
Table 6. Global Edge-Wound Inductor Sales Share by Companies, 2020-2025
Table 7. Key Manufacturers Edge-Wound Inductor Price (2020-2025) & (US$/Unit)
Table 8. Global Manufacturers Edge-Wound Inductor Product Type
Table 9. List of Global Tier 1 Edge-Wound Inductor Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 10. List of Global Tier 2 and Tier 3 Edge-Wound Inductor Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 11. Segment by Type – Global Edge-Wound Inductor Revenue, (US$, Mn), 2024 & 2032
Table 12. Segment by Type – Global Edge-Wound Inductor Revenue (US$, Mn), 2020-2025
Table 13. Segment by Type – Global Edge-Wound Inductor Revenue (US$, Mn), 2026-2032
Table 14. Segment by Type – Global Edge-Wound Inductor Sales (K Units), 2020-2025
Table 15. Segment by Type – Global Edge-Wound Inductor Sales (K Units), 2026-2032
Table 16. Segment by Application – Global Edge-Wound Inductor Revenue, (US$, Mn), 2024 & 2032
Table 17. Segment by Application – Global Edge-Wound Inductor Revenue, (US$, Mn), 2020-2025
Table 18. Segment by Application – Global Edge-Wound Inductor Revenue, (US$, Mn), 2026-2032
Table 19. Segment by Application – Global Edge-Wound Inductor Sales, (K Units), 2020-2025
Table 20. Segment by Application – Global Edge-Wound Inductor Sales, (K Units), 2026-2032
Table 21. By Region – Global Edge-Wound Inductor Revenue, (US$, Mn), 2025-2032
Table 22. By Region – Global Edge-Wound Inductor Revenue, (US$, Mn), 2020-2025
Table 23. By Region – Global Edge-Wound Inductor Revenue, (US$, Mn), 2026-2032
Table 24. By Region – Global Edge-Wound Inductor Sales, (K Units), 2020-2025
Table 25. By Region – Global Edge-Wound Inductor Sales, (K Units), 2026-2032
Table 26. By Country – North America Edge-Wound Inductor Revenue, (US$, Mn), 2020-2025
Table 27. By Country – North America Edge-Wound Inductor Revenue, (US$, Mn), 2026-2032
Table 28. By Country – North America Edge-Wound Inductor Sales, (K Units), 2020-2025
Table 29. By Country – North America Edge-Wound Inductor Sales, (K Units), 2026-2032
Table 30. By Country – Europe Edge-Wound Inductor Revenue, (US$, Mn), 2020-2025
Table 31. By Country – Europe Edge-Wound Inductor Revenue, (US$, Mn), 2026-2032
Table 32. By Country – Europe Edge-Wound Inductor Sales, (K Units), 2020-2025
Table 33. By Country – Europe Edge-Wound Inductor Sales, (K Units), 2026-2032
Table 34. By Region – Asia Edge-Wound Inductor Revenue, (US$, Mn), 2020-2025
Table 35. By Region – Asia Edge-Wound Inductor Revenue, (US$, Mn), 2026-2032
Table 36. By Region – Asia Edge-Wound Inductor Sales, (K Units), 2020-2025
Table 37. By Region – Asia Edge-Wound Inductor Sales, (K Units), 2026-2032
Table 38. By Country – South America Edge-Wound Inductor Revenue, (US$, Mn), 2020-2025
Table 39. By Country – South America Edge-Wound Inductor Revenue, (US$, Mn), 2026-2032
Table 40. By Country – South America Edge-Wound Inductor Sales, (K Units), 2020-2025
Table 41. By Country – South America Edge-Wound Inductor Sales, (K Units), 2026-2032
Table 42. By Country – Middle East & Africa Edge-Wound Inductor Revenue, (US$, Mn), 2020-2025
Table 43. By Country – Middle East & Africa Edge-Wound Inductor Revenue, (US$, Mn), 2026-2032
Table 44. By Country – Middle East & Africa Edge-Wound Inductor Sales, (K Units), 2020-2025
Table 45. By Country – Middle East & Africa Edge-Wound Inductor Sales, (K Units), 2026-2032
Table 46. Vishay Intertechnology Company Summary
Table 47. Vishay Intertechnology Edge-Wound Inductor Product Offerings
Table 48. Vishay Intertechnology Edge-Wound Inductor Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 49. Vishay Intertechnology Key News & Latest Developments
Table 50. MPS Industries, Inc Company Summary
Table 51. MPS Industries, Inc Edge-Wound Inductor Product Offerings
Table 52. MPS Industries, Inc Edge-Wound Inductor Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 53. MPS Industries, Inc Key News & Latest Developments
Table 54. EF Johnson Technologies, Inc Company Summary
Table 55. EF Johnson Technologies, Inc Edge-Wound Inductor Product Offerings
Table 56. EF Johnson Technologies, Inc Edge-Wound Inductor Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 57. EF Johnson Technologies, Inc Key News & Latest Developments
Table 58. Edge-Wound Inductor Capacity of Key Manufacturers in Global Market, 2023-2025 (K Units)
Table 59. Global Edge-Wound Inductor Capacity Market Share of Key Manufacturers, 2023-2025
Table 60. Global Edge-Wound Inductor Production by Region, 2020-2025 (K Units)
Table 61. Global Edge-Wound Inductor Production by Region, 2026-2032 (K Units)
Table 62. Edge-Wound Inductor Market Opportunities & Trends in Global Market
Table 63. Edge-Wound Inductor Market Drivers in Global Market
Table 64. Edge-Wound Inductor Market Restraints in Global Market
Table 65. Edge-Wound Inductor Raw Materials
Table 66. Edge-Wound Inductor Raw Materials Suppliers in Global Market
Table 67. Typical Edge-Wound Inductor Downstream
Table 68. Edge-Wound Inductor Downstream Clients in Global Market
Table 69. Edge-Wound Inductor Distributors and Sales Agents in Global Market

List of Figures
Figure 1. Edge-Wound Inductor Product Picture
Figure 2. Edge-Wound Inductor Segment by Type in 2024
Figure 3. Edge-Wound Inductor Segment by Application in 2024
Figure 4. Global Edge-Wound Inductor Market Overview: 2024
Figure 5. Key Caveats
Figure 6. Global Edge-Wound Inductor Market Size: 2024 VS 2032 (US$, Mn)
Figure 7. Global Edge-Wound Inductor Revenue: 2026-2034 (US$, Mn)
Figure 8. Edge-Wound Inductor Sales in Global Market: 2026-2034 (K Units)
Figure 9. The Top 3 and 5 Players Market Share by Edge-Wound Inductor Revenue in 2024
Figure 10. Segment by Type – Global Edge-Wound Inductor Revenue, (US$, Mn), 2024 & 2032
Figure 11. Segment by Type – Global Edge-Wound Inductor Revenue Market Share, 2026-2034
Figure 12. Segment by Type – Global Edge-Wound Inductor Sales Market Share, 2026-2034
Figure 13. Segment by Type – Global Edge-Wound Inductor Price (US$/Unit), 2026-2034
Figure 14. Segment by Application – Global Edge-Wound Inductor Revenue, (US$, Mn), 2024 & 2032
Figure 15. Segment by Application – Global Edge-Wound Inductor Revenue Market Share, 2026-2034
Figure 16. Segment by Application – Global Edge-Wound Inductor Sales Market Share, 2026-2034
Figure 17. Segment by Application -Global Edge-Wound Inductor Price (US$/Unit), 2026-2034
Figure 18. By Region – Global Edge-Wound Inductor Revenue, (US$, Mn), 2025 & 2032
Figure 19. By Region – Global Edge-Wound Inductor Revenue Market Share, 2020 VS 2024 VS 2032
Figure 20. By Region – Global Edge-Wound Inductor Revenue Market Share, 2026-2034
Figure 21. By Region – Global Edge-Wound Inductor Sales Market Share, 2026-2034
Figure 22. By Country – North America Edge-Wound Inductor Revenue Market Share, 2026-2034
Figure 23. By Country – North America Edge-Wound Inductor Sales Market Share, 2026-2034
Figure 24. United States Edge-Wound Inductor Revenue, (US$, Mn), 2026-2034
Figure 25. Canada Edge-Wound Inductor Revenue, (US$, Mn), 2026-2034
Figure 26. Mexico Edge-Wound Inductor Revenue, (US$, Mn), 2026-2034
Figure 27. By Country – Europe Edge-Wound Inductor Revenue Market Share, 2026-2034
Figure 28. By Country – Europe Edge-Wound Inductor Sales Market Share, 2026-2034
Figure 29. Germany Edge-Wound Inductor Revenue, (US$, Mn), 2026-2034
Figure 30. France Edge-Wound Inductor Revenue, (US$, Mn), 2026-2034
Figure 31. U.K. Edge-Wound Inductor Revenue, (US$, Mn), 2026-2034
Figure 32. Italy Edge-Wound Inductor Revenue, (US$, Mn), 2026-2034
Figure 33. Russia Edge-Wound Inductor Revenue, (US$, Mn), 2026-2034
Figure 34. Nordic Countries Edge-Wound Inductor Revenue, (US$, Mn), 2026-2034
Figure 35. Benelux Edge-Wound Inductor Revenue, (US$, Mn), 2026-2034
Figure 36. By Region – Asia Edge-Wound Inductor Revenue Market Share, 2026-2034
Figure 37. By Region – Asia Edge-Wound Inductor Sales Market Share, 2026-2034
Figure 38. China Edge-Wound Inductor Revenue, (US$, Mn), 2026-2034
Figure 39. Japan Edge-Wound Inductor Revenue, (US$, Mn), 2026-2034
Figure 40. South Korea Edge-Wound Inductor Revenue, (US$, Mn), 2026-2034
Figure 41. Southeast Asia Edge-Wound Inductor Revenue, (US$, Mn), 2026-2034
Figure 42. India Edge-Wound Inductor Revenue, (US$, Mn), 2026-2034
Figure 43. By Country – South America Edge-Wound Inductor Revenue Market Share, 2026-2034
Figure 44. By Country – South America Edge-Wound Inductor Sales, Market Share, 2026-2034
Figure 45. Brazil Edge-Wound Inductor Revenue, (US$, Mn), 2026-2034
Figure 46. Argentina Edge-Wound Inductor Revenue, (US$, Mn), 2026-2034
Figure 47. By Country – Middle East & Africa Edge-Wound Inductor Revenue, Market Share, 2026-2034
Figure 48. By Country – Middle East & Africa Edge-Wound Inductor Sales, Market Share, 2026-2034
Figure 49. Turkey Edge-Wound Inductor Revenue, (US$, Mn), 2026-2034
Figure 50. Israel Edge-Wound Inductor Revenue, (US$, Mn), 2026-2034
Figure 51. Saudi Arabia Edge-Wound Inductor Revenue, (US$, Mn), 2026-2034
Figure 52. UAE Edge-Wound Inductor Revenue, (US$, Mn), 2026-2034
Figure 53. Global Edge-Wound Inductor Production Capacity (K Units), 2026-2034
Figure 54. The Percentage of Production Edge-Wound Inductor by Region, 2024 VS 2032
Figure 55. Edge-Wound Inductor Industry Value Chain
Figure 56. Marketing Channels