Key Statistics
Key Takeaways
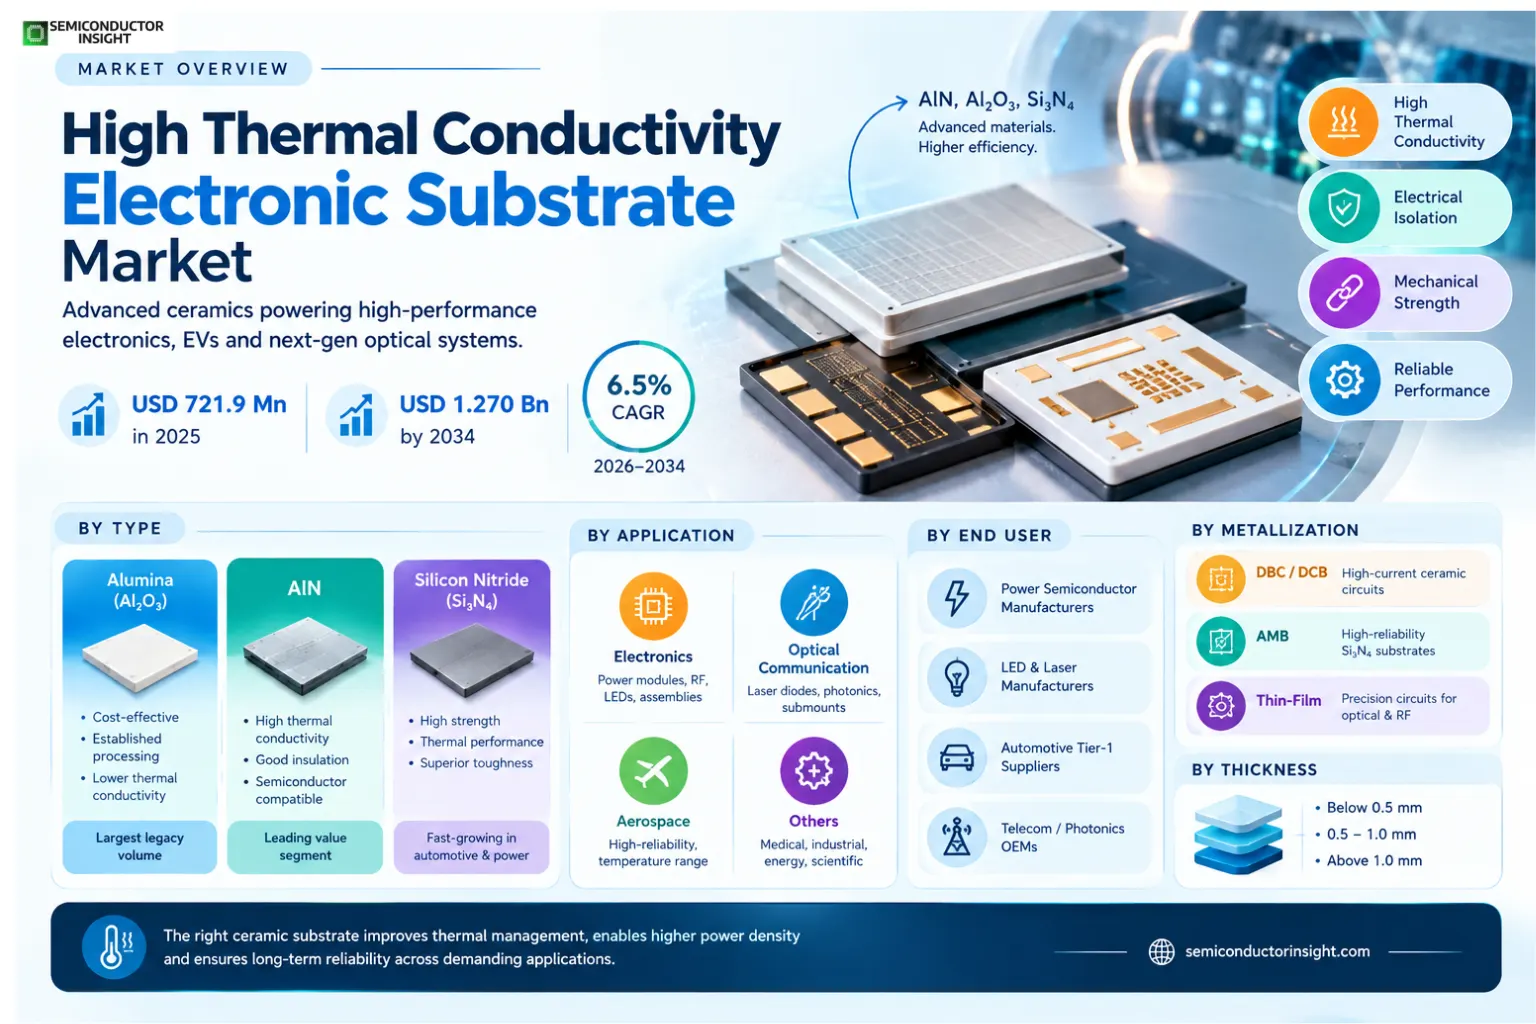
- Market size and growth: the market is valued at USD 721.9 million in 2025 and is projected to reach USD 1.270 billion by 2034, with a 6.5% CAGR over 2026–2034.
- AlN Electronic Substrates leads by type because aluminum nitride combines high thermal conductivity with electrical insulation and a coefficient of thermal expansion closer to semiconductor materials than alumina.
- Electronics is the principal application because power modules, LEDs, RF devices and high-density electronics need electrically insulating substrates that spread heat efficiently.
- Asia Pacific is the largest regional market, while Asia Pacific has the strongest incremental growth profile.
- Primary driver: SiC, GaN, EV power modules and high-power optoelectronics are increasing heat flux and the value of electrically insulating ceramic substrates
- Structural restraint: high-purity ceramic powders, energy-intensive sintering and precision metallization keep AlN and Si3N4 substrates more expensive than alumina
Market Overview
The high thermal conductivity electronic substrate market was valued at USD 721.9 million in 2025 and is projected to reach USD 1.270 billion by 2034, expanding at a 6.5% CAGR over 2026–2034. Asia Pacific leads in 2025, while the market is being reshaped by SiC/GaN power electronics, EV traction inverters, high-power LEDs and denser optical and AI hardware..
High thermal conductivity electronic substrates provide mechanical support and electrical isolation while moving heat away from semiconductor devices. Alumina remains cost-effective for mainstream electronics, aluminum nitride offers much higher thermal conductivity for high-heat-flux packages, and silicon nitride combines strong thermal performance with superior mechanical toughness. These ceramics are used beneath power semiconductors, LEDs, laser diodes, RF modules and other devices where conventional PCB materials cannot handle thermal or electrical stress.
Material properties create clear application trade-offs. CeramTec lists thermal conductivity of at least 170 W/mK for AlN compared with 24 W/mK for alumina and 90 W/mK for silicon nitride, while silicon nitride has substantially higher fracture toughness. Kyocera lists AlN grades from roughly 150 to 240 W/mK, illustrating why AlN is favored where heat removal is the first priority and Si3N4 where mechanical reliability is equally important.
EV power electronics are a major growth vector. SiC traction inverters switch high voltages at high frequency and generate concentrated heat, making ceramic substrate selection central to lifetime and power density. Optical communication and laser systems create a second premium market because precise thermal control stabilizes wavelength and device reliability. The result is a market driven by both electronics volume and growing value per substrate.
Segment Analysis: By Type
By type, the market is segmented into Alumina Electronic Substrates, AlN Electronic Substrates, Silicon Nitride Electronic Substrates. AlN Electronic Substrates leads the current mix, while suppliers differentiate through performance, reliability, manufacturability and system-level economics.
| Type | Function / role | Market position |
|---|---|---|
| Alumina Electronic Substrates | Cost-effective electrically insulating ceramic with established thick-film and DBC processing. | Largest legacy volume but lower thermal conductivity limits use in the highest heat-flux systems. |
| AlN Electronic Substrates | High thermal conductivity ceramic with good electrical insulation and semiconductor-compatible expansion. | Leading value segment for power devices, LEDs, laser diodes and optical communications. |
| Silicon Nitride Electronic Substrates | High-strength ceramic combining good thermal conductivity with superior toughness. | Fast-growing in automotive power modules where thermal cycling and mechanical reliability matter. |
Commercial implications by type
The material decision is not based on thermal conductivity alone. Alumina wins when cost dominates, AlN when maximum heat spreading and low thermal resistance are required, and silicon nitride when mechanical toughness and thermal cycling reliability are critical. Power-module suppliers increasingly design around the complete ceramic-metal stack, including copper thickness and bonding technology.
Segment Analysis: By Application
By application, the market includes Electronics, Optical Communication, Aerospace, Others. Electronics represents the largest demand pool because the technology directly affects system performance, reliability, power or cost.
| Application | Demand characteristics |
|---|---|
| Electronics | Largest application across power modules, RF devices, LEDs and dense electronic assemblies. |
| Optical Communication | Laser diodes and photonic modules need thermally stable submounts and packages. |
| Aerospace | High-reliability electronics use ceramic substrates for temperature range and electrical isolation. |
| Others | Medical, industrial laser, energy and scientific systems add specialized demand. |
By End User
| End User | Commercial relevance |
|---|---|
| Power Semiconductor Manufacturers | SiC and GaN devices require low thermal resistance and high isolation. |
| LED & Laser Manufacturers | High optical output depends on efficient junction cooling. |
| Automotive Tier-1 Suppliers | Traction inverters and onboard chargers need durable ceramic-metal substrates. |
| Telecom / Photonics OEMs | Laser and optical modules require precision thermal management. |
By Metallization
| Metallization | Commercial relevance |
|---|---|
| DBC / DCB | Direct-bonded copper creates high-current ceramic circuits for power modules. |
| AMB | Active-metal brazing is well suited to high-reliability silicon nitride substrates. |
| Thin-Film Metallization | Precision circuits support optical and RF submounts. |
By Thickness
| Thickness | Commercial relevance |
|---|---|
| Below 0.5 mm | Thin substrates reduce thermal resistance in compact modules. |
| 0.5–1.0 mm | Mainstream range balancing strength and thermal path. |
| Above 1.0 mm | Used where mechanical support or high-voltage isolation requires more ceramic thickness. |
Regional Analysis
Asia Pacific leads the market because the source study identifies Asia Pacific at 48% of 2024 market value, supported by semiconductor, EV, LED and electronics manufacturing in China, Japan, South Korea and Taiwan. Asia Pacific has the strongest expansion profile as demand rises through EV power modules, SiC/GaN devices, LEDs and regional semiconductor capacity.
How does regional demand differ across this market?
Asia Pacific is both the largest production base and the largest demand market. Europe is strong in automotive power electronics and specialty ceramics, while North America has significant aerospace, power-semiconductor and data-center electronics demand. South America and the Middle East & Africa are smaller downstream markets. Regional competition is shaped by access to ceramic powder, sintering know-how, metallization and proximity to power-module customers.
| Region | Position | Growth outlook | Demand profile | Supplier selection |
|---|---|---|---|---|
| Asia Pacific | Largest | Fastest | Power electronics and manufacturing | Thermal performance, scale, quality |
| Europe | Second | Strong | Automotive power | Reliability, toughness, lifecycle |
| North America | Third | Strong | Aerospace, power and AI systems | Performance, supply security |
| South America | Smaller | Selective | Industrial and automotive | Cost and availability |
| Middle East & Africa | Emerging | Moderate | Energy and infrastructure | Ruggedness, supply support |
Competitive Landscape
Competition is led by ceramic materials companies that combine powder formulation, sintering, precision machining and metallization with long qualification histories.
Kyocera, CeramTec, Maruwa, Toshiba Materials and Rogers compete in high-performance ceramic substrates and power-module materials. Their advantage comes from controlling ceramic composition, surface quality, flatness and metallization rather than simply offering raw sheets.
AlN suppliers compete on thermal conductivity and dielectric performance. CeramTec specifies at least 170 W/mK for its AlN substrates, while Kyocera offers grades up to a nominal 240 W/mK. Silicon nitride suppliers differentiate through fracture toughness and active-metal-brazed copper reliability for automotive power cycling.
Chinese materials companies are expanding capacity and price competition, especially in alumina and AlN. Global customers nevertheless maintain lengthy qualification because substrate defects can cause module delamination, thermal hot spots or electrical failure after assembly.
| Competitive tier | Representative participants | Competitive focus |
|---|---|---|
| Global ceramic leaders | Kyocera, CeramTec, Maruwa, Toshiba Materials | High-purity ceramics, metallization and automotive qualification |
| Power-electronics materials suppliers | Rogers, Denka, NGK/NTK | DBC/AMB materials and high-reliability substrate systems |
| Regional / emerging suppliers | Innovacera, Acro New Materials, CERcuits | Cost-competitive and specialized ceramic substrates |
Companies Profiled
Kyocera, CeramTec, Maruwa, Toshiba Materials, Rogers Corporation, Denka, NGK / NTK, Xiamen Innovacera Advanced Materials, CERcuits, Acro New Materials
Production Capacity Analysis
Capacity depends on high-purity ceramic powder, tape casting or pressing, controlled-atmosphere sintering, precision grinding, laser processing and metallization.
AlN production requires tight oxygen and impurity control because thermal conductivity is sensitive to crystal defects. Silicon nitride requires specialized sintering additives and processes to achieve both high strength and thermal conductivity. These steps make kiln capacity, process recipes and yield critical to output.
Metallization can be a separate bottleneck. DBC and AMB substrates require thick copper bonding with low voiding and controlled stress. As EV power modules move to larger areas and higher current, suppliers must maintain flatness and adhesion across larger copper patterns without warpage.
Market Dynamics
The market is moving toward materials that can support both higher heat flux and repeated thermal cycling as power semiconductors become more capable.
AlN gains value when thermal resistance is the priority, while silicon nitride gains when mechanical robustness determines lifetime. Alumina remains important because many electronics do not need premium thermal performance. This creates a tiered market in which semiconductor power density and module duty cycle determine how much customers are willing to pay for substrate performance.
Market Drivers
Drivers Impact Analysis
| Driver | Impact | Commercial mechanism |
|---|---|---|
| EV power electronics | High | Traction inverters and onboard chargers require high-current, electrically insulated thermal paths. |
| SiC and GaN adoption | High | Wide-bandgap devices raise switching frequency and power density, increasing local heat flux. |
| Optical communication | Medium | Laser diodes require stable junction temperature and precision submounts. |
| Industrial power conversion | Medium | Inverters and drives benefit from reliable high-temperature ceramic substrates. |
EV power electronics
Traction inverters and onboard chargers require high-current, electrically insulated thermal paths.
SiC and GaN adoption
Wide-bandgap devices raise switching frequency and power density, increasing local heat flux.
Optical communication
Laser diodes require stable junction temperature and precision submounts.
Industrial power conversion
Inverters and drives benefit from reliable high-temperature ceramic substrates.
Market Restraints
Restraints Impact Analysis
<thstyle=”background:#0f2a56; color:#fff; text-align:left; padding:9px 10px; border:1px solid #8eaadb; font-weight:700; width:58%” align=”left”>Commercial mechanism
| Restraint | Impact | |
|---|---|---|
| High material cost | High | AlN and Si3N4 powders and processing are more expensive than alumina. |
| Energy-intensive sintering | Medium | High-temperature furnaces contribute meaningfully to manufacturing cost. |
| Metallization yield | High | Copper bonding and warpage control can limit usable output. |
| Long qualification cycles | Medium | Automotive and aerospace customers require extensive thermal-cycling validation. |
High material cost
AlN and Si3N4 powders and processing are more expensive than alumina.
Energy-intensive sintering
High-temperature furnaces contribute meaningfully to manufacturing cost.
Metallization yield
Copper bonding and warpage control can limit usable output.
Long qualification cycles
Automotive and aerospace customers require extensive thermal-cycling validation.
Market Opportunities
SiC traction inverters
Higher switching density increases the value of low-resistance ceramic heat paths.
AMB silicon nitride
Strong ceramic and copper bonding is attractive for automotive power cycling.
Laser and photonics submounts
AlN supports optical devices where temperature stability affects wavelength and lifetime.
High-power RF packaging
GaN RF amplifiers require electrically insulating substrates with strong thermal conductivity.
Supply Chain Analysis
Alumina, AlN, Si3N4, sintering additives
Casting, pressing, sintering, grinding
DBC/DCB, AMB, thin-film circuits
Power semiconductors, LEDs, lasers, RF and aerospace
Powders
Purity and particle control affect thermal conductivity, strength and shrinkage during sintering.
Substrate fabrication
Sintering and grinding determine flatness, thickness and microstructure.
Metallization
Copper and thin-film layers convert insulating ceramics into current-carrying circuit substrates.
Module integration
Final thermal performance depends on the complete stack, including die attach, copper geometry and cooling interface.
Recent Developments
2026 — CeramTec AlN substrates specify at least 170 W/mK thermal conductivity
Current AlN products target high-power electronic substrates with strong electrical insulation. Source
2026 — Kyocera AlN substrate grades reach nominal 240 W/mK
Kyocera lists high-thermal-conductivity AlN materials for light sources, optical communications and semiconductor packaging. Source
2026 — CeramTec material comparison highlights Si3N4 toughness
The same comparison lists silicon nitride with higher fracture toughness than AlN or alumina, supporting power-cycling applications. Source
Report Scope & Segmentation
| Attribute | Coverage |
|---|---|
| Market | High Thermal Conductivity Electronic Substrate |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| 2025 Market Size | USD 721.9 million |
| 2026 Estimated Size | USD 768.6 million |
| 2034 Forecast Size | USD 1.270 billion |
| CAGR | 6.5% (2026–2034) |
| By Type | Alumina Electronic Substrates, AlN Electronic Substrates, Silicon Nitride Electronic Substrates |
| By Application | Electronics, Optical Communication, Aerospace, Others |
| By End User | Power Semiconductor Manufacturers, LED & Laser Manufacturers, Automotive Tier-1 Suppliers, Telecom / Photonics OEMs |
| By Metallization | DBC / DCB, AMB, Thin-Film Metallization |
| By Thickness | Below 0.5 mm, 0.5–1.0 mm, Above 1.0 mm |
| Regions | Asia Pacific, Europe, North America, South America, Middle East & Africa |
| Companies Profiled | Kyocera, CeramTec, Maruwa, Toshiba Materials, Rogers Corporation, Denka, NGK / NTK, Xiamen Innovacera Advanced Materials, CERcuits, Acro New Materials |
Frequently Asked Questions
What is the high thermal conductivity electronic substrate market size in 2025?
The market is valued at USD 721.9 million in 2025.
What is the projected market size by 2034?
The market is projected to reach USD 1.270 billion by 2034.
What is the CAGR from 2026 to 2034?
The market is expected to expand at a 6.5% CAGR over 2026–2034.
Which region leads the market?
Asia Pacific is the largest geographic market in 2025.
Which type leads the market?
AlN Electronic Substrates is the leading type.
Which application leads demand?
Electronics is the leading application.
What is the main growth driver?
SiC, GaN, EV power modules and high-power optoelectronics are increasing heat flux and the value of electrically insulating ceramic substrates.
What is the main restraint?
high-purity ceramic powders, energy-intensive sintering and precision metallization keep AlN and Si3N4 substrates more expensive than alumina.
Where are the strongest opportunities?
SiC traction inverters, AMB silicon nitride modules, laser-diode submounts and high-power RF packaging.
Which companies are active in the market?
Kyocera, CeramTec, Maruwa, Toshiba Materials, Rogers Corporation, Denka, NGK / NTK, Xiamen Innovacera Advanced Materials.
Research Sources & Evidence Base
View primary and official evidence used in this overview
- CeramTec: Aluminium Nitride Substrates — AlN, alumina and Si3N4 thermal and mechanical properties.
- Kyocera: Aluminum Nitride Packages / Substrates — High-thermal-conductivity ceramic substrate grades and applications.
- Rogers Corporation: Curamik ceramic substrates — Power-electronics ceramic substrate and copper-bonding applications.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF