
Key Statistics
Key Takeaways
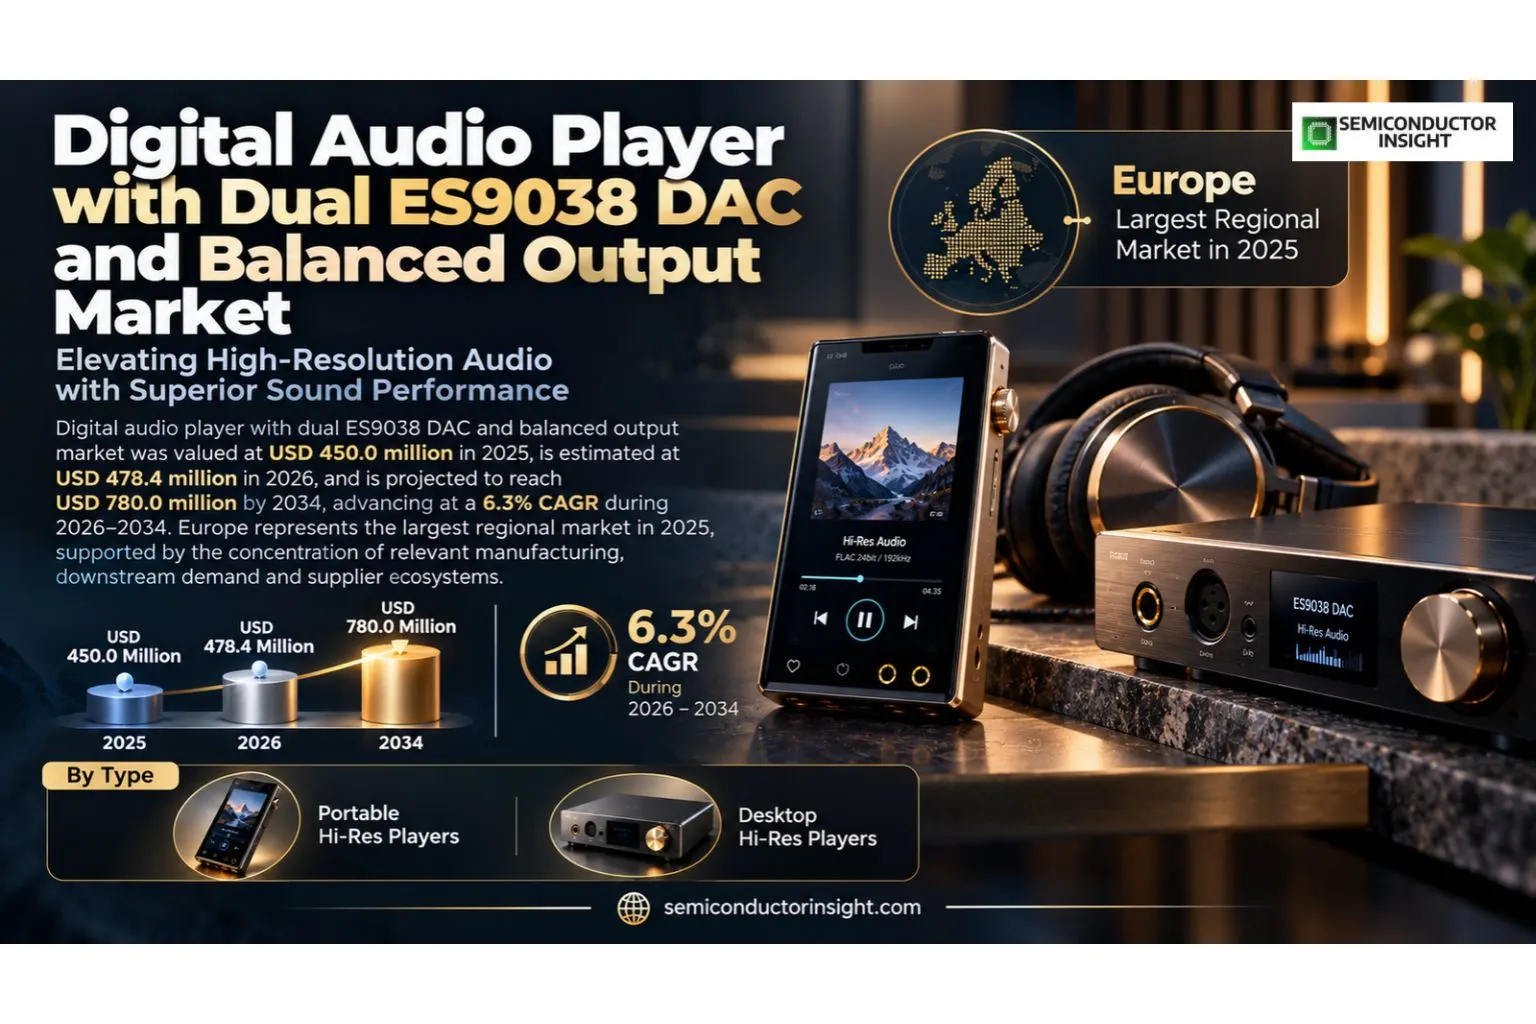
- Digital audio player with dual es9038 dac and balanced output market was valued at USD 450.0 million in 2025 and is projected to reach USD 780.0 million by 2034, representing a 6.3% CAGR over 2026–2034.
- Portable high-resolution players remain the core form factor because dedicated battery power, high-output amplification and local storage allow audiophile-grade playback without depending on a smartphone signal chain.
- Dual ES9038PRO implementations are positioned at the premium end of the market; FiiO’s M17 and Astell&Kern’s KANN CUBE demonstrate the commercial appeal of channel-separated DAC architectures paired with balanced headphone outputs.
- Europe and North America retain the deepest premium-audio customer bases, while selected Asia-Pacific markets benefit from dense specialist retail channels and strong enthusiast communities.
- Technology substitution is a material restraint because newer ESS generations such as ES9039PRO deliver lower power and updated interfaces, creating pressure on ES9038-based products to differentiate through amplifier design, firmware and system tuning.
Digital Audio Player with Dual ES9038 DAC and Balanced Output Market Overview
Digital audio player with dual es9038 dac and balanced output market was valued at USD 450.0 million in 2025, is estimated at USD 478.4 million in 2026, and is projected to reach USD 780.0 million by 2034, advancing at a 6.3% CAGR during 2026–2034. Europe represents the largest regional market in 2025, supported by the concentration of relevant manufacturing, downstream demand and supplier ecosystems.
Digital audio players in this market combine dual ESS ES9038-class digital-to-analog converters with balanced analog output stages to deliver high dynamic range, low distortion and strong channel separation. The architecture is aimed at listeners using demanding headphones or in-ear monitors who want dedicated audio hardware, local high-resolution playback and wired output power that exceeds typical smartphone implementations.
Commercial differentiation extends beyond the DAC itself. Battery capacity, thermal management, output-stage topology, operating system, streaming-app support, balanced connector format and gain structure all affect the listening experience. Premium products therefore compete as complete signal chains rather than as interchangeable containers for the same converter chip.
The commercial structure of the digital audio player with dual es9038 dac and balanced output market is shaped by design qualification, production economics and the interaction between component performance and downstream system requirements. Suppliers that can combine consistent manufacturing, application engineering and supply assurance are better positioned to convert technical eligibility into repeat business. Customer decisions increasingly account for lifecycle continuity, geographic resilience and integration cost, which makes proven process control and ecosystem compatibility as important as nominal product capability.
Segment Analysis: By Type
By type, the Digital Audio Player with Dual ES9038 DAC and Balanced Output market is segmented into Portable Hi-Res Players, Desktop Hi-Res Players. Portable players dominate because they combine local storage, streaming access and powerful headphone outputs in a mobile format. Desktop-oriented players serve users who prioritize sustained output power, larger cooling envelopes and fixed-system integration over pocketability. Purchasing decisions vary by performance requirement, qualification burden, integration complexity and lifecycle economics, so suppliers compete on application fit rather than on a single technical specification.
| Type | Role in the market | Demand characteristics |
|---|---|---|
| Portable Hi-Res Players | Portable Hi-Res Players addresses a distinct part of the product and process mix. Its commercial position depends on technical fit, manufacturing maturity, integration requirements and customer qualification rather than on headline specifications alone. | Demand is strongest where the segment aligns with established customer designs, predictable supply, and measurable system-level performance. Suppliers that can document repeatability, compatibility and lifecycle support are better placed to defend design wins. |
| Desktop Hi-Res Players | Desktop Hi-Res Players addresses a distinct part of the product and process mix. Its commercial position depends on technical fit, manufacturing maturity, integration requirements and customer qualification rather than on headline specifications alone. | Demand is strongest where the segment aligns with established customer designs, predictable supply, and measurable system-level performance. Suppliers that can document repeatability, compatibility and lifecycle support are better placed to defend design wins. |
Segment Analysis: By End User
By end user, the Digital Audio Player with Dual ES9038 DAC and Balanced Output market is segmented into Audiophiles, Musicians & Producers, High-End Travelers. Audiophiles account for the broadest demand pool, while musicians and producers value portable reference playback and travelers prioritize battery life, storage and compact high-output balanced connections. Purchasing decisions vary by performance requirement, qualification burden, integration complexity and lifecycle economics, so suppliers compete on application fit rather than on a single technical specification.
| End User | Role in the market | Demand characteristics |
|---|---|---|
| Audiophiles | Audiophiles represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
| Musicians & Producers | Musicians & Producers represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
| High-End Travelers | High-End Travelers represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
Segment Analysis: By Application
By application, the Digital Audio Player with Dual ES9038 DAC and Balanced Output market is segmented into Audiophile Home Listening, Mobile On-the-Go Streaming, Professional Monitoring, Others. Audiophile home listening remains the largest use case, while mobile high-resolution streaming is the clearest growth path as lossless catalogs and fast wireless connectivity make premium portable playback easier to access. Professional monitoring is smaller but places greater weight on repeatability and low noise. Purchasing decisions vary by performance requirement, qualification burden, integration complexity and lifecycle economics, so suppliers compete on application fit rather than on a single technical specification.
| Application | Role in the market | Demand characteristics |
|---|---|---|
| Audiophile Home Listening | Audiophile Home Listening creates demand when the underlying system requires the market’s core function at production scale. Procurement is normally tied to platform launches, equipment upgrades, capacity expansion or replacement cycles. | Buyers evaluate reliability, qualification time, integration cost and vendor support alongside unit economics. Adoption accelerates when the solution removes a system bottleneck or supports a new performance tier without creating disproportionate redesign risk. |
| Mobile On-the-Go Streaming | Mobile On-the-Go Streaming creates demand when the underlying system requires the market’s core function at production scale. Procurement is normally tied to platform launches, equipment upgrades, capacity expansion or replacement cycles. | Buyers evaluate reliability, qualification time, integration cost and vendor support alongside unit economics. Adoption accelerates when the solution removes a system bottleneck or supports a new performance tier without creating disproportionate redesign risk. |
| Professional Monitoring | Professional Monitoring creates demand when the underlying system requires the market’s core function at production scale. Procurement is normally tied to platform launches, equipment upgrades, capacity expansion or replacement cycles. | Buyers evaluate reliability, qualification time, integration cost and vendor support alongside unit economics. Adoption accelerates when the solution removes a system bottleneck or supports a new performance tier without creating disproportionate redesign risk. |
| Others | Others creates demand when the underlying system requires the market’s core function at production scale. Procurement is normally tied to platform launches, equipment upgrades, capacity expansion or replacement cycles. | Buyers evaluate reliability, qualification time, integration cost and vendor support alongside unit economics. Adoption accelerates when the solution removes a system bottleneck or supports a new performance tier without creating disproportionate redesign risk. |
Segment Analysis: By Connectivity
By connectivity, the Digital Audio Player with Dual ES9038 DAC and Balanced Output market is segmented into Wired Balanced, Advanced Bluetooth, USB-C / Digital Interface. Balanced 4.4 mm and XLR-class outputs remain central to the premium proposition, while LDAC and aptX HD broaden wireless convenience. USB DAC operation adds value by allowing the player to serve as a transportable desktop converter. Purchasing decisions vary by performance requirement, qualification burden, integration complexity and lifecycle economics, so suppliers compete on application fit rather than on a single technical specification.
| Connectivity | Role in the market | Demand characteristics |
|---|---|---|
| Wired Balanced | Wired Balanced represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
| Advanced Bluetooth | Advanced Bluetooth represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
| USB-C / Digital Interface | USB-C / Digital Interface represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
Segment Analysis: By Audio Architecture
By audio architecture, the Digital Audio Player with Dual ES9038 DAC and Balanced Output market is segmented into Dual DAC Architecture, Single DAC with Upsampling, Modular Upgradeable Platforms. Dual-DAC architectures maximize channel separation and output-stage flexibility, while newer single-chip and modular designs can reduce power consumption or extend product life through upgradeable digital sections. Purchasing decisions vary by performance requirement, qualification burden, integration complexity and lifecycle economics, so suppliers compete on application fit rather than on a single technical specification.
| Audio Architecture | Role in the market | Demand characteristics |
|---|---|---|
| Dual DAC Architecture | Dual DAC Architecture represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
| Single DAC with Upsampling | Single DAC with Upsampling represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
| Modular Upgradeable Platforms | Modular Upgradeable Platforms represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
Regional Analysis
Europe leads the digital audio player with dual es9038 dac and balanced output market in 2025, while regional growth patterns differ according to manufacturing concentration, customer investment cycles, regulation, product mix and supply-chain access. The most important regional distinction is not simply market size; it is the mechanism that converts local investment and end-market demand into qualified purchases.
How does regional demand differ across the digital audio player with dual es9038 dac and balanced output market?
Regional demand for digital audio player with dual es9038 dac and balanced output is structurally uneven because manufacturing assets, design centers, downstream customers and qualification ecosystems are not distributed evenly. Asia Pacific typically has the deepest electronics manufacturing base, North America combines technology development with capital investment, Europe emphasizes reliability and industrial requirements, and emerging regions are more dependent on imported systems. These differences influence vendor selection, inventory policy, service expectations and the pace at which new technologies are adopted.
| Region | Market position | Growth outlook | Demand profile | Supplier-selection gate |
|---|---|---|---|---|
| Europe | Largest | Steady | Premium hi-fi and specialist retail led | Brand reputation and audio performance |
| North America | Large premium market | Steady | Direct-to-consumer and headphone ecosystem led | Feature depth and channel access |
| Asia Pacific | Fastest expanding | Strong | Brand, manufacturing and enthusiast led | Product cadence and price-performance |
| South America | Emerging | Selective | Import and enthusiast led | Landed cost and distribution |
| Middle East & Africa | Developing | Selective | Luxury and e-commerce led | Channel access and affordability |
Detailed Regional Blocks
Competitive Landscape
Competition in the digital audio player with dual es9038 dac and balanced output market is determined by technical qualification, manufacturing consistency, customer relationships and the ability to support product lifecycles. Price matters, but it rarely overrides reliability, integration effort or switching cost once a supplier has been designed into a production platform.
The competitive field includes Astell&Kern, FiiO, iBasso, HiBy, Shanling, Cayin, alongside other specialized suppliers. Market share can shift when a vendor gains access to a new platform, expands qualified capacity or introduces a technology that materially improves system performance. Because customer validation can be lengthy, incumbent suppliers often benefit from continuity, while challengers need a clear technical or supply-chain advantage to displace an approved source.
Competitive strategy is increasingly multi-dimensional. Leading suppliers invest in process or product development, application engineering and regional support at the same time, while customers seek second-source options where technically feasible. This creates a market in which differentiation is sustained through documented performance, manufacturing yield, quality systems, responsiveness and the ability to support future roadmap transitions without forcing unnecessary redesigns.
| Company | Competitive position | Primary basis of competition |
|---|---|---|
| Astell&Kern | Established global / strategic supplier | Competes through product capability, qualification, account access and supply execution. |
| FiiO | Established global / strategic supplier | Competes through product capability, qualification, account access and supply execution. |
| iBasso | Established global / strategic supplier | Competes through product capability, qualification, account access and supply execution. |
| HiBy | Specialist / regional competitor | Competes through product capability, qualification, account access and supply execution. |
| Shanling | Specialist / regional competitor | Competes through product capability, qualification, account access and supply execution. |
| Cayin | Specialist / regional competitor | Competes through product capability, qualification, account access and supply execution. |
| DUNU | Focused challenger / niche participant | Competes through product capability, qualification, account access and supply execution. |
| Sony | Focused challenger / niche participant | Competes through product capability, qualification, account access and supply execution. |
| Pioneer | Focused challenger / niche participant | Competes through product capability, qualification, account access and supply execution. |
| Audio-Technica | Focused challenger / niche participant | Competes through product capability, qualification, account access and supply execution. |
Production Capacity Analysis
Production capacity is limited less by chassis assembly than by access to premium DACs, low-noise power components, matched analog stages and quality-control processes that keep channel balance and noise within specification. Small annual volumes mean manufacturers often rely on specialist contract manufacturing and shorter production runs rather than high-throughput consumer-electronics lines.
Asian manufacturing remains central because many player brands, PCB suppliers, battery vendors and enclosure specialists operate in China, South Korea and Japan. Supply planning must account for semiconductor lifecycle changes, connector availability and long lead times for premium components that may be shared with professional-audio equipment.
Capacity should therefore be evaluated on a qualified-output basis rather than as nominal installed capability. A supplier may possess equipment or production lines that appear suitable but still require customer-specific validation, process tuning, test correlation or upstream material qualification. This distinction becomes especially important during demand spikes, when headline capacity can overstate the volume that is immediately available for a particular application, technology generation or reliability class.
Market Dynamics
The digital audio player with dual es9038 dac and balanced output market is being shaped by rising performance requirements and technology transitions on the demand side, while qualification complexity, supply concentration and cost discipline constrain the pace of adoption. The balance of these forces favors suppliers that can solve a measurable system problem without increasing integration risk.
Demand expansion is not uniform across all product variants or customer groups. New technology creates attractive design opportunities, but buyers typically require a clear economic or performance case before changing a qualified architecture. At the same time, supply-chain localization, capacity investment and tighter quality requirements are changing procurement behavior. As a result, growth is likely to concentrate around applications where performance upgrades, manufacturing scale and lifecycle value reinforce one another.
Market Drivers
Four forces provide the strongest support for demand in the digital audio player with dual es9038 dac and balanced output market: performance-driven technology upgrades, expansion of relevant downstream applications, investment in manufacturing or infrastructure, and the need for more resilient supply. Their importance varies by segment, but each creates a direct reason for customers to qualify or purchase additional solutions.
| Driver | Impact | Commercial mechanism |
|---|---|---|
| Lossless streaming expands the use case for dedicated playback | High | High-resolution catalogs and offline downloads give premium players a larger content base, allowing dedicated hardware to demonstrate audible and measurable advantages over basic smartphone outputs. |
| Balanced headphone ecosystems support higher output power | High | The spread of 4.4 mm balanced connectors and harder-to-drive planar headphones increases demand for players with stronger amplification, lower crosstalk and dedicated analog stages. |
| Dual-DAC architectures remain a flagship differentiator | Medium-High | Using separate DAC resources for left and right channels supports premium positioning through channel separation, current capability and complex analog output stages. |
| Audiophile buyers value measurable engineering | Medium-High | Noise floor, THD+N, output power, sample-rate support and amplifier topology are closely compared by enthusiasts, rewarding manufacturers that can demonstrate technical advantages. |
Lossless streaming expands the use case for dedicated playback
High-resolution catalogs and offline downloads give premium players a larger content base, allowing dedicated hardware to demonstrate audible and measurable advantages over basic smartphone outputs. The commercial effect is strongest where customers can link the technology change to higher throughput, lower power, improved reliability, reduced lifecycle cost or access to a new end-market requirement.
Balanced headphone ecosystems support higher output power
The spread of 4.4 mm balanced connectors and harder-to-drive planar headphones increases demand for players with stronger amplification, lower crosstalk and dedicated analog stages. The commercial effect is strongest where customers can link the technology change to higher throughput, lower power, improved reliability, reduced lifecycle cost or access to a new end-market requirement.
Dual-DAC architectures remain a flagship differentiator
Using separate DAC resources for left and right channels supports premium positioning through channel separation, current capability and complex analog output stages. The commercial effect is strongest where customers can link the technology change to higher throughput, lower power, improved reliability, reduced lifecycle cost or access to a new end-market requirement.
Audiophile buyers value measurable engineering
Noise floor, THD+N, output power, sample-rate support and amplifier topology are closely compared by enthusiasts, rewarding manufacturers that can demonstrate technical advantages. The commercial effect is strongest where customers can link the technology change to higher throughput, lower power, improved reliability, reduced lifecycle cost or access to a new end-market requirement.
Market Restraints
Growth is moderated by qualification burden, cyclical purchasing, technology substitution and supply-chain risk. These restraints do not eliminate demand, but they can extend sales cycles, limit supplier switching and reduce the speed at which technically superior solutions convert into production revenue.
| Restraint | Impact | Commercial consequence |
|---|---|---|
| Smartphones and dongle DACs offer strong convenience | High | Modern USB DACs and mobile audio accessories deliver high quality at lower cost and with less device duplication, limiting the addressable base for dedicated players. |
| Premium pricing restricts volume | High | Dual flagship DACs, powerful amplification, large batteries and machined enclosures raise bill-of-material cost and retail prices, keeping the category concentrated among enthusiasts. |
| Newer DAC generations can shorten product relevance | Medium | ESS now positions ES9039PRO as the recommended flagship for new designs, so ES9038-based models must compete on system implementation rather than semiconductor novelty. |
| Battery and thermal constraints complicate portable design | Medium | High-output amplifiers and dual desktop-class DACs consume substantial power and generate heat, forcing tradeoffs among size, runtime, cooling and sustained output. |
Smartphones and dongle DACs offer strong convenience
Modern USB DACs and mobile audio accessories deliver high quality at lower cost and with less device duplication, limiting the addressable base for dedicated players. Suppliers can mitigate part of this pressure through stronger qualification support, transparent lifecycle planning, dual-source strategies and better alignment between product roadmaps and customer production schedules.
Premium pricing restricts volume
Dual flagship DACs, powerful amplification, large batteries and machined enclosures raise bill-of-material cost and retail prices, keeping the category concentrated among enthusiasts. Suppliers can mitigate part of this pressure through stronger qualification support, transparent lifecycle planning, dual-source strategies and better alignment between product roadmaps and customer production schedules.
Newer DAC generations can shorten product relevance
ESS now positions ES9039PRO as the recommended flagship for new designs, so ES9038-based models must compete on system implementation rather than semiconductor novelty. Suppliers can mitigate part of this pressure through stronger qualification support, transparent lifecycle planning, dual-source strategies and better alignment between product roadmaps and customer production schedules.
Battery and thermal constraints complicate portable design
High-output amplifiers and dual desktop-class DACs consume substantial power and generate heat, forcing tradeoffs among size, runtime, cooling and sustained output. Suppliers can mitigate part of this pressure through stronger qualification support, transparent lifecycle planning, dual-source strategies and better alignment between product roadmaps and customer production schedules.
Market Opportunities
The most attractive opportunities in the digital audio player with dual es9038 dac and balanced output market occur where a technology transition creates measurable value and where suppliers can enter before the customer architecture is locked. Early engagement, application-specific engineering and credible supply planning can convert these windows into durable design positions.
Desktop-replacement portable players
Large batteries, DC power modes and high-current headphone amplifiers can position a premium DAP as both portable source and compact desktop front end. The opportunity is strongest for suppliers that can demonstrate performance with production-relevant data, provide engineering support during qualification and maintain a roadmap that gives customers confidence in long-term availability.
Streaming-first audiophile platforms
Better Android support, Roon compatibility and native streaming integration can make dedicated players easier to use without sacrificing local high-resolution playback. The opportunity is strongest for suppliers that can demonstrate performance with production-relevant data, provide engineering support during qualification and maintain a roadmap that gives customers confidence in long-term availability.
Balanced IEM and headphone ecosystems
Growing 4.4 mm adoption gives manufacturers an opportunity to bundle players, cables and headphones around a common premium interface. The opportunity is strongest for suppliers that can demonstrate performance with production-relevant data, provide engineering support during qualification and maintain a roadmap that gives customers confidence in long-term availability.
Long-life firmware and modular design
Extended software support or replaceable modules can reduce obsolescence concerns and justify premium pricing for buyers who expect multi-year ownership. The opportunity is strongest for suppliers that can demonstrate performance with production-relevant data, provide engineering support during qualification and maintain a roadmap that gives customers confidence in long-term availability.
Supply Chain Analysis
Audio semiconductors and passive components
DACs, clocks, regulators, op-amps and precision passives define noise, distortion and power characteristics. Value capture at this stage depends on quality consistency, technical differentiation and the difficulty of substitution. Bottlenecks can propagate downstream when qualification or material compatibility prevents customers from shifting quickly to an alternative supplier.
Player electronics and firmware
Brands integrate processors, storage, wireless radios, power management and proprietary audio firmware around the conversion chain. Value capture at this stage depends on quality consistency, technical differentiation and the difficulty of substitution. Bottlenecks can propagate downstream when qualification or material compatibility prevents customers from shifting quickly to an alternative supplier.
Mechanical assembly and final tuning
Machined enclosures, balanced connectors, thermal solutions and battery systems are assembled and validated for output power and reliability. Value capture at this stage depends on quality consistency, technical differentiation and the difficulty of substitution. Bottlenecks can propagate downstream when qualification or material compatibility prevents customers from shifting quickly to an alternative supplier.
Specialist retail and direct sales
Premium players reach customers through brand websites, e-commerce and specialist audio dealers that often bundle headphones and cables. Value capture at this stage depends on quality consistency, technical differentiation and the difficulty of substitution. Bottlenecks can propagate downstream when qualification or material compatibility prevents customers from shifting quickly to an alternative supplier.
Recent Developments
Recent developments show how technology roadmaps, manufacturing investment and standards are changing the competitive requirements of the digital audio player with dual es9038 dac and balanced output market. The entries below are selected for their direct relevance to product capability, capacity, qualification or downstream adoption rather than for general corporate activity.
ESS introduced the ES9291 SMART Codec built on HyperStream IV, extending its newer-generation audio semiconductor portfolio. Although not a direct ES9038 replacement, the launch demonstrates the continuing shift toward higher integration and lower-power audio architectures that premium player makers must evaluate. Source
ESS introduced new SABRE PRO SMART ADCs using HyperStream IV architecture, reinforcing its current-generation high-resolution audio roadmap. The broader migration to HyperStream IV increases competitive pressure on legacy ES9038-based designs to differentiate through complete-system implementation. Source
FiiO continues to position the M17 as a portable desktop-class player using dual ES9038PRO DACs, dual THX AAA amplification, balanced outputs and a 9200 mAh battery. The product remains a direct benchmark for the architecture covered by this market. Source
Report Scope & Segmentation
| Report attribute | Coverage |
|---|---|
| Market | Digital Audio Player with Dual ES9038 DAC and Balanced Output |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| 2025 Market Size | USD 450.0 million |
| 2026 Estimated Size | USD 478.4 million |
| 2034 Forecast Size | USD 780.0 million |
| CAGR (2026–2034) | 6.3% |
| Largest Market in 2025 | Europe |
| By Type | Portable Hi-Res Players, Desktop Hi-Res Players |
| By Application | Audiophile Home Listening, Mobile On-the-Go Streaming, Professional Monitoring, Others |
| By End User | Audiophiles, Musicians & Producers, High-End Travelers |
| By Connectivity | Wired Balanced, Advanced Bluetooth, USB-C / Digital Interface |
| By Audio Architecture | Dual DAC Architecture, Single DAC with Upsampling, Modular Upgradeable Platforms |
| Companies Profiled | Astell&Kern, FiiO, iBasso, HiBy, Shanling, Cayin, DUNU, Sony, Pioneer, Audio-Technica |
Frequently Asked Questions
What was the digital audio player with dual es9038 dac and balanced output market size in 2025?
The global digital audio player with dual es9038 dac and balanced output market was valued at USD 450.0 million in 2025. The 2025 value is the base-year reference used throughout this overview and provides the starting point for comparing the 2026 estimate and the 2034 forecast.
What is the projected digital audio player with dual es9038 dac and balanced output market size in 2034?
The global market is projected to reach USD 780.0 million by 2034. The forecast reflects the interaction of downstream adoption, technology transitions, production investment and the qualification requirements that shape commercial conversion across the market.
What is the CAGR of the digital audio player with dual es9038 dac and balanced output market from 2026 to 2034?
The digital audio player with dual es9038 dac and balanced output market is expected to expand at a 6.3% CAGR during 2026–2034. Growth will not be uniform across every product or region because customer qualification, capital cycles, supply constraints and application-specific performance requirements differ materially.
Which region is the largest digital audio player with dual es9038 dac and balanced output market?
Europe is the largest regional market in 2025. Its position is supported by the concentration of relevant manufacturing, customers, technology ecosystems and downstream demand, although the precise commercial mechanism differs by country and application.
How is the digital audio player with dual es9038 dac and balanced output market segmented by type?
By type, the market is segmented into Portable Hi-Res Players, Desktop Hi-Res Players. These categories address different performance, cost and integration requirements, so supplier selection depends on application fit, qualification history and lifecycle economics rather than a single specification.
What are the main applications for digital audio player with dual es9038 dac and balanced output?
By application, the market covers Audiophile Home Listening, Mobile On-the-Go Streaming, Professional Monitoring, Others. Demand in each application is linked to platform launches, capacity expansion, equipment replacement and the degree to which the technology improves system performance or manufacturing economics.
What are the principal growth drivers for the digital audio player with dual es9038 dac and balanced output market?
Key drivers include lossless streaming expands the use case for dedicated playback and balanced headphone ecosystems support higher output power. These forces increase demand when customers can translate technical improvements into higher performance, lower cost, greater reliability or access to new applications.
What are the main restraints in the digital audio player with dual es9038 dac and balanced output market?
Important restraints include smartphones and dongle dacs offer strong convenience and premium pricing restricts volume. The resulting qualification burden, purchasing cyclicality and technology risk can extend sales cycles and limit rapid supplier substitution even when new solutions offer clear technical advantages.
Which companies participate in the digital audio player with dual es9038 dac and balanced output market?
Companies profiled in this market include Astell&Kern, FiiO, iBasso, HiBy, Shanling, Cayin, DUNU, Sony. Competition centers on qualification, product or process performance, manufacturing consistency, customer support and the ability to maintain supply across the required product lifecycle.
What should buyers evaluate when selecting a digital audio player with dual es9038 dac and balanced output supplier?
Buyers should evaluate demonstrated performance, qualification history, manufacturing consistency, lifecycle support, supply resilience and integration cost. A technically strong product can still face adoption barriers if it increases redesign risk, lacks regional support or cannot meet the customer’s production and quality requirements.
Research Sources & Evidence Base
View research sources used for this overview.
- ESS Technology. SABRE Audiophile DACs — Current ES9038PRO status, performance and migration path to newer SABRE PRO parts.
- FiiO. M17 portable desktop-class player — Dual ES9038PRO implementation, balanced outputs, amplification and battery architecture.
- Astell&Kern. KANN CUBE — Dual ES9038PRO channel architecture and balanced mini-XLR output.
- ESS Technology. ES9038PRO introduction — ES9038PRO 32-bit 8-channel architecture and performance positioning.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF





