Key Statistics
Key Takeaways
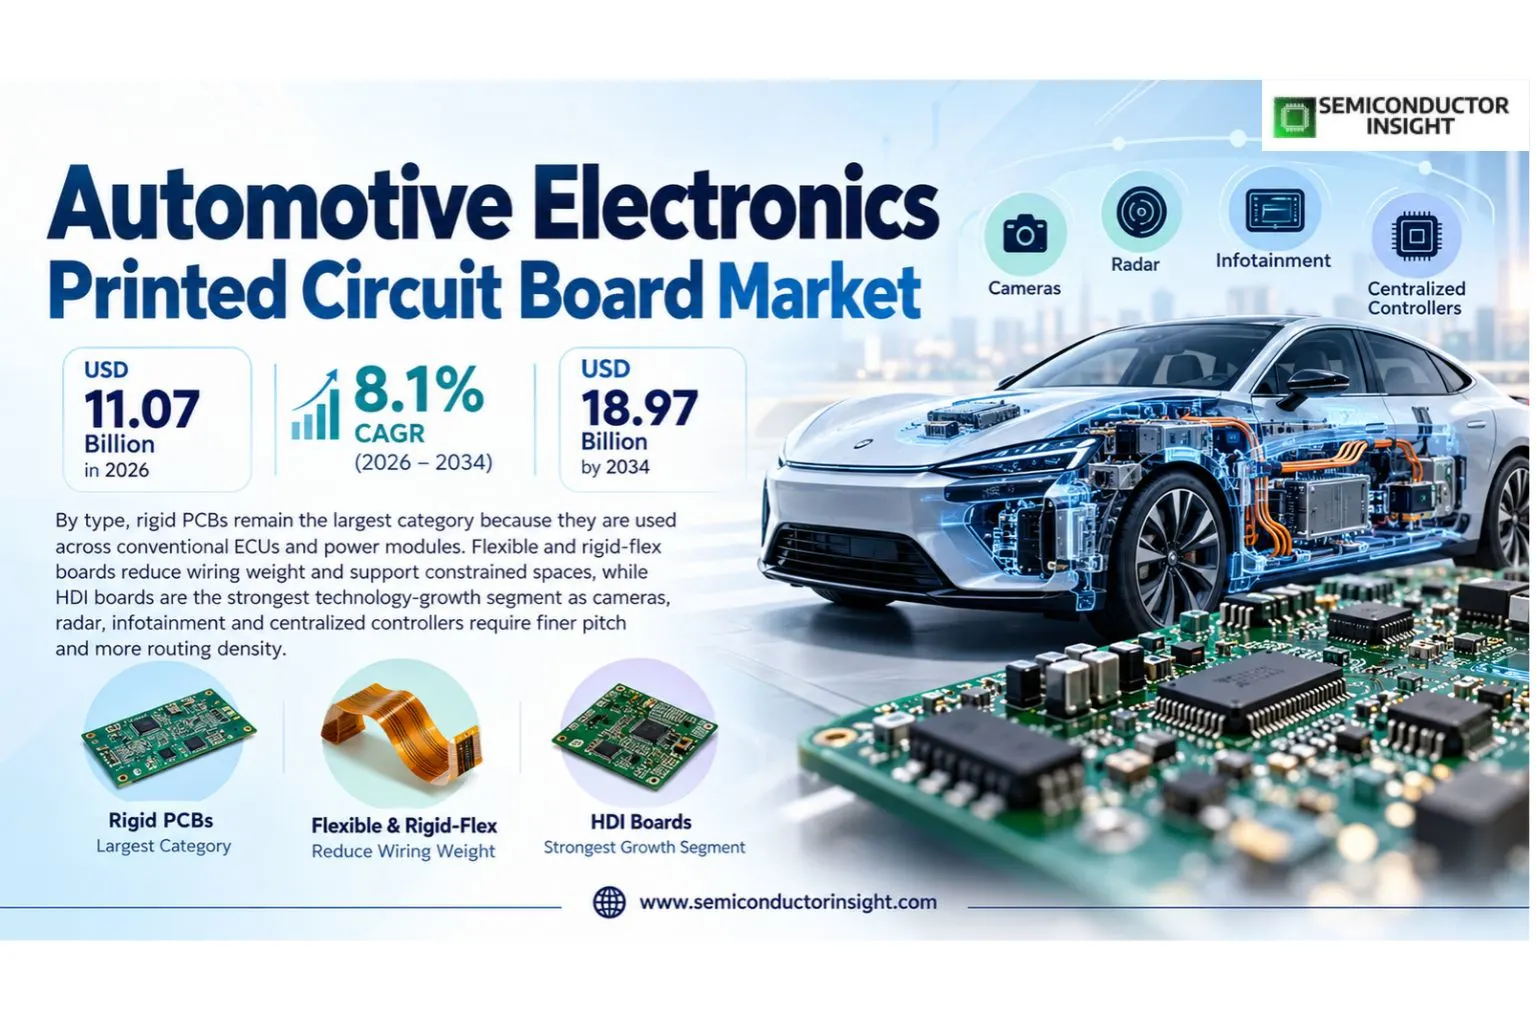
- Market size: The market is valued at USD 10.24 billion in 2025 and is projected to reach USD 18.97 billion by 2034, representing a 8.1% CAGR during 2026–2034.
- Rigid and multilayer PCBs account for the largest volume, while HDI and rigid-flex are gaining value as ADAS, cameras and domain controllers require more interconnect density.
- Asia Pacific leads the market because China, Japan and South Korea combine vehicle production, EV manufacturing and a large PCB supply chain.
- ADAS and EV power electronics are the strongest growth applications, increasing requirements for high-frequency materials, thermal management and automotive-grade reliability.
- Reliability qualification is a key competitive barrier, with automotive PCBs expected to withstand temperature cycling, vibration, humidity and long service lifetimes.
Automotive Electronics Printed Circuit Board Market Overview
Automotive electronics printed circuit board market is valued at USD 10.24 billion in 2025 and is projected to reach USD 18.97 billion by 2034, expanding at a 8.1% CAGR during 2026–2034. The 2026 market level is USD 11.07 billion. Asia Pacific leads through vehicle manufacturing, EV production and a dense PCB supply chain. Automotive electronics content is rising as vehicles add ADAS, digital cockpits, electrified powertrains, lighting, sensors and zonal or domain-control architectures.
Automotive electronics PCBs mechanically support and electrically connect semiconductors, sensors, passives and connectors across vehicle electronic systems. They include rigid, flexible, HDI and rigid-flex constructions with automotive-specific requirements for temperature cycling, vibration, humidity, contamination and long-term reliability. The board is a critical platform for ECUs, cameras, lighting, power electronics, battery systems, infotainment and increasingly centralized compute architectures.
Technology is shifting toward HDI, high-frequency laminates, heavy-copper structures, embedded thermal solutions and flexible interconnect. TTM highlights automotive capabilities spanning RF/microwave, HDI and thermal-management technologies, reflecting the need to combine signal integrity with heat removal. Higher-speed automotive Ethernet, radar and camera links also increase demand for controlled-impedance and low-loss materials.
Automotive PCB suppliers compete on quality, defect control, global manufacturing footprint and the ability to pass lengthy OEM and Tier-1 qualification. Once designed into a vehicle platform, a board can remain in production for years, creating stable revenue but demanding strict change control. EV and ADAS programs add premium content because they use more layers, tighter line widths, high-current copper and specialized thermal structures.
Segment Analysis: By Type
By type, rigid PCBs remain the largest category because they are used across conventional ECUs and power modules. Flexible and rigid-flex boards reduce wiring weight and support constrained spaces, while HDI boards are the strongest technology-growth segment as cameras, radar, infotainment and centralized controllers require finer pitch and more routing density.
| Type | Commercial role |
|---|---|
| Flexible PCB | Lightweight interconnect for cameras, displays, sensors and constrained vehicle spaces. |
| Rigid PCB | Largest-volume platform for ECUs, lighting, body electronics and power systems. |
| HDI PCB | Fine-line high-density boards for ADAS, infotainment and centralized computing. |
| Rigid-Flex PCB | Integrated rigid and flexible sections for complex three-dimensional assemblies. |
Additional Segmentation: By Vehicle Type
Vehicle type separates passenger cars, commercial vehicles and electric vehicles. Passenger cars provide the largest unit base, commercial vehicles use durable control and telematics systems, and EVs have the highest electronics value per vehicle because battery management, traction inverters, charging, thermal management and additional control electronics expand PCB content. For commercial decisions in the Automotive Electronics Printed Circuit Board market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
| Vehicle Type | Demand characteristics |
|---|---|
| Passenger Cars | Largest unit base across body, safety, infotainment and powertrain electronics. |
| Commercial Vehicles | Telematics, safety, fleet systems and rugged control electronics. |
| Electric Vehicles | High PCB value through battery, inverter, charging and software-defined vehicle systems. |
Segment Analysis: By Application
By application, transmission control, lighting, sensors and safety remain large installed categories, while ADAS, infotainment and EV power electronics provide the strongest growth. Camera, radar and domain-controller systems need high-speed routing and dense packaging, while inverters and battery electronics require heavier copper and improved thermal management. For commercial decisions in the Automotive Electronics Printed Circuit Board market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
| Application | Demand characteristics |
|---|---|
| Transmission Control | Engine and drivetrain ECUs with long automotive qualification cycles. |
| Lighting | LED drivers, adaptive lighting and body-control electronics. |
| Sensors | Radar, camera, pressure and environmental sensor electronics. |
| Safety Systems | Airbag, braking and stability-control electronics. |
| ADAS & Infotainment | Cameras, radar, displays, connectivity and centralized compute. |
| EV Power Electronics | Battery management, charging, inverter and thermal-control systems. |
Additional Segmentation: By PCB Layer / Technology
PCB technology ranges from simple single- and double-layer boards to multilayer, HDI and high-frequency or high-thermal constructions. The market is moving toward more complex boards as vehicles consolidate functions into centralized controllers and add high-speed links. Power electronics simultaneously require heavy copper and thermal solutions, creating a broader mix of advanced board technologies per vehicle.
| PCB Layer / Technology | Commercial relevance |
|---|---|
| Single / Double Layer | Simple lighting, sensors and lower-complexity control functions. |
| Multilayer | Mainstream ECU and body-electronics applications. |
| HDI | Fine-pitch computing, camera and high-density automotive electronics. |
| High-Frequency / High-Thermal | Radar, high-speed networking and power electronics requiring specialized materials. |
Regional Analysis
Asia Pacific leads through China, Japan and South Korea, which combine automotive production, EV adoption and PCB manufacturing. Europe remains strategically important in premium vehicles and automotive electronics, while North America is strong in ADAS, EVs and advanced computing. Other regions largely consume boards through global vehicle platforms. For commercial decisions in the Automotive Electronics Printed Circuit Board market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Why does regional demand differ across the Automotive Electronics Printed Circuit Board market?
Regional market share is shaped by vehicle production and the location of PCB fabrication. Asia benefits from both end demand and manufacturing scale, Europe from high electronic content in premium vehicles, and North America from advanced ADAS and EV programs. Global Tier-1 suppliers typically qualify multiple factories to ensure continuity for long vehicle programs.
| Region | Position | Demand profile | Supplier-selection factor |
|---|---|---|---|
| Asia Pacific | Largest / fastest | EVs, automotive electronics, PCB manufacturing | Scale and supply-chain integration |
| North America | High-value | ADAS, EV, connected vehicles | Advanced computing and reliability |
| Europe | Strategic | Premium vehicles, safety, EV | Qualification and engineering |
| South America | Emerging | Vehicle assembly | Global platform sourcing |
| Middle East & Africa | Emerging | Imported vehicles, assembly | Limited local PCB production |
Competitive Landscape
TTM Technologies, Nippon Mektron, Samsung Electro-Mechanics, Unimicron, Meiko, CMK and other PCB suppliers compete through automotive qualification, HDI capability, flexible circuits, thermal management and global manufacturing. Customer concentration is high because Tier-1 suppliers and OEMs qualify a limited number of factories for each program. For commercial decisions in the Automotive Electronics Printed Circuit Board market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Advanced automotive PCBs require a broader technology portfolio than conventional rigid boards. TTM highlights high-density interconnect, RF/microwave and thermal-management solutions for automotive customers, illustrating how radar, high-speed networking and power electronics are increasing material and process complexity. For commercial decisions in the Automotive Electronics Printed Circuit Board market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Competitive advantage increasingly depends on defect prevention and geographic resilience. Automotive recalls can be expensive, so customers prioritize traceability, process capability and change control. Suppliers with factories in several regions can support global vehicle platforms while reducing supply-chain risk. For commercial decisions in the Automotive Electronics Printed Circuit Board market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
| Competitive tier | Representative companies | Primary differentiation |
|---|---|---|
| Global automotive PCB leaders | TTM, Nippon Mektron, Unimicron, Meiko | Automotive qualification, HDI, flex and global manufacturing. |
| Asian high-volume suppliers | Samsung Electro-Mechanics, CMK and regional PCB firms | Scale, electronics integration and cost competitiveness. |
| Specialty technology suppliers | RF, thermal and rigid-flex specialists | Radar, power and high-density application expertise. |
Key companies profiled
TTM Technologies, Nippon Mektron, Samsung Electro-Mechanics, Unimicron Technology, Meiko Electronics, CMK and other automotive PCB manufacturers are included in the competitive scope. Supplier positions differ by rigid, flex, HDI, RF and thermal capability, as well as by factory qualification with major Tier-1 customers. For commercial decisions in the Automotive Electronics Printed Circuit Board market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Production Capacity Analysis
Automotive PCB capacity depends on laminate supply, drilling, imaging, plating, lamination, solder mask, electrical test and reliability inspection. HDI adds laser microvias and sequential lamination, while heavy-copper and thermal boards require different process windows. High mix and strict automotive documentation reduce effective capacity versus commodity consumer boards. For commercial decisions in the Automotive Electronics Printed Circuit Board market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Suppliers often dedicate or qualify specific production lines for automotive work because traceability and change control are critical. New factory qualification can take significant time, so OEM demand shifts cannot be served instantly. Regionalized capacity is valuable for supporting global vehicle platforms and reducing logistics risk. For commercial decisions in the Automotive Electronics Printed Circuit Board market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Market Dynamics
The market is driven by EVs, ADAS, connected vehicles and rising electronics content. Growth is restrained by qualification cycles, raw-material volatility and automotive production cycles. HDI, radar boards, heavy-copper power boards and centralized vehicle computing offer the strongest value-growth opportunities. For commercial decisions in the Automotive Electronics Printed Circuit Board market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Market Drivers
| Driver | Impact | Commercial mechanism |
|---|---|---|
| Vehicle electrification | High | EVs contain more power and control electronics. |
| ADAS | High | Cameras, radar and compute add high-density boards. |
| Software-defined vehicles | Medium-High | Centralized computing increases PCB complexity. |
| LED and comfort electronics | Medium | Lighting, displays and cabin systems add recurring PCB content. |
Vehicle electrification
Battery-management systems, inverters, onboard chargers and thermal control all require PCBs. EV architectures therefore raise board value per vehicle even when total vehicle unit growth is modest. For commercial decisions in the Automotive Electronics Printed Circuit Board market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
ADAS
Advanced driver-assistance systems increase the number of sensors and high-speed controllers. Radar and vision systems require low-loss materials, controlled impedance and reliable high-density interconnect. For commercial decisions in the Automotive Electronics Printed Circuit Board market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Software-defined vehicles
Zonal and domain architectures consolidate many functions into powerful controllers with high-speed Ethernet. These boards require more layers, finer pitch and stronger thermal design. For commercial decisions in the Automotive Electronics Printed Circuit Board market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
LED and comfort electronics
Adaptive lighting, digital cockpits and smart interiors increase the number of electronic modules across both conventional and electric vehicles. For commercial decisions in the Automotive Electronics Printed Circuit Board market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Market Restraints
| Restraint | Impact | Commercial consequence |
|---|---|---|
| Long qualification cycles | High | New factories and materials require extensive automotive validation. |
| Raw-material volatility | Medium-High | Copper foil, laminate and specialty materials affect cost. |
| Automotive production cycles | Medium | Board demand depends on vehicle output and platform launches. |
| Reliability burden | Medium | Field failures carry high cost and reputational risk. |
Long qualification cycles
OEMs and Tier-1 suppliers demand reliability testing and strict process change control. This slows new supplier entry and limits rapid capacity switching. For commercial decisions in the Automotive Electronics Printed Circuit Board market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Raw-material volatility
High-frequency and thermal materials are more expensive than standard FR-4. Price changes can pressure margins on long-term automotive contracts. For commercial decisions in the Automotive Electronics Printed Circuit Board market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Automotive production cycles
Economic slowdowns or model delays can reduce utilization. Suppliers mitigate this risk by serving multiple OEMs and electronics categories. For commercial decisions in the Automotive Electronics Printed Circuit Board market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Reliability burden
Boards must survive years of vibration, temperature cycling and humidity. This increases inspection, testing and documentation requirements relative to many consumer applications. For commercial decisions in the Automotive Electronics Printed Circuit Board market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Market Opportunities
ADAS HDI boards
Camera, radar and centralized compute create premium demand for fine-line, low-loss and high-layer-count boards. For commercial decisions in the Automotive Electronics Printed Circuit Board market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification. For commercial decisions in the Automotive Electronics Printed Circuit Board market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
EV power boards
Heavy-copper and thermally enhanced PCBs can capture higher value in battery, inverter and charging systems. For commercial decisions in the Automotive Electronics Printed Circuit Board market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification. For commercial decisions in the Automotive Electronics Printed Circuit Board market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Rigid-flex architectures
Reducing connectors and wiring can lower weight and improve reliability in cameras, displays and compact modules. For commercial decisions in the Automotive Electronics Printed Circuit Board market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification. For commercial decisions in the Automotive Electronics Printed Circuit Board market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
High-speed automotive Ethernet
Multi-gigabit in-vehicle networking creates a new market for controlled-impedance and low-loss PCB materials. For commercial decisions in the Automotive Electronics Printed Circuit Board market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification. For commercial decisions in the Automotive Electronics Printed Circuit Board market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Supply Chain Analysis
Materials. Copper foil, resin systems, glass fabric and specialty low-loss or thermal laminates form the upstream base. Material selection depends on frequency, temperature and current requirements. For commercial decisions in the Automotive Electronics Printed Circuit Board market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Fabrication. Automotive boards are imaged, drilled, plated and laminated with tight process control. HDI adds laser microvias, while flex and rigid-flex use specialized materials and lamination steps. For commercial decisions in the Automotive Electronics Printed Circuit Board market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Assembly. Tier-1 suppliers populate boards with semiconductors, sensors and connectors and perform functional testing. Traceability links board lots with finished ECUs. For commercial decisions in the Automotive Electronics Printed Circuit Board market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Deployment. ECUs, sensors and power modules are installed in vehicles for long service lives. Supplier continuity and change control remain important throughout each vehicle platform. For commercial decisions in the Automotive Electronics Printed Circuit Board market, buyers also weigh qualification evidence, integration effort, operating reliability, lifecycle support, supply continuity and measurable system-level value rather than a single specification.
Recent Developments in the Automotive Electronics Printed Circuit Board Market
Developments tracked through September 2026 and limited to events that materially affect technology, capacity, adoption or competition.
- 2026 Automotive Portfolio
TTM Technologies continued highlighting automotive PCB capabilities including HDI, RF/microwave and thermal-management technologies for high-reliability vehicle electronics. Source - 17 June 2026
TTM announced AEC-Q200 qualification for its Mini-Xinger RF component portfolio, illustrating the company’s continued investment in automotive-grade reliability across advanced interconnect and RF applications. Source - 2026 Technology Resources
TTM released updated automotive, HDI and thermal-management technical materials, reflecting increased design emphasis on dense interconnect and heat removal in modern vehicle electronics. Source
Report Scope & Segmentation
| Attribute | Scope |
|---|---|
| Base year | 2025 |
| Estimated year | 2026 |
| Forecast period | 2026–2034 |
| 2025 market size | USD 10.24 billion |
| 2026 estimated size | USD 11.07 billion |
| 2034 projected size | USD 18.97 billion |
| CAGR (2026–2034) | 8.1% |
| Largest market in 2025 | Asia Pacific |
| By Type | Flexible PCB; Rigid PCB; HDI PCB; Rigid-Flex PCB |
| By Application | Transmission Control; Lighting; Sensors; Safety Systems; ADAS & Infotainment; EV Power Electronics |
| By Vehicle Type | Passenger Cars; Commercial Vehicles; Electric Vehicles |
| By PCB Layer / Technology | Single/Double Layer; Multilayer; HDI; High-Frequency/High-Thermal |
| Companies profiled | TTM Technologies; Nippon Mektron; Samsung Electro-Mechanics; Unimicron; Meiko; CMK and other automotive PCB suppliers |
Frequently Asked Questions
What is the automotive electronics PCB market size in 2025?
The global market is valued at USD 10.24 billion in 2025 across rigid, flexible, HDI and rigid-flex automotive boards.
What is the market forecast for 2034?
The market is projected to reach USD 18.97 billion by 2034, representing an 8.1% CAGR during 2026–2034. The 2026 market level is USD 11.07 billion.
Which region leads the market?
Asia Pacific leads because it combines large vehicle and EV production with a dense PCB manufacturing base.
Which PCB type is largest?
Rigid PCBs remain the largest volume category, while HDI and rigid-flex products provide faster value growth.
Which applications are growing fastest?
ADAS, infotainment, centralized computing and EV power electronics are among the strongest growth applications.
Why are automotive PCBs different?
They must withstand long-term temperature cycling, vibration, humidity and strict reliability requirements over the vehicle lifetime.
Who are the major suppliers?
TTM Technologies, Nippon Mektron, Samsung Electro-Mechanics, Unimicron, Meiko and CMK are important participants.
How do EVs affect demand?
EVs add battery management, inverter, charging and thermal-control electronics, increasing PCB value per vehicle.
What limits market growth?
Long qualification cycles, raw-material cost, automotive production cycles and demanding reliability requirements are the main restraints.
What will drive growth through 2034?
EVs, ADAS, software-defined vehicles, high-speed networking and more electronic content per vehicle will support expansion.
Research Sources & Evidence Base
View research sources used in this market overview
- TTM Technologies — Automotive Market Capabilities. Automotive PCB, HDI, RF and thermal capability evidence.
- TTM Technologies — AEC-Q200 Qualification Announcement. 2026 automotive reliability development evidence.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF