Key Statistics
Key Takeaways
- 4g rru market was valued at USD 3.65 billion in 2025 and is projected to reach USD 3.33 billion by 2034, representing a -1.0% CAGR over 2026–2034.
- Macrocell base stations remain the largest application because nationwide LTE coverage and capacity still depend on distributed radio units at tower and rooftop sites.
- The market is mature rather than obsolete: operators continue replacing older radios with lighter, dual-band and more energy-efficient units even as the majority of new growth capital shifts to 5G.
- Asia Pacific leads because China, India, Southeast Asia and other markets combine the world’s largest LTE installed base with continuing rural coverage and network-modernization programs.
- Dual-band and multi-band radios reduce tower loading and operating cost by consolidating multiple legacy units, creating a replacement market even where LTE subscriber growth has slowed.
4G RRU Market Overview
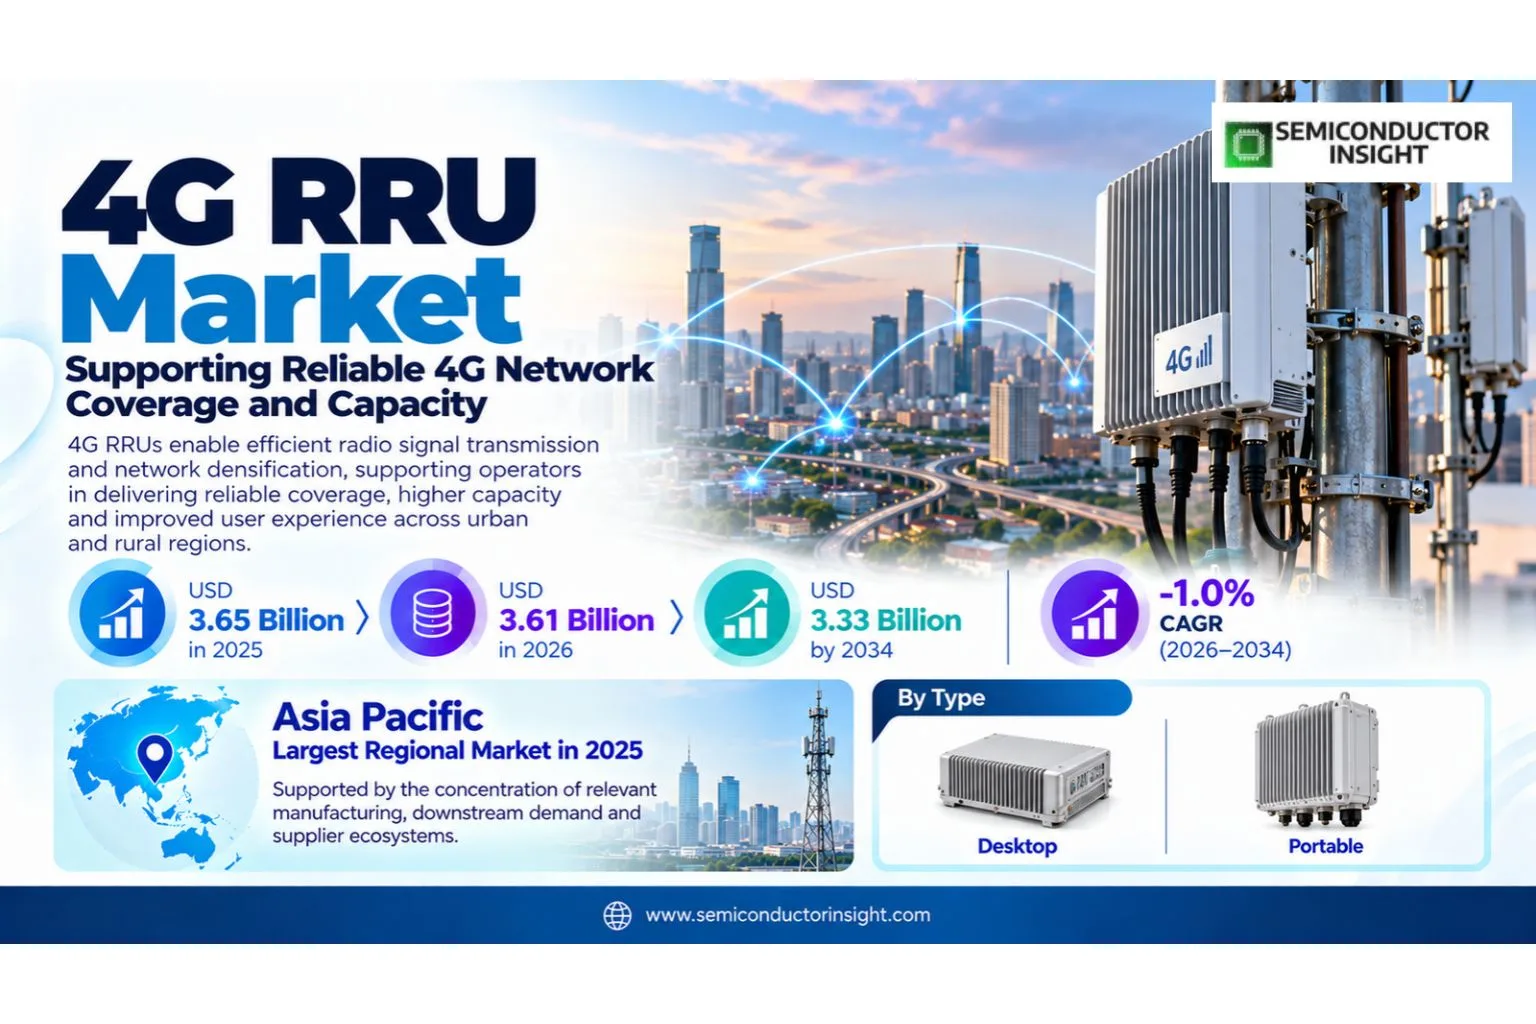
4g rru market was valued at USD 3.65 billion in 2025, is estimated at USD 3.61 billion in 2026, and is projected to reach USD 3.33 billion by 2034, advancing at a -1.0% CAGR during 2026–2034. Asia Pacific represents the largest regional market in 2025, supported by the concentration of relevant manufacturing, downstream demand and supplier ecosystems.
A 4G remote radio unit is the radio-frequency portion of a distributed LTE base station, typically mounted close to the antenna to reduce feeder loss. It handles transmit and receive amplification, filtering, conversion and digital fronthaul between the antenna system and the baseband unit. Modern units increasingly support software-defined operation, multiple bands and LTE/NR coexistence.
The market has shifted from greenfield LTE rollout toward modernization, capacity infill, rural coverage and hybrid 4G/5G operation. Operators therefore evaluate radios on energy efficiency, weight, tower loading, supported bands and the ability to preserve existing LTE assets while moving selected spectrum and traffic toward 5G.
The commercial structure of the 4g rru market is shaped by design qualification, production economics and the interaction between component performance and downstream system requirements. Suppliers that can combine consistent manufacturing, application engineering and supply assurance are better positioned to convert technical eligibility into repeat business. Customer decisions increasingly account for lifecycle continuity, geographic resilience and integration cost, which makes proven process control and ecosystem compatibility as important as nominal product capability.
Segment Analysis: By Type
By type, the 4G RRU market is segmented into Desktop, Portable. Portable or compact outdoor radio units account for the largest deployment volume because operators prefer equipment mounted close to antennas and optimized for tower or pole installation. Desktop-style or indoor units remain relevant in specialized sites and lab environments. Purchasing decisions vary by performance requirement, qualification burden, integration complexity and lifecycle economics, so suppliers compete on application fit rather than on a single technical specification.
| Type | Role in the market | Demand characteristics |
|---|---|---|
| Desktop | Desktop addresses a distinct part of the product and process mix. Its commercial position depends on technical fit, manufacturing maturity, integration requirements and customer qualification rather than on headline specifications alone. | Demand is strongest where the segment aligns with established customer designs, predictable supply, and measurable system-level performance. Suppliers that can document repeatability, compatibility and lifecycle support are better placed to defend design wins. |
| Portable | Portable addresses a distinct part of the product and process mix. Its commercial position depends on technical fit, manufacturing maturity, integration requirements and customer qualification rather than on headline specifications alone. | Demand is strongest where the segment aligns with established customer designs, predictable supply, and measurable system-level performance. Suppliers that can document repeatability, compatibility and lifecycle support are better placed to defend design wins. |
Segment Analysis: By Frequency Architecture
By frequency architecture, the 4G RRU market is segmented into Single-Band, Dual-Band, Multi-Band. Dual-band and multi-band radios are gaining share in replacement programs because they consolidate hardware and reduce site power, cabling and tower loading compared with multiple single-band RRUs. Purchasing decisions vary by performance requirement, qualification burden, integration complexity and lifecycle economics, so suppliers compete on application fit rather than on a single technical specification.
| Frequency Architecture | Role in the market | Demand characteristics |
|---|---|---|
| Single-Band | Single-Band represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
| Dual-Band | Dual-Band represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
| Multi-Band | Multi-Band represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
Segment Analysis: By Application
By application, the 4G RRU market is segmented into Macrocell Base Station, Smallcell Base Station. Macrocell base stations dominate because national LTE coverage uses large installed radio networks, while small cells support indoor, hotspot and dense urban coverage. Small-cell demand is more selective as operators increasingly deploy integrated 4G/5G radios. Purchasing decisions vary by performance requirement, qualification burden, integration complexity and lifecycle economics, so suppliers compete on application fit rather than on a single technical specification.
| Application | Role in the market | Demand characteristics |
|---|---|---|
| Macrocell Base Station | Macrocell Base Station creates demand when the underlying system requires the market’s core function at production scale. Procurement is normally tied to platform launches, equipment upgrades, capacity expansion or replacement cycles. | Buyers evaluate reliability, qualification time, integration cost and vendor support alongside unit economics. Adoption accelerates when the solution removes a system bottleneck or supports a new performance tier without creating disproportionate redesign risk. |
| Smallcell Base Station | Smallcell Base Station creates demand when the underlying system requires the market’s core function at production scale. Procurement is normally tied to platform launches, equipment upgrades, capacity expansion or replacement cycles. | Buyers evaluate reliability, qualification time, integration cost and vendor support alongside unit economics. Adoption accelerates when the solution removes a system bottleneck or supports a new performance tier without creating disproportionate redesign risk. |
Segment Analysis: By Deployment Environment
By deployment environment, the 4G RRU market is segmented into Urban, Suburban, Rural & Remote. Urban markets emphasize capacity and compact multi-band hardware, while rural deployments prioritize coverage, power efficiency and operating cost across low-traffic sites. Purchasing decisions vary by performance requirement, qualification burden, integration complexity and lifecycle economics, so suppliers compete on application fit rather than on a single technical specification.
| Deployment Environment | Role in the market | Demand characteristics |
|---|---|---|
| Urban | Urban represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
| Suburban | Suburban represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
| Rural & Remote | Rural & Remote represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
Regional Analysis
Asia Pacific leads the 4g rru market in 2025, while regional growth patterns differ according to manufacturing concentration, customer investment cycles, regulation, product mix and supply-chain access. The most important regional distinction is not simply market size; it is the mechanism that converts local investment and end-market demand into qualified purchases.
How does regional demand differ across the 4g rru market?
Regional demand for 4g rru is structurally uneven because manufacturing assets, design centers, downstream customers and qualification ecosystems are not distributed evenly. Asia Pacific typically has the deepest electronics manufacturing base, North America combines technology development with capital investment, Europe emphasizes reliability and industrial requirements, and emerging regions are more dependent on imported systems. These differences influence vendor selection, inventory policy, service expectations and the pace at which new technologies are adopted.
| Region | Market position | Growth outlook | Demand profile | Supplier-selection gate |
|---|---|---|---|---|
| Asia Pacific | Largest | Stable to declining | Installed-base modernization and coverage led | Energy efficiency and total site cost |
| North America | Mature replacement market | Declining | Modernization and spectrum refarming led | Compatibility and site economics |
| Europe | Mature | Declining slowly | Energy efficiency and network consolidation led | OPEX reduction and spectrum strategy |
| South America | Growth market | Moderate | Coverage expansion led | Capex and vendor financing |
| Middle East & Africa | Expansion market | Moderate | Coverage and rural connectivity led | Power and deployment economics |
Detailed Regional Blocks
Competitive Landscape
Competition in the 4g rru market is determined by technical qualification, manufacturing consistency, customer relationships and the ability to support product lifecycles. Price matters, but it rarely overrides reliability, integration effort or switching cost once a supplier has been designed into a production platform.
The competitive field includes Datang, Ericsson, Fujitsu, Huawei Technologies, NEC, Nokia Networks, alongside other specialized suppliers. Market share can shift when a vendor gains access to a new platform, expands qualified capacity or introduces a technology that materially improves system performance. Because customer validation can be lengthy, incumbent suppliers often benefit from continuity, while challengers need a clear technical or supply-chain advantage to displace an approved source.
Competitive strategy is increasingly multi-dimensional. Leading suppliers invest in process or product development, application engineering and regional support at the same time, while customers seek second-source options where technically feasible. This creates a market in which differentiation is sustained through documented performance, manufacturing yield, quality systems, responsiveness and the ability to support future roadmap transitions without forcing unnecessary redesigns.
| Company | Competitive position | Primary basis of competition |
|---|---|---|
| Datang | Established global / strategic supplier | Competes through product capability, qualification, account access and supply execution. |
| Ericsson | Established global / strategic supplier | Competes through product capability, qualification, account access and supply execution. |
| Fujitsu | Established global / strategic supplier | Competes through product capability, qualification, account access and supply execution. |
| Huawei Technologies | Specialist / regional competitor | Competes through product capability, qualification, account access and supply execution. |
| NEC | Specialist / regional competitor | Competes through product capability, qualification, account access and supply execution. |
| Nokia Networks | Specialist / regional competitor | Competes through product capability, qualification, account access and supply execution. |
| Samsung | Focused challenger / niche participant | Competes through product capability, qualification, account access and supply execution. |
| ZTE | Focused challenger / niche participant | Competes through product capability, qualification, account access and supply execution. |
| GrenTech | Focused challenger / niche participant | Competes through product capability, qualification, account access and supply execution. |
Production Capacity Analysis
RRU manufacturing depends on RF power amplifiers, filters, FPGAs or SoCs, power electronics, thermal design and outdoor-rated mechanical assembly. Modern radios increasingly consolidate bands and support software-defined operation, so manufacturing complexity has shifted from unit count toward higher integration and tighter RF calibration.
Asia remains the largest manufacturing base, with Huawei, ZTE, Samsung and supply-chain partners operating at scale, while Ericsson and Nokia maintain global production and integration networks. Replacement demand favors vendors that can supply radios compatible with existing baseband and network-management systems.
Capacity should therefore be evaluated on a qualified-output basis rather than as nominal installed capability. A supplier may possess equipment or production lines that appear suitable but still require customer-specific validation, process tuning, test correlation or upstream material qualification. This distinction becomes especially important during demand spikes, when headline capacity can overstate the volume that is immediately available for a particular application, technology generation or reliability class.
Market Dynamics
The 4g rru market is being shaped by rising performance requirements and technology transitions on the demand side, while qualification complexity, supply concentration and cost discipline constrain the pace of adoption. The balance of these forces favors suppliers that can solve a measurable system problem without increasing integration risk.
Demand expansion is not uniform across all product variants or customer groups. New technology creates attractive design opportunities, but buyers typically require a clear economic or performance case before changing a qualified architecture. At the same time, supply-chain localization, capacity investment and tighter quality requirements are changing procurement behavior. As a result, growth is likely to concentrate around applications where performance upgrades, manufacturing scale and lifecycle value reinforce one another.
Market Drivers
Four forces provide the strongest support for demand in the 4g rru market: performance-driven technology upgrades, expansion of relevant downstream applications, investment in manufacturing or infrastructure, and the need for more resilient supply. Their importance varies by segment, but each creates a direct reason for customers to qualify or purchase additional solutions.
| Driver | Impact | Commercial mechanism |
|---|---|---|
| Large installed LTE networks require replacement and maintenance | High | Radios age, fail or become inefficient, creating ongoing replacement demand even after greenfield LTE rollout slows. |
| Emerging markets continue 4G coverage expansion | High | Many regions still use LTE as the most economical path to broad mobile broadband and rural connectivity. |
| Multi-band radios reduce total site cost | Medium-High | Consolidation lowers tower loading, cabling, energy use and maintenance compared with multiple legacy single-band units. |
| LTE and NR coexistence extends the 4G lifecycle | Medium-High | Operators need equipment that can preserve LTE service while gradually shifting traffic and spectrum toward 5G. |
Large installed LTE networks require replacement and maintenance
Radios age, fail or become inefficient, creating ongoing replacement demand even after greenfield LTE rollout slows. The commercial effect is strongest where customers can link the technology change to higher throughput, lower power, improved reliability, reduced lifecycle cost or access to a new end-market requirement.
Emerging markets continue 4G coverage expansion
Many regions still use LTE as the most economical path to broad mobile broadband and rural connectivity. The commercial effect is strongest where customers can link the technology change to higher throughput, lower power, improved reliability, reduced lifecycle cost or access to a new end-market requirement.
Multi-band radios reduce total site cost
Consolidation lowers tower loading, cabling, energy use and maintenance compared with multiple legacy single-band units. The commercial effect is strongest where customers can link the technology change to higher throughput, lower power, improved reliability, reduced lifecycle cost or access to a new end-market requirement.
LTE and NR coexistence extends the 4G lifecycle
Operators need equipment that can preserve LTE service while gradually shifting traffic and spectrum toward 5G. The commercial effect is strongest where customers can link the technology change to higher throughput, lower power, improved reliability, reduced lifecycle cost or access to a new end-market requirement.
Market Restraints
Growth is moderated by qualification burden, cyclical purchasing, technology substitution and supply-chain risk. These restraints do not eliminate demand, but they can extend sales cycles, limit supplier switching and reduce the speed at which technically superior solutions convert into production revenue.
| Restraint | Impact | Commercial consequence |
|---|---|---|
| 5G absorbs most incremental radio capital spending | High | Operators prioritize NR for new capacity, reducing standalone 4G RRU growth. |
| Spectrum refarming reduces dedicated LTE bandwidth | High | As spectrum moves to 5G, some operators can reduce the number of LTE-only radio chains. |
| Mature coverage limits greenfield demand | Medium | In developed markets, nearly all population centers already have LTE coverage, so replacement rather than expansion drives sales. |
| Vendor consolidation increases pricing pressure | Medium | A small group of global RAN suppliers competes aggressively for large operator contracts and modernization programs. |
5G absorbs most incremental radio capital spending
Operators prioritize NR for new capacity, reducing standalone 4G RRU growth. Suppliers can mitigate part of this pressure through stronger qualification support, transparent lifecycle planning, dual-source strategies and better alignment between product roadmaps and customer production schedules.
Spectrum refarming reduces dedicated LTE bandwidth
As spectrum moves to 5G, some operators can reduce the number of LTE-only radio chains. Suppliers can mitigate part of this pressure through stronger qualification support, transparent lifecycle planning, dual-source strategies and better alignment between product roadmaps and customer production schedules.
Mature coverage limits greenfield demand
In developed markets, nearly all population centers already have LTE coverage, so replacement rather than expansion drives sales. Suppliers can mitigate part of this pressure through stronger qualification support, transparent lifecycle planning, dual-source strategies and better alignment between product roadmaps and customer production schedules.
Vendor consolidation increases pricing pressure
A small group of global RAN suppliers competes aggressively for large operator contracts and modernization programs. Suppliers can mitigate part of this pressure through stronger qualification support, transparent lifecycle planning, dual-source strategies and better alignment between product roadmaps and customer production schedules.
Market Opportunities
The most attractive opportunities in the 4g rru market occur where a technology transition creates measurable value and where suppliers can enter before the customer architecture is locked. Early engagement, application-specific engineering and credible supply planning can convert these windows into durable design positions.
Dual-band LTE/NR modernization
Radios supporting both technologies can replace older LTE units while preparing sites for 5G. The opportunity is strongest for suppliers that can demonstrate performance with production-relevant data, provide engineering support during qualification and maintain a roadmap that gives customers confidence in long-term availability.
Rural and emerging-market coverage
4G remains cost-effective for broad coverage where premium 5G capacity is not yet required. The opportunity is strongest for suppliers that can demonstrate performance with production-relevant data, provide engineering support during qualification and maintain a roadmap that gives customers confidence in long-term availability.
Energy-efficiency upgrades
Replacing older RRUs can lower site power consumption and improve operator OPEX. The opportunity is strongest for suppliers that can demonstrate performance with production-relevant data, provide engineering support during qualification and maintain a roadmap that gives customers confidence in long-term availability.
Private and industrial LTE
Dedicated 4G networks remain useful in utilities, transport and industrial sites where device ecosystems are mature. The opportunity is strongest for suppliers that can demonstrate performance with production-relevant data, provide engineering support during qualification and maintain a roadmap that gives customers confidence in long-term availability.
Supply Chain Analysis
RF semiconductors and filters
Power amplifiers, transceivers, filters and timing components create the core radio-frequency signal chain. Value capture at this stage depends on quality consistency, technical differentiation and the difficulty of substitution. Bottlenecks can propagate downstream when qualification or material compatibility prevents customers from shifting quickly to an alternative supplier.
RRU design and assembly
Vendors integrate RF, digital fronthaul, power and thermal hardware into outdoor radio units. Value capture at this stage depends on quality consistency, technical differentiation and the difficulty of substitution. Bottlenecks can propagate downstream when qualification or material compatibility prevents customers from shifting quickly to an alternative supplier.
Baseband and software integration
RRUs connect to LTE or multi-standard basebands and network-management systems. Value capture at this stage depends on quality consistency, technical differentiation and the difficulty of substitution. Bottlenecks can propagate downstream when qualification or material compatibility prevents customers from shifting quickly to an alternative supplier.
Operator deployment and maintenance
Telecom operators install radios on towers, rooftops, poles and small-cell sites and manage them over multi-year lifecycles. Value capture at this stage depends on quality consistency, technical differentiation and the difficulty of substitution. Bottlenecks can propagate downstream when qualification or material compatibility prevents customers from shifting quickly to an alternative supplier.
Recent Developments
Recent developments show how technology roadmaps, manufacturing investment and standards are changing the competitive requirements of the 4g rru market. The entries below are selected for their direct relevance to product capability, capacity, qualification or downstream adoption rather than for general corporate activity.
Nokia’s current AirScale macro remote-radio portfolio emphasizes compact, energy-efficient units and a new Doksuri generation with more than 30% greater power efficiency and lower weight, reinforcing replacement demand around total site economics. Source
Ericsson’s Radio 4438 supports both LTE and NR in a dual-band FDD radio designed to replace two single-band units, demonstrating how 4G functionality is being retained inside more integrated modernization hardware. Source
Samsung continued to position baseband hardware for simultaneous LTE and NR operation with backward compatibility, allowing operators to evolve existing infrastructure while protecting prior LTE investment. Source
Report Scope & Segmentation
| Report attribute | Coverage |
|---|---|
| Market | 4G RRU |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| 2025 Market Size | USD 3.65 billion |
| 2026 Estimated Size | USD 3.61 billion |
| 2034 Forecast Size | USD 3.33 billion |
| CAGR (2026–2034) | -1.0% |
| Largest Market in 2025 | Asia Pacific |
| By Type | Desktop, Portable |
| By Application | Macrocell Base Station, Smallcell Base Station |
| By Frequency Architecture | Single-Band, Dual-Band, Multi-Band |
| By Deployment Environment | Urban, Suburban, Rural & Remote |
| Companies Profiled | Datang, Ericsson, Fujitsu, Huawei Technologies, NEC, Nokia Networks, Samsung, ZTE, GrenTech |
Frequently Asked Questions
What was the 4g rru market size in 2025?
The global 4g rru market was valued at USD 3.65 billion in 2025. The 2025 value is the base-year reference used throughout this overview and provides the starting point for comparing the 2026 estimate and the 2034 forecast.
What is the projected 4g rru market size in 2034?
The global market is projected to reach USD 3.33 billion by 2034. The forecast reflects the interaction of downstream adoption, technology transitions, production investment and the qualification requirements that shape commercial conversion across the market.
What is the CAGR of the 4g rru market from 2026 to 2034?
The 4g rru market is expected to expand at a -1.0% CAGR during 2026–2034. Growth will not be uniform across every product or region because customer qualification, capital cycles, supply constraints and application-specific performance requirements differ materially.
Which region is the largest 4g rru market?
Asia Pacific is the largest regional market in 2025. Its position is supported by the concentration of relevant manufacturing, customers, technology ecosystems and downstream demand, although the precise commercial mechanism differs by country and application.
How is the 4g rru market segmented by type?
By type, the market is segmented into Desktop, Portable. These categories address different performance, cost and integration requirements, so supplier selection depends on application fit, qualification history and lifecycle economics rather than a single specification.
What are the main applications for 4g rru?
By application, the market covers Macrocell Base Station, Smallcell Base Station. Demand in each application is linked to platform launches, capacity expansion, equipment replacement and the degree to which the technology improves system performance or manufacturing economics.
What are the principal growth drivers for the 4g rru market?
Key drivers include large installed lte networks require replacement and maintenance and emerging markets continue 4g coverage expansion. These forces increase demand when customers can translate technical improvements into higher performance, lower cost, greater reliability or access to new applications.
What are the main restraints in the 4g rru market?
Important restraints include 5g absorbs most incremental radio capital spending and spectrum refarming reduces dedicated lte bandwidth. The resulting qualification burden, purchasing cyclicality and technology risk can extend sales cycles and limit rapid supplier substitution even when new solutions offer clear technical advantages.
Which companies participate in the 4g rru market?
Companies profiled in this market include Datang, Ericsson, Fujitsu, Huawei Technologies, NEC, Nokia Networks, Samsung, ZTE. Competition centers on qualification, product or process performance, manufacturing consistency, customer support and the ability to maintain supply across the required product lifecycle.
What should buyers evaluate when selecting a 4g rru supplier?
Buyers should evaluate demonstrated performance, qualification history, manufacturing consistency, lifecycle support, supply resilience and integration cost. A technically strong product can still face adoption barriers if it increases redesign risk, lacks regional support or cannot meet the customer’s production and quality requirements.
Research Sources & Evidence Base
View research sources used for this overview.
- Ericsson. Radio 4438 — Dual-band remote radio supporting LTE and NR, with site-consolidation benefits.
- Nokia. AirScale Macro Remote Radio Heads — Current macro-radio efficiency, weight and AI-RAN-ready modernization context.
- Samsung Networks. Baseband — LTE-NR simultaneous operation and backward compatibility for network evolution.
- Huawei. Building Energy-efficient 5G Networks — Multi-band, multi-RAT RRU power optimization and field energy-saving context.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF