
Key Statistics
Key Takeaways
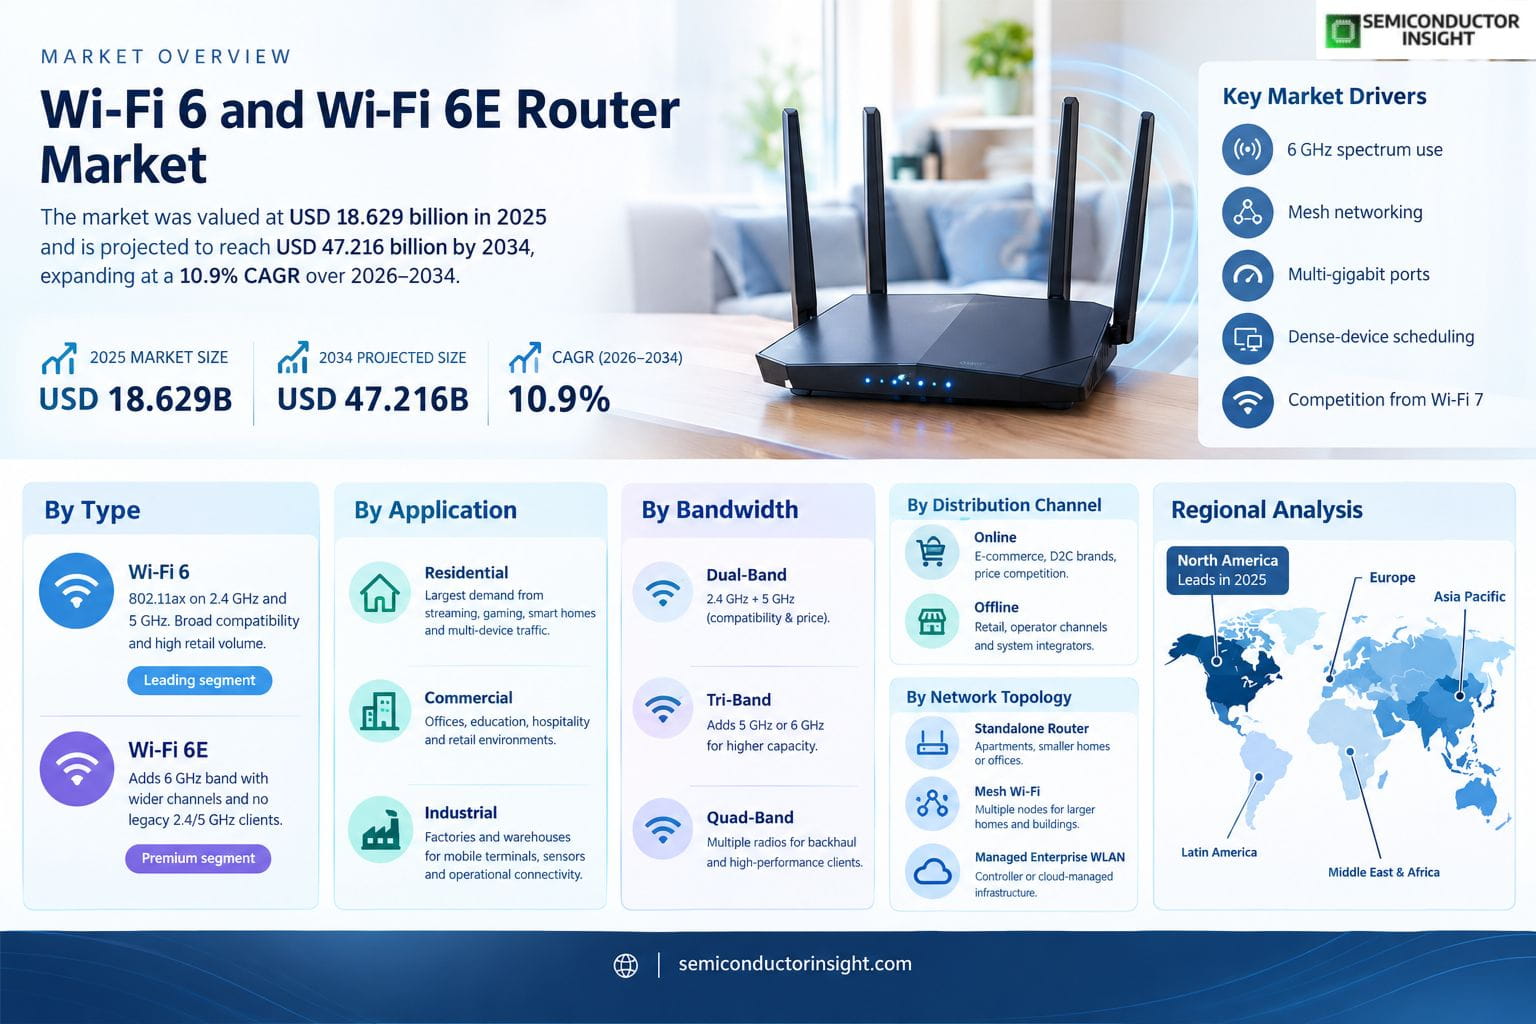
- Market size and growth: the market is valued at USD 18.629 billion in 2025 and is projected to reach USD 47.216 billion by 2034, representing a 10.9% CAGR over 2026–2034.
- Wi-Fi 6 leads by type because dual-band 802.11ax routers retain the broadest installed client compatibility and retail volume while Wi-Fi 6E remains a premium 6 GHz extension.
- Residential leads application demand because households combine streaming, gaming, work-from-home, smart-home and multi-device traffic, creating the largest unit demand for next-generation routers and mesh systems.
- North America is the largest regional market, while Asia Pacific has the strongest incremental growth profile.
- Primary driver: fiber broadband, streaming, gaming, smart homes and dense enterprise device populations continue to increase demand for higher-capacity 802.11ax networking
- Principal restraint: 6 GHz benefits require compatible clients and country-specific spectrum support, while Wi-Fi 7 is already competing for premium replacement budgets
Market Overview
The Wi-Fi 6 and Wi-Fi 6E Router Market was valued at USD 18.629 billion in 2025 and is projected to reach USD 47.216 billion by 2034, expanding at a 10.9% CAGR over 2026–2034. North America leads in 2025, while the market is being reshaped by 6 GHz spectrum use, mesh networking, multi-gigabit ports, dense-device scheduling and competition from Wi-Fi 7.. For Wi-Fi 6 and Wi-Fi 6E Router suppliers, the commercial implication is that electrical performance must translate into measurable safety, connectivity, lifecycle or integration value at the system level.
Wi-Fi 6 uses the IEEE 802.11ax generation across 2.4 GHz and 5 GHz, while Wi-Fi 6E extends the same technology into the 6 GHz band. The U.S. FCC opened 1,200 MHz from 5.925 to 7.125 GHz for unlicensed use in 2020, creating the regulatory foundation for Wi-Fi 6E devices. ASUS and NETGEAR both describe 6 GHz as supporting up to seven additional 160 MHz channels in markets where the full band is available. This additional spectrum reduces contention and allows compatible clients to avoid legacy-device traffic on older bands.
Router platforms increasingly combine multiple radios, high stream counts and multi-gigabit wired interfaces. Qualcomm’s current Dragonwing NPro 6E platform supports up to 16 spatial streams, simultaneous 5 GHz and 6 GHz operation, 160 MHz channels and peak platform speeds up to 10.8 Gbps, while TP-Link’s Archer AXE75 uses a tri-band 6 GHz architecture with a quad-core processor. These designs show how the market is moving beyond a simple radio-standard upgrade toward complete home and enterprise gateways that coordinate mesh backhaul, security and many simultaneous devices.
Security and operational maturity are also important. NETGEAR notes that WPA3 is mandatory for Wi-Fi 6-certified devices operating in 6 GHz, while Cisco’s current enterprise guidance covers migration to 6 GHz and Automated Frequency Coordination for standard-power access points. These ecosystem requirements matter because 6 GHz performance depends on compatible clients, regional spectrum rules and network design. Wi-Fi 6 therefore remains the high-volume baseline, while Wi-Fi 6E addresses premium residential, gaming, mesh and enterprise environments that can benefit from cleaner 6 GHz spectrum.
Segment Analysis: By Type
By type, the market is segmented into Wi-Fi 6, Wi-Fi 6E. Wi-Fi 6 holds the leading position because dual-band 802.11ax routers retain the broadest installed client compatibility and retail volume while Wi-Fi 6E remains a premium 6 GHz extension. Procurement decisions in the Wi-Fi 6 and Wi-Fi 6E Router market therefore consider qualification evidence, integration effort, long-term supply and technical support alongside component or equipment price. As adoption broadens, vendors that combine repeatable manufacturing with application engineering and documented reliability should be better positioned for long production programs and platform design wins.
| Type | Function / role | Market position |
|---|---|---|
| Wi-Fi 6 | 802.11ax operation on 2.4 GHz and 5 GHz with OFDMA, MU-MIMO and dense-device efficiency improvements. | Leading volume segment because it supports a broad installed client base without requiring 6 GHz compatibility. |
| Wi-Fi 6E | Wi-Fi 6 extended into 6 GHz with additional wide channels and no legacy 2.4/5 GHz clients on that band. | Premium segment offering lower congestion and stronger 160 MHz channel availability for compatible devices. |
Commercial implications by type
Wi-Fi 6 remains the largest type because it provides most 802.11ax efficiency gains while maintaining compatibility with the enormous installed base of 2.4 GHz and 5 GHz clients. Wi-Fi 6E adds meaningful spectrum headroom, but every 6 GHz benefit requires both a compatible router and compatible client. ASUS explicitly notes that older Wi-Fi 5 or Wi-Fi 6 devices can still use the router’s 2.4 GHz or 5 GHz radios but cannot connect to 6 GHz. This creates a gradual premium migration rather than an immediate replacement cycle.
Segment Analysis: By Application
By application, the market includes Residential, Commercial, Industrial. Residential leads demand because households combine streaming, gaming, work-from-home, smart-home and multi-device traffic, creating the largest unit demand for next-generation routers and mesh systems. As adoption broadens, vendors that combine repeatable manufacturing with application engineering and documented reliability should be better positioned for long production programs and platform design wins. This makes interoperability, validation and field support increasingly important because requalification or network redesign can cost more than the incremental saving from a lower-priced component.
| Application | Demand characteristics |
|---|---|
| Residential | Largest application across broadband gateways, retail routers, mesh systems, gaming and smart-home networking. |
| Commercial | Offices, education, hospitality and retail environments use Wi-Fi 6/6E for dense client populations and collaboration traffic. |
| Industrial | Factories and warehouses adopt next-generation Wi-Fi selectively for mobile terminals, sensors, video and operational connectivity. |
By Bandwidth
| Bandwidth | Commercial relevance |
|---|---|
| Dual-Band | 2.4 GHz and 5 GHz Wi-Fi 6 products balance compatibility and price for mainstream users. |
| Tri-Band | Adds either a second 5 GHz radio or 6 GHz radio to improve capacity and mesh backhaul. |
| Quad-Band | Premium mesh systems use multiple radios to isolate backhaul and high-performance clients. |
By Distribution Channel
| Distribution Channel | Commercial relevance |
|---|---|
| Online | E-commerce supports broad router comparison, direct-to-consumer brands and frequent price competition. |
| Offline | Retail, operator channels and system integrators remain important for guided purchases and bundled broadband deployments. |
By Network Topology
| Network Topology | Commercial relevance |
|---|---|
| Standalone Router | Single gateway serves apartments and smaller homes or offices. |
| Mesh Wi-Fi | Multiple nodes coordinate coverage across larger homes and buildings. |
| Managed Enterprise WLAN | Controller or cloud-managed access infrastructure serves commercial environments. |
Regional Analysis
North America leads the market because the report identifies the United States with 38% of 2024 global demand, supported by early 6 GHz regulation, high broadband penetration, premium home networking and enterprise upgrades. Asia Pacific has the strongest growth profile through China, India, Japan, South Korea and Southeast Asia combine rising broadband speeds, dense urban device counts and large networking-equipment supply chains. This makes interoperability, validation and field support increasingly important because requalification or network redesign can cost more than the incremental saving from a lower-priced component.
How does regional demand differ across this market?
North America leads current revenue because the United States opened the 6 GHz band early and has strong premium router, mesh and enterprise adoption. Asia Pacific has the fastest growth through expanding fiber broadband, smart homes, gaming and regional hardware manufacturing. Europe is a substantial market but spectrum and deployment conditions differ by country, while South America and the Middle East & Africa are more price-sensitive and broadband-led. Across regions, Wi-Fi 6 remains the volume platform, while Wi-Fi 6E adoption depends on 6 GHz regulation, client compatibility and premium bandwidth needs.
| Region | Position | Growth outlook | Demand profile | Supplier selection |
|---|---|---|---|---|
| North America | Largest | Strong | Premium home and enterprise networking | Spectrum access, security, multi-gig ports |
| Asia Pacific | Second | Fastest | Broadband, gaming and device scale | Price-performance, local channels, coverage |
| Europe | Third | Moderate | Consumer broadband and enterprise WLAN | Regulatory compliance, security, energy |
| South America | Smaller | Moderate | Broadband expansion and home Wi-Fi | Price, coverage, channel availability |
| Middle East & Africa | Emerging | Strong | New fiber and smart infrastructure | Coverage, heat, support, cost |
Competitive Landscape
Competition spans retail router brands, broadband-gateway suppliers and chipset vendors, with differentiation centered on radio count, mesh software, security, multi-gigabit Ethernet and user experience. For Wi-Fi 6 and Wi-Fi 6E Router suppliers, the commercial implication is that electrical performance must translate into measurable safety, connectivity, lifecycle or integration value at the system level. Procurement decisions in the Wi-Fi 6 and Wi-Fi 6E Router market therefore consider qualification evidence, integration effort, long-term supply and technical support alongside component or equipment price.
TP-Link competes across mainstream and premium Wi-Fi 6E with products such as Archer AXE75 and AXE95, which combine tri-band radios, 6 GHz support and consumer security software. NETGEAR positions Nighthawk and Orbi 6E systems at the premium end with multi-gigabit speeds and dedicated mesh backhaul options, while ASUS targets gaming and enthusiast users with high-stream-count routers. These vendors compete not only on peak wireless rate but also on firmware quality, mesh roaming, parental control, security subscriptions and the reliability of many simultaneous client connections.
Qualcomm’s Dragonwing NPro 6E platform illustrates competition at the silicon layer. The current platform supports up to 16 spatial streams, simultaneous 5 GHz and 6 GHz operation and peak platform speeds up to 10.8 Gbps, giving router OEMs a common architecture for premium gateways and enterprise access points. Chipset capability influences the number of radios, client capacity, 160 MHz performance and mesh backhaul. Router brands can differentiate through antennas and software, but the underlying SoC and RF platform strongly shape achievable performance, thermal design and product cost.
Cisco represents the managed enterprise side, where Wi-Fi 6E is evaluated through network design, security and spectrum coordination rather than consumer peak speed. Its 2026 6 GHz guidance addresses migration and Automated Frequency Coordination for standard-power access points, while current Catalyst access points support tri-radio architectures. Enterprise competition therefore depends on cloud management, roaming, telemetry and regulatory automation in addition to radio performance. This segment can sustain higher value per access point but requires longer qualification and support cycles than retail routers sold through online channels.
| Competitive tier | Representative participants | Competitive focus |
|---|---|---|
| Consumer router brands | TP-Link, NETGEAR, ASUS, D-Link, Xiaomi, Tenda | Retail, gaming, mesh and home broadband |
| Enterprise WLAN vendors | Cisco, HPE Aruba and managed-network suppliers | Security, cloud management, roaming and enterprise lifecycle |
| Chipset platforms | Qualcomm, Broadcom and other Wi-Fi SoC suppliers | Radio streams, 6 GHz support, CPU, acceleration and reference designs |
Companies Profiled
TP-Link, NETGEAR, ASUS, D-Link, Huawei, Xiaomi, Tenda, Cisco. The set reflects companies directly active in products, process technology, manufacturing or supporting application ecosystems rather than an evaluative ranking. Procurement decisions in the Wi-Fi 6 and Wi-Fi 6E Router market therefore consider qualification evidence, integration effort, long-term supply and technical support alongside component or equipment price. As adoption broadens, vendors that combine repeatable manufacturing with application engineering and documented reliability should be better positioned for long production programs and platform design wins.
Production Capacity Analysis
Router supply depends on Wi-Fi SoCs, RF front ends, antennas, memory, Ethernet PHYs, power management, PCB assembly and firmware release capability, with product cycles often moving faster than enterprise qualification cycles. For Wi-Fi 6 and Wi-Fi 6E Router suppliers, the commercial implication is that electrical performance must translate into measurable safety, connectivity, lifecycle or integration value at the system level. Procurement decisions in the Wi-Fi 6 and Wi-Fi 6E Router market therefore consider qualification evidence, integration effort, long-term supply and technical support alongside component or equipment price.
High-volume router manufacturing is concentrated in Asian electronics supply chains that can assemble complex multi-radio PCBs at low cost. Wi-Fi 6E raises RF complexity because tri-band systems need additional filters, antennas and front-end components for 6 GHz, while premium designs add 2.5 GbE or 10 GbE ports and faster processors. Thermal design also becomes more important as stream count and CPU performance rise. Manufacturers therefore need coordinated sourcing across Wi-Fi SoCs, RF components, memory and Ethernet devices, making platform availability a direct constraint on launch timing.
Software capacity is equally important because routers require years of firmware updates for security, mesh behavior and client interoperability. Hardware specifications can be similar across brands, yet user experience differs materially through channel selection, roaming, parental controls, cloud management and vulnerability response. Enterprise products add regulatory features such as AFC and more complex telemetry. As Wi-Fi 7 absorbs top-tier engineering resources, vendors must decide how long to maintain Wi-Fi 6/6E firmware and product lines, creating a lifecycle-management challenge even when physical manufacturing capacity remains abundant.
Market Dynamics
The market is in a transition phase where Wi-Fi 6 remains the volume standard, Wi-Fi 6E monetizes 6 GHz spectrum in premium segments, and Wi-Fi 7 increasingly captures the newest high-end replacement demand. For Wi-Fi 6 and Wi-Fi 6E Router suppliers, the commercial implication is that electrical performance must translate into measurable safety, connectivity, lifecycle or integration value at the system level. Procurement decisions in the Wi-Fi 6 and Wi-Fi 6E Router market therefore consider qualification evidence, integration effort, long-term supply and technical support alongside component or equipment price.
Wi-Fi 6 solved dense-device efficiency across existing 2.4 GHz and 5 GHz bands, while 6E added a cleaner 6 GHz band with more wide channels. That benefit is meaningful only when clients also support 6 GHz, so adoption follows the installed base of laptops, phones and adapters. At the same time, Wi-Fi 7 uses the same 6 GHz spectrum while adding new features, which can cause premium buyers to skip a 6E-only upgrade. Vendors therefore maintain Wi-Fi 6 for mainstream value and use 6E selectively where product economics remain compelling.
Market Drivers
Drivers Impact Analysis
| Driver | Impact | Commercial mechanism |
|---|---|---|
| High-speed broadband upgrades | High | Fiber and multi-gigabit cable connections expose weaknesses in older home routers because the Wi-Fi link can become the bottleneck even when the internet service is fast. Wi-Fi 6 improves spectral efficiency and supports 160 MHz channels, while Wi-Fi 6E creates more clean wide channels in the 6 GHz band. TP-Link, NETGEAR and ASUS all market multi-gigabit 6E routers around this use case. As broadband tiers rise, households increasingly replace routers to preserve more of the subscribed speed across wireless devices. |
| Dense device environments | High | Homes and offices now connect phones, laptops, TVs, cameras, speakers, appliances and IoT devices simultaneously. Wi-Fi 6 introduces OFDMA and improved multi-user scheduling to serve many clients more efficiently than older standards, while 6E adds spectrum that is free from legacy Wi-Fi devices. Qualcomm’s NPro platforms emphasize simultaneous multi-band operation and high client counts, illustrating the chipset response to density. This matters commercially because reliability under load is increasingly more important to users than the peak link rate shown on a product box. |
| Mesh networking | Medium | Larger homes and small businesses increasingly use mesh systems to extend coverage without manual roaming between access points. A tri-band Wi-Fi 6E architecture can dedicate 6 GHz or another high-capacity link to node backhaul, reducing competition with client traffic when nodes have suitable placement. NETGEAR and TP-Link both maintain mesh-oriented product families, and Qualcomm positions 6 GHz as useful for multi-gigabit wireless backhaul. Mesh therefore raises router unit value because customers may buy two or three coordinated nodes rather than one standalone gateway. |
| Enterprise 6 GHz adoption | Medium | Offices, campuses and venues can use 6 GHz to reduce contention and create wider channels for high-throughput applications, provided local regulation and compatible clients are available. Cisco’s current guidance covers migration to 6 GHz, Wi-Fi 7 and AFC, showing that enterprise deployment is moving from experimental toward operational planning. The benefit is strongest in dense environments with managed device fleets. Enterprise growth supports higher-margin access equipment, but replacement cycles are slower because organizations must validate security, roaming, cabling, PoE and controller compatibility. |
High-speed broadband upgrades
Fiber and multi-gigabit cable connections expose weaknesses in older home routers because the Wi-Fi link can become the bottleneck even when the internet service is fast. Wi-Fi 6 improves spectral efficiency and supports 160 MHz channels, while Wi-Fi 6E creates more clean wide channels in the 6 GHz band. TP-Link, NETGEAR and ASUS all market multi-gigabit 6E routers around this use case. As broadband tiers rise, households increasingly replace routers to preserve more of the subscribed speed across wireless devices.
Dense device environments
Homes and offices now connect phones, laptops, TVs, cameras, speakers, appliances and IoT devices simultaneously. Wi-Fi 6 introduces OFDMA and improved multi-user scheduling to serve many clients more efficiently than older standards, while 6E adds spectrum that is free from legacy Wi-Fi devices. Qualcomm’s NPro platforms emphasize simultaneous multi-band operation and high client counts, illustrating the chipset response to density. This matters commercially because reliability under load is increasingly more important to users than the peak link rate shown on a product box.
Mesh networking
Larger homes and small businesses increasingly use mesh systems to extend coverage without manual roaming between access points. A tri-band Wi-Fi 6E architecture can dedicate 6 GHz or another high-capacity link to node backhaul, reducing competition with client traffic when nodes have suitable placement. NETGEAR and TP-Link both maintain mesh-oriented product families, and Qualcomm positions 6 GHz as useful for multi-gigabit wireless backhaul. Mesh therefore raises router unit value because customers may buy two or three coordinated nodes rather than one standalone gateway.
Enterprise 6 GHz adoption
Offices, campuses and venues can use 6 GHz to reduce contention and create wider channels for high-throughput applications, provided local regulation and compatible clients are available. Cisco’s current guidance covers migration to 6 GHz, Wi-Fi 7 and AFC, showing that enterprise deployment is moving from experimental toward operational planning. The benefit is strongest in dense environments with managed device fleets. Enterprise growth supports higher-margin access equipment, but replacement cycles are slower because organizations must validate security, roaming, cabling, PoE and controller compatibility.
Market Restraints
Restraints Impact Analysis
| Restraint | Impact | Commercial mechanism |
|---|---|---|
| Client compatibility | High | A Wi-Fi 6E router can serve older devices on 2.4 GHz and 5 GHz, but only 6E-capable clients can use the 6 GHz radio. ASUS explicitly documents this distinction, and TP-Link provides similar compatibility guidance. That limits immediate utilization because a household may own only one or two 6 GHz-capable devices. Buyers comparing upgrade options may therefore choose a less expensive Wi-Fi 6 router or move directly to Wi-Fi 7, reducing the standalone replacement pull for 6E-only products as the market matures. |
| Regional spectrum variation | High | The 6 GHz advantage is shaped by national regulation, and not every country makes the same amount of spectrum or power level available. U.S. rules opened 1,200 MHz, while other markets may provide narrower allocations or different operating conditions. Router vendors must maintain region-specific firmware, channel lists and certification, which fragments product planning. Enterprise standard-power operation can also require AFC coordination. These differences make Wi-Fi 6 easier to sell globally because 2.4 GHz and 5 GHz support is already mature and broadly harmonized. |
| Wi-Fi 7 substitution | High | Wi-Fi 7 is now commercially available and also uses the 6 GHz band, adding features that attract premium buyers who might otherwise have purchased high-end Wi-Fi 6E equipment. Cisco’s current comparison material positions Wi-Fi 7 as the newest standard, and router brands are rapidly expanding Wi-Fi 7 portfolios. This creates a shorter premium lifecycle for 6E. Wi-Fi 6 remains protected by lower cost and broad compatibility, but 6E risks being squeezed between mainstream Wi-Fi 6 and feature-rich Wi-Fi 7 in new retail launches. |
| Hardware and thermal cost | Medium | Tri-band 6E routers require an additional 6 GHz radio path, more antennas or RF components, faster processors and often multi-gigabit Ethernet ports. Premium SoCs such as Qualcomm’s NPro 6E support many spatial streams and high peak throughput, but this capability increases BOM, power consumption and cooling needs. Vendors must balance radio count against retail price and enclosure design. In cost-sensitive markets, a well-optimized dual-band Wi-Fi 6 router may deliver sufficient practical performance at substantially lower hardware cost. |
Client compatibility
A Wi-Fi 6E router can serve older devices on 2.4 GHz and 5 GHz, but only 6E-capable clients can use the 6 GHz radio. ASUS explicitly documents this distinction, and TP-Link provides similar compatibility guidance. That limits immediate utilization because a household may own only one or two 6 GHz-capable devices. Buyers comparing upgrade options may therefore choose a less expensive Wi-Fi 6 router or move directly to Wi-Fi 7, reducing the standalone replacement pull for 6E-only products as the market matures.
Regional spectrum variation
The 6 GHz advantage is shaped by national regulation, and not every country makes the same amount of spectrum or power level available. U.S. rules opened 1,200 MHz, while other markets may provide narrower allocations or different operating conditions. Router vendors must maintain region-specific firmware, channel lists and certification, which fragments product planning. Enterprise standard-power operation can also require AFC coordination. These differences make Wi-Fi 6 easier to sell globally because 2.4 GHz and 5 GHz support is already mature and broadly harmonized.
Wi-Fi 7 substitution
Wi-Fi 7 is now commercially available and also uses the 6 GHz band, adding features that attract premium buyers who might otherwise have purchased high-end Wi-Fi 6E equipment. Cisco’s current comparison material positions Wi-Fi 7 as the newest standard, and router brands are rapidly expanding Wi-Fi 7 portfolios. This creates a shorter premium lifecycle for 6E. Wi-Fi 6 remains protected by lower cost and broad compatibility, but 6E risks being squeezed between mainstream Wi-Fi 6 and feature-rich Wi-Fi 7 in new retail launches.
Hardware and thermal cost
Tri-band 6E routers require an additional 6 GHz radio path, more antennas or RF components, faster processors and often multi-gigabit Ethernet ports. Premium SoCs such as Qualcomm’s NPro 6E support many spatial streams and high peak throughput, but this capability increases BOM, power consumption and cooling needs. Vendors must balance radio count against retail price and enclosure design. In cost-sensitive markets, a well-optimized dual-band Wi-Fi 6 router may deliver sufficient practical performance at substantially lower hardware cost.
Market Opportunities
Premium mesh systems
Wi-Fi 6E remains attractive in multi-node mesh because 6 GHz can provide a clean high-capacity backhaul when nodes are within suitable range. NETGEAR’s Orbi 6E systems and Qualcomm’s networking platforms demonstrate this use case. Premium households value coverage consistency more than one-room peak speed, so a dedicated or lightly loaded backhaul can justify higher system pricing. Vendors can strengthen the offer through automatic optimization, security subscriptions and multi-gig Ethernet, increasing recurring or accessory revenue around the hardware sale.
Multi-gigabit ISP gateways
Broadband operators delivering 2 Gbps or faster service need home gateways capable of moving that bandwidth through both Ethernet and Wi-Fi. Wi-Fi 6E routers with 2.5 GbE or faster WAN/LAN ports can serve as premium customer-premises equipment without requiring operators to move immediately to Wi-Fi 7 across every tier. The opportunity is strongest where service providers want a mature, well-tested platform with broad Wi-Fi 6 client compatibility and selective 6 GHz acceleration for newer devices. Operator volumes can also stabilize demand beyond retail cycles.
Enterprise 6 GHz deployments
Managed offices, venues and campuses can use 6 GHz to create additional capacity for newer laptops and collaboration devices while reducing contention in crowded 5 GHz channels. Cisco’s current enterprise access-point and migration documentation shows growing operational maturity, including AFC for standard-power use. This creates opportunities in network refreshes where device fleets are already modern enough to use 6 GHz. Vendors can capture more value through cloud management, analytics and security because enterprise customers purchase a lifecycle platform rather than an isolated access point.
Gaming and creator networking
Gamers, streamers and content creators value low latency, stable throughput and multi-gigabit local transfers, making them natural premium 6E buyers. ASUS, TP-Link and NETGEAR all position high-end routers around wide 160 MHz channels, powerful processors and 6 GHz access. The opportunity persists even as Wi-Fi 7 grows because 6E hardware can fall into a more accessible premium price tier. Vendors can differentiate through traffic prioritization, gaming dashboards, VPN features and high-speed wired ports that complement rather than rely entirely on wireless performance.
Supply Chain Analysis
802.11ax SoCs, radios and acceleration
Front ends, antennas, Ethernet PHYs and memory
PCB assembly, enclosure, thermal and regulatory test
Firmware, mesh, security, retail, ISP and enterprise management
Wi-Fi chipsets
Router SoCs integrate CPU cores, Wi-Fi MAC/PHY, packet acceleration and interfaces for Ethernet, USB and external radios. Qualcomm’s NPro 6E platform shows how premium silicon combines many spatial streams with simultaneous multi-band operation and 160 MHz support. Chipset choice determines how many radios a vendor can expose, how much traffic can be accelerated and what memory or cooling is required. The supply chain therefore depends heavily on a small number of advanced networking-silicon vendors and their reference platforms.
RF & networking hardware
Wi-Fi 6E adds a complete 6 GHz RF path with filters, power amplifiers, low-noise amplifiers and antennas designed for the new band. Premium routers also use 2.5 GbE or 10 GbE PHYs so wired ports do not bottleneck high broadband speeds. These extra components increase BOM and PCB complexity, especially in compact enclosures. Antenna placement must support three bands without excessive coupling, while thermal design must handle the additional radio and processor load. Component integration therefore directly affects both performance and retail cost.
Router manufacturing
Most consumer routers are produced through large Asian electronics manufacturing networks that can source chipsets, RF modules, memory and plastic enclosures at scale. Regulatory test must be repeated for regional radio rules, particularly around 6 GHz channels and power levels. Firmware and hardware versions can also diverge by market, complicating inventory. High-volume brands mitigate this through platform reuse across several retail models, while smaller vendors may rely more heavily on turnkey designs from chipset partners or original-design manufacturers to shorten certification and launch schedules.
Software & channels
Firmware defines security updates, mesh behavior, channel selection, parental controls, VPN functions and the reliability of mixed-client networks. Enterprise products add cloud management, telemetry and automated regulatory features such as AFC. Consumer vendors increasingly monetize subscriptions around cybersecurity or advanced controls, while ISPs value remote management and diagnostics. The channel mix also matters: online retail rewards price and specifications, operator deployments reward lifecycle support, and enterprise projects depend on integrators. Software capability therefore shapes recurring value after the hardware has shipped.
Recent Developments
July 2026 — Cisco updates enterprise guidance for 6 GHz and Wi-Fi migration
The guidance addresses 6 GHz design, migration and coexistence as enterprise networks move from Wi-Fi 6E toward newer standards. Source
July 2026 — ASUS refreshes Wi-Fi 6 versus Wi-Fi 6E support guidance
ASUS confirms that Wi-Fi 6E extends 802.11ax into 6 GHz and supports up to seven additional 160 MHz channels where regional rules permit. Source
Current — Qualcomm Dragonwing NPro 6E targets premium routers and gateways
The active platform supports up to 16 spatial streams, 160 MHz channels and peak speeds up to 10.8 Gbps for premium networking equipment. Source
Report Scope & Segmentation
| Attribute | Coverage |
|---|---|
| Market | Wi-Fi 6 and Wi-Fi 6E Router |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| 2025 Market Size | USD 18.629 billion |
| 2026 Estimated Size | USD 20.657 billion |
| 2034 Forecast Size | USD 47.216 billion |
| CAGR | 10.9% (2026–2034) |
| By Type | Wi-Fi 6, Wi-Fi 6E |
| By Application | Residential, Commercial, Industrial |
| By Bandwidth | Dual-Band, Tri-Band, Quad-Band |
| By Distribution Channel | Online, Offline |
| By Network Topology | Standalone Router, Mesh Wi-Fi, Managed Enterprise WLAN |
| Regions | North America, Asia Pacific, Europe, South America, Middle East & Africa |
| Companies Profiled | TP-Link, NETGEAR, ASUS, D-Link, Huawei, Xiaomi, Tenda, Cisco |
Frequently Asked Questions
What is the Wi-Fi 6 and Wi-Fi 6E router market size in 2025?
The market is valued at USD 18.629 billion in 2025.
What is the projected market size by 2034?
The market is projected to reach USD 47.216 billion by 2034.
What is the CAGR from 2026 to 2034?
The market is expected to expand at a 10.9% CAGR.
Which region leads the market?
North America is the largest regional market in 2025.
Which type leads the market?
Wi-Fi 6 is the leading type.
Which application leads demand?
Residential is the leading application.
What is the main growth driver?
fiber broadband, streaming, gaming, smart homes and dense enterprise device populations continue to increase demand for higher-capacity 802.11ax networking.
What is the principal restraint?
6 GHz benefits require compatible clients and country-specific spectrum support, while Wi-Fi 7 is already competing for premium replacement budgets.
Where are the strongest opportunities?
tri-band mesh, multi-gig broadband gateways, enterprise 6 GHz deployments, gaming routers and managed Wi-Fi upgrades.
Which companies are active in the market?
TP-Link, NETGEAR, ASUS, D-Link, Huawei, Xiaomi, Tenda, Cisco.
Research Sources & Evidence Base
View primary, official and technical evidence used in this overview
- Federal Communications Commission: FCC 20-51: Unlicensed Use of the 6 GHz Band — U.S. allocation of 1,200 MHz from 5.925–7.125 GHz for unlicensed operation, enabling Wi-Fi 6E.
- Cisco: Wi-Fi 6 vs. Wi-Fi 6E vs. Wi-Fi 7 — Current comparison of 802.11ax, 6 GHz extension and the newer Wi-Fi 7 generation.
- Qualcomm: Dragonwing NPro 6E Platform — Active Wi-Fi 6E networking platform with multi-band operation, high stream count and 160 MHz support.
- TP-Link: Archer AXE75 Wi-Fi 6E Router — Tri-band consumer router architecture, 6 GHz support, OFDMA and retail feature integration.
- ASUS: Difference Between Wi-Fi 6 and Wi-Fi 6E — 6 GHz extension, supported channel widths and client compatibility guidance.
- NETGEAR: What is Wi-Fi 6E? — 6 GHz capacity, additional 80/160 MHz channels, congestion reduction and WPA3 context.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF






