Key Statistics
Key Takeaways
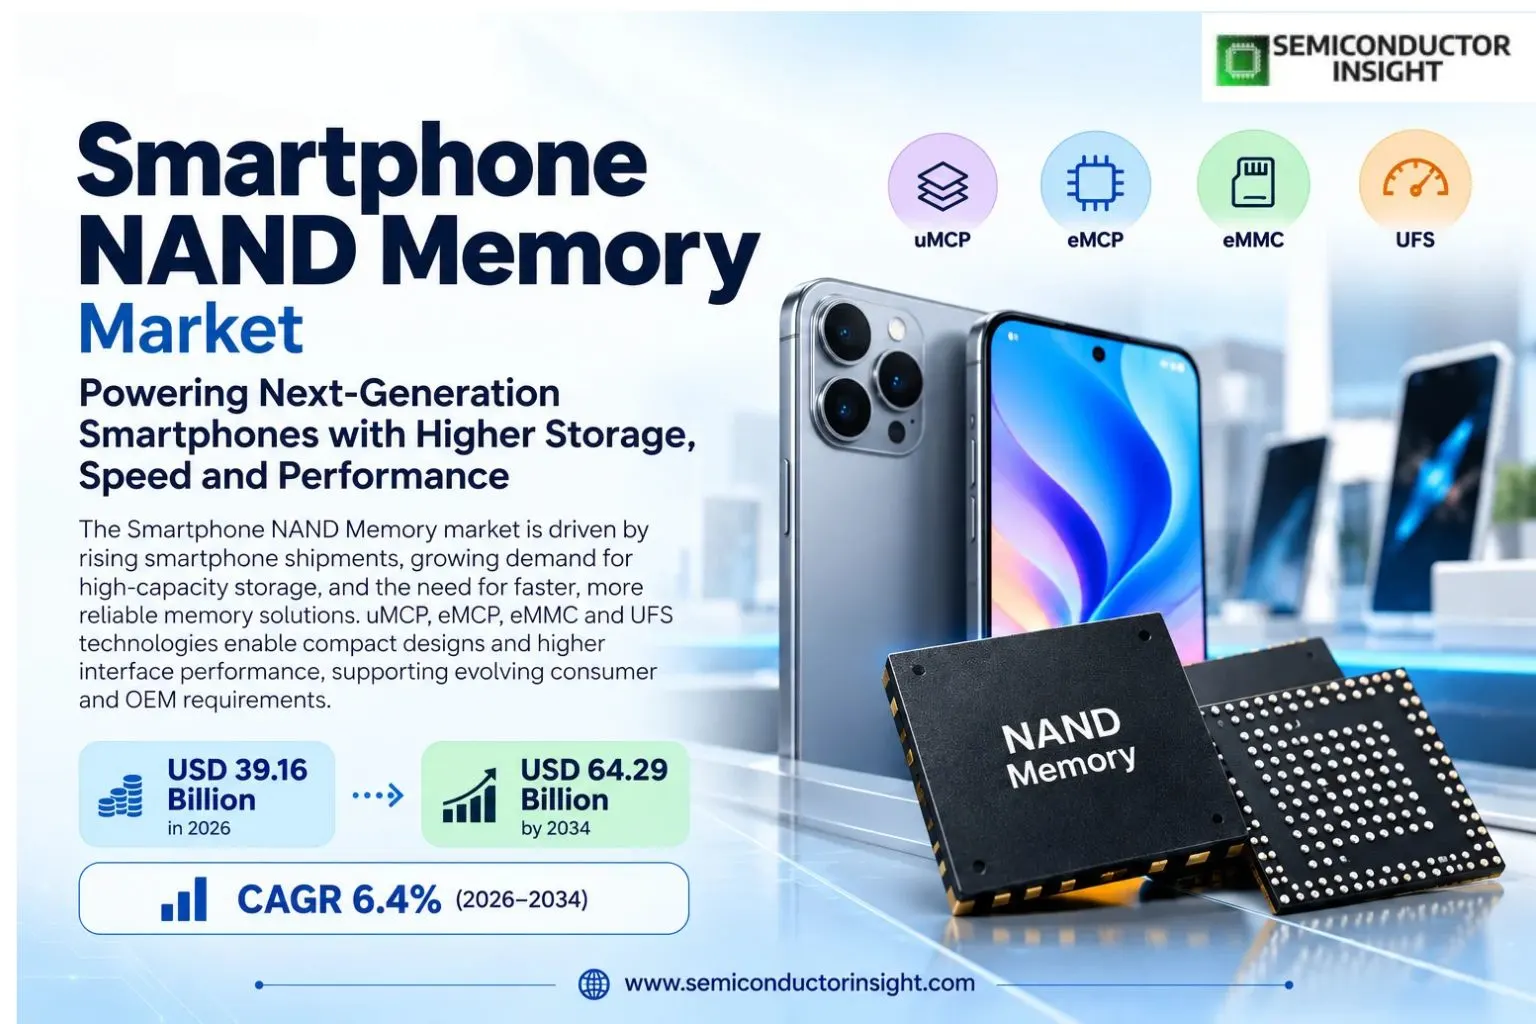
- Market size: The market is valued at USD 36.81 billion in 2025 and is projected to reach USD 64.29 billion by 2034, representing a 6.4% CAGR during 2026–2034.
- UFS and uMCP are the highest-value product categories, with flagship and premium smartphones increasingly using faster UFS interfaces and denser 3D NAND.
- Asia Pacific leads with a dominant share, supported by smartphone manufacturing and major NAND suppliers in South Korea, Japan and China.
- 256GB-512GB is the fastest-expanding capacity band as AI features, high-resolution media and 5G increase local storage needs.
- 3D NAND layer scaling remains the central cost-performance lever, while controller efficiency and UFS interface speed determine user-visible responsiveness.
Smartphone NAND Memory Market Overview
Smartphone NAND memory market is valued at USD 36.81 billion in 2025 and is projected to reach USD 64.29 billion by 2034, expanding at a 6.4% CAGR during 2026–2034. The 2026 market level is USD 39.16 billion. Asia Pacific dominates because the region combines the largest smartphone manufacturing base with Samsung, SK hynix, Kioxia and YMTC supply. Demand continues shifting toward higher-capacity UFS storage in premium and mid-range devices.
Smartphone NAND memory provides non-volatile storage for operating systems, applications, photos, video, local AI models and user data. Commercial products include uMCP, eMCP, eMMC and UFS-based devices that integrate NAND die with controllers and, in some packages, mobile DRAM. Product selection depends on capacity, sequential and random performance, power efficiency, package footprint, endurance and compatibility with the mobile processor platform.
The technology roadmap is centered on higher-layer 3D NAND and faster UFS interfaces. Samsung positions UFS 4.0 for flagship smartphones with up to 1TB capacity, double the speed of its prior generation and improved power efficiency. These gains matter because on-device AI, computational photography and high-resolution gaming increase both storage capacity and sustained data-transfer requirements.
Pricing remains cyclical because smartphone demand interacts with large NAND fabrication investments and technology migrations. OEMs typically dual-source where possible, but qualification, controller firmware and package form factor create switching costs. Suppliers with integrated NAND, controllers and mobile-package expertise can optimize performance and capture higher value than commodity bare-die providers.
Segment Analysis: By Type
By type, the market includes uMCP, eMCP, eMMC and UFS. uMCP and UFS lead premium value because they combine compact integration with higher interface performance, while eMMC remains important in cost-sensitive devices. eMCP continues serving selected mid-range platforms where integrated memory-package economics are attractive. Commercial decisions in the Smartphone NAND Memory market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Type | Commercial role |
|---|---|
| uMCP | Integrated mobile package combining UFS NAND and mobile DRAM for compact high-performance smartphones. |
| eMCP | Embedded multi-chip package combining eMMC storage and DRAM for cost-sensitive devices. |
| eMMC | Mature embedded flash interface used in entry-level and legacy devices. |
| UFS | High-performance mobile storage interface for flagship and increasingly mid-range smartphones. |
Additional Segmentation: By Capacity
Capacity segmentation reflects the shift from 64GB and 128GB configurations toward 256GB, 512GB and 1TB-class devices. Higher-resolution cameras, offline media, gaming and local AI models increase storage requirements, while falling cost per bit enables OEMs to raise standard capacities without proportionally increasing device price. Commercial decisions in the Smartphone NAND Memory market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Capacity | Demand characteristics |
|---|---|
| Below 64GB | Entry-level and legacy smartphones with strong price sensitivity. |
| 64GB-128GB | Mass-market configurations in budget and lower mid-range devices. |
| 128GB-256GB | Mainstream smartphone storage band across broad price tiers. |
| 256GB-512GB | Fast-growth premium and upper-mid-range configuration. |
| Above 512GB | Flagship, gaming and content-creation devices with very high local storage needs. |
Segment Analysis: By Application
By application, smartphones account for the overwhelming majority of demand, while tablets create a smaller adjacent market. Smartphone storage turns are much faster because annual unit shipments are higher and product cycles are shorter. Tablets increasingly use similar UFS and high-capacity NAND architectures, particularly in premium productivity devices. Commercial decisions in the Smartphone NAND Memory market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Application | Demand characteristics |
|---|---|
| Smartphone | Largest application across flagship, mid-range and budget devices. |
| Tablet | Premium and productivity devices using similar embedded NAND technologies. |
Additional Segmentation: By Technology Node
Technology-node segmentation captures the underlying NAND and controller scaling path. The industry has moved away from purely planar node shrink toward vertical 3D stacking, but controller logic and peripheral circuitry still benefit from advanced nodes. Sub-10nm-class logic and high-layer 3D NAND support better density, performance and power efficiency. Commercial decisions in the Smartphone NAND Memory market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Technology Node | Commercial relevance |
|---|---|
| Above 20nm | Legacy control and peripheral implementations. |
| 10nm-20nm | Mature mobile NAND controller and peripheral logic nodes. |
| Sub-10nm | Advanced controller and peripheral circuitry paired with high-layer 3D NAND. |
Regional Analysis
Asia Pacific is the largest and fastest-growing region, supported by smartphone manufacturing and NAND production. North America is a major premium-demand market, Europe has high storage adoption in flagship devices, and emerging regions remain more price-sensitive but continue shifting toward higher capacities. Commercial decisions in the Smartphone NAND Memory market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Why does regional demand differ across the Smartphone NAND Memory market?
Regional demand reflects smartphone unit volume, product mix and the location of memory manufacturing. Asia Pacific combines all three, North America has high flagship penetration, and Europe maintains strong premium-device demand. South America and the Middle East & Africa remain more sensitive to memory-driven handset pricing. Commercial decisions in the Smartphone NAND Memory market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Region | Position | Demand profile | Supplier-selection factor |
|---|---|---|---|
| Asia Pacific | Largest / fastest | Smartphone manufacturing and NAND supply | Scale and local supply |
| North America | High-value | Premium smartphones and AI features | Flagship mix |
| Europe | Mature | Premium and mid-range devices | High storage adoption |
| South America | Emerging | Mass-market smartphones | Price sensitivity |
| Middle East & Africa | Emerging | Entry-level to premium mix | Affordability and imports |
Competitive Landscape
Samsung Electronics, SK hynix, Kioxia, Micron, Western Digital/SanDisk and YMTC dominate smartphone NAND supply. Competition centers on 3D NAND layer count, controller integration, UFS performance, power efficiency and mobile-package integration. Commercial decisions in the Smartphone NAND Memory market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Samsung’s UFS 4.0 portfolio illustrates the premium performance benchmark, with up to 1TB capacity, major speed gains and improved efficiency. Similar roadmaps from other suppliers are expanding UFS adoption into lower price tiers. Commercial decisions in the Smartphone NAND Memory market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
The market is highly concentrated because NAND fabs require very high capital expenditure. Smartphone OEMs therefore balance supplier diversification with qualification cost, while memory vendors manage capacity carefully to avoid severe pricing cycles. Commercial decisions in the Smartphone NAND Memory market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Competitive tier | Representative companies | Primary differentiation |
|---|---|---|
| Integrated NAND leaders | Samsung, SK hynix, Kioxia | Advanced 3D NAND, UFS and mobile package integration. |
| Global memory suppliers | Micron, SanDisk/Western Digital | NAND scale, controller expertise and OEM qualification. |
| Emerging Chinese supplier | YMTC | Xtacking architecture and growing domestic smartphone adoption. |
Key companies profiled
Samsung Electronics, SK hynix, Kioxia, Micron Technology, SanDisk/Western Digital and YMTC are included in the competitive scope. Supplier strength differs by NAND process, controller, UFS generation, mobile package and access to major smartphone OEM platforms. Commercial decisions in the Smartphone NAND Memory market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Production Capacity Analysis
NAND capacity depends on advanced 300mm fabs, deposition and etch steps for hundreds of 3D layers, wafer bonding or string stacking, controller silicon and package assembly. Technology transitions can temporarily reduce effective output even when wafer-start capacity is unchanged. Commercial decisions in the Smartphone NAND Memory market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
SEMI reported in June 2026 that 3D NAND equipment spending is projected to rise 28% to USD 14 billion in 2026, showing renewed investment in storage capacity and technology. Smartphone demand competes with enterprise SSD and other NAND applications for the same upstream wafer supply. Commercial decisions in the Smartphone NAND Memory market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Market Dynamics
The market is driven by higher storage capacities, 5G, on-device AI and richer media. Growth is restrained by NAND price volatility, smartphone replacement cycles and concentrated supply. UFS 4.0/4.1, QLC mobile storage and AI-optimized package integration offer the strongest premium opportunities. Commercial decisions in the Smartphone NAND Memory market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Market Drivers
| Driver | Impact | Commercial mechanism |
|---|---|---|
| Higher storage capacity | High | Smartphones are standardizing on larger local storage tiers. |
| On-device AI | High | Local models and AI features increase storage and I/O requirements. |
| 5G adoption | Medium-High | Faster networks encourage richer content creation and consumption. |
| 3D NAND scaling | Medium | Higher layer counts reduce cost per bit. |
Higher storage capacity
Photos, 4K video, gaming and large applications raise the value of 256GB and 512GB configurations, directly increasing NAND content per device. Commercial decisions in the Smartphone NAND Memory market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
On-device AI
AI assistants, computational photography and language models create new persistent-data workloads and favor faster UFS interfaces. Commercial decisions in the Smartphone NAND Memory market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
5G adoption
Higher download speed makes large media and games more practical, increasing local storage use and performance expectations. Commercial decisions in the Smartphone NAND Memory market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
3D NAND scaling
More layers increase density without shrinking planar cell dimensions as aggressively, supporting higher smartphone capacities within compact packages. Commercial decisions in the Smartphone NAND Memory market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Market Restraints
| Restraint | Impact | Commercial consequence |
|---|---|---|
| Price volatility | High | NAND pricing can change rapidly with capacity and inventory cycles. |
| Smartphone maturity | Medium-High | Unit growth is slower in mature markets. |
| Supply concentration | Medium | A small group of suppliers controls advanced NAND output. |
| Technology complexity | Medium | Higher-layer NAND raises process difficulty and yield risk. |
Price volatility
Smartphone OEMs must manage bill-of-material cost and may adjust storage configurations when NAND prices move sharply. Commercial decisions in the Smartphone NAND Memory market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Smartphone maturity
Much of revenue growth comes from higher content per phone rather than large increases in total handset shipments. Commercial decisions in the Smartphone NAND Memory market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Supply concentration
Geographic or fab disruptions can affect global availability, encouraging OEMs to maintain multiple qualified sources. Commercial decisions in the Smartphone NAND Memory market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Technology complexity
Each new 3D generation requires tighter etch, deposition and bonding control, increasing capital intensity and ramp complexity. Commercial decisions in the Smartphone NAND Memory market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Market Opportunities
AI-optimized mobile storage
Storage firmware and package architectures can be optimized for model loading, photography and high-concurrency AI workloads. Commercial decisions in the Smartphone NAND Memory market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
QLC smartphones
QLC can reduce cost per bit and support larger capacities if endurance and performance remain suitable for mobile use. Commercial decisions in the Smartphone NAND Memory market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
UFS 4.0 and beyond
Faster interfaces create premium value in flagship and AI-focused devices. Commercial decisions in the Smartphone NAND Memory market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Higher standard capacities
Moving 256GB into mainstream tiers increases NAND content even if smartphone unit shipments grow slowly. Commercial decisions in the Smartphone NAND Memory market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Supply Chain Analysis
Wafer fabrication. NAND dies are built in highly capital-intensive 300mm fabs using repeated deposition, etch and patterning to create vertical memory stacks. Commercial decisions in the Smartphone NAND Memory market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Controller and package. NAND is paired with controllers and sometimes DRAM in UFS, uMCP or eMCP packages. Package footprint and power are critical in smartphones. Commercial decisions in the Smartphone NAND Memory market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
OEM qualification. Smartphone makers validate performance, endurance, firmware and thermal behavior with each platform. Multiple suppliers are often qualified to improve supply resilience. Commercial decisions in the Smartphone NAND Memory market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Deployment. Finished devices are sold across flagship, mid-range and budget tiers. Storage capacity and UFS generation are increasingly visible product differentiators to consumers. Commercial decisions in the Smartphone NAND Memory market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Recent Developments in the Smartphone NAND Memory Market
Developments tracked through September 2026 and limited to events that materially affect technology, capacity, adoption or competition.
- 29 June 2026
SEMI reported that worldwide 300mm equipment spending for 3D NAND is projected to rise 28% to USD 14 billion in 2026, supported by increasing data-storage requirements and higher-layer NAND transitions. Source - 2026 Current Product
Samsung continues commercial deployment of UFS 4.0 for flagship smartphones with up to 1TB capacity, double the speed of the prior generation and 45% better efficiency. Source - 2025–2026 Technology Trend
Mobile storage roadmaps continue moving toward high-layer 3D NAND and faster UFS interfaces as on-device AI and premium smartphone capacities increase. Source
Report Scope & Segmentation
| Attribute | Scope |
|---|---|
| Base year | 2025 |
| Estimated year | 2026 |
| Forecast period | 2026–2034 |
| 2025 market size | USD 36.81 billion |
| 2026 estimated size | USD 39.16 billion |
| 2034 projected size | USD 64.29 billion |
| CAGR (2026–2034) | 6.4% |
| Largest market in 2025 | Asia Pacific |
| By Type | uMCP; eMCP; eMMC; UFS |
| By Application | Smartphone; Tablet |
| By Capacity | Below 64GB; 64GB-128GB; 128GB-256GB; 256GB-512GB; Above 512GB |
| By Technology Node | Above 20nm; 10nm-20nm; Sub-10nm |
| Companies profiled | Samsung; SK hynix; Kioxia; Micron; SanDisk/Western Digital; YMTC |
Frequently Asked Questions
What is the smartphone NAND memory market size in 2025?
The global market is valued at USD 36.81 billion in 2025.
What is the market forecast for 2034?
The market is projected to reach USD 64.29 billion by 2034, representing a 6.4% CAGR during 2026–2034. The 2026 market level is USD 39.16 billion.
Which region leads the market?
Asia Pacific leads because it combines smartphone manufacturing with major NAND suppliers in South Korea, Japan and China.
Which product type is most important?
UFS and uMCP are the highest-value categories in premium and mid-range smartphones.
Which capacity band is growing fastest?
256GB-512GB is a major growth band as AI, gaming and high-resolution media increase storage requirements.
What drives NAND demand in smartphones?
Higher storage capacity, on-device AI, 5G and richer media are the main demand drivers.
Who are the major suppliers?
Samsung, SK hynix, Kioxia, Micron, SanDisk/Western Digital and YMTC are the principal suppliers.
What limits market growth?
NAND price volatility, mature smartphone unit growth, concentrated supply and technology complexity are the main restraints.
Why is UFS important?
UFS provides higher read and write performance and better efficiency than legacy eMMC, improving responsiveness in premium devices.
What will shape the market through 2034?
Higher-layer 3D NAND, larger capacities, QLC and faster UFS interfaces will shape market growth.
Research Sources & Evidence Base
View research sources used in this market overview
- Samsung Semiconductor — UFS 4.0. Current flagship mobile storage performance, capacity and efficiency evidence.
- SEMI — 300mm Memory Investment Outlook. 2026 NAND equipment investment and memory capacity evidence.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF