Key Statistics
Key Takeaways
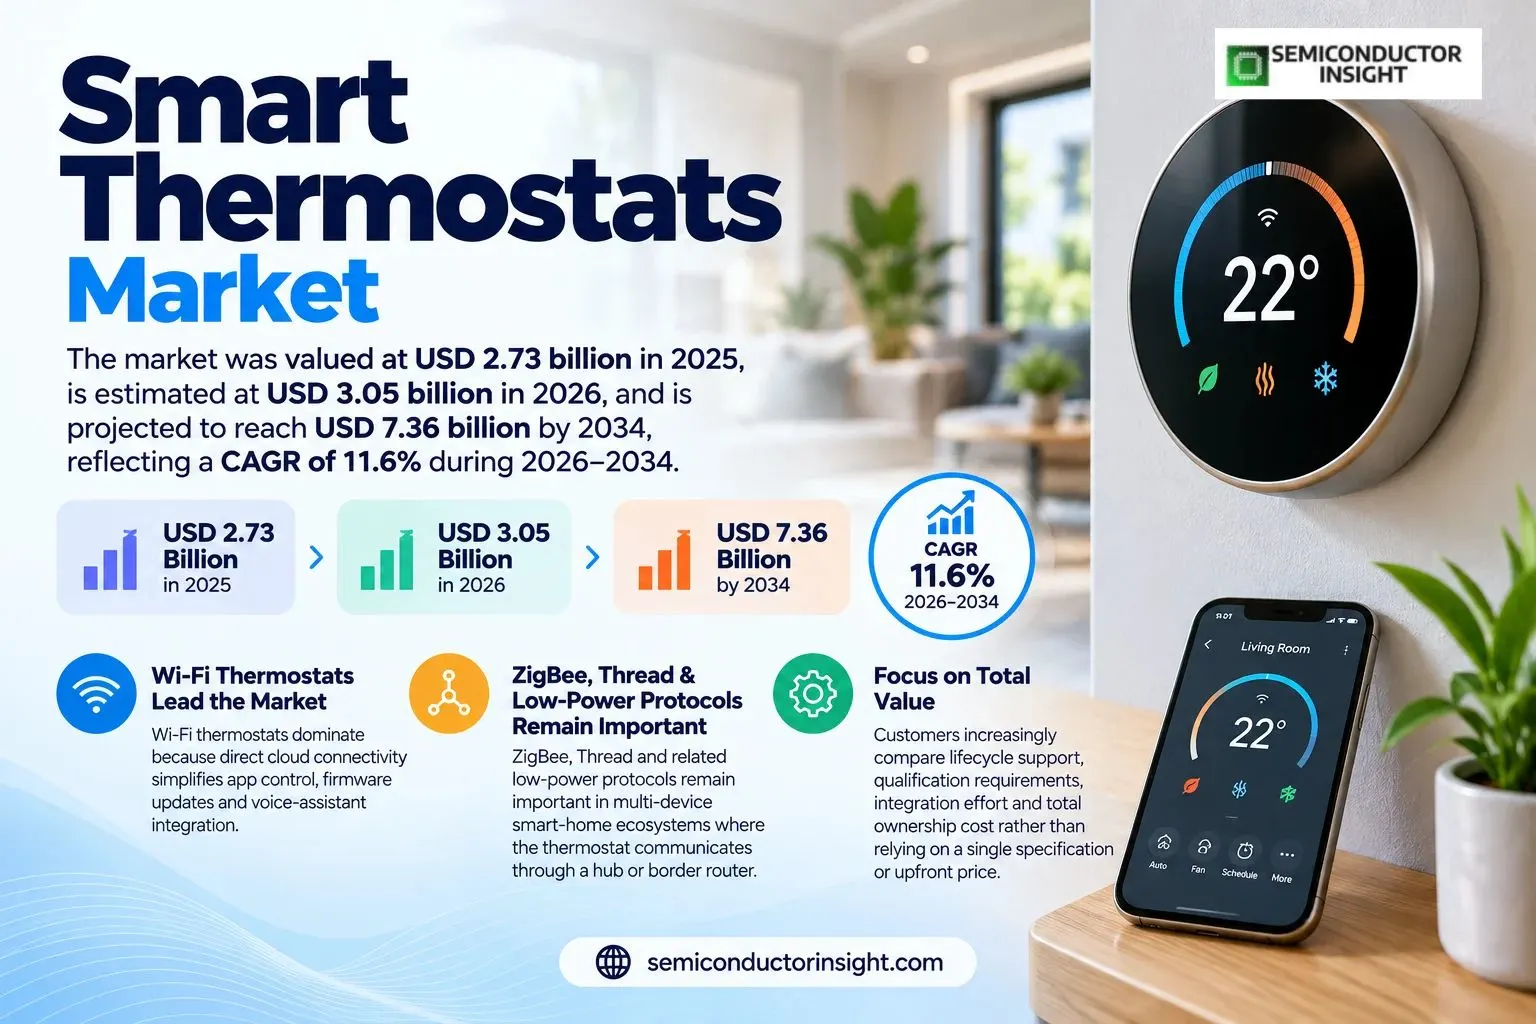
- The market is valued at USD 2.73 billion in 2025 and is projected to reach USD 7.36 billion by 2034, representing a 11.6% CAGR over 2026–2034.
- Wi-Fi Thermostats is a major product segment, while adjacent variants are expanding as performance, integration and cost requirements evolve.
- Residential is a leading application area, supported by demand across Commercial, Industrial.
- North America is the largest market in 2025 based on current demand, manufacturing concentration and ecosystem maturity.
Smart Thermostats Market Overview
Smart Thermostats are connected HVAC controllers that combine temperature sensing, scheduling, remote control and energy-management software. Compared with conventional programmable thermostats, they can learn occupancy patterns, use geofencing, integrate with voice assistants and analyze heating or cooling runtime to reduce unnecessary energy use. Commercial adoption of Smart Thermostats products therefore depends on system-level productivity, integration requirements, reliability expectations and the economics of replacing established alternatives in real operating environments.
The market is expanding as smart-home adoption, utility incentives and higher energy costs strengthen the value proposition. Premium products now add radar occupancy sensing, indoor-air-quality monitoring, remote room sensors and security functions. The category is also broadening into demand response, where utilities can coordinate temperature adjustments during grid peaks with customer consent.
Segment Analysis: By Type
Wi-Fi thermostats dominate because direct cloud connectivity simplifies app control, firmware updates and voice-assistant integration. ZigBee, Thread and related low-power protocols remain important in multi-device smart-home ecosystems where the thermostat communicates through a hub or border router. Within this segment, customers increasingly compare lifecycle support, qualification requirements, integration effort and total ownership cost rather than relying on a single specification or upfront price.
| Type | Market relevance |
|---|---|
| Wi-Fi Thermostats | Largest mainstream connected category. |
| ZigBee Thermostats | Hub-based smart-home integration. |
| Bluetooth Thermostats | Local setup and accessory connectivity. |
| Others | Thread, Z-Wave and proprietary protocols. |
Segment Analysis: By Application
Residential use is the largest application because heating and cooling account for a major share of household energy costs. Commercial adoption is also growing as offices, hotels and retail sites integrate connected thermostats with building-management and demand-response programs. Within this segment, customers increasingly compare lifecycle support, qualification requirements, integration effort and total ownership cost rather than relying on a single specification or upfront price.
| Application | Market relevance |
|---|---|
| Residential | Largest installed base. |
| Commercial | BMS and demand-response integration. |
| Industrial | Selected facility and process climate control. |
| Hospitality | Hotels and resorts with room-level optimization. |
Segment Analysis: By Technology
Learning thermostats command premium value by adapting schedules to occupancy and behavior, while programmable smart thermostats provide lower-cost remote control and fixed scheduling. The distinction is narrowing as more mid-range devices incorporate AI-assisted optimization and occupancy sensing. Within this segment, customers increasingly compare lifecycle support, qualification requirements, integration effort and total ownership cost rather than relying on a single specification or upfront price.
| Technology | Market relevance |
|---|---|
| Learning Thermostats | Adaptive schedules and occupancy learning. |
| Programmable Thermostats | Connected schedules with app control. |
| Manual / Connected Thermostats | Entry and retrofit connected products. |
Segment Analysis: By Feature
Energy monitoring and optimization are the central purchase drivers, while voice control and geofencing improve convenience. Multi-zone support and remote sensors add value in larger homes and commercial sites where temperature differs materially between occupied spaces. Within this segment, customers increasingly compare lifecycle support, qualification requirements, integration effort and total ownership cost rather than relying on a single specification or upfront price.
| Feature | Market relevance |
|---|---|
| Energy Monitoring & Optimization | Core energy-saving proposition. |
| Voice Control | Smart-home ecosystem convenience. |
| Geofencing | Location-based automatic setbacks. |
| Multi-Zone Support | Room-level comfort and zoning. |
| Others | Air quality and HVAC-health features. |
Regional Analysis
North America leads with more than 40% share cited on the report page, supported by high smart-home penetration, utility rebates and strong Nest, ecobee and Resideo ecosystems. Europe follows through energy-efficiency policy, while Asia Pacific is the fastest-growing region. Regional share also reflects supplier depth, engineering support, manufacturing concentration and the speed at which new Smart Thermostats designs can move from evaluation into repeat deployment.
| Region | 2025 Position | Growth Outlook | Demand Profile |
|---|---|---|---|
| North America | Largest | Strong | Residential smart home and utility programs led |
| Europe | Second-largest | Strong | Energy efficiency and boiler optimization led |
| Asia Pacific | Fastest growing | Very strong | Smart home, HVAC and urbanization led |
| South America | Emerging | Moderate-strong | Brazil-led residential and commercial demand |
| Middle East & Africa | Developing | Strong from smaller base | Gulf smart buildings and premium homes led |
Detailed Regional Blocks
Why is North America important to this market?
North America leads because central HVAC is widespread and consumers are familiar with smart-home devices. Utility rebate programs, demand-response participation and strong retail distribution lower the effective cost of adoption. In North America, procurement decisions also depend on service coverage, qualification resources, logistics and long-term availability, so ecosystem maturity can materially influence adoption even when core technology performance is similar.
| Country / Subregion | Role | Market Context |
|---|---|---|
| United States | Largest global market | Smart-home penetration and rebates drive adoption. |
| Canada | Heating-optimization market | Cold climates increase savings potential. |
| Mexico | Emerging residential and hospitality demand | Premium urban markets lead adoption. |
- The report page states North America held more than 40% of global market share in 2024.
- ecobee Smart Thermostat Premium includes radar occupancy sensing, indoor-air-quality monitoring and a remote SmartSensor.
- Google’s fourth-generation Nest Learning Thermostat uses a 600×600 display, Soli motion sensing and dual-band Wi-Fi.
Why is Europe important to this market?
Europe is a large market because building-efficiency rules and high energy prices support connected heating control. Boiler-centric systems and radiator zoning create different product requirements from North American forced-air HVAC. In Europe, procurement decisions also depend on service coverage, qualification resources, logistics and long-term availability, so ecosystem maturity can materially influence adoption even when core technology performance is similar.
| Country / Subregion | Role | Market Context |
|---|---|---|
| Germany | Large heating-control market | Smart radiator and boiler optimization support adoption. |
| United Kingdom | Connected heating market | App-controlled thermostats are well established. |
| France | Energy-efficiency market | Building renovation supports smart controls. |
- European products frequently integrate with boilers, heat pumps and smart radiator valves rather than only central air systems.
- Data privacy and local processing are important purchasing considerations.
- Dynamic electricity pricing can increase the value of heat-pump optimization.
Why is Asia Pacific important to this market?
Asia Pacific is expanding rapidly through China, Japan, South Korea and India. Growth varies with HVAC penetration, but connected home ecosystems and heat-pump adoption create strong long-term demand. In Asia Pacific, procurement decisions also depend on service coverage, qualification resources, logistics and long-term availability, so ecosystem maturity can materially influence adoption even when core technology performance is similar.
| Country / Subregion | Role | Market Context |
|---|---|---|
| China | Large smart-home market | Connected ecosystems support thermostat integration. |
| Japan | Heat-pump and aging-population use cases | Automation improves comfort management. |
| India | Emerging premium market | Commercial and high-income residential adoption leads growth. |
- The report page identifies Asia Pacific as the fastest-growing region through 2032.
- Commercial offices and hotels can adopt connected climate controls before residential markets in warmer countries.
- Lower-cost connected thermostats broaden adoption as local device ecosystems mature.
Why is South America important to this market?
South America is an emerging market where Brazil accounts for the largest share of regional demand. Adoption is concentrated in urban middle- and high-income households, offices and hospitality sites. In South America, procurement decisions also depend on service coverage, qualification resources, logistics and long-term availability, so ecosystem maturity can materially influence adoption even when core technology performance is similar.
| Country / Subregion | Role | Market Context |
|---|---|---|
| Brazil | Largest regional market | Urban smart-home demand supports Wi-Fi thermostats. |
| Chile | Premium residential niche | Higher connected-device adoption supports growth. |
| Argentina | Selective market | Macroeconomic volatility affects premium hardware sales. |
- Import costs remain a barrier to premium product adoption.
- Hospitality and office users can justify connected controls through operating savings.
- Wi-Fi products dominate because they work with existing home broadband.
Why is Middle East & Africa important to this market?
Middle East and Africa demand is concentrated in Gulf countries and South Africa. High cooling loads make HVAC optimization economically relevant, while smart-city projects encourage connected building controls. In Middle East & Africa, procurement decisions also depend on service coverage, qualification resources, logistics and long-term availability, so ecosystem maturity can materially influence adoption even when core technology performance is similar.
| Country / Subregion | Role | Market Context |
|---|---|---|
| United Arab Emirates | Premium smart-building market | High cooling demand supports connected control. |
| Saudi Arabia | Smart-city and residential growth | Large projects expand demand. |
| South Africa | Regional smart-home hub | Premium residential adoption leads the market. |
- High cooling loads create stronger potential energy savings than in mild climates.
- Commercial buildings are often the first adopters because centralized management has clear payback.
- Compatibility with local HVAC equipment remains a key technical requirement.
Competitive Landscape
Google Nest, ecobee, Resideo/Honeywell Home, Emerson Sensi, tado°, Netatmo/Legrand and HVAC OEMs compete through energy optimization, compatibility, sensors, app quality and ecosystem integration. Utility partnerships and service subscriptions are becoming important differentiators alongside hardware.
| Company | Position | Relevant capability |
|---|---|---|
| Google Nest | Key participant | Fourth-generation Learning Thermostat combines adaptive scheduling, Soli sensing and Google Home integration. |
| ecobee | Key participant | Premium thermostat platform with radar occupancy, air-quality monitoring, SmartSensor and multi-ecosystem compatibility. |
| Resideo / Honeywell Home | Key participant | Large installed base across residential and light-commercial HVAC controls. |
| Emerson Sensi | Key participant | Competes through product breadth, integration capability, qualification and customer support. |
| tado° | Key participant | Competes through product breadth, integration capability, qualification and customer support. |
| Netatmo / Legrand | Key participant | Competes through product breadth, integration capability, qualification and customer support. |
| Schneider Electric | Key participant | Competes through product breadth, integration capability, qualification and customer support. |
| Johnson Controls | Key participant | Competes through product breadth, integration capability, qualification and customer support. |
| Carrier | Key participant | Competes through product breadth, integration capability, qualification and customer support. |
| Lennox | Key participant | Competes through product breadth, integration capability, qualification and customer support. |
Production Capacity Analysis
Smart thermostat production depends on displays, microcontrollers, Wi-Fi/Bluetooth radios, sensors, relays, power electronics and plastic or metal housings. Consumer-electronics manufacturing can scale quickly, but HVAC compatibility and certification create more product variants than typical smart-home devices. Scaling output without degrading consistency requires stable upstream materials, disciplined process control and final testing that catches performance drift before products reach high-value customer systems.
Software and cloud infrastructure are increasingly part of effective capacity. Manufacturers must operate apps, remote access, firmware updates and energy analytics throughout the installed life of the thermostat, creating recurring engineering and cybersecurity obligations. Second-source planning and regional technical support therefore become increasingly important as deployments expand and buyers seek supply continuity without repeating lengthy qualification work.
Market Dynamics
The market is shifting from simple remote control toward automated optimization. Occupancy sensing, weather data, utility pricing and machine learning allow thermostats to adjust schedules without constant user input, increasing savings while reducing manual configuration. This is changing competitive behavior because vendors increasingly sell system-level value, workflow integration and lifecycle economics rather than an isolated component specification.
Interoperability is improving but remains uneven because HVAC wiring, boilers, heat pumps and multi-stage systems differ by region. Vendors that simplify installation and support more equipment types can expand beyond technology enthusiasts into mainstream replacement channels. Buyers consequently evaluate total ownership cost, qualification effort and roadmap stability across the life of a program instead of focusing only on initial purchase price.
Market Drivers
| Factor | Analyst Interpretation |
|---|---|
| Energy cost reduction | Heating and cooling savings create a direct household value proposition. |
| Smart-home adoption | Connected ecosystems normalize app and voice control. |
| Utility incentives | Rebates and demand-response programs lower acquisition cost. |
| Heat-pump growth | More electrified HVAC systems increase the value of intelligent control. |
Market Restraints
| Factor | Analyst Interpretation |
|---|---|
| Installation complexity | Older HVAC systems may require new wiring or adapters. |
| Upfront cost | Premium thermostats cost more than basic programmable controls. |
| Privacy and cybersecurity | Connected devices must protect household data and remote access. |
| Regional HVAC fragmentation | Boiler, heat-pump and forced-air systems need different compatibility logic. |
Market Opportunities
| Factor | Analyst Interpretation |
|---|---|
| Demand response | Utilities can use thermostats as flexible load resources with customer consent. |
| Indoor air quality | Integrated sensing can expand the thermostat into a broader home-health hub. |
| Heat-pump optimization | Smart controls can improve efficiency across changing outdoor temperatures. |
| Commercial portfolios | Multi-site management can create recurring software and service revenue. |
Supply Chain Analysis
The value chain combines sensors, connectivity ICs, embedded control, HVAC relays, displays, cloud software and installation channels. Long-term product value depends on reliable cloud service and broad HVAC compatibility as much as the physical device. Traceability and coordination between component suppliers, integrators and end users are important because failures found late in the chain can be far more expensive than the underlying part itself.
| Supply Chain Stage | Role in the Market |
|---|---|
| Sensors and connectivity | Temperature, humidity, occupancy and wireless components create device awareness. |
| Thermostat assembly | Displays, processors, relays and power circuits are integrated into wall hardware. |
| Cloud and app platform | Remote control, analytics and firmware updates run through software services. |
| HVAC installation and utility integration | Installers and energy providers connect devices to equipment and demand-response programs. |
Recent Developments
| Date | Development | Source |
|---|---|---|
| 2026 | Google continues the fourth-generation Nest Learning Thermostat with Soli motion sensing, dual-band Wi-Fi and a 600×600 display. | |
| 2026 | ecobee Smart Thermostat Premium remains a current platform with radar occupancy, air-quality monitoring, SmartSensor and multi-ecosystem support. | ecobee |
| 2026 | ecobee continues energy-optimization features and utility integration across its Wi-Fi thermostat portfolio. | ecobee |
Report Scope & Segmentation
| Scope Item | Coverage |
|---|---|
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| 2025 Market Size | USD 2.73 billion |
| 2026 Estimated Size | USD 3.05 billion |
| 2034 Forecast Size | USD 7.36 billion |
| CAGR (2026–2034) | 11.6% |
| Largest Market in 2025 | North America |
| Category | Consumer Electronics / Smart Home / HVAC Controls |
| By Type | Wi-Fi Thermostats, ZigBee Thermostats, Bluetooth Thermostats, Others |
| By Application | Residential, Commercial, Industrial, Hospitality |
| By Technology | Learning Thermostats, Programmable Thermostats, Manual / Connected Thermostats |
| By Feature | Energy Monitoring & Optimization, Voice Control, Geofencing, Multi-Zone Support, Others |
Frequently Asked Questions
What is the 2025 market size of the Smart Thermostats market?
The market is valued at USD 2.73 billion in 2025.
What is the projected 2034 market size of the Smart Thermostats market?
The market is projected to reach USD 7.36 billion by 2034.
What is the CAGR of the Smart Thermostats market from 2026 to 2034?
The market is expected to expand at a CAGR of 11.6% during 2026–2034.
Which region leads the Smart Thermostats market?
North America is the largest market in 2025 based on the current demand, manufacturing and deployment structure.
Which type segment is important in the Smart Thermostats market?
Wi-Fi Thermostats is a major segment, while adjacent product variants are gaining share as performance and integration requirements evolve.
What is the main application for Smart Thermostats products?
Residential is a leading application, with additional growth coming from Commercial, Industrial.
What drives growth in the Smart Thermostats market?
Heating and cooling savings create a direct household value proposition.
What is a key restraint for the Smart Thermostats market?
Older HVAC systems may require new wiring or adapters.
Which companies participate in the Smart Thermostats market?
Key participants include Google Nest, ecobee, Resideo / Honeywell Home, Emerson Sensi, tado°, alongside other specialized suppliers and system companies.
What technology trend is shaping the Smart Thermostats market?
Utilities can use thermostats as flexible load resources with customer consent.
Research Sources & Evidence Base
View research sources used for this overview.
- Google — Nest Thermostat Technical Specifications: Current fourth-generation Nest Learning Thermostat hardware and connectivity. Source
- ecobee — Smart Thermostat Premium: Current occupancy, air-quality, SmartSensor and HVAC compatibility features. Source
- ecobee — Smart Thermostats: Current energy optimization and smart-home ecosystem features. Source
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF