Key Statistics
Key Takeaways
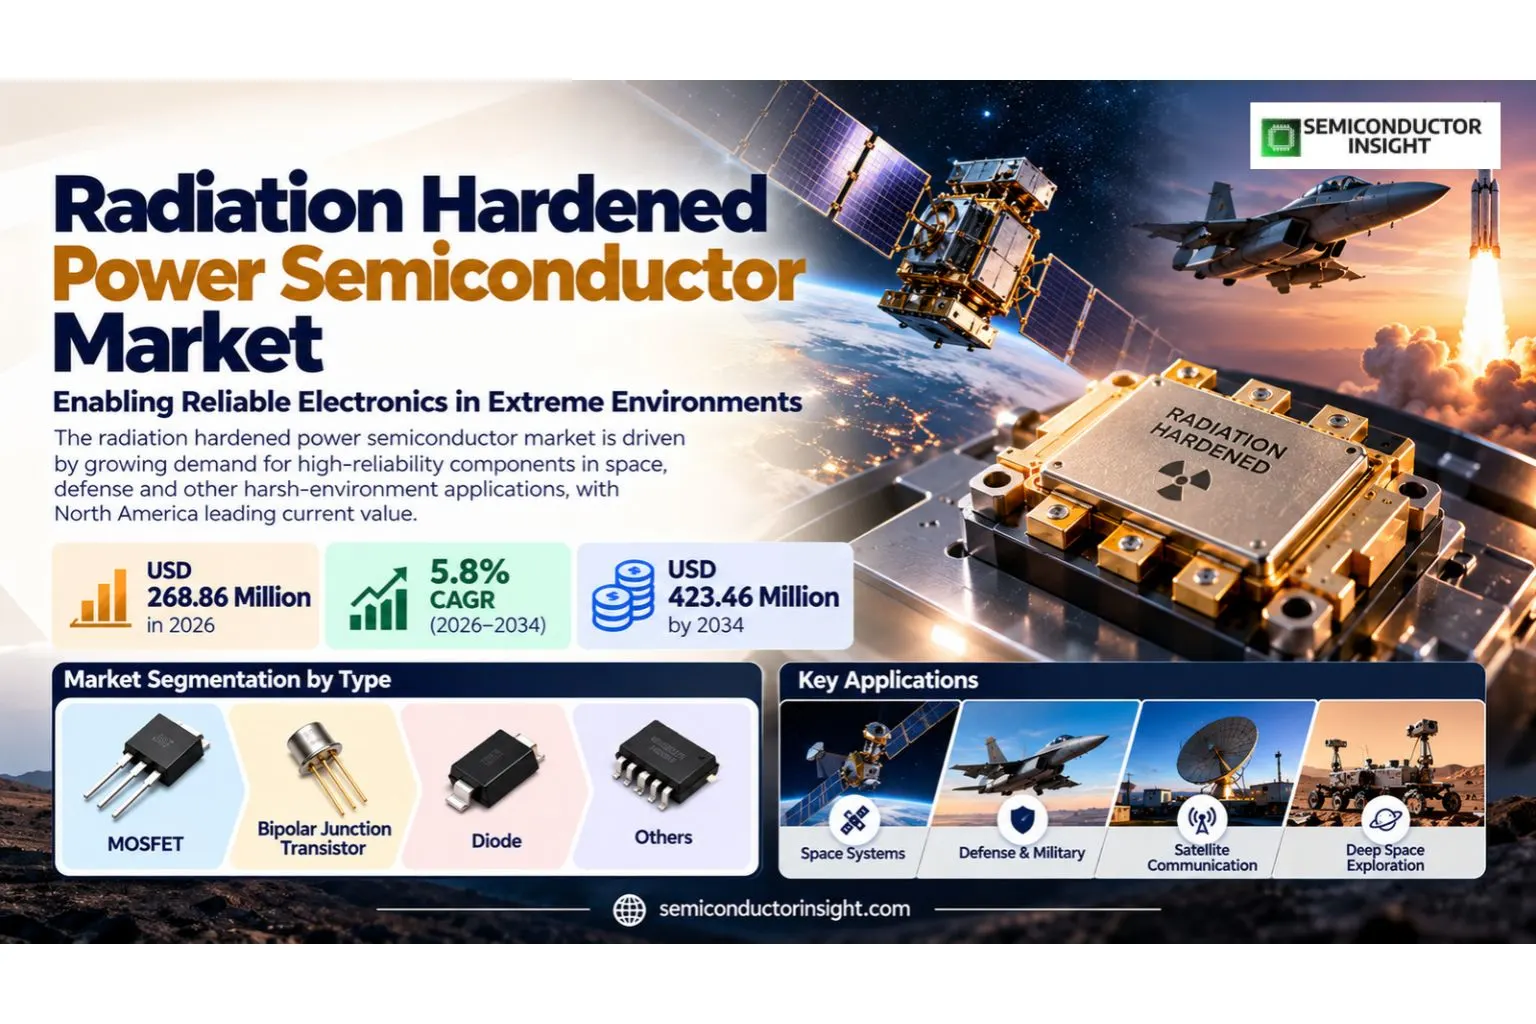
- Market size: The market is valued at USD 254.02 million in 2025 and is projected to reach USD 423.46 million by 2034, representing a 5.8% CAGR during 2026–2034.
- MOSFET is a leading segment, reflecting broad use across the largest volume applications.
- North America leads the market, while Asia Pacific provides the strongest growth profile.
- Satellite is a major application, supported by rising performance and reliability requirements.
- higher-voltage rad-hard MOSFETs, lower-loss power conversion and commercial-space cost optimization is becoming a central competitive differentiator as customers seek higher performance and lower system-level cost.
Radiation Hardened Power Semiconductor Market Overview
Radiation hardened power semiconductor market is valued at USD 254.02 million in 2025 and is projected to reach USD 423.46 million by 2034, expanding at a 5.8% CAGR during 2026–2034. The 2026 market level is USD 268.86 million. North America is used as the largest current market because U.S. space and defense programs drive high-value radiation-hardened power demand. MOSFETs represent the largest product segment in the client evidence.
Radiation Hardened Power Semiconductor products provide a critical functional layer inside modern electronic and industrial systems. Their commercial value depends on performance, reliability, manufacturability, qualification and compatibility with the broader hardware architecture. Customers increasingly assess total system impact rather than component price alone, which favors suppliers that combine proven technology with consistent global support.
Technology development is focused on higher-voltage rad-hard mosfets, lower-loss power conversion and commercial-space cost optimization, tighter integration and more automated manufacturing. These trends raise the value of precision process control and application engineering because smaller geometries, higher data rates or greater power density leave less margin for variation. Qualification therefore becomes a major barrier to entry in premium applications.
Commercial competition combines scale with specialization. Large suppliers benefit from purchasing power, engineering resources and global manufacturing, while specialist vendors can win through process expertise or application-specific performance. Design wins are often durable because changing suppliers can require requalification of electrical, thermal, mechanical or reliability performance. Commercial decisions in the Radiation Hardened Power Semiconductor market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Segment Analysis: By Type
By type, the market is segmented into MOSFET, Bipolar Junction Transistor, Diode, Others. Product selection depends on performance, cost, manufacturing complexity and the target system architecture. Higher-value variants generally offer tighter tolerances, greater integration or improved reliability, while mainstream categories retain volume leadership because of lower cost and broad compatibility.
| Type | Commercial role |
|---|---|
| MOSFET | MOSFET serves a distinct portion of the Radiation Hardened Power Semiconductor market based on performance, cost and integration requirements. |
| Bipolar Junction Transistor | Bipolar Junction Transistor serves a distinct portion of the Radiation Hardened Power Semiconductor market based on performance, cost and integration requirements. |
| Diode | Diode serves a distinct portion of the Radiation Hardened Power Semiconductor market based on performance, cost and integration requirements. |
| Others | Others serves a distinct portion of the Radiation Hardened Power Semiconductor market based on performance, cost and integration requirements. |
Additional Segmentation: By Radiation Class
Radiation Class segmentation highlights important technical or commercial differences inside the Radiation Hardened Power Semiconductor market. These categories affect pricing, qualification, process requirements and customer fit, making them useful for evaluating where value growth differs from simple unit growth. Commercial decisions in the Radiation Hardened Power Semiconductor market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Radiation Class | Demand characteristics |
|---|---|
| TID-Hardened | Designed to withstand cumulative ionizing-dose exposure. |
| SEE-Hardened | Designed to resist single-event effects from energetic particles. |
| Combined TID / SEE | Highest-reliability power devices for demanding space missions. |
Segment Analysis: By Application
By application, the market covers Satellite, Launch Vehicle, Spacecraft Power Systems, Nuclear & Defense Electronics. Demand varies by reliability, performance and product lifecycle. Premium applications usually require stricter qualification and long-term supply support, while higher-volume applications place more emphasis on cost, manufacturing scale and rapid technology migration. Commercial decisions in the Radiation Hardened Power Semiconductor market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Application | Demand characteristics |
|---|---|
| Satellite | Satellite is a material demand segment where reliability, cost and system performance influence purchasing decisions. |
| Launch Vehicle | Launch Vehicle is a material demand segment where reliability, cost and system performance influence purchasing decisions. |
| Spacecraft Power Systems | Spacecraft Power Systems is a material demand segment where reliability, cost and system performance influence purchasing decisions. |
| Nuclear & Defense Electronics | Nuclear & Defense Electronics is a material demand segment where reliability, cost and system performance influence purchasing decisions. |
Additional Segmentation: By End User
End User provides a second analytical view of the Radiation Hardened Power Semiconductor market. It captures how product architecture and end-use requirements change supplier economics, qualification effort and technology roadmaps across the forecast period. Commercial decisions in the Radiation Hardened Power Semiconductor market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| End User | Commercial relevance |
|---|---|
| Commercial Space | Satellite constellations and commercial spacecraft. |
| Defense & Government | Strategic space, launch and secure systems. |
| Scientific Missions | Deep-space, earth-observation and research platforms. |
| Nuclear Industry | Radiation-exposed instrumentation and control systems. |
Regional Analysis
North America is the largest regional market, while Asia Pacific is the fastest-growth region. Regional positioning reflects manufacturing concentration, downstream electronics demand, capital investment and the availability of qualified suppliers. Commercial decisions in the Radiation Hardened Power Semiconductor market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Why does regional demand differ across the Radiation Hardened Power Semiconductor market?
Regional demand varies with electronics manufacturing, technology adoption and local investment. North America leads through NASA, defense programs and commercial space activity, while Europe and Asia Pacific expand sovereign space and satellite programs. Commercial decisions in the Radiation Hardened Power Semiconductor market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Region | Position | Demand profile | Supplier-selection factor |
|---|---|---|---|
| Asia Pacific | Fastest growth | Technology and end-market demand | Qualification, cost and local support |
| North America | Largest / strategic | Technology and end-market demand | Qualification, cost and local support |
| Europe | Strategic | Technology and end-market demand | Qualification, cost and local support |
| South America | Strategic | Technology and end-market demand | Qualification, cost and local support |
| Middle East & Africa | Strategic | Technology and end-market demand | Qualification, cost and local support |
Competitive Landscape
Infineon, Microchip Technology, STMicroelectronics, Renesas, onsemi, Vishay, EPC Space and specialized rad-hard suppliers form the core competitive landscape. Suppliers differentiate through process capability, product breadth, qualification history, manufacturing scale and technical support. Commercial decisions in the Radiation Hardened Power Semiconductor market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
The competitive frontier is shifting toward higher-voltage rad-hard mosfets, lower-loss power conversion and commercial-space cost optimization, which raises the value of engineering integration and reduces the importance of price alone in premium segments. Commercial decisions in the Radiation Hardened Power Semiconductor market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Customer relationships are durable because qualified products become embedded inside longer-lived systems. This creates switching costs but also requires suppliers to maintain lifecycle support and predictable quality. Commercial decisions in the Radiation Hardened Power Semiconductor market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Competitive tier | Representative companies | Primary differentiation |
|---|---|---|
| Global leaders | Infineon, Microchip Technology, STMicroelectronics, Renesas, onsemi, Vishay, EPC Space and specialized rad-hard suppliers | Scale, technology and customer qualification. |
| Specialists | Regional and application-focused vendors | Process expertise and niche performance. |
| Emerging suppliers | New regional entrants | Cost, local capacity and diversification. |
Key companies profiled
Infineon, Microchip Technology, STMicroelectronics, Renesas, onsemi, Vishay, EPC Space and specialized rad-hard suppliers are included in the competitive scope. Their positions differ by product mix, technology capability, geographic manufacturing footprint and customer qualification. Commercial decisions in the Radiation Hardened Power Semiconductor market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Production Capacity Analysis
Capacity depends on specialized materials, precision manufacturing, automated inspection and qualified final test. Effective output is determined by saleable yield and customer-approved capacity rather than nominal equipment throughput alone. Commercial decisions in the Radiation Hardened Power Semiconductor market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Supply expansion increasingly requires duplicated qualification across several factories. This is strategically important because customers want resilience without sacrificing consistency, particularly in automotive, data-center, industrial and high-reliability applications. Commercial decisions in the Radiation Hardened Power Semiconductor market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Market Dynamics
The market is driven by electronics content growth, system performance requirements and supply-chain modernization. Growth is restrained by capital intensity, qualification cycles and pricing pressure. higher-voltage rad-hard MOSFETs, lower-loss power conversion and commercial-space cost optimization creates the strongest opportunity for premium value growth. Commercial decisions in the Radiation Hardened Power Semiconductor market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Market Drivers
| Driver | Impact | Commercial mechanism |
|---|---|---|
| Technology migration | High | higher-voltage rad-hard MOSFETs, lower-loss power conversion and commercial-space cost optimization increases product value and complexity. |
| Electronics demand | High | More electronic content increases component consumption. |
| Supply diversification | Medium-High | Customers want qualified capacity across several regions. |
| Automation | Medium | Higher automation improves yield and throughput. |
Technology migration
Customers are adopting more advanced architectures to improve performance, density or efficiency. This raises qualification and process-control requirements and supports premium pricing for technically differentiated suppliers. Commercial decisions in the Radiation Hardened Power Semiconductor market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Electronics demand
Growth in automotive, data centers, industrial automation and connected devices expands the installed base requiring Radiation Hardened Power Semiconductor products. Commercial decisions in the Radiation Hardened Power Semiconductor market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Supply diversification
Geopolitical and logistics risk encourage multi-site sourcing, creating opportunities for suppliers that can replicate quality across factories. Commercial decisions in the Radiation Hardened Power Semiconductor market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Automation
Automated process control, inspection and material handling can reduce variation and support larger production volumes. Commercial decisions in the Radiation Hardened Power Semiconductor market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Market Restraints
| Restraint | Impact | Commercial consequence |
|---|---|---|
| Capital intensity | High | Advanced manufacturing requires specialized equipment. |
| Qualification cycles | Medium-High | Customer approval can take many months. |
| Price pressure | Medium | High-volume segments face continuing cost reduction. |
| Supply-chain risk | Medium | Specialized materials or equipment can be concentrated. |
Capital intensity
New Radiation Hardened Power Semiconductor capacity can require significant equipment and qualification investment before revenue scales. Commercial decisions in the Radiation Hardened Power Semiconductor market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Qualification cycles
Reliability validation and system integration slow supplier switching and delay new-factory ramps. Commercial decisions in the Radiation Hardened Power Semiconductor market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Price pressure
Suppliers must offset lower average selling prices with yield, automation and differentiated technology. Commercial decisions in the Radiation Hardened Power Semiconductor market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Supply-chain risk
Dependence on limited upstream suppliers can affect lead times and create the need for strategic inventory or second sourcing. Commercial decisions in the Radiation Hardened Power Semiconductor market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Market Opportunities
higher-voltage rad-hard MOSFETs, lower-loss power conversion and commercial-space cost optimization
higher-voltage rad-hard MOSFETs, lower-loss power conversion and commercial-space cost optimization can expand value per unit and improve system performance. Commercial decisions in the Radiation Hardened Power Semiconductor market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Regional manufacturing
New qualified capacity can support customers seeking geographic diversification. Commercial decisions in the Radiation Hardened Power Semiconductor market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Automation and inspection
Better process control can raise yield and reduce lifecycle cost. Commercial decisions in the Radiation Hardened Power Semiconductor market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Application-specific products
Tailored designs can capture premium niches with stronger qualification barriers. Commercial decisions in the Radiation Hardened Power Semiconductor market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Supply Chain Analysis
Upstream. Specialized materials, wafers, laminates, metals or process equipment provide the technical foundation. Quality at this stage influences downstream yield and reliability. Commercial decisions in the Radiation Hardened Power Semiconductor market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Manufacturing. Suppliers use precision process control and automated inspection to produce Radiation Hardened Power Semiconductor products within tight tolerances. Yield improvement is a major economic lever. Commercial decisions in the Radiation Hardened Power Semiconductor market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Integration. Products are qualified inside customer systems where electrical, thermal or mechanical behavior is validated. Design changes can trigger additional testing. Commercial decisions in the Radiation Hardened Power Semiconductor market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Deployment. Finished products enter electronics, industrial, automotive, data-center or aerospace systems. Lifecycle support and supply continuity determine long-term customer value. Commercial decisions in the Radiation Hardened Power Semiconductor market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Recent Developments in the Radiation Hardened Power Semiconductor Market
Developments tracked through September 2026 and limited to events that materially affect technology, capacity, adoption or competition.
- 2026 Space Electronics
Microchip continues offering radiation-tolerant and radiation-hardened power and mixed-signal products for satellite and spacecraft applications. Source - 2026 Rad-Hard Power
Infineon continues supplying space-qualified power MOSFET technologies targeting harsh radiation environments. Source - 2026 Commercial Space
The expansion of satellite constellations increases demand for lower-cost radiation-tolerant power conversion while high-value missions retain fully hardened devices. Source
Report Scope & Segmentation
| Attribute | Scope |
|---|---|
| Base year | 2025 |
| Estimated year | 2026 |
| Forecast period | 2026–2034 |
| 2025 market size | USD 254.02 million |
| 2026 estimated size | USD 268.86 million |
| 2034 projected size | USD 423.46 million |
| CAGR (2026–2034) | 5.8% |
| Largest market in 2025 | North America |
| By Type | MOSFET; Bipolar Junction Transistor; Diode; Others |
| By Application | Satellite; Launch Vehicle; Spacecraft Power Systems; Nuclear & Defense Electronics |
| By Radiation Class | TID-Hardened; SEE-Hardened; Combined TID / SEE |
| By End User | Commercial Space; Defense & Government; Scientific Missions; Nuclear Industry |
| Companies profiled | Infineon, Microchip Technology, STMicroelectronics, Renesas, onsemi, Vishay, EPC Space and specialized rad-hard suppliers |
Frequently Asked Questions
What is the Radiation Hardened Power Semiconductor market size in 2025?
The global market is valued at USD 254.02 million in 2025.
What is the market forecast for 2034?
The market is projected to reach USD 423.46 million by 2034, representing a 5.8% CAGR during 2026–2034. The 2026 market level is USD 268.86 million.
Which region leads the market?
North America is the largest market, while Asia Pacific has the strongest growth profile.
Which type is most important?
MOSFET is a leading category within the current market structure.
Which applications matter most?
Satellite and other listed applications are the principal demand segments.
What technology trend matters most?
higher-voltage rad-hard MOSFETs, lower-loss power conversion and commercial-space cost optimization is a major technology and competitive trend.
Who are the major suppliers?
Major participants include Infineon, Microchip Technology, STMicroelectronics, Renesas, onsemi, Vishay, EPC Space and specialized rad-hard suppliers.
What drives market growth?
Electronics content, technology upgrades, automation and supply-chain modernization are the main growth drivers.
What limits growth?
Capital intensity, qualification cycles, price pressure and supply-chain concentration are the main restraints.
What will shape the market through 2034?
higher-voltage rad-hard MOSFETs, lower-loss power conversion and commercial-space cost optimization, regional manufacturing diversification and more automated production will shape the market through 2034.
Research Sources & Evidence Base
View research sources used in this market overview
- Microchip Technology — Space Electronics. Current radiation-tolerant and space-qualified semiconductor context.
- Infineon — Radiation Hardened MOSFETs. Current rad-hard power MOSFET portfolio context.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF