Key Statistics
Key Takeaways
- Market value: the global photonic integrated circuit (pic) market is valued at USD 9,089 million in 2026 and is projected to reach USD 36,930 million by 2036, a CAGR of 15.0% during 2027–2036. AI-linked optical networks and rapidly evolving photonic packaging create demand for higher functional density, with wafer process qualification still limiting how quickly new devices can become recurring purchases.
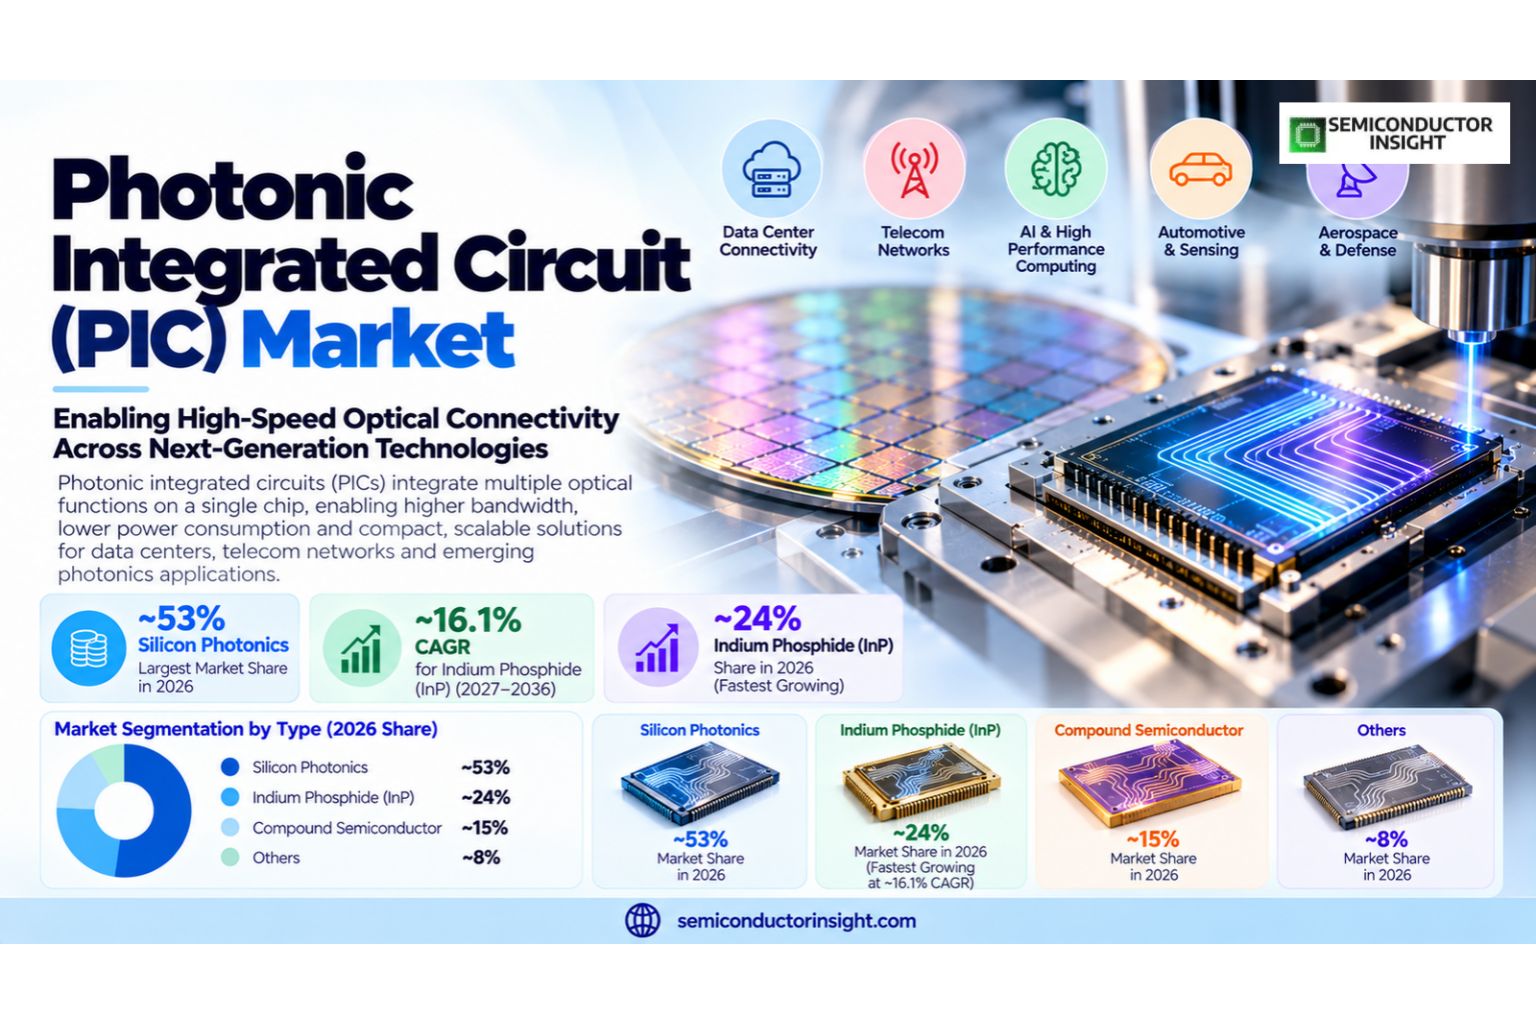
- Silicon Photonics leads: the largest type contributes an estimated ~53% of 2026 revenue, reflecting its repeatability, optical capability and established customer programmes. Indium Phosphide (InP) has the fastest type expansion at ~24% base-year share and ~16.1% CAGR as its production and packaging formats become better matched to higher-performance equipment.
- Data Center Interconnects remains the leading application: an estimated ~55% of 2026 revenue arises from this category, with qualification dependent upon functional throughput and reliability. Quantum Computing is the fastest-growing application at about ~16.6% CAGR; its value creation differs because it demands distinct optical operating parameters and downstream certification.
- North America leads global spending: the region has an estimated ~36% of 2026 revenue as optical device expertise and downstream demand converge. Asia-Pacific is the fastest-growing geography at an estimated ~16.5% CAGR, while buyers in other markets continue to favor repeatable proven devices with vendor support and visible qualification paths.
- Manufacturing and adoption constraints: precise fibre attachment, laser aging, heat dissipation, variable foundry design rules and optical wafer test requirements restrain yields and increase qualification expense. Customers increasingly need integrated electronic and optical packages, making the supplier ecosystem and capital spending cycles as important to revenues as the underlying optical performance of a standalone die.
Photonic Integrated Circuit (PIC) Market Overview
Photonic integrated circuit (pic) market was valued at USD 9,089 million in 2026 and is projected to reach USD 36,930 million by 2036, growing at a CAGR of 15.0% over the 2027–2036 forecast period. North America held the largest share in 2026 at an estimated ~36%, with purchases tied to optical transport infrastructure, device production and specialist photonic design.
A photonic integrated circuit implements multiple optical functions through lithographically defined structures such as waveguides, interferometers, splitters, modulators and detectors. Unlike a board assembled from discrete lasers and optics, a PIC controls optical phase and signal paths within a fabricated device. The relevant commercial product is the qualified photonic circuit or optical engine, not the electricity-consuming servers or complete network in which the photonic chip ultimately operates. Photonic Integrated Circuit (PIC) technologies often combine photonic and electrical functions through precision packaging and testing.
The market boundary covers the recognized sale of PIC die, optical engines and integrated photonic functional devices used in communication, computing, sensing and quantum systems; package-only assembly, electronic processors and passive fibre cable are outside the revenue boundary. The distinction is necessary because device makers, foundries, optical module vendors and network-equipment firms disclose revenue using different definitions. A photonics fabrication service, a photonic die and a fully integrated switch can all be associated with the same optical link; treating each as an independent final-market sale would multiply the value assigned to one end use.
Process architecture changes product economics. Silicon waveguides are compatible with mature semiconductor equipment, InP contributes direct-bandgap emitters, silicon nitride can support low-loss passive routing and electronic driver chips control modulation. Silicon wafer testing, known-good-die selection, laser attachment and stable fibre coupling determine sellable yield. Tower introduced a 300 mm photonics foundry route in November 2024, while ST announced high-volume 300 mm PIC100 production in March 2026, reinforcing the importance of repeatable wafer processes.
Final demand is propelled by optical channels inside high-performance AI computing, telecommunication transport and specialized precision instruments. NVIDIA introduced photonics network switches in March 2025; Intel states that its silicon photonics platform has shipped more than eight million PICs and more than 32 million integrated lasers. These engineering and deployment facts support the scale and maturity of optical designs, without making either company shipment data directly equivalent to the revenue total for photonic integrated circuit (pic) devices.
The market is changing as chip suppliers move from discrete optical engines toward denser electronic-photonic packaging. Tower outlined wafer-level stacking of PIC and electronic IC structures in November 2025, and GlobalFoundries announced a proposed U.S. R&D award in July 2026 to advance optical materials and hybrid bonding. Qualification periods, laser sourcing, foundry design kits and optical package assembly therefore influence which firms can supply dependable volume, even where prototype device performance is already attractive.
Segment Analysis: By Type
By type, photonic integrated circuit (pic) is classified as Silicon Photonics, Indium Phosphide (InP), Compound Semiconductor, Others. Silicon Photonics accounts for the largest estimated 2026 share of ~53%, while Indium Phosphide (InP) advances fastest at ~16.1% CAGR from ~24% of the base year. Commercial differences are rooted in fabrication processes, optical source availability, circuit functions and the cost of achieving stable manufacturing yield.
| Type | Function | Market position |
|---|---|---|
| Silicon Photonics | CMOS-compatible waveguides, electro-optic modulators and germanium detectors enable dense parallel lanes on mature silicon manufacturing equipment. The architectural difficulty is supplying stable lasers and maintaining low optical loss across large chips, so co-designed electronic drivers, wafer probing and laser attachment increasingly determine delivered commercial yield. A supplier is rewarded when fabrication control, optical wafer probing and component design rules produce a stable qualified device over repeated lots. The purchaser compares optical loss, thermal stability and test evidence before awarding a long-running programme. | Largest type; estimated ~53% share, ~15.4% CAGR. Commercial position depends on production-compatible process recipes, attachable lasers and test costs, not the popularity of the material name alone. A platform becomes attractive when the cost of qualifying a replacement design is outweighed by optical efficiency, delivery reliability and repeatable finished-device yield. Buyers also review long-term price erosion, capital availability and multiple-source packaging plans, especially where photonic components are qualified within multi-vendor transceivers. |
| Indium Phosphide (InP) | Indium phosphide provides electrically driven laser gain and semiconductor optical amplifiers as well as high-speed modulators and photodiodes. Its direct bandgap makes it strategically important for coherent network engines and external light sources, while epitaxy, crystal defects, chip handling and narrower qualified manufacturing capacity increase device cost. A supplier is rewarded when fabrication control, optical wafer probing and component design rules produce a stable qualified device over repeated lots. The purchaser compares optical loss, thermal stability and test evidence before awarding a long-running programme. | Fastest-growing type; estimated ~24% share, ~16.1% CAGR. Commercial position depends on production-compatible process recipes, attachable lasers and test costs, not the popularity of the material name alone. A platform becomes attractive when the cost of qualifying a replacement design is outweighed by optical efficiency, delivery reliability and repeatable finished-device yield. Buyers also review long-term price erosion, capital availability and multiple-source packaging plans, especially where photonic components are qualified within multi-vendor transceivers. |
| Compound Semiconductor | Specialized non-silicon platforms address wavelength, gain and power requirements that silicon alone cannot satisfy. Devices based on distinct III-V material stacks supply compact coherent sources, specialty detectors and photonic functions that are demanding in quantum or aerospace use, but heterogeneous packaging and thermal control restrict unit economics. A supplier is rewarded when fabrication control, optical wafer probing and component design rules produce a stable qualified device over repeated lots. The purchaser compares optical loss, thermal stability and test evidence before awarding a long-running programme. | Specialized type; estimated ~15% share, ~13.8% CAGR. Commercial position depends on production-compatible process recipes, attachable lasers and test costs, not the popularity of the material name alone. A platform becomes attractive when the cost of qualifying a replacement design is outweighed by optical efficiency, delivery reliability and repeatable finished-device yield. Buyers also review long-term price erosion, capital availability and multiple-source packaging plans, especially where photonic components are qualified within multi-vendor transceivers. |
| Others | Research and emerging chip substrates include silicon nitride passive circuits and other application-specific stacks that are sold in low to moderate production volumes. The commercial value lies in unusually low waveguide loss or specialized sensing wavelengths rather than in the mainstream optical-interconnect socket, leading to longer qualification and project-dependent ordering. A supplier is rewarded when fabrication control, optical wafer probing and component design rules produce a stable qualified device over repeated lots. The purchaser compares optical loss, thermal stability and test evidence before awarding a long-running programme. | Specialized type; estimated ~8% share, ~11.6% CAGR. Commercial position depends on production-compatible process recipes, attachable lasers and test costs, not the popularity of the material name alone. A platform becomes attractive when the cost of qualifying a replacement design is outweighed by optical efficiency, delivery reliability and repeatable finished-device yield. Buyers also review long-term price erosion, capital availability and multiple-source packaging plans, especially where photonic components are qualified within multi-vendor transceivers. |
Secondary segmentation: end user
By End User exposes a further commercial split beyond the optical type families. The largest member, Cloud Service Providers, represents an estimated ~54% of 2026 market value. These classifications describe purchaser or architecture requirements rather than additional standalone revenue pools; functional capacity, expected environment, device-level qualification and supply commitments determine commercial adoption. Comparisons among members should consider reliable system integration and the maturity of production design kits.
| Axis | Members | Commercial role |
|---|---|---|
| By End User | Cloud Service Providers · ~54% in 2026 | Cloud Service Providers has an estimated ~54% base-year allocation within this classification. This category captures photonic devices whose procurement is defined by the named technical or customer function; qualification procedures and component-level margins therefore differ from the underlying material-platform split. In practice the purchasing decision also depends upon optical loss, package constraints, expected service life and whether a preferred foundry can reproduce the design consistently. |
| By End User | Telecom Operators · ~25% in 2026 | Telecom Operators has an estimated ~25% base-year allocation within this classification. This category captures photonic devices whose procurement is defined by the named technical or customer function; qualification procedures and component-level margins therefore differ from the underlying material-platform split. In practice the purchasing decision also depends upon optical loss, package constraints, expected service life and whether a preferred foundry can reproduce the design consistently. |
| By End User | Automotive OEMs · ~10% in 2026 | Automotive OEMs has an estimated ~10% base-year allocation within this classification. This category captures photonic devices whose procurement is defined by the named technical or customer function; qualification procedures and component-level margins therefore differ from the underlying material-platform split. In practice the purchasing decision also depends upon optical loss, package constraints, expected service life and whether a preferred foundry can reproduce the design consistently. |
| By End User | Research Institutions · ~7% in 2026 | Research Institutions has an estimated ~7% base-year allocation within this classification. This category captures photonic devices whose procurement is defined by the named technical or customer function; qualification procedures and component-level margins therefore differ from the underlying material-platform split. In practice the purchasing decision also depends upon optical loss, package constraints, expected service life and whether a preferred foundry can reproduce the design consistently. |
| By End User | Others · ~4% in 2026 | Others has an estimated ~4% base-year allocation within this classification. This category captures photonic devices whose procurement is defined by the named technical or customer function; qualification procedures and component-level margins therefore differ from the underlying material-platform split. In practice the purchasing decision also depends upon optical loss, package constraints, expected service life and whether a preferred foundry can reproduce the design consistently. |
Secondary segmentation: technology
By Technology exposes a further commercial split beyond the optical type families. The largest member, Active Components, represents an estimated ~31% of 2026 market value. These classifications describe purchaser or architecture requirements rather than additional standalone revenue pools; functional capacity, expected environment, device-level qualification and supply commitments determine commercial adoption. Comparisons among members should consider reliable system integration and the maturity of production design kits.
| Axis | Members | Commercial role |
|---|---|---|
| By Technology | Passive Components · ~24% in 2026 | Passive Components has an estimated ~24% base-year allocation within this classification. This category captures photonic devices whose procurement is defined by the named technical or customer function; qualification procedures and component-level margins therefore differ from the underlying material-platform split. In practice the purchasing decision also depends upon optical loss, package constraints, expected service life and whether a preferred foundry can reproduce the design consistently. |
| By Technology | Active Components · ~31% in 2026 | Active Components has an estimated ~31% base-year allocation within this classification. This category captures photonic devices whose procurement is defined by the named technical or customer function; qualification procedures and component-level margins therefore differ from the underlying material-platform split. In practice the purchasing decision also depends upon optical loss, package constraints, expected service life and whether a preferred foundry can reproduce the design consistently. |
| By Technology | Hybrid Integration · ~29% in 2026 | Hybrid Integration has an estimated ~29% base-year allocation within this classification. This category captures photonic devices whose procurement is defined by the named technical or customer function; qualification procedures and component-level margins therefore differ from the underlying material-platform split. In practice the purchasing decision also depends upon optical loss, package constraints, expected service life and whether a preferred foundry can reproduce the design consistently. |
| By Technology | Monolithic Integration · ~12% in 2026 | Monolithic Integration has an estimated ~12% base-year allocation within this classification. This category captures photonic devices whose procurement is defined by the named technical or customer function; qualification procedures and component-level margins therefore differ from the underlying material-platform split. In practice the purchasing decision also depends upon optical loss, package constraints, expected service life and whether a preferred foundry can reproduce the design consistently. |
| By Technology | Others · ~4% in 2026 | Others has an estimated ~4% base-year allocation within this classification. This category captures photonic devices whose procurement is defined by the named technical or customer function; qualification procedures and component-level margins therefore differ from the underlying material-platform split. In practice the purchasing decision also depends upon optical loss, package constraints, expected service life and whether a preferred foundry can reproduce the design consistently. |
Secondary segmentation: deployment scenario
By Deployment Scenario exposes a further commercial split beyond the optical type families. The largest member, Core Network, represents an estimated ~39% of 2026 market value. These classifications describe purchaser or architecture requirements rather than additional standalone revenue pools; functional capacity, expected environment, device-level qualification and supply commitments determine commercial adoption. Comparisons among members should consider reliable system integration and the maturity of production design kits.
| Axis | Members | Commercial role |
|---|---|---|
| By Deployment Scenario | Edge Computing · ~25% in 2026 | Edge Computing has an estimated ~25% base-year allocation within this classification. This category captures photonic devices whose procurement is defined by the named technical or customer function; qualification procedures and component-level margins therefore differ from the underlying material-platform split. In practice the purchasing decision also depends upon optical loss, package constraints, expected service life and whether a preferred foundry can reproduce the design consistently. |
| By Deployment Scenario | Core Network · ~39% in 2026 | Core Network has an estimated ~39% base-year allocation within this classification. This category captures photonic devices whose procurement is defined by the named technical or customer function; qualification procedures and component-level margins therefore differ from the underlying material-platform split. In practice the purchasing decision also depends upon optical loss, package constraints, expected service life and whether a preferred foundry can reproduce the design consistently. |
| By Deployment Scenario | On-Chip AI Accelerators · ~22% in 2026 | On-Chip AI Accelerators has an estimated ~22% base-year allocation within this classification. This category captures photonic devices whose procurement is defined by the named technical or customer function; qualification procedures and component-level margins therefore differ from the underlying material-platform split. In practice the purchasing decision also depends upon optical loss, package constraints, expected service life and whether a preferred foundry can reproduce the design consistently. |
| By Deployment Scenario | Space Communications · ~7% in 2026 | Space Communications has an estimated ~7% base-year allocation within this classification. This category captures photonic devices whose procurement is defined by the named technical or customer function; qualification procedures and component-level margins therefore differ from the underlying material-platform split. In practice the purchasing decision also depends upon optical loss, package constraints, expected service life and whether a preferred foundry can reproduce the design consistently. |
| By Deployment Scenario | Others · ~7% in 2026 | Others has an estimated ~7% base-year allocation within this classification. This category captures photonic devices whose procurement is defined by the named technical or customer function; qualification procedures and component-level margins therefore differ from the underlying material-platform split. In practice the purchasing decision also depends upon optical loss, package constraints, expected service life and whether a preferred foundry can reproduce the design consistently. |
Segment Analysis: By Application
By application, the market comprises Data Center Interconnects, Telecom-grade Transceivers, Autonomous Vehicles, Quantum Computing, Others. Data Center Interconnects accounts for an estimated ~55% of revenue in 2026, with a ~15.8% CAGR. Quantum Computing exhibits the fastest estimated growth at ~16.6% CAGR, reflecting its distinct reliability and system-integration needs. The allocation follows end use of the integrated photonic function, not the classification of the final electronics equipment manufacturer.
| Application | Demand characteristics |
|---|---|
| Data Center Interconnects | Estimated ~55% 2026 market share; ~15.8% CAGR. Large AI cluster fabrics require short- and medium-reach optical channels whose bandwidth is scaling from 400G and 800G toward 1.6T. Buyers qualify complete electrical, optical and packaging performance; PIC revenue rises with channel density and laser complexity rather than simply with raw server counts. Demand reaches PIC producers after a buyer qualifies the optical function, circuit packaging and applicable equipment interface. A fabless designer can capture durable sales if a stable process design kit and predictable supplier contracts allow the same component to be manufactured over multiple product generations. |
| Telecom-grade Transceivers | Estimated ~24% 2026 market share; ~13.3% CAGR. Carrier networks use coherent optical engines in access, metro and long-haul transmission where spectral efficiency, operating life and network-vendor qualification outweigh the lowest initial part price. InP gain and tunable laser functions remain valuable while coherent DSP and optics packaging govern long qualification cycles. Demand reaches PIC producers after a buyer qualifies the optical function, circuit packaging and applicable equipment interface. A fabless designer can capture durable sales if a stable process design kit and predictable supplier contracts allow the same component to be manufactured over multiple product generations. |
| Autonomous Vehicles | Estimated ~9% 2026 market share; ~14.9% CAGR. Lidar and distributed vehicle sensing use photonic chips to combine light generation, steering and receiving functions in smaller assemblies. Vehicle deployments impose vibration, automotive-grade thermal specifications and multiyear reliability qualification, creating a slower revenue conversion than prototype counts alone might suggest. Demand reaches PIC producers after a buyer qualifies the optical function, circuit packaging and applicable equipment interface. A fabless designer can capture durable sales if a stable process design kit and predictable supplier contracts allow the same component to be manufactured over multiple product generations. |
| Quantum Computing | Estimated ~7% 2026 market share; ~16.6% CAGR. Quantum-photonics equipment needs low-loss waveguides, source control, beam splitting and precise detector interfacing. Foundry-access platforms are expanding this opportunity, but small processor volumes, cryogenic interfaces and reproducibility of optical quantum states make customer programs less predictable than mainstream communications procurement. Demand reaches PIC producers after a buyer qualifies the optical function, circuit packaging and applicable equipment interface. A fabless designer can capture durable sales if a stable process design kit and predictable supplier contracts allow the same component to be manufactured over multiple product generations. |
| Others | Estimated ~5% 2026 market share; ~11.7% CAGR. Biomedical interrogation, industrial optical sensors and secure-specialty systems use custom wavelength bands and small-chip footprints. Project economics are driven by sensor accuracy, optical calibration, instrument-integration cost and regulatory validation rather than by the bulk link-density incentives of AI data centers. Demand reaches PIC producers after a buyer qualifies the optical function, circuit packaging and applicable equipment interface. A fabless designer can capture durable sales if a stable process design kit and predictable supplier contracts allow the same component to be manufactured over multiple product generations. |
Sales channels differ between the two largest application categories and the emerging specialist users. Hyperscalers normally specify device performance through major optical module or system providers; telecom operators qualify network families over multi-year periods, while sensing customers commission designs and place smaller production lots. Consequently, the same photonic foundry may supply multiple markets through distinct manufacturing, licensing and channel arrangements, with pricing influenced by optical coupling, field reliability and die-level testing.
Regional Analysis
North America leads with an estimated ~36% of 2026 revenue, followed by Asia-Pacific (~34%) and Europe (~19%). Asia-Pacific grows fastest at ~16.5% CAGR. Regional buyers differ because established manufacturing concentration, optical-system design teams, government projects and network procurement do not coincide geographically. A supplier may fabricate chips in one region, package them in another and recognize customer sales in a third.
How do market demand, photonic device production and procurement differ across the five regions?
North America buys high-performance integrated optics through hyperscaler qualification and specialized wafer development. Asia-Pacific combines foundry expansion, optics assembly and rapidly expanding communications infrastructure. Europe emphasizes shared photonic pilot facilities and quality-sensitive sensing systems. South America depends heavily on imports through optical transport contractors, while the Middle East and Africa combine national networks with specialized Israeli foundry activity. A five-region view therefore captures different design-win cycles rather than assuming one common optical purchasing model.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| North America | Largest region, estimated ~36% of 2026 photonic-device revenue. Its position reflects the mixture of optical manufacturing, semiconductor engineering and customers able to qualify high-density integrated optical parts. Suppliers serve both direct device buyers and manufacturers of network or sensing products, so regional manufacturing capacity and recognized final-market demand are not interchangeable. The ranking is shaped by deployable products rather than by research publication counts or broad semiconductor revenue. | Estimated ~14.0% CAGR through 2036, supported by ai data center demand, upstream wafer r&d, precision inp sources and reliability qualification. This directional growth expectation includes both recurring module design wins and limited specialty projects. Orders still arrive through device qualification milestones, with manufacturing cost and demand growth varying between metro networks, hyperscale installations and specialist instruments. | The dominant demand profile comprises ai data center demand, upstream wafer r&d, precision inp sources and reliability qualification. Customer requirements range from reliably transmitting high-capacity data to preserving optical signal accuracy in harsh sensing environments. Application mixes also reflect whether a market builds wafer production locally or imports finished optical equipment. The commercial route therefore differs substantially from the headline global industry growth. | Access depends on supplier origin, qualification traceability and co-design engagement, with qualification imposed by optical-module companies, system vendors, foundries or specialist equipment makers. Delivered device yield, wavelength stability, documented process changes, lifetime data and fibre-attach tolerances influence approved vendor status. Extended support and predictable purchasing terms can outweigh initial wafer cost once a photonic component is integrated into critical infrastructure. |
| Asia-Pacific | Second largest region, estimated ~34% of 2026 photonic-device revenue. Its position reflects the mixture of optical manufacturing, semiconductor engineering and customers able to qualify high-density integrated optical parts. Suppliers serve both direct device buyers and manufacturers of network or sensing products, so regional manufacturing capacity and recognized final-market demand are not interchangeable. The ranking is shaped by deployable products rather than by research publication counts or broad semiconductor revenue. | Estimated ~16.5% CAGR through 2036, supported by foundry and packaging scale, specialist manufacturing and telecom network build-outs. This directional growth expectation includes both recurring module design wins and limited specialty projects. Orders still arrive through device qualification milestones, with manufacturing cost and demand growth varying between metro networks, hyperscale installations and specialist instruments. | The dominant demand profile comprises foundry and packaging scale, specialist manufacturing and telecom network build-outs. Customer requirements range from reliably transmitting high-capacity data to preserving optical signal accuracy in harsh sensing environments. Application mixes also reflect whether a market builds wafer production locally or imports finished optical equipment. The commercial route therefore differs substantially from the headline global industry growth. | Access depends on wafer yield, optical test throughput and cross-border trade compliance, with qualification imposed by optical-module companies, system vendors, foundries or specialist equipment makers. Delivered device yield, wavelength stability, documented process changes, lifetime data and fibre-attach tolerances influence approved vendor status. Extended support and predictable purchasing terms can outweigh initial wafer cost once a photonic component is integrated into critical infrastructure. |
| Europe | Third largest region, estimated ~19% of 2026 photonic-device revenue. Its position reflects the mixture of optical manufacturing, semiconductor engineering and customers able to qualify high-density integrated optical parts. Suppliers serve both direct device buyers and manufacturers of network or sensing products, so regional manufacturing capacity and recognized final-market demand are not interchangeable. The ranking is shaped by deployable products rather than by research publication counts or broad semiconductor revenue. | Estimated ~14.2% CAGR through 2036, supported by research-to-production pilots, industrial sensing, coherent networking and energy efficiency. This directional growth expectation includes both recurring module design wins and limited specialty projects. Orders still arrive through device qualification milestones, with manufacturing cost and demand growth varying between metro networks, hyperscale installations and specialist instruments. | The dominant demand profile comprises research-to-production pilots, industrial sensing, coherent networking and energy efficiency. Customer requirements range from reliably transmitting high-capacity data to preserving optical signal accuracy in harsh sensing environments. Application mixes also reflect whether a market builds wafer production locally or imports finished optical equipment. The commercial route therefore differs substantially from the headline global industry growth. | Access depends on standards compliance, optical validation and product reliability, with qualification imposed by optical-module companies, system vendors, foundries or specialist equipment makers. Delivered device yield, wavelength stability, documented process changes, lifetime data and fibre-attach tolerances influence approved vendor status. Extended support and predictable purchasing terms can outweigh initial wafer cost once a photonic component is integrated into critical infrastructure. |
| Middle East & Africa | Fourth region, estimated ~7% of 2026 photonic-device revenue. Its position reflects the mixture of optical manufacturing, semiconductor engineering and customers able to qualify high-density integrated optical parts. Suppliers serve both direct device buyers and manufacturers of network or sensing products, so regional manufacturing capacity and recognized final-market demand are not interchangeable. The ranking is shaped by deployable products rather than by research publication counts or broad semiconductor revenue. | Estimated ~15.6% CAGR through 2036, supported by high-availability optical transport, national digital projects and specialist foundry development. This directional growth expectation includes both recurring module design wins and limited specialty projects. Orders still arrive through device qualification milestones, with manufacturing cost and demand growth varying between metro networks, hyperscale installations and specialist instruments. | The dominant demand profile comprises high-availability optical transport, national digital projects and specialist foundry development. Customer requirements range from reliably transmitting high-capacity data to preserving optical signal accuracy in harsh sensing environments. Application mixes also reflect whether a market builds wafer production locally or imports finished optical equipment. The commercial route therefore differs substantially from the headline global industry growth. | Access depends on turnkey vendor qualification, heat tolerance and long service support, with qualification imposed by optical-module companies, system vendors, foundries or specialist equipment makers. Delivered device yield, wavelength stability, documented process changes, lifetime data and fibre-attach tolerances influence approved vendor status. Extended support and predictable purchasing terms can outweigh initial wafer cost once a photonic component is integrated into critical infrastructure. |
| South America | Fifth region, estimated ~4% of 2026 photonic-device revenue. Its position reflects the mixture of optical manufacturing, semiconductor engineering and customers able to qualify high-density integrated optical parts. Suppliers serve both direct device buyers and manufacturers of network or sensing products, so regional manufacturing capacity and recognized final-market demand are not interchangeable. The ranking is shaped by deployable products rather than by research publication counts or broad semiconductor revenue. | Estimated ~14.9% CAGR through 2036, supported by carrier backbone investment, replacement purchasing and specialist industrial sensing. This directional growth expectation includes both recurring module design wins and limited specialty projects. Orders still arrive through device qualification milestones, with manufacturing cost and demand growth varying between metro networks, hyperscale installations and specialist instruments. | The dominant demand profile comprises carrier backbone investment, replacement purchasing and specialist industrial sensing. Customer requirements range from reliably transmitting high-capacity data to preserving optical signal accuracy in harsh sensing environments. Application mixes also reflect whether a market builds wafer production locally or imports finished optical equipment. The commercial route therefore differs substantially from the headline global industry growth. | Access depends on import economics, network-vendor approvals and project financing, with qualification imposed by optical-module companies, system vendors, foundries or specialist equipment makers. Delivered device yield, wavelength stability, documented process changes, lifetime data and fibre-attach tolerances influence approved vendor status. Extended support and predictable purchasing terms can outweigh initial wafer cost once a photonic component is integrated into critical infrastructure. |
Competitive Landscape
Photonic Integrated Circuit (PIC) manufacturing spans integrated optical chip designers, foundries, active-material suppliers and equipment makers. Intel describes millions of delivered silicon PICs, while Tower, ST and GlobalFoundries compete through wafer and packaging process enablement. InP laser and photodiode availability remains important. Sales are therefore determined by optical function, fab qualifications and ownership of a design win rather than by a general-purpose semiconductor company ranking.
Silicon device specialists compete on production yield, wavelength loss, design kit stability and manufacturability of low-power modulators. Intel reports an integrated laser approach in shipped pluggable products; Tower supplies photonic process technology that complements customer-designed chips. Such participants occupy different points in the chain, so direct comparisons using parent-company total sales can distort their competitive positions.
Optical networking companies differentiate through end-to-end qualification. Cisco acquired Acacia for coherent technology, while Ciena and Nokia address equipment-level transmission architectures with differing levels of internal photonics. Coherent and Lumentum develop active components such as lasers and detectors that can also feed chips sold by other suppliers. Commercial concentration consequently depends on product architecture and captured device value, not one static list of brands.
Foundry access is becoming a competitive instrument. ST announced 300 mm PIC100 volume output in March 2026, and Tower expanded process access through 300 mm wafer platforms. GlobalFoundries has described optical materials and hybrid bonding work. These investments can lower the barrier facing fabless photonic designers, but each customer must still pass optical circuit and packaging verification before ramping into high repeat-order volumes.
Legacy company names need careful interpretation in technical procurement. The profiled landscape includes historical semiconductor names that survive as acquisition lineages, component brands or corporate predecessor entities; inclusion in a historical list does not establish independent 2026 sales. Customers should evaluate the currently responsible design owner and supplying legal entity before interpreting product availability, warranties or geographic exposure.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Tier 1 — PIC platforms | Intel Corp.; STMicroelectronics; Coherent; Lumentum Holdings Inc.; Tower Semiconductor | These companies offer or directly enable photonic semiconductor platforms, integrated optical functions and active materials used in merchant or vertically integrated supply chains. Commercial competition centers on reliability, qualified manufacturing scale, laser and waveguide performance, wafer testing and stable design-rule support. Revenue attribution must distinguish die sales from services, complete modules and parent-company corporate figures. |
| Tier 2 — optical device and network integration | Cisco Systems Inc.; Acacia Communications; Ciena Corp.; Nokia; GlobalFoundries | These firms qualify, integrate or fabricate photonic technologies in optical networking or customer-specific platforms. Their roles vary: some are network systems suppliers, some optical device designers and others foundry providers, so tier membership does not assert that all sell identical standalone PIC chips. The controlling competitive evidence is a verified available device programme, production process or optical engine. |
| Tier 3 — adjacent component and system ecosystem | Broadcom Inc.; NTT Electronics; Soitec; Qualcomm; historical names in the profiled list | Suppliers of supporting electronics, waveguide materials and finished systems influence the photonic cost stack without necessarily selling the same PIC revenue product. The company population includes predecessors and acquired businesses that warrant legal-entity reconciliation. Commercial relevance comes from driver electronics, materials, module assembly, distribution or customer equipment access rather than generic market presence. |
Key companies profiled
- Intel Corp.
- Lumentum Holdings Inc.
- Cisco Systems Inc.
- Acacia Communications
- Infinera Corp.
- II-VI Incorporated
- Ciena Corp.
- Broadcom Inc.
- STMicroelectronics
- Soitec
- GlobalFoundries
- NTT Electronics
- Nokia
- NeoPhotonics
- Qualcomm
Production Capacity Analysis
Photonic integrated circuit capacity is determined by more than the number of wafers processed. Wafer starts must be converted to known-good optical dice after waveguide loss screening, modulation tests, laser attachment and final optical coupling. Silicon photonics, indium phosphide and specialized material stacks use different factory toolsets. The relevant bottleneck can move from wafer processing to electronic-photonic packaging when production volumes rise.
Large-scale silicon PIC fabrication can draw upon 200 mm and 300 mm semiconductor infrastructure, but compatible process design kits and optical metrology remain essential. Tower introduced a 300 mm process in 2024, ST began PIC100 high-volume production in March 2026, and Tower subsequently outlined Japanese expansion for late 2027. These events illustrate tangible improvements in platform availability without disclosing an aggregated global PIC wafer-capacity figure.
Diversification is becoming commercially important as module designers seek resilience across countries and foundry sites. Japanese photonics expansion, U.S. optical materials R&D proposals and European pilot-line investments strengthen the manufacturing ecosystem. Device qualification cannot be moved instantly, however, because a change of foundry may alter waveguide dimensions, modulator behavior or bonding yield and therefore trigger new optical qualification cycles.
Upstream constraints include epitaxial InP wafers, laser chips, precision fibre arrays, advanced die attach, reliable thermo-electric control and test automation. Coherent described its 2026 InP supply portfolio and proposed U.S. fabrication expansion, confirming the strategic value of active-material sources. The limiting factor for a particular product can be long-duration laser reliability or assembly yield rather than nominal availability of fab cleanroom floor space.
Market Dynamics
The operating economics of photonic integrated circuit (pic) devices are driven by bandwidth, power per bit, optical integration cost, fab availability and customer qualification. Stronger AI optical-network investment coexists with expensive fibre attachment, thermal design and laser sourcing. Demand growth is therefore heterogeneous, with large optical communication programmes scaling faster than some bespoke sensing projects that must still prove reliability and manufacturability.
MARKET DRIVERS
Drivers Impact Analysis*
| Driver | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| AI cluster optical bandwidth | +2.3% | North America and Asia-Pacific | 2026–2030 |
| 300 mm silicon photonics output | +1.7% | Asia-Pacific and Europe | 2027–2032 |
| Heterogeneous PIC and electronic integration | +1.2% | North America and Europe | 2026–2034 |
| Telecom core and metro modernization | +1.0% | Worldwide carrier networks | 2026–2031 |
| Quantum and advanced sensing programmes | +0.8% | Europe and selected research hubs | 2027–2036 |
Accelerated optical link density
AI training clusters require more connections among processors, storage and network switches. NVIDIA presented photonics-enabled networking in March 2025, while Intel lists multi-terabit optical I/O research. As aggregate link speed rises, discrete optical components become harder to package within constrained energy and area budgets. Integrated circuit designs can combine modulation, detection and waveguide routing, making dense optical engines commercially attractive where customers can validate lifetime performance and available manufacturing supply.
Qualified 300 mm fabrication routes
ST described PIC100 high-volume production in March 2026 and Tower had already established a standard 300 mm silicon photonics offering in November 2024. These moves improve the feasibility of larger repeatable production lots and standardized design kits. Customers still need to establish yield statistics, optical loss budgets and thermal reliability for each chip generation, but the progression from small pilot runs to sustained fab output broadens the set of commercially viable optical functions.
Electronic-photonic packaging density
Wafer stacking, hybrid bonding and near-packaged optical engines shorten electrical connections between modulation drivers and photonic circuits. Tower announced a platform for stacked photonic and electronic ICs in November 2025 and GlobalFoundries disclosed a related R&D proposal in July 2026. Increasing package density can improve energy and board area economics; however, it also transfers value toward precision assembly, thermal management and integrated circuit inspection capabilities.
Wider application-specific demand
Optical sensing and photonic quantum hardware create demand that differs from telecom transmission. Tower and Xanadu reported expanded joint photonic quantum manufacturing efforts in February 2026, while European and Indian institutions support programmable PIC design and pilot lines. These emerging product categories may offer premium value per qualified die, although commercialization depends on repeatable manufacturing and successful system-level testing rather than on research activity alone.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Restraint | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Precision optical packaging cost | -1.8% | Worldwide | 2026–2030 |
| InP laser qualification | -1.3% | United States and Asia | 2026–2033 |
| Foundry process incompatibility | -1.0% | North America, Europe and Asia | 2026–2036 |
| Long instrument design-win cycles | -0.7% | Research and industrial buyers | 2027–2036 |
Fibre coupling and test economics
A device can perform well at the wafer probe stage yet fail final-package optical-loss targets after fibre attachment. High-speed couplers, polarization alignment, thermal cycling and contamination control require precise automation and potentially lengthy rework. These factors erode margins when optical modules face falling selling prices, especially for smaller chip designs that lack production volume to amortize specialized test capital.
Active material supply and reliability
Silicon is not an efficient native light emitter at the wavelengths needed by many network systems, leaving reliable InP and other gain-material inputs strategically important. Coherent illustrated the breadth of 2026 laser and photodiode products and proposed a U.S. fabrication expansion. Customers frequently demand accelerated aging data and controlled optical output across operating temperature, increasing inventory, qualification costs and supplier exposure.
Fragmented fabrication design ecosystems
Material platforms differ in waveguide cross-sections, layer stacks, modulators and assembly methods, preventing painless transfer of a finished PIC design between foundries. A customer moving from prototype to 300 mm production may need layout changes and renewed optical characterization. European pilot-line collaboration and foundry process-design kits can reduce these barriers, but they do not eliminate material-specific validation or loss budgeting.
Uneven end-use adoption
The rate of PIC adoption in sensing and quantum systems is constrained by instrumentation budgets, calibration and integration with external detectors or clinical devices. Telecom equipment can also remain in service for years, producing replacement cycles instead of uninterrupted volume expansion. The resulting stop-start purchasing makes specialized applications more variable than AI data-center optical channel growth even when both depend on related fabrication processes.
MARKET OPPORTUNITIES
Co-packaged optics system qualification
NVIDIA’s photonics networking launch and Tower’s stacked photonic/electronic platform create a route to place optical engines closer to switching silicon. Co-design of waveguides, drivers, lasers and package interfaces can reduce link energy and enable denser port counts. Commercial opportunities accrue to suppliers capable of demonstrating reliable optical attachment and assembly yield under system-grade thermal loading, rather than only to firms offering advanced bare-die performance.
Open foundry services and repeatable design libraries
The European Commission’s PIXEurope project aims to broaden access to photonic pilot-line capacity, while MeitY supports programmable silicon photonics in India. These efforts can help smaller design teams obtain standardized process data and wafer-level testing. The strategic opportunity lies in converting one-time prototypes into repeatable multi-project production schedules, enabling foundries and specialized packagers to amortize optical process characterization.
Quantum computing and precision sensing products
Tower and Xanadu’s 2026 collaboration signals continued engineering for photonic quantum systems. Similar waveguides and interferometric elements support advanced sensing architectures, although end-use wavelengths and package requirements differ. A successful commercial programme would combine fabricated photonic functions with detectors, calibration systems and field support, allowing chip makers to capture value in sophisticated instrumentation beyond conventional transceivers.
Energy-aware network redesign
The European Commission’s September 2026 data-centre efficiency work highlights the importance of transparently measured energy use in digital infrastructure. Integrated optical links can support higher bandwidth per unit of switching power if their laser drivers, control electronics and packaging are efficiently designed. Buyers are likely to focus increasingly on whole-link power, reliability and servicing costs, creating opportunities for qualified lower-loss photonic designs.
Supply Chain Analysis
Photonic Integrated Circuit (PIC) value passes through engineered materials, wafer fabrication, optical assembly and electronics customers. A working PIC requires more than patterned waveguides: laser or gain sourcing, packaging, test equipment and qualification data all influence the final invoice. Some vendors sell stand-alone dies, while others supply engines, IP, foundry wafers or complete equipment, so customer recognition varies across the chain.
Materials and devices. Waveguide loss, epitaxy uniformity and wafer surface quality define functional margins before any electronics are attached. Silicon photonics leverages mature fabrication capabilities, while indium phosphide laser production requires specialist compound semiconductor skills. Material decisions also determine which wavelengths and active optical gain functions can be integrated inside the finished circuit, shaping downstream optical-system efficiency and cost.
Process and testing. After a circuit has passed wafer probing, packaging must preserve coupler alignment, heat distribution and optical input-output reliability. Automated optical test makes high-volume manufacturing economically feasible, but advanced devices may still require costly burn-in and customer-specific screening. Repeatable wafer-scale metrology can thus be as consequential to commercial yield as the choice of optical chip material itself.
Qualification and distribution. Module manufacturers, network equipment firms and industrial instrument suppliers generally qualify photonic dies against a full equipment operating envelope. Design wins may be followed by several years of sustained component orders, but replacement of a qualified process can require additional tests and regulatory documentation. Distribution channels therefore value long-term supplier stability and traceable production lots.
End-use demand. Cloud computing pulls optical lane count and density upward, telecom networks require coherent reach and field longevity, and sensing users buy stable calibration and optical precision. These diverse uses support multiple pricing models for otherwise related waveguide technologies. Manufacturers serving more than one segment can diversify demand, although no two applications necessarily share identical package, wavelength or reliability requirements.
Recent Developments
- 29 July 2026 Announced
GlobalFoundries outlined a letter of intent with the U.S. Department of Commerce for a proposed USD 300 million photonics research award to develop optical materials, wafer processing and advanced packaging. The project supports future co-packaged optics development but remains a proposed programme rather than already recognized semiconductor sales. New process libraries and bonding options could eventually reduce product design barriers for network-scale PIC designers. Source - 14 July 2026 Announced
Tower Semiconductor described Japanese 300 mm silicon photonics and silicon germanium capacity expansion with government support. Its first phase, which repurposes existing fabrication assets, was expected to reach production readiness late in 2027. This matters for device procurement because broader qualified wafer availability can support supply assurance, but the announced capacity does not establish immediate customer purchasing or final photonic chip revenue. Source - 16 June 2026 Announced
Coherent reported an intended investment involving up to USD 50 million of proposed U.S. CHIPS support for its Sherman indium phosphide operation. The expansion targets laser and optical device demand associated with artificial intelligence interconnects. Additional active-material capacity would support diverse integrated photonic engines; however, delivered chips and commercially qualified equipment programmes remain the mechanisms through which production additions convert into sales. Source - 17 March 2026 Reported
Coherent presented an expanded indium phosphide optical portfolio for OFC 2026, including 200G electroabsorption lasers, higher-speed photodiodes and continuous-wave sources for silicon photonics. These products enable optical functions that pure silicon waveguides cannot readily supply. Commercial PIC integration still requires suitable driver electronics, stable fibre coupling and qualified package processes, making optical component performance one stage in a broader system solution. Source - 9 March 2026 Reported
STMicroelectronics announced high-volume silicon photonics production on its 300 mm PIC100 platform, targeting 800G and 1.6T data-centre interconnect applications. The company also outlined a plan to expand PIC100 output by 2027. The development signals a shift toward foundry-scale production discipline and repeatable optical testing, while customers must continue to qualify power consumption, long-term reliability and assembly yield in finished optical engines. Source - 19 February 2026 Announced
Tower Semiconductor and Xanadu expanded work on silicon photonics processes intended for fault-tolerant quantum computing hardware. Their collaboration includes joint tapeouts and tailored material-stack development aligned with repeatable production. Quantum photonic programmes create valuable process learning and potential specialty demand, but system scalability, detector integration and optical error control determine when such developments move from engineering lots toward repeated commercial shipments. Source - 12 November 2025 Announced
Tower Semiconductor disclosed wafer-scale stacking for silicon photonic and electronic IC technologies using manufacturing experience gained in stacked sensors. This process can shorten connections between optical chips and high-frequency driver electronics for co-packaged networking products. More compact assemblies can improve system-design options, but production value depends on mature bonding yield, thermal management and packaging-test throughput rather than on a single integration milestone. Source - 18 March 2025 Announced
NVIDIA announced Spectrum-X and Quantum-X photonics network switches aimed at very large AI clusters. The architecture incorporates optical engines with electronic switching systems and involves multiple optical materials, laser suppliers and advanced packaging partners. This creates a defined engineering direction for photonic integration, but improvements quoted for the full networking platform should not be interpreted as performance metrics of every standalone photonic integrated circuit. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2021–2036 |
| Base Year | 2026 |
| Estimated Year | 2027 |
| Forecast Period | 2027–2036 |
| Historical Period | 2021–2025 |
| 2026 Market Size | USD 9,089 million |
| 2027 Estimated Size | USD 10,457 million |
| 2036 Forecast Size | USD 36,930 million |
| Growth Rate | 15.0% |
| Revenue Unit | USD million |
| Market Definition | the recognized sale of PIC die, optical engines and integrated photonic functional devices used in communication, computing, sensing and quantum systems; package-only assembly, electronic processors and passive fibre cable are outside the revenue boundary |
| By Type | Silicon Photonics · Indium Phosphide (InP) · Compound Semiconductor · Others |
| By Application | Data Center Interconnects · Telecom-grade Transceivers · Autonomous Vehicles · Quantum Computing · Others |
| By End User | Cloud Service Providers · Telecom Operators · Automotive OEMs · Research Institutions · Others |
| By Technology | Passive Components · Active Components · Hybrid Integration · Monolithic Integration · Others |
| By Deployment Scenario | Edge Computing · Core Network · On-Chip AI Accelerators · Space Communications · Others |
| By Region | Regional coverage includes country-level demand and supplier production context, with estimated 2026 regional shares shown in the analysis. North AmericaUnited States · Canada · Mexico EuropeNetherlands · France · Germany · United Kingdom Asia-PacificChina · Japan · India · South Korea South AmericaBrazil · Chile · Argentina Middle East & AfricaSaudi Arabia · United Arab Emirates · Israel |
| Key Companies Profiled | Intel Corp.; Lumentum Holdings Inc.; Cisco Systems Inc.; Acacia Communications; Infinera Corp.; II-VI Incorporated; Ciena Corp.; Broadcom Inc.; STMicroelectronics; Soitec; GlobalFoundries; NTT Electronics; Nokia; NeoPhotonics; Qualcomm |
| Customization Scope | country demand, optical device architectures, wafer process analysis, customer segmentation, and company-level production and supply-chain analysis. |
Frequently Asked Questions
What is the photonic integrated circuit (pic) market size and forecast?
The global photonic integrated circuit (pic) market is estimated at USD 9,089 million in 2026 and forecast at USD 36,930 million in 2036, equivalent to a 15.0% compound annual growth rate during 2027–2036. The outlook reflects growing application of integrated optical functions in AI interconnects, coherent networking and specialized photonic devices. Component delivery also depends on process yield, laser availability, module qualification and optical packaging reliability.
Which region has the largest photonic integrated circuit (pic) share?
North America has the largest estimated 2026 share at ~36%, with Asia-Pacific next at ~34% and Europe at ~19%. Regional shares reflect direct device demand and manufacturing-linked purchasing rather than the location of every final networking or sensing system. Capacity expansion and advanced component engineering in several regions create a changing global supply structure.
What is the fastest-growing regional market?
Asia-Pacific has the fastest estimated expansion at ~16.5% CAGR through 2036, with revenue affected by foundry and packaging scale, specialist manufacturing and telecom network build-outs. Demand still depends on device qualification and procurement by optical system vendors, which may separate the location of a chip supplier from the country in which a completed piece of networking equipment is installed.
Which type contributes the largest revenue share?
Silicon Photonics contributes an estimated ~53% of 2026 revenue. Its leadership reflects the suitability of its integration process for commercially available optical system functions, the cost of achieving adequate wafer yield and the degree of customer qualification already established. Customers also compare other type classes on laser integration, losses, heat dissipation and long-term sourcing.
Which type grows fastest?
Indium Phosphide (InP) shows the strongest estimated type growth at ~16.1% CAGR, starting from approximately ~24% of 2026 revenue. Growth depends on the compatibility of the architecture with reliable advanced packaging and usable wavelength control. The highest-growth segment is not necessarily the largest supplier business because a smaller share can expand rapidly from a narrower initial installed base.
What is the largest application?
Data Center Interconnects accounts for an estimated ~55% of 2026 market revenue. This category converts engineering demand into repeatable device orders when electrical interfaces, optical performance, package dimensions and customer lifetime requirements can all be met. Other applications purchase different wavelengths or device layouts, so chip volumes in communications cannot automatically predict sensing or quantum-device revenue.
Which application expands most rapidly?
Quantum Computing is projected to have the highest estimated application growth at ~16.6% CAGR, reflecting its own application-specific technical requirements and adoption pattern. Products require validation at the level of the whole optical instrument or communication link, rather than a device-only demonstration. Customers weigh optical performance, calibration, reliability and repeatable fabrication before moving from prototypes to commercial orders.
Which manufacturers participate in photonic integrated circuits?
Intel, STMicroelectronics, Coherent, Lumentum and optical technology subsidiaries associated with Cisco, Nokia and other equipment groups participate through distinct device, active-material and systems activities. Foundries such as Tower and GlobalFoundries provide production platforms, while some historical business names now represent acquired or renamed operations. Evaluation therefore depends on the current supplying entity, usable product availability and manufacturing responsibility.
What are the main barriers to adoption?
The principal barriers are costly optical fibre coupling, laser supply qualification, thermal management, optical wafer inspection and nonportable process design libraries. A single process change can affect insertion loss and modulation efficiency across a finished device. Customers consequently undertake long acceptance programmes, and high design performance does not guarantee a low-cost high-yield part or immediate large-volume demand.
What technologies and period are covered?
The market covers material platforms and the application areas Data Center Interconnects, Telecom-grade Transceivers, Autonomous Vehicles, Quantum Computing, Others, across North America, Europe, Asia-Pacific, South America and the Middle East and Africa. The quantitative base year is 2026, the estimated year is 2027 and the forecast runs from 2027 to 2036. Component manufacturing, customer qualification, region-specific procurement and relevant upstream materials are addressed alongside device revenue.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF