Key Statistics
Key Takeaways
- Event-Based Vision Sensor is a leading product category because it addresses the largest current application base.
- Autonomous Vehicles is a major application, with demand shaped by performance, reliability and system integration.
- North America leads current market value, while Asia Pacific provides the strongest growth profile.
- Event-driven vision, sensor-level edge processing and multimodal neuromorphic perception is the main technology direction influencing new design wins.
- Market size and growth: USD 210 million in 2025 is projected to reach USD 1.12 billion by 2034 at a 20.4% CAGR during 2026–2034.
Neuromorphic Sensor Market Overview
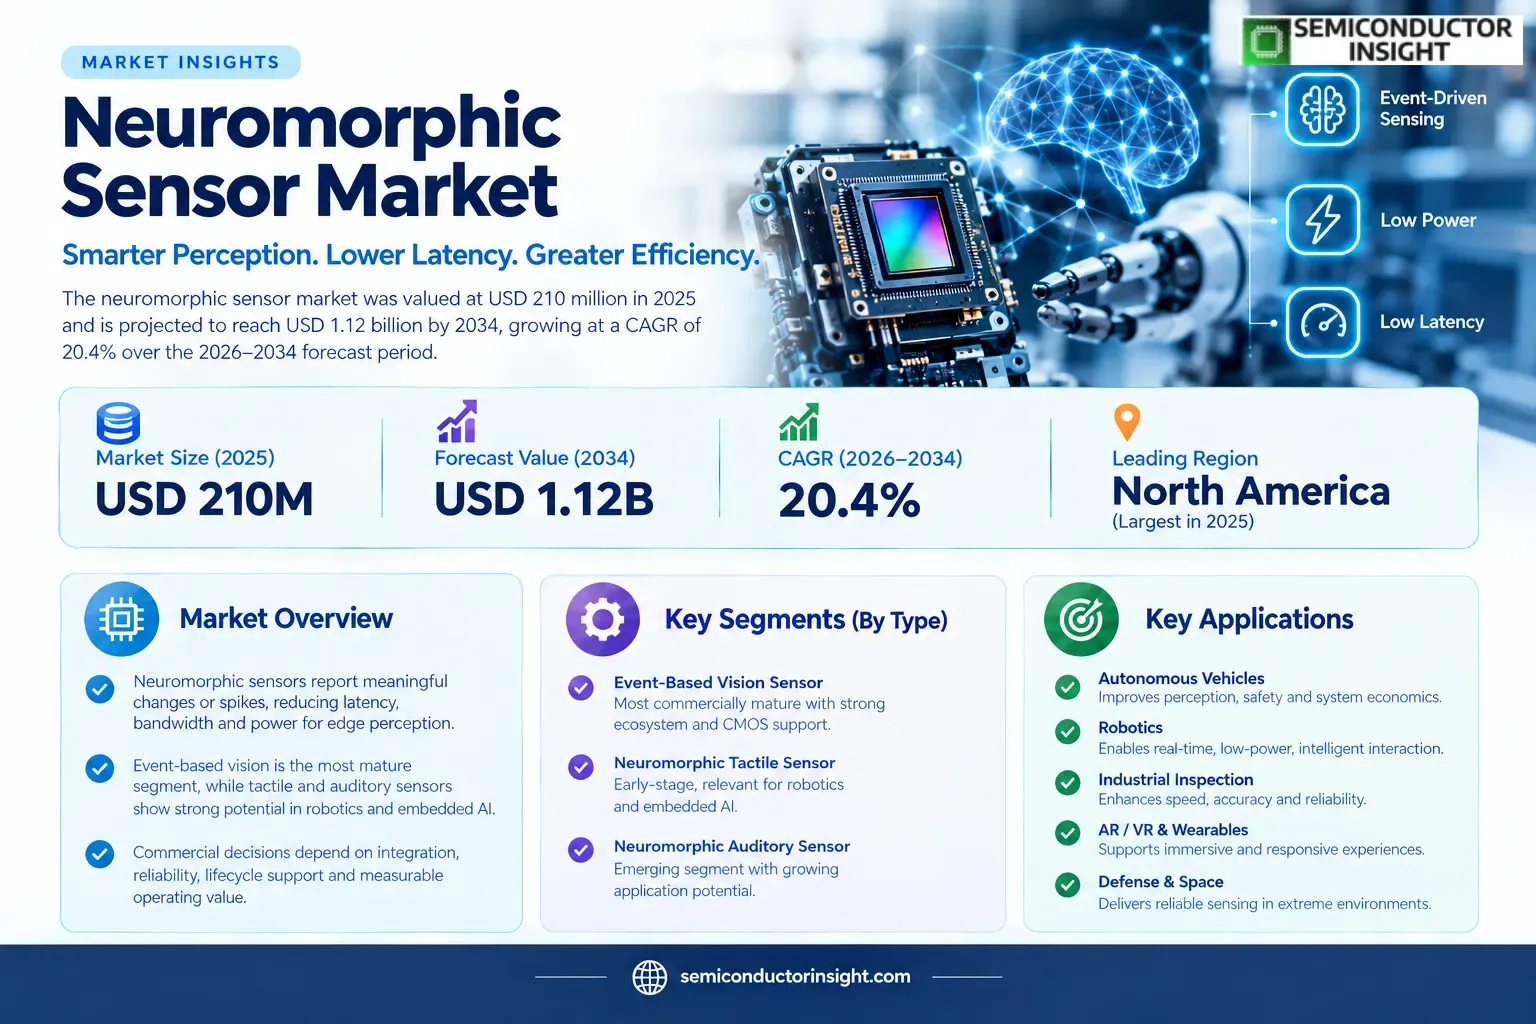
Neuromorphic sensor market was valued at USD 210 million in 2025 and is projected to reach USD 1.12 billion by 2034, growing at a CAGR of 20.4% over the 2026–2034 forecast period. North America held the largest regional position in 2025, while Asia Pacific has the strongest growth profile.
Neuromorphic sensors emulate biological sensing by reporting meaningful changes or spikes rather than continuously transmitting full-frame data, reducing latency, bandwidth and power for edge perception. Commercial decisions in the Neuromorphic Sensor market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
The market is estimated at USD 210 million in 2025 and is projected to reach USD 1.12 billion by 2034, representing a 20.4% CAGR. Event-based vision is the most commercially mature sensor class, while tactile and auditory neuromorphic approaches remain earlier-stage but relevant to robotics and embedded AI.
Sony’s event-based vision lineup includes IMX636/637/646/647 sensors, while Prophesee lists neuromorphic sensors spanning embedded low-power through HD ultra-high-speed products. Current commercial systems emphasize high temporal resolution, wide dynamic range and low sensing power. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
Segment Analysis: By Type
By type, the neuromorphic sensor market is segmented into Event-Based Vision Sensor, Neuromorphic Tactile Sensor, Neuromorphic Auditory Sensor. Each category has a distinct functional role and commercial position, so the analysis emphasizes use case, integration and competitive relevance rather than repeating a single market statistic across every row. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
| Type | Function | Market position |
|---|---|---|
| Event-Based Vision Sensor | Event-Based Vision Sensor addresses a distinct architecture or performance requirement within the Neuromorphic Sensor market. | Commercial demand depends on application fit, qualification, cost and lifecycle requirements rather than a single headline statistic. |
| Neuromorphic Tactile Sensor | Neuromorphic Tactile Sensor addresses a distinct architecture or performance requirement within the Neuromorphic Sensor market. | Commercial demand depends on application fit, qualification, cost and lifecycle requirements rather than a single headline statistic. |
| Neuromorphic Auditory Sensor | Neuromorphic Auditory Sensor addresses a distinct architecture or performance requirement within the Neuromorphic Sensor market. | Commercial demand depends on application fit, qualification, cost and lifecycle requirements rather than a single headline statistic. |
Pricing by type
Event-based vision sensors currently command the highest commercial value because they have mature CMOS implementations and software ecosystems, while tactile and auditory neuromorphic sensors remain more application-specific. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
Segment Analysis: By Application
By application, the market is segmented into Autonomous Vehicles, Robotics, Industrial Inspection, AR / VR & Wearables, Defense & Space. Application economics differ by qualification, lifecycle, reliability and system-level value, so each row below uses context specific to that application rather than mechanically repeating headline evidence. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
| Application | Demand characteristics |
|---|---|
| Autonomous Vehicles | Autonomous Vehicles creates demand where neuromorphic sensor improves integration, performance, reliability or system economics. |
| Robotics | Robotics creates demand where neuromorphic sensor improves integration, performance, reliability or system economics. |
| Industrial Inspection | Industrial Inspection creates demand where neuromorphic sensor improves integration, performance, reliability or system economics. |
| AR / VR & Wearables | AR / VR & Wearables creates demand where neuromorphic sensor improves integration, performance, reliability or system economics. |
| Defense & Space | Defense & Space creates demand where neuromorphic sensor improves integration, performance, reliability or system economics. |
Regional Analysis
North America leads current market value, while Asia Pacific has the strongest growth profile. Regional demand is shaped by manufacturing concentration, technology adoption, customer investment cycles and local supplier ecosystems. Commercial decisions in the Neuromorphic Sensor market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
How does regional demand differ across the neuromorphic sensor market?
Asia Pacific provides the deepest manufacturing scale, North America contributes high-value technology and enterprise demand, and Europe remains important in industrial, automotive and regulated applications. South America and the Middle East & Africa are smaller but developing markets. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia Pacific | High | Highest | electronics manufacturing, robotics and automotive perception | Supply scale and qualification |
| North America | Largest | Moderate-high | neuromorphic startups, autonomous systems and defense research | Technology capability and service |
| Europe | Moderate-high | Moderate | industrial vision, robotics and advanced research | Compliance and lifecycle |
| South America | Smaller | Moderate | Import/industrial led | Cost and distribution |
| Middle East & Africa | Smallest base | Emerging | Infrastructure led | Project support |
Key Neuromorphic Sensor Manufacturers and Competitive Landscape
The competitive landscape includes Sony Semiconductor Solutions, Prophesee, iniVation, Samsung Electronics, Intel, Bosch Sensortec, STMicroelectronics, BrainChip, SynSense, Qualcomm. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
Competition centers on event-driven vision, sensor-level edge processing and multimodal neuromorphic perception, customer qualification, manufacturing consistency and application support. Once a product is designed into a long-lifecycle system, switching costs can protect incumbent positions but also raise the importance of roadmap continuity. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Tier 1 | Sony Semiconductor Solutions, Prophesee, iniVation, Samsung Electronics | Global scale, broad customer qualification and advanced technology portfolios. |
| Tier 2 | Intel, Bosch Sensortec, STMicroelectronics, BrainChip | Strong specialist capability, regional design wins and application-focused portfolios. |
| Tier 3 | Regional and niche suppliers | Cost competition, customization and specialized customer support. |
Key companies profiled
- Sony Semiconductor Solutions
- Prophesee
- iniVation
- Samsung Electronics
- Intel
- Bosch Sensortec
- STMicroelectronics
- BrainChip
- SynSense
- Qualcomm
Neuromorphic Sensor Production Capacity Analysis
Production capacity in the Neuromorphic Sensor market is shaped by the underlying manufacturing process, qualification burden and customer-specific configuration. Suppliers must balance equipment utilization with quality control because high-volume output only creates value when yield, reliability and traceability remain stable. Commercial decisions in the Neuromorphic Sensor market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
Capacity additions tend to follow customer program ramps rather than headline market growth alone. Regional supply resilience is becoming more important, particularly where customers require second-source planning, long product lifecycles or shorter engineering-response times. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
The practical bottleneck is often qualified output rather than nominal installed capacity. Manufacturing, assembly, test and application support must scale together to avoid creating capacity that cannot be used in production programs. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
Neuromorphic Sensor Market Dynamics: Drivers, Restraints and Opportunities
The Neuromorphic Sensor market is shaped by growth is driven by autonomous systems, robotics, industrial inspection, xr and edge ai applications that need low-latency perception with much lower data rates than frame-based sensing. At the same time, growth is constrained by software-tool maturity, unfamiliar event-data formats, sensor cost, integration complexity and limited standardization across perception stacks. The strongest commercial opportunities are concentrated in low-power eye tracking, robot tactile skins, high-speed industrial inspection and autonomous mobility create the strongest opportunities.
MARKET DRIVERS
Drivers Impact Analysis*
| Driver | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Technology upgrade cycle | +1.6% | Global; strongest in leading adopter markets | Near to medium term |
| End-market expansion | +1.2% | Application-specific | Near term |
| Higher value per system | +0.8% | Premium and advanced systems | Medium term |
Technology adoption expands addressable demand
Growth is driven by autonomous systems, robotics, industrial inspection, XR and edge AI applications that need low-latency perception with much lower data rates than frame-based sensing. This demand is strongest where customers can measure a clear improvement in system performance, footprint, energy efficiency, reliability or operating cost. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
End-market modernization increases content per system
The technology upgrade cycle supports replacement and redesign activity as OEMs move to higher-performance architectures. New designs typically create the best opportunity because suppliers can influence specifications before qualification is locked. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
Higher-value architectures support premium mix
Expanding end markets also increase content per system, creating value growth even when unit shipments grow more slowly. Suppliers that combine engineering support with reliable supply are better positioned to capture those design transitions. Commercial decisions in the Neuromorphic Sensor market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Restraint | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Qualification and integration burden | -0.7% | Global | Ongoing |
| Price and substitution pressure | -0.5% | Cost-sensitive applications | Ongoing |
| Supply-chain or process complexity | -0.4% | Global | Medium term |
Qualification burden slows supplier switching
Growth is constrained by software-tool maturity, unfamiliar event-data formats, sensor cost, integration complexity and limited standardization across perception stacks. These constraints are most significant where customers have qualified alternatives or where the technology must prove a clear system-level advantage over lower-cost incumbent solutions. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
Price competition limits margin expansion
Qualification and integration can extend sales cycles because customers must validate performance, reliability and compatibility in their own system environment. That makes early engineering engagement important for new suppliers. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
Alternative technologies constrain selected use cases
Supply-chain complexity can also limit growth when specialized materials, tooling, test or regional support are required. Customers increasingly evaluate resilience alongside price when choosing long-lifecycle suppliers. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
MARKET OPPORTUNITIES
Advanced integration creates premium opportunities
Low-power eye tracking, robot tactile skins, high-speed industrial inspection and autonomous mobility create the strongest opportunities. The most attractive opportunities are where customers are redesigning systems rather than simply replacing like-for-like components. Commercial decisions in the Neuromorphic Sensor market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
Regional capacity and supply resilience
Event-driven vision, sensor-level edge processing and multimodal neuromorphic perception can create premium value when it lowers system complexity, improves performance or supports a new product architecture that is difficult to achieve with incumbent approaches. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
Application engineering deepens customer value
Regional engineering support and application-specific customization provide another route to growth because customers increasingly expect suppliers to support qualification, transition planning and lifecycle management. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
Neuromorphic Sensor Supply Chain Analysis
Upstream. Specialized CMOS pixels, stacked logic, event-processing circuits, sensor packaging, software toolkits and edge-AI integration form the upstream technology base. Supply quality at this stage directly affects downstream yield, reliability and cost. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
Manufacturing. Core production combines process control, assembly, inspection and test, with product-specific qualification used to verify performance before customer shipment. Commercial decisions in the Neuromorphic Sensor market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
Distribution. High-value programs are typically won through direct OEM, Tier-1 or design-house engagement, while distributors serve prototypes, regional customers and lower-volume applications. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
Downstream. End users integrate the product into systems where switching costs rise after qualification, making lifecycle support and supply continuity commercially important. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment. Commercial decisions in the Neuromorphic Sensor market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
Downstream. Panel builders and machine OEMs are the primary specifying customers, followed by electrical contractors working on building services and by facility maintenance teams handling replacement. The specification decision is usually made once, at panel design, and then repeats for the life of the design — which makes design-in position considerably more valuable than any individual transaction.
Recent Developments in the Neuromorphic Sensor Market
Developments tracked through September 2026. Items are selected for direct relevance to product technology, deployment or standards. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
- 2026 Funding & Product
Prophesee launches Mantara and raises €20M Prophesee launched Mantara, an event-based drone detection and tracking system, alongside a €20 million funding round. Source - 2026 Collaboration
IDS and Prophesee deepen industrial vision collaboration IDS and Prophesee announced plans to combine conventional and event-based sensing for faster, lower-power industrial vision. Source - 2026 Current
Sony expands event-based vision sensor lineup Sony’s current EVS lineup includes IMX636, IMX637, IMX646 and IMX647 sensors for industrial high-speed sensing. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2021–2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| Historical Period | 2021–2025 |
| Market Size 2025 | USD 210 million |
| Market Size 2034 | USD 1.12 billion |
| Growth Rate | CAGR of 20.4% from 2026–2034 |
| Unit | Value (USD Million) |
| Segmentation | By Type, By Application, By Signal Modality, By End User, and By Region |
| By Type | Event-Based Vision Sensor · Neuromorphic Tactile Sensor · Neuromorphic Auditory Sensor |
| By Application | Autonomous Vehicles · Robotics · Industrial Inspection · AR / VR & Wearables · Defense & Space |
| By End User | Automotive OEMs · Robotics Companies · Industrial Automation · Consumer Electronics · Research & Defense |
| By Signal Modality | Vision · Touch · Audio |
| By Region | Each region analysed by Type, Application and Country North AmericaU.S., Canada, Mexico EuropeGermany, France, U.K., Italy, Russia, Nordic Countries, Benelux AsiaChina, Japan, South Korea, India, Southeast Asia South AmericaBrazil, Argentina, Rest of South America Middle East & AfricaTurkey, Israel, Saudi Arabia, UAE, Rest of MEA |
| Key Companies Profiled | Sony Semiconductor Solutions, Prophesee, iniVation, Samsung Electronics, Intel, Bosch Sensortec, STMicroelectronics, BrainChip, SynSense, Qualcomm |
| Customization Scope | Free report customization (equivalent to up to 4 analyst working days) with purchase. Addition or alteration to country, regional and segment scope. |
Frequently Asked Questions
What is the current size of the Neuromorphic Sensor market?
The market is valued at USD 210 million in 2025 and is projected to reach USD 1.12 billion by 2034, expanding at a 20.4% CAGR during 2026–2034.
Which companies lead the Neuromorphic Sensor market?
Key participants include Sony Semiconductor Solutions, Prophesee, iniVation, Samsung Electronics, Intel, Bosch Sensortec, STMicroelectronics, BrainChip.
What is Neuromorphic Sensor?
Neuromorphic sensors emulate biological sensing by reporting meaningful changes or spikes rather than continuously transmitting full-frame data, reducing latency, bandwidth and power for edge perception.
What are the main product types?
The market includes Event-Based Vision Sensor, Neuromorphic Tactile Sensor, Neuromorphic Auditory Sensor.
What are the key applications?
The principal applications are Autonomous Vehicles, Robotics, Industrial Inspection, AR / VR & Wearables, Defense & Space.
Which region leads the market?
North America leads current market value, while Asia Pacific has the strongest growth profile.
What drives market growth?
Growth is driven by autonomous systems, robotics, industrial inspection, XR and edge AI applications that need low-latency perception with much lower data rates than frame-based sensing.
What are the main challenges?
Growth is constrained by software-tool maturity, unfamiliar event-data formats, sensor cost, integration complexity and limited standardization across perception stacks.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF