Key Statistics
Key Takeaways
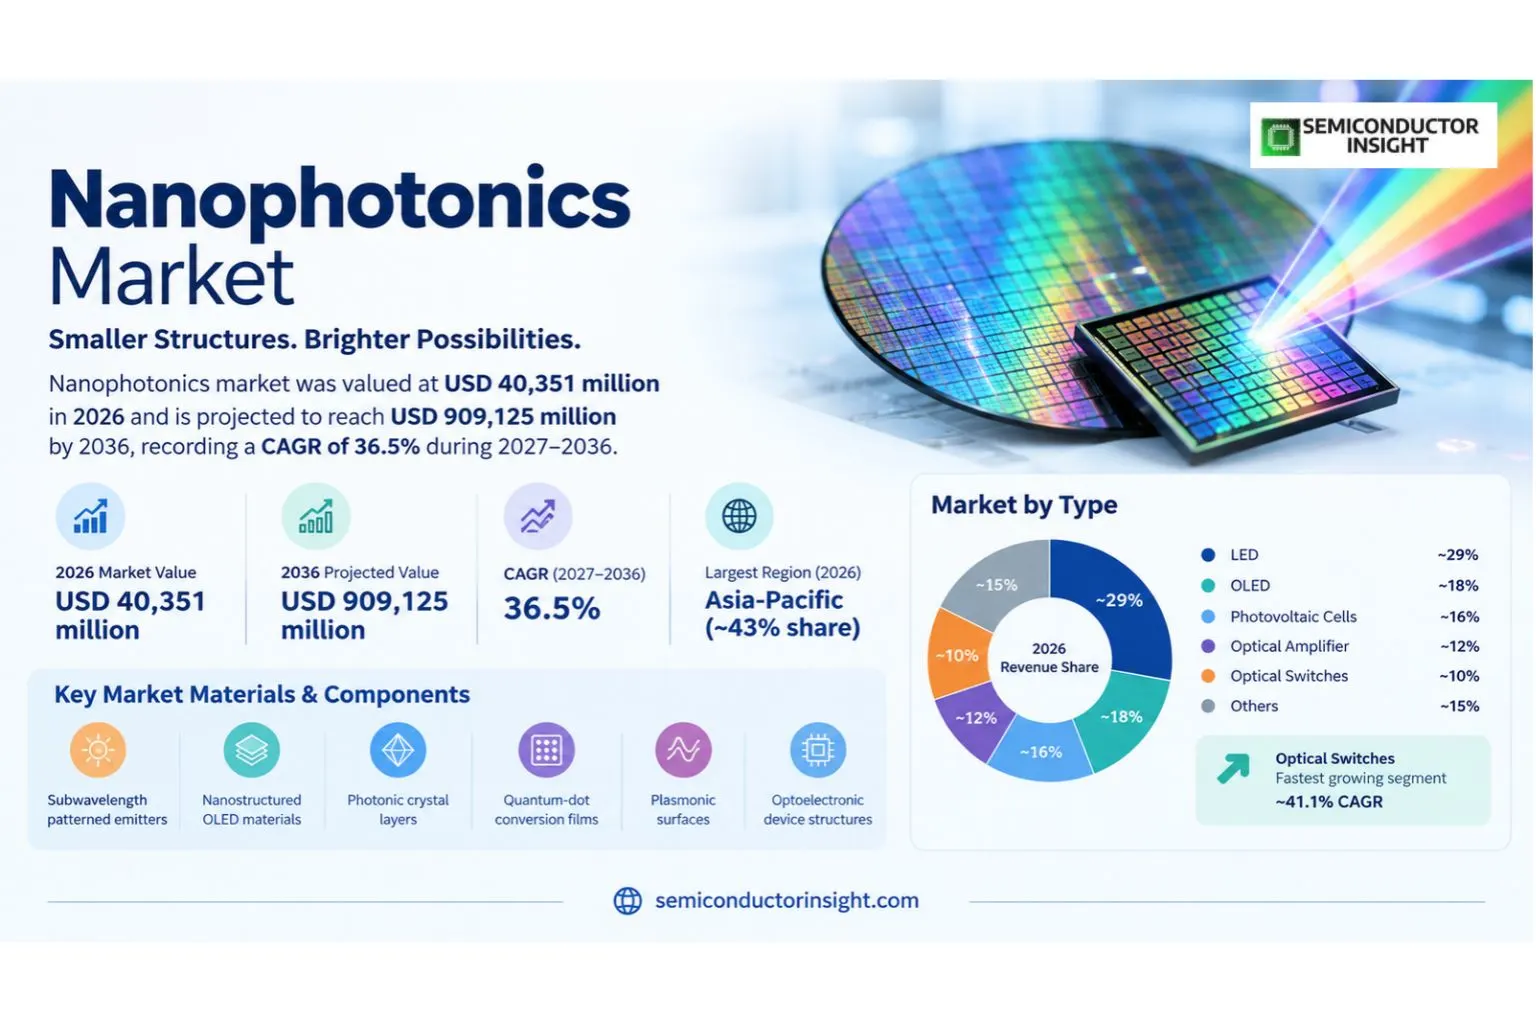
- Market trajectory: The global nanophotonics market reached USD 40,351 million in 2026 and is projected to reach USD 909,125 million by 2036 at 36.5% CAGR over 2027–2036. Demand follows the actual sale of subwavelength patterned emitters, nanostructured OLED materials, photonic crystal layers, quantum-dot conversion films, plasmonic surfaces and optoelectronic device structures, rather than the full revenue of adjacent digital infrastructure.
- LED leadership: LED has the largest estimated type share at ~29% in 2026. The fastest-growing type is Optical Switches, at ~41.1% CAGR from an estimated ~10% share. LED optical emitters use nanostructured extraction layers and engineered semiconductor junctions to improve photon escape and spectral output; high volume reduces per-unit cost but increases manufacturing yield sensitivity.
- Consumer Electronics demand: Consumer Electronics leads application revenue at an estimated ~48% in 2026, while Non Visible Wavelength Instruments grows most rapidly near ~40.8% CAGR. TVs, notebooks and smart devices incorporate quantum-dot color conversion, OLED films and LED source components to improve brightness, color efficiency and form factor. For end-use systems in 2027, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval.
- Asia-Pacific position: Asia-Pacific represents the largest regional revenue pool at an estimated ~43% in 2026. Asia-Pacific has the highest regional modeled growth at ~37.3% CAGR. China, Japan and South Korea anchor display-device production and nanostructured film manufacturing. Nanosys describes Shoei Chemical quantum-dot manufacturing in Japan; display panel makers buy materials tied to wavelength purity, lifetime and coating consistency. Across India and Southeast Asia, imports and module assembly rather than domestic quantum-dot synthesis determine many purchase orders.
- Principal constraint: Difficult lifetime and yield qualification for nanostructures is a fundamental restraint. Purchase decisions are also affected by broad category scope obscuring commercial product boundaries. Both conditions limit the speed at which a promising optical product can move into enduring installations; careful lifecycle support remains vital. In the adoption barriers setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment.
Nanophotonics Market Overview
Nanophotonics market was valued at USD 40,351 million in 2026 and is projected to reach USD 909,125 million by 2036, recording a CAGR of 36.5% during 2027–2036. Asia-Pacific was the largest region in 2026 at an estimated ~43% share. The market centers on subwavelength patterned emitters, nanostructured OLED materials, photonic crystal layers, quantum-dot conversion films, plasmonic surfaces and optoelectronic device structures.
Nanophotonics encompasses subwavelength patterned emitters, nanostructured OLED materials, photonic crystal layers, quantum-dot conversion films, plasmonic surfaces and optoelectronic device structures. The optical interaction carries or secures the functional payload, but the device must also include appropriately designed mechanical, electronic and service interfaces. Customers primarily pay for a qualified system that performs consistently in field conditions, rather than a technical principle demonstrated only at prototype level.
The defined commercial boundary includes revenue from nano-structured photonic devices and selected display, optical sensing, lighting, amplification and photovoltaic components; excludes total downstream TV and handset revenue, grid electricity sales and research grants counted as product revenue. This distinction prevents a finished datacenter, networking service or unrelated electronic product from being mistaken for direct sales of the specialized component. Supplier comparisons are meaningful only when the invoiced product and its value contribution fall within the stated market boundary.
At the engineering level, subwavelength patterned emitters, nanostructured OLED materials, photonic crystal layers, quantum-dot conversion films, plasmonic surfaces and optoelectronic device structures. Designing this technology for 2026 production requires material and mechanical stability, test coverage, procurement planning and the ability to identify a component that has begun to fail. Qualification routines can be more costly than the core material in demanding installations.
Demand develops through display panel makers, LED assemblers, optical network equipment makers, photovoltaic manufacturers, analytical instrument OEMs and research-production foundries. Those purchasers differ in the volumes they order, the length of their evaluation cycle and the documentation they require. The leading applications are Consumer Electronics, Material Science, Non Visible Wavelength Instruments, Non Visual Applications, Indicators, Other Applications; their spending patterns cannot simply be extrapolated from wider electronics or digital-storage demand.
Technology priorities are evolving toward more reliable and serviceable optical architectures. Within nanophotonic components, lED optical emitters use nanostructured extraction layers and engineered semiconductor junctions to improve photon escape and spectral output; high volume reduces per-unit cost but increases manufacturing yield sensitivity. The commercial challenge is to turn those technical characteristics into repeat purchasing, while addressing loss of compatibility, changing interfaces and the long-term economics of support.
Segment Analysis: By Type
By type, the nanophotonics market comprises LED, OLED, Photovoltaic Cells, Optical Amplifier, Optical Switches, Others. LED leads with an estimated ~29% revenue share in 2026; Optical Switches expands most rapidly at about ~41.1% CAGR from a ~10% share. Different physical designs lead to different suppliers, levels of qualification and possible expansion rates. The 2027–2036 opportunity in type overview is linked to deployment timing and customer acceptance, with supplier selection reflecting reliability, supply continuity, interface requirements and actual unit economics.
| Type | Function | Market position |
|---|---|---|
| LED | For LED nanophotonic components, lED optical emitters use nanostructured extraction layers and engineered semiconductor junctions to improve photon escape and spectral output; high volume reduces per-unit cost but increases manufacturing yield sensitivity. Each product specification maps to a different material bill, operating environment and qualification procedure. Suppliers therefore need to establish how the LED variant affects installation requirements and ongoing service. | Estimated ~29% of 2026 revenue and ~32.1% CAGR. LED is the largest type by value, with demand linked to the particular requirements of its buyers. In LED nanophotonic components, lED optical emitters use nanostructured extraction layers and engineered semiconductor junctions to improve photon escape and spectral output; high volume reduces per-unit cost but increases manufacturing yield sensitivity. Procurement teams evaluate component availability, unit cost and the necessary test records. |
| OLED | OLED panels rely on nanometer-scale emissive and charge-transport films with tightly controlled layer thickness and lifetime; panel purchases must not be confused with individual nanophotonic film revenue. Across OLED nanophotonic components, each product specification maps to a different material bill, operating environment and qualification procedure. Suppliers therefore need to establish how the OLED variant affects installation requirements and ongoing service. | Estimated ~24% of 2026 revenue and ~35.1% CAGR. OLED is a distinct product category, with demand linked to the particular requirements of its buyers. Among OLED nanophotonic components, oLED panels rely on nanometer-scale emissive and charge-transport films with tightly controlled layer thickness and lifetime; panel purchases must not be confused with individual nanophotonic film revenue. When buying OLED nanophotonic components, procurement teams evaluate component availability, unit cost and the necessary test records. |
| Photovoltaic Cells | Photovoltaic devices use nanoscale surface passivation and light-trapping treatments to improve absorption; modules have very different pricing and qualification cycles from small optical components. For suppliers of Photovoltaic Cells nanophotonic components, each product specification maps to a different material bill, operating environment and qualification procedure. Suppliers therefore need to establish how the Photovoltaic Cells variant affects installation requirements and ongoing service. | Estimated ~17% of 2026 revenue and ~38.1% CAGR. Photovoltaic Cells is a distinct product category, with demand linked to the particular requirements of its buyers. During qualification of Photovoltaic Cells nanophotonic components, photovoltaic devices use nanoscale surface passivation and light-trapping treatments to improve absorption; modules have very different pricing and qualification cycles from small optical components. Within Photovoltaic Cells nanophotonic components, procurement teams evaluate component availability, unit cost and the necessary test records. |
| Optical Amplifier | Optical amplifier and gain-structure devices improve communication link optical power, requiring gain flatness, noise control and packaging reliability; nanostructure processes affect yield. For Optical Amplifier nanophotonic components, each product specification maps to a different material bill, operating environment and qualification procedure. Suppliers therefore need to establish how the Optical Amplifier variant affects installation requirements and ongoing service. This matters for Optical Amplifier technical function, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software. | Estimated ~12% of 2026 revenue and ~40.1% CAGR. Optical Amplifier is a distinct product category, with demand linked to the particular requirements of its buyers. In Optical Amplifier nanophotonic components, optical amplifier and gain-structure devices improve communication link optical power, requiring gain flatness, noise control and packaging reliability; nanostructure processes affect yield. Across Optical Amplifier nanophotonic components, procurement teams evaluate component availability, unit cost and the necessary test records. |
| Optical Switches | Optical switches route light by moving micromirrors or controlling electro-optic index and waveguide coupling; their value is determined by insertion loss, port count and endurance. Among Optical Switches nanophotonic components, each product specification maps to a different material bill, operating environment and qualification procedure. Suppliers therefore need to establish how the Optical Switches variant affects installation requirements and ongoing service. | Estimated ~10% of 2026 revenue and ~41.1% CAGR. Optical Switches is a distinct product category, with demand linked to the particular requirements of its buyers. When buying Optical Switches nanophotonic components, optical switches route light by moving micromirrors or controlling electro-optic index and waveguide coupling; their value is determined by insertion loss, port count and endurance. For suppliers of Optical Switches nanophotonic components, procurement teams evaluate component availability, unit cost and the necessary test records. |
| Others | Other nanophotonic devices include spectroscopy substrates, nanostructured detectors and experimental quantum optical elements whose commercialization spans specialized laboratory and instrument channels. During qualification of Others nanophotonic components, each product specification maps to a different material bill, operating environment and qualification procedure. Suppliers therefore need to establish how the Others variant affects installation requirements and ongoing service. A commercial evaluation of Others technical function therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone. | Estimated ~8% of 2026 revenue and ~38.1% CAGR. Others is a distinct product category, with demand linked to the particular requirements of its buyers. Within Others nanophotonic components, other nanophotonic devices include spectroscopy substrates, nanostructured detectors and experimental quantum optical elements whose commercialization spans specialized laboratory and instrument channels. For Others nanophotonic components, procurement teams evaluate component availability, unit cost and the necessary test records. |
Secondary segmentation: By Fabrication Technology
The By Fabrication Technology classification distinguishes Lithography, Self-assembly, Nanoimprint Lithography, Electron Beam Lithography, Focused Ion Beam Lithography, Others. Lithography leads this separate estimated 2026 allocation at ~39%. Classifications are parallel descriptions of the same sold hardware; they are not additive product revenue pools. The choice among materials and assembly routes affects cost, thermal tolerance, signal characteristics and reliability.
| Axis | Members | Commercial role |
|---|---|---|
| By Fabrication Technology | Lithography; Self-assembly; Nanoimprint Lithography; Electron Beam Lithography; Focused Ion Beam Lithography; Others | Lithography accounts for an estimated ~39% of by fabrication technology revenue in 2026. Other members address different procurement specifications. The underlying technology involves subwavelength patterned emitters, nanostructured OLED materials, photonic crystal layers, quantum-dot conversion films, plasmonic surfaces and optoelectronic device structures. The best material or process choice is conditional on the actual optical device, thermal cycle, qualification plan and customer integration cost. |
Secondary segmentation: Based on End-use Sectors
The Based on End-use Sectors classification distinguishes Telecommunications, Healthcare and Life Sciences, Consumer Electronics, Energy and Power, Aerospace and Defense, Information Technology, Others. Consumer Electronics leads this separate estimated 2026 allocation at ~43%. In nanophotonic components, classifications are parallel descriptions of the same sold hardware; they are not additive product revenue pools. Across nanophotonic components, the choice among materials and assembly routes affects cost, thermal tolerance, signal characteristics and reliability.
| Axis | Members | Commercial role |
|---|---|---|
| Based on End-use Sectors | Telecommunications; Healthcare and Life Sciences; Consumer Electronics; Energy and Power; Aerospace and Defense; Information Technology; Others | Consumer Electronics accounts for an estimated ~43% of based on end-use sectors revenue in 2026. Other members address different procurement specifications. The underlying technology involves subwavelength patterned emitters, nanostructured OLED materials, photonic crystal layers, quantum-dot conversion films, plasmonic surfaces and optoelectronic device structures. The best material or process choice is conditional on the actual optical device, thermal cycle, qualification plan and customer integration cost. |
Segment Analysis: By Application
Application segments are Consumer Electronics, Material Science, Non Visible Wavelength Instruments, Non Visual Applications, Indicators, Other Applications. Consumer Electronics takes the largest estimated 2026 revenue share at ~48%, whereas Non Visible Wavelength Instruments is the fastest-growing application at ~40.8% CAGR. Channel structure, end-user servicing needs and purchasing cadence create distinct addressable opportunities despite shared underlying optical technologies.
| Application | Demand characteristics |
|---|---|
| Consumer Electronics | Estimated ~48% of 2026 revenue and ~33.8% CAGR. TVs, notebooks and smart devices incorporate quantum-dot color conversion, OLED films and LED source components to improve brightness, color efficiency and form factor. Purchasers assess the entire cost of deploying and operating the optical function, including testability, compatible equipment and procurement lead times. For Consumer Electronics application in 2032, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval. |
| Material Science | Estimated ~17% of 2026 revenue and ~38.8% CAGR. Industrial and academic material laboratories buy nano-optic standards, coating tools, photonic substrates and patterned samples for spectroscopy and new optical-material characterization. Among Material Science nanophotonic components, purchasers assess the entire cost of deploying and operating the optical function, including testability, compatible equipment and procurement lead times. In the Material Science application setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment. |
| Non Visible Wavelength Instruments | Estimated ~13% of 2026 revenue and ~40.8% CAGR. Near-infrared and infrared sensors use engineered filters, detectors and meta-optical surfaces to measure signals outside human vision; optical loss and thermal performance are decisive. When buying Non Visible Wavelength Instruments nanophotonic components, purchasers assess the entire cost of deploying and operating the optical function, including testability, compatible equipment and procurement lead times. This matters for Non Visible Wavelength Instruments application, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software. |
| Non Visual Applications | Estimated ~9% of 2026 revenue and ~38.8% CAGR. Networking, industrial ranging and quantum photonic functions use optical waveguides and nanostructures without producing human-visible images; integration and test needs set prices. For suppliers of Non Visual Applications nanophotonic components, purchasers assess the entire cost of deploying and operating the optical function, including testability, compatible equipment and procurement lead times. A commercial evaluation of Non Visual Applications application therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone. |
| Indicators | Estimated ~7% of 2026 revenue and ~34.8% CAGR. Instrument displays and visual indicators use LED and OLED technologies for visible status and optical feedback, with purchasing linked to lifetime and power efficiency. During qualification of Indicators nanophotonic components, purchasers assess the entire cost of deploying and operating the optical function, including testability, compatible equipment and procurement lead times. The 2027–2036 opportunity in Indicators application is linked to deployment timing and customer acceptance, with supplier selection reflecting reliability, supply continuity, interface requirements and actual unit economics. |
| Other Applications | Estimated ~6% of 2026 revenue and ~37.8% CAGR. Specialty biomedical devices, military photonics and photovoltaic research use devices that do not fit volume consumer channels; commercial validation is application specific. Within Other Applications nanophotonic components, purchasers assess the entire cost of deploying and operating the optical function, including testability, compatible equipment and procurement lead times. For Other Applications application in 2027, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval. |
The commercial channel is shaped by display panel makers, LED assemblers, optical network equipment makers, photovoltaic manufacturers, analytical instrument OEMs and research-production foundries. Direct equipment purchase, specialist distributor supply and OEM qualification have different order economics. Volume can be won through stable specifications and documented reliability, while replacement sales depend on spare availability and retained interface compatibility over the 2027–2036 period.
Regional Analysis
Asia-Pacific leads global revenue with an estimated ~43% share in 2026. North America follows at ~25% and Europe at ~22%. Asia-Pacific has the fastest growth at ~37.3% CAGR. Regional purchases and supplier manufacturing footprints must be distinguished for market comparisons. In the regional lead setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment.
How do regional purchasing patterns differ in nanophotonics?
Asia-Pacific: China, Japan and South Korea anchor display-device production and nanostructured film manufacturing. For nanophotonic components, nanosys describes Shoei Chemical quantum-dot manufacturing in Japan; display panel makers buy materials tied to wavelength purity, lifetime and coating consistency. In nanophotonic components, across India and Southeast Asia, imports and module assembly rather than domestic quantum-dot synthesis determine many purchase orders. North America: The United States hosts material-design firms, universities and cloud-network hardware innovators. Nanosys and Metalenz are involved in commercial nanostructured optics; broad consumer panel volumes need to be distinguished from R&D spending in photonic integrated circuits, life-science instruments and quantum optics. Customer qualification focuses on reliability and defensible nanofabrication processes. Europe has distinct qualification and network compliance requirements; South America and the Middle East and Africa rely more heavily on imported products and local distribution service.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia-Pacific | Largest (~43%) | ~37.3% CAGR | Asia-Pacific buying patterns for nanophotonic devices depend on Coating stability, quantum-dot emission peaks, photonic film moisture barriers and brightness aging are central product acceptance criteria for local buyers. Application mix and supplier origin differ between lab-scale development and volume production, so hardware procurement must be evaluated against the actual system that incorporates the optical device. Procurement cycles differ markedly between OLED screens, photovoltaic substrates and research-grade nanophotonic sensing instruments. | Buyers in Asia-Pacific require engineering fit, credible warranty conditions, appropriate import arrangements, and a qualified local service path. For subwavelength patterned emitters, nanostructured OLED materials, photonic crystal layers, quantum-dot conversion films, plasmonic surfaces and optoelectronic device structures, interface stability and the availability of replacement products can determine whether a promising order proceeds beyond initial evaluation. |
| North America | Second (~25%) | ~36.6% CAGR | North America buying patterns for nanophotonic devices depend on Coating stability, quantum-dot emission peaks, photonic film moisture barriers and brightness aging are central product acceptance criteria for local buyers. Across North America nanophotonic components buyers, application mix and supplier origin differ between lab-scale development and volume production, so hardware procurement must be evaluated against the actual system that incorporates the optical device. Among North America nanophotonic components buyers, procurement cycles differ markedly between OLED screens, photovoltaic substrates and research-grade nanophotonic sensing instruments. | Buyers in North America require engineering fit, credible warranty conditions, appropriate import arrangements, and a qualified local service path. When buying North America nanophotonic components buyers, for subwavelength patterned emitters, nanostructured OLED materials, photonic crystal layers, quantum-dot conversion films, plasmonic surfaces and optoelectronic device structures, interface stability and the availability of replacement products can determine whether a promising order proceeds beyond initial evaluation. |
| Europe | Third (~22%) | ~35.7% CAGR | Europe buying patterns for nanophotonic devices depend on Coating stability, quantum-dot emission peaks, photonic film moisture barriers and brightness aging are central product acceptance criteria for local buyers. For suppliers of Europe nanophotonic components buyers, application mix and supplier origin differ between lab-scale development and volume production, so hardware procurement must be evaluated against the actual system that incorporates the optical device. During qualification of Europe nanophotonic components buyers, procurement cycles differ markedly between OLED screens, photovoltaic substrates and research-grade nanophotonic sensing instruments. | Buyers in Europe require engineering fit, credible warranty conditions, appropriate import arrangements, and a qualified local service path. Within Europe nanophotonic components buyers, for subwavelength patterned emitters, nanostructured OLED materials, photonic crystal layers, quantum-dot conversion films, plasmonic surfaces and optoelectronic device structures, interface stability and the availability of replacement products can determine whether a promising order proceeds beyond initial evaluation. |
| South America | Fourth (~5%) | ~35.3% CAGR | South America buying patterns for nanophotonic devices depend on Coating stability, quantum-dot emission peaks, photonic film moisture barriers and brightness aging are central product acceptance criteria for local buyers. For South America nanophotonic components buyers, application mix and supplier origin differ between lab-scale development and volume production, so hardware procurement must be evaluated against the actual system that incorporates the optical device. In South America nanophotonic components buyers, procurement cycles differ markedly between OLED screens, photovoltaic substrates and research-grade nanophotonic sensing instruments. | Buyers in South America require engineering fit, credible warranty conditions, appropriate import arrangements, and a qualified local service path. Across South America nanophotonic components buyers, for subwavelength patterned emitters, nanostructured OLED materials, photonic crystal layers, quantum-dot conversion films, plasmonic surfaces and optoelectronic device structures, interface stability and the availability of replacement products can determine whether a promising order proceeds beyond initial evaluation. |
| Middle East & Africa | Fifth (~5%) | ~35.5% CAGR | Middle East & Africa buying patterns for nanophotonic devices depend on Coating stability, quantum-dot emission peaks, photonic film moisture barriers and brightness aging are central product acceptance criteria for local buyers. Among Middle East & Africa nanophotonic components buyers, application mix and supplier origin differ between lab-scale development and volume production, so hardware procurement must be evaluated against the actual system that incorporates the optical device. When buying Middle East & Africa nanophotonic components buyers, procurement cycles differ markedly between OLED screens, photovoltaic substrates and research-grade nanophotonic sensing instruments. | Buyers in Middle East & Africa require engineering fit, credible warranty conditions, appropriate import arrangements, and a qualified local service path. For suppliers of Middle East & Africa nanophotonic components buyers, for subwavelength patterned emitters, nanostructured OLED materials, photonic crystal layers, quantum-dot conversion films, plasmonic surfaces and optoelectronic device structures, interface stability and the availability of replacement products can determine whether a promising order proceeds beyond initial evaluation. |
Competitive Landscape
Competition is led by firms with relevant subwavelength patterned emitters, nanostructured OLED materials, photonic crystal layers, quantum-dot conversion films, plasmonic surfaces and optoelectronic device structures. The competitive field includes established manufacturers, original equipment suppliers and historical product brands whose present scope differs. Buyers compare product-specific technical evidence and order terms instead of total corporate turnover, because an optical component represents only part of a finished digital system.
CHERRY and Datalogic ADC illustrate different capabilities within the sector. Their product portfolios, production locations and support arrangements cannot be assumed identical. Procurement departments typically request specification sheets, samples, aging or thermal data and a long-term sourcing plan before designating a manufacturing source for a multi-year contract. This matters for manufacturer capability, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software.
Denso Wave, Exor, Honeywell Scanning and Mobility, INTELLIGENT INSTRUMENTATION, Meter Test appear in the wider manufacturer and distributor field. The roles of those entities require separation: media production, component housing manufacture, systems integration and distribution do not produce the same category of invoice. Market rivalry occurs at the level of the particular sold device, not across unrelated corporate divisions.
Other suppliers and historical business names include QD Vision, Quantum Materials, TCL Display Technology, Universal Display. Legacy corporate names and regional branches may persist in industry directories, while actual current production must be checked against updated company disclosures. Product-life-cycle changes can alter sourcing qualification even if an installed system continues to function with existing spare inventories.
For 2027–2036, vendor differentiation will depend on manufacturing yield, documentation, reliable delivery and compatibility with demanding optical interfaces. Price competition may intensify in mature configurations, whereas new package geometries or archival media offer specialized margins. A customer switching supplier must weigh requalification, sample validation and operational interruption against lower unit costs. A commercial evaluation of competitive economics therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Tier 1 | CHERRY; Datalogic ADC; Denso Wave | Direct manufacturers with published optical product or packaging activities differentiate through established process control and established technical catalogs. The first technical gate is the ability to supply subwavelength patterned emitters, nanostructured OLED materials, photonic crystal layers, quantum-dot conversion films, plasmonic surfaces and optoelectronic device structures in a documented, reproducible format, followed by customer qualification and reliable lead times. |
| Tier 2 | Exor; Honeywell Scanning and Mobility; INTELLIGENT INSTRUMENTATION; Meter Test | Regional producers and equipment suppliers compete through specialized configurations, responsive design assistance and local service. Customers generally request traceable quality records and samples in the exact form factor they need. Lower production scale can be balanced by shorter engineering response times or customization of critical interfaces. The 2027–2036 opportunity in tier 2 is linked to deployment timing and customer acceptance, with supplier selection reflecting reliability, supply continuity, interface requirements and actual unit economics. |
| Tier 3 | ROCKWELL AUTOMATION; Carbon Solutions; Cambrios Technologies; Catalytic Materials; Cnano Technology; Cree; LG Display; Nanocs; Nanocyl; Nanoco Technologies; nanoPHAB; Nanosys; Nanostructured & Amorphous Materials; OSRAM Opto Semiconductors; Philips Lumileds Lighting; QD Vision; Quantum Materials; TCL Display Technology; Universal Display | The broader value chain includes historical participants, distributors, integrators and component companies with adjacent expertise. Their names may appear in sector coverage without establishing that each currently sells an identical qualified device. Product applicability is determined by specific device families, production status and customer approvals. For tier 3 in 2032, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval. |
Key companies profiled
- CHERRY
- Datalogic ADC
- Denso Wave
- Exor
- Honeywell Scanning and Mobility
- INTELLIGENT INSTRUMENTATION
- Meter Test
- ROCKWELL AUTOMATION
- Carbon Solutions
- Cambrios Technologies
- Catalytic Materials
- Cnano Technology
- Cree
- LG Display
- Nanocs
- Nanocyl
- Nanoco Technologies
- nanoPHAB
- Nanosys
- Nanostructured & Amorphous Materials
- OSRAM Opto Semiconductors
- Philips Lumileds Lighting
- QD Vision
- Quantum Materials
- TCL Display Technology
- Universal Display
Production Capacity Analysis
Production capacity relies on specialized manufacturing and testing for subwavelength patterned emitters, nanostructured OLED materials, photonic crystal layers, quantum-dot conversion films, plasmonic surfaces and optoelectronic device structures. Effective output is constrained by qualified material lots, process yield, equipment availability and completion of electrical, optical and environmental tests. Announced industrial capability should not be equated automatically with installed sales or usable nameplate capacity.
Initial manufacturing operations include subwavelength patterned emitters, nanostructured OLED materials, photonic crystal layers, quantum-dot conversion films, plasmonic surfaces and optoelectronic device structures. Yield is influenced by each fabrication and assembly stage, while changes in materials or process equipment can require formal requalification. Japan, China and other Asia-Pacific manufacturing centers support considerable supplier capacity, although customer purchasing decisions may originate elsewhere.
Diversified capacity can reduce country-of-origin exposure and help supply different qualification requirements. However, transferring tooling and process knowledge between plants takes time, and products made in new locations may require fresh qualification. Strong inventory controls and component traceability are important during a period of changing designs and volatile customer orders. In the capacity diversification setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment.
Upstream constraints include materials, specialized assembly equipment and trained optical manufacturing staff. For nanophotonics, packaging, testing and maintenance infrastructure shape the ability to convert a technical design into reproducible revenue. Companies should distinguish capacity for direct in-scope products from headline capacity for the much larger adjacent electronics manufacturing market. This matters for capacity bottlenecks, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software.
Market Dynamics
Demand is driven by rising display demand for quantum-dot and oled films and advanced light extraction in high-efficiency leds. Growth depends on matching the optical product to qualification requirements, logistics and total ownership cost. Supplier economics also reflect the negative impact of difficult lifetime and yield qualification for nanostructures, particularly when customers require long operational support.
MARKET DRIVERS
Drivers Impact Analysis*
| Driver | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Rising display demand for quantum-dot and OLED films | +1.8% | Asia-Pacific | 2027–2036 |
| Advanced light extraction in high-efficiency LEDs | +1.4% | Global | 2028–2034 |
| Photonics integration for optical communication | +1.1% | North America | 2027–2031 |
| Optical diagnostic and instrument miniaturization | +0.9% | Europe | 2029–2036 |
| Growth of nanoimprint and wafer-level optics fabrication | +0.7% | Global | 2028–2035 |
Rising display demand for quantum-dot and OLED films
Rising display demand for quantum-dot and OLED films supports specialized purchases for nanophotonics. subwavelength patterned emitters, nanostructured OLED materials, photonic crystal layers, quantum-dot conversion films, plasmonic surfaces and optoelectronic device structures must be integrated into customer processes, inspected and supported. The growth effect is directional, not a separate addition to the headline CAGR. Actual adoption depends on confirmed orders, service requirements and the lifecycle of equipment already installed.
Advanced light extraction in high-efficiency LEDs
Advanced light extraction in high-efficiency LEDs supports specialized purchases for nanophotonics. subwavelength patterned emitters, nanostructured OLED materials, photonic crystal layers, quantum-dot conversion films, plasmonic surfaces and optoelectronic device structures must be integrated into customer processes, inspected and supported. For nanophotonic components drivers, the growth effect is directional, not a separate addition to the headline CAGR. In nanophotonic components drivers, actual adoption depends on confirmed orders, service requirements and the lifecycle of equipment already installed.
Photonics integration for optical communication
Photonics integration for optical communication supports specialized purchases for nanophotonics. subwavelength patterned emitters, nanostructured OLED materials, photonic crystal layers, quantum-dot conversion films, plasmonic surfaces and optoelectronic device structures must be integrated into customer processes, inspected and supported. Across nanophotonic components drivers, the growth effect is directional, not a separate addition to the headline CAGR. Among nanophotonic components drivers, actual adoption depends on confirmed orders, service requirements and the lifecycle of equipment already installed.
Optical diagnostic and instrument miniaturization
Optical diagnostic and instrument miniaturization supports specialized purchases for nanophotonics. subwavelength patterned emitters, nanostructured OLED materials, photonic crystal layers, quantum-dot conversion films, plasmonic surfaces and optoelectronic device structures must be integrated into customer processes, inspected and supported. When buying nanophotonic components drivers, the growth effect is directional, not a separate addition to the headline CAGR. For suppliers of nanophotonic components drivers, actual adoption depends on confirmed orders, service requirements and the lifecycle of equipment already installed.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Restraint | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Difficult lifetime and yield qualification for nanostructures | −1.5% | Global | 2027–2036 |
| Broad category scope obscuring commercial product boundaries | −1.1% | Europe and North America | 2027–2034 |
| Optical film degradation under humidity and heat | −0.8% | Asia-Pacific | 2028–2035 |
| High capital cost of nanoscale fabrication and metrology | −0.6% | Global | 2029–2036 |
Difficult lifetime and yield qualification for nanostructures
Difficult lifetime and yield qualification for nanostructures increases the effort required to qualify or replace nanophotonics. A technical disadvantage can translate into delayed procurement, more maintenance work or poorer economics for the user. Suppliers that demonstrate stable performance and clear service processes may offset some of this commercial risk, but the constraint remains important for 2027–2036 forecasts. A commercial evaluation of Difficult lifetime and yield qualification for nanostructures restraint therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone.
Broad category scope obscuring commercial product boundaries
Broad category scope obscuring commercial product boundaries increases the effort required to qualify or replace nanophotonics. During qualification of nanophotonic components restraints, a technical disadvantage can translate into delayed procurement, more maintenance work or poorer economics for the user. Within nanophotonic components restraints, suppliers that demonstrate stable performance and clear service processes may offset some of this commercial risk, but the constraint remains important for 2027–2036 forecasts.
Optical film degradation under humidity and heat
Optical film degradation under humidity and heat increases the effort required to qualify or replace nanophotonics. For nanophotonic components restraints, a technical disadvantage can translate into delayed procurement, more maintenance work or poorer economics for the user. In nanophotonic components restraints, suppliers that demonstrate stable performance and clear service processes may offset some of this commercial risk, but the constraint remains important for 2027–2036 forecasts.
High capital cost of nanoscale fabrication and metrology
High capital cost of nanoscale fabrication and metrology increases the effort required to qualify or replace nanophotonics. Across nanophotonic components restraints, a technical disadvantage can translate into delayed procurement, more maintenance work or poorer economics for the user. Among nanophotonic components restraints, suppliers that demonstrate stable performance and clear service processes may offset some of this commercial risk, but the constraint remains important for 2027–2036 forecasts.
MARKET OPPORTUNITIES
Wafer-level nanophotonic components for sensing
Wafer-level nanophotonic components for sensing creates an opportunity to improve deployment or the supplier value proposition. The relevant engineering work concerns subwavelength patterned emitters, nanostructured OLED materials, photonic crystal layers, quantum-dot conversion films, plasmonic surfaces and optoelectronic device structures. Buyers still require evidence of stable operation, a practical purchasing channel, training and a predictable replacement schedule. The commercial impact is strongest where those requirements can be standardized across several customers.
Quantum-dot color conversion in automotive displays
Quantum-dot color conversion in automotive displays creates an opportunity to improve deployment or the supplier value proposition. When buying nanophotonic components opps, the relevant engineering work concerns subwavelength patterned emitters, nanostructured OLED materials, photonic crystal layers, quantum-dot conversion films, plasmonic surfaces and optoelectronic device structures. For suppliers of nanophotonic components opps, buyers still require evidence of stable operation, a practical purchasing channel, training and a predictable replacement schedule. During qualification of nanophotonic components opps, the commercial impact is strongest where those requirements can be standardized across several customers.
Nanoscale coatings for efficient photovoltaics
Nanoscale coatings for efficient photovoltaics creates an opportunity to improve deployment or the supplier value proposition. Within nanophotonic components opps, the relevant engineering work concerns subwavelength patterned emitters, nanostructured OLED materials, photonic crystal layers, quantum-dot conversion films, plasmonic surfaces and optoelectronic device structures. For nanophotonic components opps, buyers still require evidence of stable operation, a practical purchasing channel, training and a predictable replacement schedule. In nanophotonic components opps, the commercial impact is strongest where those requirements can be standardized across several customers.
Integrated photonics for biomedical instrumentation
Integrated photonics for biomedical instrumentation creates an opportunity to improve deployment or the supplier value proposition. Across nanophotonic components opps, the relevant engineering work concerns subwavelength patterned emitters, nanostructured OLED materials, photonic crystal layers, quantum-dot conversion films, plasmonic surfaces and optoelectronic device structures. Among nanophotonic components opps, buyers still require evidence of stable operation, a practical purchasing channel, training and a predictable replacement schedule. When buying nanophotonic components opps, the commercial impact is strongest where those requirements can be standardized across several customers.
Supply Chain Analysis
The supply chain links specialized raw materials, device fabrication, verification, system integration and servicing for nanophotonics. A failure at any stage can invalidate the qualified end product. Vendor selection is therefore affected by more than selling price: replacement-component availability, inspection data, lead time and the ability to support legacy interfaces are commercially significant.
Upstream materials. For suppliers of nanophotonic components channels, materials and optical substrates required for subwavelength patterned emitters, nanostructured OLED materials, photonic crystal layers, quantum-dot conversion films, plasmonic surfaces and optoelectronic device structures; inspection before assembly. For nanophotonics, controlling change across this stage enables traceability, reliability and repeatable delivery. Purchasing teams demand technical records that explain product behavior and clarify responsibility if a component fails after deployment.
Manufacturing. Fabrication, alignment, sealing or recording operations matched to the market boundary. During qualification of nanophotonic components channels, for nanophotonics, controlling change across this stage enables traceability, reliability and repeatable delivery. Within nanophotonic components channels, purchasing teams demand technical records that explain product behavior and clarify responsibility if a component fails after deployment. The 2027–2036 opportunity in Manufacturing chain is linked to deployment timing and customer acceptance, with supplier selection reflecting reliability, supply continuity, interface requirements and actual unit economics.
Channels. For nanophotonic components channels, oEM engineering contracts, technical distributors and integrated storage or optical equipment vendors. In nanophotonic components channels, for nanophotonics, controlling change across this stage enables traceability, reliability and repeatable delivery. Across nanophotonic components channels, purchasing teams demand technical records that explain product behavior and clarify responsibility if a component fails after deployment. For Channels chain in 2027, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval.
Downstream users. Among nanophotonic components channels, display panel makers, LED assemblers, optical network equipment makers, photovoltaic manufacturers, analytical instrument OEMs and research-production foundries; qualification, deployment and lifecycle support. When buying nanophotonic components channels, for nanophotonics, controlling change across this stage enables traceability, reliability and repeatable delivery. For suppliers of nanophotonic components channels, purchasing teams demand technical records that explain product behavior and clarify responsibility if a component fails after deployment.
Recent Developments
- 9 September 2026 Announced
NIL Technology exhibited nano-patterned flat optics and wafer-level imaging elements at CIOE 2026 in Shenzhen, emphasizing practical production controls for meta-optical surfaces. This is relevant to nanophotonics because repeatable nanometer-scale features and alignment strongly influence adoption across imaging and sensing; such demos are not direct evidence of revenue from every nanophotonic product type. Source - 4 September 2026 Published
The Semiconductor Industry Association reported the July 2026 global semiconductor sales trend, showing elevated investment in advanced chip products. That industry total is not a measure of nanophotonic revenue, yet it helps suppliers assess demand for manufacturing capacity, qualified substrates and testing tools used by optical-component fabs. In the Nanophotonics development 4 September 2026 setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment. Source - 29 January 2026 Published
Nanosys and TÜV Rheinland released guidance for objectively defining a genuine quantum-dot display. Their proposed measurement-led approach makes spectral performance and functional optical conversion more transparent to buyers, potentially shifting sales toward qualified quantum-dot films and away from vague display marketing labels. This matters for Nanophotonics development 29 January 2026, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software. Source - 12 November 2025 Announced
Metalenz and UMC disclosed a 12-inch wafer production pathway for polarization-sensitive metasurface optics. Although this program primarily targets biometric sensing, it demonstrates that optical nanostructures can move into standard semiconductor manufacturing systems, a capability relevant to longer-term nanophotonics device yields and cost. A commercial evaluation of Nanophotonics development 12 November 2025 therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone. Source - 10 October 2025 Published
Nanosys described new quantum-dot material priorities covering brightness, color stability and manufacturing cost. These factors influence how nanostructured photonic conversion layers are qualified in automotive and IT displays, where temperature exposure and long operating life can be more demanding than in consumer TV applications. The 2027–2036 opportunity in Nanophotonics development 10 October 2025 is linked to deployment timing and customer acceptance, with supplier selection reflecting reliability, supply continuity, interface requirements and actual unit economics. Source - 10 July 2025 Announced
STMicroelectronics and Metalenz expanded their metasurface-optics licensing relationship for wafer-scale optical sensor production. The arrangement highlights an important industrial mechanism: converting high-resolution nanophotonic patterns into qualified photonic devices requires mature semiconductor toolchains, component tests and customer design-in programs. For Nanophotonics development 10 July 2025 in 2032, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval. Source - 19 June 2025 Announced
The European Commission signed the PIXEurope integrated-photonics pilot-line program to help close gaps between research devices and reproducible fabrication. The initiative can support high-density optical components and packaging knowledge, but pilot-line grants should not be counted as sales of completed commercial nanophotonic devices. This matters for Nanophotonics development 19 June 2025, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software. Source - 30 May 2025 Published
Nanosys presented its quantum-dot materials and automotive-display reliability demonstrations at Display Week 2025. The vendor discussed ongoing mass production and differentiation among QDEF, QD-OLED and other display configurations; the commercial implication is rising demand for verified color and lifetime performance rather than total panel revenue. In the Nanophotonics development 30 May 2025 setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2021–2036 |
| Base Year | 2026 |
| Estimated Year | 2027 |
| Forecast Period | 2027–2036 |
| Historical Period | 2021–2025 |
| Base Year Market Size | USD 40,351 million |
| Estimated Year Market Size | USD 55,098 million |
| Forecast Year Market Size | USD 909,125 million |
| CAGR | 36.5% |
| Unit | USD million |
| Market Definition | revenue from nano-structured photonic devices and selected display, optical sensing, lighting, amplification and photovoltaic components; excludes total downstream TV and handset revenue, grid electricity sales and research grants counted as product revenue |
| By Type | LED · OLED · Photovoltaic Cells · Optical Amplifier · Optical Switches · Others |
| By Application | Consumer Electronics · Material Science · Non Visible Wavelength Instruments · Non Visual Applications · Indicators · Other Applications |
| By Fabrication Technology | Lithography · Self-assembly · Nanoimprint Lithography · Electron Beam Lithography · Focused Ion Beam Lithography · Others |
| Based on End-use Sectors | Telecommunications · Healthcare and Life Sciences · Consumer Electronics · Energy and Power · Aerospace and Defense · Information Technology · Others |
| By Region | Regional demand includes display-material processing in Asia-Pacific, photonics research and design activity in North America and Europe, and equipment integration in South America and Middle East and Africa. Asia-PacificChina · Japan · India · South Korea North AmericaUnited States · Canada · Mexico EuropeGermany · United Kingdom · France South AmericaBrazil · Chile · Argentina Middle East & AfricaSaudi Arabia · United Arab Emirates · South Africa |
| Key Companies Profiled | CHERRY; Datalogic ADC; Denso Wave; Exor; Honeywell Scanning and Mobility; INTELLIGENT INSTRUMENTATION; Meter Test; ROCKWELL AUTOMATION; Carbon Solutions; Cambrios Technologies; Catalytic Materials; Cnano Technology; Cree; LG Display; Nanocs; Nanocyl; Nanoco Technologies; nanoPHAB; Nanosys; Nanostructured & Amorphous Materials; OSRAM Opto Semiconductors; Philips Lumileds Lighting; QD Vision; Quantum Materials; TCL Display Technology; Universal Display |
| Customization Scope | Supplier, type, application and regional price analysis for nanophotonics; estimated market shares in 2026 and differentiated growth paths for 2027–2036. |
Frequently Asked Questions
What is the global nanophotonics market size?
The global nanophotonics market is valued at USD 40,351 million in 2026 and is forecast to reach USD 909,125 million by 2036, with 36.5% CAGR during 2027–2036. The demand boundary is specific to the optical equipment and technology defined here rather than the full revenue of all data-center, media, automotive or electronics systems. A commercial evaluation of FAQ 1 therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone.
Which geographic region is the largest market?
Asia-Pacific is the leading 2026 regional market with an estimated ~43% of revenue. North America and Europe follow at ~25% and ~22%, respectively. Differences in OEM manufacturing locations and customer purchasing geography can otherwise distort region comparisons. The 2027–2036 opportunity in FAQ 2 is linked to deployment timing and customer acceptance, with supplier selection reflecting reliability, supply continuity, interface requirements and actual unit economics.
Which region has the fastest growth rate?
Asia-Pacific has the highest estimated regional expansion at ~37.3% CAGR through 2036. During qualification of nanophotonic components purchasers, china, Japan and South Korea anchor display-device production and nanostructured film manufacturing. Within nanophotonic components purchasers, nanosys describes Shoei Chemical quantum-dot manufacturing in Japan; display panel makers buy materials tied to wavelength purity, lifetime and coating consistency. For nanophotonic components purchasers, across India and Southeast Asia, imports and module assembly rather than domestic quantum-dot synthesis determine many purchase orders. The rate is linked to equipment deployment, supplier qualification and the technology mix, rather than broad GDP growth alone.
Which type holds the largest revenue share?
LED represents an estimated ~29% of the 2026 market. In nanophotonic components purchasers, lED optical emitters use nanostructured extraction layers and engineered semiconductor junctions to improve photon escape and spectral output; high volume reduces per-unit cost but increases manufacturing yield sensitivity. Buyers need to verify its performance, equipment compatibility and the available delivery chain before treating it as an interchangeable substitute for another optical format.
Which type is projected to expand fastest?
Optical Switches carries the strongest estimated type growth at ~41.1% CAGR, from around ~10% of 2026 revenue. The product mix changes as users adopt performance-enhancing configurations, but engineering qualification and lifecycle servicing determine how quickly that potential converts into orders. For FAQ 5 in 2027, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval.
What is the leading application?
Consumer Electronics is the largest application at approximately ~48% of 2026 revenue. Across nanophotonic components purchasers, tVs, notebooks and smart devices incorporate quantum-dot color conversion, OLED films and LED source components to improve brightness, color efficiency and form factor. Procurement specifications depend on actual operating conditions; total revenue in the wider user industry is not a direct proxy for the value of optical equipment purchased.
Which application grows fastest?
Non Visible Wavelength Instruments is projected to grow at ~40.8% CAGR from approximately ~13% of 2026 revenue. Near-infrared and infrared sensors use engineered filters, detectors and meta-optical surfaces to measure signals outside human vision; optical loss and thermal performance are decisive. Growth is affected by price changes and supplier qualification as well as physical unit demand.
Which companies are included?
The profiled market participants include CHERRY, Datalogic ADC, Denso Wave, Exor, Honeywell Scanning and Mobility, INTELLIGENT INSTRUMENTATION. These companies may operate in different parts of the value chain and in some cases retain historical naming. Comparisons need to distinguish direct in-scope equipment manufacturing from distribution, materials and wider group revenues. In the FAQ 8 setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment.
What restrains adoption?
Difficult lifetime and yield qualification for nanostructures is a notable limitation, alongside broad category scope obscuring commercial product boundaries. Customers must also examine service cost, quality-control requirements and purchasing terms. Technical improvement will not necessarily produce corresponding annual revenue growth without reproducible production and access to qualified buyers. This matters for FAQ 9, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software.
What is the study period and segmentation scope?
The base year is 2026, the estimated year is 2027, and the forecast runs through 2036 with historical context from 2021–2025. Segmentation by type covers LED, OLED, Photovoltaic Cells, Optical Amplifier, Optical Switches, Others and by application covers Consumer Electronics, Material Science, Non Visible Wavelength Instruments, Non Visual Applications, Indicators, Other Applications. Five geographic regions are included.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF