SEMICONDUCTOR INSIGHT
MARKET RESEARCH REPORT

Metalens for Optical Communication Market

2026 to 2034
MARKET INTELLIGENCE
ACROSS KEY REGIONS
2026 EDITION
OPTOELECTRONICS Semiconductor Market Research

Metalens for Optical Communication Market

◷
UPDATED 21 October 2026
▤
REPORT LENGTH Detailed Report
▣
REPORT CODE 2807de96f161
▯
FORMATS PDF

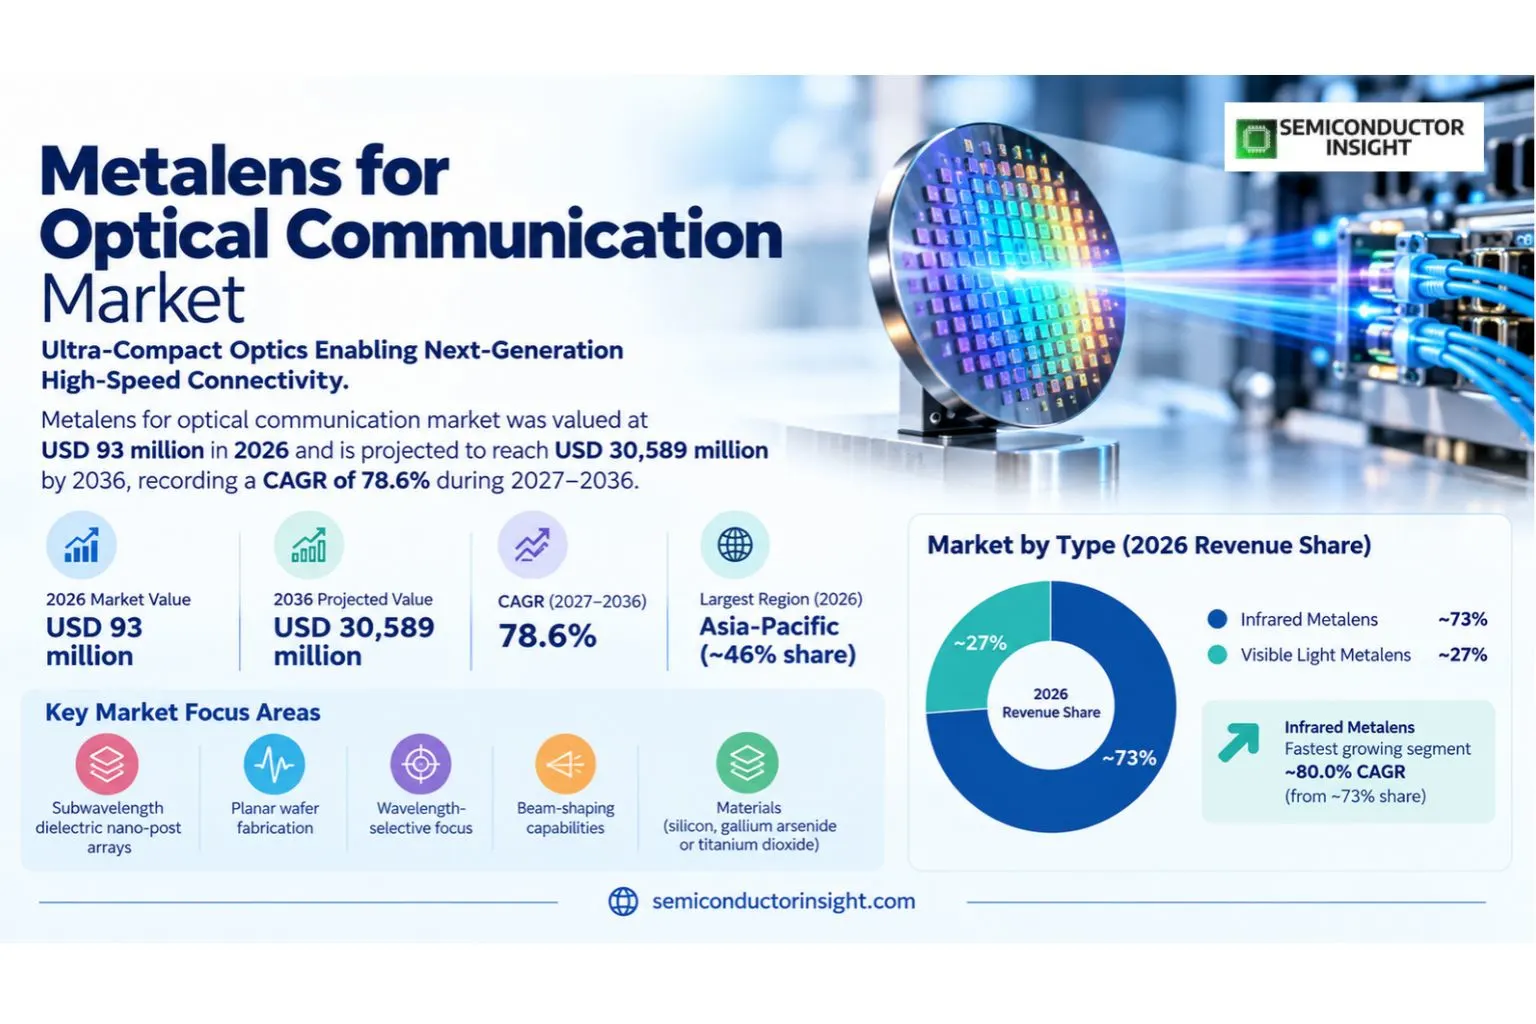
Metalens for optical communication market was valued at USD 93 million in 2026 and is projected to reach USD 30,589 million by 2036, recording a CAGR of 78.6% during 2027–2036. Asia-Pacific was the largest region in 2026 at an estimated ~46% share. The market centers on subwavelength dielectric nano-post arrays on planar wafers controlling optical wavefront, wavelength-selective focus and beam-shaping with silicon, gallium arsenide or titanium dioxide.

Get the sample PDF with study scope, segmentation and methodology details.

Key Statistics

2026 Market Size
USD 93 million
2036 Projected Size
USD 30,589 million
CAGR (2027–2036)
78.6%
Largest Market in 2026
Asia-Pacific (~46%)

Key Takeaways

  • Market trajectory: The global metalens for optical communication market reached USD 93 million in 2026 and is projected to reach USD 30,589 million by 2036 at 78.6% CAGR over 2027–2036. Demand follows the actual sale of subwavelength dielectric nano-post arrays on planar wafers controlling optical wavefront, wavelength-selective focus and beam-shaping with silicon, gallium arsenide or titanium dioxide, rather than the full revenue of adjacent digital infrastructure.
  • Infrared Metalens leadership: Infrared Metalens has the largest estimated type share at ~73% in 2026. The fastest-growing type is Infrared Metalens, at ~80.0% CAGR from an estimated ~73% share. Infrared metalenses target near-infrared and telecom-relevant wavelength bands for compact beam shaping and fiber coupling; alignment tolerances and link power budgets determine usefulness. For product categories in 2027, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval.
  • Optical Fiber Communication demand: Optical Fiber Communication leads application revenue at an estimated ~65% in 2026, while Optical Fiber Communication grows most rapidly near ~79.4% CAGR. Fiber communication components require low-loss focusing at qualified transport wavelengths, stable alignment over temperature and repeatable fabrication before any flat lens can replace a refractive optic. In the end-use systems setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment.
  • Asia-Pacific position: Asia-Pacific represents the largest regional revenue pool at an estimated ~46% in 2026. Asia-Pacific has the highest regional modeled growth at ~79.9% CAGR. China combines multiple metalens startup and fabrication candidates with established wafer-processing and optical-module suppliers; Japan and South Korea offer lithography, metrology and semiconductor packaging capacity. Telecom metalens design wins must be distinguished from near-infrared sensing shipments. The key purchasing obstacle remains optical efficiency and bandwidth across real communication wavelengths.
  • Principal constraint: No broad proof of telecom metalens shipping volumes is a fundamental restraint. Purchase decisions are also affected by chromatic aberration and optical efficiency constraints. Within metalenses for optical communication, both conditions limit the speed at which a promising optical product can move into enduring installations; careful lifecycle support remains vital. This matters for adoption barriers, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software.

Metalens for Optical Communication Market Overview

Metalens for optical communication market was valued at USD 93 million in 2026 and is projected to reach USD 30,589 million by 2036, recording a CAGR of 78.6% during 2027–2036. Asia-Pacific was the largest region in 2026 at an estimated ~46% share. The market centers on subwavelength dielectric nano-post arrays on planar wafers controlling optical wavefront, wavelength-selective focus and beam-shaping with silicon, gallium arsenide or titanium dioxide.

Base year: 2026 · Estimated year: 2027 · Forecast period: 2027–2036 · Historical data: 2021–2025 · Values in USD million

Metalens for Optical Communication encompasses subwavelength dielectric nano-post arrays on planar wafers controlling optical wavefront, wavelength-selective focus and beam-shaping with silicon, gallium arsenide or titanium dioxide. For metalenses for optical communication, the optical interaction carries or secures the functional payload, but the device must also include appropriately designed mechanical, electronic and service interfaces. In metalenses for optical communication, customers primarily pay for a qualified system that performs consistently in field conditions, rather than a technical principle demonstrated only at prototype level.

The defined commercial boundary includes flat meta-optical elements explicitly supplied for communications or fiber sensing, including experimental telecom infrared focusing and coupling components; excludes established consumer camera metalenses and all coherent transceiver electronics unless separately specified. Across metalenses for optical communication, this distinction prevents a finished datacenter, networking service or unrelated electronic product from being mistaken for direct sales of the specialized component. Among metalenses for optical communication, supplier comparisons are meaningful only when the invoiced product and its value contribution fall within the stated market boundary.

At the engineering level, subwavelength dielectric nano-post arrays on planar wafers controlling optical wavefront, wavelength-selective focus and beam-shaping with silicon, gallium arsenide or titanium dioxide. When buying metalenses for optical communication, designing this technology for 2026 production requires material and mechanical stability, test coverage, procurement planning and the ability to identify a component that has begun to fail. For suppliers of metalenses for optical communication, qualification routines can be more costly than the core material in demanding installations.

Demand develops through fiber transceiver designers, integrated photonic packaging companies, telecom equipment laboratories, fiber-sensing module OEMs and free-space optical systems developers. During qualification of metalenses for optical communication, those purchasers differ in the volumes they order, the length of their evaluation cycle and the documentation they require. The leading applications are Optical Fiber Communication, Optical Fiber Sensing, Others; their spending patterns cannot simply be extrapolated from wider electronics or digital-storage demand.

Technology priorities are evolving toward more reliable and serviceable optical architectures. Within metalenses for optical communication, infrared metalenses target near-infrared and telecom-relevant wavelength bands for compact beam shaping and fiber coupling; alignment tolerances and link power budgets determine usefulness. For metalenses for optical communication, the commercial challenge is to turn those technical characteristics into repeat purchasing, while addressing loss of compatibility, changing interfaces and the long-term economics of support.

Segment Analysis: By Type

By type, the metalens for optical communication market comprises Visible Light Metalens, Infrared Metalens. Infrared Metalens leads with an estimated ~73% revenue share in 2026; Infrared Metalens expands most rapidly at about ~80.0% CAGR from a ~73% share. In metalenses for optical communication, different physical designs lead to different suppliers, levels of qualification and possible expansion rates. A commercial evaluation of type overview therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone.

Type Function Market position
Visible Light Metalens Visible light metalenses offer compact light focusing and phase engineering for specialized free-space paths and optical instruments; chromatic dispersion limits broad multicolor uses. Across Visible Light Metalens metalenses for optical communication, each product specification maps to a different material bill, operating environment and qualification procedure. Suppliers therefore need to establish how the Visible Light Metalens variant affects installation requirements and ongoing service. Estimated ~27% of 2026 revenue and ~74.2% CAGR. Visible Light Metalens is a distinct product category, with demand linked to the particular requirements of its buyers. Among Visible Light Metalens metalenses for optical communication, visible light metalenses offer compact light focusing and phase engineering for specialized free-space paths and optical instruments; chromatic dispersion limits broad multicolor uses. When buying Visible Light Metalens metalenses for optical communication, procurement teams evaluate component availability, unit cost and the necessary test records.
Infrared Metalens For suppliers of Infrared Metalens metalenses for optical communication, infrared metalenses target near-infrared and telecom-relevant wavelength bands for compact beam shaping and fiber coupling; alignment tolerances and link power budgets determine usefulness. During qualification of Infrared Metalens metalenses for optical communication, each product specification maps to a different material bill, operating environment and qualification procedure. Suppliers therefore need to establish how the Infrared Metalens variant affects installation requirements and ongoing service. Estimated ~73% of 2026 revenue and ~80.0% CAGR. Infrared Metalens is the largest type by value, with demand linked to the particular requirements of its buyers. Within Infrared Metalens metalenses for optical communication, infrared metalenses target near-infrared and telecom-relevant wavelength bands for compact beam shaping and fiber coupling; alignment tolerances and link power budgets determine usefulness. For Infrared Metalens metalenses for optical communication, procurement teams evaluate component availability, unit cost and the necessary test records.

Secondary segmentation: By Material Type

The By Material Type classification distinguishes Silicon-based Metalens, Gallium Arsenide (GaAs) based Metalens, Titanium Dioxide (TiO₂) based Metalens, Others. Silicon-based Metalens leads this separate estimated 2026 allocation at ~54%. In metalenses for optical communication, classifications are parallel descriptions of the same sold hardware; they are not additive product revenue pools. Across metalenses for optical communication, the choice among materials and assembly routes affects cost, thermal tolerance, signal characteristics and reliability.

Axis Members Commercial role
By Material Type Silicon-based Metalens; Gallium Arsenide (GaAs) based Metalens; Titanium Dioxide (TiO₂) based Metalens; Others Silicon-based Metalens accounts for an estimated ~54% of by material type revenue in 2026. Other members address different procurement specifications. The underlying technology involves subwavelength dielectric nano-post arrays on planar wafers controlling optical wavefront, wavelength-selective focus and beam-shaping with silicon, gallium arsenide or titanium dioxide. The best material or process choice is conditional on the actual optical device, thermal cycle, qualification plan and customer integration cost.

Secondary segmentation: By End-Use Industry

The By End-Use Industry classification distinguishes Telecommunications, Data Centers, Defense & Aerospace, Medical & Healthcare, Others. Telecommunications leads this separate estimated 2026 allocation at ~42%. Among metalenses for optical communication, classifications are parallel descriptions of the same sold hardware; they are not additive product revenue pools. When buying metalenses for optical communication, the choice among materials and assembly routes affects cost, thermal tolerance, signal characteristics and reliability.

Axis Members Commercial role
By End-Use Industry Telecommunications; Data Centers; Defense & Aerospace; Medical & Healthcare; Others Telecommunications accounts for an estimated ~42% of by end-use industry revenue in 2026. Other members address different procurement specifications. The underlying technology involves subwavelength dielectric nano-post arrays on planar wafers controlling optical wavefront, wavelength-selective focus and beam-shaping with silicon, gallium arsenide or titanium dioxide. The best material or process choice is conditional on the actual optical device, thermal cycle, qualification plan and customer integration cost.

Segment Analysis: By Application

Application segments are Optical Fiber Communication, Optical Fiber Sensing, Others. Optical Fiber Communication takes the largest estimated 2026 revenue share at ~65%, whereas Optical Fiber Communication is the fastest-growing application at ~79.4% CAGR. For suppliers of metalenses for optical communication, channel structure, end-user servicing needs and purchasing cadence create distinct addressable opportunities despite shared underlying optical technologies. The 2027–2036 opportunity in application overview is linked to deployment timing and customer acceptance, with supplier selection reflecting reliability, supply continuity, interface requirements and actual unit economics.

Application Demand characteristics
Optical Fiber Communication Estimated ~65% of 2026 revenue and ~79.4% CAGR. Fiber communication components require low-loss focusing at qualified transport wavelengths, stable alignment over temperature and repeatable fabrication before any flat lens can replace a refractive optic. During qualification of Optical Fiber Communication metalenses for optical communication, purchasers assess the entire cost of deploying and operating the optical function, including testability, compatible equipment and procurement lead times.
Optical Fiber Sensing Estimated ~24% of 2026 revenue and ~77.3% CAGR. Optical fiber sensing uses compact beam collimation, interrogators and precision focusing in industrial monitors; reliability may justify advanced optics in high-value instruments. Within Optical Fiber Sensing metalenses for optical communication, purchasers assess the entire cost of deploying and operating the optical function, including testability, compatible equipment and procurement lead times. For Optical Fiber Sensing application in 2032, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval.
Others Estimated ~11% of 2026 revenue and ~76.6% CAGR. Free-space laser links, exploratory quantum photonics and specialized optical test fixtures offer non-fiber opportunities but require separate commercial qualification. For Others metalenses for optical communication, purchasers assess the entire cost of deploying and operating the optical function, including testability, compatible equipment and procurement lead times. In the Others application setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment.

The commercial channel is shaped by fiber transceiver designers, integrated photonic packaging companies, telecom equipment laboratories, fiber-sensing module OEMs and free-space optical systems developers. In metalenses for optical communication, direct equipment purchase, specialist distributor supply and OEM qualification have different order economics. Across metalenses for optical communication, volume can be won through stable specifications and documented reliability, while replacement sales depend on spare availability and retained interface compatibility over the 2027–2036 period.
Regional Analysis

Asia-Pacific leads global revenue with an estimated ~46% share in 2026. North America follows at ~25% and Europe at ~19%. Asia-Pacific has the fastest growth at ~79.9% CAGR. Among metalenses for optical communication, regional purchases and supplier manufacturing footprints must be distinguished for market comparisons. This matters for regional lead, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software.

How do regional purchasing patterns differ in metalens for optical communication?

Asia-Pacific: China combines multiple metalens startup and fabrication candidates with established wafer-processing and optical-module suppliers; Japan and South Korea offer lithography, metrology and semiconductor packaging capacity. Telecom metalens design wins must be distinguished from near-infrared sensing shipments. When buying metalenses for optical communication, the key purchasing obstacle remains optical efficiency and bandwidth across real communication wavelengths. North America: US photonics laboratories and system suppliers explore free-space optical links, beam-shaping and hybrid optics for compact interconnects. Metalenz provides clear proof of consumer sensing metasurface commercialization, but that is not evidence of a qualified mass-market telecom module using a metalens. Customers require wavelength, thermal and link-budget qualification before optical-interface substitution. For suppliers of metalenses for optical communication, europe has distinct qualification and network compliance requirements; South America and the Middle East and Africa rely more heavily on imported products and local distribution service.

Region Position Growth outlook Demand profile What decides supplier selection
Asia-Pacific Largest (~46%) ~79.9% CAGR Asia-Pacific buying patterns for communication metalenses depend on The technical decision involves phase error, numerical aperture, infrared bandwidth, fiber coupling loss and alignment retention after temperature changes. During qualification of Asia-Pacific metalenses for optical communication buyers, application mix and supplier origin differ between lab-scale development and volume production, so hardware procurement must be evaluated against the actual system that incorporates the optical device. Near-infrared camera metalenses are not automatically qualified replacements for lenses in optical transceiver packages. Within Asia-Pacific metalenses for optical communication buyers, buyers in Asia-Pacific require engineering fit, credible warranty conditions, appropriate import arrangements, and a qualified local service path. For subwavelength dielectric nano-post arrays on planar wafers controlling optical wavefront, wavelength-selective focus and beam-shaping with silicon, gallium arsenide or titanium dioxide, interface stability and the availability of replacement products can determine whether a promising order proceeds beyond initial evaluation.
North America Second (~25%) ~78.5% CAGR North America buying patterns for communication metalenses depend on The technical decision involves phase error, numerical aperture, infrared bandwidth, fiber coupling loss and alignment retention after temperature changes. For North America metalenses for optical communication buyers, application mix and supplier origin differ between lab-scale development and volume production, so hardware procurement must be evaluated against the actual system that incorporates the optical device. In North America metalenses for optical communication buyers, near-infrared camera metalenses are not automatically qualified replacements for lenses in optical transceiver packages. Across North America metalenses for optical communication buyers, buyers in North America require engineering fit, credible warranty conditions, appropriate import arrangements, and a qualified local service path. Among North America metalenses for optical communication buyers, for subwavelength dielectric nano-post arrays on planar wafers controlling optical wavefront, wavelength-selective focus and beam-shaping with silicon, gallium arsenide or titanium dioxide, interface stability and the availability of replacement products can determine whether a promising order proceeds beyond initial evaluation.
Europe Third (~19%) ~76.7% CAGR Europe buying patterns for communication metalenses depend on The technical decision involves phase error, numerical aperture, infrared bandwidth, fiber coupling loss and alignment retention after temperature changes. When buying Europe metalenses for optical communication buyers, application mix and supplier origin differ between lab-scale development and volume production, so hardware procurement must be evaluated against the actual system that incorporates the optical device. For suppliers of Europe metalenses for optical communication buyers, near-infrared camera metalenses are not automatically qualified replacements for lenses in optical transceiver packages. During qualification of Europe metalenses for optical communication buyers, buyers in Europe require engineering fit, credible warranty conditions, appropriate import arrangements, and a qualified local service path. Within Europe metalenses for optical communication buyers, for subwavelength dielectric nano-post arrays on planar wafers controlling optical wavefront, wavelength-selective focus and beam-shaping with silicon, gallium arsenide or titanium dioxide, interface stability and the availability of replacement products can determine whether a promising order proceeds beyond initial evaluation.
South America Fourth (~5%) ~76.3% CAGR South America buying patterns for communication metalenses depend on The technical decision involves phase error, numerical aperture, infrared bandwidth, fiber coupling loss and alignment retention after temperature changes. For South America metalenses for optical communication buyers, application mix and supplier origin differ between lab-scale development and volume production, so hardware procurement must be evaluated against the actual system that incorporates the optical device. In South America metalenses for optical communication buyers, near-infrared camera metalenses are not automatically qualified replacements for lenses in optical transceiver packages. Across South America metalenses for optical communication buyers, buyers in South America require engineering fit, credible warranty conditions, appropriate import arrangements, and a qualified local service path. Among South America metalenses for optical communication buyers, for subwavelength dielectric nano-post arrays on planar wafers controlling optical wavefront, wavelength-selective focus and beam-shaping with silicon, gallium arsenide or titanium dioxide, interface stability and the availability of replacement products can determine whether a promising order proceeds beyond initial evaluation.
Middle East & Africa Fifth (~5%) ~76.3% CAGR Middle East & Africa buying patterns for communication metalenses depend on The technical decision involves phase error, numerical aperture, infrared bandwidth, fiber coupling loss and alignment retention after temperature changes. When buying Middle East & Africa metalenses for optical communication buyers, application mix and supplier origin differ between lab-scale development and volume production, so hardware procurement must be evaluated against the actual system that incorporates the optical device. For suppliers of Middle East & Africa metalenses for optical communication buyers, near-infrared camera metalenses are not automatically qualified replacements for lenses in optical transceiver packages. During qualification of Middle East & Africa metalenses for optical communication buyers, buyers in Middle East & Africa require engineering fit, credible warranty conditions, appropriate import arrangements, and a qualified local service path. Within Middle East & Africa metalenses for optical communication buyers, for subwavelength dielectric nano-post arrays on planar wafers controlling optical wavefront, wavelength-selective focus and beam-shaping with silicon, gallium arsenide or titanium dioxide, interface stability and the availability of replacement products can determine whether a promising order proceeds beyond initial evaluation.

Asia-Pacific LARGEST · ~46% SHARE · FASTEST-GROWING

What determines Asia-Pacific demand for metalens for optical communication?

Asia-Pacific holds an estimated ~46% of 2026 global revenue and has ~79.9% CAGR through 2036. For Asia-Pacific metalenses for optical communication demand, china combines multiple metalens startup and fabrication candidates with established wafer-processing and optical-module suppliers; Japan and South Korea offer lithography, metrology and semiconductor packaging capacity. Telecom metalens design wins must be distinguished from near-infrared sensing shipments. In Asia-Pacific metalenses for optical communication demand, the key purchasing obstacle remains optical efficiency and bandwidth across real communication wavelengths. Original equipment sourcing and local network installations can involve separate geographies. Across Asia-Pacific metalenses for optical communication demand, in Asia-Pacific, sourcing paths and installation service arrangements have a direct bearing on opportunities for both established emitters and newly qualified laser products.

Market positionLargest (~46%)
Growth outlook~79.9% CAGR
Demand profileOptical OEM qualification
Market access gateInterface reliability and service support
Country Position in region What drives demand
China Major users Among China metalenses for optical communication, china has a large domestic optical module and display panel supply chain. When buying China metalenses for optical communication, equipment suppliers compete on production throughput, component origin and response time to assembly-line qualification. For communication metalenses purchased in China, The technical decision involves phase error, numerical aperture, infrared bandwidth, fiber coupling loss and alignment retention after temperature changes. For suppliers of China metalenses for optical communication, near-infrared camera metalenses are not automatically qualified replacements for lenses in optical transceiver packages. During qualification of China metalenses for optical communication, in China, procurement is concentrated on the operating requirements of the relevant imported or locally integrated product, rather than sales of the entire downstream system.
Japan Engineering base Within Japan metalenses for optical communication, japan has a concentration of specialist materials suppliers and precision optical inspection capabilities. For Japan metalenses for optical communication, long-term purchasing often emphasizes batch traceability, service intervals and qualification of alternative substrates. For communication metalenses purchased in Japan, The technical decision involves phase error, numerical aperture, infrared bandwidth, fiber coupling loss and alignment retention after temperature changes. In Japan metalenses for optical communication, near-infrared camera metalenses are not automatically qualified replacements for lenses in optical transceiver packages. Across Japan metalenses for optical communication, in Japan, procurement is concentrated on the operating requirements of the relevant imported or locally integrated product, rather than sales of the entire downstream system.
India Developing channel Among India metalenses for optical communication, indian procurement is tied to expanding fiber access, local consumer electronics assembly and research instrumentation. When buying India metalenses for optical communication, imported parts still require customs management, technical support and serviceable module designs. For communication metalenses purchased in India, The technical decision involves phase error, numerical aperture, infrared bandwidth, fiber coupling loss and alignment retention after temperature changes. For suppliers of India metalenses for optical communication, near-infrared camera metalenses are not automatically qualified replacements for lenses in optical transceiver packages. During qualification of India metalenses for optical communication, in India, procurement is concentrated on the operating requirements of the relevant imported or locally integrated product, rather than sales of the entire downstream system.
South Korea Selective demand Within South Korea metalenses for optical communication, south Korean display and semiconductor producers emphasize dense packaging, power efficiency and reproducible materials. For South Korea metalenses for optical communication, device makers are exacting buyers of stable film thickness and optical emissions across repeated fabrication lots. For communication metalenses purchased in South Korea, The technical decision involves phase error, numerical aperture, infrared bandwidth, fiber coupling loss and alignment retention after temperature changes. In South Korea metalenses for optical communication, near-infrared camera metalenses are not automatically qualified replacements for lenses in optical transceiver packages. Across South Korea metalenses for optical communication, in South Korea, procurement is concentrated on the operating requirements of the relevant imported or locally integrated product, rather than sales of the entire downstream system.

Market instances

  • September 2026: China meta-optic polarization device showcase. NIL Technology documented cioe 2026 meta-optical manufacturing during September 2026. 9 September 2026 supplier demonstrates polarization switching metasurface optics. In Asia-Pacific, the relevance for communication metalenses procurement is the equipment qualification and integration workload associated with the underlying optical component rather than an assumed share of an adjacent technology business. The technical decision involves phase error, numerical aperture, infrared bandwidth, fiber coupling loss and alignment retention after temperature changes. Buyers need verifiable specifications before translating this development into recurring orders.
  • November 2025: Taiwan 12-inch metasurface fabrication. November 2025 — Metalenz described umc polarization metasurface production. 12 November 2025 12-inch silicon foundry mass-production announcement. This development is relevant to Asia-Pacific because specialized communication metalenses devices enter systems via OEM qualification, overseas sourcing and integration services. Among Asia-Pacific metalenses for optical communication installations, near-infrared camera metalenses are not automatically qualified replacements for lenses in optical transceiver packages. When buying Asia-Pacific metalenses for optical communication installations, the relevant commercial effect is broader design capability and a potential future supplier pool, not a disclosed local market-size figure.
  • January 2025: Asian optics manufacturing acquisition of Danish supplier. The NIL Technology disclosure in January 2025 concerned radiant acquisition of nil technology. 6 January 2025 corporate acquisition bringing large scale optical manufacturing. For suppliers of Asia-Pacific metalenses for optical communication installations, for optical equipment installed or assessed in Asia-Pacific, attention turns to manufacturability, stable wavelength performance and verified reliability. During qualification of Asia-Pacific metalenses for optical communication installations, the technical decision involves phase error, numerical aperture, infrared bandwidth, fiber coupling loss and alignment retention after temperature changes. Within Asia-Pacific metalenses for optical communication installations, local demand can respond differently depending on whether the purchaser is a research laboratory, telecom operator or large-volume device maker.
In the full report: For Asia-Pacific metalenses for optical communication demand, volume, price and supplier detail for China, Japan, India, South Korea, with estimated 2026 shares and 2027–2036 demand drivers.

North America SECOND · ~25% SHARE

What determines North America demand for metalens for optical communication?

North America holds an estimated ~25% of 2026 global revenue and has ~78.5% CAGR through 2036. US photonics laboratories and system suppliers explore free-space optical links, beam-shaping and hybrid optics for compact interconnects. In North America metalenses for optical communication demand, metalenz provides clear proof of consumer sensing metasurface commercialization, but that is not evidence of a qualified mass-market telecom module using a metalens. Customers require wavelength, thermal and link-budget qualification before optical-interface substitution. Original equipment sourcing and local network installations can involve separate geographies. Across North America metalenses for optical communication demand, in North America, sourcing paths and installation service arrangements have a direct bearing on opportunities for both established emitters and newly qualified laser products.

Market positionSecond (~25%)
Growth outlook~78.5% CAGR
Demand profileOptical OEM qualification
Market access gateInterface reliability and service support
Country Position in region What drives demand
United States Major users Among United States metalenses for optical communication, the United States hosts sophisticated optical design teams, cloud computing operators and laboratory system integrators. When buying United States metalenses for optical communication, qualification often begins with physical interface parameters and moves to accelerated environmental endurance testing. For communication metalenses purchased in United States, The technical decision involves phase error, numerical aperture, infrared bandwidth, fiber coupling loss and alignment retention after temperature changes. For suppliers of United States metalenses for optical communication, near-infrared camera metalenses are not automatically qualified replacements for lenses in optical transceiver packages. During qualification of United States metalenses for optical communication, in United States, procurement is concentrated on the operating requirements of the relevant imported or locally integrated product, rather than sales of the entire downstream system.
Canada Engineering base Within Canada metalenses for optical communication, canadian commercial demand is dispersed between high-specification optical instrumentation, regional telecom infrastructure and advanced research laboratories. Extensive network geography makes remote diagnostics and service logistics commercially important. For communication metalenses purchased in Canada, The technical decision involves phase error, numerical aperture, infrared bandwidth, fiber coupling loss and alignment retention after temperature changes. For Canada metalenses for optical communication, near-infrared camera metalenses are not automatically qualified replacements for lenses in optical transceiver packages. In Canada metalenses for optical communication, in Canada, procurement is concentrated on the operating requirements of the relevant imported or locally integrated product, rather than sales of the entire downstream system.
Mexico Developing channel Across Mexico metalenses for optical communication, mexico combines contract electronics assembly, automotive supply chains and cross-border data infrastructure. Among Mexico metalenses for optical communication, most advanced optical devices enter as imported components installed or inspected in larger finished assemblies. For communication metalenses purchased in Mexico, The technical decision involves phase error, numerical aperture, infrared bandwidth, fiber coupling loss and alignment retention after temperature changes. When buying Mexico metalenses for optical communication, near-infrared camera metalenses are not automatically qualified replacements for lenses in optical transceiver packages. For suppliers of Mexico metalenses for optical communication, in Mexico, procurement is concentrated on the operating requirements of the relevant imported or locally integrated product, rather than sales of the entire downstream system.

Market instances

  • July 2025: US metasurface IP and production qualification. Metalenz documented stmicroelectronics metalens licensing during July 2025. 10 July 2025 300 mm semiconductor photonics production collaboration. In North America, the relevance for communication metalenses procurement is the equipment qualification and integration workload associated with the underlying optical component rather than an assumed share of an adjacent technology business. During qualification of North America metalenses for optical communication installations, the technical decision involves phase error, numerical aperture, infrared bandwidth, fiber coupling loss and alignment retention after temperature changes. Buyers need verifiable specifications before translating this development into recurring orders.
  • November 2025: North American design using Asian foundries. Within North America metalenses for optical communication installations, november 2025 — Metalenz described umc polarization metasurface production. 12 November 2025 12-inch silicon foundry mass-production announcement. This development is relevant to North America because specialized communication metalenses devices enter systems via OEM qualification, overseas sourcing and integration services. For North America metalenses for optical communication installations, near-infrared camera metalenses are not automatically qualified replacements for lenses in optical transceiver packages. In North America metalenses for optical communication installations, the relevant commercial effect is broader design capability and a potential future supplier pool, not a disclosed local market-size figure.
  • 2025: US meta-optic design and fabrication architecture. The Metalenz disclosure in 2025 concerned metasurface process architecture. Direct manufacturer explanation of wavefront control and fabless design. Across North America metalenses for optical communication installations, for optical equipment installed or assessed in North America, attention turns to manufacturability, stable wavelength performance and verified reliability. Among North America metalenses for optical communication installations, the technical decision involves phase error, numerical aperture, infrared bandwidth, fiber coupling loss and alignment retention after temperature changes. When buying North America metalenses for optical communication installations, local demand can respond differently depending on whether the purchaser is a research laboratory, telecom operator or large-volume device maker.
In the full report: For suppliers of North America metalenses for optical communication demand, volume, price and supplier detail for United States, Canada, Mexico, with estimated 2026 shares and 2027–2036 demand drivers.

Europe THIRD · ~19% SHARE

What determines Europe demand for metalens for optical communication?

Europe holds an estimated ~19% of 2026 global revenue and has ~76.7% CAGR through 2036. Denmark-based NIL Technology is directly active in metalens manufacturing, and EU-supported METAPRINT and PIXEurope programs address scalable nanopatterning. For telecom-oriented products, European buyers concentrate on wafer-level process reliability, heterogenous integration and optical loss. Pilot-line activity is an input to supply capability, rather than proof of high-volume telecom metalens orders. Original equipment sourcing and local network installations can involve separate geographies. During qualification of Europe metalenses for optical communication demand, in Europe, sourcing paths and installation service arrangements have a direct bearing on opportunities for both established emitters and newly qualified laser products.

Market positionThird (~19%)
Growth outlook~76.7% CAGR
Demand profileOptical OEM qualification
Market access gateInterface reliability and service support
Country Position in region What drives demand
Germany Major users Within Germany metalenses for optical communication, german industrial OEMs place weight on repeatable optical alignment, electromagnetic compatibility and published mechanical qualification. Factory procurement emphasizes support contracts and stable product generations. For communication metalenses purchased in Germany, The technical decision involves phase error, numerical aperture, infrared bandwidth, fiber coupling loss and alignment retention after temperature changes. For Germany metalenses for optical communication, near-infrared camera metalenses are not automatically qualified replacements for lenses in optical transceiver packages. In Germany metalenses for optical communication, in Germany, procurement is concentrated on the operating requirements of the relevant imported or locally integrated product, rather than sales of the entire downstream system.
United Kingdom Engineering base Across United Kingdom metalenses for optical communication, british photonics clusters combine component design, university facilities and advanced test instruments. Among United Kingdom metalenses for optical communication, higher-volume assembly is frequently placed outside the domestic market, separating engineering geography from invoice geography. For communication metalenses purchased in United Kingdom, The technical decision involves phase error, numerical aperture, infrared bandwidth, fiber coupling loss and alignment retention after temperature changes. When buying United Kingdom metalenses for optical communication, near-infrared camera metalenses are not automatically qualified replacements for lenses in optical transceiver packages. For suppliers of United Kingdom metalenses for optical communication, in United Kingdom, procurement is concentrated on the operating requirements of the relevant imported or locally integrated product, rather than sales of the entire downstream system.
France Developing channel France participates in European optical fabrication programs and sensor-oriented semiconductor engineering. During qualification of France metalenses for optical communication, pilot-line investment can improve process learning without creating equivalent immediate product revenue. For communication metalenses purchased in France, The technical decision involves phase error, numerical aperture, infrared bandwidth, fiber coupling loss and alignment retention after temperature changes. Within France metalenses for optical communication, near-infrared camera metalenses are not automatically qualified replacements for lenses in optical transceiver packages. For France metalenses for optical communication, in France, procurement is concentrated on the operating requirements of the relevant imported or locally integrated product, rather than sales of the entire downstream system.

Market instances

  • March 2025: French ceramic meta-optic pilot line. European Commission documented metaprint ceramic nanoimprint pilot during March 2025. March 2025 pilot-line funding for metasurface optical elements. In Europe, the relevance for communication metalenses procurement is the equipment qualification and integration workload associated with the underlying optical component rather than an assumed share of an adjacent technology business. In Europe metalenses for optical communication installations, the technical decision involves phase error, numerical aperture, infrared bandwidth, fiber coupling loss and alignment retention after temperature changes. Buyers need verifiable specifications before translating this development into recurring orders.
  • June 2025: EU optical integration pilot capacity. June 2025 — European Commission described pixeurope integrated photonics pilot. June 2025 PIC manufacturing scale-up infrastructure. This development is relevant to Europe because specialized communication metalenses devices enter systems via OEM qualification, overseas sourcing and integration services. Across Europe metalenses for optical communication installations, near-infrared camera metalenses are not automatically qualified replacements for lenses in optical transceiver packages. Among Europe metalenses for optical communication installations, the relevant commercial effect is broader design capability and a potential future supplier pool, not a disclosed local market-size figure.
  • May 2025: European wafer optics manufacturing dialogue. The imec disclosure in May 2025 concerned advanced photonics manufacturing agenda. May 2025 technical meetings on wafer-level optics and nanoimprint challenges. When buying Europe metalenses for optical communication installations, for optical equipment installed or assessed in Europe, attention turns to manufacturability, stable wavelength performance and verified reliability. For suppliers of Europe metalenses for optical communication installations, the technical decision involves phase error, numerical aperture, infrared bandwidth, fiber coupling loss and alignment retention after temperature changes. During qualification of Europe metalenses for optical communication installations, local demand can respond differently depending on whether the purchaser is a research laboratory, telecom operator or large-volume device maker.
In the full report: Within Europe metalenses for optical communication demand, volume, price and supplier detail for Germany, United Kingdom, France, with estimated 2026 shares and 2027–2036 demand drivers.

South America FOURTH · ~5% SHARE

What determines South America demand for metalens for optical communication?

South America holds an estimated ~5% of 2026 global revenue and has ~76.3% CAGR through 2036. The first plausible commercial demand involves compact sensor optics and imported fiber-network or specialized research hardware. Brazil and Argentina rely on foreign semiconductor foundries for nanoscale patterning, while local system integrators typically purchase assembled transceivers. Metalens vendors have to convince those buyers that a planar design improves installed cost or alignment stability. Original equipment sourcing and local network installations can involve separate geographies. For South America metalenses for optical communication demand, in South America, sourcing paths and installation service arrangements have a direct bearing on opportunities for both established emitters and newly qualified laser products.

Market positionFourth (~5%)
Growth outlook~76.3% CAGR
Demand profileOptical OEM qualification
Market access gateInterface reliability and service support
Country Position in region What drives demand
Brazil Major users In Brazil metalenses for optical communication, brazilian telecom upgrades, lighting and industrial monitoring depend heavily on imported specialized optics. Across Brazil metalenses for optical communication, distributor capability and exchange-rate management can shape adoption as strongly as intrinsic optical performance. For communication metalenses purchased in Brazil, The technical decision involves phase error, numerical aperture, infrared bandwidth, fiber coupling loss and alignment retention after temperature changes. Among Brazil metalenses for optical communication, near-infrared camera metalenses are not automatically qualified replacements for lenses in optical transceiver packages. When buying Brazil metalenses for optical communication, in Brazil, procurement is concentrated on the operating requirements of the relevant imported or locally integrated product, rather than sales of the entire downstream system.
Chile Engineering base Chile has substantial remote infrastructure and mineral-processing instrumentation requirements. For suppliers of Chile metalenses for optical communication, optical components generally arrive through complete systems or specialist integrators rather than a large local fabrication network. For communication metalenses purchased in Chile, The technical decision involves phase error, numerical aperture, infrared bandwidth, fiber coupling loss and alignment retention after temperature changes. During qualification of Chile metalenses for optical communication, near-infrared camera metalenses are not automatically qualified replacements for lenses in optical transceiver packages. Within Chile metalenses for optical communication, in Chile, procurement is concentrated on the operating requirements of the relevant imported or locally integrated product, rather than sales of the entire downstream system.
Argentina Developing channel For Argentina metalenses for optical communication, argentine technical demand arises in universities, electronics integrators and communications infrastructure maintenance. In Argentina metalenses for optical communication, access to stable importing channels and component substitutions is important for project continuity. For communication metalenses purchased in Argentina, The technical decision involves phase error, numerical aperture, infrared bandwidth, fiber coupling loss and alignment retention after temperature changes. Across Argentina metalenses for optical communication, near-infrared camera metalenses are not automatically qualified replacements for lenses in optical transceiver packages. Among Argentina metalenses for optical communication, in Argentina, procurement is concentrated on the operating requirements of the relevant imported or locally integrated product, rather than sales of the entire downstream system.

Market instances

  • 2026: Latin American operator demand for optical capacity. GSMA documented 2026 mobile industry outlook during 2026. Industry association primary report on optical network end users. In South America, the relevance for communication metalenses procurement is the equipment qualification and integration workload associated with the underlying optical component rather than an assumed share of an adjacent technology business. When buying South America metalenses for optical communication installations, the technical decision involves phase error, numerical aperture, infrared bandwidth, fiber coupling loss and alignment retention after temperature changes. Buyers need verifiable specifications before translating this development into recurring orders.
  • 2025: Imported metalens optical alignment specification. 2025 — NIL Technology described metalenses design and production. Manufacturer describes VIS/NIR/SWIR metasurface design and manufacturing. This development is relevant to South America because specialized communication metalenses devices enter systems via OEM qualification, overseas sourcing and integration services. For suppliers of South America metalenses for optical communication installations, near-infrared camera metalenses are not automatically qualified replacements for lenses in optical transceiver packages. During qualification of South America metalenses for optical communication installations, the relevant commercial effect is broader design capability and a potential future supplier pool, not a disclosed local market-size figure.
  • 2025: Nanoimprint yield constraints for specialist importers. The NIL Technology disclosure in 2025 concerned high-volume nir meta optics production. Manufacturer discusses electron beam masters and nanoimprint replication. Within South America metalenses for optical communication installations, for optical equipment installed or assessed in South America, attention turns to manufacturability, stable wavelength performance and verified reliability. For South America metalenses for optical communication installations, the technical decision involves phase error, numerical aperture, infrared bandwidth, fiber coupling loss and alignment retention after temperature changes. In South America metalenses for optical communication installations, local demand can respond differently depending on whether the purchaser is a research laboratory, telecom operator or large-volume device maker.
In the full report: Across South America metalenses for optical communication demand, volume, price and supplier detail for Brazil, Chile, Argentina, with estimated 2026 shares and 2027–2036 demand drivers.

Middle East & Africa FIFTH · ~5% SHARE

What determines Middle East & Africa demand for metalens for optical communication?

Middle East & Africa holds an estimated ~5% of 2026 global revenue and has ~76.3% CAGR through 2036. Advanced free-space optical communications trials and university photonics programs may create a limited metalens demand pipeline in Israel and Gulf states. Optical systems need dust, heat and beam-alignment qualification, often favoring mature conventional optics. Most commercial networks would acquire this technology through imported packaged equipment rather than bare optical metasurfaces. Original equipment sourcing and local network installations can involve separate geographies. Among Middle East & Africa metalenses for optical communication demand, in Middle East & Africa, sourcing paths and installation service arrangements have a direct bearing on opportunities for both established emitters and newly qualified laser products.

Market positionFifth (~5%)
Growth outlook~76.3% CAGR
Demand profileOptical OEM qualification
Market access gateInterface reliability and service support
Country Position in region What drives demand
Saudi Arabia Major users When buying Saudi Arabia metalenses for optical communication, saudi operators and research institutions fund network digitization and specialist instrumentation, though the revenue from the wider infrastructure should not be confused with component purchasing. For communication metalenses purchased in Saudi Arabia, The technical decision involves phase error, numerical aperture, infrared bandwidth, fiber coupling loss and alignment retention after temperature changes. For suppliers of Saudi Arabia metalenses for optical communication, near-infrared camera metalenses are not automatically qualified replacements for lenses in optical transceiver packages. During qualification of Saudi Arabia metalenses for optical communication, in Saudi Arabia, procurement is concentrated on the operating requirements of the relevant imported or locally integrated product, rather than sales of the entire downstream system.
United Arab Emirates Engineering base Within United Arab Emirates metalenses for optical communication, the UAE serves as both an optical-equipment deployment location and a regional distribution node. For United Arab Emirates metalenses for optical communication, imported component validation and logistics coverage can be important even when the optical device is built elsewhere. For communication metalenses purchased in United Arab Emirates, The technical decision involves phase error, numerical aperture, infrared bandwidth, fiber coupling loss and alignment retention after temperature changes. In United Arab Emirates metalenses for optical communication, near-infrared camera metalenses are not automatically qualified replacements for lenses in optical transceiver packages. Across United Arab Emirates metalenses for optical communication, in United Arab Emirates, procurement is concentrated on the operating requirements of the relevant imported or locally integrated product, rather than sales of the entire downstream system.
South Africa Developing channel South African carriers and laboratories maintain mixed-generation optical infrastructures. Among South Africa metalenses for optical communication, service support, access to calibrated test tools and suitable operating-temperature specifications influence replacement purchasing. For communication metalenses purchased in South Africa, The technical decision involves phase error, numerical aperture, infrared bandwidth, fiber coupling loss and alignment retention after temperature changes. When buying South Africa metalenses for optical communication, near-infrared camera metalenses are not automatically qualified replacements for lenses in optical transceiver packages. For suppliers of South Africa metalenses for optical communication, in South Africa, procurement is concentrated on the operating requirements of the relevant imported or locally integrated product, rather than sales of the entire downstream system.

Market instances

  • December 2025: Telecom optical link background. International Telecommunication Union documented itu network statistics update during December 2025. December 2025 official demand evidence for connectivity and infrastructure. In Middle East & Africa, the relevance for communication metalenses procurement is the equipment qualification and integration workload associated with the underlying optical component rather than an assumed share of an adjacent technology business. During qualification of Middle East & Africa metalenses for optical communication installations, the technical decision involves phase error, numerical aperture, infrared bandwidth, fiber coupling loss and alignment retention after temperature changes. Buyers need verifiable specifications before translating this development into recurring orders.
  • 2025: Packaged optical switching project design. 2025 — European Commission described punch optical packaging initiative. Optical switch/transceiver packaging demonstrations with micro-transfer printing. This development is relevant to Middle East & Africa because specialized communication metalenses devices enter systems via OEM qualification, overseas sourcing and integration services. Within Middle East & Africa metalenses for optical communication installations, near-infrared camera metalenses are not automatically qualified replacements for lenses in optical transceiver packages. For Middle East & Africa metalenses for optical communication installations, the relevant commercial effect is broader design capability and a potential future supplier pool, not a disclosed local market-size figure.
  • 2025: Near infrared meta-optic packaging qualification. The NIL Technology disclosure in 2025 concerned meta optics nanoimprint solutions. Manufacturer details silicon-on-glass manufacturing and narrowband near infrared designs. In Middle East & Africa metalenses for optical communication installations, for optical equipment installed or assessed in Middle East & Africa, attention turns to manufacturability, stable wavelength performance and verified reliability. Across Middle East & Africa metalenses for optical communication installations, the technical decision involves phase error, numerical aperture, infrared bandwidth, fiber coupling loss and alignment retention after temperature changes. Among Middle East & Africa metalenses for optical communication installations, local demand can respond differently depending on whether the purchaser is a research laboratory, telecom operator or large-volume device maker.
In the full report: When buying Middle East & Africa metalenses for optical communication demand, volume, price and supplier detail for Saudi Arabia, United Arab Emirates, South Africa, with estimated 2026 shares and 2027–2036 demand drivers.

Competitive Landscape

Competition is led by firms with relevant subwavelength dielectric nano-post arrays on planar wafers controlling optical wavefront, wavelength-selective focus and beam-shaping with silicon, gallium arsenide or titanium dioxide. For suppliers of metalenses for optical communication suppliers, the competitive field includes established manufacturers, original equipment suppliers and historical product brands whose present scope differs. During qualification of metalenses for optical communication suppliers, buyers compare product-specific technical evidence and order terms instead of total corporate turnover, because an optical component represents only part of a finished digital system.

Shenzhen Metalenx Technology Co., Ltd and shphotonics illustrate different capabilities within the sector. Within metalenses for optical communication suppliers, their product portfolios, production locations and support arrangements cannot be assumed identical. For metalenses for optical communication suppliers, procurement departments typically request specification sheets, samples, aging or thermal data and a long-term sourcing plan before designating a manufacturing source for a multi-year contract. A commercial evaluation of manufacturer capability therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone.

Hangzhou Najing Technology, NIL Technology (NILT), Moxtek appear in the wider manufacturer and distributor field. In metalenses for optical communication suppliers, the roles of those entities require separation: media production, component housing manufacture, systems integration and distribution do not produce the same category of invoice. Across metalenses for optical communication suppliers, market rivalry occurs at the level of the particular sold device, not across unrelated corporate divisions.

Other suppliers and historical business names include Moxtek. Among metalenses for optical communication suppliers, legacy corporate names and regional branches may persist in industry directories, while actual current production must be checked against updated company disclosures. When buying metalenses for optical communication suppliers, product-life-cycle changes can alter sourcing qualification even if an installed system continues to function with existing spare inventories. The 2027–2036 opportunity in historical company list is linked to deployment timing and customer acceptance, with supplier selection reflecting reliability, supply continuity, interface requirements and actual unit economics.

For suppliers of metalenses for optical communication suppliers, for 2027–2036, vendor differentiation will depend on manufacturing yield, documentation, reliable delivery and compatibility with demanding optical interfaces. During qualification of metalenses for optical communication suppliers, price competition may intensify in mature configurations, whereas new package geometries or archival media offer specialized margins. Within metalenses for optical communication suppliers, a customer switching supplier must weigh requalification, sample validation and operational interruption against lower unit costs. For competitive economics in 2027, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval.

Tier structure

Tier Companies Basis of competition
Tier 1 Shenzhen Metalenx Technology Co., Ltd; shphotonics; Hangzhou Najing Technology For metalenses for optical communication suppliers, direct manufacturers with published optical product or packaging activities differentiate through established process control and established technical catalogs. The first technical gate is the ability to supply subwavelength dielectric nano-post arrays on planar wafers controlling optical wavefront, wavelength-selective focus and beam-shaping with silicon, gallium arsenide or titanium dioxide in a documented, reproducible format, followed by customer qualification and reliable lead times.
Tier 2 NIL Technology (NILT); Moxtek In metalenses for optical communication suppliers, regional producers and equipment suppliers compete through specialized configurations, responsive design assistance and local service. Across metalenses for optical communication suppliers, customers generally request traceable quality records and samples in the exact form factor they need. Among metalenses for optical communication suppliers, lower production scale can be balanced by shorter engineering response times or customization of critical interfaces. In the tier 2 setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment.
Tier 3 When buying metalenses for optical communication suppliers, the broader value chain includes historical participants, distributors, integrators and component companies with adjacent expertise. For suppliers of metalenses for optical communication suppliers, their names may appear in sector coverage without establishing that each currently sells an identical qualified device. During qualification of metalenses for optical communication suppliers, product applicability is determined by specific device families, production status and customer approvals. This matters for tier 3, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software.

Key companies profiled

  • Shenzhen Metalenx Technology Co., Ltd
  • shphotonics
  • Hangzhou Najing Technology
  • NIL Technology (NILT)
  • Moxtek

Production Capacity Analysis

Production capacity relies on specialized manufacturing and testing for subwavelength dielectric nano-post arrays on planar wafers controlling optical wavefront, wavelength-selective focus and beam-shaping with silicon, gallium arsenide or titanium dioxide. Within metalenses for optical communication, effective output is constrained by qualified material lots, process yield, equipment availability and completion of electrical, optical and environmental tests. For metalenses for optical communication, announced industrial capability should not be equated automatically with installed sales or usable nameplate capacity.

Initial manufacturing operations include subwavelength dielectric nano-post arrays on planar wafers controlling optical wavefront, wavelength-selective focus and beam-shaping with silicon, gallium arsenide or titanium dioxide. In metalenses for optical communication, yield is influenced by each fabrication and assembly stage, while changes in materials or process equipment can require formal requalification. Across metalenses for optical communication, japan, China and other Asia-Pacific manufacturing centers support considerable supplier capacity, although customer purchasing decisions may originate elsewhere.

Among metalenses for optical communication, diversified capacity can reduce country-of-origin exposure and help supply different qualification requirements. When buying metalenses for optical communication, however, transferring tooling and process knowledge between plants takes time, and products made in new locations may require fresh qualification. For suppliers of metalenses for optical communication, strong inventory controls and component traceability are important during a period of changing designs and volatile customer orders. A commercial evaluation of capacity diversification therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone.

During qualification of metalenses for optical communication, upstream constraints include materials, specialized assembly equipment and trained optical manufacturing staff. For metalens for optical communication, packaging, testing and maintenance infrastructure shape the ability to convert a technical design into reproducible revenue. Within metalenses for optical communication, companies should distinguish capacity for direct in-scope products from headline capacity for the much larger adjacent electronics manufacturing market. The 2027–2036 opportunity in capacity bottlenecks is linked to deployment timing and customer acceptance, with supplier selection reflecting reliability, supply continuity, interface requirements and actual unit economics.

Market Dynamics

Demand is driven by miniaturization of optical coupling assemblies and nanoimprint scalability for wafer-level flat optics. For metalenses for optical communication lead, growth depends on matching the optical product to qualification requirements, logistics and total ownership cost. Supplier economics also reflect the negative impact of no broad proof of telecom metalens shipping volumes, particularly when customers require long operational support.

MARKET DRIVERS

Drivers Impact Analysis*

Driver (~) % impact on CAGR forecast Geographic relevance Impact timeline
Miniaturization of optical coupling assemblies +1.8% Asia-Pacific 2027–2036
Nanoimprint scalability for wafer-level flat optics +1.4% Global 2028–2034
High-bandwidth optical packaging density +1.1% North America 2027–2031
Growth in industrial fiber sensing +0.9% Europe 2029–2036
Longer-term free-space optical link research +0.7% Global 2028–2035

Miniaturization of optical coupling assemblies

Miniaturization of optical coupling assemblies supports specialized purchases for metalens for optical communication. subwavelength dielectric nano-post arrays on planar wafers controlling optical wavefront, wavelength-selective focus and beam-shaping with silicon, gallium arsenide or titanium dioxide must be integrated into customer processes, inspected and supported. In metalenses for optical communication drivers, the growth effect is directional, not a separate addition to the headline CAGR. Across metalenses for optical communication drivers, actual adoption depends on confirmed orders, service requirements and the lifecycle of equipment already installed.

Nanoimprint scalability for wafer-level flat optics

Nanoimprint scalability for wafer-level flat optics supports specialized purchases for metalens for optical communication. subwavelength dielectric nano-post arrays on planar wafers controlling optical wavefront, wavelength-selective focus and beam-shaping with silicon, gallium arsenide or titanium dioxide must be integrated into customer processes, inspected and supported. Among metalenses for optical communication drivers, the growth effect is directional, not a separate addition to the headline CAGR. When buying metalenses for optical communication drivers, actual adoption depends on confirmed orders, service requirements and the lifecycle of equipment already installed.

High-bandwidth optical packaging density

High-bandwidth optical packaging density supports specialized purchases for metalens for optical communication. subwavelength dielectric nano-post arrays on planar wafers controlling optical wavefront, wavelength-selective focus and beam-shaping with silicon, gallium arsenide or titanium dioxide must be integrated into customer processes, inspected and supported. For suppliers of metalenses for optical communication drivers, the growth effect is directional, not a separate addition to the headline CAGR. During qualification of metalenses for optical communication drivers, actual adoption depends on confirmed orders, service requirements and the lifecycle of equipment already installed.

Growth in industrial fiber sensing

Growth in industrial fiber sensing supports specialized purchases for metalens for optical communication. subwavelength dielectric nano-post arrays on planar wafers controlling optical wavefront, wavelength-selective focus and beam-shaping with silicon, gallium arsenide or titanium dioxide must be integrated into customer processes, inspected and supported. Within metalenses for optical communication drivers, the growth effect is directional, not a separate addition to the headline CAGR. For metalenses for optical communication drivers, actual adoption depends on confirmed orders, service requirements and the lifecycle of equipment already installed.

MARKET RESTRAINTS

Restraints Impact Analysis*

Restraint (~) % impact on CAGR forecast Geographic relevance Impact timeline
No broad proof of telecom metalens shipping volumes −1.5% Global 2027–2036
Chromatic aberration and optical efficiency constraints −1.1% Europe and North America 2027–2034
Nanopatterning yield and alignment challenges −0.8% Asia-Pacific 2028–2035
High uncertainty in extremely fast forecast extrapolation −0.6% Global 2029–2036

No broad proof of telecom metalens shipping volumes

No broad proof of telecom metalens shipping volumes increases the effort required to qualify or replace metalens for optical communication. In metalenses for optical communication restraints, a technical disadvantage can translate into delayed procurement, more maintenance work or poorer economics for the user. Across metalenses for optical communication restraints, suppliers that demonstrate stable performance and clear service processes may offset some of this commercial risk, but the constraint remains important for 2027–2036 forecasts. For No broad proof of telecom metalens shipping volumes restraint in 2032, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval.

Chromatic aberration and optical efficiency constraints

Chromatic aberration and optical efficiency constraints increases the effort required to qualify or replace metalens for optical communication. Among metalenses for optical communication restraints, a technical disadvantage can translate into delayed procurement, more maintenance work or poorer economics for the user. When buying metalenses for optical communication restraints, suppliers that demonstrate stable performance and clear service processes may offset some of this commercial risk, but the constraint remains important for 2027–2036 forecasts. In the Chromatic aberration and optical efficiency constraints restraint setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment.

Nanopatterning yield and alignment challenges

Nanopatterning yield and alignment challenges increases the effort required to qualify or replace metalens for optical communication. For suppliers of metalenses for optical communication restraints, a technical disadvantage can translate into delayed procurement, more maintenance work or poorer economics for the user. During qualification of metalenses for optical communication restraints, suppliers that demonstrate stable performance and clear service processes may offset some of this commercial risk, but the constraint remains important for 2027–2036 forecasts. This matters for Nanopatterning yield and alignment challenges restraint, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software.

High uncertainty in extremely fast forecast extrapolation

High uncertainty in extremely fast forecast extrapolation increases the effort required to qualify or replace metalens for optical communication. Within metalenses for optical communication restraints, a technical disadvantage can translate into delayed procurement, more maintenance work or poorer economics for the user. For metalenses for optical communication restraints, suppliers that demonstrate stable performance and clear service processes may offset some of this commercial risk, but the constraint remains important for 2027–2036 forecasts. A commercial evaluation of High uncertainty in extremely fast forecast extrapolation restraint therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone.

MARKET OPPORTUNITIES

Infrared metalenses for fiber collimation

Infrared metalenses for fiber collimation creates an opportunity to improve deployment or the supplier value proposition. The relevant engineering work concerns subwavelength dielectric nano-post arrays on planar wafers controlling optical wavefront, wavelength-selective focus and beam-shaping with silicon, gallium arsenide or titanium dioxide. In metalenses for optical communication opps, buyers still require evidence of stable operation, a practical purchasing channel, training and a predictable replacement schedule. Across metalenses for optical communication opps, the commercial impact is strongest where those requirements can be standardized across several customers.

Wafer-level integration with silicon photonics

Wafer-level integration with silicon photonics creates an opportunity to improve deployment or the supplier value proposition. Among metalenses for optical communication opps, the relevant engineering work concerns subwavelength dielectric nano-post arrays on planar wafers controlling optical wavefront, wavelength-selective focus and beam-shaping with silicon, gallium arsenide or titanium dioxide. When buying metalenses for optical communication opps, buyers still require evidence of stable operation, a practical purchasing channel, training and a predictable replacement schedule. For suppliers of metalenses for optical communication opps, the commercial impact is strongest where those requirements can be standardized across several customers.

Planar beam shaping for optical sensing

Planar beam shaping for optical sensing creates an opportunity to improve deployment or the supplier value proposition. During qualification of metalenses for optical communication opps, the relevant engineering work concerns subwavelength dielectric nano-post arrays on planar wafers controlling optical wavefront, wavelength-selective focus and beam-shaping with silicon, gallium arsenide or titanium dioxide. Within metalenses for optical communication opps, buyers still require evidence of stable operation, a practical purchasing channel, training and a predictable replacement schedule. For metalenses for optical communication opps, the commercial impact is strongest where those requirements can be standardized across several customers.

Hybrid lens assemblies for space optical links

Hybrid lens assemblies for space optical links creates an opportunity to improve deployment or the supplier value proposition. In metalenses for optical communication opps, the relevant engineering work concerns subwavelength dielectric nano-post arrays on planar wafers controlling optical wavefront, wavelength-selective focus and beam-shaping with silicon, gallium arsenide or titanium dioxide. Across metalenses for optical communication opps, buyers still require evidence of stable operation, a practical purchasing channel, training and a predictable replacement schedule. Among metalenses for optical communication opps, the commercial impact is strongest where those requirements can be standardized across several customers.

Supply Chain Analysis

The supply chain links specialized raw materials, device fabrication, verification, system integration and servicing for metalens for optical communication. A failure at any stage can invalidate the qualified end product. When buying metalenses for optical communication channels, vendor selection is therefore affected by more than selling price: replacement-component availability, inspection data, lead time and the ability to support legacy interfaces are commercially significant.

Upstream materialsMaterials and optical substrates required for subwavelength dielectric nano-post arrays on planar wafers controlling optical wavefront, wavelength-selective focus and beam-shaping with silicon, gallium arsenide or titanium dioxide; inspection before assembly. The 2027–2036 opportunity in Upstream materials is linked to deployment timing and customer acceptance, with supplier selection reflecting reliability, supply continuity, interface requirements and actual unit economics.
ManufacturingFabrication, alignment, sealing or recording operations matched to the market boundary. For Manufacturing in 2027, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval. In the Manufacturing setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment.
ChannelsFor suppliers of metalenses for optical communication channels, oEM engineering contracts, technical distributors and integrated storage or optical equipment vendors. This matters for Channels, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software. A commercial evaluation of Channels therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone.
Downstream usersfiber transceiver designers, integrated photonic packaging companies, telecom equipment laboratories, fiber-sensing module OEMs and free-space optical systems developers; qualification, deployment and lifecycle support. The 2027–2036 opportunity in Downstream users is linked to deployment timing and customer acceptance, with supplier selection reflecting reliability, supply continuity, interface requirements and actual unit economics. For Downstream users in 2032, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval.

Upstream materials. During qualification of metalenses for optical communication channels, materials and optical substrates required for subwavelength dielectric nano-post arrays on planar wafers controlling optical wavefront, wavelength-selective focus and beam-shaping with silicon, gallium arsenide or titanium dioxide; inspection before assembly. For metalens for optical communication, controlling change across this stage enables traceability, reliability and repeatable delivery. Within metalenses for optical communication channels, purchasing teams demand technical records that explain product behavior and clarify responsibility if a component fails after deployment.

Manufacturing. Fabrication, alignment, sealing or recording operations matched to the market boundary. For metalenses for optical communication channels, for metalens for optical communication, controlling change across this stage enables traceability, reliability and repeatable delivery. In metalenses for optical communication channels, purchasing teams demand technical records that explain product behavior and clarify responsibility if a component fails after deployment. In the Manufacturing chain setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment.

Channels. Across metalenses for optical communication channels, oEM engineering contracts, technical distributors and integrated storage or optical equipment vendors. Among metalenses for optical communication channels, for metalens for optical communication, controlling change across this stage enables traceability, reliability and repeatable delivery. When buying metalenses for optical communication channels, purchasing teams demand technical records that explain product behavior and clarify responsibility if a component fails after deployment. This matters for Channels chain, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software.

Downstream users. For suppliers of metalenses for optical communication channels, fiber transceiver designers, integrated photonic packaging companies, telecom equipment laboratories, fiber-sensing module OEMs and free-space optical systems developers; qualification, deployment and lifecycle support. During qualification of metalenses for optical communication channels, for metalens for optical communication, controlling change across this stage enables traceability, reliability and repeatable delivery. Within metalenses for optical communication channels, purchasing teams demand technical records that explain product behavior and clarify responsibility if a component fails after deployment for the 27 publication.

Recent Developments

  • 9 September 2026 Announced
    NIL Technology demonstrated production-oriented metasurface optics at CIOE 2026, including polarization-switching transmit optics. This expands the available design toolkit for compact photonic packages; the demonstration did not provide separately verified deployment volumes for fiber-optic communication metalenses, so conversion to qualified telecom sales remains a future commercial step. A commercial evaluation of Metalens for Optical Communication development 9 September 2026 therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone. Source
  • 27 July 2026 Published
    The European ADOPTION project reported progress in co-packaged optics, optical port breakout and wavelength-selective switching architectures. Compact beam delivery and fiber coupling may eventually benefit from metasurface design, but the existing project evidence concerns a wider optical package and does not establish telecommunications metalens procurement orders. The 2027–2036 opportunity in Metalens for Optical Communication development 27 July 2026 is linked to deployment timing and customer acceptance, with supplier selection reflecting reliability, supply continuity, interface requirements and actual unit economics. Source
  • 12 November 2025 Announced
    Metalenz and UMC disclosed foundry-ready 12-inch metasurface processing for polarization-based authentication hardware. The importance for communications-related metalens developers is scale manufacturing capability and lithographic repeatability, not immediate proof of optical transceiver qualification at telecom wavelengths. For Metalens for Optical Communication development 12 November 2025 in 2027, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval. Source
  • 10 July 2025 Announced
    STMicroelectronics and Metalenz expanded a production license for metasurface optics. The collaboration illustrates how optical nanostructures can enter a semiconductor qualification regime, with attention to yield, optical testing and customer acceptance. The announced applications are principally sensing; communication optics require distinct bandwidth and loss qualification. In the Metalens for Optical Communication development 10 July 2025 setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment. Source
  • March 2025 Published
    The European METAPRINT program started a nanoimprint-focused pilot for ceramic meta-optical elements, demonstrating an industrial route to repeated subwavelength surface features. Although its initial target is augmented-reality optics, fabrication know-how can inform future fiber-coupling and free-space communications designs when their optical budgets are independently met. For Metalens for Optical Communication development March 2025 in 2032, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval. Source
  • 29 January 2025 Published
    NIL Technology received a Prism Award for its metaEye compact camera platform using stacked flat lenses. While the optical architecture shows strong miniaturization potential, near-infrared imaging is a distinct buyer market from optical fiber transceivers; developers should validate mechanical alignment and thermal response for the communication use case. This matters for Metalens for Optical Communication development 29 January 2025, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software. Source
  • 24 January 2025 Announced
    NIL Technology launched its compact near-infrared meta-optics camera series, showing manufacturable flat-lens assemblies over a range of operating distances. The advance helps demonstrate optical design capability, yet near-infrared camera adoption cannot simply be booked as communication-metalens demand. A commercial evaluation of Metalens for Optical Communication development 24 January 2025 therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone. Source
  • 6 January 2025 Announced
    Radiant Opto-Electronics completed its acquisition of NIL Technology. The transaction added scaled optoelectronic module manufacturing resources alongside nanoscale flat-optic design. Such vertical integration could reduce the cost of future communication-optics packaging if manufacturers establish telecom wavelength performance, endurance and material qualification. The 2027–2036 opportunity in Metalens for Optical Communication development 6 January 2025 is linked to deployment timing and customer acceptance, with supplier selection reflecting reliability, supply continuity, interface requirements and actual unit economics. Source

REPORT SCOPE & SEGMENTATION

Attribute Details
Study Period 2021–2036
Base Year 2026
Estimated Year 2027
Forecast Period 2027–2036
Historical Period 2021–2025
Base Year Market Size USD 93 million
Estimated Year Market Size USD 165 million
Forecast Year Market Size USD 30,589 million
CAGR 78.6%
Unit USD million
Market Definition flat meta-optical elements explicitly supplied for communications or fiber sensing, including experimental telecom infrared focusing and coupling components; excludes established consumer camera metalenses and all coherent transceiver electronics unless separately specified
By Type Visible Light Metalens · Infrared Metalens
By Application Optical Fiber Communication · Optical Fiber Sensing · Others
By Material Type Silicon-based Metalens · Gallium Arsenide (GaAs) based Metalens · Titanium Dioxide (TiO₂) based Metalens · Others
By End-Use Industry Telecommunications · Data Centers · Defense & Aerospace · Medical & Healthcare · Others
By Region Asian optical-component manufacturing supports emerging metasurface fabrication, while North American and European optical designers focus on phase control and photonic assembly for telecom infrastructure and testing applications.
Asia-PacificChina · Japan · India · South Korea
North AmericaUnited States · Canada · Mexico
EuropeGermany · United Kingdom · France
South AmericaBrazil · Chile · Argentina
Middle East & AfricaSaudi Arabia · United Arab Emirates · South Africa
Key Companies Profiled Shenzhen Metalenx Technology Co., Ltd; shphotonics; Hangzhou Najing Technology; NIL Technology (NILT); Moxtek
Customization Scope Supplier, type, application and regional price analysis for metalens for optical communication; estimated market shares in 2026 and differentiated growth paths for 2027–2036.

Frequently Asked Questions

What is the global metalens for optical communication market size?

The global metalens for optical communication market is valued at USD 93 million in 2026 and is forecast to reach USD 30,589 million by 2036, with 78.6% CAGR during 2027–2036. For metalenses for optical communication purchasers, the demand boundary is specific to the optical equipment and technology defined here rather than the full revenue of all data-center, media, automotive or electronics systems.

Which geographic region is the largest market?

Asia-Pacific is the leading 2026 regional market with an estimated ~46% of revenue. North America and Europe follow at ~25% and ~19%, respectively. In metalenses for optical communication purchasers, differences in OEM manufacturing locations and customer purchasing geography can otherwise distort region comparisons. In the FAQ 2 setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment.

Which region has the fastest growth rate?

Asia-Pacific has the highest estimated regional expansion at ~79.9% CAGR through 2036. Across metalenses for optical communication purchasers, china combines multiple metalens startup and fabrication candidates with established wafer-processing and optical-module suppliers; Japan and South Korea offer lithography, metrology and semiconductor packaging capacity. Telecom metalens design wins must be distinguished from near-infrared sensing shipments. Among metalenses for optical communication purchasers, the key purchasing obstacle remains optical efficiency and bandwidth across real communication wavelengths. When buying metalenses for optical communication purchasers, the rate is linked to equipment deployment, supplier qualification and the technology mix, rather than broad GDP growth alone.

Which type holds the largest revenue share?

Infrared Metalens represents an estimated ~73% of the 2026 market. For suppliers of metalenses for optical communication purchasers, infrared metalenses target near-infrared and telecom-relevant wavelength bands for compact beam shaping and fiber coupling; alignment tolerances and link power budgets determine usefulness. During qualification of metalenses for optical communication purchasers, buyers need to verify its performance, equipment compatibility and the available delivery chain before treating it as an interchangeable substitute for another optical format.

Which type is projected to expand fastest?

Infrared Metalens carries the strongest estimated type growth at ~80.0% CAGR, from around ~73% of 2026 revenue. Within metalenses for optical communication purchasers, the product mix changes as users adopt performance-enhancing configurations, but engineering qualification and lifecycle servicing determine how quickly that potential converts into orders. This matters for FAQ 5, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software.

What is the leading application?

Optical Fiber Communication is the largest application at approximately ~65% of 2026 revenue. For metalenses for optical communication purchasers, fiber communication components require low-loss focusing at qualified transport wavelengths, stable alignment over temperature and repeatable fabrication before any flat lens can replace a refractive optic. In metalenses for optical communication purchasers, procurement specifications depend on actual operating conditions; total revenue in the wider user industry is not a direct proxy for the value of optical equipment purchased.

Which application grows fastest?

Optical Fiber Communication is projected to grow at ~79.4% CAGR from approximately ~65% of 2026 revenue. Across metalenses for optical communication purchasers, fiber communication components require low-loss focusing at qualified transport wavelengths, stable alignment over temperature and repeatable fabrication before any flat lens can replace a refractive optic. Among metalenses for optical communication purchasers, growth is affected by price changes and supplier qualification as well as physical unit demand.

Which companies are included?

The profiled market participants include Shenzhen Metalenx Technology Co., Ltd, shphotonics, Hangzhou Najing Technology, NIL Technology (NILT), Moxtek. When buying metalenses for optical communication purchasers, these companies may operate in different parts of the value chain and in some cases retain historical naming. For suppliers of metalenses for optical communication purchasers, comparisons need to distinguish direct in-scope equipment manufacturing from distribution, materials and wider group revenues. A commercial evaluation of FAQ 8 therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone.

What restrains adoption?

No broad proof of telecom metalens shipping volumes is a notable limitation, alongside chromatic aberration and optical efficiency constraints. Customers must also examine service cost, quality-control requirements and purchasing terms. During qualification of metalenses for optical communication purchasers, technical improvement will not necessarily produce corresponding annual revenue growth without reproducible production and access to qualified buyers. The 2027–2036 opportunity in FAQ 9 is linked to deployment timing and customer acceptance, with supplier selection reflecting reliability, supply continuity, interface requirements and actual unit economics.

What is the study period and segmentation scope?

Within metalenses for optical communication purchasers, the base year is 2026, the estimated year is 2027, and the forecast runs through 2036 with historical context from 2021–2025. Segmentation by type covers Visible Light Metalens, Infrared Metalens and by application covers Optical Fiber Communication, Optical Fiber Sensing, Others. Five geographic regions are included. For FAQ 10 in 2027, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval.

Research Sources & Evidence Base
View research sources used for this overview
  1. NIL Technology. Metalenses design and production, Manufacturer describes VIS/NIR/SWIR metasurface design and manufacturing
  2. NIL Technology. Meta optics nanoimprint solutions, Manufacturer details silicon-on-glass manufacturing and narrowband near infrared designs
  3. NIL Technology. CIOE 2026 meta-optical manufacturing, 9 September 2026 supplier demonstrates polarization switching metasurface optics
  4. NIL Technology. High-volume NIR meta optics production, Manufacturer discusses electron beam masters and nanoimprint replication
  5. NIL Technology. Metalens focusing efficiency results, Manufacturer technical report of 94% absolute focusing efficiency in controlled wavelength conditions
  6. NIL Technology. Radiant acquisition of NIL Technology, 6 January 2025 corporate acquisition bringing large scale optical manufacturing
  7. NIL Technology. MetaEye 2025 Prism Award, 29 January 2025 compact metalens imaging product award; adjacent sensor market, not proven telecom deployment
  8. Metalenz. STMicroelectronics metalens licensing, 10 July 2025 300 mm semiconductor photonics production collaboration
  9. Metalenz. UMC polarization metasurface production, 12 November 2025 12-inch silicon foundry mass-production announcement
  10. Metalenz. Commercial metasurface time-of-flight optics, 2022 first meta-optic use in consumer sensing, not an optical transceiver shipment
  11. Metalenz. Metasurface process architecture, Direct manufacturer explanation of wavefront control and fabless design
  12. European Commission. METAPRINT ceramic nanoimprint pilot, March 2025 pilot-line funding for metasurface optical elements
  13. European Commission. PIXEurope integrated photonics pilot, June 2025 PIC manufacturing scale-up infrastructure
  14. European Commission. ADOPTION co-packaged optics switching, 27 July 2026 European photonic transceiver and optical-switch integration progress
  15. International Telecommunication Union. ITU network statistics update, December 2025 official demand evidence for connectivity and infrastructure
  16. GSMA. 2026 mobile industry outlook, Industry association primary report on optical network end users
  17. NIL Technology. 2025 NIR metaCamera platform, 24 January 2025 near-infrared camera launch, illustrating optical manufacturing beyond telecom
  18. European Commission. PUNCH optical packaging initiative, Optical switch/transceiver packaging demonstrations with micro-transfer printing
  19. imec. Advanced photonics manufacturing agenda, May 2025 technical meetings on wafer-level optics and nanoimprint challenges
  20. Semiconductor Industry Association. Global semiconductor sales 2025, 6 February 2026 broader chip sector context, not direct telecom metalens sales
Metalens for Optical Communication Market

Get Sample Report PDF for Exclusive Insights

Report Sample Includes

  • Table of Contents
  • List of Tables & Figures
  • Charts, Research Methodology, and more...

PDF Icon Download Sample Report PDF

Download Sample Report

Table of Content

1 Introduction to Research & Analysis Reports
1.1 Metalens for Optical Communication Market Definition
1.2 Market Segments
1.2.1 Segment by Type
1.2.2 Segment by Application
1.3 Global Metalens for Optical Communication Market Overview
1.4 Features & Benefits of This Report
1.5 Methodology & Sources of Information
1.5.1 Research Methodology
1.5.2 Research Process
1.5.3 Base Year
1.5.4 Report Assumptions & Caveats
2 Global Metalens for Optical Communication Overall Market Size
2.1 Global Metalens for Optical Communication Market Size: 2024 VS 2032
2.2 Global Metalens for Optical Communication Market Size, Prospects & Forecasts: 2026-2034
2.3 Global Metalens for Optical Communication Sales: 2026-2034
3 Company Landscape
3.1 Top Metalens for Optical Communication Players in Global Market
3.2 Top Global Metalens for Optical Communication Companies Ranked by Revenue
3.3 Global Metalens for Optical Communication Revenue by Companies
3.4 Global Metalens for Optical Communication Sales by Companies
3.5 Global Metalens for Optical Communication Price by Manufacturer (2020-2025)
3.6 Top 3 and Top 5 Metalens for Optical Communication Companies in Global Market, by Revenue in 2024
3.7 Global Manufacturers Metalens for Optical Communication Product Type
3.8 Tier 1, Tier 2, and Tier 3 Metalens for Optical Communication Players in Global Market
3.8.1 List of Global Tier 1 Metalens for Optical Communication Companies
3.8.2 List of Global Tier 2 and Tier 3 Metalens for Optical Communication Companies
4 Sights by Product
4.1 Overview
4.1.1 Segment by Type – Global Metalens for Optical Communication Market Size Markets, 2024 & 2032
4.1.2 Visible Light Metalens
4.1.3 Infrared Metalens
4.2 Segment by Type – Global Metalens for Optical Communication Revenue & Forecasts
4.2.1 Segment by Type – Global Metalens for Optical Communication Revenue, 2020-2025
4.2.2 Segment by Type – Global Metalens for Optical Communication Revenue, 2026-2032
4.2.3 Segment by Type – Global Metalens for Optical Communication Revenue Market Share, 2026-2034
4.3 Segment by Type – Global Metalens for Optical Communication Sales & Forecasts
4.3.1 Segment by Type – Global Metalens for Optical Communication Sales, 2020-2025
4.3.2 Segment by Type – Global Metalens for Optical Communication Sales, 2026-2032
4.3.3 Segment by Type – Global Metalens for Optical Communication Sales Market Share, 2026-2034
4.4 Segment by Type – Global Metalens for Optical Communication Price (Manufacturers Selling Prices), 2026-2034
5 Sights by Application
5.1 Overview
5.1.1 Segment by Application – Global Metalens for Optical Communication Market Size, 2024 & 2032
5.1.2 Optical Fiber Communication
5.1.3 Optical Fiber Sensing
5.1.4 Others
5.2 Segment by Application – Global Metalens for Optical Communication Revenue & Forecasts
5.2.1 Segment by Application – Global Metalens for Optical Communication Revenue, 2020-2025
5.2.2 Segment by Application – Global Metalens for Optical Communication Revenue, 2026-2032
5.2.3 Segment by Application – Global Metalens for Optical Communication Revenue Market Share, 2026-2034
5.3 Segment by Application – Global Metalens for Optical Communication Sales & Forecasts
5.3.1 Segment by Application – Global Metalens for Optical Communication Sales, 2020-2025
5.3.2 Segment by Application – Global Metalens for Optical Communication Sales, 2026-2032
5.3.3 Segment by Application – Global Metalens for Optical Communication Sales Market Share, 2026-2034
5.4 Segment by Application – Global Metalens for Optical Communication Price (Manufacturers Selling Prices), 2026-2034
6 Sights by Region
6.1 By Region – Global Metalens for Optical Communication Market Size, 2024 & 2032
6.2 By Region – Global Metalens for Optical Communication Revenue & Forecasts
6.2.1 By Region – Global Metalens for Optical Communication Revenue, 2020-2025
6.2.2 By Region – Global Metalens for Optical Communication Revenue, 2026-2032
6.2.3 By Region – Global Metalens for Optical Communication Revenue Market Share, 2026-2034
6.3 By Region – Global Metalens for Optical Communication Sales & Forecasts
6.3.1 By Region – Global Metalens for Optical Communication Sales, 2020-2025
6.3.2 By Region – Global Metalens for Optical Communication Sales, 2026-2032
6.3.3 By Region – Global Metalens for Optical Communication Sales Market Share, 2026-2034
6.4 North America
6.4.1 By Country – North America Metalens for Optical Communication Revenue, 2026-2034
6.4.2 By Country – North America Metalens for Optical Communication Sales, 2026-2034
6.4.3 United States Metalens for Optical Communication Market Size, 2026-2034
6.4.4 Canada Metalens for Optical Communication Market Size, 2026-2034
6.4.5 Mexico Metalens for Optical Communication Market Size, 2026-2034
6.5 Europe
6.5.1 By Country – Europe Metalens for Optical Communication Revenue, 2026-2034
6.5.2 By Country – Europe Metalens for Optical Communication Sales, 2026-2034
6.5.3 Germany Metalens for Optical Communication Market Size, 2026-2034
6.5.4 France Metalens for Optical Communication Market Size, 2026-2034
6.5.5 U.K. Metalens for Optical Communication Market Size, 2026-2034
6.5.6 Italy Metalens for Optical Communication Market Size, 2026-2034
6.5.7 Russia Metalens for Optical Communication Market Size, 2026-2034
6.5.8 Nordic Countries Metalens for Optical Communication Market Size, 2026-2034
6.5.9 Benelux Metalens for Optical Communication Market Size, 2026-2034
6.6 Asia
6.6.1 By Region – Asia Metalens for Optical Communication Revenue, 2026-2034
6.6.2 By Region – Asia Metalens for Optical Communication Sales, 2026-2034
6.6.3 China Metalens for Optical Communication Market Size, 2026-2034
6.6.4 Japan Metalens for Optical Communication Market Size, 2026-2034
6.6.5 South Korea Metalens for Optical Communication Market Size, 2026-2034
6.6.6 Southeast Asia Metalens for Optical Communication Market Size, 2026-2034
6.6.7 India Metalens for Optical Communication Market Size, 2026-2034
6.7 South America
6.7.1 By Country – South America Metalens for Optical Communication Revenue, 2026-2034
6.7.2 By Country – South America Metalens for Optical Communication Sales, 2026-2034
6.7.3 Brazil Metalens for Optical Communication Market Size, 2026-2034
6.7.4 Argentina Metalens for Optical Communication Market Size, 2026-2034
6.8 Middle East & Africa
6.8.1 By Country – Middle East & Africa Metalens for Optical Communication Revenue, 2026-2034
6.8.2 By Country – Middle East & Africa Metalens for Optical Communication Sales, 2026-2034
6.8.3 Turkey Metalens for Optical Communication Market Size, 2026-2034
6.8.4 Israel Metalens for Optical Communication Market Size, 2026-2034
6.8.5 Saudi Arabia Metalens for Optical Communication Market Size, 2026-2034
6.8.6 UAE Metalens for Optical Communication Market Size, 2026-2034
7 Manufacturers & Brands Profiles
7.1 Shenzhen Metalenx Technology Co., Ltd
7.1.1 Shenzhen Metalenx Technology Co., Ltd Company Summary
7.1.2 Shenzhen Metalenx Technology Co., Ltd Business Overview
7.1.3 Shenzhen Metalenx Technology Co., Ltd Metalens for Optical Communication Major Product Offerings
7.1.4 Shenzhen Metalenx Technology Co., Ltd Metalens for Optical Communication Sales and Revenue in Global (2020-2025)
7.1.5 Shenzhen Metalenx Technology Co., Ltd Key News & Latest Developments
7.2 shphotonics
7.2.1 shphotonics Company Summary
7.2.2 shphotonics Business Overview
7.2.3 shphotonics Metalens for Optical Communication Major Product Offerings
7.2.4 shphotonics Metalens for Optical Communication Sales and Revenue in Global (2020-2025)
7.2.5 shphotonics Key News & Latest Developments
7.3 Hangzhou Najing Technology
7.3.1 Hangzhou Najing Technology Company Summary
7.3.2 Hangzhou Najing Technology Business Overview
7.3.3 Hangzhou Najing Technology Metalens for Optical Communication Major Product Offerings
7.3.4 Hangzhou Najing Technology Metalens for Optical Communication Sales and Revenue in Global (2020-2025)
7.3.5 Hangzhou Najing Technology Key News & Latest Developments
7.4 NIL Technology (NILT)
7.4.1 NIL Technology (NILT) Company Summary
7.4.2 NIL Technology (NILT) Business Overview
7.4.3 NIL Technology (NILT) Metalens for Optical Communication Major Product Offerings
7.4.4 NIL Technology (NILT) Metalens for Optical Communication Sales and Revenue in Global (2020-2025)
7.4.5 NIL Technology (NILT) Key News & Latest Developments
7.5 Moxtek
7.5.1 Moxtek Company Summary
7.5.2 Moxtek Business Overview
7.5.3 Moxtek Metalens for Optical Communication Major Product Offerings
7.5.4 Moxtek Metalens for Optical Communication Sales and Revenue in Global (2020-2025)
7.5.5 Moxtek Key News & Latest Developments
8 Global Metalens for Optical Communication Production Capacity, Analysis
8.1 Global Metalens for Optical Communication Production Capacity, 2026-2034
8.2 Metalens for Optical Communication Production Capacity of Key Manufacturers in Global Market
8.3 Global Metalens for Optical Communication Production by Region
9 Key Market Trends, Opportunity, Drivers and Restraints
9.1 Market Opportunities & Trends
9.2 Market Drivers
9.3 Market Restraints
10 Metalens for Optical Communication Supply Chain Analysis
10.1 Metalens for Optical Communication Industry Value Chain
10.2 Metalens for Optical Communication Upstream Market
10.3 Metalens for Optical Communication Downstream and Clients
10.4 Marketing Channels Analysis
10.4.1 Marketing Channels
10.4.2 Metalens for Optical Communication Distributors and Sales Agents in Global
11 Conclusion
12 Appendix
12.1 Note
12.2 Examples of Clients
12.3 DisclaimerList of Tables
Table 1. Key Players of Metalens for Optical Communication in Global Market
Table 2. Top Metalens for Optical Communication Players in Global Market, Ranking by Revenue (2024)
Table 3. Global Metalens for Optical Communication Revenue by Companies, (US$, Mn), 2020-2025
Table 4. Global Metalens for Optical Communication Revenue Share by Companies, 2020-2025
Table 5. Global Metalens for Optical Communication Sales by Companies, (Million Units), 2020-2025
Table 6. Global Metalens for Optical Communication Sales Share by Companies, 2020-2025
Table 7. Key Manufacturers Metalens for Optical Communication Price (2020-2025) & (US$/Unit)
Table 8. Global Manufacturers Metalens for Optical Communication Product Type
Table 9. List of Global Tier 1 Metalens for Optical Communication Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 10. List of Global Tier 2 and Tier 3 Metalens for Optical Communication Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 11. Segment by Type – Global Metalens for Optical Communication Revenue, (US$, Mn), 2024 & 2032
Table 12. Segment by Type – Global Metalens for Optical Communication Revenue (US$, Mn), 2020-2025
Table 13. Segment by Type – Global Metalens for Optical Communication Revenue (US$, Mn), 2026-2032
Table 14. Segment by Type – Global Metalens for Optical Communication Sales (Million Units), 2020-2025
Table 15. Segment by Type – Global Metalens for Optical Communication Sales (Million Units), 2026-2032
Table 16. Segment by Application – Global Metalens for Optical Communication Revenue, (US$, Mn), 2024 & 2032
Table 17. Segment by Application – Global Metalens for Optical Communication Revenue, (US$, Mn), 2020-2025
Table 18. Segment by Application – Global Metalens for Optical Communication Revenue, (US$, Mn), 2026-2032
Table 19. Segment by Application – Global Metalens for Optical Communication Sales, (Million Units), 2020-2025
Table 20. Segment by Application – Global Metalens for Optical Communication Sales, (Million Units), 2026-2032
Table 21. By Region – Global Metalens for Optical Communication Revenue, (US$, Mn), 2025-2032
Table 22. By Region – Global Metalens for Optical Communication Revenue, (US$, Mn), 2020-2025
Table 23. By Region – Global Metalens for Optical Communication Revenue, (US$, Mn), 2026-2032
Table 24. By Region – Global Metalens for Optical Communication Sales, (Million Units), 2020-2025
Table 25. By Region – Global Metalens for Optical Communication Sales, (Million Units), 2026-2032
Table 26. By Country – North America Metalens for Optical Communication Revenue, (US$, Mn), 2020-2025
Table 27. By Country – North America Metalens for Optical Communication Revenue, (US$, Mn), 2026-2032
Table 28. By Country – North America Metalens for Optical Communication Sales, (Million Units), 2020-2025
Table 29. By Country – North America Metalens for Optical Communication Sales, (Million Units), 2026-2032
Table 30. By Country – Europe Metalens for Optical Communication Revenue, (US$, Mn), 2020-2025
Table 31. By Country – Europe Metalens for Optical Communication Revenue, (US$, Mn), 2026-2032
Table 32. By Country – Europe Metalens for Optical Communication Sales, (Million Units), 2020-2025
Table 33. By Country – Europe Metalens for Optical Communication Sales, (Million Units), 2026-2032
Table 34. By Region – Asia Metalens for Optical Communication Revenue, (US$, Mn), 2020-2025
Table 35. By Region – Asia Metalens for Optical Communication Revenue, (US$, Mn), 2026-2032
Table 36. By Region – Asia Metalens for Optical Communication Sales, (Million Units), 2020-2025
Table 37. By Region – Asia Metalens for Optical Communication Sales, (Million Units), 2026-2032
Table 38. By Country – South America Metalens for Optical Communication Revenue, (US$, Mn), 2020-2025
Table 39. By Country – South America Metalens for Optical Communication Revenue, (US$, Mn), 2026-2032
Table 40. By Country – South America Metalens for Optical Communication Sales, (Million Units), 2020-2025
Table 41. By Country – South America Metalens for Optical Communication Sales, (Million Units), 2026-2032
Table 42. By Country – Middle East & Africa Metalens for Optical Communication Revenue, (US$, Mn), 2020-2025
Table 43. By Country – Middle East & Africa Metalens for Optical Communication Revenue, (US$, Mn), 2026-2032
Table 44. By Country – Middle East & Africa Metalens for Optical Communication Sales, (Million Units), 2020-2025
Table 45. By Country – Middle East & Africa Metalens for Optical Communication Sales, (Million Units), 2026-2032
Table 46. Shenzhen Metalenx Technology Co., Ltd Company Summary
Table 47. Shenzhen Metalenx Technology Co., Ltd Metalens for Optical Communication Product Offerings
Table 48. Shenzhen Metalenx Technology Co., Ltd Metalens for Optical Communication Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 49. Shenzhen Metalenx Technology Co., Ltd Key News & Latest Developments
Table 50. shphotonics Company Summary
Table 51. shphotonics Metalens for Optical Communication Product Offerings
Table 52. shphotonics Metalens for Optical Communication Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 53. shphotonics Key News & Latest Developments
Table 54. Hangzhou Najing Technology Company Summary
Table 55. Hangzhou Najing Technology Metalens for Optical Communication Product Offerings
Table 56. Hangzhou Najing Technology Metalens for Optical Communication Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 57. Hangzhou Najing Technology Key News & Latest Developments
Table 58. NIL Technology (NILT) Company Summary
Table 59. NIL Technology (NILT) Metalens for Optical Communication Product Offerings
Table 60. NIL Technology (NILT) Metalens for Optical Communication Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 61. NIL Technology (NILT) Key News & Latest Developments
Table 62. Moxtek Company Summary
Table 63. Moxtek Metalens for Optical Communication Product Offerings
Table 64. Moxtek Metalens for Optical Communication Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 65. Moxtek Key News & Latest Developments
Table 66. Metalens for Optical Communication Capacity of Key Manufacturers in Global Market, 2023-2025 (Million Units)
Table 67. Global Metalens for Optical Communication Capacity Market Share of Key Manufacturers, 2023-2025
Table 68. Global Metalens for Optical Communication Production by Region, 2020-2025 (Million Units)
Table 69. Global Metalens for Optical Communication Production by Region, 2026-2032 (Million Units)
Table 70. Metalens for Optical Communication Market Opportunities & Trends in Global Market
Table 71. Metalens for Optical Communication Market Drivers in Global Market
Table 72. Metalens for Optical Communication Market Restraints in Global Market
Table 73. Metalens for Optical Communication Raw Materials
Table 74. Metalens for Optical Communication Raw Materials Suppliers in Global Market
Table 75. Typical Metalens for Optical Communication Downstream
Table 76. Metalens for Optical Communication Downstream Clients in Global Market
Table 77. Metalens for Optical Communication Distributors and Sales Agents in Global Market

List of Figures
Figure 1. Metalens for Optical Communication Product Picture
Figure 2. Metalens for Optical Communication Segment by Type in 2024
Figure 3. Metalens for Optical Communication Segment by Application in 2024
Figure 4. Global Metalens for Optical Communication Market Overview: 2024
Figure 5. Key Caveats
Figure 6. Global Metalens for Optical Communication Market Size: 2024 VS 2032 (US$, Mn)
Figure 7. Global Metalens for Optical Communication Revenue: 2026-2034 (US$, Mn)
Figure 8. Metalens for Optical Communication Sales in Global Market: 2026-2034 (Million Units)
Figure 9. The Top 3 and 5 Players Market Share by Metalens for Optical Communication Revenue in 2024
Figure 10. Segment by Type – Global Metalens for Optical Communication Revenue, (US$, Mn), 2024 & 2032
Figure 11. Segment by Type – Global Metalens for Optical Communication Revenue Market Share, 2026-2034
Figure 12. Segment by Type – Global Metalens for Optical Communication Sales Market Share, 2026-2034
Figure 13. Segment by Type – Global Metalens for Optical Communication Price (US$/Unit), 2026-2034
Figure 14. Segment by Application – Global Metalens for Optical Communication Revenue, (US$, Mn), 2024 & 2032
Figure 15. Segment by Application – Global Metalens for Optical Communication Revenue Market Share, 2026-2034
Figure 16. Segment by Application – Global Metalens for Optical Communication Sales Market Share, 2026-2034
Figure 17. Segment by Application -Global Metalens for Optical Communication Price (US$/Unit), 2026-2034
Figure 18. By Region – Global Metalens for Optical Communication Revenue, (US$, Mn), 2025 & 2032
Figure 19. By Region – Global Metalens for Optical Communication Revenue Market Share, 2020 VS 2024 VS 2032
Figure 20. By Region – Global Metalens for Optical Communication Revenue Market Share, 2026-2034
Figure 21. By Region – Global Metalens for Optical Communication Sales Market Share, 2026-2034
Figure 22. By Country – North America Metalens for Optical Communication Revenue Market Share, 2026-2034
Figure 23. By Country – North America Metalens for Optical Communication Sales Market Share, 2026-2034
Figure 24. United States Metalens for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 25. Canada Metalens for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 26. Mexico Metalens for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 27. By Country – Europe Metalens for Optical Communication Revenue Market Share, 2026-2034
Figure 28. By Country – Europe Metalens for Optical Communication Sales Market Share, 2026-2034
Figure 29. Germany Metalens for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 30. France Metalens for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 31. U.K. Metalens for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 32. Italy Metalens for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 33. Russia Metalens for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 34. Nordic Countries Metalens for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 35. Benelux Metalens for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 36. By Region – Asia Metalens for Optical Communication Revenue Market Share, 2026-2034
Figure 37. By Region – Asia Metalens for Optical Communication Sales Market Share, 2026-2034
Figure 38. China Metalens for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 39. Japan Metalens for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 40. South Korea Metalens for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 41. Southeast Asia Metalens for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 42. India Metalens for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 43. By Country – South America Metalens for Optical Communication Revenue Market Share, 2026-2034
Figure 44. By Country – South America Metalens for Optical Communication Sales, Market Share, 2026-2034
Figure 45. Brazil Metalens for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 46. Argentina Metalens for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 47. By Country – Middle East & Africa Metalens for Optical Communication Revenue, Market Share, 2026-2034
Figure 48. By Country – Middle East & Africa Metalens for Optical Communication Sales, Market Share, 2026-2034
Figure 49. Turkey Metalens for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 50. Israel Metalens for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 51. Saudi Arabia Metalens for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 52. UAE Metalens for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 53. Global Metalens for Optical Communication Production Capacity (Million Units), 2026-2034
Figure 54. The Percentage of Production Metalens for Optical Communication by Region, 2024 VS 2032
Figure 55. Metalens for Optical Communication Industry Value Chain
Figure 56. Marketing Channels

