SEMICONDUCTOR INSIGHT
MARKET RESEARCH REPORT

Inertial Measurement Unit (IMU) Market

2026 to 2034
MARKET INTELLIGENCE
ACROSS KEY REGIONS
2026 EDITION
SENSORS Semiconductor Market Research

Inertial Measurement Unit (IMU) Market

Trends, Business Strategies 2026-2034

◷
UPDATED 22 September 2026
▤
REPORT LENGTH Detailed Report
▣
REPORT CODE 3cd97d66c390
▯
FORMATS PDF

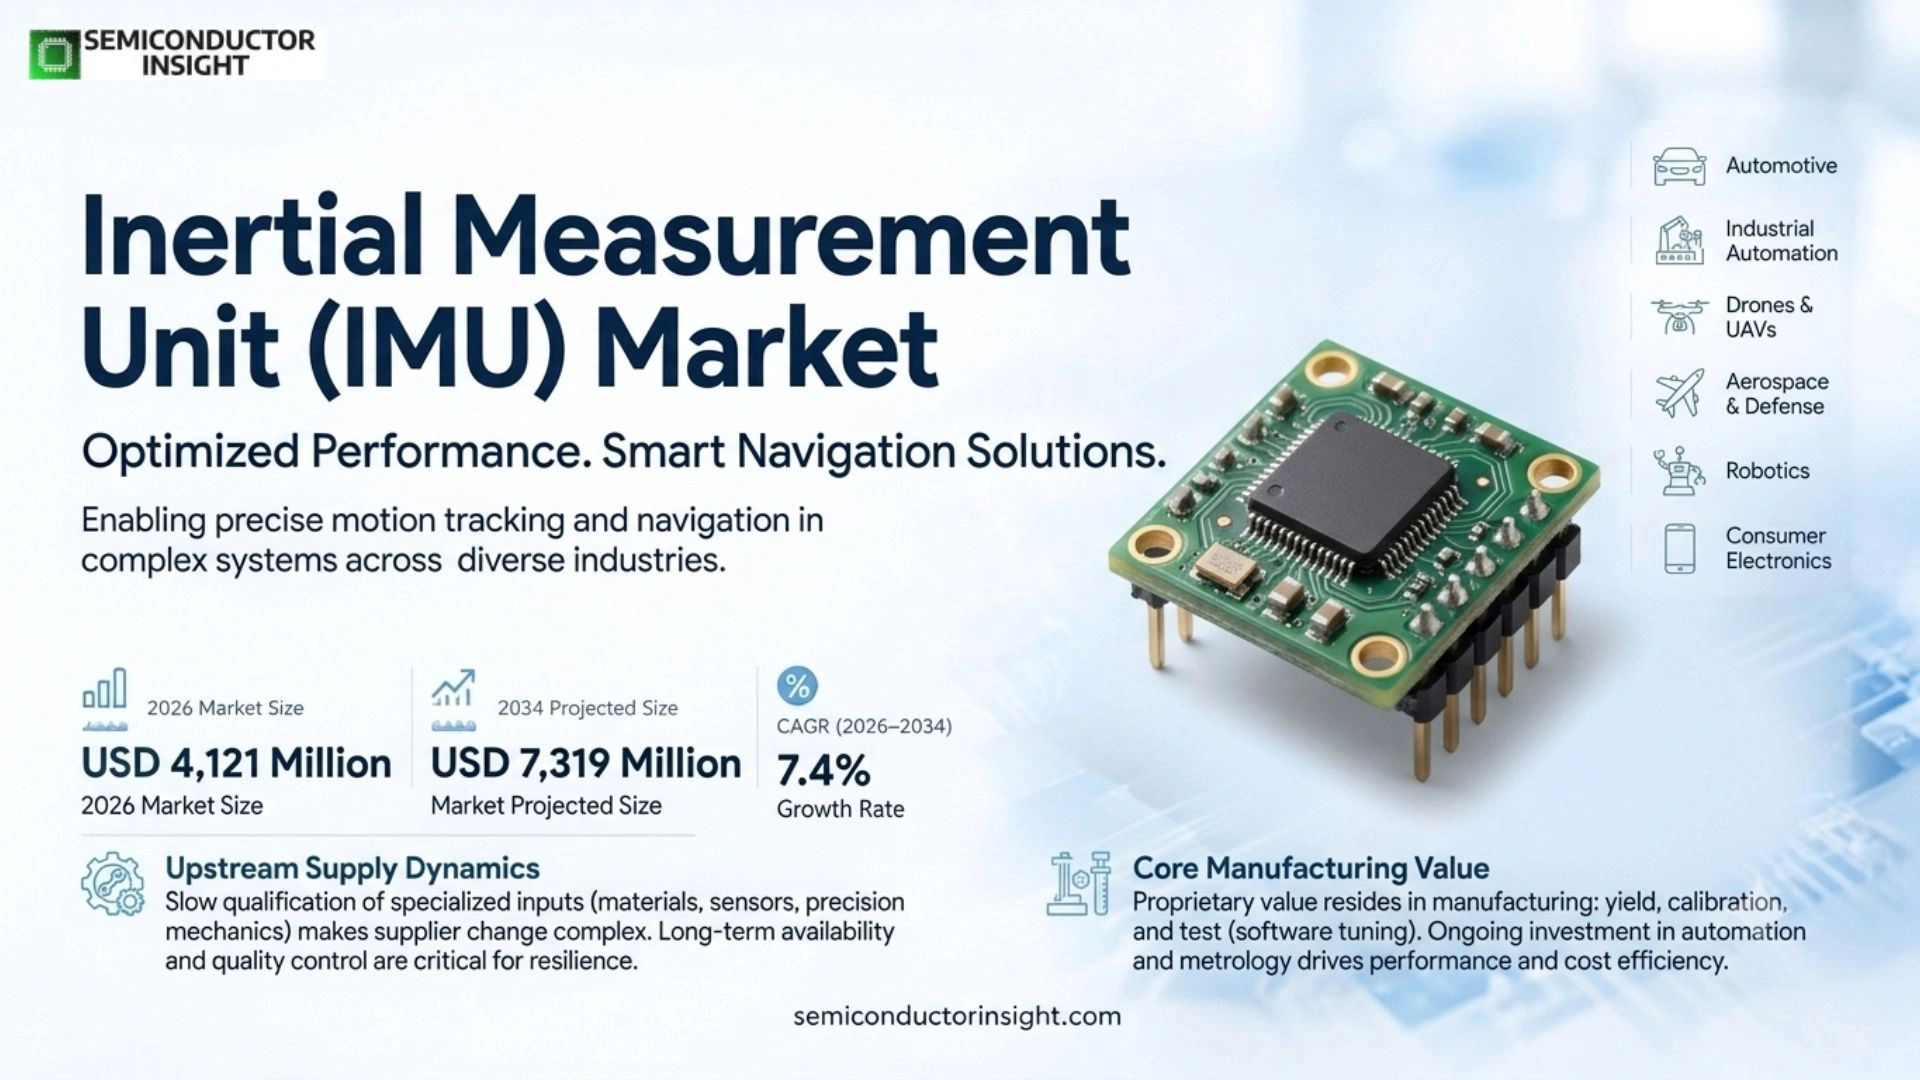
Inertial Measurement Unit (imu) Market is estimated at USD 4,121 million in 2026, and is projected to reach USD 7,319 million by 2034, corresponding to a 7.4% CAGR during 2026–2034. The leading market position in 2025 is North America (>70% on source page).

Get the sample PDF with study scope, segmentation and methodology details.

Key Statistics

2025 Market Size
USD 3,836 million
2034 Projected Size
USD 7,319 million
CAGR (2026–2034)
7.4%
Largest Market in 2025
North America (>70% on source page)

Key Takeaways

  • High-performance IMU anchors the type structure defined on the source page, while demand increasingly rewards suppliers that can improve performance per watt, integration density, calibration stability, or process productivity without increasing system complexity.
  • Defense remains a major purchasing center because system performance directly depends on the component or equipment category; qualification cycles and lifecycle support therefore matter almost as much as headline specification.
  • North America represents the leading market position in 2025, supported by the concentration of end-system production, infrastructure investment, or mission-critical procurement relevant to this category.
  • The 2025–2034 value series rises from USD 3,836 million to USD 7,319 million, implying a 7.4% CAGR for 2026–2034 when the two published market-size anchors are treated as the controlling arithmetic basis.
  • Commercial competition is increasingly ecosystem-led. Product capability remains essential, but buyers also evaluate qualification support, integration tools, service coverage, supply assurance, and roadmap continuity before changing an incumbent supplier.

Inertial Measurement Unit (IMU) Market Overview

Inertial Measurement Unit (imu) Market is valued at USD 3,836 million in 2025, is estimated at USD 4,121 million in 2026, and is projected to reach USD 7,319 million by 2034, corresponding to a 7.4% CAGR during 2026–2034. The leading market position in 2025 is North America (>70% on source page).

Base year: 2025 · Estimated year: 2026 · Forecast period: 2026–2034 · Values in USD million unless stated otherwise

Inertial Measurement Unit (IMU) sits at the intersection of component performance, system architecture, and end-market investment. The commercial boundary used here follows the source page rather than a broader adjacent category: the listed type and application segments define what is included, while neighboring technologies are discussed only where they alter purchasing behavior or substitution risk. That scope discipline matters because different performance tiers can have radically different pricing, qualification, and replacement cycles.

Demand is created when customers need a measurable improvement in throughput, bandwidth, navigation confidence, yield, power efficiency, or mission reliability that cannot be achieved by software changes alone. In response, suppliers invest in device architecture, materials, packaging, calibration, process control, and integration support. The market implication is a recurring shift toward higher-value configurations whenever end systems become more complex, even if unit volumes remain cyclical.

Technology transitions are changing the competitive basis. Buyers increasingly ask how a product behaves inside a complete platform, not just whether it meets a standalone data-sheet limit. That raises the value of reference designs, process recipes, diagnostic software, field engineering, and multi-year roadmap visibility. Suppliers able to reduce integration time or qualification risk can defend pricing better than vendors competing mainly on acquisition cost.

The forecast through 2034 therefore reflects both end-demand growth and mix improvement. Capacity additions, higher system complexity, and tighter reliability requirements expand the revenue opportunity, while cyclicality, long validation periods, export restrictions, and technology substitution temper the pace. The resulting market is attractive but technically selective: growth is strongest where the category remains essential to a customer’s performance envelope.

Segment Analysis: By Type

By type, the source page segments the Inertial Measurement Unit (IMU) market into High-performance IMU, MEMS Based IMU (except for consumer and automotive grade). These categories compete on different combinations of performance, integration complexity, lifecycle economics, and qualification burden, so revenue leadership does not necessarily track unit shipments.

Type Technical / commercial role Market position and purchasing logic
High-performance IMU High-performance IMU addresses a defined performance tier within Inertial Measurement Unit (IMU). Its technical value is determined by how effectively it improves system capability, process control, signal integrity, accuracy, or manufacturing productivity relative to alternatives.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. This segment has a leading role in the source-page structure and benefits from established qualification pathways, installed-base familiarity, and customer dependence on proven performance.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
MEMS Based IMU (except for consumer and automotive grade) MEMS Based IMU (except for consumer and automotive grade) addresses a defined performance tier within Inertial Measurement Unit (IMU). Its technical value is determined by how effectively it improves system capability, process control, signal integrity, accuracy, or manufacturing productivity relative to alternatives.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. This segment participates in the market where customers trade absolute performance against integration cost, power, footprint, manufacturability, or application-specific flexibility, creating room for differentiated suppliers.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

Pricing and value capture by type

Pricing in Inertial Measurement Unit (IMU) is shaped by qualification difficulty, performance grade, yield, packaging complexity, calibration burden, service intensity, and the economic cost of system failure. Entry configurations face greater price competition, while high-performance or process-critical variants retain stronger value capture because switching suppliers can require redesign, requalification, process re-optimization, or new reliability evidence. This creates a broad price ladder rather than a single commodity benchmark.

By End User

Segment Commercial interpretation
Government & Defense Agencies Government & Defense Agencies captures a distinct buyer requirement and qualification path. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Aerospace OEMs Aerospace OEMs captures a distinct buyer requirement and qualification path. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Industrial Corporations Industrial Corporations captures a distinct buyer requirement and qualification path. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

By Technology Grade

Segment Commercial interpretation
Tactical Grade Tactical Grade captures a distinct buyer requirement and qualification path. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Navigation Grade Navigation Grade captures a distinct buyer requirement and qualification path. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Strategic Grade Strategic Grade captures a distinct buyer requirement and qualification path. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

By System Integration

Segment Commercial interpretation
Standalone IMU Standalone IMU captures a distinct buyer requirement and qualification path. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
IMU Integrated with GPS IMU Integrated with GPS captures a distinct buyer requirement and qualification path. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
IMU as part of an INS IMU as part of an INS captures a distinct buyer requirement and qualification path. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

Segment Analysis: By Application

The application structure comprises Defense, Commercial Aerospace, Other Industrial Application. Application mix matters because purchase criteria change with reliability requirements, deployment environment, product lifecycle, acceptable downtime, and the customer’s ability to redesign around an alternative technology.

Application Demand characteristics
Defense Defense demand is created when customers need inertial measurement unit (imu) capability as part of a larger system upgrade or capacity decision. Purchasing is generally triggered by performance limits, new platform launches, capacity expansion, compliance requirements, or the need to lower operating risk. This application has the strongest structural relevance in the source-page framing and therefore serves as an important reference point for supplier positioning.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Commercial Aerospace Commercial Aerospace demand is created when customers need inertial measurement unit (imu) capability as part of a larger system upgrade or capacity decision. Purchasing is generally triggered by performance limits, new platform launches, capacity expansion, compliance requirements, or the need to lower operating risk.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Other Industrial Application Other Industrial Application demand is created when customers need inertial measurement unit (imu) capability as part of a larger system upgrade or capacity decision. Purchasing is generally triggered by performance limits, new platform launches, capacity expansion, compliance requirements, or the need to lower operating risk.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

Inertial Measurement Unit (IMU) market Size

Regional Analysis

North America (>70% on source page) holds the leading 2025 market position. Regional demand differs according to installed manufacturing capacity, end-user concentration, government policy, technology access, local engineering depth, and the maturity of supplier service networks.

How does regional demand differ across the Inertial Measurement Unit (IMU) market?

The five regional groups do not buy for identical reasons. Some markets are capacity-led, others are driven by defense or public infrastructure, and still others are shaped by advanced-node transitions, local manufacturing programs, or replacement of an aging installed base. Suppliers therefore need region-specific channel, qualification, pricing, and service strategies rather than a single global commercial model.

Region Position Growth outlook Demand profile Supplier selection
North America Largest region High-value defense and autonomy Defense/aerospace procurement in North America. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. ITAR/export controls and qualification in North America. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Europe Second tier Steady Aerospace, automotive and industrial automation in Europe. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. CE/aviation qualification and long program cycles in Europe. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Asia Pacific Fastest growth High Electronics, automotive, robotics and localization in Asia Pacific. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. Cost-performance, local supply and qualification in Asia Pacific. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
South America Smaller base Selective Defense modernization, mining and agriculture in South America. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. Import access and distributor support in South America. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Middle East & Africa Smaller base Selective Defense, space and surveying in Middle East & Africa. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. Program qualification and sovereign procurement in Middle East & Africa. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
North America LARGEST MARKET

What shapes Inertial Measurement Unit (IMU) demand in North America?

Defense/aerospace procurement in North America. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

Market positionLargest region
Growth outlookHigh-value defense and autonomy
Demand profileDefense/aerospace procurement
Market access gateITAR/export controls and qualification
Country / market Position in region Evidence-led demand logic
United States Primary demand center United States participates in Inertial Measurement Unit (IMU) demand through its mix of end-system manufacturing, infrastructure, defense, telecom, cloud, automotive, industrial, or semiconductor investment. Local purchasing decisions are influenced by project timing, technical qualification, import exposure, engineering support and the installed base of compatible platforms. in United States. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Canada Important specialist market Canada participates in Inertial Measurement Unit (IMU) demand through its mix of end-system manufacturing, infrastructure, defense, telecom, cloud, automotive, industrial, or semiconductor investment. Local purchasing decisions are influenced by project timing, technical qualification, import exposure, engineering support and the installed base of compatible platforms. in Canada. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Mexico Developing / complementary market Mexico participates in Inertial Measurement Unit (IMU) demand through its mix of end-system manufacturing, infrastructure, defense, telecom, cloud, automotive, industrial, or semiconductor investment. Local purchasing decisions are influenced by project timing, technical qualification, import exposure, engineering support and the installed base of compatible platforms. in Mexico. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

Market instances

  • North America buyers increasingly prioritize qualified supply, local technical support, and lifecycle continuity as system complexity rises. This changes supplier selection from a simple unit-price comparison into a total-risk assessment covering integration time, field reliability, and replacement availability. in North America. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
  • Investment in defense/aerospace procurement is creating fresh specification events rather than only replacement demand. New platforms or facilities allow suppliers to compete for sockets before an incumbent is locked in, so design-in support and early engineering engagement become commercially decisive. in North America. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
  • Technology roadmaps are raising performance requirements while shortening the interval between platform generations. Vendors that can support migration without forcing a complete redesign gain an advantage, particularly where customers operate long-lived assets or qualification-intensive systems. in North America. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
In the full report: country-level revenue, sales, supplier positioning, pricing and forecast detail for North America, including the markets listed above across the historical and forecast period.
Europe AEROSPACE & AUTOMOTIVE HUB

What shapes Inertial Measurement Unit (IMU) demand in Europe?

Aerospace, automotive and industrial automation in Europe. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

Market positionSecond tier
Growth outlookSteady
Demand profileAerospace, automotive and industrial automation
Market access gateCE/aviation qualification and long program cycles
Country / market Position in region Evidence-led demand logic
France Primary demand center France participates in Inertial Measurement Unit (IMU) demand through its mix of end-system manufacturing, infrastructure, defense, telecom, cloud, automotive, industrial, or semiconductor investment. Local purchasing decisions are influenced by project timing, technical qualification, import exposure, engineering support and the installed base of compatible platforms. in France. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Germany Important specialist market Germany participates in Inertial Measurement Unit (IMU) demand through its mix of end-system manufacturing, infrastructure, defense, telecom, cloud, automotive, industrial, or semiconductor investment. Local purchasing decisions are influenced by project timing, technical qualification, import exposure, engineering support and the installed base of compatible platforms. in Germany. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
United Kingdom Developing / complementary market United Kingdom participates in Inertial Measurement Unit (IMU) demand through its mix of end-system manufacturing, infrastructure, defense, telecom, cloud, automotive, industrial, or semiconductor investment. Local purchasing decisions are influenced by project timing, technical qualification, import exposure, engineering support and the installed base of compatible platforms. in United Kingdom. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

Market instances

  • Europe buyers increasingly prioritize qualified supply, local technical support, and lifecycle continuity as system complexity rises. This changes supplier selection from a simple unit-price comparison into a total-risk assessment covering integration time, field reliability, and replacement availability. in Europe. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
  • Investment in aerospace, automotive and industrial automation is creating fresh specification events rather than only replacement demand. New platforms or facilities allow suppliers to compete for sockets before an incumbent is locked in, so design-in support and early engineering engagement become commercially decisive. in Europe. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
  • Technology roadmaps are raising performance requirements while shortening the interval between platform generations. Vendors that can support migration without forcing a complete redesign gain an advantage, particularly where customers operate long-lived assets or qualification-intensive systems. in Europe. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
In the full report: country-level revenue, sales, supplier positioning, pricing and forecast detail for Europe, including the markets listed above across the historical and forecast period.
Asia Pacific FASTEST-GROWING VOLUME REGION

What shapes Inertial Measurement Unit (IMU) demand in Asia Pacific?

Electronics, automotive, robotics and localization in Asia Pacific. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

Market positionFastest growth
Growth outlookHigh
Demand profileElectronics, automotive, robotics and localization
Market access gateCost-performance, local supply and qualification
Country / market Position in region Evidence-led demand logic
China Primary demand center China participates in Inertial Measurement Unit (IMU) demand through its mix of end-system manufacturing, infrastructure, defense, telecom, cloud, automotive, industrial, or semiconductor investment. Local purchasing decisions are influenced by project timing, technical qualification, import exposure, engineering support and the installed base of compatible platforms. in China. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Japan Important specialist market Japan participates in Inertial Measurement Unit (IMU) demand through its mix of end-system manufacturing, infrastructure, defense, telecom, cloud, automotive, industrial, or semiconductor investment. Local purchasing decisions are influenced by project timing, technical qualification, import exposure, engineering support and the installed base of compatible platforms. in Japan. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
South Korea Developing / complementary market South Korea participates in Inertial Measurement Unit (IMU) demand through its mix of end-system manufacturing, infrastructure, defense, telecom, cloud, automotive, industrial, or semiconductor investment. Local purchasing decisions are influenced by project timing, technical qualification, import exposure, engineering support and the installed base of compatible platforms. in South Korea. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
India Developing / complementary market India participates in Inertial Measurement Unit (IMU) demand through its mix of end-system manufacturing, infrastructure, defense, telecom, cloud, automotive, industrial, or semiconductor investment. Local purchasing decisions are influenced by project timing, technical qualification, import exposure, engineering support and the installed base of compatible platforms. in India. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

Market instances

  • Asia Pacific buyers increasingly prioritize qualified supply, local technical support, and lifecycle continuity as system complexity rises. This changes supplier selection from a simple unit-price comparison into a total-risk assessment covering integration time, field reliability, and replacement availability. in Asia Pacific. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
  • Investment in electronics, automotive, robotics and localization is creating fresh specification events rather than only replacement demand. New platforms or facilities allow suppliers to compete for sockets before an incumbent is locked in, so design-in support and early engineering engagement become commercially decisive. in Asia Pacific. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
  • Technology roadmaps are raising performance requirements while shortening the interval between platform generations. Vendors that can support migration without forcing a complete redesign gain an advantage, particularly where customers operate long-lived assets or qualification-intensive systems. in Asia Pacific. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
In the full report: country-level revenue, sales, supplier positioning, pricing and forecast detail for Asia Pacific, including the markets listed above across the historical and forecast period.
South America EMERGING SPECIALTY MARKET

What shapes Inertial Measurement Unit (IMU) demand in South America?

Defense modernization, mining and agriculture in South America. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

Market positionSmaller base
Growth outlookSelective
Demand profileDefense modernization, mining and agriculture
Market access gateImport access and distributor support
Country / market Position in region Evidence-led demand logic
Brazil Primary demand center Brazil participates in Inertial Measurement Unit (IMU) demand through its mix of end-system manufacturing, infrastructure, defense, telecom, cloud, automotive, industrial, or semiconductor investment. Local purchasing decisions are influenced by project timing, technical qualification, import exposure, engineering support and the installed base of compatible platforms. in Brazil. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Chile Important specialist market Chile participates in Inertial Measurement Unit (IMU) demand through its mix of end-system manufacturing, infrastructure, defense, telecom, cloud, automotive, industrial, or semiconductor investment. Local purchasing decisions are influenced by project timing, technical qualification, import exposure, engineering support and the installed base of compatible platforms. in Chile. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Argentina Developing / complementary market Argentina participates in Inertial Measurement Unit (IMU) demand through its mix of end-system manufacturing, infrastructure, defense, telecom, cloud, automotive, industrial, or semiconductor investment. Local purchasing decisions are influenced by project timing, technical qualification, import exposure, engineering support and the installed base of compatible platforms. in Argentina. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

Market instances

  • South America buyers increasingly prioritize qualified supply, local technical support, and lifecycle continuity as system complexity rises. This changes supplier selection from a simple unit-price comparison into a total-risk assessment covering integration time, field reliability, and replacement availability. in South America. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
  • Investment in defense modernization, mining and agriculture is creating fresh specification events rather than only replacement demand. New platforms or facilities allow suppliers to compete for sockets before an incumbent is locked in, so design-in support and early engineering engagement become commercially decisive. in South America. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
  • Technology roadmaps are raising performance requirements while shortening the interval between platform generations. Vendors that can support migration without forcing a complete redesign gain an advantage, particularly where customers operate long-lived assets or qualification-intensive systems. in South America. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
In the full report: country-level revenue, sales, supplier positioning, pricing and forecast detail for South America, including the markets listed above across the historical and forecast period.
Middle East & Africa DEFENSE-LED NICHE

What shapes Inertial Measurement Unit (IMU) demand in Middle East & Africa?

Defense, space and surveying in Middle East & Africa. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

Market positionSmaller base
Growth outlookSelective
Demand profileDefense, space and surveying
Market access gateProgram qualification and sovereign procurement
Country / market Position in region Evidence-led demand logic
Saudi Arabia Primary demand center Saudi Arabia participates in Inertial Measurement Unit (IMU) demand through its mix of end-system manufacturing, infrastructure, defense, telecom, cloud, automotive, industrial, or semiconductor investment. Local purchasing decisions are influenced by project timing, technical qualification, import exposure, engineering support and the installed base of compatible platforms. in Saudi Arabia. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
United Arab Emirates Important specialist market United Arab Emirates participates in Inertial Measurement Unit (IMU) demand through its mix of end-system manufacturing, infrastructure, defense, telecom, cloud, automotive, industrial, or semiconductor investment. Local purchasing decisions are influenced by project timing, technical qualification, import exposure, engineering support and the installed base of compatible platforms. in United Arab Emirates. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
South Africa Developing / complementary market South Africa participates in Inertial Measurement Unit (IMU) demand through its mix of end-system manufacturing, infrastructure, defense, telecom, cloud, automotive, industrial, or semiconductor investment. Local purchasing decisions are influenced by project timing, technical qualification, import exposure, engineering support and the installed base of compatible platforms. in South Africa. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

Market instances

  • Middle East & Africa buyers increasingly prioritize qualified supply, local technical support, and lifecycle continuity as system complexity rises. This changes supplier selection from a simple unit-price comparison into a total-risk assessment covering integration time, field reliability, and replacement availability. in Middle East & Africa. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
  • Investment in defense, space and surveying is creating fresh specification events rather than only replacement demand. New platforms or facilities allow suppliers to compete for sockets before an incumbent is locked in, so design-in support and early engineering engagement become commercially decisive. in Middle East & Africa. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
  • Technology roadmaps are raising performance requirements while shortening the interval between platform generations. Vendors that can support migration without forcing a complete redesign gain an advantage, particularly where customers operate long-lived assets or qualification-intensive systems. in Middle East & Africa. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
In the full report: country-level revenue, sales, supplier positioning, pricing and forecast detail for Middle East & Africa, including the markets listed above across the historical and forecast period.

Competitive Landscape

Competition in the Inertial Measurement Unit (IMU) market is shaped by technical specialization, installed-base relationships, qualification history, intellectual property, process know-how, global service coverage, and the ability to support customer roadmaps over multi-year product or manufacturing cycles.

Leading suppliers protect their positions through accumulated application knowledge rather than scale alone. In Inertial Measurement Unit (IMU), a customer often qualifies not just a part number but a complete performance envelope, process recipe, software interface, calibration approach, or service procedure. That creates switching friction and rewards vendors with documented field history, especially in mission-critical or high-cost production environments.

The middle of the market is more contested. Specialist suppliers can win when they offer a better balance of performance, lead time, integration support, regional responsiveness, or price than the largest incumbents. However, expanding beyond a niche requires investment in quality systems, applications engineering, channel coverage, and long-term product availability, all of which raise the fixed cost of competing globally.

Customer concentration can also shape negotiating power. Large OEMs, fabs, telecom operators, aerospace programs, or government buyers can demand custom specifications and long validation cycles, which increase development burden but create durable revenue once a supplier is designed in. The strongest competitors therefore manage portfolio breadth and customer-specific engineering without allowing customization to erode manufacturing efficiency.

The competitive shift through 2034 is toward tighter integration between hardware, software, process data, and lifecycle services. Suppliers that convert product performance into lower system-level cost, higher yield, better uptime, or reduced qualification risk are positioned to capture a larger share of value than vendors selling interchangeable hardware.

Competitive tier Typical position Basis of competition
Global technology leaders Large installed bases, broad portfolios and deep qualification history. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. Technology roadmap, service coverage, IP depth and strategic customer relationships. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Specialist / focused suppliers Narrower portfolios with strong capability in defined applications or performance tiers. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. Agility, targeted performance, engineering support and customer-specific integration. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Regional / value competitors Price-sensitive or locally served segments with growing technical capability. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle. Cost, lead time, localization, distributor access and improving qualification credentials. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

Companies profiled on the source page

Honeywell International
Northrop Grumman Corp
SAFRAN
Thales
Kearfott
KVH Industries
UTC
Systron Donner Inertial
IAI Tamam
L3 Technologies
VectorNav
SBG systems
Navgnss
Starneto

Production Capacity Analysis

Production capacity for Inertial Measurement Unit (IMU) is constrained less by nominal factory floor space than by qualified process capability, specialized equipment, skilled engineering, yields, calibration or test capacity, and access to critical upstream materials or subsystems.

Where production sits reflects the technology base of the market. Capacity tends to cluster near semiconductor fabrication, precision manufacturing, aerospace electronics, photonics, advanced packaging, or specialized equipment ecosystems because suppliers need rapid access to engineering talent, component vendors, calibration facilities, and demanding customers. This clustering improves innovation speed but can increase geographic concentration risk.

Effective capacity is usually below theoretical capacity because high-performance products require lengthy setup, calibration, process stabilization, acceptance testing, and customer-specific qualification. As Inertial Measurement Unit (IMU) performance requirements rise, manufacturers must invest not just in more tools but in metrology, automation, software control, clean manufacturing, and reliability screening. These investments raise barriers to entry and extend the payback period for new capacity.

Supply risk is greatest when a small number of upstream technologies, process tools, materials, or precision subassemblies determine throughput. Suppliers respond through dual sourcing, longer-term agreements, internalization of critical steps, geographic diversification, and design changes that reduce dependence on constrained inputs. Customers increasingly examine these resilience measures during qualification because a technically superior product has limited value if it cannot be delivered through a full platform lifecycle.

Market Dynamics

The market is pulled upward by increasing system complexity, higher performance requirements, capacity expansion and new applications, while growth is moderated by qualification time, high capital or development cost, cyclicality, export constraints, and substitution by alternative architectures where performance is sufficient.

Market Drivers

What is pushing the market forward?
Driver Directional impact* Commercial mechanism
Higher performance requirements in end systems High As customers add AI, autonomy, high-speed connectivity, advanced manufacturing, or mission-critical functionality, system tolerances tighten. Inertial Measurement Unit (IMU) must deliver better accuracy, bandwidth, power efficiency, process control, yield, or reliability. This creates upgrade demand even when unit volumes grow more slowly, because higher-specification content captures more value per system.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Capacity expansion and platform refresh cycles High New fabs, data centers, telecom networks, aerospace platforms, industrial automation projects, or electronics programs create design-in events where Inertial Measurement Unit (IMU) can be specified from the start. Greenfield investment generally produces broader component and equipment demand than replacement alone, while platform refreshes create opportunities to displace incumbents before long lifecycle contracts are renewed.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Integration and miniaturization Medium-High Customers increasingly need more functionality in smaller footprints and at lower power or operating cost. Suppliers respond with improved materials, packaging, MEMS, photonic integration, advanced process control, software-assisted calibration, or automation. Better integration reduces the customer’s system burden and expands adoption into applications that could not previously justify size, power, or complexity.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Resilience and sovereign supply chains Medium-High Government incentives, export controls, and customer concern about geographic concentration are encouraging local or allied production. This does not eliminate global interdependence, but it creates parallel demand for regional capacity, second sources and localized service. Suppliers with multiple manufacturing and engineering locations can turn resilience into a commercial differentiator.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

Higher performance requirements in end systems

As customers add AI, autonomy, high-speed connectivity, advanced manufacturing, or mission-critical functionality, system tolerances tighten. Inertial Measurement Unit (IMU) must deliver better accuracy, bandwidth, power efficiency, process control, yield, or reliability. This creates upgrade demand even when unit volumes grow more slowly, because higher-specification content captures more value per system.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

Capacity expansion and platform refresh cycles

New fabs, data centers, telecom networks, aerospace platforms, industrial automation projects, or electronics programs create design-in events where Inertial Measurement Unit (IMU) can be specified from the start. Greenfield investment generally produces broader component and equipment demand than replacement alone, while platform refreshes create opportunities to displace incumbents before long lifecycle contracts are renewed.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

Integration and miniaturization

Customers increasingly need more functionality in smaller footprints and at lower power or operating cost. Suppliers respond with improved materials, packaging, MEMS, photonic integration, advanced process control, software-assisted calibration, or automation. Better integration reduces the customer’s system burden and expands adoption into applications that could not previously justify size, power, or complexity.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

Resilience and sovereign supply chains

Government incentives, export controls, and customer concern about geographic concentration are encouraging local or allied production. This does not eliminate global interdependence, but it creates parallel demand for regional capacity, second sources and localized service. Suppliers with multiple manufacturing and engineering locations can turn resilience into a commercial differentiator.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

Market Restraints

What can slow market expansion?
Restraint Directional impact* Commercial mechanism
Long qualification and certification cycles High High-performance and safety-critical systems require extensive reliability evidence, process qualification, customer testing, and sometimes regulatory certification. These steps extend time to revenue and can lock customers into existing suppliers, which protects incumbents but slows adoption of technically superior new products.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
High capital and development intensity High Advanced fabrication, precision manufacturing, specialized metrology, clean environments, calibration, software and field support require sustained investment before scale is achieved. Smaller suppliers can innovate quickly but may struggle to finance the global quality and service infrastructure needed to win large programs.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Cyclical customer investment Medium Semiconductor, electronics, telecom, automotive and industrial customers periodically pause capacity additions or inventory builds. The effect can be sharp because suppliers operate against long lead times. A demand correction therefore creates temporary underutilization even when the long-term technology trend remains favorable.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.
Technology substitution and architecture change Medium Software-defined functions, alternative sensing or communication technologies, system-on-chip integration, or new manufacturing flows can reduce standalone content in some applications. Suppliers need to move up the value chain and demonstrate system-level economics rather than depend on historical socket counts.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

Long qualification and certification cycles

High-performance and safety-critical systems require extensive reliability evidence, process qualification, customer testing, and sometimes regulatory certification. These steps extend time to revenue and can lock customers into existing suppliers, which protects incumbents but slows adoption of technically superior new products.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

High capital and development intensity

Advanced fabrication, precision manufacturing, specialized metrology, clean environments, calibration, software and field support require sustained investment before scale is achieved. Smaller suppliers can innovate quickly but may struggle to finance the global quality and service infrastructure needed to win large programs.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

Cyclical customer investment

Semiconductor, electronics, telecom, automotive and industrial customers periodically pause capacity additions or inventory builds. The effect can be sharp because suppliers operate against long lead times. A demand correction therefore creates temporary underutilization even when the long-term technology trend remains favorable.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

Technology substitution and architecture change

Software-defined functions, alternative sensing or communication technologies, system-on-chip integration, or new manufacturing flows can reduce standalone content in some applications. Suppliers need to move up the value chain and demonstrate system-level economics rather than depend on historical socket counts.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

Market Opportunities

The strongest opportunities lie where new performance requirements create a fresh design-in event, where regional capacity is being built, or where suppliers can expand from hardware into software, service, qualification support, and lifecycle economics.

AI and high-performance computing infrastructure

AI infrastructure raises bandwidth, memory, power, manufacturing and reliability requirements across the electronics stack. Suppliers that connect their product roadmap to these system bottlenecks can capture higher-value demand rather than relying only on broad electronics growth.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

Autonomy, robotics and unmanned systems

Autonomous platforms require reliable sensing, navigation, communications and control under increasingly difficult operating conditions. This expands opportunities for suppliers able to reduce size, weight, power and calibration burden while maintaining robust performance.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

Regional manufacturing localization

Government programs are creating new fabs, packaging facilities, telecom networks and strategic electronics plants in markets that historically imported most high-value technology. Localization creates fresh design-in events and can open long-lived service revenue for early supplier entrants.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

Service, software and lifecycle monetization

As hardware becomes more complex, customers value monitoring, calibration, process analytics, predictive maintenance, firmware, integration tools and field support. These services increase recurring revenue and can differentiate otherwise similar hardware offerings.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

Supply Chain Analysis

The Inertial Measurement Unit (IMU) value chain moves from specialized upstream materials, devices or process technologies through component/equipment manufacturing, system integration and distribution, and finally into end-user platforms. Value capture increases where qualification, IP, process know-how or service intensity is difficult to replicate.

Upstream materials & enabling technology
Core manufacturing / fabrication
Integration, distribution & qualification
End-system deployment & lifecycle service

Upstream suppliers determine the cost and technical ceiling of the finished product through specialized materials, wafers, sensors, photonic elements, optics, precision mechanics, chemicals, electronic components, or process tools. Qualification of these inputs can be slow, so changing a supplier is rarely equivalent to purchasing a generic substitute. Long-term availability and tight incoming quality control are therefore important elements of supply resilience.

The core manufacturing stage concentrates the proprietary value in Inertial Measurement Unit (IMU). Yield management, calibration, process recipes, clean manufacturing, packaging, test and software tuning convert upstream inputs into a reproducible commercial product. Improvements at this stage can reduce cost and raise performance simultaneously, which is why leaders continue to invest in automation, metrology, design-for-manufacturing and statistical process control.

Integration and distribution translate technical capability into a product a customer can actually deploy. Distributors, integrators, application engineers and field-service teams handle configuration, documentation, interoperability, spares and local support. In high-value markets, this layer can decide which qualified product wins because customers place a premium on quick fault isolation and reliable replacement supply.

End users capture the economic benefit through higher throughput, lower power, better navigation, improved yield, faster data transmission, improved reliability or reduced downtime. Their purchasing decisions feed back into supplier roadmaps, often through multi-year qualification programs. This closed loop makes the value chain relationship-based and favors vendors that understand the customer’s total system economics rather than only the unit price.

Recent Developments

Recent developments show that the market is being reshaped by technology migration, capacity investment, localization and tighter integration with end-system requirements. The entries below use official or company sources and connect each event to its commercial implication.

2026 – Honeywell Aerospace investor materials continue to position inertial navigation and IMUs on major defense platforms, including missiles and aircraft.

The installed program base supports long product lifecycles, qualification barriers and recurring replacement demand for high-performance units.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

2025 – Honeywell product documentation for the HG4930 and HG1700 shows continued migration toward compact rugged MEMS alongside established RLG architectures.

Suppliers are competing on SWaP-C, environmental robustness and bias stability rather than on sensor count alone, widening the addressable autonomous and industrial market.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

2025 – New product resources and updated brochures emphasize higher dynamic range, lower power and broader exportability for tactical MEMS IMUs.

This lowers integration friction for unmanned systems, mapping, robotics and stabilization applications while preserving a premium tier for navigation-grade products.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

REPORT SCOPE & SEGMENTATION

Attribute Details
Study Period 2020–2034
Base Year 2025
Estimated Year 2026
Forecast Period 2026–2034
Historical Period 2020–2025
Market Size 2025 USD 3,836 Million
Market Size 2034 USD 7,319 Million
Growth Rate CAGR of 7.4% from 2026–2034
Unit Value (USD Million) and Volume (K Units)
Segmentation By Type, By Application, By End User, By Technology Grade, By System Integration, and By Region
By Type High-performance IMU · MEMS Based IMU (except for consumer and automotive grade)
By Application Defense · Commercial Aerospace · Other Industrial Application
By End User Government & Defense Agencies · Aerospace OEMs · Industrial Corporations
By Technology Grade Tactical Grade · Navigation Grade · Strategic Grade
By System Integration Standalone IMU · IMU Integrated with GPS · IMU as part of an INS
By Region Each region analysed by applicable segment axes and country
North AmericaUnited States, Canada, Mexico
EuropeGermany, France, U.K., Italy, Russia, Nordic Countries, Benelux
AsiaChina, Japan, South Korea, Southeast Asia, India
South AmericaBrazil, Argentina
Middle East & AfricaTurkey, Israel, Saudi Arabia, UAE
Key Companies Profiled Honeywell International, Northrop Grumman Corp, SAFRAN, Thales, Kearfott, KVH Industries, UTC, Systron Donner Inertial, IAI Tamam, L3 Technologies, VectorNav, SBG systems, Navgnss, Starneto
Customization Scope Report customization is available on request for country, regional, segment, company, and other scope requirements.

Frequently Asked Questions

What is the Inertial Measurement Unit (IMU) market size in 2025?

The market is valued at USD 3,836 million in 2025. Using the growth rate implied by the source page’s published market-size anchors, the series reaches USD 4,121 million in 2026 and USD 7,319 million by 2034, corresponding to a 7.4% CAGR for the 2026–2034 period. The standardized series keeps the source scope unchanged while extending the endpoint.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

What is the forecast for the Inertial Measurement Unit (IMU) market through 2034?

The market is projected to reach USD 7,319 million by 2034 from USD 3,836 million in 2025. The implied compound growth rate is 7.4% for 2026–2034. Growth is supported by performance upgrades, capacity investment, integration requirements and new applications, while qualification, capital intensity and cyclical customer spending moderate the pace.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

Which market is largest in 2025?

North America (>70% on source page) holds the leading 2025 position in this overview. The leadership reflects the concentration of relevant end users, manufacturing capacity, infrastructure investment, technology ecosystems or strategic procurement. Regional strength is not uniform across applications, so suppliers still require market-specific channel, qualification and service strategies.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

How is the Inertial Measurement Unit (IMU) market segmented by type?

The source page segments the market into High-performance IMU, MEMS Based IMU (except for consumer and automotive grade). These categories serve different performance and cost requirements, which means revenue share can diverge from unit volume. Higher-performance configurations generally support stronger value capture where customer switching requires redesign, process re-optimization, calibration or new qualification evidence.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

Which applications are included in the market?

The application segmentation includes Defense, Commercial Aerospace, Other Industrial Application. Demand mechanisms differ by application because customers face different reliability, latency, throughput, certification, operating-environment and lifecycle requirements. Those differences shape supplier selection, pricing, qualification time and the level of engineering support required before a product can be adopted.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

What are the main growth drivers?

Major drivers include rising system complexity, higher performance requirements, capacity and infrastructure expansion, technology miniaturization, localization of strategic manufacturing, and increasing value placed on resilience. These forces create new design-in events and encourage customers to upgrade to higher-value configurations when system economics justify improved capability or lower operating risk.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

What are the main restraints?

Key restraints include long qualification cycles, high development and manufacturing investment, customer capital-spending cyclicality, export or regulatory restrictions in some applications, and substitution risk from alternative architectures. These factors can delay adoption even when technical demand is strong, especially where incumbent suppliers already hold long-lived qualified positions.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

Who are the key companies profiled?

The source page profiles Honeywell International, Northrop Grumman Corp, SAFRAN, Thales, Kearfott, KVH Industries, UTC, Systron Donner Inertial, IAI Tamam, L3 Technologies, VectorNav, SBG systems and others. Competitive positioning depends on product depth, qualification history, manufacturing consistency, intellectual property, engineering support, service coverage and roadmap continuity rather than on scale alone.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

Why is production capacity important in this market?

Usable capacity depends on more than installed factory tools. Yields, calibration, metrology, skilled engineering, clean manufacturing, qualification, upstream component availability and final test can all constrain shipment capability. As performance requirements rise, suppliers need parallel investment in process control and service infrastructure, which raises barriers to rapid entry.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

What is the strategic outlook through 2034?

The strategic outlook remains constructive because performance requirements are rising across the market’s major applications and because regionalization is creating new capacity and supply-chain investment. The strongest suppliers will be those that connect technical improvements to measurable customer economics, support qualification efficiently and maintain dependable multi-year supply and service.. Purchasing is shaped by performance qualification, integration risk, lifecycle support, and the cost of failure in the end system. Buyers evaluate supplier capability against application-specific requirements rather than nominal specifications alone, making consistency and dependable availability important throughout the operating lifecycle.

Research Sources & Evidence Base
View research sources used for this overview
  1. Honeywell Aerospace. Inertial Measurement Units, Portfolio evidence: MEMS, FOG and RLG IMUs; over one million tactical-grade IMUs delivered.
  2. Honeywell Aerospace. HG1700 Inertial Measurement Unit, Tactical-grade deployment evidence across weaponry, UAVs, stabilized platforms and commercial applications.
  3. Honeywell Aerospace. HGuide HG4930 MEMS Inertial Measurement Unit, MEMS performance, ruggedization and SWaP-C evidence for robotics, UAV and industrial applications.
  4. Honeywell. Honeywell expands navigation offerings for GPS-denied areas, Sensor-fusion and GPS-denied navigation application evidence.
Inertial Measurement Unit (IMU) Market, Trends, Business Strategies 2026-2034

Get Sample Report PDF for Exclusive Insights

Report Sample Includes

  • Table of Contents
  • List of Tables & Figures
  • Charts, Research Methodology, and more...
Download Sample Report PDF
SKU: 3cd97d66c390
Category:

Download Sample Report

Table of Content

1 Introduction to Research & Analysis Reports
1.1 Inertial Measurement Unit (IMU) Market Definition
1.2 Market Segments
1.2.1 Segment by Type
1.2.2 Segment by Application
1.3 Global Inertial Measurement Unit (IMU) Market Overview
1.4 Features & Benefits of This Report
1.5 Methodology & Sources of Information
1.5.1 Research Methodology
1.5.2 Research Process
1.5.3 Base Year
1.5.4 Report Assumptions & Caveats
2 Global Inertial Measurement Unit (IMU) Overall Market Size
2.1 Global Inertial Measurement Unit (IMU) Market Size: 2024 VS 2032
2.2 Global Inertial Measurement Unit (IMU) Market Size, Prospects & Forecasts: 2020-2032
2.3 Global Inertial Measurement Unit (IMU) Sales: 2020-2032
3 Company Landscape
3.1 Top Inertial Measurement Unit (IMU) Players in Global Market
3.2 Top Global Inertial Measurement Unit (IMU) Companies Ranked by Revenue
3.3 Global Inertial Measurement Unit (IMU) Revenue by Companies
3.4 Global Inertial Measurement Unit (IMU) Sales by Companies
3.5 Global Inertial Measurement Unit (IMU) Price by Manufacturer (2020-2025)
3.6 Top 3 and Top 5 Inertial Measurement Unit (IMU) Companies in Global Market, by Revenue in 2024
3.7 Global Manufacturers Inertial Measurement Unit (IMU) Product Type
3.8 Tier 1, Tier 2, and Tier 3 Inertial Measurement Unit (IMU) Players in Global Market
3.8.1 List of Global Tier 1 Inertial Measurement Unit (IMU) Companies
3.8.2 List of Global Tier 2 and Tier 3 Inertial Measurement Unit (IMU) Companies
4 Sights by Product
4.1 Overview
4.1.1 Segment by Type – Global Inertial Measurement Unit (IMU) Market Size Markets, 2024 & 2032
4.1.2 High-performance IMU
4.1.3 MEMS Based IMU (except for consumer and automotive grade)
4.2 Segment by Type – Global Inertial Measurement Unit (IMU) Revenue & Forecasts
4.2.1 Segment by Type – Global Inertial Measurement Unit (IMU) Revenue, 2020-2025
4.2.2 Segment by Type – Global Inertial Measurement Unit (IMU) Revenue, 2026-2032
4.2.3 Segment by Type – Global Inertial Measurement Unit (IMU) Revenue Market Share, 2020-2032
4.3 Segment by Type – Global Inertial Measurement Unit (IMU) Sales & Forecasts
4.3.1 Segment by Type – Global Inertial Measurement Unit (IMU) Sales, 2020-2025
4.3.2 Segment by Type – Global Inertial Measurement Unit (IMU) Sales, 2026-2032
4.3.3 Segment by Type – Global Inertial Measurement Unit (IMU) Sales Market Share, 2020-2032
4.4 Segment by Type – Global Inertial Measurement Unit (IMU) Price (Manufacturers Selling Prices), 2020-2032
5 Sights by Application
5.1 Overview
5.1.1 Segment by Application – Global Inertial Measurement Unit (IMU) Market Size, 2024 & 2032
5.1.2 Defense
5.1.3 Commercial Aerospace
5.1.4 Other Industrial Application
5.2 Segment by Application – Global Inertial Measurement Unit (IMU) Revenue & Forecasts
5.2.1 Segment by Application – Global Inertial Measurement Unit (IMU) Revenue, 2020-2025
5.2.2 Segment by Application – Global Inertial Measurement Unit (IMU) Revenue, 2026-2032
5.2.3 Segment by Application – Global Inertial Measurement Unit (IMU) Revenue Market Share, 2020-2032
5.3 Segment by Application – Global Inertial Measurement Unit (IMU) Sales & Forecasts
5.3.1 Segment by Application – Global Inertial Measurement Unit (IMU) Sales, 2020-2025
5.3.2 Segment by Application – Global Inertial Measurement Unit (IMU) Sales, 2026-2032
5.3.3 Segment by Application – Global Inertial Measurement Unit (IMU) Sales Market Share, 2020-2032
5.4 Segment by Application – Global Inertial Measurement Unit (IMU) Price (Manufacturers Selling Prices), 2020-2032
6 Sights by Region
6.1 By Region – Global Inertial Measurement Unit (IMU) Market Size, 2024 & 2032
6.2 By Region – Global Inertial Measurement Unit (IMU) Revenue & Forecasts
6.2.1 By Region – Global Inertial Measurement Unit (IMU) Revenue, 2020-2025
6.2.2 By Region – Global Inertial Measurement Unit (IMU) Revenue, 2026-2032
6.2.3 By Region – Global Inertial Measurement Unit (IMU) Revenue Market Share, 2020-2032
6.3 By Region – Global Inertial Measurement Unit (IMU) Sales & Forecasts
6.3.1 By Region – Global Inertial Measurement Unit (IMU) Sales, 2020-2025
6.3.2 By Region – Global Inertial Measurement Unit (IMU) Sales, 2026-2032
6.3.3 By Region – Global Inertial Measurement Unit (IMU) Sales Market Share, 2020-2032
6.4 North America
6.4.1 By Country – North America Inertial Measurement Unit (IMU) Revenue, 2020-2032
6.4.2 By Country – North America Inertial Measurement Unit (IMU) Sales, 2020-2032
6.4.3 United States Inertial Measurement Unit (IMU) Market Size, 2020-2032
6.4.4 Canada Inertial Measurement Unit (IMU) Market Size, 2020-2032
6.4.5 Mexico Inertial Measurement Unit (IMU) Market Size, 2020-2032
6.5 Europe
6.5.1 By Country – Europe Inertial Measurement Unit (IMU) Revenue, 2020-2032
6.5.2 By Country – Europe Inertial Measurement Unit (IMU) Sales, 2020-2032
6.5.3 Germany Inertial Measurement Unit (IMU) Market Size, 2020-2032
6.5.4 France Inertial Measurement Unit (IMU) Market Size, 2020-2032
6.5.5 U.K. Inertial Measurement Unit (IMU) Market Size, 2020-2032
6.5.6 Italy Inertial Measurement Unit (IMU) Market Size, 2020-2032
6.5.7 Russia Inertial Measurement Unit (IMU) Market Size, 2020-2032
6.5.8 Nordic Countries Inertial Measurement Unit (IMU) Market Size, 2020-2032
6.5.9 Benelux Inertial Measurement Unit (IMU) Market Size, 2020-2032
6.6 Asia
6.6.1 By Region – Asia Inertial Measurement Unit (IMU) Revenue, 2020-2032
6.6.2 By Region – Asia Inertial Measurement Unit (IMU) Sales, 2020-2032
6.6.3 China Inertial Measurement Unit (IMU) Market Size, 2020-2032
6.6.4 Japan Inertial Measurement Unit (IMU) Market Size, 2020-2032
6.6.5 South Korea Inertial Measurement Unit (IMU) Market Size, 2020-2032
6.6.6 Southeast Asia Inertial Measurement Unit (IMU) Market Size, 2020-2032
6.6.7 India Inertial Measurement Unit (IMU) Market Size, 2020-2032
6.7 South America
6.7.1 By Country – South America Inertial Measurement Unit (IMU) Revenue, 2020-2032
6.7.2 By Country – South America Inertial Measurement Unit (IMU) Sales, 2020-2032
6.7.3 Brazil Inertial Measurement Unit (IMU) Market Size, 2020-2032
6.7.4 Argentina Inertial Measurement Unit (IMU) Market Size, 2020-2032
6.8 Middle East & Africa
6.8.1 By Country – Middle East & Africa Inertial Measurement Unit (IMU) Revenue, 2020-2032
6.8.2 By Country – Middle East & Africa Inertial Measurement Unit (IMU) Sales, 2020-2032
6.8.3 Turkey Inertial Measurement Unit (IMU) Market Size, 2020-2032
6.8.4 Israel Inertial Measurement Unit (IMU) Market Size, 2020-2032
6.8.5 Saudi Arabia Inertial Measurement Unit (IMU) Market Size, 2020-2032
6.8.6 UAE Inertial Measurement Unit (IMU) Market Size, 2020-2032
7 Manufacturers & Brands Profiles
7.1 Honeywell International
7.1.1 Honeywell International Company Summary
7.1.2 Honeywell International Business Overview
7.1.3 Honeywell International Inertial Measurement Unit (IMU) Major Product Offerings
7.1.4 Honeywell International Inertial Measurement Unit (IMU) Sales and Revenue in Global (2020-2025)
7.1.5 Honeywell International Key News & Latest Developments
7.2 Northrop Grumman Corp
7.2.1 Northrop Grumman Corp Company Summary
7.2.2 Northrop Grumman Corp Business Overview
7.2.3 Northrop Grumman Corp Inertial Measurement Unit (IMU) Major Product Offerings
7.2.4 Northrop Grumman Corp Inertial Measurement Unit (IMU) Sales and Revenue in Global (2020-2025)
7.2.5 Northrop Grumman Corp Key News & Latest Developments
7.3 SAFRAN
7.3.1 SAFRAN Company Summary
7.3.2 SAFRAN Business Overview
7.3.3 SAFRAN Inertial Measurement Unit (IMU) Major Product Offerings
7.3.4 SAFRAN Inertial Measurement Unit (IMU) Sales and Revenue in Global (2020-2025)
7.3.5 SAFRAN Key News & Latest Developments
7.4 Thales
7.4.1 Thales Company Summary
7.4.2 Thales Business Overview
7.4.3 Thales Inertial Measurement Unit (IMU) Major Product Offerings
7.4.4 Thales Inertial Measurement Unit (IMU) Sales and Revenue in Global (2020-2025)
7.4.5 Thales Key News & Latest Developments
7.5 Kearfott
7.5.1 Kearfott Company Summary
7.5.2 Kearfott Business Overview
7.5.3 Kearfott Inertial Measurement Unit (IMU) Major Product Offerings
7.5.4 Kearfott Inertial Measurement Unit (IMU) Sales and Revenue in Global (2020-2025)
7.5.5 Kearfott Key News & Latest Developments
7.6 KVH Industries
7.6.1 KVH Industries Company Summary
7.6.2 KVH Industries Business Overview
7.6.3 KVH Industries Inertial Measurement Unit (IMU) Major Product Offerings
7.6.4 KVH Industries Inertial Measurement Unit (IMU) Sales and Revenue in Global (2020-2025)
7.6.5 KVH Industries Key News & Latest Developments
7.7 UTC
7.7.1 UTC Company Summary
7.7.2 UTC Business Overview
7.7.3 UTC Inertial Measurement Unit (IMU) Major Product Offerings
7.7.4 UTC Inertial Measurement Unit (IMU) Sales and Revenue in Global (2020-2025)
7.7.5 UTC Key News & Latest Developments
7.8 Systron Donner Inertial
7.8.1 Systron Donner Inertial Company Summary
7.8.2 Systron Donner Inertial Business Overview
7.8.3 Systron Donner Inertial Inertial Measurement Unit (IMU) Major Product Offerings
7.8.4 Systron Donner Inertial Inertial Measurement Unit (IMU) Sales and Revenue in Global (2020-2025)
7.8.5 Systron Donner Inertial Key News & Latest Developments
7.9 IAI Tamam
7.9.1 IAI Tamam Company Summary
7.9.2 IAI Tamam Business Overview
7.9.3 IAI Tamam Inertial Measurement Unit (IMU) Major Product Offerings
7.9.4 IAI Tamam Inertial Measurement Unit (IMU) Sales and Revenue in Global (2020-2025)
7.9.5 IAI Tamam Key News & Latest Developments
7.10 L3 Technologies
7.10.1 L3 Technologies Company Summary
7.10.2 L3 Technologies Business Overview
7.10.3 L3 Technologies Inertial Measurement Unit (IMU) Major Product Offerings
7.10.4 L3 Technologies Inertial Measurement Unit (IMU) Sales and Revenue in Global (2020-2025)
7.10.5 L3 Technologies Key News & Latest Developments
7.11 VectorNav
7.11.1 VectorNav Company Summary
7.11.2 VectorNav Business Overview
7.11.3 VectorNav Inertial Measurement Unit (IMU) Major Product Offerings
7.11.4 VectorNav Inertial Measurement Unit (IMU) Sales and Revenue in Global (2020-2025)
7.11.5 VectorNav Key News & Latest Developments
7.12 SBG systems
7.12.1 SBG systems Company Summary
7.12.2 SBG systems Business Overview
7.12.3 SBG systems Inertial Measurement Unit (IMU) Major Product Offerings
7.12.4 SBG systems Inertial Measurement Unit (IMU) Sales and Revenue in Global (2020-2025)
7.12.5 SBG systems Key News & Latest Developments
7.13 Navgnss
7.13.1 Navgnss Company Summary
7.13.2 Navgnss Business Overview
7.13.3 Navgnss Inertial Measurement Unit (IMU) Major Product Offerings
7.13.4 Navgnss Inertial Measurement Unit (IMU) Sales and Revenue in Global (2020-2025)
7.13.5 Navgnss Key News & Latest Developments
7.14 Starneto
7.14.1 Starneto Company Summary
7.14.2 Starneto Business Overview
7.14.3 Starneto Inertial Measurement Unit (IMU) Major Product Offerings
7.14.4 Starneto Inertial Measurement Unit (IMU) Sales and Revenue in Global (2020-2025)
7.14.5 Starneto Key News & Latest Developments
8 Global Inertial Measurement Unit (IMU) Production Capacity, Analysis
8.1 Global Inertial Measurement Unit (IMU) Production Capacity, 2020-2032
8.2 Inertial Measurement Unit (IMU) Production Capacity of Key Manufacturers in Global Market
8.3 Global Inertial Measurement Unit (IMU) Production by Region
9 Key Market Trends, Opportunity, Drivers and Restraints
9.1 Market Opportunities & Trends
9.2 Market Drivers
9.3 Market Restraints
10 Inertial Measurement Unit (IMU) Supply Chain Analysis
10.1 Inertial Measurement Unit (IMU) Industry Value Chain
10.2 Inertial Measurement Unit (IMU) Upstream Market
10.3 Inertial Measurement Unit (IMU) Downstream and Clients
10.4 Marketing Channels Analysis
10.4.1 Marketing Channels
10.4.2 Inertial Measurement Unit (IMU) Distributors and Sales Agents in Global
11 Conclusion
12 Appendix
12.1 Note
12.2 Examples of Clients
12.3 DisclaimerList of Tables
Table 1. Key Players of Inertial Measurement Unit (IMU) in Global Market
Table 2. Top Inertial Measurement Unit (IMU) Players in Global Market, Ranking by Revenue (2024)
Table 3. Global Inertial Measurement Unit (IMU) Revenue by Companies, (US$, Mn), 2020-2025
Table 4. Global Inertial Measurement Unit (IMU) Revenue Share by Companies, 2020-2025
Table 5. Global Inertial Measurement Unit (IMU) Sales by Companies, (K Units), 2020-2025
Table 6. Global Inertial Measurement Unit (IMU) Sales Share by Companies, 2020-2025
Table 7. Key Manufacturers Inertial Measurement Unit (IMU) Price (2020-2025) & (USD/Unit)
Table 8. Global Manufacturers Inertial Measurement Unit (IMU) Product Type
Table 9. List of Global Tier 1 Inertial Measurement Unit (IMU) Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 10. List of Global Tier 2 and Tier 3 Inertial Measurement Unit (IMU) Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 11. Segment by Type – Global Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2024 & 2032
Table 12. Segment by Type – Global Inertial Measurement Unit (IMU) Revenue (US$, Mn), 2020-2025
Table 13. Segment by Type – Global Inertial Measurement Unit (IMU) Revenue (US$, Mn), 2026-2032
Table 14. Segment by Type – Global Inertial Measurement Unit (IMU) Sales (K Units), 2020-2025
Table 15. Segment by Type – Global Inertial Measurement Unit (IMU) Sales (K Units), 2026-2032
Table 16. Segment by Application – Global Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2024 & 2032
Table 17. Segment by Application – Global Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2020-2025
Table 18. Segment by Application – Global Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2026-2032
Table 19. Segment by Application – Global Inertial Measurement Unit (IMU) Sales, (K Units), 2020-2025
Table 20. Segment by Application – Global Inertial Measurement Unit (IMU) Sales, (K Units), 2026-2032
Table 21. By Region – Global Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2025-2032
Table 22. By Region – Global Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2020-2025
Table 23. By Region – Global Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2026-2032
Table 24. By Region – Global Inertial Measurement Unit (IMU) Sales, (K Units), 2020-2025
Table 25. By Region – Global Inertial Measurement Unit (IMU) Sales, (K Units), 2026-2032
Table 26. By Country – North America Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2020-2025
Table 27. By Country – North America Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2026-2032
Table 28. By Country – North America Inertial Measurement Unit (IMU) Sales, (K Units), 2020-2025
Table 29. By Country – North America Inertial Measurement Unit (IMU) Sales, (K Units), 2026-2032
Table 30. By Country – Europe Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2020-2025
Table 31. By Country – Europe Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2026-2032
Table 32. By Country – Europe Inertial Measurement Unit (IMU) Sales, (K Units), 2020-2025
Table 33. By Country – Europe Inertial Measurement Unit (IMU) Sales, (K Units), 2026-2032
Table 34. By Region – Asia Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2020-2025
Table 35. By Region – Asia Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2026-2032
Table 36. By Region – Asia Inertial Measurement Unit (IMU) Sales, (K Units), 2020-2025
Table 37. By Region – Asia Inertial Measurement Unit (IMU) Sales, (K Units), 2026-2032
Table 38. By Country – South America Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2020-2025
Table 39. By Country – South America Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2026-2032
Table 40. By Country – South America Inertial Measurement Unit (IMU) Sales, (K Units), 2020-2025
Table 41. By Country – South America Inertial Measurement Unit (IMU) Sales, (K Units), 2026-2032
Table 42. By Country – Middle East & Africa Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2020-2025
Table 43. By Country – Middle East & Africa Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2026-2032
Table 44. By Country – Middle East & Africa Inertial Measurement Unit (IMU) Sales, (K Units), 2020-2025
Table 45. By Country – Middle East & Africa Inertial Measurement Unit (IMU) Sales, (K Units), 2026-2032
Table 46. Honeywell International Company Summary
Table 47. Honeywell International Inertial Measurement Unit (IMU) Product Offerings
Table 48. Honeywell International Inertial Measurement Unit (IMU) Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 49. Honeywell International Key News & Latest Developments
Table 50. Northrop Grumman Corp Company Summary
Table 51. Northrop Grumman Corp Inertial Measurement Unit (IMU) Product Offerings
Table 52. Northrop Grumman Corp Inertial Measurement Unit (IMU) Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 53. Northrop Grumman Corp Key News & Latest Developments
Table 54. SAFRAN Company Summary
Table 55. SAFRAN Inertial Measurement Unit (IMU) Product Offerings
Table 56. SAFRAN Inertial Measurement Unit (IMU) Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 57. SAFRAN Key News & Latest Developments
Table 58. Thales Company Summary
Table 59. Thales Inertial Measurement Unit (IMU) Product Offerings
Table 60. Thales Inertial Measurement Unit (IMU) Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 61. Thales Key News & Latest Developments
Table 62. Kearfott Company Summary
Table 63. Kearfott Inertial Measurement Unit (IMU) Product Offerings
Table 64. Kearfott Inertial Measurement Unit (IMU) Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 65. Kearfott Key News & Latest Developments
Table 66. KVH Industries Company Summary
Table 67. KVH Industries Inertial Measurement Unit (IMU) Product Offerings
Table 68. KVH Industries Inertial Measurement Unit (IMU) Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 69. KVH Industries Key News & Latest Developments
Table 70. UTC Company Summary
Table 71. UTC Inertial Measurement Unit (IMU) Product Offerings
Table 72. UTC Inertial Measurement Unit (IMU) Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 73. UTC Key News & Latest Developments
Table 74. Systron Donner Inertial Company Summary
Table 75. Systron Donner Inertial Inertial Measurement Unit (IMU) Product Offerings
Table 76. Systron Donner Inertial Inertial Measurement Unit (IMU) Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 77. Systron Donner Inertial Key News & Latest Developments
Table 78. IAI Tamam Company Summary
Table 79. IAI Tamam Inertial Measurement Unit (IMU) Product Offerings
Table 80. IAI Tamam Inertial Measurement Unit (IMU) Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 81. IAI Tamam Key News & Latest Developments
Table 82. L3 Technologies Company Summary
Table 83. L3 Technologies Inertial Measurement Unit (IMU) Product Offerings
Table 84. L3 Technologies Inertial Measurement Unit (IMU) Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 85. L3 Technologies Key News & Latest Developments
Table 86. VectorNav Company Summary
Table 87. VectorNav Inertial Measurement Unit (IMU) Product Offerings
Table 88. VectorNav Inertial Measurement Unit (IMU) Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 89. VectorNav Key News & Latest Developments
Table 90. SBG systems Company Summary
Table 91. SBG systems Inertial Measurement Unit (IMU) Product Offerings
Table 92. SBG systems Inertial Measurement Unit (IMU) Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 93. SBG systems Key News & Latest Developments
Table 94. Navgnss Company Summary
Table 95. Navgnss Inertial Measurement Unit (IMU) Product Offerings
Table 96. Navgnss Inertial Measurement Unit (IMU) Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 97. Navgnss Key News & Latest Developments
Table 98. Starneto Company Summary
Table 99. Starneto Inertial Measurement Unit (IMU) Product Offerings
Table 100. Starneto Inertial Measurement Unit (IMU) Sales (K Units), Revenue (US$, Mn) and Average Price (USD/Unit) & (2020-2025)
Table 101. Starneto Key News & Latest Developments
Table 102. Inertial Measurement Unit (IMU) Capacity of Key Manufacturers in Global Market, 2023-2025 (K Units)
Table 103. Global Inertial Measurement Unit (IMU) Capacity Market Share of Key Manufacturers, 2023-2025
Table 104. Global Inertial Measurement Unit (IMU) Production by Region, 2020-2025 (K Units)
Table 105. Global Inertial Measurement Unit (IMU) Production by Region, 2026-2032 (K Units)
Table 106. Inertial Measurement Unit (IMU) Market Opportunities & Trends in Global Market
Table 107. Inertial Measurement Unit (IMU) Market Drivers in Global Market
Table 108. Inertial Measurement Unit (IMU) Market Restraints in Global Market
Table 109. Inertial Measurement Unit (IMU) Raw Materials
Table 110. Inertial Measurement Unit (IMU) Raw Materials Suppliers in Global Market
Table 111. Typical Inertial Measurement Unit (IMU) Downstream
Table 112. Inertial Measurement Unit (IMU) Downstream Clients in Global Market
Table 113. Inertial Measurement Unit (IMU) Distributors and Sales Agents in Global Market

List of Figures
Figure 1. Inertial Measurement Unit (IMU) Product Picture
Figure 2. Inertial Measurement Unit (IMU) Segment by Type in 2024
Figure 3. Inertial Measurement Unit (IMU) Segment by Application in 2024
Figure 4. Global Inertial Measurement Unit (IMU) Market Overview: 2024
Figure 5. Key Caveats
Figure 6. Global Inertial Measurement Unit (IMU) Market Size: 2024 VS 2032 (US$, Mn)
Figure 7. Global Inertial Measurement Unit (IMU) Revenue: 2020-2032 (US$, Mn)
Figure 8. Inertial Measurement Unit (IMU) Sales in Global Market: 2020-2032 (K Units)
Figure 9. The Top 3 and 5 Players Market Share by Inertial Measurement Unit (IMU) Revenue in 2024
Figure 10. Segment by Type – Global Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2024 & 2032
Figure 11. Segment by Type – Global Inertial Measurement Unit (IMU) Revenue Market Share, 2020-2032
Figure 12. Segment by Type – Global Inertial Measurement Unit (IMU) Sales Market Share, 2020-2032
Figure 13. Segment by Type – Global Inertial Measurement Unit (IMU) Price (USD/Unit), 2020-2032
Figure 14. Segment by Application – Global Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2024 & 2032
Figure 15. Segment by Application – Global Inertial Measurement Unit (IMU) Revenue Market Share, 2020-2032
Figure 16. Segment by Application – Global Inertial Measurement Unit (IMU) Sales Market Share, 2020-2032
Figure 17. Segment by Application -Global Inertial Measurement Unit (IMU) Price (USD/Unit), 2020-2032
Figure 18. By Region – Global Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2025 & 2032
Figure 19. By Region – Global Inertial Measurement Unit (IMU) Revenue Market Share, 2020 VS 2024 VS 2032
Figure 20. By Region – Global Inertial Measurement Unit (IMU) Revenue Market Share, 2020-2032
Figure 21. By Region – Global Inertial Measurement Unit (IMU) Sales Market Share, 2020-2032
Figure 22. By Country – North America Inertial Measurement Unit (IMU) Revenue Market Share, 2020-2032
Figure 23. By Country – North America Inertial Measurement Unit (IMU) Sales Market Share, 2020-2032
Figure 24. United States Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2020-2032
Figure 25. Canada Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2020-2032
Figure 26. Mexico Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2020-2032
Figure 27. By Country – Europe Inertial Measurement Unit (IMU) Revenue Market Share, 2020-2032
Figure 28. By Country – Europe Inertial Measurement Unit (IMU) Sales Market Share, 2020-2032
Figure 29. Germany Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2020-2032
Figure 30. France Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2020-2032
Figure 31. U.K. Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2020-2032
Figure 32. Italy Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2020-2032
Figure 33. Russia Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2020-2032
Figure 34. Nordic Countries Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2020-2032
Figure 35. Benelux Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2020-2032
Figure 36. By Region – Asia Inertial Measurement Unit (IMU) Revenue Market Share, 2020-2032
Figure 37. By Region – Asia Inertial Measurement Unit (IMU) Sales Market Share, 2020-2032
Figure 38. China Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2020-2032
Figure 39. Japan Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2020-2032
Figure 40. South Korea Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2020-2032
Figure 41. Southeast Asia Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2020-2032
Figure 42. India Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2020-2032
Figure 43. By Country – South America Inertial Measurement Unit (IMU) Revenue Market Share, 2020-2032
Figure 44. By Country – South America Inertial Measurement Unit (IMU) Sales, Market Share, 2020-2032
Figure 45. Brazil Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2020-2032
Figure 46. Argentina Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2020-2032
Figure 47. By Country – Middle East & Africa Inertial Measurement Unit (IMU) Revenue, Market Share, 2020-2032
Figure 48. By Country – Middle East & Africa Inertial Measurement Unit (IMU) Sales, Market Share, 2020-2032
Figure 49. Turkey Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2020-2032
Figure 50. Israel Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2020-2032
Figure 51. Saudi Arabia Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2020-2032
Figure 52. UAE Inertial Measurement Unit (IMU) Revenue, (US$, Mn), 2020-2032
Figure 53. Global Inertial Measurement Unit (IMU) Production Capacity (K Units), 2020-2032
Figure 54. The Percentage of Production Inertial Measurement Unit (IMU) by Region, 2024 VS 2032
Figure 55. Inertial Measurement Unit (IMU) Industry Value Chain
Figure 56. Marketing Channels