SEMICONDUCTOR INSIGHT
MARKET RESEARCH REPORT

Global Organic LED Market

2026 to 2034
MARKET INTELLIGENCE
ACROSS KEY REGIONS
2026 EDITION
DISPLAY AND VISUALIZATION Semiconductor Market Research

Global Organic LED Market

Size, Trends, Business Strategies 2026–2034

◷
UPDATED 29 October 2026
▤
REPORT LENGTH Detailed Report
▣
REPORT CODE f5d73c3c4c37
▯
FORMATS PDF

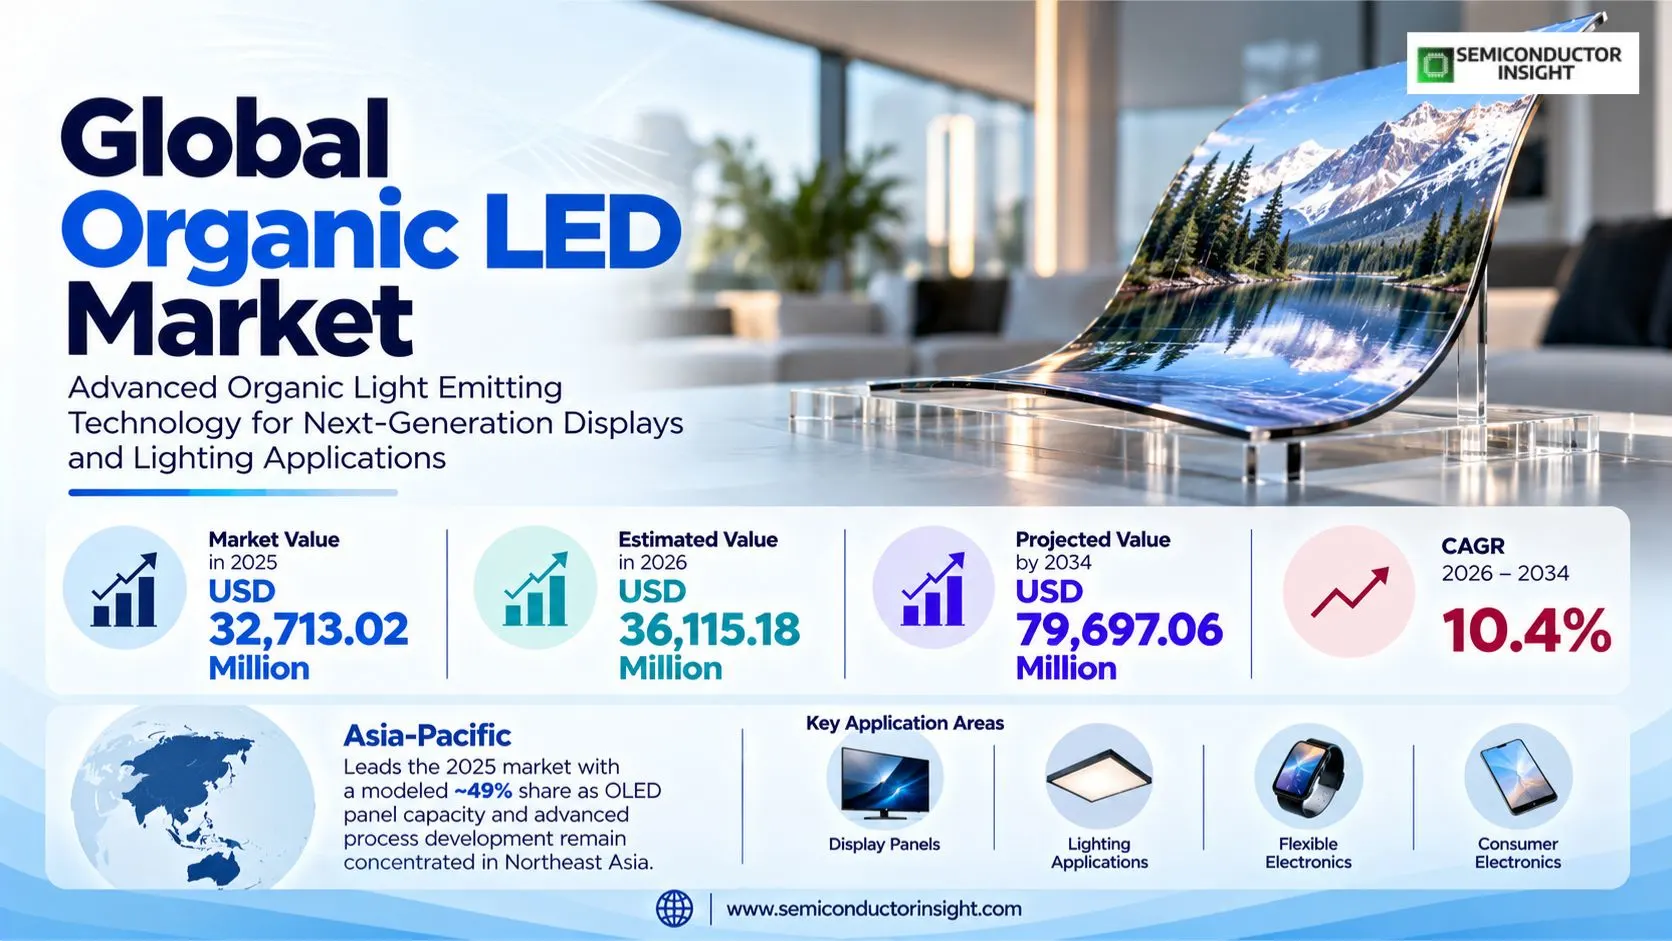
Organic LED market reached USD 32,713.02 million in 2025 and is estimated at USD 36,115.18 million in 2026. It is projected to attain USD 79,697.06 million by 2034, a 10.4% CAGR for the 2026–2034 period. Asia-Pacific leads the 2025 market with a modeled ~49% share as OLED panel capacity and advanced process development remain concentrated in Northeast Asia.

Get the sample PDF with study scope, segmentation and methodology details.

Key Statistics

2025 Market Size
USD 32,713.02 million
2034 Projected Size
USD 79,697.06 million
CAGR (2026–2034)
10.4%
Largest Market in 2025
Asia-Pacific (~49%)

Key Takeaways

  • Revenue trajectory: Organic LED panel and integrated module sales move from USD 32,713.02 million in the 2025 base year toward USD 79,697.06 million in 2034, representing a 10.4% CAGR across 2026–2034; the outlook includes active- and passive-matrix devices without counting finished consumer electronics.
  • AMOLED technology: An estimated ~86% of 2025 type revenue is associated with active-matrix panels, reflecting the pixel-control requirements of smartphones, notebook screens, televisions and dashboard systems; PMOLED retains a narrower niche in simple status interfaces.
  • Smartphone end market: Handsets represent the largest application at a modeled ~46% share in 2025, while automotive displays account for ~9% and have an estimated ~13.0% annual growth trajectory as instrument clusters and passenger screens diversify.
  • Geographic concentration: Asia-Pacific holds a modeled ~49% of the base-year market because panel fabrication, deposition equipment ecosystems and module assembly cluster around South Korea and China; North America represents ~31% of the value model, with demand rather than fabrication leading its role.
  • Technology economics: Larger-substrate investment, tandem emissive stacks and oxide backplanes expand product options, but production yields, capital intensity and the durability of blue emitters remain constraints on margin expansion and adoption in price-sensitive applications.

Organic LED Market Overview

Organic LED market reached USD 32,713.02 million in 2025 and is estimated at USD 36,115.18 million in 2026. It is projected to attain USD 79,697.06 million by 2034, a 10.4% CAGR for the 2026–2034 period. Asia-Pacific leads the 2025 market with a modeled ~49% share as OLED panel capacity and advanced process development remain concentrated in Northeast Asia.

Base year: 2025 · Estimate year: 2026 · Forecast period: 2026–2034 · Historical anchor: 2023 · Revenue in USD million

Organic light-emitting diode displays produce visible light directly in organic emissive layers rather than using the illumination system found in conventional liquid-crystal screens. The architecture supports high contrast, thin mechanical profiles and flexible substrates, although commercial products differ considerably in drive electronics, encapsulation and optical stack design. The revenue market addressed here consists of OLED panels and integrated display modules sold to equipment manufacturers, not the retail value of the televisions, phones or vehicles in which those components are installed.

The market spans active-matrix OLED and passive-matrix OLED products. Active-matrix arrays use a transistor backplane to maintain individual pixel states and are suited to high-resolution, high-refresh screens, whereas passive-matrix products scan rows and columns and remain practical for simpler, smaller indicators. Smartphones dominate installed volume in high-end handheld products, but the commercial opportunity has broadened to computer monitors, notebook computers, infotainment displays and instruments where the industrial design benefits of OLED can justify a price premium.

Supply economics depend on substrate generation, deposition equipment, backplane performance and yield at each manufacturing step. High-resolution panels require uniform thin-film transistors and stable organic layers across a large active area, while folding and curved designs also require mechanically robust encapsulation. As factories move toward larger motherglass formats for IT screens, the cost per finished panel depends not just on nominal glass area but also on how efficiently rectangular display sizes can be cut from that area without creating unproductive scrap.

Demand follows device replacement cycles but does not move uniformly across end markets. Smartphone brands can introduce OLED at lower price points through simplified stacks and more competitive panel sourcing, while premium monitor customers reward rapid pixel response and deep black levels. Automotive design programs operate on longer qualification timelines and require different lifetime and temperature margins. These differences make product mix, qualification progress and panel utilization more important to near-term revenue than any single aggregate shipment figure.

The forecast assumes that improvements in material efficiency, backplane architecture and production scale progressively offset the price pressure created by panel competition. An estimated ~86% AMOLED share signals how thoroughly the technology has moved beyond a small-screen niche, but PMOLED remains relevant for compact devices where a full active-matrix backplane would be unnecessary. The projected expansion therefore combines growing OLED penetration of established device categories with selected applications where thinness, curvature and pixel-level emission create distinctive design value.

Segment Analysis: By Type

Two device classes define the technology segmentation: AMOLED and PMOLED. AMOLED accounts for an estimated ~86% of 2025 panel revenue, and its modeled ~11.0% CAGR reflects expansion into notebook, monitor and vehicle applications. PMOLED contributes the remaining ~14% and grows more slowly at ~6.0% because its addressable products are mainly low-resolution, low-duty-cycle display modules.

Type Display architecture and operating role Commercial position and growth
AMOLED Active-matrix arrays use thin-film transistors and storage elements to drive each pixel through the refresh cycle. This permits dense subpixel layouts, high refresh rates and image stability in screens that display photographs, video or continuously changing graphical interfaces. The approach supports rigid and flexible formats and is the preferred architecture for phones, high-end televisions, notebook computers and increasingly vehicle interiors. Modeled 2025 share ~86%. The segment benefits from broader product adoption and an estimated ~11.0% annual growth rate, but the economic challenge is demanding process control. Yield losses from particulate defects, backplane variation and emissive-stack nonuniformity become costly as display area increases. Suppliers that combine reliable manufacturing with strong device-maker qualification can capture larger contracts despite continuing average selling price pressure.
PMOLED Passive-matrix OLED panels activate rows and columns sequentially rather than assigning a transistor-controlled current source to every pixel. This lowers circuit complexity for small monochrome or limited-information screens, and the resulting modules suit appliance indicators, industrial controls and compact instrumentation. However, increasing resolution or panel size raises drive-current and duty-cycle burdens, so passive-matrix structures are not the preferred choice for mainstream smartphone or television panels. Modeled 2025 share ~14%. Demand is steadier in specialist applications where the user interface needs a few lines of information rather than full-motion video. The modeled growth rate is ~6.0%, reflecting continued use in embedded equipment and replacement programs. Futaba markets OLED display products that illustrate this long-tail demand, although pricing is sensitive to alternatives such as small LCDs and e-paper modules.

AMOLED panels: from premium mobile to mid-size IT screens

AMOLED adoption is extending beyond high-value handsets because panel makers have improved backplane efficiency and scaled flexible and rigid product families. High refresh rates and compact bezels matter in gaming notebooks, while the deep-black capability helps professional monitors where dark-scene detail is visible. Larger manufacturing substrates can lower unit cost only when yield and panel-cut efficiency improve together, making production engineering central to the economics of this category.

LG Display markets Tandem WOLED panels with peak brightness claims up to 4,500 nits and 0.3% reflectance under specified conditions, demonstrating how optical performance has become a competitive differentiator for premium television screens. These are product specifications rather than market-wide averages, and the relevant revenue remains the panel or integrated module sold into a finished device. Material selection and thermal design influence how such headline performance can be sustained over useful operating life.

Modeled segment revenue trajectories (USD million, 2026–2034)

These annual values are calculated from the market share model and segment growth assumptions, rather than quoted from individual supplier filings. The type and application columns represent separate views of the same market, so the two groups must not be added together. Rounding is applied after calculation, and modeled annual paths describe analytical scenarios rather than independently observed yearly transactions.

Year AMOLED PMOLED Smartphones TV & monitors Notebooks & tablets Automotive Others
2025 28,133.2 4,579.8 15,048.0 7,524.0 4,907.0 2,944.2 2,289.9
2026 31,227.8 4,854.2 16,447.5 8,314.0 5,495.8 3,326.9 2,511.8
2027 34,662.9 5,145.0 17,977.1 9,187.0 6,155.3 3,759.4 2,755.2
2028 38,475.8 5,453.2 19,648.9 10,151.6 6,893.9 4,248.1 3,022.1
2029 42,708.2 5,779.9 21,476.3 11,217.5 7,721.2 4,800.4 3,315.0
2030 47,406.1 6,126.1 23,473.6 12,395.4 8,647.7 5,424.4 3,636.2
2031 52,620.7 6,493.1 25,656.6 13,696.9 9,685.5 6,129.6 3,988.5
2032 58,409.0 6,882.1 28,042.7 15,135.1 10,847.7 6,926.5 4,374.9
2033 64,834.0 7,294.3 30,650.7 16,724.3 12,149.4 7,826.9 4,798.8
2034 71,965.8 7,731.3 33,501.2 18,480.3 13,607.4 8,844.4 5,263.8

PMOLED modules: compact interfaces with stable product lifecycles

PMOLED is often selected where the display must remain legible in a compact enclosure and the number of pixels is small enough for multiplex driving. Industrial controllers and handheld instruments may value module continuity over annual increases in resolution, creating a different sales pattern from consumer handsets. Vendors serving this market maintain many mechanical and electrical variants, which can preserve customer relationships even when annual production quantities are modest.

The PMOLED model assigns ~14% of 2025 revenue to passive-matrix products rather than treating them as a separate market added to AMOLED totals. This avoids double counting when suppliers offer both technologies through one sales channel. A smaller addressable design envelope and limited suitability for video-rich interfaces restrain growth, although niche replacement and low-power indicators continue to create profitable custom-module opportunities for qualified vendors.

Segment Analysis: By Application

Application demand is divided into Television and Monitors, Smartphones, Notebooks and Tablets, Automotive, and Others. The modeled 2025 distribution assigns smartphones ~46%, television and monitors ~23%, notebooks and tablets ~15%, automotive ~9%, and other devices ~7%. These categories separate the display panel value from finished-device retail sales and do not count a display twice when an electronics brand sources it through a contract assembler.

Application Demand characteristics
Smartphones The handset segment is the largest because OLED enables thin bezels, always-on indicators, deep blacks and flexible panel constructions for premium and upper-midrange phones. Panel orders depend on launch calendars, refresh-cycle demand and the availability of alternative sources with matching electrical interfaces. Its estimated ~46% base-year share reflects broad AMOLED penetration, but the modeled ~9.3% growth rate is tempered by mature replacement cycles and intense procurement negotiations.
Television and Monitors Large-area displays are sold into premium living-room television products and increasingly into high-refresh computer monitors. Panel size, brightness, color stability and pixel response are critical selection factors, while glass utilization and yield govern supplier cost. This category holds a modeled ~23% of 2025 market revenue and grows at ~10.5% as monitor offerings expand beyond a narrow enthusiast niche and television products compete on image quality.
Notebooks and Tablets Portable computing screens demand low thickness, power efficiency across varied content and stable color performance. OLED has room to gain share where buyers value display quality, but notebook procurement emphasizes long service life, panel availability and cost control. The category represents a modeled ~15% of the base year and advances at ~12.0%, supported by a shift toward larger motherglass processing for mid-size IT panel formats.
Automotive Vehicle dashboards and center displays require long operating life, wide temperature capability and predictable brightness across many years of use. Curved and integrated cockpit surfaces make OLED attractive to designers, while qualification cycles delay revenue relative to consumer product launches. The modeled ~9% starting share is smaller than phones but the ~13.0% annual expansion reflects growing display area per vehicle and more screens per cabin in selected models.
Others This residual category includes industrial instrumentation, healthcare devices, wearables and specialist equipment whose screens do not fit the four major end markets. Purchasing is fragmented and technical requirements differ sharply between a small status module and a medical display. The model assigns ~7% of base-year value with ~9.7% growth, reflecting steady replacement orders and application-specific development rather than one large standardized product cycle.

Application revenue cannot be inferred simply by multiplying the number of finished products by their retail selling prices. A premium phone contains one or more display components but most of its value arises from processors, cameras, memory, software and distribution. The model therefore assigns display revenue at the panel and module transaction level and treats brand-device sales as downstream indicators rather than as the OLED market itself.

The fastest modeled application growth is automotive at ~13.0%, but qualification makes the segment less responsive to short-term consumer sentiment. A successful display platform may remain in a vehicle family for several model years, whereas a notebook panel may be redesigned after a shorter product cycle. This distinction shapes how suppliers balance high-volume consumer orders against lower-volume, longer-duration industrial and mobility programs.
Regional Analysis

Regional revenue follows both the location of display manufacturing and the purchasing footprint of global electronics brands. Asia-Pacific is the largest 2025 region at a modeled ~49% share, with North America ~31%, Europe ~15%, South America ~3%, and the Middle East and Africa ~2%. The model differentiates factory investment from end-user demand and uses distinct adoption, sourcing and qualification assumptions in each territory.

How does regional OLED demand differ between production hubs and device markets?

The industry has a highly concentrated manufacturing geography but a dispersed consumption footprint. Korean and Chinese panel makers supply customers on several continents, so a region with little front-end OLED fabrication can still be a substantial market for screens integrated into devices sold there. The regional allocation captures that commercial distinction rather than implying that the largest share of global fabrication occurs wherever consumers purchase the most electronics.

Asia-Pacific has the highest modeled growth rate among the major regions at ~11.2% CAGR because new manufacturing lines, regional component ecosystems and domestic device makers reinforce one another. North America is modeled at ~9.5% as premium electronics and vehicle interfaces sustain demand, while Europe at ~9.7% relies on automotive engineering, industrial design and high-value consumer products. Smaller regional markets can expand from low bases without changing the manufacturing center of gravity.

Region Position Growth outlook Demand profile What decides supplier selection
Asia-Pacific Largest, ~49% ~11.2% CAGR Manufacturing and end-use demand Advanced backplane yield, large-substrate utilization and long-term OEM qualification
North America Second, ~31% ~9.5% CAGR Premium devices and design demand Color performance, platform certification and assured global sourcing
Europe Third, ~15% ~9.7% CAGR Automotive and industrial integration Long-lifecycle supply, durability testing and engineering support
South America Developing, ~3% ~8.5% CAGR Imported panels in assembled devices Affordable supply, logistics resilience and distribution partnerships
Middle East & Africa Emerging, ~2% ~11.5% CAGR Premium electronics and specialist installations After-sales support, import reliability and environmental robustness

Asia-Pacific LARGEST · ~49% SHARE

Why does Asia-Pacific dominate OLED manufacturing and panel sales?

Asia-Pacific accounts for an estimated ~49% of 2025 revenue, reflecting the close relationship between fabrication capacity, component suppliers and consumer-electronics assembly. South Korea anchors advanced OLED process knowledge while China is adding new production capability, and Japan contributes materials, manufacturing equipment and device-design expertise. The modeled ~11.2% CAGR reflects expansion into computing screens and continued regional investment rather than reliance on one handset launch.

Market positionLargest market (~49%)
Growth outlookHigh (~11.2% CAGR)
Demand profileFactory ecosystem and device assembly
Market access gateYield at new panel generations
Country Position in region What drives demand
South Korea Advanced OLED technology base South Korean producers supply high-performance OLED panels to global electronics brands and have extensive experience with flexible substrates, tandem structures and advanced thin-film transistor processes. The country is an important engineering center for yield optimization, material qualification and product transitions. Customer requirements for premium image quality support investment, while rising competition encourages Korean manufacturers to differentiate through efficiency, reliability and new form factors rather than competing solely on price.
China Major capacity expansion center Chinese manufacturers have been expanding AMOLED capabilities and seeking larger shares of IT and automotive display demand. Domestic device assembly and a broad component supplier network shorten some development cycles, but qualification with international brands remains demanding. The transition toward larger-glass manufacturing is commercially significant because mid-size screens require a different substrate economics profile from smartphone panels, and new facilities must demonstrate stable yields before their nameplate capacity translates into merchant shipments.
Japan Materials and equipment specialization Japanese firms play a major role in precision process equipment, organic materials, encapsulation inputs and demanding industrial display applications. Some domestic customers prioritize long product lifecycles and optical stability rather than the lowest initial panel cost. This position gives Japan influence over technical specifications even where large-scale panel assembly is elsewhere, and it creates opportunities for component suppliers whose equipment must be qualified on both Korean and Chinese OLED production lines.

Market instances

  • China targets larger-substrate AMOLED economics. BOE announced the start of mass production at its Chengdu Gen 8.6 AMOLED facility in June 2026, signaling a transition toward production methods suited to notebook and tablet displays. The significance lies in glass utilization and process learning rather than nominal capacity alone. As yields stabilize, larger substrates can support more competitive IT panel pricing, potentially accelerating OLED penetration in portable computing without requiring the same margins as flagship smartphones.
  • South Korean process leadership extends into new panel classes. Samsung Display and LG Display have broadened their offerings from mobile panels into monitors, IT devices and specialized displays, placing greater emphasis on high refresh rates and stack efficiency. The commercial effect is diversification of the product mix beyond handset procurement cycles. It also creates demand for new manufacturing controls because larger screens expose uniformity problems that can be less visible in small phone panels.
In the full report: country-level market revenue, AMOLED versus PMOLED demand, panel format economics and supplier positioning for China, South Korea, Japan, India and Southeast Asia.

North America SECOND LARGEST · ~31% SHARE

What supports OLED panel value in North America?

North America holds an estimated ~31% of the 2025 revenue model, supported by premium smartphones, televisions, professional computing products and automotive design programs. The region is not the center of merchant panel fabrication; instead, purchasing influence comes from brands that specify displays and from consumers willing to pay for differentiated image quality. The modeled ~9.5% CAGR is moderated by mature replacement cycles and the need to qualify global manufacturing partners.

Market positionSecond largest (~31%)
Growth outlookSteady (~9.5% CAGR)
Demand profileHigh-value product design
Market access gatePlatform approval and supply assurance
Country Position in region What drives demand
United States Premium device specification center American consumer-electronics companies and technology buyers influence the performance requirements of many globally sourced OLED panels. Product teams prioritize brightness, color accuracy, thinness, battery efficiency and consistency between successive model generations. Procurement decisions depend on qualification and capacity assurance because a delayed screen can disrupt an entire device launch. The region also hosts research, materials and licensing businesses whose corporate revenue must not be confused with panel shipments.
Canada Selective premium and industrial demand Canadian demand is concentrated in imported consumer electronics, professional displays and specialist equipment rather than in large-scale OLED panel fabrication. Distribution and service support are important because buyers may need replacement screens over long equipment lifecycles. Premium adoption benefits from the availability of advanced monitors and handheld products, while industrial buyers emphasize documented operating characteristics and stable supply arrangements more than the newest visual features.
Mexico Electronics assembly and cross-border integration Mexico participates through electronics assembly and regional distribution serving North American customers. OLED demand follows the device models built or sold in the country, and procurement can be sensitive to component import logistics and factory scheduling. Suppliers that offer reliable module packaging and documentation are better positioned to support assembly operations, while price competition limits how quickly premium panels replace lower-cost LCD alternatives in mass-market products.

Market instances

  • US device makers influence worldwide panel qualification. North American product designers often set requirements for brightness consistency, touch integration and mechanical packaging even when the panels are fabricated overseas. A successful qualification can generate global orders across multiple assembly locations, making the region commercially important beyond its domestic screen consumption. This purchasing structure rewards manufacturers with process traceability, rapid engineering support and enough manufacturing redundancy to handle a large product launch.
  • Professional monitor buyers broaden the addressable market. The growing availability of OLED gaming and creator monitors provides an additional route to premium display revenue outside televisions and phones. Monitor customers value fast response, contrast and color control, but are also attentive to image retention and warranty conditions. The market effect is a differentiated product tier in which panel makers can recover engineering costs through performance rather than relying entirely on high-volume handset pricing.
In the full report: United States, Canada and Mexico market estimates, premium product adoption, brand qualification requirements and imported OLED module sourcing.

Europe THIRD LARGEST · ~15% SHARE

Why are automotive and industrial uses important in Europe?

Europe represents a modeled ~15% of 2025 OLED revenue and grows at an estimated ~9.7% CAGR, with automotive displays and specialist industrial equipment shaping the demand profile. European buyers frequently specify long qualification periods, temperature endurance and spare-part continuity. Consumer televisions and notebooks also contribute, but the commercial distinction is the emphasis on engineering documentation and supply relationships that last beyond a single annual device refresh.

Market positionThird largest (~15%)
Growth outlookModerate (~9.7% CAGR)
Demand profileAutomotive and industrial design
Market access gateLong-life component validation
Country Position in region What drives demand
Germany Automotive engineering concentration German automotive manufacturers and tier-one suppliers evaluate OLED for instrument clusters, infotainment screens and integrated cockpit designs. Vehicle projects require predictable performance across wide operating conditions, and suppliers must support documentation, traceability and spare-part commitments. OLED can enable visually continuous dashboard surfaces, but it competes with mature LCD technologies on cost and lifetime. Consequently, design wins tend to be more valuable as multi-year programs than as immediate volume spikes.
France Specialist systems and premium devices French demand spans premium consumer electronics, automotive electronics and specialized industrial or professional displays. The selection process often combines optical performance with service requirements and integration support. For equipment intended to remain in operation for years, manufacturers may value stable panel specifications more than frequent feature changes. That makes qualified display-module suppliers relevant even when local front-end OLED fabrication is limited.
United Kingdom High-end computing and instrument use British customers purchase OLED-enabled premium monitors, portable computing products and specialist instruments through international supply chains. In industrial and research applications, users may specify color stability, dark-scene contrast and consistent display behavior under controlled lighting. Suppliers face the challenge of providing long-term availability for a technology market driven largely by fast-changing consumer products, creating demand for carefully managed product revisions.

Market instances

  • Cockpit redesigns create longer revenue tails. An OLED panel qualified for a vehicle platform may remain in production or service for several model years, which differs sharply from the short planning horizon of many consumer handsets. This makes European automotive integration an attractive but demanding market for suppliers capable of documenting thermal, optical and mechanical reliability. The impact on the revenue mix is gradual expansion of automotive panel value rather than a sudden wholesale replacement of LCD dashboards.
  • Industrial procurement favors controlled specifications. European equipment makers often require fixed mechanical dimensions, repeatable color performance and a documented change process when a display component is redesigned. OLED suppliers can win such contracts by offering stable module interfaces and lifecycle management, even without the largest panel factories. This demand profile creates specialized opportunities that are less sensitive to quarterly smartphone shipment fluctuations but more dependent on engineering support and certification discipline.
In the full report: European OLED revenue by country, industrial display applications, automotive qualification programs and manufacturer sourcing requirements.

South America DEVELOPING · ~3% SHARE

How does affordability shape OLED adoption in South America?

South America accounts for a modeled ~3% of the global base-year market and advances at an estimated ~8.5% CAGR. Imported smartphones and televisions are the principal routes through which OLED technology reaches customers, while local electronics assembly and distribution influence availability. Currency fluctuations, retail financing and replacement affordability are more immediate demand variables than new OLED fabrication investment, which remains concentrated in other regions.

Market positionDeveloping (~3%)
Growth outlookMeasured (~8.5% CAGR)
Demand profileImported consumer devices
Market access gatePrice and distribution reliability
Country Position in region What drives demand
Brazil Largest regional consumer base Brazil has a broad market for smartphones, televisions and computing equipment, with OLED adoption concentrated initially in products whose visual performance justifies a higher selling price. Local distribution and assembly arrangements can affect which panel-equipped models are offered and at what price. Import costs and currency conditions influence affordability, so the transition from LCD to OLED depends heavily on brand pricing strategies and the availability of midrange products.
Argentina Price-sensitive premium niche Argentina participates mainly through imported electronic devices, and purchasing patterns are sensitive to exchange rates and household budgets. OLED-equipped handsets and televisions compete with lower-cost alternatives that may satisfy mainstream use cases. Suppliers and distributors therefore prioritize manageable inventory exposure and service access, while the premium segment remains interested in high contrast, thin displays and visually distinctive product designs.
Chile Retail-driven technology adoption Chile has a consumer-electronics market in which international brands introduce premium screens through established retail and distribution channels. The availability of OLED products depends on global model portfolios rather than domestic panel manufacturing. Buyers may compare screen quality and energy use with competing LCD products, but adoption is constrained by price premiums. Market growth is consequently more closely linked to imported device mix than to local production expansion.

Market instances

  • Midrange handset offerings determine volume conversion. The decisive commercial step for OLED in South America is the move from flagship phones into models affordable to a broader customer base. Panel cost reductions and additional qualified suppliers can support that transition, but retail prices are affected by taxes, logistics and exchange-rate movements. The market implication is that a technical improvement at the factory may take several product cycles to become visible in regional OLED device sales.
  • Premium television retail provides a second channel. OLED televisions reach regional consumers through international brands that compete on picture quality, viewing angles and thin form factors. The panels are generally sourced from manufacturing hubs outside South America, making shipping costs and local inventory planning important. Demand can rise with premium household spending, but the addressable market remains smaller than the mass-market LCD category and is sensitive to financing conditions.
In the full report: Brazil, Argentina, Chile and other South American markets, distribution-led adoption, panel import dependencies and consumer affordability scenarios.

Middle East & Africa EMERGING · ~2% SHARE

Which OLED applications are expanding in the Middle East and Africa?

The Middle East and Africa represent an estimated ~2% of global 2025 panel revenue, with a modeled ~11.5% CAGR from a comparatively small base. Premium consumer devices, hospitality screens and selected industrial applications account for much of the visible demand. Market access depends on import channels, after-sales service and device brand support rather than regional front-end OLED fabrication, while environmental conditions raise the importance of operating-temperature and brightness specifications.

Market positionEmerging (~2%)
Growth outlookSelective (~11.5% CAGR)
Demand profilePremium device imports
Market access gateClimate and service assurance
Country Position in region What drives demand
United Arab Emirates Premium electronics distribution hub The United Arab Emirates supports a concentrated market for premium smartphones, televisions and high-end computing products, with international retailers and distributors supplying OLED-equipped models. Hospitality and commercial installations may value thin screens and high contrast for visual presentation. Import availability and service arrangements are important because panels are sourced from overseas production sites, and commercial buyers may need dependable replacement modules for equipment installed in public spaces.
Saudi Arabia Consumer and commercial expansion Saudi demand combines consumer electronics with display installations in commercial, entertainment and hospitality environments. OLED products are attractive where image quality and distinctive form factors matter, although conventional LED-backlit displays remain competitive for very large or cost-sensitive installations. Buyers evaluate operating conditions and warranty support carefully, particularly when equipment is exposed to high ambient temperatures or long daily operating hours.
South Africa Premium retail and specialist demand South African OLED adoption is concentrated in premium consumer products and selected professional applications where contrast and viewing characteristics justify additional cost. Distribution networks determine model availability and the quality of after-sales support. Power reliability and replacement-part access can influence equipment decisions, and businesses often weigh total ownership cost against the visual benefits of OLED when specifying displays for longer service periods.

Market instances

  • Hospitality design adds a niche premium channel. Hotels, showrooms and high-end commercial venues in Gulf markets may specify thin OLED screens where aesthetics and contrast contribute to the visitor experience. Such projects can command higher value per panel but involve modest volumes compared with consumer smartphones. Their commercial relevance lies in diversification of end-use demand and the need for integrators capable of supporting installation, environmental management and long-term service.
  • Import logistics remain the principal market-access filter. Most OLED products sold across the region arrive as finished electronics or integrated modules sourced from Asian supply chains. Local buyers consequently assess warranty coverage, authorized service and spare-part availability as well as initial screen performance. This creates a commercial advantage for suppliers with dependable regional distributors, but it also means that fluctuations in shipping and currency costs can delay the adoption of newer OLED display classes.
In the full report: country-level OLED adoption in Gulf economies and Africa, premium product demand, distribution constraints and specialist commercial installations.

Organic LED Competitive Landscape and Supplier Positioning

Competition is shaped by the manufacturing capabilities of Samsung Display, LG Display, BOE and Visionox, while materials and intellectual-property suppliers such as Universal Display Corporation influence device performance without selling the same finished panel product. Qualification at major device brands, access to deposition equipment and consistent high-volume yield determine which producers can capture revenue as OLED extends into larger screens and specialized modules.

Samsung Display has a broad position in mobile AMOLED and advanced OLED product development, while LG Display is prominent in large-area OLED television technology and other display categories. BOE and Visionox are expanding their technical offerings and manufacturing sophistication in China. These companies compete for the same end-device programs but often offer different combinations of substrate size, stack architecture, flexible capability and volume assurance, making a simple supplier count an inadequate measure of competitive intensity.

Customer qualification is a barrier because the display is both a functional electronic component and the most visible surface of many devices. A defect that affects luminance uniformity or image retention can damage a brand relationship even when the rest of the product works correctly. Panel makers therefore invest in process traceability, reliability testing and optical calibration, and large customers may maintain multiple qualified sources to reduce dependence on one factory or country.

The supply chain contains companies with different revenue boundaries. Universal Display licenses phosphorescent OLED technology and supplies emissive materials; its financial results should not be added to the merchant panel market as if they represented finished OLED screens. Futaba participates in small OLED modules, a product category with different scale economics from large AMOLED fabrication. AUO is relevant to adjacent display competition, including MicroLED, but such competing display revenue is excluded from the OLED panel total.

Competition also differs by application. Smartphone procurement rewards rapid design transitions, high yields and competitive pricing, while automotive contracts emphasize reliability documentation and continuity. Television and monitor products require large-area uniformity and optical performance, and embedded PMOLED modules are frequently sold through long-standing industrial channels. These contrasts create several competitive arenas rather than one uniform ranking based solely on corporate display sales.

Tier structure

Tier Companies Basis of competition
Large AMOLED manufacturers Samsung Display, LG Display, BOE, Visionox Companies investing in OLED backplanes, deposition technology, encapsulation and high-volume panel manufacturing for global device makers. Their scale provides engineering resources and multiple product families, but expensive factories require strong utilization. Winning business depends on delivering consistent display performance across very large production batches while maintaining the flexibility to adapt to customer design changes.
Specialized OLED module suppliers Futaba and other qualified small-display producers Manufacturers serving compact displays and application-specific modules with comparatively smaller production runs and longer design lifecycles. Competitive strengths include mechanical customization, electrical-interface support and reliable replacement supply. Their addressable market is narrower than mainstream AMOLED, yet specialist customers may accept higher unit values in exchange for predictable quality and stable component availability.
Upstream and adjacent technology Universal Display Corporation; AUO as adjacent competitor Materials and intellectual-property companies affect the performance and cost of OLED manufacturing but should not be classified as direct merchant panel suppliers. Universal Display contributes phosphorescent materials and licensing, while AUO showcases competing display technologies. Their relevance is technological influence and competitive substitution rather than direct equivalence with OLED display-module sales.

Key companies profiled

  • Samsung Display
  • LG Display
  • BOE Technology Group
  • Visionox Technology
  • Futaba Corporation
  • Universal Display Corporation (upstream)
  • AUO Corporation (adjacent display competitor)

Organic LED Production Capacity and Manufacturing Economics

OLED production requires tightly controlled thin-film transistor fabrication, organic deposition, encapsulation and module assembly. Commercial capacity is concentrated in Asian manufacturing clusters, but nameplate glass throughput is not the same as sellable panel output. Yield losses, panel cutting patterns, substrate dimensions and device qualification determine how much of a newly installed line becomes available to electronics manufacturers at an economically viable price.

Gen 8.6 AMOLED manufacturing is particularly important for notebook and tablet panels because larger glass can accommodate multiple mid-size displays with better cutting efficiency than processes optimized for phones. BOE announced production at a Chengdu Gen 8.6 line in June 2026, indicating a move toward this product mix. The commercial question is how quickly the process can achieve uniform emission and backplane behavior over larger areas while limiting expensive scrap during the ramp.

Backplane innovation remains central to capacity utilization. Visionox disclosed an atomic-layer-deposition all-oxide transistor backplane demonstration in May 2026, using a 6.39-inch test display to illustrate device development. Such demonstrations do not prove high-volume production economics, but they show how suppliers seek better electrical control and potentially improved manufacturing options. Process transfer, defect density and lifetime qualification determine whether a promising prototype can support repeatable shipments.

OLED fabrication also depends on precise organic material deposition and encapsulation systems. Moisture and oxygen can degrade sensitive layers, and the risks become more complex in flexible or foldable constructions where mechanical stresses interact with barrier performance. Production planners must balance new materials against the cost of process requalification, because a change that improves optical efficiency may introduce additional equipment or yield risk before it reduces the cost of saleable panels.

Capacity additions can pressure prices if several suppliers ramp similar product classes at once, yet insufficient yield can create shortages even when installed equipment appears abundant. This duality is especially visible in premium screens, where customers may reject panels that meet basic electrical tests but fail demanding visual-uniformity standards. Factory investment therefore translates into market share only after stable production, predictable delivery and the approval of major downstream buyers.

Organic LED Market Dynamics: Growth Drivers, Restraints and Opportunities

The market expansion is supported by broader AMOLED adoption in computing, continued smartphone demand, new automotive interfaces and improvements in light-emission efficiency. These gains are partially offset by capital-intensive manufacturing, yield risk, durability requirements and lower-priced competing displays. The impact model allocates positive and negative contributions across the forecast period and reconciles to the overall growth rate rather than treating each factor as an independent forecast.

MARKET DRIVERS

Drivers Impact Analysis*

Market Drivers Impact Rank CAGR Contribution (%) 2026–2028 2029–2031 2032–2034
OLED penetration of notebook and tablet displays High +4.80% High High Medium
Premium smartphone replacement and panel upgrades High +3.20% High Medium Medium
Advanced monitor and television panel adoption Medium-High +2.70% Medium High High
Automotive cockpit display integration Medium +1.90% Medium High High
Tandem stacks and emissive-efficiency advances Low-Medium +1.50% Medium Medium High
Others (wearables, specialist industrial interfaces and custom modules) Low +1.10% Low Medium Medium

Portable computing offers a new manufacturing scale opportunity

Notebook and tablet adoption creates demand for OLED panels larger than a typical handset screen but smaller than a television. This product mix is attractive to factories designed around larger glass, provided that the cutting pattern and yield support competitive prices. Device manufacturers also value lower thickness and premium color performance, but adoption depends on durability and battery behavior under real computing workloads.

Smartphone platforms sustain the largest installed demand base

Handset brands continue to use OLED for high-contrast displays, narrow borders and flexible product construction. The category is mature enough that annual sales depend more on product mix and replacement timing than on first-time technology adoption. Suppliers can still gain value by moving OLED into less expensive models, improving panel efficiency and reducing manufacturing cost while meeting increasingly strict visual quality standards.

Monitors and televisions broaden the premium product portfolio

Gaming and professional displays create demand for high refresh rates, rapid response and controlled dark-scene performance, allowing OLED to compete on image quality rather than price alone. The opportunity differs from handset supply because large-area uniformity and panel cutting efficiency become more important. Wider model availability can increase penetration, although warranty management and image-retention concerns remain important to buyers.

Automotive interiors add display area per vehicle

Vehicle manufacturers are redesigning cockpits around larger and sometimes curved displays, creating opportunities for thin OLED modules that can be integrated into complex surfaces. Qualification cycles are long, and the requirements for heat resistance and useful life are stricter than for many consumer devices. Once approved, however, a component may be supplied over multiple vehicle model years, providing a different revenue profile from annual handset launches.

Efficiency gains support brighter screens at manageable power

Improved emissive materials, optical extraction and tandem device structures can help panel makers deliver greater brightness without proportional increases in power or heat. This matters for outdoor visibility, battery-operated devices and large-area displays where thermal management affects lifetime. Technology advances must still pass production and reliability validation, so laboratory efficiency improvements reach commercial revenue only through qualified manufacturing processes.

MARKET RESTRAINTS

Restraints Impact Analysis*

Market Restraints Impact Rank CAGR Contribution (%) 2026–2028 2029–2031 2032–2034
High capital cost and yield sensitivity High -2.10% High High Medium
Organic material durability and image retention Medium-High -1.30% High Medium Medium
LCD and MicroLED competition in selected formats Medium -0.90% Medium Medium High
Others (pricing pressure and supply-chain qualification delays) Low -0.50% Medium Medium Low
*CAGR contribution shows the percentage points each factor adds to or removes from the forecast CAGR for 2026–2034; driver contributions less restraint contributions equal the market CAGR. For organic LED panels, the period columns distinguish the expected timing of factory utilization, device adoption and materials challenges.

Factory economics can delay the benefit of added capacity

A new OLED line requires substantial capital before it produces qualified panels at target yield. During the ramp, scrap, process adjustments and customer testing can consume the apparent benefit of larger glass or faster equipment. When several producers target the same screen sizes, the resulting pricing pressure may reduce revenue per unit even as shipment volumes increase, limiting the contribution of capacity expansion to market value.

Lifetime requirements differ sharply by application

Organic emission layers can be sensitive to cumulative operating stress, moisture and oxygen exposure, making lifetime engineering a central design requirement. A premium monitor used for static content and a vehicle display exposed to temperature variation present different risk profiles. Manufacturers must balance peak brightness, efficiency and expected use patterns, and additional qualification can slow adoption where long-term reliability is valued above thinness.

Competing display architectures retain cost and performance niches

LCD remains a strong competitor in price-sensitive products and very large screen formats, while MicroLED is being developed for applications that prioritize high brightness and inorganic emitters. OLED therefore does not replace every existing display technology. Panel suppliers must justify a price premium through contrast, response time, flexibility or industrial design, and the available benefit varies by device category and customer budget.

MARKET OPPORTUNITIES

Mid-size OLED screens can diversify panel factory utilization

A broader portfolio of notebook, tablet and monitor formats allows producers to serve multiple customer categories from related manufacturing platforms. Better glass utilization can make previously expensive OLED sizes more competitive, but suppliers must coordinate design rules and process recipes to preserve yield. Successful diversification reduces dependence on handset launch schedules and can create more stable factory loading over the forecast period.

Specialist modules reward engineering services

Industrial and medical equipment makers often need fixed dimensions, reliable interfaces and extended product support rather than the latest mass-market display specification. OLED suppliers that offer application engineering and controlled product changes can build durable customer relationships. The opportunity is relatively small in volume but may support differentiated pricing because switching display components can require extensive equipment redesign and validation.

Automotive display systems favor integrated form factors

Curved and segmented cockpit designs create demand for panels that fit complex interior surfaces while maintaining readable information and attractive aesthetics. OLED has a potential advantage in thinness and pixel-level emission, but its success depends on meeting automotive qualification standards. Suppliers that solve temperature and longevity challenges may gain access to longer production contracts than those common in consumer electronics.

Organic LED Supply Chain and Technology Inputs

The supply chain extends from organic emitters and precision deposition equipment through backplane fabrication, panel encapsulation and final module integration. Value is captured at different stages, so materials sales and licensing income must be separated from merchant OLED panel revenue. Supplier relationships matter because a display design can depend on a specific emitter chemistry or manufacturing process that cannot be replaced without substantial requalification.

Materials and intellectual propertyPhosphorescent emitters, host materials, encapsulation inputs and licensed device architectures influence efficiency and usable life. Universal Display operates in this upstream layer, where revenue arises from materials and technology rights rather than finished panel shipments.
Fabrication and depositionBackplane transistors, organic layer deposition, optical stacks and encapsulation require specialized equipment and stable process control. Yield and panel dimensions determine whether nominal factory capacity translates into commercially competitive output.
Panel and module integrationOLED panels are bonded with driver electronics, touch components and mechanical supports according to the customer product design. Flexible and automotive applications introduce additional requirements for assembly tolerances and reliability.
Device brands and distributionSmartphone, computer, television and vehicle manufacturers purchase qualified panels or modules and integrate them into finished equipment. Retail device revenue is downstream and is not included in the OLED component market value.

Emitter and materials sourcing. Organic emitters and host materials affect brightness, color and energy consumption, and changes to these inputs can alter both optical performance and production yield. Universal Display extended material supply and intellectual-property arrangements with LG Display in February 2026, illustrating how long-term technical partnerships support continuity. Such contracts indicate upstream ecosystem investment but cannot be added directly to panel revenue without double counting.

Manufacturing process control. Thin-film transistor backplanes and organic deposition must maintain uniform electrical and optical properties across the entire display. Inspection, cleaning and environmental controls therefore influence manufacturing cost alongside equipment speed. Process improvements can reduce scrap and support new screen sizes, but they often require extended engineering work before a line reaches stable customer-qualified output.

Optical extraction and efficiency. Universal Display introduced its OLEDX light-extraction platform in August 2026 as an approach to improving the amount of generated light that leaves the device. Better extraction could reduce power consumption or support higher brightness at similar electrical drive, but actual benefits depend on integration into commercial panel stacks. The technology is an upstream input rather than a finished OLED screen shipment.

Downstream qualification and after-sales support. Device manufacturers set requirements for mechanical interfaces, visual uniformity, brightness, reliability and ongoing supply. A panel may satisfy a laboratory specification yet still need substantial validation before it can enter a handset or vehicle program. Suppliers that provide process traceability, replacement compatibility and responsive engineering support are more likely to maintain contracts through multiple product generations.

Recent Developments in the Organic LED Market

  • 17 June 2026 Manufacturing
    BOE announced the start of mass production at its Gen 8.6 AMOLED facility in Chengdu, a manufacturing milestone aimed at the economics of medium-sized display panels. The significance is a potential expansion of qualified supply for notebook and tablet screens, although installed capacity must still be assessed against yield, product mix and customer approvals before being translated into merchant panel revenue. Source
  • 1 June 2026 Product
    Samsung Display presented a Computex 2026 OLED lineup covering gaming and computing applications, including QD-OLED monitor technology and thinner notebook panels. The product emphasis shows how suppliers are extending OLED differentiation beyond handsets. Higher refresh rates and improved packaging create value for premium customers, while the commercial outcome depends on panel pricing and the willingness of computer makers to adopt the technology at scale. Source
  • 7 May 2026 Technology
    Visionox described atomic-layer-deposition all-oxide thin-film transistor technology and a 6.39-inch demonstration panel. The disclosure highlights continuing work on the backplane architecture that controls OLED pixels, with potential implications for electrical stability and process design. It is evidence of technical development, not proof that the demonstrated configuration has reached commercial high-volume production or that it already contributes a measurable share of market revenue. Source
  • 5 May 2026 Showcase
    Samsung Display outlined new display concepts at Display Week 2026, including wider-color-gamut OLED and sensor-integrated display approaches. These developments broaden the functionality that panel makers may offer to device brands, but adoption requires integration and manufacturing qualification. Their market relevance lies in differentiation and future product design options rather than an immediate assumption of higher unit sales across every OLED category. Source
  • 19 August 2026 Materials
    Universal Display introduced the OLEDX technology platform, focused on light extraction and efficiency in OLED devices. This is an upstream technology announcement whose commercial implications depend on whether panel manufacturers integrate the architecture into saleable products. Greater extraction efficiency could improve brightness-power trade-offs, but the announcement does not itself constitute a finished-panel shipment or independently establish market-wide performance gains. Source
  • 26 February 2026 Agreement
    LG Display and Universal Display extended long-term agreements involving OLED materials and intellectual-property licensing. The arrangement reinforces the importance of supply continuity and collaborative emitter development for panel manufacturing. Because the agreement concerns upstream materials and rights, its financial implications should not be counted as additional merchant OLED panel revenue; it instead supports the manufacturing ecosystem from which finished screens are produced. Source
  • 30 March 2026 Adjacent competition
    AUO showcased MicroLED technology as part of its advanced display portfolio, illustrating the competitive landscape facing OLED in selected premium applications. MicroLED relies on a different emissive architecture and should not be included in OLED market sales. Its relevance is as a potential substitute where brightness, lifetime or unusual form factors are priorities, although manufacturing cost and scale remain important commercialization factors. Source

REPORT SCOPE & SEGMENTATION

Attribute Details
Study Period 2023–2034
Base Year 2025
Estimated Year 2026
Forecast Period 2026–2034
Historical Anchor Year 2023
Market Size 2025 USD 32,713.02 million
Market Size 2026 USD 36,115.18 million
Market Size 2034 USD 79,697.06 million
Growth Rate CAGR of 10.4% from 2026–2034
Unit Revenue (USD million)
Segmentation By Type, By Application and By Region
By Type PMOLED · AMOLED
By Application Television and Monitors · Smartphones · Notebooks and Tablets · Automotive · Others
By Region Each region assessed by type, application and country with modeled 2025 market shares and 2026–2034 growth paths.
North AmericaUnited States, Canada, Mexico
EuropeGermany, France, United Kingdom, Italy, Rest of Europe
Asia-PacificChina, Japan, South Korea, India, Southeast Asia
South AmericaBrazil, Argentina, Chile, Rest of South America
Middle East & AfricaUnited Arab Emirates, Saudi Arabia, South Africa, Rest of Middle East and Africa
Key Companies Profiled Samsung Display, LG Display, BOE Technology Group, Visionox Technology, Futaba Corporation, Universal Display Corporation (upstream materials and IP), AUO Corporation (adjacent display technology)
Customization Scope Customization may cover additional display-size classes, national demand assumptions, panel technology detail and company-level analysis subject to the agreed research scope.

Frequently Asked Questions

What is the estimated size of the organic LED market?

The global OLED panel and integrated module market was valued at USD 32,713.02 million in 2025 and is projected to reach USD 79,697.06 million in 2034, implying a 10.4% CAGR across 2026–2034. The scope measures display components supplied to manufacturers rather than the retail sales of phones, televisions or vehicles containing those screens. The forecast reflects both increasing OLED penetration and changes in the mix of panel sizes and technologies.

Which OLED technology has the largest market share?

AMOLED is the dominant type, accounting for a modeled ~86% of 2025 revenue, because active-matrix pixel control is suitable for high-resolution mobile, computing and television displays. PMOLED represents the remaining ~14%, serving compact instruments and status interfaces that do not need a full transistor-controlled pixel array. These shares are analytical allocations and should not be interpreted as independently reported supplier shipment statistics.

Why is Asia-Pacific the leading OLED region?

Asia-Pacific has an estimated ~49% share because South Korean and Chinese manufacturers host major fabrication operations and are linked to extensive electronics assembly networks. The region combines production capability with demand from local and international device brands. Japan also contributes specialist materials and equipment expertise, while the modeled ~11.2% annual growth rate reflects both manufacturing investment and a shift toward OLED computing screens.

What is driving OLED use in laptops and monitors?

OLED enables deep blacks, rapid pixel response and thin product designs that appeal to premium computer users. The adoption decision also depends on power consumption, image retention, warranty conditions and the price difference from LCD alternatives. New manufacturing processes aimed at medium-size screens could improve cost competitiveness, but commercial expansion requires sustained yields and customer qualification rather than factory investment alone.

How does automotive demand differ from smartphone demand?

Vehicle display programs require extensive reliability testing and may run for several model years, whereas smartphone displays are frequently redesigned with annual product launches. Automotive buyers value performance under temperature stress, mechanical durability and stable spare-part supply. The modeled automotive application share is ~9% in 2025, with ~13.0% annual growth, but the long approval cycle means design activity can precede revenue by years.

Are OLED materials companies included as panel manufacturers?

Materials and licensing companies are part of the OLED ecosystem but occupy a different revenue layer from merchant panel producers. Universal Display supplies emissive technology and intellectual property used by panel makers, while Samsung Display, LG Display, BOE and Visionox manufacture screens. Adding the full upstream corporate revenues to finished-panel sales would double count value already embedded in the display supply chain.

What are the biggest obstacles to OLED growth?

Production investment and yield management are major constraints, particularly as manufacturers move toward larger display formats. Organic emitters and encapsulation must also satisfy long-term brightness and lifetime requirements, while LCD and MicroLED technologies compete in particular price or performance niches. The market can grow in units while facing pressure on average selling prices, so product mix and manufacturing efficiency determine the value outcome.

Does the OLED market include PMOLED and AMOLED?

Yes, both passive-matrix and active-matrix OLED panels are included because they are alternative drive architectures within the same display technology family. Their applications differ: PMOLED is used for simpler interfaces, while AMOLED supports image-rich, high-resolution screens. The segmentation keeps the categories mutually exclusive at the panel level and excludes non-OLED technologies such as LCD, LCoS and MicroLED.

Which applications offer the strongest OLED opportunities?

Smartphones remain the largest application with a modeled ~46% base-year share, but portable computing and automotive interfaces offer meaningful opportunities to broaden the customer mix. Notebook and tablet panels benefit from larger-substrate production economics, while vehicle displays reward thin, shaped modules and long-duration contracts. Premium monitors also create differentiation through fast response and contrast, subject to cost and durability considerations.

What geographic and forecast scope is covered?

The analysis covers a 2025 base year, 2026 estimate and 2034 forecast, with the modeled 2026–2034 growth path applied to two types and five application categories. North America, Europe, Asia-Pacific, South America, and the Middle East and Africa are assessed separately. Revenue is expressed in USD million at the OLED panel or integrated module level, and regional shares are estimates supported by production and demand indicators.

Research Sources & Evidence Base
View research sources used for this overview
  1. BOE Technology Group. Chengdu Gen 8.6 AMOLED mass-production milestone, Company announcement dated 17 June 2026 on larger-substrate OLED manufacturing.
  2. Visionox Technology. ALD oxide TFT backplane demonstration, Company technical release dated 7 May 2026 concerning a 6.39-inch display demonstration.
  3. Samsung Display. Computex 2026 OLED computing and gaming lineup, Official product showcase dated 1 June 2026.
  4. Samsung Display. Display Week 2026 OLED and sensor display concepts, Official announcement dated 5 May 2026.
  5. Samsung Display. QD-OLED 31.5-inch 4K 360Hz monitor technology, Company product announcement in May 2026.
  6. LG Display. Tandem WOLED product technology, Official technical specifications on brightness and reflection under stated conditions.
  7. LG Display. OLED technology and manufacturing announcements, Official company media center with current product and process developments.
  8. Universal Display Corporation. OLEDX technology platform, 19 August 2026 announcement of light-extraction technology for OLED devices.
  9. Universal Display Corporation. LG Display OLED partnership extension, 26 February 2026 announcement on materials and intellectual-property agreements.
  10. Universal Display Corporation. OLED emissive-layer efficiency research, 25 March 2026 technical presentation on phosphorescent OLED advances.
  11. Universal Display Corporation. Chengdu OLED Technology and Innovation Center, 2 June 2026 opening of a regional materials and customer collaboration center.
  12. Universal Display Corporation. Blue phosphorescent emitter research, 29 April 2026 announcement of SID Display Week presentations.
  13. Universal Display Corporation. Second-quarter 2026 corporate financial results, 30 July 2026 materials and licensing company financial disclosure; not panel revenue.
  14. Universal Display Corporation. Korean phosphorescent OLED research recognition, 30 September 2026 announcement on OLED technology ecosystem activity.
  15. AUO Corporation. MicroLED display technology showcase, 30 March 2026 competitive technology evidence; not counted as OLED sales.
  16. Futaba Corporation. OLED display product portfolio, Official display-module catalogue documenting small OLED product offerings.
  17. Futaba Corporation. OLED module specifications and product information, Official Japanese manufacturer product pages for specialist OLED modules.
Global Organic LED Market, Size, Trends, Business Strategies 2026–2034

Get Sample Report PDF for Exclusive Insights

Report Sample Includes

  • Table of Contents
  • List of Tables & Figures
  • Charts, Research Methodology, and more...

PDF Icon Download Sample Report PDF

Download Sample Report

Table of Content

Table of Contents
1 Research Methodology and Statistical Scope
1.1 Market Definition and Statistical Scope of Organic LED
1.2 Key Market Segments
1.2.1 Organic LED Segment by Type
1.2.2 Organic LED Segment by Application
1.3 Methodology & Sources of Information
1.3.1 Research Methodology
1.3.2 Research Process
1.3.3 Market Breakdown and Data Triangulation
1.3.4 Base Year
1.3.5 Report Assumptions & Caveats
2 Organic LED Market Overview
2.1 Global Market Overview
2.1.1 Global Organic LED Market Size (M USD) Estimates and Forecasts (2026-2034)
2.1.2 Global Organic LED Sales Estimates and Forecasts (2026-2034)
2.2 Market Segment Executive Summary
2.3 Global Market Size by Region
3 Organic LED Market Competitive Landscape
3.1 Global Organic LED Sales by Manufacturers (2019-2025)
3.2 Global Organic LED Revenue Market Share by Manufacturers (2019-2025)
3.3 Organic LED Market Share by Company Type (Tier 1, Tier 2, and Tier 3)
3.4 Global Organic LED Average Price by Manufacturers (2019-2025)
3.5 Manufacturers Organic LED Sales Sites, Area Served, Product Type
3.6 Organic LED Market Competitive Situation and Trends
3.6.1 Organic LED Market Concentration Rate
3.6.2 Global 5 and 10 Largest Organic LED Players Market Share by Revenue
3.6.3 Mergers & Acquisitions, Expansion
4 Organic LED Industry Chain Analysis
4.1 Organic LED Industry Chain Analysis
4.2 Market Overview of Key Raw Materials
4.3 Midstream Market Analysis
4.4 Downstream Customer Analysis
5 The Development and Dynamics of Organic LED Market
5.1 Key Development Trends
5.2 Driving Factors
5.3 Market Challenges
5.4 Market Restraints
5.5 Industry News
5.5.1 New Product Developments
5.5.2 Mergers & Acquisitions
5.5.3 Expansions
5.5.4 Collaboration/Supply Contracts
5.6 Industry Policies
6 Organic LED Market Segmentation by Type
6.1 Evaluation Matrix of Segment Market Development Potential (Type)
6.2 Global Organic LED Sales Market Share by Type (2019-2025)
6.3 Global Organic LED Market Size Market Share by Type (2019-2025)
6.4 Global Organic LED Price by Type (2019-2025)
7 Organic LED Market Segmentation by Application
7.1 Evaluation Matrix of Segment Market Development Potential (Application)
7.2 Global Organic LED Market Sales by Application (2019-2025)
7.3 Global Organic LED Market Size (M USD) by Application (2019-2025)
7.4 Global Organic LED Sales Growth Rate by Application (2019-2025)
8 Organic LED Market Consumption by Region
8.1 Global Organic LED Sales by Region
8.1.1 Global Organic LED Sales by Region
8.1.2 Global Organic LED Sales Market Share by Region
8.2 North America
8.2.1 North America Organic LED Sales by Country
8.2.2 U.S.
8.2.3 Canada
8.2.4 Mexico
8.3 Europe
8.3.1 Europe Organic LED Sales by Country
8.3.2 Germany
8.3.3 France
8.3.4 U.K.
8.3.5 Italy
8.3.6 Russia
8.4 Asia Pacific
8.4.1 Asia Pacific Organic LED Sales by Region
8.4.2 China
8.4.3 Japan
8.4.4 South Korea
8.4.5 India
8.4.6 Southeast Asia
8.5 South America
8.5.1 South America Organic LED Sales by Country
8.5.2 Brazil
8.5.3 Argentina
8.5.4 Columbia
8.6 Middle East and Africa
8.6.1 Middle East and Africa Organic LED Sales by Region
8.6.2 Saudi Arabia
8.6.3 UAE
8.6.4 Egypt
8.6.5 Nigeria
8.6.6 South Africa
9 Organic LED Market Production by Region
9.1 Global Production of Organic LED by Region (2019-2025)
9.2 Global Organic LED Revenue Market Share by Region (2019-2025)
9.3 Global Organic LED Production, Revenue, Price and Gross Margin (2019-2025)
9.4 North America Organic LED Production
9.4.1 North America Organic LED Production Growth Rate (2019-2025)
9.4.2 North America Organic LED Production, Revenue, Price and Gross Margin (2019-2025)
9.5 Europe Organic LED Production
9.5.1 Europe Organic LED Production Growth Rate (2019-2025)
9.5.2 Europe Organic LED Production, Revenue, Price and Gross Margin (2019-2025)
9.6 Japan Organic LED Production (2019-2025)
9.6.1 Japan Organic LED Production Growth Rate (2019-2025)
9.6.2 Japan Organic LED Production, Revenue, Price and Gross Margin (2019-2025)
9.7 China Organic LED Production (2019-2025)
9.7.1 China Organic LED Production Growth Rate (2019-2025)
9.7.2 China Organic LED Production, Revenue, Price and Gross Margin (2019-2025)
10 Key Companies Profile
10.1 Samsung
10.1.1 Samsung Organic LED Basic Information
10.1.2 Samsung Organic LED Product Overview
10.1.3 Samsung Organic LED Product Market Performance
10.1.4 Samsung Business Overview
10.1.5 Samsung Organic LED SWOT Analysis
10.1.6 Samsung Recent Developments
10.2 LG
10.2.1 LG Organic LED Basic Information
10.2.2 LG Organic LED Product Overview
10.2.3 LG Organic LED Product Market Performance
10.2.4 LG Business Overview
10.2.5 LG Organic LED SWOT Analysis
10.2.6 LG Recent Developments
10.3 AUO
10.3.1 AUO Organic LED Basic Information
10.3.2 AUO Organic LED Product Overview
10.3.3 AUO Organic LED Product Market Performance
10.3.4 AUO Organic LED SWOT Analysis
10.3.5 AUO Business Overview
10.3.6 AUO Recent Developments
10.4 Panasonic
10.4.1 Panasonic Organic LED Basic Information
10.4.2 Panasonic Organic LED Product Overview
10.4.3 Panasonic Organic LED Product Market Performance
10.4.4 Panasonic Business Overview
10.4.5 Panasonic Recent Developments
10.5 Philips
10.5.1 Philips Organic LED Basic Information
10.5.2 Philips Organic LED Product Overview
10.5.3 Philips Organic LED Product Market Performance
10.5.4 Philips Business Overview
10.5.5 Philips Recent Developments
10.6 Osram
10.6.1 Osram Organic LED Basic Information
10.6.2 Osram Organic LED Product Overview
10.6.3 Osram Organic LED Product Market Performance
10.6.4 Osram Business Overview
10.6.5 Osram Recent Developments
10.7 Universal Display
10.7.1 Universal Display Organic LED Basic Information
10.7.2 Universal Display Organic LED Product Overview
10.7.3 Universal Display Organic LED Product Market Performance
10.7.4 Universal Display Business Overview
10.7.5 Universal Display Recent Developments
10.8 Futaba
10.8.1 Futaba Organic LED Basic Information
10.8.2 Futaba Organic LED Product Overview
10.8.3 Futaba Organic LED Product Market Performance
10.8.4 Futaba Business Overview
10.8.5 Futaba Recent Developments
10.9 Ltd
10.9.1 Ltd Organic LED Basic Information
10.9.2 Ltd Organic LED Product Overview
10.9.3 Ltd Organic LED Product Market Performance
10.9.4 Ltd Business Overview
10.9.5 Ltd Recent Developments
10.10 Kunshan Visionox
10.10.1 Kunshan Visionox Organic LED Basic Information
10.10.2 Kunshan Visionox Organic LED Product Overview
10.10.3 Kunshan Visionox Organic LED Product Market Performance
10.10.4 Kunshan Visionox Business Overview
10.10.5 Kunshan Visionox Recent Developments
10.11 Display Company
10.11.1 Display Company Organic LED Basic Information
10.11.2 Display Company Organic LED Product Overview
10.11.3 Display Company Organic LED Product Market Performance
10.11.4 Display Company Business Overview
10.11.5 Display Company Recent Developments
10.12 Pioneer
10.12.1 Pioneer Organic LED Basic Information
10.12.2 Pioneer Organic LED Product Overview
10.12.3 Pioneer Organic LED Product Market Performance
10.12.4 Pioneer Business Overview
10.12.5 Pioneer Recent Developments
10.13 Acuity Brands Lighting
10.13.1 Acuity Brands Lighting Organic LED Basic Information
10.13.2 Acuity Brands Lighting Organic LED Product Overview
10.13.3 Acuity Brands Lighting Organic LED Product Market Performance
10.13.4 Acuity Brands Lighting Business Overview
10.13.5 Acuity Brands Lighting Recent Developments
10.14 InnoLux
10.14.1 InnoLux Organic LED Basic Information
10.14.2 InnoLux Organic LED Product Overview
10.14.3 InnoLux Organic LED Product Market Performance
10.14.4 InnoLux Business Overview
10.14.5 InnoLux Recent Developments
11 Organic LED Market Forecast by Region
11.1 Global Organic LED Market Size Forecast
11.2 Global Organic LED Market Forecast by Region
11.2.1 North America Market Size Forecast by Country
11.2.2 Europe Organic LED Market Size Forecast by Country
11.2.3 Asia Pacific Organic LED Market Size Forecast by Region
11.2.4 South America Organic LED Market Size Forecast by Country
11.2.5 Middle East and Africa Forecasted Consumption of Organic LED by Country
12 Forecast Market by Type and by Application (2025-2032)
12.1 Global Organic LED Market Forecast by Type (2025-2032)
12.1.1 Global Forecasted Sales of Organic LED by Type (2025-2032)
12.1.2 Global Organic LED Market Size Forecast by Type (2025-2032)
12.1.3 Global Forecasted Price of Organic LED by Type (2025-2032)
12.2 Global Organic LED Market Forecast by Application (2025-2032)
12.2.1 Global Organic LED Sales (K Units) Forecast by Application
12.2.2 Global Organic LED Market Size (M USD) Forecast by Application (2025-2032)
13 Conclusion and Key FindingsList of Tables
Table 1. Introduction of the Type
Table 2. Introduction of the Application
Table 3. Market Size (M USD) Segment Executive Summary
Table 4. Organic LED Market Size Comparison by Region (M USD)
Table 5. Global Organic LED Sales (K Units) by Manufacturers (2019-2025)
Table 6. Global Organic LED Sales Market Share by Manufacturers (2019-2025)
Table 7. Global Organic LED Revenue (M USD) by Manufacturers (2019-2025)
Table 8. Global Organic LED Revenue Share by Manufacturers (2019-2025)
Table 9. Company Type (Tier 1, Tier 2, and Tier 3) & (based on the Revenue in Organic LED as of 2022)
Table 10. Global Market Organic LED Average Price (USD/Unit) of Key Manufacturers (2019-2025)
Table 11. Manufacturers Organic LED Sales Sites and Area Served
Table 12. Manufacturers Organic LED Product Type
Table 13. Global Organic LED Manufacturers Market Concentration Ratio (CR5 and HHI)
Table 14. Mergers & Acquisitions, Expansion Plans
Table 15. Industry Chain Map of Organic LED
Table 16. Market Overview of Key Raw Materials
Table 17. Midstream Market Analysis
Table 18. Downstream Customer Analysis
Table 19. Key Development Trends
Table 20. Driving Factors
Table 21. Organic LED Market Challenges
Table 22. Global Organic LED Sales by Type (K Units)
Table 23. Global Organic LED Market Size by Type (M USD)
Table 24. Global Organic LED Sales (K Units) by Type (2019-2025)
Table 25. Global Organic LED Sales Market Share by Type (2019-2025)
Table 26. Global Organic LED Market Size (M USD) by Type (2019-2025)
Table 27. Global Organic LED Market Size Share by Type (2019-2025)
Table 28. Global Organic LED Price (USD/Unit) by Type (2019-2025)
Table 29. Global Organic LED Sales (K Units) by Application
Table 30. Global Organic LED Market Size by Application
Table 31. Global Organic LED Sales by Application (2019-2025) & (K Units)
Table 32. Global Organic LED Sales Market Share by Application (2019-2025)
Table 33. Global Organic LED Sales by Application (2019-2025) & (M USD)
Table 34. Global Organic LED Market Share by Application (2019-2025)
Table 35. Global Organic LED Sales Growth Rate by Application (2019-2025)
Table 36. Global Organic LED Sales by Region (2019-2025) & (K Units)
Table 37. Global Organic LED Sales Market Share by Region (2019-2025)
Table 38. North America Organic LED Sales by Country (2019-2025) & (K Units)
Table 39. Europe Organic LED Sales by Country (2019-2025) & (K Units)
Table 40. Asia Pacific Organic LED Sales by Region (2019-2025) & (K Units)
Table 41. South America Organic LED Sales by Country (2019-2025) & (K Units)
Table 42. Middle East and Africa Organic LED Sales by Region (2019-2025) & (K Units)
Table 43. Global Organic LED Production (K Units) by Region (2019-2025)
Table 44. Global Organic LED Revenue (US$ Million) by Region (2019-2025)
Table 45. Global Organic LED Revenue Market Share by Region (2019-2025)
Table 46. Global Organic LED Production (K Units), Revenue (US$ Million), Price (USD/Unit) and Gross Margin (2019-2025)
Table 47. North America Organic LED Production (K Units), Revenue (US$ Million), Price (USD/Unit) and Gross Margin (2019-2025)
Table 48. Europe Organic LED Production (K Units), Revenue (US$ Million), Price (USD/Unit) and Gross Margin (2019-2025)
Table 49. Japan Organic LED Production (K Units), Revenue (US$ Million), Price (USD/Unit) and Gross Margin (2019-2025)
Table 50. China Organic LED Production (K Units), Revenue (US$ Million), Price (USD/Unit) and Gross Margin (2019-2025)
Table 51. Samsung Organic LED Basic Information
Table 52. Samsung Organic LED Product Overview
Table 53. Samsung Organic LED Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 54. Samsung Business Overview
Table 55. Samsung Organic LED SWOT Analysis
Table 56. Samsung Recent Developments
Table 57. LG Organic LED Basic Information
Table 58. LG Organic LED Product Overview
Table 59. LG Organic LED Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 60. LG Business Overview
Table 61. LG Organic LED SWOT Analysis
Table 62. LG Recent Developments
Table 63. AUO Organic LED Basic Information
Table 64. AUO Organic LED Product Overview
Table 65. AUO Organic LED Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 66. AUO Organic LED SWOT Analysis
Table 67. AUO Business Overview
Table 68. AUO Recent Developments
Table 69. Panasonic Organic LED Basic Information
Table 70. Panasonic Organic LED Product Overview
Table 71. Panasonic Organic LED Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 72. Panasonic Business Overview
Table 73. Panasonic Recent Developments
Table 74. Philips Organic LED Basic Information
Table 75. Philips Organic LED Product Overview
Table 76. Philips Organic LED Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 77. Philips Business Overview
Table 78. Philips Recent Developments
Table 79. Osram Organic LED Basic Information
Table 80. Osram Organic LED Product Overview
Table 81. Osram Organic LED Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 82. Osram Business Overview
Table 83. Osram Recent Developments
Table 84. Universal Display Organic LED Basic Information
Table 85. Universal Display Organic LED Product Overview
Table 86. Universal Display Organic LED Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 87. Universal Display Business Overview
Table 88. Universal Display Recent Developments
Table 89. Futaba Organic LED Basic Information
Table 90. Futaba Organic LED Product Overview
Table 91. Futaba Organic LED Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 92. Futaba Business Overview
Table 93. Futaba Recent Developments
Table 94. Ltd Organic LED Basic Information
Table 95. Ltd Organic LED Product Overview
Table 96. Ltd Organic LED Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 97. Ltd Business Overview
Table 98. Ltd Recent Developments
Table 99. Kunshan Visionox Organic LED Basic Information
Table 100. Kunshan Visionox Organic LED Product Overview
Table 101. Kunshan Visionox Organic LED Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 102. Kunshan Visionox Business Overview
Table 103. Kunshan Visionox Recent Developments
Table 104. Display Company Organic LED Basic Information
Table 105. Display Company Organic LED Product Overview
Table 106. Display Company Organic LED Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 107. Display Company Business Overview
Table 108. Display Company Recent Developments
Table 109. Pioneer Organic LED Basic Information
Table 110. Pioneer Organic LED Product Overview
Table 111. Pioneer Organic LED Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 112. Pioneer Business Overview
Table 113. Pioneer Recent Developments
Table 114. Acuity Brands Lighting Organic LED Basic Information
Table 115. Acuity Brands Lighting Organic LED Product Overview
Table 116. Acuity Brands Lighting Organic LED Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 117. Acuity Brands Lighting Business Overview
Table 118. Acuity Brands Lighting Recent Developments
Table 119. InnoLux Organic LED Basic Information
Table 120. InnoLux Organic LED Product Overview
Table 121. InnoLux Organic LED Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 122. InnoLux Business Overview
Table 123. InnoLux Recent Developments
Table 124. Global Organic LED Sales Forecast by Region (2025-2032) & (K Units)
Table 125. Global Organic LED Market Size Forecast by Region (2025-2032) & (M USD)
Table 126. North America Organic LED Sales Forecast by Country (2025-2032) & (K Units)
Table 127. North America Organic LED Market Size Forecast by Country (2025-2032) & (M USD)
Table 128. Europe Organic LED Sales Forecast by Country (2025-2032) & (K Units)
Table 129. Europe Organic LED Market Size Forecast by Country (2025-2032) & (M USD)
Table 130. Asia Pacific Organic LED Sales Forecast by Region (2025-2032) & (K Units)
Table 131. Asia Pacific Organic LED Market Size Forecast by Region (2025-2032) & (M USD)
Table 132. South America Organic LED Sales Forecast by Country (2025-2032) & (K Units)
Table 133. South America Organic LED Market Size Forecast by Country (2025-2032) & (M USD)
Table 134. Middle East and Africa Organic LED Consumption Forecast by Country (2025-2032) & (Units)
Table 135. Middle East and Africa Organic LED Market Size Forecast by Country (2025-2032) & (M USD)
Table 136. Global Organic LED Sales Forecast by Type (2025-2032) & (K Units)
Table 137. Global Organic LED Market Size Forecast by Type (2025-2032) & (M USD)
Table 138. Global Organic LED Price Forecast by Type (2025-2032) & (USD/Unit)
Table 139. Global Organic LED Sales (K Units) Forecast by Application (2025-2032)
Table 140. Global Organic LED Market Size Forecast by Application (2025-2032) & (M USD)
List of Figures
Figure 1. Product Picture of Organic LED
Figure 2. Data Triangulation
Figure 3. Key Caveats
Figure 4. Global Organic LED Market Size (M USD), 2026-2034
Figure 5. Global Organic LED Market Size (M USD) (2026-2034)
Figure 6. Global Organic LED Sales (K Units) & (2026-2034)
Figure 7. Evaluation Matrix of Segment Market Development Potential (Type)
Figure 8. Evaluation Matrix of Segment Market Development Potential (Application)
Figure 9. Evaluation Matrix of Regional Market Development Potential
Figure 10. Organic LED Market Size by Country (M USD)
Figure 11. Organic LED Sales Share by Manufacturers in 2023
Figure 12. Global Organic LED Revenue Share by Manufacturers in 2023
Figure 13. Organic LED Market Share by Company Type (Tier 1, Tier 2 and Tier 3): 2023
Figure 14. Global Market Organic LED Average Price (USD/Unit) of Key Manufacturers in 2023
Figure 15. The Global 5 and 10 Largest Players: Market Share by Organic LED Revenue in 2023
Figure 16. Evaluation Matrix of Segment Market Development Potential (Type)
Figure 17. Global Organic LED Market Share by Type
Figure 18. Sales Market Share of Organic LED by Type (2019-2025)
Figure 19. Sales Market Share of Organic LED by Type in 2023
Figure 20. Market Size Share of Organic LED by Type (2019-2025)
Figure 21. Market Size Market Share of Organic LED by Type in 2023
Figure 22. Evaluation Matrix of Segment Market Development Potential (Application)
Figure 23. Global Organic LED Market Share by Application
Figure 24. Global Organic LED Sales Market Share by Application (2019-2025)
Figure 25. Global Organic LED Sales Market Share by Application in 2023
Figure 26. Global Organic LED Market Share by Application (2019-2025)
Figure 27. Global Organic LED Market Share by Application in 2023
Figure 28. Global Organic LED Sales Growth Rate by Application (2019-2025)
Figure 29. Global Organic LED Sales Market Share by Region (2019-2025)
Figure 30. North America Organic LED Sales and Growth Rate (2019-2025) & (K Units)
Figure 31. North America Organic LED Sales Market Share by Country in 2023
Figure 32. U.S. Organic LED Sales and Growth Rate (2019-2025) & (K Units)
Figure 33. Canada Organic LED Sales (K Units) and Growth Rate (2019-2025)
Figure 34. Mexico Organic LED Sales (Units) and Growth Rate (2019-2025)
Figure 35. Europe Organic LED Sales and Growth Rate (2019-2025) & (K Units)
Figure 36. Europe Organic LED Sales Market Share by Country in 2023
Figure 37. Germany Organic LED Sales and Growth Rate (2019-2025) & (K Units)
Figure 38. France Organic LED Sales and Growth Rate (2019-2025) & (K Units)
Figure 39. U.K. Organic LED Sales and Growth Rate (2019-2025) & (K Units)
Figure 40. Italy Organic LED Sales and Growth Rate (2019-2025) & (K Units)
Figure 41. Russia Organic LED Sales and Growth Rate (2019-2025) & (K Units)
Figure 42. Asia Pacific Organic LED Sales and Growth Rate (K Units)
Figure 43. Asia Pacific Organic LED Sales Market Share by Region in 2023
Figure 44. China Organic LED Sales and Growth Rate (2019-2025) & (K Units)
Figure 45. Japan Organic LED Sales and Growth Rate (2019-2025) & (K Units)
Figure 46. South Korea Organic LED Sales and Growth Rate (2019-2025) & (K Units)
Figure 47. India Organic LED Sales and Growth Rate (2019-2025) & (K Units)
Figure 48. Southeast Asia Organic LED Sales and Growth Rate (2019-2025) & (K Units)
Figure 49. South America Organic LED Sales and Growth Rate (K Units)
Figure 50. South America Organic LED Sales Market Share by Country in 2023
Figure 51. Brazil Organic LED Sales and Growth Rate (2019-2025) & (K Units)
Figure 52. Argentina Organic LED Sales and Growth Rate (2019-2025) & (K Units)
Figure 53. Columbia Organic LED Sales and Growth Rate (2019-2025) & (K Units)
Figure 54. Middle East and Africa Organic LED Sales and Growth Rate (K Units)
Figure 55. Middle East and Africa Organic LED Sales Market Share by Region in 2023
Figure 56. Saudi Arabia Organic LED Sales and Growth Rate (2019-2025) & (K Units)
Figure 57. UAE Organic LED Sales and Growth Rate (2019-2025) & (K Units)
Figure 58. Egypt Organic LED Sales and Growth Rate (2019-2025) & (K Units)
Figure 59. Nigeria Organic LED Sales and Growth Rate (2019-2025) & (K Units)
Figure 60. South Africa Organic LED Sales and Growth Rate (2019-2025) & (K Units)
Figure 61. Global Organic LED Production Market Share by Region (2019-2025)
Figure 62. North America Organic LED Production (K Units) Growth Rate (2019-2025)
Figure 63. Europe Organic LED Production (K Units) Growth Rate (2019-2025)
Figure 64. Japan Organic LED Production (K Units) Growth Rate (2019-2025)
Figure 65. China Organic LED Production (K Units) Growth Rate (2019-2025)
Figure 66. Global Organic LED Sales Forecast by Volume (2026-2034) & (K Units)
Figure 67. Global Organic LED Market Size Forecast by Value (2026-2034) & (M USD)
Figure 68. Global Organic LED Sales Market Share Forecast by Type (2025-2032)
Figure 69. Global Organic LED Market Share Forecast by Type (2025-2032)
Figure 70. Global Organic LED Sales Forecast by Application (2025-2032)
Figure 71. Global Organic LED Market Share Forecast by Application (2025-2032)