Key Statistics
Key Takeaways
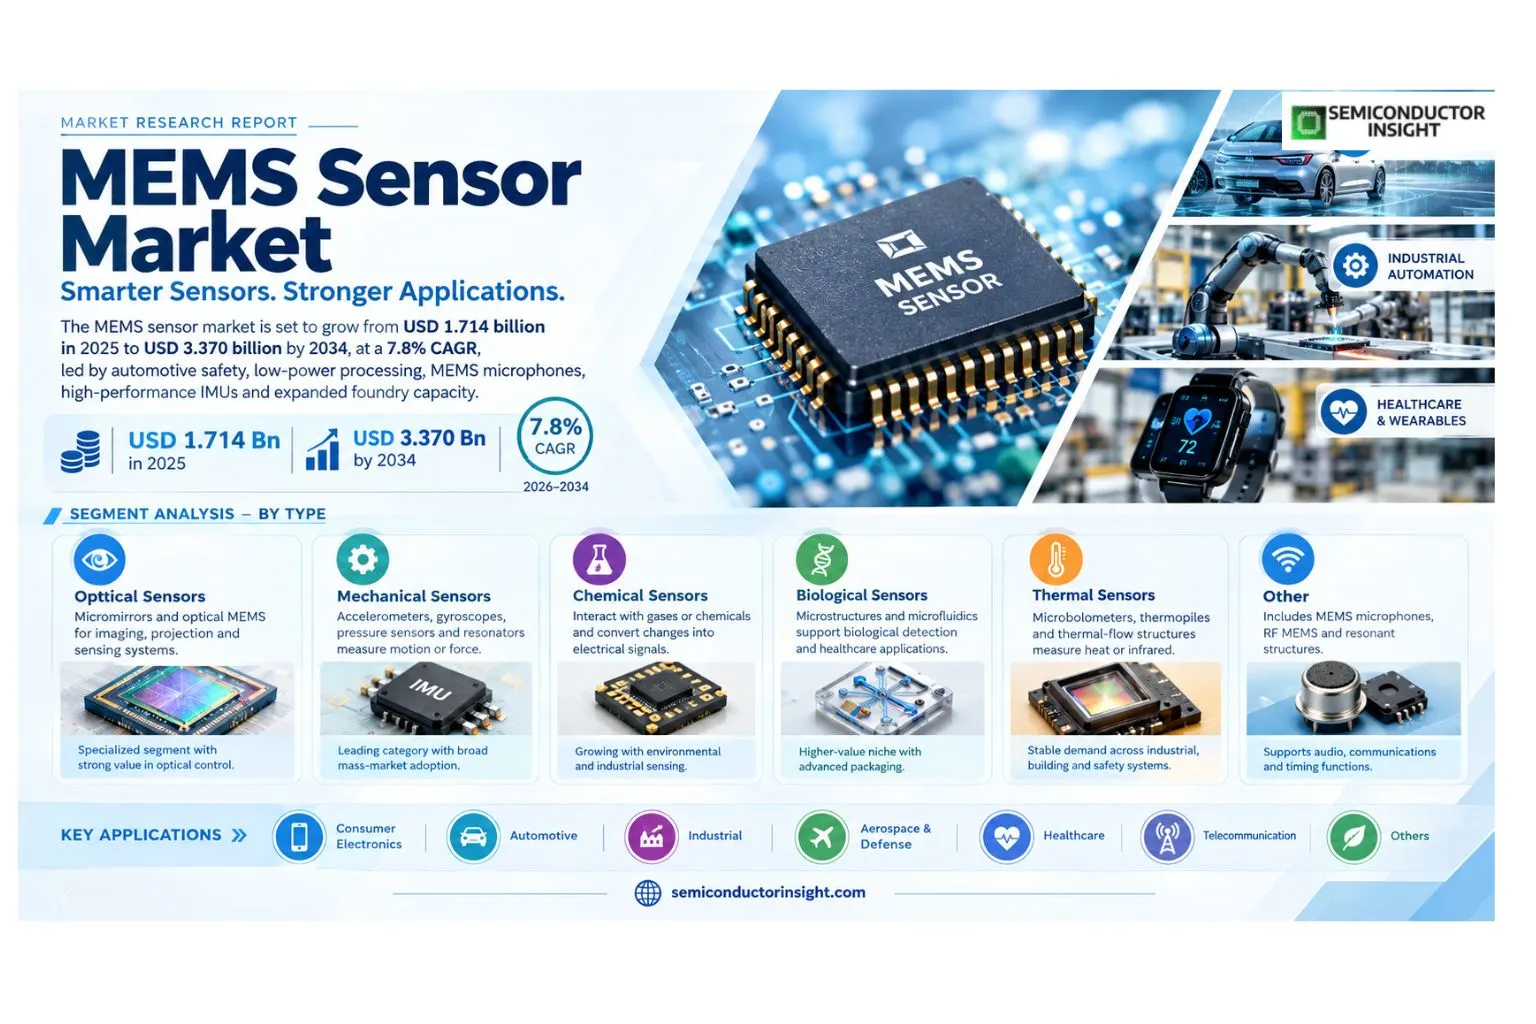
- Market size and growth: the market is valued at USD 1.714 billion in 2025 and is projected to reach USD 3.370 billion by 2034, representing a 7.8% CAGR over 2026–2034.
- Mechanical Sensors leads by type because accelerometers, gyroscopes and pressure sensors have the broadest installed base across smartphones, vehicles, industrial equipment and navigation systems.
- Consumer Electronics leads application demand because smartphones, wearables, earbuds and connected devices integrate multiple motion, pressure, acoustic and environmental MEMS functions at very high unit volume.
- Asia Pacific is the largest regional market, while Asia Pacific has the strongest incremental growth profile.
- Primary driver: consumer, automotive, industrial and wearable systems continue to increase the number and sophistication of motion, pressure, acoustic and environmental sensors
- Principal restraint: MEMS process specialization, calibration, packaging and long qualification cycles raise development cost and make second sourcing difficult for custom devices
Market Overview
The MEMS sensor market was valued at USD 1.714 billion in 2025 and is projected to reach USD 3.370 billion by 2034, expanding at a 7.8% CAGR over 2026–2034. Asia Pacific leads in 2025, while the market is being reshaped by automotive safety qualification, low-power motion processing, MEMS microphones, high-performance inertial measurement and expanded specialty-foundry capacity.. For MEMS (Micro-Electromechanical System) Sensor suppliers, the commercial implication is that product performance must translate into a measurable system benefit, not only a stronger component specification.
MEMS sensors combine micromachined mechanical structures with semiconductor electronics to measure motion, pressure, sound, environmental conditions and other physical phenomena in compact packages. Bosch Sensortec’s current portfolio spans accelerometers, gyroscopes, IMUs, pressure, magnetic, gas and smart-sensor products, while STMicroelectronics states that it has shipped more than 20 billion MEMS sensors across consumer, automotive and industrial applications. This scale demonstrates that MEMS is no longer a single-device niche; it is a mature manufacturing platform supporting many sensor modalities with different process, packaging and qualification requirements.
Automotive and industrial demand is pushing the market toward higher reliability and better embedded intelligence. TDK’s automotive IAM-20689 inertial sensor is positioned for safety-related vehicle applications, while ST offers automotive-qualified motion sensors and NXP has historically supplied automotive pressure sensors. Analog Devices and Honeywell address a different performance tier with calibrated inertial measurement units for industrial, aerospace and navigation systems. These products show that market value does not track unit volume alone: precision, temperature stability, calibration and functional-safety support can create substantial value per sensor.
MEMS manufacturing is also becoming more geographically diversified. Silex Microsystems operates as a pure-play MEMS foundry and has expanded capacity through 8-inch wafer manufacturing and a 2026 U.S. fab acquisition, while large IDMs continue to integrate design, wafer processing and packaging internally. At the application level, MEMS microphones from Infineon and Knowles support earbuds, voice interfaces and wearables, illustrating continued diversification beyond inertial sensing. Growth therefore depends on both high-volume consumer platforms and specialist applications that require custom structures, packaging and long qualification cycles.
Segment Analysis: By Type
By type, the market is segmented into Optical Sensors, Mechanical Sensors, Chemical Sensors, Biological Sensors, Thermal Sensors, Other. Mechanical Sensors holds the leading position because accelerometers, gyroscopes and pressure sensors have the broadest installed base across smartphones, vehicles, industrial equipment and navigation systems. Procurement decisions in the MEMS (Micro-Electromechanical System) Sensor market therefore increasingly consider qualification evidence, integration effort, lifecycle support and supply continuity alongside unit price. As adoption broadens, vendors that combine repeatable manufacturing with application engineering and documented reliability should be better positioned for long production programs.
| Type | Function / role | Market position |
|---|---|---|
| Optical Sensors | Micromirrors and optical MEMS manipulate or detect light in imaging, projection and sensing systems. | Specialized segment with strong value in optical control and emerging sensing. |
| Mechanical Sensors | Accelerometers, gyroscopes, pressure sensors and resonators use micromachined structures to measure physical motion or force. | Leading category because motion and pressure functions are embedded across many mass-market platforms. |
| Chemical Sensors | MEMS structures interact with gases or chemical species and convert changes into electrical signals. | Growing with environmental monitoring, air quality and industrial sensing. |
| Biological Sensors | Microstructures and microfluidic interfaces support biological detection and healthcare applications. | Higher-value niche requiring strong packaging and surface-functionalization control. |
| Thermal Sensors | Microbolometers, thermopiles and thermal-flow structures measure infrared radiation, heat or fluid movement. | Stable demand across industrial, building and safety systems. |
| Other | Includes MEMS microphones, RF MEMS and specialized resonant structures. | Important adjacent category supporting audio, communications and timing functions. |
Commercial implications by type
Mechanical MEMS remains the broadest commercial category because inertial and pressure sensors scale from low-cost consumer devices to automotive and aerospace products. However, the manufacturing and business models differ sharply across applications. A smartphone IMU competes on power, package size and algorithm integration, while an aerospace IMU competes on bias stability, temperature calibration and long-term drift. MEMS microphones emphasize acoustic performance and wafer-level packaging, and optical or chemical devices often require specialized materials. Suppliers therefore need application-specific process and packaging expertise rather than one universal MEMS flow.
Segment Analysis: By Application
By application, the market includes Consumer Electronics, Automotive, Industrial, Aerospace and Defense, Healthcare, Telecommunication, Others. Consumer Electronics leads demand because smartphones, wearables, earbuds and connected devices integrate multiple motion, pressure, acoustic and environmental MEMS functions at very high unit volume. As adoption broadens, vendors that combine repeatable manufacturing with application engineering and documented reliability should be better positioned for long production programs. This makes design support and field-proven integration increasingly important because the cost of requalification can exceed the incremental saving from a lower-priced component.
| Application | Demand characteristics |
|---|---|
| Consumer Electronics | Largest unit market across smartphones, wearables, earbuds, gaming, cameras and smart-home devices. |
| Automotive | Safety, navigation, airbag, tire, pressure and vehicle-dynamics systems use qualified MEMS sensors. |
| Industrial | Condition monitoring, robotics, machine control and predictive maintenance require rugged motion and pressure sensing. |
| Aerospace and Defense | High-performance IMUs and pressure sensors support navigation, stabilization and control. |
| Healthcare | Wearables, inhalers, pumps, diagnostic devices and monitoring systems use compact sensor functions. |
| Telecommunication | MEMS microphones, timing, RF and environmental sensing support communications equipment. |
| Others | Energy, agriculture and research applications broaden demand. |
By Sensing Modality
| Sensing Modality | Commercial relevance |
|---|---|
| Inertial Motion | Accelerometers and gyroscopes measure linear acceleration and angular rate. |
| Pressure & Environmental | Pressure, gas and environmental MEMS monitor physical conditions. |
| Acoustic | MEMS microphones convert sound pressure into electrical signals. |
| Optical / Thermal | Micromirrors, bolometers and thermopiles support imaging and control. |
By Integration Level
| Integration Level | Commercial relevance |
|---|---|
| Discrete MEMS Sensor | Standalone sensor connects to an external MCU or application processor. |
| Sensor + ASIC | MEMS structure and signal-conditioning ASIC are co-packaged for calibration and digital output. |
| Smart Sensor Module | Adds embedded processing, sensor fusion, filtering or machine-learning functions. |
By End User
| End User | Commercial relevance |
|---|---|
| Consumer Device OEMs | Drive highest unit volumes and aggressive power/size targets. |
| Automotive Tier 1s & OEMs | Require AEC-Q qualification, safety documentation and long supply life. |
| Industrial Equipment Makers | Prioritize ruggedness, calibration and lifecycle stability. |
| Aerospace & Defense Integrators | Value precision, low drift and environmental qualification. |
Regional Analysis
Asia Pacific leads the market because China, Japan, South Korea and Taiwan combine large consumer-electronics, automotive and sensor manufacturing ecosystems, while Japan and regional suppliers have deep MEMS process and packaging expertise. Asia Pacific has the strongest growth profile through industrial automation, electric vehicles, wearables and regional semiconductor capacity continue to expand both unit volume and specialty MEMS production. This makes design support and field-proven integration increasingly important because the cost of requalification can exceed the incremental saving from a lower-priced component.
How does regional demand differ across this market?
Asia Pacific leads volume because consumer electronics, automotive production and sensor manufacturing are concentrated across China, Japan, South Korea and Taiwan. North America remains a high-value market for industrial, aerospace, medical and advanced sensing, while Europe has strong automotive and MEMS supplier ecosystems through Bosch, ST and specialist foundries. South America and the Middle East & Africa are primarily downstream demand regions. Across markets, unit volume and revenue mix diverge: consumer MEMS ships in enormous quantities, while automotive, industrial and aerospace products command higher value through calibration, qualification and reliability.
| Region | Position | Growth outlook | Demand profile | Supplier selection |
|---|---|---|---|---|
| Asia Pacific | Largest | Fastest | Consumer, automotive and manufacturing scale | Cost, package size, high-volume quality |
| North America | Second | Strong | Industrial, aerospace and medical | Precision, calibration, lifecycle support |
| Europe | Third | Strong | Automotive and industrial | AEC-Q, safety, precision, long lifecycle |
| South America | Smaller | Moderate | Automotive and industrial downstream demand | Cost, availability, support |
| Middle East & Africa | Emerging | Moderate | Infrastructure, industrial and connected devices | Ruggedness, low power, availability |
Competitive Landscape
Competition combines high-volume IDMs, specialist MEMS foundries and precision-sensor vendors, with differentiation driven by process IP, calibration, embedded algorithms, packaging and qualification. For MEMS (Micro-Electromechanical System) Sensor suppliers, the commercial implication is that product performance must translate into a measurable system benefit, not only a stronger component specification. Procurement decisions in the MEMS (Micro-Electromechanical System) Sensor market therefore increasingly consider qualification evidence, integration effort, lifecycle support and supply continuity alongside unit price. As adoption broadens, vendors that combine repeatable manufacturing with application engineering and documented reliability should be better positioned for long production programs.
Bosch Sensortec and STMicroelectronics compete strongly in high-volume consumer and automotive MEMS. Bosch’s portfolio spans motion, pressure, environmental and smart sensing, while ST states that it has shipped more than 20 billion MEMS sensors and supports automotive-qualified motion devices. Their scale provides strong process learning and packaging economics, but differentiation increasingly comes from embedded algorithms, always-on power and sensor fusion. A device that reduces processor workload or arrives with mature software can create more system value than a sensor with only a marginally better standalone noise specification.
TDK InvenSense occupies a major motion-sensing position through consumer, industrial and automotive IMUs, including current automotive-grade devices designed for safety-related systems. Analog Devices and Honeywell address higher-performance inertial sensing where bias stability, calibration and environmental ruggedness command much higher value per unit. Infineon and Knowles compete in MEMS microphones, demonstrating that themarket is diversified by modality. This fragmentation means vendors rarely compete across every MEMS category; leadership is usually application-specific and tied to distinct process, packaging and algorithm expertise.
Silex Microsystems represents the pure-play foundry model, providing MEMS wafer manufacturing for customers that own device designs but lack dedicated fabs. Its expansion into U.S. capacity in 2026 highlights growing interest in geographically diversified MEMS production. Foundries compete on process flexibility, wafer size, bonding, through-silicon structures and the ability to transfer a custom development into stable volume production. This model is especially important for optical, medical, industrial and emerging sensors that do not have enough volume to justify an IDM’s dedicated process but still require highly specialized micromachining.
| Competitive tier | Representative participants | Competitive focus |
|---|---|---|
| High-volume MEMS IDMs | Bosch, STMicroelectronics, TDK InvenSense | Consumer, automotive and smart-sensor scale |
| Precision and specialty sensor vendors | Analog Devices, Honeywell, Infineon, Knowles | Industrial, aerospace, acoustic and high-value sensing |
| Pure-play MEMS foundries | Silex Microsystems and regional specialists | Custom process development and wafer manufacturing |
Companies Profiled
Bosch Sensortec, STMicroelectronics, TDK InvenSense, Analog Devices, Honeywell, Infineon Technologies, Knowles, Silex Microsystems, Sensata Technologies. The set reflects companies directly active in products, process technology, manufacturing or the supporting application ecosystem rather than an evaluative ranking. Procurement decisions in the MEMS (Micro-Electromechanical System) Sensor market therefore increasingly consider qualification evidence, integration effort, lifecycle support and supply continuity alongside unit price. As adoption broadens, vendors that combine repeatable manufacturing with application engineering and documented reliability should be better positioned for long production programs.
Production Capacity Analysis
MEMS capacity depends on specialized micromachining, deposition, deep reactive-ion etch, wafer bonding, cavity formation, sensor ASIC supply, wafer-level packaging and extensive calibration rather than a standardized logic-node flow. For MEMS (Micro-Electromechanical System) Sensor suppliers, the commercial implication is that product performance must translate into a measurable system benefit, not only a stronger component specification. Procurement decisions in the MEMS (Micro-Electromechanical System) Sensor market therefore increasingly consider qualification evidence, integration effort, lifecycle support and supply continuity alongside unit price.
Unlike commodity CMOS logic, MEMS products often require application-specific process modules and structures that cannot be moved between fabs without extensive requalification. Accelerometers and gyroscopes need carefully controlled proof masses, springs and cavities, microphones need acoustic membranes, and pressure sensors need diaphragms and media-compatible packaging. This specialization makes fab flexibility and process-transfer know-how critical. Silex’s pure-play model exists because smaller sensor developers need access to deep micromachining, wafer bonding and packaging without building a dedicated facility, while large IDMs use scale to optimize proprietary flows.
Calibration and packaging are major contributors to effective capacity. An inertial sensor may require multi-temperature calibration, bias compensation and package-stress characterization before shipment, while automotive parts add AEC-Q qualification and traceability. MEMS microphones and pressure sensors need environmental or acoustic test that differs from motion sensors. Production expansion therefore requires more than adding wafer starts; backend equipment, test time, calibration algorithms and package supply must scale together. Suppliers with integrated wafer-level packaging and automated calibration can lower unit cost and improve consistency across high-volume production lots.
Market Dynamics
The market is evolving from discrete physical sensing toward smart sensor nodes that combine MEMS structures, signal conditioning, embedded algorithms and application-specific intelligence in one qualified package. For MEMS (Micro-Electromechanical System) Sensor suppliers, the commercial implication is that product performance must translate into a measurable system benefit, not only a stronger component specification. Procurement decisions in the MEMS (Micro-Electromechanical System) Sensor market therefore increasingly consider qualification evidence, integration effort, lifecycle support and supply continuity alongside unit price.
Smartphones established the economics of high-volume MEMS, but future value growth is increasingly distributed across automotive safety, industrial monitoring, medical devices and high-performance navigation. These markets demand more calibration and longer lifecycle than consumer electronics, creating a different revenue mix even when unit volumes are lower. At the same time, consumer and wearable platforms continue pushing power and package size downward. Suppliers that can reuse core MEMS structures while differentiating through ASICs, firmware and application software are better positioned to serve several markets without redesigning every process from the ground up.
Market Drivers
Drivers Impact Analysis
| Driver | Impact | Commercial mechanism |
|---|---|---|
| Automotive sensor content | High | Vehicles use MEMS accelerometers, gyroscopes and pressure sensors for airbags, stability control, tire pressure, navigation, battery systems and advanced driver-assistance functions. Automotive-grade products need wide-temperature operation, functional-safety support and long-term supply, raising value per device. TDK and ST both maintain automotive-oriented inertial products, while established pressure-sensor families serve safety and control functions. Electric and software-defined vehicles add more sensing points, creating sustained demand even if individual sensor prices decline through manufacturing scale and integration. |
| Wearables and consumer devices | High | Smartphones, earbuds, watches and smart-home products integrate multiple motion, pressure, acoustic and environmental sensors while imposing strict power and package limits. Bosch, ST and TDK continue to add embedded processing and low-power modes so sensors can remain active without continuously waking the main application processor. This creates value beyond the mechanical element because firmware can perform gesture detection, orientation or activity classification locally. Very large consumer volumes also improve manufacturing learning, helping suppliers fund smaller geometries, wafer-level packaging and more integrated smart-sensor architectures. |
| Industrial condition monitoring | Medium | Factories increasingly use vibration, motion and pressure data to monitor machines, predict failures and automate control. MEMS sensors are attractive because they are compact, inexpensive compared with traditional instrumentation and easy to network with edge processors. Industrial buyers, however, require better noise, bandwidth and temperature stability than many consumer devices, creating a premium segment for calibrated sensors and modules. As maintenance shifts from scheduled service toward condition-based strategies, sensor suppliers can capture value through reference designs, embedded diagnostics and long lifecycle support in addition to the MEMS die. |
| MEMS microphones and voice interfaces | Medium | Earbuds, smartphones, laptops, hearing devices and smart speakers use multiple microphones for beamforming, active-noise cancellation and voice interaction. Infineon and Knowles continue to develop high-performance MEMS microphone families with small packages and strong acoustic characteristics. Increasing microphone count per device can offset price pressure and broadens MEMS exposure beyond inertial sensing. Future growth also includes automotive cabins and industrial acoustic monitoring, where microphone arrays can detect speech, anomalies or equipment condition while benefiting from semiconductor-style consistency and automated assembly. |
Automotive sensor content
Vehicles use MEMS accelerometers, gyroscopes and pressure sensors for airbags, stability control, tire pressure, navigation, battery systems and advanced driver-assistance functions. Automotive-grade products need wide-temperature operation, functional-safety support and long-term supply, raising value per device. TDK and ST both maintain automotive-oriented inertial products, while established pressure-sensor families serve safety and control functions. Electric and software-defined vehicles add more sensing points, creating sustained demand even if individual sensor prices decline through manufacturing scale and integration. For MEMS (Micro-Electromechanical System) Sensor suppliers, the commercial implication is that product performance must translate into a measurable system benefit, not only a stronger component specification.
Wearables and consumer devices
Smartphones, earbuds, watches and smart-home products integrate multiple motion, pressure, acoustic and environmental sensors while imposing strict power and package limits. Bosch, ST and TDK continue to add embedded processing and low-power modes so sensors can remain active without continuously waking the main application processor. This creates value beyond the mechanical element because firmware can perform gesture detection, orientation or activity classification locally. Very large consumer volumes also improve manufacturing learning, helping suppliers fund smaller geometries, wafer-level packaging and more integrated smart-sensor architectures.
Industrial condition monitoring
Factories increasingly use vibration, motion and pressure data to monitor machines, predict failures and automate control. MEMS sensors are attractive because they are compact, inexpensive compared with traditional instrumentation and easy to network with edge processors. Industrial buyers, however, require better noise, bandwidth and temperature stability than many consumer devices, creating a premium segment for calibrated sensors and modules. As maintenance shifts from scheduled service toward condition-based strategies, sensor suppliers can capture value through reference designs, embedded diagnostics and long lifecycle support in addition to the MEMS die.
MEMS microphones and voice interfaces
Earbuds, smartphones, laptops, hearing devices and smart speakers use multiple microphones for beamforming, active-noise cancellation and voice interaction. Infineon and Knowles continue to develop high-performance MEMS microphone families with small packages and strong acoustic characteristics. Increasing microphone count per device can offset price pressure and broadens MEMS exposure beyond inertial sensing. Future growth also includes automotive cabins and industrial acoustic monitoring, where microphone arrays can detect speech, anomalies or equipment condition while benefiting from semiconductor-style consistency and automated assembly.
Market Restraints
Restraints Impact Analysis
| Restraint | Impact | Commercial mechanism |
|---|---|---|
| Process customization | High | MEMS manufacturing is highly application-specific because mechanical structures, materials, cavity depth and packaging can differ substantially between motion, pressure, microphone and optical devices. A process developed for one product cannot always be transferred to another fab or supplier without redesign and requalification. This raises non-recurring engineering cost and slows second sourcing, particularly for custom industrial or medical sensors. Pure-play foundries reduce the barrier, but customers still need stable design rules, specialized masks and long process-development cycles before production yield becomes commercially acceptable. |
| Calibration and packaging cost | High | The mechanical structure is only part of a MEMS product’s value. Package stress, temperature, humidity and mounting can alter sensor output, so high-performance devices require calibration and compensation after assembly. Automotive and aerospace products may need multi-temperature test and long reliability qualification, while microphones and pressure sensors require application-specific acoustic or media exposure. These backend steps add cost and test time, meaning wafer-level yield improvements alone do not guarantee lower final sensor cost. Suppliers must optimize assembly and calibration together with the MEMS die. |
| Consumer price pressure | Medium | Smartphone and wearable OEMs purchase very large volumes and expect continuous cost reduction, creating intense pressure on mainstream accelerometer, gyroscope and environmental-sensor pricing. Suppliers need scale, automated calibration and package integration to protect margins as functionality rises. Embedded algorithms can differentiate premium products, but customers may switch suppliers when performance converges and qualification is manageable. The strongest defense is a broad platform that combines hardware, software and application support so the sensor becomes more deeply integrated into the OEM’s product architecture than a simple interchangeable component. |
| Qualification barriers | Medium | Automotive, medical, industrial and aerospace sensors require extensive validation before adoption because failure can affect safety, navigation or long equipment lifetimes. Changing a MEMS process, package or manufacturing site can trigger requalification even if nominal electrical specifications remain unchanged. This makes capacity expansion slower and can limit a customer’s willingness to adopt a second source. Suppliers benefit from sticky design wins once qualified, but new entrants face a long path from sample performance to production revenue, especially in safety-related systems governed by AEC-Q or functional-safety expectations. |
Process customization
MEMS manufacturing is highly application-specific because mechanical structures, materials, cavity depth and packaging can differ substantially between motion, pressure, microphone and optical devices. A process developed for one product cannot always be transferred to another fab or supplier without redesign and requalification. This raises non-recurring engineering cost and slows second sourcing, particularly for custom industrial or medical sensors. Pure-play foundries reduce the barrier, but customers still need stable design rules, specialized masks and long process-development cycles before production yield becomes commercially acceptable.
Calibration and packaging cost
The mechanical structure is only part of a MEMS product’s value. Package stress, temperature, humidity and mounting can alter sensor output, so high-performance devices require calibration and compensation after assembly. Automotive and aerospace products may need multi-temperature test and long reliability qualification, while microphones and pressure sensors require application-specific acoustic or media exposure. These backend steps add cost and test time, meaning wafer-level yield improvements alone do not guarantee lower final sensor cost. Suppliers must optimize assembly and calibration together with the MEMS die.
Consumer price pressure
Smartphone and wearable OEMs purchase very large volumes and expect continuous cost reduction, creating intense pressure on mainstream accelerometer, gyroscope and environmental-sensor pricing. Suppliers need scale, automated calibration and package integration to protect margins as functionality rises. Embedded algorithms can differentiate premium products, but customers may switch suppliers when performance converges and qualification is manageable. The strongest defense is a broad platform that combines hardware, software and application support so the sensor becomes more deeply integrated into the OEM’s product architecture than a simple interchangeable component.
Qualification barriers
Automotive, medical, industrial and aerospace sensors require extensive validation before adoption because failure can affect safety, navigation or long equipment lifetimes. Changing a MEMS process, package or manufacturing site can trigger requalification even if nominal electrical specifications remain unchanged. This makes capacity expansion slower and can limit a customer’s willingness to adopt a second source. Suppliers benefit from sticky design wins once qualified, but new entrants face a long path from sample performance to production revenue, especially in safety-related systems governed by AEC-Q or functional-safety expectations.
Market Opportunities
Automotive safety and navigation
Vehicles are adding more inertial, pressure and environmental sensing while demanding stronger functional-safety and cybersecurity integration. Higher-value IMUs can support dead reckoning, chassis control and assisted driving when GNSS or camera data are unreliable. TDK’s automotive-grade IMU portfolio and ST’s qualified motion sensors demonstrate active supplier investment. Future opportunities include redundant sensing, domain-controller integration and smarter diagnostics that monitor sensor health over vehicle life. These features can increase semiconductor value even as basic accelerometer functions become more standardized and cost-competitive.
Industrial smart sensors
Industrial customers increasingly want modules that combine vibration sensing, embedded processing and connectivity rather than raw sensor outputs. A MEMS accelerometer or microphone can perform local anomaly detection and send only meaningful events, reducing network bandwidth and central processing. Suppliers with low-noise devices, long lifecycle and reference algorithms can therefore move up the value chain from components to condition-monitoring platforms. This opportunity is especially attractive in motors, pumps, fans and factory equipment where early failure detection can create savings far greater than the cost of the sensor node.
Custom MEMS foundry services
Many emerging optical, biomedical, microfluidic and resonant sensors have attractive performance but insufficient volume to justify a dedicated fab. Pure-play foundries such as Silex allow these companies to develop specialized structures using established micromachining, bonding and wafer-handling platforms. The opportunity grows as startups and system companies seek differentiated sensors without becoming semiconductor manufacturers. Foundries that provide design-for-manufacturing support, pilot production and a clear transfer path into 8-inch volume can capture long-lived programs and diversify beyond one high-volume consumer sensor cycle.
High-performance inertial systems
MEMS technology continues moving into navigation applications that historically required larger mechanical or fiber-optic gyroscopes. Analog Devices and Honeywell supply calibrated IMUs with stronger bias stability and environmental performance for industrial and aerospace use. Improvements in MEMS structures, vacuum packaging and calibration can expand this addressable market into drones, autonomous equipment, precision agriculture and resilient navigation. The unit volumes are lower than smartphones, but average selling prices and customer lifetime are much higher, supporting attractive revenue if suppliers can meet demanding drift and reliability specifications.
Supply Chain Analysis
Micromachining, materials and device structures
Etch, deposition, bonding and cavity formation
Signal conditioning, wafer-level packaging and module assembly
Temperature test, algorithms, qualification and system software
MEMS process development
Every MEMS device begins with a mechanical structure whose dimensions, materials and damping determine sensitivity, bandwidth and noise. Accelerometers use proof masses and springs, pressure sensors use diaphragms, and microphones use acoustic membranes. Design must consider the fabrication process from the beginning because etch depth, release behavior and residual stress directly affect performance. Foundry design rules are therefore more coupled to product architecture than in conventional digital logic, making process-device co-development a central part of the MEMS supply chain.
Wafer fabrication
MEMS fabs rely on deep reactive-ion etching, thin-film deposition, wafer bonding, cavity formation and specialized materials in addition to conventional lithography. Device wafers may be bonded to cap wafers under vacuum or controlled atmosphere, creating sealed reference cavities for gyroscopes or pressure sensors. Yield depends on mechanical as well as electrical defects, so metrology must monitor geometry and stress. Larger wafer sizes can improve economics, but moving a MEMS process from 6-inch to 8-inch production requires significant redevelopment and customer qualification.
ASIC & packaging
Most commercial MEMS sensors combine a mechanical die with a CMOS ASIC that provides drive circuitry, analog front ends, calibration memory, digital interfaces and increasingly embedded processing. Co-packaging reduces board area but creates thermal and mechanical stress that can shift the sensor output. Wafer-level packaging and through-silicon connections can lower size and cost at volume. Suppliers with internal ASIC and package expertise can optimize the complete sensor, while fabless MEMS companies rely on close coordination among foundry, ASIC and assembly partners.
Calibration & integration
Final performance is shaped by calibration, temperature compensation and software. High-volume consumer sensors use automated test to correct bias and scale factor, while industrial and aerospace IMUs may require extensive multi-axis and multi-temperature calibration. Automotive products add traceability and safety documentation. Embedded sensor fusion can combine accelerometer, gyroscope, magnetometer or pressure data into higher-level outputs. This downstream engineering layer increasingly determines customer value because a calibrated, intelligent module can shorten OEM development time far more than a bare MEMS element with slightly better nominal sensitivity.
Recent Developments
2026 — Silex expands U.S. MEMS manufacturing footprint
Silex announced expansion through a U.S. fab acquisition, strengthening geographic diversity for pure-play MEMS manufacturing. Source
Current — ST maintains broad MEMS technology and automotive portfolio
ST highlights more than 20 billion MEMS sensors shipped and broad consumer, automotive and industrial applications. Source
Current — TDK offers automotive-grade inertial sensors
IAM-20689 targets automotive motion sensing with qualification and safety-oriented positioning. Source
Report Scope & Segmentation
| Attribute | Coverage |
|---|---|
| Market | MEMS (Micro-Electromechanical System) Sensor |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| 2025 Market Size | USD 1.714 billion |
| 2026 Estimated Size | USD 1.848 billion |
| 2034 Forecast Size | USD 3.370 billion |
| CAGR | 7.8% (2026–2034) |
| By Type | Optical Sensors, Mechanical Sensors, Chemical Sensors, Biological Sensors, Thermal Sensors, Other |
| By Application | Consumer Electronics, Automotive, Industrial, Aerospace and Defense, Healthcare, Telecommunication, Others |
| By Sensing Modality | Inertial Motion, Pressure & Environmental, Acoustic, Optical / Thermal |
| By Integration Level | Discrete MEMS Sensor, Sensor + ASIC, Smart Sensor Module |
| By End User | Consumer Device OEMs, Automotive Tier 1s & OEMs, Industrial Equipment Makers, Aerospace & Defense Integrators |
| Regions | Asia Pacific, North America, Europe, South America, Middle East & Africa |
| Companies Profiled | Bosch Sensortec, STMicroelectronics, TDK InvenSense, Analog Devices, Honeywell, Infineon Technologies, Knowles, Silex Microsystems, Sensata Technologies |
Frequently Asked Questions
What is the MEMS sensor market size in 2025?
The market is valued at USD 1.714 billion in 2025.
What is the projected market size by 2034?
The market is projected to reach USD 3.370 billion by 2034.
What is the CAGR from 2026 to 2034?
The market is expected to expand at a 7.8% CAGR.
Which region leads the market?
Asia Pacific is the largest regional market in 2025.
Which type leads the market?
Mechanical Sensors is the leading type.
Which application leads demand?
Consumer Electronics is the leading application.
What is the main growth driver?
consumer, automotive, industrial and wearable systems continue to increase the number and sophistication of motion, pressure, acoustic and environmental sensors.
What is the principal restraint?
MEMS process specialization, calibration, packaging and long qualification cycles raise development cost and make second sourcing difficult for custom devices.
Where are the strongest opportunities?
automotive safety sensing, low-power smart IMUs, MEMS microphones, industrial condition monitoring and custom foundry manufacturing.
Which companies are active in the market?
Bosch Sensortec, STMicroelectronics, TDK InvenSense, Analog Devices, Honeywell, Infineon Technologies, Knowles, Silex Microsystems.
Research Sources & Evidence Base
View primary, official and technical evidence used in this overview
- Bosch Sensortec: MEMS Technology Overview — MEMS manufacturing, application history and sensor technology context.
- Bosch Sensortec: Sensor Product Portfolio — Motion, pressure, magnetic, gas and smart-sensor product coverage.
- STMicroelectronics: MEMS Technology — Shipment scale, MEMS platform history and application breadth.
- STMicroelectronics: MEMS and Sensor Documentation — Current technical documentation across motion and environmental sensors.
- TDK InvenSense: Sensor Portfolio — Consumer, industrial and automotive motion-sensing portfolio.
- TDK InvenSense: SmartMotion Inertial Sensors — Accelerometer, gyroscope and IMU technology across applications.
- TDK InvenSense: IAM-20689 Automotive IMU — Automotive-grade inertial sensing and safety-oriented use.
- Analog Devices: ADIS16487 Precision IMU — High-performance calibrated inertial sensing for industrial and navigation applications.
- Honeywell Aerospace: HG4930 MEMS IMU — Aerospace-grade MEMS inertial measurement and navigation use.
- Infineon Technologies: MEMS Microphones — MEMS microphone architecture and consumer/IoT applications.
- Knowles: SiSonic MEMS Microphones — Wearable and high-performance acoustic MEMS development.
- Silex Microsystems: MEMS Foundry — Pure-play MEMS foundry services, wafer processing and volume manufacturing.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF