
Key Statistics
Key Takeaways
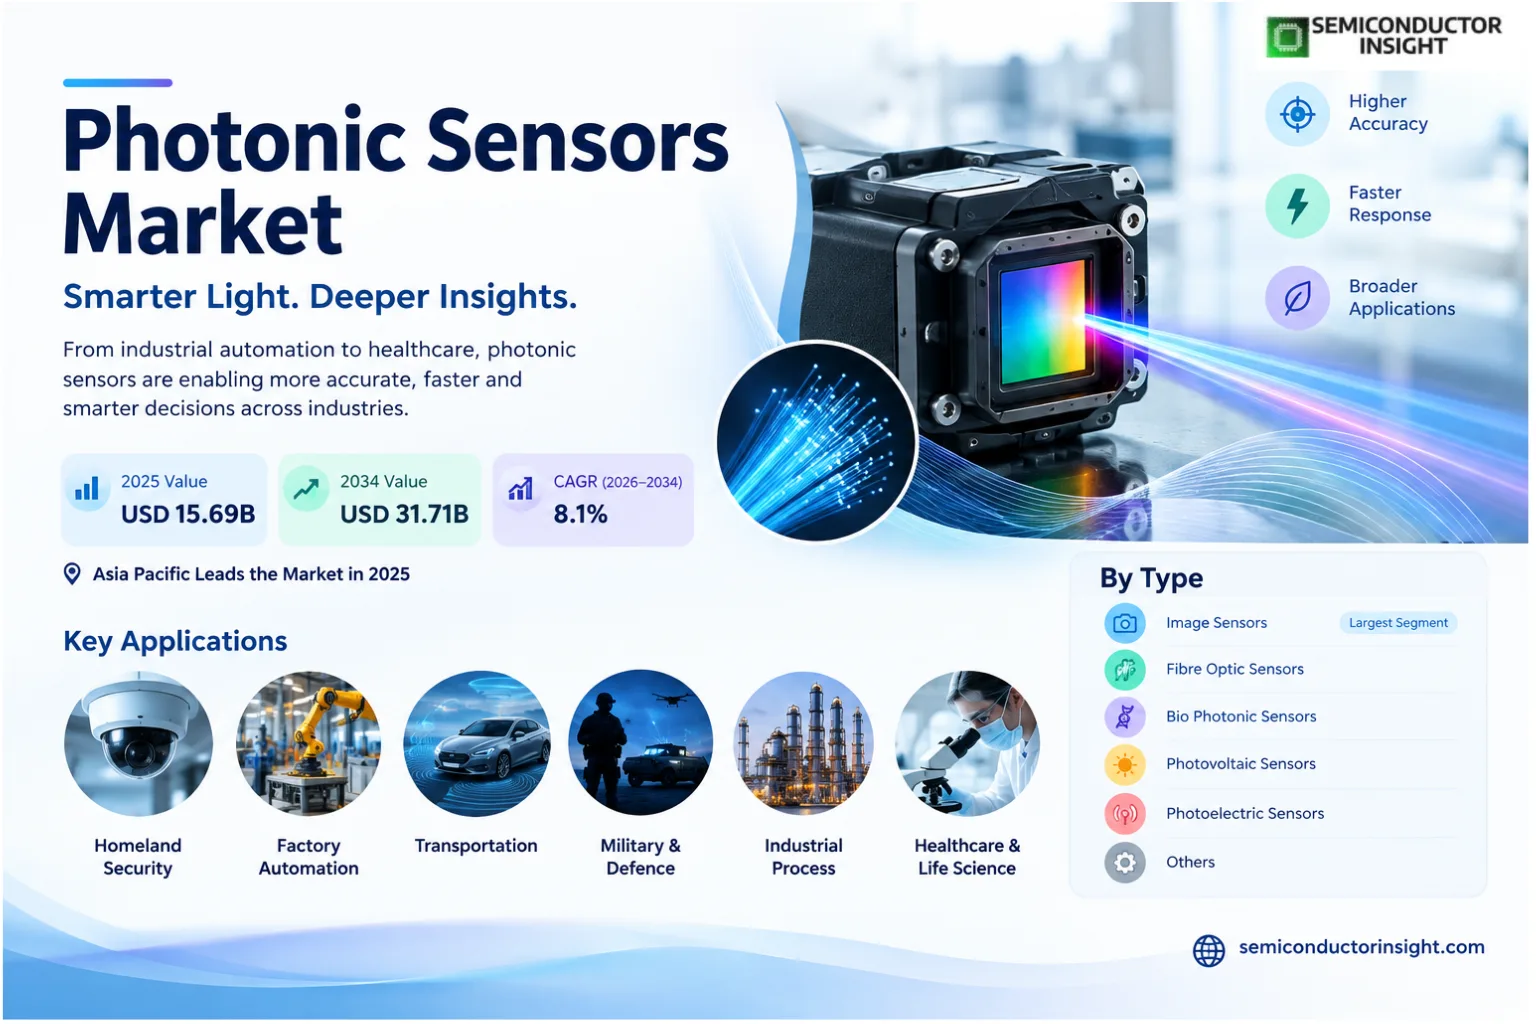
- Market scale: Photonic Sensors was valued at USD 15.69 billion in 2025 and is projected to reach USD 31.71 billion by 2034, with a 8.1% CAGR over 2026–2034.
- Image Sensors leads by type because machine vision, consumer imaging, scientific measurement and automotive perception create the broadest revenue base.
- Factory Automation is the largest application because machine vision, counting, positioning and inspection require large numbers of optical sensors across automated production.
- Asia Pacific is the largest regional market, while Asia Pacific has the strongest incremental growth profile.
- Growth driver: Automation, machine vision, automotive sensing and medical photonics are increasing the number and value of optical sensing functions
- Restraint: Optical noise, calibration requirements and specialized packaging can raise system cost and qualification effort
Photonic Sensors Market Overview
Photonic Sensors market was valued at USD 15.69 billion in 2025 and is projected to reach USD 31.71 billion by 2034, expanding at a 8.1% CAGR during 2026–2034. Asia Pacific leads the market in 2025.
Photonic sensors measure physical, chemical or biological conditions through the interaction of light with a target or environment. The category spans image sensors, photodiodes, fiber-optic sensors, photon-counting devices, photoelectric sensors and detectors covering ultraviolet, visible, infrared and other spectral regions.
The market includes both scaled semiconductor products and highly specialized modules. High-volume image and photoelectric sensors benefit from manufacturing scale, while scientific, medical and aerospace devices compete on sensitivity, wavelength response, noise, timing and qualification.
Current optical sensor portfolios illustrate increasing integration of detectors with signal processing, modules and application-ready packaging. This reduces customer design effort and expands supplier value beyond a bare sensing element.
Segment Analysis: By Type
By type, the market is segmented into Image Sensors, Fibre Optic Sensors, Bio Photonic Sensors, Photovoltaic Sensors, Photoelectric Sensors, Others. Image Sensors holds the leading position.
| Type | Market role | Commercial position |
|---|---|---|
| Image Sensors | Spatial optical imaging using CCD, CMOS and related architectures. | Largest segment across industrial, consumer, scientific and automotive use. |
| Fibre Optic Sensors | Measures strain, temperature, pressure or other variables through optical fibers. | Strong in distributed and electromagnetically noisy environments. |
| Bio Photonic Sensors | Optical detection of biological or biochemical conditions. | High-value growth in diagnostics and life science. |
| Photovoltaic Sensors | Converts incident light into electrical output. | Established sensing and energy-related applications. |
| Photoelectric Sensors | Detects object presence, position or intensity. | Large automation installed base. |
| Others | Specialty detectors and modules. | Niche wavelengths and photon-counting applications. |
Commercial implications by type
Technology economics vary sharply by architecture. Image and photoelectric sensors benefit from scale, while fiber, SWIR and biophotonic devices can command higher value because they solve application-specific measurement problems.
Segment Analysis: By Application
By application, the market is segmented into Homeland Security, Factory Automation, Transportation, Military and Defence, Industrial Process, Others. Factory Automation is the largest demand pool.
| Application | Demand characteristics |
|---|---|
| Homeland Security | Imaging, spectroscopy and detection support perimeter and identification systems. |
| Factory Automation | Largest application across machine vision, counting and process control. |
| Transportation | Vehicles use image, distance and optical sensors for ADAS and control. |
| Military and Defence | Photonics supports surveillance, targeting, navigation and communications. |
| Industrial Process | Optical and fiber sensors improve process visibility and safety. |
| Others | Healthcare, research and consumer applications add diverse demand. |
By Sensing Principle
| Sensing Principle | Commercial relevance |
|---|---|
| Imaging | CMOS/CCD and related sensors convert spatial light information into electronic data. |
| Fiber / Interferometric | Optical-fiber methods measure phase, wavelength, intensity or scattering changes. |
| Spectroscopic | Spectral sensors identify material composition or concentration. |
| Photon Counting | APD, SPAD and SiPM devices detect very low light levels and timing events. |
By End-Use Industry
| End-Use Industry | Commercial relevance |
|---|---|
| Industrial | Automation and process control create broad recurring demand. |
| Consumer Electronics | Cameras and optical interfaces provide high-volume applications. |
| Automotive | ADAS and cabin sensing increase optical content per vehicle. |
| Healthcare & Life Science | Diagnostics and analytical instruments use high-value detectors. |
| Aerospace & Defense | Imaging, ranging and radiation applications require specialized components. |
Regional Analysis
Asia Pacific leads the market because the region combines high-volume electronics production, image-sensor manufacturing, automotive supply chains and aggressive factory automation. Asia Pacific is positioned for the strongest incremental growth.
How does regional demand differ across the Photonic Sensors market?
Regional demand reflects both sensor manufacturing and end-use deployment. Asia Pacific combines scale and supply-chain depth, North America is strong in medical, defense and scientific photonics, and Europe has substantial automation, automotive and precision-instrument demand.
| Region | Position | Growth outlook | Demand profile | Supplier selection |
|---|---|---|---|---|
| Asia Pacific | Largest | Highest | Manufacturing and volume | Performance, scale, cost |
| North America | Second | Strong | High-value applications | Performance and integration |
| Europe | Third | Moderate | Industrial and automotive | Precision and lifecycle |
| South America | Smaller | Selective | Industrial projects | Cost and service |
| Middle East & Africa | Emerging | Project-led | Infrastructure and security | Ruggedness and support |
Competitive Landscape
Competition spans diversified electronics companies, specialist photonics manufacturers and automation suppliers.
Hamamatsu Photonics offers photodiodes, APDs, SiPM/SPADs, image sensors, infrared detectors and radiation sensors across scientific and industrial applications.
Technology leadership is application-specific: image sensors, fiber sensors and photon-counting devices require different manufacturing and packaging capabilities.
Integration of detectors with front-end electronics, optics and calibrated modules is increasingly important because it reduces customer design burden and shortens qualification.
| Competitive tier | Representative participants | Competitive focus |
|---|---|---|
| Diversified leaders | Sony, Samsung, Honeywell, onsemi | Scaled image sensing and integrated semiconductor solutions |
| Photonics specialists | Hamamatsu, Teledyne, Luna Innovations | High-performance optical detection and specialty sensing |
| Automation specialists | Banner, Baumer, Omron | Application-ready industrial photoelectric sensing |
Companies Profiled
Honeywell International, Samsung, Toshiba, Mitsubishi Electric, Fujifilm, Hamamatsu Photonics, Banner Engineering, Baumer Holding, Omron Corporation, Analog Devices, Inc., onsemi, Teledyne Technologies, Sony Corporation, Luna Innovations
Production Capacity Analysis
Capacity depends on semiconductor detector fabrication, compound-semiconductor materials, optical packaging and calibrated module assembly.
High-volume image sensors benefit from CMOS scale, while InGaAs, APD and SiPM products require more specialized processes and packaging.
Module production adds lenses, filters, electronics and calibration, making automated test and characterization important to consistent field performance.
Market Dynamics
The market grows as optical sensing moves from simple detection toward richer embedded perception and measurement.
A photoelectric switch competes on cost and ruggedness, while image, spectral and photon-counting sensors compete on information content. This supports business models ranging from scaled semiconductor production to specialized modules sold with application engineering.
Market Drivers
Drivers Impact Analysis
| Driver | Impact | Commercial mechanism |
|---|---|---|
| Factory automation and machine vision | High | Automated inspection, robotics and process control require reliable optical detection. |
| Automotive optical sensing | High | ADAS and cabin monitoring increase optical sensing functions per vehicle. |
| Medical and analytical photonics | Medium | Diagnostics and spectroscopy favor low-noise, high-sensitivity detectors. |
| Photon-counting and low-light detection | Medium | SPAD and SiPM technologies enable LiDAR, scientific and medical applications. |
Factory automation and machine vision
Automated inspection, robotics and process control require reliable optical detection.
Automotive optical sensing
ADAS and cabin monitoring increase optical sensing functions per vehicle.
Medical and analytical photonics
Diagnostics and spectroscopy favor low-noise, high-sensitivity detectors.
Photon-counting and low-light detection
SPAD and SiPM technologies enable LiDAR, scientific and medical applications.
Market Restraints
Restraints Impact Analysis
| Restraint | Impact | Commercial mechanism |
|---|---|---|
| Optical noise and ambient interference | Medium | Stray light and temperature drift can degrade measurement quality. |
| Packaging and calibration cost | Medium | Precision alignment and calibration add cost. |
| Application-specific qualification | Medium | Medical, automotive and aerospace markets require long validation. |
| Competing sensing modalities | Low | Radar, ultrasonic and electrical sensors can be better suited to some tasks. |
Optical noise and ambient interference
Stray light and temperature drift can degrade measurement quality.
Packaging and calibration cost
Precision alignment and calibration add cost.
Application-specific qualification
Medical, automotive and aerospace markets require long validation.
Competing sensing modalities
Radar, ultrasonic and electrical sensors can be better suited to some tasks.
Market Opportunities
SWIR and multispectral sensing
Material identification and machine vision create opportunities beyond visible wavelengths.
SPAD and SiPM platforms
Photon-counting devices address LiDAR, time-of-flight and low-light measurement.
Distributed fiber sensing
Infrastructure and energy monitoring benefit from long-range optical sensing.
Integrated optical sensor modules
Combining detectors, optics and processing raises value per sensing function.
Supply Chain Analysis
Silicon, InGaAs, fibers, filters
CMOS, photodiodes, APD/SPAD
Optics, calibration, signal processing
Automation, medical, automotive, defense
Materials and wafers
Material choice determines wavelength response, noise and cost.
Device fabrication
Detector architecture determines quantum efficiency, dark current, gain and timing.
Packaging and modules
Optical alignment and calibration account for significant value in specialty products.
End-use integration
Customers evaluate the complete sensing chain, including optics, electronics and algorithms.
Recent Developments
2026 — Broad optical sensor portfolio
Hamamatsu’s current lineup spans photodiodes, APDs, SiPM/SPADs, image sensors, infrared, radiation and distance sensors. Source
2026 — Advanced image-sensor offering
Hamamatsu offers CCD, CMOS and NMOS image sensors for UV-VIS-NIR industrial and scientific measurement. Source
2026 — High-speed silicon photodiodes
Current silicon photodiode families include high-speed and broad spectral-response devices. Source
Report Scope & Segmentation
| Attribute | Coverage |
|---|---|
| Market | Photonic Sensors |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| 2025 Market Size | USD 15.69 billion |
| 2026 Estimated Size | USD 16.97 billion |
| 2034 Forecast Size | USD 31.71 billion |
| CAGR | 8.1% (2026–2034) |
| By Type | Image Sensors, Fibre Optic Sensors, Bio Photonic Sensors, Photovoltaic Sensors, Photoelectric Sensors, Others |
| By Application | Homeland Security, Factory Automation, Transportation, Military and Defence, Industrial Process, Others |
| By Sensing Principle | Imaging, Fiber / Interferometric, Spectroscopic, Photon Counting |
| By End-Use Industry | Industrial, Consumer Electronics, Automotive, Healthcare & Life Science, Aerospace & Defense |
| Regions | North America, Europe, Asia Pacific, South America, Middle East & Africa |
| Companies Profiled | Honeywell International, Samsung, Toshiba, Mitsubishi Electric, Fujifilm, Hamamatsu Photonics, Banner Engineering, Baumer Holding, Omron Corporation, Analog Devices, Inc., onsemi, Teledyne Technologies, Sony Corporation, Luna Innovations |
Frequently Asked Questions
What is the Photonic Sensors market size in 2025?
The market is valued at USD 15.69 billion in 2025.
What is the projected Photonic Sensors market size by 2034?
The market is projected to reach USD 31.71 billion by 2034.
What is the CAGR from 2026 to 2034?
The market is expected to expand at a 8.1% CAGR.
Which region leads the Photonic Sensors market?
Asia Pacific is the largest market in 2025.
What is the leading type?
Image Sensors is the leading type.
What is the leading application?
Factory Automation is the largest application segment.
What is a major growth driver?
Automation, machine vision, automotive sensing and medical photonics are increasing the number and value of optical sensing functions.
What is a major restraint?
Optical noise, calibration requirements and specialized packaging can raise system cost and qualification effort.
Where are the strongest opportunities?
SPAD/SiPM sensing, SWIR imaging, distributed fiber sensing and integrated optical modules.
Which companies are active in the market?
Honeywell International, Samsung, Toshiba, Mitsubishi Electric, Fujifilm, Hamamatsu Photonics, Banner Engineering, Baumer Holding.
Research Sources & Evidence Base
View primary and industry evidence used in this overview
- Hamamatsu Photonics: Optical sensors portfolio — Detector categories and application breadth.
- Hamamatsu Photonics: CCD / CMOS / NMOS image sensors — Image-sensor technology context.
- Hamamatsu Photonics: Si photodiodes — Silicon photodiode performance context.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF


Be the first to review “Photonic Sensors Market Size, Share & amp; Industry Analysis, By Type (Image Sensors, Fibre Optic Sensors, Bio Photonic Sensors, Photovoltaic Sensors, Photoelectric Sensors, Others), By Application (Homeland Security, Factory Automation, Transportation, Military and Defence, Industrial Process, Others), By Sensing Principle (Imaging, Fiber / Interferometric, Spectroscopic, Photon Counting), By End-Use Industry (Industrial, Consumer Electronics, Automotive, Healthcare & Life Science, Aerospace & Defense), and Regional Forecast, 2026-2034”