SEMICONDUCTOR INSIGHT
MARKET RESEARCH REPORT

Industrial Machine Vision Market

2026 to 2034
MARKET INTELLIGENCE
ACROSS KEY REGIONS
2026 EDITION
ARTIFICIAL INTELLIGENCE Semiconductor Market Research

Industrial Machine Vision Market

Size, Share & Industry Analysis, By Type (PC-Based, Smart Camera-Based), By Application (Automotive, Medical, Industrial Manufacturing, Utilities, Logistics), By Vision Dimension (2D, 3D, Hyperspectral/Other), By Component (Camera/Sensor, Optics & Lighting, Vision Controller, Software), and Regional Forecast, 2026-2034

◷
UPDATED 08 October 2026
▤
REPORT LENGTH Detailed Report
▣
REPORT CODE afe782c6ca6a
▯
FORMATS PDF

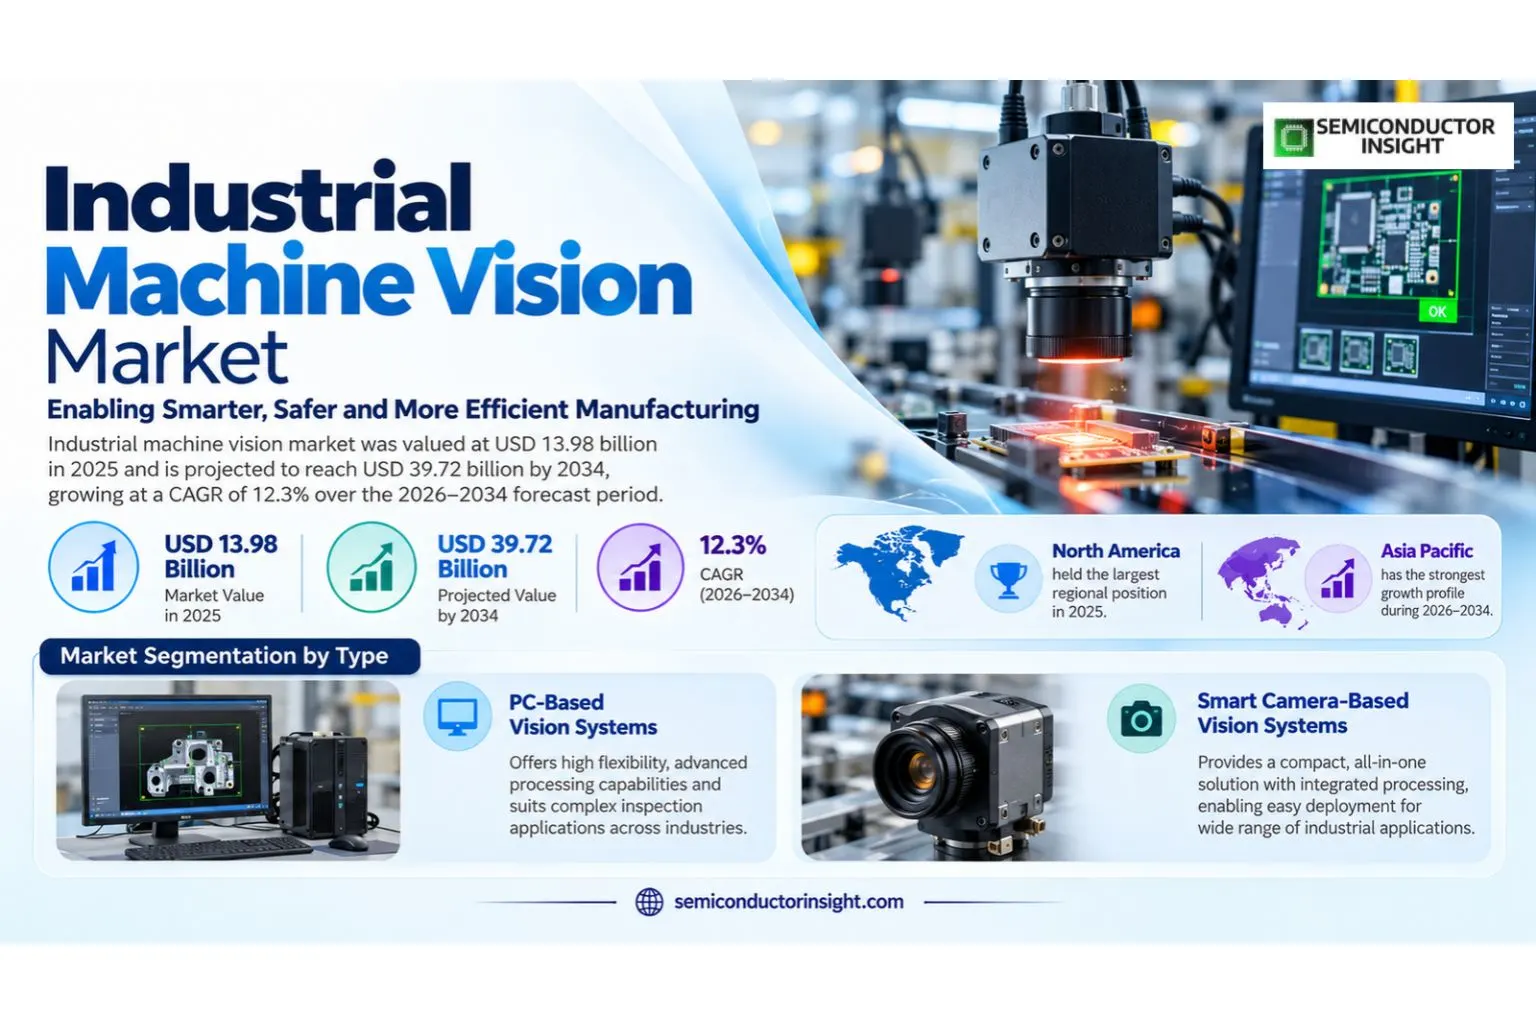
Industrial machine vision market was valued at USD 13.98 billion in 2025 and is projected to reach USD 39.72 billion by 2034, growing at a CAGR of 12.3% over the 2026–2034 forecast period. North America held the largest regional position in 2025, while Asia Pacific has the strongest growth profile.

Get the sample PDF with study scope, segmentation and methodology details.

Key Statistics

2025 Market Size
USD 13.98 billion
2034 Projected Market Size
USD 39.72 billion
CAGR (2026–2034)
12.3%
Largest Market in 2025
North America

Key Takeaways

  • PC-Based Vision Systems is a leading product category because it addresses the largest current application base.
  • Automotive is a major application, with demand shaped by performance, reliability and system integration.
  • North America leads current market value, while Asia Pacific provides the strongest growth profile.
  • Edge ai, easier model training and combined 2d/3d robotic perception is the main technology direction influencing new design wins.
  • Market size and growth: USD 13.98 billion in 2025 is projected to reach USD 39.72 billion by 2034 at a 12.3% CAGR during 2026–2034.

Industrial Machine Vision Market Overview

Industrial machine vision market was valued at USD 13.98 billion in 2025 and is projected to reach USD 39.72 billion by 2034, growing at a CAGR of 12.3% over the 2026–2034 forecast period. North America held the largest regional position in 2025, while Asia Pacific has the strongest growth profile.

Base year: 2025 · Estimated year: 2026 · Forecast period: 2026–2034 · Historical data: 2021–2025 · Values in USD

The industrial machine vision market industrial machine vision combines cameras, optics, lighting and image-processing software to automate inspection, measurement, identification, robot guidance and quality-control tasks in manufacturing and distribution. Commercial decisions in the Industrial Machine Vision market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.

The global market was valued at USD 12.45 billion in 2024 and is projected to reach USD 24.85 billion by 2030 at a 12.3% CAGR. Manufacturing quality control held 45% share in 2023 in the client evidence, showing how strongly the market is tied to automated inspection.

Cognex’s 2026 research across more than 500 manufacturers, integrators and OEMs found 57% already use AI in machine vision and another 30% plan near-term deployment. Its April 2026 In-Sight 6900 controller uses NVIDIA Jetson technology for edge AI processing without an external PC. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.

Segment Analysis: By Type

By type, the industrial machine vision market is segmented into PC-Based Vision Systems, Smart Camera-Based Vision Systems. Each category has a distinct functional role and commercial position, so the analysis emphasizes use case, integration and competitive relevance rather than repeating a single market statistic across every row. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.

Type Function Market position
PC-Based Vision Systems PC-Based Vision Systems addresses a distinct architecture or performance requirement within the Industrial Machine Vision market. Commercial demand depends on application fit, qualification, cost and lifecycle requirements rather than a single headline statistic.
Smart Camera-Based Vision Systems Smart Camera-Based Vision Systems addresses a distinct architecture or performance requirement within the Industrial Machine Vision market. Commercial demand depends on application fit, qualification, cost and lifecycle requirements rather than a single headline statistic.

Pricing by type

Smart cameras are priced as integrated systems, while PC-based architectures can scale to more cameras and higher compute. 3D, hyperspectral and AI-enabled systems command premiums because sensors, optics and software increase solution value. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.

Segment Analysis: By Application

By application, the market is segmented into Automotive, Medical, Industrial Manufacturing, Utilities, Logistics. Application economics differ by qualification, lifecycle, reliability and system-level value, so each row below uses context specific to that application rather than mechanically repeating headline evidence. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.

Application Demand characteristics
Automotive Automotive creates demand where industrial machine vision improves integration, performance, reliability or system economics.
Medical Medical creates demand where industrial machine vision improves integration, performance, reliability or system economics.
Industrial Manufacturing Industrial Manufacturing creates demand where industrial machine vision improves integration, performance, reliability or system economics.
Utilities Utilities creates demand where industrial machine vision improves integration, performance, reliability or system economics.
Logistics Logistics creates demand where industrial machine vision improves integration, performance, reliability or system economics.

Regional Analysis

North America is used as the largest current market because the United States alone was valued at USD 3.85 billion in 2024, equal to roughly 31% of the global total before Canada and Mexico are included. Asia Pacific has the strongest growth outlook through electronics, automotive and factory automation investment.

How does regional demand differ across the industrial machine vision market?

Europe remains a large automation market led by Germany and Italy, while Asia Pacific is scaling machine vision rapidly across semiconductors, batteries and electronics. North America combines high software value with a large installed base in logistics and manufacturing. Commercial decisions in the Industrial Machine Vision market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.

Region Position Growth outlook Demand profile What decides supplier selection
Asia Pacific Fastest-growing Highest Electronics/automation led Integration and skills
North America Largest High Software/automation led AI usability and ROI
Europe Large Moderate-high Automotive/industrial led Integration and engineering cost
South America Emerging High from smaller base Industrialization led Cost and integration
Middle East & Africa Emerging Moderate Logistics/industrial led Integrator availability

Asia Pacific FASTEST-GROWING

What shapes demand in Asia Pacific?

Asia Pacific is the fastest-growing region as China, Japan, South Korea, India and Southeast Asia expand automation, electronics and EV production. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.

Market positionFastest-growing
Growth outlookHighest
Demand profileElectronics/automation led
Market access gateIntegration and skills
Country Position in region What drives demand
China Largest regional volume Electronics, batteries and general manufacturing.
Japan High-spec Robotics, automotive and precision manufacturing.
South Korea Semiconductor led Electronics and wafer inspection.
India High growth Factory automation and quality-control adoption.
Market instances

  • Electronics manufacturing creates dense inspection points. PCB, semiconductor and battery lines use vision repeatedly across process steps.
  • AI lowers deployment barriers. Easier training can expand use beyond specialist vision engineers.
In the full report: country-level market size, segment revenue, supplier analysis and forecast detail across 2021–2034.

North America LARGEST REGION

What shapes demand in North America?

North America leads current value through a large U.S. installed base in manufacturing, logistics, automotive and packaging. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.

Market positionLargest
Growth outlookHigh
Demand profileSoftware/automation led
Market access gateAI usability and ROI
Country Position in region What drives demand
United States Dominant USD 3.85 billion market value in 2024 in the client evidence.
Canada Established Automotive, food and industrial automation.
Mexico Manufacturing hub Automotive and electronics assembly.
Market instances

  • Cognex reports more than 30,000 customers worldwide. North America remains central to its software-rich machine vision ecosystem.
  • AI deployment is accelerating. Cognex’s 2026 survey found 57% of respondents already use AI in machine vision and another 30% plan near-term deployment.
In the full report: country-level market size, segment revenue, supplier analysis and forecast detail across 2021–2034.

Europe LARGE REGION

What shapes demand in Europe?

Europe has deep machine-vision adoption in automotive, machinery, pharmaceuticals, food and packaging. Commercial decisions in the Industrial Machine Vision market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.

Market positionLarge
Growth outlookModerate-high
Demand profileAutomotive/industrial led
Market access gateIntegration and engineering cost
Country Position in region What drives demand
Germany Largest Automotive and industrial automation.
Italy Machine-building led Packaging, machinery and factory automation.
France Industrial Automotive, aerospace and food inspection.
United Kingdom High-value Pharma, logistics and advanced manufacturing.
Market instances

  • Machine builders drive embedded vision demand. Inspection is often integrated directly into production equipment.
  • 3D and AI vision expand addressable tasks. Bin picking and complex surface inspection are important growth areas.
In the full report: country-level market size, segment revenue, supplier analysis and forecast detail across 2021–2034.

South America

What shapes demand in South America?

South America is led by Brazil, where automotive, food and beverage and industrial automation create the largest demand base. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.

Market positionEmerging
Growth outlookHigh from smaller base
Demand profileIndustrialization led
Market access gateCost and integration
Country Position in region What drives demand
Brazil Largest Automotive, food and industrial automation.
Argentina Niche Food, packaging and industrial inspection.
Rest of region Smaller Project-based automation.
Market instances

  • Labor productivity is a core business case. Vision can automate repetitive inspection and traceability tasks.
  • Integrator capability is critical. Customers often need local support for optics, lighting and line integration.
In the full report: country-level market size, segment revenue, supplier analysis and forecast detail across 2021–2034.

Middle East & Africa EMERGING

What shapes demand in Middle East & Africa?

The Middle East & Africa is a smaller market with demand in logistics, food, packaging, energy and selected manufacturing hubs. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment. Commercial decisions in the Industrial Machine Vision market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.

Market positionEmerging
Growth outlookModerate
Demand profileLogistics/industrial led
Market access gateIntegrator availability
Country Position in region What drives demand
UAE Logistics led Warehousing and high-throughput distribution.
Saudi Arabia Industrial growth Manufacturing localization and logistics.
South Africa Established niche Automotive, food and industrial inspection.
Market instances

  • Logistics is a strong entry application. Barcode reading, dimensioning and package inspection can deliver clear ROI.
  • Manufacturing localization creates future upside. New factories can adopt machine vision at commissioning rather than retrofit.
In the full report: country-level market size, segment revenue, supplier analysis and forecast detail across 2021–2034.

Key Industrial Machine Vision Manufacturers and Competitive Landscape

The competitive landscape includes Cognex, KEYENCE, Basler, OMRON, Teledyne Technologies, SICK, MVTec Software, JAI, Baumer, National Instruments. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.

Competition centers on edge AI, easier model training and combined 2D/3D robotic perception, customer qualification, manufacturing consistency and application support. Once a product is designed into a long-lifecycle system, switching costs can protect incumbent positions but also raise the importance of roadmap continuity. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.

Tier structure

Tier Companies Basis of competition
Tier 1 Cognex, KEYENCE, Basler, OMRON Global scale, broad customer qualification and advanced technology portfolios.
Tier 2 Teledyne Technologies, SICK, MVTec Software, JAI Strong specialist capability, regional design wins and application-focused portfolios.
Tier 3 Regional and niche suppliers Cost competition, customization and specialized customer support.

Key companies profiled

  • Cognex
  • KEYENCE
  • Basler
  • OMRON
  • Teledyne Technologies
  • SICK
  • MVTec Software
  • JAI
  • Baumer
  • National Instruments

Industrial Machine Vision Production Capacity Analysis

Production capacity in the Industrial Machine Vision market is shaped by the underlying manufacturing process, qualification burden and customer-specific configuration. Suppliers must balance equipment utilization with quality control because high-volume output only creates value when yield, reliability and traceability remain stable. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.

Capacity additions tend to follow customer program ramps rather than headline market growth alone. Regional supply resilience is becoming more important, particularly where customers require second-source planning, long product lifecycles or shorter engineering-response times. Commercial decisions in the Industrial Machine Vision market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.

The practical bottleneck is often qualified output rather than nominal installed capacity. Manufacturing, assembly, test and application support must scale together to avoid creating capacity that cannot be used in production programs. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.

Industrial Machine Vision Market Dynamics: Drivers, Restraints and Opportunities

The Industrial Machine Vision market is shaped by growth is driven by automated quality control, labor shortages, ev and battery manufacturing, semiconductor inspection, logistics automation and easier deployment of ai-based inspection. At the same time, growth is constrained by integration cost, lighting and optics complexity, shortage of vision expertise, cybersecurity concerns and difficulty maintaining models across changing production conditions. The strongest commercial opportunities are concentrated in ai smart cameras, 3d robotic perception, hyperspectral inspection and software that reduces setup time create the strongest opportunities.

MARKET DRIVERS

Drivers Impact Analysis*

Driver (~) % impact on CAGR forecast Geographic relevance Impact timeline
Technology upgrade cycle +1.6% Global; strongest in leading adopter markets Near to medium term
End-market expansion +1.2% Application-specific Near term
Higher value per system +0.8% Premium and advanced systems Medium term

Technology adoption expands addressable demand

Growth is driven by automated quality control, labor shortages, EV and battery manufacturing, semiconductor inspection, logistics automation and easier deployment of AI-based inspection. This demand is strongest where customers can measure a clear improvement in system performance, footprint, energy efficiency, reliability or operating cost. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.

End-market modernization increases content per system

The technology upgrade cycle supports replacement and redesign activity as OEMs move to higher-performance architectures. New designs typically create the best opportunity because suppliers can influence specifications before qualification is locked. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.

Higher-value architectures support premium mix

Expanding end markets also increase content per system, creating value growth even when unit shipments grow more slowly. Suppliers that combine engineering support with reliable supply are better positioned to capture those design transitions. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.

MARKET RESTRAINTS

Restraints Impact Analysis*

Restraint (~) % impact on CAGR forecast Geographic relevance Impact timeline
Qualification and integration burden -0.7% Global Ongoing
Price and substitution pressure -0.5% Cost-sensitive applications Ongoing
Supply-chain or process complexity -0.4% Global Medium term

Qualification burden slows supplier switching

Growth is constrained by integration cost, lighting and optics complexity, shortage of vision expertise, cybersecurity concerns and difficulty maintaining models across changing production conditions. These constraints are most significant where customers have qualified alternatives or where the technology must prove a clear system-level advantage over lower-cost incumbent solutions. Commercial decisions in the Industrial Machine Vision market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.

Price competition limits margin expansion

Qualification and integration can extend sales cycles because customers must validate performance, reliability and compatibility in their own system environment. That makes early engineering engagement important for new suppliers. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.

Alternative technologies constrain selected use cases

Supply-chain complexity can also limit growth when specialized materials, tooling, test or regional support are required. Customers increasingly evaluate resilience alongside price when choosing long-lifecycle suppliers. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.

MARKET OPPORTUNITIES

Advanced integration creates premium opportunities

AI smart cameras, 3D robotic perception, hyperspectral inspection and software that reduces setup time create the strongest opportunities. The most attractive opportunities are where customers are redesigning systems rather than simply replacing like-for-like components. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.

Regional capacity and supply resilience

Edge ai, easier model training and combined 2d/3d robotic perception can create premium value when it lowers system complexity, improves performance or supports a new product architecture that is difficult to achieve with incumbent approaches. Commercial decisions in the Industrial Machine Vision market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.

Application engineering deepens customer value

Regional engineering support and application-specific customization provide another route to growth because customers increasingly expect suppliers to support qualification, transition planning and lifecycle management. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.

Industrial Machine Vision Supply Chain Analysis

Upstream. CMOS sensors, industrial cameras, optics, lighting, processors, GPUs, embedded controllers and machine-vision software form the upstream technology stack. Supply quality at this stage directly affects downstream yield, reliability and cost. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.

UpstreamElectromechanical relays, microcontrollers, passive components, moulded housings, DIN clips, terminal blocks
ManufacturingPCB assembly, housing moulding, calibration and functional test, approval marking
ChannelElectrical wholesalers, industrial distributors, catalogue houses, direct OEM supply
DownstreamPanel builders, machine OEMs, electrical contractors, facility maintenance, utilities

Manufacturing. Core production combines process control, assembly, inspection and test, with product-specific qualification used to verify performance before customer shipment. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment. Commercial decisions in the Industrial Machine Vision market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.

Distribution. High-value programs are typically won through direct OEM, Tier-1 or design-house engagement, while distributors serve prototypes, regional customers and lower-volume applications. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.

Downstream. End users integrate the product into systems where switching costs rise after qualification, making lifecycle support and supply continuity commercially important. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.

Downstream. Panel builders and machine OEMs are the primary specifying customers, followed by electrical contractors working on building services and by facility maintenance teams handling replacement. The specification decision is usually made once, at panel design, and then repeats for the life of the design — which makes design-in position considerably more valuable than any individual transaction.

Recent Developments in the Industrial Machine Vision Market

Developments tracked through September 2026. Items are selected for direct relevance to product technology, deployment or standards. Commercial decisions in the Industrial Machine Vision market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.

  • 2026 New Product
    Cognex launches In-Sight 6900 Cognex introduced a modular AI vision controller powered by NVIDIA Jetson for compute-intensive industrial inspection without external PCs. Source
  • 2026 Research
    Cognex AI vision survey Cognex reported that 57% of surveyed machine-vision users already deploy AI and another 30% plan near-term deployment. Source
  • 2026 M&A
    Cognex agrees to acquire RealSense Cognex announced an agreement to acquire RealSense, extending its machine-vision portfolio into 3D robotic perception. Source

REPORT SCOPE & SEGMENTATION

Attribute Details
Study Period 2021–2034
Base Year 2025
Estimated Year 2026
Forecast Period 2026–2034
Historical Period 2021–2025
Market Size 2025 USD 13.98 billion
Market Size 2034 USD 39.72 billion
Growth Rate CAGR of 12.3% from 2026–2034
Unit Value (USD Million)
Segmentation By Type, By Application, By Vision Dimension, By Component, and By Region
By Type PC-Based Vision Systems · Smart Camera-Based Vision Systems
By Application Automotive · Medical · Industrial Manufacturing · Utilities · Logistics
By Component Camera / Sensor · Optics & Lighting · Vision Controller · Software
By Vision Dimension 2D · 3D · Hyperspectral / Other
By Region Each region analysed by Type, Application and Country
North AmericaU.S., Canada, Mexico
EuropeGermany, France, U.K., Italy, Russia, Nordic Countries, Benelux
AsiaChina, Japan, South Korea, India, Southeast Asia
South AmericaBrazil, Argentina, Rest of South America
Middle East & AfricaTurkey, Israel, Saudi Arabia, UAE, Rest of MEA
Key Companies Profiled Cognex, KEYENCE, Basler, OMRON, Teledyne Technologies, SICK, MVTec Software, JAI, Baumer, National Instruments
Customization Scope Free report customization (equivalent to up to 4 analyst working days) with purchase. Addition or alteration to country, regional and segment scope.

Frequently Asked Questions

What is the current size of the Industrial Machine Vision market?

The market is valued at USD 13.98 billion in 2025 and is projected to reach USD 39.72 billion by 2034, expanding at a 12.3% CAGR during 2026–2034.

Which companies lead the Industrial Machine Vision market?

Key participants include Cognex, KEYENCE, Basler, OMRON, Teledyne Technologies, SICK, MVTec Software, JAI.

What is Industrial Machine Vision?

Industrial machine vision combines cameras, optics, lighting and image-processing software to automate inspection, measurement, identification, robot guidance and quality-control tasks in manufacturing and distribution.

What are the main product types?

The market includes PC-Based Vision Systems, Smart Camera-Based Vision Systems.

What are the key applications?

The principal applications are Automotive, Medical, Industrial Manufacturing, Utilities, Logistics.

Which region leads the market?

North America leads current market value, while Asia Pacific has the strongest growth profile.

What drives market growth?

Growth is driven by automated quality control, labor shortages, EV and battery manufacturing, semiconductor inspection, logistics automation and easier deployment of AI-based inspection.

What are the main challenges?

Growth is constrained by integration cost, lighting and optics complexity, shortage of vision expertise, cybersecurity concerns and difficulty maintaining models across changing production conditions.

Research Sources & Evidence Base
View research sources used for this overview
  1. Cognex. Investor Relations / Company Overview, current industrial machine vision company scale, technology and served-market context.
  2. KEYENCE. Machine Vision Systems, current 2D/3D industrial machine vision product and inspection context.
  3. Cognex. In-Sight 6900 Launch, 2026 edge-AI machine vision controller development.
Industrial Machine Vision Market Size, Share & Industry Analysis, By Type (PC-Based, Smart Camera-Based), By Application (Automotive, Medical, Industrial Manufacturing, Utilities, Logistics), By Vision Dimension (2D, 3D, Hyperspectral/Other), By Component (Camera/Sensor, Optics & Lighting, Vision Controller, Software), and Regional Forecast, 2026-2034

Get Sample Report PDF for Exclusive Insights

Report Sample Includes

  • Table of Contents
  • List of Tables & Figures
  • Charts, Research Methodology, and more...
Download Sample Report PDF

Download Sample Report

Table of Content

Table of Contents
1 Research Methodology and Statistical Scope
1.1 Market Definition and Statistical Scope of Industrial Machine Vision
1.2 Key Market Segments
1.2.1 Industrial Machine Vision Segment by Type
1.2.2 Industrial Machine Vision Segment by Application
1.3 Methodology & Sources of Information
1.3.1 Research Methodology
1.3.2 Research Process
1.3.3 Market Breakdown and Data Triangulation
1.3.4 Base Year
1.3.5 Report Assumptions & Caveats
2 Industrial Machine Vision Market Overview
2.1 Global Market Overview
2.1.1 Global Industrial Machine Vision Market Size (M USD) Estimates and Forecasts (2026-2034)
2.1.2 Global Industrial Machine Vision Sales Estimates and Forecasts (2026-2034)
2.2 Market Segment Executive Summary
2.3 Global Market Size by Region
3 Industrial Machine Vision Market Competitive Landscape
3.1 Global Industrial Machine Vision Sales by Manufacturers (2019-2024)
3.2 Global Industrial Machine Vision Revenue Market Share by Manufacturers (2019-2024)
3.3 Industrial Machine Vision Market Share by Company Type (Tier 1, Tier 2, and Tier 3)
3.4 Global Industrial Machine Vision Average Price by Manufacturers (2019-2024)
3.5 Manufacturers Industrial Machine Vision Sales Sites, Area Served, Product Type
3.6 Industrial Machine Vision Market Competitive Situation and Trends
3.6.1 Industrial Machine Vision Market Concentration Rate
3.6.2 Global 5 and 10 Largest Industrial Machine Vision Players Market Share by Revenue
3.6.3 Mergers & Acquisitions, Expansion
4 Industrial Machine Vision Industry Chain Analysis
4.1 Industrial Machine Vision Industry Chain Analysis
4.2 Market Overview of Key Raw Materials
4.3 Midstream Market Analysis
4.4 Downstream Customer Analysis
5 The Development and Dynamics of Industrial Machine Vision Market
5.1 Key Development Trends
5.2 Driving Factors
5.3 Market Challenges
5.4 Market Restraints
5.5 Industry News
5.5.1 New Product Developments
5.5.2 Mergers & Acquisitions
5.5.3 Expansions
5.5.4 Collaboration/Supply Contracts
5.6 Industry Policies
6 Industrial Machine Vision Market Segmentation by Type
6.1 Evaluation Matrix of Segment Market Development Potential (Type)
6.2 Global Industrial Machine Vision Sales Market Share by Type (2019-2024)
6.3 Global Industrial Machine Vision Market Size Market Share by Type (2019-2024)
6.4 Global Industrial Machine Vision Price by Type (2019-2024)
7 Industrial Machine Vision Market Segmentation by Application
7.1 Evaluation Matrix of Segment Market Development Potential (Application)
7.2 Global Industrial Machine Vision Market Sales by Application (2019-2024)
7.3 Global Industrial Machine Vision Market Size (M USD) by Application (2019-2024)
7.4 Global Industrial Machine Vision Sales Growth Rate by Application (2019-2024)
8 Industrial Machine Vision Market Segmentation by Region
8.1 Global Industrial Machine Vision Sales by Region
8.1.1 Global Industrial Machine Vision Sales by Region
8.1.2 Global Industrial Machine Vision Sales Market Share by Region
8.2 North America
8.2.1 North America Industrial Machine Vision Sales by Country
8.2.2 U.S.
8.2.3 Canada
8.2.4 Mexico
8.3 Europe
8.3.1 Europe Industrial Machine Vision Sales by Country
8.3.2 Germany
8.3.3 France
8.3.4 U.K.
8.3.5 Italy
8.3.6 Russia
8.4 Asia Pacific
8.4.1 Asia Pacific Industrial Machine Vision Sales by Region
8.4.2 China
8.4.3 Japan
8.4.4 South Korea
8.4.5 India
8.4.6 Southeast Asia
8.5 South America
8.5.1 South America Industrial Machine Vision Sales by Country
8.5.2 Brazil
8.5.3 Argentina
8.5.4 Columbia
8.6 Middle East and Africa
8.6.1 Middle East and Africa Industrial Machine Vision Sales by Region
8.6.2 Saudi Arabia
8.6.3 UAE
8.6.4 Egypt
8.6.5 Nigeria
8.6.6 South Africa
9 Key Companies Profile
9.1 Cognex
9.1.1 Cognex Industrial Machine Vision Basic Information
9.1.2 Cognex Industrial Machine Vision Product Overview
9.1.3 Cognex Industrial Machine Vision Product Market Performance
9.1.4 Cognex Business Overview
9.1.5 Cognex Industrial Machine Vision SWOT Analysis
9.1.6 Cognex Recent Developments
9.2 Basler
9.2.1 Basler Industrial Machine Vision Basic Information
9.2.2 Basler Industrial Machine Vision Product Overview
9.2.3 Basler Industrial Machine Vision Product Market Performance
9.2.4 Basler Business Overview
9.2.5 Basler Industrial Machine Vision SWOT Analysis
9.2.6 Basler Recent Developments
9.3 OMRON
9.3.1 OMRON Industrial Machine Vision Basic Information
9.3.2 OMRON Industrial Machine Vision Product Overview
9.3.3 OMRON Industrial Machine Vision Product Market Performance
9.3.4 OMRON Industrial Machine Vision SWOT Analysis
9.3.5 OMRON Business Overview
9.3.6 OMRON Recent Developments
9.4 KEYENCE Corporation
9.4.1 KEYENCE Corporation Industrial Machine Vision Basic Information
9.4.2 KEYENCE Corporation Industrial Machine Vision Product Overview
9.4.3 KEYENCE Corporation Industrial Machine Vision Product Market Performance
9.4.4 KEYENCE Corporation Business Overview
9.4.5 KEYENCE Corporation Recent Developments
9.5 National Instruments
9.5.1 National Instruments Industrial Machine Vision Basic Information
9.5.2 National Instruments Industrial Machine Vision Product Overview
9.5.3 National Instruments Industrial Machine Vision Product Market Performance
9.5.4 National Instruments Business Overview
9.5.5 National Instruments Recent Developments
9.6 Sony
9.6.1 Sony Industrial Machine Vision Basic Information
9.6.2 Sony Industrial Machine Vision Product Overview
9.6.3 Sony Industrial Machine Vision Product Market Performance
9.6.4 Sony Business Overview
9.6.5 Sony Recent Developments
9.7 Teledyne Technologies
9.7.1 Teledyne Technologies Industrial Machine Vision Basic Information
9.7.2 Teledyne Technologies Industrial Machine Vision Product Overview
9.7.3 Teledyne Technologies Industrial Machine Vision Product Market Performance
9.7.4 Teledyne Technologies Business Overview
9.7.5 Teledyne Technologies Recent Developments
9.8 Texas Instruments
9.8.1 Texas Instruments Industrial Machine Vision Basic Information
9.8.2 Texas Instruments Industrial Machine Vision Product Overview
9.8.3 Texas Instruments Industrial Machine Vision Product Market Performance
9.8.4 Texas Instruments Business Overview
9.8.5 Texas Instruments Recent Developments
9.9 Intel
9.9.1 Intel Industrial Machine Vision Basic Information
9.9.2 Intel Industrial Machine Vision Product Overview
9.9.3 Intel Industrial Machine Vision Product Market Performance
9.9.4 Intel Business Overview
9.9.5 Intel Recent Developments
9.10 Baumer Optronic
9.10.1 Baumer Optronic Industrial Machine Vision Basic Information
9.10.2 Baumer Optronic Industrial Machine Vision Product Overview
9.10.3 Baumer Optronic Industrial Machine Vision Product Market Performance
9.10.4 Baumer Optronic Business Overview
9.10.5 Baumer Optronic Recent Developments
9.11 tordivel
9.11.1 tordivel Industrial Machine Vision Basic Information
9.11.2 tordivel Industrial Machine Vision Product Overview
9.11.3 tordivel Industrial Machine Vision Product Market Performance
9.11.4 tordivel Business Overview
9.11.5 tordivel Recent Developments
9.12 ISRA VISION
9.12.1 ISRA VISION Industrial Machine Vision Basic Information
9.12.2 ISRA VISION Industrial Machine Vision Product Overview
9.12.3 ISRA VISION Industrial Machine Vision Product Market Performance
9.12.4 ISRA VISION Business Overview
9.12.5 ISRA VISION Recent Developments
9.13 MVTec Software
9.13.1 MVTec Software Industrial Machine Vision Basic Information
9.13.2 MVTec Software Industrial Machine Vision Product Overview
9.13.3 MVTec Software Industrial Machine Vision Product Market Performance
9.13.4 MVTec Software Business Overview
9.13.5 MVTec Software Recent Developments
9.14 SICK
9.14.1 SICK Industrial Machine Vision Basic Information
9.14.2 SICK Industrial Machine Vision Product Overview
9.14.3 SICK Industrial Machine Vision Product Market Performance
9.14.4 SICK Business Overview
9.14.5 SICK Recent Developments
9.15 JAI A/S
9.15.1 JAI A/S Industrial Machine Vision Basic Information
9.15.2 JAI A/S Industrial Machine Vision Product Overview
9.15.3 JAI A/S Industrial Machine Vision Product Market Performance
9.15.4 JAI A/S Business Overview
9.15.5 JAI A/S Recent Developments
10 Industrial Machine Vision Market Forecast by Region
10.1 Global Industrial Machine Vision Market Size Forecast
10.2 Global Industrial Machine Vision Market Forecast by Region
10.2.1 North America Market Size Forecast by Country
10.2.2 Europe Industrial Machine Vision Market Size Forecast by Country
10.2.3 Asia Pacific Industrial Machine Vision Market Size Forecast by Region
10.2.4 South America Industrial Machine Vision Market Size Forecast by Country
10.2.5 Middle East and Africa Forecasted Consumption of Industrial Machine Vision by Country
11 Forecast Market by Type and by Application (2025-2030)
11.1 Global Industrial Machine Vision Market Forecast by Type (2025-2030)
11.1.1 Global Forecasted Sales of Industrial Machine Vision by Type (2025-2030)
11.1.2 Global Industrial Machine Vision Market Size Forecast by Type (2025-2030)
11.1.3 Global Forecasted Price of Industrial Machine Vision by Type (2025-2030)
11.2 Global Industrial Machine Vision Market Forecast by Application (2025-2030)
11.2.1 Global Industrial Machine Vision Sales (K Units) Forecast by Application
11.2.2 Global Industrial Machine Vision Market Size (M USD) Forecast by Application (2025-2030)
12 Conclusion and Key FindingsList of Tables
Table 1. Introduction of the Type
Table 2. Introduction of the Application
Table 3. Market Size (M USD) Segment Executive Summary
Table 4. Industrial Machine Vision Market Size Comparison by Region (M USD)
Table 5. Global Industrial Machine Vision Sales (K Units) by Manufacturers (2019-2024)
Table 6. Global Industrial Machine Vision Sales Market Share by Manufacturers (2019-2024)
Table 7. Global Industrial Machine Vision Revenue (M USD) by Manufacturers (2019-2024)
Table 8. Global Industrial Machine Vision Revenue Share by Manufacturers (2019-2024)
Table 9. Company Type (Tier 1, Tier 2, and Tier 3) & (based on the Revenue in Industrial Machine Vision as of 2022)
Table 10. Global Market Industrial Machine Vision Average Price (USD/Unit) of Key Manufacturers (2019-2024)
Table 11. Manufacturers Industrial Machine Vision Sales Sites and Area Served
Table 12. Manufacturers Industrial Machine Vision Product Type
Table 13. Global Industrial Machine Vision Manufacturers Market Concentration Ratio (CR5 and HHI)
Table 14. Mergers & Acquisitions, Expansion Plans
Table 15. Industry Chain Map of Industrial Machine Vision
Table 16. Market Overview of Key Raw Materials
Table 17. Midstream Market Analysis
Table 18. Downstream Customer Analysis
Table 19. Key Development Trends
Table 20. Driving Factors
Table 21. Industrial Machine Vision Market Challenges
Table 22. Global Industrial Machine Vision Sales by Type (K Units)
Table 23. Global Industrial Machine Vision Market Size by Type (M USD)
Table 24. Global Industrial Machine Vision Sales (K Units) by Type (2019-2024)
Table 25. Global Industrial Machine Vision Sales Market Share by Type (2019-2024)
Table 26. Global Industrial Machine Vision Market Size (M USD) by Type (2019-2024)
Table 27. Global Industrial Machine Vision Market Size Share by Type (2019-2024)
Table 28. Global Industrial Machine Vision Price (USD/Unit) by Type (2019-2024)
Table 29. Global Industrial Machine Vision Sales (K Units) by Application
Table 30. Global Industrial Machine Vision Market Size by Application
Table 31. Global Industrial Machine Vision Sales by Application (2019-2024) & (K Units)
Table 32. Global Industrial Machine Vision Sales Market Share by Application (2019-2024)
Table 33. Global Industrial Machine Vision Sales by Application (2019-2024) & (M USD)
Table 34. Global Industrial Machine Vision Market Share by Application (2019-2024)
Table 35. Global Industrial Machine Vision Sales Growth Rate by Application (2019-2024)
Table 36. Global Industrial Machine Vision Sales by Region (2019-2024) & (K Units)
Table 37. Global Industrial Machine Vision Sales Market Share by Region (2019-2024)
Table 38. North America Industrial Machine Vision Sales by Country (2019-2024) & (K Units)
Table 39. Europe Industrial Machine Vision Sales by Country (2019-2024) & (K Units)
Table 40. Asia Pacific Industrial Machine Vision Sales by Region (2019-2024) & (K Units)
Table 41. South America Industrial Machine Vision Sales by Country (2019-2024) & (K Units)
Table 42. Middle East and Africa Industrial Machine Vision Sales by Region (2019-2024) & (K Units)
Table 43. Cognex Industrial Machine Vision Basic Information
Table 44. Cognex Industrial Machine Vision Product Overview
Table 45. Cognex Industrial Machine Vision Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2024)
Table 46. Cognex Business Overview
Table 47. Cognex Industrial Machine Vision SWOT Analysis
Table 48. Cognex Recent Developments
Table 49. Basler Industrial Machine Vision Basic Information
Table 50. Basler Industrial Machine Vision Product Overview
Table 51. Basler Industrial Machine Vision Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2024)
Table 52. Basler Business Overview
Table 53. Basler Industrial Machine Vision SWOT Analysis
Table 54. Basler Recent Developments
Table 55. OMRON Industrial Machine Vision Basic Information
Table 56. OMRON Industrial Machine Vision Product Overview
Table 57. OMRON Industrial Machine Vision Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2024)
Table 58. OMRON Industrial Machine Vision SWOT Analysis
Table 59. OMRON Business Overview
Table 60. OMRON Recent Developments
Table 61. KEYENCE Corporation Industrial Machine Vision Basic Information
Table 62. KEYENCE Corporation Industrial Machine Vision Product Overview
Table 63. KEYENCE Corporation Industrial Machine Vision Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2024)
Table 64. KEYENCE Corporation Business Overview
Table 65. KEYENCE Corporation Recent Developments
Table 66. National Instruments Industrial Machine Vision Basic Information
Table 67. National Instruments Industrial Machine Vision Product Overview
Table 68. National Instruments Industrial Machine Vision Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2024)
Table 69. National Instruments Business Overview
Table 70. National Instruments Recent Developments
Table 71. Sony Industrial Machine Vision Basic Information
Table 72. Sony Industrial Machine Vision Product Overview
Table 73. Sony Industrial Machine Vision Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2024)
Table 74. Sony Business Overview
Table 75. Sony Recent Developments
Table 76. Teledyne Technologies Industrial Machine Vision Basic Information
Table 77. Teledyne Technologies Industrial Machine Vision Product Overview
Table 78. Teledyne Technologies Industrial Machine Vision Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2024)
Table 79. Teledyne Technologies Business Overview
Table 80. Teledyne Technologies Recent Developments
Table 81. Texas Instruments Industrial Machine Vision Basic Information
Table 82. Texas Instruments Industrial Machine Vision Product Overview
Table 83. Texas Instruments Industrial Machine Vision Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2024)
Table 84. Texas Instruments Business Overview
Table 85. Texas Instruments Recent Developments
Table 86. Intel Industrial Machine Vision Basic Information
Table 87. Intel Industrial Machine Vision Product Overview
Table 88. Intel Industrial Machine Vision Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2024)
Table 89. Intel Business Overview
Table 90. Intel Recent Developments
Table 91. Baumer Optronic Industrial Machine Vision Basic Information
Table 92. Baumer Optronic Industrial Machine Vision Product Overview
Table 93. Baumer Optronic Industrial Machine Vision Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2024)
Table 94. Baumer Optronic Business Overview
Table 95. Baumer Optronic Recent Developments
Table 96. tordivel Industrial Machine Vision Basic Information
Table 97. tordivel Industrial Machine Vision Product Overview
Table 98. tordivel Industrial Machine Vision Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2024)
Table 99. tordivel Business Overview
Table 100. tordivel Recent Developments
Table 101. ISRA VISION Industrial Machine Vision Basic Information
Table 102. ISRA VISION Industrial Machine Vision Product Overview
Table 103. ISRA VISION Industrial Machine Vision Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2024)
Table 104. ISRA VISION Business Overview
Table 105. ISRA VISION Recent Developments
Table 106. MVTec Software Industrial Machine Vision Basic Information
Table 107. MVTec Software Industrial Machine Vision Product Overview
Table 108. MVTec Software Industrial Machine Vision Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2024)
Table 109. MVTec Software Business Overview
Table 110. MVTec Software Recent Developments
Table 111. SICK Industrial Machine Vision Basic Information
Table 112. SICK Industrial Machine Vision Product Overview
Table 113. SICK Industrial Machine Vision Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2024)
Table 114. SICK Business Overview
Table 115. SICK Recent Developments
Table 116. JAI A/S Industrial Machine Vision Basic Information
Table 117. JAI A/S Industrial Machine Vision Product Overview
Table 118. JAI A/S Industrial Machine Vision Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2024)
Table 119. JAI A/S Business Overview
Table 120. JAI A/S Recent Developments
Table 121. Global Industrial Machine Vision Sales Forecast by Region (2025-2030) & (K Units)
Table 122. Global Industrial Machine Vision Market Size Forecast by Region (2025-2030) & (M USD)
Table 123. North America Industrial Machine Vision Sales Forecast by Country (2025-2030) & (K Units)
Table 124. North America Industrial Machine Vision Market Size Forecast by Country (2025-2030) & (M USD)
Table 125. Europe Industrial Machine Vision Sales Forecast by Country (2025-2030) & (K Units)
Table 126. Europe Industrial Machine Vision Market Size Forecast by Country (2025-2030) & (M USD)
Table 127. Asia Pacific Industrial Machine Vision Sales Forecast by Region (2025-2030) & (K Units)
Table 128. Asia Pacific Industrial Machine Vision Market Size Forecast by Region (2025-2030) & (M USD)
Table 129. South America Industrial Machine Vision Sales Forecast by Country (2025-2030) & (K Units)
Table 130. South America Industrial Machine Vision Market Size Forecast by Country (2025-2030) & (M USD)
Table 131. Middle East and Africa Industrial Machine Vision Consumption Forecast by Country (2025-2030) & (Units)
Table 132. Middle East and Africa Industrial Machine Vision Market Size Forecast by Country (2025-2030) & (M USD)
Table 133. Global Industrial Machine Vision Sales Forecast by Type (2025-2030) & (K Units)
Table 134. Global Industrial Machine Vision Market Size Forecast by Type (2025-2030) & (M USD)
Table 135. Global Industrial Machine Vision Price Forecast by Type (2025-2030) & (USD/Unit)
Table 136. Global Industrial Machine Vision Sales (K Units) Forecast by Application (2025-2030)
Table 137. Global Industrial Machine Vision Market Size Forecast by Application (2025-2030) & (M USD)
List of Figures
Figure 1. Product Picture of Industrial Machine Vision
Figure 2. Data Triangulation
Figure 3. Key Caveats
Figure 4. Global Industrial Machine Vision Market Size (M USD), 2019-2030
Figure 5. Global Industrial Machine Vision Market Size (M USD) (2026-2034)
Figure 6. Global Industrial Machine Vision Sales (K Units) & (2026-2034)
Figure 7. Evaluation Matrix of Segment Market Development Potential (Type)
Figure 8. Evaluation Matrix of Segment Market Development Potential (Application)
Figure 9. Evaluation Matrix of Regional Market Development Potential
Figure 10. Industrial Machine Vision Market Size by Country (M USD)
Figure 11. Industrial Machine Vision Sales Share by Manufacturers in 2023
Figure 12. Global Industrial Machine Vision Revenue Share by Manufacturers in 2023
Figure 13. Industrial Machine Vision Market Share by Company Type (Tier 1, Tier 2 and Tier 3): 2023
Figure 14. Global Market Industrial Machine Vision Average Price (USD/Unit) of Key Manufacturers in 2023
Figure 15. The Global 5 and 10 Largest Players: Market Share by Industrial Machine Vision Revenue in 2023
Figure 16. Evaluation Matrix of Segment Market Development Potential (Type)
Figure 17. Global Industrial Machine Vision Market Share by Type
Figure 18. Sales Market Share of Industrial Machine Vision by Type (2019-2024)
Figure 19. Sales Market Share of Industrial Machine Vision by Type in 2023
Figure 20. Market Size Share of Industrial Machine Vision by Type (2019-2024)
Figure 21. Market Size Market Share of Industrial Machine Vision by Type in 2023
Figure 22. Evaluation Matrix of Segment Market Development Potential (Application)
Figure 23. Global Industrial Machine Vision Market Share by Application
Figure 24. Global Industrial Machine Vision Sales Market Share by Application (2019-2024)
Figure 25. Global Industrial Machine Vision Sales Market Share by Application in 2023
Figure 26. Global Industrial Machine Vision Market Share by Application (2019-2024)
Figure 27. Global Industrial Machine Vision Market Share by Application in 2023
Figure 28. Global Industrial Machine Vision Sales Growth Rate by Application (2019-2024)
Figure 29. Global Industrial Machine Vision Sales Market Share by Region (2019-2024)
Figure 30. North America Industrial Machine Vision Sales and Growth Rate (2019-2024) & (K Units)
Figure 31. North America Industrial Machine Vision Sales Market Share by Country in 2023
Figure 32. U.S. Industrial Machine Vision Sales and Growth Rate (2019-2024) & (K Units)
Figure 33. Canada Industrial Machine Vision Sales (K Units) and Growth Rate (2019-2024)
Figure 34. Mexico Industrial Machine Vision Sales (Units) and Growth Rate (2019-2024)
Figure 35. Europe Industrial Machine Vision Sales and Growth Rate (2019-2024) & (K Units)
Figure 36. Europe Industrial Machine Vision Sales Market Share by Country in 2023
Figure 37. Germany Industrial Machine Vision Sales and Growth Rate (2019-2024) & (K Units)
Figure 38. France Industrial Machine Vision Sales and Growth Rate (2019-2024) & (K Units)
Figure 39. U.K. Industrial Machine Vision Sales and Growth Rate (2019-2024) & (K Units)
Figure 40. Italy Industrial Machine Vision Sales and Growth Rate (2019-2024) & (K Units)
Figure 41. Russia Industrial Machine Vision Sales and Growth Rate (2019-2024) & (K Units)
Figure 42. Asia Pacific Industrial Machine Vision Sales and Growth Rate (K Units)
Figure 43. Asia Pacific Industrial Machine Vision Sales Market Share by Region in 2023
Figure 44. China Industrial Machine Vision Sales and Growth Rate (2019-2024) & (K Units)
Figure 45. Japan Industrial Machine Vision Sales and Growth Rate (2019-2024) & (K Units)
Figure 46. South Korea Industrial Machine Vision Sales and Growth Rate (2019-2024) & (K Units)
Figure 47. India Industrial Machine Vision Sales and Growth Rate (2019-2024) & (K Units)
Figure 48. Southeast Asia Industrial Machine Vision Sales and Growth Rate (2019-2024) & (K Units)
Figure 49. South America Industrial Machine Vision Sales and Growth Rate (K Units)
Figure 50. South America Industrial Machine Vision Sales Market Share by Country in 2023
Figure 51. Brazil Industrial Machine Vision Sales and Growth Rate (2019-2024) & (K Units)
Figure 52. Argentina Industrial Machine Vision Sales and Growth Rate (2019-2024) & (K Units)
Figure 53. Columbia Industrial Machine Vision Sales and Growth Rate (2019-2024) & (K Units)
Figure 54. Middle East and Africa Industrial Machine Vision Sales and Growth Rate (K Units)
Figure 55. Middle East and Africa Industrial Machine Vision Sales Market Share by Region in 2023
Figure 56. Saudi Arabia Industrial Machine Vision Sales and Growth Rate (2019-2024) & (K Units)
Figure 57. UAE Industrial Machine Vision Sales and Growth Rate (2019-2024) & (K Units)
Figure 58. Egypt Industrial Machine Vision Sales and Growth Rate (2019-2024) & (K Units)
Figure 59. Nigeria Industrial Machine Vision Sales and Growth Rate (2019-2024) & (K Units)
Figure 60. South Africa Industrial Machine Vision Sales and Growth Rate (2019-2024) & (K Units)
Figure 61. Global Industrial Machine Vision Sales Forecast by Volume (2026-2034) & (K Units)
Figure 62. Global Industrial Machine Vision Market Size Forecast by Value (2026-2034) & (M USD)
Figure 63. Global Industrial Machine Vision Sales Market Share Forecast by Type (2025-2030)
Figure 64. Global Industrial Machine Vision Market Share Forecast by Type (2025-2030)
Figure 65. Global Industrial Machine Vision Sales Forecast by Application (2025-2030)
Figure 66. Global Industrial Machine Vision Market Share Forecast by Application (2025-2030)