Key Statistics
Key Takeaways
- Point Light Guide is a leading product category because it addresses the largest current application base.
- Passenger Vehicle is a major application, with demand shaped by performance, reliability and system integration.
- Asia Pacific leads current market value, while Asia Pacific provides the strongest growth profile.
- Intelligent rgb leds, zone-controlled dynamic lighting and functional warning integration is the main technology direction influencing new design wins.
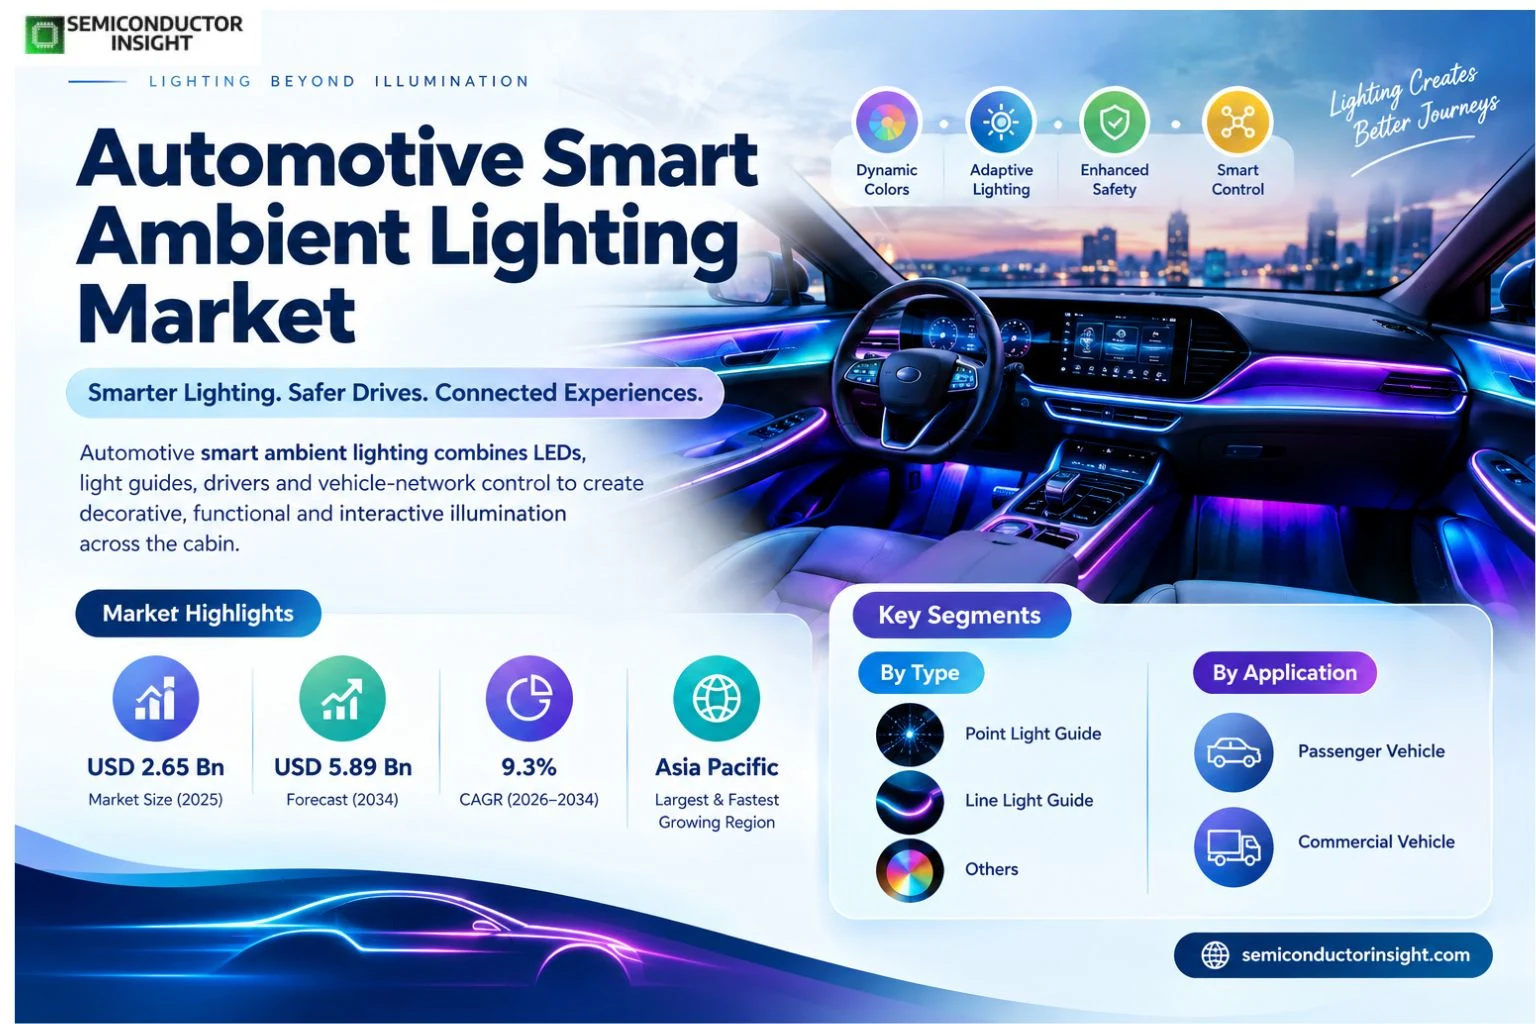
- Market size and growth: USD 2.65 billion in 2025 is projected to reach USD 5.89 billion by 2034 at a 9.3% CAGR during 2026–2034.
Automotive Smart Ambient Lighting Market Overview
Automotive smart ambient lighting market was valued at USD 2.65 billion in 2025 and is projected to reach USD 5.89 billion by 2034, growing at a CAGR of 9.3% over the 2026–2034 forecast period. Asia Pacific held the largest regional position in 2025, while Asia Pacific has the strongest growth profile.
Automotive smart ambient lighting combines LEDs, light guides, drivers and vehicle-network control to create decorative, functional and interactive illumination across the cabin. Commercial decisions in the Automotive Smart Ambient Lighting market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
The client evidence values the market at USD 2.215 billion in 2023 and projects USD 4.931 billion by 2032 at a 9.3% CAGR. Asia Pacific is expected to dominate through vehicle production and adoption of smart interior technologies, while passenger vehicles remain the main application. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
ams OSRAM’s automotive ambient-lighting architecture combines RGB LEDs, intelligent RGB devices, LED drivers and Open System Protocol control, enabling dynamic color, gradients and warning functions across distributed cabin zones. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
Segment Analysis: By Type
By type, the automotive smart ambient lighting market is segmented into Point Light Guide, Line Light Guide, Others. Each category has a distinct functional role and commercial position, so the analysis emphasizes use case, integration and competitive relevance rather than repeating a single market statistic across every row. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
| Type | Function | Market position |
|---|---|---|
| Point Light Guide | Point Light Guide addresses a distinct architecture or performance requirement within the Automotive Smart Ambient Lighting market. | Commercial demand depends on application fit, qualification, cost and lifecycle requirements rather than a single headline statistic. |
| Line Light Guide | Line Light Guide addresses a distinct architecture or performance requirement within the Automotive Smart Ambient Lighting market. | Commercial demand depends on application fit, qualification, cost and lifecycle requirements rather than a single headline statistic. |
| Others | Others addresses a distinct architecture or performance requirement within the Automotive Smart Ambient Lighting market. | Commercial demand depends on application fit, qualification, cost and lifecycle requirements rather than a single headline statistic. |
Pricing by type
Simple point-light systems compete on cost, while dynamic RGB and intelligent segment-based systems command premiums through drivers, calibration, networking and optical integration. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment. Commercial decisions in the Automotive Smart Ambient Lighting market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
Segment Analysis: By Application
By application, the market is segmented into Passenger Vehicle, Commercial Vehicle. Application economics differ by qualification, lifecycle, reliability and system-level value, so each row below uses context specific to that application rather than mechanically repeating headline evidence. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
| Application | Demand characteristics |
|---|---|
| Passenger Vehicle | Passenger Vehicle creates demand where automotive smart ambient lighting improves integration, performance, reliability or system economics. |
| Commercial Vehicle | Commercial Vehicle creates demand where automotive smart ambient lighting improves integration, performance, reliability or system economics. |
Regional Analysis
Asia Pacific leads current market value, while Asia Pacific has the strongest growth profile. Regional demand is shaped by manufacturing concentration, technology adoption, customer investment cycles and local supplier ecosystems. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
How does regional demand differ across the automotive smart ambient lighting market?
Asia Pacific provides the deepest manufacturing scale, North America contributes high-value technology and enterprise demand, and Europe remains important in industrial, automotive and regulated applications. South America and the Middle East & Africa are smaller but developing markets. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia Pacific | Largest | Highest | vehicle production, EV interiors and smart-cabin electronics | Supply scale and qualification |
| North America | High | Moderate-high | premium cabins, EV adoption and connected vehicles | Technology capability and service |
| Europe | Moderate-high | Moderate | premium automotive interiors, human-centric lighting and safety functions | Compliance and lifecycle |
| South America | Smaller | Moderate | Import/industrial led | Cost and distribution |
| Middle East & Africa | Smallest base | Emerging | Infrastructure led | Project support |
Key Automotive Smart Ambient Lighting Manufacturers and Competitive Landscape
The competitive landscape includes ams OSRAM, FORVIA HELLA, Marelli, Grupo Antolin, ZKW, Stanley Electric, Valeo, Varroc, DRÄXLMAIER, Hyundai Mobis. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment. Commercial decisions in the Automotive Smart Ambient Lighting market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
Competition centers on intelligent RGB LEDs, zone-controlled dynamic lighting and functional warning integration, customer qualification, manufacturing consistency and application support. Once a product is designed into a long-lifecycle system, switching costs can protect incumbent positions but also raise the importance of roadmap continuity. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Tier 1 | ams OSRAM, FORVIA HELLA, Marelli, Grupo Antolin | Global scale, broad customer qualification and advanced technology portfolios. |
| Tier 2 | ZKW, Stanley Electric, Valeo, Varroc | Strong specialist capability, regional design wins and application-focused portfolios. |
| Tier 3 | Regional and niche suppliers | Cost competition, customization and specialized customer support. |
Key companies profiled
- ams OSRAM
- FORVIA HELLA
- Marelli
- Grupo Antolin
- ZKW
- Stanley Electric
- Valeo
- Varroc
- DRÄXLMAIER
- Hyundai Mobis
Automotive Smart Ambient Lighting Production Capacity Analysis
Production capacity in the Automotive Smart Ambient Lighting market is shaped by the underlying manufacturing process, qualification burden and customer-specific configuration. Suppliers must balance equipment utilization with quality control because high-volume output only creates value when yield, reliability and traceability remain stable. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
Capacity additions tend to follow customer program ramps rather than headline market growth alone. Regional supply resilience is becoming more important, particularly where customers require second-source planning, long product lifecycles or shorter engineering-response times. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
The practical bottleneck is often qualified output rather than nominal installed capacity. Manufacturing, assembly, test and application support must scale together to avoid creating capacity that cannot be used in production programs. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
Automotive Smart Ambient Lighting Market Dynamics: Drivers, Restraints and Opportunities
The Automotive Smart Ambient Lighting market is shaped by growth is driven by ev interiors, premium cabin differentiation, personalization, hmi integration and the use of lighting for warnings, interaction and driver/passenger experience. At the same time, growth is constrained by added vehicle bom, software integration, color consistency, thermal management and the need to coordinate lighting with zone controllers and vehicle networks. The strongest commercial opportunities are concentrated in dynamic pixel lighting, smart surfaces, human-centric white lighting and safety-linked visual alerts create the strongest opportunities.
MARKET DRIVERS
Drivers Impact Analysis*
| Driver | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Technology upgrade cycle | +1.6% | Global; strongest in leading adopter markets | Near to medium term |
| End-market expansion | +1.2% | Application-specific | Near term |
| Higher value per system | +0.8% | Premium and advanced systems | Medium term |
Technology adoption expands addressable demand
Growth is driven by EV interiors, premium cabin differentiation, personalization, HMI integration and the use of lighting for warnings, interaction and driver/passenger experience. This demand is strongest where customers can measure a clear improvement in system performance, footprint, energy efficiency, reliability or operating cost. Commercial decisions in the Automotive Smart Ambient Lighting market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
End-market modernization increases content per system
The technology upgrade cycle supports replacement and redesign activity as OEMs move to higher-performance architectures. New designs typically create the best opportunity because suppliers can influence specifications before qualification is locked. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
Higher-value architectures support premium mix
Expanding end markets also increase content per system, creating value growth even when unit shipments grow more slowly. Suppliers that combine engineering support with reliable supply are better positioned to capture those design transitions. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Restraint | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Qualification and integration burden | -0.7% | Global | Ongoing |
| Price and substitution pressure | -0.5% | Cost-sensitive applications | Ongoing |
| Supply-chain or process complexity | -0.4% | Global | Medium term |
Qualification burden slows supplier switching
Growth is constrained by added vehicle BOM, software integration, color consistency, thermal management and the need to coordinate lighting with zone controllers and vehicle networks. These constraints are most significant where customers have qualified alternatives or where the technology must prove a clear system-level advantage over lower-cost incumbent solutions. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
Price competition limits margin expansion
Qualification and integration can extend sales cycles because customers must validate performance, reliability and compatibility in their own system environment. That makes early engineering engagement important for new suppliers. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
Alternative technologies constrain selected use cases
Supply-chain complexity can also limit growth when specialized materials, tooling, test or regional support are required. Customers increasingly evaluate resilience alongside price when choosing long-lifecycle suppliers. Commercial decisions in the Automotive Smart Ambient Lighting market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
MARKET OPPORTUNITIES
Advanced integration creates premium opportunities
Dynamic pixel lighting, smart surfaces, human-centric white lighting and safety-linked visual alerts create the strongest opportunities. The most attractive opportunities are where customers are redesigning systems rather than simply replacing like-for-like components. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
Regional capacity and supply resilience
Intelligent rgb leds, zone-controlled dynamic lighting and functional warning integration can create premium value when it lowers system complexity, improves performance or supports a new product architecture that is difficult to achieve with incumbent approaches. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
Application engineering deepens customer value
Regional engineering support and application-specific customization provide another route to growth because customers increasingly expect suppliers to support qualification, transition planning and lifecycle management. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
Automotive Smart Ambient Lighting Supply Chain Analysis
Upstream. Automotive LEDs, light guides, drivers, CAN/LIN transceivers, zone controllers, optical plastics, trim modules and software calibration form the supply chain. Supply quality at this stage directly affects downstream yield, reliability and cost. Commercial decisions in the Automotive Smart Ambient Lighting market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
Manufacturing. Core production combines process control, assembly, inspection and test, with product-specific qualification used to verify performance before customer shipment. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
Distribution. High-value programs are typically won through direct OEM, Tier-1 or design-house engagement, while distributors serve prototypes, regional customers and lower-volume applications. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
Downstream. End users integrate the product into systems where switching costs rise after qualification, making lifecycle support and supply continuity commercially important. Commercial decisions in the Automotive Smart Ambient Lighting market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
Downstream. Panel builders and machine OEMs are the primary specifying customers, followed by electrical contractors working on building services and by facility maintenance teams handling replacement. The specification decision is usually made once, at panel design, and then repeats for the life of the design — which makes design-in position considerably more valuable than any individual transaction.
Recent Developments in the Automotive Smart Ambient Lighting Market
Developments tracked through September 2026. Items are selected for direct relevance to product technology, deployment or standards. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
- 2026 Current
ams OSRAM dynamic ambient lighting ams OSRAM supports dynamic automotive ambient lighting with intelligent RGB LEDs, LED drivers and its Open System Protocol architecture. Source - 2026 Current
Interior lighting expands into sensing and interaction ams OSRAM positions ambient lighting, smart surfaces, display backlighting and in-cabin sensing as connected cabin functions. Source - 2026 Current
High-CRI automotive interior LEDs ams OSRAM’s OSTUNE family targets automotive white ambient lighting with high CRI and a wide color-temperature range. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2021–2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| Historical Period | 2021–2025 |
| Market Size 2025 | USD 2.65 billion |
| Market Size 2034 | USD 5.89 billion |
| Growth Rate | CAGR of 9.3% from 2026–2034 |
| Unit | Value (USD Million) |
| Segmentation | By Type, By Application, By Lighting Architecture, By Installation Zone, and By Region |
| By Type | Point Light Guide · Line Light Guide · Others |
| By Application | Passenger Vehicle · Commercial Vehicle |
| By Installation Zone | Dashboard & Console · Door & Trim · Footwell & Roof · Seats / Other |
| By Lighting Architecture | Static RGB · Dynamic RGB · Intelligent Pixel / Segment Lighting |
| By Region | Each region analysed by Type, Application and Country North AmericaU.S., Canada, Mexico EuropeGermany, France, U.K., Italy, Russia, Nordic Countries, Benelux AsiaChina, Japan, South Korea, India, Southeast Asia South AmericaBrazil, Argentina, Rest of South America Middle East & AfricaTurkey, Israel, Saudi Arabia, UAE, Rest of MEA |
| Key Companies Profiled | ams OSRAM, FORVIA HELLA, Marelli, Grupo Antolin, ZKW, Stanley Electric, Valeo, Varroc, DRÄXLMAIER, Hyundai Mobis |
| Customization Scope | Free report customization (equivalent to up to 4 analyst working days) with purchase. Addition or alteration to country, regional and segment scope. |
Frequently Asked Questions
What is the current size of the Automotive Smart Ambient Lighting market?
The market is valued at USD 2.65 billion in 2025 and is projected to reach USD 5.89 billion by 2034, expanding at a 9.3% CAGR during 2026–2034.
Which companies lead the Automotive Smart Ambient Lighting market?
Key participants include ams OSRAM, FORVIA HELLA, Marelli, Grupo Antolin, ZKW, Stanley Electric, Valeo, Varroc.
What is Automotive Smart Ambient Lighting?
Automotive smart ambient lighting combines LEDs, light guides, drivers and vehicle-network control to create decorative, functional and interactive illumination across the cabin.
What are the main product types?
The market includes Point Light Guide, Line Light Guide, Others.
What are the key applications?
The principal applications are Passenger Vehicle, Commercial Vehicle.
Which region leads the market?
Asia Pacific leads current market value, while Asia Pacific has the strongest growth profile.
What drives market growth?
Growth is driven by EV interiors, premium cabin differentiation, personalization, HMI integration and the use of lighting for warnings, interaction and driver/passenger experience.
What are the main challenges?
Growth is constrained by added vehicle BOM, software integration, color consistency, thermal management and the need to coordinate lighting with zone controllers and vehicle networks.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF